
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Composites Market Size, Share, By Fiber Type (Carbon Fiber Composites, Glass Fiber Composites, Aramid Fiber Composites, UHMWPE Fiber Composites and Others), By Resin Type (Thermoset Matrix Composites and Thermoplastic Matrix Composites), By Manufacturing Process (Manual & Semi-Automated Prepreg Lay-Up, Resin Transfer Molding, Vacuum Infusion, Compression Molding, Filament Winding, Pultrusion, Injection Molding Process, Hand Lay-Up & Spray-Up and Others), By End-Use Industry (Commercial Aerospace & Space, Defense & Military Systems, Passenger & Commercial Automotive, Wind Energy, Marine, Sporting Goods & Recreation, Electrical & Electronics, Industrial & Infrastructure and Others), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5276
September 16, 2026
289 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $112.5 Billion in 2025, projected to reach $214.5 Billion by 2033 at a 8.4% CAGR.
Dominant Segment: Carbon Fiber Composites lead the market, driven by their increasing adoption in the aerospace sector for lightweight and high-strength applications.
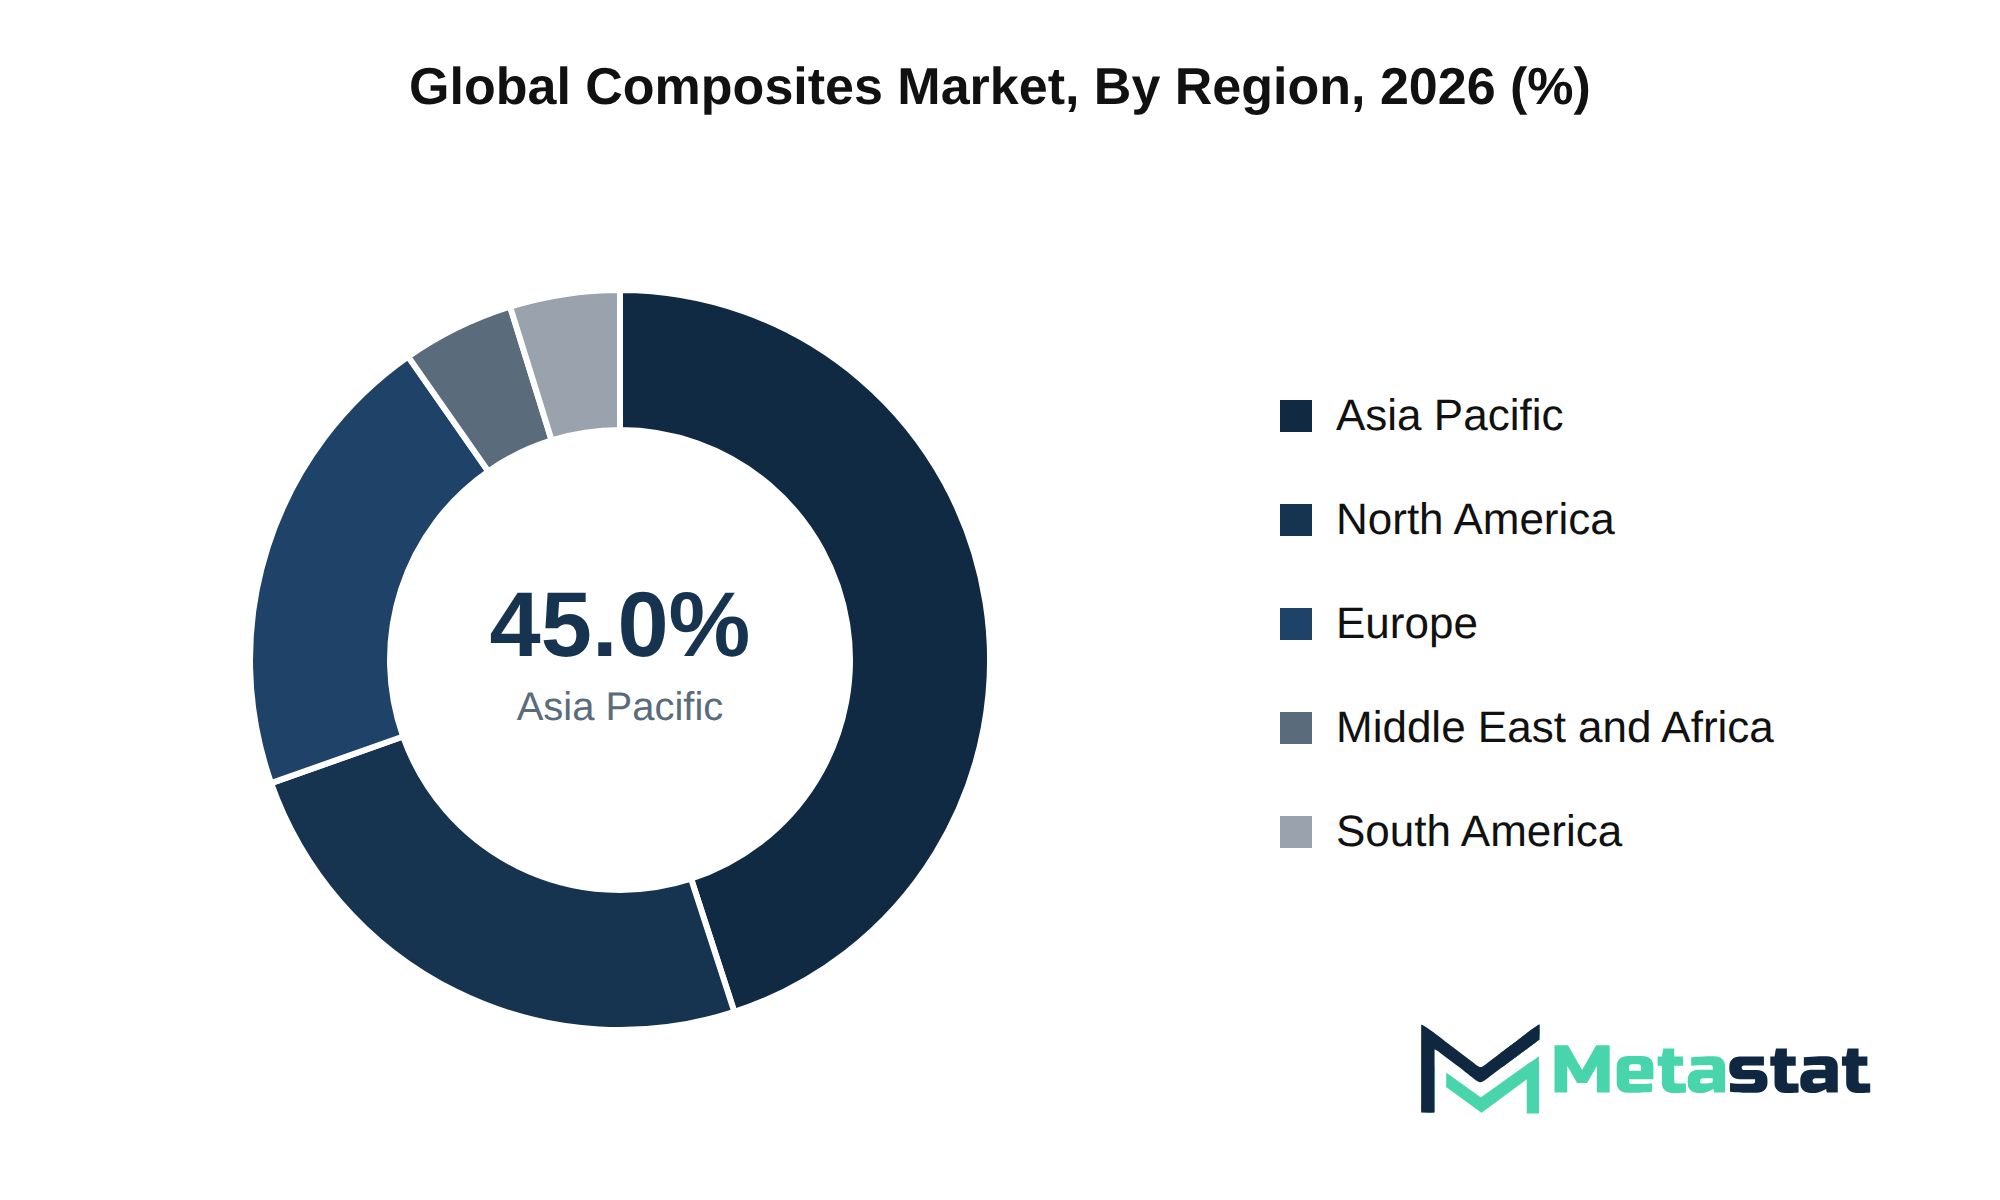
Geographic Lead: The Asia Pacific region is experiencing the fastest growth, fueled by rapid urbanization and significant investments in infrastructure and automotive sectors.
What's Inside: This report provides a comprehensive analysis of the global Composites market, including detailed segmentation by fiber type, resin type, manufacturing process, and end-use industry.
Emerging Regional Demands: Emerging economies are driving market growth through modernization projects that prioritize lightweight and durable composite materials.
Digital Transformation: The integration of digital technologies is enhancing operational efficiency, enabling manufacturers to streamline processes and improve product quality.
The global Composites market was valued at USD 112.5 billion in 2025 and is projected to reach USD 214.5 billion by 2033, growing at a CAGR of 8.4% over the forecast period.
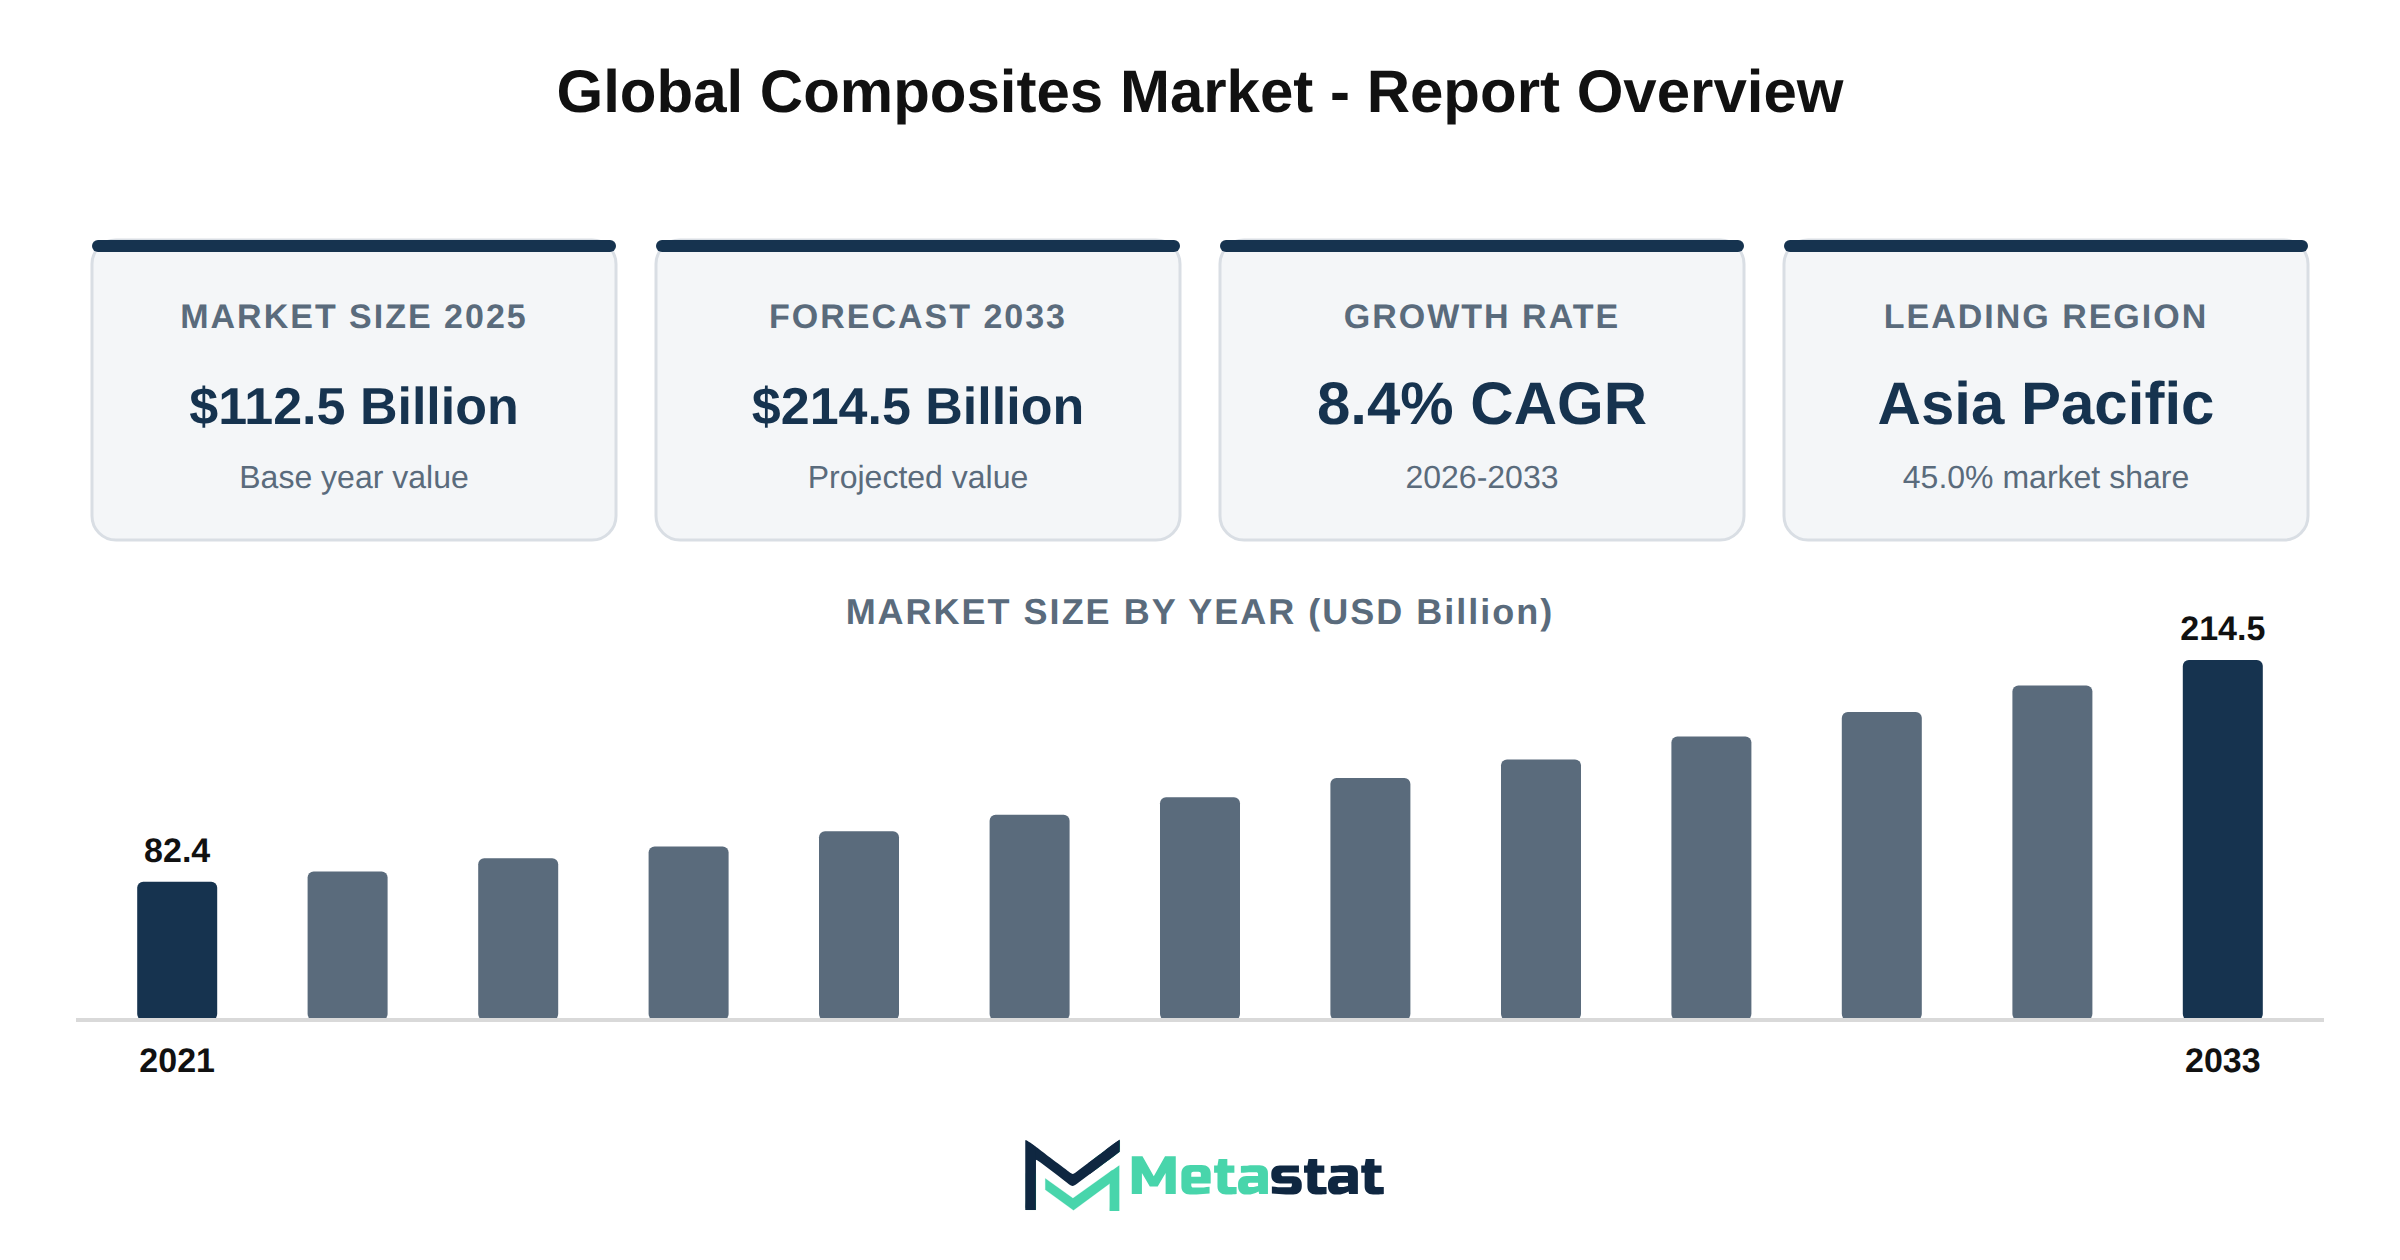
The global Composites market reached USD 112.5 billion in 2025 and is projected to expand to USD 214.5 billion by 2033, reflecting a compound annual growth rate (CAGR) of 8.4%. This growth is driven by the increasing demand for lightweight high-performance materials across various industries.
Rising demand in the aerospace and space sectors for advanced composite structures significantly influences market dynamics. Key players focus on developing innovative materials to meet stringent performance and weight requirements in aircraft design.
Automotive lightweighting initiatives accelerate the adoption of carbon and glass fiber composites. While manufacturers prioritize fuel efficiency and emissions reduction, the integration of these materials into vehicle designs enhances performance while lowering overall weight.
The motorsport industry experiences expanding demand for high-performance carbon fiber composites. These materials provide superior strength-to-weight ratios, contributing to enhanced vehicle performance and safety, thus driving growth in this segment.
Defense modernization initiatives support the rising demand for advanced composite materials. Military applications benefit from the unique properties of composites, which provide durability and reduced weight, essential for various defense systems.
Thermoplastic composites gain momentum across high-performance applications, driven by their recyclability and processing advantages. This trend aligns with industry efforts to develop more sustainable material options, further propelling market growth.
Carbon fiber composites capture an increasing share in structural applications due to their strong and rigid properties. Their ability to withstand extreme conditions positions them because the material of choice for critical structural components.
Glass fiber composites remain essential for cost-effective high-volume production. Industries requiring large quantities of durable materials benefit from the affordability and versatility of glass fiber composites, ensuring sustained market relevance.
Automated composite manufacturing technologies enhance the adoption of automated fiber placement (AFP) and automated tape laying (ATL) methods. These advancements streamline production processes and improve efficiency in composite component manufacturing.
Resin transfer molding (RTM) and high-pressure RTM (HP-RTM) technologies enable faster composite component production. These methods facilitate the quick fabrication of complex geometries, meeting the growing demand for efficiency in manufacturing.
Innovation in composite manufacturing targets complex hollow and lightweight structures. Enhanced design capabilities allow manufacturers to explore new applications and markets, contributing to the overall growth of the Composites market.
Global demand for lightweight, high-performance materials drives significant growth in the Composites market. Industries including aerospace and automotive increasingly seek advanced composite structures to enhance performance while reducing weight.
In aerospace, the surge in demand for advanced composite structures enhances fuel efficiency and operational performance. This trend leads manufacturers to adopt innovative composite materials, positioning them because a vital component in aircraft design and production.
The automotive sector accelerates the adoption of carbon and glass fiber composites to achieve lightweighting objectives, improving fuel economy and lowering emissions. This shift reflects an industry-wide transition towards sustainability and performance enhancement.
Motorsport applications further expand the utilization of high-performance carbon fiber composites, where weight reduction and strength optimization are critical. The competitive nature of this industry drives continuous innovation in composite materials and manufacturing processes.
Ongoing defense modernization initiatives support robust demand for advanced composite materials, enhancing the performance and durability of military equipment. This sector's requirements drive technological advancements in composite applications.
Thermoplastic composites gain momentum across high-performance applications, providing flexibility in manufacturing and potential for recyclability. Their increasing adoption is evident in various industries seeking efficient and sustainable solutions.
Carbon fiber composites capture a growing share in structural applications due to their superior strength-to-weight ratio. This trend positions them because a preferred choice for critical components in numerous sectors.
Glass fiber composites remain essential for cost-effective, high-volume production, particularly in industries that prioritize affordability without compromising performance. Their versatility ensures continued relevance in the market.
Advancements in automated composite manufacturing facilitate the adoption of automated fiber placement (AFP) and automated tape laying (ATL) technologies. These innovations enhance production efficiency and consistency in composite component manufacturing.
Resin transfer molding (RTM) and high-pressure resin transfer molding (HP-RTM) technologies enable faster production of composite components, aligning with industry demands for speed and efficiency. This trend supports a shift towards high-volume manufacturing capabilities.
Innovation in composite manufacturing targets complex hollow and lightweight structures, addressing the evolving needs of various industries. This focus on advanced design capabilities enhances product offerings and market competitiveness.
The growth of the wind energy sector strengthens demand for large-scale composite components, essential for turbine manufacturing. This trend highlights the role of composites in supporting renewable energy initiatives.
Efforts towards recycling and circularity reshape the development of composite materials, promoting sustainable practices within the industry. This focus aligns with broader environmental goals and consumer expectations.
Bio-based and recycled composite materials gain commercial relevance, appealing to environmentally conscious consumers and industries. This shift contributes to the diversification of the material landscape in the market.
Composite raw material pricing and supply chain dynamics significantly influence market growth. Fluctuations in raw material availability impact production costs and, ultimately, market pricing strategies.
Aerospace-grade composite qualification and certification shape market entry strategies, ensuring compliance with rigorous safety and performance standards. This regulatory environment influences product development timelines and market access.
Strategic investments expand global carbon fiber and composite production capacity, reflecting an industry commitment to meeting growing demand. This expansion supports enhanced competitiveness in the global market.
Composite manufacturers increasingly forge partnerships across aerospace, automotive, and defense sectors, driving collaboration and innovation. These strategic alliances enhance capabilities and market reach.
Asia Pacific emerges because a major hub for composite manufacturing and demand, driven by robust industrial growth and investment. This region's expansion contributes significantly to the overall market landscape.
North America and Europe lead in high-performance composite innovation, focusing on advanced materials and technologies. Their strong research and development efforts drive the market forward.
Additive manufacturing creates new opportunities for composite tooling and components, enabling customized solutions and reducing lead times. This trend reflects the evolving landscape of production methods in the industry.
Future growth in the composites market favors lightweight, durable, and multifunctional materials, aligning with industry trends towards efficiency and performance. This focus on advanced materials continues to shape the market dynamics.
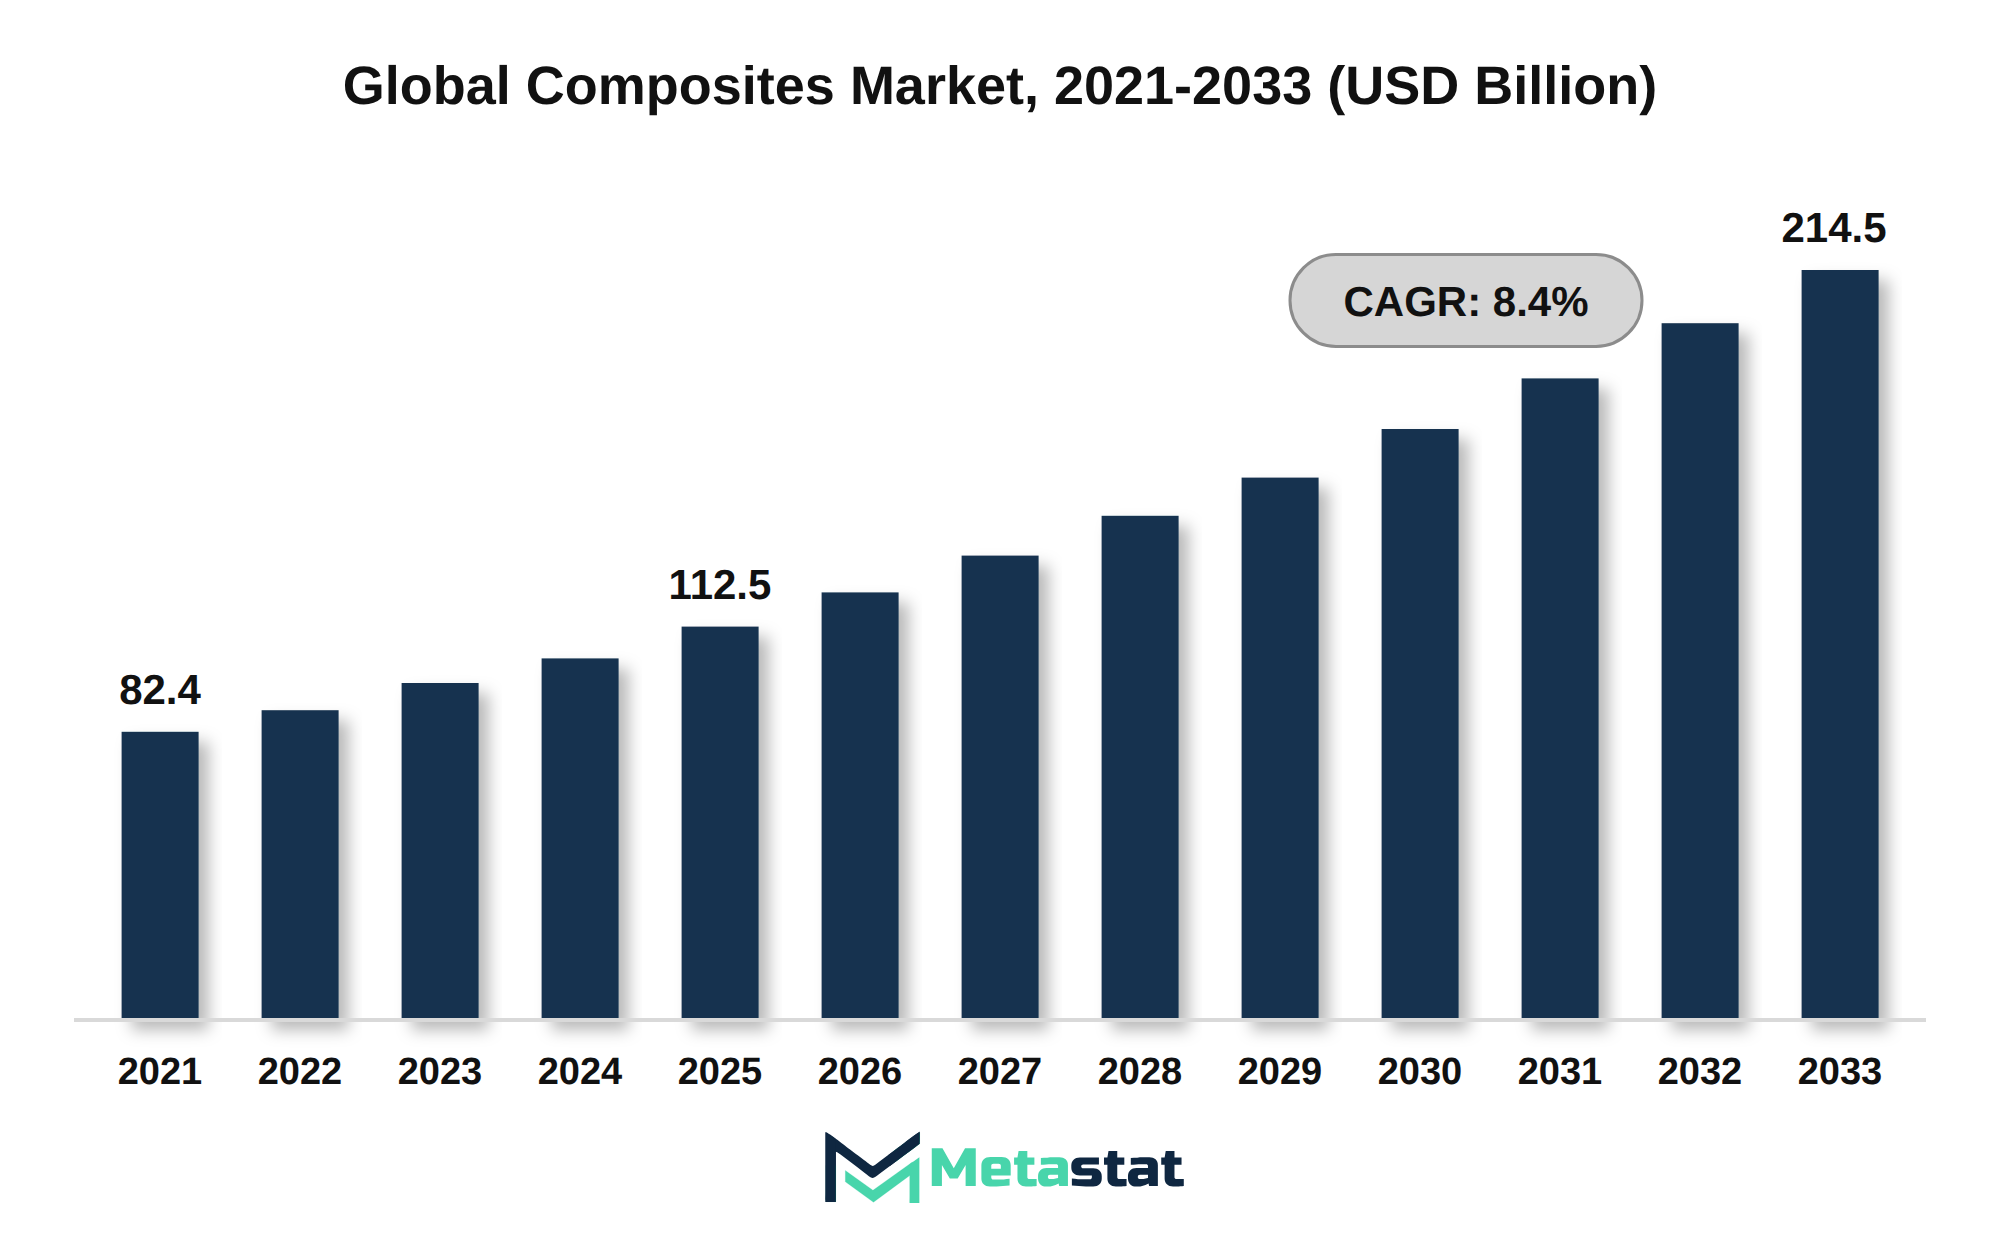
Economic growth in various regions significantly influences the Composites market. Increasing gross domestic product (GDP) stimulates capital investments across multiple sectors, leading to higher demand for advanced materials. Industries including automotive, aerospace, and construction experience rising pressure to enhance performance and reduce weight in products, driving the adoption of composite materials.
Investment in infrastructure development and modernization enhances the demand for composites, with applications in wind energy, marine, and industrial sectors. Companies prioritize operational productivity and cost-efficiency initiatives, focusing on lightweight alternatives that reduce energy consumption and lower emissions. This shift toward sustainability aligns with evolving consumer behaviors prioritizing environmentally friendly products.
The market reflects a trend toward innovation-led product diversification, where manufacturers leverage advanced technologies to develop new composite solutions that meet diverse end-use requirements. Such innovations, combined with strong economic performance, enhance the market's growth trajectory, positioning composites because integral components in numerous applications.
The adoption of digital transformation strategies significantly boosts efficiency within the Composites market. Enterprises increasingly invest in automation, advanced software solutions, and the digitization of legacy processes to streamline operations and reduce costs. This shift towards digital technologies enables manufacturers to enhance productivity, optimize resource allocation, and improve product quality.
Automation technologies, including robotics and artificial intelligence, play a crucial role in improving manufacturing capabilities. By implementing automated processes, manufacturers achieve faster production cycles and lower labor costs, driving competitive advantages. The integration of these technologies supports the shift towards advanced composite materials, which require precise manufacturing methods.
Digital solutions facilitate data analytics and real-time monitoring, allowing companies to respond swiftly to market demands and operational challenges. Enhanced visibility across supply chains leads to improved decision-making and resource management, contributing to stronger market positioning. The growth of smart factories reflects this trend. Manufacturers leverage data to enhance production efficiency and reduce waste.
Digital transformation serves because a key driver for the Composites market, promoting operational efficiency, reducing costs, and enabling manufacturers to meet evolving customer demands effectively. This trend is expected to influence the market positively over the forecast period, supporting significant growth and adoption of advanced composite materials.
Strict regulatory compliance requirements present significant challenges within the Composites market. Manufacturers face increasing pressure to adhere to environmental and safety standards, leading to heightened operational costs and potential delays in product development. These compliance hurdles deter investment in new technologies and processes, restricting innovation and limiting market expansion.
Macroeconomic headwinds, including inflation and supply chain disruptions, contribute to rising costs and operational inefficiencies. The market experiences challenges in sourcing raw materials, which further escalates production costs and impacts profitability. Geopolitical instability exacerbates these issues, creating uncertainty that discourages investment and complicates global supply chains.
The composites sector confronts technological obsolescence, with rapid advancements in alternative materials presenting substitution risks. Buyers increasingly evaluate the performance and cost-effectiveness of newer offerings, impacting demand for traditional composite products. This shift creates added pressure on manufacturers to innovate and remain competitive.
Overall, these market restraints collectively hinder growth opportunities within the Composites market. Companies navigate complex regulatory landscapes while managing escalating costs and evolving consumer preferences, all of which affect their ability to compete effectively in an increasingly challenging environment.
Geopolitical fragmentation introduces significant challenges for the Composites market by disrupting established supply chains, leading to increased tariffs and trade deficits. Heightened tensions among nations create barriers to international trade, affecting the availability and pricing of raw materials and components necessary for composite production. Industries reliant on global supply chains, including automotive and aerospace, experience delays and increased costs, which influence operational efficiency and profit margins.
Technological disruptions further complicate market dynamics, necessitating complex research and development integrations. Companies investing in advanced manufacturing technologies face hurdles associated with interoperable systems, which hinder productivity and increase implementation timelines. Pressures related to workforce skill gaps and talent retention impact the ability to effectively leverage these technological innovations.
Environmental lifecycle footprints and sustainability demands impose additional constraints, pushing manufacturers to adopt more responsible practices. Compliance with evolving legal liabilities around environmental impact requires investments that strain financial resources, leading to pricing compression. This compression challenges profitability, particularly for smaller players in the market, who struggle to absorb rising input costs while maintaining competitive pricing against larger, more established companies.
The confluence of these factors results in a volatile landscape for the Composites market, necessitating strategic adaptations from manufacturers. Navigating geopolitical fragmentation, technological advancements, and sustainability pressures will determine future growth trajectories and competitive positioning within the market.
Rapid urbanization and industrialization in emerging economies fuel significant demand for composite materials. Regions including Asia Pacific experience infrastructure modernization projects that prioritize lightweight and durable materials, directly impacting the composites market. Increased investments in construction, automotive, and aerospace sectors in these regions enhance opportunities for growth.
Technological disruptions, including advancements in manufacturing processes and sustainable practices, contribute to market dynamics. Innovations including thermoplastic composites and automated manufacturing techniques enable higher efficiency and lower production costs. These developments attract diverse industries, resulting in increased adoption of composite materials.
Digital transformation reshapes procurement methods within the market. Companies shift towards online platforms for sourcing composite materials, resulting in streamlined purchasing processes and improved supply chain management. Evolving buying behaviors emphasize the need for transparency and customization, driving suppliers to align their offerings accordingly.
Environmental, social, and governance (ESG) considerations influence market strategies, prompting businesses to adopt eco-friendly practices. Sustainability imperatives lead to the integration of recycled materials and reduced carbon footprints in production processes. Companies prioritizing green transformations gain competitive advantages and enhance their market positions.
Market diversification into niche applications highlights opportunities for growth. Industries including wind energy, marine, and sporting goods seek specialized composite solutions, increasing demand for tailored products. This diversification strategy positions companies favorably within the composites market, enabling them to address unique customer needs and enhance revenue potential.
The Global Composites market is segmented based on Fiber Type, Resin Type, Manufacturing Process, and End-Use Industry.
Demand for Carbon Fiber Composites demonstrates growth, driven by the increasing need for lightweight and high-strength materials in various applications, particularly in the aerospace and automotive sectors. This segment is valued at USD 48 billion in 2026 and is projected to reach USD 89.9 billion by 2033, at a CAGR of 9.4% during the forecast period. Adoption in the commercial aerospace sector significantly contributes to this expansion, because manufacturers seek to enhance fuel efficiency and reduce emissions.
Technological advancements in production processes, including automated fiber placement and advanced manufacturing techniques, support the segment's growth by enabling cost-effective and high-quality composite solutions. Increased investment in research and development within the Composites market drives innovation, leading to next-generation products that cater to evolving consumer demands.
Regulatory compliance standards, particularly in environmental and safety regulations, create an impetus for manufacturers to adopt carbon fiber composites. Companies that invest in these materials experience improved market positioning and competitive advantages. The automotive industry's shift towards electric vehicles further accelerates demand, with carbon fiber composites playing a critical role in weight reduction and overall vehicle performance.
Pricing volatility for raw materials, including carbon fibers and resins, presents challenges for manufacturers. Strategic sourcing and long-term contracts mitigate these issues, allowing companies to maintain profitability. The need for sustainable materials drives innovation in recycling processes for carbon fiber composites, creating additional opportunities for market growth.
The Carbon Fiber Composites segment stands poised for development, driven by technological maturation and increasing end-use demand. The outlook for this segment within the Composites market remains optimistic, with anticipated investments and industry trends supporting continued expansion.
Demand for Glass Fiber Composites stems from their unique properties, including high strength-to-weight ratio and resistance to corrosion, positioning them because favorable materials in various applications. Industries including automotive, construction, and aerospace are prominent consumers, leveraging these composites to enhance product performance and durability. The segment is estimated to reach USD 103.8 billion by 2033, at a CAGR of 7.4% during the forecast period.
Technological advancements in production processes, including Resin Transfer Molding and Compression Molding, facilitate lower production costs and improved efficiency, driving wider adoption across end-use sectors. Evolution in product formulations enhances the performance characteristics of glass fiber composites, aligning them with the growing demand for sustainable solutions in manufacturing.
Regulatory compliance with environmental standards influences material selection, prompting manufacturers to opt for glass fiber composites that meet these criteria while providing superior mechanical properties. The market encounters competition from alternative materials, yet glass fiber remains robust due to its cost-effectiveness and versatility in applications ranging from wind energy to marine structures.
Capital investments in research and development are essential, driving innovation and addressing market demands through next-generation upgrades. The continued evolution of the composites market, particularly for glass fiber composites, signifies a strategic opportunity for players aiming to enhance their market presence and cater to evolving consumer preferences.
Increasing demand for high-strength, lightweight materials drives growth in the Aramid Fiber Composites segment. This segment is expected to reach USD 9.4 billion by 2033. Industries including aerospace and defense prioritize these composites for their excellent mechanical properties, including high resistance to abrasion and impact. The segment's expansion is fueled by advancements in manufacturing techniques and the development of innovative applications across various end-use industries. Regulatory compliance in aerospace and military applications necessitates the use of materials that meet stringent performance criteria, leading to increased adoption of aramid fiber composites.
Technological maturation contributes to enhanced material performance and cost-effectiveness. Investment in research and development facilitates the evolution of next-generation aramid fiber products, driving their integration into new applications. The end-use dynamics indicate a shift towards more sustainable and high-performance materials, aligning with global trends in lightweighting and efficiency. The market anticipates continued growth driven by manufacturers seeking materials that deliver both performance and compliance with environmental standards.
Strong performance in the UHMWPE Fiber Composites segment reflects a growing recognition of its superior properties, including high strength-to-weight ratio and resistance to abrasion. These characteristics position UHMWPE Fiber Composites favorably across various applications, particularly in the defense and aerospace sectors, which seek materials that enhance durability while minimizing weight.
Technological maturation plays a critical role in segment growth, with advancements in manufacturing processes facilitating the production of more complex and efficient composite structures. Increased investments in research and development contribute to product evolution, enabling the introduction of next-generation composites that meet emerging industry standards.
Demand for UHMWPE Fiber Composites is projected to grow at a CAGR of 10.4% during the forecast period, driven by rising consumption in end-use industries that prioritize material performance. These dynamics within the Composites market present strategic opportunities for manufacturers focused on innovation and adaptation to market demands.
Market participants face challenges in sourcing raw materials, which affect production timelines and costs. Strategic partnerships and investments in supply chain resilience enhance the ability to mitigate risks associated with material availability, ensuring stability in pricing and supply.
The UHMWPE Fiber Composites segment presents significant growth potential within the broader Composites market, characterized by technological advancements, evolving applications, and a focus on meeting the demands of high-performance industries.
Materials categorized under Others (Basalt, Natural, Boron and Quartz Fiber Composites) play a crucial role in the Composites market due to their unique characteristics, which include lightweight properties and high strength. The shift towards sustainable materials increases the appeal of natural fibers, while basalt and boron fibers offer high thermal resistance and excellent mechanical properties, making them suitable for various demanding applications.
Technological maturation contributes to the expansion of this segment, with innovations in processing techniques enhancing the performance and versatility of these composites. Next-generation upgrades, including the development of hybrid materials that incorporate these fibers, drive increased adoption in industries including construction, automotive, and aerospace.
End-use dynamics influence market trends, with growing applications in infrastructure projects and renewable energy sectors driving demand for durable, lightweight materials. Regulatory compliance standards increasingly favor the use of environmentally friendly materials, positioning the Others segment favorably within the market landscape.
Cost structures and pricing volatility present challenges, yet the unique benefits provided by basalt, natural, boron, and quartz fibers maintain their competitive edge. The ongoing exploration of substitution risks opens opportunities for these materials, driven by manufacturers seeking alternatives to traditional composites.
Strategic opportunity windows emerge from the need for enhanced performance materials in specialized applications. These factors contribute to a positive capital investment outlook, encouraging stakeholders to explore the potential of Others (Basalt, Natural, Boron and Quartz Fiber Composites) within the broader Composites market.
Thermoset Matrix Composites segment is valued at USD 77.5 billion in 2026 and is projected to reach USD 128.4 billion by 2033, at a CAGR of 7.5% during the forecast period. The increasing adoption of these composites in various applications, including automotive, aerospace, and industrial sectors, significantly contributes to market expansion. Their superior mechanical properties, resistance to heat and chemicals, and long-term durability align with the growing demand for reliable materials across industries.
Technological advancements in manufacturing processes enhance the efficiency and scalability of Thermoset Matrix Composites, further supporting their integration into diverse applications. The development of next-generation materials and formulations improves product performance, catering to the evolving needs of end-users. This segment's growth is driven by an expanding focus on sustainability and eco-friendly practices, prompting manufacturers to innovate in resin formulations and processing technologies.
Regulatory compliance standards for materials in safety-critical applications enhance the demand for Thermoset Matrix Composites, attributed to industries prioritizing materials that meet stringent requirements. Cost structures and pricing volatility affect producers, yet the established benefits of these composites often justify the investment, maintaining robust interest across sectors. Growing competition and emerging players in the market will shape the landscape, creating strategic opportunity windows for stakeholders across the value chain.
Growth in the Thermoplastic Matrix Composites segment reflects increasing demand for lightweight, durable materials across various industries, including automotive and aerospace. This segment is projected to reach USD 86.2 billion by 2033, at a CAGR of 9.8% during the forecast period. Improved fuel efficiency and regulatory compliance drive significant adoption among manufacturers aiming to enhance product performance while minimizing environmental impact.
Technological advancements in processing and material formulation enhance the performance characteristics of thermoplastic composites, making them more appealing to end-users. The shift towards sustainable manufacturing practices supports the use of these composites, leading to increased investments in R&D. Industries transitioning to more eco-friendly alternatives contribute to the expansion of the thermoplastic matrix composites market, providing opportunities for innovation and product evolution.
Increased applications in sectors including wind energy and marine further indicate robust end-use dynamics. These sectors require materials that offer superior strength-to-weight ratios, making thermoplastic composites a preferred choice. Continuous evolution in design and application capabilities allows thermoplastic matrix composites to penetrate new markets, driving overall growth in the Composites market.
Valued at USD 10.4 billion in 2026, the Manual & Semi-Automated Prepreg Lay-Up segment is projected to reach USD 17.2 billion by 2033, reflecting a CAGR of 7.4% during the forecast period. Demand for this manufacturing process arises from its ability to produce high-quality composite components, which find extensive application in industries including aerospace, automotive, and industrial sectors. The trend towards lightweight and high-strength materials drives manufacturers to adopt this process, enhancing performance while reducing overall structural weight.
Technological maturation influences segment expansion. Advances in automation technology and process optimization have improved production efficiency and consistency, enabling manufacturers to meet rising demand. The introduction of next-generation materials and enhancements in prepreg formulations improve performance characteristics, stimulating adoption across various end-use industries.
Regulatory compliance with stringent safety and quality standards influences production practices within the segment. Manufacturers investing in certifications and quality assurance benefit from improved market competitiveness, gaining an edge over non-compliant competitors. The dynamics of the composites market demonstrate a notable shift towards adopting sustainable practices, further encouraging investment in this segment.
Pricing volatility in raw materials presents challenges, particularly driven by manufacturers striving to manage costs while maintaining quality. Fluctuations in the supply chain for key materials impact production margins and pricing strategies. Establishing robust supplier relationships and diversifying sourcing options enhances supply chain resilience, mitigating risks associated with raw material sourcing and logistics vulnerabilities.
Strategic opportunity windows arise from increasing investments in sectors including renewable energy and electric vehicles. These industries emphasize lightweight materials, driving demand for advanced composites manufactured through the Manual & Semi-Automated Prepreg Lay-Up process. The segment's growth trajectory aligns closely with broader trends in the composites market, highlighting the importance of ongoing innovation and adaptation to emerging market needs.
Resin Transfer Molding (RTM & HP-RTM) segment is estimated to reach USD 27.4 billion by 2033, at a CAGR of 9.8% during the forecast period. This growth results from increased demand for efficient manufacturing processes that enhance production speed and reduce waste. Industries including automotive and aerospace prioritize the benefits offered by RTM methods, including the ability to create complex shapes and achieve high-quality surface finishes. Technological advancements in RTM processes create opportunities for next-generation applications, pushing manufacturers to optimize their operations further.
Strong adoption of lightweight materials in various end-use sectors drives investment in RTM technologies. Strategies involving sustainable and efficient production align with evolving consumer preferences for environmentally friendly products. Regulatory compliance standards increasingly focus on reducing emissions and waste, further incentivizing manufacturers to adopt RTM solutions. Consequently, businesses experience cost efficiencies, improved product performance, and adaptability to changing market dynamics.
The RTM segment's growth trajectory reflects a shift in consumption patterns, emphasizing the need for advanced manufacturing techniques. With strategic investments in innovation and efficiency, the segment positions itself favorably within the broader Composites market. End-use dynamics reflect a growing reliance on RTM in high-performance applications, demonstrating the segment's relevance in meeting industry demands. While market drivers evolve, organizations leverage the advantages of RTM to enhance their competitive positioning.
Increasing adoption of the Vacuum Infusion manufacturing process demonstrates its efficiency in producing complex composite parts with high surface quality. This technique facilitates the infusion of resin into the dry fiber layup, significantly reducing labor costs and material waste, making it an attractive option for manufacturers. The automotive and aerospace industries, known for their demand for lightweight and high-strength materials, drive this adoption. Companies seek to enhance production efficiency while maintaining structural integrity, resulting in rising demand for Vacuum Infusion.
Technological advancements within the Vacuum Infusion segment play a crucial role in expanding capabilities. Innovations in resin formulations and infusion techniques enhance the speed and quality of production. The segment is expected to reach USD 20.6 billion by 2033, reflecting a commitment to continual improvements that align with end-use industry requirements. Manufacturers leverage these advancements to meet stringent regulatory compliance standards while addressing consumer preferences for sustainable and performance-driven products.
Supply chain resilience remains a focus in the Vacuum Infusion segment, particularly regarding raw material sourcing and logistics management. Ongoing assessment of raw material availability and pricing volatility influences manufacturers' operational strategies. Strategic partnerships with suppliers enhance supply chain stability, allowing players in the Composites market to navigate potential disruptions effectively. This proactive approach supports growth and ensures consistent product quality across various applications.
Strong growth in the Compression Molding (SMC & BMC) segment reflects rising demand for efficient manufacturing processes in the Composites market. This segment benefits from its ability to produce complex shapes with minimal waste, appealing to industries including automotive and aerospace, which prioritize lightweight materials to enhance performance and fuel efficiency.
Compression Molding (SMC & BMC) segment is projected to grow at a CAGR of 9.3% during the forecast period. This growth is fueled by advancements in material technology and increasing adoption of composites in high-performance applications. Manufacturers focus on optimizing production techniques, enhancing product quality and reducing costs, further driving expansion in this segment.
Demand for Compression Molding techniques correlates with the ongoing push for more sustainable manufacturing practices. The ability to recycle materials and reduce energy consumption aligns with regulatory compliance standards that emphasize environmental responsibility. This adherence to regulations strengthens market positioning for manufacturers employing Compression Molding processes.
Supply chain resilience emerges because a critical factor for the success of the Compression Molding segment. Manufacturers actively seek reliable raw material sources to mitigate risks associated with price volatility and ensure consistent production capabilities. Strategic investments in technology and partnerships enhance logistics efficiencies, positioning firms to capitalize on emerging opportunities in the market.
Overall, the Compression Molding (SMC & BMC) segment significantly contributes to the broader Composites market, supporting advancements in various end-use applications. The expected expansion reflects a strong alignment between market needs and technological capabilities, indicating robust opportunities for growth in the coming years.
Filament Winding technology is essential in the manufacturing of high-performance composite materials, particularly for applications requiring complex geometries and high strength-to-weight ratios. The increasing adoption of this technology results from its suitability for producing components in sectors including aerospace, automotive, and marine, where lightweight and durable materials are critical. End-use industries increasingly seek efficient manufacturing processes that minimize waste and reduce production times, driving interest in Filament Winding methods.
Technological maturation in Filament Winding techniques enhances production capabilities, allowing for improved customization and precision in composite structures. Innovations in automation and robotics within this manufacturing process lead to higher productivity levels and consistency in product quality. While industries evolve, the shift towards more sustainable practices influences demand for processes that optimize resource use, aligning with regulatory standards that embrace environmental considerations.
Consumption shifts towards advanced composite materials, propelled by their superior performance characteristics, create strategic opportunity windows for manufacturers employing Filament Winding. This segment of the Composites market benefits from the growing trend toward lightweight solutions in various applications, responding to increased pressure for energy efficiency and reduced emissions. Manufacturers leveraging advancements in Filament Winding technology position themselves to capture significant market share in the evolving landscape.
Raw material sourcing and supply chain resilience present additional factors influencing the Filament Winding segment. The complexity of securing high-quality raw materials, coupled with fluctuations in availability, impacts production schedules and costs. Manufacturers ensure a stable supply chain while balancing the demand for innovative composite solutions.
Cost structures and pricing volatility in the Composites market further affect the Filament Winding segment. Competitive pricing strategies become essential for manufacturers aiming to maintain margins amid rising raw material costs. The ongoing evolution of Filament Winding technologies and processes shapes the market, providing avenues for product evolution and greater efficiency in composite material applications.
Interest in the Pultrusion manufacturing process stems from its ability to produce continuous lengths of composite materials with consistent cross-sectional shapes. This method enhances production efficiency and reduces waste, aligning well with the industry's focus on sustainability and cost-effectiveness. The process finds extensive applications in various sectors, including construction, automotive, and aerospace, where high-performance materials are crucial.
Technological advancements play a significant role in the evolution of Pultrusion. Innovations in resin formulations and reinforcement techniques drive improvements in material performance and processing capabilities. These developments drive the growing demand for tailored composites, capable of meeting specific performance requirements across diverse end-use applications.
Regulatory compliance standards increasingly influence the adoption of Pultrusion. Industries including construction and automotive prioritize materials that meet stringent safety and environmental regulations. This environment creates opportunities for manufacturers to leverage Pultrusion technology to develop compliant composites that enhance product offerings and expand market reach.
Investment in Pultrusion technology presents strategic opportunities for companies within the Composites market. Industries continue to seek lightweight and durable materials, driving demand for Pultruded composites. This trend encourages manufacturers to explore innovative applications and expand their product portfolios, positioning them for sustained growth in the evolving market.
Supply chain resilience impacts the Pultrusion process, particularly regarding raw material sourcing. Reliable access to high-quality fibers and resins remains critical for ensuring consistent production. Manufacturers focusing on establishing strong relationships with suppliers mitigate risks related to material shortages or fluctuations in pricing, thereby maintaining competitive advantage within the market.
Interest in the Injection Molding Process within the Composites market arises from its efficiency and ability to create complex shapes with minimal waste. Primary demand drivers include the growing need for custom parts across various industries, particularly in automotive and consumer goods. Enhanced production speed and lower labor costs contribute to its increasing adoption, allowing manufacturers to meet rising consumer expectations for rapid delivery of high-quality products.
Segment expansion benefits from advancements in material science, enabling the use of engineered thermoplastics that improve mechanical properties and thermal stability. Innovations in injection molding technology, including multi-material injection and in-mold assembly, drive product evolution, allowing for more intricate designs and improved functional performance. These developments appeal to end-use industries prioritizing lightweight and durable components, further boosting demand.
Consumption shifts toward sustainable practices influence the Injection Molding Process segment, with manufacturers exploring bio-based and recyclable materials. Regulatory compliance standards push firms to adopt more environmentally friendly production methods, aligning with global sustainability goals. This transition creates opportunities for companies innovating in material sourcing and production techniques, positioning them favorably in the evolving market.
Strategic investments in infrastructure for the Injection Molding Process enhance supply chain resilience by ensuring reliable access to high-quality raw materials. Challenges related to pricing volatility and margin pressures persist, driven by fluctuations in raw material costs and increasing competition. Addressing these risks requires a focus on cost-effective production methods and enhanced operational efficiencies, providing a clear pathway for future growth in the Composites market.
Market dynamics for the Hand Lay-Up & Spray-Up manufacturing process reflect a strong emphasis on customizable solutions and versatility in production. This process finds significant adoption in industries that prioritize flexibility and the ability to create complex geometries. Increasing demand for lightweight and durable materials in sectors including aerospace and automotive fuels growth in this segment.
Technological maturation enhances the efficiency of the Hand Lay-Up & Spray-Up process, with advancements leading to improved material performance and reduced production time. The evolution of product designs in end-use applications contributes to a shift toward more innovative composite solutions, enabling manufacturers to meet diverse customer requirements.
Regulatory compliance standards impacting the composites market encourage manufacturers to adopt eco-friendly practices, driving innovation in materials and processes. Increased focus on sustainability prompts investments in research and development, facilitating next-generation upgrades that further optimize the Hand Lay-Up & Spray-Up technique.
Challenges related to cost structures and pricing volatility influence market dynamics, because suppliers navigate fluctuating raw material prices. Strategic opportunity windows arise from balancing quality, cost, and production efficiency, enhancing supply chain resilience within this segment. Continued investment in this manufacturing process strengthens its position in the broader composites market, addressing both current and future demands.
Innovative manufacturing techniques including Braiding, Bladder Molding, and Additive Composite Manufacturing provide distinct advantages in flexibility and customization within the Composites market. These methods support the production of complex geometries and lightweight structures, which are increasingly demanded across various industries, including aerospace and automotive. Technological maturation in these processes has led to enhanced product quality and reduced waste, aligning with sustainability objectives in manufacturing practices.
Adoption of these techniques receives impetus from the rising need for efficiency and performance in end-use applications. Industries focused on high-performance components are particularly inclined toward these manufacturing processes, given their ability to improve mechanical properties and reduce overall weight. This strategic alignment with performance requirements drives further segment expansion, propelling investment in research and development to refine methods and outputs.
Regulatory compliance standards drive innovation in manufacturing, influencing the choice of processes based on environmental impact and material properties. Certifications related to safety and performance standards become critical, particularly in sectors including aerospace and defense. These dynamics shape consumption shifts, with manufacturers prioritizing processes that offer both compliance and performance benefits.
Cost structures within the segment evolve due to the integration of advanced technologies that improve efficiency. Pricing volatility reflects fluctuations in raw material sourcing and production costs, impacting margins and competitive positioning. Strategic opportunity windows emerge owing to manufacturers seeking to differentiate their offerings through unique manufacturing capabilities, enhancing overall market competitiveness.
Supply chain resilience ensures consistent raw material availability, critical for sustaining production levels. Any disruptions within the logistics framework significantly affect the adoption of these advanced manufacturing processes. Thus, firms operating in this segment focus on establishing robust supply chains to mitigate risks associated with sourcing and production.
Disruptive alternatives within traditional manufacturing processes challenge existing methods, encouraging innovation and adaptation. The potential for technological obsolescence requires ongoing investment in next-generation upgrades and continuous improvement. The landscape of the Composites market increasingly prioritizes these innovative processes, positioning them because key drivers of future growth and competitiveness.
Commercial Aerospace & Space segment is valued at USD 20.7 billion in 2026 and is projected to reach USD 39.5 billion by 2033, at a CAGR of 9.7% during the forecast period. Demand for composite materials in this segment stems from the aerospace industry's need for lightweight, high-strength materials that enhance fuel efficiency while maintaining safety standards. Technological advancements drive the adoption of composites, particularly carbon and glass fibers, due to their superior mechanical properties and corrosion resistance. Key manufacturers focus on next-generation upgrades and product evolution, developing new applications in aircraft components, including fuselage and wing structures.
Investment in research and development drives innovation in composite technologies, further propelling the segment's growth. Regulatory compliance standards and certifications enhance product reliability, aligning with the increasing focus on environmental sustainability within the aerospace sector. Price volatility in raw materials, including carbon fiber, poses challenges, influencing overall cost structures and profit margins. Nevertheless, demand for advanced composite solutions remains robust, driven by growth in commercial air travel and the need for fuel-efficient aircraft. The dynamics of the Composites market indicate a promising future, with strategic opportunity windows emerging because manufacturers adapt to evolving market conditions.
Growth within the Defense & Military Systems segment is driven by increasing demand for advanced materials that enhance the performance and durability of military equipment. Technological advancements in composite materials, including improved strength-to-weight ratios and resistance to environmental factors, enable more effective designs for defense applications. Military organizations worldwide prioritize innovation and efficiency in operations, leading to higher adoption rates of composites that align with these objectives.
The segment is projected to reach USD 16 billion by 2033, growing at a CAGR of 9.5% during the forecast period. Regulatory compliance and certifications specific to defense standards increase the need for high-quality composite products, influencing procurement strategies within defense contractors. Consequently, the market for composites benefits from investments in next-generation defense technologies and modernization initiatives across various military sectors.
Strategic opportunities arise from the evolving nature of warfare, which emphasizes lightweight, durable materials that enhance overall operational effectiveness. Increased defense budgets globally contribute to expanding the market. Governments seek to upgrade existing military capabilities with advanced composite solutions that support a range of applications, including aircraft, naval vessels, and personal protective equipment.
Demand for composites within the passenger and commercial automotive sector reflects a significant transition toward lightweight materials that enhance fuel efficiency and performance. Innovations in automotive design increasingly emphasize the need for materials that provide both strength and reduced weight, driving the adoption of composites. This shift aligns with broader industry trends focused on sustainability and regulatory compliance, including emissions standards that pressure manufacturers to produce more fuel-efficient vehicles.
Investment in advanced composite materials signifies a commitment to technological maturation and next-generation upgrades in the automotive space. Manufacturers increasingly leverage carbon fiber and thermoplastic matrix composites, both known for their high strength-to-weight ratio. The anticipated growth within this segment is expected to reach USD 49.9 billion by 2033, highlighting the potential for revenue generation driven by technological advancements and evolving consumer demands for more efficient vehicles.
The market experiences shifts in consumption patterns resulting from consumers prioritizing environmentally friendly options. The emergence of electric vehicles (EVs) plays a key role in enhancing demand for composite materials, because these vehicles benefit significantly from weight reduction to improve range and efficiency. Regulatory compliance standards further accelerate adoption because manufacturers pursue materials that meet stringent environmental criteria.
The integration of composites into passenger and commercial vehicles offers strategic opportunity windows. Players in the market position themselves to exploit these advancements by developing innovative products that address both performance needs and regulatory requirements. Continued investment in the passenger and commercial automotive market, supported by a strong focus on sustainability, ensures that this segment remains a critical area for growth within the composites market.
Significant advancements in materials and manufacturing processes drive demand in the Motorsport & Racing segment. This segment is projected to grow at a CAGR of 9.6% during the forecast period. Enhanced performance requirements from racing teams and manufacturers necessitate lightweight yet durable materials, prompting a shift towards advanced composites. Technological maturation in composite production methods, particularly in carbon fiber and thermoplastic composites, supports this trend.
Investment in high-performance vehicles and motorsport technology fuels the segment's expansion. Automotive manufacturers increasingly explore composites to improve speed and efficiency, leading to higher adoption rates among racing teams. The demand for innovative solutions that enhance vehicle performance and safety influences the market's trajectory.
Regulatory compliance and racing standards influence material selection and usage, pushing manufacturers towards advanced composites that meet stringent safety requirements. Cost structures associated with raw materials and production techniques shape pricing strategies, affecting profit margins across the value chain. Stakeholders pursue strategic opportunities within this dynamic segment, focusing on product evolution and next-generation upgrades to maintain a competitive position in the market.
Growing interest in renewable energy sources drives significant demand for composites within the Wind Energy segment. The shift towards sustainable solutions prompts manufacturers to seek lightweight, durable materials to enhance the efficiency and longevity of wind turbine components. Advances in composite materials support this trend, allowing for larger and more efficient turbine blades that contribute to enhanced energy production capabilities.
Technological maturation within the composites market facilitates the introduction of next-generation materials specifically designed for wind energy applications. Innovations in resin formulations and fiber types lead to improved fatigue resistance and strength, which are crucial for enduring harsh environmental conditions. The ongoing evolution of product offerings aligns with the demands of the wind energy sector, reflecting a commitment to sustainability and performance.
Downstream applications for composites in wind energy highlight the industry's transition towards larger and more powerful turbines. Enhanced performance characteristics of composite materials influence consumption patterns, driven by energy producers opting for high-quality, reliable solutions. Regulatory compliance standards further reinforce the adoption of composite materials, with an increasing emphasis on environmental performance and lifecycle assessment.
Amid rising cost structures and potential pricing volatility, manufacturers face margin pressures, influencing strategic sourcing decisions. Supply chain resilience remains a critical focus, because firms navigate raw material sourcing challenges and address vulnerabilities in logistics. Strategic opportunity windows arise from disruptions in traditional material markets, prompting exploration of alternative composites and innovative solutions.
Investment outlooks reflect an optimistic trajectory for the Wind Energy segment. Capital investments target advancements in composite production techniques and technologies, aligning with the broader shift towards renewable energy. While the demand for environmentally responsible solutions continues to rise, the composites market plays a critical role in shaping the future of wind energy applications.
Demand in the Marine segment of the Composites market stems from the need for lightweight, durable materials that enhance fuel efficiency and reduce emissions in marine vessels. Increased focus on sustainability drives manufacturers to adopt composite materials, which offer resistance to corrosion and lower maintenance costs compared to traditional materials.
Adoption of advanced composite manufacturing techniques enables enhanced performance characteristics in marine applications. Innovations including resin transfer molding and vacuum infusion contribute to producing stronger, lighter structures, which further attract investment in this segment. This trend reflects a broader movement toward optimizing vessel designs for improved efficiency and environmental compliance.
End-use dynamics emphasize the shift toward composite materials in recreational and commercial boating, where performance and longevity are essential. Integration of composites into marine designs supports enhanced structural integrity and reduces overall weight, contributing to improved speed and fuel economy.
Regulatory compliance standards increasingly favor eco-friendly materials, pushing companies to explore composite options that align with environmental regulations. These developments create a strategic opportunity window for manufacturers and suppliers within the market, enhancing their competitive positioning in an evolving regulatory landscape.
Capital investment outlook remains positive, driven by ongoing research and development in composite materials. Focus on next-generation upgrades continues to shape product evolution, leading to innovative solutions that address shifting consumer preferences and regulatory demands.
Market demand within the Sporting Goods & Recreation sub-segment relies on various factors, including a growing emphasis on lightweight materials that enhance performance in sports equipment. Increased consumer awareness regarding health and fitness contributes to higher participation in recreational activities, further driving demand for advanced composite materials. Manufacturers and consumers seek improved durability and performance in products including bicycles, tennis rackets, and fishing rods, enhancing overall user experience.
Technological maturation within the composites sector enables the development of next-generation sporting goods that integrate advanced materials like carbon fiber and aramid fibers. These innovations provide superior strength-to-weight ratios, leading to enhanced performance and competitive advantages. The evolution of product features focuses on sustainability, with eco-friendly composites gaining traction, appealing to environmentally conscious consumers seeking greener alternatives.
Shifts in consumption patterns reflect a growing preference for high-performance sports equipment, leading to increased investment in research and development for composite materials that meet consumer expectations. Regulatory compliance standards surrounding material safety and environmental impact influence product development strategies. Manufacturers adopt certifications that validate their products, ensuring safety and performance criteria are met in the marketplace.
Market participants face ongoing pressures related to cost structures and pricing volatility, affecting margins within the sporting goods sector. Supply chain resilience remains crucial, particularly in raw material sourcing, where fluctuations pose risks to production timelines and costs. Competition drives continuous innovation, with firms exploring disruptive alternatives to traditional materials, enhancing the composite offerings available in the market.
Strategic opportunity windows arise in addressing emerging trends within the Sporting Goods & Recreation market, including the incorporation of smart technologies and wearable devices that utilize composite materials. Investments in these areas signal a commitment to maintaining relevance and competitiveness in an evolving landscape. Comprehensive analyses of white-space opportunities will inform future capital investments, supporting the sustained growth of the composites market.
Technological advancements in the Electrical & Electronics segment of the Composites market influence demand significantly. The push for lighter, more durable components aligns with trends in consumer electronics and renewable energy systems, creating opportunities for composite materials that provide both strength and weight savings. Innovations in production techniques, including enhanced molding processes and improved fiber-reinforcement methods, enable manufacturers to produce advanced materials that meet the evolving requirements of this segment.
Adoption within the Electrical & Electronics sector relies heavily on performance requirements including thermal stability, electrical insulation, and mechanical integrity. These properties drive the specification of composites in products ranging from printed circuit boards to structural components in high-performance devices. Regulatory compliance and certification standards shape product development timelines and market entry strategies.
Investment in research and development remains critical for sustaining competition within the Electrical & Electronics segment. Companies focus on next-generation upgrades that incorporate smart technologies and sustainable materials to enhance product offerings. This focus on innovation creates a robust pipeline of new applications, positioning companies within the market to address shifting consumer preferences toward environmentally friendly and energy-efficient products.
Supply chain resilience becomes increasingly important in the context of raw material sourcing, particularly for specialized fibers and resins. The segment faces challenges related to pricing volatility and margin pressures, prompting manufacturers to explore alternative sources and materials that mitigate risks associated with supply disruptions. Strategic opportunity windows arise for companies investing in diversifying their material inputs and enhancing their production flexibility.
Growing investment in infrastructure projects drives demand for composites within the Industrial & Infrastructure sub-segment. Composites offer strong strength-to-weight ratios and durability, making them suitable for applications including bridges, buildings, and roads. Increasing urbanization and the need for sustainable construction solutions enhance the attractiveness of composites, aligning with global trends towards lightweight and energy-efficient designs.
Technological maturation within the composites sector facilitates the development of advanced materials that fulfill stringent regulatory compliance standards. Innovations in resin formulations and fiber technologies contribute to extending the lifecycle of infrastructure components, reducing maintenance costs, and improving overall performance. Strong interest from construction and civil engineering professionals seeking to incorporate high-performance materials into their projects drives market dynamics.
Strategic opportunity windows arise through enhanced collaboration among stakeholders, including manufacturers, contractors, and regulatory bodies. This collective effort promotes knowledge sharing, enabling the integration of composites into traditional construction practices. Rising awareness of environmental considerations influences consumption shifts, encouraging the adoption of sustainable materials that minimize ecological footprints.
Cost structures within the market reflect ongoing advancements in manufacturing processes, which promote efficiency and reduce waste. Pricing volatility challenges stakeholders to explore flexible sourcing strategies that ensure raw material availability without compromising quality. The emergence of disruptive alternatives highlights the need for ongoing innovation, compelling industry players to invest in research and development to maintain competitive advantages.
Maintaining supply chain resilience becomes crucial in the face of potential logistics vulnerabilities and fluctuating raw material prices. Building strategic partnerships with suppliers enhances stability and supports mutual growth, essential for navigating a dynamic market. The combination of factors influences the long-term growth trajectory of the composites market within the Industrial & Infrastructure segment.
Interest in the "Others" sub-segment, encompassing rail, medical, and oil and gas applications, stems from the growing need for lightweight and durable materials that offer specific advantages over traditional materials. The adoption of composites within these industries aligns with stringent regulatory compliance standards, which emphasize safety and performance in critical applications. Innovations in composite materials provide enhanced structural integrity, corrosion resistance, and reduced maintenance costs, thereby enabling their integration into more demanding environments.
Technological maturation supports the expansion of this segment. Advances in manufacturing processes enable the production of composites with superior properties, catering to specialized applications in rail, medical, and oil and gas sectors. For instance, medical devices benefit from biocompatible materials, while the rail industry leverages lightweight composites to improve fuel efficiency and performance. In oil and gas, composites contribute to safer and more efficient operations through enhanced durability and resistance to harsh environmental conditions.
Downstream applications continue to shape demand in the market. In rail, the move towards lightweight trains drives the need for composites that enhance energy efficiency and overall performance. In the medical industry, the demand for advanced equipment and devices necessitates materials that meet rigorous safety standards while offering superior performance. The oil and gas sector's focus on sustainable practices further highlights the importance of composites that reduce environmental impact while maintaining operational efficiency.
Consumption shifts reflect an increasing preference for composites in these end-use industries. This trend aligns with the broader movement towards sustainability and efficiency, prompting manufacturers to explore innovative materials that meet the evolving demands of their respective sectors. Strategic opportunity windows emerge due to companies seeking to capitalize on the benefits of composites, driving further investment in research and development to enhance product capabilities.
Based on geography, the Global Composites market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America accounts for 24.6% of the global Composites market in 2025. A combination of factors drives market dynamics, including increasing demand in the Commercial Aerospace and Space segment, projected to grow from USD 20.7 billion in 2026 to USD 39.5 billion by the end of 2033. The region's strong manufacturing base, particularly in the United States, Canada, and Mexico, supports robust production capabilities and enhances competitiveness.
The ongoing modernization of infrastructure contributes to an expanding market, fueling demand across various applications within the composites sector. Strategies including nearshoring and localized manufacturing strengthen supply chain resilience while enabling quicker responses to changing market requirements. The presence of established domestic players further enhances market stability, facilitating collaboration on innovative solutions and technology advancements.
Investment in research and development remains strong, enabling companies to explore new composite materials and applications. Factors including energy grid resiliency and resource availability in North America enhance operational efficiencies. The forecasted CAGR of 8.4% for the Composites market during the upcoming years indicates continued growth, with a projected market size of USD 50.6 billion by the end of 2033.
The Composites market in Europe exhibits diverse dynamics influenced by regional demand drivers, technological advancements, and specific industry requirements. Countries including Germany, France, and the UK play important roles within the market, contributing to substantial shares of the regional revenue. Increasing investments in aerospace and automotive sectors underline the significance of advanced composites, particularly in high-performance applications.
Germany, recognized for its strong industrial base, shows robust demand for carbon fiber composites, driven by the automotive industry's push for lightweight materials. France and the UK leverage similar trends by focusing on enhancing fuel efficiency and sustainability in transport. Spain and Italy capitalize on rising trends in renewable energy projects that involve composite materials.
Russia represents an emerging market within Europe, with potential growth in defense and military systems, reflecting the strategic importance of advanced materials in national security applications. The Rest of Europe sector demonstrates varying levels of development, where localized approaches to manufacturing and procurement strategies gain traction.
Competitive landscapes across Europe display an array of domestic market participants, emphasizing localized procurement dynamics and tailored offerings. The growing emphasis on high-value replacement cycles in established industries promotes incremental growth in the market. Enhanced cross-border trade corridors and regional supply chain efficiencies facilitate the sharing of innovations and best practices across the continent.
Overall, the Composites market in Europe outlines a landscape of opportunity, driven by a blend of technological advancements, sector-specific demands, and a commitment to sustainability in manufacturing processes.
Asia-Pacific accounts for 45.0% of the global Composites market in 2025. Strong economic growth in countries including China, India, and South Korea drives an increase in demand across multiple sectors, including aerospace, automotive, and construction. The presence of established manufacturing bases and advancements in production technologies enhance the region's competitive edge, enabling local players to meet both domestic and export demand effectively.
Emerging market front-runners like China and India drive substantial investments in infrastructure modernization, supporting the adoption of composites in construction and transportation. The region benefits from a robust supply chain network, facilitating localized manufacturing and decreasing dependency on imports. Cross-border trade corridors improve the movement of materials and finished goods, creating a more integrated market environment.
Cultural nuances influence B2B buying behaviors, with regional companies increasingly prioritizing high-performance materials that align with sustainability initiatives. The competitive landscape features domestic market participants that innovate and expand their offerings, enhancing overall market growth. Foreign direct investment flows into the region signal confidence in its potential, further driving the market's expansion.
While demand for composites continues to rise in Asia-Pacific, the sector experiences high-value replacement cycles, particularly in mature industries. Incremental growth vectors across various end-use applications contribute to a diversified market landscape, positioning the region for sustained development in the coming years. This trend indicates a promising outlook for the composites market in Asia-Pacific.
In South America, the Composites market presents unique opportunities driven by increasing investments in infrastructure and construction, particularly in Brazil and Argentina. The economic landscape in these countries supports the adoption of innovative materials, enhancing performance in various applications including transportation, construction, and energy. Brazil's expanding automotive and aerospace sectors significantly contribute to market growth, with both local and international companies increasing their focus on composite materials to improve efficiency and reduce weight in vehicle designs.
Argentina demonstrates its potential through rising demand for advanced materials in the defense and military sectors. The market benefits from ongoing modernization initiatives, which create a favorable environment for the introduction of composite solutions. Localized manufacturing efforts gain traction, allowing for enhanced supply chain dynamics and reduced lead times. The Rest of South America exhibits gradual growth in composite adoption, driven by regional infrastructure projects and increasing awareness of the benefits of lightweight materials.
The regional competitive landscape features both domestic players and international entrants, creating a diverse ecosystem. Vendors prioritize collaboration with local manufacturers to meet specific market needs while navigating regulatory frameworks that impact material usage and safety standards. Overall, the Composites market in South America is projected to experience incremental growth, supported by strategic investments, an evolving competitive environment, and a focus on high-performance materials across various sectors.
The Composites market in the Middle East and Africa demonstrates unique characteristics driven by regional demand dynamics. Countries like Saudi Arabia and the UAE focus on infrastructure modernization and energy diversification, significantly influencing the adoption of composite materials. South Africa's robust manufacturing sector benefits from composite applications in various industries, including automotive and aerospace, creating a favorable environment for market growth.
Investment in local manufacturing capabilities supports the market, while geopolitical factors encourage cross-border collaborations and trade. Regional vendors focus on meeting local compliance mandates and leveraging domestic resource availability to enhance competitive positioning. Emerging market participants in the region capitalize on high-value replacement cycles and incremental growth vectors, contributing to an anticipated increase in market share.
The market benefits from incremental growth opportunities tied to localized procurement dynamics and cultural nuances influencing B2B buying behaviors. The region's composites landscape is positioned for expansion, driven by strategic entry barriers and foreign direct investment flows.
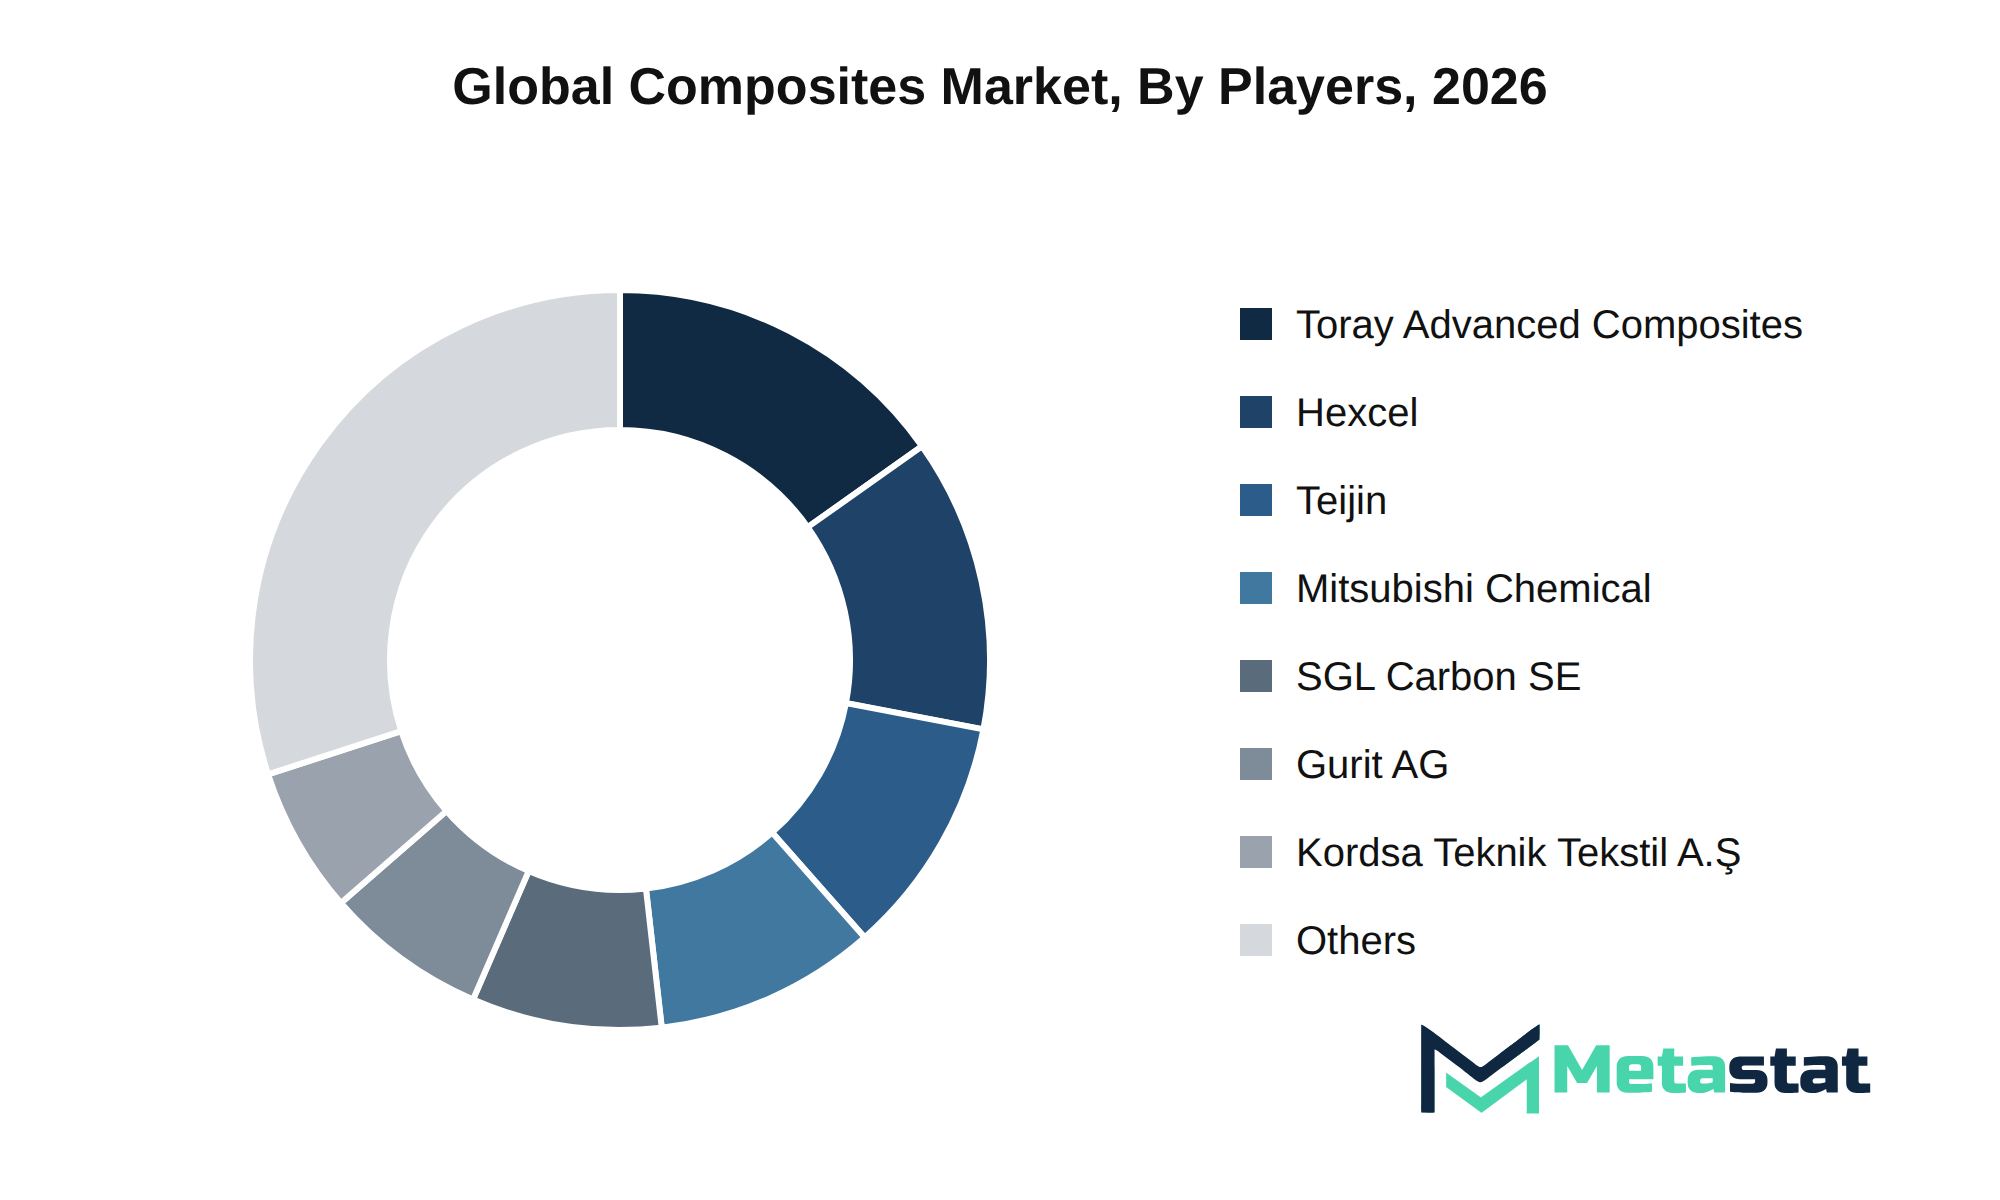
The competitive landscape of the Composites market reflects a dynamic interaction of strategic behaviors and market positioning among key players. Companies engage in a variety of tactics, including mergers, acquisitions, and strategic consolidation efforts, to enhance their market presence and operational efficiencies. For instance, significant players pursue joint ventures and strategic alliances to leverage complementary strengths and drive innovation. This collaborative approach facilitates access to proprietary technologies and expands product offerings, which strengthens competitiveness.
Pricing architectures and commercial models play a crucial role in shaping market dynamics. Players, including Toray Advanced Composites and Hexcel Corporation, adopt differentiated pricing strategies to cater to diverse customer segments. The establishment of strong intellectual property portfolios enhances technological defensibility, while ongoing R&D pipelines ensure that these companies remain leaders in innovation in the market. The threat of new entrants remains pertinent, driven by emerging startups that introduce disruptive technologies that challenge established companies, especially in niche sectors.
Value chain integration and supply chain dominance are vital components of competitive strategy. Companies including BASF SE and DuPont de Nemours Inc. leverage procurement leverage to optimize costs and enhance customer retention strategies. By driving brand equity dynamics, these players maintain customer loyalty and reduce switching costs, which strengthens their market positions. The future competitive outlook for the Composites market indicates a continued emphasis on strategic growth vectors, driven by technological advancements and evolving customer needs.
Market size is forecast to rise from USD 112.5 billion in 2025 to over USD 214.5 billion by 2033. The base case scenario indicates a compound annual growth rate (CAGR) of 8.4%, reflecting steady expansion driven by several macroeconomic factors. The evolving geopolitical landscape and shifting trade corridors influence supply chain dynamics, impacting the Composites market and downstream demand.
In a bull case scenario, robust investment in next-generation technologies and strategic capital allocation could lead to accelerated growth. Under a bear case scenario, economic downturns or regulatory challenges could slow growth; however, underlying demand for composites across various industries remains strong.
Core industry maturation, including advancements in R&D and commercialization timelines, supports competitive positioning for companies in the market. Regulatory evolution, alongside imminent compliance milestones, shapes operational frameworks and influences market strategies. Companies that adapt to these changes effectively enhance their market presence.
Emerging white-space opportunities and unmet enterprise needs represent high-growth pockets within the market. These areas require thorough exploration and investment to capture potential. Strategic imperatives will guide firms in navigating these complexities, focusing on defensibility roadmaps and long-term growth recommendations.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Composites market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 8.4% from 2026 to 2033 |
Revenue Unit | USD billion |
Segmentation | By Fiber Type, Resin Type, Manufacturing Process, End-Use Industry, and Region |
By Region | North America (By Fiber Type, Resin Type, Manufacturing Process, End-Use Industry, and Country)
|
Europe (By Fiber Type, Resin Type, Manufacturing Process, End-Use Industry, and Country)
| |
Asia Pacific (By Fiber Type, Resin Type, Manufacturing Process, End-Use Industry, and Country)
| |
South America (By Fiber Type, Resin Type, Manufacturing Process, End-Use Industry, and Country)
| |
Middle East and Africa (By Fiber Type, Resin Type, Manufacturing Process, End-Use Industry, and Country)
|
Find answers to common questions about this report
The Composites market size was valued at USD 112.5 billion in 2025.
The Composites market is projected to grow at a CAGR of 8.4% during the forecast period from 2026 to 2033.
The North America Composites market size is estimated to reach USD 50.6 billion by 2033.
The Carbon Fiber Composites segment leads the Composites market with a projected value of USD 89.9 billion by 2033, reflecting a compound annual growth rate of 9.4%. This growth positions it ahead of other fiber types in the market.
Economic growth across various regions drives the Composites market, because rising GDP stimulates capital investments in sectors including automotive, aerospace, and construction. Increased demand for lightweight and sustainable materials, coupled with digital transformation initiatives, further enhances operational efficiency and product quality, supporting market expansion.
Asia Pacific holds the dominant share of the Composites market, accounting for 45 percent in 2025. This region surpasses others, including North America at 24.6 percent and Europe at 20.7 percent.
Strict regulatory compliance requirements and macroeconomic headwinds, including inflation and supply chain disruptions, significantly restrain growth in the Composites market. Rising operational costs, sourcing challenges, and geopolitical instability create barriers to investment and innovation, limiting market expansion and competitiveness.
Economic growth across various regions, coupled with rising demand for lightweight and sustainable materials, significantly favors product adoption in the Composites market. Industries including automotive, aerospace, and construction increasingly prioritize advanced composite solutions to enhance performance and reduce emissions, aligning with evolving consumer preferences for environmentally friendly products.
The Composites market is estimated to reach a valuation of USD 214.5 billion by 2033.
Key players operating in the Composites market include Toray Advanced Composites, Hexcel Corporation, Teijin Limited, Mitsubishi Chemical Corporation, SGL Carbon SE, Gurit Holding AG, and Owens Corning.
Choose Your License
Global Composites Market
The analysts below cover Chemicals and Materials research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
INDUSTRY CONSULTANT - CHEMICALS & ADVANCED MATERIALS
Chemicals and Materials · Machinery & Equipment · Packaging
Amit Gadhekar Consultant for Chemicals and Materials at MetaStat Insight, directing sector-specific intelligence, research, and strategic consulting across global chemical and processing markets.
Tracking capacity expansion in single-use bioprocessing requires dependable data on raw material availability and cleanroom-grade polymer supply chains. The competitive landscape chapter gave a grounded evaluation of secondary component suppliers across North America and Asia-Pacific rather than simply reprinting press releases. Having that level of supplier benchmarking helped clarify dual-sourcing considerations for our clinical pipeline planning.
When evaluating distributed energy resource management systems, standard research summaries tend to gloss over the operational differences between front-of-the-meter utility deployments and behind-the-meter industrial sites. The MetaStat Insight report addressed those distinctions directly, especially regarding software interoperability standards and grid interconnection backlogs. The five-year market sizing across regional transmission organizations provided actionable context for our grid modernization strategy.
Most industry reports on warehouse automation bundle autonomous mobile robots and fixed conveyor installations into the same top-level numbers, which complicates advisory work. This study split the market cleanly by payload tiers, navigation technology, and fleet management software layers. The regional forecast for Western Europe gave our team defensible adoption benchmarks when evaluating capital allocation for logistics clients, saving us days of secondary data scrubbing.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950