
LEAD ANALYST

Global ISO Tank Container Market Size, Share, By Tank Type (Standard Liquid Tank Containers, Gas Tank Containers, Cryogenic Tank Containers, Food-Grade Tank Containers, Lined Tank Containers, Heated Tank Containers, and Others), By Capacity (Up to 10,000 Liters, 10,001-20,000 Liters, 20,001-26,000 Liters, and Above 26,000 Liters), By End-Use Industry (Chemicals, Petrochemicals, Industrial Gases, Food & Beverage, Pharmaceuticals, Oil & Gas, Energy & LNG, Mining & Metals, Environmental & Waste Management, and Others), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-4896
August 11, 2026
Updated
280 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
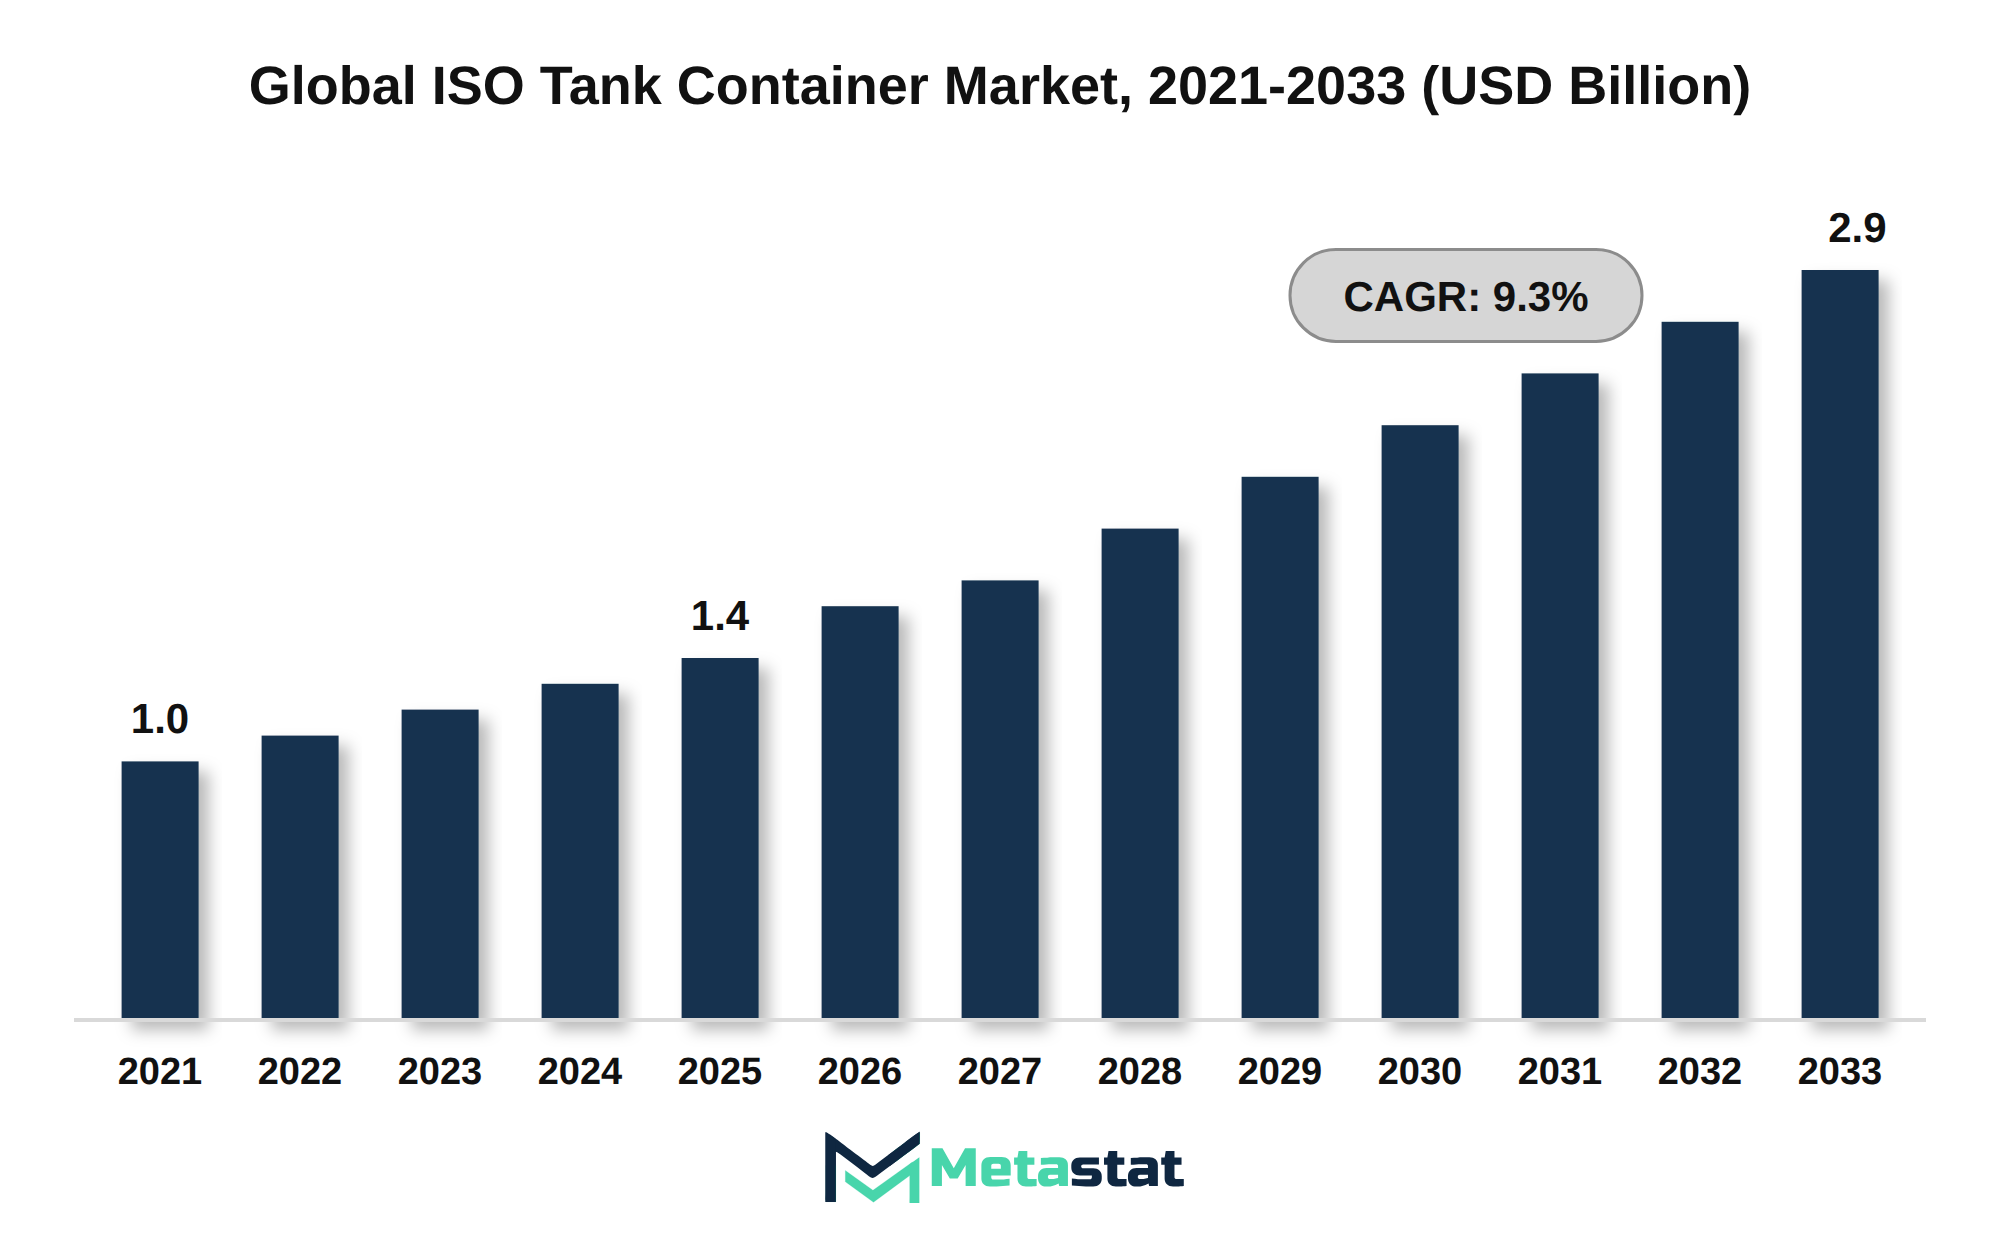
The global ISO Tank Container market was valued at USD 1.4 billion in 2025 and is projected to reach USD 2.9 billion by 2033, growing at a CAGR of 9.3% over the forecast period.
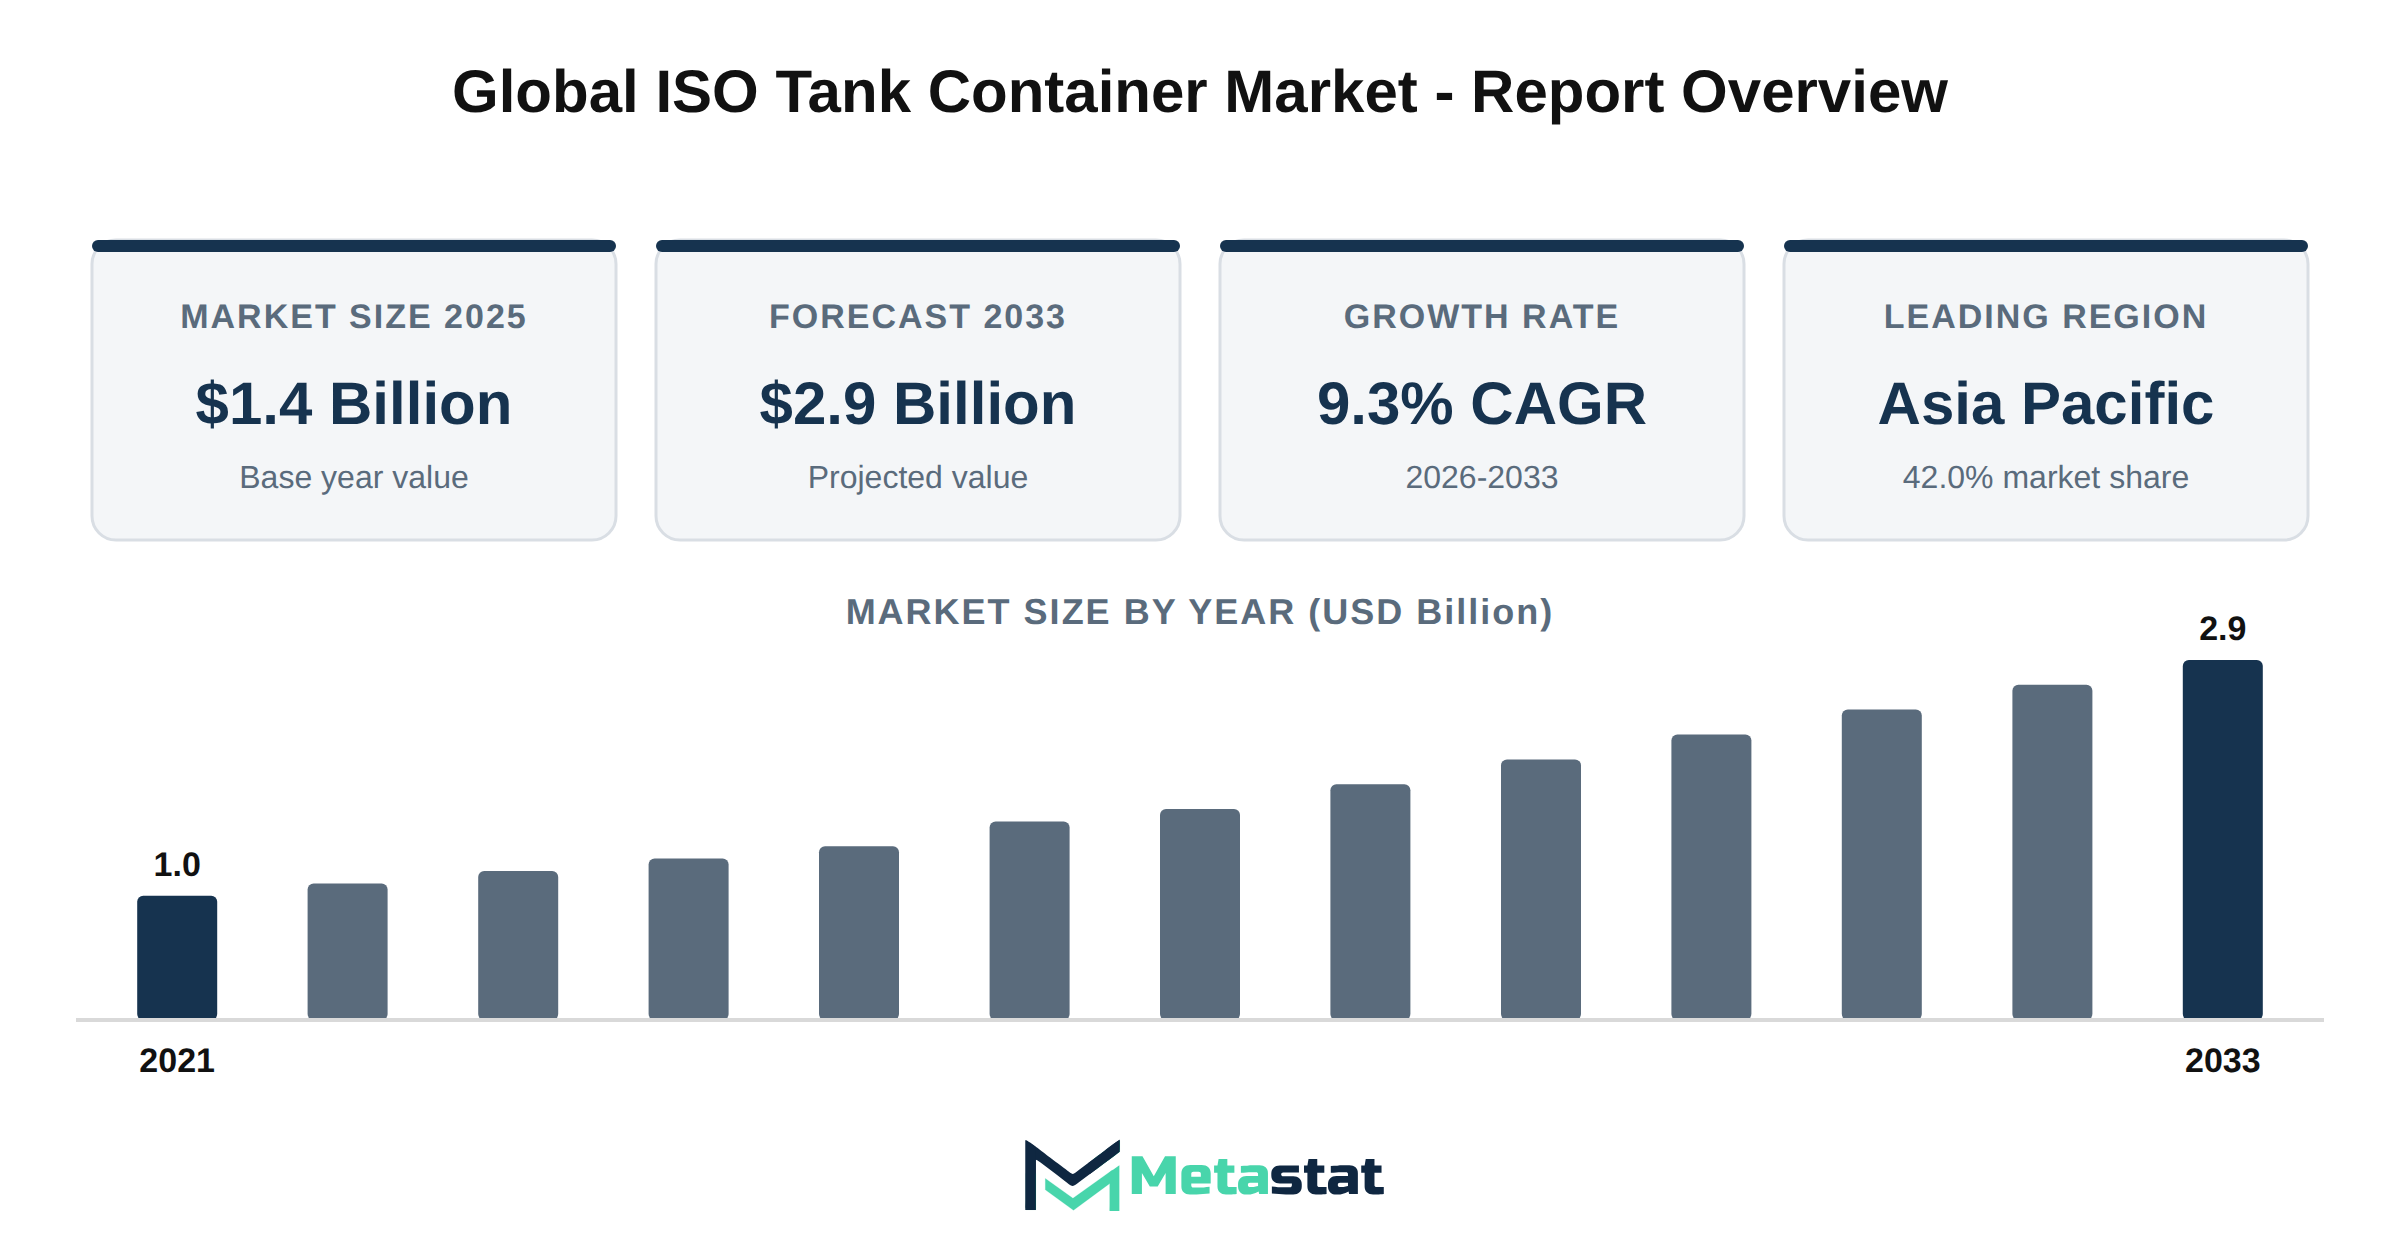
The ISO Tank Container market reached a value of USD 1.4 billion in 2025 and is projected to grow significantly, with an estimated value of USD 2.9 billion by 2033. This growth reflects a compound annual growth rate (CAGR) of 9.3% during the forecast period from 2026 to 2033. Historical data indicates steady growth, with the market valued at USD 1 billion in 2021 and increasing progressively to USD 1.3 billion in 2024.
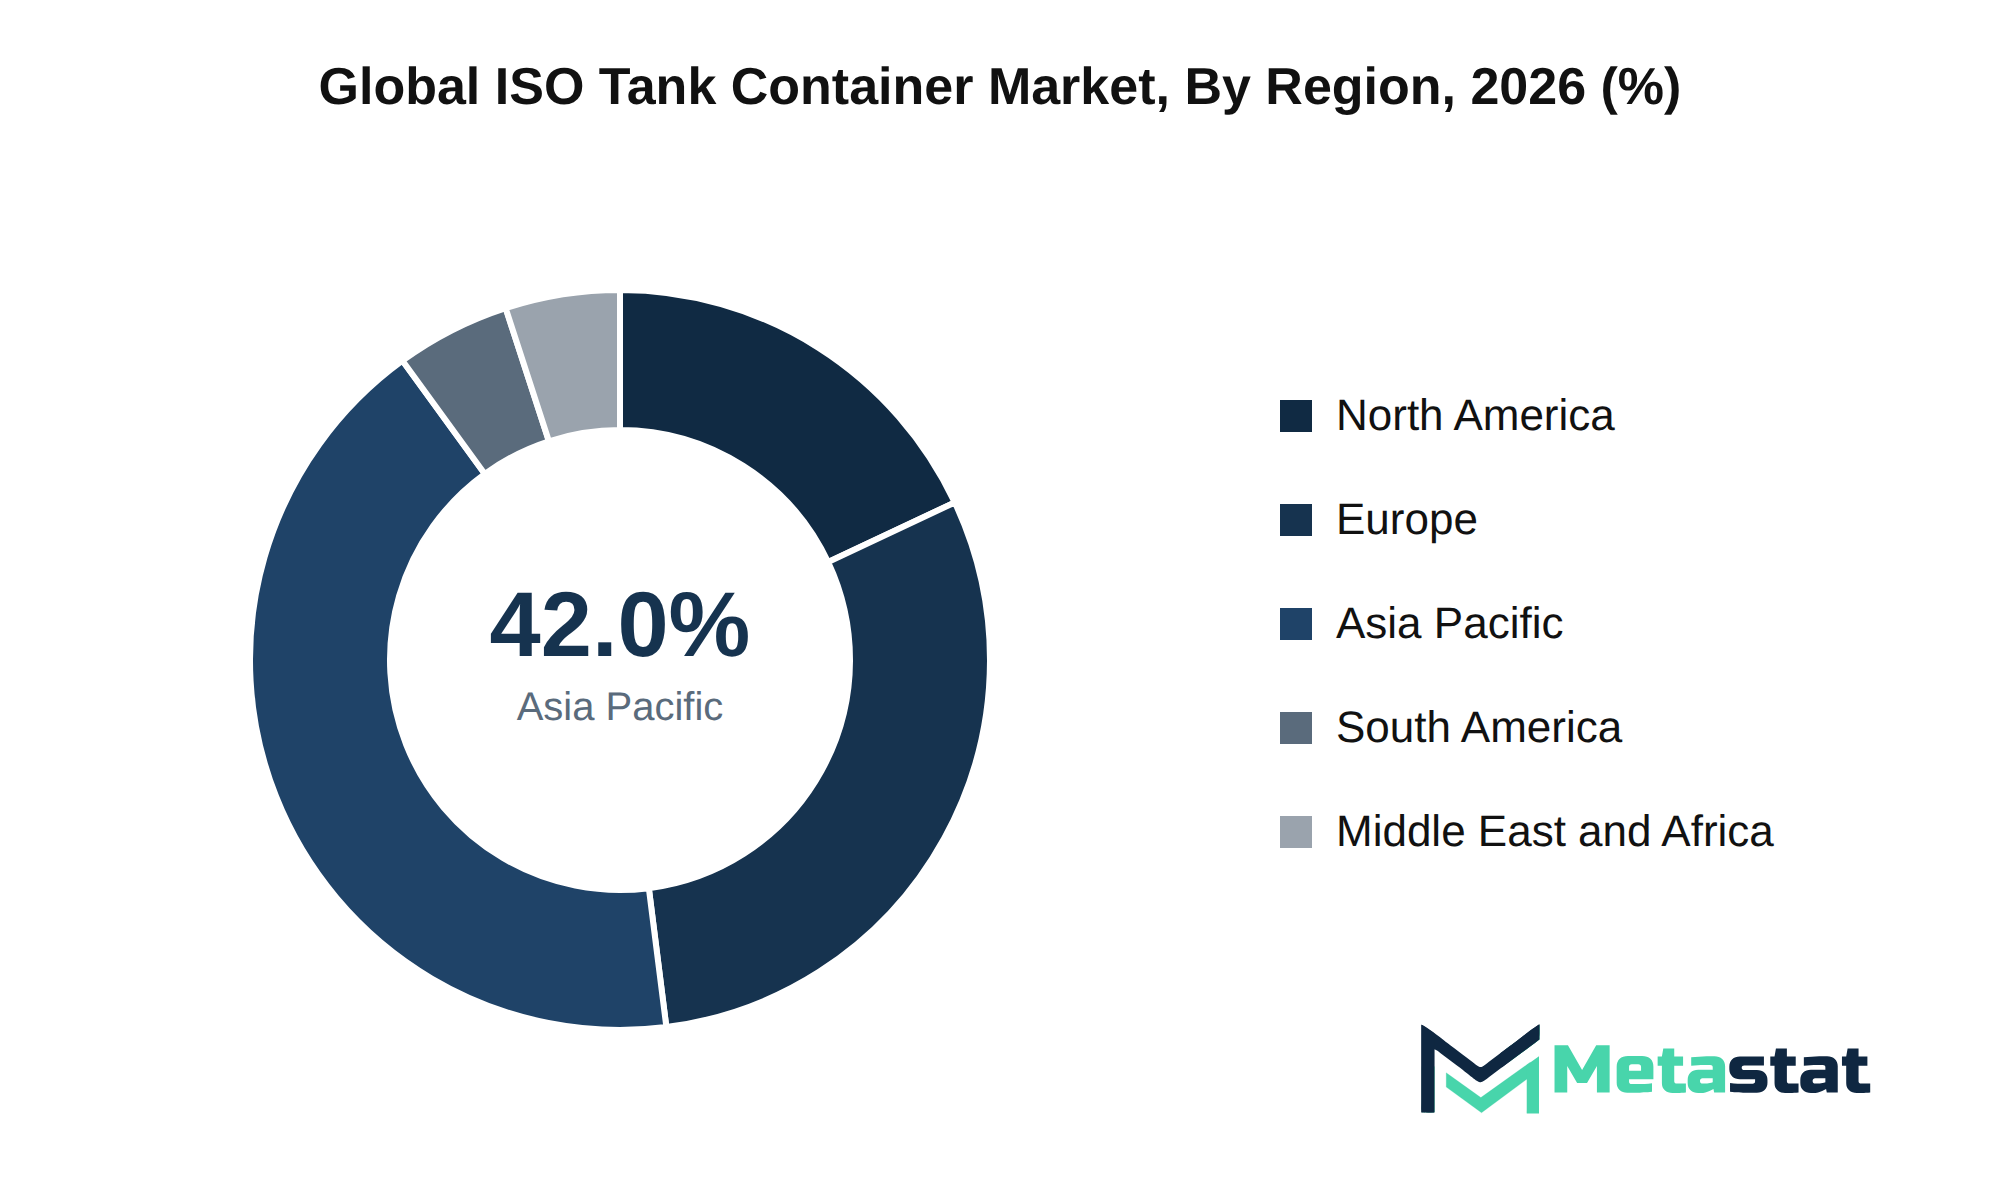
Regional distribution highlights that Asia Pacific holds the largest share at 42%, followed by Europe at 30% and North America at 18%. The market's expansion is driven by increasing demand across various end-use industries, particularly chemicals and petrochemicals. The chemicals segment is expected to grow from USD 0.7 billion in 2026 to USD 1.3 billion in 2033, representing a CAGR of 9.5%.
Investment in infrastructure and technology plays a critical role in shaping the market. Enhanced logistics architecture and sourcing landscape contribute to operational efficiency and cost-effectiveness, attracting investments. The influence of regulations and standards related to safety and environmental compliance drives manufacturers to innovate and adapt their offerings to meet market demands.
Next-generation innovations in tank container designs, focusing on improved capacity and specialized applications, stimulate market growth. The introduction of cryogenic tank containers and food-grade tank containers demonstrates the industry's responsiveness to evolving customer requirements. Market maturity prompts strategies focusing on sustainable transformation and decarbonization that become increasingly prominent.
The regulatory environment for the ISO Tank Container market plays a critical role in shaping operational practices. Compliance with international safety standards ensures the safe transport of hazardous materials. Regulatory frameworks, including those established by the International Maritime Organization, dictate stringent guidelines for tank construction and material specifications. Manufacturers face significant pressure to maintain compliance, which impacts production costs and influences market dynamics.
Geopolitical risks, including trade tensions and international sanctions, introduce volatility within the market. These risks affect supply chains and sourcing strategies, compelling companies to develop adaptive approaches to mitigate disruptions. The potential for interruptions in trade routes drives companies to explore alternative sourcing options, thereby reshaping the logistical architecture and influencing procurement decisions.
Investment in research and development is vital for the ISO Tank Container market, with companies focusing on next-generation innovations. Advancements in materials and design technology enhance the safety and efficiency of tank containers. Companies investing in R&D achieve competitive advantages, positioning themselves to meet evolving customer demands and regulatory standards.
Sustainable transformation within the industry highlights the growing emphasis on decarbonization and circular economy dynamics. Companies increasingly prioritize eco-friendly practices in production and logistics, responding to stakeholder demands for sustainability. The integration of circular economy principles into operations significantly enhances market penetration and customer loyalty.
The supply chain landscape of the ISO Tank Container market continues to evolve, with strategic partnerships and collaborations becoming essential for success. Companies leveraging synergies within their supply chains optimize costs and improve service delivery. This collaborative approach strengthens market positions and builds resilience against economic fluctuations.
Macroeconomic headwinds, including inflationary pressures and currency volatility, introduce challenges for stakeholders in the market. Rising costs of raw materials directly influence pricing strategies, affecting profit margins. Companies navigate these economic factors carefully to maintain competitiveness and meet financial targets.
Looking ahead, the strategic outlook for the ISO Tank Container market is optimistic, supported by a projected compound annual growth rate of 9.3% through 2033. Companies prioritizing capital allocation towards infrastructure investments will likely enhance operational efficiency and responsiveness to market demands. High-value recommendations for stakeholders include focusing on innovation, strengthening supply chain resilience, and adopting sustainable practices to capitalize on emerging opportunities.
Modern tank container design is shifting toward smart connectivity and advanced materials. Telematics units mounted on tank shells now track GPS location, internal pressure, temperature, and shock events in real time. These digital systems communicate via satellite and cellular networks, allowing chemical logistics managers to spot deviations before cargo degrades.
Container design has also evolved through composite insulation panels, lighter chassis designs, and high-tensile stainless steel alloys. These materials reduce the tare weight of standard T11 tank containers and T14 tank containers, enabling higher cargo payloads within standard gross weight limits. In the gas transport segment, innovations in multi-layer vacuum insulation have significantly reduced boil-off rates for cryogenic and temperature-sensitive chemicals.
Rising economic growth contributes significantly to the expansion of the ISO Tank Container market. Increased global trade and industrial activities, particularly in emerging economies, stimulate demand for transportation and storage solutions for bulk liquids and gases. Key sectors including chemicals, petrochemicals, and food and beverage industries exhibit heightened activity, leading to greater utilization of ISO tank containers.
Investment in infrastructure development aligns with economic growth, enhancing logistics networks and supply chain efficiencies. Upgraded facilities and transportation routes promote the movement of goods, supporting the ISO Tank Container market. Improved infrastructure reduces overhead costs for businesses and provides reliable delivery mechanisms, driving operational productivity and reinforcing long-term demand.
The increasing emphasis on sustainability and environmental compliance further influences the market. Companies prioritize eco-friendly practices, and ISO tank containers offer advantages in terms of reducing carbon footprints and enabling circular economy initiatives. This focus aligns with consumer preferences for ethical governance and responsible resource stewardship, positioning the market favorably for future growth and expanding the addressable base.
Overall, economic growth, infrastructure investment, and sustainability initiatives are expected to enhance demand for ISO Tank Containers. The market is projected to reach USD 2.9 billion by 2033, reflecting a compound annual growth rate of 9.3 percent during the forecast period.
The ISO Tank Container market experiences significant growth driven by technological integration. Automation, artificial intelligence, and software adoption streamline operations, allowing for more efficient handling of tank containers. This integration reduces manual labor requirements while enhancing accuracy in managing inventory and logistics processes. Companies increasingly prioritize operational productivity, and investments in innovative technologies produce measurable gains in efficiency.
Shifting demographic patterns and consumer behaviors further drive the demand for advanced solutions within the market. Urbanization and evolving buying preferences influence organizations to adopt modern practices that cater to the needs of diverse populations. Transitioning to automated systems and digitally integrated processes positions businesses competitively, enabling faster response times to market changes and customer requirements.
The focus on sustainability aligns with technological advancements in the market. Companies actively seek to reduce carbon footprints through resource stewardship initiatives, integrating eco-friendly technologies into their operations. This commitment to sustainability fulfills corporate social responsibility and appeals to environmentally conscious consumers, further supporting market expansion.
Investment in digital transformation strategies positions organizations to adapt to changing market conditions effectively. The integration of advanced technologies enhances supply chain resilience and operational flexibility, ensuring businesses meet the growing demand for ISO Tank Containers. This focus on innovation and efficiency drives revenue growth, with the market projected to reach USD 2.9 billion by 2033, reflecting a compound annual growth rate of 9.3% during the forecast period.
The ISO Tank Container market faces significant challenges stemming from regulatory compliance hurdles that create barriers to entry for new players. Increasingly stringent regulations regarding environmental standards and safety protocols require companies to invest in advanced technologies and processes to meet these demands. This situation places considerable financial strain on smaller firms, limiting their ability to compete with established players that have the resources to adapt to compliance requirements.
Macroeconomic headwinds, including inflationary pressures, further complicate the landscape. Rising costs of raw materials and labor lead to higher operational expenses, which deter investment in the market. Many companies experience reduced profit margins, impeding their capability to expand operations or upgrade equipment to conform to evolving regulations.
Supply chain disruptions resulting from geopolitical instability have led to inconsistent availability of essential components, affecting production timelines and increasing costs. These disruptions create uncertainty, discouraging investment in new ISO Tank Container projects and delaying potential growth opportunities.
Resource scarcity presents an additional challenge, limiting the availability of critical materials needed for manufacturing tank containers. This scarcity results in increased costs and potential delays in production, affecting overall market performance.
Infrastructure gaps in certain regions hinder the efficient deployment of ISO Tank Containers. Inadequate transportation networks and limited access to port facilities restrict market expansion in those areas, affecting customer access and service levels.
Talent gaps and skilled labor deficiencies challenge the market. A shortage of qualified personnel results in operational inefficiencies, impacting productivity and the ability to meet demand. Competition for skilled workers drives labor costs higher, further constraining profitability.
Data security vulnerabilities and privacy concerns contribute to market risks. Companies invest in robust cybersecurity measures to protect sensitive information, increasing operational costs. This investment diverts resources that could otherwise support growth initiatives.
Collectively, these factors create a complex environment for the ISO Tank Container market, influencing investment decisions and shaping the competitive landscape. Addressing these challenges will be crucial for companies aiming to capitalize on growth opportunities in the coming years.
The ISO Tank Container market encounters significant challenges stemming from geopolitical fragmentation and trade deficits. Rising tensions among countries disrupt established trade routes and create uncertainty, impacting the efficient movement of goods. This instability affects various industries reliant on tank containers, including chemicals and petrochemicals, leading to increased operational costs and delays in supply chain logistics.
Tariff friction introduces additional financial burdens for companies operating within the market. Increased import tariffs raise costs for manufacturers and suppliers, prompting price adjustments that burden end-users. This shift in pricing dynamics creates competitive pressures, particularly in regions heavily reliant on imports for tank containers.
Technological disruptions present another challenge, resulting from rapid advancements that complicate interoperability between different systems and equipment. Companies face increased costs associated with integrating new technologies into their existing frameworks, which hinder operational efficiency. The need for effective integration across diverse tank container systems remains critical to maintaining competitiveness.
Supply chain volatility, driven by environmental factors, further complicates the market landscape. Disruptions stemming from natural disasters or logistical challenges impact the availability of feedstocks and components essential for tank container production. Such volatility leads to production delays and increased costs, ultimately affecting the overall growth trajectory of the market.
Intellectual property protection deficits and cybersecurity risks pose additional threats. Companies operating in the ISO Tank Container market face challenges in safeguarding proprietary technologies and processes, exposing them to potential data breaches and loss of competitive advantage. This vulnerability necessitates heightened investment in cybersecurity measures, further straining operational budgets.
Ultimately, these challenges create an environment of uncertainty, impacting demand and growth within the ISO Tank Container market. Companies navigate this complex landscape while striving to maintain profitability and operational efficiency.
The ISO Tank Container market reflects significant opportunities driven by various emerging trends. A marked increase in regional demands arises from the growth in industries including chemicals and petrochemicals, particularly in Asia Pacific, which holds a 42% share of the market. This demand shift compels manufacturers to modernize infrastructure and enhance supply chain efficiencies, facilitating timely delivery and reducing operational costs.
Technological disruptions contribute prominently to market expansion. Innovations in digital transformation, including automated tracking systems and advanced logistics platforms, optimize supply chains while improving transparency and reliability. These factors enable companies to respond swiftly to changing market dynamics, further driving the adoption of ISO tank containers.
Sustainability imperatives increasingly influence purchasing decisions. Organizations commit to environmental, social, and governance (ESG) standards, fueling demand for eco-friendly tank solutions. These commitments encourage manufacturers to integrate sustainable practices into product development, creating a favorable landscape for next-generation innovations.
Downstream market diversification presents additional avenues for growth. Industries including food and beverage, which require specialized tank containers for handling sensitive products, illustrate the versatility of ISO tanks. Such niche applications promote product integration and capture a broader customer base, enhancing revenue potential across various sectors.
Strategic consolidation among industry players signifies a trend toward comprehensive service offerings. Mergers and acquisitions enable companies to enhance capabilities and expand geographical reach, strengthening their competitive position. This strategy encourages collaboration across industries, prompting innovations and spurring market growth.
Ultimately, evolving buying behaviors reflect a shift toward digital procurement models. Organizations increasingly favor online platforms for sourcing and purchasing, prompting suppliers to adapt their commercial models. This transition increases market accessibility and participation, supporting the overall growth trajectory of the ISO Tank Container market.
The Global ISO Tank Container market is segmented based on Tank Type, Capacity, and End-Use Industry.
Valued at USD 0.4 billion in 2026, the Standard Liquid Tank Containers segment is projected to reach USD 0.7 billion by 2033, demonstrating a CAGR of 7.9% during the forecast period. This growth stems from the increasing demand for the transportation of various liquids, including chemicals and food-grade products. The expansion of industries, including chemicals and petrochemicals, directly influences the demand for standard liquid tank containers, contributing to the segment's upward trajectory.
Technological maturation enhances the efficiency and safety of standard liquid tank containers. Innovations in materials and design optimize the performance and durability of these containers, attracting investments focused on modernization. These advancements align with regulatory compliance standards, ensuring that containers meet stringent safety and quality requirements, thereby boosting market confidence.
Downstream applications in industries like food and beverage, chemicals, and pharmaceuticals further drive the consumption of standard liquid tank containers. Companies increasingly recognize the importance of reliable and efficient liquid transport solutions for maintaining product integrity and compliance. This trend highlights the segment's potential for capturing market share, driven by companies shifting towards more sustainable and regulatory-compliant transport methods.
Cost structures significantly impact the market, with fluctuations in raw material prices influencing the overall pricing of standard liquid tank containers. Companies actively seek to mitigate these pressures through strategic partnerships and vertical integration, securing supply chain resilience. Such strategies enhance operational efficiency, allowing businesses to maintain competitive pricing during market volatility.
Strategic opportunity windows present themselves due to evolving global trade dynamics. Regions with growing industries in Asia Pacific, North America, and Europe show substantial potential for investment and growth. Capturing market share in these areas requires a focused approach on meeting local demands and adapting to specific regulatory environments, ultimately strengthening the position of players in the ISO Tank Container market.
Significant growth in the Gas Tank Containers segment of the ISO Tank Container market stems from increasing demand for efficient transportation and storage of gaseous materials, particularly in the chemicals and petrochemicals industries. Factors driving adoption include advancements in technology and the need for compliance with stringent safety regulations. This segment is estimated to reach USD 0.6 billion by 2033, at a CAGR of 9.9% during the forecast period, reflecting robust interest from end-users aiming to enhance operational efficiency and safety in transporting gases.
The emergence of next-generation upgrades significantly contributes to segment expansion. Innovations in materials and design lead to improved durability and performance, catering to the changing needs of various industries. End-use dynamics indicate a shift towards gas tank containers driven by industries prioritizing sustainability and regulatory compliance, influencing consumption patterns across multiple sectors. The ongoing investment in infrastructure further supports market growth, providing opportunities for manufacturers to enhance capacity and meet rising demand.
Cost structures and pricing volatility impact the competitive landscape within the gas tank containers segment. Manufacturers focus on optimizing production processes to mitigate margin pressures stemming from fluctuating raw material costs. Supply chain resilience remains a vital consideration, ensuring that disruptions do not hinder the timely delivery of products. Enhanced logistics capabilities contribute to improved service levels, strengthening relationships between suppliers and customers.
Strategic opportunity windows emerge because market participants explore new applications and regions. This includes tapping into emerging markets where industrial growth presents untapped potential. Companies that successfully navigate these opportunities and innovate their offerings are positioned for substantial growth in the evolving ISO Tank Container market.
Significant growth in the Cryogenic Tank Containers segment will contribute to the expansion of the ISO Tank Container market, with projections indicating a value of USD 0.7 billion by 2033. This increase stems from rising demand in various industries, particularly for transporting liquefied gases and cryogenic liquids. Industries including chemicals and energy, which rely heavily on efficient transportation of these substances, drive this demand. Technological advancements in cryogenic storage and handling improve operational efficiency and safety, further supporting segment growth.
Market expansion is supported by heightened focus on energy-efficient logistics solutions. Companies seek to optimize their supply chains, creating opportunities for cryogenic technology adoption. Regulatory compliance standards regarding the transportation of hazardous materials influence the segment, compelling manufacturers to enhance their offerings to meet safety and environmental standards. Competition within the market intensifies owing to industry players innovating and refining their product portfolios to align with evolving consumer needs.
Investment in cryogenic tank container technology reflects a broader trend of capital allocation towards sustainable logistics solutions. With increasing demand for cleaner energy sources, the segment is positioned to benefit from shifts in consumption patterns driven by industries prioritizing environmentally friendly practices. The combination of regulatory pressures and market demand encourages ongoing research and development efforts to upgrade existing technologies, ensuring the segment remains competitive and resilient against emerging alternatives.
Growth in the Food-Grade Tank Containers segment aligns with increasing demand for safe and efficient transportation of food and beverage products. The food and beverage industry emphasizes compliance with strict safety and quality regulations, pushing suppliers toward the use of certified tank containers. This focus on safety enhances operational efficiency and boosts market growth potential.
The Food-Grade Tank Containers segment is projected to grow at a CAGR of 7.4% during the forecast period. This growth stems from rising consumer awareness regarding food safety and quality. Consumers demand higher standards, and manufacturers adopt advanced solutions, creating a favorable environment for food-grade container adoption.
Technological advancements play a critical role in product evolution, introducing new features and enhancing performance in food-grade containers. Innovations including temperature control systems and improved sealing technologies contribute to maintaining product integrity during transportation. These advancements attract investments and support market expansion.
Regulatory compliance standards heavily influence the dynamics in this segment. Strict regulations ensure that food-grade materials meet health and safety requirements, pushing manufacturers to prioritize certifications. This trend strengthens the competitive landscape, compelling players to invest in compliance-oriented solutions, driving growth in the ISO Tank Container market.
Cost structures within the food-grade tank containers segment reflect the high standards required for materials and manufacturing processes. Initial investments are significant, but the long-term benefits of reduced spoilage and enhanced efficiency justify the costs. This financial perspective encourages companies to invest in food-grade solutions, further stimulating market growth.
Strategic opportunity windows arise from changing consumption patterns and a growing preference for sustainable packaging solutions. Environmental concerns increase, prompting companies to explore eco-friendly alternatives in food-grade containers. This shift aligns with consumer trends and opens avenues for innovation and differentiation within the ISO Tank Container market.
Shifting consumer preferences toward environmentally friendly materials drive growth in the lined tank containers segment. Industries including chemicals and petrochemicals increasingly adopt lined tank containers to ensure the safe transportation of hazardous and sensitive materials. Enhanced safety features and regulatory compliance requirements contribute to the demand for this segment within the ISO Tank Container market.
Technological maturation in manufacturing processes supports the production of high-quality lined tank containers. Improved materials science and innovation in design lead to enhanced durability and efficiency, translating to better performance in various applications. Ongoing investments in research and development facilitate next-generation upgrades, reinforcing the segment's position in the market.
Regulatory compliance standards significantly influence the adoption of lined tank containers. Stricter environmental regulations promote the use of lined tanks designed to prevent leaks and spills, thereby reducing environmental impact. Companies prioritizing compliance enhance their market competitiveness while adhering to evolving policies.
Cost structures and pricing volatility in the raw materials market impact the overall economics of lined tank containers. Fluctuations in the costs of materials including steel and composite materials pressure profit margins. Strategic sourcing and supply chain resilience are crucial for manufacturers to mitigate these challenges and maintain competitive pricing.
Market dynamics indicate a shift toward increased consumption of lined tank containers due to their adaptability in various end-use industries. The segment experiences a growing presence in food and beverage applications, where safety and hygiene considerations are critical. This trend highlights the evolving nature of the ISO Tank Container market.
Demand for heated tank containers derives primarily from industries requiring precise temperature control during transport and storage. Applications in the food and beverage, chemicals, and pharmaceuticals sectors significantly drive this demand, driven by these industries' handling of materials sensitive to temperature fluctuations. Adoption of heated tank containers enhances operational efficiency, reducing product spoilage and maintaining quality throughout the supply chain. Technological maturation in heating systems and insulation materials boosts the performance and reliability of these containers. Next-gen upgrades focus on incorporating smart technologies for real-time monitoring, further enhancing safety and compliance with stringent regulatory standards. Regulatory compliance plays a critical role in shaping market dynamics, with stringent hygiene and safety standards influencing product design and operational practices. This compliance, coupled with evolving certification requirements, affects market entry barriers for new players and drives competition among established manufacturers. Pricing volatility in raw materials impacts cost structures for heated tank containers, necessitating strategic sourcing practices to mitigate margin pressures. Ongoing fluctuations in energy prices contribute to overall cost dynamics, compelling manufacturers to seek efficiencies and innovative solutions. Strategic opportunity windows exist owing to industries increasingly shifting towards sustainable practices. Investment in eco-friendly technologies and materials enhances brand reputation, appealing to environmentally conscious consumers. The market for heated tank containers is expected to undergo significant evolution, driven by a combination of these factors and the ongoing exploration of disruptive alternatives that challenge traditional supply chain methods.
Valued at USD 0.2 billion in 2026, the Up to 10,000 Liters segment is projected to reach USD 0.4 billion by 2033, at a CAGR of 6.3% during the forecast period. This growth aligns with increasing demand from the chemicals and food and beverage industries, both of which use smaller tank containers for efficient transportation of liquid products. The segment benefits from advancements in tank design and materials, which enhance safety and operational efficiency.
Technological maturation fuels demand within this sub-segment, with innovations leading to improved product features and performance. Regulatory compliance standards in various industries further drive adoption, ensuring that transportation meets safety and environmental regulations. This segment's growth is supported by strong consumption shifts toward more sustainable practices and cost-effective solutions in logistics.
Market dynamics reflect a competitive landscape that encourages strategic opportunities. Investment in next-gen upgrades signifies a focus on enhancing the operational capabilities of these tank containers, thereby attracting a broader range of end users. Increased capital investment in developing specialized containers tailored for specific applications enhances market potential.
Overall, the Up to 10,000 Liters segment significantly contributes to the ISO Tank Container market, and its growth trajectory indicates a positive outlook driven by industries seeking efficient solutions to meet rising logistical demands.
Demand for the 10,001-20,000 Liters segment stems from several industries requiring medium-capacity ISO tank containers for efficient transportation and storage of liquids. This segment experiences strong growth driven by the expanding chemical and petrochemical industries, which rely on efficient logistics for bulk shipments. Adoption of these containers aligns with rising environmental regulations that favor sustainable transport solutions, enhancing operational efficiency and compliance.
Technological advancements in tank manufacturing and materials contribute to the evolution of product offerings, leading to improved durability and safety standards. The emphasis on regulatory compliance and certifications influences purchasing decisions, ensuring that suppliers meet industry standards. This segment is projected to reach USD 0.8 billion by 2033, with a CAGR of 7.9% during the forecast period.
Strategic opportunity windows arise from increasing demand for specialized liquids in various sectors, including pharmaceuticals and food and beverage. Companies invest in next-generation upgrades for existing fleets, facilitating expansion into emerging markets. Ongoing development of supply chain resilience enhances logistics capabilities, addressing vulnerabilities in sourcing raw materials and distribution networks.
Growth within the ISO Tank Container market reflects strong demand for the 20,001-26,000 Liters segment, driven by industries requiring larger capacity solutions for transportation and storage. The chemical and petrochemical sectors significantly contribute to this demand, attributed to their increasing adoption of ISO tank containers for bulk transport of liquid substances. Environmental regulations and safety standards in these industries encourage the adoption of compliant storage solutions, reinforcing the segment's expansion.
Technological advancements in tank design enhance efficiency and safety, supporting the segment's growth trajectory. Innovations in materials and manufacturing processes improve the durability and performance of these containers, appealing to manufacturers focused on reducing operational costs. The segment is expected to reach USD 0.7 billion by 2033, indicating a robust compound annual growth rate supported by industries continuing to embrace reliable transport solutions.
Rising logistics demands, coupled with global trade trends, position this segment favorably for investment and strategic development. Companies are increasingly investing in optimizing supply chains to enhance delivery capabilities, which aligns with the upward trend in container utilization. Ongoing improvements in raw material sourcing and supply chain resilience further strengthen market positions, supporting sustained growth in the coming years.
Significant growth is expected in the Above 26,000 Liters segment, driven by rising demand from industries requiring the transport of larger volumes of liquid products. This segment's expansion aligns with increasing investments in sectors including chemicals and petrochemicals, where bulk transportation solutions are essential for operational efficiency. Companies are gravitating toward larger tank containers to optimize logistics and minimize the frequency of shipments, effectively reducing overall transportation costs.
Technological advancements play a crucial role in segment growth. Innovations in tank design and materials enhance safety and reliability, catering to stringent regulatory compliance standards. These improvements facilitate wider adoption among end-users prioritizing safety and efficiency in their operations.
Rising consumption of chemicals and industrial gases contributes to market momentum. The shift toward sustainable practices encourages companies to invest in environmentally friendly transportation solutions, further supporting the Above 26,000 Liters segment. With a projected CAGR of 11.5% during the forecast period, the segment is set to reflect strong performance, offering strategic opportunities for manufacturers and suppliers targeting this growing market segment.
Growth within the chemicals segment of the ISO Tank Container market is evident, with a valuation of USD 0.7 billion in 2026, projected to reach USD 1.3 billion by 2033, reflecting a CAGR of 9.5% during the forecast period. This growth stems from increased demand for efficient transportation solutions in the chemical industry, driven by the need for secure and reliable shipping of hazardous materials and bulk chemicals. The ongoing expansion of the global chemicals industry, particularly in developing regions, enhances market opportunities.
Technological maturation plays a critical role, with advancements in tank design and safety features facilitating wider adoption of ISO tank containers. Enhanced regulatory compliance standards concerning the transportation of chemicals increase demand for high-quality, certified containers that meet stringent safety requirements. Consequently, companies within the market invest in modernizing their fleets to accommodate diverse chemical products while ensuring adherence to these regulations.
Consumption shifts towards more sustainable and environmentally friendly solutions influence the market. Industries increasingly prioritize eco-friendly practices, leading to a higher preference for ISO tank containers that minimize environmental impact during transportation. This trend encourages investments in next-gen upgrades and innovative designs that enhance efficiency and sustainability.
Strategic opportunity windows arise from increasing globalization and international trade, necessitating robust logistics solutions. The chemicals segment effectively capitalizes on these opportunities by ensuring reliable supply chain resilience and addressing raw material sourcing challenges. Manufacturers focus on strengthening their supply chains to mitigate logistics vulnerabilities, allowing for effective transportation of chemical products across borders.
Market participants include notable players including CIMC ENRIC, Chart Inc., and Singamas Container Holdings Limited, which drive competition and innovation. Their strategies revolve around expanding product portfolios, enhancing service capabilities, and establishing partnerships that strengthen market presence. These initiatives contribute to a dynamic and competitive landscape within the chemicals segment of the ISO Tank Container market.
Demand for ISO Tank Containers within the petrochemicals segment reflects strong growth, driven by increasing production and consumption of various petrochemical products. The rising need for efficient and safe transportation solutions aligns with the growing global petrochemical market, which is essential in multiple industries including plastics, textiles, and automotive. Strong demand for high-capacity transport solutions enables companies to optimize supply chains while adhering to stringent safety and regulatory standards.
Technological advancements in tank container design and materials contribute to enhanced durability and efficiency. These innovations support the transport of a wide range of petrochemical products, including hazardous materials, while minimizing risks associated with leaks or contamination during transit. The market is projected to reach USD 0.4 billion by 2033, at a CAGR of 9.4% during the forecast period, reflecting significant investment in this sector.
Ongoing shifts in consumer preferences toward sustainable practices further strengthen the position of ISO Tank Containers in the petrochemicals segment. Companies increasingly focus on eco-friendly solutions, driving demand for tank containers that meet both operational and environmental criteria. Such dynamics present opportunities for market participants to enhance service offerings and capture a larger share of the growing market.
Growth within the Industrial Gases segment reflects increasing demand for efficient transportation solutions across various industries. This demand arises from the need for reliable and safe delivery of gases, including oxygen, nitrogen, and argon, in diverse applications including manufacturing, healthcare, and energy production. Investment in infrastructure and advancements in technologies related to ISO Tank Containers drive segment expansion, enabling better handling and distribution of these gases.
Regulatory compliance standards related to safety and environmental impacts influence purchasing decisions, resulting in a shift toward ISO Tank Containers designed to meet these stringent requirements. Cost structures remain critical, with fluctuations in raw material prices impacting overall expenditure. Suppliers are adapting their strategies to manage pricing volatility by optimizing manufacturing processes and enhancing operational efficiencies.
The Industrial Gases segment is expected to reach USD 0.3 billion by 2033. This projected growth highlights the significance of this sub-segment within the broader ISO Tank Container market, where competition intensifies among key players aiming to capture increasing market demand. Strategic opportunities for investment and innovation abound, particularly in areas focusing on next-gen upgrades and product evolution to support emerging applications.
Growth within the Food & Beverage segment is projected to grow at a CAGR of 8% during the forecast period. Increasing global demand for food safety and quality assurance drives the adoption of ISO Tank Containers, particularly in the transportation of liquids including juices, oils, and dairy products. Stringent regulations regarding food safety further enhance the necessity for high-quality transport solutions, creating an environment conducive to market expansion.
Technological advancements in the manufacturing and design of ISO Tank Containers facilitate the handling of diverse food products, thus supporting segment growth. Manufacturers focus on developing food-grade containers that comply with international safety standards, which influences purchasing decisions among food and beverage companies. Enhanced product features, including better insulation and temperature control, cater to the needs of companies requiring efficient transport for perishable items.
While consumers shift towards healthy and organic food products, food and beverage companies emphasize the importance of maintaining product integrity during transportation. This shift increases demand for specialized ISO Tank Containers designed for specific food applications, improving operational efficiencies. The growing trend of e-commerce in the food sector necessitates reliable and safe transport methods, further validating the need for ISO Tank Containers.
Competitive pressures within the food and beverage industry prompt companies to seek cost-effective logistics solutions, driving investment in ISO Tank Containers that optimize transport efficiency. The market reflects a broader trend of increasing investments in sustainable practices, with companies seeking containers that support environmentally friendly practices. This focus not only aligns with regulatory requirements but reflects consumer preferences for sustainability.
Overall, the Food & Beverage segment within the ISO Tank Container market reflects promising growth opportunities driven by evolving consumer preferences, regulatory compliance, and technological innovations.
Diverse demand drivers in the pharmaceuticals sector influence the adoption of ISO Tank Containers. Regulatory compliance standards play a critical role in shaping the market, driven by stringent guidelines that necessitate secure and efficient transportation solutions for sensitive pharmaceutical products. The sector emphasizes the importance of maintaining product integrity and temperature control throughout the supply chain, stimulating the need for specialized containers designed for pharmaceuticals.
Technological maturation within the industry enhances operational efficiency, enabling smoother logistics and improved tracking of shipments. Innovations in container materials and design facilitate the safe transport of volatile compounds. The growing focus on next-generation upgrades supports the incorporation of smart technologies into ISO Tank Containers, allowing for real-time monitoring of conditions during transportation.
Market dynamics within the pharmaceuticals segment show a shift toward environmentally sustainable practices. Companies increasingly prioritize green logistics, driving demand for containers that minimize carbon footprints. This transition influences purchasing decisions, leading to an increased preference for ISO Tank Containers that align with sustainability objectives.
The capital investment outlook for the pharmaceuticals segment remains positive. Continued investment in research and development supports the evolution of products tailored to meet specific needs within the sector. Supply chain resilience is critical, reflecting the industry's commitment to overcoming logistical vulnerabilities and ensuring uninterrupted access to essential medications.
Overall, the market for ISO Tank Containers within the pharmaceuticals segment experiences significant growth, driven by shifting consumer preferences, stringent regulatory requirements, and ongoing advancements in technology. Demand for reliable and efficient transportation solutions positions this segment because a vital component of the broader ISO Tank Container market.
Increased investment in exploration and production from the Oil and Gas sector significantly influences demand for ISO Tank Containers. Expanding infrastructure to support oil and natural gas operations drives this trend, driven by companies seeking efficient and safe transport solutions for liquids and gases. The industry's focus on sustainability and regulatory compliance further encourages the adoption of advanced tank containers, which comply with stringent safety standards.
The movement toward energy transition and the shift from traditional fossil fuels to cleaner energy sources create dynamic changes within the Oil and Gas segment. Companies focus on enhancing operational efficiency and reducing emissions, increasing the need for innovative transport solutions. This transformation impacts logistics, prompting suppliers to adopt ISO Tank Containers for various applications, including the transportation of liquefied natural gas and other petrochemical products.
Technological advancements and the maturation of the ISO Tank Container market facilitate the introduction of next-generation containers that offer improved safety, durability, and functionality. Innovations including smart monitoring systems enhance supply chain visibility and operational efficiency, providing a competitive edge while addressing industry needs. Continuous product evolution aligns with the industry's growth trajectory, supporting robust demand within the Oil and Gas segment.
Regulatory compliance standards and certifications play a critical role in shaping the market dynamics. Companies adhere to safety regulations and environmental policies, which necessitate the use of reliable transport solutions. The focus on compliance drives investments in ISO Tank Containers, reinforcing their importance in the supply chain for the Oil and Gas sector.
Pricing volatility and margin pressures impact operational costs for companies in the Oil and Gas segment. Fluctuations in raw material prices affect the cost structures of ISO Tank Containers, prompting suppliers to optimize their offerings while maintaining competitive pricing. This environment highlights the strategic opportunity window for manufacturers that invest in cost-effective solutions without compromising quality.
Supply chain resilience remains crucial owing to logistics challenges and potential disruptions faced by companies. The need for reliable transportation methods influences the decision-making process when selecting ISO Tank Containers. Firms prioritize partnerships with established suppliers to ensure the steady availability of containers while mitigating risks associated with logistics vulnerabilities.
The Oil and Gas segment experiences significant demand for ISO Tank Containers due to rising exploration activities, regulatory pressures, and the industry's shift toward sustainable practices. The combination of these factors shapes the market, presenting ongoing opportunities for growth and innovation.
Increasing demand for energy products, particularly liquefied natural gas (LNG), significantly influences the adoption of ISO Tank Containers within the Energy & LNG segment. This trend arises from the global shift towards cleaner energy sources and the growing emphasis on efficient transportation solutions. Key players in the energy sector, including LNG producers and distributors, benefit from these containers to facilitate safe and efficient transport, enhancing operational efficiencies.
Investment in infrastructure to support LNG facilities contributes to the growth of this segment. New projects and expansions in LNG terminals create a higher demand for ISO Tank Containers, driven by the need for reliable transportation solutions for storage and distribution. Regulatory compliance regarding safety and environmental standards further drives companies to invest in technologically advanced containers that meet stringent requirements.
Technological advancements play a crucial role in segment expansion. Innovations in insulation materials and design improve the efficiency and safety of transporting LNG. Enhanced container features, including pressure regulation systems and temperature control, support operational effectiveness and help mitigate risks associated with the transportation of hazardous materials.
Fluctuations in global energy prices impact cost structures within the segment. Market volatility leads to margin pressures for suppliers, compelling them to seek cost-effective solutions. Companies that invest in robust supply chain resilience and strategic partnerships with logistics providers enhance their competitive positioning, allowing them to navigate pricing fluctuations more effectively.
Competition in the ISO Tank Container market intensifies owing to new entrants emerging and existing players expanding their offerings. The Energy & LNG segment features a dynamic relationship of traditional energy companies and innovative newcomers, each aiming to capture market share through specialized solutions tailored to industry demands. This evolving landscape presents strategic opportunity windows for companies that adapt to emerging trends and changing consumer preferences toward cleaner energy solutions.
Growth in the Mining & Metals sector contributes significantly to increasing demand for ISO Tank Containers, driven by the necessity for safe and efficient transportation of various raw materials and chemicals. Factors including the rising need for sustainable mining practices and advancements in extraction technologies fuel adoption within this segment. End-user industries prioritize high-quality and robust containers to ensure product integrity and compliance with strict safety regulations.
Technological maturation within the sector influences the development of innovative tank designs that enhance operational efficiencies and reduce transportation costs. Next-gen upgrades, including automation and IoT integration, support tracking and monitoring, further driving market expansion. The continuous evolution of product offerings aligns with the changing requirements of mining operations, enabling firms to adapt to new challenges in logistics and material handling.
End-use dynamics within the Mining & Metals sector indicate shifts towards greater sustainability and lower environmental impact, prompting organizations to invest in ISO Tank Containers that align with these goals. Regulatory compliance standards dictate stringent requirements for transport, necessitating compliance from manufacturers and suppliers. Capital investment outlooks remain positive, driven by firms within this segment seeking to enhance supply chain resilience and mitigate vulnerabilities.
Cost structures stemming from fluctuating raw material prices impact the financial planning of companies. Pricing volatility presents challenges that organizations navigate to maintain margins while ensuring product availability. Strategic opportunity windows emerge for suppliers that develop solutions addressing these cost pressures, enhancing their competitive advantage in a demanding market.
Overall, the Mining & Metals sector significantly shapes the ISO Tank Container market, with an emphasis on robust supply chain management, environmental stewardship, and technological advancements steering the landscape towards future growth.
Investment in environmental and waste management drives the demand for ISO tank containers, primarily owing to an increase in regulations and public awareness regarding waste disposal and recycling processes. Companies operating within this sector focus on improving sustainability and minimizing the environmental impact of their operations. Enhanced regulations regarding hazardous waste disposal necessitate advanced containment solutions, which further increases the need for ISO tank containers in this industry.
Growing urbanization and industrialization contribute to increased waste generation, leading to higher demand for effective waste management solutions. Municipalities and private entities seek efficient methods to collect, transport, and process waste materials, thereby favoring the adoption of ISO tank containers for safe and compliant waste handling. This ongoing evolution in waste management practices signifies a positive trajectory for the market.
Technological advancements in container design and manufacturing enhance the capabilities of ISO tank containers, improving safety and efficiency in waste management applications. Innovations including real-time monitoring systems for waste contents and automated tracking solutions support operational efficiency and compliance with regulations. These developments reflect a commitment to improving service delivery in the environmental sector, enhancing the overall effectiveness of waste management.
Demand for ISO tank containers in the environmental and waste management sector reflects a shift in consumption patterns, with increased emphasis on recycling and the recovery of valuable materials from waste streams. Companies are investing in technologies that facilitate the separation and processing of recyclable materials, further driving the need for specialized containers that handle a variety of waste types safely.
Regulatory compliance has become a central focus for companies within this segment, necessitating investment in ISO tank containers designed to meet stringent environmental standards. Compliance with local and international regulations regarding waste transportation and disposal reinforces the importance of industry-specific containment solutions, thereby boosting market growth.
Supply chain resilience remains a priority, particularly in response to global disruptions and increasing logistical challenges. The ability to ensure secure and compliant transportation of waste materials requires a robust framework, with ISO tank containers playing a crucial role in supporting operational continuity. Strategic partnerships among suppliers and service providers within the market are essential for navigating these complexities effectively.
Growth within the Others segment, which encompasses agriculture, cosmetics, and specialty materials, reflects rising demand for diverse applications. Agricultural products often require specific transportation methods for maintaining quality, enhancing the demand for ISO Tank Containers designed for sensitive materials. In the cosmetics industry, growing interest in sustainable and eco-friendly packaging contributes to the adoption of tank containers, allowing for safer and more efficient transport of raw materials.
Specialty materials, which often include high-value products that require careful handling, create opportunities for tank containers designed to meet specific regulatory compliance standards. The segment benefits from technological maturation, with advancements in container design and materials facilitating safer and more efficient storage and transportation. Strategic opportunity windows open for suppliers who address the unique needs of these diverse industries, supporting their growth in the market.
Several challenges persist, including pricing volatility and margin pressures that impact manufacturers' cost structures. Companies involved in this segment navigate complex supply chain vulnerabilities, especially concerning raw material sourcing and logistics. Despite these challenges, the demand for ISO Tank Containers in these specialized sectors continues to evolve, driven by consumption shifts and regulatory requirements that push for greater compliance and efficiency.
Based on geography, the Global ISO Tank Container market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa. Regional growth patterns reflect local manufacturing activity, environmental regulations, and infrastructure quality.
North America represents a significant portion of the global ISO Tank Container market, holding an 18% share in 2025. The market is projected to expand at a CAGR of 9.3% within the forecast period, reaching a market size (TAM) of USD 0.5 billion by the end of 2033. Key factors driving this growth include increasing demand from various end-use industries, particularly chemicals and food and beverage, which contribute to the adoption of ISO Tank Containers.
Growth is driven by the Gulf Coast petrochemical industry. Intermodal rail links connect production hubs with export terminals, though depot congestion and driver availability periodically constrain velocity.
Investment in infrastructure modernization enhances the capacity for localized manufacturing, enabling firms in the United States, Canada, and Mexico to meet rising demand efficiently. Supply chain regionalization and nearshoring initiatives strengthen the market by promoting local production and reducing reliance on overseas suppliers. Domestic firms including CIMC ENRIC and Chart Inc. provide innovative solutions to meet customer needs.
The growth trajectory of the market benefits from cross-border trade corridors, facilitating the movement of goods within North America. A focus on compliance with geographic regulatory frameworks ensures that companies adhere to local mandates. This adherence supports firms in minimizing operational disruptions while enhancing their market position. Increased foreign direct investment (FDI) flows into sectors including chemicals and industrial gases further contribute to market expansion.
Emerging market front-runners in the ISO Tank Container market exemplify the potential for growth in underpenetrated territories. The increasing trend towards localized procurement dynamics highlights the importance of cultural nuances and regional B2B buying behaviors in shaping market strategies. While the market evolves, high-value replacement cycles and incremental growth vectors will influence long-term growth in North America.
The ISO Tank Container market in Europe accounts for 30.00% of the global market share in 2025. Demand within this region is driven by various factors, including a strong presence of industries including chemicals, petrochemicals, and food and beverages. Countries like Germany and France emerge due to key players with extensive manufacturing capabilities and established supply chains that facilitate the adoption of ISO tank containers.
Maintains a mature, highly integrated intermodal network. Stringent environmental rules incentivize shippers to shift cargo from road transport to rail and inland waterways using tank containers.
Investment in infrastructure modernization significantly enhances the distribution networks across Europe, enabling smoother logistics and transportation processes. The UK's initiatives focusing on sustainability and energy transition increase the demand for cryogenic tank containers, particularly within the industrial gases sector. In Italy and Spain, increasing production in the chemicals sector further drives the need for standard liquid tank containers.
Emerging market front-runners including Russia contribute to incremental growth vectors, supported by local compliance mandates and regulatory frameworks that encourage safer and more efficient transportation solutions. Localized procurement dynamics in these countries facilitate domestic manufacturing, reducing reliance on imports and improving cost-effectiveness for businesses. The competitive landscape features several domestic market participants, including CIMC ENRIC and Cryocan, which actively engage in vendor consolidation trends and strategic partnerships to strengthen their market position.
Energy grid resiliency and local infrastructure readiness are critical in enhancing the overall market performance in Europe. Foreign direct investment flows towards localized manufacturing setups highlight the region's attractiveness for global players seeking to establish a foothold in the ISO Tank Container market. Overall, the combination of regional demand drivers, coupled with high-value replacement cycles and localized manufacturing densities, creates a positive outlook for the market in the coming years.
The Asia-Pacific region accounts for a substantial 42.00% share of the global ISO Tank Container market in 2025. Rapid industrialization and urbanization in countries including China and India drive demand for ISO Tank Containers, particularly in the chemicals and petrochemicals sectors. Increased production and transportation of energy products, including liquefied natural gas (LNG), further contribute to this growth. Countries in Southeast Asia, alongside established markets like Japan and South Korea, experience an uptick in infrastructure modernization efforts, enhancing regional logistics capabilities.
Represents the fastest-growing region for both manufacturing and equipment adoption. Rising domestic chemical production in China and India drives strong demand for intermodal transportation to replace traditional steel drums.
Emerging markets within the region demonstrate significant potential for penetration, with local manufacturers seeking to optimize their supply chains. The prevalence of cross-border trade corridors creates a competitive environment that encourages investment in ISO Tank Container fleets. Geopolitical considerations, including trade policy shifts, influence procurement strategies among domestic players.
Major suppliers in the region, including CIMC ENRIC, Chart Inc., and INOX India Limited, adapt their offerings to cater to specific regional demands. Local compliance mandates and cultural nuances impact B2B buying behaviors, highlighting the need for tailored solutions in the market. While the region progresses, energy grid resiliency and local infrastructure readiness play essential roles in shaping growth during the forecast period.
The ISO Tank Container market in South America represents a 5.00% share of the global landscape in 2025. Brazil and Argentina emerge because key players in this region, with growing economies that support increased demand for transportation and storage solutions. Infrastructure modernization, characterized by enhanced logistics networks and transportation corridors, significantly influences the market's growth trajectory. Local compliance mandates and regional trade agreements promote cross-border trade, further driving demand for ISO tank containers.
Investment in energy sectors, particularly in Brazil, supports the expansion of liquid and gas tank containers, addressing the rising needs of the chemicals and petrochemicals industries. The growth of localized manufacturing densities in these countries strengthens supplier networks, reducing lead times and transportation costs. By 2033, the market is projected to expand, reaching an estimated value of USD 2.9 billion, reflecting a compound annual growth rate of 9.3% during the forecast period.
The ISO Tank Container market in the Middle East and Africa reflects a modest 5.00% share of the global market in 2025. Significant growth opportunities arise from increasing demand for logistics solutions in the region, particularly in Saudi Arabia, the UAE, and South Africa. Investment in infrastructure modernization enhances operational capacity and reliability of supply chains in these countries. Key industries including chemicals, petrochemicals, and food and beverage sectors drive demand for ISO tank containers, contributing to overall market expansion.
The Middle East is expanding downstream chemical refining, driving the acquisition of standard and specialized tank fleets. Africa remains an emerging market where port modernization is unlocking new liquid bulk import corridors.
Domestic market participants, including companies like CIMC ENRIC and Cryocan, leverage localized procurement dynamics and strategic entry barriers to enhance their competitive position. The ongoing trend of nearshoring initiatives supports regional supply chain resilience, reducing dependency on international logistics and encouraging localized manufacturing densities. Emerging market front-runners benefit from favorable geographic regulatory frameworks that streamline compliance and trade policies.
In South Africa, increasing investment in energy infrastructure strengthens demand for ISO tank containers, particularly for the transportation of liquefied natural gas. The region's distinct cultural nuances influence B2B buying behaviors, requiring tailored marketing strategies to effectively engage stakeholders. Overall, the Middle East and Africa present a blend of opportunities driven by infrastructure development, strategic investments, and evolving market dynamics.
The ISO tank supply chain involves equipment manufacturers, leasing firms, logistics operators, depot networks, and end shippers. Manufacturers source high-grade stainless steel, valves, gaskets, and structural framing that comply with the ISO 6346 standard and international dangerous goods codes. Tank lessors purchase standard units to lease out to operators or direct chemical shippers under master lease or long-term arrangements.
Operational bottlenecks most commonly occur at intermediate touchpoints: tank cleaning depots, inspection facilities, and intermodal rail terminals. Because tank containers carry hazardous materials, units require certified washing, steam heating, and periodic pressure testing before being reloaded. Efficient depot networks and balanced two-way trade lanes are essential to prevent empty repositioning, which represents a major operational cost.
Pricing Trends and Analysis
Pricing structures in the ISO tank container market consist of new-build asset costs, daily leasing rates, and end-to-end freight tariffs. New-build prices depend heavily on raw material inputs, particularly nickel, chrome, and specialty stainless steel grades like 316L. Changes in component costs, such as relief valves, burst discs, and insulation materials, directly influence production quotes.
Daily leasing and operational freight rates follow global container shipping cycles and chemical output levels. Freight rates fluctuate based on ocean carrier space availability, port congestion surcharges, and intermodal fuel prices. Furthermore, specialized units such as T14 tank containers—used for corrosive and hazardous acids—and temperature-controlled gas tanks command significant price premiums over standard liquid units due to higher capital expenditure and maintenance requirements.
Attractive investment opportunities center on fleet digitization, specialized high-value equipment, and dedicated regional depot networks. Capital allocations toward smart telematics, heated tanks, and cryogenic equipment offer steady returns driven by high-margin chemical logistics contracts. Expanding specialized cleaning and repair infrastructure in emerging logistics hubs also addresses severe capacity bottlenecks.
Conversely, investors face distinct regulatory and cyclical risks. Asset utilization is directly tied to global chemical output and industrial manufacturing cycles. Changes to IMO regulations or transport safety mandates can require costly structural retrofits for older tank designs. Additionally, imbalances in global trade flows pose financial risks by driving up the expense of repositioning empty containers back to major export centers.
The COVID-19 pandemic disrupted the tank container sector through severe port congestion, blank sailings, and labor shortages at cleaning depots. During the initial outbreak, factory shutdowns curtailed chemical production, causing short-term fleet idling. However, as trade resumed, severe imbalances in container vessel schedules stranded equipment in import regions, creating artificial shortages across major export hubs.
The recovery phase accelerated the long-term adoption of intermodal tank transport. Supply chain disruptions highlighted the vulnerability of intermediate bulk containers and drums, prompting chemical producers to switch to ISO tanks for safer bulk storage and transport. Shippers also recognized the value of remote asset tracking, cementing IoT monitoring as a permanent operational requirement across modern fleets.
The global market for intermodal tank transport relies on specialized operators, lessors, and manufacturers. Operators manage large fleets to provide door-to-door chemical logistics and liquid bulk handling. Leading logistics service providers include Stolt-Nielsen Limited, HOYER GmbH, Bertschi AG, Bulkhaul Limited, and Royal Den Hartogh Logistics. These operators coordinate intermodal transportation networks across rail, deep-sea shipping, and road haulage.
On the manufacturing front, companies like CIMC Group, Welfit Oddy, and Chart Industries drive equipment supply. CIMC Group leads standard container production, while Welfit Oddy specializes in stainless steel vessels and high-specification builds. Chart Industries engineers cryogenic and specialized gas vessels. Together, these industry leaders set operational benchmarks by adhering to the ISO 6346 standard and international safety conventions.
The ISO Tank Container market experiences a highly competitive environment driven by strategic consolidation and partnerships among key players. Companies pursue mergers and acquisitions to enhance their market reach and operational capabilities. Major firms including CIMC ENRIC, Singamas Container Holdings Limited, and Chart Inc. operate in the market, engaging in collaborative efforts that strengthen their position.
Product differentiation remains crucial, with firms investing in research and development to create proprietary technologies and specialized tank containers. For instance, Cryocan and INOX India Limited focus on developing cryogenic tank containers that cater to specific industry needs. This innovation contributes to a competitive landscape where companies leverage unique offerings to capture market share.
Pricing strategies play a significant role in shaping competition, with suppliers implementing flexible pricing architectures to address varying customer requirements. This approach enhances customer retention and brand equity dynamics within the market. The threat of new entrants influences existing players to fortify their market presence by optimizing their value chain and establishing procurement leverage. Companies increasingly focus on adapting to these pressures.
The future competitive outlook for the ISO Tank Container market reflects defensive imperatives and strategic growth vectors. Companies focus on enhancing operational efficiencies and expanding into emerging markets, creating additional opportunities for investment and innovation within the sector.
Stolt-Nielsen Limited (Stolt Tank Containers): Operates the largest global fleet of tank containers, specializing in hazardous chemicals, food-grade liquids, and clean petroleum products.
HOYER GmbH: Provides integrated logistics solutions, dry bulk services, and European intermodal transportation networks with strong depot coverage.
Bertschi AG: Focuses heavily on European rail-road intermodal tank transport and specialized chemical logistics, with growing operations in Asia and the Middle East.
Bulkhaul Limited: Manages a large, dedicated fleet serving global deep-sea routes with tailored transport solutions for bulk liquids.
Royal Den Hartogh Logistics: Specializes in bulk chemical and gas logistics, emphasizing combined transport to reduce transport emissions across continental networks.
CIMC Group: The dominant global container manufacturer, producing high volumes of ISO-certified tanks for global leasing companies and transport operators.
Welfit Oddy: A premier manufacturer of specialized stainless steel tank containers, custom designs, and high-pressure units.
Chart Industries: Focuses on engineered systems, including vacuum-insulated cryogenic tanks for liquefied natural gas and industrial gases.
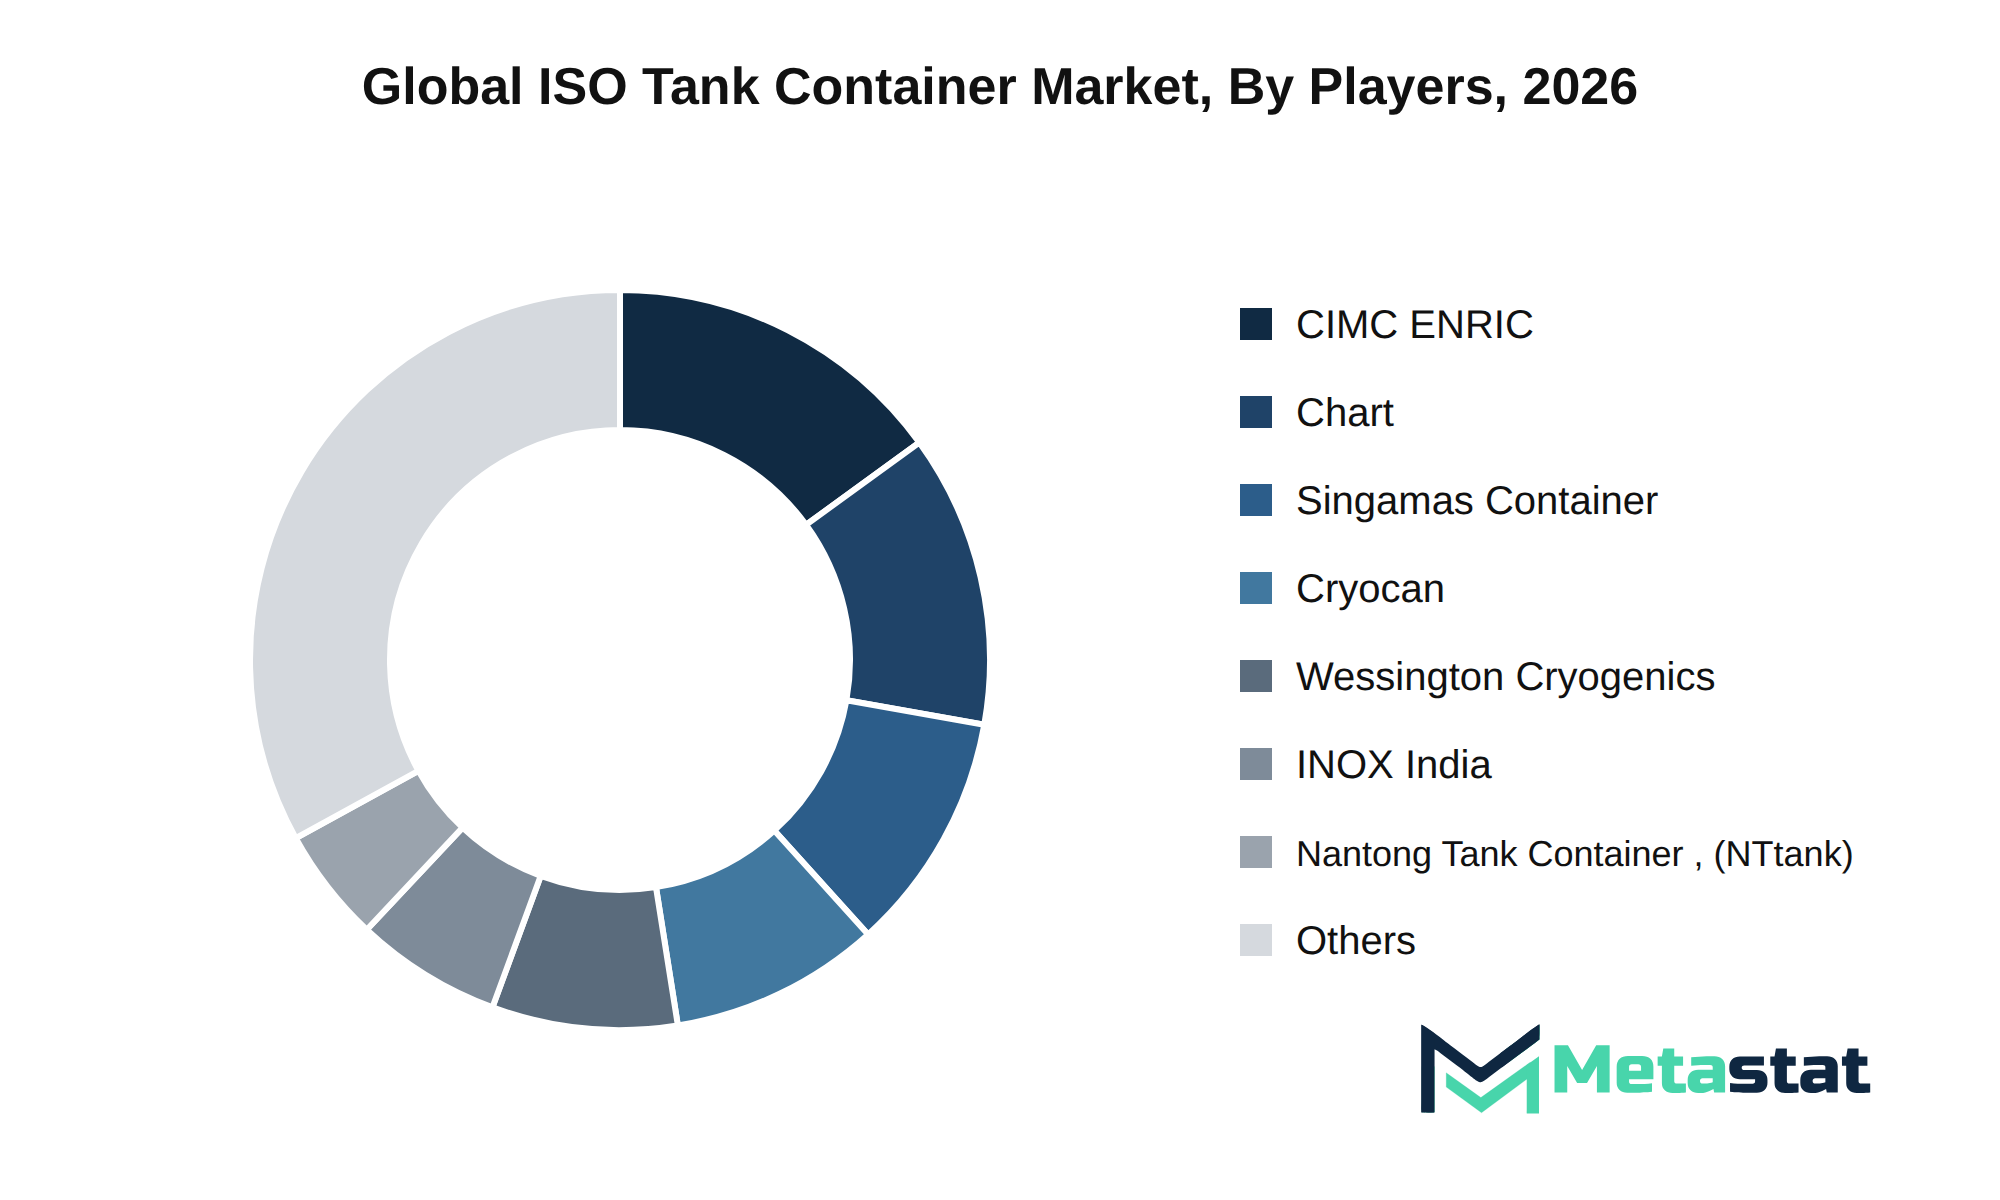
Market concentration varies significantly between manufacturing and fleet operations. The manufacturing tier shows high consolidation. A small group of Chinese and international manufacturers, led primarily by CIMC Group, accounts for the clear majority of standard new-build production capacity.
In contrast, the operating tier remains moderately fragmented. Stolt-Nielsen Limited and HOYER GmbH hold leading positions by fleet volume, supported by established international depot networks. Mid-tier regional operators, such as Bertschi AG in European rail corridors and Bulkhaul Limited in oceanic trade lanes, maintain strong positions in dedicated sectors. Leading operators differentiate themselves by investing in dedicated cleaning stations, proprietary maintenance depots, and custom-engineered equipment rather than competing solely on volume.
Market size is forecast to rise from USD 1.4 billion in 2025 to over USD 2.9 billion by 2033, achieving a compound annual growth rate (CAGR) of 9.3%. This growth trajectory reflects robust demand across key sectors, driven by advancements in logistics and increased global trade activities.
The bull case for the ISO Tank Container market hinges on accelerated adoption of next-generation technologies and innovations in transportation and storage solutions. Increased investments in infrastructure and strategic capital allocation will likely enhance operational efficiencies, stimulating demand across various industries. In contrast, the bear case identifies potential challenges, including economic downturns or regulatory hurdles that could impact growth. These dynamics will shape the competitive landscape and influence market players’ strategies over the forecast period.
Regional growth will vary, with Asia Pacific anticipated to dominate the market share, supported by heightened industrial activity and strong demand from end-use industries. North America and Europe follow, benefitting from established supply chains and regulatory frameworks that drive market expansion. Overall, the ISO Tank Container market presents numerous avenues for growth attributed to stakeholders navigating evolving trends, regulations, and market demands.
Strategic realignments, fleet modernizations, and cross-border partnerships define recent market movements. Tank container operators are expanding intermodal logistics footprints in developing trade lanes, particularly within Southeast Asia and the Middle East. Fleet renewal programs focus heavily on swapping older units for modern, lightweight T11 tank containers to optimize payload capacity.
Partnerships between chemical producers and logistics providers have shifted from spot-market hires to dedicated, long-term fleet management agreements. Additionally, manufacturers and operators are forming alliances with industrial Internet of Things (IoT) vendors. These collaborations aim to equip fleets with active telematics systems directly on the factory floor, improving end-to-end asset visibility.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the ISO Tank Container market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 9.3% from 2026 to 2033 |
|
Revenue Unit |
USD billion |
|
Segmentation |
By Tank Type, Capacity, End-Use Industry, and Region |
|
By Region |
North America (By Tank Type, Capacity, End-Use Industry, and Country)
|
|
Europe (By Tank Type, Capacity, End-Use Industry, and Country)
|
|
|
Asia Pacific (By Tank Type, Capacity, End-Use Industry, and Country)
|
|
|
South America (By Tank Type, Capacity, End-Use Industry, and Country)
|
|
|
Middle East and Africa (By Tank Type, Capacity, End-Use Industry, and Country)
|
Find answers to common questions about this report
The ISO Tank Container market size was valued at USD 1.4 billion in 2025.
The ISO Tank Container market is projected to grow at a CAGR of 9.3% during the forecast period from 2026 to 2033.
The North America ISO Tank Container market size is estimated to reach USD 0.5 billion by 2033.
Gas Tank Containers lead the ISO Tank Container market, with a projected value of USD 0.6 billion by 2033. This segment's growth reflects a compound annual growth rate of 9.9 percent.
Rising economic growth, infrastructure investment, and sustainability initiatives drive the ISO Tank Container market. Increased global trade and technological integration enhance operational efficiency, while the focus on eco-friendly practices aligns with consumer preferences, positioning the market for significant growth. The market is projected to reach USD 2.9 billion by 2033, reflecting a compound annual growth rate of 9.3 percent during the forecast period.
Asia Pacific holds the dominant share of the ISO Tank Container market, accounting for 42 percent in 2025. This significant share positions the region ahead of Europe, which holds 30 percent.
The ISO Tank Container market growth is restrained by regulatory compliance hurdles, which create barriers for new entrants and impose financial strains on smaller firms. Macroeconomic headwinds, supply chain disruptions, resource scarcity, and labor shortages further complicate the market landscape, impacting production timelines and operational efficiency.
Rising economic growth, infrastructure investment, and sustainability initiatives favor product adoption in the ISO Tank Container market. Key sectors, including chemicals and food and beverage, drive demand, while technological integration enhances operational efficiency and supports environmental compliance. This dynamic environment positions the market for significant growth, projected to reach USD 2.9 billion by 2033.
The ISO Tank Container market is estimated to reach a valuation of USD 2.9 billion by 2033.
Key players in the ISO Tank Container market include CIMC ENRIC, Singamas Container Holdings Limited, Cryocan, Chart Inc., INOX India Limited, Wessington Cryogenics, and HOYER GmbH.
The conflict disrupted direct land-rail corridors linking East Asia and Western Europe, forcing intermodal tank transport to reroute through maritime lanes and southern transit passages. In addition, trade sanctions prompted western operators to wind down local operations and reassign fleets, increasing transit times and operational costs on affected Eurasian trade lanes.
The Asia-Pacific region is experiencing the fastest growth, led by expanding chemical manufacturing in China, India, and Southeast Asia. Growth is driven by rapid industrialization, regulatory shifts moving hazardous liquids out of traditional drums, and sustained investments in intermodal rail and port infrastructure.
High capital requirements, complex regulatory frameworks, and depot infrastructure present the largest barriers to entry. Operating a fleet requires adherence to strict IMO regulations, international dangerous goods codes, and recurring inspection schedules. Additionally, established players hold proprietary global networks of cleaning, heating, and repair facilities that are difficult and costly for new entrants to replicate.
Key innovations focus on integrated digital tracking and advanced lightweight construction. Fleets are incorporating ATEX-certified IoT sensors that monitor real-time temperature, pressure, location, and liquid levels. Mechanical designs feature high-efficiency composite insulation materials and refined structural frames that reduce tare weight while maintaining full compliance with the ISO 6346 standard.
Consolidation has centered on expanding geographic reach, depot services, and multimodal capabilities. Examples include Royal Den Hartogh Logistics acquiring regional chemical logistics firms to strengthen its presence in Asia and Europe, along with major operators purchasing regional tank cleaning and maintenance depots to secure reliable turnaround capacity.
Prices vary according to manufacturing origin, raw material costs, vessel capacity, and design specifications. Standard capacity units—typically 21,000 to 26,000 liters—built in Asia carry lower manufacturing costs than custom-engineered, high-pressure vessels produced in Europe or South Africa. Furthermore, specialized designs with anti-corrosive linings or complex heating systems command significantly higher capital costs than general-purpose liquid tanks.
Operators are cutting carbon emissions by shifting road freight to electrified rail and inland waterway networks. Companies are also adopting water-recycling and energy-efficient steam systems across tank cleaning stations, fitting lightweight components to optimize cargo payload efficiency, and trialing alternative fuels for road transport legs.
Choose Your License
Global ISO Tank Container Market
LEAD ANALYST
Last Updated: September 2026
Enterprise zero-trust network rollouts are often slowed down by multi-cloud transit latency and proprietary hardware retirement schedules. This study provided realistic total cost of ownership models comparing cloud-delivered security edge solutions against traditional hardware refreshes. The analysis of contract renewal lengths and software maintenance fees gave us clear visibility into enterprise replacement cycles over the next three to five years.
Scaling antibody-drug conjugate manufacturing hinges on contract manufacturing availability for high-potency active ingredients. The MetaStat Insight analysis looked closely at global cleanroom slot constraints, bioconjugation batch failure rates, and supply chain redundancies between the US, Europe, and India. The supplier capability matrix proved genuinely useful for our team when mapping secondary source options across our clinical pipeline.
Floating offshore wind feasibility relies heavily on specialized installation vessel availability and port crane limits, which most broad renewable energy forecasts ignore. The report delivered a thorough analysis of dry dock capacity, mooring chain supply constraints, and raw material pricing trends for deepwater anchor installations. It served as a solid independent sanity check for our offshore project capital expenditure assumptions.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950