
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Military Tactical Communication Market Size, Share, By System Type (Tactical Radio Systems, Tactical SATCOM Systems, Tactical Data Link Systems, Tactical Networking and Backhaul Systems, Tactical Mobile and End-User Device Systems, Tactical Intercom and Crew Communication Systems), By Component (Hardware, Software, Services), By Platform (Land, Airborne, Naval and Maritime), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5238
September 14, 2026
259 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $22.1 Billion in 2025, projected to reach $37.7 Billion by 2033 at a 6.9% CAGR.
Dominant Segment: The Tactical Radio Systems segment leads the market, driven by increasing demand for reliable communication solutions among military forces. Advancements in technology, such as software-defined radios, enhance operational capabilities and interconnectivity.
Geographic Lead: North America is the leading region in the Military Tactical Communication market, supported by advanced defense infrastructure and ongoing modernization initiatives. The U.S. military's focus on technological advancements ensures strategic superiority.
What's Inside: This report provides comprehensive competitive coverage, detailed analyses of market dynamics, and forecasts extending to 2033. It includes segmentation by system type, component, and platform, offering insights into growth drivers and challenges.
Increased Demand for Technological Integ: The market is experiencing significant growth due to rising demand for technological integration, with organizations seeking solutions that incorporate automation and advanced software applications to enhance operational capabilities.
Regulatory Compliance and Geopolitical I: Challenges related to regulatory compliance and geopolitical instability are impacting the market, creating uncertainties in supply chains and complicating the production process for communication systems.
The global Military Tactical Communication market was valued at USD 22.1 billion in 2025 and is projected to reach USD 37.7 billion by 2033, growing at a CAGR of 6.9% over the forecast period.
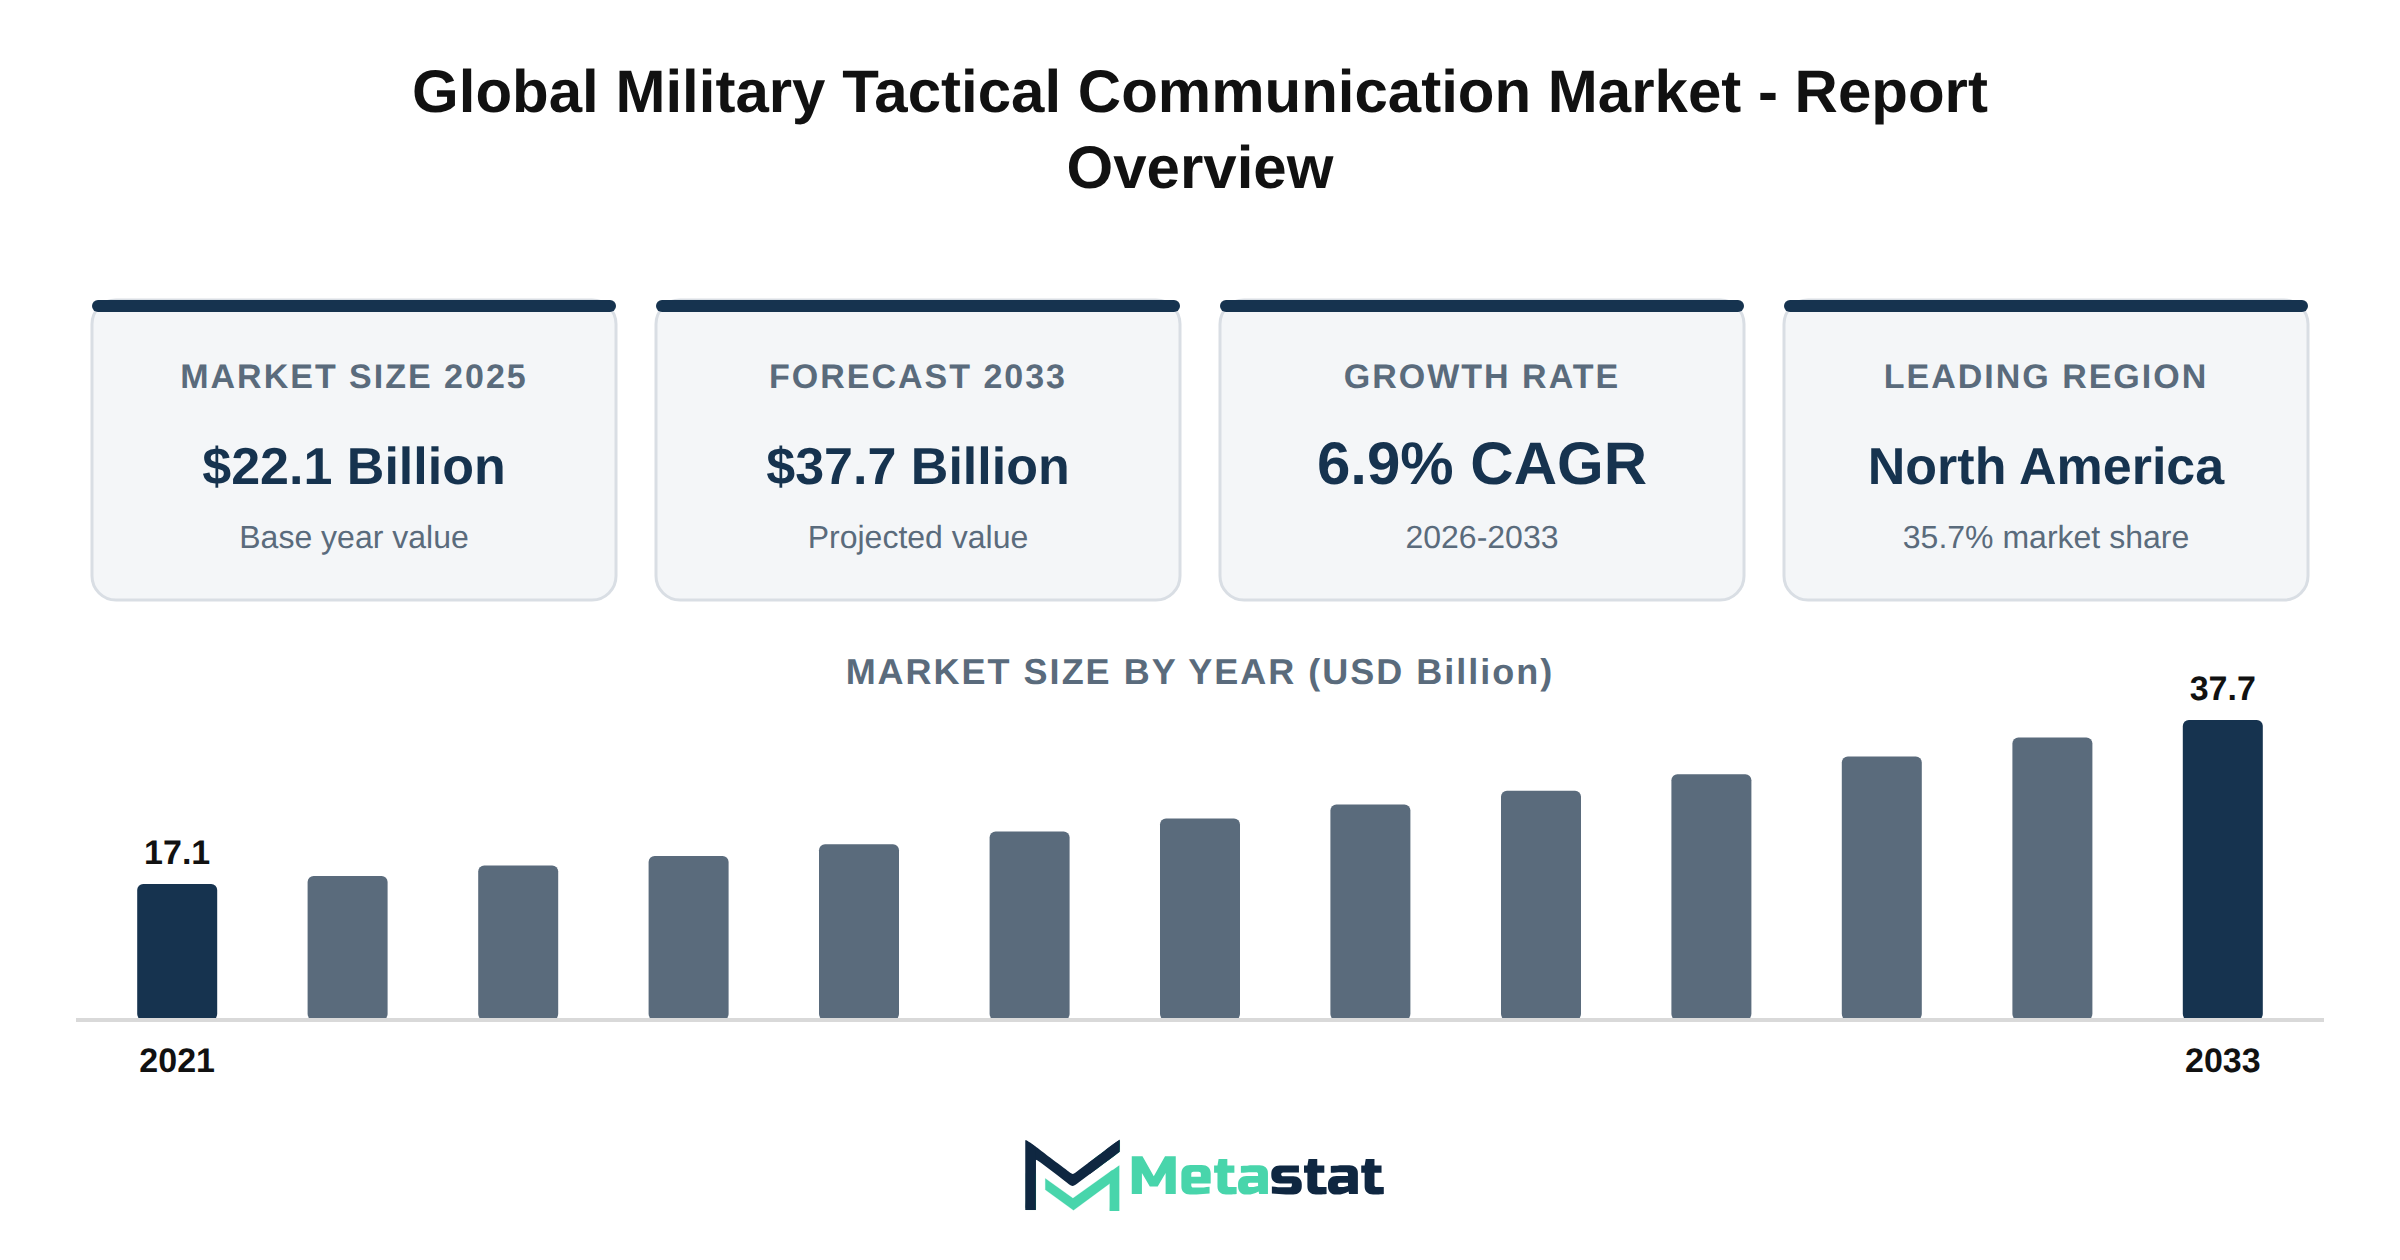
The Military Tactical Communication market is projected to grow from USD 22.1 billion in 2025 to USD 37.7 billion by 2033, reflecting a compound annual growth rate (CAGR) of 6.9%. Historical data indicates a steady rise in market value, starting from USD 17.1 billion in 2021 and reaching USD 20.6 billion in 2024. This growth trajectory signifies increasing demand for advanced communication systems within military operations.
Factors driving the expansion of the market include the adoption of tactical 5G and private networks, which enhance communication capabilities. Secure tactical end-user device (EUD) adoption supports effective communication in various operational environments. Radio-EUD and ATAK interoperability enable collaboration among military units, facilitating efficient information sharing and decision-making processes.
Developments in classified mobility and CSfC certification play a vital role in ensuring secure communications. Anti-jam and electronic warfare-resilient networking capabilities provide an added layer of security, crucial for modern military operations. The defense procurement landscape, alongside device refresh cycles, influences investments in advanced technologies, thereby driving market growth.
Regulatory compliance and regional risk frameworks guide the development and deployment of military communication systems. Disruptions within the supply chain landscape impact logistics architecture and sourcing strategies, necessitating adaptive approaches among market players. R&D trajectories focus on next-generation innovations, emphasizing sustainable transformation and decarbonization efforts in military operations.
Market fragmentation remains a significant characteristic, with numerous players competing to capture market share. M&A dynamics influence the competitive environment, shaping the value chain and procurement processes. Understanding customer journey dynamics and capital allocation strategies enhances operational effectiveness, ensuring alignment with future strategic outlooks.
The Military Tactical Communication market is experiencing significant advancements driven by the adoption of tactical 5G and private networks. These technologies enhance data transmission capabilities, ensuring secure communications in diverse operational environments. Military organizations prioritize the integration of these networks to improve operational effectiveness and enable real-time data sharing among troops.
Secure tactical end-user device (EUD) adoption represents a critical focus area, attributed to military forces increasingly relying on mobile devices for communication and data exchange. These devices require stringent security protocols to protect sensitive information from potential cyber threats. Manufacturers are investing in advanced encryption technologies to ensure that tactical EUDs meet the necessary security standards.
Interoperability between radio-EUD systems and applications including the Android Team Awareness Kit (ATAK) enhances situational awareness for military personnel. This integration allows for effective communication and data sharing, improving coordination during operations. The market recognizes the necessity of ensuring compatibility between various communication platforms.
Classified mobility and Commercial Solutions for Classified (CSfC) certification are gaining importance, driven by military organizations striving to maintain secure and mobile communication capabilities. Compliance with CSfC requirements supports the deployment of commercial technologies while safeguarding classified information, promoting innovation while ensuring security.
Anti-jam and electronic warfare-resilient networking solutions are essential for maintaining communication in contested environments. These technologies protect military communications from interference and disruption, allowing forces to operate effectively under adverse conditions. Investments in robust anti-jamming solutions are crucial for maintaining operational effectiveness.
Defense procurement and device refresh cycles significantly influence market dynamics, with military organizations regularly updating their communication systems to align with technological advancements. This continuous refresh ensures that forces maintain access to the latest capabilities, enhancing their operational readiness.
Regulatory compliance, standards, and regional risk frameworks shape the operational landscape for the Military Tactical Communication market. Adherence to established standards ensures that systems are interoperable and secure, while navigating regional regulations presents challenges for manufacturers seeking to expand their market presence.
Disruptions in the supply chain landscape, logistics architecture, and sourcing dynamics impact the availability and cost of military communication systems. Manufacturers adapt to these challenges, ensuring that they maintain reliable supply chains to meet the growing demand in the market.
The fragmented nature of the market, characterized by numerous players and varying capabilities, drives competition and innovation. M&A dynamics play a role in shaping the competitive landscape, because companies seek to enhance their portfolios and expand their market reach.
Investment in research and development trajectories leads to next-generation innovations within the Military Tactical Communication market. This commitment to R&D is essential for developing advanced technologies that meet evolving military needs and enhance operational effectiveness.
Corporate imperatives focus on sustainable transformation, decarbonization, and circular economy dynamics. The market is increasingly prioritizing environmentally friendly practices, influencing procurement strategies and product development.
Future strategic outlooks highlight the importance of capital allocation and infrastructure investments in driving growth. Companies are focusing on high-value recommendations to enhance their competitive positions and address the evolving needs of military customers.
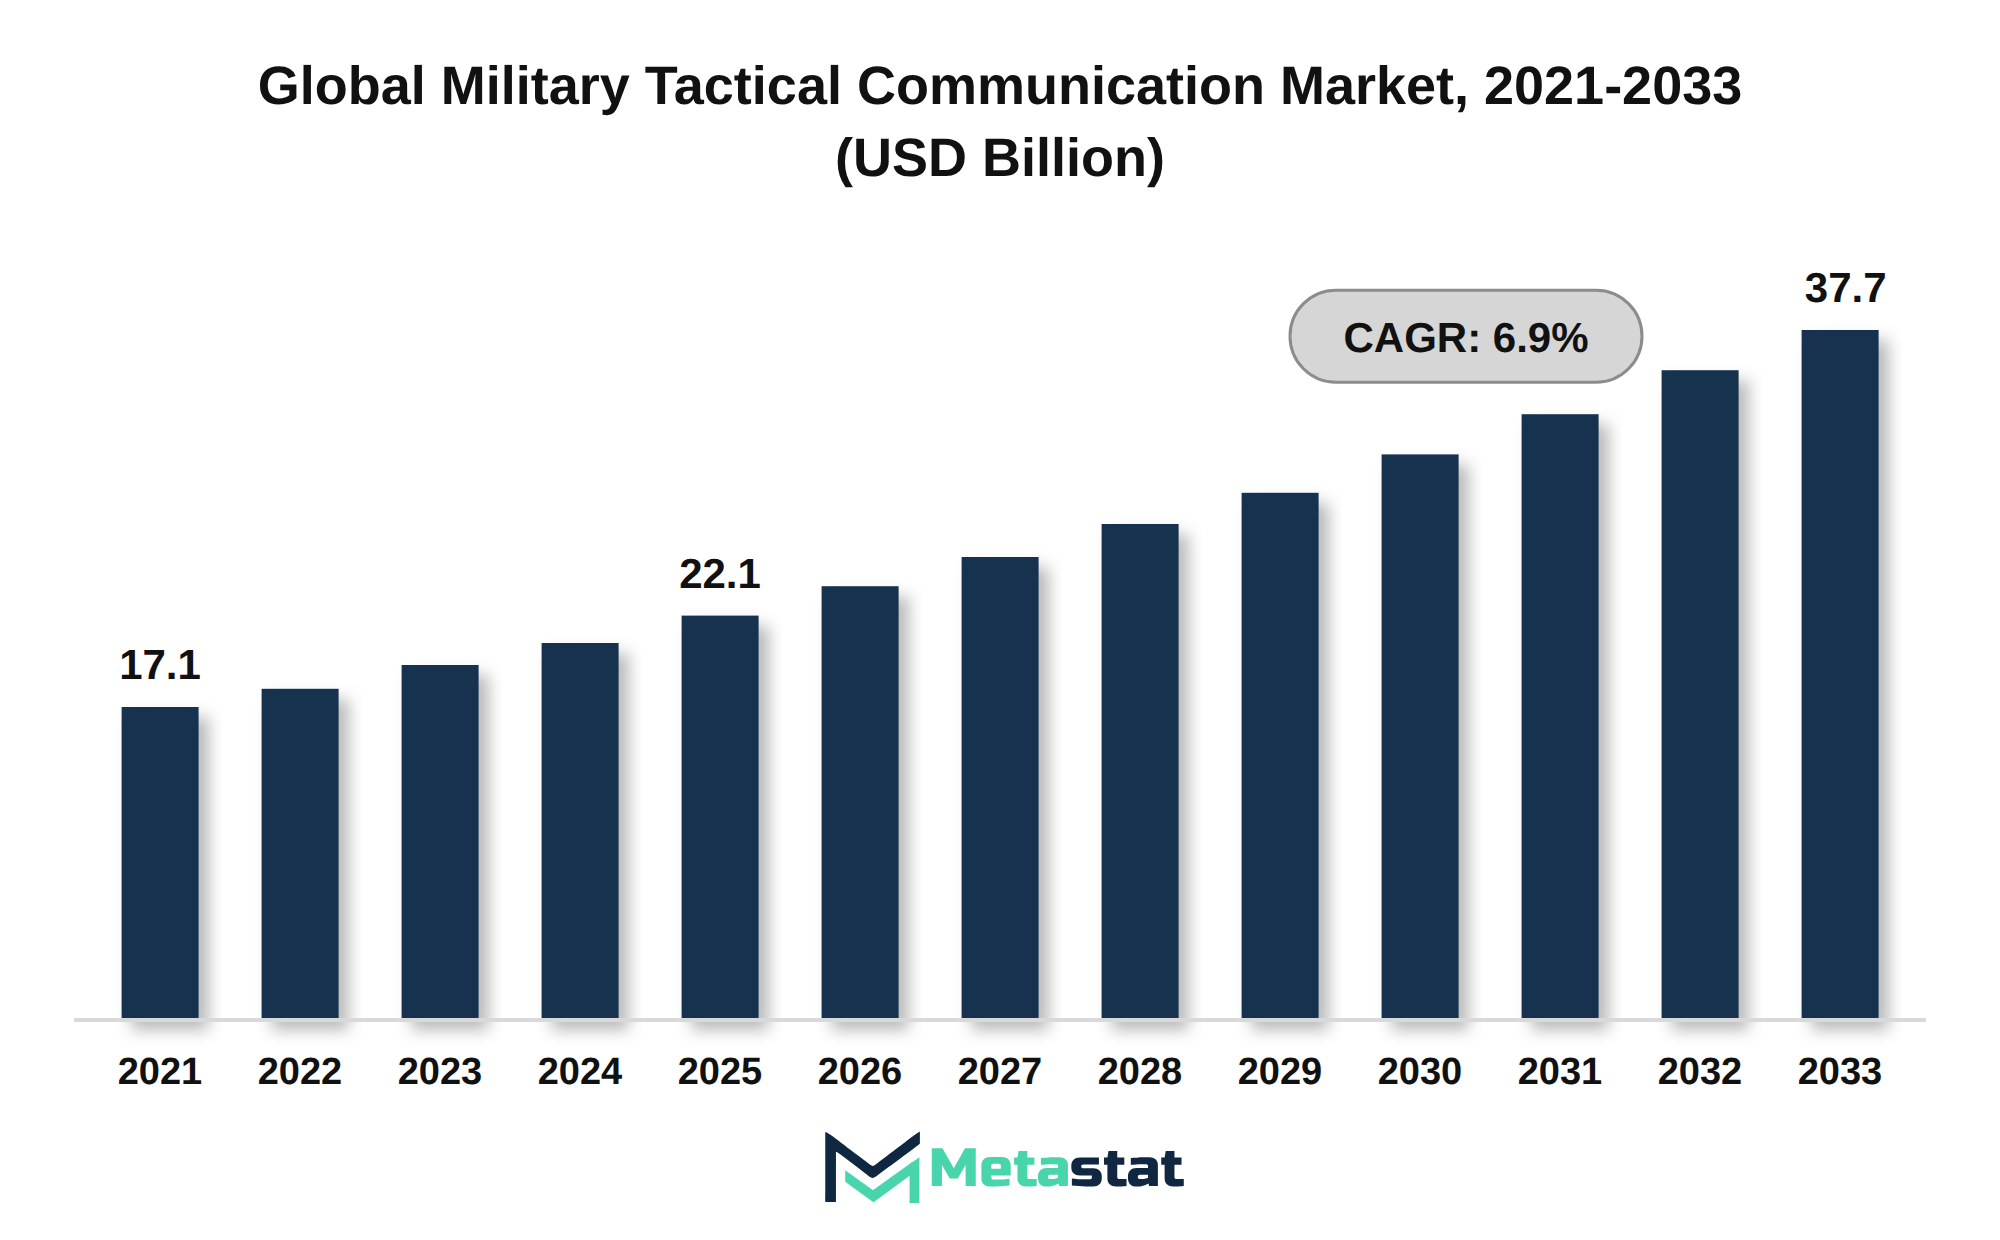
Increasing capital investment environments significantly influence the Military Tactical Communication market. Factors including GDP growth, favorable interest rates, and enhanced public-private spending power create a robust financial landscape. Venture funding has expanded, particularly for technologies addressing defense requirements. This influx of capital facilitates technological integration, enabling advancements in tactical communication systems.
The demand for innovative communication solutions arises from heightened geopolitical tensions and modernization initiatives across armed forces. Nations prioritize upgrading their defense capabilities, resulting in substantial investments in military technologies. This shift enhances operational productivity and efficiency within defense sectors and drives competition among suppliers. Consequently, the market experiences sustained growth, with an expected compound annual growth rate of 6.9% through 2033, reflecting increased investment in advanced communication solutions.
Military organizations seek to digitize legacy processes and automate communication frameworks, escalating demand for advanced systems. Investments directed toward research and development promote innovation-led product diversification, addressing the evolving needs of defense forces. The military's commitment to upgrading communication networks ensures continued expansion of the Military Tactical Communication market, reinforcing its strategic importance in modern warfare.
The Military Tactical Communication market experiences significant growth driven by increasing demand for technological integration. Organizations seek to enhance operational capabilities through solutions that incorporate automation, artificial intelligence, and advanced software applications. This shift results from the necessity to digitize legacy processes, leading to improved data management and communication efficiency across military operations.
The drive for technological integration impacts various sectors within the market. Tactical radio systems and SATCOM systems benefit significantly from advancements in digital technologies, enabling effective interoperability among platforms. Enhanced interoperability supports multi-domain operations, where different military branches collaborate effectively. Consequently, suppliers prioritizing innovative technology development position themselves favorably to capture market share and meet evolving defense requirements.
The ongoing integration of technology drives considerable investment in research and development. This trend allows companies to expand their product offerings and deliver advanced solutions that address specific military communication needs. Investments in technological advancements contribute to increased efficiency and cost-effectiveness, ultimately driving demand for the Military Tactical Communication market.
The Military Tactical Communication market faces significant challenges due to regulatory compliance and geopolitical instability. Tightening regulations across various jurisdictions impose stringent requirements on communication systems, increasing costs and complicating the production process. Suppliers encounter hurdles in aligning their offerings with diverse legal mandates, resulting in delays and potential market entry barriers.
Geopolitical instability exacerbates these challenges by creating uncertainties in supply chains and an unpredictable market environment. Conflicts or tensions in key regions disrupt the availability of critical components and resources, leading to project delays and increased operating expenses. These factors collectively restrict the growth potential of the market, prompting stakeholders to reassess investment strategies and prioritize resource allocation.
Consequently, the relationship between regulatory demands and geopolitical factors influences buyer sentiment within the Military Tactical Communication market. Organizations remain cautious in making long-term commitments when faced with fluctuating regulations and geopolitical uncertainties, ultimately impacting market dynamics and growth forecasts.
Geopolitical fragmentation presents significant challenges for the Military Tactical Communication market, leading to trade deficits and tariff friction. This fragmentation complicates international collaborations and creates uncertainties in supply chains, which directly impacts operational efficiency. Various countries prioritize local production, placing additional burdens on manufacturers relying on imported components.
Technological disruptions further exacerbate these challenges. Rapid advancements in communication technologies require continuous investment in research and development, straining resources for firms operating within strict budget constraints. Complex R&D integrations hinder the ability of companies to keep pace with innovations while managing existing product lines.
Interoperability friction among different systems creates barriers to effective communication among military forces. Variations in technology standards across nations necessitate investment in solutions that ensure compatibility, adding to operational costs. The market experiences heightened pressure from rising input costs and compliance overhead associated with evolving legal liabilities, which constrains profitability.
Supply chain instability stemming from logistics disruptions significantly influences the market landscape. Issues including geopolitical tensions and environmental constraints lead to material shortages and increased transportation costs. Such disruptions create vulnerabilities that limit timely delivery of critical communication systems, affecting military readiness.
The Military Tactical Communication market faces ongoing pressures from tight labor markets and workforce skill gaps. Retaining skilled talent becomes increasingly difficult in a competitive environment where automation displacements threaten job security. These factors influence innovation, operational efficiency, and the ability to meet rising demand within the sector.
Growing regional demands significantly influence the Military Tactical Communication market. Security concerns and defense initiatives drive heightened investments in communication technologies across regions, particularly in North America and Europe. Infrastructure modernization in various nations supports this trend, ensuring advanced capabilities in tactical communication systems. Countries invest in upgrading existing military communication systems to enhance operational efficiency and interoperability among allied forces.
Technological disruptions contribute to market expansion. Innovations in software and hardware facilitate more efficient communication solutions. The rise of digital transformation initiatives pushes military organizations to adopt next-generation innovations, leading to improved tactical data links and networking systems. Sustainability imperatives increasingly guide procurement strategies, prompting suppliers to focus on eco-friendly technologies and solutions that align with environmental goals.
Geographical expansion into emerging markets presents opportunities for market participants to diversify offerings and meet unique local needs. The trend of strategic consolidation through mergers and acquisitions enhances competitive positioning in the Military Tactical Communication market, allowing companies to leverage shared technologies and resources. Evolving buying behaviors favor digital procurement shifts, prompting suppliers to adapt commercial models to attract new customers.
Overall, the combination of these regional demands, technological advancements, and strategic initiatives provides a favorable landscape for growth within the Military Tactical Communication market. Companies that align strategies with these evolving trends are expected to capitalize on increased demand and drive long-term success.
The Global Military Tactical Communication market is segmented based on System Type, Component, and Platform.
Tactical Radio Systems segment is valued at USD 9.7 billion in 2026 and is projected to reach USD 14.3 billion by 2033, at a CAGR of 5.6% during the forecast period. Increasing demand for reliable communication solutions among military forces drives growth in this segment. Key factors include advancements in technology, enabling enhanced operational capabilities and interconnectivity on the battlefield. Military forces prioritize the need for secure and efficient communication systems, resulting in a surge in procurement and modernization activities.
Technological maturation significantly impacts the Tactical Radio Systems segment, driven by innovations including software-defined radios and advanced encryption techniques that enhance performance. These next-generation upgrades improve communication reliability and interoperability among various military platforms. Evolving end-use dynamics, including the integration of tactical radio systems into joint operations and multinational exercises, further stimulate market expansion.
Regulatory compliance standards and certifications play a crucial role in shaping purchasing decisions within the market. Military organizations emphasize compliance with specific standards to ensure system reliability and security. This focus on compliance drives manufacturers to invest in R&D, leading to the development of more robust and advanced solutions.
Pricing volatility and margin pressures challenge suppliers in the Tactical Radio Systems segment. Fluctuations in raw material costs and supply chain vulnerabilities impact production expenses, compelling manufacturers to adopt efficient cost management strategies. Despite these challenges, opportunities for strategic investments and partnerships exist, allowing companies to enhance their competitive positions and seize growth opportunities in the evolving Military Tactical Communication market.
Demand for Tactical SATCOM Systems arises from the increasing need for reliable communication capabilities in military operations. The segment benefits from advancements in satellite technology, enabling secure and efficient communication across various platforms. This evolution directly responds to the growing complexity of modern warfare, where real-time data exchange and coordination are critical.
Adoption of these systems expands owing to military forces investing in next-generation upgrades that enhance operational efficiency. Increased focus on interoperability among different military branches drives this trend, ensuring integration of Tactical SATCOM Systems into existing communication frameworks. Enhanced capabilities in data transmission and encryption support mission success in diverse environments.
Investment in infrastructure and technological maturation facilitates a favorable environment for Tactical SATCOM Systems. The segment is estimated to reach USD 8.3 billion by 2033, at a CAGR of 8% during the forecast period. This growth indicates a strong trajectory attributed to military organizations prioritizing advanced communication solutions that align with strategic operational goals.
Regulatory compliance standards influence the adoption of Tactical SATCOM Systems. Military procurement processes increasingly emphasize certifications and policy adherence, ensuring that systems meet stringent operational requirements. These factors contribute to the resilience of the supply chain, allowing manufacturers to respond effectively to shifting market demands.
Competitive pressures necessitate continual innovation among suppliers. Manufacturers focus on developing disruptive alternatives that enhance performance and reduce costs, ensuring long-term sustainability in the Tactical SATCOM Systems segment. Strategic opportunity windows emerge because military forces recognize the value of next-gen communication technologies in enhancing operational readiness and effectiveness.
Strong growth characterizes the Tactical Data Link Systems segment within the Military Tactical Communication market, which is expected to reach USD 5.3 billion by 2033. Increasing demand for real-time data sharing among military forces drives this expansion, enhancing operational effectiveness and situational awareness in various operational theaters.
Technological maturation influences segment development. The evolution of secure, high-capacity data links aligns with the need for interoperability among allied forces, prompting investments in next-generation upgrades. This trend encourages innovation in data link technologies, enabling integration with existing platforms.
Regulatory compliance standards and military certifications shape the landscape, with stringent requirements enhancing system reliability and performance. This compliance ensures that Tactical Data Link Systems meet operational needs while adhering to international standards, impacting procurement decisions across defense agencies.
Cost structures and pricing volatility pose challenges, affecting budget allocations in an environment of increasing defense expenditures. While military organizations prioritize modernization, Tactical Data Link Systems represent vital investments. Strategic opportunity windows arise for suppliers who adapt to evolving military requirements and offer solutions that enhance mission success while ensuring cost-effectiveness.
Significant developments within the Military Tactical Communication market stem from the increasing reliance on Tactical Networking & Backhaul Systems. This segment is projected to grow at a CAGR of 7.9% during the forecast period. Demand derives from the need for secure and efficient communication capabilities across various platforms, including land, air, and naval operations.
Expanding military budgets worldwide further contribute to the growth of this segment, with nations investing heavily in advanced communication technologies to enhance operational capabilities. Increased focus on network interoperability and resilience forms a critical driver, enabling effective communication among diverse military assets.
Technological advancements, including improved data transmission rates and enhanced encryption methods, support the development of next-generation Tactical Networking & Backhaul Systems. These innovations enable military forces to maintain connectivity in challenging environments, directly impacting mission success.
Market participants are continually exploring opportunities for product evolution, leading to the introduction of more integrated solutions that combine hardware and software components. This integration enhances the overall performance of communication systems, promoting greater adoption among military users.
While end-use dynamics evolve, major players in the sector focus on providing tailored solutions that address specific operational requirements. This strategy aligns with shifting consumption patterns, where military forces demand more versatile and adaptable communication systems.
Investment in research and development remains a priority, with companies working to mitigate risks related to technological obsolescence. By doing so, they address the concerns of potential substitution risks posed by emerging technologies.
Strategic opportunity windows arise from the increasing collaboration between defense contractors and technology firms, driving innovation and enhancing supply chain resilience. The outlook for Tactical Networking & Backhaul Systems reflects a commitment to addressing the evolving needs of the military, ultimately shaping the future of the Military Tactical Communication market.
Advancements in Tactical Mobile & End-User Device Systems focus on enhancing connectivity and communication capabilities for military personnel in various operational settings. Demand for these systems stems from evolving battlefield requirements, emphasizing real-time data sharing and secure communications. The introduction of next-generation technologies, including 5G and advanced encryption methods, strengthens the capability of mobile communications, leading to increased adoption in the field.
Market expansion benefits from the integration of artificial intelligence and machine learning, which streamline operations and improve decision-making processes. Manufacturers work towards meeting the growing needs for interoperability among diverse communication platforms, facilitating efficient collaboration among military forces. Product evolution emphasizes compact design, ruggedness, and user-friendly interfaces, ensuring efficacy in challenging conditions.
End-use dynamics highlight a shift towards mobile solutions that cater to individual soldier requirements, reflecting broader consumption trends in military tactics. Regulatory compliance standards influence product design and functionality, ensuring systems meet stringent military specifications. Strategic opportunity windows arise from ongoing modernization initiatives across defense sectors, driving investment in innovative solutions that enhance operational effectiveness.
Market players focus on maintaining supply chain resilience, addressing potential vulnerabilities through diversified sourcing strategies. Increased competition drives technological advancements, with emphasis placed on mitigating risks associated with technological obsolescence. Investments in research and development support disruptive alternatives that enhance the capabilities of mobile communication systems in military applications.
Overall, the Tactical Mobile & End-User Device Systems segment plays an integral role in the Military Tactical Communication market, reflecting the broader shift towards enhanced operational efficiency and adaptability in military operations.
Demand for Tactical Intercom & Crew Communication Systems arises from the increasing need for reliable and secure voice communication among military personnel. This segment plays a critical role in enhancing coordination and operational efficiency during missions, making it indispensable for modern warfare. The sector experiences steady growth due to advancements in audio quality, miniaturization of hardware, and integration with other communication systems. Technological maturation contributes to the segment’s expansion, with next-generation upgrades incorporating advanced features including noise cancellation and improved encryption protocols.
Product evolution within this segment aligns with shifts in consumption patterns, where military forces prioritize lightweight, portable communication solutions. Downstream applications span various military branches, including land, air, and naval platforms, reinforcing the importance of versatile intercom solutions. Regulatory compliance standards and certifications further shape the industry landscape, ensuring systems meet operational requirements and safety protocols. Margin pressures arise from fluctuating component costs; however, the segment adapts by optimizing supply chain resilience and exploring alternative sourcing strategies.
Strategic opportunity windows exist for manufacturers focusing on innovative technologies, including digital communication systems and software-defined networking. The Military Tactical Communication market benefits from increased capital investment driven by governments seeking to modernize their defense capabilities. Competitive dynamics intensify owing to players introducing disruptive alternatives, enhancing overall market growth while addressing challenges related to technological obsolescence.
Valued at USD 15.8 billion in 2026, the Hardware segment is projected to reach USD 23 billion by 2033, at a CAGR of 5.5% during the forecast period. Ongoing modernization and upgrading of military communication systems drive demand for hardware components, ensuring operational efficiency and interoperability across various platforms. Increasing complexity of military operations influences adoption, requiring advanced communication capabilities to support real-time decision-making and coordination among different military branches.
Technological maturation plays a critical role in this segment, enabling manufacturers to integrate next-gen technologies including artificial intelligence and machine learning into hardware systems. Evolution of products focuses on enhancing durability, reliability, and ease of integration with existing military infrastructure. End-use dynamics reflect a trend toward modular and scalable hardware solutions that cater to diverse operational needs. Consumption shift toward advanced tactical communication hardware signifies a growing emphasis on secure, resilient, and high-performance systems.
Regulatory compliance standards and certifications governing military hardware significantly impact market dynamics. Suppliers navigate stringent requirements to ensure that products meet operational specifications. Cost structures have evolved, with rising raw material prices affecting overall pricing strategies. Market pricing experiences volatility, influenced by fluctuations in demand and supply chain challenges, which exert margin pressures on manufacturers.
Strategic opportunity windows arise for companies investing in innovative hardware solutions that address emerging threats and operational challenges. The market offers significant potential for growth, particularly in regions with ongoing defense modernization initiatives. Capital investment outlook remains positive, driven by governmental defense budgets aimed at enhancing military capabilities, further supporting growth within the Military Tactical Communication market.
Growing demand for advanced communication solutions significantly influences the Software segment within the Military Tactical Communication market. Adoption of software that enhances data security and interoperability drives investments across military and defense organizations. This segment is projected to reach USD 9 billion by 2033, at a CAGR of 9.7% during the forecast period. Emerging technologies, including artificial intelligence and machine learning, support next-generation upgrades, enabling more efficient communication systems. Increased focus on regulatory compliance and certifications creates opportunities for software developers to offer innovative solutions that meet rigorous military standards. Downstream applications in various military platforms, including land, airborne, and naval systems, highlight the segment's importance in real-time tactical operations. Continuous technological advancements create cost pressures and pricing volatility, compelling software providers to maintain competitive pricing strategies. These dynamics contribute to a strategic opportunity window for both established players and new entrants in the market.
Services within the Military Tactical Communication market is projected to reach USD 5.6 billion by 2033. This growth stems from increasing requirements for training, maintenance, and operational support driven by militaries seeking to enhance overall communication capabilities. The rising complexity of military operations necessitates tailored service offerings that address specific mission demands and technological advancements.
Adoption of new technologies, including artificial intelligence and machine learning, drives service innovation and supports the integration of advanced communication systems. This process encourages defense contractors to expand service portfolios, ensuring that solutions remain relevant during rapid technological evolution in the market. Customization of services enhances user experience and performance, aligning with the unique needs of military agencies.
Demand for services reflects the broader trend of increasing digitization in military operations. The shift towards more integrated and automated systems places a premium on service providers that offer effective support and maintenance solutions. While militaries adopt next-generation communication technologies, the need for reliable services becomes critical to ensure operational readiness and mission success.
Strategic partnerships between service providers and military organizations improve compliance with regulatory standards and certifications. This collaboration enhances the credibility and reliability of service offerings, leading to improved market positioning. The focus on services in the Military Tactical Communication market is essential for sustaining long-term growth and operational effectiveness.
Valued at USD 14.5 billion in 2026, the Land segment is projected to reach USD 21.8 billion by 2033, at a CAGR of 6.1% during the forecast period. The growing emphasis on network-centric warfare drives demand for advanced land communication solutions, enhancing operational efficiency and situational awareness for military forces. Adoption of next-generation technologies, including software-defined radios and enhanced interoperability protocols, contributes to improved communication capabilities. Increased investment in defense budgets across various nations supports the expansion of this segment, facilitating the integration of advanced communication tools into land platforms.
This market experiences a shift toward digital and secure communication systems, aligning with evolving military strategies focused on rapid response and information superiority. Enhanced collaboration among defense contractors and technology providers drives innovations, enabling the development of integrated platforms that address the unique challenges of land operations. The rising complexity of military missions necessitates robust communication solutions, positioning the Land segment for sustained growth and a strong competitive edge within the Military Tactical Communication market.
Growth in the airborne segment within the Military Tactical Communication market reflects an increasing focus on advanced aerial communication capabilities. Factors driving this expansion include the modernization of military forces and the rising need for secure, reliable communication systems for airborne platforms. The segment is expected to reach USD 8.7 billion by 2033, at a CAGR of 7.9% during the forecast period.
Technological maturation significantly shapes this segment, with innovations in secure communication protocols and enhanced data transmission capabilities becoming essential. Next-gen upgrades in airborne systems contribute to improved operational efficiency and mission success, particularly in complex scenarios where effective communication is critical. The integration of advanced technologies, including artificial intelligence and machine learning, supports real-time data processing and situational awareness, driving adoption among military operators.
Changing end-use dynamics highlight the shift towards multifunctional airborne communication systems. Investments in research and development focus on creating adaptable solutions that meet the evolving requirements of military operations. Enhanced interoperability with ground and naval forces ensures effective coordination during joint operations, broadening the segment's appeal across various military branches.
Regulatory compliance and certification standards influence the direction and growth of the airborne segment. Adhering to stringent military specifications ensures reliability and performance under diverse operational conditions. Pricing volatility in components and systems impacts budget allocations for defense procurement, thereby shaping strategies for capital investment and long-term operational planning.
Strategic opportunity windows emerge owing to increased defense budgets by governments, particularly in light of geopolitical tensions. This trend enhances the investment landscape for airborne communication technologies, attracting both established and emerging players in the market. Continuous innovation and a commitment to meeting the rigorous demands of military operations will strengthen the airborne segment's position and drive competitive growth within the Military Tactical Communication market.
Significant investments in naval capabilities drive growth within the Naval & Maritime segment of the Military Tactical Communication market. Nations emphasize enhancing their naval forces, resulting in increased demand for robust communication systems that ensure effective coordination and real-time information sharing during operations. With a projected value of USD 7.2 billion by 2033, this segment experiences a compound annual growth rate of 6.1% from 2026.
Technological maturation advances the capabilities of naval communication systems. The integration of next-generation technologies, including advanced encryption and satellite communication, enhances secure communications, thus contributing to overall military effectiveness. While military operations increasingly rely on sophisticated communication networks, the necessity for interoperability among various platforms gains importance.
End-user dynamics reflect a strong push for modernization within naval fleets. The focus on integrating advanced systems ensures that naval forces maintain a tactical edge in evolving warfare scenarios. Regulatory compliance standards further shape the segment, compelling manufacturers to develop solutions that meet stringent operational requirements for naval engagements.
Pricing volatility in raw material costs impacts the overall value chain within the market. Strategic investments and long-term contracts with key suppliers enhance supply chain resilience, ensuring a steady flow of critical components for naval communication systems. This resilience supports manufacturers in managing production costs, thereby enabling competitive pricing strategies in the market.
With technological obsolescence presenting challenges, continuous upgrades and enhancements to existing systems are essential for maintaining operational effectiveness. Strategic opportunity windows arise from demand for innovative solutions aligning with evolving military strategies. This dynamic creates an environment ripe for capital investment in new technologies that address the changing landscape of naval operations.
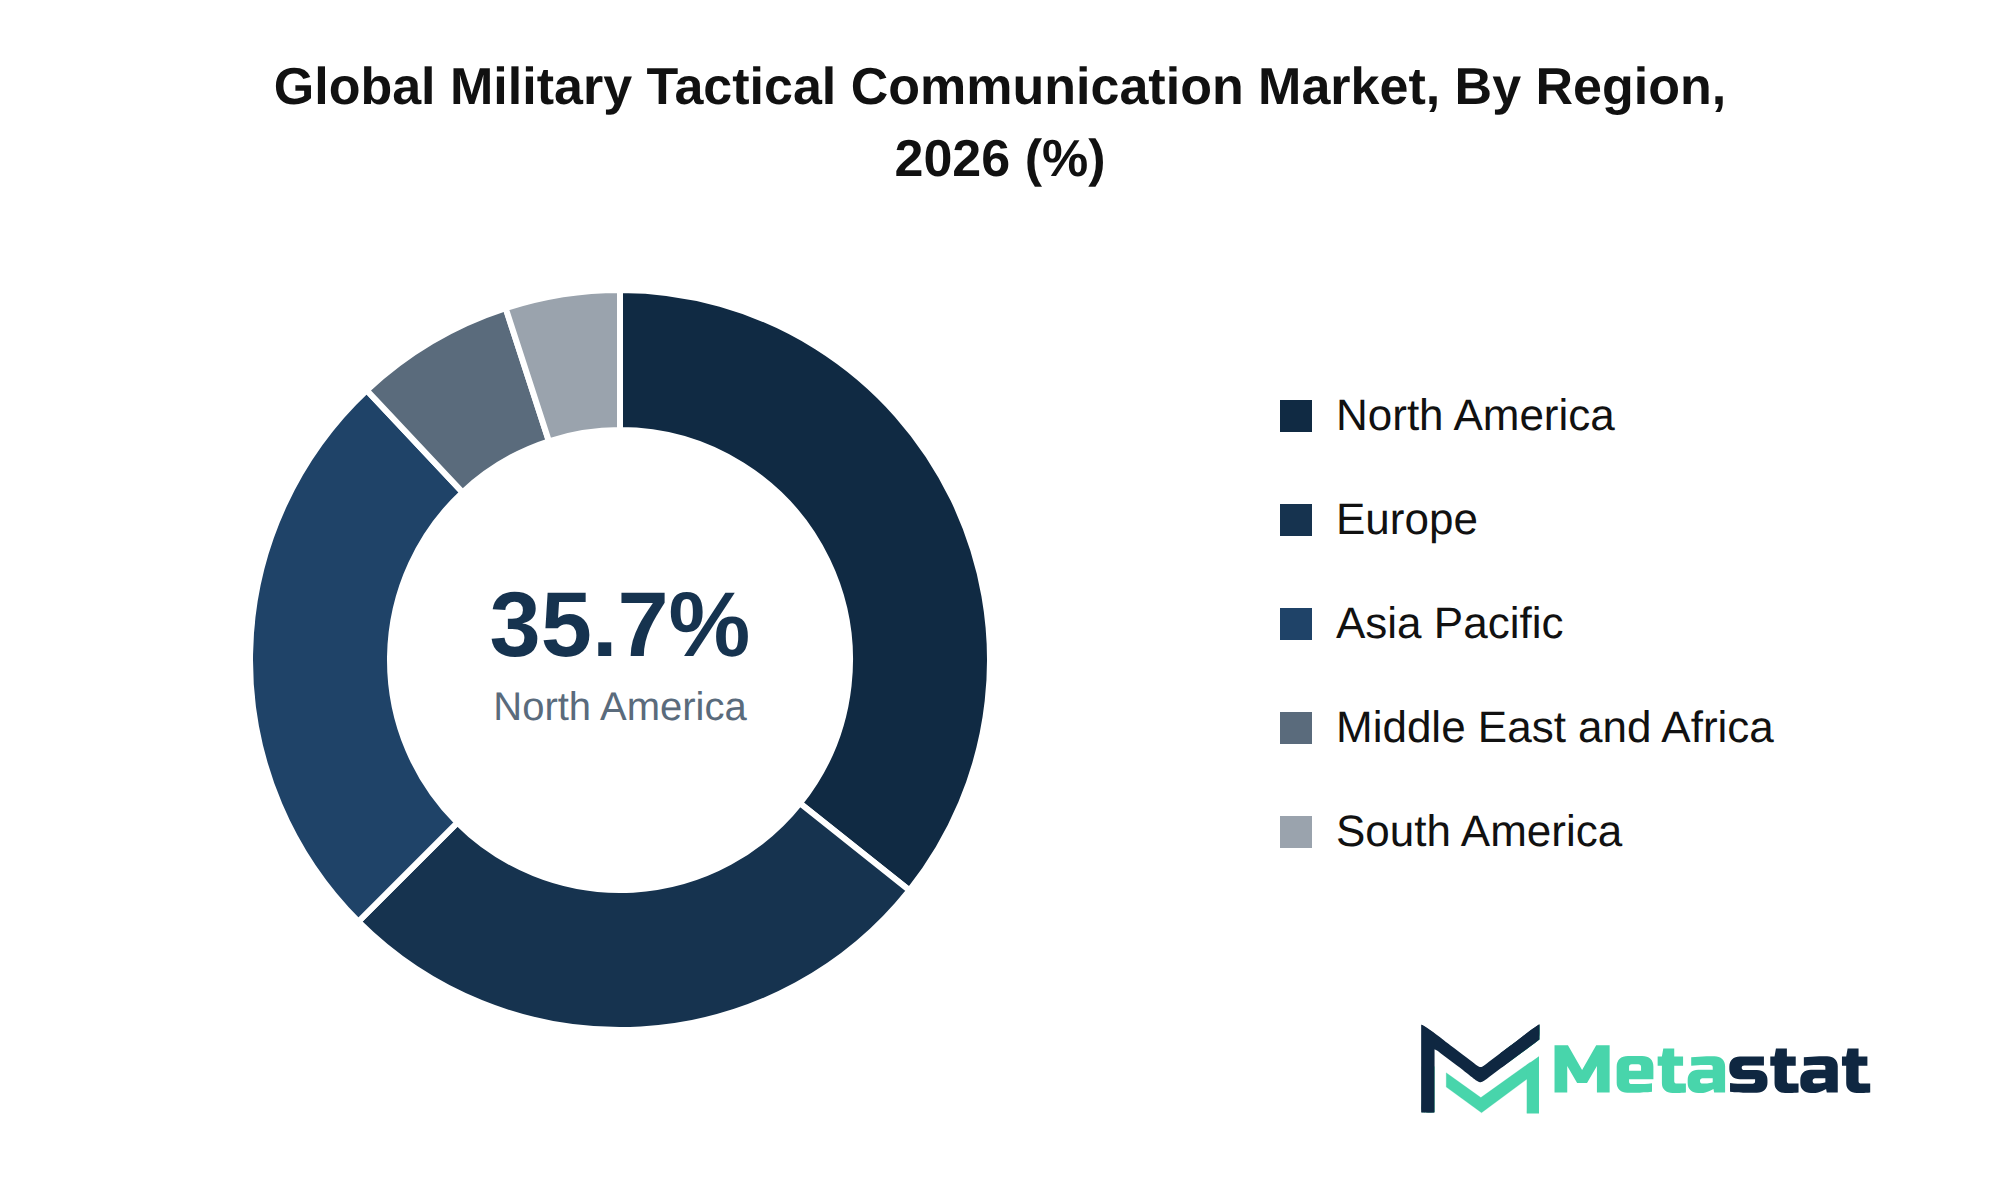
Based on geography, the Global Military Tactical Communication market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America presents a significant opportunity within the Military Tactical Communication market, driven by the region's advanced defense infrastructure and the increasing focus on modernization initiatives. The demand for military communication solutions stems from ongoing geopolitical tensions and the necessity for enhanced operational effectiveness across military branches. With an estimated market size of USD 12.4 billion by 2033, North America is expected to exhibit a compound annual growth rate (CAGR) of 6.9% during the forecast period.
The United States, Canada, and Mexico comprise the primary countries contributing to this market expansion. The U.S. military prioritizes technological advancements in communication systems to maintain strategic superiority. Investments in localized manufacturing and nearshoring initiatives enhance supply chain resilience and promote the adoption of innovative communication technologies. This strategy supports military readiness and encourages collaboration among domestic vendors, ultimately leading to a more competitive landscape.
Regional participants, including L3Harris Technologies, Inc. and RTX Corporation - Collins Aerospace, capitalize on this high-value replacement cycle, focusing on the development of Tactical Radio Systems and Tactical SATCOM Systems. The steady demand for these solutions reflects the military's commitment to integrating advanced communication systems that enhance real-time information sharing and operational coordination. Consequently, the market experiences incremental growth vectors fueled by both hardware and software advancements.
The Military Tactical Communication market in Europe is poised for significant growth, driven by a combination of technological advancements and increasing defense budgets across key nations. Countries including Germany, France, the UK, Italy, and Spain exhibit strong demand for enhanced military capabilities, necessitating sophisticated communication systems to ensure operational efficiency and interoperability among forces.
Strategic investments in infrastructure modernization support the adoption of advanced communication solutions. The presence of established defense contractors and regional players enhances competition, prompting innovations tailored to emerging battlefield requirements. This competitive environment encourages advancements in Tactical Radio Systems and Tactical SATCOM Systems, which are essential for effective military operations.
High-value replacement cycles for outdated communication equipment further stimulate market growth. European nations prioritize the integration of advanced technologies to enhance military readiness and capabilities. The growing emphasis on localized manufacturing aligns with regional procurement dynamics, facilitating quicker deployment of new systems.
Geopolitical fragmentation and evolving security threats influence procurement strategies, making the Military Tactical Communication market an attractive area for investment. Domestic market participants, including Thales S.A. and L3Harris Technologies, play crucial roles in meeting the demands of local armed forces while navigating regulatory frameworks and compliance mandates.
With a market share of 26.8% projected for 2025, Europe remains a vital region within the global Military Tactical Communication market. The integration of innovative solutions and proactive strategies will enhance European nations' defense capabilities, ensuring they remain competitive on the global stage.
Asia-Pacific represents a significant player in the Military Tactical Communication market, accounting for a share of 25.5% in 2025. Rising defense budgets across countries including China, India, and South Korea drive increased investments in military capabilities, particularly in advanced communication systems. Regional infrastructures require modernization to support evolving communication needs, creating demand for tactical systems that enhance operational effectiveness.
China, with its robust defense sector, leads the market through extensive investments in Tactical Radio Systems and Tactical SATCOM Systems. Japan emphasizes collaboration with allied nations to enhance joint operational capabilities, influencing demand for advanced communication technologies. India’s focus on indigenization and defense modernization initiatives promotes local manufacturing and procurement of tactical communication solutions.
South Korea's strategic initiatives to improve defense readiness contribute to heightened investments in tactical networking systems. Australia prioritizes interoperability with allied forces, enhancing its tactical communication infrastructure. Southeast Asia, driven by regional security concerns, experiences increasing adoption of tactical systems to strengthen defense capabilities.
Overall, the market benefits from heightened defense spending and strategic partnerships aimed at enhancing military capabilities, reflecting a positive growth trajectory for the Asia-Pacific region in the Military Tactical Communication market.
Brazil and Argentina represent key markets within the Military Tactical Communication market in South America, contributing to overall growth through various demand drivers. Increasing investments in defense modernization and regional security initiatives spur market expansion, while ongoing geopolitical tensions necessitate advanced communication solutions. Infrastructure modernization remains a priority since governments focus on enhancing military capabilities, driving demand for innovative communication systems.
Localized procurement dynamics shape the decision-making processes within these countries, where cultural nuances influence both purchasing behaviors and vendor selection. The market experiences a gradual shift towards domestic sourcing, with local manufacturers establishing partnerships to meet the unique needs of regional armed forces. Such dynamics create a competitive landscape where domestic players vie for a larger market share, enhancing overall service offerings.
Infrastructure readiness, including the region's energy grid resiliency and communication networks, plays a critical role in deploying effective military solutions. The Military Tactical Communication market in South America is anticipated to benefit from strategic foreign direct investment flows, allowing for enhanced product availability and increased competition among vendors. This trend positions the market for steady development since new opportunities for collaboration emerge, facilitating growth in underpenetrated territories.
The Military Tactical Communication market in the Middle East and Africa exhibits a unique growth trajectory driven by various factors. Significant military investments from countries like Saudi Arabia and the UAE enhance demand for advanced communication solutions. Infrastructure modernization initiatives and an increasing focus on achieving strategic defense capabilities fuel market expansion.
Market dynamics indicate a gradual transition towards localized manufacturing densities. Countries within the region enhance domestic production capabilities to reduce reliance on external suppliers. This strategy aligns with geopolitical trends aimed at achieving self-sufficiency in defense sectors.
In South Africa and the Rest of the Middle East and Africa, emerging market front-runners invest in military communication technologies. These investments address the need for robust tactical communication systems. The market is expected to experience steady growth during the forecast period.
Supply chain regionalization is evident, supported by cross-border trade corridors that facilitate procurement dynamics. Local compliance mandates shape the competitive landscape, with domestic market participants adapting to evolving consumer preferences. The Military Tactical Communication market reflects a blend of traditional defense needs and modern technological advancements, positioning it for sustained growth in the coming years.
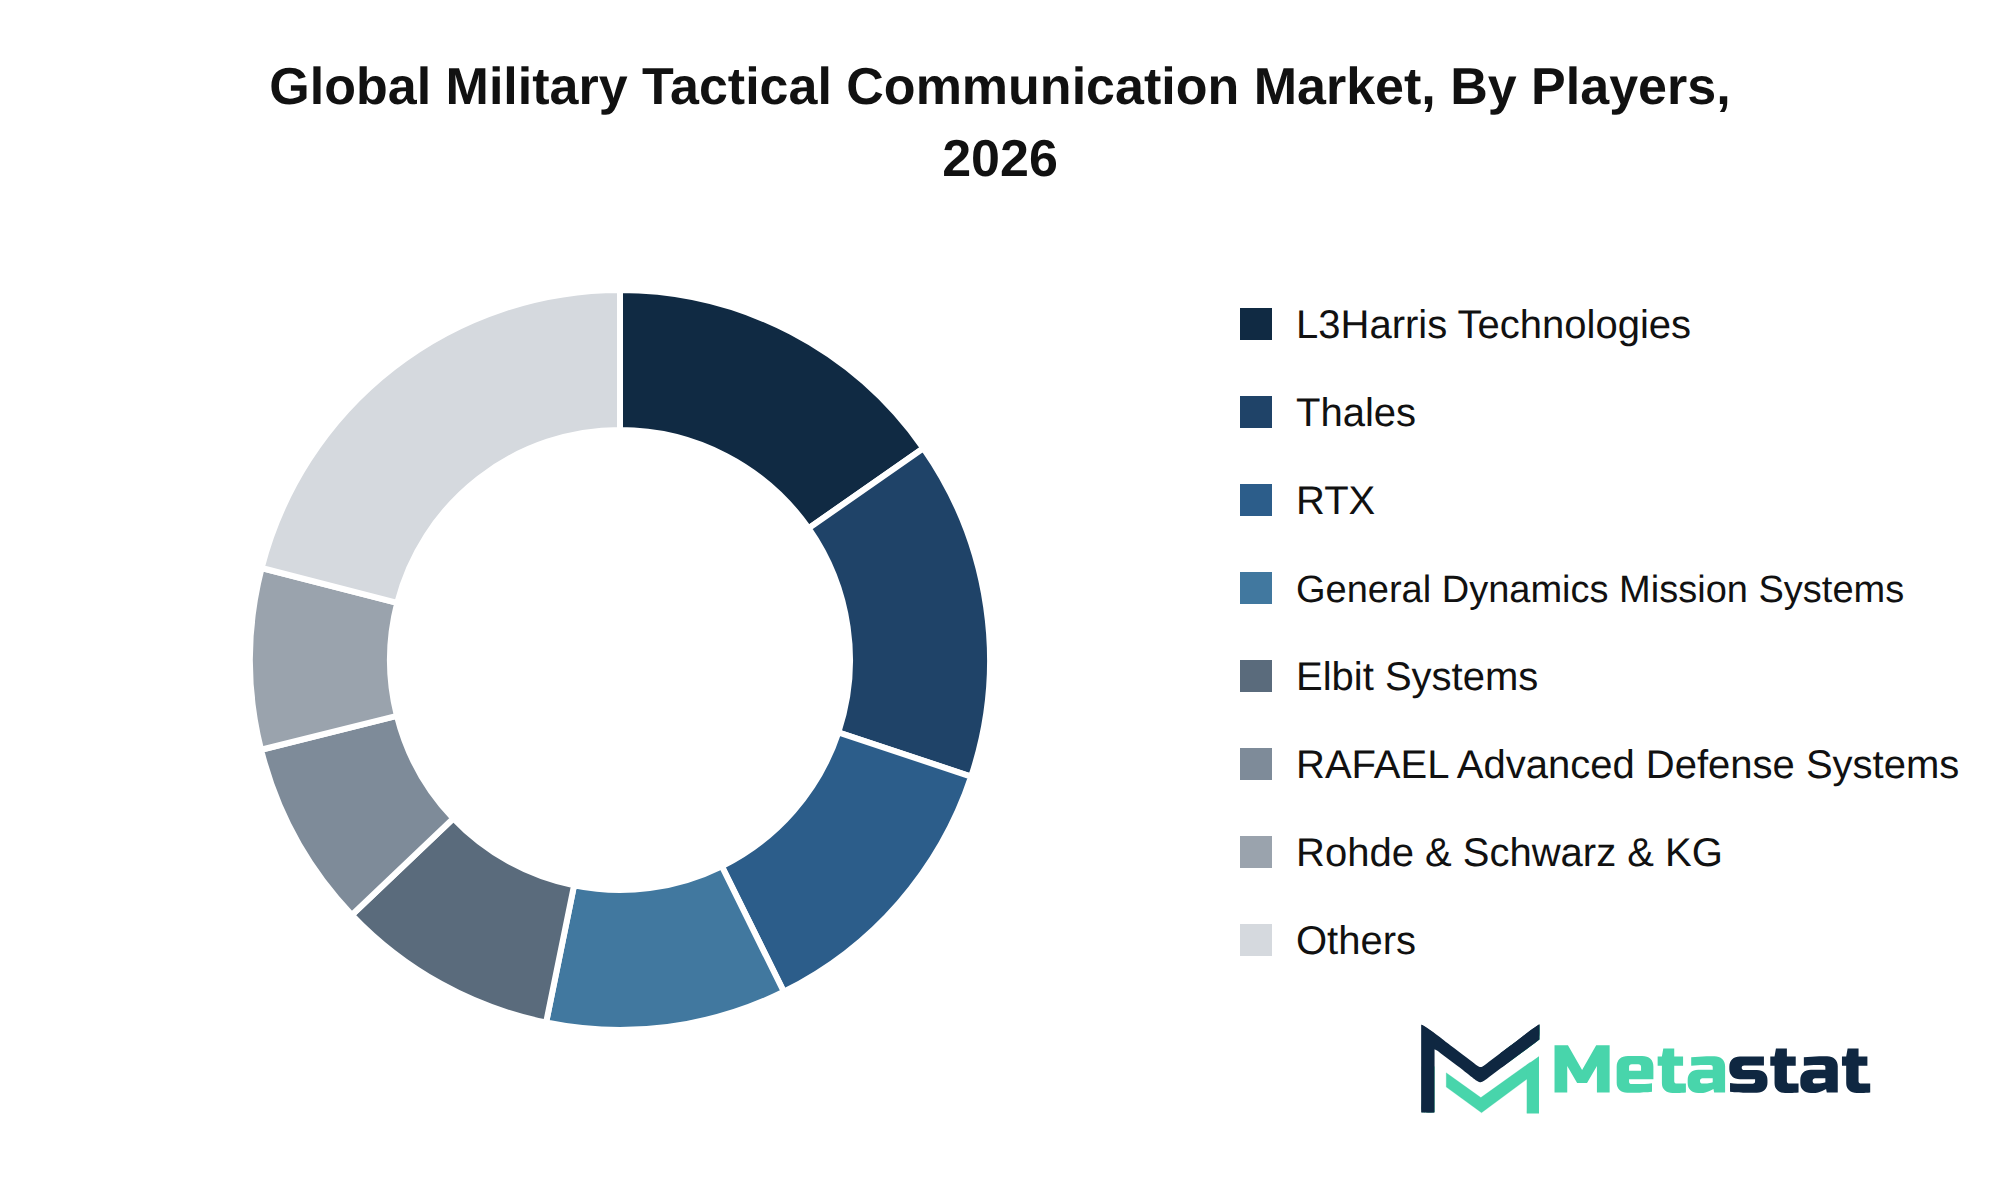
The Military Tactical Communication market features a diverse competitive landscape driven by strategic consolidation and evolving go-to-market strategies. Key players focus on product differentiation and technological advancements to enhance their market positions. Companies actively pursue mergers and acquisitions to strengthen their portfolios and expand their market reach.
In the Military Tactical Communication market, strategic alliances play a significant role in driving innovation and expanding capabilities. Companies like L3Harris Technologies, Inc. and Thales S.A. leverage joint ventures and cross-industry partnerships to enhance their product offerings. Such collaborations enhance technological defensibility and ensure access to advanced technologies while addressing barriers to entry for potential market entrants.
Value chain integration emerges because a critical competitive strategy, with firms focusing on supply chain dominance and procurement leverage. This approach optimizes costs and enhances customer retention strategies. Brand equity dynamics contribute to customer loyalty in the market, because established players like General Dynamics Mission Systems, Inc. and Elbit Systems Ltd. strengthen their reputations through consistent innovation and reliable service delivery.
Future competitive outlook suggests that the Military Tactical Communication market will experience intensified competition, fueled by advancements in R&D pipelines and proprietary technology moats. Companies are positioned to explore new growth vectors, enhancing their operational capabilities and market penetration.
Market size is forecast to rise from USD 22.1 billion in 2025 to over USD 37.7 billion by 2033. The base case represents a steady growth trajectory, maintaining a 6.9% compound annual growth rate (CAGR). A bullish outlook anticipates accelerated growth driven by advancements in next-generation technologies, increased defense budgets, and heightened geopolitical tensions. This scenario highlights the potential for expanded investment in military tactical communication systems, leading to greater revenue and market penetration.
Conversely, a bearish case reflects challenges stemming from economic uncertainties, changing regulatory environments, and potential supply chain disruptions. Such factors could hinder projected growth, emphasizing the importance of strategic capital allocation and proactive measures to adapt to shifting market dynamics. The Military Tactical Communication market remains positioned for continued evolution, driven by technological integration and the unfolding landscape of global defense requirements.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Military Tactical Communication market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 6.9% from 2026 to 2033 |
Revenue Unit | USD billion |
Segmentation | By System Type, Component, Platform, and Region |
By Region | North America (By System Type, Component, Platform, and Country)
|
Europe (By System Type, Component, Platform, and Country)
| |
Asia Pacific (By System Type, Component, Platform, and Country)
| |
South America (By System Type, Component, Platform, and Country)
| |
Middle East and Africa (By System Type, Component, Platform, and Country)
|
Find answers to common questions about this report
The Military Tactical Communication market size was valued at USD 22.1 billion in 2025, according to the Metastat Insights study.
The Military Tactical Communication market is projected to grow at a CAGR of 6.9% during the forecast period from 2026 to 2033.
The North America Military Tactical Communication market size is estimated to reach USD 12.4 billion by 2033.
Tactical Radio Systems lead the Military Tactical Communication market, with a projected value of USD 14.3 billion by 2033. This segment demonstrates significant growth potential, driven by increasing demand for advanced communication solutions.
Key drivers for the Military Tactical Communication market include increasing capital investment environments, heightened geopolitical tensions, and the demand for technological integration. Nations prioritize upgrading defense capabilities, leading to substantial investments in military technologies and innovative communication solutions that enhance operational productivity and efficiency.
North America holds the dominant share of the Military Tactical Communication market, with a value of USD 12.4 billion in 2033, representing 35.7 percent of the total market.
The Military Tactical Communication market growth faces significant challenges due to regulatory compliance and geopolitical instability. Tightening regulations increase costs and complicate production processes, while geopolitical tensions disrupt supply chains and create uncertainties, impacting operational efficiency and market dynamics.
Increasing capital investment environments significantly influence product adoption in the Military Tactical Communication market. Factors including GDP growth, favorable interest rates, and heightened geopolitical tensions drive demand for advanced communication solutions, prompting nations to prioritize upgrades in defense capabilities. This results in substantial investments in military technologies, enhancing operational productivity and efficiency.
The Military Tactical Communication market is estimated to reach a valuation of USD 37.7 billion by 2033.
Key players in the Military Tactical Communication market include L3Harris Technologies, Inc., Thales S.A., RTX Corporation - Collins Aerospace, Elbit Systems Ltd., RAFAEL Advanced Defense Systems Ltd., and Rohde & Schwarz GmbH & Co. KG.
Choose Your License
Global Military Tactical Communication Market
The analysts below cover Aerospace and Defense research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
Ambulatory surgical centers have very different purchasing cycles for robotic-assisted surgery platforms than major hospital networks. The MetaStat Insight study focused squarely on capital expenditure depreciation, procedural reimbursement pathways, and surgeon training overhead. That operational clarity made it much simpler to validate multi-year procedure growth forecasts against actual ambulatory center adoption patterns.
When planning edge sensor rollouts across refinery environments, generic IoT reports typically miss the harsh-environment certification bottlenecks. MetaStat Insight gave an objective evaluation of ATEX and Class 1 Division 2 hardware availability, along with realistic five-year maintenance cycle cost projections. The comparison of wireless mesh versus private cellular backhaul helped our team pressure-test network reliability models for remote processing facilities.
In the biological seed treatment space, registration timelines vary drastically between the European Union, Brazil, and North America. The MetaStat Insight research handled these cross-border regulatory barriers with genuine nuance, mapping commercialization pathways alongside historical field adoption rates. The segmentation between microbial strains and biochemical active ingredients was particularly well structured.
Explore related market intelligence reports worth reading alongside this one.