
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Digital Crop Farming and Precision Agriculture Market Size, Share, By Offering (Hardware, Software, Services), By Application (Farm Planning, Records & Analytics, Equipment Guidance, Steering & Fleet Telematics, Planting & Seeding Optimization, Crop Monitoring & Scouting, Irrigation & Water Management, Nutrient Management & Fertilization, Crop Protection & Precision Spraying, Harvesting, Yield Mapping & Harvest Management), By Crop Type (Cereals & Grains, Oilseeds & Pulses, Fruits & Vegetables, Cotton & Other Fiber Crops, Sugar Crops, Plantation & Permanent Crops, Forage & Fodder Crops), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5258
September 16, 2026
303 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $15.7 Billion in 2025, projected to reach $42 Billion by 2033 at a 13.1% CAGR.
Dominant Segment: The Hardware segment leads the market, projected to grow from USD 8 billion in 2026 to USD 17.2 billion by 2033, driven by increasing adoption of precision agriculture technologies that enhance productivity.
Geographic Lead: North America is the leading region, expected to generate USD 13.5 billion by 2033, supported by robust investments in technology and a strong emphasis on innovative farming practices.
What's Inside: The report provides a comprehensive analysis of market dynamics, competitive landscape, and detailed forecasts from 2026 to 2033, covering offerings, applications, and crop types.
Emerging Trends: Technological integration and a shift towards sustainable practices are driving growth, with significant demand for advanced solutions that optimize resource usage and enhance operational efficiency.
Market Dynamics: Macro-economic factors and evolving consumer preferences are influencing investment in precision agriculture, while regulatory compliance challenges and geopolitical tensions pose hurdles to market growth.
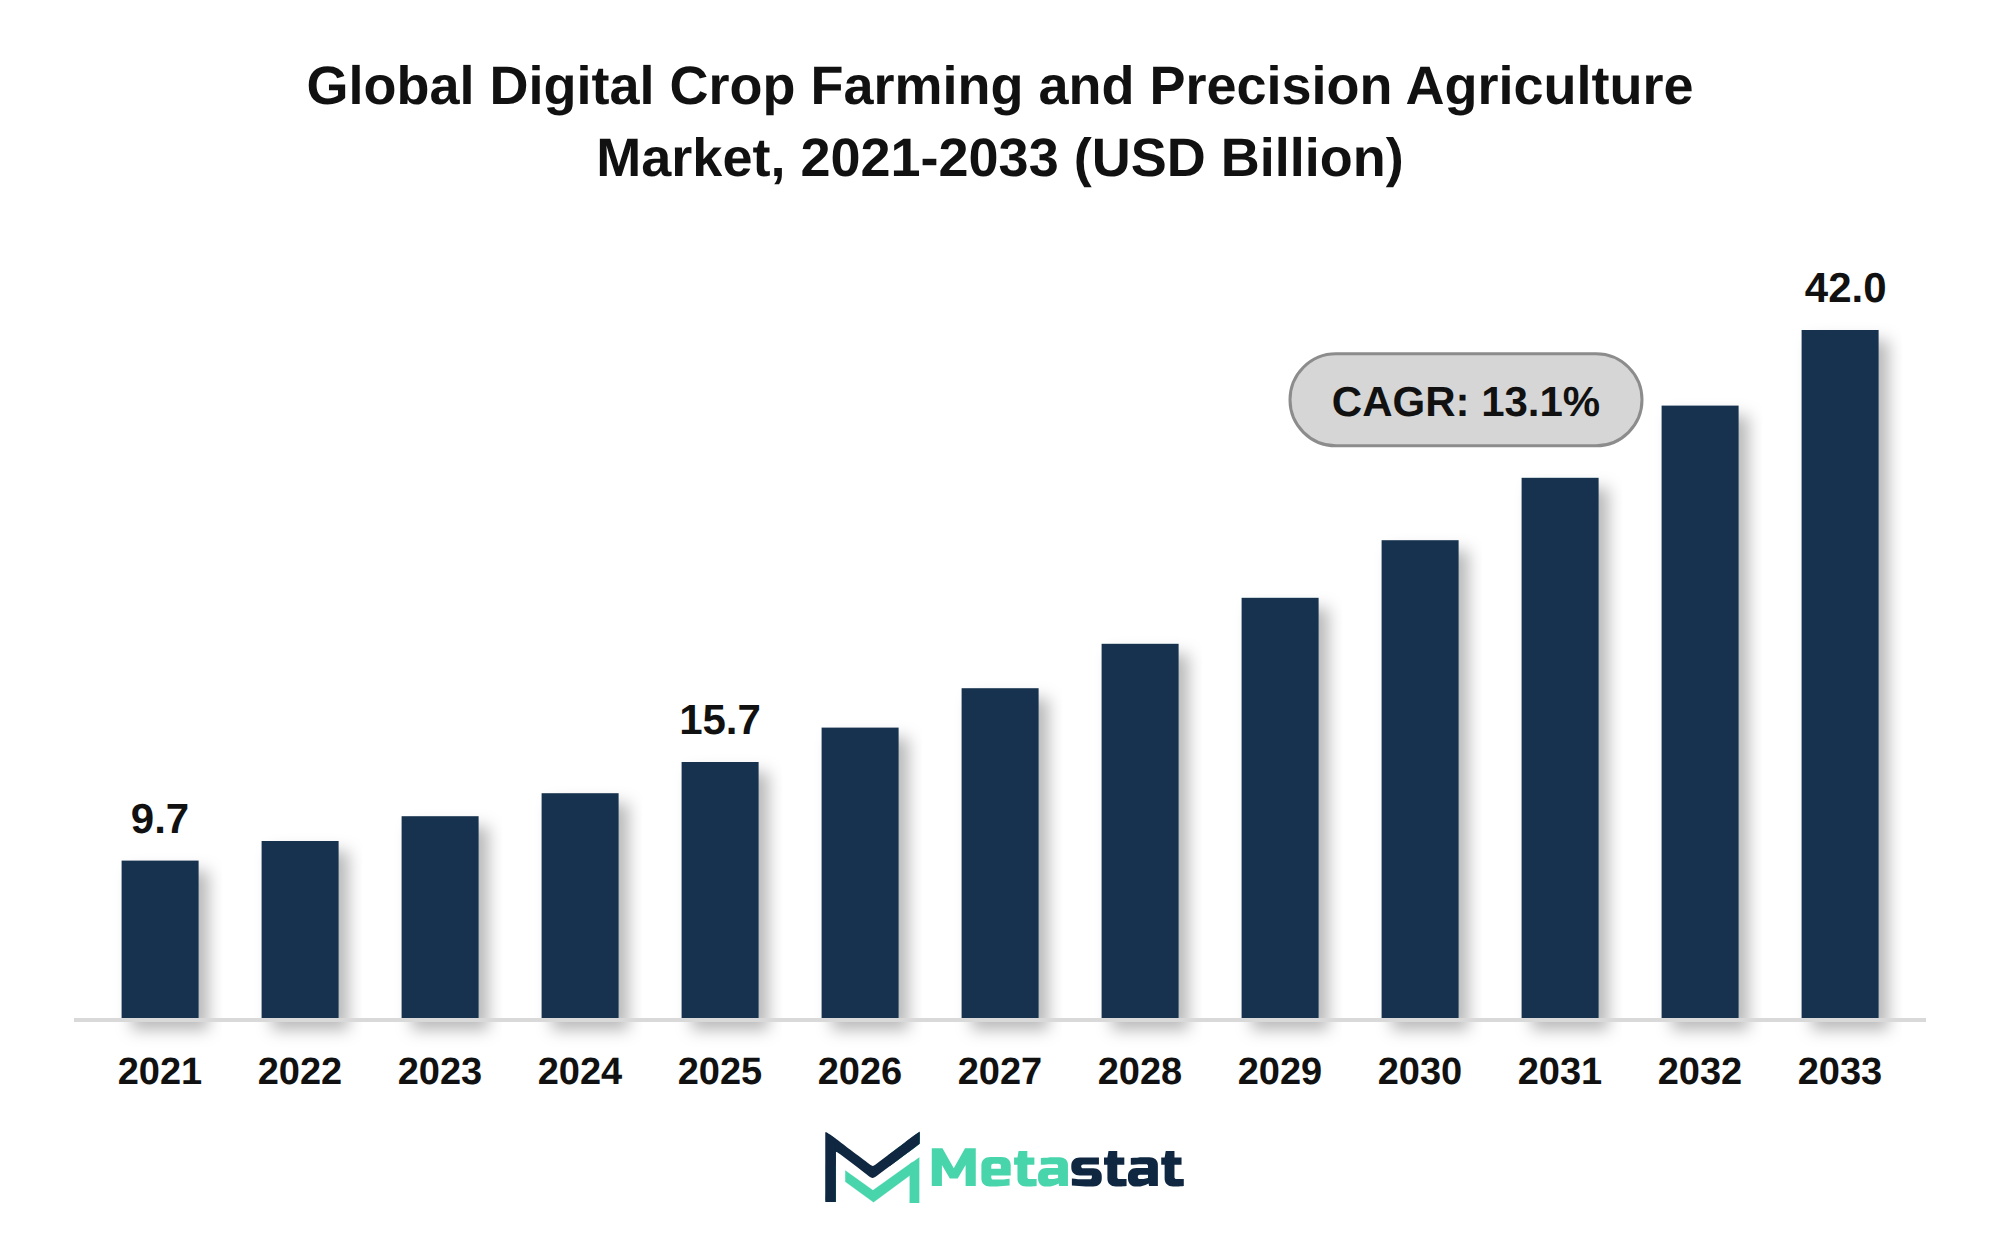
The global Digital Crop Farming and Precision Agriculture market was valued at USD 15.7 billion in 2025 and is projected to reach USD 42 billion by 2033, growing at a CAGR of 13.1% over the forecast period.
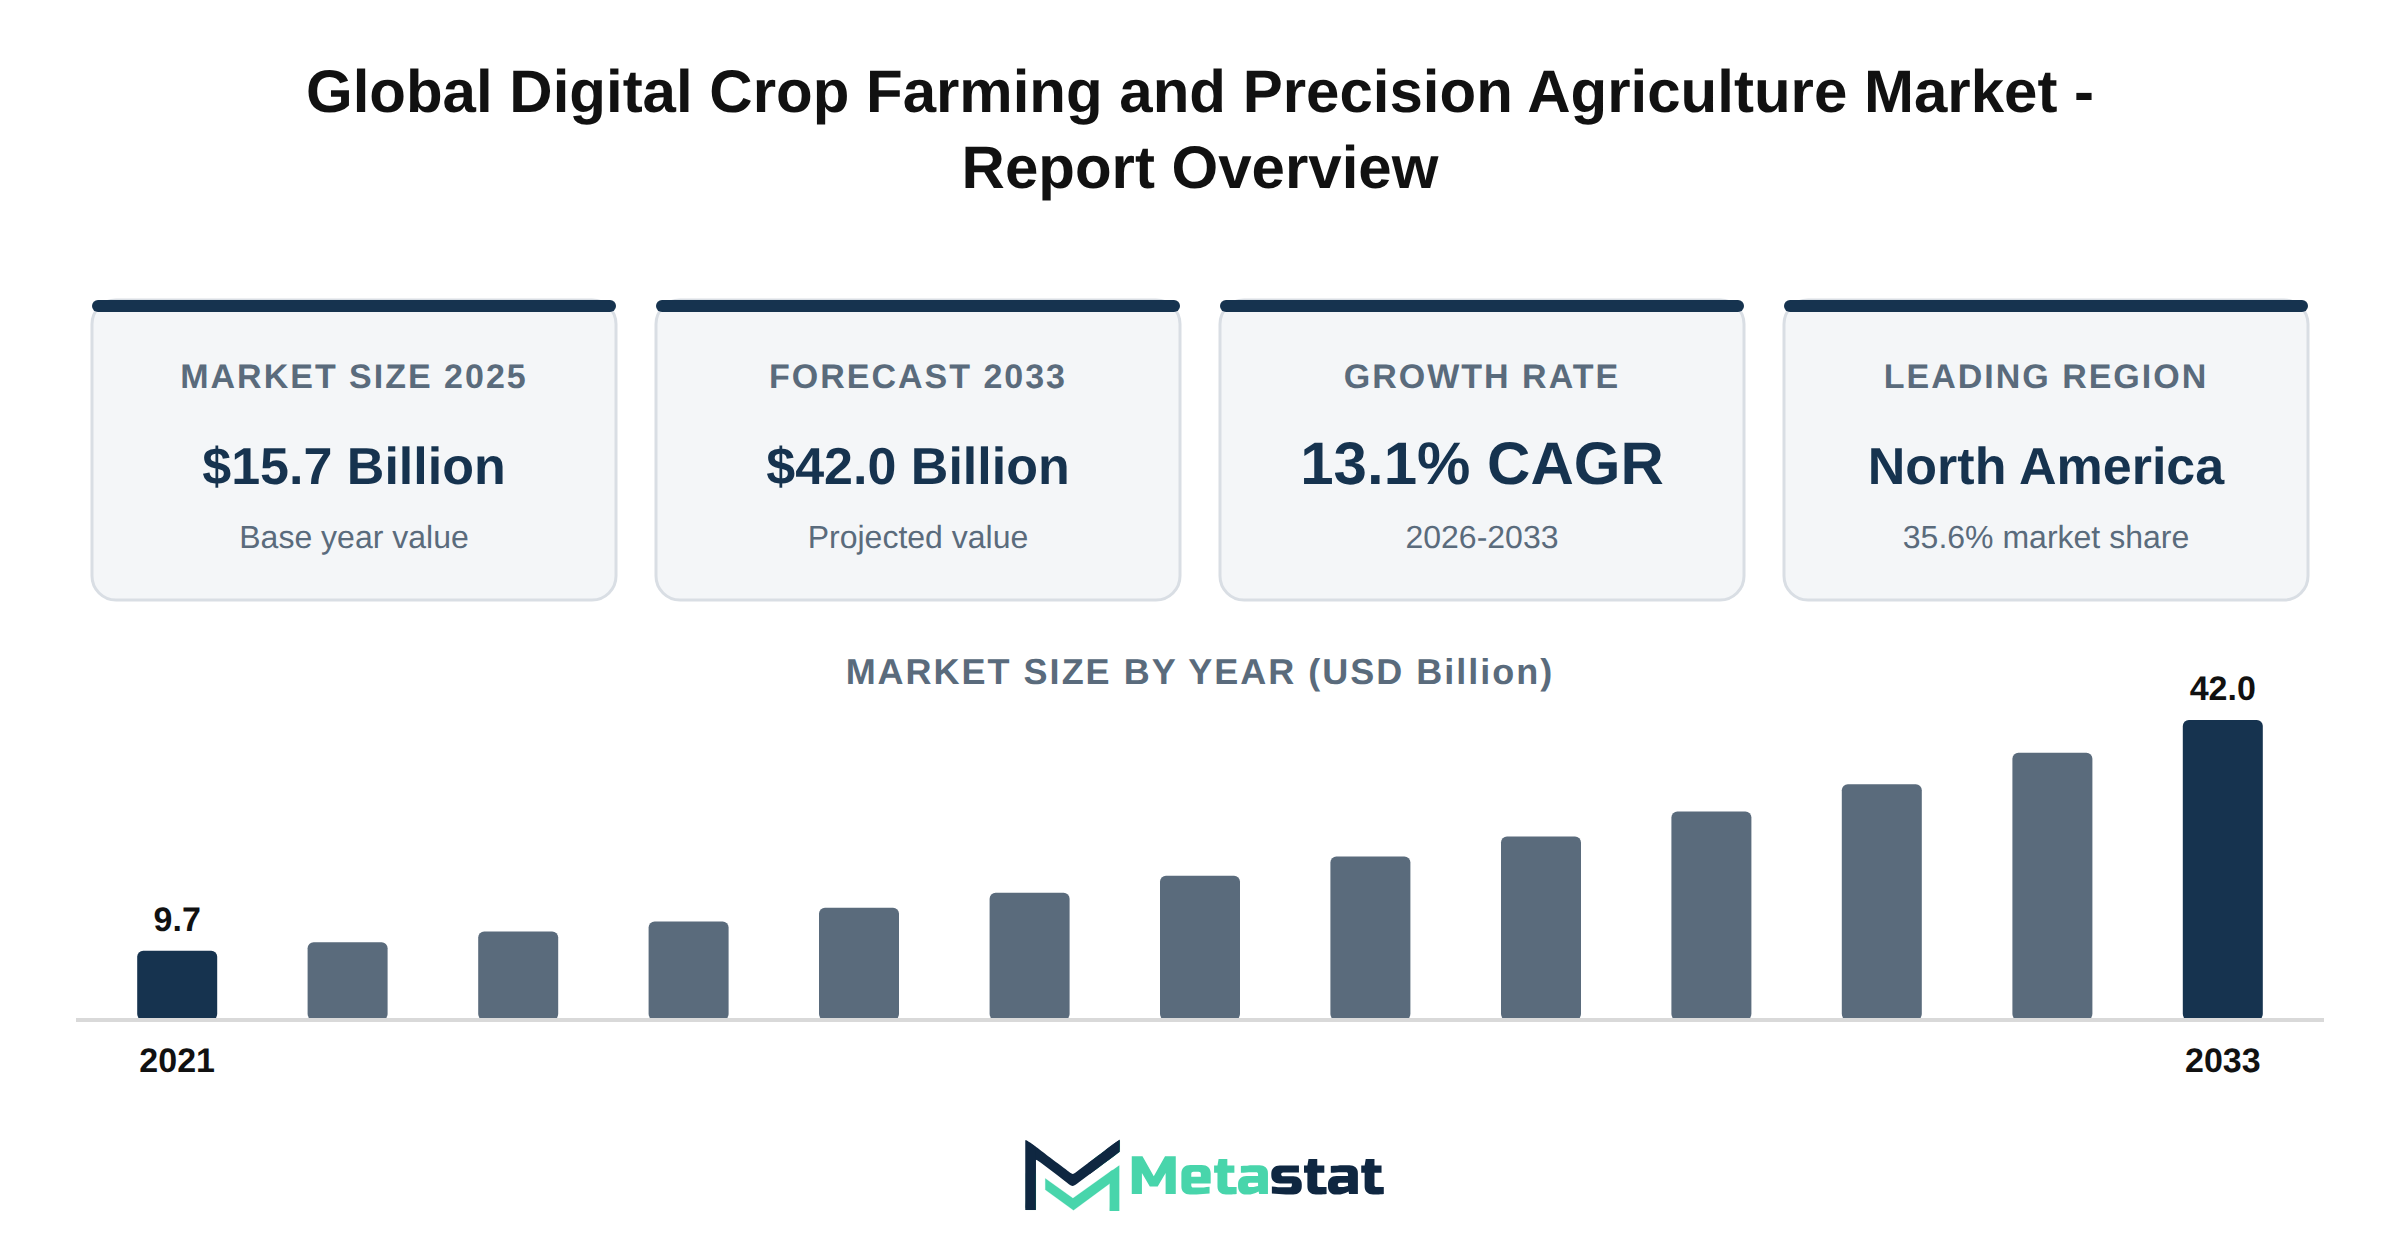
The Digital Crop Farming and Precision Agriculture market reached USD 15.7 billion in 2025, reflecting a significant growth trajectory since USD 9.7 billion in 2021. This market is projected to expand to USD 42 billion by 2033, achieving a compound annual growth rate (CAGR) of 13.1% during the forecast period from 2026 to 2033. Growth in this market is driven by increasing demand for advanced agricultural solutions that enhance productivity and efficiency.
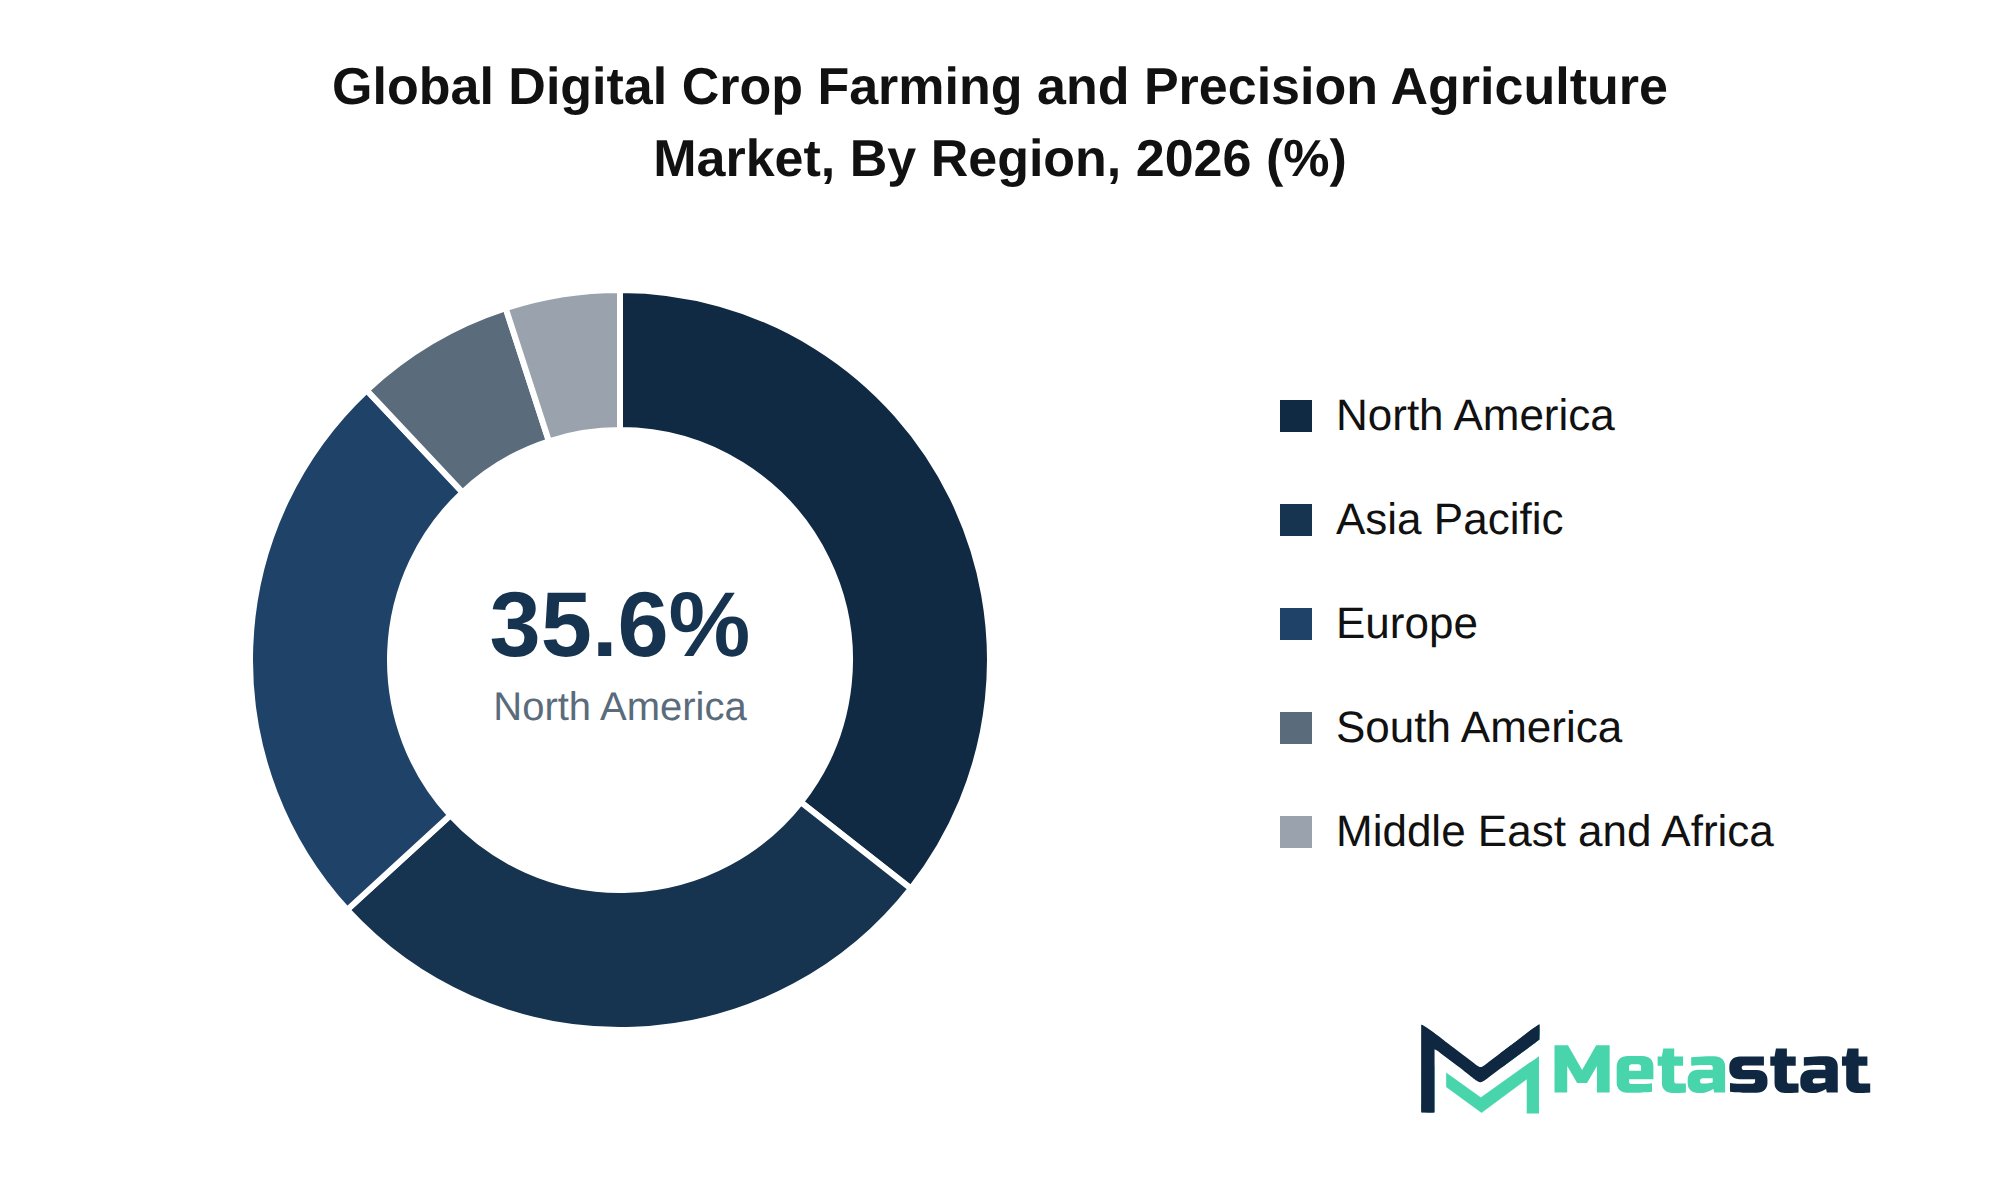
Regional dynamics illustrate varied contributions, with North America accounting for 35.6% of the market share, followed by Asia Pacific at 27.6%, and Europe at 24.8%. By 2033, North America is projected to generate USD 13.5 billion in market value, supported by robust investments in technology and infrastructure. The region's emphasis on innovative farming practices underpins its strong market position.
Hardware offerings within the Digital Crop Farming and Precision Agriculture market are projected to grow from USD 8 billion in 2026 to USD 17.2 billion by 2033, reflecting a CAGR of 11.6%. Software offerings are anticipated to reach USD 16.2 billion during the same period, driven by increasing reliance on data analytics and farm management solutions. Services associated with precision agriculture will see growth, with expectations of reaching USD 8.6 billion by 2033.
In terms of applications, Farm Planning, Records & Analytics is expected to grow from USD 2.9 billion in 2026 to USD 6.9 billion by 2033, marking a CAGR of 13.3%. Equipment Guidance, Steering & Fleet Telematics will reach USD 7 billion by 2033, supported by the adoption of autonomous technologies that streamline farming operations. Crop Monitoring & Scouting, with a CAGR of 14.4%, reflects the increasing importance of real-time data collection and analysis in modern agriculture.
Crop types show significant trends, with Cereals & Grains projected to grow from USD 5.6 billion in 2026 to USD 12.6 billion by 2033, achieving a CAGR of 12.2%. The Oilseeds & Pulses category is projected to reach USD 7.1 billion by 2033, driven by rising global demand for these essential crops. Fruits & Vegetables will contribute significantly, with a projected value of USD 9.5 billion by 2033.
The increasing focus on mixed-fleet data interoperability transforms operational efficiency within the Digital Crop Farming and Precision Agriculture market. This integration facilitates communication between various agricultural equipment and software platforms, enabling farmers to optimize their operations and enhance productivity. Improved interoperability leads to significant time and cost savings, fueling the adoption of advanced technologies across diverse farming practices.
Autonomous harvest and grain handling systems continue to gain traction, driven by advancements in robotics and artificial intelligence. These technologies enhance efficiency during critical harvesting periods, reducing labor costs and operational risks. The shift toward automation supports scalable farming practices, enabling producers to manage larger areas with fewer resources.
The emphasis on contractor return on investment (ROI) and payback economics influences decision-making in the market. Farmers increasingly seek solutions that demonstrate tangible financial benefits, leading to a rise in demand for precision agriculture technologies that deliver measurable results. This trend encourages technology providers to offer transparent pricing models and performance metrics to attract buyers.
Harvest data ownership and portability play a crucial role in shaping relationships between farmers and technology providers. While farmers seek greater control over their data, providers face pressure to deliver solutions that prioritize data privacy and ownership rights. This shift builds trust and encourages long-term partnerships within the market.
Customer reporting and service differentiation serve because key competitive advantages in the Digital Crop Farming and Precision Agriculture market. Companies that provide comprehensive reporting tools and tailored services stand out, enhancing customer satisfaction and loyalty. This focus on personalized service reinforces the importance of understanding individual client needs and preferences.
OEM-platform integration partnerships emerge because a vital strategy for enhancing product offerings and expanding market reach. Collaborations between original equipment manufacturers and software developers enable the creation of integrated solutions that address specific agricultural challenges. These partnerships drive innovation and improve overall system performance.
Regulatory compliance and adherence to standards significantly impact the market landscape. Companies navigate various regulations and risk frameworks to ensure their technologies align with regional requirements. This compliance builds legitimacy and trust among consumers, essential for long-term success.
Disruption from emerging technologies drives R&D trajectories within the market. Investment in next-generation innovations, including machine learning and IoT applications, positions companies to stay competitive. This ongoing commitment to research and development underpins continuous improvement and adaptation to changing agricultural practices.
Sustainable transformation, decarbonization, and circular economy dynamics shape the future of the Digital Crop Farming and Precision Agriculture market. Stakeholders increasingly prioritize environmentally friendly practices, influencing product development and operational strategies. This focus on sustainability drives demand for solutions that minimize environmental impact while maximizing productivity.
The evolving supply chain landscape and logistics architecture require strategic sourcing and procurement models. Companies adapt to shifts in sourcing dynamics while maintaining efficiency and cost-effectiveness. This evolution necessitates a comprehensive understanding of market trends and consumer demands.
Market fragmentation presents both challenges and opportunities. Companies navigating this complex landscape differentiate their offerings while addressing diverse customer needs. This competition drives innovation and advances within the Digital Crop Farming and Precision Agriculture market.
M&A dynamics play a critical role in shaping market structure. Strategic acquisitions enable companies to expand their capabilities, enhance product offerings, and streamline operations. This trend influences competitive positioning and growth strategies across the industry.
A well-defined value chain enhances operational efficiency and customer satisfaction. By understanding and optimizing each step in the value chain, stakeholders improve profitability and strengthen market presence. This approach facilitates better alignment between producers and technology providers.
Capital allocation remains a crucial consideration for stakeholders in the market. Strategic investments in technology and infrastructure drive growth and innovation, shaping the future landscape of the Digital Crop Farming and Precision Agriculture market. Companies that prioritize capital efficiency position themselves for long-term success.
Infrastructure investments play a significant role in supporting market growth. Enhanced connectivity and access to advanced agricultural technologies allow farmers to leverage data-driven insights for informed decision-making. This infrastructure development strengthens the overall ecosystem and supports the adoption of precision agriculture solutions.
The future strategic outlook for the Digital Crop Farming and Precision Agriculture market emphasizes the importance of adaptability and innovation. Companies remain agile in response to evolving consumer demands and technological advancements. Corporate imperatives focus on building a culture of continuous improvement, aligning operations with market trends, and delivering high-value recommendations to stakeholders.
The Digital Crop Farming and Precision Agriculture market benefits from macro-economic factors that encourage investment in advanced agricultural technologies. Growth in GDP and a favorable capital investment environment, characterized by low-interest rates and increased venture funding, stimulates spending on precision agriculture solutions. Agricultural producers and technology developers invest in innovations that enhance efficiency and productivity, aligning with broader economic trends.
Growing urbanization and shifting demographic patterns lead to evolving consumer preferences, emphasizing the need for sustainable and efficient farming practices. These factors drive demand for precision agriculture technologies that optimize resource usage and reduce costs. The market sees significant opportunities attributed to stakeholders increasingly prioritizing operational productivity and cost-efficiency initiatives.
Technological integration, including the adoption of automation and AI, further enhances the market potential. By digitizing legacy processes and streamlining operations, agricultural stakeholders improve overall performance and resource management. The Digital Crop Farming and Precision Agriculture market is positioned for growth, supported by continuous innovation and investment in advanced technologies.
The integration of advanced technologies fuels significant growth in the Digital Crop Farming and Precision Agriculture market. Automation, artificial intelligence, and software adoption enhance farming capabilities, enabling producers to increase efficiency and optimize resource use. These advancements streamline legacy processes, allowing for improved data management and real-time analytics. Enhanced data accuracy leads to informed decision-making, which strengthens operational productivity.
Investment in new technologies aligns with shifting consumer behaviors and expectations. Farmers increasingly prioritize tools that not only boost yields but contribute to sustainability efforts and resource stewardship. These technologies support carbon footprint reduction initiatives while promoting responsible governance practices. Enhanced operational efficiency and cost-effectiveness are critical, contributing to the market's growth trajectory.
The ongoing digital transformation within agriculture emphasizes the importance of technological integration, creating a competitive environment among producers. This integration positions the Digital Crop Farming and Precision Agriculture market for continued expansion, driven by stakeholders seeking innovative solutions to meet evolving industry demands.
Compliance hurdles associated with regulatory frameworks significantly hinder progress in the Digital Crop Farming and Precision Agriculture market. Industry participants face challenges in meeting stringent standards, leading to increased operational costs that impede adoption. These compliance requirements place a financial burden on farmers and agricultural businesses, limiting their ability to invest in advanced technologies essential for enhancing productivity.
Capital stagnation emerges from the high capital investment requirements necessary for adopting precision agriculture solutions. Many stakeholders encounter difficulties securing funding for innovations, especially during periods of economic uncertainty. Inflationary pressures increase the cost of equipment and services, further straining operational budgets.
Infrastructure gaps and connectivity deficits impact the deployment of digital farming technologies. In regions lacking robust internet access, implementing data-driven solutions becomes challenging, limiting the market's growth potential. Deployment bottlenecks arise from insufficient skilled labor, which constrains the ability to implement and maintain advanced agricultural systems effectively.
Data security vulnerabilities and privacy concerns pose substantial risks within the Digital Crop Farming and Precision Agriculture market. The reliance on data analytics and cloud-based systems increases exposure to potential breaches, creating hesitance among producers to fully embrace digital solutions. Intellectual property theft risks discourage innovation, impeding competitive growth.
Market fragmentation contributes to the complexity of navigating the market. Various players, including small startups and established corporations, compete for market share, leading to inconsistent adoption rates and varying levels of technology integration across the sector. Cultural barriers and regional adoption resistors complicate the situation, resulting in uneven progress in different geographical areas.
Slowing downstream demand in certain crop segments exacerbates the challenges faced by stakeholders. While industry cycles mature and market saturation occurs, growth opportunities become increasingly elusive. These factors collectively contribute to a restrained outlook for the Digital Crop Farming and Precision Agriculture market, necessitating strategic adjustments by stakeholders to overcome these barriers.
The Digital Crop Farming and Precision Agriculture market faces challenges stemming from geopolitical fragmentation and ongoing trade tensions. Disruptions in global supply chains stem from tariff friction, affecting the availability and cost of essential inputs. This situation pressures manufacturers to identify alternative suppliers or adjust pricing strategies, impacting operational budgets.
Technological disruptions, coupled with interoperability friction, complicate the integration of advanced systems across various agricultural operations. Gaps in intellectual property protection and cybersecurity risks contribute to hesitancy among investors and firms. The complexity of research and development processes further strains resources, leading to delays in product launches and innovations.
Market saturation presents another challenge, because increased competition compresses pricing. While firms strive to maintain market share, profit margins face significant pressure. Rising input costs associated with labor and materials exacerbate this situation, compelling stakeholders to identify efficient solutions to sustain profitability in the Digital Crop Farming and Precision Agriculture market.
Workforce skill gaps hinder the adoption of automation technologies, which limits productivity enhancements. Talent retention pressures further complicate operational efficiency, because skilled labor becomes increasingly scarce. The commitment to sustainability demands necessitates substantial investments in retrofitting existing infrastructure, presenting additional implementation bottlenecks for stakeholders in the market. Addressing these issues is crucial for ensuring growth and maintaining competitiveness in the face of evolving demands and pressures.
Shifts in consumer preferences towards sustainable agricultural practices create robust demand within the Digital Crop Farming and Precision Agriculture market. Increased awareness of environmental impacts drives producers to adopt innovative solutions that enhance productivity while minimizing ecological footprints. This transition encourages investments in advanced technologies that support sustainable practices, aligning with global sustainability imperatives.
Infrastructure modernization represents another significant opportunity fueling market expansion. Many regions invest in upgrading agricultural infrastructure to support precision farming techniques. Improved connectivity and access to digital tools enhance operational efficiencies, enabling farmers to make data-driven decisions that contribute to higher yields and lower resource consumption.
Geographical expansion into emerging markets results in increased adoption of digital solutions. Regions including Asia Pacific and South America exhibit untapped potential, where rising populations and changing dietary preferences drive the need for efficient farming methods. This demand leads to greater investment in precision agriculture technologies, further stimulating growth in the market.
Technological disruptions in the form of next-generation innovations, including IoT and AI, enhance precision agriculture capabilities. These technologies provide farmers with real-time data and insights, enabling precise monitoring and management of crop health. Enhanced accuracy results in improved resource allocation and increased operational yields, reinforcing the market's attractiveness to investors.
Shifts in buying behaviors and the rise of digital procurement platforms transform how agricultural stakeholders engage with suppliers. Transitioning to digital procurement enhances supply chain resilience and efficiency, facilitating quicker access to essential tools and services within the market. Adoption of digital solutions contributes to streamlined operations and reduced costs, presenting compelling advantages for stakeholders.
Strategic consolidation through cross-industry mergers further strengthens the market landscape. Collaborations among technology providers and agricultural firms drive innovations that enhance service offerings and expand market reach. These partnerships create an environment conducive to the development of integrated solutions that meet evolving consumer demands, strengthening competitive positions within the market.
Finally, asset life-cycle extensions, maintenance upgrades, and retrofitting dynamics contribute to ongoing improvements in productivity and cost-effectiveness. Emphasizing asset longevity aligns with sustainability goals, prompting investments that optimize operations. This focus on maximizing asset value enhances competitiveness within the Digital Crop Farming and Precision Agriculture market, positioning players favorably for sustained growth.
The Global Digital Crop Farming and Precision Agriculture market is segmented based on Offering, Application, Crop Type.
Valued at USD 8 billion in 2026, the Hardware segment of the Digital Crop Farming and Precision Agriculture market is projected to reach USD 17.2 billion by 2033, reflecting a CAGR of 11.6% during the forecast period. Increasing adoption of precision agriculture technologies drives demand for advanced hardware solutions, enabling farmers to enhance productivity and optimize resource utilization. Innovations in agricultural machinery, including autonomous tractors and drones, contribute significantly to segment growth by improving operational efficiency and reducing labor costs.
Technological maturation facilitates the integration of advanced hardware into farming practices. The evolution of sensors, robotics, and IoT devices enhances the functionality of equipment, enabling real-time data collection and analytics. This technological advancement attracts investment from established agricultural players and new entrants focused on developing next-generation solutions.
End-use dynamics further influence the expansion of the Hardware segment. Farmers increasingly recognize the value of investing in high-quality machinery that provides long-term benefits, including increased yield and reduced operational costs. Regulatory compliance standards regarding environmental sustainability drive the adoption of efficient hardware solutions, pushing manufacturers to innovate and meet these requirements.
Pricing volatility remains a challenge for stakeholders within the Hardware segment. Fluctuations in raw material prices impact manufacturing costs and profit margins, necessitating strategic pricing strategies to maintain competitiveness. However, potential strategic opportunity windows exist, especially for companies that leverage advancements in materials science to develop more cost-effective solutions.
Overall, the Hardware segment of the Digital Crop Farming and Precision Agriculture market demonstrates significant growth potential, driven by technological advancements, investment in innovative solutions, and shifts in end-user preferences. This segment's trajectory indicates a favorable outlook for stakeholders seeking to capitalize on emerging opportunities within the agricultural technology landscape.
In the Digital Crop Farming and Precision Agriculture market, the Software segment is estimated to reach USD 16.2 billion by 2033, at a CAGR of 14.7% during the forecast period. Adoption of software solutions in precision agriculture derives from the growing demand for data-driven decision-making, which enhances crop yields and optimizes resource management. Technological maturation has led to effective integration of software with hardware, promoting real-time data analysis and predictive analytics.
Product evolution within the Software segment focuses on delivering innovative solutions tailored to specific agricultural applications, including farm planning, records and analytics, equipment guidance, and crop monitoring. These advancements improve end-use dynamics, enabling farmers to leverage insights that enhance operational efficiency.
Consumption shifts towards precision agriculture software reflect an increasing emphasis on sustainable farming practices and regulatory compliance. Addressing these compliance challenges through software solutions strengthens market participation, encouraging investment in next-generation upgrades. Strategic opportunity windows arise from increasing agricultural productivity demands and the need for efficient resource utilization, positioning software providers for competitive advantage.
Pricing volatility and margin pressures persist due to market competition, necessitating robust capital investment in research and development to maintain technological relevance. Software providers that navigate these economic pressures effectively capture market share, thereby reinforcing the growth trajectory of the Digital Crop Farming and Precision Agriculture market.
Growth in the Services segment of the Digital Crop Farming and Precision Agriculture market is driven by the increasing demand for comprehensive solutions that enhance operational efficiency and sustainability in agricultural practices. Farmers increasingly seek services that integrate technology with traditional farming methods, optimizing resource utilization and maximizing yield. The evolution of precision agriculture technologies, including data analytics and IoT applications, supports this trend, leading to a heightened focus on service offerings that facilitate farm planning, monitoring, and management.
Technological maturation enhances the expansion of the Services segment, with advancements in remote sensing, machine learning, and cloud computing enhancing service capabilities. These technologies enable real-time data collection and analysis, allowing farmers to make informed decisions regarding crop management and resource allocation. The ongoing development of next-generation upgrades ensures that service providers remain competitive by incorporating innovative solutions that address emerging agricultural challenges.
Forecasts indicate that the Services segment is expected to reach USD 8.6 billion by 2033, reflecting the increasing adoption of these technologies across various agricultural practices. End-use dynamics demonstrate a robust shift towards data-driven decision-making in agriculture, with service providers offering tailored solutions to meet specific crop and operational requirements. Regulatory compliance standards further influence service offerings, pushing providers to develop solutions that assist farmers in adhering to evolving agricultural regulations.
Cost structures and pricing volatility associated with service provisions have direct implications for market dynamics. Providers navigate these challenges while maintaining competitive pricing strategies to attract and retain clients. Strategic opportunity windows emerge owing to service providers focusing on enhancing service quality and expanding their portfolios to include innovative solutions that cater to the evolving needs of the agricultural sector.
Valued at USD 2.9 billion in 2026, the Farm Planning, Records & Analytics segment is projected to reach USD 6.9 billion by 2033, at a CAGR of 13.3% during the forecast period. Demand for advanced data analytics tools in agriculture drives significant interest from various stakeholders in the Digital Crop Farming and Precision Agriculture market. The increasing emphasis on precision farming techniques enhances farm management practices through real-time data collection and analysis, enabling better decision-making and resource allocation.
Technological advancements in data processing, cloud computing, and Internet of Things (IoT) applications contribute to the evolution of solutions within this segment. Increased adoption of these technologies leads to a shift towards more efficient and sustainable farming methods. Regulatory compliance related to data management and reporting requirements encourages the integration of sophisticated record-keeping solutions, enhancing operational effectiveness.
The evolution of digital tools catering to farm planning and analytics opens strategic opportunity windows for technology providers. Enhanced functionalities, including predictive analytics and machine learning capabilities, position these solutions because vital assets for farmers aiming to optimize yields and reduce operational costs. Sustained investments in technology development and upgrades are essential for companies operating within the market.
The Farm Planning, Records & Analytics segment experiences growth propelled by technological maturation, increased demand for efficiency, and ongoing investment in next-generation agricultural solutions. The trends shaping this segment highlight its significance within the broader context of the Digital Crop Farming and Precision Agriculture market.
Growth in the Equipment Guidance, Steering & Fleet Telematics segment reflects a significant evolution in agricultural practices, addressing the need for enhanced operational efficiency and productivity in the Digital Crop Farming and Precision Agriculture market. This segment is projected to reach USD 7 billion by 2033, expanding at a CAGR of 12.2% during the forecast period. The adoption of advanced technologies including GPS, automation, and telematics systems drives the demand for precision equipment, enabling farmers to optimize operations and reduce waste.
Innovation in product offerings continues to attract investments, with manufacturers developing next-generation upgrades that incorporate artificial intelligence and machine learning. These advancements enable farmers to gather and analyze real-time data, facilitating improved decision-making and resource allocation. The increasing emphasis on sustainability and regulatory compliance standards further drives demand for precise agricultural practices, pushing the market towards more efficient solutions.
The growing emphasis on data-driven farming practices influences consumption shifts within the industry, with stakeholders seeking technologies that provide measurable benefits. Regulatory frameworks supporting sustainable farming practices encourage investments in precision equipment, enhancing the overall market landscape. Overall, the Equipment Guidance, Steering & Fleet Telematics segment plays a crucial role in shaping the future of the Digital Crop Farming and Precision Agriculture market.
Investment in advanced agricultural technologies drives adoption of planting and seeding optimization solutions. Increased demand for efficient farming practices pushes producers to seek tools that enhance crop yield and minimize resource waste. The growing pressure to adopt precision agriculture techniques results in a notable shift towards smart planting solutions. Technological advancements in this field enable farmers to apply data analytics and automation for improved decision-making. These innovations facilitate accurate planting, ultimately enhancing productivity and profitability.
Market growth is supported by the rising need for sustainable agricultural practices. Environmental concerns prompt stakeholders to incorporate precision techniques that optimize seed placement and minimize the use of fertilizers and pesticides. Enhanced regulatory frameworks focusing on sustainable farming practices support this transition, further propelling market expansion.
Planting & Seeding Optimization segment is expected to reach USD 4.1 billion by 2033. The segment’s evolution reflects the broader trends within the Digital Crop Farming and Precision Agriculture market, which emphasizes efficiency and productivity. Continuous advancements in technology create opportunities for suppliers to introduce next-gen solutions that meet the evolving needs of farmers.
Strategic investments in research and development enhance competitive dynamics within the market. Companies aggressively pursue innovation to secure a leading position in the planting and seeding optimization landscape. This ongoing evolution positions the segment for sustained growth, driven by agricultural practices that continue to transform in response to market demands.
Growing awareness of crop health and yield optimization drives demand for Crop Monitoring & Scouting technologies within the Digital Crop Farming and Precision Agriculture market. Farmers increasingly adopt these technologies to enhance agricultural practices, ensuring higher productivity and resource efficiency. The segment is projected to grow at a CAGR of 14.4% during the forecast period, reflecting the rising emphasis on data-driven farming decisions.
Technological maturation significantly influences the advancement of crop monitoring tools, including drones, satellite imagery, and IoT devices. These innovations enable real-time insights into crop conditions, weather patterns, and soil health, supporting timely interventions. The integration of next-gen upgrades facilitates efficient data collection, analysis, and application, allowing farmers to make informed decisions that impact yield and profitability.
Regulatory compliance standards increasingly influence market dynamics, pushing for sustainable agricultural practices that align with environmental policies. Crop monitoring technologies contribute to meeting these standards by providing the necessary data to demonstrate compliance and sustainability. This trend enhances adoption rates among farmers aiming to align with government policies while improving operational efficiency.
Investment in crop monitoring solutions reflects broader consumption shifts toward precision agriculture. Stakeholders prioritize technologies that offer measurable benefits, including reduced chemical use, improved crop health, and enhanced yield forecasting. This strategic focus on efficiency and sustainability strengthens the segment's position within the Digital Crop Farming and Precision Agriculture market, attracting capital investments that drive innovation and growth.
Increasing pressure on water resources drives innovation in irrigation and water management technologies within the Digital Crop Farming and Precision Agriculture market. Farmers seek efficient solutions to optimize water usage, reduce waste, and ensure crop health, enhancing productivity across various agricultural landscapes. Technological maturation facilitates the adoption of precision irrigation systems, including automated drip and sprinkler systems, enabling real-time monitoring and control of water application.
Emerging trends highlight the importance of data-driven decision-making in water management. Advanced analytics provide insights into soil moisture levels, weather conditions, and crop water needs, allowing farmers to tailor irrigation practices accordingly. Adoption of these technologies results in improved crop yields and sustainable water usage, addressing the environmental challenges associated with traditional farming practices.
Regulatory compliance shapes irrigation practices. Governments implement standards to promote sustainable water use and protect water quality, prompting farmers to invest in precision irrigation solutions. This regulatory landscape encourages the market's growth, particularly in regions facing water scarcity, where efficient irrigation is essential for agricultural success.
Investment in irrigation and water management technologies signals strategic opportunity windows for market players. Companies focusing on the development and deployment of innovative solutions find avenues for growth in the expanding Digital Crop Farming and Precision Agriculture market. Continuous advancements and evolving consumer preferences towards sustainability serve because catalysts for further innovation in this critical segment.
Growing awareness of nutrient management promotes sustainable agricultural practices in the market. This shift aligns with consumer demand for high-quality produce while reducing environmental impacts related to fertilizer usage. Adoption of precision agriculture technologies enhances nutrient application efficiencies, effectively supporting crop health and yield optimization.
Technological advancements, including data analytics and IoT integration, drive the evolution of nutrient management solutions. These innovations facilitate real-time monitoring and precise application of fertilizers, ultimately improving operational practices for farmers. Increased focus on data-driven decision-making in the market ensures that nutrient management strategies are tailored to specific crop needs and field conditions.
Regulatory compliance standards surrounding fertilizer usage and environmental protection shape the dynamics of the market. Stricter regulations encourage farmers to adopt precision nutrient management practices to ensure adherence while maximizing crop productivity. This regulatory environment drives investment in advanced technologies that support responsible fertilizer use.
Cost structures and pricing volatility associated with raw materials influence the market. Fluctuations in fertilizer prices impact farmers' budgeting and encourage the exploration of alternative solutions. Strategic opportunities arise in the development of innovative nutrient management products that reduce reliance on traditional fertilizers while maintaining crop performance. This exploration enhances the overall efficiency of nutrient management.
The nutrient management and fertilization segment within the Digital Crop Farming and Precision Agriculture market reflects a significant shift towards precision practices, driven by technological advancements, regulatory pressures, and the need for sustainability in agriculture.
Increasing emphasis on sustainable farming practices drives demand for effective crop protection solutions. Farmers seek to enhance yield while minimizing environmental impact, leading to growth in technologies that support precision spraying. Adoption of advanced digital tools enables precise application of agrochemicals, resulting in reduced waste and improved crop health.
Investment in research and development accelerates the maturation of crop protection technologies. Enhanced formulations and targeted applications represent significant advancements, catering to the evolving needs of farmers. These innovations contribute to improved efficiency and effectiveness in pest and disease management.
Regulatory compliance standards surrounding agricultural inputs influence market dynamics. Stringent regulations promote the use of safer and more environmentally friendly products, compelling manufacturers to innovate and adapt their offerings. Achieving certifications and meeting compliance benchmarks enhances product credibility, ultimately affecting adoption rates.
Changing consumer preferences toward organically produced food further impact end-use dynamics. Farmers responding to market demands for organic products increasingly integrate precision spraying techniques to manage pests and diseases while adhering to organic standards. This alignment with consumer expectations drives market growth and opens new opportunities for businesses within the Digital Crop Farming and Precision Agriculture market.
Margin pressures stemming from fluctuating raw material prices challenge producers in the crop protection segment. Companies navigate these cost structures while ensuring competitive pricing strategies. Strategic partnerships and supply chain resilience become essential to mitigate risks associated with sourcing and logistics vulnerabilities.
Advancements in technology significantly influence the Harvesting, Yield Mapping & Harvest Management segment within the Digital Crop Farming and Precision Agriculture market. Innovations in data analytics and sensor technology enhance decision-making processes for farmers, allowing for precise yield mapping and effective harvesting strategies. Increasing demand for optimal resource utilization drives growers to adopt these technologies, leading to improved crop management and productivity.
Pressure to increase productivity while minimizing waste fuels investments in this segment. Enhanced yield mapping allows farmers to identify high-performing areas within fields, enabling targeted interventions that optimize yields. This shift directly aligns with broader agricultural trends emphasizing efficiency and sustainability.
Several factors contribute to the evolution of this segment, including the maturation of precision agriculture technologies and the push for next-generation upgrades. Integration of real-time data from various sources allows for dynamic adjustments in harvesting techniques, further driving the segment's growth. Continuous improvement in agricultural practices shapes downstream applications, enhancing the effectiveness of yield management strategies.
Regulatory compliance influences market dynamics, driven by governments introducing policies promoting sustainable practices. These regulations often incentivize farmers to adopt advanced technologies, creating an environment conducive to growth. The focus on minimizing environmental impact aligns with consumer expectations and drives investment into this segment.
Overall, the Harvesting, Yield Mapping & Harvest Management segment presents significant opportunities within the Digital Crop Farming and Precision Agriculture market. The combination of technological advancements, regulatory support, and shifting consumer preferences creates a favorable environment for continued growth and innovation.
Valued at USD 5.6 billion in 2026, the Cereals & Grains segment is projected to reach USD 12.6 billion by 2033, at a CAGR of 12.2% during the forecast period. Demand in this segment stems from an increasing global population and a growing need for food security, particularly in regions heavily reliant on cereal production. Advancements in agricultural technologies enhance efficiency and yield, driving adoption among producers. The integration of precision agriculture tools facilitates data-driven decisions and optimized resource allocation, contributing to overall segment growth. Rising consumer preferences for organic and sustainably sourced grains influence market dynamics, prompting farmers to adopt innovative practices that align with these trends.
Regulatory frameworks promoting sustainable agricultural practices create opportunities for investment in technologies that support environmental compliance. The necessity for certifications in organic farming and environmentally friendly practices impacts production processes, leading to cost adjustments that affect pricing structures. Strategic investments in next-generation agricultural solutions, including sensor technology and data analytics, position stakeholders to benefit from evolving market demands. The resilience of supply chains remains critical amid challenges presented by weather variability and geopolitical factors, necessitating adaptive strategies to mitigate risks associated with raw material sourcing.
The Digital Crop Farming and Precision Agriculture market exhibits significant potential for growth. Stakeholders explore strategic opportunity windows created by technological advancements. A focus on product evolution and enhancements in existing offerings ensures alignment with consumer expectations and regulatory requirements. Overall, the Cereals & Grains segment reflects a robust trajectory within the market, driven by innovation, strategic investment, and a commitment to sustainability.
Growing interest in oilseeds and pulses fuels significant growth in the Digital Crop Farming and Precision Agriculture market. Factors driving this interest include the rising global demand for plant-based proteins and the shift towards sustainable agricultural practices. Producers increasingly adopt advanced technologies to optimize yields and enhance efficiency in oilseed and pulse cultivation. The segment is estimated to reach USD 7.1 billion by 2033, at a CAGR of 12.9% during the forecast period.
Technological maturation supports segment expansion. Innovations in precision agriculture equipment and software enhance crop monitoring, resource management, and data analytics capabilities. Farmers increasingly rely on these technologies to address challenges including climate change, pest management, and soil health. The adoption of next-generation upgrades further enhances efficiency and profitability in oilseed and pulse production.
Consumption shifts towards healthier food options drive demand within this segment. Oilseeds and pulses are recognized for their nutritional benefits, leading to increased consumer preferences for plant-based diets. Regulatory compliance standards focusing on sustainable farming practices encourage producers to employ more environmentally friendly methods in oilseed and pulse cultivation, reinforcing market growth.
Strategic opportunity windows emerge owing to rising investment in oilseeds and pulses. Capital investment in research and development supports advancements in crop varieties, pest resistance, and yield optimization. This environment positions the oilseeds and pulses segment for accelerated growth within the broader market, ensuring suppliers meet the evolving demands of consumers and regulatory frameworks.
Investment in the Fruits & Vegetables segment is expected to reach USD 9.5 billion by 2033. Growing consumer preference for fresh and organic produce drives demand for advanced agricultural technologies. Innovations in precision farming, including data analytics and AI-driven solutions, enhance crop yields and improve overall quality. This segment experiences significant expansion due to increasing urbanization and changing dietary preferences, leading to higher consumption of fruits and vegetables. Regulatory compliance surrounding food safety and sustainability further encourages adoption of precision agriculture practices among growers. Enhanced supply chain resilience remains essential, driven by growers adopting new technologies to mitigate risks associated with climate change and market fluctuations. The emphasis on sustainable practices, coupled with advancements in farming techniques, positions the Fruits & Vegetables sub-segment for strong growth within the Digital Crop Farming and Precision Agriculture market.
Growth in the Cotton & Other Fiber Crops segment aligns with increasing global demand for sustainable and efficient farming practices. Technological advancements facilitate the adoption of innovative solutions including precision irrigation, which enhances resource management. These factors contribute to expanding market opportunities, particularly in regions with robust agricultural infrastructures.
The Cotton & Other Fiber Crops segment is projected to grow at a CAGR of 12.2% during the forecast period. Rising focus on yield optimization and resource efficiency drives investment in digital agriculture technologies. End users prioritize solutions that improve crop health and maximize productivity, leading to an uptick in demand across the Digital Crop Farming and Precision Agriculture market.
Increased research and development efforts support the evolution of products tailored for cotton and fiber crop cultivation. This evolution addresses challenges related to pest management and environmental sustainability, ensuring compliance with regulatory standards. Continuous improvement of technologies creates strategic opportunities, enhancing growth prospects in this segment.
Competition within the market influences pricing strategies, affecting margin pressures for suppliers. Companies increasingly focus on building resilient supply chains to navigate raw material sourcing challenges and mitigate disruptions. Strategic partnerships enhance innovation and technological maturity, positioning the segment for sustained growth in the evolving agricultural environment.
Increasing focus on sustainable practices drives interest in sugar crops, particularly due to their essential role in food security and biofuel production. Adoption of advanced technologies within the Digital Crop Farming and Precision Agriculture market enables more efficient cultivation methods for sugar crops. Precision agriculture techniques improve yield, resource management, and pest control, reflecting the industry's shift towards data-driven farming practices.
Growing global demand for sugar products and biofuels fuels investment in the segment, encouraging innovation in cultivation techniques. Regulatory compliance standards promote sustainable farming, influencing practices and technology adoption within this crop type. The market encounters challenges including price volatility and margin pressures, which affect profitability and operational decisions for growers focused on sugar crops.
Strategic opportunity windows arise from the need for enhanced resilience in supply chains, influencing raw material sourcing and logistics strategies. Addressing substitution risks and technological obsolescence remains crucial for sustaining growth and ensuring competitiveness in the Digital Crop Farming and Precision Agriculture market. Investment in next-gen upgrades and product evolution enhances operational efficiency and crop quality in the sugar crops segment.
Investment in the plantation and permanent crops sector reflects rising demand for sustainable agricultural practices and reliable food sources. Increased consumer preference for organic and sustainably produced crops necessitates technological advancements in this segment. Adoption of precision agriculture technologies enables farmers to optimize yields, reduce waste, and enhance resource efficiency.
Technological maturation plays a critical role in shaping the evolution of products tailored for plantation and permanent crops. Innovations in crop monitoring and data analytics facilitate informed decision-making, enhancing productivity and operational efficiency. Technology progress provides growers access to advanced tools that streamline farming practices and improve overall crop management.
Regulatory compliance standards continue to influence market dynamics. Stricter policies promote the adoption of sustainable farming practices, compelling producers to integrate advanced technologies to meet these requirements. Compliance with such standards ensures that growers benefit from market access and consumer trust.
Cost structures, including initial investments in technology and ongoing operational expenses, pose challenges for smaller producers. Long-term benefits of enhanced productivity and resource management provide substantial returns on investment. Addressing pricing volatility through strategic planning and technology investment enhances resilience in the face of market fluctuations.
Increased focus on supply chain resilience ensures producers maintain a stable flow of goods from cultivation to market. Strategic partnerships and collaborations across the supply chain enhance logistics and distribution, mitigating vulnerabilities associated with raw material sourcing and transportation.
The Digital Crop Farming and Precision Agriculture market sees significant opportunities in the plantation and permanent crops segment. Strategic investment windows arise due to technology advancements, offering innovative solutions that cater to the evolving needs of growers. This segment holds great potential for expansion, driven by a combination of technological advancements and changing consumer preferences.
Growing demand for Forage & Fodder Crops stems from the increasing focus on livestock nutrition and the need for sustainable agricultural practices. Adoption of advanced technologies enhances yield management, leading to improved product quality and feed efficiency. Innovations in crop monitoring and precision agriculture facilitate effective management of forage resources, which supports overall farm productivity. The segment benefits from evolving consumer preferences for high-quality animal products, pushing producers to invest in advanced farming solutions.
Heightened interest from livestock producers aims to optimize operations and reduce costs associated with feed production. Regulatory compliance standards concerning animal welfare and environmental impact drive the adoption of precision farming practices. Strategic opportunities arise from the advancement of smart technologies that improve crop monitoring and data-driven decision-making, ensuring that forage and fodder crops meet the nutritional needs of various livestock species.
Investment in this segment aligns with broader trends in the Digital Crop Farming and Precision Agriculture market, focusing on sustainable practices and resource efficiency. Enhanced capital investment in next-gen upgrades and product evolution addresses challenges related to pricing volatility and margin pressures. The overall outlook indicates that continued technological maturation will further strengthen the position of Forage & Fodder Crops within the market.
Market dynamics for the Others (Turf, Herbs, Specialty Crops) segment reflect increasing interest in specialty crops driven by evolving consumer preferences for locally sourced and organic products. Factors contributing include a rising demand for sustainable agricultural practices, supporting the adoption of innovative farming technologies to enhance crop quality and yield.
Technological advancements play a crucial role in the cultivation of turf, herbs, and specialty crops, enabling better monitoring and management of growing conditions. Enhanced product evolution, including the integration of precision agriculture techniques, improves productivity and efficiency. Downstream applications incorporate these technologies into various end-use sectors, including landscaping, culinary arts, and pharmaceuticals, increasing consumption shifts within the market.
Regulatory compliance standards and certifications for organic farming enhance consumer confidence in these products. Compliance with these standards promotes market expansion by increasing the credibility of the offerings in the market. Cost structures and pricing volatility present challenges, particularly due to fluctuations in raw material sourcing and increasing labor costs, which affect profit margins.
Strategic opportunity windows are evident, driven by investments in research and development that continue to focus on enhancing cultivation techniques and improving product quality. The emergence of disruptive alternatives, including hydroponics and vertical farming, signifies a shift in operational paradigms, providing new avenues for growth in the Others (Turf, Herbs, Specialty Crops) segment. With ongoing technological maturation, the market anticipates capital investments aimed at driving innovation and expanding market reach within this specific crop type segment.
Based on geography, the Global Digital Crop Farming and Precision Agriculture market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America accounts for a substantial share of the Digital Crop Farming and Precision Agriculture market, with a projected market size of USD 13.5 billion by the end of 2033. This expansion reflects a compound annual growth rate (CAGR) of 13.1% during the forecast period. The United States, Canada, and Mexico play crucial roles in driving market dynamics through a combination of advanced technological adoption and a strong agricultural base.
The emphasis on precision farming techniques and data-driven decision-making enhances farm productivity and sustainability. Adoption rates of digital tools are higher in this region due to established infrastructure, strong investment in agricultural technology, and a robust framework for research and development. These factors contribute to significant market growth across various segments including software and services.
Mature market dynamics in North America indicate a shift towards high-value replacement cycles, where older farming technologies are replaced with more efficient digital solutions. Localized manufacturing densities and nearshoring initiatives strengthen the supply chain, enabling faster access to innovative products and services. Regional resource availability, particularly in technology and skilled labor, supports the ongoing evolution of the market.
Domestic market participants continue to innovate and consolidate, enhancing competitive landscapes and increasing pressure on less established players. The presence of established agricultural firms and technology providers encourages collaboration, pushing the market towards comprehensive solutions that combine hardware, software, and services tailored to regional needs. These dynamics further highlight the importance of North America in shaping the future of the Digital Crop Farming and Precision Agriculture market.
The Digital Crop Farming and Precision Agriculture market in Europe demonstrates strong growth potential, driven by increasing technological adoption among farmers and agricultural companies. Countries like Germany, France, the UK, Italy, and Spain lead the region in deploying advanced agricultural technologies, which enhance productivity and crop management efficiencies. Investments in infrastructure modernization contribute significantly to this growth, facilitating improved access to precision agriculture solutions.
Emerging market front-runners in Europe, including Germany and France, exhibit robust adoption rates of digital farming tools, influenced by the necessity for sustainable practices and regulatory compliance. The region's diverse agricultural landscape, characterized by varying crop types, supports segment expansion, especially in software solutions that optimize farm planning and crop monitoring.
Localized procurement dynamics play a critical role in shaping market behavior in Europe, because companies seek to align with regional suppliers to enhance operational efficiencies. Cultural nuances in agricultural practices influence B2B buying behaviors, with European farmers increasingly favoring solutions that integrate seamlessly into existing workflows.
The Digital Crop Farming and Precision Agriculture market in Europe anticipates substantial growth fueled by high-value replacement cycles for outdated technologies. An emphasis on enhancing yield and resource management, combined with favorable foreign direct investment flows, strengthens market prospects. These trends collectively position Europe because a competitive landscape for digital agriculture solutions.
Rapid urbanization and population growth in Asia-Pacific significantly influence the Digital Crop Farming and Precision Agriculture market. Countries including China and India present unique opportunities due to their extensive agricultural landscapes and rising demand for food security. Technological advancements in precision farming enhance productivity and efficiency, attracting investments across the region. The increasing adoption of data-driven solutions supports farm planning, crop monitoring, and resource management, driving market expansion.
Infrastructure modernization enhances agricultural practices. Improved transportation networks and access to digital technologies facilitate the implementation of precision agriculture solutions. Countries like Japan and South Korea focus on integrating advanced technologies, creating a competitive environment that encourages innovation within the market.
Localized manufacturing and nearshoring initiatives contribute to market growth by providing tailored solutions that address specific regional needs. Domestic players in Southeast Asia leverage their understanding of local markets, enhancing their capabilities to meet the unique demands of farmers. This localized approach strengthens supply chains, ensuring timely delivery of products and services.
Competitive dynamics in Asia-Pacific illustrate a landscape characterized by significant vendor consolidation trends. Leading companies are focusing on strategic partnerships and collaborations to enhance their market presence. Investment in research and development enables these players to create innovative solutions that cater to the evolving needs of farmers, further propelling the growth of the market.
Asia-Pacific holds an increasing share of the global market, with an estimated value of USD 15.7 billion in 2025. The region's diverse agricultural needs, technological advancements, and competitive landscape position it for significant growth in the Digital Crop Farming and Precision Agriculture market through 2033.
The Digital Crop Farming and Precision Agriculture market in South America represents a growing opportunity with a share of 7.0% in 2025. Brazil and Argentina serve because the primary contributors to market expansion, driven by increasing agricultural productivity and technological adoption.
Investment in modern farming technologies remains essential for enhancing efficiency and output. Localized procurement dynamics and cultural nuances influence buying behaviors, particularly in Brazil and Argentina, where farmers adopt innovations that improve crop yields and reduce inputs.
Emerging market front-runners actively seek to modernize agricultural practices, addressing underpenetrated territories that present significant growth potential. The market in South America benefits from strategic entry barriers that encourage foreign direct investment (FDI), supporting localized manufacturing and supply chain regionalization.
Infrastructure readiness, particularly in rural areas, is essential for facilitating the adoption of precision agriculture technologies. With a focus on sustainability and resource optimization, the market is expected to experience incremental growth vectors in the coming years.
Understanding regional compliance mandates and local regulatory frameworks contributes to effective market navigation. The competitive landscape features domestic market participants who leverage innovative solutions to meet increasing demand, positioning themselves advantageously within the Digital Crop Farming and Precision Agriculture market.
The Digital Crop Farming and Precision Agriculture market in the Middle East and Africa faces unique challenges and opportunities influenced by regional dynamics. A share of 5.0% of the global market in 2025 highlights the region's current positioning while indicating significant growth potential driven by increasing local awareness of precision agriculture technologies. Countries including Saudi Arabia and the UAE demonstrate enhanced investment in advanced farming technologies and practices to support food security initiatives. South Africa contributes to market development through various agricultural programs aimed at modernizing farming practices.
Infrastructure modernization remains critical for enhancing adoption rates. Efforts to improve irrigation systems, telecommunications, and supply chain logistics play a vital role in encouraging investment in precision agriculture. Localized procurement dynamics and cultural nuances significantly influence B2B buying behaviors, resulting in tailored solutions that address specific needs within the region.
The Digital Crop Farming and Precision Agriculture market continues to evolve, driven by domestic market leaders strengthening their positions. Geopolitical factors and regulatory frameworks add complexity, resulting in varying levels of compliance among countries. Despite these challenges, the region's potential for growth remains robust, particularly in underpenetrated territories where investment yields substantial returns.
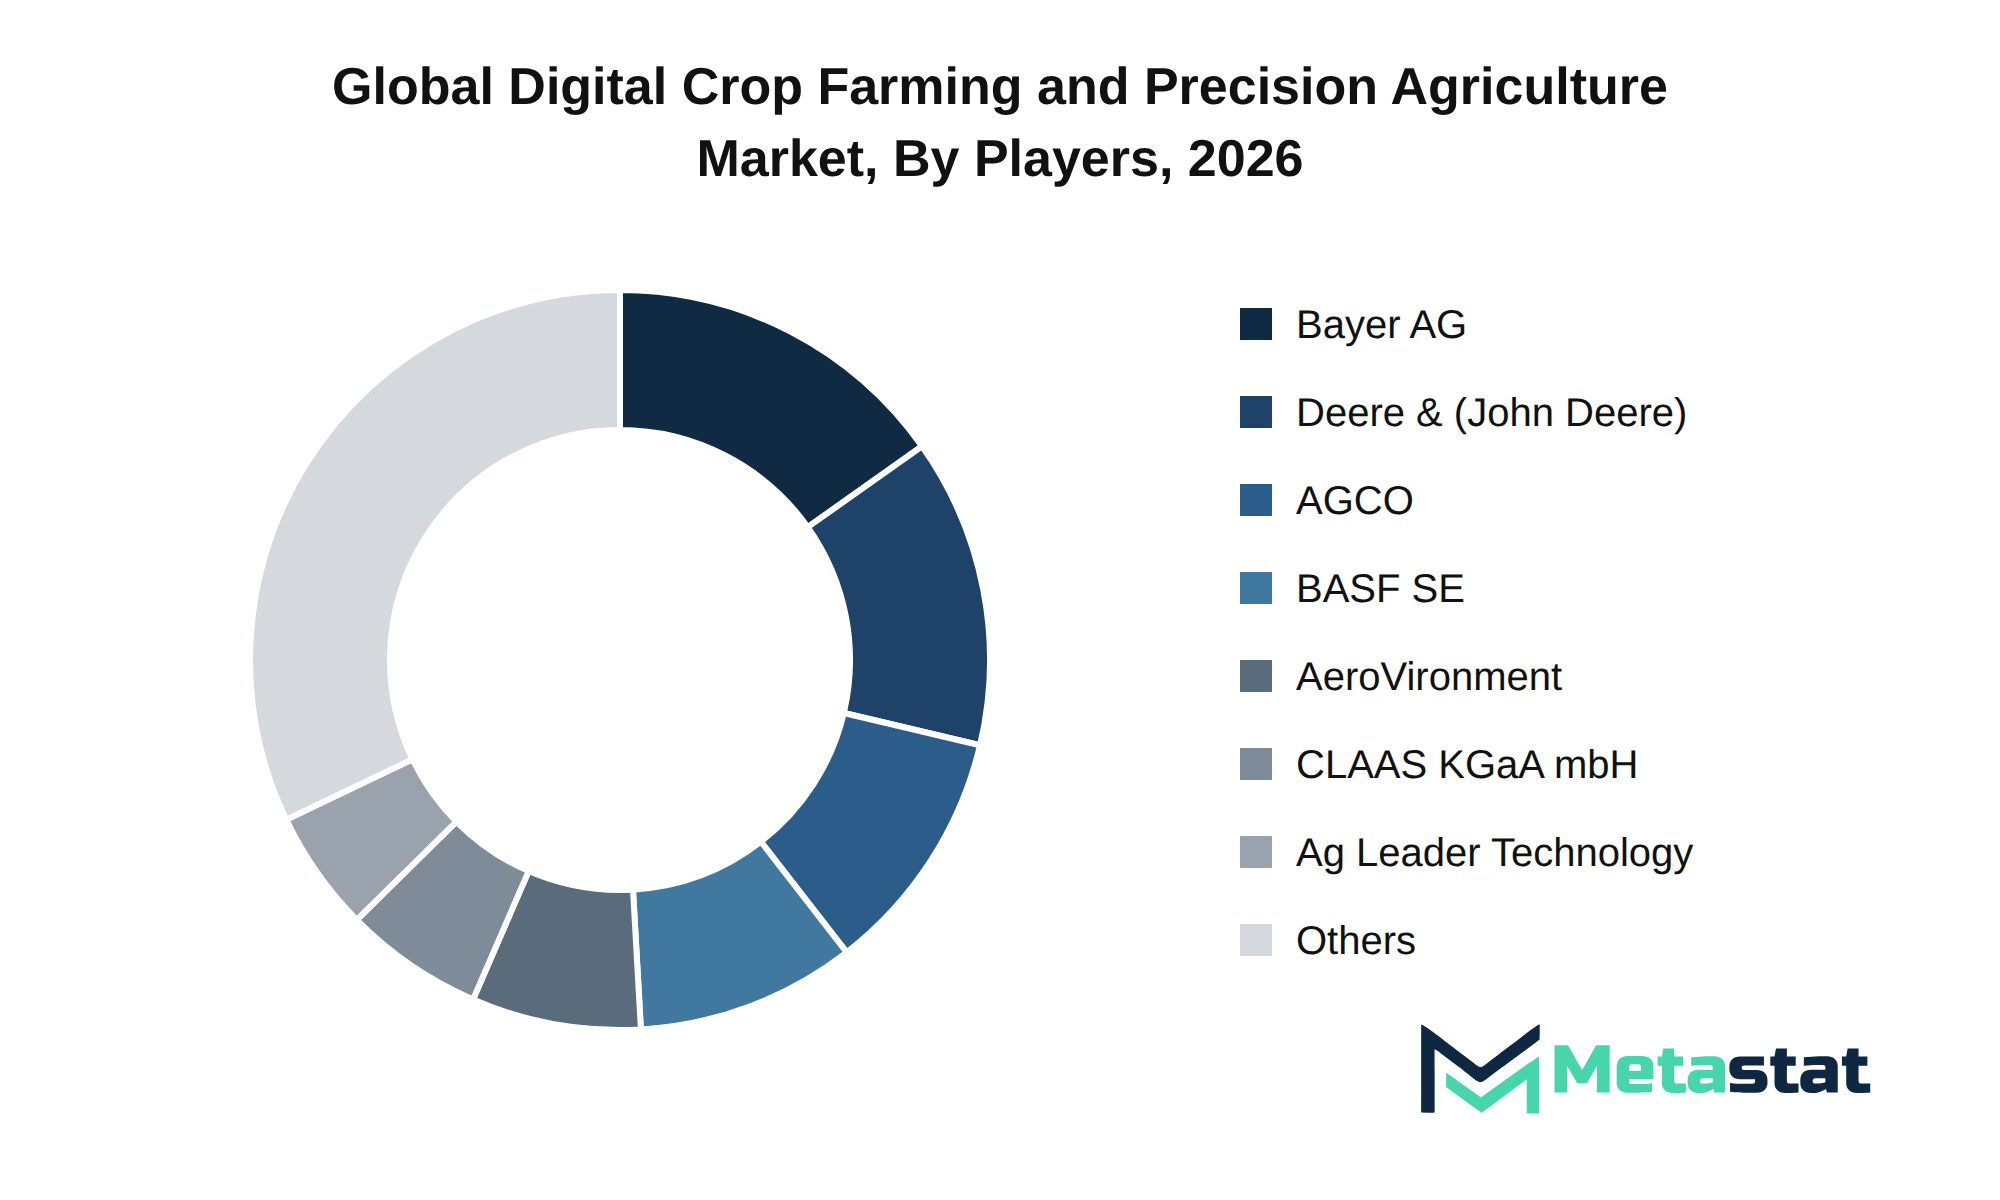
The Digital Crop Farming and Precision Agriculture market experiences significant competitive dynamics driven by mergers, acquisitions, and strategic consolidation among major players. Companies including Bayer AG, BASF SE, and AGCO Corporation pursue aggressive growth strategies through collaborative ventures and acquisitions designed to broaden product portfolios and enhance technological capabilities.
Strategic alliances play a crucial role in expanding market presence and driving innovation. Partnerships among technology firms, like IBM Corporation and Microsoft Corporation, focus on integrating advanced data analytics and artificial intelligence into farming solutions, ensuring their offerings remain competitive. Companies invest in R&D pipelines to develop proprietary technologies that address evolving agricultural challenges, reinforcing their market positions.
Barriers to entry remain high due to established brand equity and intellectual property portfolios held by dominant players. Startups in the market face challenges in achieving scale and gaining visibility against well-capitalized companies like Deere & Company (John Deere) and Trimble. These larger firms leverage extensive supply chains and procurement capabilities to maintain pricing power and customer loyalty.
The competitive outlook for the Digital Crop Farming and Precision Agriculture market indicates a focus on value chain integration and supply chain dominance. Companies including CNH Industrial N.V. and Kubota Corporation demonstrate this by enhancing operational efficiencies and ensuring customer retention through tailored solutions. While technological advancements unfold, firms navigate the landscape carefully, ensuring sustained growth while addressing emerging threats from new entrants and disruptive startups.
Market size is forecast to rise from USD 15.7 billion in 2025 to over USD 42 billion by 2033. The base case reflects growth at a 13.1% CAGR, driven by increasing adoption of next-generation technologies and the integration of advanced solutions in the agricultural sector. A bullish outlook anticipates rapid advancements in research and development, leading to the commercialization of innovative products that enhance efficiency and productivity.
Conversely, a bearish scenario could arise from economic fluctuations, regulatory changes, or geopolitical tensions that disrupt the supply chain. External pressures hinder investment in infrastructure and capital expenditures, impacting the overall growth trajectory. Nonetheless, the Digital Crop Farming and Precision Agriculture market benefits from structural consumption shifts, where heightened awareness of sustainability and food security increases demand for precision agriculture solutions.
Ongoing regulatory evolution and compliance milestones further shape the market landscape, creating opportunities for businesses that adapt to these changes effectively. While new policies emerge, strategic capital allocation will focus on high-growth pockets and unmet enterprise needs. Companies that prioritize innovation and align with executive-level strategic imperatives are well positioned to capitalize on future growth opportunities within the Digital Crop Farming and Precision Agriculture market.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Digital Crop Farming and Precision Agriculture market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 13.1% from 2026 to 2033 |
Revenue Unit | USD billion |
Segmentation | By Offering, Application, Crop Type, and Region |
By Region | North America (By Offering, Application, Crop Type, and Country)
|
Europe (By Offering, Application, Crop Type, and Country)
| |
Asia Pacific (By Offering, Application, Crop Type, and Country)
| |
South America (By Offering, Application, Crop Type, and Country)
| |
Middle East and Africa (By Offering, Application, Crop Type, and Country)
|
Find answers to common questions about this report
The Digital Crop Farming and Precision Agriculture market size was valued at USD 15.7 billion in 2025.
The Digital Crop Farming and Precision Agriculture market is projected to grow at a CAGR of 13.1% during the forecast period from 2026 to 2033.
The North America Digital Crop Farming and Precision Agriculture market size is estimated to reach USD 13.5 billion by 2033.
The Software segment leads the Digital Crop Farming and Precision Agriculture market, projected to reach USD 16.2 billion by 2033. This figure surpasses other segments based on growth potential and revenue generation.
Investment in advanced agricultural technologies drives the Digital Crop Farming and Precision Agriculture market. Growth in GDP, favorable capital investment conditions, and increasing urbanization contribute to demand for efficient and sustainable farming practices. Technological integration, including automation and artificial intelligence, enhances operational productivity and resource management, positioning the market for significant expansion.
North America holds the dominant share of the Digital Crop Farming and Precision Agriculture market, with a value of USD 13.5 billion in 2033, representing 35.6 percent of the total market.
Compliance hurdles associated with regulatory frameworks significantly hinder progress in the Digital Crop Farming and Precision Agriculture market. High capital investment requirements, inflationary pressures, and infrastructure gaps further restrict adoption and growth potential. data security vulnerabilities and market fragmentation complicate the competitive landscape, limiting stakeholders' ability to fully embrace advanced technologies.
Investment in advanced agricultural technologies is increasing due to favorable macro-economic factors, including growth in GDP and low-interest rates. the integration of automation and artificial intelligence enhances operational productivity and aligns with evolving consumer preferences for sustainable farming practices. These elements collectively drive demand for precision agriculture solutions.
The Digital Crop Farming and Precision Agriculture market is estimated to reach a valuation of USD 42 billion by 2033.
Key players operating in the Digital Crop Farming and Precision Agriculture market include AeroVironment Inc, AGCO Corporation, Bayer AG, Deere & Company (John Deere), IBM Corporation, Syngenta Group, Trimble, and Valmont Industries, Inc. (Valley Irrigation).
Choose Your License
Global Digital Crop Farming and Precision Agriculture Market
The analysts below cover Agriculture research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
Our team was tracking whether regional recycling infrastructure could realistically absorb the growing volume of lithium iron phosphate batteries over the next decade. The report did a solid job separating announced hydrometallurgical plant capacity from active, permitted operational throughput. That distinction made the feedstock availability projections and regional recovery rate models far more credible than standard commercial overviews.
Tracking capacity expansion in single-use bioprocessing requires dependable data on raw material availability and cleanroom-grade polymer supply chains. The competitive landscape chapter gave a grounded evaluation of secondary component suppliers across North America and Asia-Pacific rather than simply reprinting press releases. Having that level of supplier benchmarking helped clarify dual-sourcing considerations for our clinical pipeline planning.
When evaluating distributed energy resource management systems, standard research summaries tend to gloss over the operational differences between front-of-the-meter utility deployments and behind-the-meter industrial sites. The MetaStat Insight report addressed those distinctions directly, especially regarding software interoperability standards and grid interconnection backlogs. The five-year market sizing across regional transmission organizations provided actionable context for our grid modernization strategy.
Explore related market intelligence reports worth reading alongside this one.