
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Meat Analogue Market Size, Share, By Product Type (Burgers and Patties, Mince and Ground Meat Analogues, Sausages and Hot Dogs, Nuggets and Tenders, Chunks, Strips and Pieces, Steaks, Fillets and Whole-Cut Analogues, Meatballs, Deli Slices and Cold Cuts), By Primary Protein Source (Soy Protein, Wheat Protein and Seitan, Pea Protein, Mycoprotein, Mycelium Protein), By Meat Analogue Type (Beef Analogues, Chicken Analogues, Pork Analogues, Seafood Analogues), By Distribution Channel (Supermarkets and Hypermarkets, Convenience Stores, Specialty and Natural Food Stores, Online Retail, Foodservice), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5398
September, 2026
257 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $7,515.9 Million in 2025, projected to reach $18,748.1 Million by 2033 at a 12.1% CAGR.
Dominant Segment: The Burgers and Patties segment leads the market, projected to grow from USD 2,348.6 million in 2026 to USD 4,679.5 million by 2033, driven by increasing health consciousness and demand for plant-based options.
Geographic Lead: The Asia Pacific region emerges as a key growth market for meat analogues, fueled by rising disposable incomes and changing dietary preferences that favor plant-based products.
What's Inside: The report provides a comprehensive analysis of the competitive landscape, market segmentation by product type, protein source, and distribution channel, along with growth trends and forecasts from 2026 to 2033.
Emerging Trends: Technological advancements and innovation in protein sources are reshaping product offerings, with a focus on enhancing taste, texture, and nutritional profiles to meet evolving consumer demands.
Foodservice Adoption: The foodservice sector presents significant growth opportunities as restaurants increasingly incorporate meat analogues into their menus, catering to health-conscious diners.
The global Meat Analogue market was valued at USD 7,515.9 million in 2025 and is projected to reach USD 18,748.1 million by 2033, growing at a CAGR of 12.1% over the forecast period.
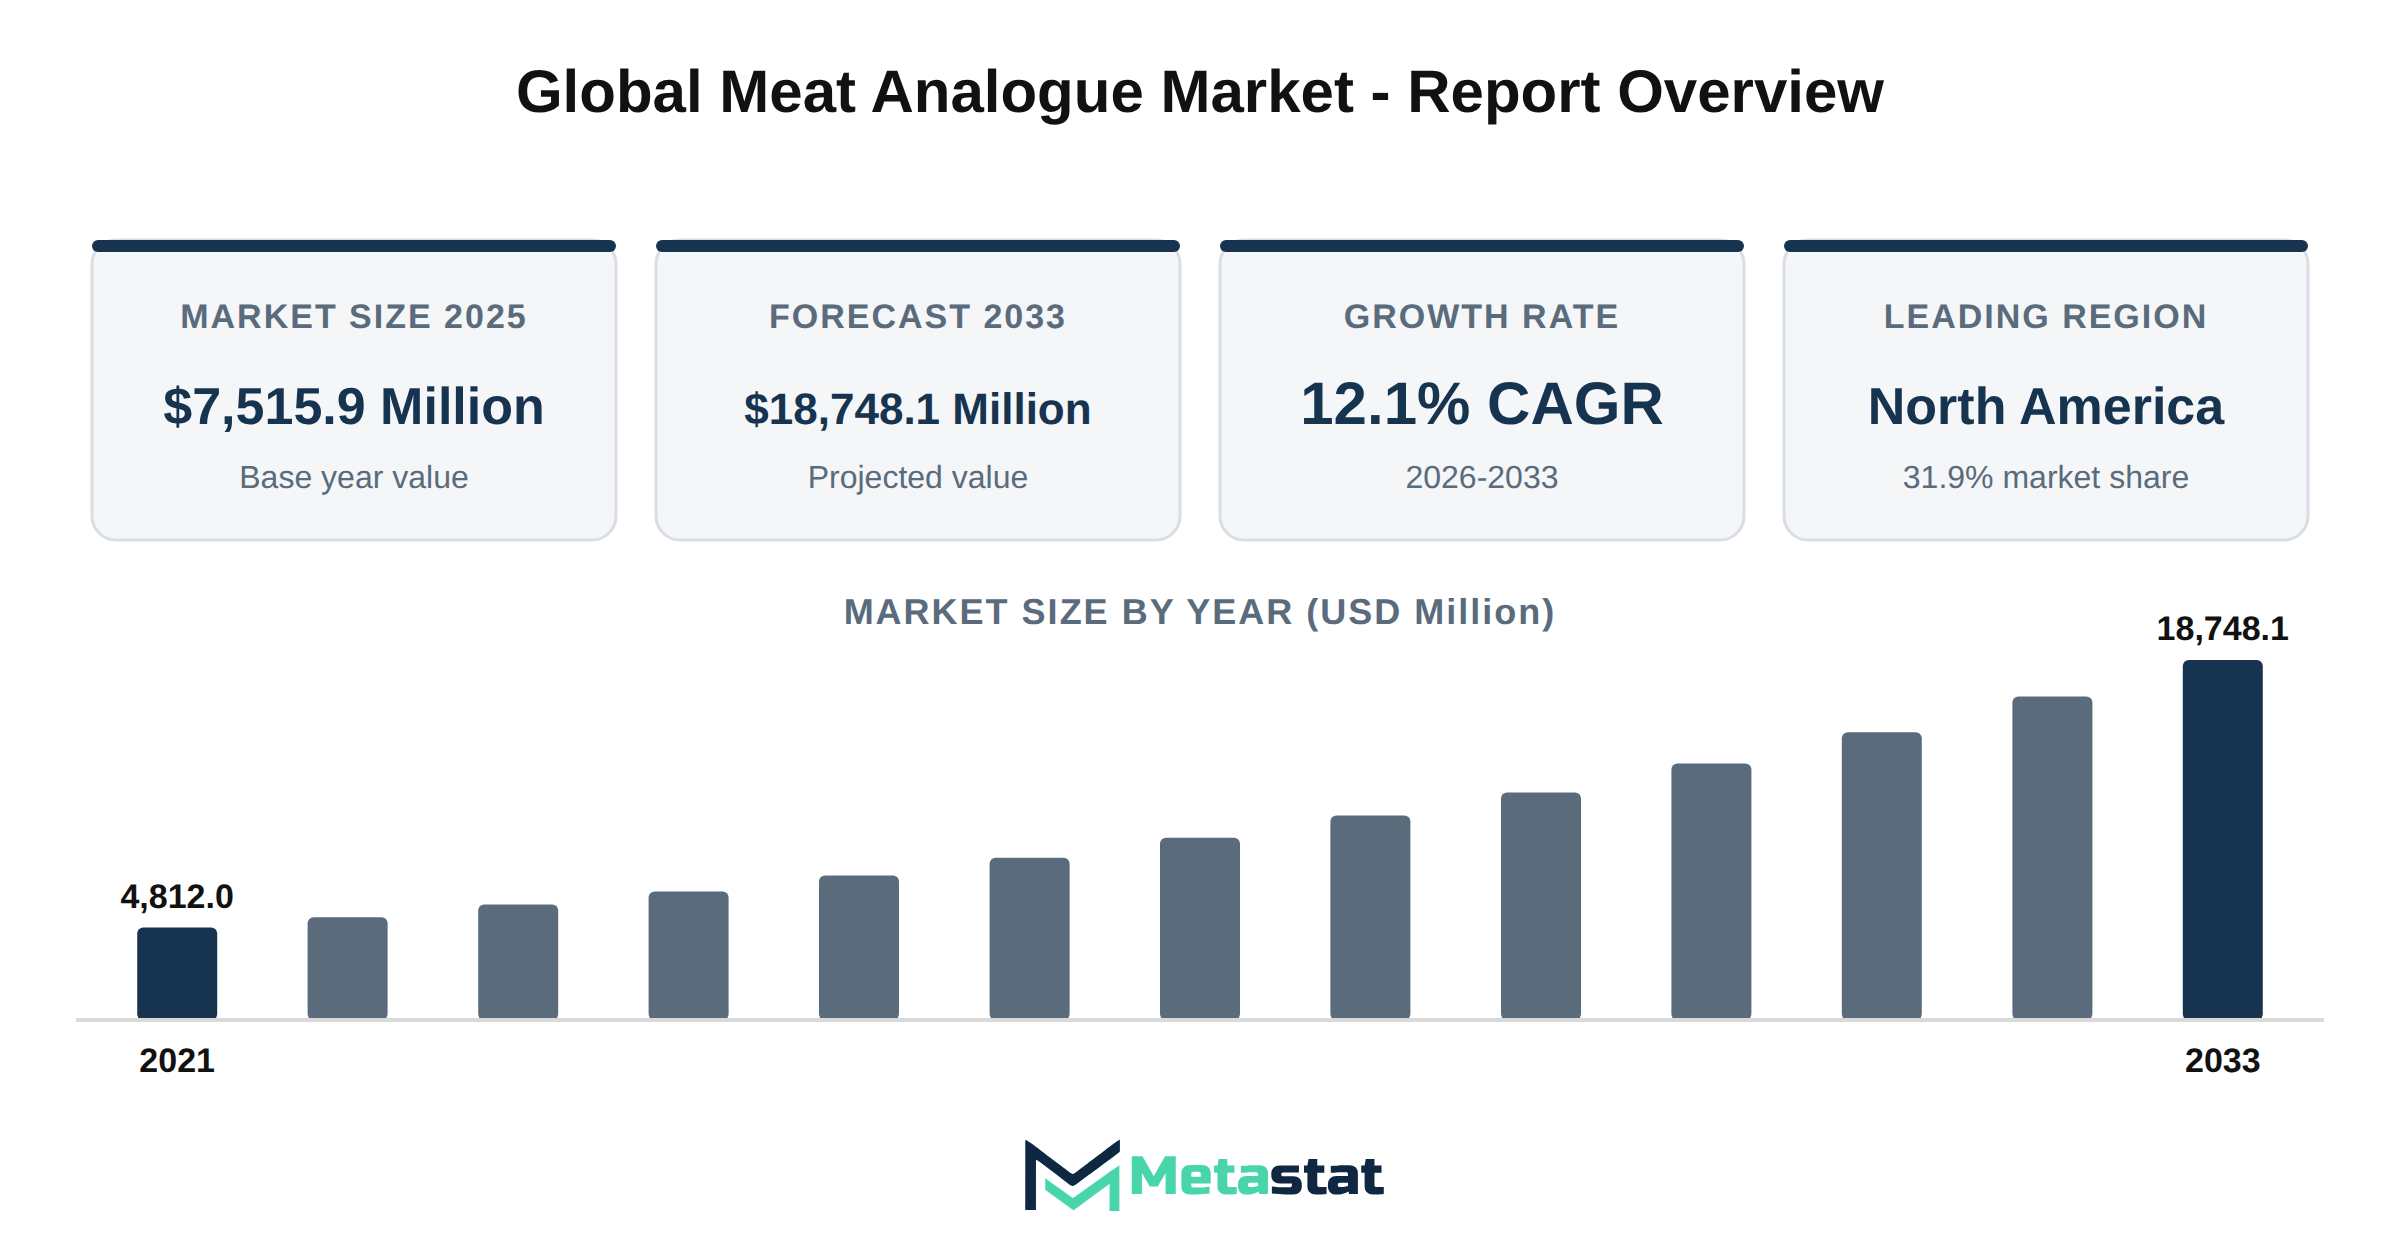
The global Meat Analogue market is experiencing significant growth, with a base value of USD 7,515.9 million in 2025, projected to reach USD 18,748.1 million by 2033, reflecting a compound annual growth rate (CAGR) of 12.1%. This expansion is driven by increasing consumer demand for plant-based alternatives, compelling manufacturers to innovate and adapt their product offerings.
Shifts in demand for plant-based meat products highlight changing consumer preferences toward healthier and sustainable food choices. The rise of flexitarian diets, where consumers incorporate more plant-based foods into their meals, is a critical factor influencing growth in the market. Younger consumers, particularly millennials and Gen Z, prioritize ethical sourcing and environmental impact, further driving the adoption of meat analogue products.
Innovation in protein sources is reshaping the Meat Analogue market, with manufacturers exploring diverse ingredients to enhance product appeal. Soy protein remains a dominant choice, while wheat protein and pea protein are gaining traction due to their nutritional benefits and functional properties. Mycoprotein and mycelium proteins are emerging because viable alternatives, broadening the spectrum of offerings available to consumers.
Whole-cut meat analogues are gaining commercial momentum, appealing to consumers seeking authentic meat experiences without compromising on taste or texture. Advancements in food technology facilitate the development of products that closely mimic traditional meat, enabling companies to capture a larger share of consumer interest. Beef and chicken analogues lead product development, reflecting the high demand for these protein types in various cuisines globally.
Trends towards clean-label formulations are prevalent within the Meat Analogue market, because consumers increasingly seek transparency regarding ingredient sourcing and processing. This demand for simplicity drives companies to formulate products with fewer additives and preservatives, aligning with consumer preferences for wholesome and natural food options.
Innovations in taste, texture, and nutrition are central to product development in the market. Manufacturers invest in research and development to create meat analogues that satisfy consumer expectations, focusing on flavor profiles and mouthfeel that replicate traditional meat products. This emphasis on sensory experience enhances market competitiveness and builds consumer loyalty.
Pricing strategies and cost competitiveness play a crucial role in market dynamics. With the rising availability of raw materials and advancements in production techniques, companies strive to maintain affordability while ensuring quality. This balance influences consumer purchasing decisions and shapes market growth trajectories.
Retail expansion significantly accelerates meat analogue availability, with supermarkets and hypermarkets leading distribution efforts. The growth of online retail channels further strengthens direct-to-consumer sales, allowing brands to reach broader audiences and cater to evolving shopping behaviors. Foodservice adoption generates new growth opportunities, because restaurants and cafes increasingly incorporate meat analogues into their menus, appealing to health-conscious diners.
Shifts in plant-based meat demand reflect a growing consumer inclination towards healthier and sustainable food options. This movement drives the adoption of meat analogues across diverse demographics, particularly among millennials and gen Z consumers. The market experiences a surge in interest driven by more individuals seeking alternatives to traditional meat products, leading to increased investment in marketing and product development focused on taste and nutritional benefits.
Innovation in protein sources significantly impacts the formulation of meat analogue products. Manufacturers explore various plant proteins, including soy, pea, and wheat, to enhance the texture and flavor profiles of their offerings. This diversification allows brands to cater to a broader range of dietary preferences and restrictions, ultimately driving market growth.
Whole-cut meat analogues are gaining traction within the market, appealing to consumers seeking authentic meat experiences. Developments in technology enable manufacturers to create products that closely mimic the taste and texture of traditional meat cuts. This trend opens new avenues for product launches and expands the consumer base for meat analogues.
Beef and chicken analogues dominate product development efforts, reflecting consumer familiarity and preference. These categories command significant market share, driving innovation in flavor, texture, and overall quality. Companies increasingly invest resources into refining these product types to meet rising consumer expectations.
Mycoprotein and mycelium are emerging because viable alternative protein sources in the meat analogue market. Their unique nutritional profiles and sustainable production methods attract attention from health-conscious consumers. This trend drives the introduction of innovative products that provide additional options for consumers seeking plant-based alternatives.
Clean-label formulations are becoming a standard expectation among consumers, prompting manufacturers to focus on transparency and ingredient integrity. The shift towards recognizable ingredients enhances consumer trust and encourages brand loyalty. This trend significantly influences product development strategies within the market.
Innovation within the market prioritizes taste, texture, and nutritional content. Manufacturers invest in research and development to create products that not only satisfy taste preferences but deliver nutritional benefits. This focus supports the growth of the market and enhances consumer engagement with meat analogue products.
Pricing strategies in the meat analogue market reflect competitive dynamics and consumer willingness to pay. Brands strive to balance quality and affordability, which influences market penetration and sales growth. Cost competitiveness remains critical because consumers increasingly evaluate value in their food choices.
Expansion of retail channels enhances the availability of meat analogues, facilitating greater consumer access. Supermarkets, specialty stores, and online platforms are key distribution channels, contributing to increased product visibility. This trend directly influences market growth by attracting new customers and enhancing brand recognition.
The foodservice sector presents new growth opportunities for meat analogue products. Restaurants and food establishments increasingly incorporate these alternatives into their menus, catering to evolving consumer preferences. This trend enhances market visibility and drives sales for manufacturers.
Online retail channels strengthen direct-to-consumer sales within the market. The convenience of online shopping and the increasing popularity of home delivery services drive consumer engagement with meat analogue products. This shift in purchasing behavior supports revenue growth and expands market reach.
Private-label products are intensifying competitive pressure within the meat analogue market. Retailers increasingly introduce their own brands, often at lower price points, which challenges established brands to innovate and differentiate their offerings. This trend influences market dynamics and encourages ongoing product enhancements.
Manufacturing advancements and scale-up developments enhance the production capabilities of meat analogue products. Innovations in processing techniques and supply chain management contribute to improved efficiency and reduced costs. These improvements support market growth by enabling manufacturers to meet rising demand.
Supply dynamics of key raw materials, including soy, pea, and wheat proteins, significantly impact market stability. Fluctuations in availability and pricing of these ingredients influence production costs and pricing strategies. Manufacturers closely monitor these dynamics to navigate potential challenges in sourcing.
Sustainability claims increasingly influence purchasing decisions among consumers in the meat analogue market. A growing segment of the population prioritizes eco-friendly products, prompting brands to highlight their sustainability efforts. This trend shapes marketing strategies and product positioning within the competitive environment.
Regulatory scrutiny regarding labeling practices for plant-based meat products continues to evolve. Manufacturers navigate compliance requirements to ensure accurate representation of product contents. This scrutiny impacts marketing strategies and consumer perception of meat analogues.
Investment trends within alternative protein technologies reveal increasing interest from venture capitalists and industry stakeholders. Funding directed towards innovative startups and established players accelerates research and development efforts, driving advancements in product quality and market reach.
Strategic partnerships and consolidation among companies in the plant-based meat sector enhance competitive positioning. Collaborations facilitate resource sharing, technology transfer, and market expansion opportunities. This trend influences the overall structure of the market, shaping future growth trajectories.
The Asia Pacific region emerges because a significant growth market for meat analogues. Rising disposable incomes and changing dietary preferences contribute to increased demand for plant-based products. Companies strategically target this region to capitalize on growth opportunities and expand their market presence.
Future growth opportunities in next-generation meat analogues lie in innovation and consumer engagement. Continuous advancements in technology and product development will further enhance the appeal of meat analogues. Brands that effectively address consumer needs and preferences will position themselves for success in the expanding market.
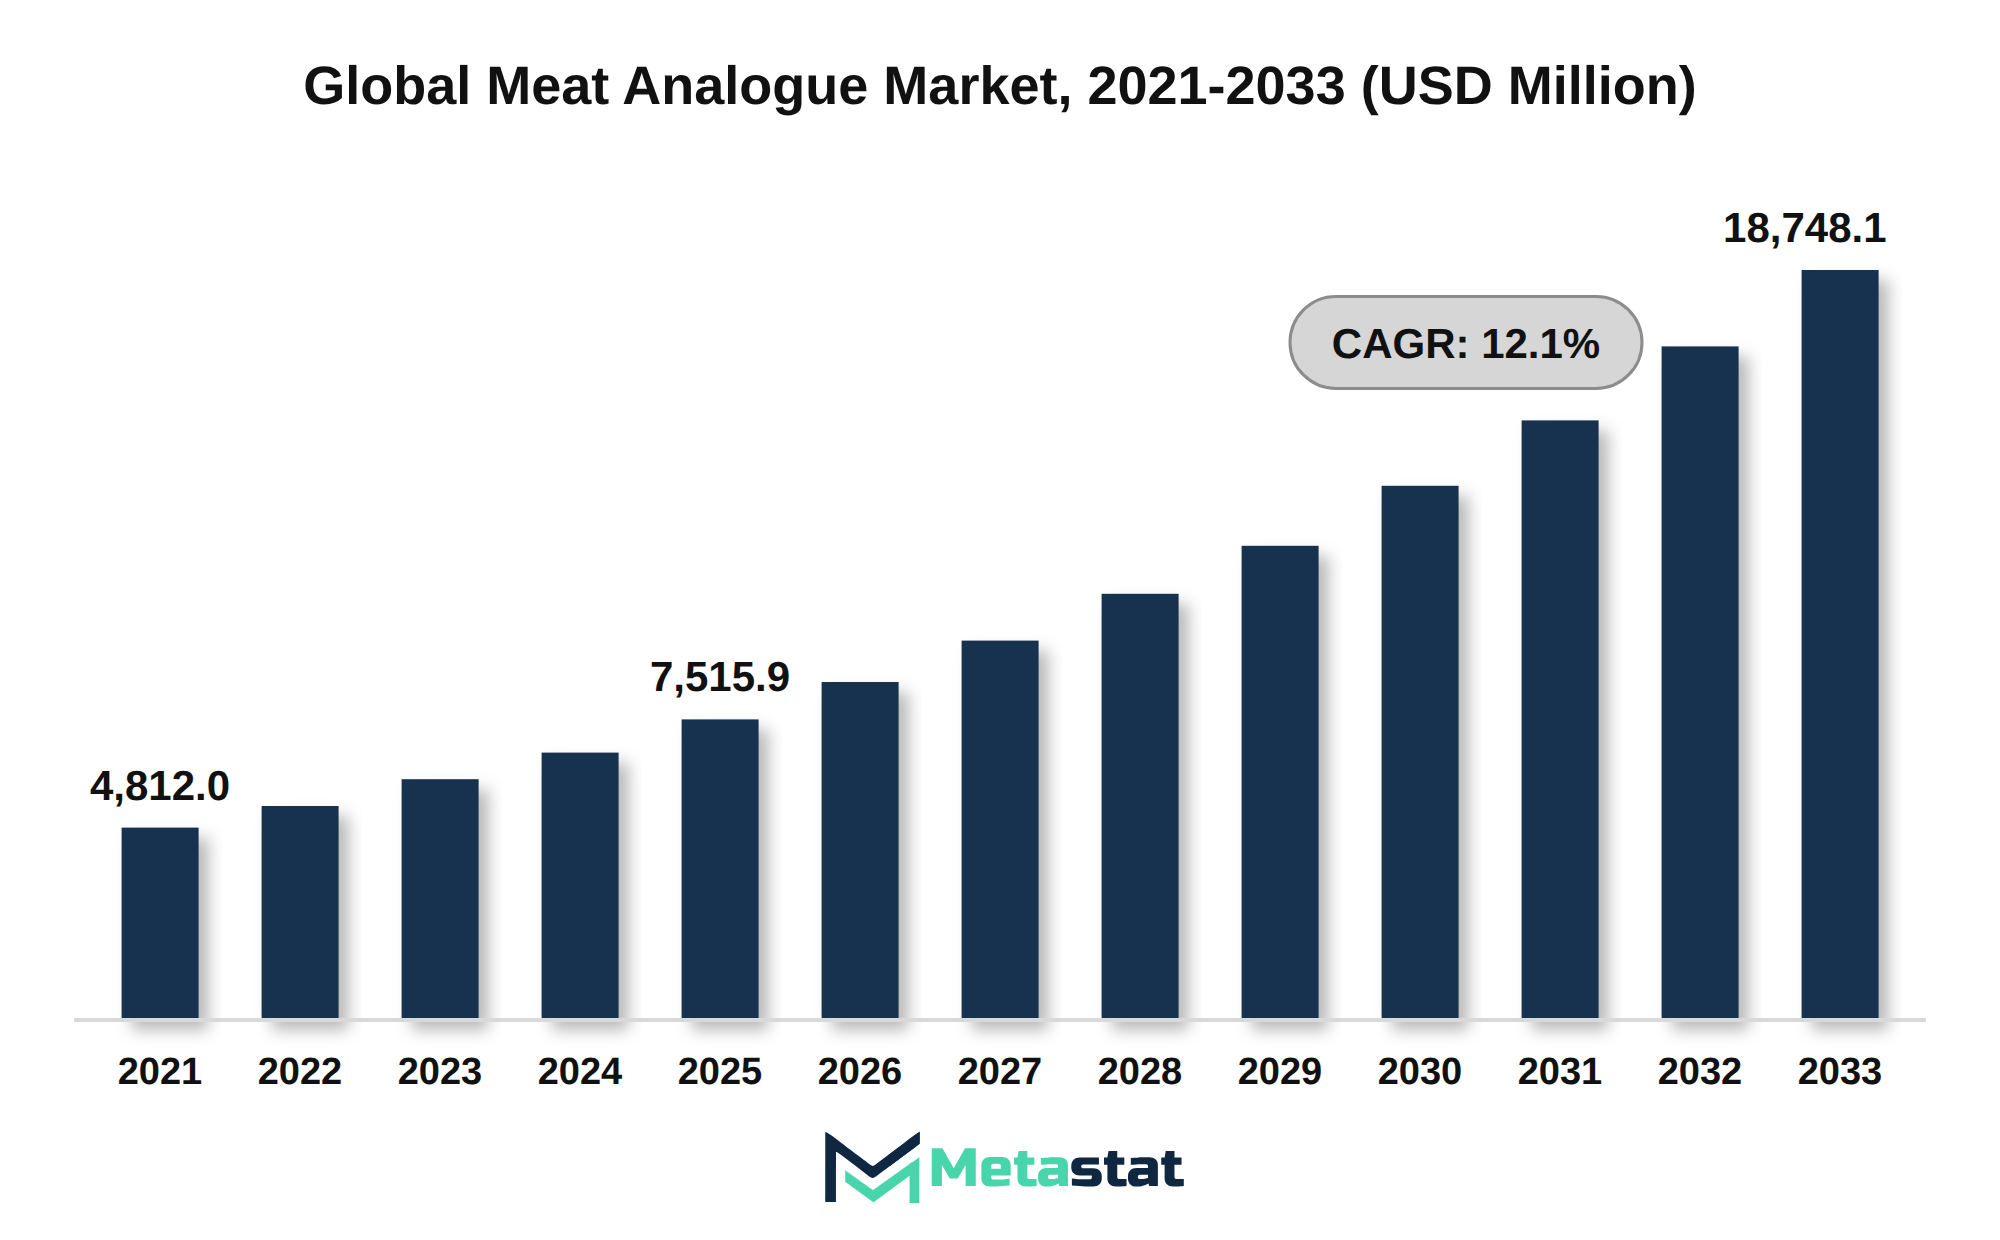
The Meat Analogue market experiences growth driven by changing consumer preferences, particularly towards health and sustainability. Increasing awareness about the impacts of meat consumption on health and the environment influences many consumers to seek alternatives. The rising popularity of plant-based diets reflects a broader societal shift towards healthy eating and ethical food choices.
Urbanization influences this trend, with city dwellers exhibiting a greater inclination to adopt meat analogue products. Busy lifestyles in urban areas contribute to the demand for convenient, ready-to-eat options that align with health-conscious dietary preferences. Younger generations, particularly millennials and Gen Z, prioritize sustainability and ethical sourcing, prompting manufacturers to innovate and expand their offerings within the market.
The growing availability of meat analogue products in supermarkets and online retailers enhances consumer access, further driving demand. Innovations in product development, including improved taste and texture, cater to the evolving expectations of consumers, reinforcing the meat analogue's role in modern diets. This trend sets the foundation for significant growth in the market, with expectations for continued expansion driven by increasing consumer awareness and preference for plant-based options.
The Meat Analogue market experiences notable growth driven by increasing consumer awareness surrounding sustainability initiatives. Concerns related to environmental impact, climate change, and resource conservation influence purchasing behaviors. Consumers prefer products that align with their values, resulting in heightened demand for meat analogue products that emphasize sustainable production methods.
Companies focusing on sustainable practices, including eco-friendly sourcing and production, capture the interest of environmentally conscious consumers. This trend leads to an expansion in product offerings that highlight plant-based ingredients and reduced carbon footprints. Marketing meat analogue products based on their sustainability credentials enhances competitive positioning and drives revenue growth.
Investment in sustainable technologies and practices supports innovation within the market. Firms embracing sustainable approaches experience enhanced operational efficiency and cost benefits, creating a favorable business climate. Companies strive to meet consumer expectations while anticipating continued investment in research and development of sustainable meat analogue options.
Sustainability initiatives present a significant growth driver, positioning the Meat Analogue market favorably within the broader food industry. The ongoing shift toward environmentally responsible practices is expected to maintain momentum, encouraging further adoption and market expansion.
The Meat Analogue market faces challenges stemming from regulatory compliance and the evolving legal landscape. Stricter regulations surrounding food safety and labeling requirements impose additional costs on producers, hindering their ability to innovate and compete effectively. These compliance hurdles create burdens for manufacturers navigating federal and state laws, leading to delays in product launches and market entry.
Macroeconomic factors exacerbate these challenges. Inflationary pressures affect production costs, including raw materials and labor, which constrain profit margins. Suppliers experience difficulty managing these rising costs, impacting their capacity to invest in new technologies or expand production capabilities. Compounded by geopolitical instability, the market encounters disruptions in the supply chain, complicating procurement and logistics.
Infrastructure gaps pose significant barriers to market growth. Limited access to distribution networks and insufficient cold chain facilities impede the efficient movement of products from manufacturers to consumers. This lack of connectivity slows down market penetration efforts and limits the availability of meat analogue products in certain regions, ultimately affecting sales performance.
Skilled labor deficiencies contribute to operational challenges within the market. Difficulty attracting and retaining talent restricts innovation and leads to inefficiencies in production processes. Data security vulnerabilities and privacy concerns create operational risks for companies, impacting consumer trust and brand reputation, which are crucial for sustaining market growth.
The combination of these factors leads to market fragmentation, where varying regional regulations and consumer preferences create a complex competitive environment. Players in the Meat Analogue market address these challenges to ensure sustained growth and adapt to an evolving landscape marked by heightened scrutiny and changing consumer expectations.
The Meat Analogue market encounters significant challenges stemming from geopolitical fragmentation and trade deficits. These factors disrupt supply chains and create uncertainty in sourcing materials, impacting production timelines and costs. Trade restrictions and tariffs imposed by various countries inflate costs for manufacturers, leading to increased prices for end consumers and reducing market competitiveness.
Technological disruptions and complex research and development integrations complicate the market landscape. Innovations in product formulations and production techniques require substantial investment in R&D, straining financial resources for smaller players. The current environment prioritizes rapid advancements; however, firms face hurdles in keeping pace with evolving technologies.
Supply chain instability results from logistics disruptions and feedstock volatility, adversely affecting the timely delivery of ingredients and components. Fluctuations in raw material availability and costs, influenced by global market dynamics, add pressure on profit margins. These operational challenges hinder manufacturers' ability to scale efficiently, limiting growth potential in the Meat Analogue market.
Tightening global regulatory standards and compliance overhead represent another barrier. Firms navigate complex legal landscapes that demand adherence to stringent environmental and safety regulations, diverting resources from core business activities. The evolving nature of liabilities in this regulatory climate complicates operational strategies and impacts investment decisions.
Market saturation and changing downstream demands create additional pressure on the Meat Analogue market. Increased competition from both traditional and alternative protein sources prompts innovations in product offerings. Companies adapt to shifting consumer preferences while addressing pricing compression, which threatens profitability in a highly competitive space.
The Meat Analogue market experiences robust opportunity fueled by several emerging trends. Increasing regional demands for plant-based alternatives highlight a shift in consumer preferences towards sustainable diets. This transformation drives manufacturers to innovate and expand product offerings, tapping into various protein sources including soy, pea, and mycoprotein. The growth trajectory of the market is expected to accelerate through 2033, reaching an estimated value of USD 18,748.1 million.
Infrastructure modernization in distribution channels supports the wider availability of meat analogue products. Supermarkets and hypermarkets lead the way, with significant projected growth from USD 3,418.7 million in 2026 to USD 6,921.8 million in 2033. Online retail channels further enhance accessibility by catering to evolving buying behaviors, enabling consumers to purchase products conveniently from their homes.
Technological disruptions contribute to the development of next-generation innovations in meat analogue products. Advances in food technology enable the creation of more appealing textures and flavors, enhancing consumer acceptance. This progress aligns with sustainability imperatives, where reducing the environmental impact of protein production becomes essential for many brands.
Strategic consolidation among industry players is reshaping the competitive landscape. Mergers and acquisitions allow companies to diversify product portfolios and expand geographical reach. By integrating various food technologies and expertise, firms enhance operational efficiencies and meet diverse consumer demands effectively.
Supply chain localization emerges because a response to global uncertainties, allowing companies to minimize risks related to import dependencies. This strategy promotes resilience and supports a stable supply of ingredients necessary for meat analogue production, ultimately strengthening market positioning.
The Global Meat Analogue market is segmented based on Product Type, Primary Protein Source, Meat Analogue Type, and Distribution Channel.
Burgers and Patties segment is valued at USD 2,348.6 million in 2026 and is projected to reach USD 4,679.5 million by 2033, at a CAGR of 10.3% during the forecast period. Growing health consciousness among consumers drives demand for plant-based options. This trend aligns with rising concerns regarding the environmental impact of traditional meat production. Increased availability of innovative and diverse burger and patty formulations supports adoption across various demographics, particularly among younger consumers. Enhanced flavor profiles and textures of meat analogues improve their appeal in foodservice and retail channels.
Investment in research and development facilitates technological maturation, leading to the creation of next-generation products. Manufacturers focus on improving the nutritional profile of burgers and patties, aiming to provide protein-rich alternatives without compromising taste. Regulatory compliance, along with certifications for plant-based products, boosts consumer confidence in meat analogue offerings. Price volatility in traditional meat markets contributes to shifting consumer preferences toward affordable plant-based alternatives, further strengthening the position of the segment within the Meat Analogue market.
Strategic opportunity windows arise because brands explore innovative marketing strategies to educate consumers about the benefits of burgers and patties. Supply chain resilience and raw material sourcing practices become critical in meeting the increasing demand for plant-based products. The segment's expansion aligns with broader consumption shifts toward sustainable and ethical food choices, reinforcing the growth trajectory of the Meat Analogue market.
Mince and Ground Meat Analogues represent an expanding segment within the Meat Analogue market, projected to reach USD 2,759.7 million by 2033, at a CAGR of 11.5% during the forecast period. Increased consumer interest in plant-based diets significantly drives this growth, influenced by health considerations, environmental concerns, and ethical factors surrounding traditional meat consumption. The evolving landscape of dietary preferences fuels demand for innovative meat alternatives that mimic the taste and texture of conventional meats.
Technological advancements play a crucial role in enhancing product quality and variety. Manufacturers invest in research and development to improve the taste, texture, and nutritional profiles of these analogues, aligning them more closely with consumer expectations. The introduction of new formulations and flavors contributes to segment expansion, attracting a broader audience.
Shifts in consumer behavior towards flexitarian and vegan diets further support the adoption of Mince and Ground Meat Analogues. Retailers increasingly feature these products prominently, making them more accessible to consumers. Strategic partnerships between manufacturers and retailers enhance distribution channels, ensuring availability in supermarkets, specialty stores, and online platforms.
Regulatory compliance standards regarding labeling and ingredient transparency influence market dynamics. Adhering to these regulations builds consumer trust, prompting brands to invest in certifications that highlight product quality and safety. This focus on compliance supports market growth and enhances brand reputation.
While the Meat Analogue market evolves, challenges including pricing volatility and raw material sourcing emerge. Fluctuations in ingredient costs impact profit margins, necessitating strategic sourcing and efficient supply chain management. Manufacturers that navigate these challenges effectively position themselves for sustained growth in the competitive landscape.
Growth in the Sausages and Hot Dogs segment aligns with shifting consumer preferences towards plant-based alternatives. These shifts arise from increased awareness of health benefits and sustainability concerns associated with traditional meat products. The market experiences heightened demand driven by a growing population seeking convenient, protein-rich food options that mimic the taste and texture of animal-based products.
Technological advancements play a crucial role in segment expansion, allowing manufacturers to develop innovative products with improved flavor profiles and textures. Continuous product evolution in the Meat Analogue market creates a competitive landscape, attracting both established and emerging players seeking to capture market share. Consumer interest in new flavor varieties and cooking applications supports this dynamic, driving further development.
By 2033, the segment is projected to reach USD 2,217.9 million, reflecting a strong trajectory in revenue growth. This forecast indicates robust investment and commitment from companies aiming to enhance their offerings and meet escalating consumer expectations. The increasing prevalence of vegetarian and vegan diets contributes to significant consumption shifts, further reinforcing the segment's growth potential.
Regulatory compliance standards remain a consideration for producers, influencing product formulation and marketing strategies. Adherence to labeling requirements and health certifications enhances credibility and consumer trust. Cost structures and pricing volatility represent ongoing challenges; however, strategic sourcing of raw materials and efficient production methods contribute positively to profitability.
While the Meat Analogue market continues to evolve, opportunities for strategic partnerships and innovative collaborations emerge. Investments in research and development support next-generation upgrades, resulting in products that appeal to health-conscious consumers. The segment's alignment with broader dietary trends and sustainability objectives positions it well to capitalize on market opportunities.
Nuggets and Tenders exhibit strong growth potential within the Meat Analogue market. This segment is projected to grow at a CAGR of 11.4% during the forecast period. Increased health consciousness among consumers drives demand for plant-based options, positioning nuggets and tenders because favorable alternatives to traditional meat products. The rising trend of flexitarian diets further supports market expansion, with consumers seeking to reduce meat consumption while maintaining familiar flavors and textures.
Technological advancements in food processing enhance the quality and appeal of meat analogue nuggets and tenders, attracting a broader consumer base. Innovations in flavor profiles and textures continue to evolve, addressing the expectations of consumers seeking authentic taste experiences. The expansion of distribution channels, particularly online retail, facilitates accessibility, allowing consumers to purchase these products conveniently.
Strong branding and marketing efforts by key players in the market contribute to heightened awareness and acceptance of nuggets and tenders. The introduction of various product lines catering to different dietary preferences, including gluten-free or high-protein options, further enhances market appeal. Regulatory compliance and certifications related to health and safety standards play crucial roles in building consumer trust.
Cost structures reflect the competitive landscape of the meat analogue industry, with pricing strategies adapting to market dynamics. The challenge of raw material sourcing impacts overall production costs, necessitating strategic partnerships to ensure supply chain resilience. Potential substitution risks from alternative protein sources are addressed through continuous product innovation.
The Nuggets and Tenders segment within the Meat Analogue market reflects a combination of consumer trends, technological advancements, and strategic positioning by industry players, creating a robust outlook for growth in the coming years.
Consumer preferences favor convenience and versatility, driving demand for Chunks, Strips and Pieces in the Meat Analogue market. This sub-segment aligns with the increasing popularity of ready-to-eat and easy-to-prepare meals, appealing to busy lifestyles. Alongside these trends, the growing awareness of health and sustainability among consumers enhances interest in plant-based alternatives, underpinning the segment's expansion.
Technological advancements in food processing and ingredient formulation contribute significantly to the evolution of this sub-segment. Innovations in texturization techniques allow manufacturers to create products that closely mimic the taste and texture of traditional meat, supporting broader acceptance among consumers. The evolving landscape encourages investment in research and development, resulting in next-generation upgrades that cater to varying dietary preferences.
Downstream applications include various culinary uses in home cooking and foodservice, highlighting the adaptability of these products. The integration of Chunks, Strips and Pieces into diverse cuisines reflects an increasing consumer inclination towards incorporating plant-based options into everyday meals. This trend enhances the market's appeal across multiple demographics, including flexitarians and health-conscious consumers.
Regulatory compliance and certification play crucial roles in ensuring product safety and quality, further influencing consumer trust in the Meat Analogue market. Adherence to standards enhances market credibility and facilitates entry into new distribution channels. Maintaining competitive pricing strategies amid volatile raw material costs remains essential for manufacturers aiming to sustain margins while expanding their market presence.
Strategic opportunity windows emerge due to rising consumer interest in plant-based diets. By identifying white-space analysis areas, manufacturers capitalize on unmet demands, enhancing competitive positioning. The growing focus on sustainability and ethical food choices provides fertile ground for innovation, enabling players within this segment to expand product offerings and cater to evolving consumer needs.
Consumer preferences increasingly shift towards meat alternatives, driving demand for Steaks, Fillets and Whole-Cut Analogues. Factors influencing adoption include health consciousness, environmental concerns, and ethical considerations associated with traditional meat consumption. This uptick in demand presents opportunities for innovation in product offerings, focusing on texture and flavor profiles closely resembling conventional meat.
Technological advancements in food processing techniques contribute to the maturation of this sub-segment. Companies invest in research and development to enhance the sensory experience of meat analogue products, aiming to capture a broader consumer base. The evolution of product formulations supports the emergence of next-generation alternatives, appealing to both flexitarian and fully plant-based diets.
Regulatory compliance standards and certifications establish credibility within the Meat Analogue market. Compliance with food safety regulations ensures that products meet consumer expectations while building trust. Strategic partnerships along the supply chain strengthen resilience, allowing companies to navigate potential disruptions in raw material sourcing and logistics.
Pricing volatility and margin pressures present challenges that influence market dynamics. Sourcing high-quality ingredients at competitive prices remains crucial for maintaining profitability. The presence of disruptive alternatives necessitates continuous innovation to remain competitive. Strategic opportunity windows arise through targeted marketing and product diversification.
Growing interest in plant-based diets drives the demand for meat alternatives, particularly in the Meatballs sub-segment. Shifts toward healthier eating habits and increased awareness of environmental sustainability influence consumer choices. The market benefits from these trends, driven by consumers searching for convenient and versatile meal options.
Technological advancements contribute to the development of innovative meatball formulations, enhancing taste and texture while maintaining nutritional value. The introduction of next-generation products has expanded the appeal of meatballs, attracting a broader consumer base. This evolution encourages manufacturers to invest in research and development to create enhanced offerings.
Regulatory compliance shapes product standards within the market. Adherence to food safety and quality regulations drives producers to maintain high manufacturing standards, building consumer trust. Certifications related to health and sustainability further enhance the product's marketability, appealing to discerning consumers.
Cost structures influence pricing strategies within the market, affecting profit margins for producers. Fluctuations in raw material prices create margin pressures, compelling manufacturers to optimize sourcing and production processes. Strategic opportunities arise because brands explore cost-effective alternatives, ensuring competitiveness in a crowded marketplace.
Supply chain resilience remains critical for the production of meat analogue products, including meatballs. Challenges in logistics and distribution require firms to develop robust networks that ensure product availability. Addressing these vulnerabilities enhances the overall stability of the market, promoting sustained growth.
While consumer preferences continue to evolve, the meat analogue market anticipates a shift toward more diverse offerings. The demand for meatballs, alongside other plant-based options, reflects a transformation in eating habits, highlighting a broader acceptance of plant-based proteins in everyday diets.
Consumer interest in Deli Slices and Cold Cuts reflects a broader trend toward plant-based protein alternatives. This segment attracts health-conscious consumers seeking nutritious options and aligns with growing awareness of environmental sustainability. Adoption of these products benefits from innovative formulations that closely mimic traditional deli meats in texture and flavor, enhancing consumer acceptance.
Technological advancements enhance the quality and appeal of meat analogue products. Manufacturers invest in next-generation upgrades to improve taste, texture, and nutritional profiles, addressing diverse consumer preferences. Cost structures remain a crucial factor, with producers seeking efficiencies in sourcing raw materials and optimizing production processes to maintain competitive pricing, which is essential for broader market penetration.
Regulatory compliance significantly shapes the market landscape. Stringent food safety standards and labeling regulations influence product development and marketing strategies. The meat analogue market benefits from evolving consumer sentiments toward transparency in sourcing and ingredient disclosure, emphasizing the importance of certifications and quality assurance, which are critical for building consumer trust.
Downstream applications in foodservice and retail channels provide significant growth opportunities. Increased distribution through supermarkets and online platforms enhances product accessibility, catering to diverse consumer demographics. This expansion aligns with the market's trajectory toward greater acceptance of plant-based options in everyday diets, supporting overall market growth and reinforcing the shift in consumer eating habits.
Consumer interest in meat alternatives drives demand for products within the Others (Bacon Analogues, Pepperoni, Kebabs) segment. This shift aligns with broader trends favoring plant-based diets and healthier eating habits, influencing various demographics. The Meat Analogue market benefits from increased adoption among health-conscious consumers and flexitarians seeking versatile meal options.
Technological advancements in the production of meat analogues enhance product quality, texture, and flavors, contributing to the segment's appeal. Innovations enable manufacturers to create taste profiles that closely resemble traditional meat products, thereby attracting a wider audience. Regulatory compliance and certifications play significant roles in ensuring product safety and quality, building consumer trust and enhancing market penetration.
Raw material sourcing remains a crucial aspect, with suppliers focusing on sustainable and ethically sourced ingredients. Supply chain resilience proves essential, especially in navigating fluctuations in the availability of key components. Competition within the market intensifies owing to new entrants exploring opportunities for differentiation through unique flavor offerings and innovative marketing strategies, driving the overall growth of the sector.
Soy protein is essential in the Meat Analogue market, reflecting a growing consumer preference for plant-based alternatives. Valued at USD 3,749.8 million in 2026, this segment is projected to reach USD 7,731.7 million by 2033, at a CAGR of 10.9% during the forecast period. Increasing health consciousness and environmental concerns drive the demand for soy protein, leading to its adoption across various food products.
Technological advancements enhance the quality and variety of soy protein products, making them more appealing to consumers. Innovations in production techniques contribute to improved texture and flavor, addressing previous limitations associated with meat analogues. The market benefits from evolving product offerings that cater to diverse consumer preferences and dietary needs.
Regulatory compliance shapes the market landscape. Adherence to food safety standards and labeling regulations ensures consumer trust in meat analogue products. The focus on clean labels and transparent sourcing influences consumer choices, encouraging manufacturers to emphasize quality and sustainability in their offerings.
Next-generation upgrades, including fortified soy protein products, enable manufacturers to target health-conscious consumers seeking nutritional enhancements. While the market continues to evolve, capital investment in research and development supports innovation, allowing companies to remain competitive in the expanding meat analogue landscape.
Wheat Protein and Seitan exhibit significant promise within the Meat Analogue market, driven by increasing consumer awareness surrounding health benefits associated with plant-based proteins. The rising preference for sustainable and ethical food sources contributes to the segment's growth, reflecting a consumer shift towards alternatives that reduce environmental impact.
The Wheat Protein and Seitan segment is projected to reach USD 3,134.7 million by 2033, with a CAGR of 10.9% during the forecast period. The expansion of this segment correlates with technological advancements in processing, improving product taste and texture, which enhances market acceptance. Innovations in formulations and production methods attract a diverse range of consumers, including health-conscious individuals and flexitarians seeking to reduce meat consumption.
Increased distribution through various retail channels, including supermarkets, specialty stores, and online platforms, supports accessibility and convenience for consumers. This segment's growth reflects broader trends within the market, where plant-based proteins increasingly penetrate mainstream food offerings. Educational campaigns emphasizing the nutritional and environmental benefits of wheat protein reinforce consumer adoption.
Significant demand for plant-based protein drives interest in the Pea Protein segment within the Meat Analogue market. Increasing health consciousness and dietary shifts toward vegetarian and vegan lifestyles contribute to this growth trajectory. The ability of pea protein to deliver essential amino acids while being allergen-friendly enhances its appeal among consumers seeking nutritious alternatives.
Forecasts indicate that the Pea Protein segment is projected to reach USD 3,550.9 million by 2033. This growth reflects the rising popularity of pea-based products across various applications, including burgers, sausages, and meat analogues. A notable shift toward clean label products and transparency in ingredient sourcing supports the segment's expansion. Manufacturers invest in research and development to innovate and enhance product formulations, positively impacting market dynamics.
Increased availability of pea protein products through diverse distribution channels, including supermarkets, online retail, and specialty stores, strengthens market penetration. The segment demonstrates resilience against competition from other protein sources, including soy and wheat protein, due to its unique nutritional profile and sustainability benefits. Continued consumer education regarding the health benefits of pea protein will likely create further growth opportunities within the Meat Analogue market.
Strong growth in the Mycoprotein segment occurs due to rising consumer interest in sustainable and nutritious protein sources. This segment is projected to grow at a CAGR of 12.7% during the forecast period. Health-conscious consumers increasingly opt for plant-based protein alternatives, driving demand for mycoprotein products in various applications, including meat analogues and ready-to-eat meals. Technological advancements in food processing enhance the quality and taste of mycoprotein, further boosting its appeal in the Meat Analogue market.
Regulatory support for plant-based products focuses on health benefits and environmental sustainability, creating favorable conditions for mycoprotein adoption. While consumers become more aware of environmental issues associated with traditional meat production, mycoprotein offers a compelling alternative. This shift aligns with the ongoing trend toward cleaner labels and transparency in food sourcing, promoting a broader range of product offerings in the market.
Investment in research and development drives the evolution of mycoprotein products. Brands actively innovate to improve texture and flavor profiles, catering to diverse consumer preferences. Such strategic initiatives lead to the introduction of next-generation mycoprotein products that capture consumer interest and expand market penetration.
Interest in Mycelium Protein within the Meat Analogue market reflects a growing trend towards innovative protein sources. This segment gains traction due to its unique texture and nutritional profile, appealing to consumers seeking alternatives to traditional meat products. Adoption of Mycelium Protein benefits from technological advancements in fermentation processes, enhancing production efficiency and product quality.
Expansion catalysts for this segment include increasing consumer awareness of sustainability and health, driving demand for alternative proteins. Companies are investing in research and development to improve the sensory attributes of Mycelium-based products, facilitating wider acceptance in mainstream markets. Regulatory compliance with food safety standards supports the credibility of Mycelium Protein, strengthening its position within the broader Meat Analogue market.
Shifts in consumption patterns reflect a preference for clean label products, positioning Mycelium Protein favorably among health-conscious consumers. Strategic opportunity windows exist for manufacturers to create diverse product offerings, tapping into the growing demand for convenience and plant-based options. The ongoing evolution of Mycelium Protein highlights its potential in addressing dietary needs while contributing to environmental sustainability.
Growing interest in alternative protein sources significantly influences the adoption of Other Plant Proteins (Oat, Fava Bean) within the Meat Analogue market. Increasing health consciousness among consumers drives demand for these protein sources, known for their nutritional benefits and sustainability. The rise of plant-based diets further accelerates interest, driven by consumers seeking diverse options that align with their dietary preferences.
Innovations in product development enhance the appeal of Other Plant Proteins, leading to a broader range of applications in various food products. Manufacturers actively explore next-generation upgrades, focusing on improving texture and flavor profiles to better mimic traditional meat products. This evolution in product offerings supports expansion and addresses consumer expectations for meat alternatives.
Regulatory compliance and certifications play a crucial role in shaping the market dynamics for Other Plant Proteins. Companies increasingly focus on transparency in sourcing and production practices to build consumer trust. This emphasis on compliance facilitates access to new markets, allowing brands to capitalize on growing consumer demand for ethical and sustainable food options.
Pricing volatility and margin pressures impact the operational landscape for producers of Other Plant Proteins. Fluctuations in raw material costs affect profit margins, necessitating strategic sourcing and cost management to ensure competitive pricing. Companies that effectively navigate these challenges position themselves favorably within the market.
Supply chain resilience remains a critical consideration for manufacturers of plant-based protein products. Building strong relationships with suppliers helps mitigate risks associated with sourcing raw materials. This approach enhances overall stability in the supply chain, ensuring consistent product availability because demand continues to grow.
Identifying strategic opportunity windows within the Meat Analogue market allows companies to innovate and capture emerging consumer trends. By leveraging insights into consumption shifts and evolving preferences, manufacturers tailor their product lines to meet the specific needs of target demographics. This proactive strategy supports long-term growth in the market.
Growing consumer interest in plant-based diets drives expansion in the Beef Analogues segment. Valued at USD 3,455.2 million in 2026, this sub-segment is projected to reach USD 7,096.2 million by 2033, reflecting a CAGR of 10.8% during the forecast period. Increased awareness of health and environmental issues associated with traditional meat consumption encourages consumers to seek alternatives that align with their values. This trend drives food manufacturers to innovate and diversify their product offerings, integrating beef analogue options into their portfolios.
Technological maturation enhances the sensory properties and textures of beef analogues. Advancements in food technology enable manufacturers to create products that closely mimic the taste and mouthfeel of traditional beef, addressing concerns of texture and flavor that consumers often associate with plant-based alternatives. While the market evolves, continuous product evolution occurs, with companies launching next-generation beef analogue products that align with shifting consumer preferences.
Downstream applications of beef analogues extend across various foodservice channels and retail environments. The growing adoption of these products in restaurants and fast-food chains demonstrates a shift in consumer dining habits, because establishments increasingly offer meat analogue options to cater to a wider range of dietary preferences. This expansion enhances market penetration and reinforces the Beef Analogues segment's contribution to the broader Meat Analogue market.
Regulatory compliance standards contribute to shaping the trajectory of the Beef Analogues segment. While food safety regulations evolve, manufacturers navigate complexities in labeling, formulations, and production processes. Adherence to these standards builds consumer trust and confidence, driving market growth. Cost structures and pricing volatility in raw materials influence profitability; however, strategic sourcing and supply chain resilience are critical in mitigating these challenges.
Strategic opportunity windows exist for brands willing to invest in marketing and consumer education regarding the benefits of beef analogues. Enhanced awareness leads to increased adoption among skeptical consumers, further strengthening the Beef Analogues segment's position within the market. By addressing substitution risks and competitive threats from traditional meat products, companies capitalize on the growing demand for sustainable and health-conscious protein sources.
Strong demand for Chicken Analogues arises from a growing focus on health, environmental sustainability, and ethical considerations surrounding traditional meat consumption. This shift in dietary habits encourages consumers to seek out plant-based protein options, leading to increased sales of chicken alternatives. The Meat Analogue market experiences significant growth driven by manufacturers introducing innovative products that closely mimic the taste and texture of traditional chicken products.
Technological advancements play a crucial role in the development of Chicken Analogues, enhancing flavor profiles and improving the overall eating experience. Brands continuously invest in research and development to create next-generation products that cater to evolving consumer preferences and dietary restrictions. Chicken Analogues are projected to reach USD 5,804.4 million by 2033, at a CAGR of 13% during the forecast period. This segment demonstrates strong growth potential, supported by these advancements.
Shifting consumption patterns influence the Chicken Analogues segment. Consumers increasingly prioritize convenience and variety. This trend is evident in the growing popularity of ready-to-eat meals and snacks featuring chicken alternatives, appealing to busy lifestyles. The Meat Analogue market benefits from this demand for accessible options, resulting in expanded distribution channels including supermarkets, convenience stores, and online platforms.
Regulatory compliance and certification standards surrounding food products significantly impact the Chicken Analogues segment. Awareness of food safety and quality assurance drives manufacturers to adhere to established guidelines, building consumer trust and encouraging market growth. While the sector evolves, companies that successfully navigate these regulations capitalize on strategic opportunities, enhancing their competitive positioning within the market.
Growing awareness of health and sustainability encourages consumers to seek meat alternatives, influencing the Pork Analogues segment within the Meat Analogue market. This segment is expected to reach USD 3,509.6 million by 2033, highlighting its importance in meeting evolving dietary preferences. The demand for pork analogues stems from an increasing focus on plant-based diets and the desire for lower fat and cholesterol options compared to traditional pork products.
Technological advancements in food processing support the development of pork analogues, enhancing their texture and flavor to closely resemble traditional meat. Continuous innovation in formulation and production methods contributes to improved product offerings, appealing to a broader consumer base. Collaborations among key players in the market create competitive advantages, driving further exploration within this sub-segment.
Consumer acceptance of pork analogues is expected to increase due to the growing variety of products available in retail and foodservice channels. Awareness of environmental impact and animal welfare concerns influences purchasing decisions, encouraging shifts towards meat alternatives. While regulations evolve and certifications for plant-based products become more prevalent, the market experiences a more structured approach to product development and marketing, enhancing credibility and consumer trust.
Pricing dynamics play a crucial role in shaping the market. Fluctuations in raw material costs affect the pricing of pork analogues, impacting consumer accessibility and willingness to purchase. Strategic investments in supply chain resilience and raw material sourcing improve stability and ensure a consistent product flow, which mitigates potential risks associated with price volatility.
The Pork Analogues segment represents a significant opportunity within the broader Meat Analogue market. A focus on health trends, technological advancements, and evolving consumer preferences positions this segment for strong growth, making it a key player in the plant-based protein landscape. Companies investing in innovation and strategic partnerships will likely see enhanced market presence and profitability driven by rising demand.
Rising consumer preference for sustainable seafood alternatives contributes significantly to the growth of seafood analogues within the Meat Analogue market. This segment is projected to grow at a CAGR of 14.3% during the forecast period. Increasing awareness of the environmental impact of overfishing drives demand for products that mimic traditional seafood flavors and textures. Innovations in food technology enhance the ability to create realistic seafood alternatives, attracting health-conscious consumers seeking lower-calorie, plant-based options.
Changing dietary habits and growing interest in vegetarian and vegan lifestyles increase the popularity of seafood analogues. Manufacturers invest in research and development to improve the nutritional profile of these products while ensuring broad audience appeal. The market for seafood analogues benefits from a diverse range of culinary applications, providing opportunities for use in appetizers, main dishes, and snacks.
Regulatory compliance regarding food safety and labeling standards shapes product offerings in this segment. Certifications that highlight the sustainability of raw materials and production processes enhance market positioning and attract environmentally conscious consumers. Continued investment in marketing and consumer education will further enhance the growth trajectory of seafood analogues, ensuring they remain a viable and attractive choice within the Meat Analogue market.
Growing awareness of diverse protein sources influences interest in meat analogues derived from lamb, mutton, turkey, and mixed-meat alternatives. Consumers increasingly seek products that mimic traditional meat flavors and textures while promoting sustainability and health benefits. This segment benefits from a shift toward reducing red meat consumption, with many individuals exploring alternatives that align with dietary preferences and lifestyle choices.
Product evolution in this sub-segment centers around improving taste, texture, and nutritional profiles to meet consumer expectations. Companies invest in research and development to create offerings that appeal to both meat-eaters and vegetarians, resulting in innovative solutions that capture the interest of a broad audience. The market observes a growing adoption of these alternatives, driven by changing consumption patterns and the desire for sustainable options.
Regulatory compliance standards play a crucial role in shaping product formulations within the meat analogue market. Manufacturers navigate these regulations while ensuring that their products meet consumer demands. Certifications related to health and sustainability enhance product appeal, building consumer trust and driving sales. Effective communication of these benefits remains essential in maximizing market potential for lamb, mutton, turkey, and mixed-meat analogue products.
The competitive landscape in this segment encourages companies to identify strategic opportunity windows. A focus on capital investment in technology and innovation positions players to respond to evolving consumer preferences effectively. This environment supports the continued growth of the meat analogue market, with the lamb, mutton, turkey, and mixed-meat alternatives segment positioned for further expansion amid rising demand.
Increasing consumer demand for meat alternatives influences growth in the Supermarkets and Hypermarkets distribution channel. The popularity of plant-based diets contributes significantly to this trend, driven by consumers prioritizing healthier and more sustainable food options. Supermarkets and hypermarkets provide convenient access to a wide range of meat analogue products, which facilitates consumer exploration and adoption of these alternatives. This channel plays a critical role in the market, enhancing visibility and availability of products. Retailers often present innovative meat analogue offerings, attracting health-conscious shoppers and driving impulse purchases.
The Supermarkets and Hypermarkets segment is valued at USD 3,418.7 million in 2026 and is projected to reach USD 6,921.8 million by 2033, at a CAGR of 10.6% during the forecast period. Competitive pricing strategies within this channel further support market growth, encouraging consumers to try various meat analogue products. Enhanced promotional activities and in-store tastings often lead to increased product trials, fueling demand within this segment. The growing inclination towards online shopping complements the traditional supermarket experience, enabling consumers to order meat analogue products conveniently.
Strategic partnerships between retailers and meat analogue manufacturers strengthen supply chain dynamics, ensuring consistent product availability. Retailers prioritize sourcing high-quality meat analogue products to meet evolving consumer preferences. Continuous product innovation, including new flavors and textures, creates excitement within the market. By adapting to consumer feedback and trends, brands position themselves competitively within supermarkets and hypermarkets, ensuring alignment with the market's growing demands.
Growth in the Convenience Stores segment reflects evolving consumer shopping habits, with increased demand for accessible and convenient meat alternatives. The segment benefits from the rising trend of on-the-go meals and snacks, which positions meat analogue products because appealing choices for busy consumers. The trend influences various demographics, particularly younger generations and health-conscious individuals, driving higher foot traffic in these retail outlets.
Convenience Stores are estimated to reach USD 1,829.8 million by 2033, at a CAGR of 10.8% during the forecast period. The segment's expansion correlates with consumer preferences for quick and nutritious meal options, prompting retailers to diversify their product offerings. The introduction of innovative meat analogue options tailored to meet dietary preferences enhances the attractiveness of these stores, supporting growth within the Meat Analogue market.
Technological advancements in food production contribute to the evolution of product offerings in Convenience Stores. The development of new flavors and textures, alongside improvements in nutritional profiles, enhances the consumer experience. Retailers adopting next-generation upgrades better cater to the increasing demand for high-quality, plant-based alternatives, ensuring competitive positioning within the market.
The market faces pressure from pricing volatility and margin fluctuations, impacting the profitability of Convenience Stores. Retailers strategically adjust pricing to remain competitive, balancing cost structures while ensuring product availability. This dynamic environment necessitates effective supply chain management to mitigate risks associated with raw material sourcing and logistics vulnerabilities, maintaining resilience in a competitive environment.
Consumer preferences increasingly favor plant-based options, driving growth within the Specialty and Natural Food Stores segment. This segment reflects a shift toward healthier lifestyles, with shoppers prioritizing nutritious and sustainable food choices. Rising awareness of the environmental impact of traditional meat production influences consumers to actively seek alternatives, impacting demand across the Meat Analogue market.
Specialty and Natural Food Stores typically offer a wide range of meat analogue products, accommodating diverse dietary needs, including vegan and vegetarian options. This variety enhances customer engagement and loyalty, encouraging repeat purchases. The segment is expected to reach USD 2,283.5 million by 2033, reflecting significant growth potential driven by evolving consumer dynamics.
Technological advancements in food production continue to enhance the quality and flavor of meat analogue products, appealing to an expanding consumer base. Collaborations between manufacturers and retailers strengthen distribution channels, ensuring greater accessibility to consumers. Innovation drives product evolution, with fresh offerings consistently attracting attention in the market.
Regulatory compliance and certifications play vital roles in shaping consumer confidence. Meeting these standards assures shoppers of product quality and safety, further promoting sales in Specialty and Natural Food Stores. This segment's growth trajectory aligns with the broader Meat Analogue market trend, characterized by a commitment to health and sustainability.
Growing popularity of online shopping significantly impacts the Meat Analogue market. Consumers increasingly prefer the convenience of purchasing meat alternatives through digital platforms, leading to a surge in the Online Retail segment. Online retailing offers broader access to various products, catering to the diverse preferences of consumers, including unique and innovative meat analogue options. In addition, the rise of health-conscious consumers correlates with a preference for plant-based diets, driving the demand for meat substitutes available online.
Online Retail segment is projected to grow at a CAGR of 15.9% during the forecast period. This growth reflects a robust shift in consumer behavior towards e-commerce, creating new opportunities for suppliers and retailers. Enhanced marketing strategies and targeted advertising through social media further strengthen online sales, reaching potential customers who prioritize health and sustainability.
Competition among retailers intensifies because companies strive to establish a strong online presence. Offering exclusive products and promotions encourages brand loyalty and attracts a wider customer base. The dynamic nature of consumer preferences, coupled with technological advancements in e-commerce platforms, positions the Online Retail segment because a key driver of growth within the Meat Analogue market.
Growing interest in the foodservice sector significantly enhances the Meat Analogue market. This segment thrives on rising consumer demand for plant-based menu options, driven by increased health consciousness and environmental awareness. Operators in restaurants and catering services actively seek to diversify their offerings, capitalizing on trends toward healthier diets and sustainable practices.
Adaptation in foodservice establishments to incorporate meat analogue products aligns with changing culinary preferences. Innovation in product development creates an expanding array of offerings, appealing to consumers seeking variety in their meals. Enhanced flavor profiles and textures in these products contribute to their acceptance in diverse cuisines, creating new opportunities for growth within the market.
Regulatory compliance continues to impact the foodservice segment, necessitating adherence to food safety standards and labeling requirements. Certifications for plant-based products enhance consumer confidence and acceptance, further driving demand. Operators invest in staff training and menu development to effectively incorporate meat analogues, improving their competitive position while navigating the evolving landscape of consumer preferences.
Pricing volatility in raw materials influences cost structures within the foodservice sector. Strategic supplier partnerships and innovative sourcing strategies mitigate risks associated with price fluctuations. This proactive approach enables operators to maintain favorable margins while delivering high-quality meat analogue offerings.
Technological advancements play a crucial role in enhancing product quality and supply chain resilience. Developments in production processes lead to more efficient manufacturing methods, reducing costs and increasing the availability of meat analogues. The focus on sustainability within the market creates a collaborative environment, prompting players to explore disruptive alternatives that further cater to evolving tastes and values of consumers.
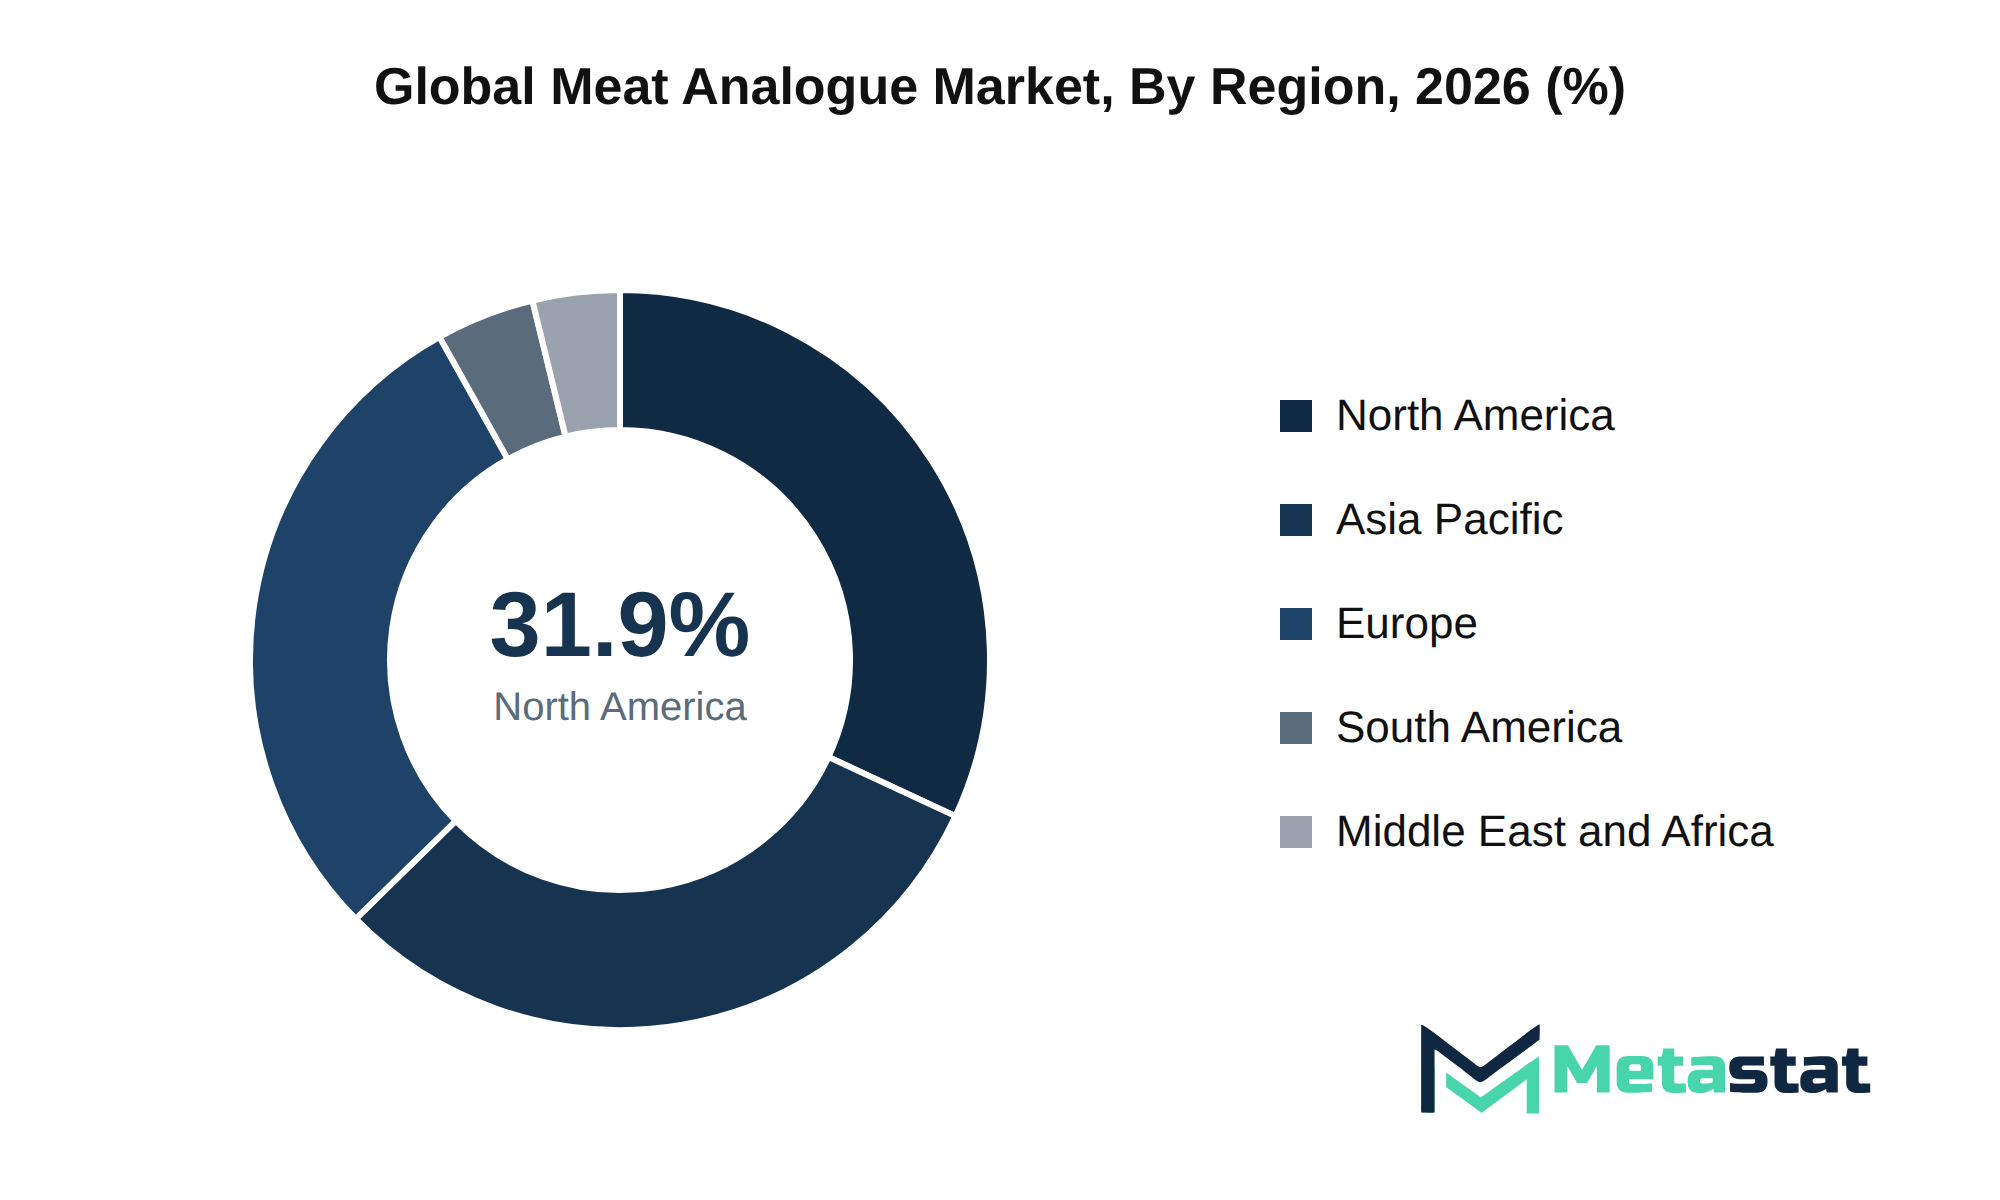
Based on geography, the Global Meat Analogue market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America holds a significant position in the Meat Analogue market, with a projected market size of USD 5,538.2 million by the end of 2033, expanding at a CAGR of 12.1% during the forecast period. The region accounted for 31.9% of the global market share in 2025, highlighting its importance in the overall growth trajectory of meat alternatives.
Increasing health consciousness among consumers drives demand for protein-rich alternatives, particularly in the United States, Canada, and Mexico. A shift towards sustainable eating habits increases consumer interest in meat analogue products, leading to enhanced adoption rates. Retail channels, especially supermarkets and hypermarkets, play a crucial role in product accessibility, contributing to the market's expansion.
Emerging trends, including localized manufacturing and supply chain regionalization, support the development of the market. Businesses prioritize nearshoring initiatives, strengthening domestic production capabilities and allowing for better compliance with local regulations and consumer preferences. The competitive landscape features a mix of established players and new entrants, encouraging innovation and product diversification.
Overall, the Meat Analogue market in North America is characterized by dynamic growth factors driven by evolving consumer behaviors, strategic local manufacturing, and a robust regulatory framework that promotes the development of sustainable food options.
Europe represents a 29.2% share of the global Meat Analogue market in 2025. Demand for meat alternatives in this region experiences strong support from evolving consumer preferences towards healthier and more sustainable food options. The market benefits from a well-established retail infrastructure, with supermarkets and hypermarkets serving because primary distribution channels for meat analogue products.
Germany, France, the UK, Italy, Spain, and Russia emerge because key players in the European market, representing diverse consumer bases and varying levels of product adoption. In particular, the growth of plant-based diets and the increasing popularity of flexitarian lifestyles drive the demand for Meat Analogues. Local manufacturers respond to these trends by introducing innovative products that align with regional tastes and preferences.
The competitive landscape in Europe features both established players and new entrants, contributing to a dynamic environment for product development and marketing strategies. Domestic market participants emphasize sustainability and ethical sourcing in their branding, appealing to conscious consumers. Localized procurement strategies enhance supply chain efficiencies and support regional manufacturing capabilities.
Investment in marketing campaigns and partnerships with local retailers expands the market reach of meat analogue products. The evolving regulatory frameworks across European countries create an environment conducive to innovation while ensuring compliance with health and safety standards. Overall, Europe's Meat Analogue market exhibits strong growth potential, driven by changing consumer behaviors and increasing availability of product offerings.
The Meat Analogue market in Asia-Pacific shows significant potential for expansion, driven by increasing health consciousness and dietary shifts towards plant-based options. Countries including China and India lead the market, propelled by their large populations and rising incomes. Urbanization and changing lifestyles in these regions contribute to a growing demand for convenient and healthy food alternatives.
Infrastructure modernization across Asia-Pacific enhances distribution capabilities, enabling efficient supply chains. Enhanced logistics networks facilitate the availability of meat analogue products even in remote areas, further promoting market penetration. The region's cultural nuances, which emphasize traditional diets, drive innovation in product development and appeal to local preferences.
Emerging market front-runners, particularly in Southeast Asia, demonstrate a growing appetite for innovative meat alternatives. Local manufacturers increasingly focus on sustainable production techniques, using regional agricultural resources. The competitive landscape features a blend of established international brands and local players, each vying for market share through unique positioning and product offerings.
Producers capitalize on the growing trend of localized procurement, which allows for fresh ingredients and increased consumer trust. The Meat Analogue market is expected to benefit from foreign direct investment flows, enhancing production capacities and driving innovation. This influx of investment strengthens the region's position because a key player in the global market.
South America presents a unique landscape for the Meat Analogue market, characterized by a growing consumer base interested in vegetarian and vegan diets. The region, which holds a 4.3% share of the global market in 2025, includes key markets including Brazil and Argentina, where rising health consciousness and environmental concerns influence dietary choices. Cultural shifts towards plant-based options drive demand for meat alternatives, with increasing availability of these products through various distribution channels.
Infrastructure modernization in the region supports market growth, with improvements in logistics and supply chains enhancing access to meat analogue products. Local compliance mandates and regulatory frameworks shape product offerings, necessitating adherence to region-specific standards that impact market entry strategies. Domestic market leaders are establishing a strong presence, focusing on localized manufacturing to meet the demands of consumers seeking familiar flavors and textures in alternative meats.
Emerging brands are gaining traction within the market, appealing to younger demographics that prioritize sustainability and ethical consumption. The evolving competitive landscape encourages collaboration and innovation, with companies investing in research and development to enhance product quality. Strategic entry barriers exist, but foreign direct investment flows into the region contribute to a more diverse array of offerings, positioning South America because a significant player in the global Meat Analogue market.
In the Middle East and Africa, the Meat Analogue market experiences slow growth, influenced by cultural preferences and regional dietary habits. Limited consumer acceptance of meat alternatives presents challenges for market penetration. Increasing health consciousness among consumers gradually encourages exploration of plant-based options, highlighting an emerging trend.
Saudi Arabia and the UAE exhibit a growing interest in health and wellness, influencing consumers to seek healthier dietary choices. The South African market shows a potential shift towards meat analogues driven by urbanization and changing lifestyles. Retail channels, particularly supermarkets and hypermarkets, significantly expand product availability and consumer awareness throughout the region.
Local manufacturers and international players collaborate to establish production facilities that cater to regional tastes, enhancing product localization. This strategy supports the supply chain by reducing dependency on imports. The Meat Analogue market in this region is projected to see gradual growth through strategic partnerships, local sourcing, and targeted marketing efforts.
The regional market is characterized by unique cultural dynamics and evolving consumer preferences, creating opportunities for market players willing to engage with local consumers effectively.
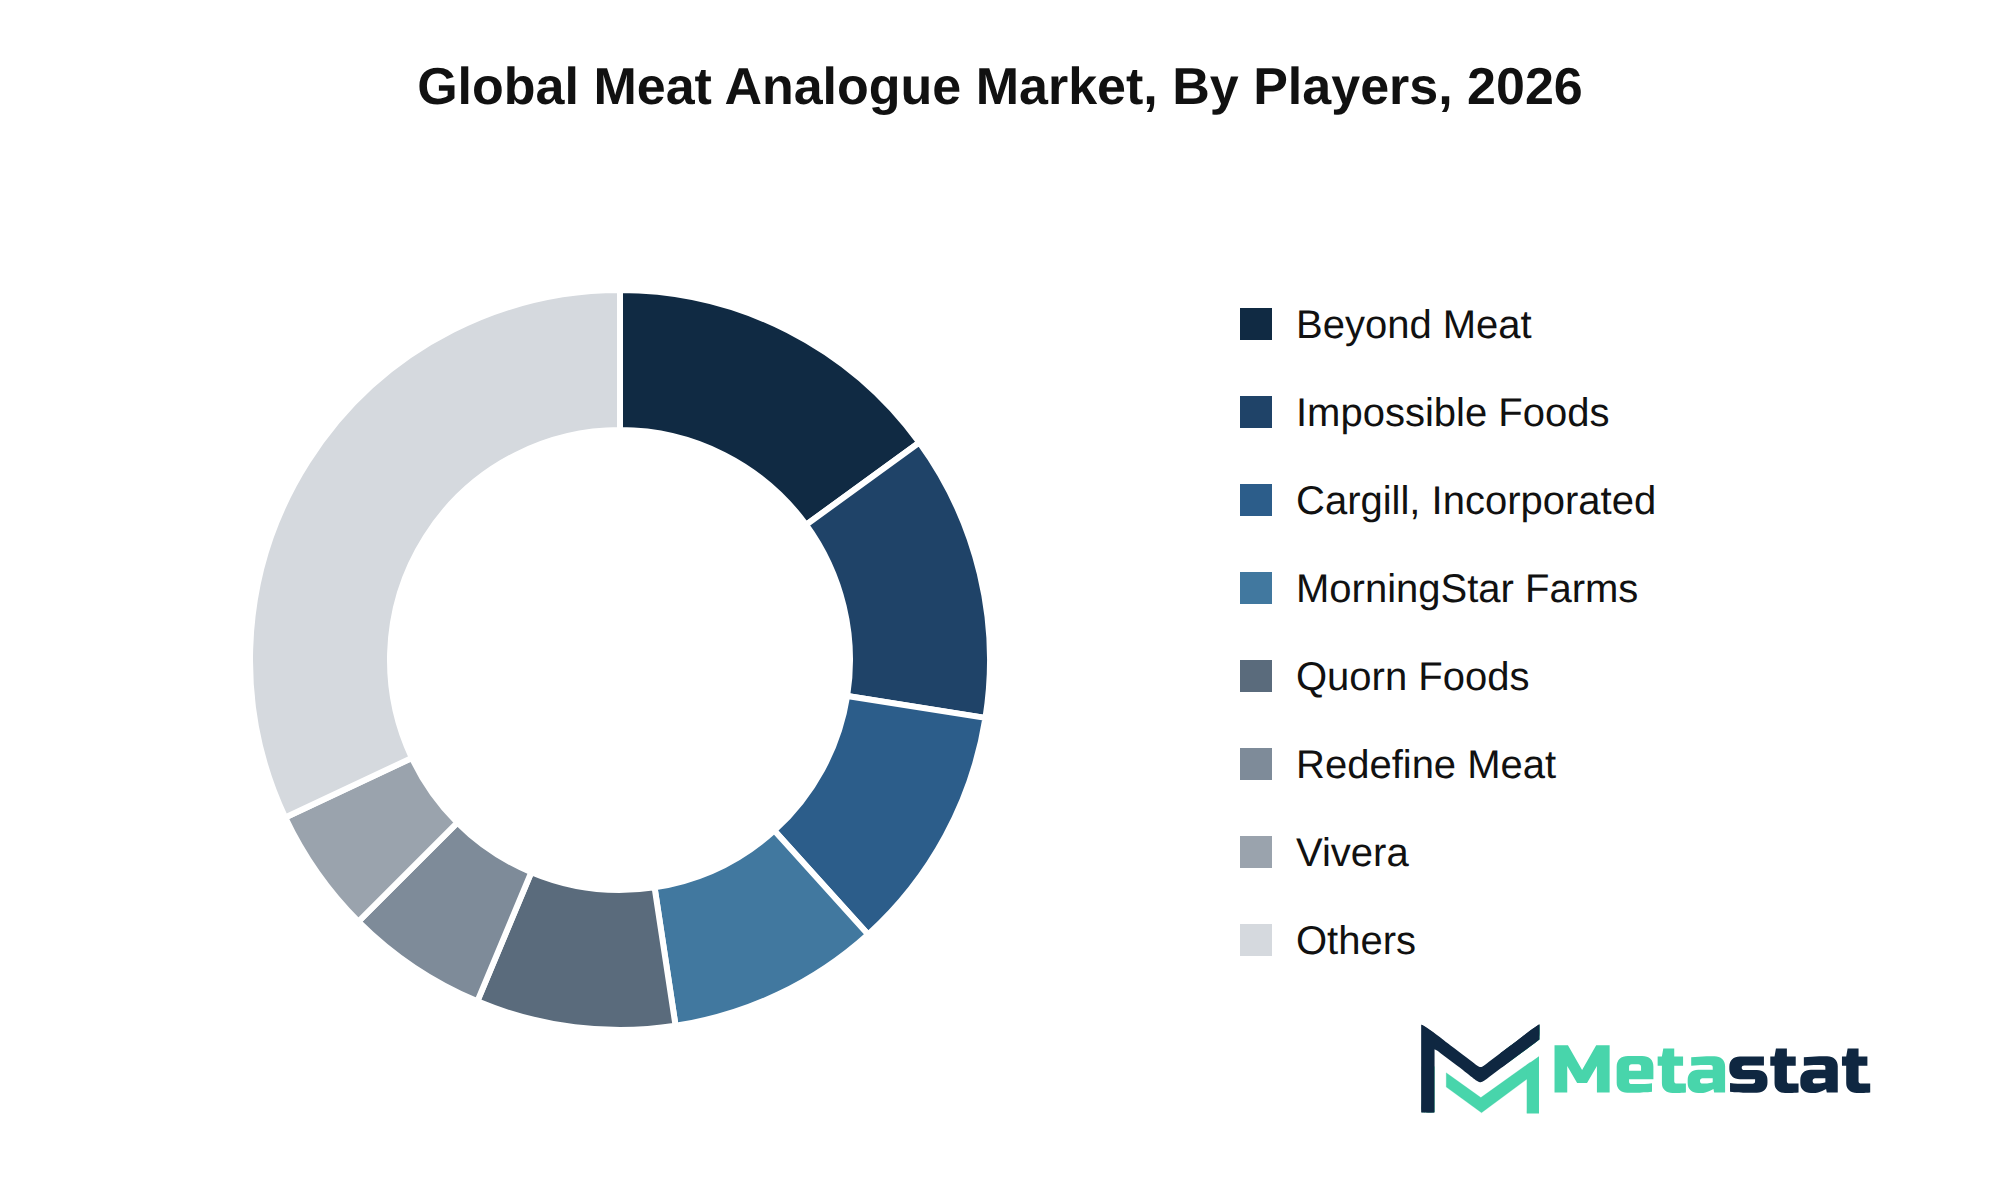
The Meat Analogue market experiences significant activity characterized by strategic consolidation, partnerships, and product differentiation. Companies leverage proprietary technologies and research and development pipelines to establish competitive advantages. Players including Beyond Meat, Inc., Impossible Foods Inc., and Cargill, Incorporated engage in continuous innovation to enhance their product offerings while addressing consumer preferences for plant-based alternatives.
Strategic alliances and cross-industry partnerships play a critical role in shaping market dynamics. Unilever (The Vegetarian Butcher), Redefine Meat Ltd., and Heura Foods exemplify firms that capitalize on collaborative efforts to expand their market reach and enhance brand equity. The landscape features various players, including MorningStar Farms and Quorn Foods, which focus on customer retention strategies and brand loyalty to differentiate themselves within the market.
Barriers to entry and the threat of new entrants influence competitive dynamics. Established players including Vivera and Tofurky maintain supply chain dominance and procurement leverage, which fortifies their market positions. The market is projected to undergo further transformations driven by evolving consumer demands and the continued emphasis on sustainable food options.
Future competitive outlooks indicate that companies will intensify efforts in product innovation and market expansion strategies. Firms like Daring Foods and Moving Mountains Foods focus on capturing emerging trends and consumer preferences, positioning themselves favorably within the Meat Analogue market.
Market size is forecast to rise from USD 7,515.9 million in 2025 to over USD 18,748.1 million by 2033. The base case is USD 7,515.9 million in 2025 to USD 18,748.1 million by 2033 at a 12.1% CAGR. The bull case anticipates accelerated growth driven by increasing consumer interest in plant-based diets, innovative product launches, and enhanced distribution channels. The bear case reflects potential challenges including economic downturns, shifting regulatory frameworks, and supply chain disruptions that could impede market growth.
The macroeconomic environment significantly influences the Meat Analogue market. The ongoing evolution of consumer preferences towards healthier dietary options plays a critical role in driving demand. Continued investment in research and development, alongside advancements in technology, enhances product offerings and consumer engagement. These factors contribute to structural shifts in consumption patterns, focusing on sustainability and ethical sourcing.
Regulatory developments will impact market dynamics, with upcoming compliance milestones necessitating adaptations from producers. Companies will align product lines with evolving health and safety regulations, which could affect operational costs and market entry strategies. Geopolitical realignments and trade corridor shifts introduce complexities to the global supply chain, influencing pricing and availability of key ingredients.
Strategic capital allocation and infrastructure commitments represent vital factors for growth. Companies focusing on high-growth pockets and unmet consumer needs will likely capture significant market shares. This focus drives innovation timelines, ensuring products remain relevant in an increasingly competitive environment. The emphasis on executive-level strategic imperatives guides firms in navigating future challenges while maximizing opportunities within the Meat Analogue market.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Meat Analogue market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 12.1% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Product Type, Primary Protein Source, Meat Analogue Type, Distribution Channel, and Region |
By Region | North America (By Product Type, Primary Protein Source, Meat Analogue Type, Distribution Channel, and Country)
|
Europe (By Product Type, Primary Protein Source, Meat Analogue Type, Distribution Channel, and Country)
| |
Asia Pacific (By Product Type, Primary Protein Source, Meat Analogue Type, Distribution Channel, and Country)
| |
South America (By Product Type, Primary Protein Source, Meat Analogue Type, Distribution Channel, and Country)
| |
Middle East and Africa (By Product Type, Primary Protein Source, Meat Analogue Type, Distribution Channel, and Country)
|
Find answers to common questions about this report
The Meat Analogue market size was valued at USD 7,515.9 million in 2025.
The Meat Analogue market is projected to grow at a CAGR of 12.1% during the forecast period from 2026 to 2033.
The North America Meat Analogue market size is estimated to reach USD 5,538.2 million by 2033.
The leading segment in the Meat Analogue market is Burgers and Patties, with a projected value of USD 4,679.5 million by 2033. This segment demonstrates significant growth potential compared to other product types.
Key drivers for the Meat Analogue market include changing consumer preferences towards health and sustainability, increased awareness of the environmental impacts of meat consumption, and the rising popularity of plant-based diets. Urbanization and the demand for convenient, ready-to-eat options further contribute to market growth, particularly among younger generations prioritizing ethical sourcing.
North America holds the dominant share of the Meat Analogue market, with a value of USD 5,538.2 million projected for 2033, representing 31.9 percent of the total market.
The Meat Analogue market faces challenges from regulatory compliance, which imposes additional costs on producers and hinders innovation. Macroeconomic factors, including inflationary pressures on production costs and geopolitical instability affecting supply chains, further complicate the market environment and restrict growth potential.
The Meat Analogue market experiences increased product adoption driven by changing consumer preferences towards health and sustainability. The rising popularity of plant-based diets, particularly among younger generations, alongside greater availability of meat analogue products in retail channels, enhances consumer access and aligns with health-conscious dietary choices.
The Meat Analogue market is estimated to reach a valuation of USD 18,748.1 million by 2033.
Key players in the Meat Analogue market include Beyond Meat, Inc., Impossible Foods Inc., MorningStar Farms, Quorn Foods, Redefine Meat Ltd., and Nestlé S.A. (Garden Gourmet).
Choose Your License
Global Meat Analogue Market
The analysts below cover Food and Beverages research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

LEAD PRINCIPAL ANALYST, PHARMA AND HEALTHCARE
Food and Beverages · Healthcare · Healthcare IT · Medical Devices
Ajay Devgire is the Lead Healthcare Analyst at MetaStat Insight, leading strategic research and market intelligence initiatives across the global healthcare domain.
SENIOR RESEARCH ANALYST
Biotechnology · Food and Beverages · Medical Devices · Packaging
Snehal Pasalkar is a Research Analyst at MetaStat Insight, operating at the intersection of life sciences research, competitive strategy, and market intelligence.
Decarbonizing industrial thermal processes hinges on refrigerant regulations and compressor efficiency limits. Metastat Insights delivered a thorough market analysis that evaluated natural refrigerants like CO2 and hydrocarbons against synthetic low-GWP alternatives. The breakdown of utility incentives and grid capacity constraints across key European manufacturing hubs offered valuable perspective. The follow-up conversation with their sector analysts addressed our specific questions on mechanical vapor recompression systems efficiently.
Assessing 200mm wafer transition schedules and substrate supply bottlenecks requires precise technical intelligence. MetaStat Insight supplied an actionable breakdown comparing planar and trench MOSFET architectures across automotive and industrial drive markets. The regional capacity estimates for Asia-Pacific foundries helped clarify lead-time uncertainties during our strategic planning session. When we needed additional clarification on high-purity raw material sourcing, their analyst team responded with helpful context within twenty-four hours.
Tracking maintenance cycle demand for secondary flight display units and terrain collision avoidance systems across regional jet fleets involves complex aftermarket dynamics. MetaStat Insight provided practical analysis separating airline retrofit programs from OEM forward-fit production schedules in North America and Southeast Asia. The supplier matrix highlighted component obsolescence timelines without resorting to vague generalizations. The dataset served as a dependable reference during our annual program review meetings.
Explore related market intelligence reports worth reading alongside this one.