
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Wet Wire Drawing Lubricants Market Size, Share, By Type (Polymer-Based Lubricants, Synthetic Lubricants, Semi-Synthetic Lubricants and Hybrid Lubricants), By Metal Type (Ferrous and Non-Ferrous), By Distribution Channel (Direct Sales, Distributors and Dealers, Online Retail and Industrial Suppliers), By End-Use Industry (Automotive and Tyre Manufacturing, Construction and Infrastructure, Electrical Cables and Power Transmission, Industrial Fasteners and Springs, Welding and Metal Fabrication and Telecommunications and Electronics), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-3106
Published
October, 2026
Pages
306 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
Market Valuation: Valued at $100.8 Million in 2025, projected to reach $154.7 Million by 2033 at a 5.5% CAGR.
Dominant Segment: Polymer-Based Lubricants lead the market, driven by their increasing demand in automotive and electrical applications, reflecting a trend towards specialized lubricants that enhance productivity.
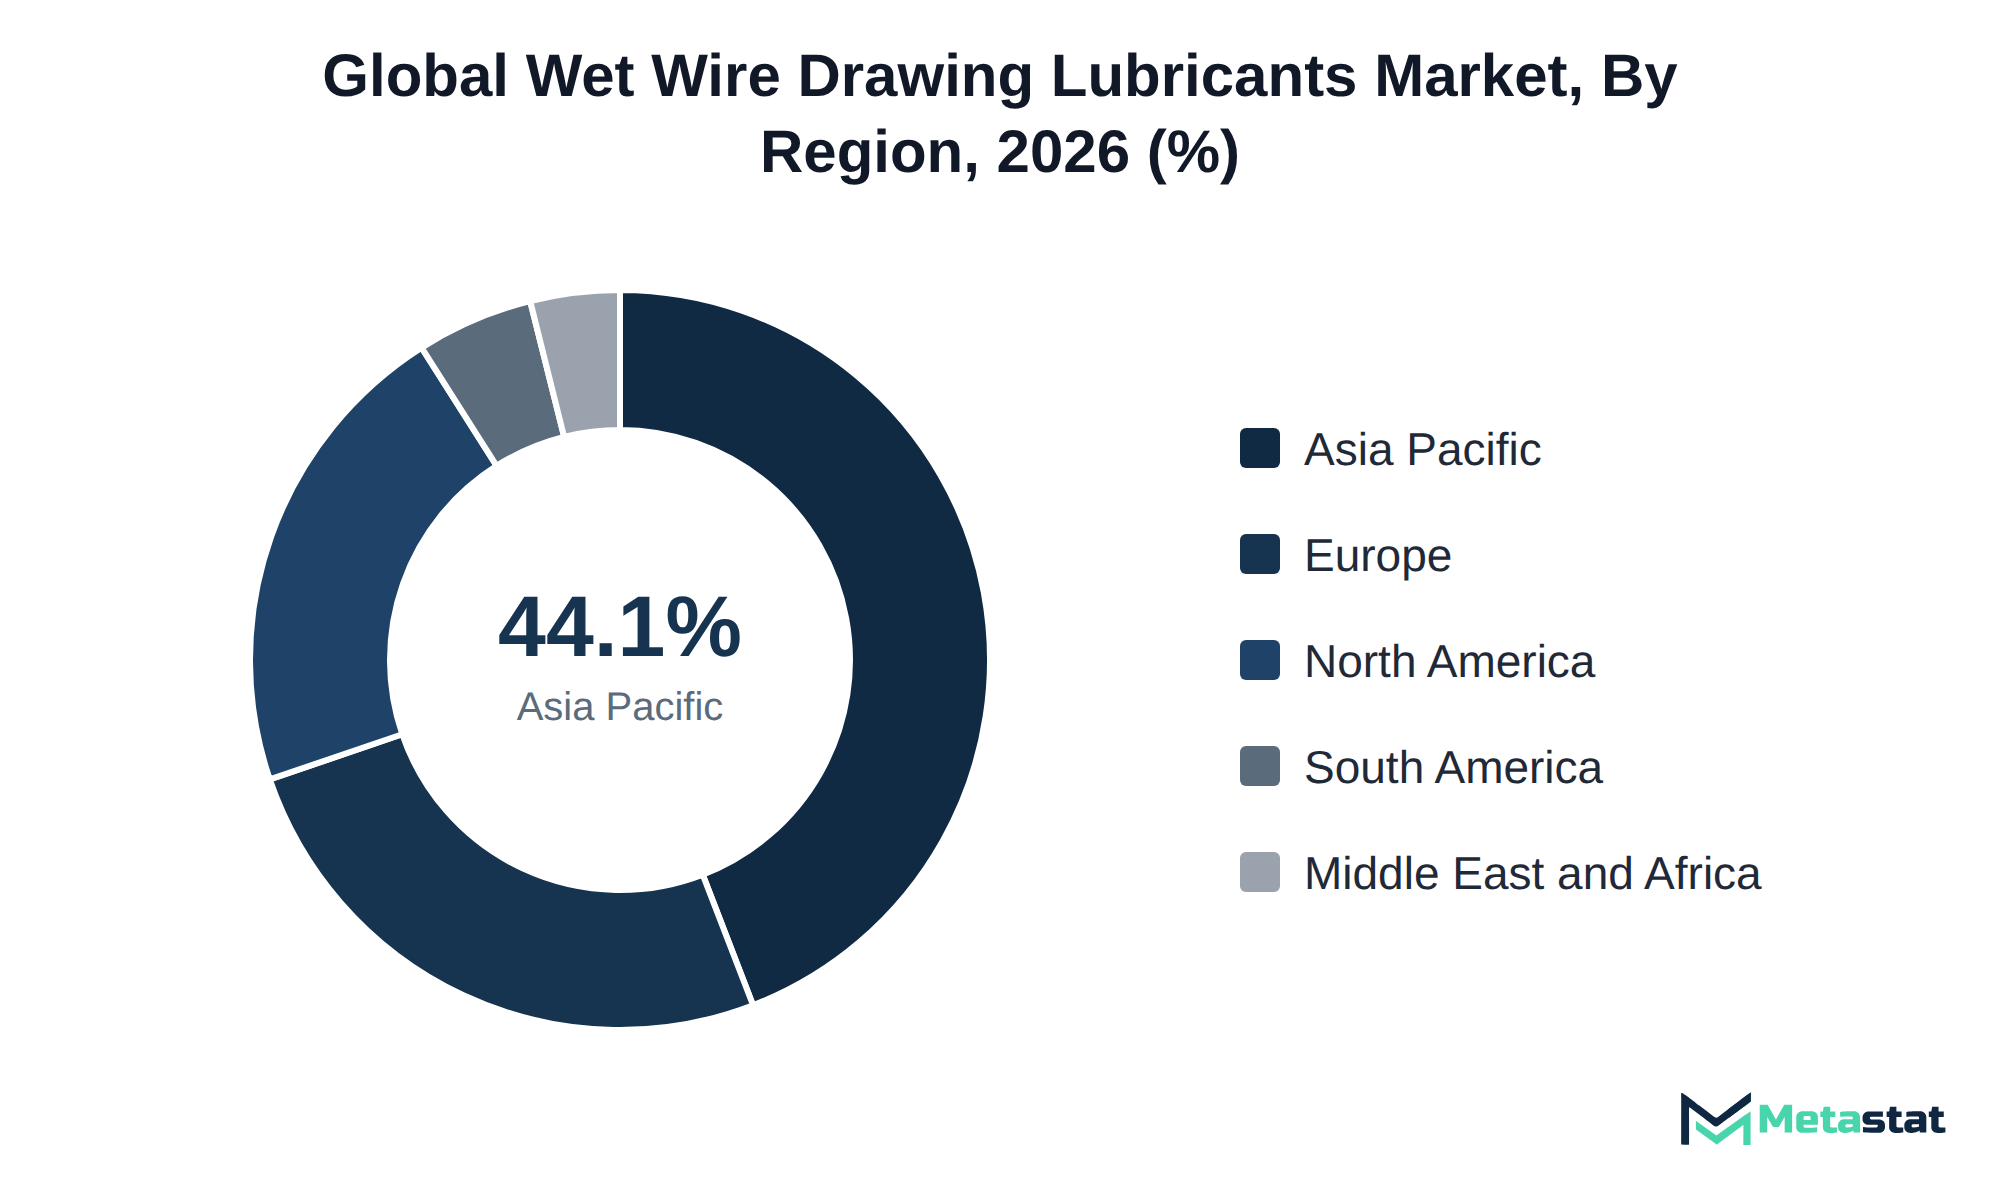
Geographic Lead: The Asia Pacific region commands the largest market share at 44.1% in 2025, supported by rising manufacturing needs and a focus on high-performance lubricants.
What's Inside: The report provides a comprehensive analysis of market dynamics, competitive landscape, and forecasts from 2026 to 2033, covering various lubricant types and end-use industries.
Emerging Opportunities: The Non-Ferrous lubricants segment is projected to grow at a CAGR of 6.4%, highlighting advancements in electrical cables and power transmission, which demand high-performance solutions.
Choose Your License
Global Wet Wire Drawing Lubricants Market
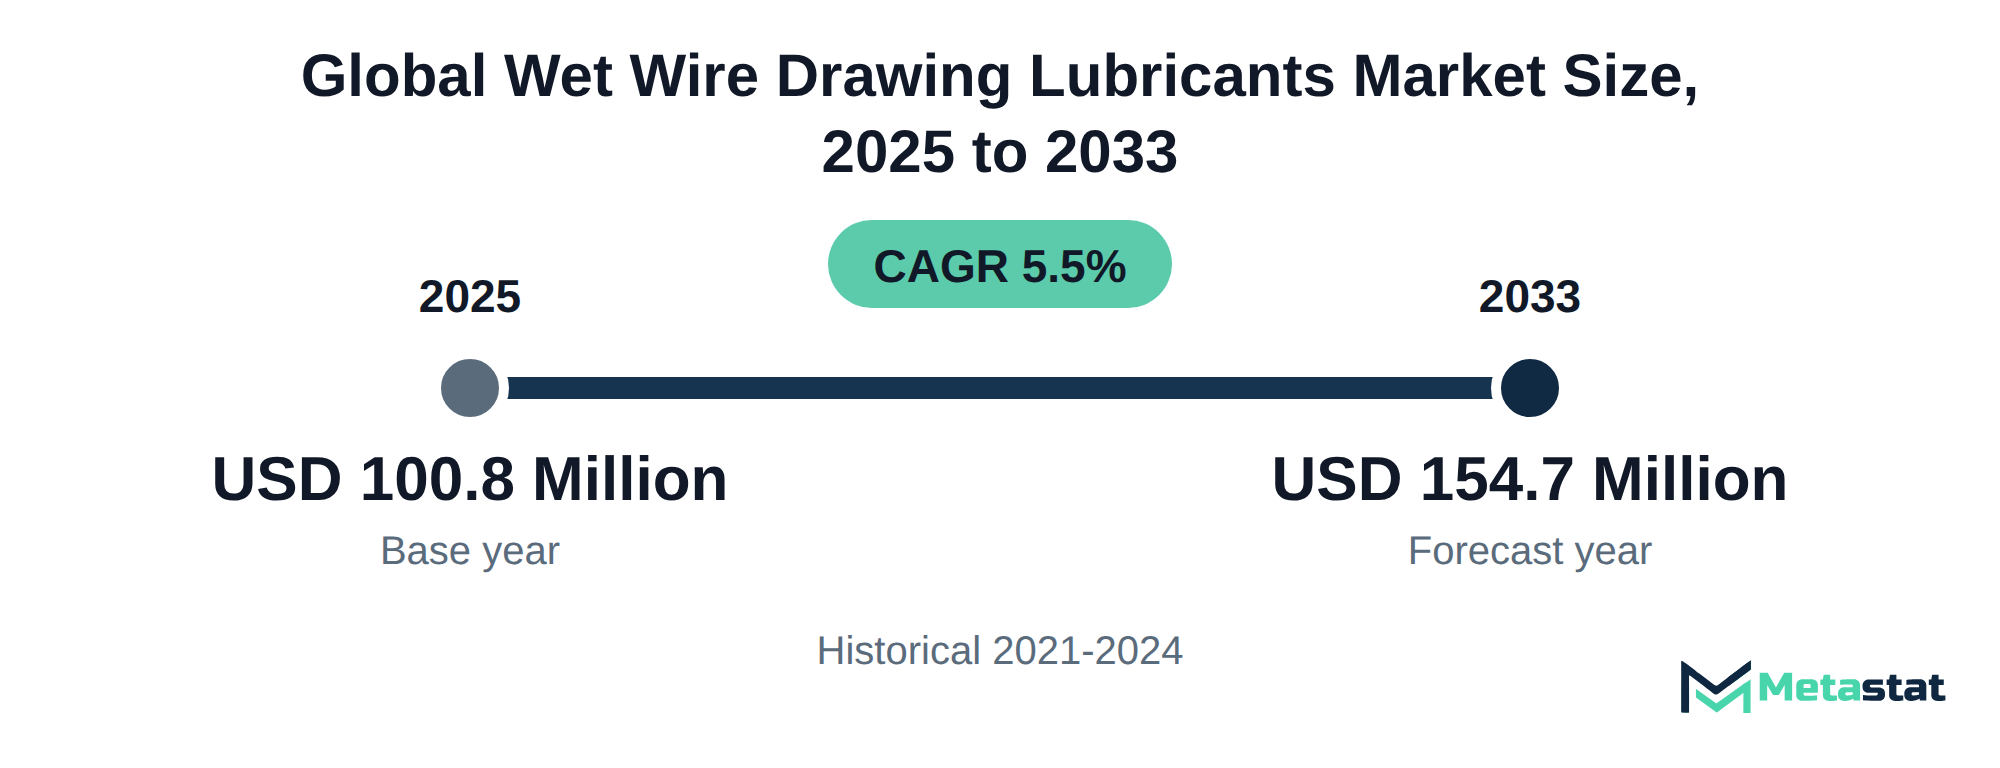
The global Wet Wire Drawing Lubricants market was valued at USD 100.8 million in 2025 and is projected to reach USD 154.7 million by 2033, growing at a CAGR of 5.5% over the forecast period.
The Wet Wire Drawing Lubricants market encompasses various types of lubricants used during the wire drawing process, enhancing the quality and efficiency of wire production. Buyers invest in these lubricants to ensure optimal performance, reduce friction, and prolong the life of machinery. Industries including automotive, electrical, and construction represent significant consumer groups, driven by their demand for high-quality and durable wire products.
Growth in the market is supported by the increasing focus on high-performance lubricants, particularly synthetic options, which offer superior properties compared to traditional alternatives. The Asia Pacific region commands the largest market share, accounting for 44.1% in 2025. North America holds 21.2% of the market in 2025, with the US leading in 2026. The rising need for advanced materials in manufacturing processes significantly contributes to market expansion.
Among the various segments, Polymer-Based Lubricants emerge as the most valuable, expected to see a notable increase in demand. This segment's growth reflects a broader trend towards adopting specialized lubricants that enhance productivity and operational efficiency. As industries evolve, the emphasis on sustainable and high-performance solutions drives the market forward, ensuring continued investment and innovation.
The Wet Wire Drawing Lubricants market serves various industries, including automotive, construction, and electrical sectors, focusing on enhancing wire quality and operational efficiency. Buyers invest in these lubricants to meet demanding production standards and improve product performance. Factors driving spending include the increasing emphasis on product quality and the need for efficient manufacturing processes.
Growth in the market is primarily driven by the rising demand for high-quality wire products across multiple sectors. Among the segments, Synthetic Lubricants represent the highest value, reflecting a trend towards advanced formulations that provide superior performance. North America holds 21.2% of the market in 2025, with the US leading in 2026, while Asia Pacific captures the largest share at 44.1%, indicating significant market potential in that region.
Investment in research and development has enabled innovation in lubricant formulations, allowing manufacturers to cater to specific industry requirements. The focus on sustainability and eco-friendly practices further influences market dynamics, with companies seeking to comply with environmental regulations and meet consumer preferences for greener products. This trend enhances competitive positioning and encourages investment in product development.
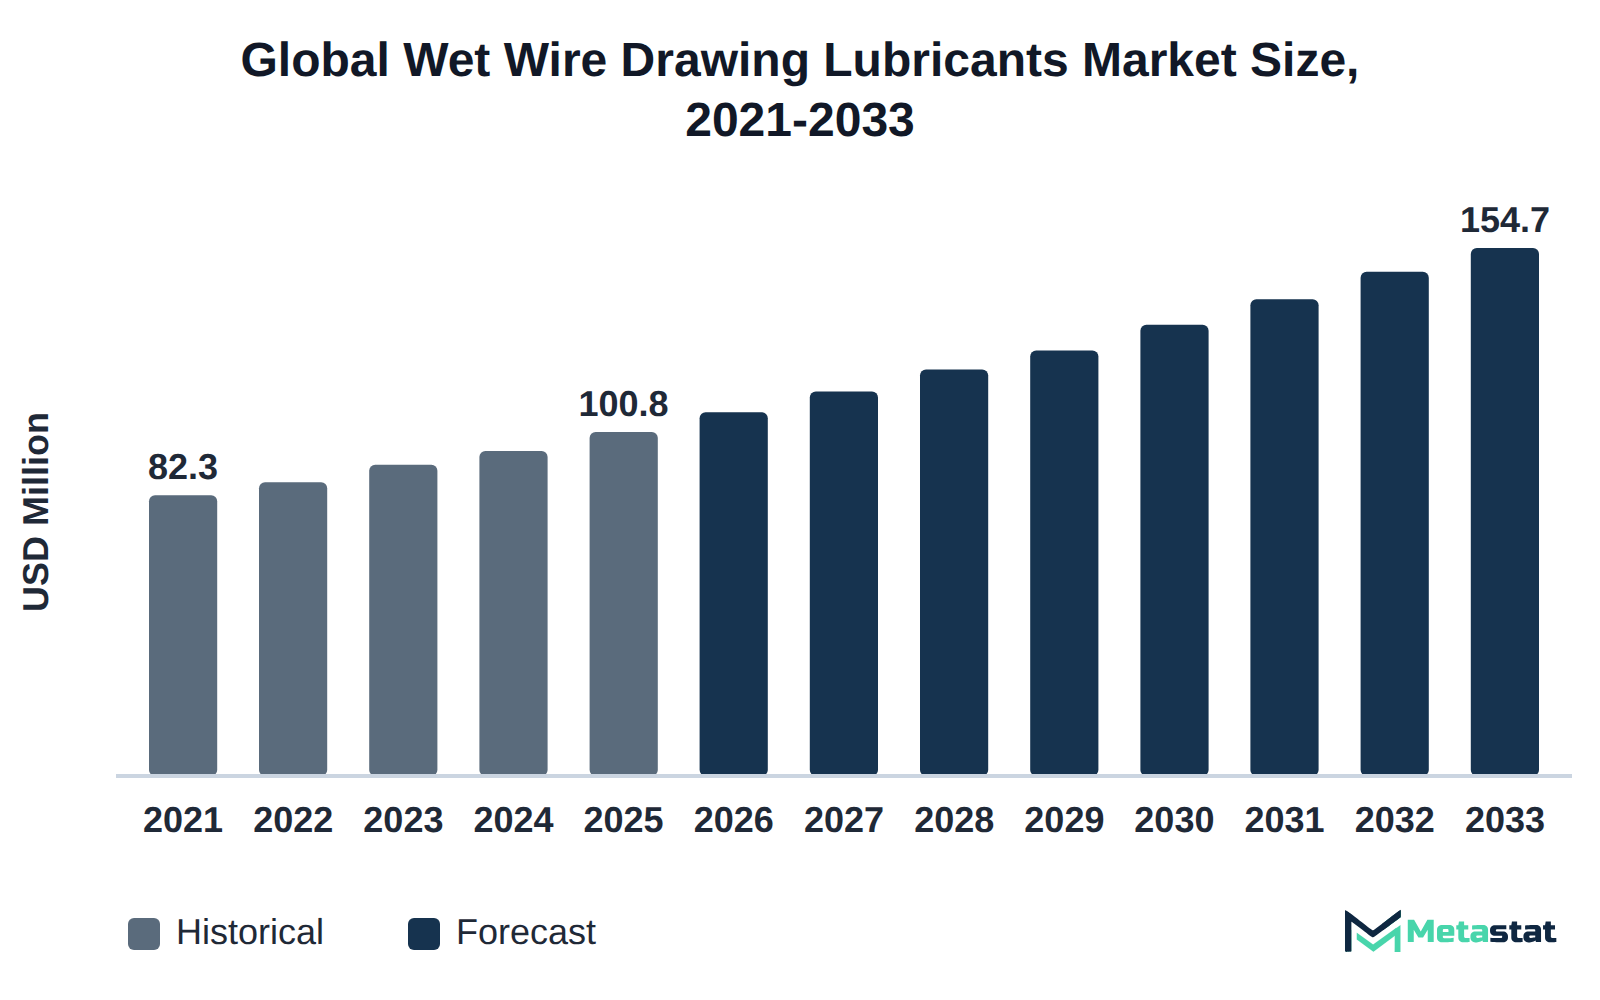
The Wet Wire Drawing Lubricants market is experiencing a significant transition toward synthetic and polymer-based lubricants, driven by the need for enhanced process efficiency and improved product performance. Synthetic lubricants are projected to achieve a market value of USD 52.2 million by 2033, reflecting a robust compound annual growth rate (CAGR) of 6.9%. This growth trajectory results from their superior lubrication properties, which facilitate smoother wire drawing processes, reduce friction, and prolong tool life.
Polymer-based lubricants, which are expected to grow from USD 44.4 million in 2026 to USD 60.2 million by 2033, with a CAGR of 4.4%, further highlight this shift. Their unique formulation provides stability under varying operational conditions, making them particularly appealing to manufacturers within the automotive and electrical cable sectors. The increasing demand for high-performance lubricants aligns with the industry's pursuit of efficiency and quality assurance in production processes.
This transition not only addresses operational challenges but significantly impacts commercial outcomes. Manufacturers adopting these advanced lubricants expect reduced downtime, lower maintenance costs, and enhanced product quality, positioning themselves competitively in the evolving Wet Wire Drawing Lubricants market.
The increasing adoption of electric vehicles drives significant demand for precision wire drawing applications. The need for high-performance power transmission cables necessitates the use of advanced Wet Wire Drawing Lubricants, enhancing operational efficiency and product lifespan. In the Wet Wire Drawing Lubricants market, the electrical cables and power transmission segment is poised for considerable growth, with an anticipated value reaching USD 50.2 million by 2033. This growth stems from escalating requirements for energy-efficient systems and the global shift towards sustainable energy solutions.
Pricing and contract models significantly influence purchasing decisions among buyers in this market. Manufacturers frequently adopt long-term contracts to secure stable supplies of lubricants, ensuring quality and consistency in their operations. These contracts create predictable pricing structures, which are vital in managing operational costs while navigating fluctuations in raw material prices. Buyers increasingly emphasize value-added services, including technical support and customized formulations, further influencing their procurement strategies.
The collaboration between lubricant suppliers and manufacturers strengthens the supply chain and drives innovation in product development. Establishing strategic partnerships promotes the introduction of innovative lubricants tailored for specific applications in electric vehicles and power transmission cables. Such collaborations enhance market competitiveness and meet the demand for high-quality solutions, ultimately driving growth in the Wet Wire Drawing Lubricants market.
Increasingly stringent sustainability and wastewater regulations influence formulations within the Wet Wire Drawing Lubricants market. This trend reflects a global shift towards environmentally friendly practices in manufacturing processes. Regulatory bodies emphasize the reduction of harmful substances in lubricants, pushing suppliers to innovate with biodegradable or low-toxicity components. For instance, polymer-based lubricants, projected to grow from USD 44.4 million in 2026 to USD 60.2 million by 2033, exemplify this shift, with manufacturers seeking to align their products with sustainability goals. The growth rate for these lubricants stands at 4.4%, reflecting rising acceptance driven by regulatory pressures.
Buyers across various industries increasingly prioritize lubricants that comply with environmental standards and contribute to sustainable manufacturing. The automotive sector, for example, demands lubricants that enhance performance while minimizing ecological impact. A clear focus on sustainability leads to higher operational costs for manufacturers not adhering to these regulations, reducing competitiveness. The Wet Wire Drawing Lubricants market is expected to evolve as suppliers adapt their offerings to meet the needs of environmentally conscious buyers.
Advanced lubricant formulations play a critical role in enhancing wire quality and prolonging die life in high-speed drawing operations. Polymer-based lubricants are increasing in importance in the Wet Wire Drawing Lubricants market. These specialized lubricants improve lubrication properties, reduce friction, and lower wear on dies, resulting in finer wire surfaces and improved dimensional accuracy.
The application of synthetic lubricants further contributes to operational efficiency. Synthetic lubricants offer superior thermal stability and resistance to oxidation, leading to extended lubricant life and reduced downtime during production. This improvement in performance directly correlates with the reduction of scrap rates and production costs, enhancing profitability for manufacturers.
Advancements in lubricant technology, including semi-synthetic and hybrid formulations, provide manufacturers with options that meet specific operational challenges. Semi-synthetic lubricants are achieving significant market traction, and manufacturers investing in these formulations expect enhanced performance metrics, resulting in increased competitiveness within the market.
Growing awareness of the benefits of synthetic lubricants drives higher expenditures from manufacturers in various sectors, particularly automotive and electrical industries. These lubricants offer superior performance characteristics, leading to improved efficiency and reduced downtime in production processes. The shift toward more environmentally friendly formulations aligns with broader sustainability goals, compelling buyers to transition from traditional options. This trend highlights the movement toward innovative solutions that enhance production efficacy while adhering to regulations. Demand remains strong among industries focused on quality and sustainability, further influencing purchasing patterns and market dynamics.
Adoption of advanced lubricant technologies aligns with stricter emission regulations across various industries. These regulations have prompted manufacturers to seek environmentally friendly solutions, enhancing the demand for synthetic formulations in the Wet Wire Drawing Lubricants market. Synthetic lubricants offer improved performance characteristics, including superior lubrication properties and reduced environmental impact, fulfilling regulatory requirements while maintaining operational efficiency.
The automotive and electrical sectors significantly contribute to this trend, driven by their commitment to sustainability. Manufacturers in these industries prioritize investments in synthetic lubricants to achieve compliance and enhance product performance. Consequently, growth in these sectors directly supports the increasing adoption of synthetic lubricants within the Wet Wire Drawing Lubricants market.
Overall, the relationship between regulatory pressures and the advantages of synthetic formulations creates a favorable environment for market expansion. Suppliers focusing on innovative lubricant technologies are likely to capture a larger share of the growing demand driven by these evolving standards.
Rising material costs present a significant restraint within the Wet Wire Drawing Lubricants market. Manufacturers face heightened expenses for raw materials, which directly impacts their pricing strategies. Buyers in the automotive and construction industries, often sensitive to cost fluctuations, exhibit slower uptake when faced with increased prices. Smaller orders frequently arise from concerns about budget constraints, resulting in delayed replacements or adoption of newer lubricant technologies. This cautious approach ultimately restricts overall market growth, affecting long-term investments and operational efficiencies in sectors relying on effective wire drawing lubricants. Addressing these cost dynamics remains critical for ensuring sustained demand in the market.
Fluctuating raw material costs present a challenge for suppliers within the Wet Wire Drawing Lubricants market. Rising prices for base materials, including petroleum-derived inputs, create strain on profit margins across the industry. Suppliers face the dual pressure of maintaining product quality while managing higher operational expenses. In response, many manufacturers explore alternative sourcing strategies to mitigate costs, including regional procurement and long-term contracts. Suppliers invest in research and development to formulate cost-effective lubricant alternatives that do not compromise performance. This trend helps ensure competitive pricing while responding to the evolving demands of end-use industries. Such adaptations support market stability during periods of economic uncertainty and shifting resource availability.
The demand for non-ferrous wet wire drawing lubricants is expected to rise significantly. Projected growth in this segment reflects advancements in industries including electrical cables and power transmission, highlighting the need for high-performance lubricants that enhance operational efficiency. The CAGR of 6.4% for non-ferrous lubricants reflects their increasing importance within the market, driven by technological innovations and growing end-user expectations. Manufacturers targeting the non-ferrous segment leverage advanced formulations to meet specific performance metrics required in high-precision applications.
Companies expanding their product offerings to include specialized non-ferrous lubricants are likely to capture a larger share of the market. This growth opportunity aligns with broader industry trends emphasizing enhanced performance and sustainability, positioning suppliers to address evolving customer demands effectively. The focus on non-ferrous lubricants presents a strategic avenue for investment, enabling firms to enhance their competitive edge and respond to the distinct requirements of this segment.
The Global Wet Wire Drawing Lubricants market is segmented based on Type, Metal Type, Distribution Channel, and End-Use Industry.
These lubricants primarily serve the automotive, electrical, and construction industries, enhancing performance and efficiency in the wire drawing process. Increasing demand for high-performance lubricants drives the growth of this segment, particularly due to rising production of electric vehicles and advanced power transmission systems. Compared to other segments, Polymer-Based Lubricants exhibit a more moderate growth rate. Synthetic Lubricants, for instance, are projected to grow at a CAGR of 6.9%, reflecting faster adoption in applications requiring higher precision and lower environmental impact. This segment's steady performance highlights its importance in achieving operational efficiency while catering to the evolving needs of various end-use industries.
These lubricants are widely used in industries requiring high-performance solutions, particularly in wire drawing applications. Manufacturers in the automotive and electrical sectors rely heavily on synthetic lubricants due to their superior properties, which enhance the efficiency and quality of wire drawing processes. The increasing emphasis on sustainability and performance drives demand specifically for synthetic lubricants, differentiating them from other lubricant types that do not offer the same level of efficiency. This segment experiences faster growth compared to polymer-based alternatives, influenced by advancements in formulation technologies that improve lubrication performance and reduce environmental impact.
Semi-Synthetic Lubricants segment is expected to reach USD 29.5 million by 2033. These lubricants find application in various industries, particularly in automotive and electrical cable manufacturing, where they enhance the drawing process by providing improved lubrication and cooling. The growth of this segment aligns with the increasing demand for high-quality wire products that require effective lubrication solutions. Demand drivers include the ongoing transition towards more advanced lubricant technologies, which aim to improve efficiency and performance. Compared to Polymer-Based Lubricants, which exhibit a CAGR of 4.4%, Semi-Synthetic Lubricants display stronger growth potential with a CAGR of 4.7%. This segment's differentiation lies in its pricing structure and performance characteristics, appealing to buyers seeking a balance between cost and effectiveness in their lubricant choices. The market evolves with a growing focus on innovative formulations that cater to the specific needs of various end-use sectors.
USD 29.5 million defines the Others (Hybrid Lubricants) segment, projected to grow at a CAGR of 5.6% during the forecast period. This segment finds application across various industries, particularly in automotive and electrical sectors, where hybrid lubricants enhance the performance of wire drawing processes. Demand for hybrid lubricants stems from the need for more versatile formulations that offer improved lubrication properties and environmental benefits. This segment stands apart from others due to its focus on combining the advantages of both synthetic and semi-synthetic lubricants, enabling higher performance standards. Compared to synthetic lubricants, which are expected to reach USD 52.2 million by 2033, hybrid lubricants attract a different buyer demographic, appealing to manufacturers seeking tailored solutions for specific applications. This distinct positioning influences both pricing strategies and market dynamics.
Ferrous lubricants are valued at USD 59.7 million in 2026 and projected to reach USD 82.3 million by 2033, at a CAGR of 4.7% during the forecast period. These lubricants primarily serve the wire drawing processes in industries including automotive and electrical manufacturing, where high-quality wire products are essential. Demand for ferrous lubricants is driven by the need for enhanced performance in wire drawing operations, particularly in applications requiring strong and durable wire. In comparison to synthetic lubricants, which exhibit a higher growth rate of 6.9%, ferrous lubricants demonstrate a steadier increase in demand. The competitive pricing associated with ferrous lubricants appeals to manufacturers operating under cost constraints, differentiating this segment from others within the market. Maintaining efficient production processes in industries reliant on ferrous materials ensures continued interest in this segment.
Non-Ferrous segment is estimated to reach USD 72.4 million by 2033, at a CAGR of 6.4% during the forecast period. This segment serves industries including automotive and electrical, where non-ferrous materials are integral for applications like wiring and transmission components. Demand for lightweight materials and better conductivity drives growth in this segment. Compared to the Ferrous segment, which experiences a lower CAGR of 4.7%, the Non-Ferrous segment demonstrates a higher growth trajectory. This difference in growth rates stems from the increasing preference for non-ferrous metals due to their corrosion resistance and lightweight properties. The market shift towards enhancing performance and sustainability further accelerates the adoption of non-ferrous wet wire drawing lubricants.
Direct Sales segment is valued at USD 51 million in 2026 and is projected to reach USD 69.8 million by 2033, at a CAGR of 4.6% during the forecast period. This segment serves buyers who prefer a direct relationship with suppliers, facilitating customized solutions for their specific lubrication needs. Industries including automotive and electrical manufacturing frequently engage in direct purchasing to ensure quality and consistency. The driving force behind this segment stems from the desire for lower supply chain costs and a streamlined purchasing process. Compared to other distribution channels, Direct Sales demonstrates slower growth rates. This slower pace contrasts with the rapidly expanding Online Retail segment, where increased digital presence enhances purchasing convenience and access to a wider range of products. The Wet Wire Drawing Lubricants market evolves with significant shifts in buyer preferences and distribution strategies.
Distributors and Dealers segment is estimated to reach USD 45.6 million by 2033, at a CAGR of 4.6% during the forecast period. This segment supplies wet wire drawing lubricants to various end-users, including manufacturers in automotive and construction industries. The growth of this segment is driven by the increasing demand for efficient and high-performance lubricants that enhance operational efficiency. Compared to other distribution channels, this segment benefits from established relationships and trust built over time with industrial clients, enabling it to capture a significant share of the market. The need for specialized lubricants tailored to specific applications further enhances the importance of distributors and dealers, ensuring they offer products that meet the varying requirements of different industries. With rising demand for innovative lubricant solutions, this segment is positioned for steady growth, contributing significantly to the overall expansion of the market.
The Online Retail segment is expected to reach USD 12.9 million by 2033. This distribution channel facilitates direct access for consumers and businesses seeking wet wire drawing lubricants, particularly in the automotive and electrical industries. The increasing shift toward digital purchasing platforms enhances convenience and accessibility for buyers who prefer online transactions over traditional brick-and-mortar options. This segment distinguishes itself with a lower projected growth rate compared to others, driven by a CAGR of 4.6%. The rising prevalence of e-commerce and the need for efficiency in procurement processes significantly influence this segment's expansion. While more buyers adopt online purchasing, competition among suppliers intensifies, prompting them to enhance their digital presence and optimize pricing strategies to attract consumers. The distinct characteristics of this segment contribute to the overall development of the market, reflecting changing consumer behaviors and preferences in lubricant procurement.
Industrial Suppliers segment is projected to grow at a CAGR of 7.7% during the forecast period. This segment serves various industries by providing necessary lubricants that enhance the performance and longevity of machinery used in processes including metal drawing and fabrication. A significant demand driver for this segment stems from the increasing focus on efficiency and sustainability among manufacturers. The market dynamics for Industrial Suppliers differ from other segments due to its higher reliance on direct relationships with manufacturers, often resulting in tailored solutions that meet specific operational requirements. This direct engagement creates strong partnerships, leading to higher customer loyalty. In contrast, other distribution channels including Distributors and Dealers exhibit lower growth rates, projected at a CAGR of 4.6%, indicating that Industrial Suppliers hold a competitive advantage in responsiveness and customization, which directly impacts the market's overall growth trajectory.
Automotive and Tyre Manufacturing segment is valued at USD 27.9 million in 2026 and is projected to reach USD 38.9 million by 2033, at a CAGR of 4.8% during the forecast period. This segment serves manufacturers of vehicles and tyres, requiring lubricants for wire drawing processes essential in producing components like steel cables and wire connections. The growth of this segment is driven by increasing automotive production and demand for high-performance vehicles. Unlike other segments, this category experiences slower growth compared to the Non-Ferrous segment, which is projected to grow at a CAGR of 6.4%. The focus on quality and performance in automotive applications leads to higher expenditure on advanced lubricant formulations. The market benefits from technological advancements in lubrication applications, ensuring enhanced efficiency and reduced wear in manufacturing processes.
Construction and Infrastructure segment is estimated to reach USD 21.8 million by 2033, at a CAGR of 4.2% during the forecast period. This segment is significant in various construction activities, including building roads, bridges, and residential structures. Major buyers include construction companies and infrastructure developers emphasizing high-quality materials and effective lubrication solutions. Increased investments in infrastructure projects drive demand in this segment, alongside ongoing urbanization and population growth. Compared to other segments, including Automotive and Tyre Manufacturing, this segment exhibits a slower growth rate, with Automotive projected to grow at a CAGR of 4.8%. The construction sector’s focus on enhancing operational efficiency and reducing environmental impact shapes lubricant preferences, particularly for products that provide superior performance and sustainability. The Wet Wire Drawing Lubricants market benefits from these trends, reflecting strong alignment with industry needs.
This segment serves industries involved in manufacturing electrical cables and power transmission systems, focusing on enhancing the performance and longevity of wire products. Key drivers include increasing demand for energy-efficient solutions and expansion of electrical infrastructure worldwide. Compared to other segments, this segment experiences significant growth due to rising investments in renewable energy and smart grid technologies. The anticipated CAGR for this segment highlights a strong upward trajectory, distinguishing it from slower-growing segments in the market. The specialized nature of lubricants for electrical applications often leads to higher pricing structures, appealing to specific buyers seeking quality and efficiency.
Industrial Fasteners and Springs segment is projected to grow at a CAGR of 4.7% during the forecast period. This segment supports the manufacturing of components crucial for various mechanical applications, including machinery and automotive parts. Industries focused on production and assembly use these lubricants to ensure smooth operation and longevity of fasteners and springs. Increasing demand for lightweight and durable materials drives growth within this segment. Compared to other segments, including Automotive and Tyre Manufacturing, which is expected to see a CAGR of 4.8%, the growth trajectory of Industrial Fasteners and Springs highlights a more stable pace, suggesting consistent demand rather than rapid expansion. The need for enhanced performance in manufacturing processes continues to influence purchasing decisions, leading to sustained interest in this sector. This segment fulfills the lubricating requirements of various industrial applications, reinforcing its position in the Wet Wire Drawing Lubricants market.
Welding and Metal Fabrication involves processes essential for assembling and manufacturing metal structures and components. This segment serves industries engaged in metalworking, including construction, automotive, and machinery. Demand for advanced welding lubricants increases due to the growing need for efficiency, precision, and quality during metal processing. The segment distinguishes itself by catering specifically to high-performance applications, contrasting with other segments that focus on general-purpose lubricants. Technological advancements in welding techniques and materials drive innovation in lubricant formulations tailored for metal fabrication. These products often carry higher prices than standard lubricants due to their specialized nature and performance benefits, appealing to industrial buyers seeking enhanced production capabilities. Environmental regulations push for the development of more sustainable lubricant options, impacting the competitive landscape of welding lubricants. The Wet Wire Drawing Lubricants market reflects these dynamics through evolving product offerings that align with industry needs.
Others (Telecommunications and Electronics) includes applications that require specialized wire drawing lubricants for the production of communication cables and electronic components. This segment serves manufacturers focused on high-performance electronics where precision and reliability are crucial. Demand in this segment is influenced by rapid advancements in telecommunications technologies and increasing emphasis on electronic device efficiency. Unlike other segments, it experiences a distinct growth trajectory driven by innovation in consumer electronics and telecommunications infrastructure. The unique requirements for high-quality lubricants differentiate this segment, often resulting in higher pricing compared to more traditional applications including automotive or industrial uses. Ongoing development of smart technologies and connectivity solutions further increases the demand for these specialized lubricants, contributing to a dynamic environment within the market.
Based on geography, the Global Wet Wire Drawing Lubricants market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Demand for wet wire drawing lubricants in North America stems primarily from the automotive and electrical cables industries, which require high-performance lubricants for efficient manufacturing processes. The presence of established automotive manufacturers in the United States drives the need for specialized lubricants that enhance productivity and reduce equipment wear. In addition, the market benefits from increasing investments in infrastructure development in Canada and Mexico, further supporting lubricant application across construction and electrical sectors. North America is projected to reach USD 30.8 million by the end of 2033, accounting for 21.2% of the global market share in 2025. This growth reflects a strong regional commitment to enhancing manufacturing capabilities and maintaining competitive production standards, ensuring sustained demand for wet wire drawing lubricants.
Europe represents a significant market for Wet Wire Drawing Lubricants, contributing 25.6% to the global share in 2025. The automotive and tire manufacturing industries drive demand, alongside construction and infrastructure sectors. Germany, France, and the UK emerge as key players with robust industrial activities in these sectors. Cost structures in Europe include stringent environmental regulations that influence lubricant formulation and production processes. This regulatory environment creates a need for innovative solutions to meet both performance and compliance standards. Suppliers focusing on high-quality, environmentally friendly lubricants are likely to find expanding opportunities within the market through 2033.
Asia-Pacific holds a 44.1% share in the Wet Wire Drawing Lubricants market for 2025. Growing demand in automotive and electrical cable manufacturing drives this sector, with countries like China, India, and Japan serving as key contributors. The region's rapid industrialization, along with increasing investments in infrastructure projects, fuels the need for efficient wire drawing processes. Manufacturing capabilities across Southeast Asia further enhance local production of lubricants. Rising production capacities and technological advancements in lubricant formulations create a competitive landscape, prompting suppliers to innovate and offer enhanced products. Regulatory frameworks focused on environmental sustainability influence the formulation of lubricants, ensuring compliance with standards while meeting market needs. By 2033, the market in Asia-Pacific is forecasted to reach USD 154.7 million, reflecting sustained growth opportunities.
In South America, the Wet Wire Drawing Lubricants market benefits from the growth of industries including automotive manufacturing and construction. Brazil and Argentina stand out as the leading countries, focusing on enhancing production capabilities and improving infrastructure. The market's share of 5.1% in 2025 highlights its importance in the global context. Rising investments in manufacturing processes drive the demand for high-quality lubricants that support operational efficiency. The growing construction sector contributes to the increasing need for advanced wire drawing lubricants, reflecting a trend toward modernization in production techniques. Overall, the market experiences favorable conditions for growth driven by industry developments and technological advancements.
The market in the Middle East and Africa faces unique dynamics that shape its growth trajectory. Significant demand arises from the automotive sector, particularly in Saudi Arabia and the UAE, where automotive manufacturing continues to expand. Infrastructure development projects in South Africa further contribute to market demand, with investments aimed at enhancing construction capabilities. The region's market share stands at 3.9% in 2025, reflecting an environment that encourages the adoption of advanced lubricants. The increasing focus on energy-efficient solutions drives manufacturers to seek high-performance wet wire drawing lubricants. This trend aligns with broader industrial goals to improve operational efficiency and reduce environmental impact, making the market a vital component for various regional industries.
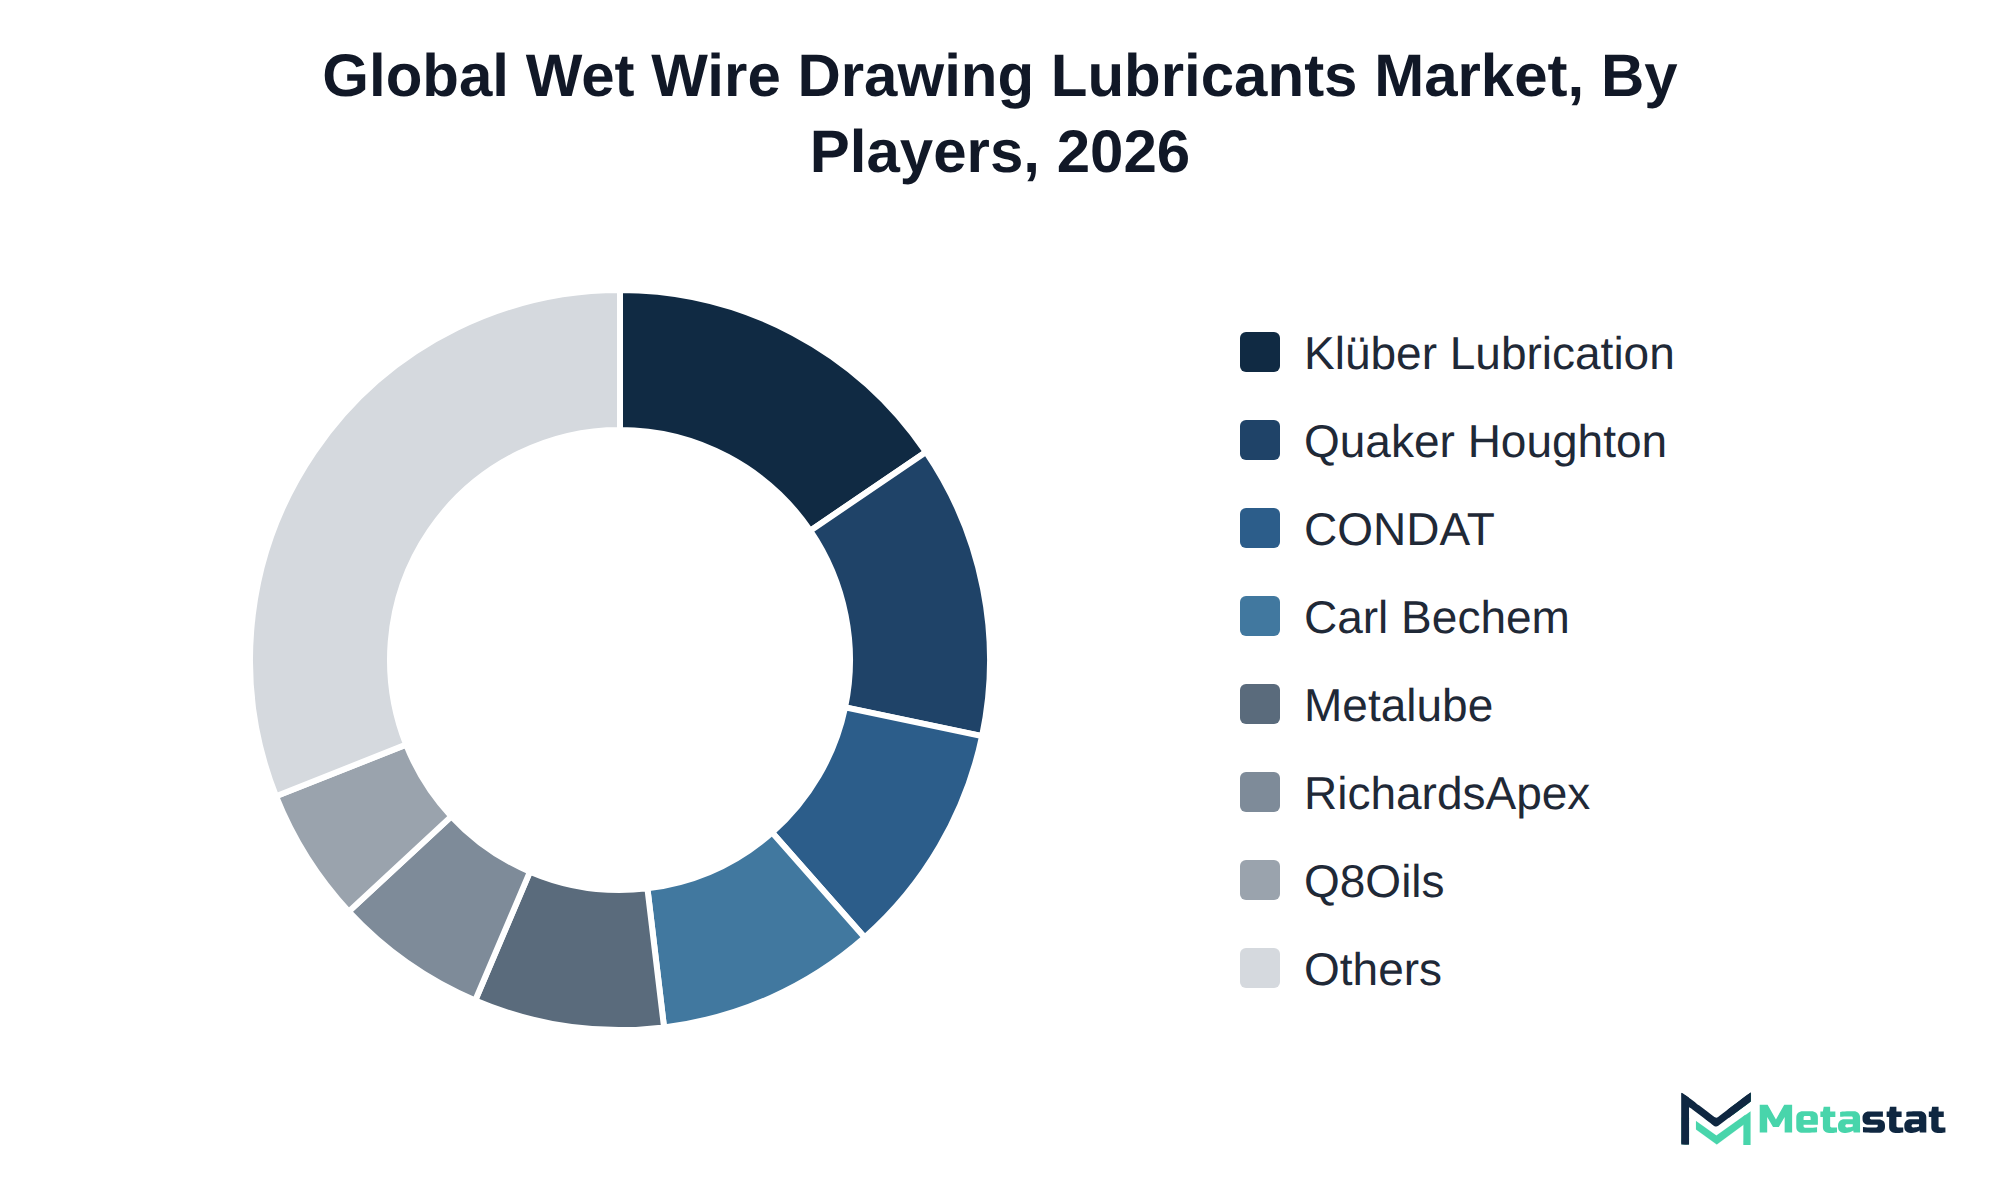
The Wet Wire Drawing Lubricants market features considerable competition among various players focusing on different aspects of product offerings. Companies position themselves based on factors including price, customization, certification, and service quality, which influence buyers' choices. The market includes both polymer-based and synthetic lubricants, catering to diverse needs across segments.
CONDAT S.A. specializes in high-performance lubricants tailored for specific applications, enhancing operational efficiency for clients. Klüber Lubrication GmbH emphasizes innovative formulations and customer support, fortifying its presence in the market. Quaker Houghton targets industrial applications with a broad product portfolio, offering solutions that address various operational challenges.
Companies like FUCHS SE and PETROFER leverage extensive distribution networks to reach a wider customer base, adapting their strategies to the evolving demands of the market. Customization and responsiveness to client requirements serve as key differentiators, with companies striving to deliver tailored solutions that meet industry standards and expectations.
This growth relies on several key developments within the Wet Wire Drawing Lubricants market. First, the expansion of synthetic lubricants, projected to achieve USD 52.2 million by 2033 at a CAGR of 6.9%, enhances product performance across multiple sectors, particularly in automotive manufacturing. Second, the adoption of polymer-based lubricants, expected to increase from USD 44.4 million in 2026 to USD 60.2 million by 2033 at a CAGR of 4.4%, drives efficiency and reduces environmental impact, appealing to sustainability-focused industries. Third, robust demand from the Asia Pacific region, which holds a market share of 44.1%, indicates a strong growth trajectory fueled by industrial activities and investments in infrastructure development. Potential fluctuations in raw material prices pose a risk to this growth, affecting profit margins for suppliers. Rising material costs could lead to increased prices for end-users, potentially slowing adoption rates in the market.
By Type: Polymer-Based Lubricants, Synthetic Lubricants, Semi-Synthetic Lubricants, Others (Hybrid Lubricants)
By Metal Type: Ferrous, Non-Ferrous
By Distribution Channel: Direct Sales, Distributors and Dealers, Online Retail, Industrial Suppliers
By End-Use Industry: Automotive and Tyre Manufacturing, Construction and Infrastructure, Electrical Cables and Power Transmission, Industrial Fasteners and Springs, Welding and Metal Fabrication, Others (Telecommunications and Electronics)
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Wet Wire Drawing Lubricants market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 5.5% from 2026 to 2033 |
|
Revenue Unit |
USD million |
|
Segmentation |
By Type, Metal Type, Distribution Channel, End-Use Industry, and Region |
|
By Region |
North America (By Type, Metal Type, Distribution Channel, End-Use Industry, and Country)
|
|
Europe (By Type, Metal Type, Distribution Channel, End-Use Industry, and Country)
|
|
|
Asia Pacific (By Type, Metal Type, Distribution Channel, End-Use Industry, and Country)
|
|
|
South America (By Type, Metal Type, Distribution Channel, End-Use Industry, and Country)
|
|
|
Middle East and Africa (By Type, Metal Type, Distribution Channel, End-Use Industry, and Country)
|
Find answers to common questions about this report
The Wet Wire Drawing Lubricants market size was valued at USD 100.8 million in 2025.
The market is projected to grow at a CAGR of 5.5% during the forecast period from 2026 to 2033.
The North America Wet Wire Drawing Lubricants market size is estimated to reach USD 30.8 million by 2033.
Polymer-Based Lubricants lead the Wet Wire Drawing Lubricants market with a value of USD 44.4 million in 2026. This segment's growth reflects its significant share compared to other types.
Growing awareness of the benefits of synthetic lubricants drives higher expenditures from manufacturers, particularly in the automotive and electrical industries. The demand for non-ferrous wet wire drawing lubricants is expected to rise significantly, reflecting advancements in industries including electrical cables and power transmission.
Rising material costs restrain growth in the Wet Wire Drawing Lubricants market by impacting pricing strategies and leading to slower uptake among buyers sensitive to cost fluctuations. Fluctuating raw material prices challenge suppliers, straining profit margins while maintaining product quality amid increasing operational expenses.
Several factors favor adoption in the Wet Wire Drawing Lubricants industry. The increasing demand for non-ferrous lubricants, driven by advancements in electrical cables and power transmission, supports this trend. the projected CAGR of 6.4% for non-ferrous lubricants emphasizes their growing significance in enhancing operational efficiency and meeting performance metrics in high-precision applications.
The Wet Wire Drawing Lubricants market is estimated to reach a valuation of USD 154.7 million by 2033.
Key players operating in the Wet Wire Drawing Lubricants market include CONDAT S.A., Klüber Lubrication GmbH, Carl Bechem GmbH, Metalube Limited, Quaker Houghton, FUCHS SE, and Excel Petroleum Private Limited.
Polymer-based lubricants are projected to reach a value of USD 60.2 million by 2033, reflecting a compound annual growth rate (CAGR) of 4.4 percent.
The analysts below cover Chemicals and Materials research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
INDUSTRY CONSULTANT - CHEMICALS & ADVANCED MATERIALS
Chemicals and Materials · Machinery & Equipment · Packaging
Amit Gadhekar Consultant for Chemicals and Materials at MetaStat Insight, directing sector-specific intelligence, research, and strategic consulting across global chemical and processing markets.
Assessing commercial microgrid software adoption requires looking past top-level installation numbers and examining utility interconnection queues. The research provided verifiable data on average permitting timelines, tariff structures, and battery storage integration costs across regional utility territories. That grounded perspective was valuable for our team when building five-year demand projections for industrial microgrid controllers.
Ambulatory surgical centers have very different purchasing cycles for robotic-assisted surgery platforms than major hospital networks. The MetaStat Insight study focused squarely on capital expenditure depreciation, procedural reimbursement pathways, and surgeon training overhead. That operational clarity made it much simpler to validate multi-year procedure growth forecasts against actual ambulatory center adoption patterns.
When planning edge sensor rollouts across refinery environments, generic IoT reports typically miss the harsh-environment certification bottlenecks. MetaStat Insight gave an objective evaluation of ATEX and Class 1 Division 2 hardware availability, along with realistic five-year maintenance cycle cost projections. The comparison of wireless mesh versus private cellular backhaul helped our team pressure-test network reliability models for remote processing facilities.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950