
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Automotive Composite Market Size, Share, By Fiber Type (Glass Fiber Composites, Carbon Fiber Composites, Natural Fiber Composites, Aramid Fiber Composites, Basalt Fiber Composites, Hybrid Fiber Composites and Others (UHMWPE and Specialty Fibers)), By Resin Type (Polypropylene (PP), Polyamide (PA), Epoxy, Unsaturated Polyester, Vinyl Ester, Polyurethane (PU), Polyphenylene Sulfide (PPS), Polyaryletherketones (PEEK, PEKK and Other PAEK) and Phenolic Resins), By Application (Body and Exterior Panels, Body-in-White and Structural Components, Chassis and Suspension Components, Interior Components, Underbody and Aerodynamic Components, Powertrain and Under-the-Hood Components, EV Battery Enclosures and Protection Structures, Pressure Vessels and Fuel-System Components, Wheels and Braking and Performance Components and Others (Brackets, Covers and Specialty Components)), By Manufacturing Process (Compression Molding, Injection Molding and Overmolding, Resin Transfer Molding (RTM and HP-RTM), Prepreg Lay-up and Autoclave/Out-of-Autoclave Molding, Thermoforming and Stamp Forming, Pultrusion, Filament Winding, Vacuum Infusion and Hand Lay-up and Spray-up and Others (Automated Fiber Placement and Specialty Processes)), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5337
September 22, 2026
294 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $13.8 Billion in 2025, projected to reach $27.5 Billion by 2033 at a 9.0% CAGR.
Dominant Segment: The Glass Fiber Composites segment leads the market, driven by the increasing demand for lightweight materials that enhance fuel efficiency and reduce emissions.
Geographic Lead: The Asia Pacific region is experiencing the fastest growth, fueled by rising automotive production and demand for advanced composite materials.
What's Inside: The report provides comprehensive competitive coverage, detailed analyses of market dynamics, and a forecast window extending from 2026 to 2033.
Emerging Demands: The market is innovating in response to consumer preferences for lightweight and eco-friendly materials, particularly in electric vehicles and structural applications.
Regulatory Compliance: Manufacturers face significant challenges due to stringent regulations, impacting operational costs and complicating market entry for smaller players.
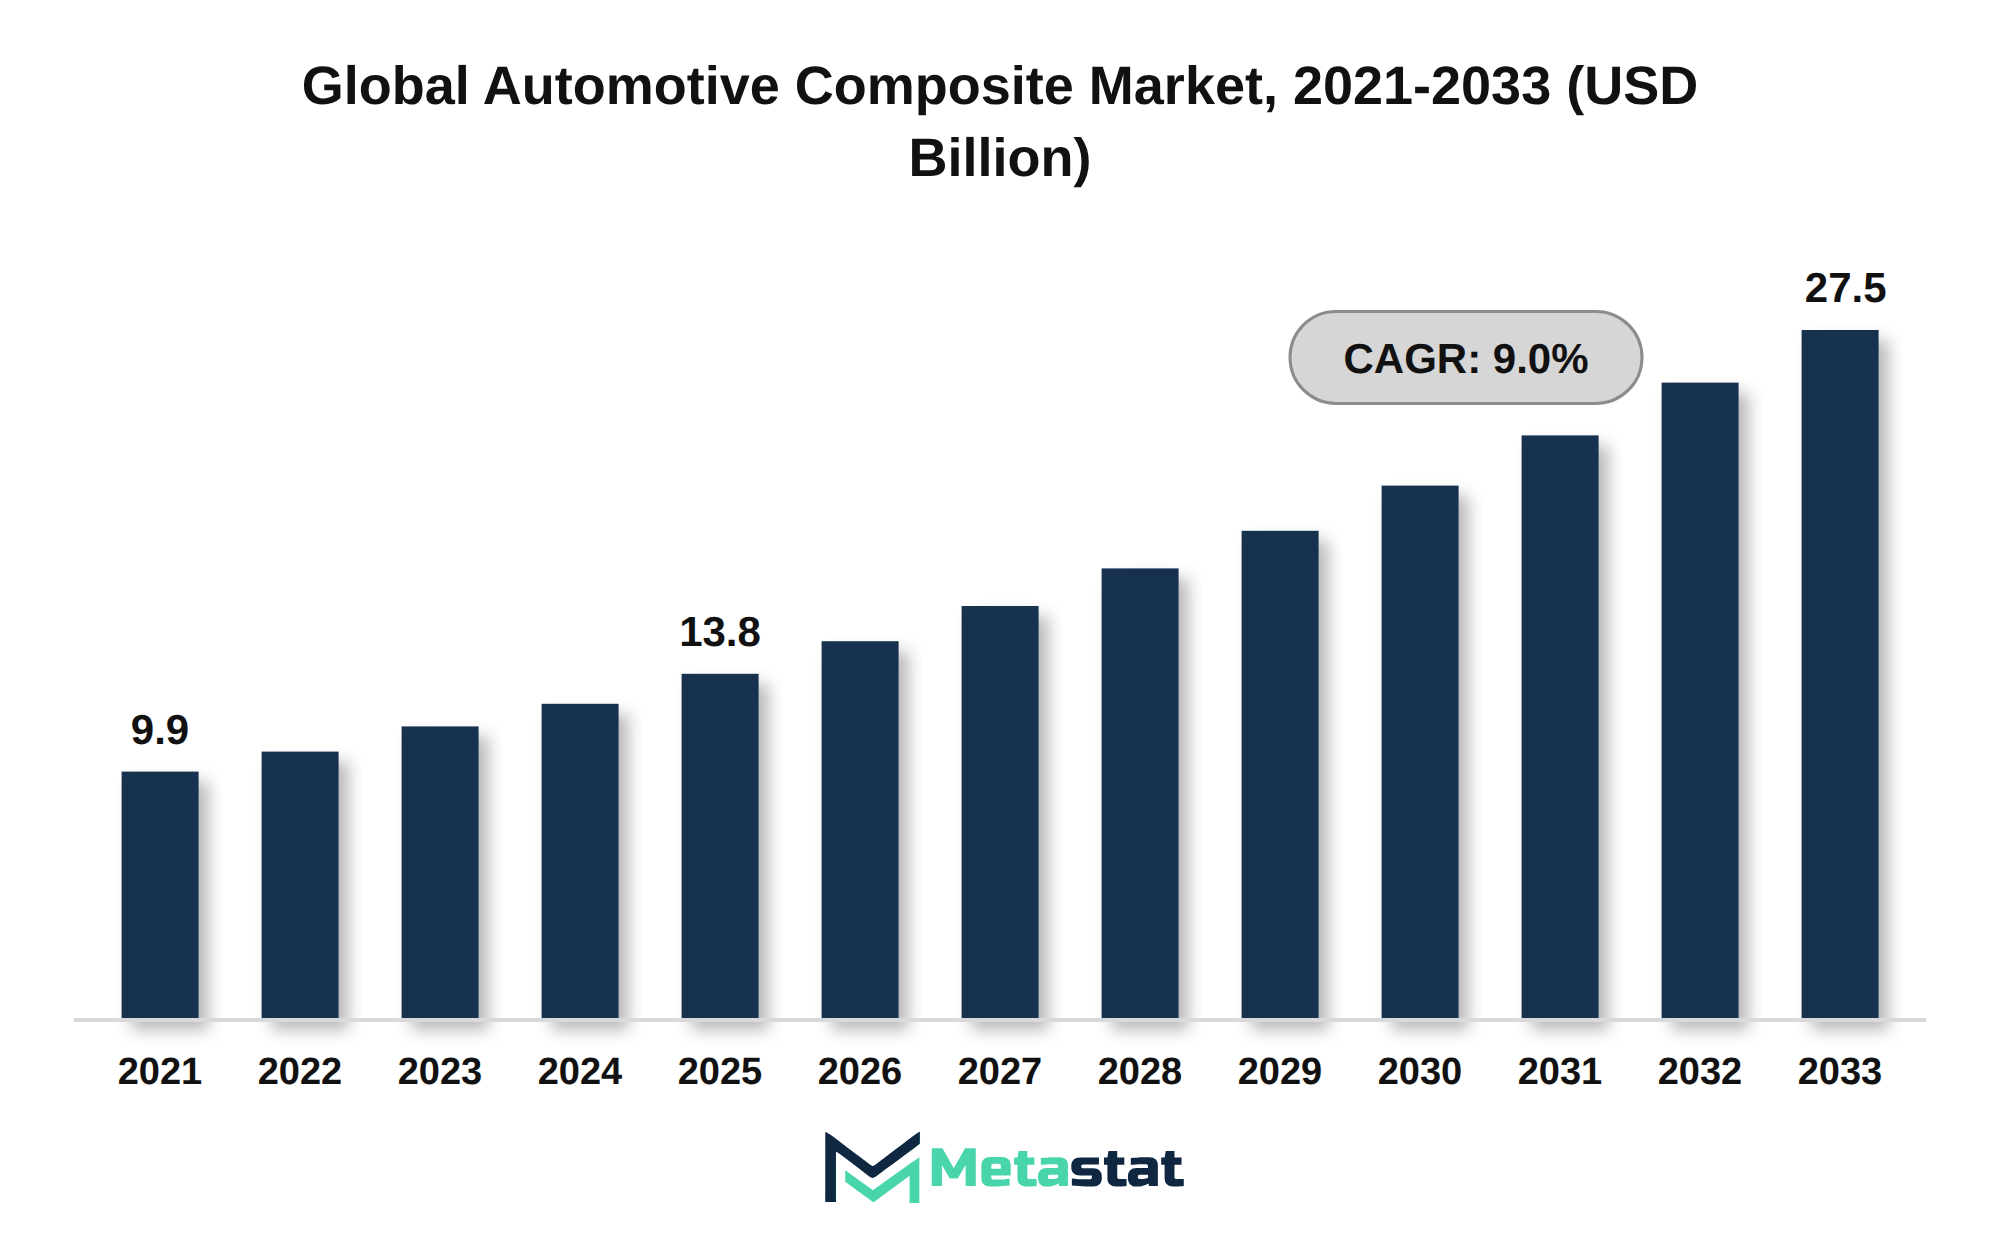
The global Automotive Composite market was valued at USD 13.8 billion in 2025 and is projected to reach USD 27.5 billion by 2033, growing at a CAGR of 9.0% over the forecast period.
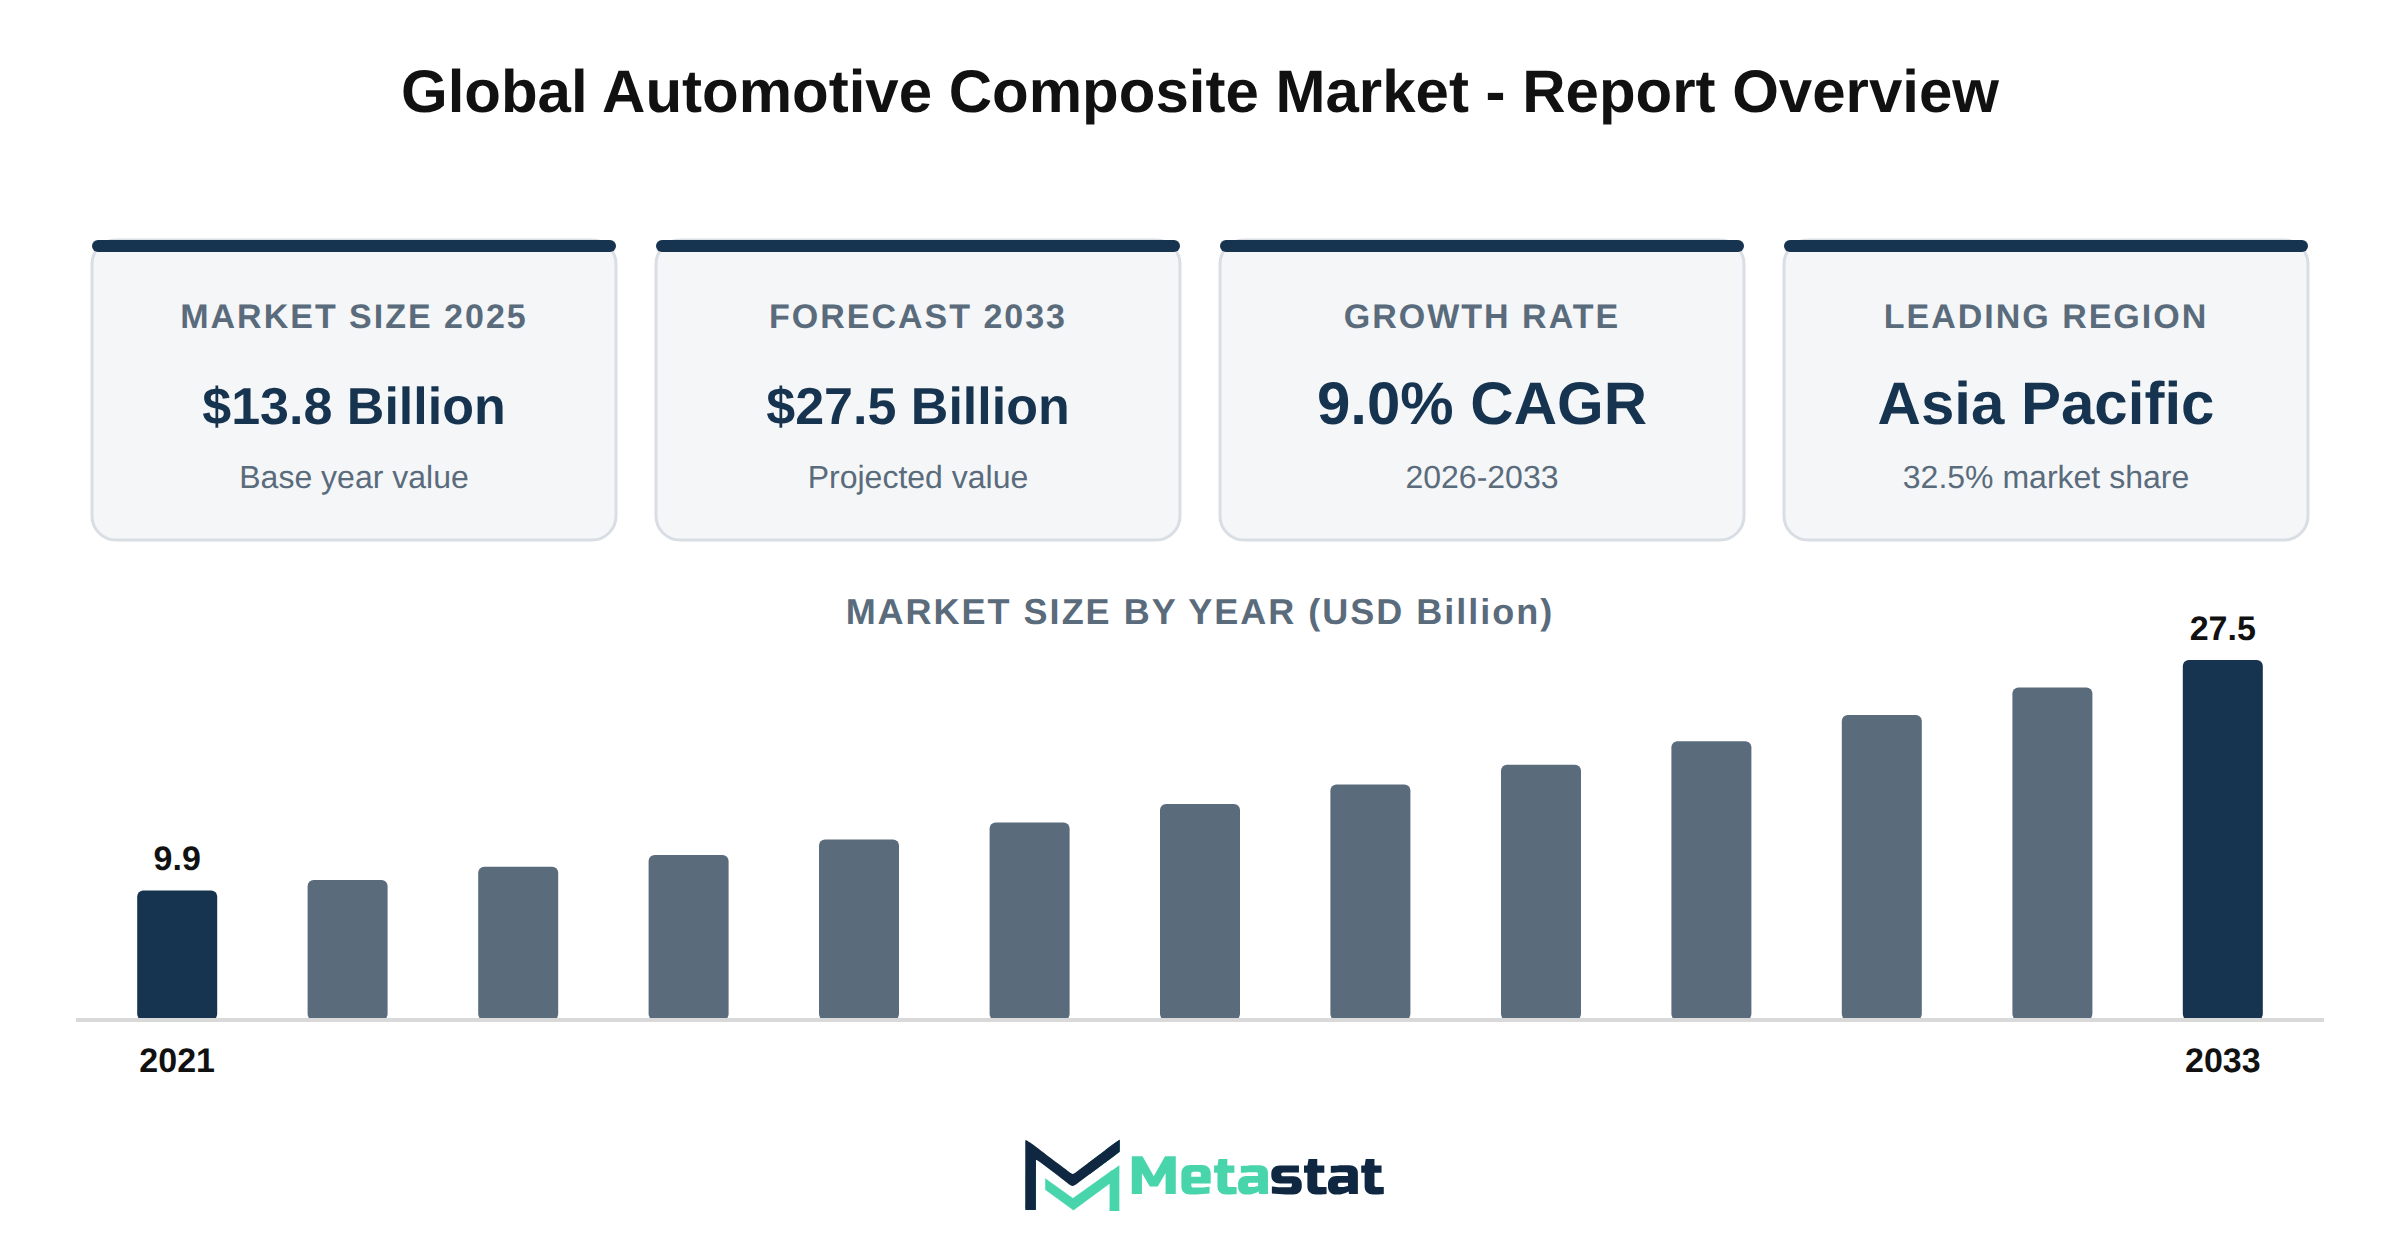
The global Automotive Composite market reached USD 13.8 billion in 2025 and is projected to grow to USD 27.5 billion by 2033, reflecting a compound annual growth rate (CAGR) of 9%. This expansion results from a significant shift towards lightweight vehicle designs, with rising automotive demand for carbon fiber and glass fiber composites contributing to this growth.
Growth in the electric vehicle sector accelerates the adoption of automotive composites, particularly in applications requiring enhanced performance and reduced weight. Opportunities arise in the development of EV battery enclosures and protection structures, which require innovative composite solutions. Thermoplastic composites gain traction in high-volume automotive manufacturing, offering versatility and efficiency in production processes.
Carbon fiber composites increasingly serve structural automotive applications, enhancing vehicle safety and durability. Glass fiber composites provide cost-effective solutions for vehicle lightweighting, enabling manufacturers to meet stringent fuel efficiency standards. Advanced manufacturing techniques, including high-pressure resin transfer molding (RTM) and compression molding, advance composite mass production capabilities, further supporting market growth.
Innovation in body-in-white and structural components highlights the potential of automotive composites in improving vehicle design and performance. The growing use of composites in chassis and suspension systems enhances vehicle stability and handling, while demand for composites in body panels and exterior applications continues to rise, driven by aesthetics and functionality.
Attention to recyclable and sustainable automotive composites increases within the industry, aligning with global environmental goals. Natural fiber composites expand into automotive interior applications, providing lightweight and eco-friendly alternatives. The cost of automotive composite materials and production economics significantly influence market dynamics, impacting OEM and Tier 1 composite sourcing strategies.
Recent developments in the automotive composite supply chain enhance material availability, while regulatory pressure for vehicle lightweighting and emissions reduction drives innovation. Challenges in recycling and end-of-life material management remain significant considerations for the industry, impacting the long-term sustainability of automotive composites.
In the Asia Pacific region, manufacturing and demand opportunities for automotive composites continue to grow, driven by increasing automotive production. North America experiences growth led by investments in electric vehicles and lightweighting technologies, while Europe's market is driven by sustainability initiatives and vehicle efficiency standards. The competitive landscape within the automotive composite market features ongoing supplier innovation, focusing on composite tooling, automation, and digital manufacturing.
The Automotive Composite market experiences significant trends shaping lightweight vehicle design, driven by increasing demand for performance and efficiency. The integration of carbon fiber and glass fiber composites is essential in meeting these requirements, resulting in lighter vehicles that enhance fuel efficiency and reduce emissions.
Electric vehicle growth serves because a catalyst for automotive composite adoption, with manufacturers seeking materials that support performance while addressing sustainability goals. The market sees opportunities in EV battery enclosures and protection structures, where advanced composite materials offer the necessary strength and lightweight properties.
Thermoplastic composites gain traction in high-volume automotive manufacturing due to their ease of processing and recyclability, aligning with industry shifts towards sustainable practices. Carbon fiber composites expand in structural automotive applications, delivering superior strength-to-weight ratios that benefit vehicle dynamics and safety.
Glass fiber composites support cost-effective vehicle lightweighting, providing a balanced solution for manufacturers striving to meet both performance and cost objectives. Advanced manufacturing techniques, including high-pressure resin transfer molding (RTM) and compression molding, drive the mass production of composites, improving efficiency and reducing production costs.
Innovation in body-in-white and structural components highlights the potential of automotive composites in enhancing overall vehicle design. The growing use of composites in chassis and suspension systems reflects a broader trend towards integrating lightweight materials into critical automotive structures, improving performance and handling.
Demand for automotive composites in body panels and exterior applications continues to rise, driven by aesthetic and functional considerations. The industry increasingly focuses on recyclable and sustainable materials, addressing environmental concerns while meeting regulatory requirements for vehicle lightweighting and emissions reduction.
Natural fiber composites expand their presence in automotive interior applications, offering a sustainable alternative that appeals to environmentally conscious consumers. The cost of automotive composite materials and production economics influences market dynamics, shaping sourcing strategies among OEMs and Tier 1 suppliers.
Recent developments in the automotive composite supply chain emphasize material availability and the need for innovation in sourcing strategies. Regulatory pressure for vehicle lightweighting and emissions reduction intensifies competition among manufacturers, prompting ongoing advancements in composite technologies.
Challenges related to automotive composite recycling and end-of-life materials persist, necessitating collaboration among stakeholders to develop effective solutions. The Asia Pacific region presents significant manufacturing and demand opportunities, driven by the rapid growth of automotive production and increasing investments in lightweight technologies.
North America leads the growth of the automotive composite market, propelled by investments in electric vehicles and lightweighting initiatives. Europe’s market is driven by sustainability efforts and a focus on vehicle efficiency, ensuring compliance with stringent regulatory standards.
The competitive landscape within the automotive composite sector highlights supplier innovation and the emergence of new applications. Composite tooling, automation, and digital manufacturing enhance production capabilities, allowing manufacturers to meet the evolving demands of the automotive industry.
Emerging applications for hybrid and advanced fiber composites present future growth opportunities within the automotive composite materials and components sector. Contract manufacturing opportunity mapping reveals potential for collaboration between OEMs and suppliers, facilitating the efficient delivery of composite solutions.
Automotive supplier qualification requirements evolve alongside market demands, necessitating robust strategies for quality assurance and compliance. The economics of prototype-to-low-volume programs influence decisions regarding outsourcing, driving manufacturers to seek partnerships that enhance flexibility and reduce time to market.
Composite tooling and finishing opportunities continue to expand, supporting the production of high-quality components. The localization potential in the UAE and GCC regions fosters regional growth, while the transfer of processes from aerospace to automotive sectors reflects broader trends in material applications.
Growth in the Automotive Composite market aligns closely with various macro-economic factors, including GDP growth and capital investment conditions. While economies expand, increased financial resources become available for automotive manufacturers to invest in advanced materials. Heightened venture funding further drives innovation within this sector, enhancing the development of composite technologies.
Shifting consumer behaviors, characterized by a growing preference for lightweight and fuel-efficient vehicles, contribute to rising demand for automotive composites. The automotive industry responds to these trends by integrating composites to reduce vehicle weight, thereby improving fuel economy and lowering emissions. This consumer-driven shift strengthens the market growth trajectory.
Operational productivity initiatives within the automotive sector support the adoption of composites. Manufacturers focus on optimizing production processes and reducing overhead costs, which enhances the economic viability of using advanced materials. The emphasis on cost-efficient manufacturing techniques facilitates wider adoption of automotive composites across various applications.
Digital transformation and technological integration play significant roles in market growth. Adoption of automation and sophisticated AI technologies allows for streamlined production processes and improved product quality. Manufacturers digitize legacy systems, and efficiencies gained from these advancements encourage the use of composites in automotive applications.
The Automotive Composite market benefits from advancements in technological integration, particularly automation, artificial intelligence, and software adoption. These innovations streamline production processes, reduce operational costs, and improve product quality. Enhanced manufacturing techniques, including automation, facilitate quicker output while maintaining high standards, attracting investment from manufacturers aiming to increase efficiency. Investment in these technologies supports firms in optimizing labor and resources, significantly impacting overall productivity.
Digital transformation initiatives reshape the Automotive Composite market by enabling more agile responses to consumer preferences and market demands. Companies incorporating AI and data analytics into their operations gain insights that drive innovation and help tailor products to meet evolving consumer behaviors. This trend enhances competitiveness and positions companies for growth in an increasingly demanding marketplace, driving further investment in research and development.
The push for technological integration influences supply chain resilience by strengthening collaboration among suppliers, manufacturers, and customers. A more digitized supply chain enhances visibility and reduces risks associated with disruptions, a crucial factor in the current global environment. Embracing these advancements positions the market for sustained growth, with firms leveraging technology to navigate challenges and seize opportunities effectively.
Regulatory compliance hurdles significantly impact the Automotive Composite market by increasing operational complexities and costs. Manufacturers face stringent regulations that require adherence to specific material standards, necessitating additional testing and certification processes. These requirements strain production timelines and divert resources from innovation to compliance management.
High capital investment requirements associated with advanced manufacturing technologies contribute to barriers in market entry and expansion. Companies allocate substantial financial resources to acquire state-of-the-art equipment and implement best practices. This financial burden limits the ability of smaller players to compete effectively, reinforcing the dominance of established firms.
Inflationary pressures exacerbate production costs, affecting profit margins across the market. Rising prices for raw materials and energy force manufacturers to pass costs onto consumers, leading to reduced demand for composite products. Supply chain disruptions stemming from geopolitical instability hinder the availability of essential materials, complicating production processes.
Technological obsolescence poses another challenge, driven by rapid advancements in composite materials and manufacturing processes that outpace existing technologies. Companies that invest in outdated systems face risks of reduced competitiveness in the Automotive Composite market. Cultural barriers and regional adoption resistors impact the implementation of composite solutions, particularly in markets with traditional material preferences.
Overall, these factors create a challenging environment for stakeholders in the Automotive Composite market, necessitating strategic approaches to navigate compliance and operational hurdles effectively.
Geopolitical tensions contribute to supply chain instability within the Automotive Composite market. Volatility in international trade relations, exacerbated by tariff friction and trade deficits, disrupts the flow of materials and components essential for production. This instability impacts manufacturers, increasing sourcing costs and complicating logistical operations.
Manufacturers face challenges in securing reliable feedstock due to geopolitical fragmentation. Regions involved in producing key materials, including carbon and glass fibers, experience varying degrees of export restrictions and tariffs, leading to delays in production timelines. These disruptions result in increased operational costs, forcing suppliers to reassess pricing strategies and manage their margins more effectively.
Technological disruptions add another layer of complexity. Evolving manufacturing processes require continuous investment in research and development, which strains resources for companies operating in an already volatile market. The need for interoperability between new technologies and existing systems complicates the integration of advanced materials. This challenge is relevant for companies looking to maintain competitiveness while adapting to innovations in composite manufacturing.
Environmental sustainability demands heighten market challenges, pushing companies to align with decarbonization goals and manage lifecycle footprints. Compliance with tightening global standards increases operational overhead, requiring significant investment in sustainable practices. This situation diverts resources away from other necessary areas, including talent retention and skill development, further complicating the competitive landscape within the automotive sector.
Overall, the combination of geopolitical tensions, technological challenges, and sustainability demands creates a challenging environment for the Automotive Composite market. Stakeholders navigate these complexities to ensure stability and growth in an increasingly uncertain global landscape.
The Automotive Composite market presents significant opportunities driven by emerging regional demands and evolving consumer preferences. The increasing focus on lightweight materials enhances performance and efficiency across various vehicle types, aligning with the automotive industry's shift towards sustainability and fuel efficiency. Infrastructure modernization across critical markets supports the integration of advanced manufacturing processes, facilitating the growth of automotive composites in vehicle production. Geographical expansion into developing regions introduces new customer bases, spurring demand for innovative composite solutions tailored to local needs.
Technological disruptions play a vital role in shaping the market landscape. Advancements in composite materials, including carbon fiber and natural fibers, enhance product performance while reducing environmental impact. Digital transformation initiatives within manufacturing processes optimize production capabilities, reduce costs, and improve quality. Innovations in product integration and niche applications allow automotive composites to penetrate various vehicle segments, further expanding market reach.
Sustainability imperatives drive manufacturers to align with eco-friendly practices and ESG-driven objectives, influencing procurement decisions and supply chain strategies. The market experiences growth through strategic consolidation and cross-industry collaborations that promote innovation and share resources. Evolving buying behaviors reflect a shift towards digital procurement, enabling more efficient purchasing processes and enhancing competition among suppliers.
Asset life-cycle extensions and maintenance upgrades enable the automotive sector to maximize the value of existing products, promoting the adoption of advanced composite solutions. Localization strategies support supply chain resilience and reduce dependency on imports, enhancing operational flexibility. These dynamics contribute to the robust expansion of the automotive composite market, positioning it for sustained growth through 2033.
The Global Automotive Composite market is segmented based on Fiber Type, Resin Type, Application, and Manufacturing Process.
Demand for Glass Fiber Composites within the Automotive Composite market stems from the need for lightweight materials that enhance fuel efficiency and reduce emissions. These composites offer high strength-to-weight ratios, which play a vital role in improving vehicle performance while maintaining structural integrity. The automotive industry's ongoing transition towards electrification drives this demand, because manufacturers seek to optimize energy efficiency.
Glass Fiber Composites segment is valued at USD 8.3 billion in 2026 and is projected to reach USD 14.1 billion by 2033, at a CAGR of 7.8% during the forecast period. This growth reflects the segment's adaptation to evolving automotive design requirements, including the increased use of composites in safety-critical applications including body and exterior panels. Regulatory compliance concerning vehicle emissions and safety standards enhances the adoption rate of these materials, influencing manufacturers to integrate them into their production processes.
The segment expansion benefits from advancements in manufacturing technologies, including compression molding and injection molding techniques that streamline production and enhance material properties. Continuous improvements in resin formulations and fiber treatments contribute to the increased durability and performance of Glass Fiber Composites, positioning them because a preferred material choice within various automotive applications. Overall, the Glass Fiber Composites segment's growth trajectory within the Automotive Composite market aligns with broader industry trends focusing on sustainability and efficiency.
Growth in the Carbon Fiber Composites segment is driven by increasing demand for lightweight materials that enhance fuel efficiency in vehicles. This segment benefits from advancements in manufacturing processes, which improve performance and reduce the overall cost of carbon fiber materials. Adoption occurs primarily in high-performance automotive applications, where vehicles require enhanced strength-to-weight ratios and improved durability. The segment is projected to reach USD 9 billion by 2033, at a CAGR of 10.6% during the forecast period.
Technological maturation in carbon fiber production has led to the development of more accessible and cost-effective solutions. Original equipment manufacturers integrate these composites into their product lines, enhancing vehicle performance and safety features. Ongoing evolution in product design and engineering continues to expand the applications of carbon fiber composites, particularly in structural components and body-in-white applications. Regulatory compliance standards focusing on emissions and safety drive further investment in this market segment.
Market players actively invest in research and development to innovate new applications for carbon fiber composites, fueling competition and market dynamics. Strategic opportunity windows arise from the increasing consumer preference for electric and hybrid vehicles, where lightweight materials play a critical role in optimizing battery life and overall vehicle efficiency. The Carbon Fiber Composites segment demonstrates strong potential for growth within the Automotive Composite market, driven by its unique properties and expanding applications.
Natural Fiber Composites have gained traction within the Automotive Composite market due to rising consumer demand for eco-friendly materials. The shift towards sustainable practices prompts manufacturers to explore alternatives that reduce environmental impact while maintaining performance. This segment is expected to reach USD 1.3 billion by 2033, reflecting growing acceptance of natural fibers in vehicle production.
Technological maturation significantly influences the adoption of Natural Fiber Composites. Innovations in processing techniques enhance the strength and durability of these materials, making them competitive against traditional composites. The development of next-generation upgrades and product evolution encourages further investment in this segment, motivating manufacturers to integrate natural fibers into various applications.
Downstream applications of Natural Fiber Composites include body and exterior panels, where lightweight and sustainable solutions align with automotive manufacturers' goals of reducing overall vehicle weight. Consumption shifts towards greener products arise from increasing consumer awareness of environmental issues, reinforcing the trend toward natural fiber utilization.
Regulatory compliance standards regarding emissions and material safety further drive market growth. Manufacturers face pressures related to cost structures and pricing volatility; however, the benefits of adopting Natural Fiber Composites, including enhanced marketability and alignment with sustainable practices, create significant strategic opportunities.
Raw material sourcing for natural fibers presents unique challenges, including supply chain resilience and potential vulnerabilities. Nevertheless, manufacturers actively explore alternatives and partnerships to mitigate risks associated with sourcing. The segment's adaptability to changing market dynamics positions it favorably for future growth in the Automotive Composite market.
Demand for Aramid Fiber Composites continues to increase, driven by their strong strength-to-weight ratio and resistance to heat and chemicals, making them suitable for various automotive applications. The automotive industry increasingly incorporates these composites into high-performance parts, including protective gear and structural components, enhancing vehicle safety and efficiency. Aramid Fiber Composites segment is projected to grow at a CAGR of 8% during the forecast period. Investment in research and development facilitates advancements in manufacturing processes, leading to improved properties and cost-effectiveness, thus appealing to manufacturers focused on innovation and sustainability.
Adoption of Aramid Fiber Composites aligns with the industry's shift towards lightweight materials, which directly contribute to enhanced fuel efficiency and reduced emissions. Stringent regulations regarding vehicle emissions and safety standards further increase the demand for these composites. Consequently, automotive manufacturers prioritize sourcing materials that align with sustainability goals and regulatory compliance, positioning Aramid Fiber Composites because a strategic choice. While the Automotive Composite market evolves, innovations in production techniques enhance the performance and versatility of aramid composites, reinforcing their role in future automotive applications.
Interest in Basalt Fiber Composites within the Automotive Composite market stems from their combination of beneficial properties, including lightweight, high strength, and thermal stability. Demand for these composites arises from the automotive industry's pursuit of performance efficiency and reduced weight in vehicle components. Increasing regulatory standards for emissions and fuel consumption drive manufacturers towards lightweight materials, propelling the adoption of basalt fibers.
Technological maturation in the manufacturing of Basalt Fiber Composites continues to enhance their performance attributes, enabling broader applications across various automotive components. Innovations in production techniques improve the mechanical properties of basalt composites, resulting in expanded use in structural applications and body panels, where durability is crucial.
Downstream application dynamics show a growing preference for sustainable materials, aligning with the automotive sector's shift towards eco-friendly practices. The evolving consumption landscape prioritizes materials that contribute to weight reduction and energy efficiency, positioning basalt fibers favorably in the market. Regulatory compliance standards emphasizing sustainability further increase the importance of these composites within vehicle design.
Certain challenges persist, including raw material sourcing and pricing volatility. Fluctuations in the availability of basalt fibers impact production timelines and costs, influencing manufacturers' pricing strategies. Addressing these issues enhances supply chain resilience and secures a competitive standing in the market.
Strategic opportunity windows exist for investments targeting the development and commercialization of advanced basalt composite applications. Initiatives aimed at integrating basalt fibers in high-performance automotive components create significant growth potential. Collaborations among stakeholders facilitate knowledge transfer and innovation in the use of basalt composites, further shaping the future of the Automotive Composite market.
Hybrid Fiber Composites represent a significant evolution in material science within the Automotive Composite market. The combination of various fibers enhances mechanical properties, providing manufacturers with superior materials for lightweight applications. Increasing demand for fuel-efficient vehicles drives the adoption of these composites, because manufacturers focus on reducing overall vehicle weight without compromising structural integrity. The automotive sector's shift toward sustainability encourages the incorporation of hybrid fibers, contributing to lower emissions and improved performance.
Technological advancements facilitate the development of hybrid fiber composites that meet diverse performance requirements across different automotive applications. Ongoing research leads to improvements in fiber combinations and processing methods, resulting in enhanced mechanical properties and cost efficiencies. End-users benefit from these innovations, since hybrid composites enhance performance in critical components including body panels and structural elements. The automotive market's competitive landscape encourages continuous investment in research and development, focusing on optimizing hybrid fiber formulations to achieve specific performance targets.
Regulatory compliance standards increasingly emphasize lightweight materials to support emission reduction goals. This shift creates strategic opportunities for hybrid fiber composites, because they offer a sustainable solution that aligns with industry standards. Cost structures associated with hybrid fiber composites demonstrate competitive advantages over traditional materials, particularly considering the long-term savings associated with fuel efficiency and vehicle performance. The market landscape reflects a growing acceptance of these materials, driven by their ability to meet both performance and regulatory demands.
Interest in specialty fibers, including UHMWPE, within the Automotive Composite market derives from their unique properties, including high strength-to-weight ratios and strong chemical resistance. These characteristics cater to the increasing demand for lightweight materials in automotive applications, particularly driven by manufacturers' emphasis on efficiency and performance. The focus on sustainability and environmental considerations influences the adoption of specialty fibers, owing to their advantageous mechanical properties coupled with reduced environmental impact compared to traditional materials.
Technological maturation fuels innovation within the segment, enabling enhancements in fiber processing and integration techniques. Next-generation upgrades in manufacturing processes enhance the performance of automotive components, aligning with the industry's shift towards advanced materials. Applications across various vehicle parts, including battery enclosures and structural components, highlight the versatility of specialty fibers in meeting diverse automotive requirements. This versatility supports the growing need for innovative solutions.
Regulatory compliance standards increasingly emphasize material safety and environmental considerations. This regulatory landscape encourages manufacturers to explore alternative materials like specialty fibers, which align with sustainability initiatives. Downstream application dynamics indicate a growing trend towards lightweighting and improved fuel efficiency, reinforcing the need for advanced materials in vehicle design and production.
Market participants face challenges related to cost structures and pricing volatility, particularly regarding raw material sourcing and supply chain stability. Strategic opportunity windows emerge for players invested in research and development, focusing on innovative applications and processing techniques for specialty fibers. The market reflects an evolving environment, with potential disruptions arising from advancements in alternative materials, highlighting the importance of continuous adaptation and investment in the Automotive Composite market.
Valued at USD 4.2 billion in 2026, the Polypropylene (PP) segment is projected to reach USD 8 billion by 2033, reflecting a CAGR of 9.6% during the forecast period. Strong demand arises from the automotive industry's need for lightweight materials that enhance fuel efficiency and reduce emissions. Increased adoption of polypropylene composites in applications including body and exterior panels supports this trend, aligning with broader industry goals for sustainability.
Advancements in recycling technologies serve because catalysts for segment expansion, improving the environmental profile of polypropylene composites. This factor appeals to manufacturers and consumers prioritizing eco-friendly solutions. The growing trend towards electric vehicles (EVs) leads to evolving product specifications, driving demand for innovative materials in vehicle construction.
Technological maturation within the segment enhances product offerings, enabling the development of high-performance materials that compete with traditional metals and other composites. End-use dynamics shift towards materials that provide structural integrity and aesthetic appeal, particularly in interior components of vehicles.
Pricing volatility and margin pressures impact the segment, reflecting fluctuations in raw material sourcing and production costs. Supply chain resilience plays a critical role, with manufacturers seeking stable partnerships for polypropylene procurement. Strategic opportunities arise from the increasing focus on lightweight solutions, positioning the segment favorably within the Automotive Composite market.
Growth in the Polyamide (PA) segment reflects increasing demand for high-performance materials in automotive applications. This segment is estimated to reach USD 4.2 billion by 2033, at a CAGR of 9.7% during the forecast period. Rising emphasis on lightweighting and fuel efficiency drives manufacturers to explore advanced material solutions. The automotive industry prioritizes materials that offer excellent mechanical properties and processability, positioning Polyamide (PA) because a preferred choice. Enhanced durability and resistance to automotive fluids and chemicals expand its applicability in various vehicle components.
Innovation in manufacturing technologies supports the segment's expansion. Continuous advancements in production processes improve efficiency and reduce the costs associated with Polyamide (PA) composites. Increased investment in R&D facilitates the development of next-generation materials, which contribute to the growing adoption of Polyamide (PA) in the Automotive Composite market. The shift towards electric vehicles further increases demand due to the lightweight requirements of EVs.
Regulatory compliance regarding emissions and safety standards influences product specifications, compelling manufacturers to adopt materials like Polyamide (PA) that meet these requirements. Supply chain resilience remains critical, with raw material sourcing impacting availability and pricing of Polyamide (PA) composites. The strategy to mitigate substitution risks will be essential for maintaining competitive positioning. Overall, the segment displays growth potential, driven by a combination of technological maturation, evolving consumer preferences, and stringent regulatory landscapes.
Growing applications in various automotive components drive demand for epoxy resins within the Automotive Composite market. Epoxy resins exhibit excellent adhesive and mechanical properties, making them suitable for body and structural components. Their strong resistance to environmental factors enhances durability, which attracts manufacturers aiming for longevity in vehicle lifecycle performance.
Market dynamics indicate a shift toward lightweight materials, particularly in electric vehicles. Higher adoption rates of epoxy resins arise from their lightweight nature, which improves fuel efficiency and lowers emissions. Regulatory compliance standards promoting sustainable practices further drive the shift towards these composites.
Investment in research and development significantly influences the technological maturation of epoxy formulations. Innovations in composite technologies enhance processing efficiency and product performance, leading to wider use in advanced automotive applications. The epoxy segment is expected to reach USD 5.9 billion by 2033, reflecting strong growth potential driven by these advancements.
Market participants face increasing pressure from pricing volatility and raw material sourcing challenges. Fluctuations in resin prices impact production costs, necessitating strategic sourcing and supply chain resilience. Manufacturers focusing on long-term partnerships with suppliers mitigate risks associated with material availability and pricing.
Overall, the epoxy segment's expansion aligns with evolving automotive design trends and consumer preferences for performance and sustainability. Increased collaboration among stakeholders in the automotive ecosystem will enhance the segment's adaptability to changing market conditions and consumer demands.
Growth in the Unsaturated Polyester segment reflects an increasing demand for cost-effective, lightweight materials in various automotive applications. This growth aligns with the trend towards energy-efficient vehicles, where weight reduction enhances fuel efficiency. Unsaturated polyester resins provide favorable mechanical properties, making them suitable for a wide range of applications including body panels and structural components.
Adoption rates in the Automotive Composite market are further stimulated by advancements in manufacturing processes that enhance the efficiency of unsaturated polyester production. These innovations lead to improved resin formulations, resulting in better performance characteristics and broader application scopes. End-use dynamics indicate a significant shift towards high-performance composite materials in automotive manufacturing, driving the demand for unsaturated polyesters.
The Unsaturated Polyester segment is projected to grow at a CAGR of 7.1% during the forecast period. This trajectory suggests strong interest from manufacturers seeking to leverage the benefits of these materials in a competitive landscape. The segment faces challenges related to pricing volatility and margin pressures, primarily attributed to fluctuations in raw material costs. Strategic opportunities arise from the potential to innovate and develop high-value applications.
Increasing regulations focused on environmental sustainability further influence the market. Compliance with these standards compels manufacturers to adopt eco-friendly materials, boosting the attractiveness of unsaturated polyesters. The segment's evolution reflects broader consumption shifts towards sustainable practices in vehicle production, ensuring its relevance in the evolving Automotive Composite market.
Demand for Vinyl Ester within the Automotive Composite market arises from its advantageous chemical properties, including corrosion resistance and high strength-to-weight ratio. The segment experiences growth owing to its suitability in various automotive applications, particularly in environments requiring durability and chemical resilience. Adoption of Vinyl Ester aligns with market trends favoring lightweight materials that enhance fuel efficiency and performance in vehicles.
Technological maturation plays a critical role in the evolution of Vinyl Ester, with advancements in manufacturing techniques contributing to improved material performance and cost-effectiveness. Innovations in the formulation and processing of Vinyl Ester contribute to greater application versatility, driving interest from automotive manufacturers seeking to optimize material properties for specific use cases. This dynamic fosters a competitive edge in the market.
End-use dynamics reflect a shift towards composite materials, driven by environmental regulations and the push for sustainable manufacturing practices. Regulatory compliance standards increasingly favor materials that reduce emissions and enhance recyclability, positioning Vinyl Ester because a viable option for manufacturers aiming to meet these requirements.
Consumption shifts within the automotive sector further influence demand for Vinyl Ester. While vehicle designs evolve towards greater use of composites, the segment benefits from increased integration in structural components and body panels. Capital investment outlook remains positive, with stakeholders recognizing potential returns from expanding production capabilities to meet growing demand.
Growing applications of Polyurethane (PU) in the Automotive Composite market arise from its favorable properties, including flexibility, durability, and resistance to various environmental factors. Demand for PU arises primarily in interior components, where adaptability to different designs and finishes enhances vehicle aesthetics and functionality.
Technological maturation significantly influences the segment's expansion, with advancements in manufacturing processes enabling the production of more complex and refined PU components. Innovations, including improved formulations that enhance performance and reduce weight, attract automotive manufacturers seeking to optimize vehicle efficiency and safety.
Regulatory compliance standards significantly influence the PU segment. Stringent environmental regulations drive demand for sustainable and eco-friendly materials, prompting manufacturers to develop PU formulations with lower volatile organic compounds (VOCs). Such developments align with consumer preferences for greener automotive solutions, stimulating market growth.
Pricing volatility remains a challenge for the PU segment, influenced by fluctuations in raw material costs. Despite these pressures, strategic opportunity windows exist for manufacturers to invest in research and development, potentially leading to the introduction of next-generation PU products. Long-term investments in innovative technologies and sustainable practices enhance competitive positioning within the market.
Polyphenylene Sulfide (PPS) materials play a crucial role in the Automotive Composite market, driven by their excellent thermal stability and chemical resistance. Increasing adoption in automotive applications, particularly in electrical and electronic components, reflects the growing demand for high-performance materials capable of withstanding harsh environments. This segment experiences expansion due to innovations in processing technologies, which enhance the usability of PPS in various applications.
Shifts in consumer preferences toward lightweight materials further increase the demand for PPS. Manufacturers seek to improve fuel efficiency and reduce emissions, highlighting the contribution of PPS to lightweight automotive structures. Regulatory compliance standards relating to emissions and energy efficiency create additional impetus for the adoption of PPS, making it attractive for automotive applications that prioritize sustainability.
Cost structures associated with PPS production, including raw material sourcing and processing, influence market dynamics. Pricing volatility, particularly concerning the availability of precursor materials, affects profit margins for producers. Strategic opportunity windows arise for manufacturers that secure reliable raw material sources and develop innovative production techniques to mitigate cost pressures. Overall, the integration of PPS into automotive composites reflects the industry's response to evolving technological demands and regulatory landscapes.
Demand for Polyaryletherketones (PEEK, PEKK and Other PAEK) within the Automotive Composite market arises from their superior thermal and chemical resistance, making them suitable for high-performance applications. These materials are essential in various automotive components, particularly in environments requiring durability and stability. The automotive industry increasingly seeks materials that enhance vehicle efficiency while maintaining safety standards. Regulatory compliance standards regarding emissions and fuel efficiency drive the adoption of advanced materials like PAEK, which contribute to lighter and more efficient vehicle designs.
Technological maturation in the production of Polyaryletherketones enables manufacturers to create components with precise specifications while reducing waste. The evolution of these materials aligns with shifts in end-use dynamics, where manufacturers shift towards lightweight and high-strength composites to improve fuel economy and performance. Investments in research and development support innovations that enhance the properties of PAEK, leading to its growing acceptance across various automotive applications.
The segment faces competitive pressure from alternative materials, including traditional polymers and metals. However, the unique properties of PAEK, including a high strength-to-weight ratio and excellent thermal stability, position it favorably in the market. Strategic opportunity windows arise from automotive manufacturers exploring advanced materials to meet changing consumer preferences and stricter environmental regulations. Capital investment in production capabilities remains critical for companies aiming to secure a strong foothold in the Automotive Composite market.
Increasing interest in Phenolic Resins reflects their unique properties, including excellent thermal stability, chemical resistance, and mechanical strength. These attributes make phenolic resins suitable for a variety of automotive applications, enhancing structural integrity and safety. The automotive industry's growing focus on lightweight materials aligns with the characteristics of phenolic resins, enabling improved fuel efficiency and reduced emissions in vehicles.
Technological advancements in resin formulations contribute to the ongoing evolution of phenolic resins, facilitating their integration into modern production processes. The market faces consumption shifts attributed to manufacturers prioritizing sustainable materials, driving research into bio-based phenolic resins that align with environmental standards. Regulatory compliance regarding emissions and material safety influences the adoption of these resins within the automotive sector.
Supply chain resilience remains critical for phenolic resins, particularly concerning raw material sourcing and logistics vulnerabilities. Producers emphasize securing stable supplies of phenolic compounds to mitigate potential disruptions. Market players explore alternative sourcing strategies and partnerships to enhance supply chain robustness.
Strategic opportunity windows arise from the demand for phenolic resins in next-generation automotive applications, including electric vehicles. Automotive manufacturers increasingly seek lightweight, efficient materials. Phenolic resins are positioned favorably within the Automotive Composite market, offering significant benefits in performance and sustainability.
Distinct applications of acrylic and specialty thermoplastics in the Automotive Composite market stem from their advantageous properties, including lightweight, durability, and resistance to various environmental factors. These materials contribute to innovations in automotive design, particularly in enhancing fuel efficiency and overall vehicle performance. An increasing focus on sustainability drives interest in these materials, aligning with the automotive industry's shift towards eco-friendly solutions.
The adoption of polymer blends and composites containing acrylic and specialty thermoplastics creates opportunities for enhanced performance in automotive parts, particularly those subjected to high-temperature conditions and mechanical stress. Manufacturers explore next-generation upgrades that incorporate these materials, emphasizing weight reduction and improved energy efficiency.
Downstream applications see a rising trend in vehicle interiors and exterior components, where aesthetics and functionality converge. The market's evolving dynamics reflect a broader acceptance of these materials across various automotive segments, reinforcing their importance in modern vehicle manufacturing.
Regulatory compliance standards further encourage the utilization of acrylic and specialty thermoplastics due to their recyclable nature, positioning them favorably with stringent environmental regulations. The market landscape reflects a commitment to sustainable practices, with manufacturers prioritizing materials that contribute to lower environmental impact and enhanced recyclability.
Investment in research and development advances the capabilities of acrylic and specialty thermoplastics, driving innovation and competitive differentiation. Strategic opportunities lie within the development of specialized formulations that meet the specific requirements of automotive applications, ensuring alignment with market needs and consumer preferences.
Valued at USD 3 billion in 2026, the Body and Exterior Panels segment is projected to reach USD 4.9 billion by 2033, reflecting a CAGR of 7.4% during the forecast period. Demand for lightweight materials within the Automotive Composite market drives growth in this segment, supported by the automotive industry's shift towards enhancing fuel efficiency and reducing emissions. Increasing consumer preferences for vehicle performance and aesthetics lead manufacturers to adopt innovative materials for body and exterior applications.
Technological advancements in composite materials enhance durability and design flexibility, allowing for more complex shapes and structures. Regulatory compliance regarding emissions and sustainability further increases the adoption of advanced composites, because automotive manufacturers align with global environmental standards. The segment's expansion is supported by investments in research and development, aiming to improve the mechanical properties and cost-effectiveness of composites.
Shifts in consumer demand for electric vehicles significantly influence the segment, because lighter materials contribute to the overall efficiency and range of electric vehicles. This alignment with market trends positions the Body and Exterior Panels segment because crucial within the broader Automotive Composite market, attracting substantial capital investments from key players aiming to capture emerging opportunities.
Segment growth continues to accelerate with increasing applications in lightweight vehicle construction. Automotive manufacturers emphasize structural integrity and fuel efficiency, driving demand for advanced materials in body-in-white and structural components. Innovations in composite materials enhance the strength-to-weight ratio, making them ideal for meeting rigorous safety standards while reducing vehicle weight.
The body-in-white and structural components segment is estimated to reach USD 4.9 billion by 2033, at a CAGR of 9.8% during the forecast period. This growth stems from stringent regulations regarding emissions and fuel efficiency across major automotive markets. Manufacturers increasingly rely on composites to achieve compliance with evolving regulations while enhancing vehicle performance.
The pursuit of technological advancements fuels segment expansion. New manufacturing processes, including compression molding and injection molding, optimize production efficiency and reduce costs. These developments enable manufacturers to scale production while maintaining high standards for durability and performance. Increased adoption of composite materials in the automotive sector results from these factors.
Market dynamics reflect a shift in consumer preferences toward electric vehicles, which further drives demand for lightweight and high-strength materials. The automotive composite market anticipates substantial investments in R&D aimed at developing next-generation composites tailored for specific applications in modern vehicles. This trend presents strategic opportunities for companies focused on innovation within the automotive industry.
Overall, continued advancements in composite technologies and alignment with regulatory demands position the body-in-white and structural components segment for growth within the automotive composite market. While manufacturers adapt to changing market conditions, investments in advanced materials will likely play a critical role in shaping future vehicle designs.
Growth within the Automotive Composite market is influenced by increasing demand for lightweight, high-strength materials in various applications, particularly in chassis and suspension components. The pursuit of enhanced performance and fuel efficiency drives manufacturers to integrate advanced composite materials, which deliver superior strength-to-weight ratios while reducing overall vehicle weight.
Chassis and suspension components face a transition toward greater adoption of composites due to their ability to improve vehicle dynamics and safety. Regulatory compliance regarding emissions and fuel economy standards intensifies the focus on lightweight materials that decrease vehicle weight without compromising structural integrity. Consequently, automotive manufacturers invest in innovative composite materials to enhance product offerings and competitive positioning.
Cost structures and pricing volatility surrounding raw materials significantly impact the growth trajectory of this segment. Fluctuations in the prices of key materials create margin pressures for manufacturers, necessitating strategic sourcing and supply chain management to maintain profitability. Competition among suppliers drives innovation, resulting in the development of next-generation composites tailored for specific automotive applications.
Technological maturation in the manufacturing processes of composite materials supports the expansion of this segment. Advances in molding techniques, including injection molding and compression molding, enhance efficiency and scalability, allowing for more widespread adoption of composites in chassis and suspension components. Increased investment in R&D further supports product evolution, enabling the introduction of advanced composites that offer improved performance and durability.
By 2033, the Chassis and Suspension Components segment is projected to reach USD 3.2 billion, reflecting the overall upward trend in the Automotive Composite market. This growth aligns with heightened interest in sustainability and performance, highlighting the vital role of composite materials in shaping the future of automotive engineering.
Growing demand for lightweight materials drives interest in the Interior Components segment of the Automotive Composite market. Consumers increasingly seek vehicles that enhance fuel efficiency while maintaining performance levels. The segment is projected to grow at a CAGR of 7.5% during the forecast period. Manufacturers focus on integrating advanced composite materials to meet these performance and weight reduction goals.
Technological maturation in composite manufacturing significantly influences the expansion of the Interior Components segment. Innovations in material properties, including enhanced strength-to-weight ratios, lead to the adoption of composites in various interior applications. These advancements enable the production of complex shapes and designs, enhancing aesthetic appeal while reducing vehicle weight.
Regulatory compliance standards concerning emissions and fuel efficiency drive the demand for composites in the automotive sector. Stricter regulations necessitate the adoption of lightweight materials, positioning composites because an effective solution for manufacturers seeking to meet these requirements. Compliance with these regulations creates a strategic opportunity for investment in composite technologies.
Cost structures associated with raw materials impact pricing dynamics within the segment. Fluctuations in pricing for key materials, including carbon fibers and resins, influence overall production costs. Manufacturers focus on sourcing strategies to mitigate these impacts, aiming for supply chain resilience to ensure stable pricing and availability of essential materials.
Downstream application dynamics shape the demand trajectory for composites in interior components. The automotive industry increasingly incorporates composite materials into seating, dashboard structures, and trim elements. This trend reflects a shift towards higher quality, more durable options that enhance consumer satisfaction while adhering to performance standards. The integration of composites into these applications supports overall vehicle performance and consumer preferences.
Strategic opportunity windows arising from advancements in composite technologies encourage manufacturers to explore new applications within the Interior Components segment. Continuous product evolution ensures that companies remain competitive within the automotive landscape, capitalizing on emerging trends and consumer preferences.
Increasing focus on vehicle efficiency significantly drives demand for lightweight materials in the automotive sector. The push for reductions in carbon emissions encourages manufacturers to adopt advanced materials, leading to heightened interest in composites for underbody and aerodynamic components. These materials contribute to improved fuel efficiency and performance, aligning with global sustainability goals.
Technological advancements enable the development of next-generation composites tailored for specific applications. Innovations in resin formulations and fiber types enhance the performance characteristics of underbody components, including vibration dampening, thermal resistance, and structural integrity. Automotive manufacturers recognize the benefits of integrating these materials into their designs, translating to competitive advantages in the market.
The segment's evolution reflects a response to regulatory compliance standards and safety requirements. Stringent regulations regarding vehicle weight and emissions necessitate ongoing advancements in material technologies. Compliance with these standards encourages investment in research and development, creating a cycle of innovation within the automotive composite market.
Cost structures and pricing volatility play a significant role in shaping decisions within this sub-segment. Manufacturers navigate fluctuating raw material prices while optimizing production costs. Efficient supply chain management becomes essential to mitigate logistical vulnerabilities and ensure consistent sourcing of high-quality materials, thereby maintaining profitability.
Strategic opportunity windows arise from increasing consumer preferences for electric and hybrid vehicles. The shift towards electrification necessitates lightweight components for enhanced range and efficiency, driving demand for composites in underbody and aerodynamic applications. Manufacturers who align their offerings with these evolving consumer dynamics are positioned for growth within the automotive composite market.
Increasing focus on enhancing vehicle performance and fuel efficiency drives significant demand for Automotive Composites in powertrain and under-the-hood components. The trend toward lightweight materials in this segment supports improved energy efficiency, leading to lower emissions in compliance with stringent environmental regulations. Advanced technologies in manufacturing processes further enable the use of composites, which enhances the production of high-performance components that meet consumer expectations for durability and reliability.
Shifts toward electric and hybrid vehicle production heighten the need for innovative materials in this segment. The rising adoption of electric vehicle (EV) technology necessitates lightweight composites to counterbalance the weight of batteries, enhancing overall vehicle efficiency. Regulatory compliance standards serve because catalysts for investment in new materials, prompting manufacturers to explore advanced composites that align with evolving automotive design and environmental mandates.
Cost structures linked to raw material sourcing remain crucial in shaping market dynamics within this segment. Fluctuations in pricing for key materials impact production costs, necessitating strategic sourcing and supply chain resilience. End-use dynamics reflect a growing emphasis on performance characteristics, with manufacturers prioritizing materials that offer a balance of weight, strength, and thermal stability in powertrain applications.
While the market progresses, opportunities emerge for strategic investments in research and development. This focus on technological maturation supports next-generation upgrades and product evolution, allowing manufacturers to capitalize on emerging trends. Consumer preferences and regulatory frameworks shape the future of powertrain and under-the-hood components in the Automotive Composite market.
Increasing adoption of electric vehicles (EVs) drives demand for EV battery enclosures and protection structures within the Automotive Composite market. This segment benefits from the need for enhanced safety and performance characteristics, including thermal management and structural integrity. Growing emphasis on lightweight materials for EVs influences manufacturers to adopt composites, which offer significant weight reduction compared to traditional materials, leading to improved energy efficiency and extended battery life.
Technological advancements in composite materials facilitate the development of innovative battery enclosures. Enhanced manufacturing processes, including compression molding and injection molding, optimize production efficiency while maintaining high standards for quality and performance. Regulatory compliance with safety and environmental standards drives investment and development within this segment, ensuring that products meet strict guidelines for durability and safety.
Consumption shifts towards sustainable and recyclable materials influence the evolution of EV battery enclosures. Manufacturers focus on adopting natural and recyclable composites to align with consumer preferences and regulatory requirements for sustainability. This shift represents a strategic opportunity for companies looking to expand their offerings in the Automotive Composite market.
Overall, robust demand for EV battery enclosures and protection structures significantly impacts the growth trajectory of the Automotive Composite market, with ongoing investments in R&D and technological innovations shaping the future of this segment.
Innovative advancements in automotive technologies significantly influence demand for Pressure Vessels and Fuel-System Components within the Automotive Composite market. The increasing focus on enhancing safety and performance drives manufacturers to adopt composites that offer superior strength-to-weight ratios and corrosion resistance. This sub-segment benefits from the shift towards lightweight materials aimed at improving fuel efficiency and reducing emissions across various vehicle types.
Technological maturation influences the adoption of advanced composite materials. Ongoing research and development efforts lead to the introduction of next-generation composites that provide enhanced thermal stability and impact resistance, essential for pressure vessel applications. These innovations contribute to the evolution of products within the market, responding to stringent regulatory compliance standards surrounding automotive safety and environmental impacts.
Cost structures and pricing volatility remain critical factors affecting this sub-segment. Manufacturers face challenges related to raw material sourcing and supply chain resilience, especially in light of recent disruptions. Strategic opportunity windows arise for producers investing in sustainable sourcing and innovative manufacturing processes that lower costs while meeting regulatory requirements.
Competitive dynamics within the market highlight the emergence of disruptive alternatives, including traditional metal components being replaced by advanced composites. This trend reflects a broader consumption shift towards environmentally friendly solutions, further encouraging investment in the development of composites tailored for pressure vessels and fuel systems.
Demand for Wheels, Braking and Performance Components within the Automotive Composite market reflects a strong emphasis on vehicle safety, performance, and weight reduction. Rising automotive standards and regulatory compliance drive manufacturers to adopt advanced materials that enhance braking efficiency and overall vehicle dynamics. The increasing prevalence of electric vehicles (EVs) further increases the demand for lightweight components, driven by reduced weight contributing to improved battery range and efficiency.
Technological advancements in composite materials enable the development of high-performance components that meet stringent industry requirements. Innovations in fiber and resin technologies facilitate the creation of lightweight, durable, and high-strength products tailored for critical applications. While manufacturers focus on next-generation upgrades, investments in research and development play an essential role in driving the evolution of Wheels, Braking and Performance Components.
Consumption shifts towards eco-friendly and sustainable materials influence the segment's growth trajectory. Environmentally conscious consumers and manufacturers prioritize the use of renewable resources and recyclable materials in automotive applications. This trend aligns with the broader objectives of reducing carbon footprints and enhancing sustainability within the automotive industry.
While the demand for high-performance components continues to surge, strategic opportunity windows emerge for manufacturers investing in innovative solutions. Capital investment in advanced manufacturing processes, including automated production lines, enhances efficiency and reduces production costs. The ongoing emphasis on performance and safety standards underscores the significance of Wheels, Braking and Performance Components within the broader Automotive Composite market.
Increasing utilization of composite materials in automotive applications drives demand for specialty components, including brackets and covers. These components enhance structural integrity while contributing to weight reduction, which enhances overall vehicle performance. Manufacturers strive to meet stringent regulatory compliance standards and consumer preferences for lightweight vehicles, intensifying the focus on innovative solutions.
Technological maturation within the automotive composite market facilitates the development of advanced materials that offer better durability and improved performance characteristics. Research and development efforts direct optimization of the properties of composites to ensure their suitability for diverse applications, including those in harsh environments. The evolution of these products leads to opportunities for manufacturers to innovate and differentiate their offerings.
Downstream application dynamics play a significant role in shaping the market landscape. Automotive manufacturers increasingly prioritize sustainability. The adoption of composites contributes to reduced environmental impact while maintaining performance standards. This shift aligns with growing consumer awareness and regulatory pressures regarding sustainable practices within the automotive industry.
Strategic opportunity windows arise from heightened emphasis on cost optimization and supply chain resilience. Manufacturers explore alternative sourcing strategies to mitigate disruptions and ensure a steady supply of raw materials. This proactive approach positions players to navigate market challenges effectively and capitalize on emerging trends in the automotive composite market.
Compression molding is essential in the Automotive Composite market, valued at USD 4.1 billion in 2026 and projected to reach USD 7 billion by 2033, at a CAGR of 8.1% during the forecast period. Increasing demand for lightweight and durable materials in automotive applications drives the adoption of this manufacturing process. The segment benefits from its ability to produce complex shapes with high precision, which is essential for components like body panels and structural elements. Innovations in material formulations, including the development of high-performance resins, enhance the capabilities of compression molding, attracting interest from manufacturers focused on improving production efficiency and product performance. Regulatory compliance regarding vehicle weight reduction further supports the expansion of this segment, reflecting global initiatives aimed at lowering emissions. With strategic capital investment directed towards advanced manufacturing technologies, the market positions itself for sustained growth, reflecting the increasing reliance on composite materials across various automotive applications.
With a projected value of USD 5.7 billion by 2033, the Injection Molding and Overmolding segment of the Automotive Composite market demonstrates strong growth, evidenced by a compound annual growth rate (CAGR) of 9.8% during the forecast period. The rising preference for lightweight materials in automotive manufacturing significantly influences this segment, driven by the need for enhanced fuel efficiency and performance. Technological advancements in injection molding processes facilitate the production of complex geometries, thereby expanding applications across various vehicle components.
Increasing demand for durable, high-performance components in automotive applications directly correlates with the shifting trends towards sustainable materials. Manufacturers actively seek alternatives to traditional materials, leading to a surge in the adoption of advanced composites. This shift emphasizes product evolution and strategic opportunities for innovation within the supply chain. Regulatory compliance standards shape product development, pushing companies to invest in next-generation upgrades that align with eco-friendly mandates.
The market dynamics surrounding Injection Molding and Overmolding are supported by the continuous need for cost-effective solutions amid fluctuating raw material prices. Companies engage in strategic partnerships and capital investments to enhance operational capabilities and respond to pricing volatility. With significant growth on the horizon, the Injection Molding and Overmolding segment remains a critical area of focus within the broader Automotive Composite market.
Demand for Resin Transfer Molding (RTM and HP-RTM) reflects the increasing focus on efficient manufacturing processes in the automotive sector. This segment enables the production of complex shapes and lightweight components, which aligns with the industry's push for enhanced fuel efficiency and reduced emissions. The growing utilization of composite materials contributes to significant weight savings, directly impacting vehicle performance.
Technological advancements in RTM processes facilitate quicker production cycles and improved part quality, attracting investments from manufacturers. The segment is projected to reach USD 4 billion by 2033. Enhanced automation in manufacturing processes supports scalability, allowing companies to respond effectively to rising demand in the Automotive Composite market.
Applications in body and structural components benefit from RTM, driving adoption across various automotive segments. These characteristics position RTM because a crucial manufacturing method for producing lightweight and durable components, aligning with regulatory and consumer demands for more sustainable automotive solutions. Strategic investments in this segment provide opportunities for growth and expansion, further enhancing its role in the automotive industry.
Growth in the Prepreg Lay-up and Autoclave/Out-of-Autoclave Molding segment reflects a significant shift towards advanced composite manufacturing processes within the Automotive Composite market. This segment benefits from increasing demand for high-performance materials that enhance structural integrity and reduce weight in vehicle design, driving robust adoption of these techniques. The evolving automotive landscape emphasizes energy efficiency and sustainability, aligning with the capabilities of prepreg technologies, which deliver consistent quality and performance in production.
Investments in technological maturation further enhance production capabilities and efficiency, leading to lower production costs over time. The anticipated rise in electric vehicle adoption and stringent regulatory compliance standards regarding fuel efficiency and emissions influence production methods, reinforcing the role of advanced composites. The Prepreg Lay-up and Autoclave/Out-of-Autoclave Molding segment is projected to grow at a CAGR of 8% during the forecast period.
Strategic opportunities arise from increasing production capacities and advancements in materials technology, which address challenges related to raw material sourcing and pricing volatility. The segment's ability to satisfy the demand for lightweight and durable components positions it favorably within the overall market. Forecasts indicate a growing market value, highlighting the critical role that this segment plays in shaping the future of automotive manufacturing.
Adoption of Thermoforming and Stamp Forming within the Automotive Composite market is driven by the need for efficient production processes that accommodate complex geometries and large volume outputs. This manufacturing method supports the production of lightweight components, crucial in enhancing vehicle fuel efficiency and performance. While automotive manufacturers increasingly focus on sustainability, the shift towards composite materials creates opportunities for the growth of this segment.
Next-generation upgrades in thermoforming technologies highlight significant advancements, improving precision and reducing waste during production. Such innovations directly influence the market by enabling manufacturers to meet stringent regulatory compliance standards while maintaining cost-effectiveness. The development of these processes ensures that automotive composites remain competitive compared to traditional materials, reinforcing their role in various applications including body panels and structural components.
End-use dynamics within the market reflect an increasing preference for lightweight materials driven by consumer demand for more fuel-efficient and environmentally friendly vehicles. Consumption shifts towards electric and hybrid models increase the necessity for advanced composites, with thermoforming providing solutions for efficient manufacturing. Strategic opportunity windows exist for manufacturers who capitalize on these shifts by investing in R&D and enhancing their production capabilities.
Pricing volatility and margin pressures within the market often arise from fluctuations in raw material costs. Resilience in the supply chain becomes critical because companies navigate these challenges while ensuring quality and availability of materials essential for thermoforming. Firms focused on sourcing sustainable raw materials will likely gain a competitive edge, because consumers increasingly prioritize eco-friendly products. Continuous innovation within the segment mitigates risks associated with technological obsolescence, ensuring that manufacturers remain relevant in the automotive landscape.
Interest in pultrusion within the Automotive Composite market aligns with the industry's shift toward efficient manufacturing processes. The technology offers advantages in producing composite materials with high strength-to-weight ratios, appealing to automakers focused on enhancing vehicle performance. Adoption of pultrusion emphasizes the need for precision and consistency in the production of composite components.
Technological maturation drives advancements in pultrusion techniques, leading to improvements in product quality and production speed. Increased capabilities for customization support the demand for tailored solutions in automotive applications, contributing to market growth. Evolving product designs in vehicles push manufacturers to explore innovative materials and processes like pultrusion.
End-use dynamics in the market reflect a growing preference for lightweight materials that improve fuel efficiency and overall vehicle performance. Regulatory compliance standards demanding lower emissions reinforce the shift toward composite materials, positioning pultrusion because a viable manufacturing process. While environmental regulations tighten, pultrusion offers an effective solution for creating lightweight components that meet these standards.
Raw material sourcing and supply chain resilience remain crucial factors influencing the adoption of pultrusion technologies. Manufacturers increasingly seek reliable suppliers who provide high-quality raw materials essential for the pultrusion process. This focus on quality ensures that automotive composites produced via pultrusion meet the rigorous performance and safety standards required in the industry.
Strategic opportunity windows arise from advancements in pultrusion technology, allowing companies to differentiate their offerings in a competitive landscape. Investments in next-generation upgrades and research into innovative applications drive further adoption of pultrusion within the Automotive Composite market. Capital investment outlook remains optimistic, reflecting confidence in the long-term viability of pultrusion because a key manufacturing process.
Filament winding technology significantly influences the Automotive Composite market, particularly for applications requiring high strength and lightweight materials. This manufacturing process enables the creation of complex shapes and geometries, essential for structural components in modern vehicles. The increasing demand for lightweight materials in automotive production drives interest in filament winding, allowing manufacturers to achieve desired performance characteristics without compromising structural integrity.
Technological maturation within filament winding enhances production efficiency and product quality. Advances in automation and process control contribute to improved accuracy and reduced cycle times, making filament winding more attractive for automotive applications. The evolving landscape of automotive design, with a significant focus on electric vehicles and performance-oriented features, fuels the adoption of this technology and aligns with industry trends towards innovative material solutions.
End-use dynamics illustrate a shift towards using filament winding in high-performance components, including drive shafts and pressure vessels. This shift aligns with regulatory compliance standards demanding reductions in vehicle weight and emissions. While automotive manufacturers increasingly prioritize sustainability, filament winding presents a viable solution, addressing both performance and environmental concerns.
Strategic opportunity windows emerge owing to manufacturers investing in developing filament winding capabilities to meet growing demand. This investment reflects the need for robust supply chain resilience and diversification of material sourcing, ensuring manufacturers remain competitive in the evolving market. The automotive composite sector continues to recognize the advantages of filament winding, positioning it because a key player in the future of automotive manufacturing.
Interest in Vacuum Infusion within the Automotive Composite market arises from its efficiency in producing large, complex parts with a high strength-to-weight ratio. This manufacturing process employs a vacuum to draw resin into a fiber reinforcement, ensuring thorough saturation and minimizing voids. Enhanced surface finish and reduced waste contribute to the appeal of this method among automotive manufacturers.
Technological maturation in the Vacuum Infusion process leads to improved resin formulation and curing techniques. Manufacturers increasingly adopt next-generation materials and developments that enhance the overall performance of composites. Evolution in product design emphasizes the importance of lightweight structures to meet stringent fuel efficiency and emissions regulations.
Downstream applications in the automotive sector highlight the significance of body and exterior panels, where the demand for durable yet lightweight components is strong. The market experiences consumption shifts driven by the automotive industry's transition towards sustainable practices, further boosting interest in composite solutions. Regulatory compliance standards increasingly focus on environmental impact, prompting manufacturers to explore more eco-friendly materials and processes.
Cost structures in the Vacuum Infusion segment reflect the balance between raw material expenses and the benefits of reduced labor and energy costs. Pricing volatility remains a concern for manufacturers, particularly concerning resin prices that fluctuate based on market conditions. Strategic opportunity windows arise from automotive companies seeking innovative solutions to address the challenges posed by traditional manufacturing methods.
Supply chain resilience becomes critical in ensuring the availability of high-quality raw materials essential for effective Vacuum Infusion processes. Sourcing reliable materials contributes to consistent production output while mitigating risks associated with logistics vulnerabilities. Disruptive alternatives, including advanced manufacturing techniques, continuously reshape the market, compelling the market to adapt and innovate.
Technological obsolescence presents a challenge for manufacturers who remain competitive by adopting the latest advancements in the industry. Strategic investment in research and development ensures that companies leverage new technologies to enhance their offerings. This proactive approach supports sustained growth within the Automotive Composite market.
Increasing interest in Hand Lay-up and Spray-up techniques aligns with the rising demand for lightweight and high-strength components in the automotive sector. This manufacturing process enables greater design flexibility and customization, appealing to manufacturers aiming to create unique vehicle components. The simplicity of the process facilitates quick adjustments and adaptations during production, ensuring responsiveness to market trends and consumer preferences. The method supports cost-effective small-scale production runs, crucial for specialized automotive applications.
Technological advancements play a significant role in enhancing the efficiency and quality of the Hand Lay-up and Spray-up process. Improvements in resin formulations and fiber materials contribute to superior mechanical properties and reduced cycle times. Ongoing innovations in application techniques further optimize material usage, promoting sustainability within the market. Consequently, manufacturers gain a competitive edge by delivering high-performance composite components that satisfy stringent regulatory compliance standards.
Shifts in consumer preferences toward electric vehicles significantly influence the demand landscape within the automotive composite market. The emphasis on sustainability drives manufacturers to explore eco-friendly materials and processes, including Hand Lay-up and Spray-up. This shift presents strategic opportunities for companies willing to invest in research and development, leading to the evolution of products that cater to environmentally conscious consumers.
Supply chain resilience remains crucial for the Hand Lay-up and Spray-up segment. Secure access to quality raw materials influences production efficiency and cost structures. Partnerships with reliable suppliers ensure a steady supply of advanced composites, reducing vulnerabilities associated with logistics disruptions. Manufacturers who prioritize robust supply chains mitigate risks related to pricing volatility and margin pressures, strengthening their position in the competitive environment.
While the automotive industry continues to evolve, Hand Lay-up and Spray-up processes are positioned to capture growing demand within the market. Companies that proactively adapt to emerging trends and consumer demands will likely find success in this dynamic segment. The integration of next-generation technologies and sustainable practices will drive further advancements, reinforcing the role of this manufacturing process in the future of automotive composites.
Growing interest in innovative manufacturing techniques drives the adoption of Automated Fiber Placement and Specialty Processes within the Automotive Composite market. These advanced methods enhance production efficiency, reduce labor costs, and improve product quality. The incorporation of advanced automation in manufacturing aligns with the automotive industry's push for greater efficiency and precision in component production.
Technological maturation plays a significant role in facilitating the transition towards these sophisticated methods. While companies increasingly invest in next-generation upgrades, the market experiences a shift towards automated solutions that enhance capabilities while maintaining competitive pricing. This evolution signifies a strategic opportunity window for manufacturers seeking to improve their operational efficiencies and product offerings.
Downstream applications benefit significantly from the increased deployment of automated techniques, because these processes enable the precise fabrication of complex geometries. The expansion of the Automotive Composite market aligns with growing demand for lightweight and high-performance components, essential for modern vehicle designs aimed at fuel efficiency and reduced emissions.
Stringent regulatory compliance standards and certifications necessitate the use of high-quality manufacturing processes. This requirement drives investment in technology that ensures adherence to safety and performance criteria, reinforcing the role of automated processes in meeting industry expectations. Shifts in consumption patterns towards more sustainable practices promote the adoption of innovative manufacturing solutions that align with environmental goals.
Supply chain resilience is enhanced through the integration of automated processes, which optimize raw material sourcing and minimize vulnerabilities. While manufacturers seek to mitigate risks associated with material shortages and logistics challenges, the focus on automation becomes crucial. This strategic emphasis creates a competitive advantage in a market characterized by evolving demands and challenges.
Overall, the incorporation of Automated Fiber Placement and Specialty Processes represents a transformational shift in the Automotive Composite market, aligning with broader industry trends towards innovation, efficiency, and sustainability. The ongoing evolution in this sub-segment illustrates the commitment of manufacturers to leverage advanced technologies for improved product outcomes and market competitiveness.
Based on geography, the Global Automotive Composite market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America represents a significant portion of the Automotive Composite market, holding a share of 31.1% in 2025. The market is set to expand at a CAGR of 9.0% within the forecast period, reaching a market size (TAM) of USD 8.2 billion by the end of 2033. This growth results from increasing demand across various automotive applications, particularly in the United States, Canada, and Mexico.
Technological advancements in composite materials enhance the performance and efficiency of automotive components, driving adoption. The presence of established players and a mature supply chain in North America supports rapid innovation and consumer acceptance of these materials. Regional manufacturing capabilities further contribute to market expansion, driven by companies focusing on local production to meet demand effectively.
Investment in infrastructure modernization remains a key catalyst for growth. Enhanced manufacturing facilities allow for the efficient production of advanced composite materials, aligning with rising consumer expectations for quality and performance. The regional competitive landscape features a mix of domestic market leaders and global players, creating a dynamic environment for innovation and collaboration.
Cultural nuances and localized procurement dynamics influence B2B buying behaviors in the region. Automotive manufacturers prioritize partnerships with suppliers who demonstrate reliability and advanced technological capabilities. This focus on collaboration enhances the potential for growth within the market, driven by companies seeking to leverage regional strengths and expertise.
The Automotive Composite market in Europe displays growth driven by increasing production and adoption of lightweight materials across the automotive sector. Germany, France, the UK, Italy, Spain, and Russia contribute significantly to this trend, leveraging advanced manufacturing capabilities and established automotive industries. Technological advancements in fiber and resin types enhance the market potential, particularly in carbon fiber composites, which attract investments targeting high-performance applications.
High-value replacement cycles in mature markets like Germany and France lead to consistent demand for innovative solutions. Incremental growth vectors in underpenetrated territories, including Eastern Europe, present new opportunities. Localized manufacturing densities across Europe support supply chain regionalization, allowing automotive manufacturers to streamline operations and reduce costs. Cross-border trade corridors within the European Union facilitate market access, ensuring a steady flow of materials and components critical for automotive composite production.
Geopolitical considerations and regional compliance mandates influence procurement dynamics, creating a competitive landscape where domestic leaders capitalize on localized knowledge and manufacturing capabilities. With significant investments in infrastructure modernization, European markets stand prepared for continued growth in the Automotive Composite market, positioning themselves because strategic hubs for innovation and production.
The Asia-Pacific region exhibits significant potential within the Automotive Composite market, reflecting a strong growth trajectory driven by increasing automotive production and technological advancements. Countries including China, Japan, and India emerge because front-runners, with an automotive sector that embraces lightweight materials to improve vehicle efficiency and performance. The push for electric vehicles in these markets fuels demand for advanced composite materials, particularly in critical components like EV battery enclosures and structural elements.
Infrastructure modernization across Asia-Pacific enhances production capabilities, while local manufacturing densities strengthen the supply chain and reduce dependency on imports. The ongoing trend of nearshoring initiatives contributes to localized production efforts, providing a competitive edge to regional manufacturers. Cultural nuances and regional B2B buying behaviors influence procurement dynamics, with an increasing preference for domestic suppliers who offer tailored solutions to meet specific market needs.
The market's competitive landscape features several domestic leaders and global players, creating an environment of collaboration and innovation. Strategic foreign direct investment (FDI) flows into the region support expansion efforts and facilitate the adoption of advanced manufacturing processes. Local compliance mandates and regulatory frameworks create opportunities and challenges for market participants, necessitating a keen understanding of the regional landscape to navigate operational complexities effectively.
Ultimately, the Asia-Pacific region stands poised for sustained growth in the Automotive Composite market, driven by a confluence of factors including high-value replacement cycles, emerging technologies, and an increasingly sophisticated consumer base. Continued investment in R&D and an agile approach to market dynamics will be crucial for stakeholders aiming to capitalize on the expanding opportunities within this sector.
South America, comprising Brazil, Argentina, and the Rest of South America, is positioned to maintain a modest share of the global Automotive Composite market at 3.4% in 2025. The region experiences challenges related to infrastructure modernization, which affects adoption rates and overall market dynamics. Incremental growth vectors emerge through localized manufacturing densities, impacting supply chain regionalization efforts and nearshoring initiatives.
Domestic market participants focus on enhancing procurement dynamics tailored to the cultural nuances of the region. Strategic entry barriers hinder foreign direct investment (FDI) flows, impacting geographic expansion windows. Local compliance mandates and regulatory frameworks further influence the competitive landscape, shaping vendor consolidation trends and participation in cross-border trade corridors.
Resource availability and energy grid resiliency are critical for the Automotive Composite market in South America. Companies operating within the region leverage local resources to optimize production processes, catering to regional demand while addressing the nuances of B2B buying behaviors. This localized approach creates growth opportunities, allowing firms to adapt to market fluctuations and consumer preferences.
The Automotive Composite market in the Middle East and Africa is evolving, driven by a growing automotive sector in countries like Saudi Arabia and the UAE. The region's share of the global market is projected at 4.3% in 2025, indicating a moderate but significant presence. Increasing investments in infrastructure modernization, including the development of manufacturing facilities, support local production of composite materials. These investments align with government initiatives to reduce dependency on imports and enhance domestic capabilities.
South Africa positions itself because a key player, with expanding automotive production and a rising demand for lightweight materials. The market benefits from governmental support aimed at stimulating local industries and attracting foreign direct investment (FDI). The presence of established automotive manufacturers creates a competitive landscape, encouraging domestic suppliers to improve their offerings and capabilities.
Localized procurement dynamics influence purchasing decisions, with businesses increasingly seeking suppliers that provide cost-effective, high-quality materials. Cultural nuances play a role in B2B buying behaviors, often emphasizing strong relationships between buyers and suppliers. Forecasts indicate that the Automotive Composite market in the region is expected to experience incremental growth, driven by high-value replacement cycles and the need for innovative materials to meet evolving consumer preferences.
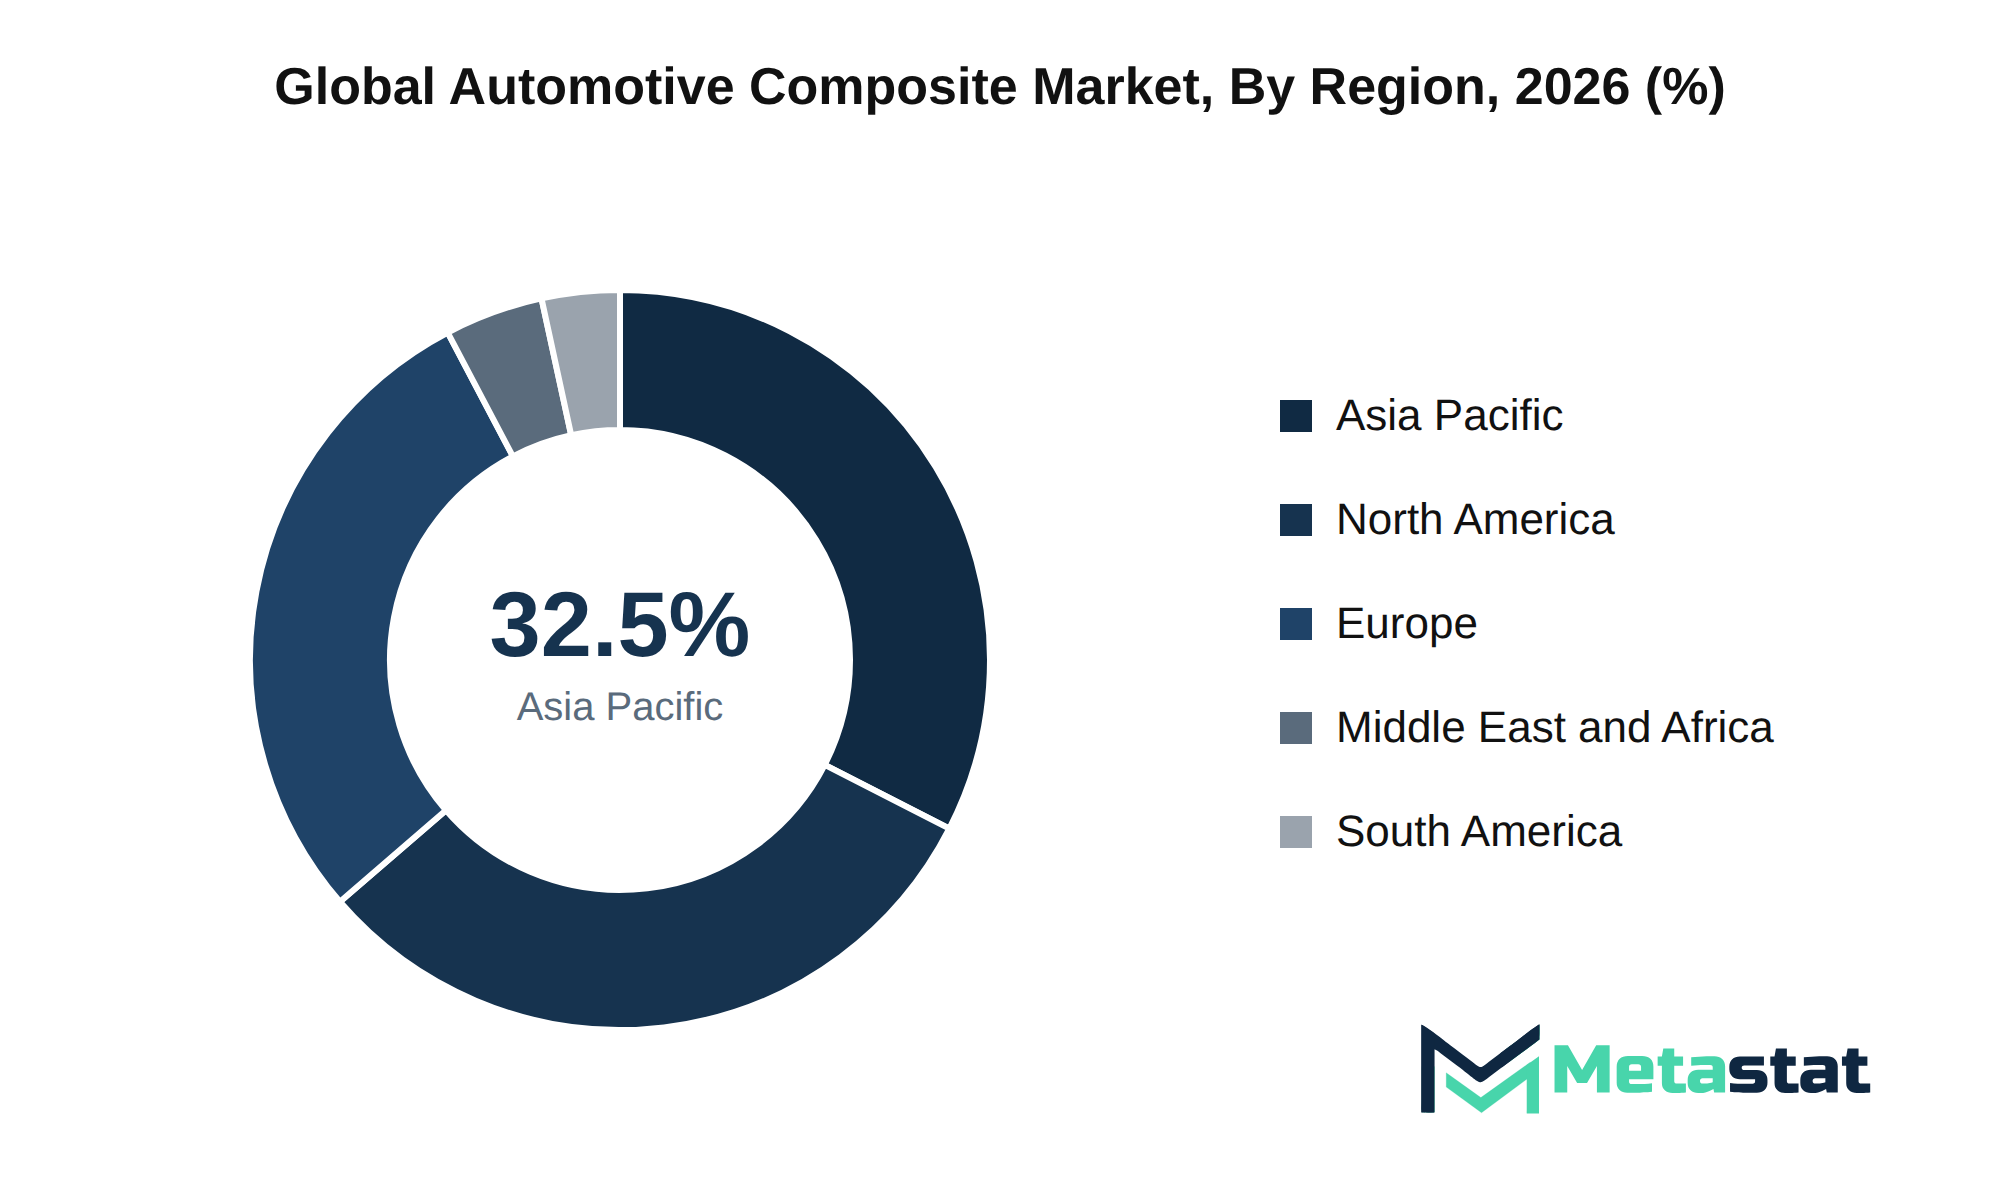
The competitive landscape in the automotive composite market features a mix of established players and emerging companies focusing on innovation and differentiation. Companies including 3M Co., BASF SE, and DuPont de Nemours Inc. leverage extensive research and development capabilities to produce advanced composite materials that enhance performance and reduce weight in automotive applications.
Strategic alliances and partnerships play a crucial role in shaping market dynamics. Firms like Hexcel Corporation and Toray Industries, Inc. collaborate with automotive manufacturers to co-develop tailored solutions that meet specific performance requirements. This approach strengthens their market position while enhancing customer loyalty and brand equity.
Barriers to entry in the automotive composite market include high capital investment and the need for advanced technological expertise. Established companies, including Arkema S.A. and Owens Corning, maintain a competitive edge through proprietary technologies and strong intellectual property portfolios. This situation creates significant challenges for new entrants aiming to disrupt the market.
The future competitive outlook indicates continued growth driven by rising demand for lightweight materials and sustainability initiatives. Companies that invest in innovative manufacturing processes, including injection molding and compression molding, are expected to capture a larger share of the market, enhancing revenue potential and operational efficiency.
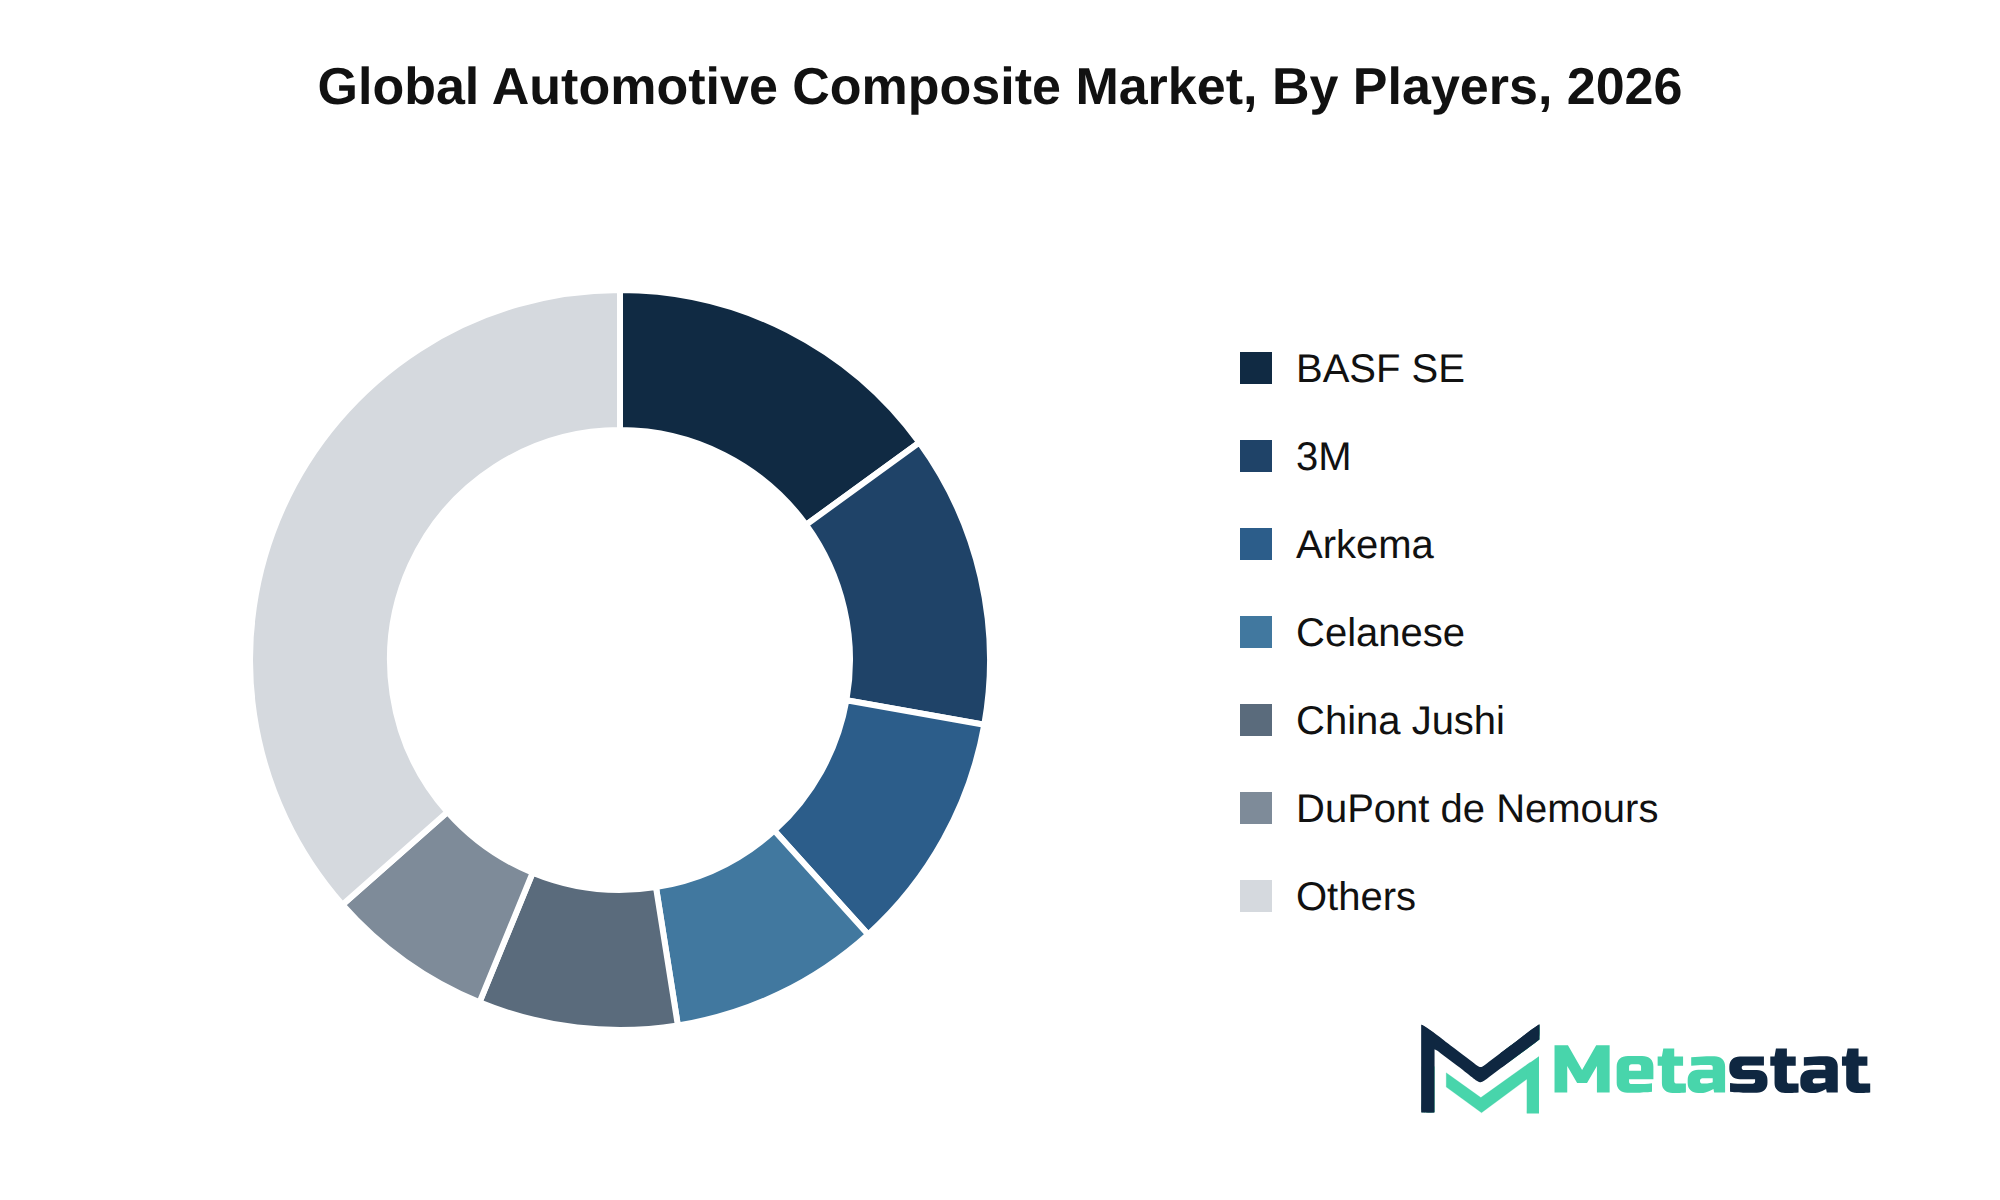
Market size is forecast to rise from USD 13.8 billion in 2025 to over USD 27.5 billion by 2033. This growth reflects a compound annual growth rate (CAGR) of 9.0%, indicating strong momentum in the Automotive Composite market. Key drivers of this expansion include advancements in next-generation technologies, growing demand for lightweight materials, and increasing adoption of composites in various automotive applications. The market's evolution faces challenges stemming from regulatory changes and geopolitical factors that impact supply chains.
The bull case envisions accelerated adoption of innovative materials and processes, supporting growth beyond current projections. Conversely, the bear case anticipates potential disruptions in manufacturing and supply chains, which could hinder the pace of market development. In this dynamic environment, stakeholders navigate shifting consumer preferences and regulatory landscapes while capitalizing on emerging opportunities arising from unmet enterprise needs. The focus on strategic capital allocation and infrastructure commitments remains essential for sustainable growth in the Automotive Composite market.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Automotive Composite market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 9.0% from 2026 to 2033 |
Revenue Unit | USD billion |
Segmentation | By Fiber Type, Resin Type, Application, Manufacturing Process, and Region |
By Region | North America (By Fiber Type, Resin Type, Application, Manufacturing Process, and Country)
|
Europe (By Fiber Type, Resin Type, Application, Manufacturing Process, and Country)
| |
Asia Pacific (By Fiber Type, Resin Type, Application, Manufacturing Process, and Country)
| |
South America (By Fiber Type, Resin Type, Application, Manufacturing Process, and Country)
| |
Middle East and Africa (By Fiber Type, Resin Type, Application, Manufacturing Process, and Country)
|
Find answers to common questions about this report
The Automotive Composite market size was valued at USD 13.8 billion in 2025.
The Automotive Composite market is projected to grow at a CAGR of 9.0% during the forecast period from 2026 to 2033.
The North America Automotive Composite market size is estimated to reach USD 8.2 billion by 2033.
The Glass Fiber Composites segment leads the Automotive Composite market, with a projected value of USD 14.1 billion by 2033. This figure reflects a compound annual growth rate of 7.8 percent from 2026.
Key drivers for the Automotive Composite market include increasing demand for lightweight and fuel-efficient vehicles, advancements in technological integration, and operational productivity initiatives. These factors encourage manufacturers to adopt composites, enhancing vehicle performance and aligning with evolving consumer preferences.
North America holds the dominant share of the Automotive Composite market, with a projected value of USD 8.2 billion for 2033, representing 31.1% of the total market share.
Several factors restrain the Automotive Composite market growth, including stringent regulatory compliance that increases operational complexities and costs. High capital investment requirements for advanced manufacturing technologies create barriers for smaller players, while inflationary pressures and supply chain disruptions stemming from geopolitical tensions further complicate production processes and increase costs.
Factors favoring product adoption in the Automotive Composite market include a growing preference for lightweight and fuel-efficient vehicles, which drives demand for advanced materials. operational productivity initiatives and technological integration enhance manufacturing efficiency, making composites more economically viable for automotive applications.
The Automotive Composite market is estimated to reach a valuation of USD 27.5 billion by 2033.
Key players operating in the Automotive Composite market include 3B-the Fibreglass Company, 3M Co., Arkema S.A., BASF SE, DuPont de Nemours Inc., Hexcel Corporation, LyondellBasell Industries N.V., and Mitsubishi Chemical Carbon Fiber and Composites, Inc.
Choose Your License
Global Automotive Composite Market
The analysts below cover Automotive and Transportation research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.
Evaluating secondary resin quality across post-consumer packaging streams requires reliable technical segmentation. MetaStat Insight delivered an objective assessment that distinguished between extrusion-grade flake pricing and optical sorting throughput limitations across Western Europe. The competitive positioning breakdown for licensed depolymerization technology providers answered several questions during our feedstock feasibility audit. Their team clarified regional trade restrictions on mixed plastic scrap quickly when our team submitted follow-up requests.
Evaluating sovereign cloud deployments for core banking platforms demands a clear view of data residency regulations and migration exit strategies. MetaStat Insight delivered an exhaustive review of regional latency tolerances, mainframe decommission milestones, and third-party vendor concentration risk. The regulatory compliance mapping across European and Asian financial jurisdictions gave our team a dependable baseline for multi-cloud infrastructure discussions.
Replacing petrochemical surfactants with bio-based alternatives requires realistic timelines on industrial precision fermentation scaling. The market research broke down commercialization timelines, feedstock sugar price sensitivities, and regional cosmetic ingredient regulatory approvals in Europe and East Asia. That supplier readiness mapping gave our formulations team reliable context when comparing renewable chemical sourcing roadmaps.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950
Starting from
$2950