
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Biochar Market Size, Share, By Technology (Pyrolysis, Gasification and Others), By Feedstock (Woody Biomass, Animal Manure and Others), By Application (Agriculture, Water Filtration, Animal Feed Additive, Electricity Generation, Heat Generation, Biogas Production and Others), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5169
September 6, 2026
Updated
278 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
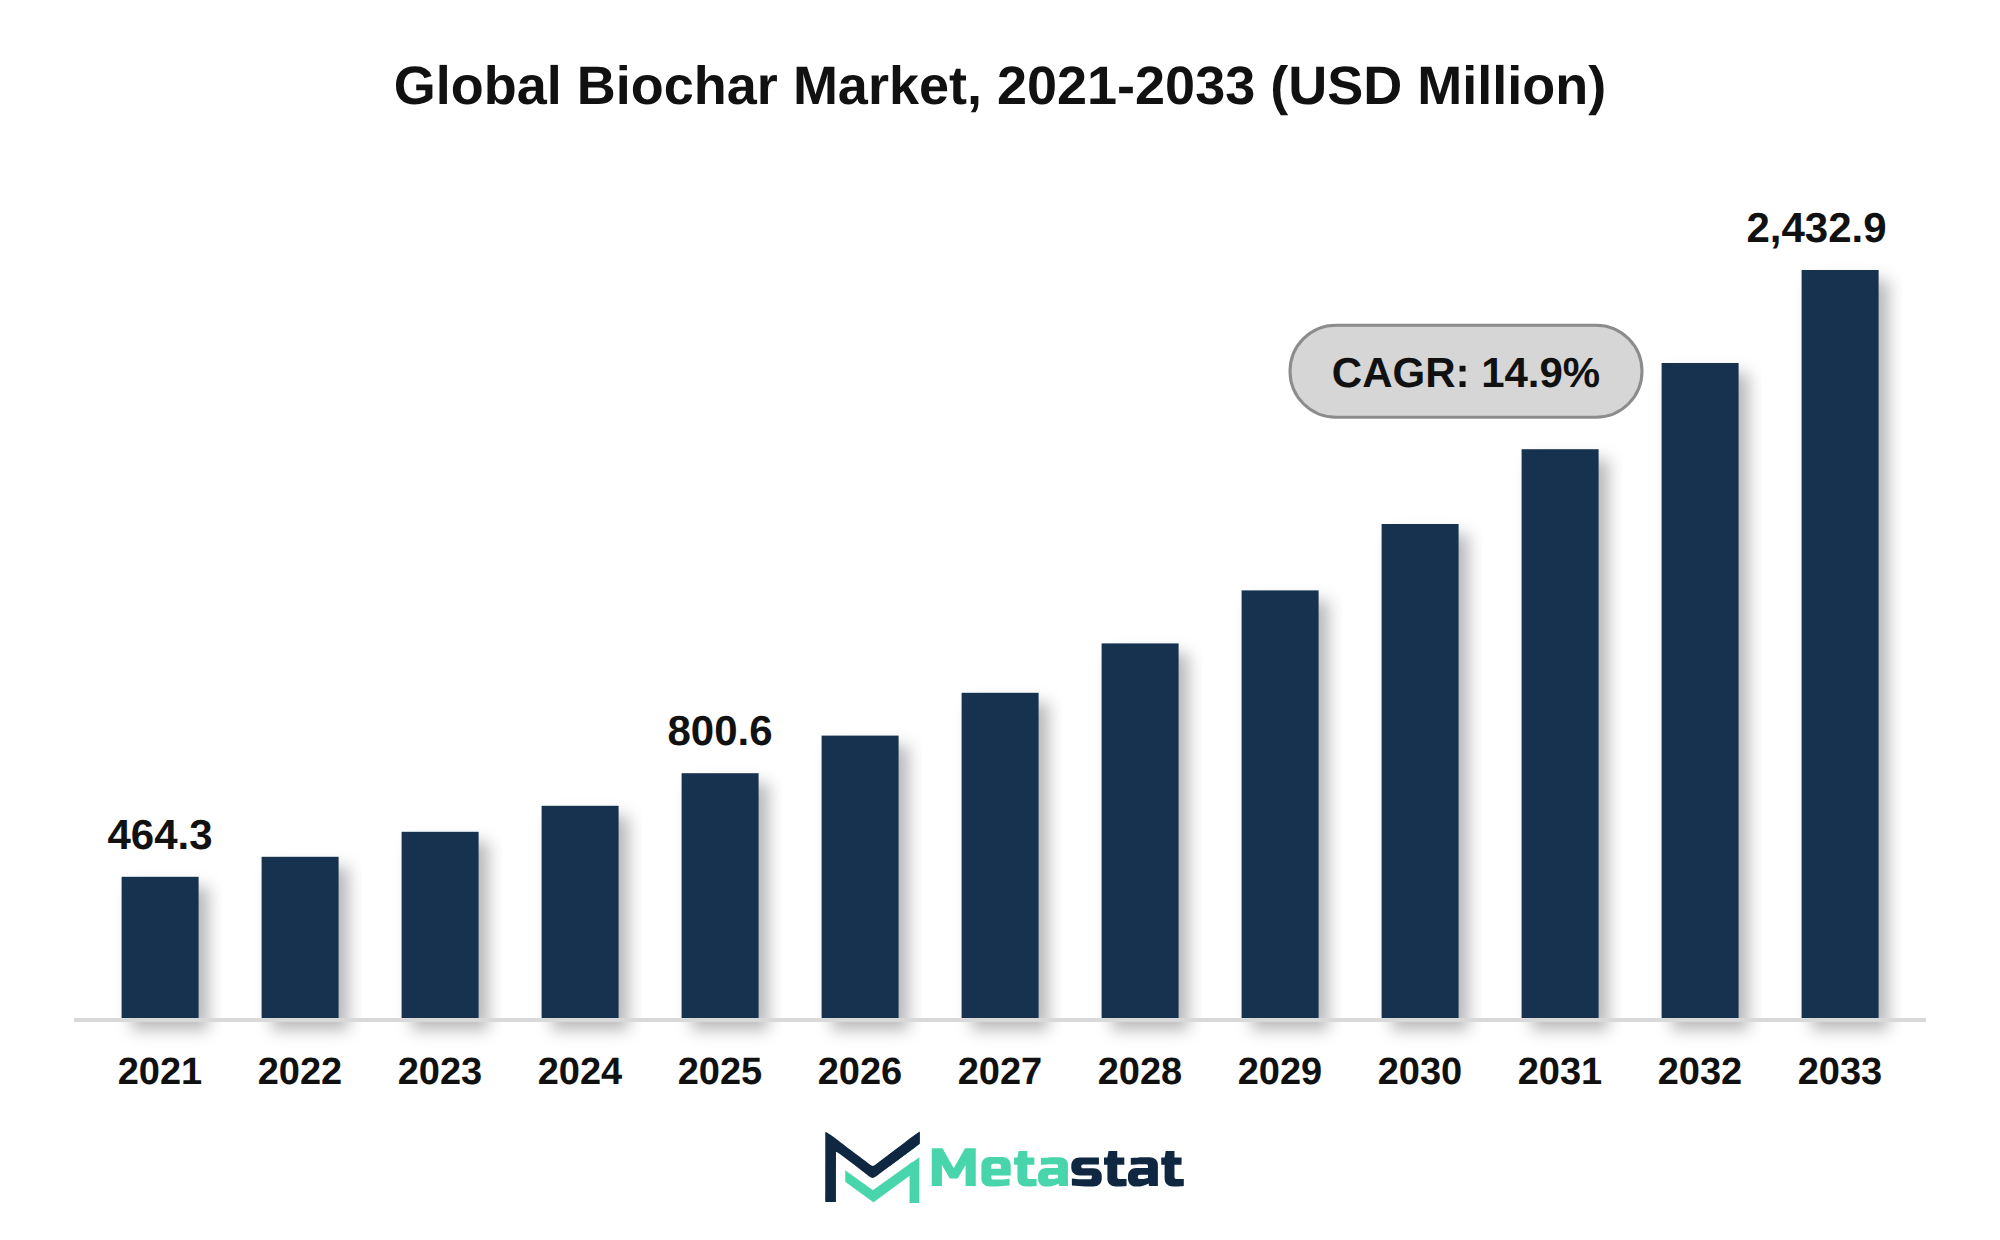
The global Biochar market was valued at USD 800.6 million in 2025 and is projected to reach USD 2,432.9 million by 2033, growing at a CAGR of 14.9% over the forecast period.
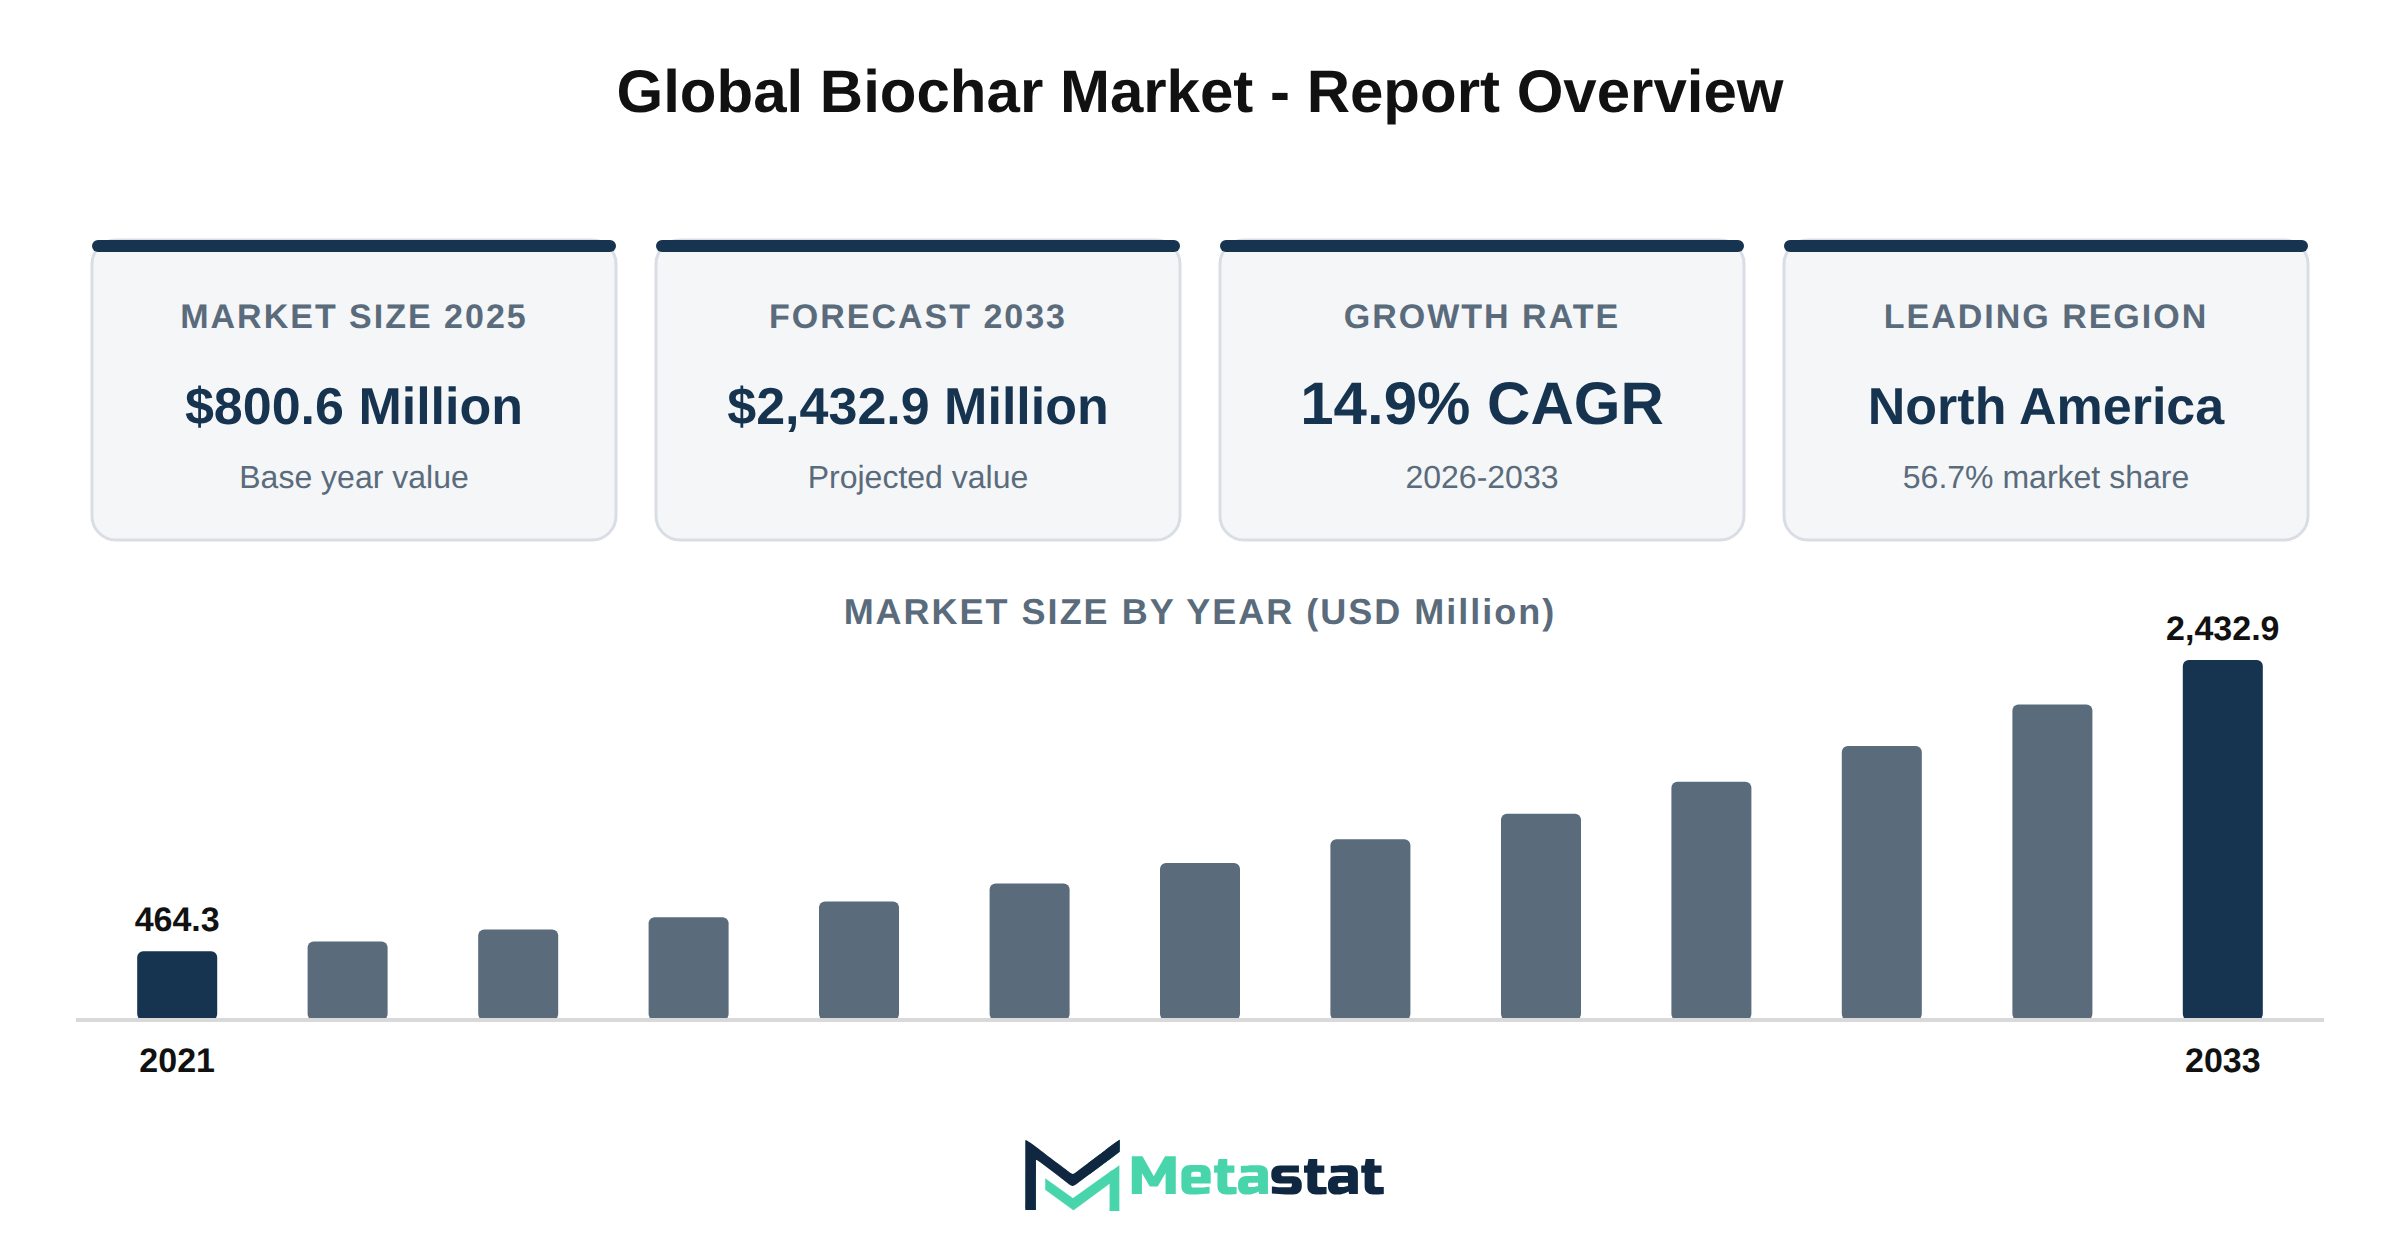
The global Biochar market reached USD 800.6 million in 2025 and is projected to grow significantly, reaching USD 2,432.9 million by 2033. This represents a compound annual growth rate (CAGR) of 14.9%. Historical data indicates steady growth, with the market valued at USD 464.3 million in 2021, increasing to USD 694.6 million in 2024. The upward trajectory highlights increasing awareness and adoption of biochar in various applications.
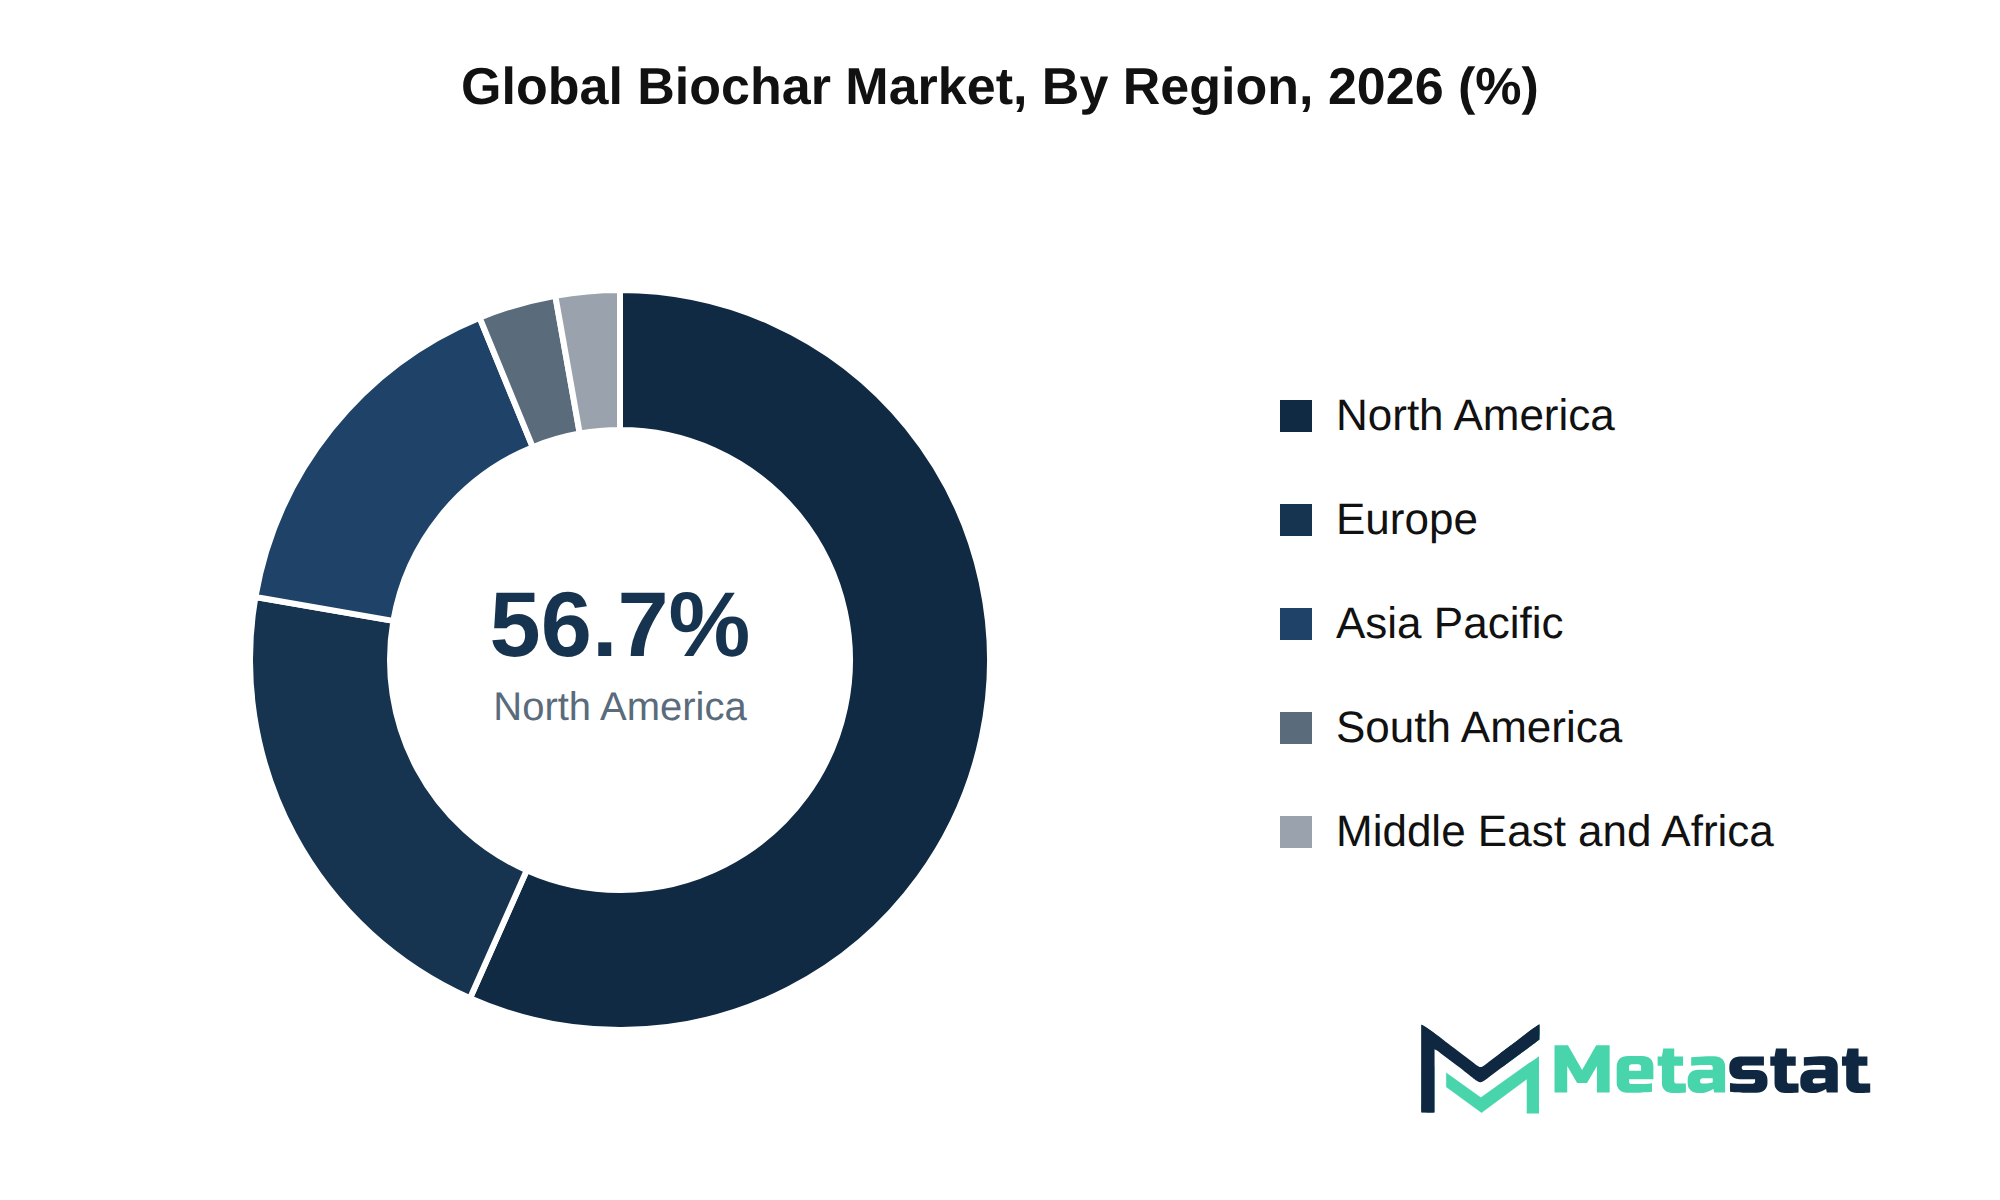
North America holds a dominant position in the market, accounting for 56.7% of the total share. This region's market value is anticipated to reach USD 1,162.9 million by 2033, with a CAGR of 14.9%. Europe follows with a 21.1% share, while Asia Pacific constitutes 16.1%. The growth in North America is driven by strong demand for sustainable agricultural practices and carbon sequestration strategies.
Biochar production technologies are essential in shaping market dynamics. Pyrolysis and gasification stand out because primary methods. Pyrolysis, with an estimated market value of USD 598.5 million in 2026, is projected to reach USD 1,475.5 million by 2033, reflecting a CAGR of 13.8%. Gasification is expected to reach USD 785.1 million by the end of the forecast period, achieving a CAGR of 17.2%. These technologies play a critical role in the effectiveness and efficiency of biochar production.
Feedstock types, including woody biomass, animal manure, and others, significantly influence production costs and quality. The value of woody biomass because feedstock is anticipated to rise from USD 539.4 million in 2026 to USD 1,463.6 million by 2033, marking a CAGR of 15.3%. Conversely, animal manure is projected to reach USD 591.7 million by 2033, with a CAGR of 14.5%. Understanding the feedstock economics is crucial for market players seeking to optimize production processes and minimize costs.
Biochar production technologies primarily include pyrolysis and gasification, both of which offer distinct advantages. Pyrolysis operates within a temperature range of 300-700°C, resulting in a stable product that retains significant carbon content, beneficial for soil enhancement. Gasification, while generating energy, focuses on converting organic materials into syngas, which are applied in various applications. The choice between these technologies hinges on the desired end product and operational efficiency, influencing market dynamics.
Carbon credit markets present monetization strategies for biochar, allowing producers to capitalize on environmental benefits while contributing to carbon sequestration efforts. Standards including the Verra VCS carbon standard and the Gold Standard for biochar credits establish frameworks for quantifying and trading carbon credits, enhancing market appeal. This aspect attracts investment and encourages broader adoption across different regions.
Certification standards, including the International Biochar Initiative (IBI) and the European Biochar Certificate (EBC), play an essential role in ensuring quality and safety in biochar production. Compliance with these standards provides assurance to end-users regarding product efficacy, building trust and potentially increasing demand within the market.
Case studies highlight successful commercial biochar deployment in agriculture, demonstrating its effectiveness in enhancing soil quality and crop yields. Implementations have shown the positive impact of biochar on soil organic carbon (SOC) levels and cation exchange capacity (CEC), which are critical for improving soil fertility and health over time.
Feedstock economics significantly influence the market, with cost analysis showing variations by raw material type. Common feedstocks include wood waste, agricultural residues, and animal manure, each contributing differently to production costs and quality outcomes. Understanding these dynamics allows stakeholders to optimize their supply chains effectively.
Biochar quality metrics, including surface area, pH, and nutrient retention, serve because critical indicators of product performance. These metrics directly affect the efficacy of biochar in agricultural applications, guiding producers in selecting appropriate feedstock and production methods to meet market demands.
The regulatory landscape for biochar is evolving, with policies from the EPA, EU, and Asia-Pacific regions shaping market conditions. These regulations establish guidelines for production, application, and environmental safety, influencing investment decisions and market strategies for companies operating within the biochar sector.
Investment trends reflect a growing interest in biochar startups, driven by venture capital and corporate funding. This influx of capital supports innovation and expansion within the market, positioning biochar because a viable alternative to compost and synthetic fertilizers. Comparative ROI analysis highlights the long-term benefits of biochar application rates, reinforcing its role in sustainable agriculture and soil management.
Growing concerns about environmental sustainability and climate change drive interest in biochar production and utilization. Emission limits imposed on industries encourage businesses to seek solutions that reduce their carbon footprint. This trend influences numerous sectors, including agriculture, waste management, and energy production, all of which increasingly adopt biochar to meet sustainability goals.
The Biochar market benefits from this shift due to companies prioritizing initiatives that align with emission reduction strategies. Biochar enhances soil health and captures carbon, making it an attractive option for organizations aiming to comply with stringent environmental regulations. This dynamic leads to increased demand for biochar products, ultimately driving market growth.
Investment in biochar technology and infrastructure supports this adoption, with businesses focusing on technologies like pyrolysis and gasification that efficiently convert biomass into biochar. The integration of these technologies into production processes ensures companies meet regulatory requirements while gaining operational efficiencies, further reinforcing biochar's role within a circular economy.
Investment in infrastructure development significantly influences the growth trajectory of the Biochar market. Enhanced physical and digital capacities improve production efficiency and distribution networks, facilitating better access to raw materials and markets. Upgrading facilities and modernizing technologies attract new entrants, driving competition and innovation within the sector. This increased capacity enables producers to meet rising demand while maintaining cost efficiency.
Integrating advanced technologies enhances operational productivity. Automation and digitization streamline production processes, reduce labor costs, and improve output quality. The adoption of innovative practices creates a more resilient supply chain, allowing businesses to adapt quickly to market fluctuations and consumer preferences. These developments lead to a more robust market environment, contributing to sustained growth in the coming years.
Investment in infrastructure not only supports the Biochar market but aligns with sustainability initiatives aimed at reducing carbon footprints and promoting resource stewardship. While producers enhance their operational capabilities, increased focus on environmentally friendly practices reinforces the market's appeal to eco-conscious consumers and stakeholders.
Regulatory complexity significantly impacts the Biochar market, with intricate frameworks and compliance requirements creating barriers to entry for new players. Obtaining necessary permits and adhering to environmental standards delays project timelines and increases operational costs for suppliers. Companies investing in biochar production face challenges while navigating various regulatory landscapes across different regions. These hurdles particularly affect small and medium-sized enterprises, limiting their market participation and innovation potential.
Fluctuating economic conditions contribute to capital stagnation within the industry. High initial investment requirements for biochar production facilities deter potential investors during times of economic uncertainty. This lack of investment restricts the introduction of innovative technologies and solutions, which impedes overall market growth. Suppliers encounter difficulties in securing financing, directly impacting their capacity to expand operations and meet rising demand for biochar.
Inflationary pressures escalate operating costs, straining profit margins for companies in the market. Increased prices for raw materials and energy result in higher production costs, making biochar less competitive against alternative offerings. This economic environment slows adoption rates among potential customers in price-sensitive sectors including agriculture.
Supply chain disruptions caused by geopolitical instability and resource scarcity complicate market dynamics. Unpredictable sourcing of feedstocks influences production schedules, while delays in logistics result in significant lead times for delivery. These factors undermine customer confidence and result in lost sales opportunities. Overall, regulatory complexity, economic pressures, and supply chain challenges hinder growth potential in the Biochar market.
Geopolitical fragmentation leads to trade deficits and tariff friction, creating challenges for the Biochar market. Political unrest and disruptions in trade relationships complicate sourcing of raw materials and affect pricing stability. Stakeholders in various industries face increased costs due to tariffs and trade barriers, hindering adoption rates and overall market growth.
Technological disruptions contribute to complex research and development integrations, complicating the path for innovation within the market. Companies encounter difficulties in harmonizing new technologies with existing processes, impacting their ability to scale production effectively. Interoperability friction between different technologies limits the integration of advanced biochar production systems, affecting competitiveness.
Volatility in feedstock availability and pricing presents additional challenges. Fluctuations in supply directly influence production costs, leading to margin pressures for producers. High input costs and the need for skilled labor strain operations, affecting overall profitability within the market.
Environmental lifecycle footprints and decarbonization mandates impose stringent requirements on producers. Compliance overhead associated with evolving legal liabilities adds complexity and operational costs, deterring new entrants into the Biochar market. Retrofitting barriers and implementation bottlenecks in existing facilities delay the adoption of biochar technologies, affecting market penetration.
Intellectual property protection deficits and cybersecurity risks hinder innovation and investment within the market. Companies face potential data vulnerabilities that risk their competitive edge and market position. Changing downstream demands and market saturation intensify competition, creating pressures for differentiation and innovation in biochar applications.
Technological disruptions significantly enhance opportunities within the Biochar market. Advancements in production methods, particularly pyrolysis and gasification, enable efficient conversion of biomass into biochar, encouraging wider adoption across various sectors. The integration of automated processes and smart technologies streamlines operations, improving yield and reducing costs. These innovations attract more stakeholders, increasing competition and driving down pricing, which expands the market’s reach.
Emerging regional demands represent another driving force behind market growth. Regions including North America and Europe exhibit heightened interest in biochar applications, particularly within agriculture and environmental management. The pursuit of sustainable farming practices, coupled with rising awareness of carbon sequestration benefits, increases the demand for biochar. This trend encourages suppliers to diversify their offerings and explore strategic partnerships to meet specific regional needs.
Geographical expansion significantly shapes market dynamics. Countries in Asia Pacific, particularly China and India, engage in scaling production capabilities to meet domestic and export demands. Infrastructure modernization further supports this growth by enabling enhanced logistics and supply chain management, ensuring timely delivery of biochar products to various end-users.
Digital transformation contributes significantly to evolving buying behaviors within the market. Increased reliance on digital procurement platforms enables customers to access a wider array of products and suppliers, facilitating more informed purchasing decisions. Enhanced transparency in the supply chain enhances buyer confidence, driving further market penetration.
Sustainability imperatives drive alignment with environmentally friendly practices across industries. End-users increasingly seek products that align with environmental, social, and governance (ESG) criteria. The Biochar market benefits from this shift, driven by biochar’s carbon-negative profile, which positions it because a viable solution for industries aiming to reduce their carbon footprint.
Overall, the synthesis of technological innovations, regional demands, geographical expansion, and digital transformation creates a favorable environment for the Biochar market. Stakeholders that strategically navigate these emerging trends will capture significant market share and drive long-term growth.
The Global Biochar market is segmented based on Technology, Feedstock, and Application.
Valued at USD 598.5 million in 2026, the Pyrolysis segment is projected to reach USD 1,475.5 million by 2033, at a CAGR of 13.8% during the forecast period. Demand drivers include the increasing need for effective waste management solutions and the push for sustainable agricultural practices. Technological maturation in pyrolysis processes enhances efficiency, attracting investment and driving adoption across various industries. Next-generation upgrades focus on improving conversion rates and product quality, enabling wider application in agriculture and soil enhancement.
The strong growth in the Biochar market aligns with rising global initiatives aimed at carbon sequestration and soil health improvement. Regulatory compliance, particularly concerning carbon emissions and agricultural sustainability, further drives adoption in sectors looking to mitigate environmental impact. The segment benefits from favorable policies promoting biochar utilization, creating strategic opportunity windows for stakeholders. Cost structures in pyrolysis production are increasingly favorable due to technological advancements that streamline operations and reduce raw material sourcing challenges.
Pricing volatility impacts the market dynamically, influenced by raw material availability and production costs. Supply chain resilience remains critical, with logistics vulnerabilities addressed through better sourcing strategies and enhanced partnerships. Substitution risks from alternative technologies prompt continuous innovation within the pyrolysis domain, ensuring competitive positioning in the market. The focus on disruptive alternatives fuels product evolution, supporting expansive growth driven by industries seeking to meet sustainability goals.
In the Biochar market, the Gasification segment is estimated to reach USD 785.1 million by 2033, at a CAGR of 17.2% during the forecast period. This growth results from increasing demand for efficient waste-to-energy solutions and the rising focus on sustainable agricultural practices. The adoption of gasification technology by various industries demonstrates its potential in converting organic waste into valuable biochar, while simultaneously producing energy. This dual benefit attracts investments, enhancing operational efficiencies in energy production and waste management.
Technological maturation is essential for the expansion of the gasification segment. Advancements in gasification processes improve yield rates and reduce emissions, thus aligning with global environmental standards. The development of next-generation gasifiers emphasizes higher efficiency and lower operational costs, appealing to investors and end-users alike. Increased awareness about the advantages of biochar in carbon sequestration and soil enhancement further drives market growth.
Regulatory compliance standards regarding waste management and emissions control strengthen the demand for biochar produced through gasification. The ability of this technology to meet stringent environmental regulations positions it favorably in the market. Companies leveraging gasification processes gain a competitive edge in the evolving market of biochar production, enhancing their market share and profitability.
Cost structures linked to the gasification technology reflect both operational expenditures and capital investments. Pricing volatility in raw materials influences the economic feasibility of gasification systems. Despite price fluctuations, the long-term benefits of gasification, including reduced waste disposal costs and energy savings, support its implementation across various sectors.
Strategic opportunity windows arise from the growing trend toward circular economies and sustainable practices. Collaboration among players in the Biochar market accelerates innovation and the development of new applications for gasification-derived biochar. This collaboration creates a robust investment climate, driving advancements in technology and expanding the reach of gasification because a preferred method of biochar production.
Technological advancements in the Biochar market promote diversification within the Others segment, enabling innovative processes and applications. This sub-segment encompasses various emerging technologies that enhance biochar production efficiency and environmental benefits. Investment in research and development accelerates the emergence of next-generation solutions that address specific agricultural and industrial needs.
Adoption of biochar across different sectors reflects shifting consumption patterns, emphasizing the importance of sustainability and eco-friendliness. Regulatory compliance and voluntary certifications further support the segment's growth outlook, motivating manufacturers to explore alternative feedstocks and production methods. Strategic collaborations among industry players heighten the competitive landscape, driving innovation and market penetration.
The Others segment is projected to reach USD 172.2 million by 2033. This growth presents significant opportunities for companies focused on developing unique solutions tailored to diverse end-use applications, including soil enhancement and carbon sequestration. By capitalizing on emerging trends, businesses strengthen their market position and respond to evolving consumer demands.
Valued at USD 539.4 million in 2026, the Woody Biomass segment is projected to reach USD 1,463.6 million by 2033, with a CAGR of 15.3% during the forecast period. Increased recognition of biochar's benefits in enhancing soil health and its role in carbon sequestration drives demand for this feedstock. The agricultural sector primarily focuses on improving crop yields and soil fertility with woody biomass. Regulatory support for sustainable agricultural practices further boosts segment growth, owing to governments implementing policies incentivizing carbon-neutral technologies.
Technological maturation within biochar production processes enhances the reliability and efficiency of woody biomass use. Continuous advancements in pyrolysis and gasification technologies facilitate improved conversion rates and product quality. Market players increasingly emphasize next-generation upgrades, focusing on optimizing the carbonization process to maximize output and minimize emissions. These developments create strategic opportunity windows for investment, encouraging firms to enhance production capacities and market penetration.
While the biochar market evolves, consumption shifts toward applications that demonstrate clear environmental benefits. Increased awareness of the product's capabilities in carbon management and agriculture leads to rising adoption rates among farmers and agribusinesses. This growing focus on sustainability reinforces market dynamics, positioning woody biomass because a crucial component of eco-friendly agricultural practices. The anticipated expansion of the market highlights the significance of this feedstock in addressing both agricultural productivity and climate change challenges.
Increasing demand for sustainable agricultural practices drives the adoption of biochar derived from animal manure. This feedstock type enhances soil fertility and water retention, making it attractive for farmers seeking effective solutions for crop production. Environmental regulations promoting waste reduction and nutrient recycling create additional incentives for using animal manure in biochar production.
Animal manure segment is estimated to reach USD 591.7 million by 2033, at a CAGR of 14.5% during the forecast period. This growth reflects a broader trend of integrating organic waste management practices into agricultural systems. The transition supports circular economy principles by turning waste into a valuable resource, thereby reducing disposal costs for livestock producers.
End-use dynamics show a growing preference for organic fertilizers and soil amendments, aligning with the increasing consumer demand for organic produce. The market for biochar drawn from animal manure benefits from this shift, positioning itself because a viable alternative to synthetic fertilizers. Technological maturation in biochar production processes enhances efficiency and product quality, attracting investment and driving innovation.
Regulatory compliance standards reinforcing environmental sustainability strengthen market credibility and encourage stakeholders to invest in biochar solutions. While awareness of climate change impacts rises, agricultural practices incorporating biochar contribute to carbon sequestration efforts. This multifaceted approach positions the animal manure segment because a key player in the expanding biochar market.
Emerging feedstocks within the Biochar market represent diverse organic materials for production. The segment labeled "Others" incorporates various resources that do not fit the primary categories of woody biomass or animal manure. Factors driving adoption in this segment include rising demand for sustainable waste management solutions and the increasing recognition of biochar's environmental benefits.
The "Others" segment is projected to reach USD 377.6 million by 2033. This growth stems from the exploration and application of alternative feedstock sources, enhancing biochar production's flexibility and accessibility. Industries engaged in waste recycling and organic waste management find significant potential in transforming diverse organic materials into valuable biochar products.
Technological advancements support the segment's maturation, enabling efficient processing and conversion methods for varied feedstocks. Innovations in production methods enhance the quality and characteristics of biochar derived from unconventional sources, catering to specific agricultural and environmental applications.
Regulatory pressures and environmental standards drive companies to invest in sustainable practices. The push for reduced carbon footprints and improved soil health strengthens demand across agricultural applications, further supporting the growth of the "Others" segment in the Biochar market.
Investment in sustainable agricultural practices drives significant growth in the Biochar market. Valued at USD 629.8 million in 2026, the agriculture segment is projected to reach USD 1,682.1 million by 2033, at a CAGR of 15.1% during the forecast period. Increased awareness of the environmental benefits of biochar, including improved soil health and carbon sequestration, contributes to rising adoption rates among farmers. Enhanced soil fertility and moisture retention lead to better crop yields, attracting attention from agricultural stakeholders seeking innovative solutions to enhance productivity.
Technological maturation of biochar production processes, particularly pyrolysis and gasification, enables efficient conversion of organic materials into biochar. This advancement reduces production costs and improves the overall feasibility of integrating biochar into agricultural practices. Growing research efforts highlight the positive impacts of biochar on nutrient cycling and soil microbial activity, further validating its utility in agricultural applications.
Regulatory compliance and environmental certifications play a crucial role in shaping demand dynamics within the market. Policies promoting sustainable farming practices encourage the use of biochar because a soil amendment, aligning agricultural operations with environmental goals. Consequently, farmers increasingly incorporate biochar into their production systems to meet regulatory requirements and enhance market competitiveness.
End-use dynamics reflect a shift towards circular economy principles in agriculture, emphasizing waste reduction and resource efficiency. Biochar production from agricultural residues and waste materials supports this trend, offering farmers a means to manage waste while improving soil quality. The market outlook is robust, supported by the continuous evolution of biochar applications in agriculture, positioning it because a vital component of sustainable farming strategies.
Increasing emphasis on water quality and safety drives demand for advanced filtration solutions that use biochar. This material demonstrates significant adsorption properties, effectively removing contaminants from water sources, enhancing its appeal in various applications, including municipal water treatment and industrial processes. Regulatory compliance surrounding water quality standards supports growth within this segment, encouraging investments in biochar-based filtration technologies.
The water filtration segment is estimated to reach USD 211.7 million by 2033, at a CAGR of 15.9% during the forecast period. Rising environmental awareness promotes the adoption of sustainable practices among industries and consumers alike, further enhancing market growth. Significant advancements in technology and product evolution support the development of next-generation filtration systems, equipped with improved efficiency and performance metrics.
While the biochar market evolves, potential expansion opportunities arise in developing regions where water scarcity and pollution pose pressing challenges. This segment's growth will benefit from strategic capital investments targeting innovative applications and the continuous improvement of production methods, ensuring the material's competitiveness against traditional filtration media.
Demand for biochar because an Animal Feed Additive stems from its potential to enhance animal health and productivity. Incorporating biochar into animal feed improves nutrient absorption and supports gut health, leading to better growth rates in livestock. Growing awareness of animal welfare and sustainable farming practices stimulates interest in biochar applications across the agriculture sector. This segment is projected to reach USD 153.5 million by 2033, reflecting a significant opportunity for manufacturers and suppliers within the biochar market.
Factors driving the expansion of this segment include increased consumer preference for sustainably sourced food products. Ruminants and poultry benefit from the inclusion of biochar in their diets, which enhances overall feed efficiency. Understanding the regulatory compliance standards surrounding animal feed products further influences adoption rates. The rising focus on environmental sustainability motivates producers to explore innovative feed solutions, emphasizing biochar's positive environmental attributes.
Pricing volatility in raw materials used to produce biochar impacts its market dynamics. Fluctuations in feedstock availability and quality create challenges for suppliers, compelling them to establish resilient supply chains. Strategic investments in research and development play a crucial role in mitigating these risks, supporting technological maturation within the segment. Overall, the Animal Feed Additive sub-segment represents a compelling avenue for growth in the biochar market, driven by evolving consumer preferences and regulatory pressures.
Interest in biochar for electricity generation grows in response to increasing energy demands and environmental sustainability initiatives. The pursuit of renewable energy sources drives the expansion of this segment, with electricity generation from biochar offering a carbon-negative alternative to traditional fossil fuels. Technological advancements in conversion processes, including gasification and pyrolysis, enhance efficiency and reduce emissions, aligning with global efforts to mitigate climate change.
Electricity Generation segment is projected to grow at a CAGR of 13.8% during the forecast period. This growth reflects the increasing adoption of biochar because a reliable energy source, particularly in regions prioritizing renewable energy solutions. The market benefits from supportive regulatory frameworks, encouraging investment in clean energy technologies and enhancing the viability of biochar-based electricity generation systems.
Strategic opportunities arise from the integration of biochar into existing energy infrastructures, providing a pathway for energy producers to diversify their fuel sources and improve sustainability profiles. Demand for renewable energy escalates, and the biochar market stands poised for significant growth, driven by advancements in technology and a shift towards greener alternatives within the energy sector.
Shifts towards renewable energy sources significantly boost interest in heat generation applications using biochar. This trend aligns with global priorities for sustainable energy solutions, resulting in stronger demand from industries seeking to reduce carbon footprints and enhance energy efficiency. Biochar's unique properties enable its effective use in thermal energy production, which presents an attractive alternative to traditional fossil fuels.
Investment in technology development enhances innovation in biochar production processes, improving operational efficiencies and lowering costs. The continuous evolution of production methods supports the market, aligning with the growing need for efficient heat generation solutions. While industries pursue cleaner energy sources, biochar stands because a viable option, driving its integration into energy systems.
Increasing regulatory support for renewable energy initiatives shapes the market landscape. Governments worldwide implement policies favoring sustainable energy practices, which increase the potential for biochar in heat generation applications. This regulatory environment facilitates investment and adoption, ensuring that the market captures opportunities linked to government incentives for renewable energy sources.
In addition, the transition towards cleaner energy solutions reflects changing consumer preferences and societal expectations. Growing awareness of climate change and sustainability issues drives demand for alternatives to conventional fuels. Biochar's role in heat generation aligns with these shifting consumer attitudes, providing an eco-friendly solution that contributes to the overall sustainability goals of various sectors.
While industries and governments collaborate to achieve energy transition objectives, biochar's presence in heat generation applications is poised for expansion. This segment of the market exemplifies how biochar contributes to broader goals of environmental responsibility and energy efficiency, ultimately positioning itself because a key player in future energy solutions.
Growing interest in renewable energy sources increases the demand for biogas production within the Biochar market. This sub-segment benefits from the increasing focus on sustainable waste management practices, utilizing organic waste materials for energy generation. Adoption of biogas technology aligns with global initiatives aimed at reducing greenhouse gas emissions and enhancing energy security.
Technological maturation advances biogas production capabilities. Innovations in anaerobic digestion processes and integration with biochar applications enhance energy yield and overall efficiency. This evolution supports the expansion of biogas facilities and encourages investment in next-generation upgrades.
Compliance with regulatory standards drives strategic opportunities within this segment. Governments worldwide implement policies promoting renewable energy, creating a favorable environment for biogas initiatives. This regulatory landscape influences market dynamics by incentivizing investments and encouraging partnerships among stakeholders.
Cost structures and pricing volatility impact investment decisions in biogas production. While the initial capital investment for biogas facilities presents challenges, long-term benefits, including energy savings and reduced waste disposal costs, enhance the segment's attractiveness. The resilience of supply chains for raw material sourcing ensures consistent availability of feedstock for biogas production.
Competition from disruptive alternatives, including fossil fuels, persists but creates strategic windows for biogas production investments. Rising consumer awareness of sustainability drives demand toward greener energy solutions, further enhancing the role of biogas within the broader Biochar market. Overall, the segment presents a compelling opportunity for companies seeking to capitalize on the transition to renewable energy sources.
Growing applications for biochar in various industries contribute to the expansion of the market. Downstream applications of biochar extend beyond traditional agricultural use, with increasing interest in its role in environmental remediation, carbon sequestration, and soil enhancement. Regulatory compliance standards surrounding environmental sustainability push industries to explore innovative ways to apply biochar in diverse applications, enhancing its market relevance.
Technological maturation influences the development of the Others segment, facilitating enhanced product evolution and efficiency in biochar production processes. Innovations in production methods, including improved pyrolysis technology, enable the generation of biochar with specific characteristics to meet varying end-use requirements. These advancements position the market for strategic opportunity windows, allowing stakeholders to capitalize on new applications and fill market gaps.
End-use dynamics within the Others segment highlight a shift in consumption patterns attributed to industries increasingly recognizing the environmental benefits of biochar. Growing consumer awareness regarding sustainability drives demand for biochar in emerging applications, using its unique properties for enhanced performance in various sectors. This trend opens avenues for diversification and expansion, reinforcing the market's growth trajectory.
Ongoing investment in research and development further strengthens the market's position, with stakeholders focusing on maximizing biochar's potential in innovative applications. The biochar market remains dynamic, with continuous exploration of next-generation upgrades and disruptive alternatives, ensuring its relevance across various sectors. This evolution creates a robust environment for capital investment and supports the overall growth of the biochar market.
Based on geography, the Global Biochar market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America represents a significant portion of the Biochar market, contributing 56.7% of the global market share in 2025. The market expands at a CAGR of 14.9% within the forecast period, reaching a market size (TAM) of USD 1,162.9 million by the end of 2033. Key demand drivers include a growing focus on sustainable agricultural practices and the increasing need for effective carbon sequestration strategies. Investments in innovative biochar technologies are prevalent, particularly in the United States, Canada, and Mexico, leading to enhanced product availability and performance.
The region's agriculture sector evolves rapidly, with rising adoption rates of biochar because a soil amendment. This trend improves soil health and supports crop yields, directly aligning with the increasing emphasis on sustainable farming. Infrastructure modernization initiatives within North America facilitate the development of biochar facilities, enabling localized production and reducing transportation costs. Emerging market front-runners focus on advanced feedstock utilization, including woody biomass and agricultural residues, which enhance the market's growth potential.
Competition within the North American Biochar market intensifies, with several domestic players actively expanding their operations and product offerings. Companies pursue strategic partnerships and collaborations to leverage local expertise and strengthen their market position. Factors including localized procurement dynamics and cultural nuances significantly influence B2B buying behaviors, resulting in tailored marketing strategies and customer engagement approaches.
Geographic regulatory frameworks in North America become more supportive of biochar adoption, with increasing recognition of its environmental benefits. Compliance mandates and governmental incentives for carbon reduction contribute to an encouraging landscape for market participants. The combination of these elements positions North America because a critical growth region in the Biochar market, with substantial opportunities arising from both established and emerging applications.
The Biochar market in Europe experiences significant growth, driven by a combination of factors including a strong emphasis on environmental sustainability and innovative agricultural practices. Countries like Germany, France, the UK, Italy, Spain, and Russia actively pursue biochar applications, aligning with regional policies promoting carbon sequestration and soil enhancement. This regional commitment to sustainability strengthens demand for biochar products across various sectors.
Investment in local production capabilities enhances market expansion. European nations prioritize infrastructure modernization and localized manufacturing densities, enhancing supply chain resilience for biochar. Increased regulatory frameworks supporting environmental compliance further stimulate growth opportunities within the market.
Germany leads in market share, driven by its advanced agricultural sector and commitment to sustainable practices. France and the UK follow closely, leveraging innovative technologies to optimize biochar production and application. The growing trend of sustainable and organic farming practices generates a favorable environment for biochar adoption, highlighting the applications of this product in enhancing soil quality and crop yields.
Market dynamics reflect a mature landscape with established players focusing on product innovation and strategic partnerships. Competition within the market encourages vendor consolidation trends, contributing to enhanced operational efficiencies and expanded market reach. These localized procurement dynamics align with the cultural nuances and regional B2B buying behaviors prevalent across European countries.
Overall, the European Biochar market presents substantial growth potential, fueled by robust demand for sustainable solutions, investment in innovative technologies, and a strong regulatory framework that supports environmental initiatives.
Asia-Pacific represents a significant opportunity within the Biochar market, driven by increasing awareness of sustainable agricultural practices and environmental benefits associated with biochar usage. Countries including China and India focus on enhancing soil health and carbon sequestration. The regional infrastructure modernization efforts support the adoption of biochar technologies, particularly in agriculture, where efficient waste management and soil enhancement are crucial.
China's rapid industrial growth and urbanization have created a demand for innovative solutions to combat soil degradation, positioning the country because a vital player in the Biochar market. Japan and South Korea show strong investment in advanced biochar technologies, driven by government initiatives and private sector engagement focused on sustainability. Southeast Asia, with its diverse agriculture sectors, presents an underpenetrated territory with substantial growth potential for biochar applications.
Local manufacturers in the region increasingly collaborate with international players to enhance production capabilities and meet rising demand. This trend of regionalization in supply chains supports the growth of the market, allowing for localized manufacturing that aligns with cultural preferences and procurement dynamics. The Asia-Pacific region's unique circumstances create a competitive environment that encourages innovation and drives incremental growth vectors in the Biochar market.
The Biochar market in South America encounters unique dynamics shaped by the distinct agricultural practices and resource availability of Brazil and Argentina. The region's agricultural sector significantly influences market growth, driven by increasing awareness of sustainable farming methods and the environment. Brazil, because the largest economy in South America, presents an emerging market front-runner with substantial potential for biochar adoption. Localized manufacturing densities and increasing foreign direct investment (FDI) enhance the region's capability to produce biochar. These factors contribute to supply chain regionalization, improving access to the market. Cultural nuances and regional B2B buying behaviors further shape demand patterns in this territory. The market experiences complexities in compliance with local regulations, which impact adoption rates. By 2025, South America constitutes 3.4% of the global Biochar market, positioning itself because a niche yet significant participant in the industry. Efforts to improve energy grid resiliency through modern agricultural practices support biochar's role in sustainable solutions. Incremental growth vectors in the region indicate a favorable outlook for future market expansion.
The Biochar market in the Middle East and Africa presents unique characteristics influenced by diverse factors across the region. The region plays a substantial but developing role in biochar production and utilization.
Countries including Saudi Arabia, the UAE, and South Africa actively pursue sustainability initiatives, which drive demand for biochar in agricultural applications and environmental remediation. The focus on improving soil health and enhancing agricultural productivity aligns with regional goals for food security and resource efficiency.
Infrastructure modernization efforts, particularly in urban areas, support the implementation of biochar technologies. Localized manufacturing densities enhance supply chain efficiencies, creating a conducive environment for biochar producers. These dynamics indicate a potential for growth because market players seek to establish a foothold in underpenetrated territories.
The competitive landscape features domestic market participants that emphasize innovative solutions tailored to regional needs. These entities contribute to the development of localized procurement dynamics that align with cultural nuances and B2B buying behaviors, ensuring relevance in the market. Foreign direct investment flows into this region further create opportunities for market expansion and technological adoption.
Overall, the Biochar market in the Middle East and Africa reflects a landscape ripe for development, characterized by strategic entry barriers and the need for enhanced collaboration among stakeholders to realize the full potential of biochar applications.
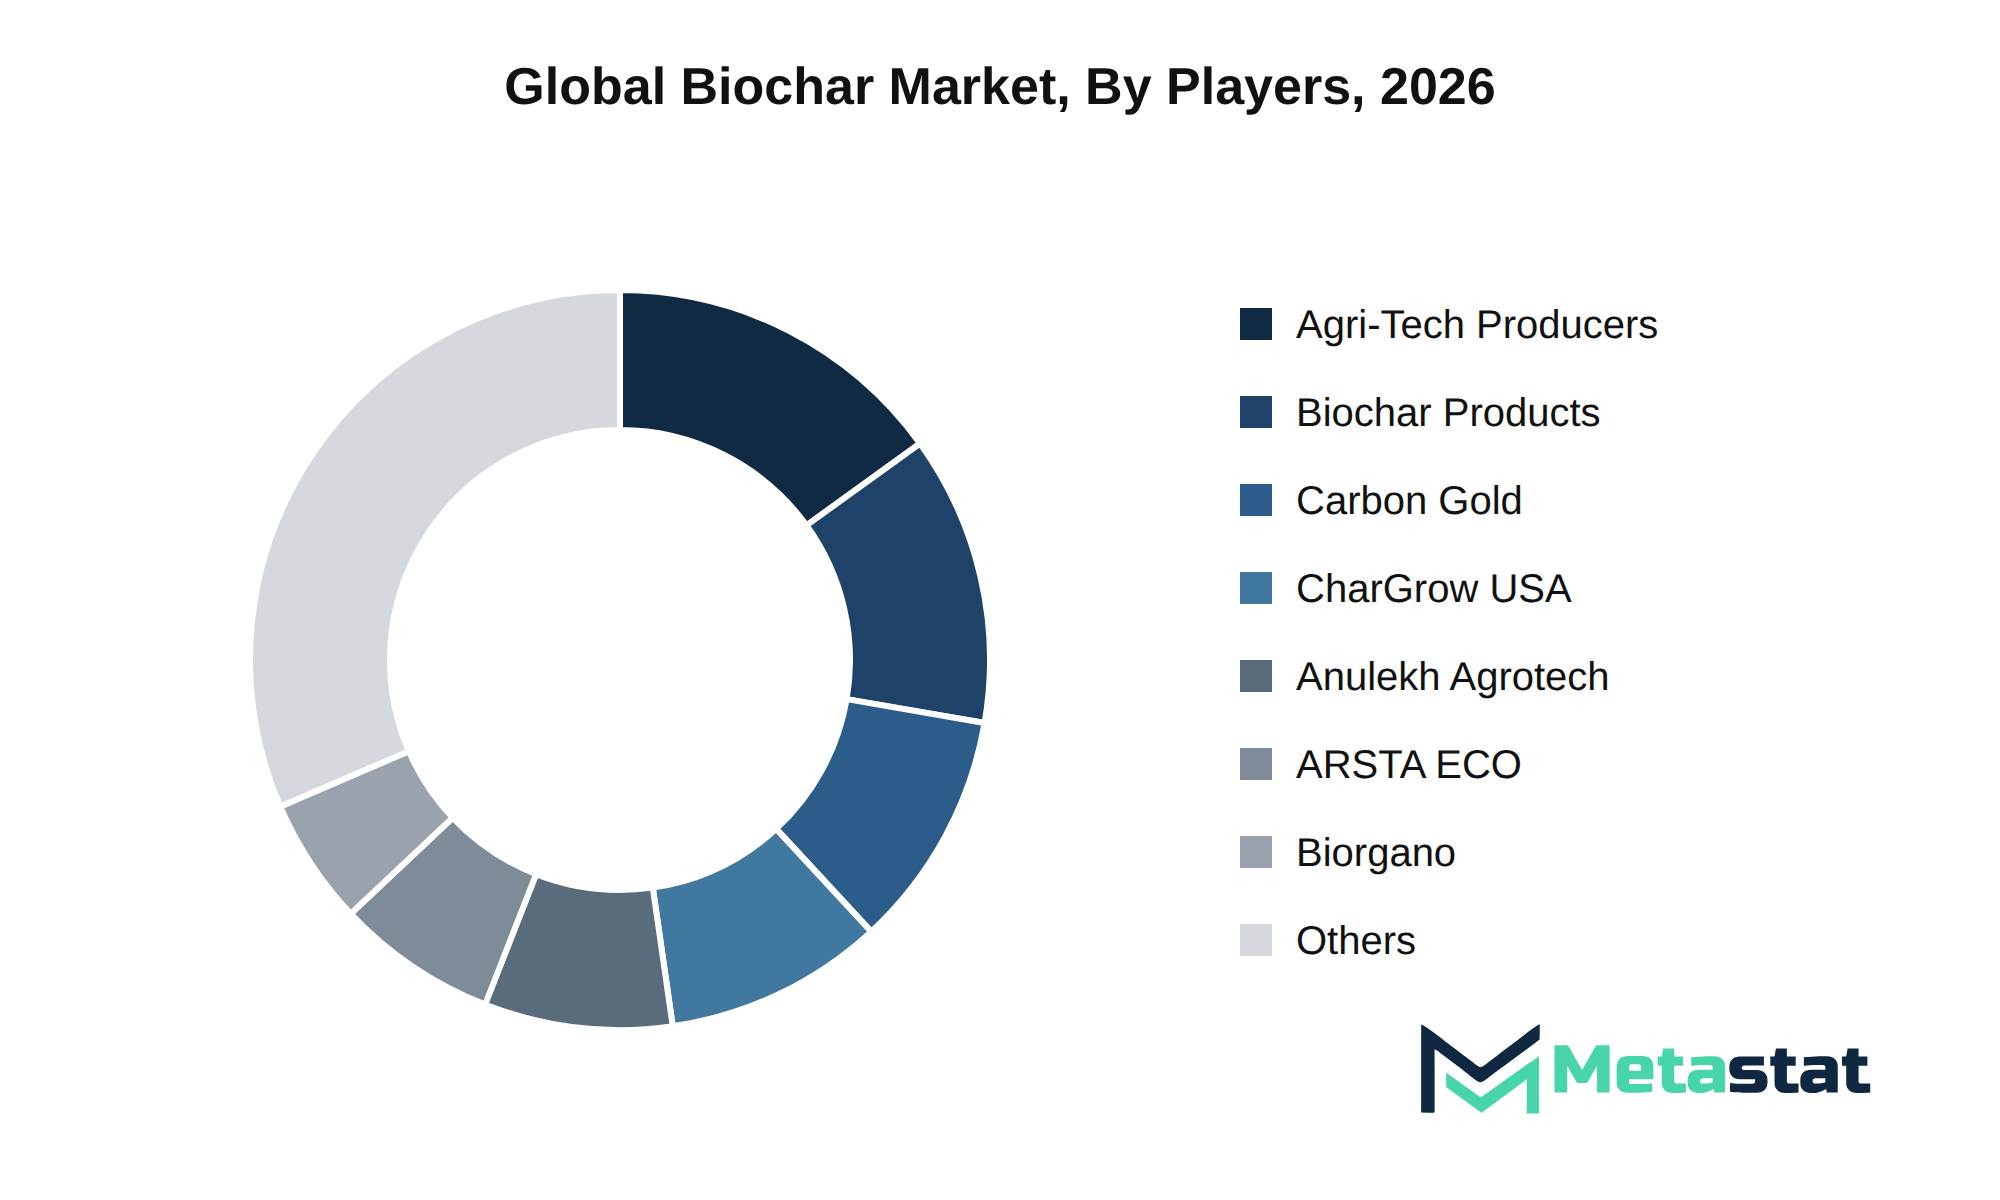
Competition within the Biochar market intensifies due to strategic consolidation and partnerships among various players. Companies actively pursue mergers and acquisitions to enhance their market position and broaden their product offerings. Notable companies engaging in these activities include Agri-Tech Producers LLC, AgroCCS, and Biochar Products, Inc. Their efforts focus on integrating value chains and optimizing supply chains to achieve procurement leverage.
Diverse go-to-market strategies characterize the market, with firms differentiating themselves through innovative technologies and product offerings. Companies including Carbon Gold and Cool Planet invest in R&D to develop proprietary technologies that strengthen their competitive advantage. Strategic alliances and joint ventures among players like EcoKrishi Solutions and Engrow Carbon facilitate access to new markets and enhance customer retention strategies, further enhancing brand equity.
Barriers to entry in the Biochar market include high initial investment costs and established relationships within the supply chain. New entrants face challenges from dominant players like CharGrow USA LLC and Synchar, which benefit from significant economies of scale and established customer bases. The future competitive outlook relies on the ability of companies to adapt to changing consumer preferences while maintaining sustainable practices and addressing environmental regulations.
Market size is forecast to rise from USD 800.6 million in 2025 to over USD 2,432.9 million by 2033. The base case indicates growth at a compound annual growth rate (CAGR) of 14.9%. Certain macroeconomic factors, including inflation trends and commodity prices, directly influence consumer behavior and industrial demand. Downstream sectors including agriculture and renewable energy increasingly adopt biochar technology, driven by environmental regulations and sustainability goals.
The bull case anticipates accelerated adoption driven by businesses pushing towards carbon neutrality and seeking innovative solutions for waste management. Conversely, the bear case considers potential setbacks from regulatory changes or economic downturns, which could dampen investment in new technologies. The market adapts through the integration of next-generation technologies and ongoing research and development efforts, enhancing the commercial viability of biochar applications across multiple sectors.
Regulatory frameworks evolve, impacting compliance timelines and enforcement measures that govern biochar production. Geopolitical shifts and trade dynamics alter supply chains, necessitating strategic capital allocation and infrastructure investments. Emerging opportunities include underserved markets and unmet enterprise needs, where growth potential resides. Focused efforts on product lifecycle management and the execution of defensibility roadmaps will dictate future growth trajectories in the biochar market.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Biochar market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 14.9% from 2026 to 2033 |
|
Revenue Unit |
USD million |
|
Segmentation |
By Technology, Feedstock, Application, and Region |
|
By Region |
North America (By Technology, Feedstock, Application, and Country)
|
|
Europe (By Technology, Feedstock, Application, and Country)
|
|
|
Asia Pacific (By Technology, Feedstock, Application, and Country)
|
|
|
South America (By Technology, Feedstock, Application, and Country)
|
|
|
Middle East and Africa (By Technology, Feedstock, Application, and Country)
|
Find answers to common questions about this report
The Biochar market size was valued at USD 800.6 million in 2025.
The Biochar market is projected to grow at a CAGR of 14.9% during the forecast period from 2026 to 2033.
The North America Biochar market size is estimated to reach USD 1,162.9 million by 2033.
The Agriculture application segment leads the Biochar market, with a projected value of USD 1,682.1 million by 2033. This segment demonstrates significant growth potential compared to other applications.
Growing concerns about environmental sustainability and climate change drive interest in biochar production. Emission limits imposed on industries encourage businesses to seek solutions that reduce their carbon footprint, influencing sectors including agriculture, waste management, and energy production. This trend leads to increased demand for biochar products, supporting market growth.
North America holds the dominant share of the Biochar market, accounting for USD 1,162.9 million in 2033, representing 56.7 percent of the total market.
Regulatory complexity, economic pressures, and supply chain disruptions hinder Biochar market growth. Navigating intricate compliance requirements increases operational costs and delays projects, while high initial investments deter potential investors. geopolitical instability and resource scarcity complicate sourcing, affecting pricing stability and customer confidence.
Growing concerns about environmental sustainability and climate change drive interest in biochar production. Emission limits imposed on industries encourage businesses to adopt biochar to reduce their carbon footprint, enhancing soil health and capturing carbon. This trend influences sectors like agriculture and waste management, ultimately increasing demand for biochar products.
The Biochar market is estimated to reach a valuation of USD 2,432.9 million by 2033.
Key players in the Biochar market include Agri-Tech Producers LLC, Biochar Products, Inc., Carbon Gold, Cool Planet, Pacific Biochar Benefit Corporation, and PYREG.
Choose Your License
Global Biochar Market
The analysts below cover Chemicals and Materials research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
INDUSTRY CONSULTANT - CHEMICALS & ADVANCED MATERIALS
Chemicals and Materials · Machinery & Equipment · Packaging
Amit Gadhekar Consultant for Chemicals and Materials at MetaStat Insight, directing sector-specific intelligence, research, and strategic consulting across global chemical and processing markets.
Last Updated: September 2026
Transitioning ultra-class mining haul trucks to alternative power requires concrete data on remote hydrogen refueling infrastructure economics. The report evaluated megawatt-scale electrolyzer installation expenses, onsite storage safety mandates, and heavy-duty fuel cell stack degradation under continuous duty cycles. That technical rigor helped our engineers benchmark realistic total operating cost horizons for off-highway fleet decarbonization.
Enterprise zero-trust network rollouts are often slowed down by multi-cloud transit latency and proprietary hardware retirement schedules. This study provided realistic total cost of ownership models comparing cloud-delivered security edge solutions against traditional hardware refreshes. The analysis of contract renewal lengths and software maintenance fees gave us clear visibility into enterprise replacement cycles over the next three to five years.
Scaling antibody-drug conjugate manufacturing hinges on contract manufacturing availability for high-potency active ingredients. The MetaStat Insight analysis looked closely at global cleanroom slot constraints, bioconjugation batch failure rates, and supply chain redundancies between the US, Europe, and India. The supplier capability matrix proved genuinely useful for our team when mapping secondary source options across our clinical pipeline.
Explore related market intelligence reports worth reading alongside this one.