
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Building-Integrated Photovoltaic (BIPV) Roofing Market Size, Share, By Product Type (Solar Roof Tiles and Shingles, In-Roof Photovoltaic Modules, Solar Metal Roofing Systems, Photovoltaic Glass Roofs and Skylights, Others), By Technology (Crystalline Silicon, Thin-Film Photovoltaics, Others), By Roof Configuration (Pitched / Sloped Roofs, Flat / Low-Slope Roofs, Curved / Complex Roofs), By End-Use (Residential Buildings, Commercial Buildings, Industrial Buildings and Institutional & Public Buildings), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5400
September, 2026
255 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $19.7 Billion in 2025, projected to reach $78.3 Billion by 2033 at a 18.8% CAGR.
Dominant Segment: The solar roof tiles and shingles segment leads the market, driven by increasing consumer awareness of sustainability and energy efficiency, with a projected growth from USD 8.3 billion in 2026 to USD 29.6 billion by 2033.
Geographic Lead: The Asia-Pacific region is expected to grow the fastest, fueled by rapid urbanization and investments in renewable energy infrastructure, aligning with global sustainability goals.
What's Inside: This report provides a comprehensive analysis of the competitive landscape, market dynamics, and detailed forecasts for the Building-Integrated Photovoltaic (BIPV) Roofing market from 2026 to 2033.
Investment in infrastructure development: Increased spending on infrastructure, driven by GDP growth and public-private partnerships, enhances the adoption of BIPV technologies in new constructions and renovations.
Emerging demands for sustainable roofing: Growing environmental awareness and regulatory pressures are driving the demand for sustainable roofing solutions, particularly in urban areas where energy efficiency is critical.
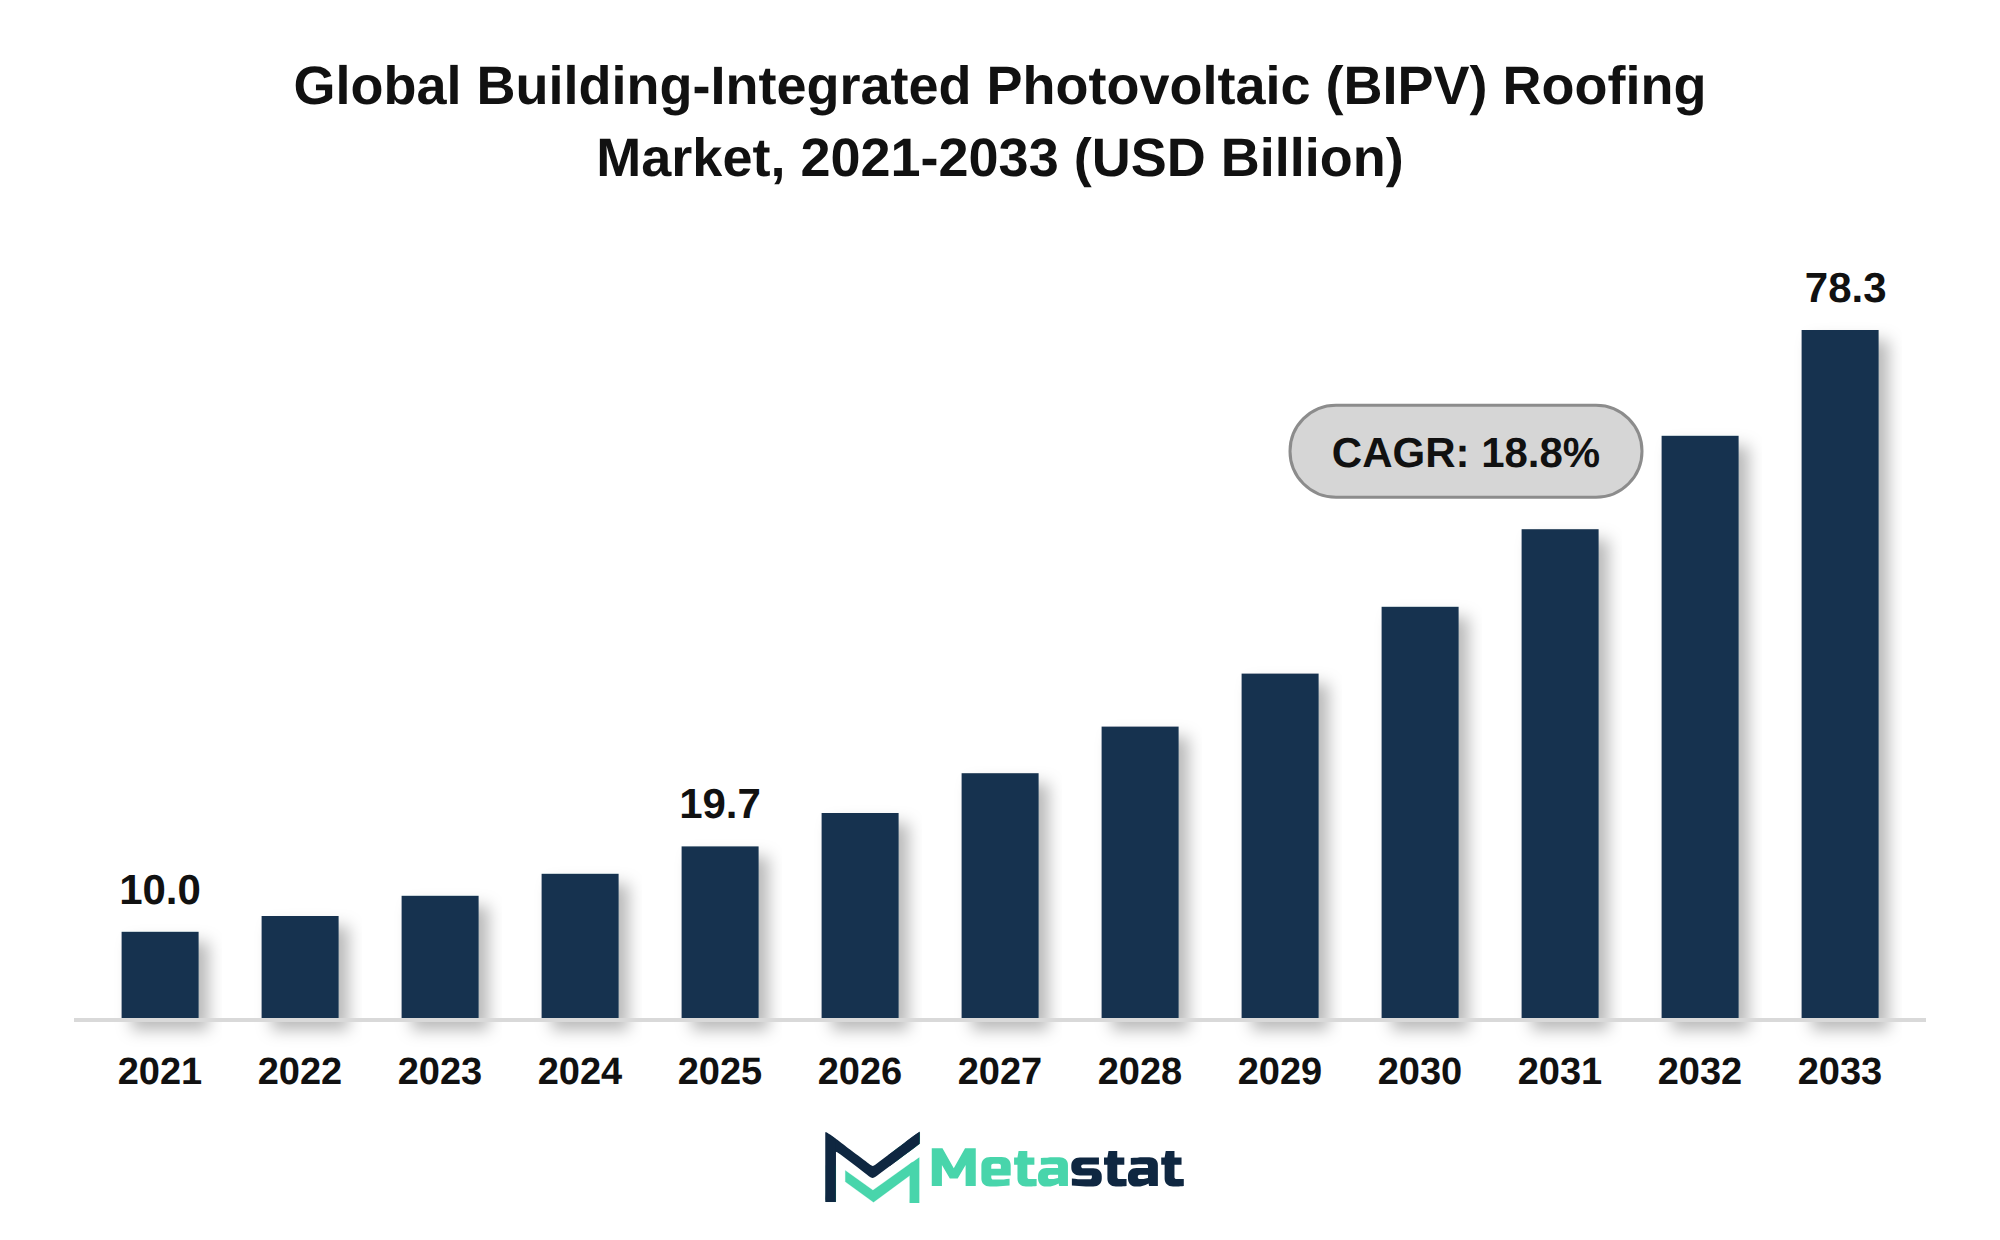
The global Building-Integrated Photovoltaic (BIPV) Roofing market was valued at USD 19.7 billion in 2025 and is projected to reach USD 78.3 billion by 2033, growing at a CAGR of 18.8% over the forecast period.
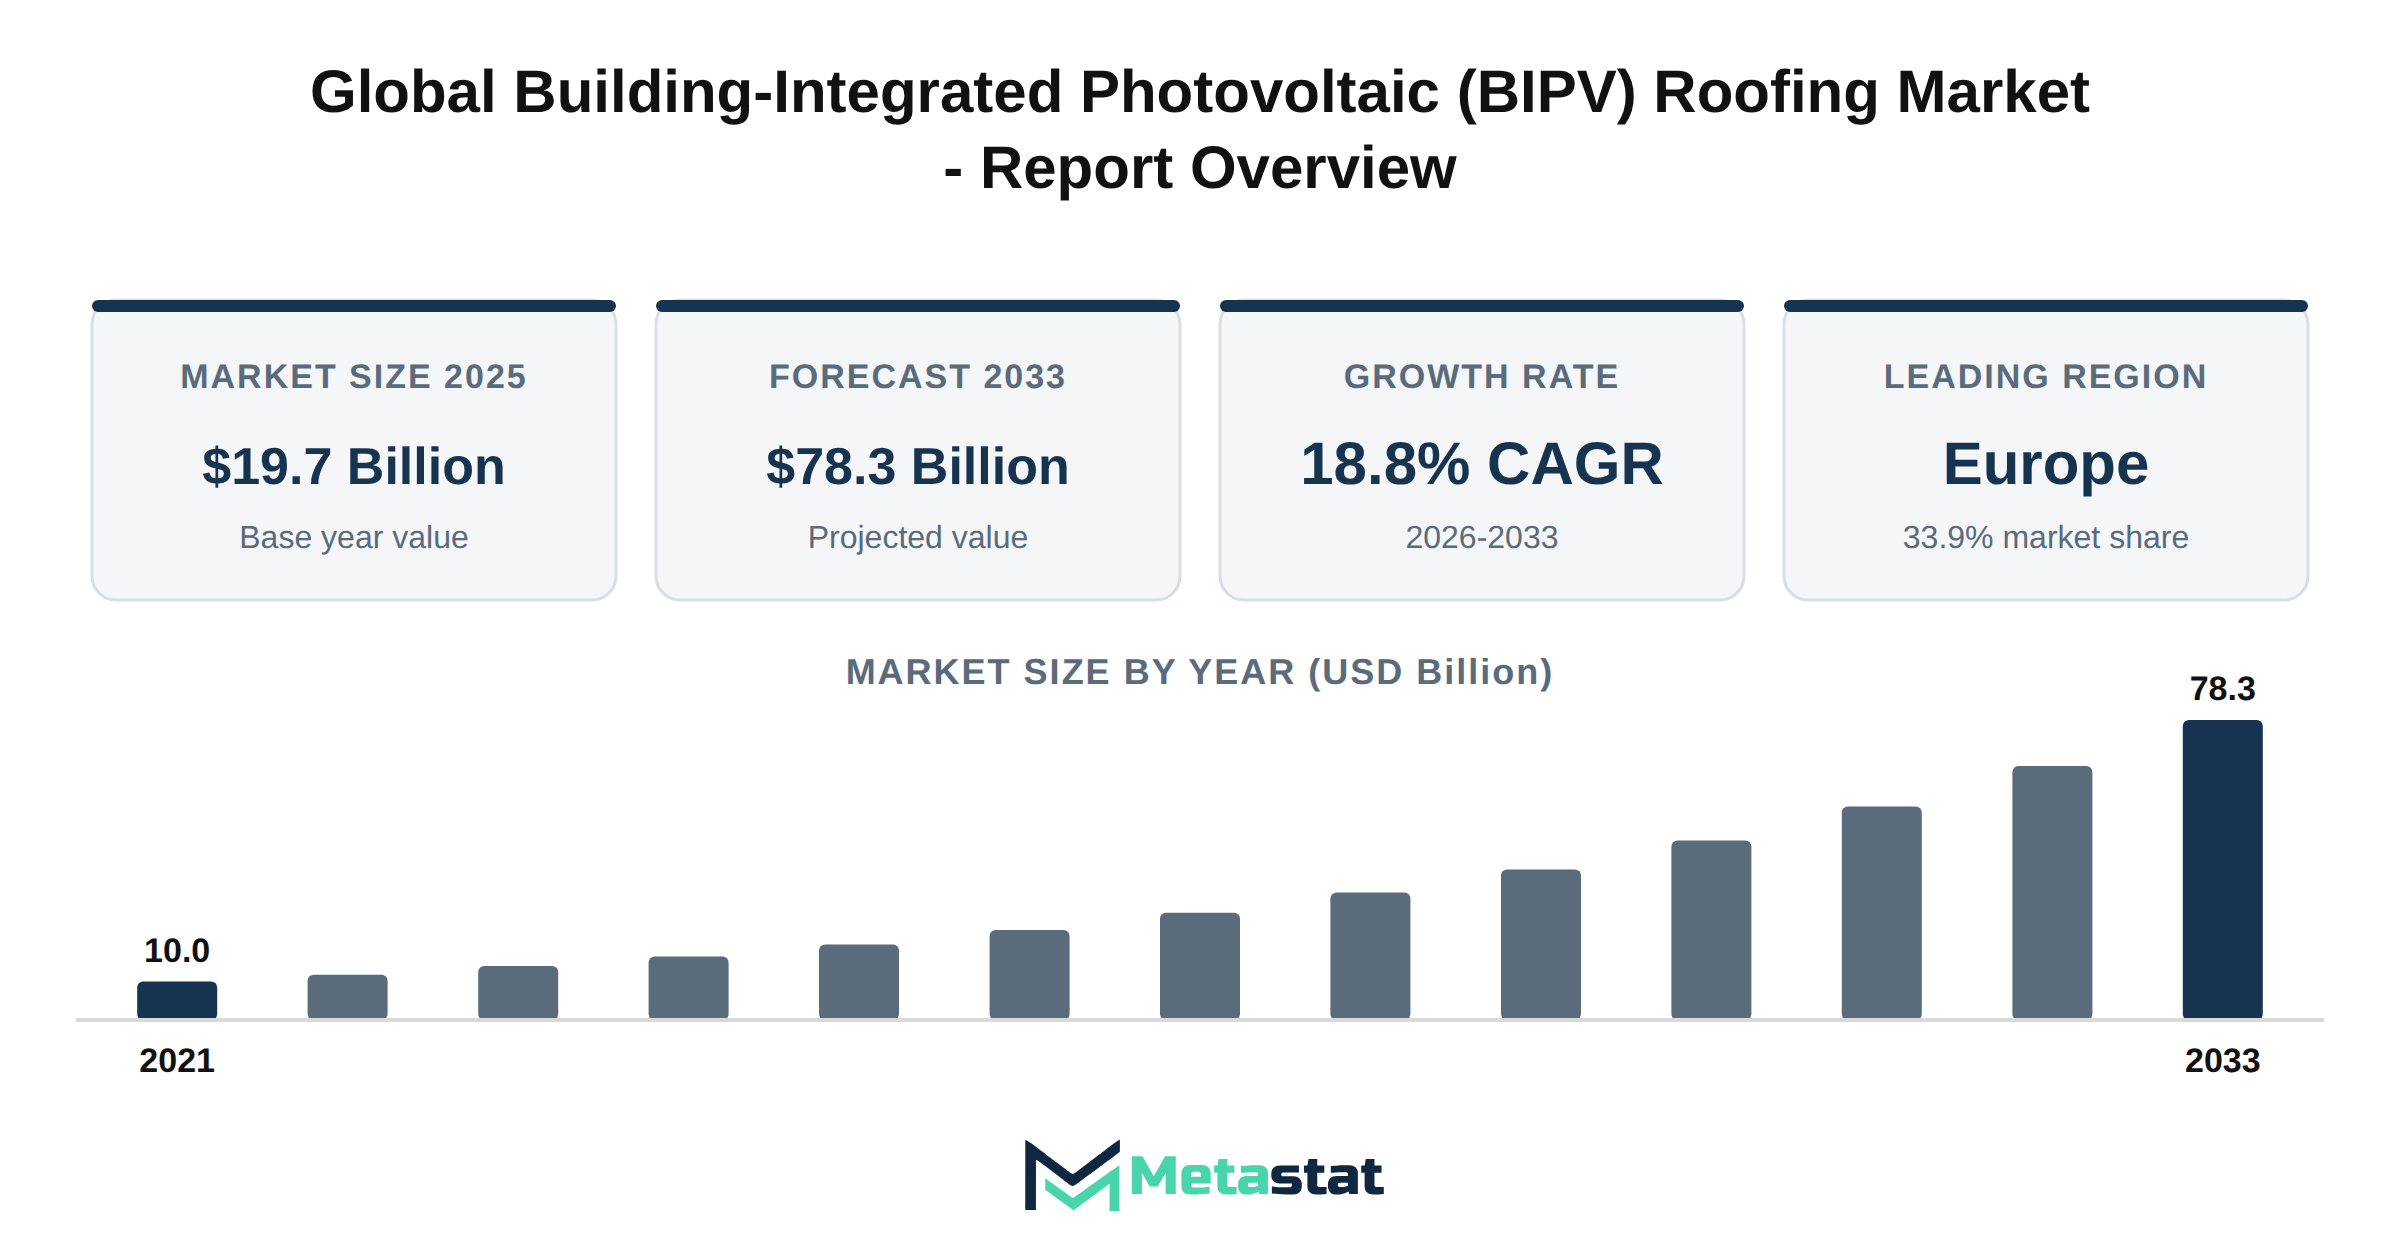
The Building-Integrated Photovoltaic (BIPV) Roofing market reached a value of USD 19.7 billion in 2025 and is projected to expand significantly, with a forecast of USD 78.3 billion by 2033. This represents a compound annual growth rate (CAGR) of 18.8% during the forecast period from 2026 to 2033. Historical growth figures show a steady increase from USD 10 billion in 2021 to USD 16.6 billion in 2024, indicating a robust trend in adoption.
Adoption trends in the market reflect growing awareness of sustainability and energy efficiency among consumers, driving demand for integrated solar solutions. The segment for solar roof tiles and shingles is anticipated to show particularly strong growth, expanding from USD 8.3 billion in 2026 to USD 29.6 billion by 2033, marking a CAGR of 19.9%. In-roof photovoltaic modules are gaining traction, with expectations of reaching USD 22.1 billion by 2033.
Crystalline silicon technology remains dominant in the BIPV Roofing market, with a projected increase from USD 17.8 billion in 2026 to USD 57.1 billion in 2033, reflecting a CAGR of 18.1%. Thin-film photovoltaics are emerging within integrated roofing applications, with an expected value of USD 16 billion by 2033, achieving a notable growth rate of 20.2%.
The demand for BIPV Roofing in residential buildings is set to rise significantly, growing from USD 9.1 billion in 2026 to USD 31.6 billion by 2033, driven by increasing consumer preference for sustainable living solutions. Commercial buildings are embracing integrated solar roofs, with a projected market size of USD 25.9 billion by 2033, demonstrating a CAGR of 18.3%.
Developments in solar metal roofing systems and photovoltaic glass roofs facilitate further market expansion. Solar metal roofing systems are expected to reach a value of USD 14.5 billion by 2033, while photovoltaic glass roofs and skylights increasingly integrate into modern architectural designs, enhancing aesthetic appeal and energy efficiency. Economic advantages of BIPV roofing solutions contribute to growing adoption, supported by net-zero building policies and green building certifications.
Building-Integrated Photovoltaic (BIPV) Roofing adoption trends reflect a significant shift towards sustainable energy solutions in the construction industry. Increased environmental awareness and stringent regulations drive the demand for integrated solar solutions, particularly in residential and commercial sectors. Stakeholders recognize the long-term value generated through energy savings and enhanced property value.
Demand growth for solar roof tiles and shingles demonstrates a robust trajectory, with projections indicating substantial market expansion through 2033. These products offer aesthetic advantages alongside functionality, appealing to homeowners and builders seeking to integrate renewable energy seamlessly into building designs.
Innovation in in-roof photovoltaic modules continues to reshape the market for solar technology. Enhanced efficiency and aesthetic design features contribute to the growing acceptance of these systems in both new constructions and retrofits. The integration of advanced materials supports the functionality and lifespan of these products.
Crystalline silicon remains the dominant technology in BIPV roofing, accounting for a significant share of the market. Its established performance and efficiency in energy conversion reinforce its popularity among consumers and builders. The anticipated growth in this segment is supported by ongoing advancements in solar cell efficiency and manufacturing processes.
Thin-film photovoltaics are gaining traction in integrated roofing applications, offering lightweight and flexible solutions ideal for various roofing configurations. Their lower production costs and versatility enhance their appeal in the market, particularly for unique architectural designs and renovation projects.
BIPV roofing demand across residential buildings highlights the increasing inclination towards sustainable living. Homeowners are increasingly investing in integrated solar solutions, motivated by both environmental concerns and the potential for reduced energy bills. This trend aligns with the broader shift towards energy-efficient home designs.
Commercial building adoption of integrated solar roofs reflects a growing commitment to sustainability among businesses. Corporations prioritize environmentally responsible practices, enhancing their public image while benefiting from energy savings. This segment's growth aligns with corporate sustainability initiatives and regulatory pressures.
Developments in solar metal roofing systems indicate a rising preference for durable and energy-efficient materials in construction. These systems offer longevity and performance, appealing to builders and property owners focused on long-term investments and reducing operational costs.
Integration of photovoltaic glass roofs and skylights represents an innovative approach to BIPV roofing. This technology allows natural light infiltration while generating renewable energy, enhancing the aesthetic appeal and functionality of buildings.
Cost considerations and installation economics significantly impact the BIPV roofing landscape. While initial investments are substantial, long-term savings on energy bills and potential tax incentives enhance the overall value proposition for consumers and builders alike.
Net-zero building policies drive BIPV roofing demand, owing to municipalities and governments mandating energy-efficient construction practices. Compliance with these regulations incentivizes the adoption of solar technologies, ensuring alignment with sustainability goals.
Building codes and solar roofing regulations play a critical role in shaping the BIPV roofing market. Compliance with evolving standards ensures safety and performance, influencing consumer confidence in integrated solar solutions.
Green building certifications support BIPV roofing adoption by providing frameworks for evaluating sustainability. These certifications encourage builders and developers to incorporate solar technologies into their projects, enhancing market visibility and appeal.
Developments in the roofing material and photovoltaic supply chain further optimize the BIPV roofing sector. Streamlined processes and innovative materials enhance production efficiency, ultimately benefiting consumers through reduced costs and improved product availability.
Energy efficiency mandates accelerate BIPV roof deployment, aligning construction practices with national and regional sustainability targets. These initiatives encourage investments in solar technologies, supporting the market's growth trajectory.
Architectural integration and aesthetic solar roofing trends influence consumer preferences significantly. Builders increasingly prioritize designs that blend aesthetics with functionality, ensuring that solar solutions enhance rather than detract from architectural appeal.
Smart building integration with BIPV roofing systems represents a technological advancement in energy management. The ability to monitor and optimize energy use through integrated systems appeals to tech-savvy consumers and businesses focused on sustainability.
High-efficiency solar cell technologies for BIPV roofs continue to evolve, offering enhanced energy conversion rates. These innovations contribute to the overall effectiveness of integrated solar solutions in meeting energy demands.
Tandem and next-generation PV technologies in roofing signify the future direction of the market. These advancements promise improved efficiency and performance, capturing the interest of consumers and developers alike.
Retrofitting opportunities for building-integrated solar roofing present significant market potential. Older structures increasingly undergo renovations to incorporate modern solar technologies, enhancing energy efficiency and sustainability.
New construction demand for BIPV roofing systems aligns with broader trends towards sustainable building practices. Developers actively seek integrated solar solutions to meet consumer expectations and regulatory requirements, reinforcing the market's growth.
BIPV roofing performance and durability innovation focus on enhancing product reliability and lifespan. Continuous improvements in materials and technology ensure that integrated solar solutions meet the rigorous demands of modern construction.
Fire safety and weather resistance standards for solar roofs remain critical considerations in the industry. Compliance with these standards fosters consumer confidence and ensures the safety and longevity of integrated solar products.
BIPV roofing investment and project development activity reflects a growing commitment to renewable energy solutions. Increased funding for solar projects signifies confidence in the market's potential, driving further innovation and expansion.
Competitive innovation among solar roofing manufacturers intensifies because companies strive to differentiate their offerings. This dynamic environment encourages advancements in technology and product design, enhancing the overall appeal of BIPV roofing solutions.
Partnerships between roofing and solar technology companies strengthen market offerings. Collaborative efforts facilitate knowledge sharing and resource optimization, ultimately benefiting consumers through improved product availability and performance.
BIPV roofing opportunities in North America highlight the region's commitment to sustainability and renewable energy. The market is poised for significant growth, driven by regulatory support and increasing consumer demand for integrated solar solutions.
European building renovation policies supporting BIPV roofing reflect a comprehensive approach to sustainability. These initiatives encourage energy-efficient retrofitting, enhancing the market's growth potential across the region.
Asia Pacific growth opportunities for integrated solar roofs represent a dynamic segment within the market. Rapid urbanization and increasing energy demands drive the adoption of sustainable building practices, contributing to market expansion.
Emerging BIPV roofing demand in the Middle East illustrates the region's commitment to diversifying energy sources. Innovative solutions tailored to local climates and building practices enhance the market's appeal.
Future growth prospects for Building-Integrated Photovoltaic (BIPV) Roofing indicate a promising market fueled by technological advancements, regulatory support, and evolving consumer preferences.
Investment in infrastructure development significantly enhances the Building-Integrated Photovoltaic (BIPV) Roofing market. Increased spending on infrastructure results from various macroeconomic factors, including GDP growth and public-private partnerships, which create a favorable environment for BIPV adoption. Emerging trends in urbanization and sustainability further compel stakeholders to incorporate renewable energy solutions, including BIPV systems, into new constructions and renovation projects.
While urban centers expand, the demand for energy-efficient roofing solutions rises, providing ample opportunities for BIPV technologies. Investments directed towards modernizing existing facilities and updating building codes cater to the growing need for sustainable energy sources. This modernization prioritizes energy independence and carbon footprint reduction, aligning with the market's core values.
Public spending power significantly influences market dynamics, driven by government commitments to enhance energy infrastructure and promote renewable energy initiatives. The integration of BIPV in urban development projects not only ensures compliance with emerging environmental standards but generates economic benefits for both developers and end-users. The Building-Integrated Photovoltaic (BIPV) Roofing market is poised for substantial growth, supported by these macroeconomic trends and investment strategies.
Technological integration drives significant advancements in the Building-Integrated Photovoltaic (BIPV) Roofing market. The rapid adoption of automation, artificial intelligence, and software solutions enhances operational productivity and efficiency. Businesses increasingly prioritize digitizing legacy processes to streamline their operations, resulting in cost savings and improved performance metrics. This trend attracts capital investment, driven by firms recognizing the potential for enhanced profitability through technological upgrades.
Shifting consumer behaviors, influenced by urbanization and evolving lifestyle preferences, increase the demand for innovative solutions in the market. Customers seek sustainable and technologically advanced roofing options, encouraging manufacturers to invest in research and development. This focus on innovation drives competition and the introduction of new, high-performance products designed to meet modern energy and aesthetic requirements.
While companies enhance their technological capabilities, the market experiences growth in the adoption of advanced roofing systems, including crystalline silicon and thin-film photovoltaics. These technologies support the growing emphasis on resource stewardship and sustainability, aligning with global efforts to reduce carbon footprints. Consequently, increased competitive pressures prompt suppliers to improve their technology offerings, further accelerating growth within the market.
The Building-Integrated Photovoltaic (BIPV) Roofing market faces significant challenges due to stringent regulatory compliance requirements. These regulations demand extensive documentation and adherence to strict safety and performance standards, complicating the installation process for manufacturers and installers. Businesses navigate these complexities while associated costs and timelines escalate, deterring investment and hindering market entry.
Compliance hurdles lead to delays in project approvals, impacting the overall timeline for market deployment. Companies allocate resources to manage compliance, diverting attention from innovation and growth strategies. Fluctuations in regulatory frameworks across regions create an uneven playing field, complicating market participation for new entrants and smaller players.
In regions with stricter regulations, adoption rates slow down, contributing to a fragmented market. High compliance costs discourage investment in new technologies, limiting the potential for advancements within the Building-Integrated Photovoltaic (BIPV) Roofing market. The combination of these factors creates a challenging environment for stakeholders aiming to expand operations and capture emerging opportunities. Regulatory compliance challenges significantly impact market dynamics, shaping adoption rates and influencing competitive positioning.
Geopolitical fragmentation creates considerable challenges for the Building-Integrated Photovoltaic (BIPV) Roofing market, disrupting trade relationships and increasing tariffs. Political tensions between key global players result in unpredictable policy changes, affecting the flow of materials and technologies needed for BIPV production. Trade deficits contribute to increased costs, impacting manufacturers and end-users alike.
Supply chain instability emerges because a prominent obstacle. Components critical to BIPV systems often originate from various regions, and disruptions in one area lead to delays across the entire supply chain. These interruptions exacerbate pricing compression and margin pressures, compelling firms to reassess their sourcing strategies and operational costs.
Technological disruptions, stemming from rapid advancements, introduce complexities in research and development integrations. Companies in the market face pressures to innovate while dealing with rising input cost structures. Workforce skill gaps hinder the ability to leverage new technologies effectively, resulting in productivity challenges and slower adoption rates.
Environmental lifecycle footprints generate additional demands for sustainability, driving the need for compliance with tightening global regulatory standards. These requirements add compliance overhead, complicating operations for companies striving to meet evolving legal liabilities while maintaining profitability. Consequently, barriers to retrofitting and implementation limit growth potential.
The Building-Integrated Photovoltaic (BIPV) Roofing market benefits from increasing demands for sustainable roofing solutions across various regions. Consumers and businesses prioritize eco-friendly options owing to rising environmental awareness and regulatory pressures aimed at reducing carbon footprints. This growing commitment to sustainability drives up adoption rates, particularly in urban areas where energy efficiency and renewable resources are critical considerations.
Infrastructure modernization significantly contributes to this market's expansion. Countries worldwide invest in upgrading their energy frameworks, supporting the installation of innovative BIPV systems within broader renewable energy strategies. This aligns with global sustainability imperatives, creating a favorable environment for innovative roofing technologies that integrate seamlessly into existing structures.
Geographical expansion fuels growth, particularly in regions like North America and Europe, where policy initiatives encourage the use of renewable energy sources. These markets experience rising demand for BIPV solutions attributed to consumers seeking both aesthetic and functional benefits in roofing systems. The strategic alignment between market players and local governments enhances project viability and adoption rates across these regions.
Technological disruptions within the industry further strengthen the market. Advances in solar technology, including improved efficiency in crystalline silicon and thin-film photovoltaics, support innovative roofing solutions that align with consumer preferences for performance and sustainability. This technological evolution creates opportunities for product integration across various building types, catering to the needs of residential, commercial, and industrial sectors.
Downstream market diversification presents additional opportunities within the Building-Integrated Photovoltaic (BIPV) Roofing market. Companies increasingly explore niche applications and unique configurations to address specific architectural needs. This targeted approach enhances product offerings and creates avenues for strategic consolidation and partnerships, leading to greater market penetration and competitive positioning.
The Global Building-Integrated Photovoltaic (BIPV) Roofing market is segmented based on Product Type, Technology, Roof Configuration, and End-Use.
Valued at USD 8.3 billion in 2026, the Solar Roof Tiles & Shingles segment is projected to reach USD 29.6 billion by 2033, at a CAGR of 19.9% during the forecast period. This segment thrives on the growing demand for sustainable building solutions, driven by increasing consumer awareness of environmental issues and energy efficiency. Rising energy costs further drive residential and commercial consumers toward solar solutions, presenting a compelling incentive for adoption.
Technological advancements in solar roof tile design enhance aesthetic appeal, functionality, and energy output, contributing to the segment's growth. The development of next-generation materials and integration of energy storage solutions improve the overall performance and usability of solar roof tiles and shingles. Regulatory frameworks promoting renewable energy usage and incentivizing solar installations support segment expansion, leading to increased investments from manufacturers.
End-use dynamics highlight a significant shift toward residential buildings, where homeowners prioritize renewable energy for cost savings and sustainability. The commercial sector follows closely, adopting solar solutions to meet sustainability targets and reduce operational costs. While the Building-Integrated Photovoltaic (BIPV) Roofing market evolves, ongoing research into product evolution and enhanced efficiencies attracts a broader consumer base, further supporting growth.
Cost structures within the segment remain influenced by fluctuating raw material prices and the overall supply chain resilience. Competitive pricing strategies among manufacturers play a crucial role in attracting customers while maintaining profit margins. The growing availability of financing options for solar installations enhances accessibility, driving consumption shifts across various demographics. The outlook for the Solar Roof Tiles & Shingles segment remains strong, supported by strategic opportunity windows and an increasing emphasis on sustainable building practices.
Growth in the In-Roof Photovoltaic Modules segment aligns with increasing consumer interest in energy-efficient solutions and sustainable building practices. Factors driving this demand include advances in technology that enhance the efficiency of photovoltaic systems, making them more attractive to builders and homeowners. Stringent regulatory compliance standards regarding energy efficiency and sustainability are propelling adoption across various regions. The segment is estimated to reach USD 22.1 billion by 2033, at a CAGR of 18% during the forecast period.
Technological maturation has enabled the development of high-performance In-Roof Photovoltaic Modules, contributing to their competitive edge in the market. New innovations, including lightweight materials and integrated designs, facilitate easier installation and improved aesthetic appeal, catering to both residential and commercial segments. Energy consumption shifts toward renewable sources drive the segment's growth, with increasing emphasis on reducing carbon footprints influencing purchase decisions.
Investment in research and development continues to play a crucial role in product evolution, enhancing the performance and longevity of In-Roof Photovoltaic Modules. Strategic opportunity windows arise due to manufacturers exploring next-generation upgrades and emerging technologies, including tandem solar cells, which promise higher efficiency rates. These advancements position the market favorably for future growth, allowing players to capture a larger share of the renewable energy sector.
Pricing volatility in raw materials poses challenges, yet strategic sourcing and supply chain resilience support stability in production costs. Competitive pricing strategies implemented by key players in the Building-Integrated Photovoltaic (BIPV) Roofing market enhance accessibility for consumers, further driving adoption. Overall, the In-Roof Photovoltaic Modules segment is positioned for significant expansion, reflecting the broader trends in sustainability and renewable energy integration.
Increasing adoption of Solar Metal Roofing Systems aligns with the growing focus on renewable energy solutions. Environmental considerations and rising energy costs drive homeowners and businesses to seek sustainable alternatives for energy generation. This segment is projected to reach USD 14.5 billion by 2033.
Technological advancements in solar metal roofing enhance efficiency and performance, attracting commercial and residential sectors. Integration of energy-efficient materials and designs significantly influences market dynamics, promoting wider acceptance across various end-use segments.
Regulatory compliance significantly shapes market growth. Governments worldwide implement policies favoring renewable energy adoption, providing incentives that stimulate investments in solar technologies. This shift toward sustainability encourages manufacturers to innovate and improve their offerings, further expanding market opportunities.
Pricing volatility and raw material sourcing challenges impact cost structures, necessitating strategic approaches to maintain profitability. Manufacturers prioritize supply chain resilience to mitigate risks associated with disruption, ensuring steady product availability and competitive pricing.
Strategic partnerships among industry players facilitate knowledge sharing and resource optimization. Such collaborations contribute to the development of next-generation upgrades and technologies, positioning stakeholders favorably within the Building-Integrated Photovoltaic (BIPV) Roofing market. Continuous investment in research and development enhances competitive advantages and drives long-term growth.
Growth in the Photovoltaic Glass Roofs & Skylights segment significantly reflects the increasing demand for energy-efficient building solutions. This demand arises from stricter regulatory compliance standards and heightened awareness regarding sustainability among consumers. The segment is projected to grow at a CAGR of 17.4% during the forecast period, indicating robust adoption across various end-use applications, including residential and commercial buildings.
Technological maturation within the market provides innovative solutions that enhance product performance and aesthetics. Advances in glass technology, including enhanced transparency and durability, support the increasing integration of photovoltaic systems into building designs. These innovations attract both residential and commercial developers aiming to meet sustainability goals while enhancing building aesthetics.
Cost structures associated with Photovoltaic Glass Roofs & Skylights have improved due to increased competition and technological advancements, leading to decreased pricing volatility. This favorable pricing environment encourages broader adoption across different market segments, particularly in urban areas where space is limited and aesthetic considerations are critical.
Supply chain resilience remains a key factor influencing the segment. Raw material sourcing strategies focusing on sustainable and local suppliers enhance the market's stability. Strategic investment in research and development opens opportunities for next-generation upgrades that further distinguish offerings in the Building-Integrated Photovoltaic (BIPV) Roofing market.
Overall, the Photovoltaic Glass Roofs & Skylights segment is positioned for significant growth, driven by evolving consumer preferences, technological advancements, and supportive regulatory frameworks. This growth trajectory highlights the segment's role within the broader Building-Integrated Photovoltaic (BIPV) Roofing market.
Emerging trends indicate a growing interest in flexible and membrane-integrated photovoltaic roofing solutions. This sub-segment caters to the increasing demand for lightweight, aesthetically pleasing, and versatile solar options, which appeal particularly to architects and builders focused on innovative design. Adoption hinges on advancements in material science that enhance the performance and durability of these products, allowing for broader implementation across various roof types.
Technological maturation drives this segment's growth. Continuous improvements in efficiency and energy conversion rates contribute to heightened market confidence among consumers and commercial developers. Integration with smart building technologies facilitates the adoption of flexible solutions, aligning with modern architectural practices that prioritize sustainability.
Consumer preferences shift toward eco-friendly building practices, driving demand for products that blend seamlessly into existing structures. Regulatory compliance standards increasingly favor renewable energy solutions, creating a favorable policy environment for the adoption of flexible and membrane-integrated roofing technologies. While the building codes evolve to support green infrastructure, market players find strategic opportunities to enhance their product offerings.
Cost structures remain a consideration for stakeholders in this market segment. While initial investment appears higher compared to traditional roofing solutions, long-term energy savings and reduced carbon footprints offset these costs over time. Supply chain resilience becomes essential, particularly with regard to sourcing raw materials necessary for production, because fluctuations in availability impact pricing and operational margins.
In terms of competition, the flexible and membrane-integrated segment faces challenges from disruptive alternatives, including conventional roofing systems and emerging technologies. Strategic opportunity windows arise from the need for differentiation in product offerings, compelling manufacturers to innovate constantly and adapt to evolving consumer expectations. Investment in research and development remains vital because companies strive to position themselves effectively within the Building-Integrated Photovoltaic (BIPV) Roofing market.
Growing interest in sustainable energy solutions enhances the Crystalline Silicon segment within the Building-Integrated Photovoltaic (BIPV) Roofing market. Valued at USD 17.8 billion in 2026, this segment is projected to reach USD 57.1 billion by 2033, at a CAGR of 18.1% during the forecast period. Increased emphasis on renewable energy sources, alongside rising electricity costs, drives demand across residential, commercial, and industrial sectors.
Technological maturation enhances the efficiency and performance of Crystalline Silicon technologies. Innovations including bifacial solar modules and improved cell architectures contribute to higher energy conversion rates, supporting adoption across diverse applications. The growing focus on energy-efficient buildings further strengthens demand for advanced roofing solutions.
Regulatory compliance standards increasingly favor the integration of renewable energy systems into building designs. Governments worldwide implement policies that promote the use of BIPV technologies, including financial incentives and subsidies. This regulatory landscape encourages investments from developers and construction companies, enhancing the market's growth potential.
Cost structures associated with Crystalline Silicon production have improved significantly, driven by economies of scale and advancements in manufacturing processes. Reduced production costs enhance profitability for manufacturers while enabling competitive pricing for end-users. This trend accelerates the adoption of Crystalline Silicon roofing solutions within various building sectors.
The segment's resilience in the face of supply chain challenges demonstrates its adaptability and strategic opportunity windows. Effective raw material sourcing and logistics management strengthen the supply chain, minimizing disruptions. Market players continue to explore innovative materials and processes, ensuring sustainable growth in the Crystalline Silicon segment.
Significant growth in the Thin-Film Photovoltaics segment aligns with the increasing focus on sustainable energy solutions and advancements in photovoltaic technology. This segment is projected to reach USD 16 billion by 2033, at a CAGR of 20.2% during the forecast period. Various factors drive this expansion, including regulatory support for renewable energy initiatives, which incentivize the adoption of BIPV solutions across multiple sectors. Increased consumer awareness regarding energy efficiency and environmental impacts boosts demand for these innovative roofing systems.
Technological maturation enhances the performance and efficiency of thin-film photovoltaics, making them a competitive option in the market. Product evolution, including next-generation upgrades, facilitates greater integration into various architectural designs, maximizing energy generation while maintaining aesthetic value. Downstream applications in residential, commercial, and industrial buildings contribute to the segment's growth, offering tailored solutions for diverse end-use dynamics.
Cost structures associated with thin-film photovoltaic systems are becoming more favorable, driven by advancements in manufacturing processes and economies of scale. Pricing volatility in raw materials impacts profit margins; however, strategic investment in supply chain resilience mitigates risks associated with sourcing and logistics vulnerabilities. These dynamics create a strong investment outlook, enabling market participants to capitalize on strategic opportunity windows and meet the increasing demand for integrated solar solutions.
Innovation in photovoltaic technologies underpins segment growth within the Building-Integrated Photovoltaic (BIPV) Roofing market. The emergence of tandem and next-generation PV technologies enhances efficiency and expands application potential. Adoption of these advanced technologies aligns with increasing regulatory support for sustainable energy solutions. Regulatory compliance strengthens market foundations, stimulating demand across various end-use sectors.
Investment in research and development drives further advancements, supporting both product evolution and technological maturation. Increased efficiency translates into reduced costs over time, benefiting consumers and commercial entities alike. The segment demonstrates resilience amid price volatility, ensuring competitive positioning in a changing environment.
The Others (Emerging Tandem and Next-Generation PV Technologies) segment is projected to reach USD 5.2 billion by 2033. This growth reflects strategic opportunities arising from shifting consumer preferences towards more sustainable energy solutions.
While the market evolves, ongoing innovation will dictate the trajectory of this segment, influencing overall dynamics in the Building-Integrated Photovoltaic (BIPV) Roofing market.
Pitched / Sloped Roofs in the Building-Integrated Photovoltaic (BIPV) Roofing market demonstrates significant growth potential, with a valuation of USD 13.6 billion in 2026 and a projected increase to USD 43.3 billion by 2033, reflecting a CAGR of 18% during the forecast period. Demand for this segment is driven by rising consumer preference for energy-efficient solutions, alongside stringent regulatory frameworks promoting renewable energy adoption. The integration of advanced technologies enhances product appeal, offering consumers improved performance and aesthetic options.
Technological maturation in roofing materials and systems supports the expansion of the Pitched / Sloped Roofs segment. Innovations in design and efficiency contribute to product evolution, attracting both residential and commercial end-users. The growing emphasis on sustainable building practices influences investments in this segment, aligning with broader environmental goals. Consequently, the market anticipates a shift towards greater penetration of Pitched / Sloped Roofs in new constructions and retrofitting projects.
Regulatory compliance standards and financial incentives further drive adoption within the segment. Governments worldwide implement policies promoting renewable energy solutions, ensuring long-term viability for Pitched / Sloped Roofs. The market experiences shifts in consumption patterns owing to increased awareness of environmental impact and energy independence among consumers. Together, these factors position the Pitched / Sloped Roofs segment because a key contributor to the overall growth of the Building-Integrated Photovoltaic (BIPV) Roofing market.
Flat / Low-Slope Roofs represent an important segment within the Building-Integrated Photovoltaic (BIPV) Roofing market, with an estimated value of USD 27.8 billion by 2033, at a CAGR of 19.7% during the forecast period. This growth arises from the increasing emphasis on energy efficiency in building designs and the integration of renewable energy solutions into architectural frameworks.
Adoption of BIPV technologies in flat and low-slope configurations aligns with the shift towards sustainable building practices. These roof types offer substantial surface areas for solar installations, enhancing their appeal to commercial and residential developers focused on maximizing energy generation while minimizing aesthetic impact. This segment benefits from advancements in photovoltaic technology, leading to improved efficiency and durability.
The regulatory landscape significantly influences this segment, with policies promoting renewable energy and energy-efficient buildings driving demand. Compliance with building codes and standards enhances the attractiveness of flat and low-slope roofs equipped with integrated solar solutions. Continued investment in research and development drives innovation, ensuring competitive pricing structures and enhanced product offerings.
Technological maturation in this sector fuels market expansion. Manufacturers introduce next-generation upgrades that improve performance and reduce costs. The resilience of supply chains for raw materials essential to BIPV solutions mitigates risks associated with sourcing and logistics, further supporting segment growth. Strategic opportunity windows arise owing to increasing consumer awareness of the benefits of sustainable building practices, leading to heightened demand within the market.
Curved and complex roofs within the Building-Integrated Photovoltaic (BIPV) Roofing market represent a growing segment, projected to reach USD 7.3 billion by 2033. This growth reflects increasing demand for aesthetically pleasing and functional roofing solutions that integrate energy generation capabilities. Architects and builders increasingly prefer these designs for their innovative appeal and efficiency in energy capture.
Primary demand drivers include the rising need for sustainable building practices and the growing emphasis on energy efficiency in construction. Clients in both residential and commercial sectors prioritize unique roof configurations that enhance building aesthetics while providing long-term cost savings through energy generation. Stringent regulatory compliance standards regarding energy efficiency further accelerate adoption, prompting architects and builders to incorporate BIPV solutions into their projects.
Technological maturation supports segment expansion, with advancements in solar technology enabling better performance and adaptability for complex roof designs. Innovations in manufacturing techniques and material enhancements improve efficiency and lower production costs, enhancing competitiveness. Continuous upgrades in photovoltaic technology support the development of next-generation products, allowing more effective integration into curved roofing structures.
End-use dynamics reflect a shift toward more personalized building design, with increasing consumer interest in energy independence driving the demand for BIPV solutions. The segment experiences significant enthusiasm from residential builders, who recognize the long-term benefits of implementing solar solutions in unique roof configurations. This trend proves advantageous for manufacturers and suppliers who successfully navigate the evolving market.
Investment in the segment remains robust, with strategic opportunity windows emerging from ongoing urbanization trends and shifts in construction practices. The segment's resilience relies on supply chain stability and raw material sourcing strategies that mitigate cost pressures and enhance profit margins. Overall, the curved and complex roofs sub-segment within the Building-Integrated Photovoltaic (BIPV) Roofing market is poised for substantial growth, driven by technological advancements and increasing consumer demand for sustainable energy solutions.
Valued at USD 9.1 billion in 2026, the Residential Buildings segment is projected to reach USD 31.6 billion by 2033, at a CAGR of 19.4% during the forecast period. Increasing consumer awareness regarding energy efficiency drives demand for Building-Integrated Photovoltaic (BIPV) Roofing solutions in residential applications. Homeowners seek sustainable alternatives to traditional roofing materials, driving the adoption of photovoltaic technologies.
Technological advancements significantly enhance the performance of photovoltaic modules, supporting the segment's growth. Innovations in energy storage solutions improve the appeal of BIPV systems, allowing homeowners to maximize energy utilization. While the market evolves, increasing collaborations between manufacturers and technology providers encourage the development of next-generation products tailored to residential needs.
Government incentives and regulatory compliance standards promoting renewable energy adoption contribute to market expansion. Many regions implement policies encouraging the integration of solar technologies in residential construction, influencing consumer preferences toward BIPV solutions. The potential for long-term energy savings strengthens the value proposition of solar roofing, attracting investment in this segment.
Rising costs of conventional energy sources influence consumers to consider solar options for energy independence. The transition to sustainable energy solutions aligns with broader environmental goals, promoting a growing segment within the market. While competition intensifies, companies focus on differentiating their offerings through advanced technology and enhanced product features, capturing a larger share of the residential market.
Demand for Building-Integrated Photovoltaic (BIPV) Roofing within commercial buildings reflects a strong trend toward sustainability and energy efficiency. Regulatory compliance standards increasingly emphasize reducing carbon footprints, driving businesses to integrate renewable energy solutions into their structures. The segment is estimated to reach USD 25.9 billion by 2033, at a CAGR of 18.3% during the forecast period. This growth results from heightened awareness of environmental impacts and the need for operational cost reductions, particularly in energy expenses.
Adoption of innovative technologies enhances the commercial buildings segment, increasing demand for advanced photovoltaic solutions. Technological maturation in BIPV roofing products supports greater efficiency and aesthetic integration into existing structures. Consequently, businesses experience improved energy production and lower reliance on traditional energy sources, creating a favorable environment for investment in these technologies.
Consumption shifts toward renewable energy sources have prompted a reevaluation of building designs, with developers increasingly prioritizing energy generation capabilities. The economic landscape encourages long-term investments in energy-efficient roofing systems, yielding significant savings over time. Strategic opportunity windows emerge, driven by organizations seeking to differentiate themselves through sustainability, improving their market position.
Cost structures surrounding BIPV technologies continuously evolve, influenced by raw material sourcing and pricing volatility. Fluctuations in material costs affect overall project budgets, yet advancements in manufacturing techniques contribute to competitive pricing. This dynamic environment incentivizes stakeholders to invest in innovative solutions within the Building-Integrated Photovoltaic (BIPV) Roofing market, creating resilience against economic uncertainties.
Demand for Building-Integrated Photovoltaic (BIPV) Roofing solutions within industrial buildings arises from a shift towards sustainable construction practices and energy efficiency. The integration of solar technologies within this sector aligns with regulatory compliance standards aimed at reducing carbon footprints and achieving energy independence. Developers increasingly recognize the potential for significant operational cost savings through energy generation and consumption reduction.
Investments in next-generation upgrades and technological maturation of solar technologies enhance the attractiveness of BIPV roofing. Manufacturers focus on product evolution, improving performance and integration into various industrial applications. Enhanced durability and aesthetic appeal of these roofing systems meet the diverse requirements of industrial clients, driving segment expansion.
Valued at USD 13.6 billion by 2033, the industrial buildings segment reflects strong growth prospects. The ongoing transition towards clean energy solutions and heightened environmental awareness further supports demand. Strategic opportunity windows arise from increasing public and private investments in sustainable infrastructure, prompting stakeholders to capitalize on evolving market dynamics.
Developers face challenges related to cost structures and pricing volatility in raw materials. Effective supply chain resilience and alternative sourcing strategies mitigate risks associated with potential material shortages. Competition intensifies within the market, and ongoing advancements in technology and innovative solutions influence market positioning and growth for players involved in the industrial buildings segment.
Significant growth in the Institutional & Public Buildings segment aligns with increasing investments in renewable energy initiatives. This segment is projected to grow at a CAGR of 18.4% during the forecast period, reflecting a shift toward sustainable building practices. Regulatory compliance standards encourage public sector entities to adopt renewable energy solutions, often supported by government incentives that facilitate solar technology integration. Rising energy costs heighten the appeal of Building-Integrated Photovoltaic (BIPV) Roofing systems among institutional buyers, resulting in a growing preference for energy-efficient infrastructure. Technological maturation, including advancements in photovoltaic efficiency and durability, enhances the attractiveness of BIPV products in this segment. The market benefits from a heightened focus on environmental sustainability within educational institutions and public buildings, positioning it because a crucial area for investment and development.
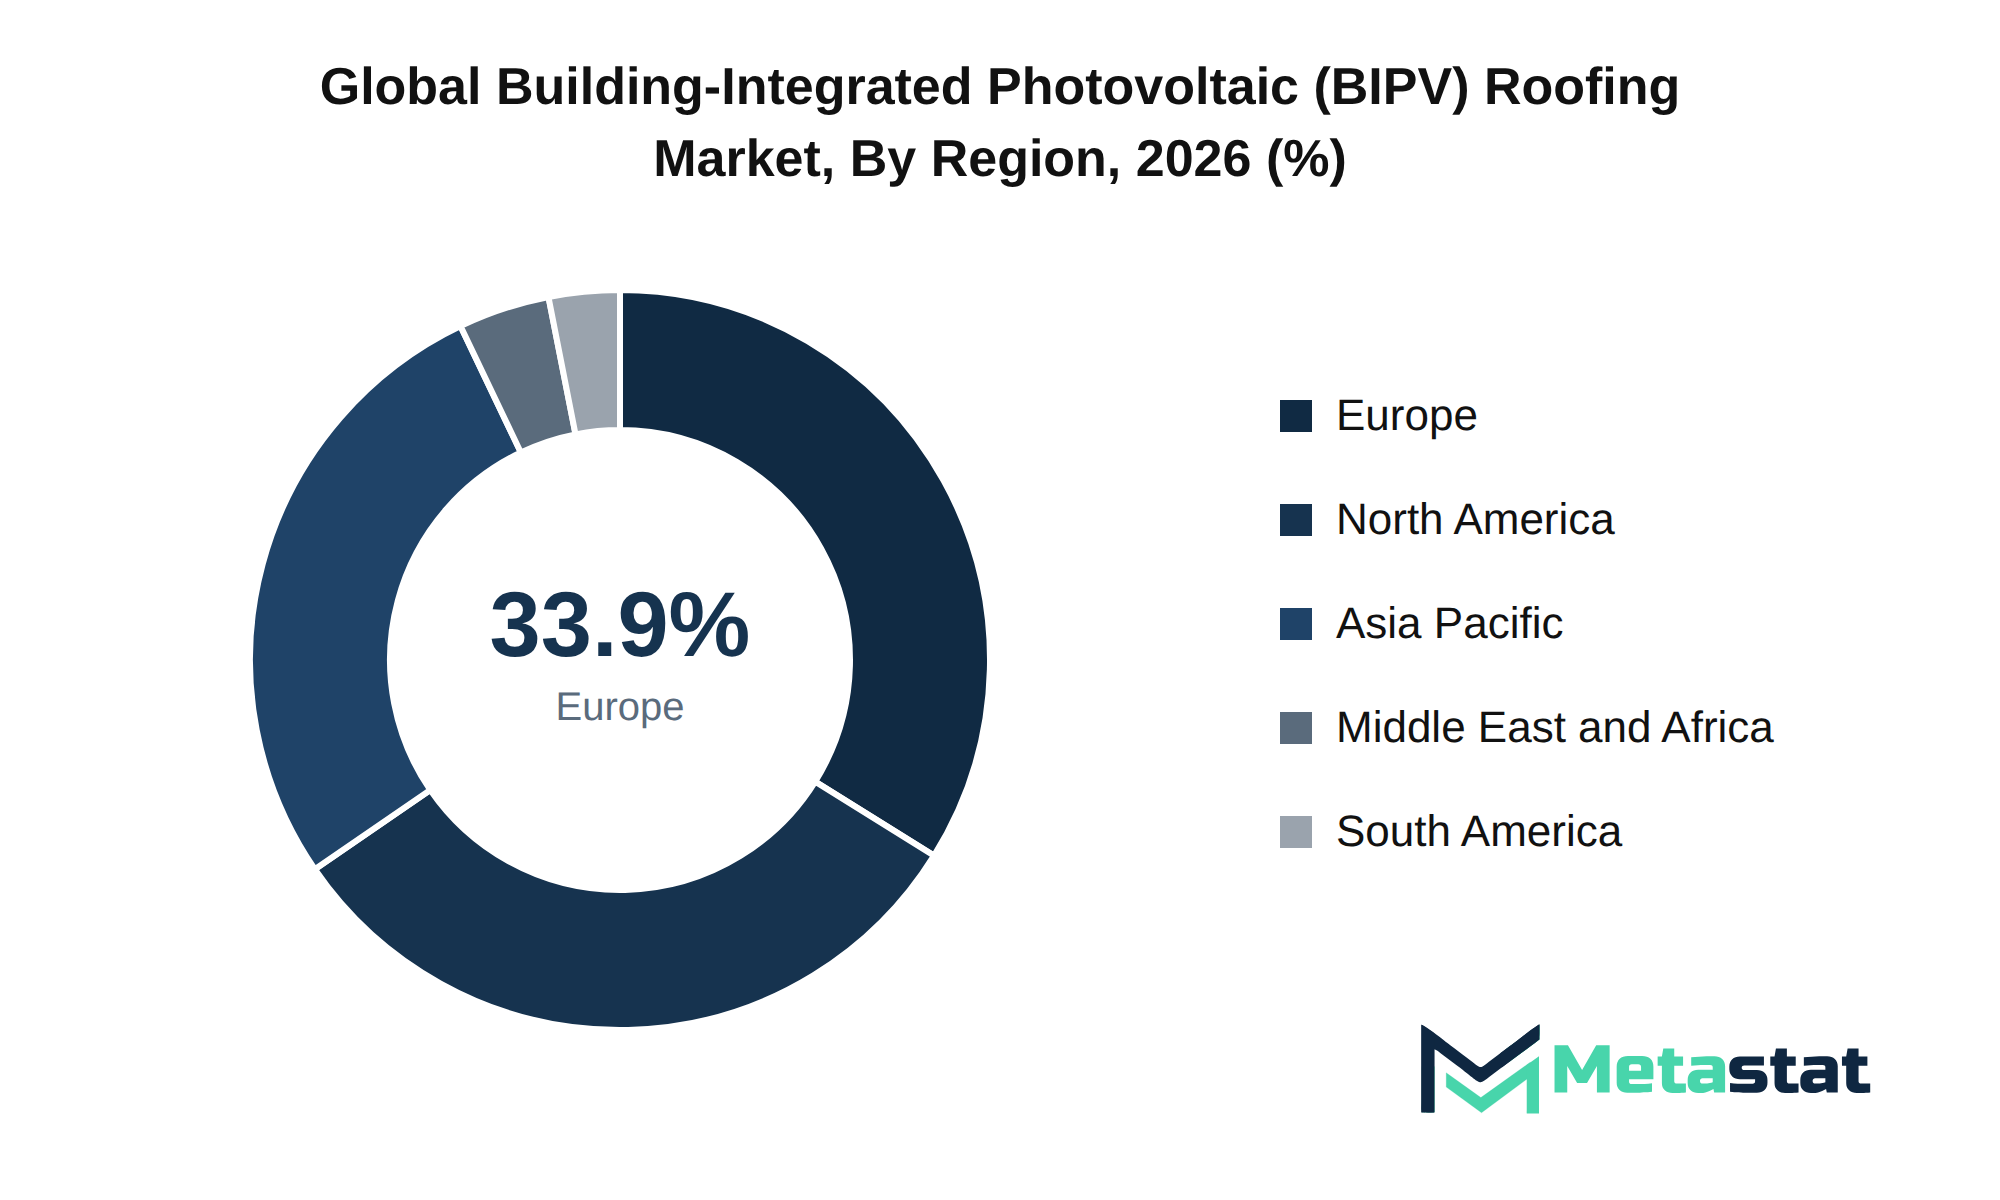
Based on geography, the Global Building-Integrated Photovoltaic (BIPV) Roofing market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Expansion of the Building-Integrated Photovoltaic (BIPV) Roofing market in North America aligns with increasing investment in sustainable construction and energy-efficient technologies. With a projected market size of USD 24.9 billion by the end of 2033, this region anticipates a CAGR of 18.8% throughout the forecast period. Adoption of BIPV solutions gains traction among construction firms, architects, and building owners, driven by stricter environmental regulations and a growing emphasis on renewable energy sources.
The United States, Canada, and Mexico represent the primary markets in this region, collectively accounting for 31.6% of the global market share in 2025. A robust infrastructure for renewable energy, along with supportive policies, facilitates growth of BIPV installations. Local compliance mandates and regulatory frameworks encourage integration of solar technologies into new residential and commercial buildings, enhancing energy efficiency and reducing carbon footprints.
Increasing awareness of climate change impacts leads to heightened demand for green technologies, particularly in urban areas. The market benefits from the presence of domestic market participants who drive innovation and competition in BIPV products. Localized manufacturing and supply chain regionalization support timely delivery and adaptation to market needs. This environment fosters a competitive landscape that enhances product offerings and improves customer satisfaction.
Investment in research and development by key players results in technological advancements, promoting adoption of diverse product types, including solar roof tiles and in-roof photovoltaic modules. With infrastructure modernization efforts underway across North America, the market presents significant potential for growth in underpenetrated territories, particularly in regions with limited access to traditional energy sources.
The Building-Integrated Photovoltaic (BIPV) Roofing market in Europe experiences substantial growth driven by increasing investments in renewable energy technologies and sustainability measures. Countries including Germany, France, and the UK lead advancements in building standards and energy efficiency regulations, creating a favorable environment for BIPV adoption. The significant share of 33.9% of the global market in 2025 indicates robust interest and commitment to integrating photovoltaic solutions within infrastructure.
Emerging market front-runners focus on innovative solar technologies, including crystalline silicon and thin-film photovoltaics, which attract attention due to their efficiency and versatility. The presence of major manufacturers and localized procurement dynamics enhance competitive landscapes, allowing for strategic partnerships and collaborations that improve market positioning. Vendors within the region concentrate on optimizing supply chains and facilitating nearshoring initiatives that strengthen local manufacturing capabilities.
Infrastructure modernization plays a critical role in market expansion, with investments in energy grid resiliency and local readiness driving demand for advanced roofing solutions. Regulatory frameworks specific to each country ensure compliance and incentivize the adoption of BIPV technologies. While the market evolves, incremental growth vectors emerge, emphasizing energy independence and sustainability goals.
The growing emphasis on energy efficiency and reduction of carbon footprints aligns with cultural nuances and regional B2B buying behaviors across Europe. Domestic market participants capitalize on established networks, leveraging foreign direct investment flows that open new geographic expansion windows. The Building-Integrated Photovoltaic (BIPV) Roofing market in Europe remains poised for continued growth, with potential opportunities arising from strategic entry barriers and increasing consumer awareness regarding sustainable building practices.
The Asia-Pacific region accounts for 27.5% of the Building-Integrated Photovoltaic (BIPV) Roofing market by 2025. Rapid urbanization and increasing energy demands drive the adoption of innovative roofing solutions across key countries including China, Japan, and India. Government incentives and policies aimed at promoting renewable energy sources support this trend, creating a conducive environment for growth.
Infrastructure modernization plays an essential role in the expansion of BIPV technologies. Countries including South Korea and Australia demonstrate progressive building regulations that encourage the integration of renewable energy in construction. This creates opportunities for both new installations and retrofitting existing structures, enhancing overall market penetration.
Emerging front-runners within the region exhibit a keen focus on localized manufacturing and supply chain regionalization. This shift helps reduce costs and improve response times to market demands, further stimulating growth. Southeast Asia and the Rest of Asia-Pacific present underpenetrated territories where the potential for BIPV adoption remains high, driven by increasing awareness of sustainability.
Competitive dynamics within the Asia-Pacific BIPV market are characterized by a mix of domestic and international players. This competitive landscape encourages innovation and enhances product offerings, resulting in a diverse range of solutions tailored to meet specific regional needs. Companies actively engage in strategic partnerships to enhance their market presence and capitalize on emerging opportunities.
Regional energy grid resiliency and infrastructure readiness significantly contribute to the growth of the Building-Integrated Photovoltaic (BIPV) Roofing market. Investments in energy storage solutions and smart grid technologies complement BIPV installations, ensuring a reliable energy supply. These advancements reinforce the case for BIPV integration in both new and existing buildings, driving demand across the region.
The Building-Integrated Photovoltaic (BIPV) Roofing market in South America, with a share of 3.1% of the global market in 2025, experiences slower growth compared to other regions. Brazil and Argentina lead the market in this region, driven by increasing energy demands and rising awareness of renewable energy solutions. Infrastructure modernization, combined with supportive government policies, encourages adoption, particularly in urban areas where traditional energy sources face reliability challenges.
The market benefits from a growing number of localized manufacturing facilities, which enhance supply chain resilience and reduce costs associated with import dependencies. Domestic players actively pursue opportunities in residential and commercial buildings, addressing underpenetrated territories that present high-value replacement cycles. This dynamic encourages competition among local vendors, leading to vendor consolidation trends that strengthen market presence.
Cross-border trade corridors between Brazil and Argentina facilitate the exchange of BIPV products, contributing to a more integrated regional market. The geographic regulatory frameworks in place support solar energy initiatives, creating an environment conducive to the expansion of Building-Integrated Photovoltaic (BIPV) Roofing solutions. Energy grid resiliency and local infrastructure readiness remain critical factors influencing the rate of adoption in South America, impacting strategic entry barriers for new market entrants.
The Building-Integrated Photovoltaic (BIPV) Roofing market in the Middle East and Africa is characterized by emerging demand for solar solutions driven by increasing energy needs and a shift toward sustainable building practices. Countries including Saudi Arabia and the UAE have actively invested in renewable energy initiatives, creating a conducive environment for the adoption of BIPV technologies. South Africa represents a growing market, with efforts to enhance energy security and reduce reliance on traditional power sources.
Investment in infrastructure modernization and energy grid resiliency facilitates market expansion. Several local manufacturers and suppliers are establishing operations within the region, contributing to localized manufacturing densities and improved supply chain efficiencies. Cultural nuances and regional B2B buying behaviors influence procurement strategies, with an increasing preference for sustainable energy solutions among construction firms and developers.
Domestic market participants focus on developing innovative products tailored to regional requirements. This trend aligns with cross-border trade corridors that enable the flow of resources and technology, enhancing competitive positioning. The region's regulatory frameworks support the integration of renewable energy sources, further enhancing growth potential for the Building-Integrated Photovoltaic (BIPV) Roofing market.
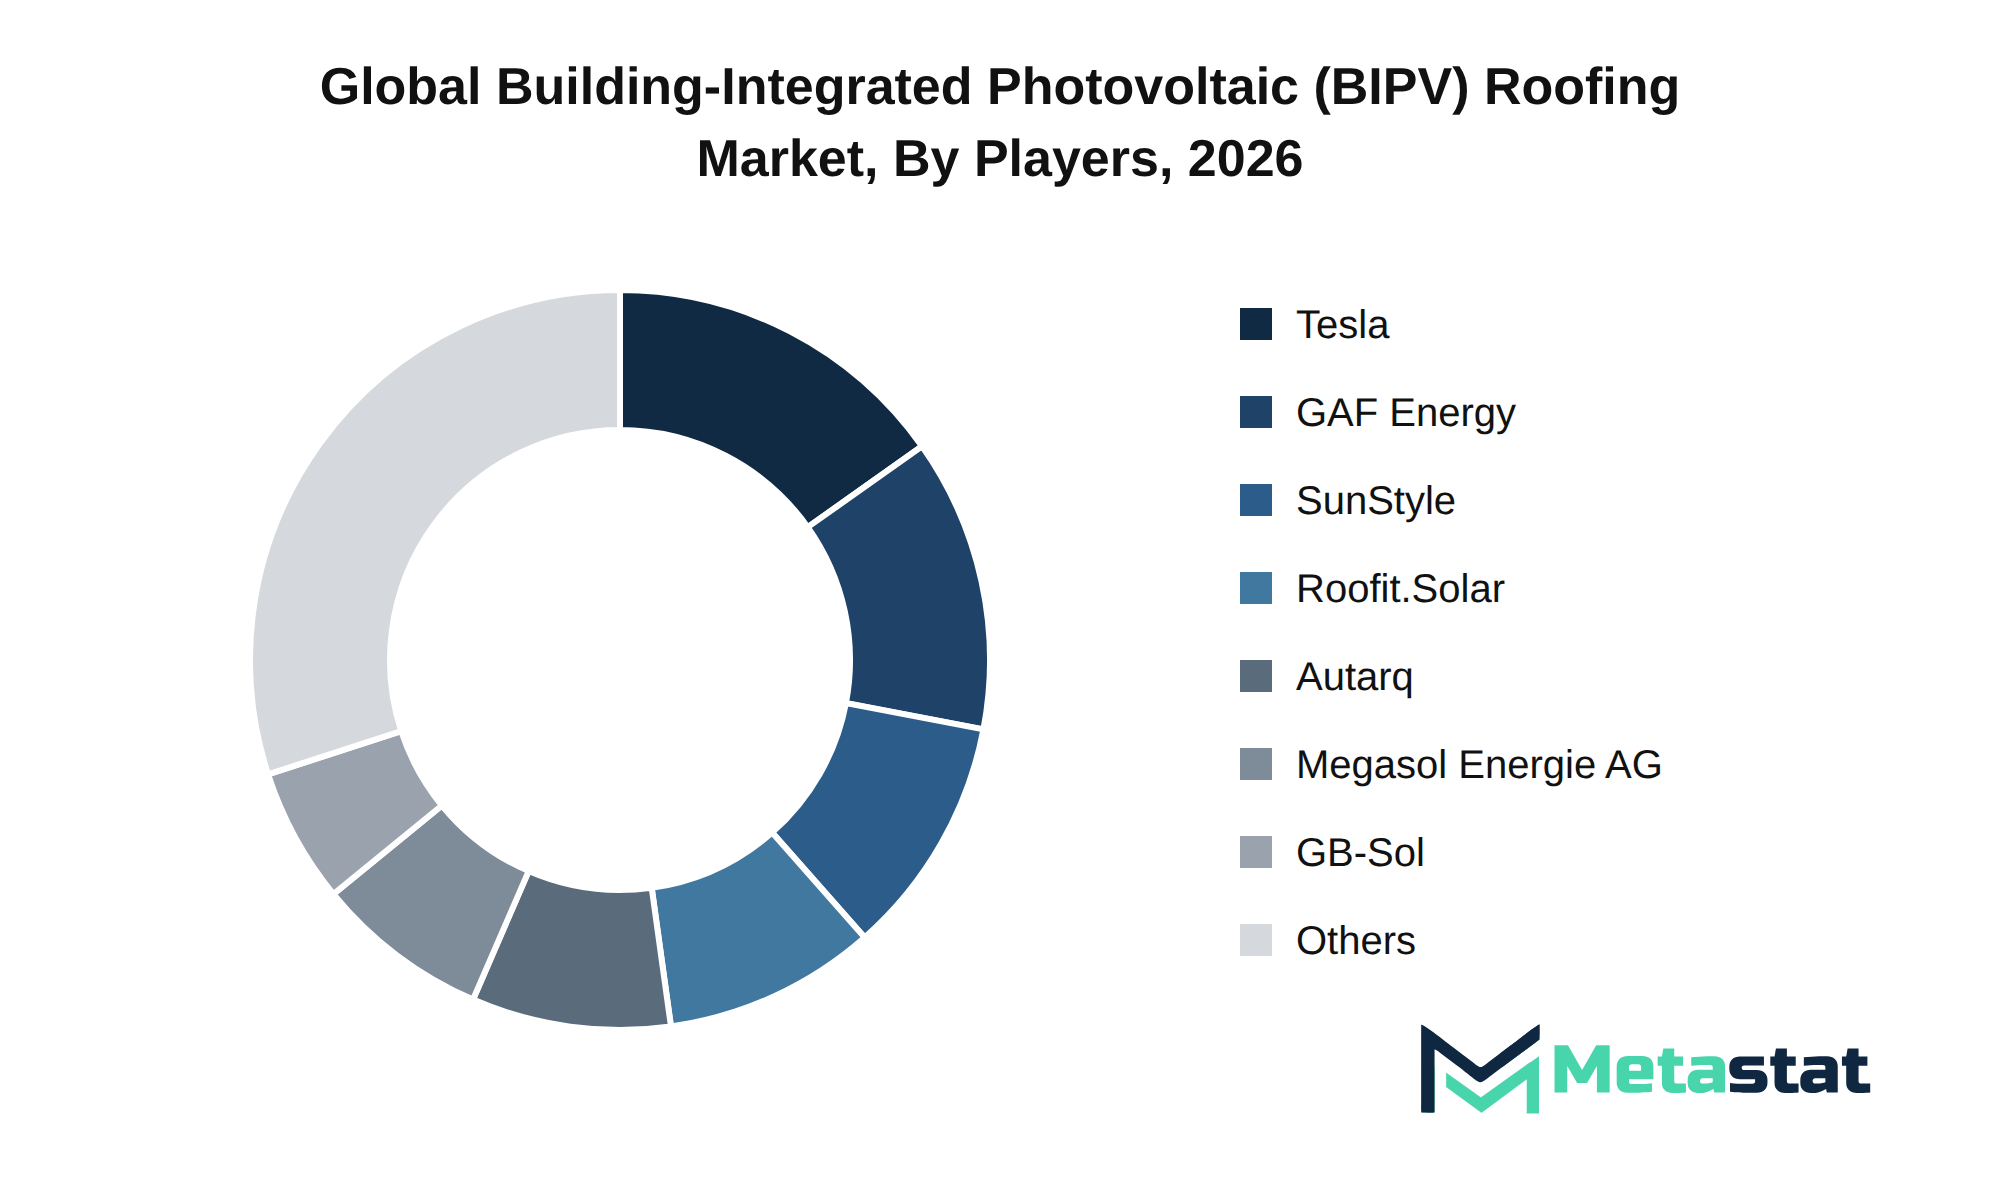
The Building-Integrated Photovoltaic (BIPV) Roofing market features a diverse range of players pursuing various strategies to enhance their market positions. Key strategies include mergers and acquisitions, which facilitate consolidation among established firms and enable them to capture greater market share. Players including Tesla, Inc. and GAF Energy LLC engage in strategic partnerships to leverage technological advancements and expand their product offerings.
Product differentiation remains crucial for competitive positioning. Companies like SunStyle and Roofit.Solar focus on developing proprietary technologies that enhance efficiency and performance, addressing diverse customer needs in the market. Research and development activities are significant, with firms investing heavily to innovate and improve existing products, thereby maintaining a competitive edge.
Strategic alliances and joint ventures play an important role in market dynamics. Collaborations create cross-industry partnerships that drive technological advancements and broaden market reach. For instance, partnerships among players including Autarq GmbH and Megasol Energie AG enhance capabilities in developing advanced solar roofing solutions.
Barriers to entry persist, particularly for new entrants seeking to establish themselves in the market. Established players benefit from strong brand equity, intellectual property portfolios, and procurement leverage, which create challenges for startups aiming to disrupt the status quo. The threat of new entrants remains a consideration for established firms, prompting them to strengthen customer retention strategies and address potential competitive threats effectively.
The future competitive outlook indicates a focus on sustainable growth vectors. Companies prioritize value chain integration and supply chain efficiency to optimize operational performance. This approach supports profitability and enhances the resilience of firms in the Building-Integrated Photovoltaic (BIPV) Roofing market. Firms are expected to explore innovative solutions that align with evolving consumer preferences and regulatory requirements.
Market size is forecast to rise from USD 19.7 billion in 2025 to over USD 78.3 billion by 2033. The base case establishes a trajectory of USD 19.7 billion in 2025 escalating to USD 78.3 billion by 2033 at an 18.8% CAGR. Bull cases reflect a scenario where accelerating technological advancements and regulatory incentives stimulate faster adoption, leading to greater market expansion. Conversely, bear cases highlight potential economic downturns or tightening regulations that could inhibit growth, resulting in slower market progression.
Macroeconomic factors will substantially influence the Building-Integrated Photovoltaic (BIPV) Roofing market. Economic cycles, including shifts in consumer behavior and construction activity, will impact downstream demand. Greater adoption of next-generation technologies will enhance product offerings and operational efficiency, aligning with the increasing focus on sustainability.
Significant structural consumption shifts will arise from evolving governmental policies and compliance requirements, driving the transition towards BIPV solutions. Regulatory evolution timelines will play a crucial role in determining market dynamics, especially with imminent compliance milestones compelling industry participants to innovate and adapt quickly.
Geopolitical realignments and global supply chain shifts will necessitate strategic capital allocation directives. Investment in infrastructure commitments will strengthen the market's foundation. Sectors showing high-growth pockets present emerging white-space opportunities. Identifying and addressing unmet enterprise needs will become essential for stakeholders aiming to capitalize on these developing trends.
Executive-level strategic imperatives will focus on defensibility roadmaps. Organizations navigate the complexities of market evolution. Ensuring robust R&D commercialization timelines equips firms with the necessary tools to remain competitive, maximizing growth potential within the Building-Integrated Photovoltaic (BIPV) Roofing market.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Building-Integrated Photovoltaic (BIPV) Roofing market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 18.8% from 2026 to 2033 |
Revenue Unit | USD billion |
Segmentation | By Product Type, Technology, Roof Configuration, End-Use, and Region |
By Region | North America (By Product Type, Technology, Roof Configuration, End-Use, and Country)
|
Europe (By Product Type, Technology, Roof Configuration, End-Use, and Country)
| |
Asia Pacific (By Product Type, Technology, Roof Configuration, End-Use, and Country)
| |
South America (By Product Type, Technology, Roof Configuration, End-Use, and Country)
| |
Middle East and Africa (By Product Type, Technology, Roof Configuration, End-Use, and Country)
|
Find answers to common questions about this report
The Building-Integrated Photovoltaic (BIPV) Roofing market size was valued at USD 19.7 billion in 2025, according to the Metastat Insights study.
The Building-Integrated Photovoltaic (BIPV) Roofing market is projected to grow at a CAGR of 18.8% during the forecast period from 2026 to 2033.
The North America Building-Integrated Photovoltaic (BIPV) Roofing market size is estimated to reach USD 24.9 billion by 2033.
The leading segment in the Building-Integrated Photovoltaic (BIPV) Roofing market is Solar Roof Tiles & Shingles, with a projected value of USD 29.6 billion by 2033. This segment demonstrates the highest growth potential compared to others in the market.
Investment in infrastructure development and technological integration drive the Building-Integrated Photovoltaic (BIPV) Roofing market. Increased spending on infrastructure, coupled with advancements in automation and artificial intelligence, enhances operational efficiency and attracts capital investment, supporting market growth. Shifting consumer preferences for sustainable solutions further increase demand for innovative BIPV products.
Europe holds the dominant share of the Building-Integrated Photovoltaic (BIPV) Roofing market, with a figure of USD 19.7 billion in 2025, representing 33.9% of the total market.
Stringent regulatory compliance requirements and associated costs significantly restrain the Building-Integrated Photovoltaic (BIPV) Roofing market growth. Extensive documentation and safety standards complicate installation processes, leading to delays in project approvals and deterring investment. fluctuations in regulatory frameworks create an uneven playing field, hindering market entry for new entrants and smaller players.
Investment in infrastructure development and a focus on sustainability significantly favor product adoption in the Building-Integrated Photovoltaic (BIPV) Roofing market. Increased public spending and urbanization drive the demand for energy-efficient roofing solutions, while technological advancements enhance operational productivity and attract capital investment. These factors create a favorable environment for BIPV technologies in new constructions and renovations.
The Building-Integrated Photovoltaic (BIPV) Roofing market is estimated to reach a valuation of USD 78.3 billion by 2033.
Key players operating in the Building-Integrated Photovoltaic (BIPV) Roofing market include Tesla, Inc., GAF Energy LLC, SunStyle, Roofit.Solar, Autarq GmbH, and Trina Solar Co., Ltd.
Choose Your License
Global Building-Integrated Photovoltaic (BIPV) Roofing Market
The analysts below cover Energy and Power research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.
Tracking maintenance cycle demand for secondary flight display units and terrain collision avoidance systems across regional jet fleets involves complex aftermarket dynamics. MetaStat Insight provided practical analysis separating airline retrofit programs from OEM forward-fit production schedules in North America and Southeast Asia. The supplier matrix highlighted component obsolescence timelines without resorting to vague generalizations. The dataset served as a dependable reference during our annual program review meetings.
Evaluating secondary resin quality across post-consumer packaging streams requires reliable technical segmentation. MetaStat Insight delivered an objective assessment that distinguished between extrusion-grade flake pricing and optical sorting throughput limitations across Western Europe. The competitive positioning breakdown for licensed depolymerization technology providers answered several questions during our feedstock feasibility audit. Their team clarified regional trade restrictions on mixed plastic scrap quickly when our team submitted follow-up requests.
Evaluating sovereign cloud deployments for core banking platforms demands a clear view of data residency regulations and migration exit strategies. MetaStat Insight delivered an exhaustive review of regional latency tolerances, mainframe decommission milestones, and third-party vendor concentration risk. The regulatory compliance mapping across European and Asian financial jurisdictions gave our team a dependable baseline for multi-cloud infrastructure discussions.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950