
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Electrical Conduit Market Size, Share, By Product Type (Rigid Metal Conduit (RMC), Intermediate Metal Conduit (IMC), Electrical Metallic Tubing (EMT), Flexible Metal Conduit (FMC), Liquidtight Flexible Metal Conduit (LFMC), Rigid PVC Conduit, HDPE Conduit, Electrical Nonmetallic Tubing (ENT), Others (FNC/LFNC, RTRC, Fiberglass)), By Application (Building Power & Lighting Wiring, Utility Transmission & Distribution, Industrial Power, Control & Instrumentation, Data & Telecommunications Cabling, Transportation & Infrastructure Electrification, Renewable Energy Systems), By End-Use Industry (Residential Buildings, Commercial & Institutional Buildings, Industrial & Manufacturing, Energy & Utilities, Data Centers & Telecommunications, Transportation Infrastructure, Oil & Gas, Mining & Petrochemicals, Renewable Energy, Others (Marine, Agriculture, Defense)), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5301
September 18, 2026
269 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $8.9 Billion in 2025, projected to reach $16.9 Billion by 2033 at a 8.4% CAGR.
Dominant Segment: The Electrical Metallic Tubing (EMT) segment leads the market, driven by its lightweight and corrosion-resistant properties, making it ideal for various applications. Its compliance with safety standards and alignment with energy-efficient construction practices further bolster its demand.
Geographic Lead: The Asia Pacific region exhibits the fastest growth, fueled by rapid urbanization and significant investments in infrastructure development. Countries like India and Brazil are at the forefront, driving demand for efficient electrical systems.
What's Inside: The report provides a comprehensive analysis of the global Electrical Conduit market, including detailed segmentation by product type, application, and end-use industry. It covers competitive dynamics, market trends, and forecasts through 2033.
Emerging Regional Demands: Emerging markets, particularly in Asia Pacific and South America, are experiencing heightened demand for electrical conduits due to urbanization and industrialization. This trend is supported by government initiatives focused on modernization and infrastructure development.
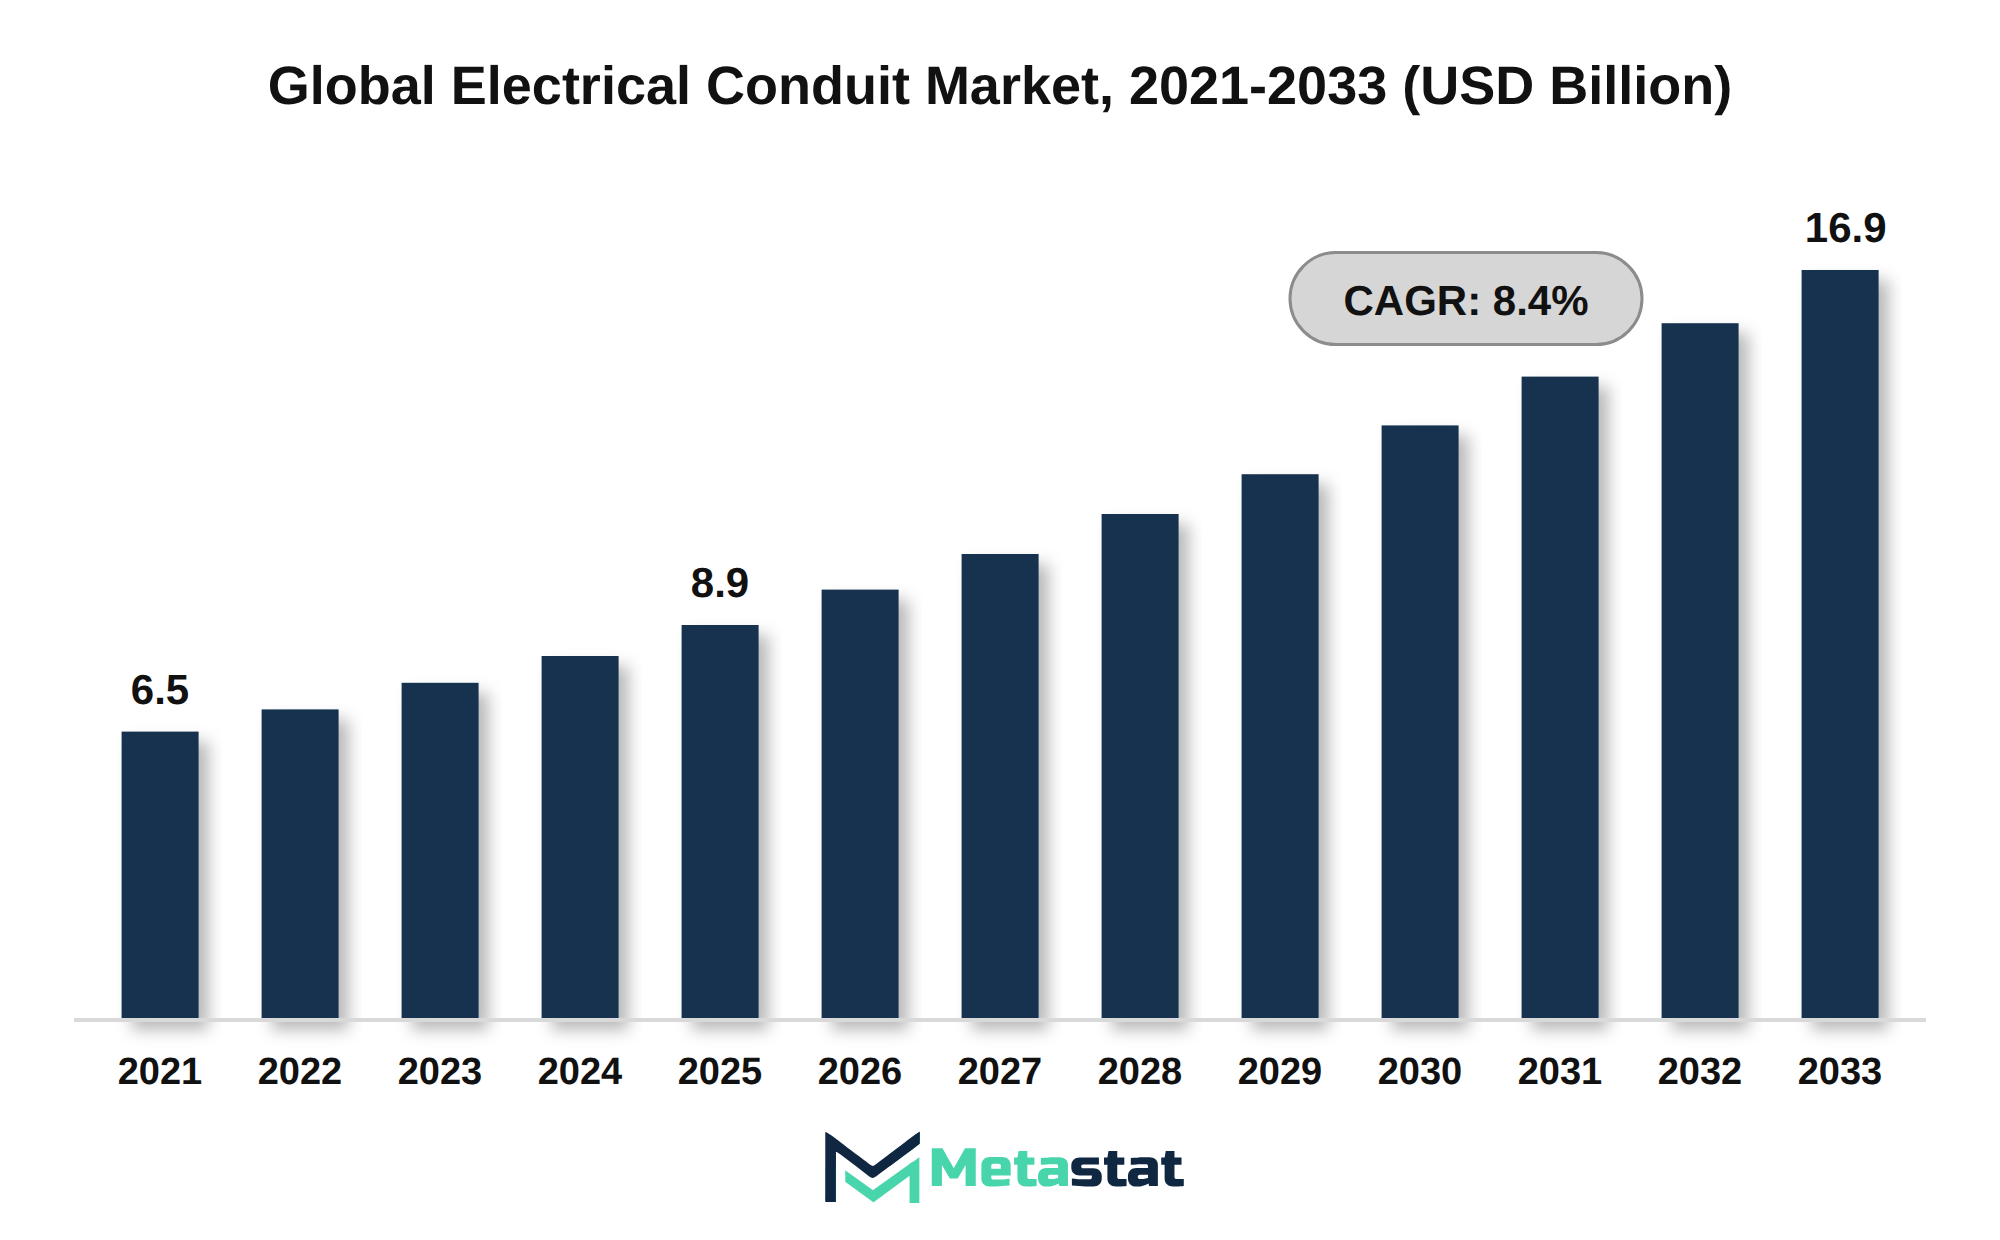
The global Electrical Conduit market was valued at USD 8.9 billion in 2025 and is projected to reach USD 16.9 billion by 2033, growing at a CAGR of 8.4% over the forecast period.
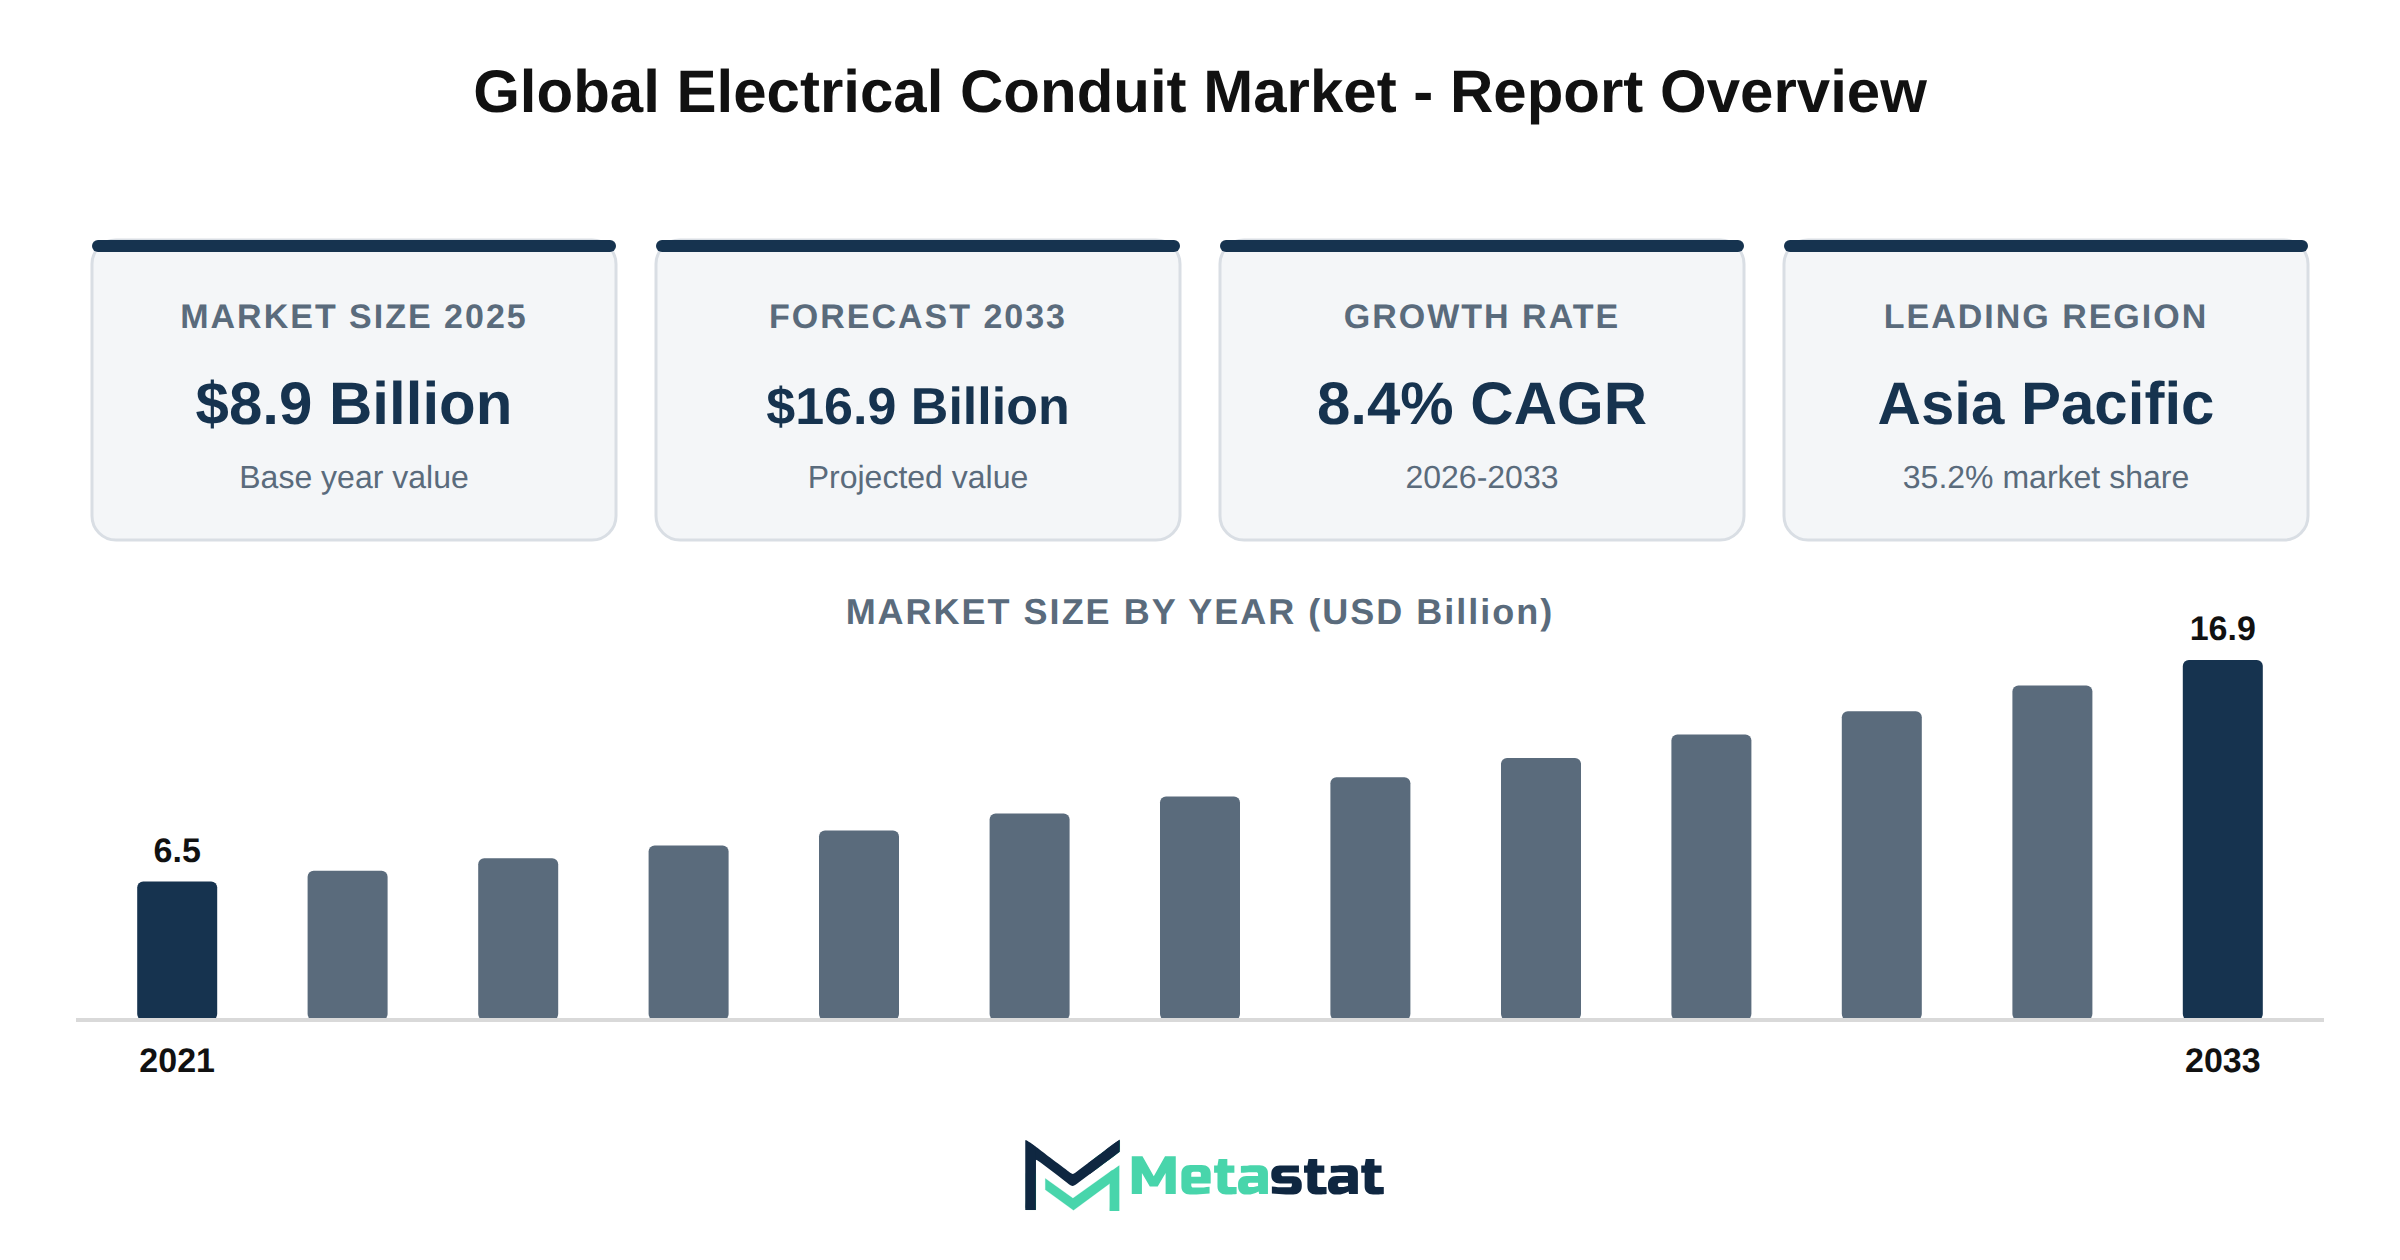
The global Electrical Conduit market reached a value of USD 8.9 billion in 2025 and is projected to expand to USD 16.9 billion by 2033, reflecting a compound annual growth rate (CAGR) of 8.4%. The market exhibits robust demand trends across building and infrastructure projects, driven by increasing construction activities and the need for efficient electrical solutions.
A noticeable shift toward nonmetallic and HDPE electrical conduit systems occurs due to their lightweight properties and resistance to corrosion. This transition benefits industries focused on sustainability and cost-effectiveness. Data center expansion significantly influences electrical conduit consumption, driven by the need for advanced cabling solutions that escalate with growing digital infrastructure.
Utility grid modernization fuels demand for underground conduit systems, allowing for enhanced reliability and reduced maintenance. Renewable energy projects create new opportunities in the electrical conduit market, because the installation of solar and wind energy systems requires specialized conduit solutions.
Commercial and industrial construction plays a critical role in supporting market growth, with increased investments in facilities and infrastructure. Electrical conduit adoption in transportation infrastructure projects enhances connectivity and safety, reflecting the industry's response to evolving urban development needs.
Flexible and liquidtight conduit demand rises in industrial applications, driven by the need for versatile and durable wiring solutions in challenging environments. In residential and commercial construction, PVC electrical conduit growth aligns with the trend toward cost-effective and efficient building practices.
Smart buildings and high-density cabling requirements influence conduit specifications, necessitating innovation in materials and designs. Electrical conduit material innovation and performance improvements enhance product offerings, catering to diverse market needs.
Fire safety and electrical code compliance shape conduit selection, ensuring that installations meet regulatory standards. Raw material prices impact electrical conduit manufacturing cost trends, influencing pricing strategies across the market.
The electrical conduit supply chain focuses on capacity expansion strategies to meet increasing demand. Competitive dynamics among metallic and nonmetallic conduit manufacturers drive innovation, enhancing product availability and performance.
Infrastructure investment in the Asia Pacific region significantly drives electrical conduit growth, supported by government initiatives aimed at enhancing connectivity. In North America, electrical code standards influence conduit demand trends, promoting safety and efficiency in installations.
Sustainability and recyclability trends in electrical conduit manufacturing reflect the industry's commitment to environmental responsibility. Underground power distribution expands HDPE conduit applications, supporting the shift toward safer and more efficient energy distribution systems.
Future growth opportunities in global electrical conduit systems lie in emerging technologies and innovations that address evolving market demands.
Demand for electrical conduit benefits significantly from building and infrastructure projects. Increasing investments in both sectors drive a robust requirement for conduit solutions, facilitating efficient electrical installations and enhancing overall project efficiency. This trend indicates a solid commitment to modernizing infrastructure, which directly correlates with heightened conduit consumption.
The shift toward nonmetallic and HDPE electrical conduit systems reflects evolving industry preferences. Nonmetallic materials offer advantages including corrosion resistance and lightweight properties, making them increasingly attractive for various applications. The transition aligns with sustainability goals, promoting eco-friendly construction practices.
Data center expansion serves because a key driver of electrical conduit consumption. The growing demand for data storage and processing capabilities necessitates the deployment of advanced electrical infrastructure. Consequently, this results in higher demand for conduit solutions that support the intricate wiring and cabling requirements of modern data centers.
Utility grid modernization generates increased demand for underground conduit solutions. Upgrading aging infrastructure, coupled with the need for reliable power distribution, drives the adoption of electrical conduit. This trend supports efforts to enhance system resilience and efficiency, vital for meeting contemporary energy demands.
Renewable energy projects create new opportunities for electrical conduit applications. The transition to sustainable energy sources, including solar and wind, necessitates robust electrical systems, which directly influences conduit demand. This trend highlights the importance of adaptable conduit solutions that align with the unique requirements of renewable energy installations.
Commercial and industrial construction projects drive market growth. While businesses expand and modernize facilities, the need for reliable electrical systems intensifies. This surge in construction activity translates into heightened demand for electrical conduit, reinforcing its role because a critical component in modern building practices.
Transportation infrastructure development significantly influences conduit adoption. Investments in roads, railways, and airports necessitate comprehensive electrical systems, driving the need for conduit solutions that ensure safe and efficient electrical installations. This trend emphasizes the essential role of electrical conduit in supporting transportation projects.
Flexible and liquidtight conduit demand in industrial applications illustrates the versatility of conduit solutions. Industries requiring robust and adaptable electrical installations increasingly favor these types of conduits to address unique operational challenges. This trend enhances operational efficiency and reliability in various industrial settings.
The growth of PVC electrical conduit in residential and commercial construction reflects changing preferences. PVC offers a balance of affordability, durability, and ease of installation, making it a preferred choice for many projects. This trend supports ongoing market expansion within the residential and commercial sectors.
Smart buildings and high-density cabling requirements influence conduit specifications. The integration of advanced technologies within buildings increases the complexity of electrical systems, necessitating conduit solutions that accommodate higher data and power loads. This evolution represents a significant shift in how electrical conduit supports modern building designs.
Material innovation and performance improvements shape the electrical conduit landscape. Manufacturers continuously develop new materials and technologies that enhance conduit durability and performance. This ongoing innovation drives competitiveness in the market, ensuring that products meet stringent regulatory and operational standards.
Fire safety and electrical code compliance significantly influence conduit selection. Adherence to regulations ensures safe installations, prompting manufacturers to prioritize compliance in their product offerings. This focus on safety and regulatory adherence strengthens market integrity and builds consumer confidence.
Raw material prices and manufacturing cost trends impact the overall electrical conduit market. Fluctuations in material costs directly influence pricing strategies and profit margins, necessitating strategic planning by manufacturers. Understanding these trends is crucial for maintaining competitiveness in an evolving market.
Supply chain and capacity expansion strategies play a vital role in meeting growing demand. Manufacturers are actively enhancing their production capabilities to ensure timely delivery and availability of electrical conduit products. This strategic approach supports market stability and encourages sustained growth.
Competitive dynamics among metallic and nonmetallic conduit manufacturers shape market development. Companies strive to differentiate themselves through innovative products and strategic partnerships, influencing overall market positioning. This competition drives advancements in technology and product offerings, benefiting end-users across various sectors.
Asia Pacific infrastructure investment significantly boosts electrical conduit growth. Governments and private entities are increasingly allocating funds to develop essential infrastructure, directly correlating with heightened demand for conduit solutions. This trend positions the region because a key player in the global electrical conduit market.
North America’s electrical code standards shape conduit demand trends. Regulatory frameworks dictate material specifications and installation practices, influencing market dynamics. Adherence to these standards ensures safety and reliability, reinforcing the importance of compliance in the electrical conduit sector.
Sustainability and recyclability trends in electrical conduit manufacturing reflect an industry shift toward environmentally conscious practices. Manufacturers are exploring sustainable materials and production processes, responding to increasing consumer demand for eco-friendly solutions. This trend enhances the overall market appeal and aligns with global sustainability goals.
Underground power distribution expands HDPE conduit applications, supporting modern energy distribution needs. The growing emphasis on safety and reliability in power distribution systems drives the adoption of HDPE solutions, reinforcing their significance in contemporary infrastructure projects.
Future growth opportunities in global electrical conduit systems remain promising. The combination of technological advancements, regulatory support, and evolving market demands positions the sector for sustained development. Key players are well-positioned to capitalize on emerging opportunities, ensuring continued market expansion.
Increased economic growth stimulates investment in infrastructure projects, significantly impacting the Electrical Conduit market. Governments and private entities expand budgets for construction, renovation, and modernization, enhancing demand for electrical conduits. This trend results from a focus on sustainable urban development and improved energy efficiency in new buildings.
Rising consumer spending contributes to the expansion of commercial and residential infrastructure, with a notable emphasis on electrical systems for power distribution and telecommunications. Prioritization of infrastructure development by nations drives market growth, supported by rising capital expenditures and an inclination towards upgrading existing facilities.
The combination of public and private funding creates opportunities for key players in the Electrical Conduit market to innovate and diversify their product offerings, meeting evolving consumer needs. Enhanced economic conditions encourage investments that support technological advancements, further propelling market growth.
Investment in infrastructure modernization plays a critical role in driving demand within the Electrical Conduit market. Governments and private sectors allocate resources toward upgrading aging infrastructure to support urbanization and technological advancements. Enhanced infrastructure supports the growing need for efficient energy distribution and management, directly influencing market growth.
Public-private partnerships boost capital investment environments, facilitating projects that prioritize electrical conduit installation. These investments contribute to improved energy efficiency and sustainability, aligning with global goals for resource stewardship. Rising demand for smart infrastructure creates opportunities for innovative solutions, enhancing operational productivity across various sectors.
Technological integration, including advancements in automation and software adoption, influences the market. The need for digitizing legacy processes encourages investment in electrical conduits, essential for modern energy systems. This focus on modernization and efficiency drives growth in the Electrical Conduit market, reflecting ongoing trends in urban development and energy management.
The Electrical Conduit market faces significant challenges stemming from regulatory compliance and escalating operational costs. Strict adherence to safety and environmental regulations drives up manufacturing costs for producers. Compliance with these regulations requires substantial investment in technology and processes, which increases operational expenses and limits smaller companies’ market entry. These factors contribute to a competitive disadvantage for manufacturers operating under tighter budget constraints.
High capital investment requirements in production facilities and technologies further restrain market growth. Manufacturers allocate considerable financial resources to upgrade equipment in response to evolving regulations. This capital stagnation inhibits innovation and the development of new products, leading to slower market expansion. Reduced agility in adapting to customer demands and emerging trends limits competitive positioning.
Escalating operating costs related to raw materials and labor further impact the overall profitability of the Electrical Conduit market. Inflationary pressures on material costs increase the burden on manufacturers, while rising labor costs affect operational efficiencies. The combination of these factors leads to higher product prices, which limit consumer demand in price-sensitive segments.
Supply chain disruptions arising from geopolitical instability and resource scarcity introduce additional uncertainty within the market. Such disruptions affect the timely delivery of materials needed for manufacturing electrical conduits, leading to delays and increased costs. This instability impacts the ability of companies to meet customer expectations and results in lost business opportunities.
These challenges collectively hamper the growth potential of the Electrical Conduit market, restricting both investment and the ability to respond to market changes effectively. While companies navigate these complexities, the need for strategic planning becomes essential to mitigate risks and enhance market positioning.
The electrical conduit market encounters significant challenges owing to geopolitical fragmentation, which disrupts established supply chains and increases uncertainty among manufacturers. Trade deficits and tariff friction complicate international procurement of raw materials and components, raising costs for producers. These challenges affect industries reliant on electrical conduit products, forcing them to adapt to fluctuating prices and availability of necessary inputs.
Technological disruptions contribute to market instability, creating barriers for companies trying to innovate and integrate new solutions. Complex research and development processes hinder the ability to respond swiftly to evolving market demands. This situation impacts the competitive landscape, because firms struggle to maintain profitability, leading to pricing compression and margin pressures.
Rising input cost structures further complicate operational challenges. Manufacturers in the electrical conduit market face increasing costs associated with raw materials and production processes, which limit their ability to invest in growth and expansion initiatives. These factors heighten the pressure on companies to streamline operations while maintaining product quality and compliance with tightening global regulatory standards.
Environmental lifecycle footprints and sustainability demands play a critical role in shaping market dynamics. Companies invest in sustainable practices and materials to meet the expectations of environmentally conscious consumers and regulatory bodies. Consequently, this focus on sustainability leads to increased capital expenditure, challenging profitability and market competitiveness.
Infrastructure gaps and retrofitting barriers present additional obstacles. The need for upgrading and maintaining existing infrastructure often delays project timelines and complicates the implementation of new electrical conduit solutions. This environment stifles growth in the market, because potential projects experience disruptions and setbacks.
Finally, talent retention pressures and workforce skill gaps exacerbate recruitment challenges. The demand for skilled labor in advanced manufacturing processes intensifies competition for qualified workers, further straining operational capabilities. The electrical conduit market faces these workforce challenges while striving to maintain productivity and innovation to succeed in an increasingly competitive environment.
The Electrical Conduit market benefits from significant regional demands, particularly in emerging markets within Asia Pacific and South America. Rapid urbanization and industrialization in these regions generate increasing needs for infrastructure development, enhancing the demand for efficient electrical systems. Countries including India and Brazil are investing heavily in modernization initiatives, driving market expansion owing to new projects requiring extensive electrical conduit solutions.
Technological disruptions further influence growth within the market. Advancements in materials science, including the development of lightweight and flexible conduits, enhance product offerings and appeal to a broader customer base. These innovations improve installation processes and performance, attracting attention from various sectors beyond traditional electrical applications.
Sustainability imperatives shape buying behaviors, with a rising emphasis on eco-friendly products. The market sees increased interest in sustainable manufacturing practices and materials, aligning with global environmental goals. Companies that adopt green transformations and promote environmentally responsible products gain competitive advantages and deepen relationships with environmentally conscious clients.
Digital transformation initiatives are reshaping procurement strategies within the market. The shift towards digital procurement enhances efficiency and transparency, allowing buyers to make data-driven decisions. This evolution in purchasing behavior supports the growth of e-commerce platforms that facilitate the distribution of electrical conduit products, thereby broadening market accessibility.
Strategic consolidation through mergers and acquisitions creates opportunities for enhanced product integration and expanded market reach. Companies acquiring smaller firms leverage existing technologies and customer bases, leading to increased operational efficiencies and market competitiveness. This trend highlights the importance of adapting to market dynamics and evolving consumer expectations.
The Electrical Conduit market is positioned for growth driven by emerging regional demands, technological advancements, and evolving buying behaviors. These factors collectively contribute to a dynamic market environment, presenting significant opportunities for stakeholders to capitalize on the expanding potential of electrical conduit applications across various industries.
The Global Electrical Conduit market is segmented based on Product Type, Application, and End-Use Industry.
Valued at USD 1.2 billion in 2026, the Rigid Metal Conduit (RMC) segment is projected to reach USD 1.9 billion by 2033, at a CAGR of 6.6% during the forecast period. Growth in this segment stems from increasing demand for durable and reliable electrical infrastructure, particularly in industrial and commercial applications. The need for robust solutions for power distribution and wiring drives adoption of RMC in various projects.
Technological maturation influences the development of RMC products, with innovations enhancing durability and ease of installation. This evolution enables the segment's ability to meet the growing demands of industries focusing on energy efficiency and smart-building technologies. Regulatory compliance standards play a critical role, driven by stringent safety and performance regulations that encourage the usage of RMC products in construction and renovation projects.
Economic factors, including rising construction activity and a focus on sustainability, increase demand in the electrical conduit market. The segment benefits from shifts in consumption patterns, where preference leans towards materials that provide long-lasting performance and low maintenance costs. Strategic opportunity windows arise from infrastructure investments in developing regions, further enhancing the market potential for RMC.
Raw material sourcing remains a focal point, with supply chain resilience ensuring consistent availability of key inputs. This stability mitigates pricing volatility and margin pressures, creating a favorable environment for manufacturers. The future outlook indicates that ongoing capital investments will support continuous improvements in product offerings and market positioning for players within the RMC segment.
Growth in the Intermediate Metal Conduit (IMC) segment is projected to reach USD 1.1 billion by 2033, with a CAGR of 6.5% during the forecast period. This segment benefits from increased adoption across various sectors, driven by the need for durable and robust electrical routing solutions in residential, commercial, and industrial applications. Enhanced focus on safety and compliance with regulatory standards further supports the demand for IMC, because these conduits provide excellent protection for electrical wiring against environmental hazards.
Technological advancements in manufacturing processes contribute to the segment's expansion, allowing for lighter yet stronger materials that meet evolving industry needs. This evolution positions IMC favorably within the Electrical Conduit market, appealing to sectors that prioritize both performance and cost-effectiveness. Regulatory compliance requirements, particularly in construction and electrical installation, drive demand for IMC due to its superior structural integrity and fire resistance.
The IMC segment gains traction from increasing investments in infrastructure projects. Urbanization and population growth in developing regions fuel demand for new electrical installations, further enhancing the segment's prospects. While industries adapt to evolving energy needs, the role of Intermediate Metal Conduits becomes vital in providing reliable electrical pathways. The continuous push for sustainable energy solutions creates opportunities for this segment within renewable energy projects.
Growth in the IMC segment aligns with broader trends in the Electrical Conduit market, characterized by a shift toward greater efficiency and performance in electrical installations. Strategic investments from key players will likely play a crucial role in driving innovation and expanding market share within this competitive landscape.
Demand for Electrical Metallic Tubing (EMT) experiences strong growth driven by its advantages in electrical installations. EMT offers lightweight, corrosion-resistant properties, making it a preferred choice for residential, commercial, and industrial applications.
Regulatory compliance further supports adoption, because EMT adheres to safety standards that enhance building integrity. The push towards energy-efficient solutions in construction boosts the segment's prominence, aligning with trends in sustainable building practices.
Technological advancements in manufacturing processes lead to enhanced performance characteristics of EMT, thereby expanding its application scope. By 2033, the Electrical Metallic Tubing (EMT) segment is expected to reach USD 3.2 billion, reflecting robust market demand.
Investment in smart infrastructure drives consumption shifts, with increased integration of EMT into modern electrical systems. This transition emphasizes the need for high-quality materials that support innovative technologies.
Cost structures influence pricing strategies, while competition within the market drives innovation. Manufacturers invest in research and development to improve product offerings, ensuring that EMT remains relevant in evolving market dynamics.
Growth in the Flexible Metal Conduit (FMC) segment reflects a strong response to rising demand for versatile and adaptable conduit solutions. Increasing applications across various industries, including telecommunications and renewable energy, drive adoption. FMC accommodates movement and vibration, enhancing its appeal in dynamic environments and leading to higher consumption rates.
Regulatory compliance standards focusing on safety and environmental sustainability fuel market expansion. Manufacturers invest in next-generation upgrades and product evolution to enhance the durability and performance of FMC. With an emphasis on energy efficiency and resilience against harsh conditions, end-users increasingly turn to FMC solutions for critical infrastructure projects.
The Flexible Metal Conduit (FMC) segment is projected to grow at a CAGR of 7.6% during the forecast period. The emphasis on sustainable energy systems and the need for robust solutions in data centers and industrial applications contribute to this growth. Strategic opportunity windows emerge for manufacturers to innovate and capture greater market share, driven by market evolution.
Capital investment outlook remains positive, with increasing venture funding supporting technological maturation in the FMC sector. This investment drives the development of advanced materials and production processes, enhancing product offerings. The Electrical Conduit market is poised for significant advancement, driven by demand for innovative, flexible solutions that meet evolving industry requirements.
Demand for Liquidtight Flexible Metal Conduit (LFMC) arises from heightened requirements for protection against moisture and environmental factors in electrical installations. This conduit type is particularly valued in sectors where exposure to water, dust, and other contaminants occurs frequently. Industries including construction, manufacturing, and utilities increasingly adopt LFMC to ensure compliance with stringent safety and performance standards. The growing emphasis on safety regulations and certifications reinforces the segment’s relevance in electrical applications, supporting its integration across varied environments.
Technological advancements contribute to the evolution of LFMC, with innovations enhancing flexibility and durability. Product evolution aligns with broader trends toward lightweight and efficient materials, appealing to designers and engineers seeking streamlined solutions. Increased focus on reducing installation time and costs drives demand for more adaptable conduit options, including LFMC. This adaptability positions LFMC favorably within the Electrical Conduit market, allowing it to meet changing consumer preferences.
End-use dynamics show a shift toward sustainable building practices, with LFMC offering advantages in both energy efficiency and installation versatility. The segment experiences traction in renewable energy sectors, where reliable conduit solutions are critical for solar and wind power installations. Consumption shifts toward higher-quality and environmentally friendly materials reflect broader market trends, driving growth in LFMC utilization.
Cost structures related to LFMC production often reflect the raw material sourcing challenges that persist in the market. Fluctuations in prices for metals and plastics apply pressure on manufacturers, influencing overall pricing strategies. Margins compress owing to producers striving to balance quality with competitive pricing in a dynamic marketplace. Maintaining supply chain resilience proves crucial, because manufacturers navigate logistical vulnerabilities and competition from substitute products.
Amid potential disruptive alternatives, LFMC retains its position due to unique properties that meet specific application needs. Strategic opportunity windows appear in areas where traditional conduits fall short, positioning LFMC because a preferred choice for projects demanding reliability and performance. The capital investment outlook for LFMC indicates positive trends, with manufacturers aiming to enhance production capabilities and meet rising demand within the Electrical Conduit market.
Investments in infrastructure development significantly influence the demand for Rigid PVC Conduit within the Electrical Conduit market. This product type benefits from its lightweight properties, corrosion resistance, and ease of installation, making it suitable for various applications including residential and commercial wiring. The trend towards sustainable construction materials drives interest in Rigid PVC, aligning with growing environmental awareness and regulatory initiatives aimed at reducing carbon footprints.
Rapid urbanization contributes to increased construction activities, further driving the adoption of Rigid PVC Conduit for electrical installations. End-users in the residential and commercial sectors prioritize cost-effective solutions, and Rigid PVC offers competitive pricing compared to metal alternatives. Enhancements in manufacturing processes, alongside technological advancements, support product evolution. This results in improved performance and longevity of Rigid PVC Conduit.
Regulatory compliance shapes the market landscape, with standards governing electrical installations driving the selection of conduit materials. Evolving construction practices emphasize safety and efficiency, leading to a shift towards robust, compliant solutions. Supply chain resilience becomes essential, ensuring consistent access to raw materials for production while mitigating risks related to sourcing and logistics vulnerabilities.
Shifts in consumption patterns reflect a growing preference for Rigid PVC Conduit, particularly in regions investing heavily in residential and commercial infrastructure. Strategic opportunities arise from the increasing demand for next-generation electrical systems that require durable and flexible conduit solutions. This dynamic environment presents avenues for capital investment, enabling manufacturers to enhance production capabilities while capturing emerging market segments within the Electrical Conduit market.
Adoption of HDPE conduit reflects a growing interest in lightweight, durable, and corrosion-resistant solutions within the Electrical Conduit market. The expansion of this segment aligns with increasing investments in infrastructure and energy projects, which demand reliable and efficient wiring systems. Technological advancements contribute to the evolution of HDPE conduit, enhancing its properties and application versatility. Regulatory compliance standards for environmental safety and performance support its integration across various industries.
The segment benefits from downstream applications in residential, commercial, and industrial settings, where demand for efficient power distribution systems remains robust. End-use dynamics indicate a shift toward sustainable materials, with HDPE conduit emerging because a preferred choice for its recyclability and lower environmental impact. This trend aligns with global efforts to promote eco-friendly construction practices, influencing consumption patterns within the market.
Strategic opportunity windows arise because manufacturers invest in innovation and product development, enhancing HDPE conduit offerings. Supply chain resilience remains critical, with raw material sourcing practices focusing on sustainability to mitigate disruptions. The segment's ability to adapt to changing market conditions positions it favorably for future growth within the broader Electrical Conduit market.
Electrical Nonmetallic Tubing (ENT) plays a significant role in the electrical conduit market due to its lightweight and flexible nature, making it suitable for various applications, including residential wiring and telecommunications. The increasing trend toward energy-efficient building practices drives demand, attributed to ENT's advantages in insulation and protection against environmental factors.
Growth in the segment is supported by technological advancements that enhance product durability and performance, aligning with the industry's shift toward more sustainable materials and practices. The evolution of smart technologies, requiring efficient wiring solutions, has further highlighted the importance of ENT in modern installations.
Regulatory compliance concerning safety standards and environmental impact influences the segment's expansion. Certifications related to fire resistance and safety ratings contribute to increased adoption across various end-use industries, including residential and commercial construction. The market responds to these regulatory landscapes by innovating products that meet rigorous standards.
Challenges related to pricing volatility affect the cost structure of ENT, impacting margins for manufacturers and suppliers. Fluctuations in raw material prices lead to increased production costs, necessitating strategic sourcing and supply chain management to maintain competitiveness. Manufacturers implement measures to mitigate these challenges and ensure stable operations.
Strategic opportunity windows emerge through increased investment in infrastructure projects, particularly in emerging markets. These regions present significant potential for expanding the use of ENT in new construction and refurbishment projects, enhancing overall market growth prospects.
Emerging trends in the Others (FNC/LFNC, RTRC, Fiberglass) segment highlight the increasing adoption of materials that provide enhanced durability and resistance to harsh environments. These attributes align with the growing demand for high-performance conduits in applications including renewable energy systems and industrial settings. Technological maturation in manufacturing processes supports the development of innovative products that cater to specific customer needs, driving overall market growth.
Substitution risks arise due to the availability of alternative materials, prompting manufacturers to focus on differentiating their product offerings. Engagement with regulatory compliance standards is significant, because adherence to safety and environmental regulations influences the adoption of these conduits across various applications. The segment's expansion is further supported by strategic investments in research and development, which enhance product evolution and market penetration.
End-use dynamics shift towards sectors that prioritize sustainability and energy efficiency, increasing the market's relevance in green building initiatives. Demand for fiberglass conduits, in particular, reflects a growing preference for lightweight and corrosion-resistant options. The interaction of market drivers creates a strategic opportunity window for stakeholders to capitalize on emerging applications and encourage long-term growth in the Electrical Conduit market.
Valued at USD 3.2 billion in 2026, the Building Power & Lighting Wiring segment is projected to reach USD 5.1 billion by 2033, at a CAGR of 7.1% during the forecast period. Demand for building power and lighting wiring solutions stems from a surge in construction activities and infrastructure development. Urbanization and rising population densities in metropolitan areas drive the need for efficient wiring solutions, pushing builders and contractors to invest in advanced electrical conduits that enhance safety and reliability.
Technological advancements play a crucial role in shaping the segment's growth. Innovations in materials and manufacturing processes contribute to the development of conduits that offer better performance while ensuring compliance with stringent regulatory standards. Increasing focus on energy efficiency and sustainability fuels demand for products designed to minimize energy consumption and reduce environmental impact.
End-use dynamics significantly influence the market landscape. The residential sector exhibits strong growth due to rising investments in smart home technologies, which integrate advanced electrical systems for power and lighting. Commercial and institutional sectors actively seek improved electrical infrastructure to support expanding operational capacities. This trend reinforces the need for reliable and durable conduit solutions.
Pricing volatility poses challenges for suppliers, driven by fluctuations in raw material costs that affect profit margins. Suppliers actively monitor market conditions to adjust pricing strategies effectively. Despite these pressures, the overall outlook for the Building Power & Lighting Wiring segment remains positive, with continued investments expected to drive growth within the Electrical Conduit market.
Growth in the Utility Transmission & Distribution segment reflects a strong focus on upgrading and expanding electrical infrastructure globally. Increasing investments in renewable energy systems and smart grid technologies drive demand for reliable and efficient transmission solutions. This segment is projected to reach USD 3.5 billion by 2033, at a CAGR of 8.1% during the forecast period. Rising energy consumption and urbanization necessitate robust and efficient electrical conduits to support expansive utility networks.
Regulatory compliance standards influence the adoption of advanced electrical conduits, ensuring safety and reliability in transmission systems. The push for sustainable energy solutions contributes to the increasing relevance of this segment within the Electrical Conduit market. Enhancements in product technologies, including improved insulation and corrosion resistance, further facilitate broader application across various utility installations, reinforcing the segment's growth potential.
Strategic opportunity windows arise due to governments prioritizing energy infrastructure projects, enhancing financial support for utility transmission developments. The focus on reducing carbon emissions strengthens the imperative for innovative conduit solutions that align with eco-friendly energy goals. Overall, the Utility Transmission & Distribution segment is a critical component of the evolving Electrical Conduit market, poised for significant expansion in response to global energy demands.
Demand for the Industrial Power, Control & Instrumentation segment benefits from ongoing advancements in automation and control systems across various industries. Increasing reliance on industrial automation and the integration of smart technologies into manufacturing processes drive the adoption of electrical conduits specifically designed for power and instrumentation applications. These conduits support critical infrastructure, ensuring the reliable transmission of power and data within industrial settings.
Investment in renewable energy systems further drives growth in this segment, with electrical conduits playing a significant role in connecting and managing power generation sources. Heightened focus on energy efficiency and sustainability results in higher demand for effective power management solutions, enhancing the segment's appeal in the market.
Valued at USD 2.9 billion by 2033, the segment reflects a strong growth trajectory driven by escalating demand for reliable power distribution and control systems in various end-use industries, including energy and utilities. The ongoing shift toward smart manufacturing and industrial IoT applications emphasizes the need for advanced electrical conduit solutions that cater to evolving technical specifications.
Regulatory compliance standards further influence market dynamics, compelling industries to adopt conduits that meet stringent safety and performance requirements. Manufacturers increasingly focus on product innovation and upgrades to enhance performance and compatibility with next-generation systems. This continuous evolution within the sector ensures resilience against competitive pressures and positions the segment for sustained growth within the broader Electrical Conduit market.
Rapid advancements in technology drive significant interest in the Data & Telecommunications Cabling segment of the Electrical Conduit market. This segment is projected to grow at a CAGR of 10.5% during the forecast period. The increasing demand for high-speed internet and the expansion of data centers strengthen the need for efficient cabling solutions. Companies invest in next-generation upgrades to enhance performance, reliability, and scalability of their infrastructure.
Changing consumption patterns towards digital solutions further contribute to this growth. Businesses prioritize the modernization of their communication networks to support rising data traffic and the proliferation of IoT devices. Regulatory compliance standards around data security and network reliability necessitate robust cabling systems, influencing purchasing decisions across various industries.
Competitive pressures encourage investments in innovative cabling technologies that promote energy efficiency and enhanced functionality. The segment's growth reflects broader trends within the Electrical Conduit market, emphasizing the importance of reliable and durable cabling solutions in supporting digital transformation initiatives. This segment plays a critical role in meeting the evolving needs of modern communication infrastructures.
Investment in transportation and infrastructure electrification drives significant demand within the Electrical Conduit market. Enhanced focus on sustainable urban development and renewable energy systems accelerates the requirement for effective conduits in modern transportation projects. Incorporation of innovative technologies and materials supports the evolution of electrical conduit solutions tailored for efficient electrification in various infrastructure applications.
Regulatory compliance standards are evolving to support infrastructure electrification, promoting the adoption of high-performance conduit systems. These changes ensure that electrical conduits meet stringent safety and efficiency requirements, further influencing market dynamics. Increased investments in smart grid technologies and electric vehicle (EV) charging infrastructure create new opportunities for conduit suppliers, driven by the need for reliable and durable electrical solutions.
The growing emphasis on renewable energy integration, coupled with advancements in electric transportation, enhances the market's overall appeal. Demand for efficient electrical installations in transportation hubs, including airports and railway stations, reflects a shift towards greener technologies and sustainable practices. Consequently, manufacturers and suppliers focus on developing next-generation products designed to meet the unique challenges posed by this evolving sector.
Strategic opportunity windows arise for market participants looking to capitalize on advancements in electrification technologies. Increased competition drives innovation, leading to enhanced product offerings that align with the needs of end users in the transportation and infrastructure sectors. Overall, the relationship between regulatory frameworks, technological advancements, and market dynamics will shape the future trajectory of the electrical conduit market in this critical application area.
Increasing investment in renewable energy sources drives demand for electrical conduits in renewable energy systems. The global shift towards sustainability and clean energy adoption reinforces this trend, prompting significant interest from various stakeholders in the electrical conduit market. Major technological advancements in solar and wind energy generation contribute to the necessity for reliable and efficient conduit systems that facilitate safe electrical wiring and component connections.
Regulatory compliance standards and certifications related to renewable energy projects enhance the market's attractiveness. These requirements ensure that installed electrical systems meet safety and performance benchmarks, which builds confidence among investors and project developers. Emerging policies aimed at promoting renewable energy generation further stimulate demand for conduits designed for these applications.
Consumption shifts towards renewable energy technologies reflect growing awareness of environmental concerns and economic advantages associated with sustainable energy solutions. This transition results in increased funding for renewable energy projects worldwide, ultimately influencing the growth trajectory of the electrical conduit market. Strategic opportunity windows emerge for manufacturers and suppliers focused on innovating products tailored to the specific needs of the renewable energy sector.
Expansion of renewable energy systems necessitates greater supply chain resilience and effective raw material sourcing strategies. Disruptive alternatives in energy generation processes prompt continuous evolution in product designs and innovations. Consequently, the market experiences heightened competition among key players striving to capture emerging segments and drive value through next-generation upgrades.
Overall, the renewable energy systems application shapes the future of the electrical conduit market, presenting significant opportunities for growth and development within this sector. Continued focus on capital investment and technological progression enhances market dynamics in the coming years.
Growing emphasis on residential space modernization drives demand for electrical conduits in residential buildings. Valued at USD 2.2 billion in 2026, this segment is projected to reach USD 3.4 billion by 2033, reflecting a compound annual growth rate (CAGR) of 6.7% during the forecast period. Increased construction activity within the residential sector, combined with rising consumer preferences for energy-efficient solutions, fuels this growth. Compliance with regulatory standards that mandate the use of specific conduit types enhances adoption among builders and contractors.
Technological advancements in conduit materials contribute to segment expansion. The market benefits from innovations that enhance product durability and electrical performance. Rising environmental concerns drive manufacturers to focus on sustainable materials that align with green building practices, further strengthening market positioning. Consumer shifts towards smart home technologies drive the need for efficient wiring solutions, positioning the electrical conduit market favorably within the residential buildings sector.
Projected growth in the Commercial & Institutional Buildings segment reflects ongoing investments in public and private sector projects, contributing to increased demand for electrical infrastructure. This segment is estimated to reach USD 3.5 billion by 2033, at a CAGR of 7.8% during the forecast period. The expansion is primarily driven by the rising need for upgraded electrical systems in urban areas and the increasing complexity of building designs, necessitating enhanced electrical conduit solutions.
Technological maturation shapes this segment, with advancements in conduit materials providing improved compliance with safety standards and enhancing durability. Adoption of energy-efficient solutions in commercial buildings further boosts demand for specialized electrical conduit products, aligning with regulatory compliance standards aimed at reducing energy consumption.
Consumption shifts towards sustainable construction practices influence purchasing decisions, with stakeholders prioritizing environmentally friendly materials. The Electrical Conduit market reflects this trend through innovations in product evolution, including the introduction of recyclable and low-emission conduit options.
Strategic opportunity windows arise from increased capital investment in commercial projects, enabling suppliers to enhance product offerings and penetrate emerging markets. Overall, the dynamics influencing the Commercial & Institutional Buildings segment highlight its contribution to the broader electrical conduit landscape, ensuring sustained growth throughout the forecast period.
Growth in the Industrial & Manufacturing segment stems from increasing automation and the need for efficient power distribution in production environments. Significant investments in smart manufacturing technologies enhance productivity, driving demand for electrical conduit solutions that ensure safe and organized wiring. The market for this segment is projected to reach USD 2.7 billion by 2033, reflecting a strong commitment to upgrading infrastructure to meet modern production standards.
Technological advancements support the evolution of conduit products, focusing on lightweight and durable materials that cater to specific industrial needs. Regulatory compliance standards emphasizing safety and efficiency drive manufacturers to prioritize high-quality conduit solutions to avoid downtime and ensure operational integrity. Enhanced product offerings and flexibility in designs enable manufacturers to adapt to varying industrial requirements, further stimulating market growth.
Demand dynamics within the Industrial & Manufacturing sector reflect a broader trend toward sustainability and energy efficiency. Increased awareness of environmental impacts encourages industries to adopt more eco-friendly electrical conduit options, aligning with global sustainability goals. These factors contribute to a robust outlook for the Electrical Conduit market, driving innovation and investment across the supply chain.
Investment in the Energy & Utilities segment reflects a strategic response to increased demand for efficient and reliable energy solutions. This segment is projected to grow at a CAGR of 8.9% during the forecast period, driven by ongoing modernization of infrastructure and a shift towards sustainable energy sources. Utilities increasingly adopt advanced technology solutions for transmission and distribution networks, necessitating the use of robust electrical conduits to enhance reliability and safety.
The demand for electrical conduits in the Energy & Utilities sector aligns with regulatory pressures aimed at improving energy efficiency and reducing environmental impact. Compliance with evolving regulations encourages utilities to upgrade existing systems and implement new projects, contributing to segment growth. Increased investment in renewable energy systems leads to a surge in demand for electrical conduits that facilitate the integration of alternative energy sources into the grid.
Technological advancements in conduit materials and designs enhance performance and durability, further supporting market expansion. Innovations including flexible metal conduits enable more versatile installations, accommodating various application needs in energy distribution. Enhanced product offerings cater to the specific requirements of utilities, driving adoption and reinforcing the segment's position within the broader electrical conduit market.
Strategic investments in infrastructure development and energy transition initiatives fuel demand for electrical conduits in this segment. The focus on creating resilient energy networks continues to push utilities toward adopting advanced conduit solutions, with significant implications for overall market dynamics. The integration of smart technologies and enhanced materials ensures ongoing growth and transformation within the Energy & Utilities segment.
Investment in data centers and telecommunications continues to rise, driven by increased demand for high-speed internet and cloud services. This growth highlights the importance of reliable and efficient electrical conduit solutions tailored for sophisticated installations. Technological advancements, including the shift towards 5G networks and Internet of Things (IoT) applications, create further opportunities for innovation within the electrical conduit market.
The increasing focus on energy efficiency and sustainability influences product evolution in this segment. Manufacturers explore new materials and designs that enhance performance while reducing environmental impact. Regulatory compliance standards shape the market, ensuring that products meet safety and performance requirements in data centers and telecommunications facilities.
Cost pressures related to raw material sourcing and pricing volatility challenge producers in this segment. Supply chain resilience becomes crucial to maintain competitive pricing and reliable product availability. Strategic opportunity windows arise for companies that effectively navigate these challenges while delivering high-quality solutions tailored to the demands of the electrical conduit market.
Investment in transportation infrastructure significantly influences growth in the Electrical Conduit market. This segment benefits from the increasing need for efficient power distribution systems, driven by urbanization and rising population density in metropolitan areas. Infrastructure projects, including roads, bridges, and rail networks, demand reliable electrical systems to support lighting, signaling, and communication technologies. The expansion of smart city initiatives further increases demand, because cities seek to integrate advanced electrical systems into their infrastructure.
Technological advancements play a crucial role in shaping this segment. Innovations in conduit materials and designs enhance durability and ease of installation, making them attractive options for transportation applications. The emphasis on sustainability encourages the use of environmentally friendly materials, aligning with regulatory compliance standards aimed at reducing carbon footprints. Consequently, manufacturers are focused on developing next-generation conduit solutions that meet evolving industry requirements.
Increased government spending on infrastructure projects creates strategic opportunity windows for suppliers within the market. Various programs aimed at enhancing transportation networks provide a steady demand for electrical conduits. This investment trend supports the overall growth trajectory, encouraging strategic partnerships among industry players to capitalize on these opportunities. By aligning product offerings with the specific needs of transportation projects, suppliers position themselves favorably within the competitive landscape.
Investment in the Oil & Gas, Mining & Petrochemicals segment contributes significantly to the demand within the Electrical Conduit market. Increasing regulatory compliance standards and the need for reliable electrical systems drive the adoption of electrical conduits in these industries. Advanced technologies in conduit manufacturing enhance product durability and performance, ensuring they meet the rigorous demands of oil and gas operations, which often occur in extreme environments.
End-use dynamics in this sector highlight the importance of safety and efficiency. Utilization of electrical conduits improves operational efficiency while providing crucial protection for electrical wiring in hazardous environments. Consumption shifts towards more robust and flexible conduit solutions reflect advancements in safety measures and environmental regulations.
Strategic opportunity windows exist owing to companies seeking to modernize aging infrastructures and adopt next-generation upgrades. Investments in sustainable practices and the integration of renewable energy systems within oil and gas operations expand the applications of electrical conduit solutions. Heightened focus on minimizing downtime and optimizing operational costs drives demand for various conduit types, ensuring a resilient supply chain.
Renewable energy integration represents a crucial driver in the Electrical Conduit market, reflecting a global shift toward sustainable power sources. Increased government incentives and regulatory frameworks aimed at promoting clean energy initiatives significantly impact adoption rates. Investments in solar, wind, and other renewable technologies boost demand for robust electrical infrastructure, including conduits that ensure safe and efficient electrical distribution.
Advancements in renewable energy technologies enhance the operational efficiency of electrical conduits. Innovations in materials and designs improve resistance to environmental factors, ensuring longevity and reliability in diverse applications. Stakeholders in the renewable energy sector require conduits that withstand harsh conditions, driving product evolution and adaptation to meet these demands.
End-use dynamics within the renewable energy sector center around the need for efficient energy transmission and distribution systems. While renewable installations proliferate, the demand for conduits designed for solar panels, wind farms, and other clean energy applications escalates. This growth trajectory emphasizes the importance of strategic opportunity windows for manufacturers and suppliers in the market.
Regulatory compliance standards continue to shape the renewable energy segment. Governments worldwide implement stringent guidelines to ensure safety and environmental sustainability, compelling manufacturers to focus on certifications and compliance in their product offerings. Such standards influence cost structures and pricing strategies, pushing companies to innovate and optimize their supply chains.
Market players actively seek to enhance supply chain resilience by diversifying raw material sourcing and improving logistics capabilities. This strategic approach mitigates the risks associated with supply chain vulnerabilities, ensuring timely delivery and cost-effectiveness. Disruptive alternatives, including emerging technologies in renewable energy, challenge established paradigms, prompting further investment in next-generation upgrades and technological maturation.
Identifying white-space opportunities in the renewable energy segment drives competition and capital investment outlook. Companies that anticipate shifts in consumer preferences toward green technology position themselves favorably to capitalize on emerging trends. Such strategic positioning within the Electrical Conduit market ensures sustained growth and relevance during evolving market demands.
Interest in the Others (Marine, Agriculture, Defense) segment stems from increasing investments in specialized applications that require robust and compliant electrical conduit solutions. Various sectors within this sub-segment demand electrical conduits that meet stringent regulatory compliance standards, ensuring safety and reliability in challenging environments. This segment experiences significant growth opportunities driven by advancements in technology that enhance conduit performance and durability, addressing the unique requirements of marine applications and agricultural installations.
The evolution of electrical conduit products facilitates integration into diverse applications, including renewable energy systems and specialized industrial processes. Adoption of next-generation upgrades, including corrosion-resistant materials and flexible design options, strengthens the market position of conduit manufacturers catering to these sectors. Demand dynamics shift towards innovative solutions that improve efficiency and product lifespan, reflecting the ongoing transformation in the Electrical Conduit market.
Strategic opportunities arise from the increasing focus on sustainable practices and efficient resource management across marine and agricultural industries. The introduction of environmentally friendly materials and production techniques aligns with the growing emphasis on sustainability, attracting investments and enhancing market growth. This sub-segment provides avenues for capital investment and product innovation, contributing to the overall development of the market.
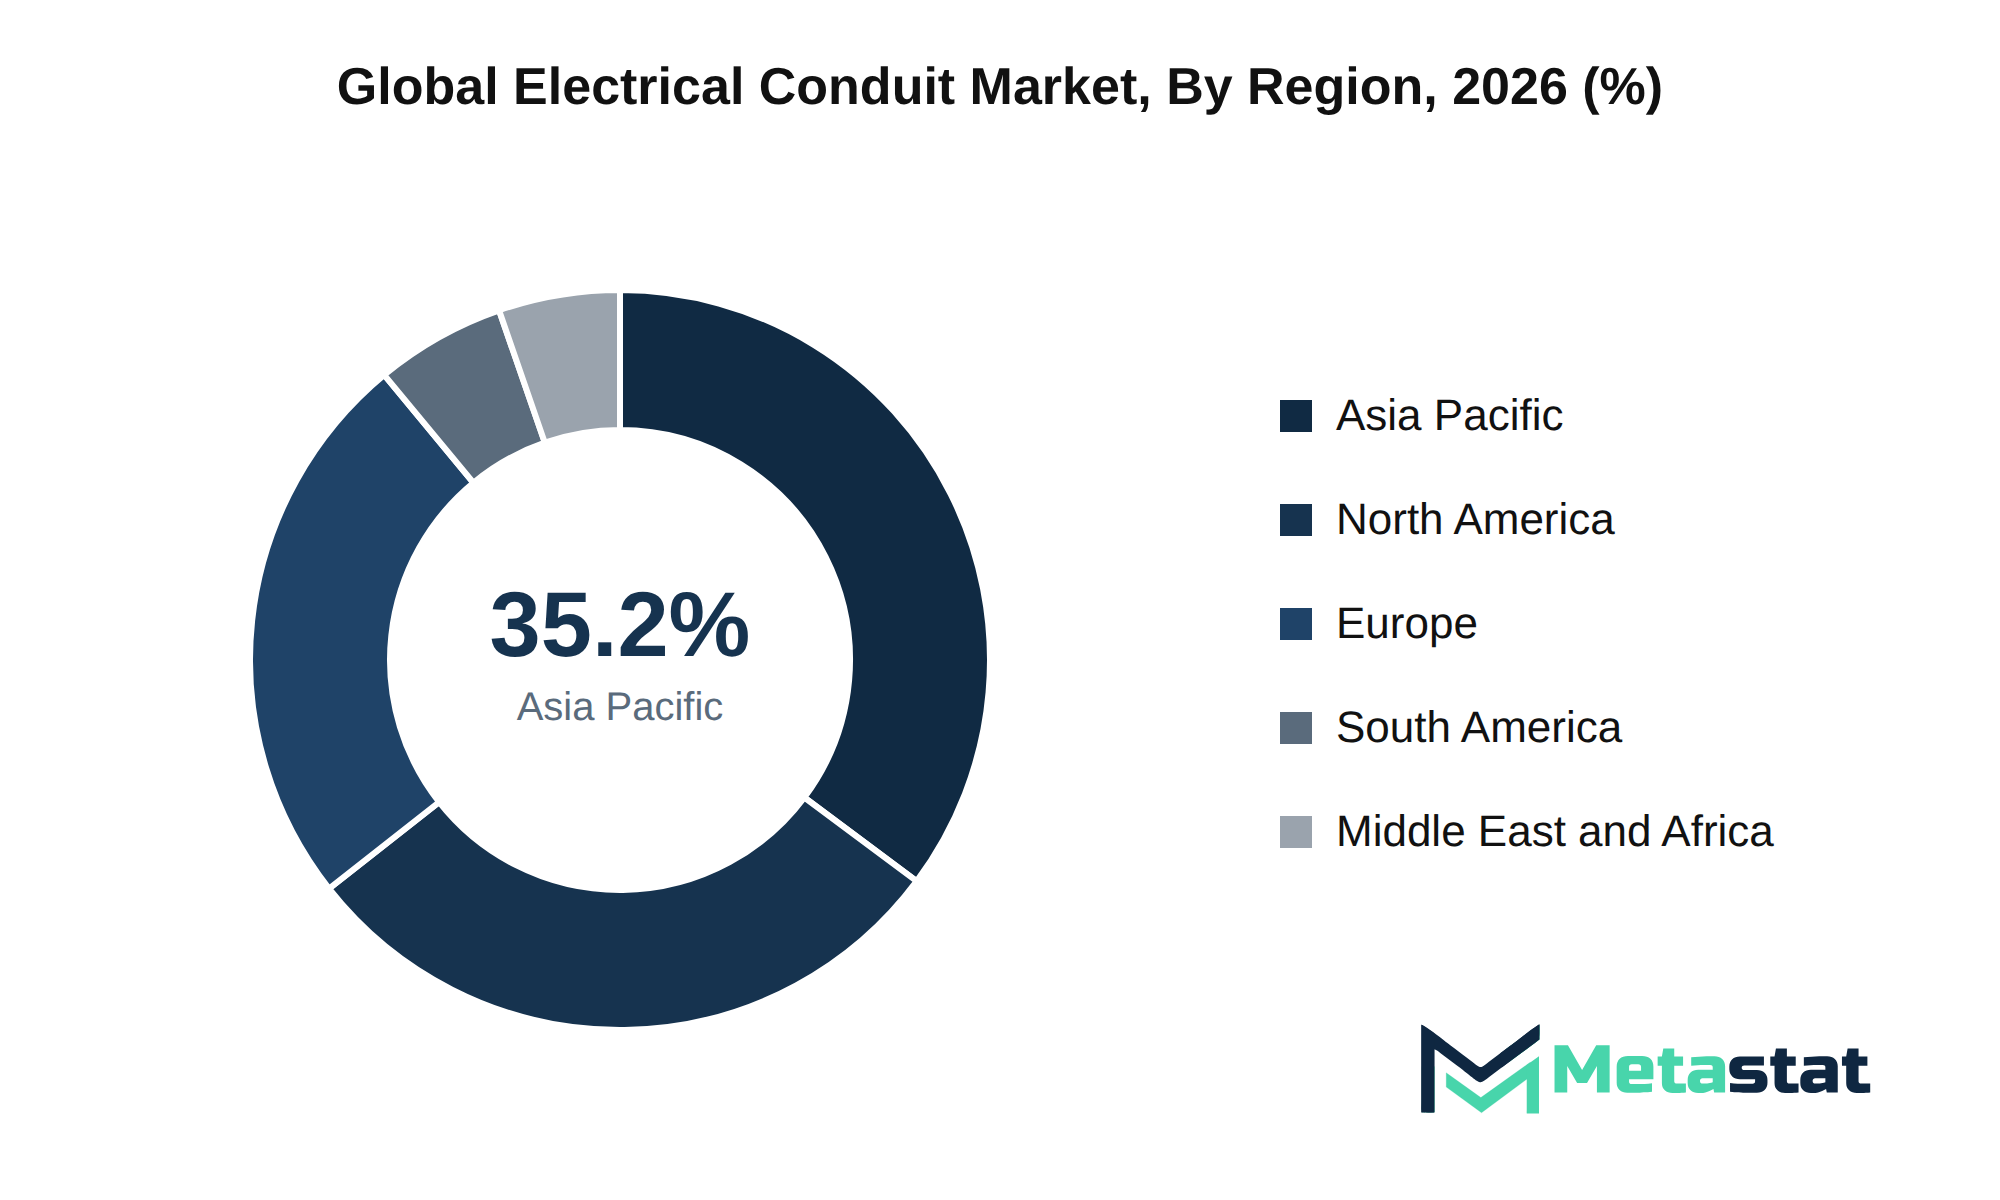
Based on geography, the Global Electrical Conduit market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America represents a substantial portion of the global Electrical Conduit market, holding a share of 29.2% in 2025. The market is set to expand at a CAGR of 8.4% within the forecast period, reaching a market size (TAM) of USD 4.7 billion by the end of 2033.
Investment in infrastructure modernization acts because a primary demand driver, particularly within the United States, Canada, and Mexico. These countries prioritize upgrading their electrical systems to meet evolving energy needs and enhance grid resiliency. The focus on energy efficiency and reliable power distribution increases the adoption of electrical conduit solutions.
The residential buildings segment particularly benefits from increasing consumer demand for sustainable and energy-efficient solutions. Growth in this sector corresponds with rising population densities and urbanization trends across major cities in North America.
Several factors contribute to regional market dynamics, including supply chain regionalization and localized manufacturing densities. Efforts to nearshore production and strengthen domestic supply chains enhance competitive advantages for vendors operating in the market, facilitating quicker response times to customer demands.
Geopolitical influences and trade policy shifts significantly affect the competitive landscape. Domestic market participants leverage strategic partnerships and collaborations to strengthen their positions. This consolidation trend encourages innovation, driving further advancements in product offerings and efficiencies.
Cross-border trade corridors between the United States, Canada, and Mexico support efficient procurement processes. The cultural nuances and B2B purchasing behaviors in these countries shape how businesses approach procurement decisions, emphasizing trust and reliability in supplier relationships.
Overall, the North American Electrical Conduit market reflects strong growth potential, driven by modernization initiatives and strategic investments across various sectors. The combination of local market dynamics, competitive strategies, and infrastructure readiness primes the region for sustained expansion.
The Electrical Conduit market in Europe is characterized by a diverse range of applications and demand drivers. Key countries contributing to market growth include Germany, France, the UK, Italy, Spain, and Russia, each exhibiting unique requirements and consumption patterns. The region accounts for 24.6% of the global market in 2025.
Infrastructure modernization across Europe drives the adoption of electrical conduit systems, particularly in residential and commercial building sectors. Regulatory frameworks surrounding energy efficiency and safety standards influence procurement decisions. Local compliance mandates drive manufacturers to innovate and enhance product offerings, aligning with regional requirements for sustainable and efficient solutions.
In the context of supply chains, regionalization and nearshoring initiatives enable faster response times and improved inventory management, enhancing market dynamics. This shift leads to localized manufacturing densities, creating competitive advantages for domestic market participants. The market dynamics in Europe reflect a balance between established players and emerging innovators, contributing to a competitive landscape.
Overall, the Electrical Conduit market in Europe benefits from strategic foreign direct investment flows and geographic expansion windows that support growth. Market participants continue to navigate geopolitical fragmentation effectively, ensuring resilience within the regional framework. This environment presents both opportunities and challenges for stakeholders aiming to penetrate underdeveloped areas while maintaining competitiveness amid mature market conditions.
The Asia-Pacific region accounts for 35.2% of the global Electrical Conduit market in 2025. Key drivers of growth include rapid urbanization and increased infrastructure development. Major economies, including China and India, invest heavily in modernization efforts, leading to heightened demand for electrical installations. Japan and South Korea contribute to market expansion through advanced technology adoption and energy-efficient solutions.
Localized manufacturing capabilities offer competitive advantages, supporting supply chain efficiency. Countries with robust industrial bases, like China, facilitate high-volume production of electrical conduit products, catering to regional demand. The growing focus on energy grid resilience and sustainable infrastructure further increases investments in electrical conduit applications.
Emerging markets within Southeast Asia present strong potential, driven by industrial growth and infrastructure initiatives. These countries represent underpenetrated territories, creating opportunities for market players. Cross-border trade corridors enhance accessibility to various regional markets, increasing competition among suppliers.
The presence of domestic market participants, coupled with the regional competitive landscape, influences procurement behaviors. Local compliance mandates and regulatory frameworks shape business strategies, necessitating adherence to specific standards across the region. Cultural nuances in B2B purchasing further guide vendor relationships and market dynamics.
While the Asia-Pacific region continues to mature, incremental growth vectors will emerge from replacement cycles and ongoing investments in infrastructure. The combination of high-value projects and localized production efforts positions the market for sustained growth through 2033.
South America holds a share of 5.7% in the global Electrical Conduit market in 2025. The adoption of electrical conduit products in Brazil and Argentina reflects a growing recognition of the importance of infrastructure modernization. Investment in residential buildings and commercial projects enhances demand for efficient electrical systems, driving market expansion.
Infrastructure developments, particularly in urban areas, contribute to the increasing need for electrical conduit solutions. The region's focus on improving energy grid resilience positively influences market dynamics, presenting opportunities for localized manufacturing and procurement strategies. Brazil's substantial infrastructure projects and Argentina's efforts towards modernization increase overall market potential.
Regional competitive landscapes highlight the presence of domestic suppliers, promoting vendor consolidation trends and localized procurement dynamics. Supply chain regionalization and nearshoring initiatives enhance responsiveness to demand fluctuations, thereby supporting market growth. The evolving geopolitical landscape impacts cross-border trade corridors, creating an environment conducive to investment in electrical conduit solutions.
The Electrical Conduit market in the Middle East and Africa reflects emerging growth driven by infrastructure modernization and an increasing focus on energy efficiency. Countries including Saudi Arabia and the UAE prioritize investments in energy grid resiliency, enhancing demand for conduit solutions that support sustainable energy initiatives. South Africa's expanding industrial sector contributes to the region's growth, with significant projects in construction and utilities requiring robust conduit systems.
Localized manufacturing densities enhance the competitiveness of domestic players. Companies adapt to evolving regulatory frameworks, ensuring compliance with local mandates while catering to the unique procurement dynamics prevalent in the region. Cultural nuances influence B2B buying behaviors, emphasizing durability and reliability in conduit materials.
Supply chain regionalization trends and nearshoring initiatives are evident. Companies seek to optimize operational efficiencies. The Electrical Conduit market experiences incremental growth driven by high-value replacement cycles and the introduction of advanced conduit technologies. Overall, the region's market dynamics reflect a blend of mature and emerging characteristics, presenting opportunities for both established and new entrants seeking to capitalize on the growing demand.
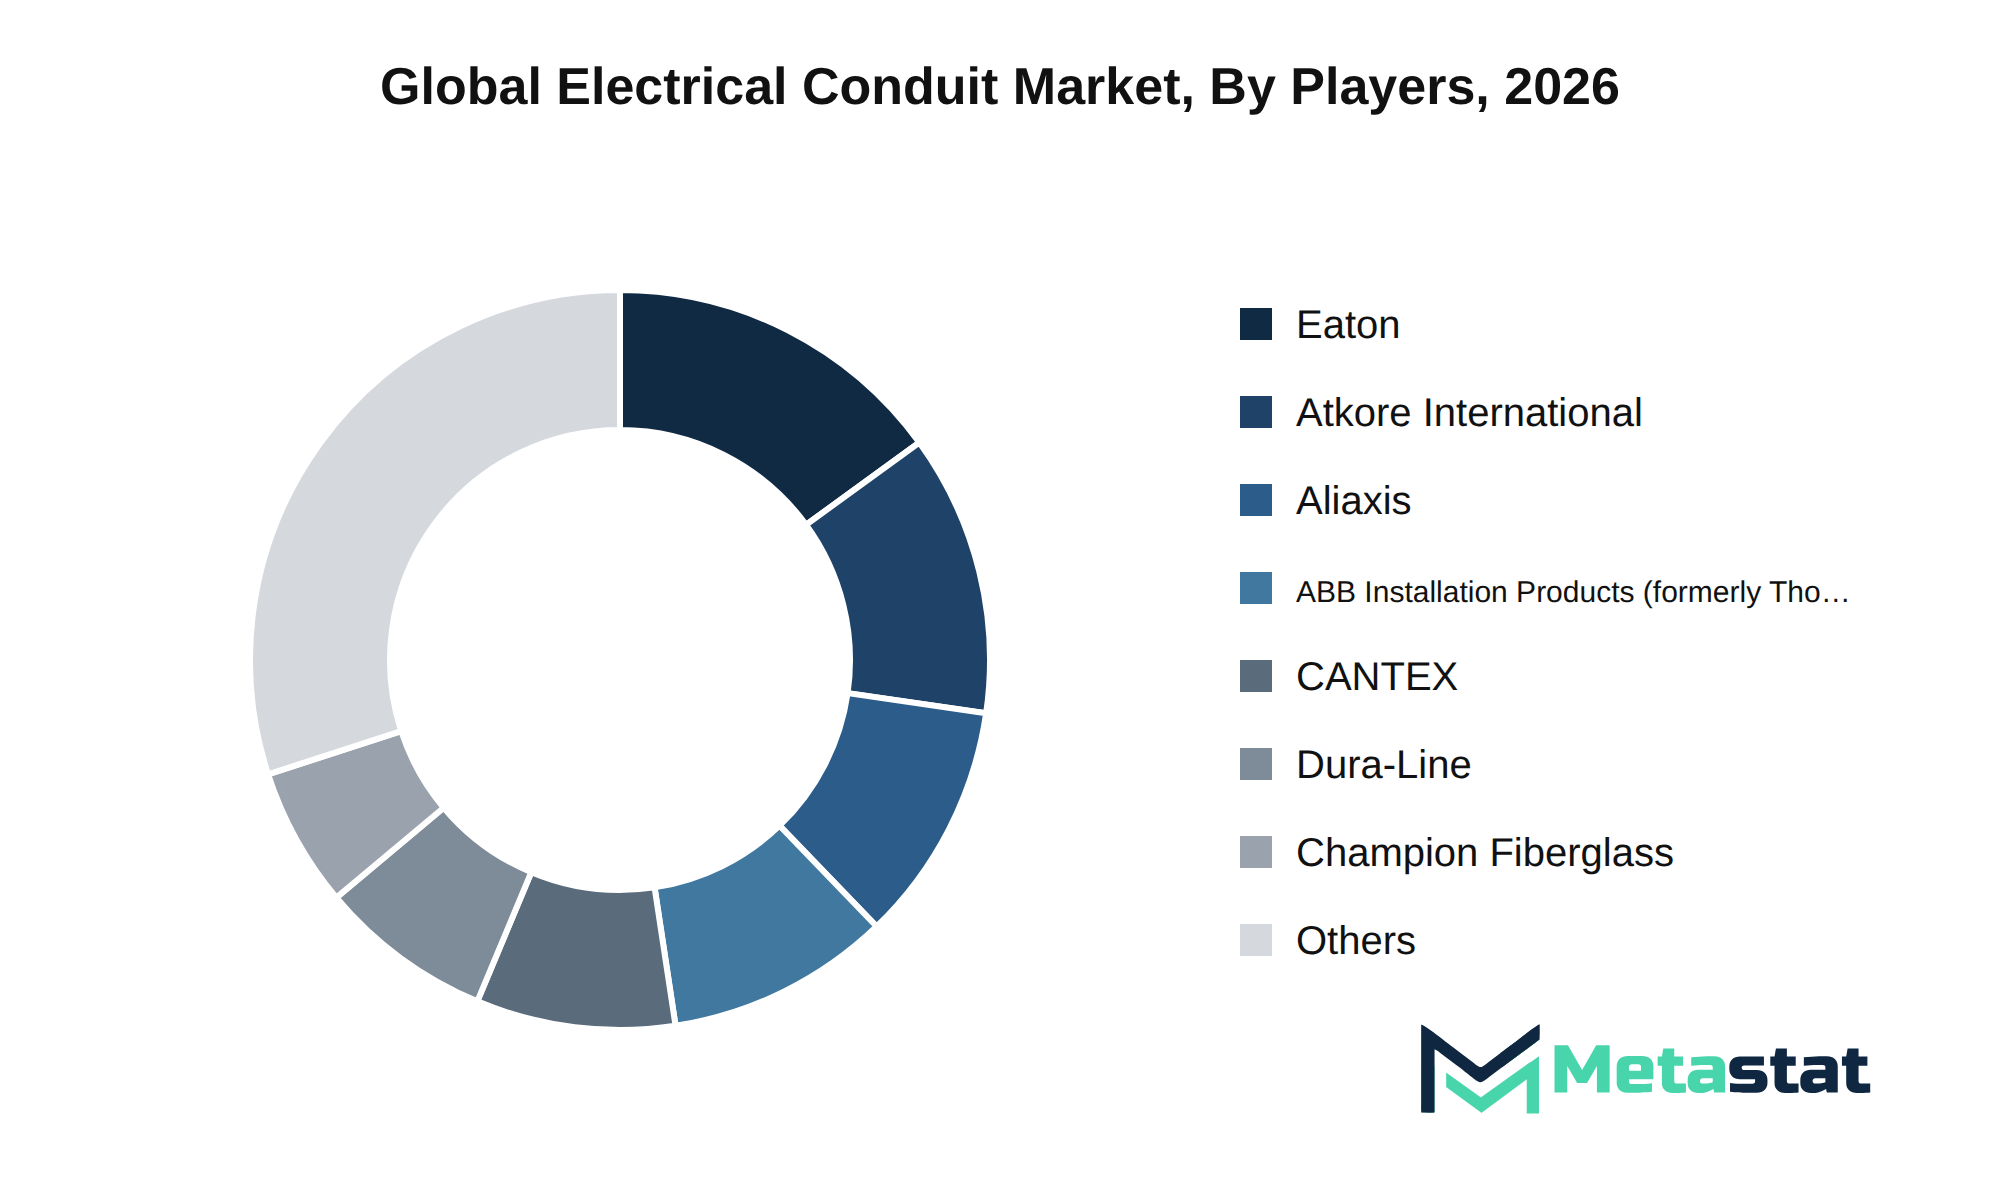
The Electrical Conduit market displays a diverse range of players, each employing unique strategies to secure their positions. Companies including ABB Installation Products, Eaton Corporation plc, and Schneider Electric focus on product differentiation, emphasizing innovation and quality in their offerings. Their commitment to research and development enhances proprietary technology moats, improving their competitive edge.
Strategic alliances and partnerships significantly influence the market. For instance, companies like Atkore International and Aliaxis SA engage in cross-industry collaborations to expand their reach and leverage complementary strengths. This approach strengthens resilience against new entrants, ensuring robust market positions while evolving demands persist.
Price architecture and procurement leverage influence competitiveness. Companies including Dura-Line Corporation and CANTEX Inc. implement strategic pricing models to attract diverse customer segments while maintaining profitability. Customer retention strategies, including loyalty programs and enhanced service offerings, contribute to sustained market presence.
Intellectual property portfolios serve because a defensive imperative for leading companies like Siemens AG and GEWISS S.p.A. Their extensive patent landscapes protect innovations, creating barriers to entry for potential disruptors. The future competitive outlook in the Electrical Conduit market hinges on continued technological advancements and strategic growth vectors, ensuring dynamic development and adaptation.
Market size is forecast to rise from USD 8.9 billion in 2025 to over USD 16.9 billion by 2033. The base case anticipates growth at an 8.4% CAGR, driven by a combination of macroeconomic factors and structural shifts within core industries. Bull case scenarios suggest accelerated demand through technological advancements and increased infrastructure investments, enhancing revenue generation within the Electrical Conduit market. Alternatively, bear case conditions highlight potential challenges, including geopolitical tensions and supply chain disruptions, which could impede growth rates.
Downstream demand patterns reflect an evolution influenced by urbanization and increased energy efficiency regulations. The maturation of core industries contributes to a stable consumption environment, while next-generation technology integration, particularly in renewable energy systems, creates new opportunities for market participants. Research and development commercialization timelines play a crucial role in determining the introduction of innovative products, reinforcing competitive positioning.
Regulatory evolution impacts compliance timelines, creating an imperative for companies to adapt swiftly to new standards. Evolving trade corridors and global supply chain shifts necessitate strategic capital allocation directives, ensuring resilience in the face of economic fluctuations. Emerging white-space opportunities, stemming from unmet enterprise needs in sectors like renewable energy and smart infrastructure, present high-growth pockets for investment.
Executive-level strategic imperatives focus on defensibility roadmaps, emphasizing the importance of maintaining competitive advantages. Companies operating in the market prioritize adaptability and innovation to navigate the complexities of the evolving environment. Future growth recommendations include enhancing operational efficiencies and exploring collaborations that leverage technological advancements to meet changing consumer demands.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Electrical Conduit market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 8.4% from 2026 to 2033 |
Revenue Unit | USD billion |
Segmentation | By Product Type, Application, End-Use Industry, and Region |
By Region | North America (By Product Type, Application, End-Use Industry, and Country)
|
Europe (By Product Type, Application, End-Use Industry, and Country)
| |
Asia Pacific (By Product Type, Application, End-Use Industry, and Country)
| |
South America (By Product Type, Application, End-Use Industry, and Country)
| |
Middle East and Africa (By Product Type, Application, End-Use Industry, and Country)
|
Find answers to common questions about this report
The Electrical Conduit market size was valued at USD 8.9 billion in 2025, according to the Metastat Insights study.
The Electrical Conduit market is projected to grow at a CAGR of 8.4% during the forecast period from 2026 to 2033.
The North America Electrical Conduit market size is estimated to reach USD 4.7 billion by 2033.
The Electrical Metallic Tubing (EMT) segment leads the market, projected to reach USD 3.2 billion by 2033. This figure surpasses other product types, indicating strong demand in this category.
Increased economic growth and investment in infrastructure projects significantly drive the Electrical Conduit market. Government and private sector budgets expand for construction and modernization, enhancing demand for efficient energy distribution and management systems. Rising consumer spending on commercial and residential infrastructure further supports market growth.
The Electrical Conduit market faces challenges from regulatory compliance, escalating operational costs, and supply chain disruptions. Strict adherence to safety regulations increases manufacturing expenses, while rising raw material and labor costs limit profitability. Geopolitical instability further complicates procurement processes, creating uncertainty and affecting timely delivery of materials.
Investment in infrastructure modernization and urban development drives product adoption in the Electrical Conduit market. Enhanced economic conditions and a focus on energy efficiency encourage governments and private sectors to allocate resources toward upgrading aging infrastructure, creating significant opportunities for innovation and diversification of product offerings.
The Electrical Conduit market is estimated to reach a valuation of USD 16.9 billion by 2033.
Key players in the Electrical Conduit market include ABB Installation Products (formerly Thomas & Betts), Aliaxis SA, Atkore International, Eaton Corporation plc, Legrand S.A., Schneider Electric, Siemens AG, and Southwire Company, LLC.
The Electrical Conduit market in Asia Pacific is projected to reach USD 5.7 billion by 2033, driven by increasing infrastructure development and urbanization.
Choose Your License
Global Electrical Conduit Market
The analysts below cover Chemicals and Materials research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
INDUSTRY CONSULTANT - CHEMICALS & ADVANCED MATERIALS
Chemicals and Materials · Machinery & Equipment · Packaging
Amit Gadhekar Consultant for Chemicals and Materials at MetaStat Insight, directing sector-specific intelligence, research, and strategic consulting across global chemical and processing markets.
Scaling antibody-drug conjugate manufacturing hinges on contract manufacturing availability for high-potency active ingredients. The MetaStat Insight analysis looked closely at global cleanroom slot constraints, bioconjugation batch failure rates, and supply chain redundancies between the US, Europe, and India. The supplier capability matrix proved genuinely useful for our team when mapping secondary source options across our clinical pipeline.
Floating offshore wind feasibility relies heavily on specialized installation vessel availability and port crane limits, which most broad renewable energy forecasts ignore. The report delivered a thorough analysis of dry dock capacity, mooring chain supply constraints, and raw material pricing trends for deepwater anchor installations. It served as a solid independent sanity check for our offshore project capital expenditure assumptions.
Assessing commercial microgrid software adoption requires looking past top-level installation numbers and examining utility interconnection queues. The research provided verifiable data on average permitting timelines, tariff structures, and battery storage integration costs across regional utility territories. That grounded perspective was valuable for our team when building five-year demand projections for industrial microgrid controllers.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950