
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Hard Chrome Plated Steel Bar Market Size, Share, By Product Configuration (Standard Hard Chrome Plated Bars and Induction-Hardened Hard Chrome Plated Steel Bars), By Bar Diameter (Up to 20 mm, 21-50 mm, 51-100 mm, and Above 100 mm), By Base Steel Grade (Carbon Steel, Alloy Steel, Stainless Steel, and Microalloyed Steel), By Application (Hydraulic Cylinder Piston Rods, Pneumatic Cylinder Rods, Linear Motion Shafts, Machine Columns, Tie Bars and Guide Rods, Gas Springs and Shock Absorbers, and Others), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5355
September, 2026
250 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $744.4 Million in 2025, projected to reach $1,125.6 Million by 2033 at a 5.3% CAGR.
Dominant Segment: The Induction-Hardened Hard Chrome Plated Steel Bars segment leads with a projected growth to USD 403.9 million by 2033, driven by increased demand for durable materials in hydraulic and pneumatic systems.
Geographic Lead: The Asia-Pacific region is expected to witness the fastest growth, fueled by ongoing infrastructure development and rising industrial automation trends.
What's Inside: This report provides a comprehensive analysis of the competitive landscape, market dynamics, and detailed forecasts for the Hard Chrome Plated Steel Bar market from 2026 to 2033.
Emerging Applications: Significant opportunities arise from emerging applications in industries such as automotive and aerospace, where hard chrome plated steel bars are increasingly adopted for their superior performance.
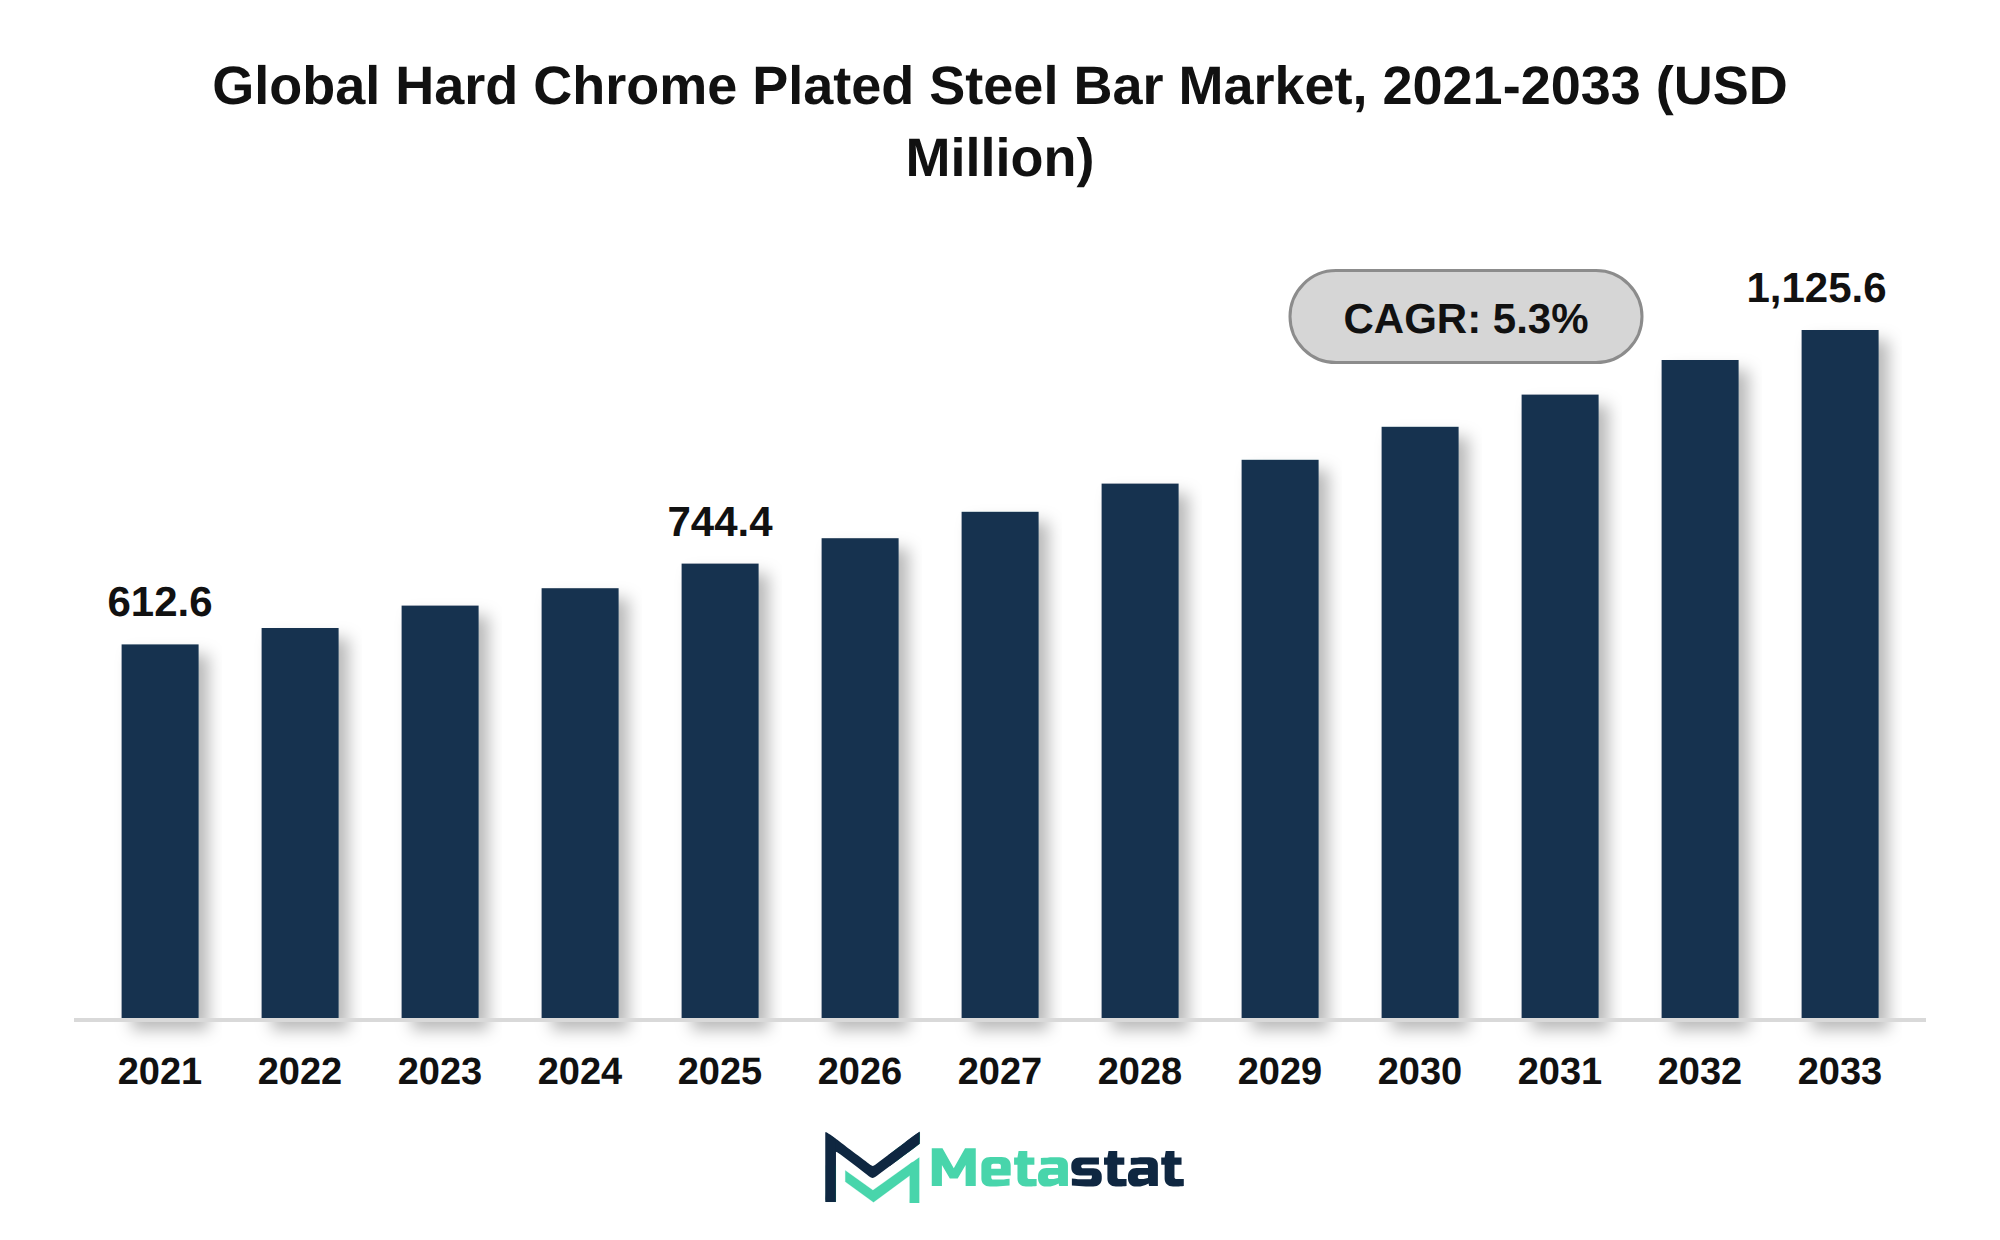
The global Hard Chrome Plated Steel Bar market was valued at USD 744.4 million in 2025 and is projected to reach USD 1,125.6 million by 2033, growing at a CAGR of 5.3% over the forecast period.
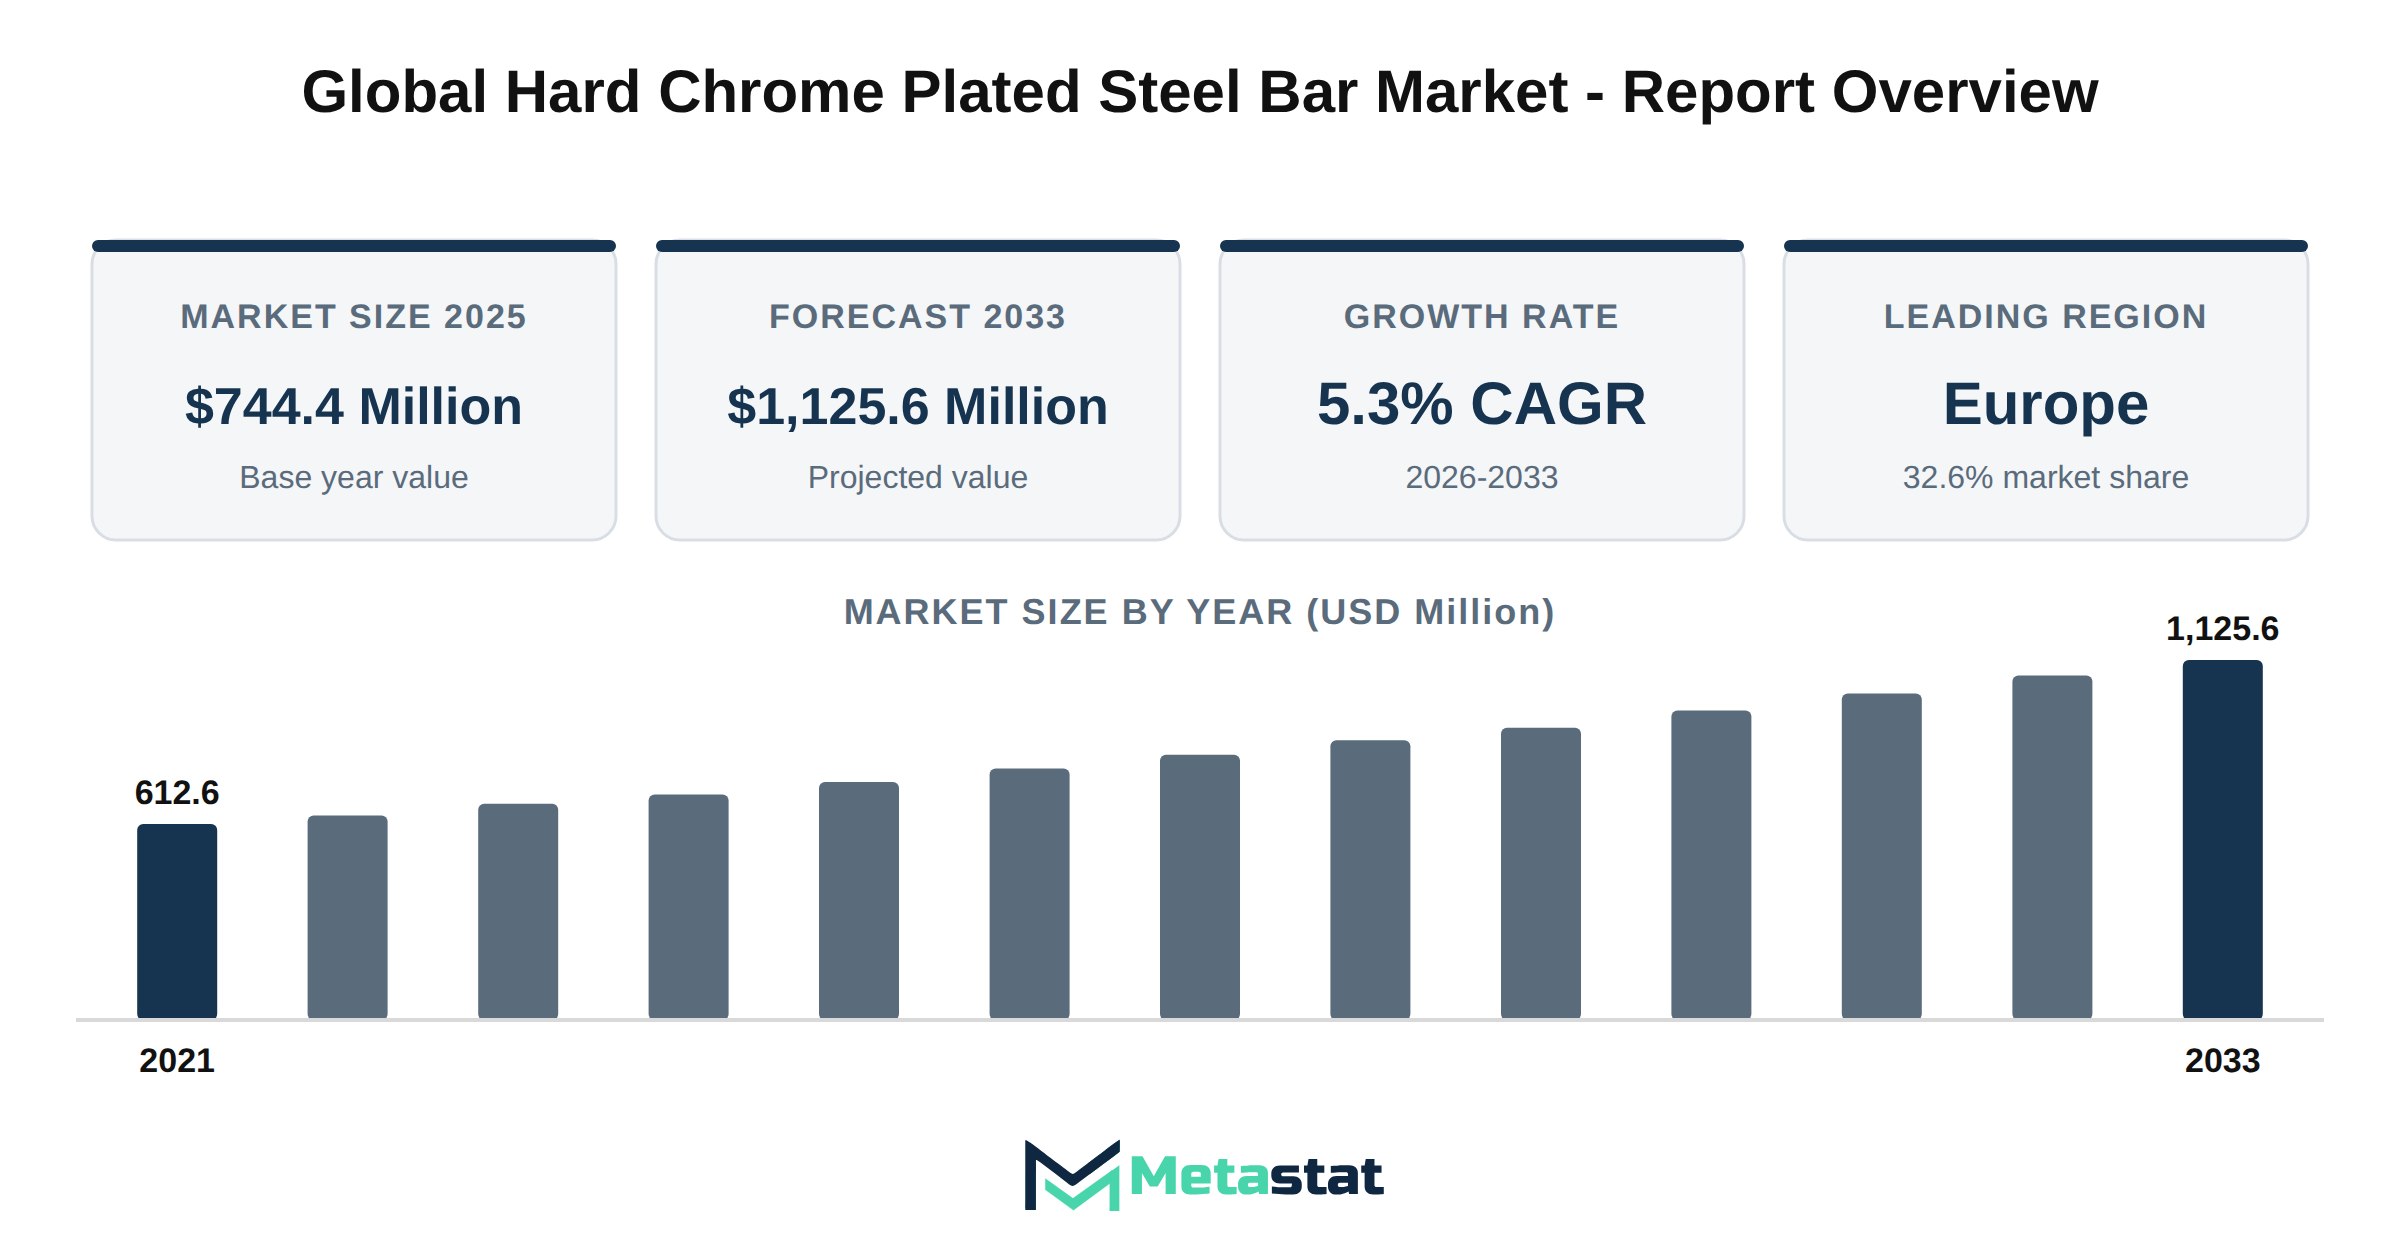
The Hard Chrome Plated Steel Bar market reached a valuation of USD 744.4 million in the base year of 2025. This market is projected to attain USD 1,125.6 million by the end of the forecast period in 2033, reflecting a compound annual growth rate (CAGR) of 5.3% between 2026 and 2033.
Demand across hydraulic and pneumatic cylinder applications significantly influences market growth. Sectors including automotive and industrial machinery drive this demand, highlighting the importance of high-performance hydraulic systems. The expansion of induction-hardened chrome plated bars in heavy-duty machinery contributes to enhanced durability and operational efficiency, positioning these bars favorably within the market.
Hydraulic cylinder manufacturing trends increase the need for hard chrome plated steel bars, with manufacturers focusing on producing lightweight and high-strength components. The construction and earthmoving equipment sectors exhibit substantial demand for these bars, driven by ongoing infrastructure development projects globally.
Industrial automation trends expand the demand for precision chrome plated shafts, essential for achieving high accuracy and reliability in automated systems. Production of hard chrome plated bars primarily involves carbon steel and alloy steel, with a noticeable shift towards using high-strength materials to meet evolving industry standards.
Stainless steel chrome plated bars gain traction in corrosive environments, where resistance to oxidation and wear is critical. Innovations in surface hardness and corrosion resistance enhance the longevity and performance of chrome plated steel bars, catering to the needs of various industrial applications.
Demand for hard chrome plated steel bars is significant across hydraulic and pneumatic cylinder applications, driven by the increasing need for high-performance components in various industrial sectors. Hydraulic cylinder manufacturing trends focus on producing durable and efficient systems, which boosts the demand for sturdy chrome plated bars that enhance performance and reliability.
The growth of induction-hardened chrome plated bars in heavy-duty machinery reflects the industry's shift towards more robust materials that withstand extreme conditions. This trend highlights the adaptation of chrome plated bars to meet the rigorous demands of heavy machinery, increasing their market penetration.
Construction and earthmoving equipment sectors exhibit a rising demand for hard chrome plated steel bars, largely due to their essential role in hydraulic systems. This equipment relies on the superior performance and longevity of chrome plated components, contributing to market growth.
Industrial automation further expands the demand for precision chrome plated shafts, driven by manufacturers seeking components that enhance accuracy and efficiency in automation processes. The integration of advanced technologies in production lines increases the importance of high-quality chrome plated bars.
Trends in hard chrome plated bar production show a notable shift towards carbon steel and alloy steel, which offer superior mechanical properties. The preference for these materials supports the production of chrome plated bars that meet stringent application requirements in various industries.
Stainless steel chrome plated bars are gaining traction in corrosive environments, where their resistance to oxidation and degradation ensures product longevity. This trend reflects a broader market movement towards selecting materials that enhance durability in challenging conditions.
Innovation in surface hardness and corrosion resistance for chrome plated steel bars enhances their appeal to manufacturers. Advances in technology allow for the development of bars with superior performance characteristics, attracting investment and interest in the market.
Chrome plating thickness and surface finish trends in piston rod manufacturing indicate a focus on achieving optimal performance metrics. Manufacturers prioritize these attributes to ensure that chrome plated bars meet the specific needs of advanced hydraulic systems.
Supply chain dynamics for steel, chromium, and precision bar processing significantly influence production capabilities and costs in the market. Fluctuations in raw material availability impact pricing and supply chain efficiency, shaping overall market conditions.
Environmental regulations are reshaping hard chrome plating technologies, pushing manufacturers towards eco-friendly alternatives and practices. This shift not only affects production methods but influences consumer preferences for sustainable products.
Compliance with hexavalent chromium regulations drives the development of alternative surface treatment solutions. Manufacturers are investing in innovative technologies that align with environmental standards while maintaining product quality in the hard chrome plated steel bar market.
Competitive benchmarking among global hard chrome plated bar manufacturers illustrates varying strategies aimed at market share expansion. Companies are adopting differentiated approaches to meet diverse customer needs and capitalize on emerging opportunities.
Asia Pacific manufacturing expansion in hard chrome plated steel bars positions the region because a critical player in the global market. Investment in production capabilities enhances regional competitiveness and supports increased output to meet growing demand.
European demand for high-performance hydraulic piston rod materials reflects a trend towards quality and reliability in component selection. This demand influences production strategies and market positioning within the region.
North American opportunities in construction and material handling equipment create a favorable environment for hard chrome plated steel bar manufacturers. The ongoing investment in infrastructure projects drives the need for high-quality components, supporting market growth.
The outlook for large-diameter hard chrome plated steel bars indicates potential growth due to their application in heavy machinery and specialized equipment. This segment presents an opportunity for manufacturers to innovate and expand their product offerings.
Linear motion and guide shaft applications contribute to new growth opportunities within the market. The increasing reliance on precision components in various sectors highlights the importance of hard chrome plated bars in enhancing operational efficiency.
Pricing trends for hard chrome plated steel bars and specialty steel grades are influenced by market dynamics and raw material costs. Understanding these trends is crucial for manufacturers to effectively navigate the competitive environment.
Future growth opportunities in high-performance chrome plated piston rods point to an evolving market driven by technological advancements and increasing demand for specialized applications.
Investment in infrastructure development significantly influences the Hard Chrome Plated Steel Bar market. Increased public and private spending on construction, transportation, and industrial facilities drives demand for high-quality materials, including hard chrome plated steel bars. These materials are essential for applications in hydraulic systems, machinery, and automotive components, where durability and performance are critical. The growing focus on upgrading existing infrastructure and building new assets enhances the need for reliable and robust materials.
Economic factors, including GDP growth and capital investments, create favorable conditions for the construction industry. Strengthening economies lead businesses to invest in new projects, resulting in an increased requirement for hard chrome plated steel bars. This trend drives market expansion by creating opportunities across various sectors, including manufacturing, automotive, and energy.
Technological advancements in construction and manufacturing processes further contribute to the demand for hard chrome plated steel bars. Automation and digital transformation in industries enhance operational efficiency, requiring high-performance materials that withstand rigorous operational conditions. This dynamic promotes growth within the market, leading to improved productivity and cost-efficiency for end-users.
The ongoing technological integration in manufacturing processes significantly boosts efficiency in the Hard Chrome Plated Steel Bar market. Automation, artificial intelligence, and software adoption streamline operations, reducing production times and enhancing product quality. Manufacturers leveraging advanced technologies optimize workflows, leading to cost savings and improved output. This increase in operational efficiency attracts investments, further stimulating market growth.
Digitizing legacy processes enables firms to respond swiftly to changing consumer demands. Greater flexibility allows manufacturers to adjust production schedules and quantities, aligning closer with market trends. Such adaptability positions the Hard Chrome Plated Steel Bar market favorably against competitors who do not fully embrace these technological advancements.
The emphasis on technological integration not only enhances productivity but supports sustainable practices. Improved resource management through automation reduces waste, contributing to environmental goals. Overall, this trend toward digital transformation in the manufacturing sector directly influences the market’s expansion and its ability to meet evolving consumer needs.
Regulatory compliance presents significant challenges within the Hard Chrome Plated Steel Bar market, hindering expansion efforts. Stringent environmental regulations and compliance requirements increase operational complexity and costs for manufacturers. Firms face difficulties in adapting to evolving regulations, which restrict production capabilities and lead to delays in bringing products to market.
Capital stagnation further exacerbates these challenges, because companies struggle to secure necessary investments for compliance-related upgrades and technology improvements. Many manufacturers experience inflationary pressures that increase operational costs, making it difficult to maintain competitive pricing while adhering to regulatory mandates. These factors contribute to a more fragmented market, where smaller players find it challenging to navigate the compliance landscape, ultimately impacting overall market growth.
Geopolitical instability disrupts supply chains, leading to shortages of essential materials needed for production. This disruption results in increased costs and delays, further complicating compliance with local and international regulations. Several players in the Hard Chrome Plated Steel Bar market find themselves at a competitive disadvantage, ultimately affecting their market position and opportunities for growth.
Geopolitical fragmentation significantly impacts the Hard Chrome Plated Steel Bar market through trade deficits and tariff friction between various countries. Rising protectionism raises operational costs for companies engaging in international trade, ultimately affecting their pricing strategies and market competitiveness. This scenario restricts access to raw materials and components, resulting in supply chain instability and heightened uncertainty for manufacturers.
Technological disruptions further complicate the market landscape. Companies face challenges in adopting new technologies while dealing with complex research and development integrations. These disruptions create barriers to entry for smaller firms lacking the resources to invest in advanced production methods, limiting overall market growth. Interoperability friction between different technologies delays implementation timelines and increases development costs.
The evolving demands for sustainability and decarbonization exert pressure on the industry to innovate and adapt to stricter environmental standards. Companies address these pressures while managing rising input costs and workforce skill gaps, creating potential talent retention challenges. The Hard Chrome Plated Steel Bar market experiences ongoing transformation driven by firms striving to balance environmental compliance with operational efficiency.
Lastly, the market faces logistics disruptions and infrastructure gaps that hinder efficient transportation of goods. These challenges contribute to increased lead times and operational delays, affecting overall supply chain dynamics. Successful navigation of these issues is crucial for companies aiming to maintain their competitive edge in the Hard Chrome Plated Steel Bar market.
The Hard Chrome Plated Steel Bar market experiences significant opportunities due to emerging applications across various industries. The demand for hydraulic cylinder piston rods, pneumatic cylinder rods, and machine columns drives the need for hard chrome plated steel bars. Industries including automotive, aerospace, and manufacturing increasingly adopt these bars due to their superior durability and performance in critical applications. The expansion of these applications supports revenue growth and market penetration.
Digital transformation influences purchasing behaviors, with companies prioritizing efficient procurement processes. The shift towards online procurement platforms streamlines sourcing activities, creating a more competitive environment. This transition allows suppliers to reach a broader customer base, enhancing sales opportunities and encouraging innovation within the market.
Geographical expansion remains a key factor, particularly in developing regions. Increased infrastructure projects and industrial growth in Asia Pacific and South America contribute to rising demand for hard chrome plated steel bars. This geographical diversification supports manufacturers in capitalizing on emerging markets, driving investment and production capacities to meet local needs.
Sustainability imperatives push industries towards eco-friendly practices, leading to increased interest in green transformations. Adoption of hard chrome plated steel bars that adhere to environmentally friendly manufacturing processes attracts companies focused on aligning with ESG principles. Meeting these sustainable practices enhances brand reputation and drives growth in customer segments prioritizing responsible sourcing.
Strategic consolidation through mergers and partnerships among key players enhances competitive positioning. Collaborations enable shared resources, technological advancements, and expanded product portfolios, increasing efficiency. Such initiatives create a robust market environment for hard chrome plated steel bars, encouraging innovation and customer-focused solutions that align with evolving market demands.
The Global Hard Chrome Plated Steel Bar market is segmented based on Product Configuration, Bar Diameter, Base Steel Grade, and Application.
Valued at USD 531 million in 2026, the Standard Hard Chrome Plated Bars segment is projected to reach USD 721.7 million by 2033, achieving a CAGR of 4.5% during the forecast period. Increasing demand from various end-use applications, particularly in hydraulic and pneumatic systems, drives this growth. Industries including construction and manufacturing significantly contribute to consumption, owing to the requirement for durable and corrosion-resistant materials for critical components.
The evolution of product quality and performance standards enhances the appeal of standard hard chrome plated bars. Manufacturers increasingly focus on improving surface finishes and dimensional accuracy, responding to the growing requirements for high-performance applications. This technological maturation supports market growth, allowing suppliers to meet specific customer needs efficiently.
Cost structures in this segment reflect the balance between raw material sourcing and production processes. Fluctuations in raw material prices pressure margins, prompting manufacturers to seek alternative sourcing strategies or innovative production techniques. Regulatory compliance standards further shape the operational landscape, necessitating adherence to quality certifications that influence the competitive environment.
Strategic opportunity windows arise from the increasing adoption of automation and advancements in manufacturing technologies. These factors influence consumption shifts, encouraging investment in next-generation upgrades that enhance efficiency. While the Hard Chrome Plated Steel Bar market grows, stakeholders remain agile to capitalize on emerging trends and maintain supply chain resilience.
Induction-Hardened Hard Chrome Plated Steel Bars represent a dynamic segment within the Hard Chrome Plated Steel Bar market, projected to reach USD 403.9 million by 2033, at a CAGR of 6.8% during the forecast period. The growth of this segment aligns with increased demand for durable materials in various applications, particularly in hydraulic and pneumatic systems. End-users actively seek enhanced performance and longer lifespans in components, driving adoption across industries including manufacturing, construction, and automotive.
Technological advancements facilitate the expansion of this segment. Innovations in induction hardening processes improve the material's strength and wear resistance, appealing to manufacturers targeting high-performance applications. The trend towards automation in manufacturing processes further accelerates the adoption of induction-hardened bars, driven by industries increasingly investing in equipment that demands high durability and precision.
Regulatory compliance standards impact the segment, prompting manufacturers to innovate and improve their offerings. Emerging regulations emphasize the need for environmentally friendly production processes, compelling suppliers to adopt sustainable practices while maintaining product quality. This shift influences the cost structures and pricing strategies of manufacturers, leading to a more competitive market environment.
Downstream applications contribute significantly to the segment's growth. Industries using induction-hardened bars prioritize components in critical systems, driving demand for reliable and robust products. The continuous evolution of end-use dynamics in sectors including hydraulics, pneumatics, and machinery supports the sustained expansion of this segment within the overall market.
Valued at USD 176.7 million in 2026, the Up to 20 mm segment is projected to reach USD 240.2 million by 2033, reflecting a compound annual growth rate (CAGR) of 4.5% during the forecast period. Primary demand drivers for this segment include applications in hydraulic systems and machinery, where precise dimensions and high durability are crucial. Industries including automotive, aerospace, and construction employ components within this diameter range for hydraulic cylinder piston rods and pneumatic cylinder rods.
Technological maturation enhances product quality, making advancements in manufacturing processes essential. Investments in next-generation upgrades support consistent evolution in performance and reliability, driving the adoption of hard chrome plated steel bars in various applications. Regulatory compliance standards influence production practices, ensuring that materials meet safety and environmental regulations, which strengthens market integrity.
Supply chain resilience directly impacts raw material sourcing, where fluctuations in pricing affect overall margins. Substitution risks arise from alternative materials developed with advanced characteristics, prompting manufacturers to innovate continuously. This dynamic environment creates strategic opportunity windows for investment in research and development, enhancing product offerings within the hard chrome plated steel bar market.
Demand for hard chrome plated steel bars within the 21-50 mm segment stems from various applications, particularly in industries requiring precision and durability. This segment's growth reflects an increased focus on hydraulic and pneumatic systems, where robust materials are essential. Shifting consumer preferences towards higher-quality components that enhance operational efficiency and lifespan directly influence market dynamics.
Technological advancements are critical in expanding this segment. Ongoing development of manufacturing processes that enhance the hardness and wear resistance of steel bars contributes to their adoption in high-stress applications. Investments in research and development drive innovation in product offerings, ensuring compatibility with emerging technologies.
The 21-50 mm segment is projected to reach USD 396.9 million by 2033, at a CAGR of 4.9% during the forecast period. This anticipated growth reflects a broader trend towards the use of hard chrome plated steel bars in various manufacturing sectors, aligning with rising demand for components that withstand harsh operational conditions.
Regulatory compliance shapes the landscape of the market. Stricter standards related to material properties and environmental impact compel manufacturers to adopt advanced processing techniques. Meeting these standards enhances product appeal and opens avenues for entry into new markets, facilitating expansion and increasing competitiveness.
Overall, the ongoing evolution of applications, coupled with technological maturation and regulatory pressures, positions the 21-50 mm segment for sustained growth within the hard chrome plated steel bar market. The focus on product quality and performance ensures that this segment remains integral to the broader market.
Growth in the 51-100 mm segment reflects increasing demand from various industrial applications, particularly in hydraulic systems and machinery. These applications rely heavily on high-performance materials, driving manufacturers to adopt hard chrome plated steel bars for their durability and resistance to wear. Enhanced product characteristics, including improved hardness and surface finish, contribute to the segment's expansion, attracting investments from businesses focused on quality and performance.
Technological advancements enable manufacturers to produce more efficient and precise hard chrome plated steel bars that meet the stringent requirements of modern machinery. This evolution aligns with industry standards and customer expectations, encouraging further adoption within the market. While these bars provide significant advantages in terms of longevity and operational efficiency, industries including automotive and manufacturing increasingly prefer them.
By 2033, the 51-100 mm segment is projected to reach USD 343 million. With the rising focus on sustainability and regulatory compliance, the hard chrome plated steel bar market experiences further pressure on costs and pricing strategies. Manufacturers adapt by optimizing their supply chain processes and enhancing production efficiency, which positions them competitively in the marketplace.
Projected growth in the Above 100 mm segment occurs at a CAGR of 6.1% during the forecast period. This segment's development correlates with increasing demand for heavy-duty applications, particularly within industries including construction and manufacturing. The adoption of these larger diameter bars is driven by their superior strength and durability, which meet requirements for high-stress environments.
Infrastructural projects, particularly in emerging economies, stimulate demand for heavy lifting and robust machinery that relies on components made from hard chrome plated steel bars. Manufacturers focus on enhancing product features, leading to innovations that improve performance and meet evolving industry standards. Such advancements increase consumption in sectors prioritizing reliability and efficiency.
Pricing volatility in raw materials and increased operational costs influence the cost structure of the Above 100 mm segment. However, these factors create an opportunity for manufacturers to implement strategic pricing models that reflect value. Effective supply chain management and robust sourcing strategies ensure that suppliers maintain competitiveness while navigating challenges presented by fluctuating material prices.
Enhanced regulatory compliance standards increase the importance of quality and safety certifications, particularly in construction and heavy machinery sectors. Compliance with industry standards positions manufacturers favorably in the market, building trust among end-users and promoting increased adoption of hard chrome plated steel bars.
Market dynamics indicate a shift towards larger diameter applications, responding to the growing need for high-performance components. This trend underlines the strategic opportunity for investment, particularly in technology that enhances production capabilities and product longevity. Overall, the Above 100 mm segment is poised for significant growth, contributing to the broader expansion of the hard chrome plated steel bar market.
Valued at USD 373.9 million in 2026, the Carbon Steel segment is projected to reach USD 502.2 million by 2033, at a CAGR of 4.3% during the forecast period. Rising demand for Carbon Steel in various applications, particularly in hydraulic components, drives this growth. Enhanced properties, including resistance to wear and improved fatigue strength, contribute to the popularity of Carbon Steel in the Hard Chrome Plated Steel Bar market.
Technological advancements in production processes facilitate the development of high-quality Carbon Steel products. These innovations enable manufacturers to meet increasing expectations for performance and durability. Evolving industry standards and the transition to more efficient and reliable components fuel the demand for Carbon Steel in the market.
Downstream applications, particularly in hydraulic cylinder piston rods and pneumatic cylinder rods, significantly influence consumption trends. The automotive and machinery sectors exhibit increased adoption of Carbon Steel components, reflecting growing confidence in their performance and reliability. The segment's expansion closely ties to the overall health of these industries.
Raw material sourcing and supply chain resilience play critical roles in the stability of Carbon Steel prices. Fluctuations in raw material costs impact profit margins for manufacturers. Strategic sourcing and efficient logistics management are essential to mitigate pricing volatility and maintain competitive positioning.
Overall, the Carbon Steel segment demonstrates strong growth potential, driven by ongoing technological advancements, increased adoption in key industries, and evolving market dynamics. Planned expansion and investment in production capabilities will further strengthen the segment's position in the Hard Chrome Plated Steel Bar market.
Demand for alloy steel in the Hard Chrome Plated Steel Bar market is driven by its unique properties, which enhance performance in various applications. Industries using hydraulic systems, automotive components, and machinery benefit from the strength and durability of alloy steel. The segment is expected to attract attention due to its reliability in high-stress environments, significantly influencing adoption rates. Market expansion results from advancements in manufacturing technologies and an increasing focus on product quality.
Alloy steel is estimated to reach USD 286.8 million by 2033, at a CAGR of 5.5% during the forecast period. The growing preference for alloy steel over traditional carbon steel highlights its superior performance characteristics. Regulatory compliance, especially in industries where safety and reliability are critical, further supports the demand for alloy steel in critical applications. This shift towards higher-quality materials indicates a market transition that aligns with broader trends in manufacturing and engineering.
Technological maturation influences the evolution of alloy steel applications, with continuous innovations in metallurgy and processing techniques enhancing its properties. The development of next-generation alloy steel grades, tailored for specific applications, provides opportunities for manufacturers to differentiate their offerings within the market. In addition, cost structures are influenced by raw material sourcing and supplier dynamics, emphasizing the importance of maintaining efficient supply chains to mitigate price volatility.
Competitive pressures exist owing to alternative materials vying for market share, yet the unique characteristics of alloy steel ensure its relevance in demanding applications. Strategic investment in research and development will be essential for suppliers aiming to capitalize on emerging trends and consumer demands. Overall, the alloy steel segment within the Hard Chrome Plated Steel Bar market demonstrates solid growth potential driven by industry-specific dynamics and evolving customer preferences.
Growth in the stainless steel segment reflects increasing application across various industries, driven by excellent corrosion resistance and high strength properties. Valued at USD 161.7 million by 2033, this segment benefits from heightened demand in sectors including automotive, aerospace, and manufacturing, where durability and reliability are essential. Adoption of advanced manufacturing techniques further enhances product performance, encouraging manufacturers to invest in stainless steel hard chrome plated bars.
Technological advancements in coating processes improve the efficiency and effectiveness of stainless steel applications. These innovations enable the production of components that meet stringent regulatory compliance standards, promoting broader acceptance in high-performance environments. The market's expansion depends on meeting evolving customer requirements for reliability and performance, ensuring sustained growth in this segment.
Price stability in raw materials influences cost structures across the industry. Fluctuations in stainless steel prices affect margins and profitability for manufacturers, necessitating strategic sourcing and inventory management to mitigate risks. Effective supply chain resilience supports manufacturers in maintaining product availability and competitive pricing, which is crucial for sustaining market presence. Increasing investment in stainless steel applications reinforces the growth trajectory of the hard chrome plated steel bar market.
Interest in Microalloyed Steel within the Hard Chrome Plated Steel Bar market reflects its potential to meet the demands for high-performance applications. This segment is projected to grow at a CAGR of 6.6% during the forecast period. Factors driving this growth include enhanced mechanical properties, which optimize the performance of components subjected to high stress and wear. Industries including automotive, construction, and machinery manufacturing increasingly adopt microalloyed steel for its superior strength-to-weight ratio.
Innovations in metallurgical techniques facilitate the production of microalloyed steel, enabling manufacturers to tailor properties for specific applications. The increasing preference for lightweight materials in end-use applications fuels the demand for microalloyed steel, allowing for improved efficiency and performance. The segment aligns with sustainability trends, because improved durability reduces the frequency of replacements, contributing to lower material waste and resource consumption.
Cost structures specific to microalloyed steel production indicate favorable pricing strategies, supported by advancements in technology that lower manufacturing costs. This competitive pricing enhances its attractiveness in a market characterized by fluctuating raw material prices. Strategic investments in production capabilities and supply chain resilience further position the segment for sustained growth, enhancing its presence in the evolving Hard Chrome Plated Steel Bar market.
Valued at USD 331.5 million in 2026, the Hydraulic Cylinder Piston Rods segment is projected to reach USD 451.6 million by 2033, at a CAGR of 4.5% during the forecast period. The demand for hydraulic cylinder piston rods is driven by their critical role in various applications, particularly in industrial machinery and equipment. Increasing investment in infrastructure and construction projects across multiple regions contributes to the rising need for hydraulic systems, which boosts demand for these components.
Technological advancements in hydraulic systems enhance the performance and reliability of hydraulic cylinder piston rods, leading to greater adoption in various industries. Industries including construction, automotive, and manufacturing exhibit significant growth, fueling demand within the market. Improved manufacturing processes and product evolution ensure that these rods meet stringent performance and durability standards, addressing end-user expectations.
Shifts in consumption towards more efficient and durable products influence the dynamics of the hydraulic cylinder piston rods segment. Regulatory compliance standards regarding environmental sustainability and operational efficiency prompt manufacturers to innovate and enhance product offerings. The market experiences pressure from pricing volatility and margin constraints, compelling companies to streamline operations and optimize cost structures.
Strategic opportunity windows appear due to manufacturers focusing on developing next-generation hydraulic cylinder piston rods that offer enhanced performance characteristics. Supply chain resilience remains vital, ensuring reliable raw material sourcing and mitigating potential disruptions. This segment's growth trajectory reflects the increasing importance of hydraulic systems across various sectors, contributing to the overall expansion of the Hard Chrome Plated Steel Bar market.
Growth in the Pneumatic Cylinder Rods segment aligns with increasing demand from industries requiring efficient and reliable pneumatic solutions. Innovations in pneumatic technology drive higher adoption rates, enhancing performance and reducing energy consumption in applications including manufacturing and automation. Customers emphasize the importance of lightweight and durable materials, which enhances the need for high-quality hard chrome plated steel bars.
The Pneumatic Cylinder Rods segment is projected to reach USD 203.5 million by 2033, at a CAGR of 4.9% during the forecast period. Regulatory compliance and industry standards push manufacturers towards using superior materials, leading to enhanced product offerings in the market. The ongoing trend towards automation further fuels demand, with pneumatic systems becoming integral to modern manufacturing processes.
Technological advancements in manufacturing processes contribute to the evolution of pneumatic cylinder rods, resulting in the development of more efficient and specialized products. This evolution supports the market by creating opportunities for suppliers to innovate and cater to diverse applications. Enhanced performance parameters, including increased load-bearing capacity and resistance to wear, shape customer preferences and drive the market forward.
Growth in the Linear Motion Shafts segment derives from increased applications in advanced machinery and automation systems. This segment is projected to reach USD 188.2 million by 2033, driven by rising demand for precise and efficient motion control solutions across various industries. Expansion catalysts include technological advancements that enhance the durability and performance of hard chrome plated steel bars, enabling manufacturers to meet stringent specifications in sectors including robotics and automotive.
End-use dynamics reflect a shift towards automation, resulting in higher consumption of Linear Motion Shafts in manufacturing processes. Regulatory compliance standards concerning safety and efficiency drive the adoption of high-quality materials in these applications. Cost pressures in production highlight the importance of materials that balance performance with economic considerations. The emergence of next-generation upgrades in machinery presents strategic opportunity windows for suppliers in the Hard Chrome Plated Steel Bar market.
Growth in the Machine Columns, Tie Bars and Guide Rods segment is driven by increasing applications within various industrial sectors, particularly in machinery and equipment manufacturing. The demand for reliable and durable components including machine columns and tie bars plays a critical role in ensuring operational efficiency and safety. With projected growth at a CAGR of 5.8% during the forecast period, this segment demonstrates significant expansion potential within the Hard Chrome Plated Steel Bar market.
Technological advancements contribute to the enhancement of product performance, allowing manufacturers to produce components that meet stringent industry standards. The evolution of engineering requirements and the need for precision in manufacturing processes further support the adoption of hard chrome plated steel bars in this segment. Increasing awareness of the benefits of using high-quality materials for machine components strengthens the segment's growth trajectory.
In terms of cost structures, the segment benefits from economies of scale resulting from increased production volumes. Efficient sourcing of high-grade raw materials mitigates risks related to pricing volatility and margin pressures within the market. Overall, the Machine Columns, Tie Bars and Guide Rods segment offers strategic opportunities for investment and development, creating a competitive environment for suppliers and manufacturers alike.
Demand for hard chrome plated steel bars in applications involving gas springs and shock absorbers derives from various factors, including advancements in automotive and industrial sectors. The growing focus on enhancing product performance and reliability drives manufacturers to seek high-quality materials that provide effective solutions for vibration dampening and load bearing. While technology matures, manufacturers increasingly adopt innovative designs and advanced materials, contributing to the segment's expansion within the market.
Evolution in product specifications, alongside the rising need for efficiency and durability in end-use applications, influences consumption dynamics. Industries that use gas springs and shock absorbers require components that meet stringent regulatory compliance standards, promoting demand for hard chrome plated steel bars. This trend highlights the necessity for suppliers to ensure product integrity and performance, creating a competitive environment.
Strategic opportunities emerge owing to companies investing in research and development to create next-generation gas springs and shock absorbers. Innovations in materials and applications play a crucial role in driving growth, enabling manufacturers to respond to shifting consumer preferences. Consequently, the market anticipates enhanced product offerings tailored to meet the evolving requirements of end-users.
The segment focused on precision guide shafts and specialized motion rods experiences growth driven by advancements in automation and increasing demand for high-precision components. Industries including manufacturing and robotics increasingly adopt these products for their durability and performance. The expansion of this segment results from a heightened emphasis on improving operational efficiency and reliability in critical applications.
Technological maturation shapes the market landscape. Innovations in hard chrome plating processes enhance the performance characteristics of these components, contributing to their attractiveness. The evolving needs of end-users in engineering and manufacturing sectors prompt manufacturers to invest in next-generation upgrades, ensuring alignment with market demands.
Product evolution continues to influence adoption rates, with manufacturers developing specialized solutions tailored to specific applications. The growing emphasis on regulatory compliance standards ensures that manufacturers meet the quality requirements expected by industries reliant on precision components. A shift in consumption patterns toward sustainable products drives innovations within this segment, allowing manufacturers to explore alternative raw materials while maintaining performance standards.
This sub-segment faces challenges related to pricing volatility and margin pressures, stemming from fluctuations in raw material costs. Strategic opportunity windows emerge because manufacturers navigate these challenges, balancing cost structures while seeking to enhance supply chain resilience. Continuous improvements and investment in production capabilities facilitate a competitive edge within the hard chrome plated steel bar market.
Based on geography, the Global Hard Chrome Plated Steel Bar market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
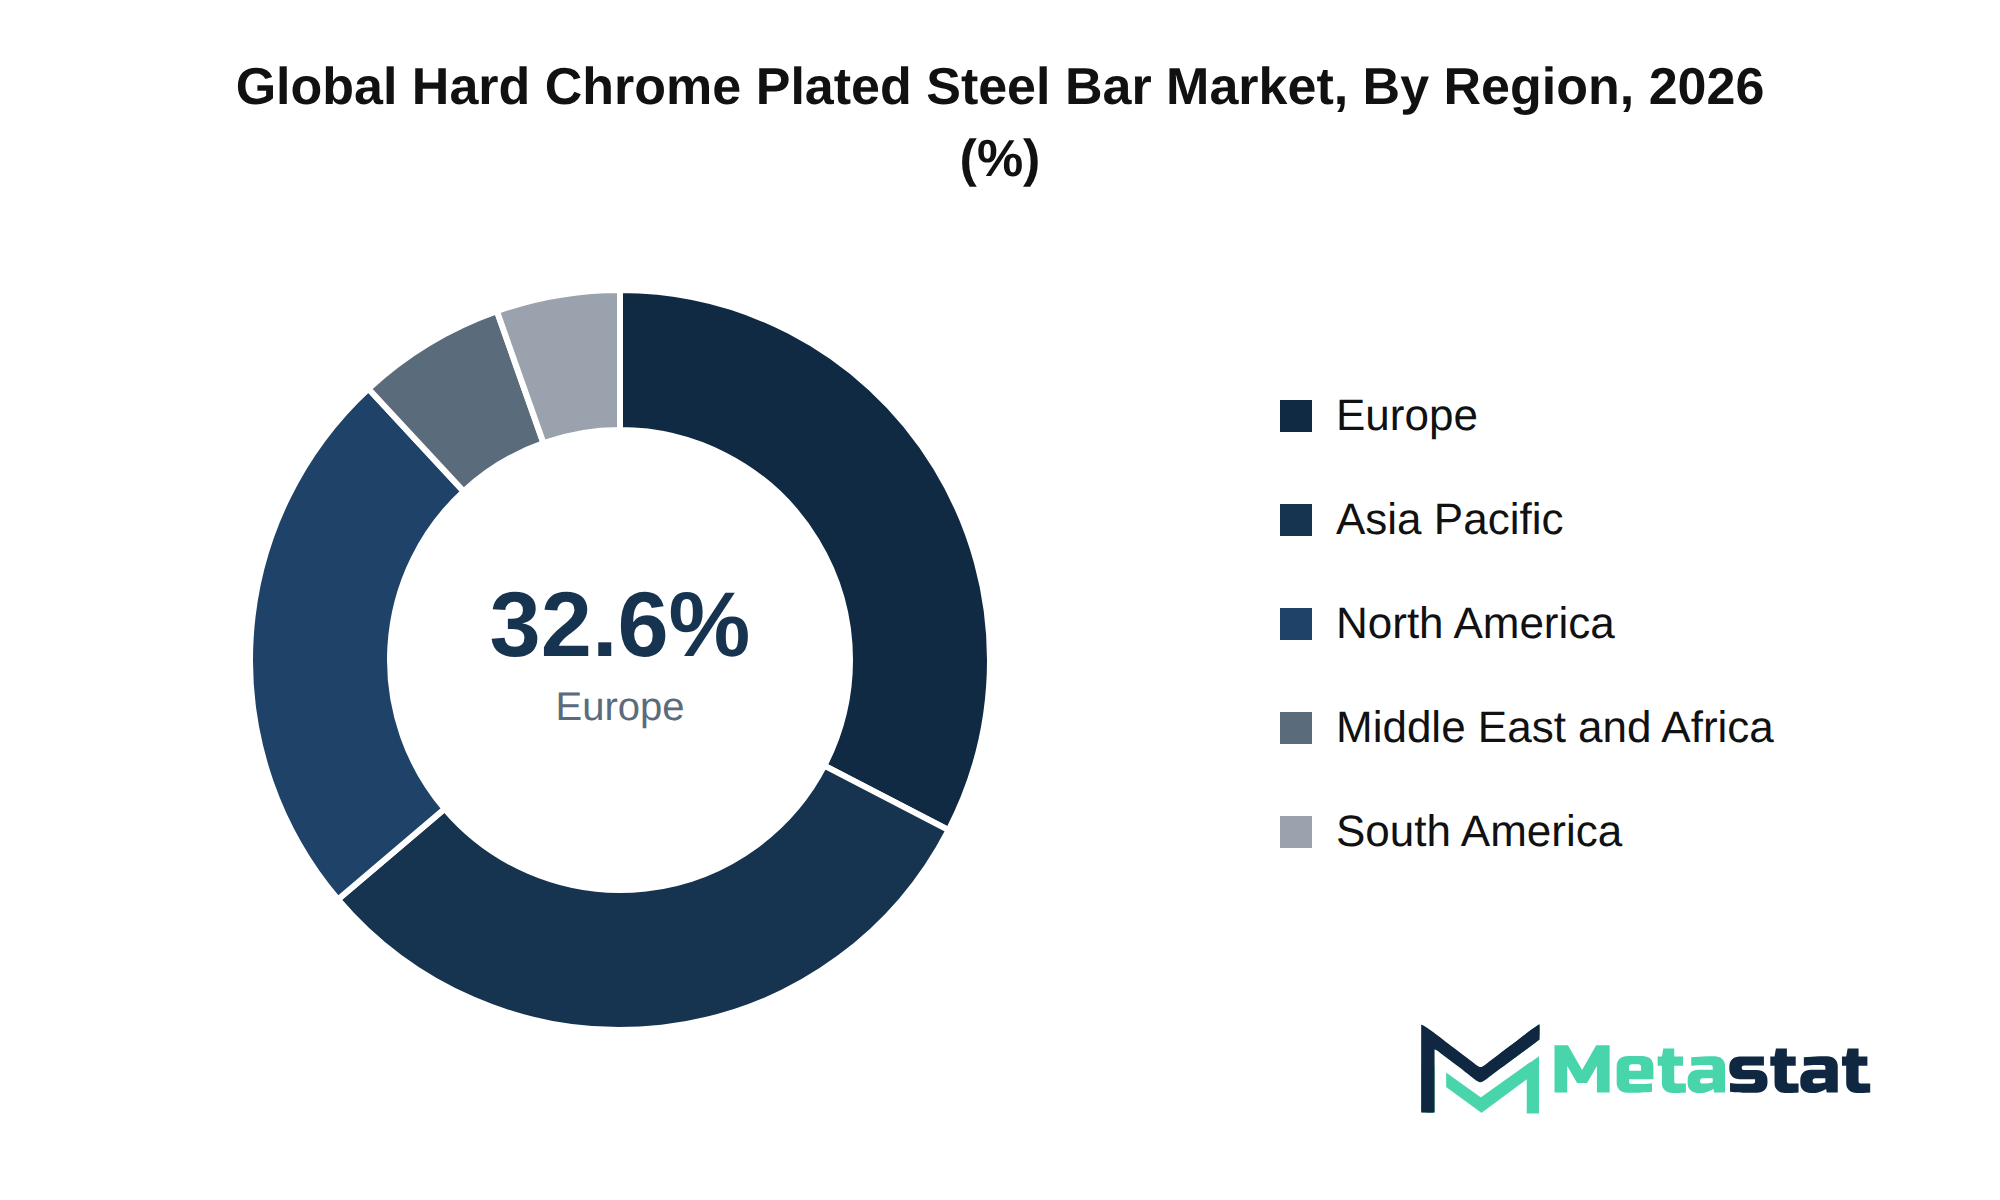
North America Hard Chrome Plated Steel Bar market is set to expand at a CAGR of 5.3% within the forecast period, reaching a market size (TAM) of USD 260.7 million by the end of 2033. The United States, Canada, and Mexico represent key contributors to this growth, driven by ongoing infrastructure modernization and increasing demand from various sectors. The market's share of the global landscape is projected at 24.3% in 2025, signifying a robust commitment to the use of hard chrome plated steel bars in industrial applications.
Focusing on localized manufacturing densities and nearshoring initiatives strengthens the supply chain in the region. Domestic market participants are adapting to shifts in procurement dynamics and regional B2B buying behaviors, enhancing their competitive position. Incremental growth vectors, driven by high-value replacement cycles, reflect a mature market dynamic that warrants strategic investment and attention.
Infrastructure readiness and energy grid resiliency play critical roles in determining market performance. While geopolitical fragmentation influences trade routes, North America remains positioned to leverage its resource availability for sustained growth in the hard chrome plated steel bar market. The presence of various local compliance mandates and regulatory frameworks necessitates a tailored approach to market engagement for stakeholders.
Europe represents a significant portion of the Hard Chrome Plated Steel Bar market, with a share of 32.6% in 2025. The region's industrial infrastructure and robust manufacturing capabilities drive strong demand across various applications. Key countries including Germany, France, the UK, Italy, and Spain demonstrate substantial market participation, supported by a well-established supply chain.
The focus on hydraulic cylinder piston rods and pneumatic cylinder rods reflects a growing need for reliable components in the automotive and machinery sectors. The presence of major manufacturers enhances competitive dynamics, facilitating increased investment in advanced production technologies. Adoption rates in Europe benefit from ongoing modernization initiatives, emphasizing efficiency and sustainability.
Germany leads because a primary market, characterized by high production volumes and a focus on precision engineering. Local compliance mandates influence procurement strategies, ensuring that products meet stringent quality standards. Regional players strategically position themselves to capitalize on incremental growth vectors, particularly in emerging markets within Eastern Europe.
Localized manufacturing densities encourage cross-border trade corridors, facilitating the movement of goods within the region. Geopolitical factors further shape market dynamics, prompting companies to enhance their regional presence. The Hard Chrome Plated Steel Bar market in Europe is poised for steady growth, driven by continuous demand across key applications and the need for high-quality materials.
The Asia-Pacific region represents a significant portion of the Hard Chrome Plated Steel Bar market, accounting for 31.2% of the global share in 2025. This market positioning results from robust demand across various sectors, particularly in China, Japan, India, and South Korea.
Infrastructure modernization within these countries drives market growth. Investments in hydraulic systems and manufacturing processes enhance the utilization of hard chrome plated steel bars, particularly in hydraulic cylinder piston rods and pneumatic cylinder rods applications.
Emerging market front-runners in this region focus on localized manufacturing. This approach strengthens supply chain regionalization and supports nearshoring initiatives, enabling more efficient production and distribution.
Market dynamics in Asia-Pacific reflect mature sectors alongside incremental growth vectors. High-value replacement cycles in established industries contribute to sustained demand, particularly in sectors including automotive and machinery.
The competitive landscape features various domestic market participants. Companies in the region leverage local procurement dynamics, aligning their offerings with specific cultural nuances and regional B2B buying behaviors.
While regional resource availability supports production capabilities, energy grid resiliency and local infrastructure readiness remain critical. Strategic entry barriers, including foreign direct investment (FDI) flows, facilitate geographic expansion opportunities for new market entrants.
Demand stems primarily from Brazil and Argentina, where industrial activities, particularly in manufacturing and hydraulics, drive consumption. The market reflects a growing need for hydraulic cylinder piston rods, with investments in local manufacturing facilities enhancing production capacities. This trend is expected to strengthen long-term demand for hard chrome plated steel bars in these sectors.
Infrastructure modernization efforts in Brazil and Argentina increase the demand for high-quality materials, including hard chrome plated steel bars. Local manufacturers seek to meet both domestic and regional requirements, allowing for improved supply chain efficiencies. Cultural nuances and regional B2B buying behaviors influence procurement strategies, emphasizing quality and reliability in industrial applications, which are critical for maintaining competitive advantages.
Increasing foreign direct investment (FDI) in the region supports growth opportunities for the hard chrome plated steel bar market. Emerging local players positioning themselves favorably against established vendors enhance competitive dynamics. The market's growth trajectory will hinge upon maintaining compliance with regional regulations and adapting to shifting trade policies, which are essential for navigating the evolving landscape of the industry.
The Middle East and Africa region represents a growing segment of the Hard Chrome Plated Steel Bar market, with a market share of 6.5% in 2025. Key markets within this region include Saudi Arabia, UAE, and South Africa, where industrial growth and infrastructure developments drive demand. Modernization efforts in various sectors, including construction and manufacturing, enhance the adoption of hard chrome plated steel bars.
Localized manufacturing initiatives and foreign direct investment contribute to the strengthening of supply chains within the region. This trend aligns with rising demand for high-performance materials that support the production of hydraulic and pneumatic components. The market attracts the attention of domestic players, who aim to leverage regional resources and energy availability, thus enhancing growth potential.
Cross-border trade corridors facilitate the movement of goods, while geopolitical dynamics influence operational strategies for suppliers. Local procurement trends reflect cultural nuances in purchasing behavior, impacting how vendors approach the market. Overall, the Hard Chrome Plated Steel Bar market in the Middle East and Africa shows promising avenues for expansion due to the region's continued investment in essential infrastructure and manufacturing capabilities.
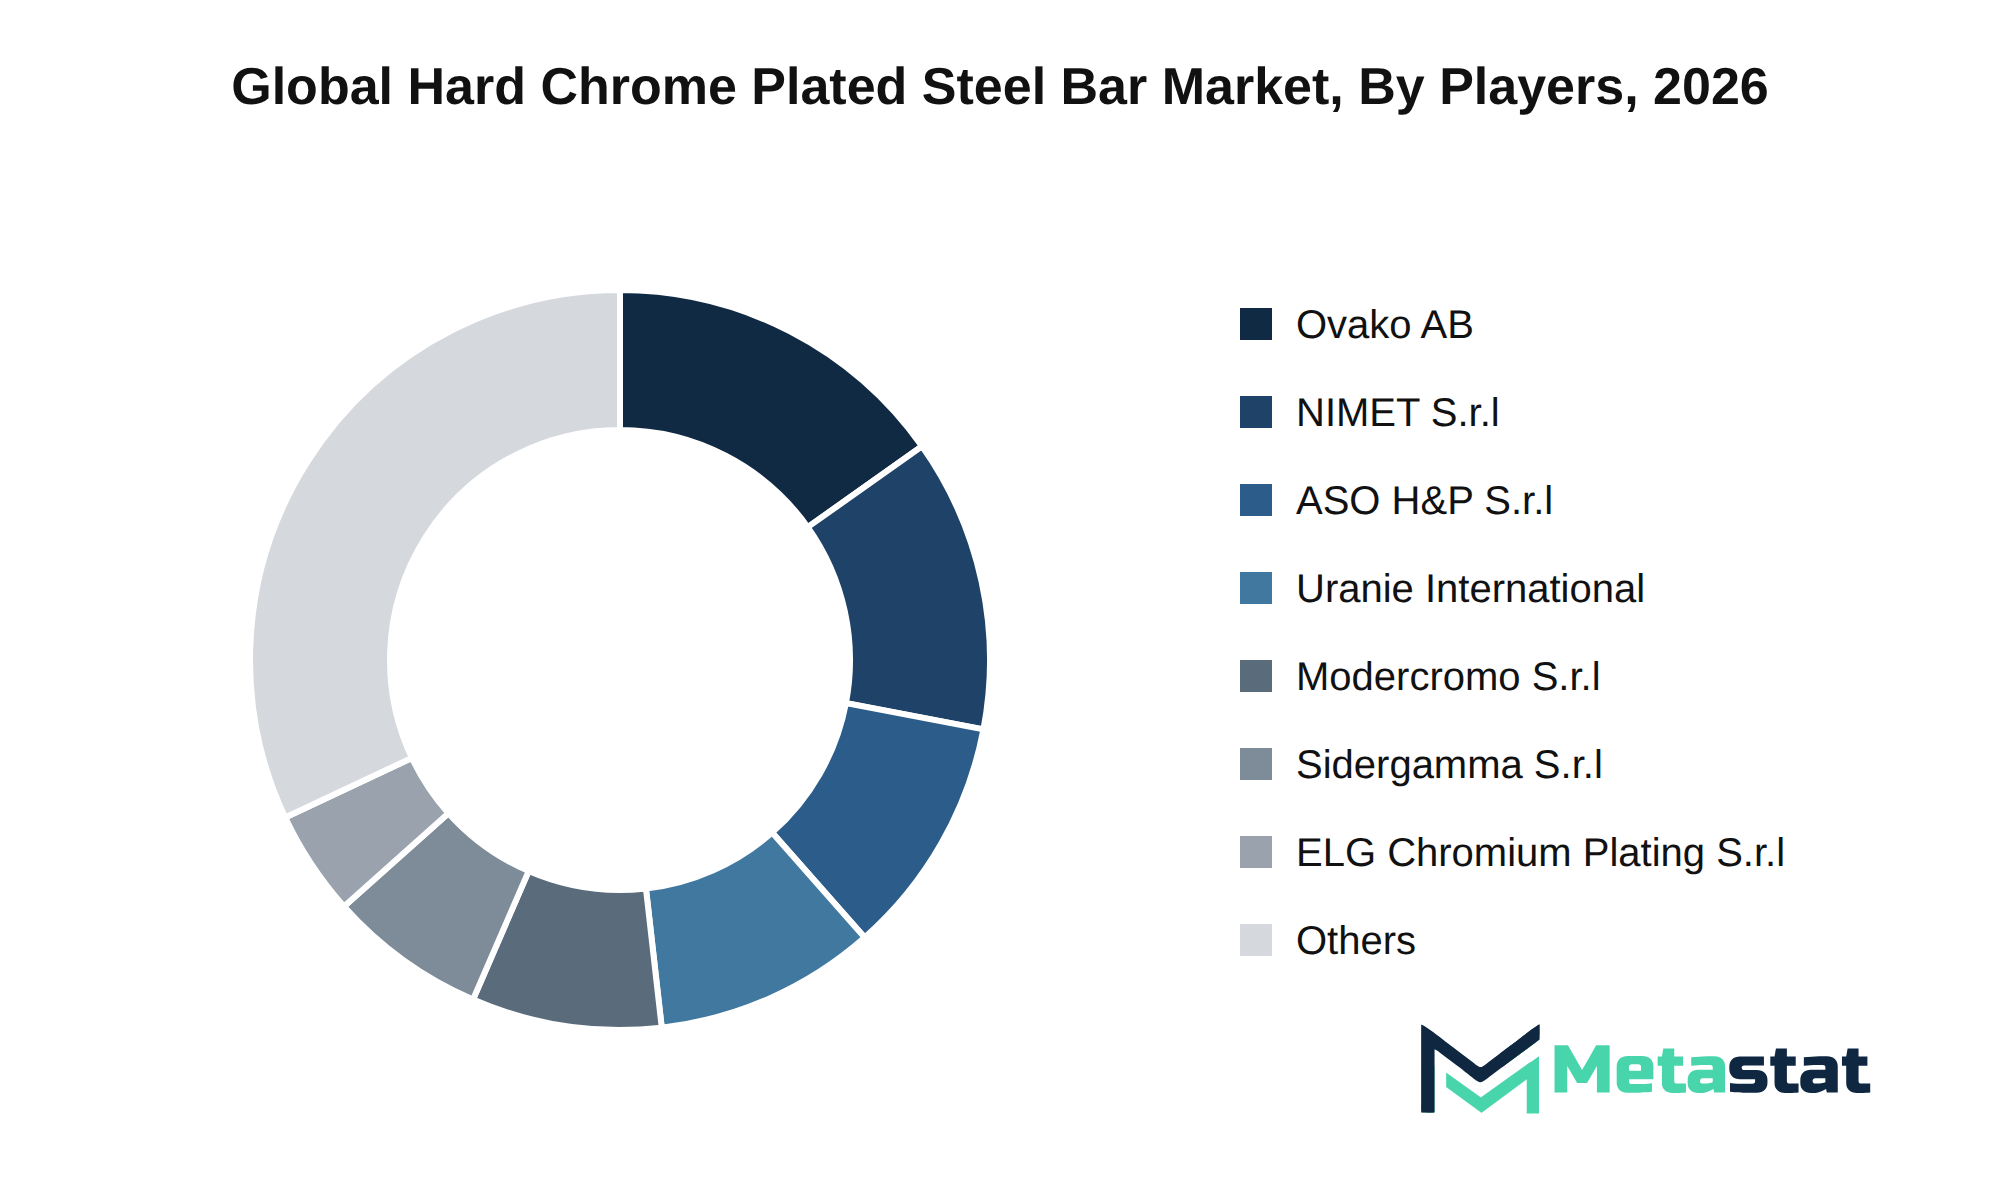
Competitive dynamics in the Hard Chrome Plated Steel Bar market feature significant interaction among key players. Companies pursue mergers and acquisitions to enhance market share and integrate complementary technologies. Strategic alliances and joint ventures among firms like Ovako AB, NIMET S.r.l., and ASO H&P S.r.l. facilitate resource sharing and innovation, strengthening competitive positioning.
Product differentiation remains a crucial strategy within the market, with companies investing in proprietary technologies and R&D pipelines. The focus on high-performance applications, including hydraulic and pneumatic cylinder rods, drives demand for innovative solutions among suppliers like ELG Chromium Plating S.r.l. and Uranie International. Barriers to entry include established brand equity and intellectual property portfolios, creating challenges for new entrants and startups attempting to disrupt the market.
Future competitive outlooks indicate a shift towards value chain integration, with firms emphasizing procurement leverage and customer retention strategies. Understanding switching costs allows established players to maintain market dominance while offering tailored solutions to meet evolving customer needs. The strategic growth vectors adopted by industry leaders like Sidergamma S.r.l. and Modercromo S.r.l. highlight the importance of maintaining technological defensibility in an increasingly competitive environment.
Market size is forecast to rise from USD 744.4 million in 2025 to over USD 1,125.6 million by 2033. The base case reflects a steady annual growth at a 5.3% CAGR during the forecast period. In the bullish scenario, increased demand driven by advancements in next-generation technologies and infrastructure commitments could lead to accelerated growth, attracting further investments and boosting production capacity. Alternatively, in a bearish scenario, supply chain disruptions and regulatory challenges hinder growth, leading to potential stagnation in the Hard Chrome Plated Steel Bar market.
Several macroeconomic factors influence the trajectory of the market. Structural shifts in consumption patterns, particularly in industries including construction and automotive, play a significant role. The ongoing maturation of core industries contributes to the steady demand for hard chrome plated steel bars, while evolving trade corridors and geopolitical realignments impact supply chain dynamics. Regulatory timelines and compliance milestones within the industry necessitate strategic adjustments from players, driving a proactive approach to R&D and commercialization timelines.
Executive-level strategic imperatives focus on capital allocation directives, with firms exploring emerging white-space opportunities to address unmet enterprise needs. Investment in infrastructure and capital expenditure vectors further supports market expansion, enabling firms to enhance their competitive positioning. While demand evolves, the Hard Chrome Plated Steel Bar market is expected to continue adapting, driving innovation and responsiveness to emerging trends.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Hard Chrome Plated Steel Bar market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 5.3% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Product Configuration, Bar Diameter, Base Steel Grade, Application, and Region |
By Region | North America (By Product Configuration, Bar Diameter, Base Steel Grade, Application, and Country)
|
Europe (By Product Configuration, Bar Diameter, Base Steel Grade, Application, and Country)
| |
Asia Pacific (By Product Configuration, Bar Diameter, Base Steel Grade, Application, and Country)
| |
South America (By Product Configuration, Bar Diameter, Base Steel Grade, Application, and Country)
| |
Middle East and Africa (By Product Configuration, Bar Diameter, Base Steel Grade, Application, and Country)
|
Find answers to common questions about this report
The Hard Chrome Plated Steel Bar market size was valued at USD 744.4 million in 2025, according to the Metastat Insights study.
The Hard Chrome Plated Steel Bar market is projected to grow at a CAGR of 5.3% during the forecast period from 2026 to 2033.
The North America Hard Chrome Plated Steel Bar market size is estimated to reach USD 260.7 million by 2033.
The segment of Standard Hard Chrome Plated Bars leads the Hard Chrome Plated Steel Bar market, with a projected value of USD 721.7 million by 2033. This segment demonstrates a compound annual growth rate of 4.5% from 2026 to 2033.
Investment in infrastructure development and increased public and private spending drive demand for hard chrome plated steel bars. Technological advancements in manufacturing processes enhance operational efficiency, while the focus on sustainability and compliance with environmental regulations shapes market dynamics. These factors collectively support the growth of the Hard Chrome Plated Steel Bar market.
Europe holds the dominant share of the Hard Chrome Plated Steel Bar market, accounting for 32.6% in 2025. This positions Europe ahead of other regions, including North America and Asia Pacific.
Investment in infrastructure development and technological advancements significantly favor product adoption in the Hard Chrome Plated Steel Bar market. Increased public and private spending on construction and manufacturing enhances demand for high-quality materials, while automation and digital transformation improve operational efficiency and responsiveness to market trends.
The Hard Chrome Plated Steel Bar market is estimated to reach a valuation of USD 1,125.6 million by 2033.
Key players in the Hard Chrome Plated Steel Bar market include Ovako AB, NIMET S.r.l., ASO H&P S.r.l., Uranie International, Modercromo S.r.l., and ELG Chromium Plating S.r.l.
Emerging applications for Hard Chrome Plated Steel Bars include hydraulic cylinder components and precision parts in automotive and aerospace industries. The demand for wear-resistant and corrosion-resistant materials in these sectors drives market expansion.
Choose Your License
Global Hard Chrome Plated Steel Bar Market
The analysts below cover Chemicals and Materials research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
INDUSTRY CONSULTANT - CHEMICALS & ADVANCED MATERIALS
Chemicals and Materials · Machinery & Equipment · Packaging
Amit Gadhekar Consultant for Chemicals and Materials at MetaStat Insight, directing sector-specific intelligence, research, and strategic consulting across global chemical and processing markets.
Evaluating calorific value requirements and air permit compliance across municipal waste facilities requires localized data. Metastat Insight structured their analysis around operational throughput capacity and feedstock composition variations in Latin America and Eastern Europe. Their competitive mapping of sorting equipment vendors helped clarify technology differences between optical separators and heavy media systems. The study provided an objective baseline during our capital expenditure reviews.
Decarbonizing industrial thermal processes hinges on refrigerant regulations and compressor efficiency limits. Metastat Insights delivered a thorough market analysis that evaluated natural refrigerants like CO2 and hydrocarbons against synthetic low-GWP alternatives. The breakdown of utility incentives and grid capacity constraints across key European manufacturing hubs offered valuable perspective. The follow-up conversation with their sector analysts addressed our specific questions on mechanical vapor recompression systems efficiently.
Assessing 200mm wafer transition schedules and substrate supply bottlenecks requires precise technical intelligence. MetaStat Insight supplied an actionable breakdown comparing planar and trench MOSFET architectures across automotive and industrial drive markets. The regional capacity estimates for Asia-Pacific foundries helped clarify lead-time uncertainties during our strategic planning session. When we needed additional clarification on high-purity raw material sourcing, their analyst team responded with helpful context within twenty-four hours.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950