
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Stainless Steel Market Size, Share, By Type (Austenitic Stainless Steel (200 & 300 Series), Ferritic Stainless Steel, Martensitic Stainless Steel, Duplex Stainless Steel, Precipitation-Hardening Stainless Steel), By Product Form (Flat Products (Coils, Sheets, Plates, Strips) and Long Products (Bars, Wire Rods, Wires, Rebars, Sections) and Tubular Products (Seamless and Welded Pipes & Tubes) and Semi-Finished Products (Slabs, Billets, Blooms, Ingots)), By Process (Hot Rolled and Cold Rolled and Cold Drawn), By End-Use Industry (Automotive & Transportation and Building & Construction and Consumer Goods & Home Appliances and Industrial Machinery & Equipment and Oil & Gas and Chemical & Petrochemical and Power Generation & Renewable Energy and Food & Beverage Processing and Medical & Healthcare and Others (Aerospace & Defense and Water & Wastewater)), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5294
September 17, 2026
Updated
278 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $137 Billion in 2025, projected to reach $251.8 Billion by 2033 at a 7.9% CAGR.
Dominant Segment: The Austenitic Stainless Steel (200 & 300 Series) segment leads the market, driven by its high corrosion resistance and flexibility in applications, particularly in automotive and construction.
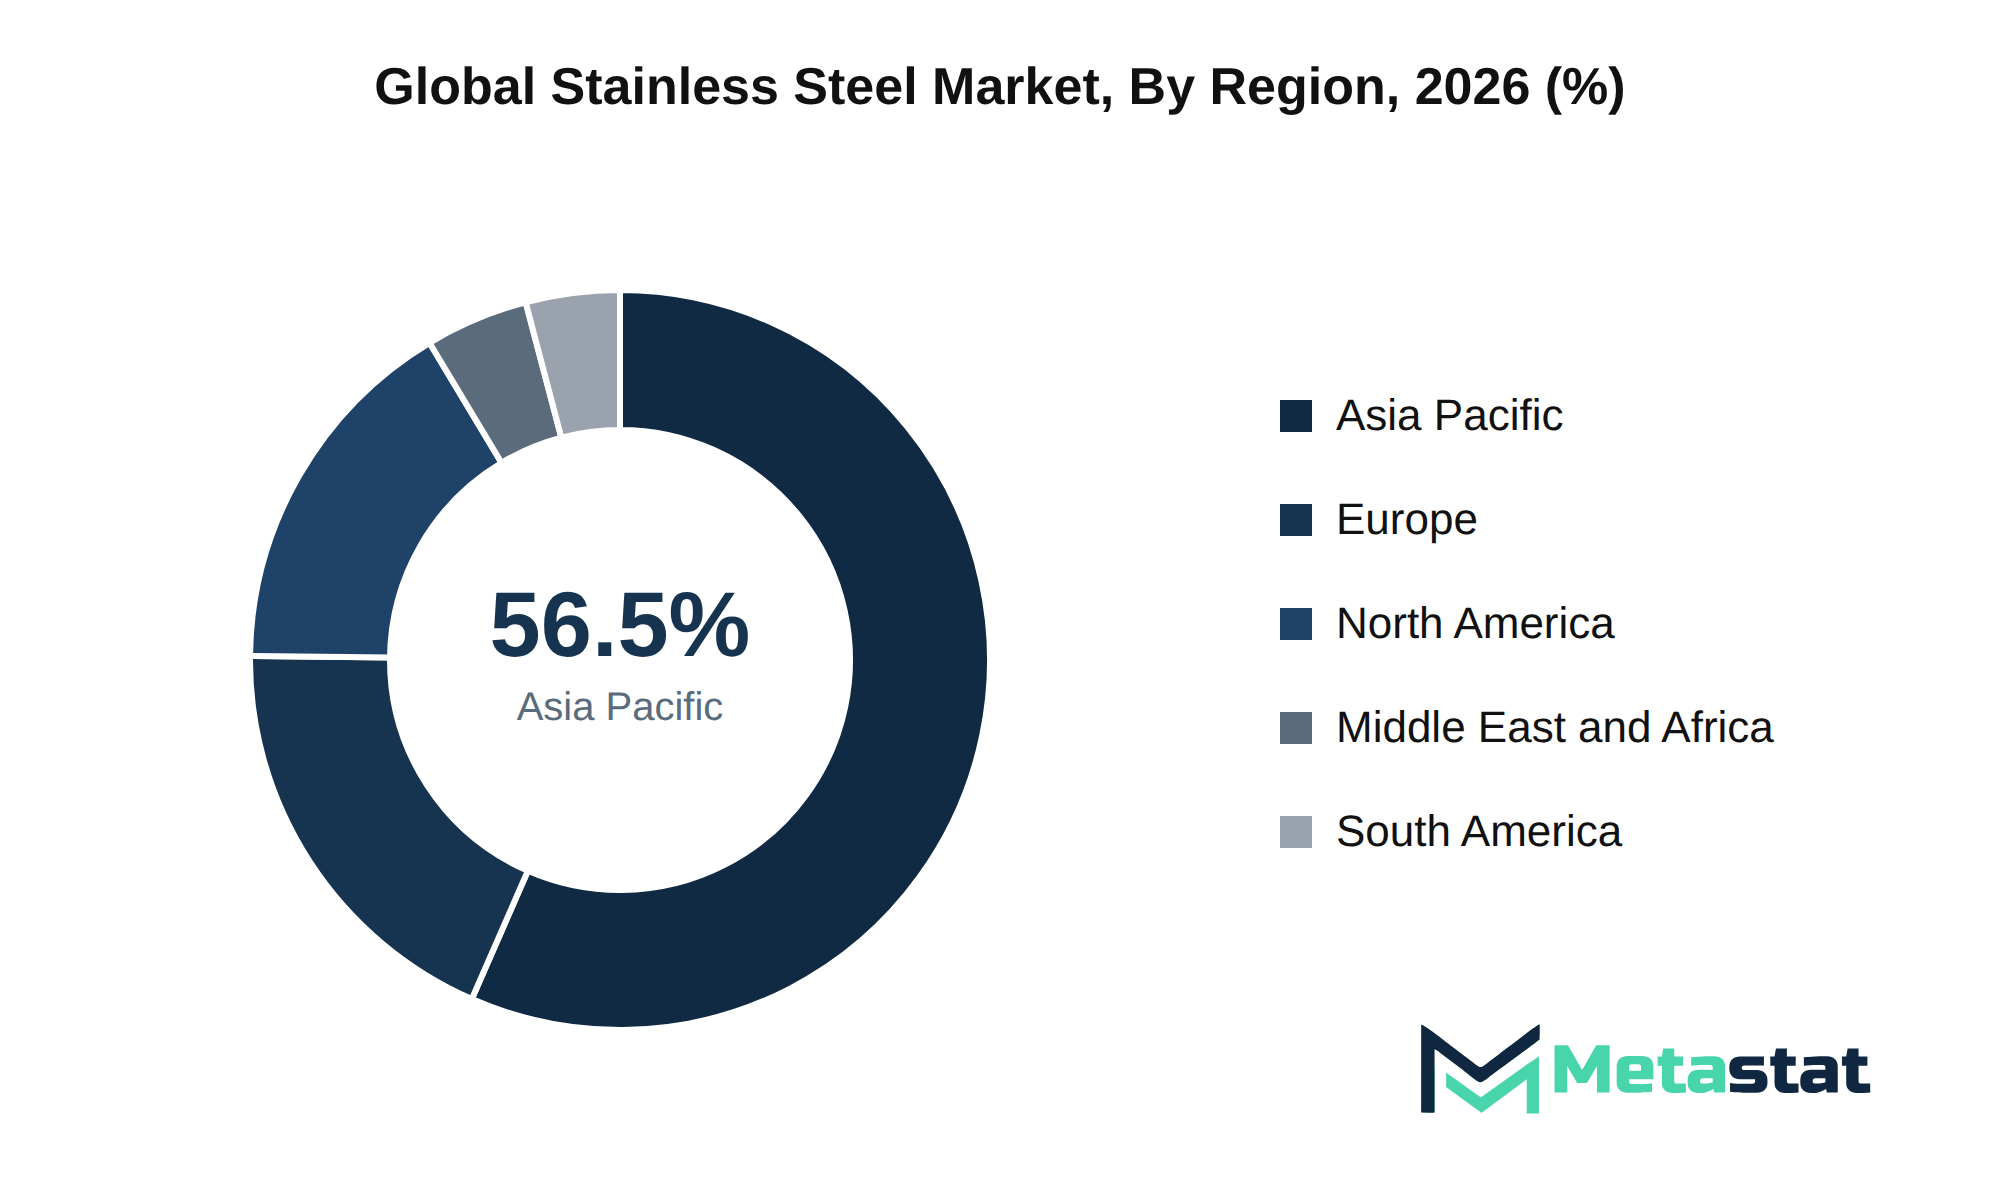
Geographic Lead: The Asia Pacific region, particularly China and India, shows the fastest growth due to robust demand for stainless steel in infrastructure and industrial applications.
What's Inside: This report provides comprehensive competitive coverage, detailed analyses of market dynamics, and forecasts for the period 2026-2033, focusing on key trends and growth drivers.
Emerging Demands: Technological advancements and increased investments in infrastructure modernization across Asia Pacific, North America, and Europe are driving significant opportunities in the stainless steel market.
Macroeconomic Headwinds: Rising inflation and geopolitical tensions are creating challenges for the stainless steel market, impacting production costs and supply chain stability.
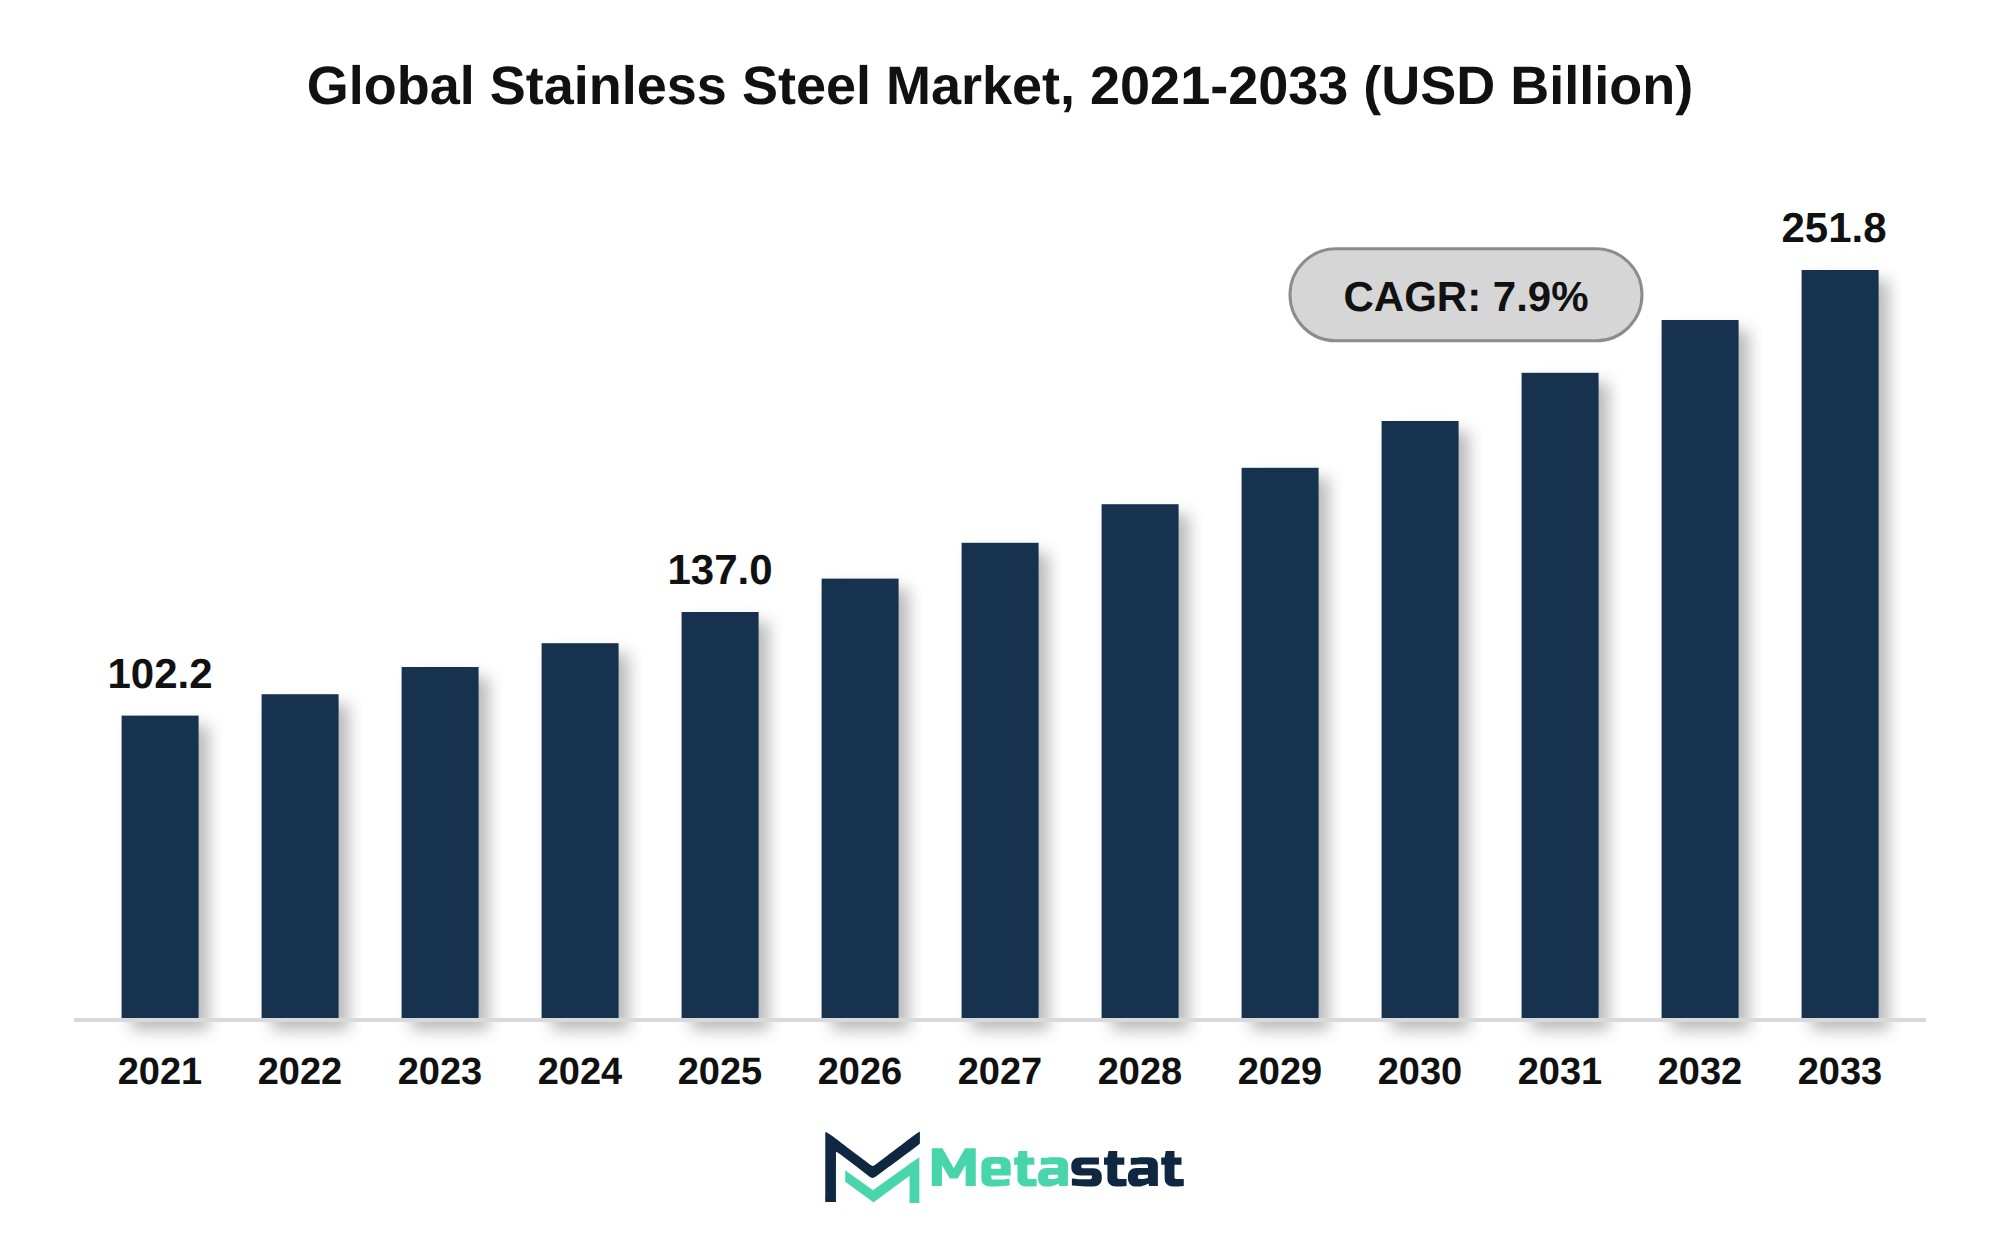
The global Stainless Steel market was valued at USD 137 billion in 2025 and is projected to reach USD 251.8 billion by 2033, growing at a CAGR of 7.9% over the forecast period.
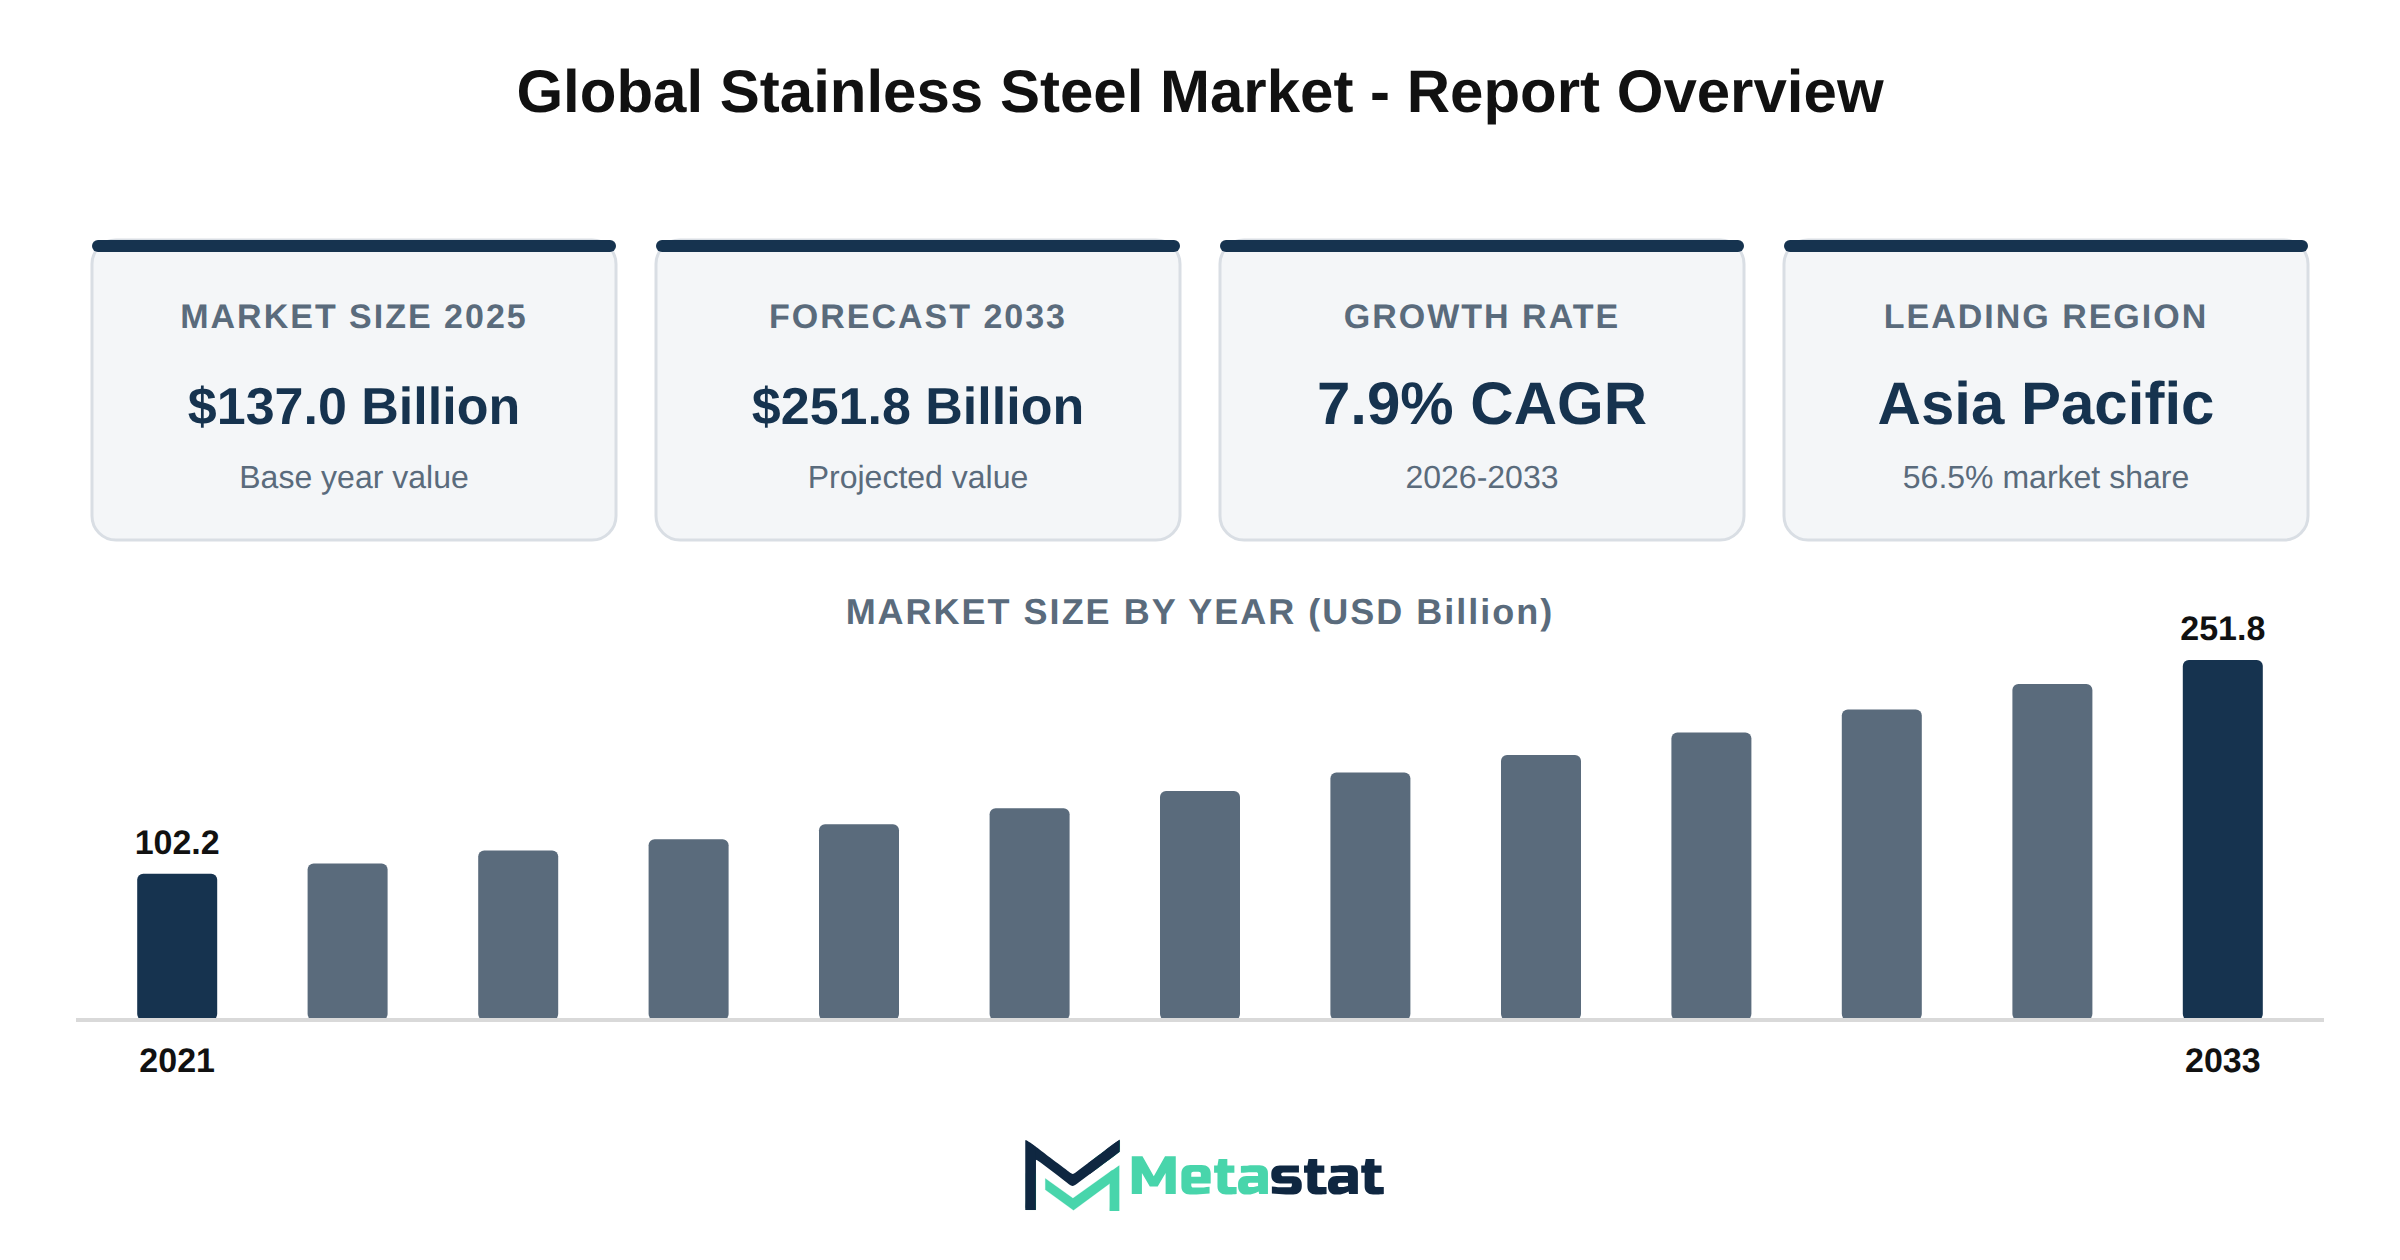
The global Stainless Steel market reached a value of USD 137 billion in 2025, with a projected growth to USD 251.8 billion by 2033, reflecting a compound annual growth rate (CAGR) of 7.9%. Increasing demand for stainless steel across various sectors, including automotive, construction, energy, and consumer applications drives this market expansion. The automotive and construction industries exhibit significant demand due to the material's lightweight properties and corrosion resistance, enhancing vehicle efficiency and building durability.
Rising adoption of austenitic and duplex stainless steel grades contributes to the market's growth trajectory. These grades offer superior strength and resistance to corrosion, making them ideal for challenging environments in sectors like oil and gas, chemical processing, and renewable energy. Expansion of stainless steel capacity in the Asia Pacific region reflects robust demand, with countries including China and India leading in production and consumption.
Raw material availability remains a crucial factor influencing the global stainless steel supply chain. Fluctuations in nickel and chromium prices directly impact production costs, compelling manufacturers to optimize their sourcing strategies. Integration of low carbon stainless steel production and green steel initiatives aligns with global sustainability efforts, appealing to environmentally conscious consumers and industries.
Numerous opportunities exist in North America and Europe, driven by growing investments in infrastructure and renewable energy projects. Increasing utilization of stainless steel in power generation and renewable energy applications reinforces its importance in modern energy infrastructure. Demand for stainless steel in oil, gas, and petrochemical applications continues to rise, propelled by ongoing industrial activities and the need for durable materials.
Innovation in high-strength and corrosion-resistant stainless steel grades enhances product offerings, meeting the evolving needs of various industries. Production trends indicate a strong focus on hot rolled and cold rolled stainless steel, with manufacturers adjusting their processes to increase efficiency and product quality. Emphasis on stainless steel recycling, circularity, and scrap utilization reflects a growing commitment to sustainability within the market.
Demand for stainless steel across various sectors, including automotive, construction, energy, and consumer applications, reflects a strong growth trajectory. The automotive industry drives substantial demand, focusing on lightweight materials that enhance fuel efficiency while providing excellent corrosion resistance. In the construction sector, the increasing use of stainless steel in structural components and architectural finishes supports market expansion. Renewable energy projects, particularly in solar and wind, further contribute to rising consumption, necessitating durable materials that withstand harsh environmental conditions.
The adoption of austenitic and duplex stainless steel grades influences market dynamics. These grades offer superior mechanical properties and corrosion resistance, making them ideal for various applications. Industries prioritize these materials for their performance advantages, influencing overall consumption trends and encouraging producers to innovate in these segments.
The global stainless steel supply chain experiences fluctuations due to raw material availability trends. Nickel and chromium, key components in stainless steel production, face price volatility, impacting production costs. While scrap prices fluctuate, manufacturers adapt their sourcing strategies to maintain competitive pricing while ensuring product quality.
Initiatives promoting low carbon stainless steel production align with growing environmental consciousness. Producers focus on reducing the carbon footprint of manufacturing processes, responding to increasing regulatory pressures and market demands for sustainable practices. Green steel initiatives reflect a commitment to environmentally friendly production, enhancing the appeal of stainless steel in various applications.
Capacity expansion within the Asia Pacific region significantly influences market dynamics. Investments in new production facilities and technology upgrades support increased output, meeting rising demand from both domestic and international markets. This expansion strengthens the region's position because a global leader in stainless steel production.
Opportunities in the North American and European markets arise from infrastructure development and modernization efforts. These regions witness increased investments in stainless steel applications, particularly in construction and energy sectors. The focus on updating aging infrastructure creates demand for high-quality materials that ensure durability and longevity.
The growing use of stainless steel in renewable energy and power infrastructure highlights its importance in the transition toward sustainable energy sources. The industry seeks materials that provide longevity and reliability in various applications, reinforcing the need for high-performance stainless steel grades.
Oil, gas, and petrochemical applications continue to drive stainless steel demand. The industry's push for efficient, corrosion-resistant materials enhances the appeal of stainless steel, particularly in harsh environments where durability is critical. Producers respond by developing grades tailored to these demanding applications.
Automotive lightweighting and corrosion resistance significantly influence stainless steel consumption. Manufacturers prioritize materials that reduce vehicle weight without compromising safety or performance, driving innovation in high-strength alloys. Such developments enhance the market's competitive edge, catering to evolving industry requirements.
Innovation in high-strength and corrosion-resistant stainless steel grades remains a focal point for producers. Continuous advancements in material properties address specific industry needs, enhancing competitiveness and driving adoption across various sectors.
Trends in hot rolled and cold rolled stainless steel production highlight the industry's adaptability to changing market conditions. Producers invest in technology to optimize processes, ensuring efficient production while maintaining high-quality standards.
Stainless steel recycling and circularity initiatives gain traction, emphasizing the importance of scrap utilization. The industry's focus on sustainability encourages the development of closed-loop systems, enhancing resource efficiency while minimizing environmental impact.
Trade policies, tariffs, and carbon regulations significantly influence stainless steel markets. Producers navigate these evolving frameworks to maintain competitiveness and ensure compliance, impacting pricing strategies and market access.
Competitive strategies among global stainless steel producers reflect a dynamic market environment. Companies invest in capacity expansions, technological advancements, and strategic partnerships to enhance their market position and meet growing demand.
Investment in new stainless steel production facilities aligns with market growth projections. Producers recognize the importance of expanding capacity to meet increasing demand while addressing supply chain challenges.
Emerging opportunities in medical, food processing, and water infrastructure sectors present new avenues for stainless steel applications. The industry's versatility positions it well to meet the diverse needs of these growing markets.
Future growth prospects for the global stainless steel market indicate a strong upward trajectory, driven by innovation, sustainability efforts, and evolving industry demands.
Infrastructure development serves because a significant growth driver for the stainless steel market. Major investments in public infrastructure, including roads, bridges, and buildings, create a robust demand for stainless steel products, particularly in the construction sector. The ongoing urbanization trend, reflected in increasing population densities in metropolitan areas, drives this demand further, because cities require modernized infrastructure to accommodate their growing populations.
In addition to traditional infrastructure projects, renewable energy initiatives, including solar and wind energy installations, incorporate stainless steel components for their durability and resistance to corrosion. These factors contribute to a projected compound annual growth rate (CAGR) of 7.9% for the market through 2033. The alignment of public and private investments towards sustainable infrastructure enhances the competitive landscape, allowing suppliers to capitalize on emerging opportunities within the stainless steel market.
The shift towards smart city developments necessitates advanced construction materials, with stainless steel being favored for its longevity and performance. While cities increasingly adopt smart technologies to improve service delivery and resource management, stainless steel's role within these infrastructures emphasizes its importance, driving further market growth.
Urbanization contributes significantly to the growth of the stainless steel market. Rapid migration towards urban centers creates a heightened demand for infrastructure, housing, and public facilities. This trend necessitates increased production of stainless steel products, which are essential for constructing durable and aesthetically appealing buildings, transportation systems, and other urban structures.
Investment in urban infrastructure is supported by both public and private sectors, leading to enhanced capital flow into the stainless steel industry. Urbanization drives the need for modern amenities and services, prompting governments and corporations to allocate substantial funds for development projects. These investments directly influence production levels and boost market revenue.
The stainless steel market benefits from the growing focus on sustainable urban development. While cities evolve, environmentally friendly practices become a priority, resulting in a higher preference for stainless steel. This material’s durability and recyclability align with sustainability goals, making it an attractive choice for modern construction projects.
Urbanization acts because a catalyst for the stainless steel market, stimulating demand through increased investment in infrastructure and a shift towards sustainable practices. The ongoing trend of urban migration and development continues to create opportunities for growth within the market.
Macroeconomic headwinds significantly impact the stainless steel market, primarily through rising inflation and fluctuating economic stability. Inflationary pressures lead to increased raw material costs, affecting profitability for manufacturers. Higher production costs often result in increased prices for end-users, which reduce demand across various sectors. Constrained spending by industries, particularly in construction and automotive, contributes to slower growth rates.
Geopolitical instability introduces uncertainty in trade relationships and supply chains, leading to disruptions in material availability and increased logistics costs. Such instability results in companies hesitating to invest in new projects or expand operations, creating a ripple effect on market dynamics. The cumulative effect of these macroeconomic challenges creates barriers to growth and investment in the stainless steel market.
Capital stagnation occurs when companies face difficulties in securing funding for expansion, research, and development. This stagnation limits innovation and technological advancement within the market, preventing producers from optimizing processes or adopting new materials that could improve competitiveness. Limited access to capital hinders the drive for operational efficiency and modernization, which is critical in an increasingly competitive environment.
Market fragmentation complicates the stainless steel market. A variety of suppliers and varying product offerings create complexity in procurement processes, often leading to inefficiencies. The presence of many small players in the market dilutes brand recognition and customer loyalty, making it challenging for companies to establish a prominent market position. Such fragmentation slows the adoption of new technologies or standards, impacting overall market growth.
Geopolitical tensions significantly influence the stainless steel market by creating supply chain risks and disruptions. Events including trade deficits and tariff friction result in fluctuating prices and availability of raw materials, impacting manufacturers' operational costs and market pricing strategies. Affected industries include automotive, construction, and consumer goods, which rely heavily on stable supply chains for production processes.
Increased complexity in research and development efforts arises from these geopolitical challenges. Manufacturers invest in adapting technologies and processes to navigate trade barriers and sourcing complications, leading to higher compliance overheads and potential delays. The market responds with heightened demand for robust strategies to address evolving challenges while maintaining competitiveness.
Rising input costs compounded by geopolitical instability exert pressure on profit margins. Companies face heightened costs associated with logistics and procurement, necessitating strategic adjustments to maintain profitability. Price compression from competitive pressures complicates these dynamics, compelling firms to innovate and optimize operations to remain viable in the market.
Workforce skill gaps present another challenge, with companies struggling to retain talent capable of navigating the complexities of modern manufacturing environments affected by geopolitical factors. Investment in employee training and retention strategies becomes essential to build a skilled workforce equipped to respond to market demands. Addressing these gaps hinders operational efficiency and market responsiveness.
Overall, geopolitical tensions create multifaceted challenges for the stainless steel market, influencing every aspect from supply chain stability to workforce management. Addressing these risks requires comprehensive strategies to mitigate impacts and ensure continued growth in an increasingly volatile environment.
The Stainless Steel market experiences significant opportunities due to emerging regional demands and technological disruptions. Countries across Asia Pacific, North America, and Europe increasingly invest in infrastructure modernization that boosts the consumption of stainless steel. This investment focuses on upgrading transportation networks, urban infrastructure, and energy facilities, resulting in heightened demand for durable materials.
Geographical expansion of stainless steel applications in emerging economies contributes to market growth. Nations including India and Brazil pursue industrial development strategies that prioritize stainless steel due to its corrosion resistance and strength. This trend influences the construction and automotive sectors, affecting production levels and market penetration.
Technological advancements, particularly in manufacturing processes, enhance operational yield and product quality within the market. Innovations in cold rolling techniques and alloy compositions provide manufacturers with competitive advantages, supporting long-term growth. Digital transformation in procurement practices streamlines supply chain operations, facilitating efficient sourcing of raw materials.
Sustainability imperatives shape the stainless steel market, with increasing pressure from consumers and regulatory bodies to adopt eco-friendly practices. Green transformations in production techniques, including using recycled stainless steel, align with environmental goals and enhance brand reputation. Companies that pursue ESG-driven alignments position themselves favorably within the market.
Downstream market diversification represents a key opportunity, with stainless steel applications expanding into sectors including renewable energy, food processing, and medical devices. This diversification strengthens resilience against economic fluctuations and enhances market positioning. Strategic consolidation through mergers and acquisitions further enhances operational capabilities and market reach.
The combination of evolving buying behaviors and commercial model transitions accelerates demand within the stainless steel market. Increased reliance on digital procurement channels provides customers with improved access to products and pricing information, driving competition among suppliers. This shift enhances market dynamics, creating an active environment for growth and innovation.
The Global Stainless Steel market is segmented based on Type, Product Form, Process, and End-Use Industry.
Austenitic Stainless Steel (200 & 300 Series) segment is valued at USD 102.5 billion in 2026 and is projected to reach USD 171 billion by 2033, at a CAGR of 7.6% during the forecast period. Growing demand for high corrosion resistance and flexibility in applications drives the adoption of this segment across various industries. Major end-use sectors include automotive, construction, and consumer goods, which rely on austenitic grades for components requiring durability and aesthetic appeal.
Technological advancements in production processes and material science enhance the quality and efficiency of austenitic stainless steel. Innovations focusing on lightweight and high-strength materials cater to evolving market needs, particularly in automotive and machinery applications. This trend stimulates sustained demand and further segment expansion.
Regulatory compliance standards regarding sustainability and environmental impact influence the market landscape. Manufacturers align their production methods with these regulations to meet consumer expectations for environmentally friendly products. Consequently, investment in austenitic stainless steel technologies reflects a strategic opportunity for companies seeking to enhance their competitive positioning.
Pricing dynamics in the stainless steel market, influenced by raw material costs and global supply chain factors, play a significant role in shaping operational margins. Fluctuations in nickel prices, a primary alloying element, directly affect the cost structures associated with austenitic grades. To mitigate pricing volatility, stakeholders explore alternative sourcing strategies and enhance supply chain resilience.
Ferritic Stainless Steel segment is projected to reach USD 47.2 billion by 2033, with a CAGR of 8.1% during the forecast period. This segment benefits from increasing demand across various end-use industries, including automotive, construction, and consumer goods. The strong emphasis on cost-effective and corrosion-resistant materials drives growth in applications where durability is essential. Enhanced awareness of sustainability and environmental issues supports the adoption of ferritic stainless steel, which offers a lower nickel content compared to austenitic grades while maintaining desirable mechanical properties.
Technological advancements in manufacturing processes improve the quality and availability of ferritic stainless steel products. Ongoing investments in R&D support the evolution of this material, enabling its use in innovative applications including energy-efficient appliances and automotive components. Regulatory compliance concerning material sustainability increases its appeal, particularly in markets demanding eco-friendly solutions.
Overall, the expansion of the Ferritic Stainless Steel segment aligns with broader trends in the Stainless Steel market, where efficiency and performance influence procurement decisions. While the market continues to evolve, opportunities for growth expand across various sectors, presenting significant potential for manufacturers and suppliers.
Growing applications in various industries drive the demand for Martensitic Stainless Steel. Known for its high strength and corrosion resistance, this sub-segment finds extensive use in sectors including automotive, industrial machinery, and consumer goods. Continuous advancements in manufacturing technologies enhance product quality and performance characteristics, promoting wider adoption across different applications.
The Martensitic Stainless Steel segment is expected to reach USD 16.7 billion by 2033. The increasing focus on product evolution and next-generation upgrades contributes to strong growth within this segment. Industries seek materials that offer enhanced performance and durability, further reinforcing the segment’s position in the Stainless Steel market.
End-use dynamics reflect a shift toward high-performance materials, particularly in automotive and industrial applications. Regulatory compliance standards and certifications shape the segment, influencing production practices and material specifications. Evolving consumption patterns in consumer goods highlight the necessity for versatile and durable materials, further boosting demand for Martensitic Stainless Steel.
Pricing volatility and margin pressures constitute challenges for manufacturers in this segment. Global fluctuations in raw material costs impact pricing strategies, necessitating agile business models to maintain profitability. Strategic opportunity windows arise from the need for innovative solutions that align with market trends, driving capital investments aimed at enhancing production capabilities.
Significant growth in the Duplex Stainless Steel segment aligns with increasing demand from various end-use industries, including automotive, construction, and energy. This sub-segment is projected to grow at a CAGR of 11.9% during the forecast period. The unique properties of duplex stainless steel, which combine high strength and excellent resistance to corrosion, position it well against competing materials, enhancing its appeal across diverse applications.
Technological advancements drive product evolution, driven by manufacturers focusing on developing next-generation duplex stainless steel alloys that improve performance and reduce production costs. Adoption trends indicate a shift toward using duplex stainless steel in high-demand applications where durability and weight reduction are critical. This trend reflects the growing priority on materials that contribute to sustainability and efficiency in manufacturing processes.
Regulatory compliance standards play a crucial role in shaping demand dynamics within the market. Stringent environmental regulations incentivize industries to adopt materials with lower environmental impact, positioning duplex stainless steel because an attractive option. Cost structures for producers remain competitive, particularly because raw material sourcing stabilizes and supply chain resilience strengthens in response to market fluctuations.
Investment in capital projects aimed at expanding production capacity supports the anticipated growth in the duplex segment. With increasing competition among suppliers, strategic opportunity windows emerge for companies to innovate and differentiate their products. The growth trajectory of the duplex stainless steel segment highlights its importance in the Stainless Steel market and its potential for sustained expansion in the coming years.
Demand for Precipitation-Hardening Stainless Steel arises from its unique properties, including high strength and corrosion resistance. Various industries, particularly aerospace and defense, adopt this material due to its ability to withstand extreme conditions while maintaining structural integrity.
Technological maturation enables manufacturers to produce this type of stainless steel with enhanced performance characteristics. Development of next-generation upgrades focuses on improving mechanical properties and fatigue resistance, expanding its application across critical sectors.
End-use dynamics highlight the relevance of Precipitation-Hardening Stainless Steel in specialized applications, including oil and gas, chemical processing, and medical equipment. The segment's evolution aligns with trends toward lightweight and durable materials, particularly in transportation and healthcare, where reducing weight while ensuring safety remains imperative.
Regulatory compliance standards and certifications significantly impact production processes and material selection. Adherence to these standards ensures that products meet industry-specific requirements, enhancing market acceptance.
Pricing volatility and margin pressures present challenges for manufacturers in maintaining competitive pricing while ensuring product quality. Strategic opportunity windows arise for companies investing in R&D and innovative production techniques, allowing differentiation of their offerings in the market.
Supply chain resilience remains a critical factor, particularly concerning raw material sourcing. Challenges associated with logistics vulnerabilities restrict availability, influencing production timelines and costs.
Substitution risks persist with alternative materials; however, the unique advantages offered by Precipitation-Hardening Stainless Steel sustain its market position. Its superior characteristics enhance its appeal relative to conventional materials, driving demand in the stainless steel market.
Valued at USD 86.2 billion in 2026, the Flat Products (Coils, Sheets, Plates, Strips) segment is projected to reach USD 143.3 billion by 2033, reflecting a CAGR of 7.5% during the forecast period. Primary demand drivers for this segment include the increasing use of stainless steel in various end-use applications, including automotive and construction, where durability and corrosion resistance are critical. Significant expansion occurs due to technological advancements in manufacturing processes, enhancing efficiency and product quality.
Technological maturation significantly shapes the segment, with manufacturers adopting next-generation upgrades that improve production techniques and reduce waste. Product evolution continues to refine the properties of flat products, catering to evolving customer preferences for aesthetics and performance. Downstream application diversity supports robust demand, allowing manufacturers to address specific needs across industries.
End-use dynamics influence consumption patterns, with sectors including automotive and consumer goods showing marked growth. Regulatory compliance standards ensure that products meet safety and environmental criteria, impacting market players' strategies. Cost structures and pricing volatility present challenges, demanding continuous adaptation among manufacturers to maintain margins amid fluctuating raw material prices.
Supply chain resilience remains a focal point, with companies enhancing their sourcing strategies to mitigate risks associated with global disruptions. Substitution risks from alternative materials pose a challenge for flat products, emphasizing the need for continued innovation. Strategic opportunity windows arise from increasing demand in emerging markets, presenting avenues for growth within the Stainless Steel market that align with global industrial trends.
Growth in the Long Products (Bars, Wire Rods, Wires, Rebars, Sections) segment stems from increased demand across various industries, including construction and automotive. Infrastructure projects, particularly in emerging economies, drive the need for these products, supported by ongoing urbanization and population growth. Enhanced product specifications and the development of innovative manufacturing techniques have improved performance characteristics, appealing to end-users seeking durability and strength. The segment is projected to reach USD 45.7 billion by 2033, at a CAGR of 7.5% during the forecast period.
Shifts in consumption patterns show a growing preference for stainless steel in construction and infrastructure applications, prompted by its corrosion resistance and recyclability. Regulatory compliance standards mandate the use of durable materials, further increasing the segment's attractiveness. Price volatility in raw materials creates margin pressures, influencing production costs and pricing strategies within the market.
Strategic opportunities arise from advancements in technology that facilitate the production of high-quality long products. Investment in R&D enhances the competitive landscape, allowing manufacturers to respond to evolving market demands effectively. Supply chain resilience plays a critical role in maintaining production levels and ensuring timely delivery, essential for meeting the demands of major construction and infrastructure projects.
Overall, the Long Products segment stands to benefit from a robust market environment, characterized by strong growth drivers and a commitment to innovation. Investment in advanced manufacturing capabilities is expected to provide a significant edge in meeting future demand within the stainless steel market.
Increasing demand for Tubular Products (Welded Pipes & Tubes) within the Stainless Steel market aligns with the needs of various industries, particularly in oil and gas, construction, and manufacturing. This segment benefits from advancements in technology that enhance product performance while reducing production costs. Innovations in manufacturing processes have resulted in improved strength and durability of tubular products, driving adoption across sectors requiring high-quality materials for critical applications.
Regulatory compliance standards further influence the growth of the segment, driven by industries adhering to stringent safety and quality requirements. The increasing emphasis on environmental sustainability encourages manufacturers to invest in eco-friendly production methods, enhancing the appeal of stainless steel products. Consumption shifts towards durable and low-maintenance materials reinforce the demand for tubular products, promoting a favorable market outlook.
By 2033, the Tubular Products (Welded Pipes & Tubes) segment is expected to reach USD 41 billion. Competitive pressures within the market drive players to explore strategic opportunities, including partnerships and capacity expansions, to meet the rising demand effectively. Capital investment in innovative technologies and infrastructure will play a key role in shaping the future of this segment.
Semi-Finished Products (Slabs, Billets, Blooms, Ingots) segment experiences substantial growth driven by the increasing demand for raw materials in various applications, particularly in the construction and automotive sectors. This segment is projected to grow at a CAGR of 7.9% during the forecast period. Factors including advancements in manufacturing techniques and the rising focus on sustainable practices contribute to its expansion. The increasing focus on energy efficiency and product longevity in the market further enhances the demand for semi-finished products, because they serve critical inputs in numerous downstream applications.
Technological maturation within the sector facilitates the production of higher-quality semi-finished products, appealing to end-users requiring enhanced performance characteristics. Evolving consumption patterns among buyers emphasize the importance of sourcing materials that align with environmental compliance standards, driving further adoption. Fluctuations in raw material prices and margin pressures continue to challenge the market, necessitating strategic responses from players to maintain competitiveness. Ultimately, the strategic opportunity windows created by these dynamics position semi-finished products because essential components in the broader stainless steel market.
Valued at USD 71.2 billion in 2026, the Hot Rolled segment is projected to reach USD 118.1 billion by 2033, at a CAGR of 7.5% during the forecast period. This growth stems from increasing demand across various sectors, particularly in construction and automotive industries, where the material's strength and versatility provide significant advantages. Technological advancements in manufacturing processes enhance production efficiency, driving down costs while improving product quality.
Adoption of hot rolled stainless steel is gaining momentum due to its applications in critical infrastructure and heavy machinery, where durability is essential. End-use dynamics highlight a shift towards lightweight and high-strength materials, reinforcing the role of hot rolled products in achieving these objectives. Regulatory compliance standards focusing on sustainability motivate the transition towards stainless steel in construction applications, where environmental considerations are increasingly important.
Pricing volatility in raw materials influences the cost structures of hot rolled products, prompting manufacturers to explore alternative sourcing strategies. Strategic investment in modern production facilities ensures supply chain resilience, enabling producers to respond swiftly to market changes. Consumption shifts towards innovative designs and sustainable practices encourage continuous product evolution, benefiting the overall dynamics of the market.
Technological obsolescence poses risks, necessitating ongoing upgrades in production methods to maintain competitive advantages. These strategic opportunity windows encourage collaboration between research institutions and manufacturers, facilitating the development of next-generation hot rolled stainless steel products. While the market evolves, participation from key players will significantly shape trends and drive advancements in the segment.
Emerging trends in the Cold Rolled segment of the Stainless Steel market reflect increasing integration of advanced technologies and manufacturing processes. Innovations including enhanced rolling techniques and quality control measures significantly contribute to product performance and consistency. Industries including automotive and construction, which prioritize material quality and durability, heavily influence demand dynamics.
The Cold Rolled segment is projected to reach USD 102.5 billion by 2033, at a CAGR of 8.3% during the forecast period. These figures indicate strong growth driven by rising applications in high-performance sectors, where the properties of cold-rolled stainless steel provide critical advantages. Increased investment in infrastructure and consumer goods further supports the adoption of cold-rolled products.
With regulatory compliance becoming more stringent, manufacturers face pressure to meet sustainability and quality standards. This environment encourages investments in technologies that enhance production efficiency and reduce waste. The focus on lowering environmental impact while maintaining product integrity shapes the strategic direction of players in the market.
Supply chain resilience remains vital, particularly concerning raw material sourcing. Fluctuations in the availability of key inputs influence production costs and pricing strategies. Companies actively seek diverse sourcing options and develop strategic partnerships to mitigate risks associated with supply chain vulnerabilities.
Continual advancements in cold-rolled technologies, including the development of next-gen upgrades, enhance the evolution of product offerings. This evolution addresses the changing needs of end-users while ensuring competitiveness in the market. Growth in this sub-segment reinforces the overall expansion of the Stainless Steel market, highlighting its significance across numerous industries.
Adoption of Cold Drawn stainless steel is driven by its applications in industries requiring high strength and precision. Key demand arises from sectors including automotive, industrial machinery, and construction, where the need for durable and resilient materials is significant. With a robust CAGR of 8.3%, the segment's expansion is anticipated, reflecting increasing investments in sectors relying on superior material properties. The Cold Drawn segment is projected to reach USD 31.1 billion by 2033, indicating significant growth potential in the market.
Technological advancements in cold drawing processes enhance material characteristics, enabling the production of higher quality products. Evolving standards for efficiency and sustainability in manufacturing further fuel demand for this segment. Downstream application dynamics indicate a shift towards lightweight yet strong materials, a trend prevalent across several end-user industries. Consequently, these factors contribute to a stable outlook for the Cold Drawn segment within the broader stainless steel market.
Demand for stainless steel in the automotive and transportation sectors drives significant market growth. Valued at USD 21.6 billion in 2026, the segment is projected to reach USD 37.6 billion by 2033, at a CAGR of 8.2% during the forecast period. This growth results from increasing production of vehicles and advancements in transportation technologies. Manufacturers actively seek high-strength, lightweight materials to enhance fuel efficiency and reduce emissions, leading to greater adoption of stainless steel in various automotive applications.
Technological maturation and next-generation upgrades in vehicle design contribute to evolving requirements for materials. Stainless steel's corrosion resistance and durability align with regulatory compliance standards, pushing automotive manufacturers to incorporate these materials more extensively. Trends toward electric and hybrid vehicles create new opportunities for the market, driven by the need for specialized components that incorporate stainless steel.
Consumption shifts toward sustainable materials reinforce the segment's growth. The automotive industry increasingly prioritizes environmentally friendly practices, driving demand for recyclable materials including stainless steel. Raw material sourcing and supply chain resilience remain critical factors in sustaining this demand. The strategic opportunity windows in the automotive and transportation sectors present avenues for innovation and investment, enhancing market competitiveness.
Pricing volatility stemming from fluctuating raw material costs impacts margins in this segment. However, the long-term outlook for the stainless steel market remains positive, supported by consistent demand from the automotive and transportation industries. The segment's expansion reflects a broader trend toward increased integration of advanced materials in manufacturing processes.
Investment in the Building & Construction segment drives significant demand for stainless steel, reflecting the sector's expansion and modernization efforts. This segment is estimated to reach USD 46.4 billion by 2033, at a CAGR of 7% during the forecast period. Increasing urbanization and infrastructure development in Asia Pacific and North America contribute to this growth. Enhanced material properties, including corrosion resistance and durability, further support adoption among construction firms. Regulatory compliance related to building materials promotes the use of stainless steel, driven by its ability to meet stricter environmental and safety standards.
Technological advancements in the manufacturing processes of stainless steel enhance product quality, making it suitable for various applications in construction. Innovations in design and fabrication methods enable more sustainable construction practices, aligning with global trends in reducing environmental impact. Downstream application dynamics shift toward high-strength materials, creating opportunities for stainless steel in structural components. Continued investment in green building initiatives drives demand for stainless steel, reinforcing its critical role in the evolving construction industry.
Significant growth in the Consumer Goods & Home Appliances segment aligns with the rising trend of home renovations and consumer preferences for high-quality, durable materials. This segment is expected to reach USD 38.9 billion by 2033, driven primarily by increasing demand for stainless steel kitchen appliances, cookware, and other home products that exhibit enhanced aesthetic appeal and longevity. The durability of stainless steel enhances its attractiveness in this segment, ensuring steady consumption across various applications.
Technological maturation in manufacturing processes facilitates the production of cost-effective and versatile stainless steel products, enabling innovation in appliance designs and functionality. Enhanced production capabilities enable manufacturers to respond promptly to changing consumer preferences and market dynamics, supporting growth within the overall market. The integration of advanced technologies in home appliances leads to efficient energy consumption and improved user interfaces, reinforcing stainless steel's position in the consumer goods sector.
Shifts in consumer behavior toward premium and sustainable products significantly influence purchasing decisions in the Consumer Goods & Home Appliances segment. Increasing awareness of environmental sustainability drives demand for stainless steel due to its recyclability and long lifespan, positioning it favorably against alternative materials. Regulatory compliance standards supporting the use of sustainable materials encourage manufacturers to adopt stainless steel in product offerings.
Overall, strategic opportunity windows exist for companies operating in the market, particularly those leveraging advancements in stainless steel technology. Capital investment in research and development facilitates the introduction of innovative products catering to evolving consumer needs. Continued expansion in this segment aligns with broader market trends, ensuring a positive outlook for stainless steel in consumer goods and home appliances.
Valued at USD 21.6 billion in 2026, the Industrial Machinery & Equipment segment is projected to grow at a CAGR of 7.8% during the forecast period. An increasing focus on automation and efficiency in manufacturing processes drives demand for stainless steel within this segment. Technological advancements enhance product performance, enabling machinery to withstand higher stress and corrosive environments. These factors lead to a growing acceptance of stainless steel components in various industrial applications.
Investments in infrastructure and industrial expansion continue to serve because catalysts for growth, particularly in emerging economies. The need for durable and reliable machinery fuels consumption, with stainless steel providing the necessary strength and resistance. End users prioritize materials that offer long-term value and low maintenance, further propelling the adoption of stainless steel in machinery and equipment.
Market dynamics indicate a shift towards sustainable practices, with regulatory compliance and environmental considerations influencing material selection. Manufacturers increasingly incorporate stainless steel in response to stringent regulations governing emissions and waste management. This trend enhances the competitive advantage of stainless steel products in the market.
Technological obsolescence presents challenges, with ongoing innovations requiring constant adaptation among manufacturers. Companies investing in next-generation upgrades improve operational efficiency and align with evolving industry standards and consumer preferences. The strategic opportunity windows available in this segment highlight the importance of remaining agile in response to market shifts.
Overall, the Industrial Machinery & Equipment segment within the Stainless Steel market demonstrates robust potential driven by advancements and evolving end-use dynamics. Continued investment and development within this sector promise to sustain momentum because the segment matures and adapts to new challenges.
Investment in the Oil & Gas sector drives demand for stainless steel due to its strength, durability, and corrosion resistance. The industry's ongoing expansion relies on these properties, particularly for applications involving high-pressure environments and extreme temperatures. Rising global energy needs support this growth, with the market catering to various applications including drilling, refining, and transportation of oil and gas products.
Technological advancements shape the segment. Continuous improvements in stainless steel manufacturing processes enhance product performance, allowing for innovations that align with the evolving requirements of the Oil & Gas sector. Enhanced efficiency in production and processing ensures the delivery of high-quality materials that meet industry standards.
Regulatory compliance affects the segment, with strict guidelines governing material selection and quality assurance. Manufacturers focus on obtaining necessary certifications, which enhances their competitive position within the market. Compliance strengthens consumer trust and facilitates market entry in regions with stringent regulations.
Consumption shifts towards sustainability influence the Oil & Gas segment. Companies increasingly prioritize environmentally friendly practices, leading to the adoption of more sustainable materials, including stainless steel with reduced carbon footprints. This shift aligns with global efforts to minimize environmental impacts while meeting energy demands.
Raw material sourcing remains a critical aspect of the segment, with fluctuations in prices impacting cost structures. Suppliers and manufacturers strategically manage their relationships to maintain supply chain resilience. Companies seek to diversify their supplier networks to mitigate risks associated with price volatility and availability.
The global demand for energy continues to increase, positioning the Oil & Gas segment within the stainless steel market for sustained growth. Investment in advanced technologies and compliance with regulatory standards will further enhance the segment's contribution to overall market dynamics.
Increasing activity within the Chemical and Petrochemical sector drives demand for stainless steel, particularly in applications requiring high corrosion resistance and durability. The ongoing transition towards more sustainable practices within this industry enhances interest in stainless steel products that meet strict environmental standards. Technological advancements in production processes facilitate the development of next-generation stainless steel materials tailored to the specific needs of the chemical and petrochemical sectors.
Regulatory compliance standards significantly influence purchasing decisions in this segment. Tightening environmental regulations globally lead manufacturers to prioritize materials that align with these evolving standards. This shift opens strategic opportunity windows for stainless steel suppliers capable of offering compliant products. Continuous innovation in product evolution supports adoption across various downstream applications, enhancing the market’s overall growth potential.
Cost structures and pricing volatility directly affect profitability for stakeholders in the chemical and petrochemical industries. Fluctuations in raw material costs lead to margin pressures, prompting companies to evaluate their sourcing strategies. Supply chain resilience remains crucial, particularly in sourcing high-quality stainless steel to mitigate risks associated with logistics vulnerabilities. Demand for stainless steel in this segment reflects broader consumption shifts towards more sustainable and efficient materials, reinforcing its role in the ongoing development of the stainless steel market.
Growth within the Power Generation & Renewable Energy sub-segment of the Stainless Steel market is driven by the global shift towards sustainable and alternative energy sources. This transition increases the demand for durable and corrosion-resistant materials, essential for infrastructure and equipment used in renewable energy facilities, including wind and solar power plants.
Technological maturation in renewable energy systems creates a reliance on high-performance materials, including stainless steel, which enhances energy efficiency and extends the lifespan of equipment. The sector's expansion is supported by stringent regulatory compliance standards aimed at reducing carbon emissions and promoting sustainable practices across the energy landscape.
Investment in renewable projects continues to rise, encouraging manufacturers to innovate and develop advanced stainless steel products tailored for specific applications in this sector. Downstream applications, including power generation turbines and solar panel supports, increasingly adopt stainless steel due to its strength, lightweight properties, and resistance to environmental degradation.
Shifts in consumption patterns towards cleaner energy solutions and the need for reliable materials in the construction and maintenance of energy systems reinforce the role of stainless steel. The dynamics of this sub-segment reflect a significant opportunity within the broader Stainless Steel market, aligning with global efforts to enhance energy sustainability.
Growth within the Food & Beverage Processing segment of the Stainless Steel market stems from increasing consumer demand for processed and packaged food products. While health and safety regulations tighten, the need for durable and corrosion-resistant materials intensifies. Stainless steel meets these requirements effectively, promoting its adoption across various applications, including tanks, pipes, and processing equipment.
Technological advancements in manufacturing processes enhance the quality and efficiency of stainless steel production. Innovations drive the development of new grades and finishes, allowing for greater versatility in food processing applications. The segment's expansion is further supported by the trend toward more sustainable and eco-friendly materials, positioning stainless steel because a favorable choice for environmentally-conscious manufacturers.
Compliance with stringent sanitary and hygienic standards remains crucial within this sector. Regulations dictate the use of materials that ensure product safety and avoid contamination, steering food and beverage producers toward stainless steel solutions. This compliance strengthens market demand and encourages investment in high-quality stainless steel products.
Pricing volatility in raw materials impacts the overall cost structures for manufacturers. Fluctuations in nickel and chromium prices directly affect stainless steel production costs, creating margin pressures. Manufacturers in the food and beverage processing space continuously seek strategies to mitigate these costs, including optimizing supply chain processes and sourcing raw materials more effectively.
Investment in the Food & Beverage Processing segment reflects a commitment to enhancing production capabilities and expanding operational capacity. Strategic opportunity windows arise from increasing global consumption patterns, highlighting the critical role stainless steel plays in modern food production and processing. The dynamics of this segment underpin the overall growth trajectory of the Stainless Steel market.
Demand for stainless steel within the Medical & Healthcare segment stems from the increasing focus on advanced medical technologies and equipment. The healthcare industry's evolving requirements for sterilization and corrosion resistance drive the adoption of high-grade stainless steel in surgical instruments, implants, and medical devices. Regulatory compliance standards influence material selection, with stainless steel meeting stringent hygiene and safety requirements.
Technological maturation within the healthcare sector facilitates the development of innovative products, enhancing the segment's attractiveness. Advances in manufacturing processes, including additive manufacturing and precision machining, enable the production of complex components with improved performance characteristics. Such developments create strategic opportunities for investment in next-generation upgrades across various applications.
Consumption shifts toward minimally invasive surgical procedures necessitate lightweight and durable materials, prompting an increase in demand for specialized stainless steel grades. Market participants benefit from these trends by integrating new technologies and refining their product offerings to meet the evolving needs of healthcare providers. The resilience of the supply chain and effective raw material sourcing strategies remain crucial for maintaining competitiveness in the market.
Pricing volatility presents challenges, impacting margins and necessitating careful management of costs. Strategic planning and investment in supply chain resilience mitigate risks associated with logistics vulnerabilities and disruptions. The Medical & Healthcare segment of the Stainless Steel market continues to evolve, and companies that adapt to these dynamics secure their positions in this growing sector.
In the Aerospace and Defense, Water and Wastewater sub-segment, demand stems from critical applications where reliability and durability are essential. These industries require materials that withstand varying environmental conditions, including corrosion and high temperatures. Consequently, the need for high-performance stainless steel is evident, enhancing safety and longevity in applications ranging from aerospace structures to wastewater treatment facilities. Regulatory compliance standards significantly influence this sub-segment, with stringent requirements driving manufacturers to adopt superior materials that align with safety and environmental regulations.
Technological maturation in manufacturing processes enables advancements in stainless steel production, enhancing its performance characteristics. Innovations in alloying and processing lead to the development of specialized grades tailored for specific applications within the Aerospace and Defense, Water and Wastewater sectors. Investment in next-generation upgrades creates opportunities for product evolution, where stainless steel adapts to meet the precise needs of modern engineering challenges. This evolution attracts stakeholders interested in high-quality materials capable of supporting complex applications.
End-use dynamics reflect a shift towards sustainable practices and efficiency, influencing consumption patterns within these industries. The market's emphasis on sustainability aligns with increasing legislative actions focused on environmental impact, reinforcing the demand for stainless steel that contributes to energy-efficient and low-carbon processes. While industries adapt to these consumption shifts, strategic opportunity windows arise for manufacturers, presenting avenues for investment and growth within the stainless steel market.
Based on geography, the Global Stainless Steel market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America stands poised for growth within the Stainless Steel market, expanding at a CAGR of 7.9% throughout the forecast period. By the end of 2033, the market is set to reach a total addressable market size of USD 37.6 billion. The region accounted for 16.2% of the global market in 2025, highlighting its substantial role in the overall dynamics of stainless steel supply and demand.
Several factors influence market growth in North America. Increased investment in infrastructure modernization, particularly in the United States, drives demand for stainless steel across various sectors. The automotive and transportation industries remain major contributors, with rising production levels necessitating high-quality materials. Local manufacturing densities and nearshoring initiatives enhance the competitive landscape, ensuring efficient supply chains that cater to regional needs.
Geopolitical fragmentation and local compliance regulations shape procurement dynamics in North America. Domestic market participants focus on enhancing production capabilities to meet evolving standards while navigating potential trade policy shifts. Consequently, these factors contribute to a mature market environment characterized by high-value replacement cycles and incremental growth vectors.
Localized procurement strategies reflect cultural nuances and regional B2B buying behaviors, allowing participants to adapt to market demands effectively. Resource availability and energy grid resiliency will play a vital role in shaping future investments and expansions across the North American stainless steel sector.
In Europe, the Stainless Steel market presents a robust environment, characterized by significant opportunities driven by a combination of domestic demand and strategic investment initiatives. Countries including Germany, France, the UK, Italy, and Spain contribute to a collective market share of 18.6% in 2025, reflecting the region's established industrial base and high-value applications.
Investment in infrastructure modernization supports growth across various sectors, particularly in automotive and construction industries. Increasing regulatory frameworks and local compliance mandates encourage manufacturers to enhance operational capabilities and service delivery. The ongoing shift towards localized manufacturing densities and nearshoring initiatives aligns with rising demand for high-quality stainless steel products.
Emerging market front-runners within the region, particularly in Germany and Italy, highlight the competitive landscape marked by domestic leaders adapting to evolving market dynamics. Cultural nuances and regional B2B buying behaviors influence procurement strategies, ensuring suppliers remain agile and responsive to industry needs.
Geopolitical fragmentation and cross-border trade corridors impact regional supply chains, reinforcing the need for vendors to optimize local operations. Sustained demand across end-use industries positions the Stainless Steel market in Europe for significant growth, fueled by high-value replacement cycles and incremental growth vectors.
Asia Pacific holds a substantial share of the global Stainless Steel market, accounting for 56.5% in 2025. This region features robust demand stemming from various industrial sectors, including automotive, construction, and consumer goods. The rapid industrialization and urbanization in countries like China and India significantly contribute to this demand, with increasing infrastructure projects driving the need for stainless steel products.
The competitive landscape in Asia Pacific reflects a diverse range of players, with established manufacturers like Baosteel Group Corporation and JFE Steel Corporation leading the market. Localized manufacturing efforts, supported by foreign direct investment, enhance the supply chain resilience and improve production capacities. This development aligns with the regional trend towards nearshoring initiatives, which aim to reduce lead times and enhance supply chain efficiencies.
Emerging economies within Southeast Asia exhibit underpenetrated territories that present growth opportunities for market participants. The increasing focus on sustainable construction practices and energy-efficient solutions in Australia and South Korea further supports the market. Domestic procurement dynamics and cultural nuances play a vital role in influencing buying behaviors, shaping the competitive strategies of vendors.
Investments in infrastructure modernization across the region continue to drive segment expansion, particularly in the flat products and tubular products categories. The anticipated growth in the market reflects the ongoing evolution of regional resource availability and energy grid resiliency. This combination of factors positions Asia Pacific because a key area for stainless steel market development, with sustained growth expected through 2033.
In South America, the Stainless Steel market experiences unique dynamics influenced by local economic conditions and industry demands. Brazil and Argentina represent the primary markets within this region, contributing significantly to the overall market share. The share of the global market in 2025 is estimated at 4.1%, indicating a moderate presence in the global landscape.
Key drivers for growth include rising infrastructure investments and increasing demand from construction and automotive sectors. The region demonstrates potential for expansion, particularly in high-value applications, supported by ongoing modernization efforts. Local manufacturers benefit from rising demand for durable and sustainable materials, with stainless steel becoming a preferred choice due to its strength and corrosion resistance.
Supply chain trends indicate a movement towards localized manufacturing, which enhances efficiency and reduces lead times. The strategic focus on domestic production aligns with broader economic goals to support local economies. This trend creates a competitive environment among local players, encouraging innovation and the development of specialized products tailored to regional needs.
Increased foreign direct investment (FDI) flows into the region further enhance the market's growth potential. The presence of domestic market participants creates opportunities for collaboration and potential consolidation, strengthening the overall competitive environment in the Stainless Steel market. This environment promotes sustained investments in production capabilities and technological advancements, supporting the market's growth trajectory through 2033.
The Middle East and Africa region exhibits substantial potential in the Stainless Steel market, driven by ongoing infrastructure projects and urbanization initiatives. Saudi Arabia and the UAE play important roles in market advancement, with various construction and industrial activities enhancing stainless steel demand. South Africa contributes significantly through its mining and manufacturing sectors, which increasingly adopt stainless steel for various applications. The region’s underpenetrated territories present opportunities for market players to expand their presence and cater to rising consumption patterns.
Regional dynamics show a growing trend towards localized manufacturing, enabling companies to reduce lead times and optimize supply chains. Foreign direct investment flows support this localized approach, enhancing the competitiveness of domestic players. Cultural nuances influence procurement practices, with regional businesses favoring suppliers that align with local compliance mandates and quality standards.
While the Stainless Steel market evolves, strategic entry barriers diminish, promoting vendor consolidation trends and encouraging partnerships among local and international firms. Market players focus on high-value replacement cycles within existing industrial frameworks, ensuring resilience and sustainability in their operations. Continual investment in infrastructure modernization further enhances the market landscape, establishing a foundation for incremental growth across various segments.
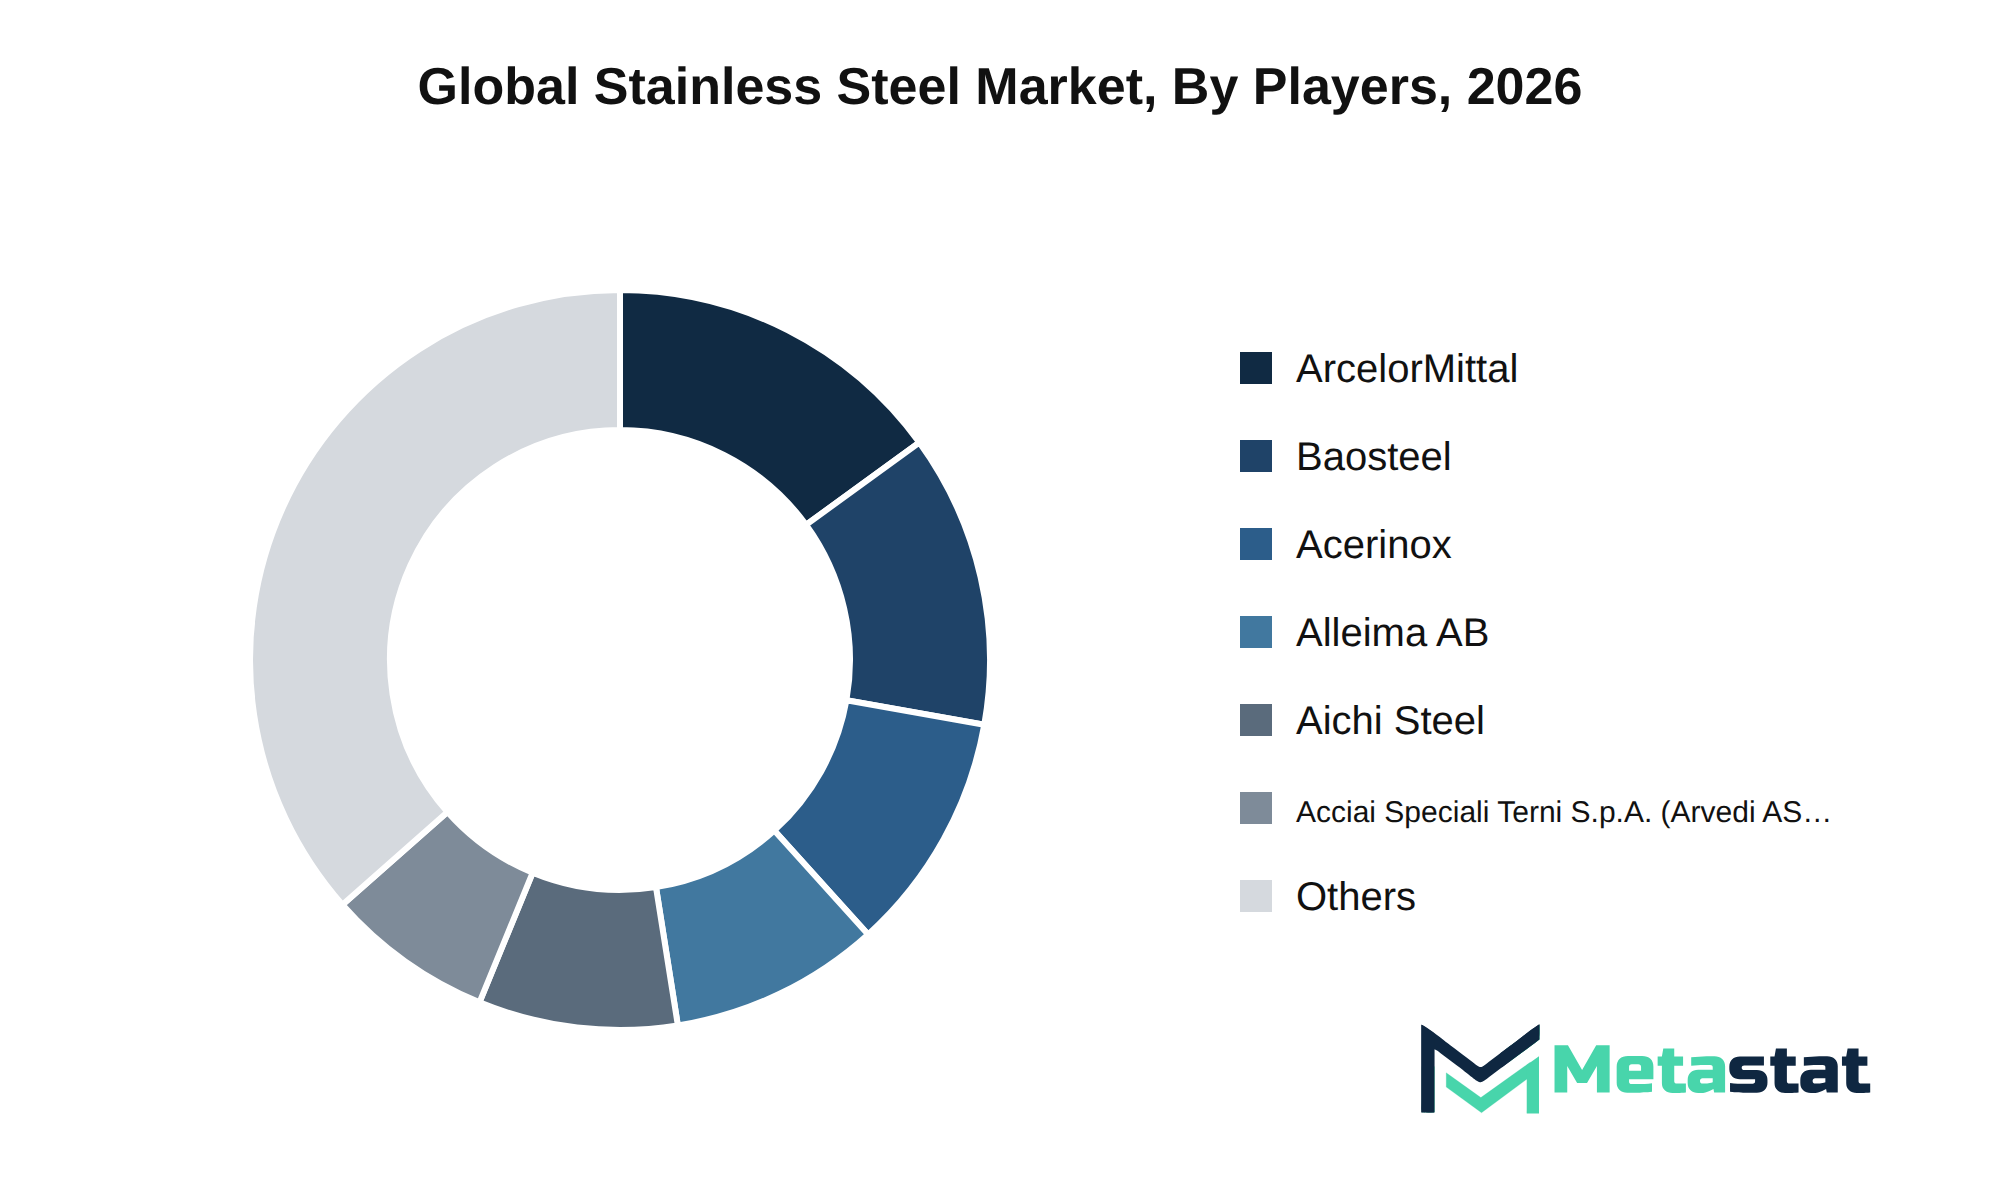
The competitive dynamics in the Stainless Steel market reflect a landscape characterized by significant mergers, acquisitions, and strategic consolidations among key players. Companies including ArcelorMittal S.A., POSCO, and Acerinox, S.A. actively pursue growth through partnerships and alliances to enhance their market position and expand their technological capabilities. This trend creates a climate of innovation and collaboration, positioning these firms to leverage new market opportunities.
Product differentiation remains critical, with leaders investing in research and development to create proprietary technologies that provide competitive advantages. Companies like Baosteel Group Corporation and Nippon Steel Corporation focus on enhancing their intellectual property portfolios to protect their innovations and improve their market offerings. Strategic pricing architectures contribute to maintaining profitability while ensuring customer retention through brand equity dynamics.
The Stainless Steel market faces barriers to entry influenced by established players and their procurement leverage. This situation deters new entrants, maintaining market stability and enabling existing companies to optimize their supply chains. The future competitive outlook indicates a focus on defensive imperatives, including value chain integration and customer retention strategies, which are essential for sustained growth in a changing market.
Market size is forecast to rise from USD 137 billion in 2025 to over USD 251.8 billion by 2033. The base case reflects a 7.9% CAGR, driven by strong downstream demand from various industries, including automotive, construction, and consumer goods. The market experiences growth due to technological advancements, regulatory changes, and evolving trade corridors that influence supply chain dynamics.
In the bullish scenario, rapid advancements in next-generation technologies and enhanced R&D commercialization timelines lead to accelerated adoption of stainless steel in emerging applications. Conversely, a bearish outlook arises from economic downturns that hinder investment in infrastructure and capital expenditures, impacting overall demand. Geopolitical realignments and trade disruptions influence market stability and growth potential.
Strategic capital allocation directives focus on addressing unmet enterprise needs and identifying high-growth pockets within the stainless steel market. Emerging white-space opportunities attract investment, driven by businesses adapting to shifting consumption patterns and product life cycles. Regulatory evolution and compliance milestones will shape operational practices and capabilities within the market, ensuring alignment with sustainability goals and industry standards.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Stainless Steel market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 7.9% from 2026 to 2033 |
Revenue Unit | USD billion |
Segmentation | By Type, Product Form, Process, End-Use Industry, and Region |
By Region | North America (By Type, Product Form, Process, End-Use Industry, and Country)
|
Europe (By Type, Product Form, Process, End-Use Industry, and Country)
| |
Asia Pacific (By Type, Product Form, Process, End-Use Industry, and Country)
| |
South America (By Type, Product Form, Process, End-Use Industry, and Country)
| |
Middle East and Africa (By Type, Product Form, Process, End-Use Industry, and Country)
|
Find answers to common questions about this report
The Stainless Steel market size was valued at USD 137 billion in 2025.
The Stainless Steel market is projected to grow at a CAGR of 7.9% during the forecast period from 2026 to 2033.
The North America Stainless Steel market size is estimated to reach USD 37.6 billion by 2033.
Austenitic Stainless Steel (200 & 300 Series) leads the Stainless Steel market with a projected value of USD 171 billion by 2033. This segment demonstrates significant growth potential, with a compound annual growth rate of 7.6 percent.
Key drivers for the stainless steel market include significant investments in public infrastructure and the ongoing trend of urbanization, which heightens demand for durable construction materials. the focus on sustainable urban development and renewable energy initiatives further enhances the market's growth potential.
Macroeconomic headwinds, including rising inflation and fluctuating economic stability, restrain growth in the stainless steel market. Higher production costs reduce demand across sectors like construction and automotive, while geopolitical instability introduces uncertainties in trade relationships, leading to supply chain disruptions and increased logistics costs. These factors collectively create barriers to investment and market expansion.
Infrastructure development, driven by urbanization and renewable energy initiatives, significantly favors product adoption in the stainless steel industry. The material's durability, resistance to corrosion, and alignment with sustainability goals enhance its appeal for modern construction projects, driving increased demand and investment in infrastructure.
The Stainless Steel market is estimated to reach a valuation of USD 251.8 billion by 2033.
Top players operating in the Stainless Steel industry include Acciai Speciali Terni S.p.A. (Arvedi AST), Acerinox, S.A., Aichi Steel Corporation, ArcelorMittal S.A., Baosteel Group Corporation, POSCO, and Outokumpu Oyj.
Infrastructure development serves because a significant growth driver for the stainless steel market. Major investments in public infrastructure, urbanization, and renewable energy initiatives contribute to robust demand for stainless steel products.
Choose Your License
Global Stainless Steel Market
The analysts below cover Chemicals and Materials research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
INDUSTRY CONSULTANT - CHEMICALS & ADVANCED MATERIALS
Chemicals and Materials · Machinery & Equipment · Packaging
Amit Gadhekar Consultant for Chemicals and Materials at MetaStat Insight, directing sector-specific intelligence, research, and strategic consulting across global chemical and processing markets.
Last Updated: September 2026
Tracking maintenance cycle demand for secondary flight display units and terrain collision avoidance systems across regional jet fleets involves complex aftermarket dynamics. MetaStat Insight provided practical analysis separating airline retrofit programs from OEM forward-fit production schedules in North America and Southeast Asia. The supplier matrix highlighted component obsolescence timelines without resorting to vague generalizations. The dataset served as a dependable reference during our annual program review meetings.
Evaluating secondary resin quality across post-consumer packaging streams requires reliable technical segmentation. MetaStat Insight delivered an objective assessment that distinguished between extrusion-grade flake pricing and optical sorting throughput limitations across Western Europe. The competitive positioning breakdown for licensed depolymerization technology providers answered several questions during our feedstock feasibility audit. Their team clarified regional trade restrictions on mixed plastic scrap quickly when our team submitted follow-up requests.
Evaluating sovereign cloud deployments for core banking platforms demands a clear view of data residency regulations and migration exit strategies. MetaStat Insight delivered an exhaustive review of regional latency tolerances, mainframe decommission milestones, and third-party vendor concentration risk. The regulatory compliance mapping across European and Asian financial jurisdictions gave our team a dependable baseline for multi-cloud infrastructure discussions.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950