
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global High Voltage (HV) Battery Management System (BMS) Market Size, Share, By Battery Capacity (75 kWh-150 kWh, 151 kWh-225 kWh, 226 kWh-300 kWh and >300 kWh), By Battery Type (Lithium Iron Phosphate (LFP), Lithium Nickel Manganese Cobalt Oxide (NMC), Lithium Nickel Cobalt Aluminium Oxide (NCA), Lithium Titanate Oxide (LTO) and Others (Lithium Manganese Oxide, Sodium-Ion, Solid-State and Other Emerging Chemistries)), By Voltage (400-600V and >600V), By Application (Passenger Cars, Buses, Trucks and Stationary Energy Storage Systems), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5371
September, 2026
252 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $4,479.7 Million in 2025, projected to reach $9,466.8 Million by 2033 at a 9.8% CAGR.
Dominant Segment: The 75 kWh-150 kWh segment leads the market, driven by the increasing adoption of electric vehicles and energy storage solutions that emphasize performance and efficiency.
Geographic Lead: Asia Pacific is the fastest-growing region, propelled by rising urbanization and regulatory pressures for sustainable energy solutions, prompting manufacturers to align their offerings with local demands.
What's Inside: The report provides a comprehensive analysis of market dynamics, competitive landscape, and forecasts from 2026 to 2033, covering key segments by battery capacity, type, voltage, and application.
Technological Integration: The integration of advanced technologies such as AI and automation is enhancing operational efficiency in battery management systems, driving demand across various applications including passenger cars and energy storage.
Emerging Regional Demands: Emerging regions are experiencing significant growth opportunities, with increasing investments in electrification and energy storage solutions that align with global sustainability goals.
The global High Voltage (HV) Battery Management System (BMS) market was valued at USD 4,479.7 million in 2025 and is projected to reach USD 9,466.8 million by 2033, growing at a CAGR of 9.8% over the forecast period.
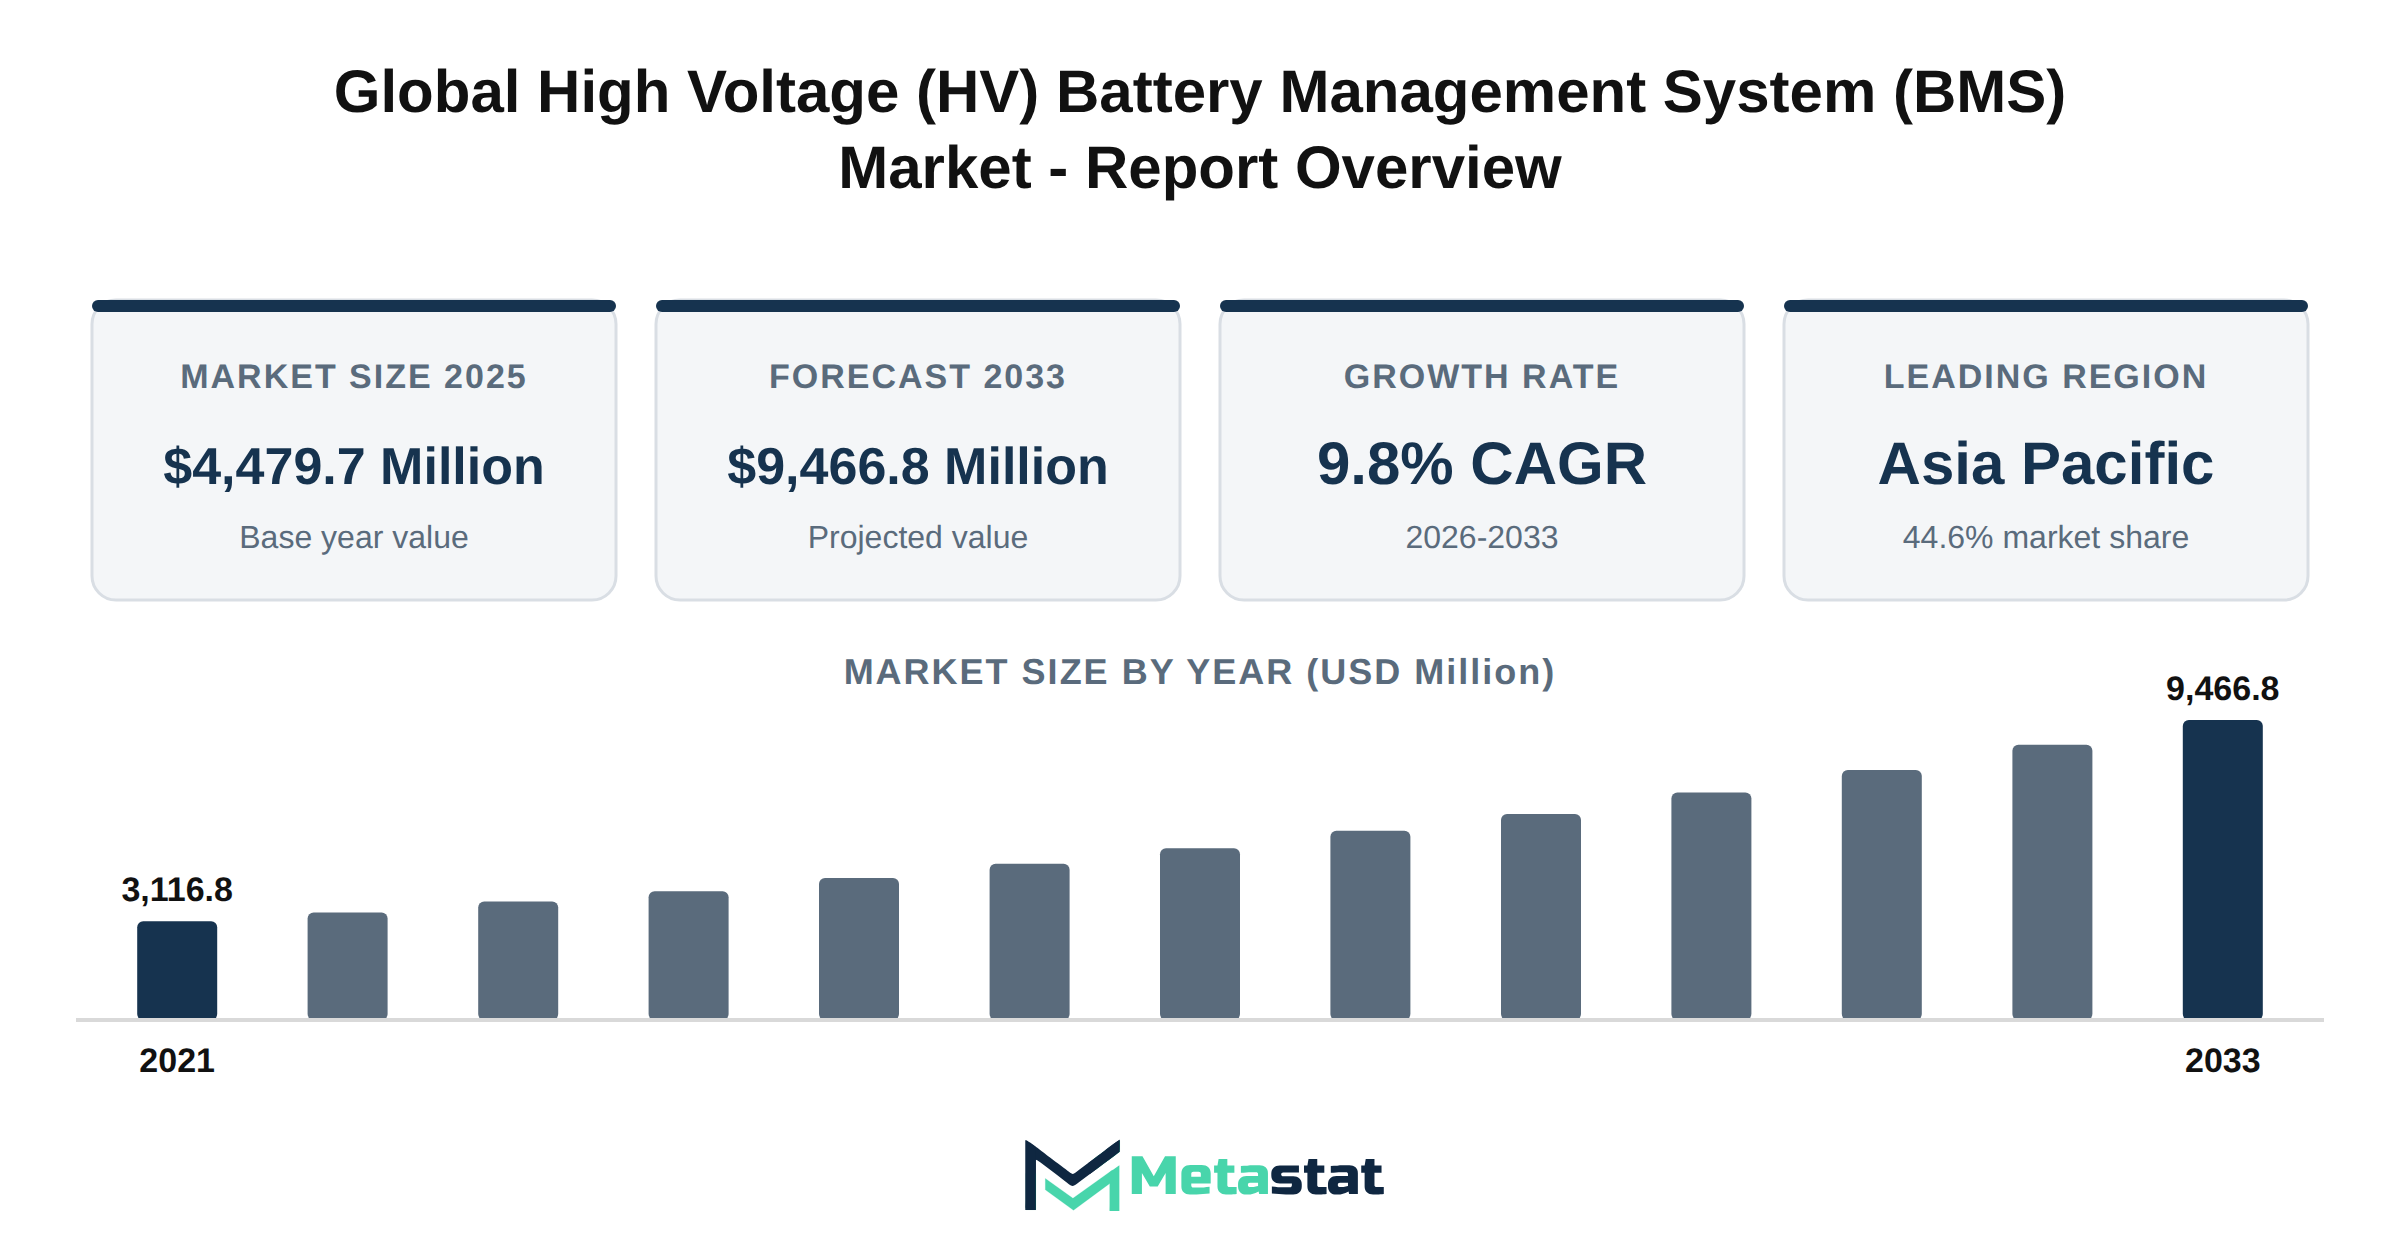
The High Voltage (HV) Battery Management System (BMS) market reached a valuation of USD 4,479.7 million in 2025. Revenue projections indicate growth to USD 9,466.8 million by 2033, reflecting a compound annual growth rate (CAGR) of 9.8% during the forecast period from 2026 to 2033. This upward trajectory is fueled by various factors including the increasing adoption of electric vehicles (EVs) and the need for efficient energy storage solutions.
The shift towards 800V and 1000V EV architectures significantly enhances high voltage BMS adoption. This transition enables faster charging times and improved performance, directly influencing consumer preferences and OEM strategies. The demand for robust battery management systems capable of handling higher voltages aligns with advancements in EV technology.
Key demand drivers include a surge in electric vehicles and utility energy storage requirements. The growing emphasis on sustainable energy solutions and government incentives for EV adoption further supports market growth. Innovations in wireless high voltage BMS and cell-to-pack integration trends enhance operational efficiency and battery performance.
Functional safety and thermal runaway prevention are essential in driving compliance with automotive standards including ISO 26262 and ASIL-D. These standards ensure that BMS designs incorporate stringent safety measures, protecting both vehicle performance and passenger safety. The integration of cloud-connected and AI-powered high voltage BMS facilitates predictive battery health monitoring, improving maintenance strategies and extending battery life.
Supply chain dynamics, including semiconductor shortages, significantly impact the high voltage BMS market. Manufacturers adopt strategic component sourcing approaches to mitigate risks associated with production delays. Competitive landscape analysis shows tier-1 suppliers positioning themselves through strategic OEM partnerships, enhancing their market reach and technological capabilities.
Regional growth corridors highlight significant market expansion across Asia Pacific, Europe, and North America. These regions are witnessing increased investments in EV infrastructure and energy storage solutions, positioning them because key players in the high voltage BMS market evolution. Commercial vehicle electrification and the demand for mega-watt charging infrastructures are reshaping specifications and driving innovations in BMS technology.
Investment trends, including venture funding and strategic mergers and acquisitions, play a crucial role in the development of high voltage battery intelligence. The ongoing commercialization of solid-state batteries introduces next-generation high voltage BMS technical requirements that will define future industry standards. The market outlook remains focused on continuous innovation and adaptation to emerging technological advancements.
The High Voltage (HV) Battery Management System (BMS) market experiences significant growth driven by the transition to higher voltage electric vehicle architectures, specifically 800V and 1000V systems. This shift supports enhanced efficiency and performance, leading to increased adoption of high voltage BMS technologies across various vehicle types.
Several factors contribute to the demand for high voltage BMS technologies. The proliferation of electric vehicles (EVs) and the growing need for utility energy storage solutions create a robust market environment. The electrification of commercial vehicles and the emergence of mega-watt charging infrastructure reshape specifications and requirements for high voltage BMS systems.
Innovation in wireless high voltage BMS solutions and cell-to-pack integration trends enhances operational efficiency and performance. These advancements facilitate more compact designs, improved energy density, and streamlined manufacturing processes, pushing the market towards more integrated and efficient systems.
Functional safety remains a critical focus, particularly concerning automotive compliance with ISO 26262 and ASIL-D standards. The need for thermal runaway prevention drives the development of safety features within high voltage BMS, ensuring reliability and safety in automotive applications.
The integration of cloud connectivity and artificial intelligence in high voltage BMS enables predictive battery health monitoring. This capability allows for real-time data analysis, improving maintenance schedules and extending the longevity of battery systems while enhancing overall performance.
Supply chain dynamics, including semiconductor shortages and component sourcing strategies, significantly impact the high voltage BMS market. Manufacturers adapt to these challenges by optimizing supply chains and exploring alternative component sources, ensuring uninterrupted production and availability of high voltage BMS technologies.
The competitive landscape features a range of tier-1 suppliers and strategic partnerships with original equipment manufacturers (OEMs). This positioning influences market dynamics, with collaborations driving innovation and expanding the reach of high voltage BMS solutions.
Regional growth corridors indicate substantial market expansion in the Asia Pacific, Europe, and North America. Investments in electric vehicle infrastructure and supportive regulatory frameworks in these regions stimulate demand for high voltage BMS technologies.
Investment trends show increasing venture funding and strategic mergers and acquisitions within the high voltage battery intelligence sector. These activities support the development of next-generation solutions and enhance competitive positioning in the market.
Solid-state battery commercialization introduces new technical requirements for high voltage BMS, prompting manufacturers to adapt their offerings. This evolution supports advancements in battery technology while addressing consumer demands for higher performance and safety levels.
The high voltage battery management system market forecast anticipates long-term growth, driven by ongoing technological advancements and increasing adoption rates across various applications. The strategic outlook reflects a strong trajectory, positioning the market for continued expansion and innovation.
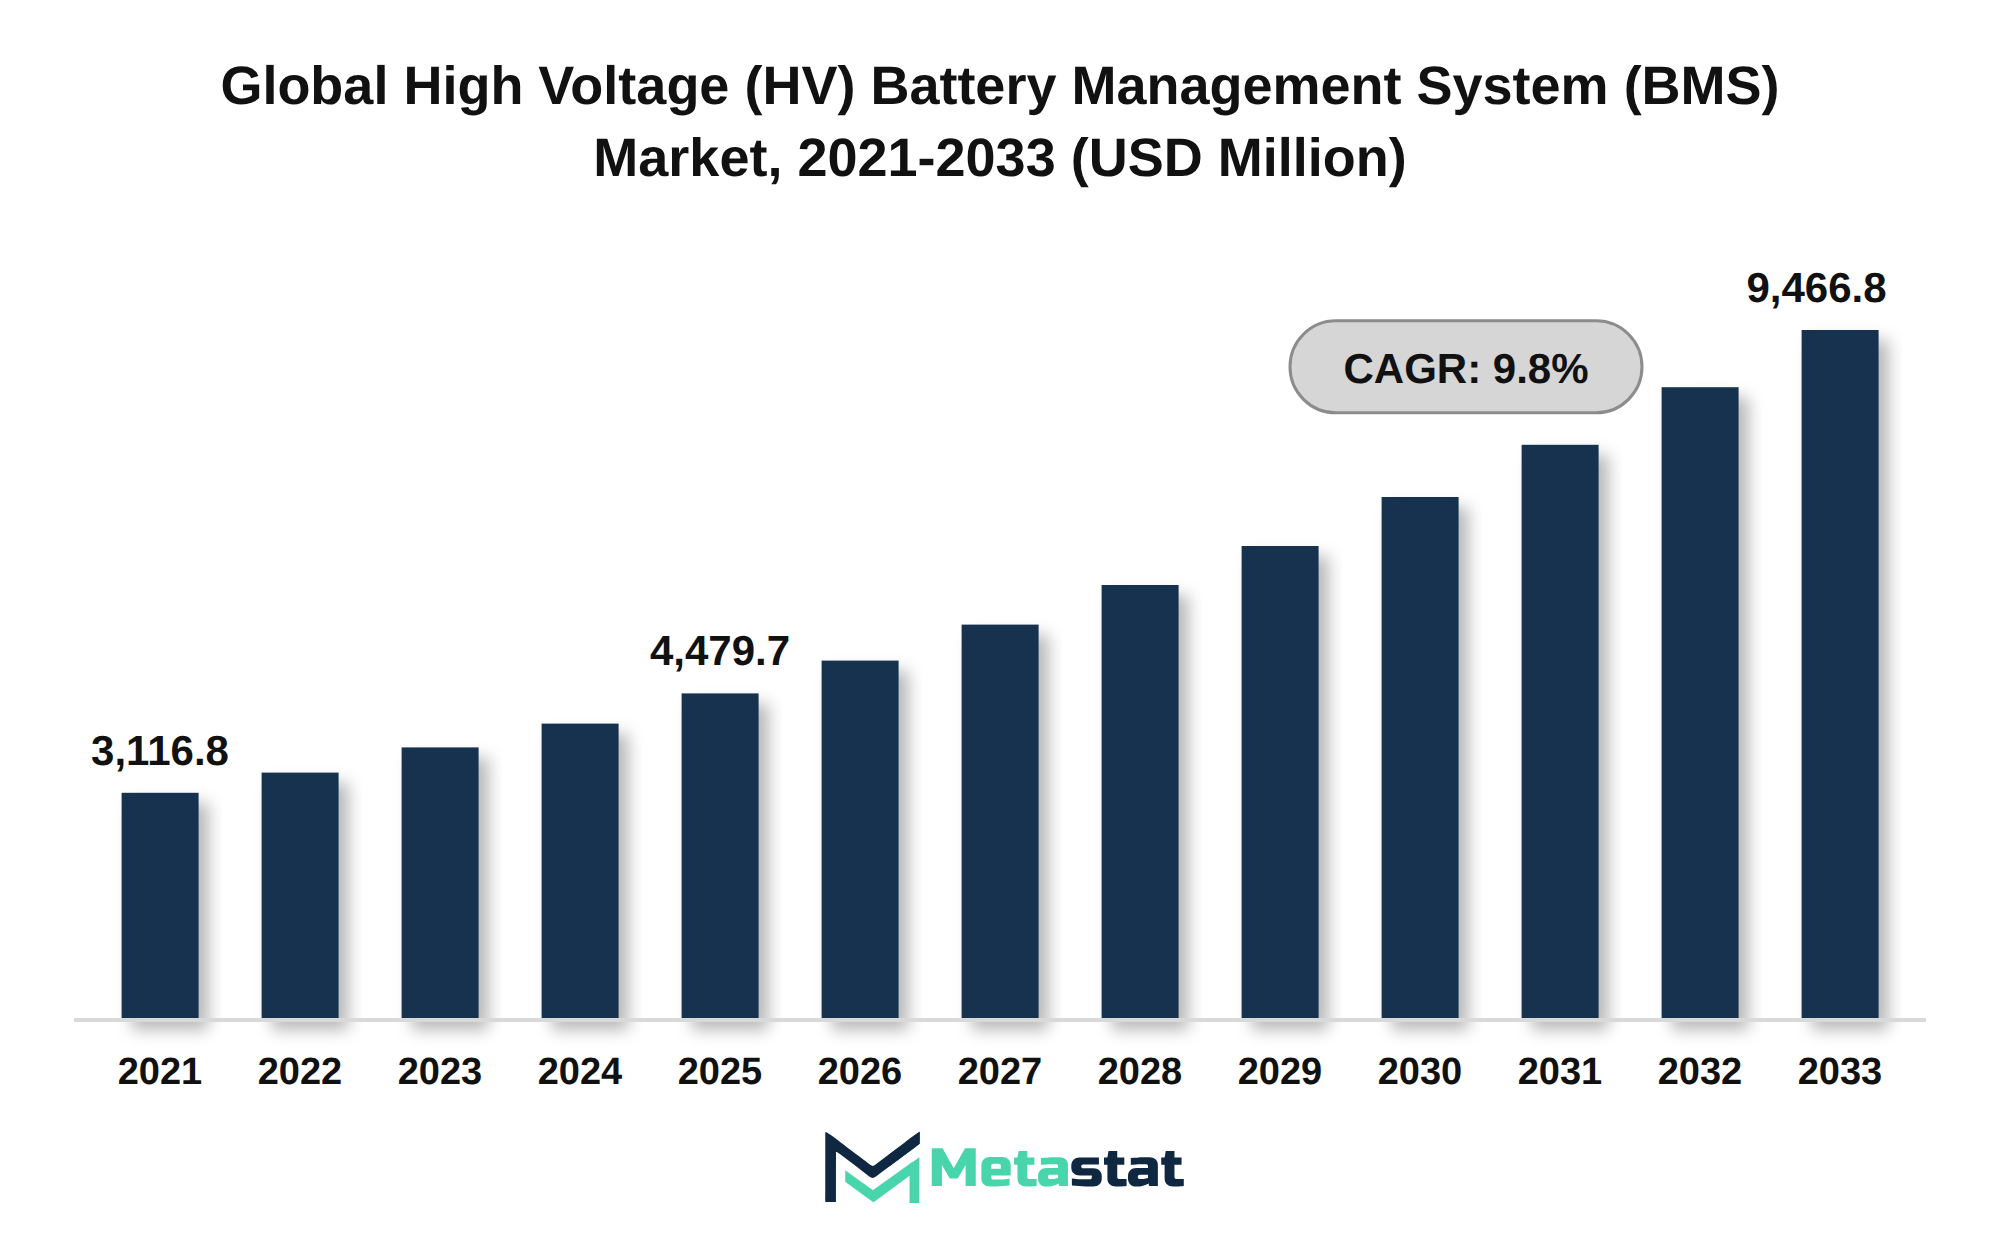
The growth of the High Voltage (HV) Battery Management System (BMS) market correlates with increased capital investment across various sectors. A robust capital investment environment, characterized by favorable interest rates and rising GDP, enables companies to allocate resources toward the development and adoption of advanced battery management technologies. This financial backing encourages innovation and enhances operational capabilities in industries including automotive, energy storage, and telecommunications, where demand for efficient battery systems is escalating.
Strong venture funding and public-private spending power create a competitive landscape, attracting new entrants and supporting existing players in expanding their product portfolios and market offerings. Automakers invest heavily in electric vehicle production, driving demand for sophisticated battery management systems that optimize performance and safety. This trend reflects a broader shift toward electrification and sustainability, pushing the market toward a more integrated and technologically advanced future.
The focus on operational productivity and cost-efficiency initiatives within organizations further consolidates this trend. Businesses prioritize battery management systems that minimize overhead costs and enhance performance, ensuring that the market continues to grow. The alignment of capital investment trends with operational goals fuels the expansion of the High Voltage (HV) Battery Management System (BMS) market, establishing a foundation for sustainable growth through 2033.
The integration of advanced technologies significantly enhances the High Voltage (HV) Battery Management System (BMS) market. Automation, artificial intelligence (AI), and software adoption drive efficiency and accuracy in battery management processes. These technologies streamline operations, reduce errors, and improve overall system performance, which is critical in applications including passenger cars and stationary energy storage systems.
Demand for efficient energy solutions drives investment in innovative battery management technologies. Organizations focus on digitizing legacy processes to optimize productivity and reduce operational costs. The ongoing digital transformation within industries creates a pressing need for systems that enable real-time data analysis and predictive maintenance, ensuring maximum battery performance and longevity.
Investment in research and development significantly contributes to innovation within the High Voltage (HV) Battery Management System (BMS) market. Companies prioritize developing proprietary technologies that enhance system capabilities and expand their offerings. This innovation-driven approach addresses current consumer demands and positions market participants to tackle future challenges in energy management.
The push for sustainability and resource stewardship drives the adoption of advanced battery technologies. Companies increasingly recognize the importance of reducing carbon footprints and implementing circular economy principles. Technological advancements in battery management systems align with these goals, promoting environmentally responsible practices while meeting growing energy demands.
The High Voltage (HV) Battery Management System (BMS) market faces significant constraints stemming from high capital investment requirements. The development, manufacturing, and deployment of advanced battery management systems necessitate substantial financial resources, which creates barriers for new entrants and smaller players in the market. This financial pressure often leads to longer project timelines and delayed market entry for innovative solutions.
Infrastructure gaps further exacerbate the situation, hindering the effective deployment of battery management systems across various sectors. Insufficient charging infrastructure, particularly in emerging markets, limits the potential for widespread adoption of electric vehicles and energy storage systems. Consequently, these gaps hinder investment returns and affect the overall growth trajectory of the market.
Inflationary pressures and rising operating costs have compounded these challenges, forcing manufacturers to reassess pricing strategies. Increased costs associated with raw materials and labor place additional strain on profit margins, which deters investment into research and development for advanced technologies in the High Voltage (HV) Battery Management System (BMS) market. This environment of economic uncertainty restricts growth and innovation.
Market fragmentation creates further difficulties, resulting from numerous players operating within localized niches without sufficient collaboration or integration. This fragmentation dilutes brand strength and consumer recognition, making it challenging for companies to establish a dominant presence. The diverse regulatory landscapes across regions contribute to this fragmentation, complicating the path toward standardization and interoperability.
Consequently, these factors contribute to a complex market environment where high capital investment requirements and associated risks limit the growth potential of the High Voltage (HV) Battery Management System (BMS) market. Addressing these constraints will require strategic partnerships, innovative financing solutions, and focused efforts on building infrastructure to enable broader market acceptance and expansion.
The High Voltage (HV) Battery Management System (BMS) market encounters significant challenges stemming from geopolitical fragmentation and trade deficits. Countries implementing tariff friction impact the pricing and availability of critical components. This scenario increases operational costs for manufacturers, leading to pricing compression that adversely affects profit margins.
Technological disruptions complicate research and development integration efforts. Companies face interoperability friction when attempting to align diverse systems and methodologies, which delays product development timelines. Such obstacles hinder market responsiveness and innovation, limiting competitiveness against emerging players.
Infrastructure gaps and retrofitting barriers further exacerbate issues in the market. Companies encounter implementation bottlenecks due to insufficient support systems, leading to delays in product rollout. This situation constrains adoption rates for advanced battery management solutions, impacting overall market growth prospects.
Supply chain instability arises from component volatility and logistics disruptions. Fluctuations in feedstock availability create challenges in maintaining consistent production levels, leading to an inability to meet demand and lost market opportunities. The combination of these factors places pressure on companies to secure reliable supply chains.
Evolving legal liabilities and tightening global regulatory standards create burdensome compliance overhead. Companies navigate increasingly complex regulatory environments while managing environmental lifecycle footprints and decarbonization mandates. These pressures require additional resources, straining financial performance and operational capacities in the High Voltage (HV) Battery Management System (BMS) market.
Increasing demand for high voltage battery management systems in emerging regions presents significant opportunities for market growth. Regions including Asia Pacific demonstrate a strong inclination towards electrification, driven by rising urbanization and regulatory pressures for sustainable energy solutions. This regional momentum influences manufacturers and suppliers, compelling them to align their offerings with local needs. Enhanced infrastructure modernization efforts accelerate the adoption of advanced battery management systems.
The transition towards digital transformation within the energy sector drives the integration of next-generation innovations in high voltage battery management systems. Technological disruptions, including improved analytics and real-time monitoring capabilities, enhance operational efficiency and battery performance. Companies operating in the market benefit from these advancements, driving adoption across various applications, including passenger cars and energy storage systems.
Shifts in buying behaviors, favoring digital procurement channels, create new avenues for market participants. The increasing emphasis on sustainability imperatives and environmental, social, and governance (ESG) criteria influences investment decisions and product development strategies. Companies are compelled to integrate eco-friendly practices into their operations, aligning with consumer preferences for greener technologies. This trend emphasizes the need for ongoing product innovation and diversification across multiple applications within the high voltage battery management system market.
Strategic consolidation through mergers and acquisitions enhances competitive positioning for market players. Such initiatives allow companies to leverage complementary technologies and broaden their service offerings. This consolidation leads to improved resource allocation, enabling firms to respond effectively to evolving market demands and capitalize on emerging opportunities.
The Global High Voltage (HV) Battery Management System (BMS) market is segmented based on Battery Capacity, Battery Type, Voltage, and Application.
Valued at USD 2,301.4 million in 2026, the 75 kWh-150 kWh segment is projected to reach USD 4,208.9 million by 2033, at a CAGR of 9% during the forecast period. This growth stems from increasing adoption of electric vehicles and energy storage solutions, where battery capacity plays a critical role in performance and efficiency. The rising focus on sustainability and energy efficiency across various industries drives demand for high-capacity batteries in passenger vehicles and commercial applications.
Technological advancements in battery chemistry and management systems significantly enhance performance metrics including energy density, lifespan, and safety. Innovations including lithium iron phosphate (LFP) and lithium nickel manganese cobalt oxide (NMC) batteries contribute to improved efficiency and cost-effectiveness, directly influencing market adoption. The expanding electric vehicle market, driven by government incentives and changing consumer preferences toward sustainable transportation, presents a strategic opportunity for manufacturers within the High Voltage (HV) Battery Management System (BMS) market.
Robust regulatory frameworks, including emissions reduction targets and renewable energy initiatives, support the transition toward high-capacity battery solutions. Compliance with emerging standards impacts manufacturers’ operational strategies, ensuring products align with safety and environmental requirements. Consequently, these dynamics create a competitive landscape, motivating companies to invest in research and development for next-generation battery technologies.
Supply chain resilience becomes increasingly important, particularly regarding raw material sourcing for battery production. Fluctuations in material costs, driven by mining capacities and geopolitical factors, affect pricing structures and profit margins within this segment. Manufacturers navigate these challenges to maintain competitiveness and profitability while advancing product offerings to meet evolving consumer and regulatory demands.
Growth in the 151 kWh-225 kWh segment of the High Voltage (HV) Battery Management System (BMS) market stems from rising demand in commercial vehicle applications and enhanced energy storage solutions. This segment is characterized by advancements in battery technology, particularly in lithium-ion chemistries, which improve performance and efficiency. Manufacturers increasingly focus on higher energy density and longer lifecycle batteries, driving adoption among various end users.
Technological maturation significantly influences segment expansion, facilitating next-generation upgrades and product evolution. Developments in Lithium Iron Phosphate (LFP) and Lithium Nickel Manganese Cobalt Oxide (NMC) batteries enhance capacity and performance metrics. This evolution aligns with regulatory compliance standards that emphasize sustainability and efficiency, further influencing market dynamics.
Investment in infrastructure supporting electric vehicle (EV) adoption continues to fuel consumption shifts within this segment. Increased government incentives and consumer awareness regarding environmental concerns impact purchasing decisions, pushing manufacturers to adapt their offerings. The segment is projected to reach USD 2,862.8 million by 2033, at a CAGR of 9.7% during the forecast period.
Strategic opportunity windows arise due to evolving end-use dynamics, with growing applications in passenger cars, buses, and stationary energy storage systems. The segment demonstrates resilience against supply chain vulnerabilities, maintaining a robust outlook driven by diversified raw material sourcing and innovative manufacturing processes. Disruptive alternatives remain a consideration, but the sector's focus on technological advancements ensures competitive positioning in the market.
Demand for high voltage battery management systems in the 226 kWh-300 kWh segment grows due to the increasing adoption of electric vehicles and the expansion of renewable energy storage solutions. The shift towards sustainable energy sources drives investments in larger battery capacities, enhancing the necessity for efficient management systems. This segment is projected to reach USD 1,096.3 million by 2033.
Technological advancements in battery technologies, particularly lithium-ion chemistries, support the development of more efficient and reliable systems tailored for this capacity range. The integration of advanced monitoring and control features optimizes performance, resulting in significant operational benefits for end-users. Increasing regulatory compliance regarding emissions and energy efficiency influences the demand for robust battery management systems.
In the context of application, passenger cars and stationary energy storage systems represent major end-users leveraging this segment. The growing trend of electrification in transportation and energy sectors accelerates the uptake of larger battery systems, thereby boosting the high voltage battery management system market. Strategic investments and collaborations among key players in the industry contribute to an increasingly competitive landscape, ensuring ongoing innovation and market penetration.
Growing adoption of high voltage battery management systems for applications requiring extensive energy storage drives expansion in the market. The increasing need for efficient energy management solutions across sectors including electric vehicles and renewable energy storage significantly influences this trend. High voltage battery systems, particularly those exceeding 300 kWh, support high-performance applications, enhancing their attractiveness to manufacturers and users.
Projected growth in this sub-segment stands at a CAGR of 11.7% during the forecast period. This strong growth reflects the demand from sectors prioritizing high-capacity energy solutions, particularly in electric buses and commercial vehicles. Enhanced performance, improved efficiency, and the ability to manage larger battery packs are critical factors for stakeholders in the High Voltage (HV) Battery Management System (BMS) market.
Investment in next-generation technologies and innovations aligns with the increasing capacity requirements. Manufacturers focus on developing advanced battery technologies and management systems that ensure optimal performance and longevity, addressing consumer expectations for reliability and efficiency. While industries shift towards electrification, these advancements play a crucial role in shaping the market for high voltage battery solutions.
By 2033, the market value for systems in the >300 kWh sub-segment is expected to reach USD 1,096.3 million. This valuation highlights the financial opportunities tied to the expanding adoption of high-capacity energy storage solutions across various sectors. The shift towards sustainability and electrification further emphasizes this sub-segment's significance in the overall high voltage battery management ecosystem.
Lithium Iron Phosphate (LFP) segment is valued at USD 2,207.8 million in 2026 and is projected to reach USD 4,733.4 million by 2033, at a CAGR of 11.5% during the forecast period. Increasing adoption of LFP batteries results from their safety, long cycle life, and cost-effectiveness, making them suitable for various applications, including electric vehicles and energy storage systems. Robust demand arises from the rising need for sustainable energy solutions and the growing focus on reducing carbon emissions.
Technological advancements have led to improvements in LFP battery performance, enhancing energy density and charging speeds. Innovations in manufacturing processes contribute to reduced costs, facilitating broader market adoption. Regulatory frameworks promoting electric vehicles and renewable energy sources support the growth of the High Voltage (HV) Battery Management System (BMS) market, particularly for LFP batteries.
The segment benefits from a diverse range of applications, particularly in passenger cars, where demand for electric vehicles continues to rise. Consumption shifts towards sustainable energy solutions influence manufacturers to invest in LFP technology, positioning it favorably for the future. Pricing stability in raw materials and improved supply chain resilience strengthen the segment's outlook.
Strategic opportunity windows appear for companies to enhance product offerings and expand into new markets. While the LFP segment of the market evolves, ongoing investments in research and development will likely lead to next-generation upgrades and product evolution, reinforcing its position in the High Voltage (HV) Battery Management System (BMS) market.
In the High Voltage (HV) Battery Management System (BMS) market, the Lithium Nickel Manganese Cobalt Oxide (NMC) segment attracts significant attention owing to its favorable performance characteristics and increasing adoption in various applications. This segment is estimated to reach USD 3,313.4 million by 2033, at a CAGR of 7.6% during the forecast period. Primary demand drivers include the growing need for high energy density and improved thermal stability in battery systems, which directly enhances the performance and safety of electric vehicles and stationary storage solutions.
Technological maturation plays a critical role in the expansion of this segment, with advancements in battery chemistry and manufacturing processes leading to improved efficiency and reduced costs. Next-generation upgrades focus on enhancing the lifecycle and performance metrics of NMC batteries, enabling greater market acceptance. The ongoing evolution of products, combined with shifts in consumption patterns towards sustainable energy solutions, positions the NMC segment because a strong player in the market.
Regulatory compliance standards increasingly emphasize the importance of safety and environmental considerations, driving manufacturers to invest in NMC technology. This adherence aligns with consumer preferences for greener solutions, creating a positive outlook for market growth. Pricing volatility and margin pressures remain challenges for manufacturers, influenced by the fluctuating costs of raw materials, particularly cobalt and nickel. Supply chain resilience and strategic opportunity windows become essential factors in maintaining competitive advantage, because companies navigate potential substitution risks from alternative battery chemistries.
Overall, the Lithium Nickel Manganese Cobalt Oxide (NMC) segment within the High Voltage (HV) Battery Management System (BMS) market demonstrates robust potential for growth, driven by technological advancements, regulatory shifts, and increased demand for efficient energy storage solutions.
Adoption of Lithium Nickel Cobalt Aluminium Oxide (NCA) in the High Voltage (HV) Battery Management System (BMS) market results from its favorable characteristics, including high energy density and thermal stability. These attributes appeal to manufacturers focused on improving performance in electric vehicles and stationary energy storage systems. Growing regulatory pressures for sustainable solutions drive the shift towards NCA technology, aligning with increasing demand for eco-friendly battery types.
The segment is valued at USD 568 million by 2033, reflecting strong growth potential. Technological maturation and ongoing advancements in battery design enhance the viability of NCA cells, leading to essential upgrades in existing product lines. The economic landscape supports investment in next-generation battery chemistries, enabling players to expand their market presence effectively.
Consumer preferences increasingly shift towards high-performance batteries that provide longer ranges and faster charging times. NCA's capabilities in delivering these benefits secure a competitive edge among battery types. End-use applications, particularly in electric passenger cars and commercial vehicles, drive demand for this technology.
Despite market challenges including raw material sourcing and pricing volatility, strategic opportunity windows continue to emerge. Capital investment in innovation and supply chain resilience strengthens the segment's position, supporting continuous growth in the High Voltage (HV) Battery Management System (BMS) market.
Significant growth in the Lithium Titanate Oxide (LTO) segment of the High Voltage (HV) Battery Management System (BMS) market stems from increasing demand for rapid charging and long cycle life applications. LTO batteries exhibit fast charge and discharge capabilities, making them ideal for electric vehicles, grid energy storage, and various industrial applications. This characteristic attracts end-users seeking efficient and reliable energy solutions.
Valued at USD 2,207.8 million in 2026, the LTO segment is projected to grow at a CAGR of 11.7% during the forecast period. The ongoing technological maturation of Lithium Titanate Oxide chemistry continues to enhance performance metrics, leading to wider adoption in critical applications including public transportation and emergency backup systems. This expansion is supported by increasing regulatory focus on energy efficiency and sustainability, reflecting global efforts toward reducing carbon emissions.
Investment in LTO technology drives product evolution, with manufacturers focusing on improving energy density and reducing costs. The segment's resilience in supply chains secures access to raw materials and mitigates risks associated with component shortages. Strategic opportunity windows emerge for companies innovating in LTO battery systems, particularly in markets prioritizing clean energy technology and progressive transportation initiatives.
Emerging chemistries including Lithium Manganese Oxide, Sodium-Ion, and Solid-State technology present significant potential within the High Voltage (HV) Battery Management System (BMS) market. Primary demand drivers for this segment stem from the need for improved energy density and safety, appealing to manufacturers focused on next-generation battery solutions. Adoption of these technologies is fueled by innovations that enhance performance, reliability, and environmental sustainability, aligning with increasing regulatory pressures emphasizing lower emissions and sustainable practices.
Advancements in material science and manufacturing processes contribute to the viability of these alternative chemistries. Growth in electric vehicle production and stationary energy storage applications exemplifies downstream demand dynamics, driving interest in diverse battery types that fulfill specific operational requirements. Consumption shifts towards more sustainable options prompt manufacturers to explore these emerging technologies, reflecting changing consumer preferences for greener energy solutions.
Regulatory compliance standards, including safety certifications and performance benchmarks, shape the strategic landscape for players investing in these chemistries. Cost structures influence pricing strategies, creating pressures that impact overall market dynamics. Supply chain resilience becomes increasingly critical, with raw material sourcing and logistics vulnerabilities for these technologies warranting attention, especially regarding their sustainability and availability.
Technological obsolescence poses a challenge, urging developers to innovate continuously and stay ahead of disruptive alternatives. Strategic opportunity windows arise from increased investment in research and development, enabling breakthroughs that enhance the competitive positioning of emerging chemistries. The landscape within the High Voltage (HV) Battery Management System (BMS) market continues to evolve, with significant potential for players who adapt to these shifts and capitalize on new advancements.
Valued at USD 3,041.4 million in 2026, the 400-600V segment is projected to reach USD 5,159.4 million by 2033, at a CAGR of 7.8% during the forecast period. Demand drivers for this segment primarily include the increasing popularity of electric vehicles (EVs) and the growing need for efficient energy management systems in various applications. Adoption of advanced battery technologies, coupled with regulatory support for cleaner transportation solutions, enhances the growth prospects within the segment.
Technological maturation in battery management systems significantly influences the 400-600V segment, with innovations aimed at improving energy density, thermal management, and charge cycles. Next-generation upgrades, driven by the quest for higher efficiency and performance, motivate manufacturers to invest in advanced research and development initiatives. Evolving product evolution enhances competitiveness among suppliers, leading to improved offerings that meet diverse consumer needs.
Downstream applications, particularly in the automotive sector, exhibit a marked shift toward high voltage systems. Growth in passenger cars, buses, and commercial vehicles calls for robust battery management systems capable of operating efficiently at voltages within this range. Regulatory compliance standards focused on emissions reduction further accelerate investments in the segment, creating a favorable environment for growth.
Cost structures within the segment are influenced by raw material sourcing and pricing volatility, particularly for critical components used in high voltage battery systems. Strategic opportunity windows emerge because manufacturers seek to mitigate supply chain vulnerabilities and explore sustainable alternatives. This dynamic encourages investment in new technologies, enhancing supply chain resilience and positioning companies to capitalize on disruptive alternatives that arise in the future.
The High Voltage (HV) Battery Management System (BMS) market reflects an evolving landscape, with the 400-600V segment poised for substantial expansion. Continued innovation and strategic investments are essential for stakeholders to navigate challenges and maximize growth potential in this competitive environment.
Expansion in the >600V segment reflects the increasing focus on high-performance applications that require enhanced energy efficiency and power output. This segment aligns with the rising demand for electric vehicles and renewable energy systems, driving the need for advanced battery management solutions. Regulatory requirements concerning emissions and energy efficiency drive investments in high voltage technologies, particularly in markets including automotive and industrial applications. Significant advancements in battery technology, particularly in terms of charging speeds and lifespan, further support this shift toward higher voltage systems.
Growing adoption of high voltage systems facilitates the integration of next-generation battery chemistries, leading to improved performance metrics. The segment is expected to reach USD 4,307.4 million by 2033, at a CAGR of 12.5% during the forecast period. Increased focus on cost efficiency and sustainability among manufacturers influences pricing strategies, making higher voltage solutions more competitive. Overall, the >600V segment shapes the future of the High Voltage (HV) Battery Management System (BMS) market.
Valued at USD 3,492.1 million in 2026, this segment is projected to reach USD 6,252.8 million by 2033, reflecting a CAGR of 8.7% during the forecast period. Increased demand for electric vehicles drives the growth of the Passenger Cars segment within the High Voltage (HV) Battery Management System (BMS) market. The transition towards sustainable transportation solutions, coupled with stringent regulatory frameworks aimed at reducing emissions, encourages manufacturers to invest in advanced battery technologies.
Technological advancements enhance battery performance and efficiency, encouraging automakers to integrate high voltage battery management systems in new models. This integration supports longer ranges and faster charging times, aligning with consumer expectations for convenience and sustainability. The competitive environment encourages continuous innovation, with manufacturers striving to develop next-generation batteries that offer improved performance and reduced costs.
Regulatory compliance influences product development. Governments implement stricter emissions standards, prompting automakers to prioritize adopting battery management systems that optimize performance and energy efficiency. This focus on compliance creates a market environment conducive to growth and investment. Fluctuations in raw material prices impact production costs, influencing pricing strategies and market dynamics.
Overall, the Passenger Cars segment within the market demonstrates significant growth potential fueled by evolving consumer preferences, regulatory pressures, and technological advancements. Strategic investments in research and development are expected to lead to innovations that enhance system capabilities and performance, reinforcing the segment's importance in the broader context of sustainable automotive solutions.
Market dynamics indicate strong demand growth in the Buses segment of the High Voltage (HV) Battery Management System (BMS) market, driven by increasing investments in public transportation electrification and environmental sustainability initiatives. Regulatory frameworks promoting electric bus adoption enhance operational efficiency and reduce emissions, aligning with global decarbonization goals. Significant technological maturation of battery management systems improves operational capabilities and safety, influencing transit agencies to upgrade existing fleets.
Investment in charging infrastructure, alongside advancements in battery technologies, facilitates the transition towards electric buses, enhancing their viability in urban environments. The segment is projected to reach USD 1,109.5 million by 2033, at a CAGR of 11.7% during the forecast period. This growth trajectory reflects expanding consumer preference for sustainable transportation solutions and increased governmental support for electric vehicle initiatives.
Financial considerations play a crucial role, with operational cost savings associated with electric buses attracting investments. Enhanced performance capabilities of battery management systems contribute to extended vehicle lifespans and reduced maintenance costs, offering strategic advantages to fleet operators. The market positions itself to benefit from evolving consumption patterns in urban mobility, further strengthening the role of high voltage battery management systems in shaping the future of public transport.
Growing interest in electric trucks drives demand for high voltage battery management systems. Increasing regulatory support for emissions reduction and sustainability initiatives fuels this trend. Truck manufacturers implement advanced battery management technologies to enhance energy efficiency and optimize vehicle performance. These systems improve battery life, monitor performance, and ensure safe operation under varying conditions, attracting investment in the segment. By 2033, the trucks segment is projected to reach USD 961.8 million, reflecting ongoing innovations and a shift towards electric mobility.
Increased reliance on renewable energy sources drives demand for energy storage solutions, particularly in the context of stationary energy storage systems. These systems provide the necessary support for balancing energy supply and demand, improving grid stability, and enhancing energy efficiency. Regulatory frameworks promoting renewable integration further support the growth of these systems, creating a favorable environment for investment and innovation. The Stationary Energy Storage Systems segment is projected to grow at a CAGR of 13.7% during the forecast period.
Market participants respond to rising consumer interest in sustainability through the development of advanced technologies that improve energy storage efficiency and reduce costs. Innovations in battery technologies, including the integration of more efficient chemistries, enhance performance and longevity. This advancement ensures that stationary energy storage systems meet the growing demands of various applications, including residential, commercial, and industrial sectors.
Increased capital investments in renewable energy projects contribute to the expansion of the market. Companies involved in energy production and distribution recognize the strategic importance of stationary energy storage systems in optimizing their operations and enhancing service delivery. The market for high voltage battery management systems benefits from ongoing technological advancements and shifts in consumption patterns driven by industries adapting to new energy paradigms.
Expanding applications of high voltage battery management systems in electric vans, off-highway vehicles, marine, rail, and specialty vehicles indicate a diversification of demand drivers. The shift towards sustainable transportation and energy solutions fuels interest in these vehicles, particularly driven by regulatory frameworks that increasingly support electrification initiatives. This trend aligns with broader market dynamics, where manufacturers seek to enhance energy efficiency and reduce emissions.
Technological advancements play a significant role in this segment, contributing to improved battery performance and management capabilities. Innovations in battery chemistry and thermal management systems enhance operational efficiency, addressing specific requirements of various applications. These upgrades support the proliferation of high voltage systems in niche markets, allowing original equipment manufacturers to leverage emerging technologies to meet evolving consumer preferences.
Adoption trends highlight a growing inclination towards electric and hybrid solutions among fleet operators and transport services. The pursuit of cost-effective alternatives to traditional fossil fuel-powered vehicles drives investments in electric vehicles across multiple sectors, impacting market development. Consumption patterns shift towards electrification, influenced by increases in fuel prices and the need for lower operational costs.
Regulatory compliance standards further shape the landscape, because many regions implement stricter emissions regulations, compelling industries to transition to cleaner technologies. While governments renew commitments to carbon neutrality and sustainable practices, the market for high voltage battery management systems sees enhanced support through incentives and grants aimed at promoting electrification.
Strategic opportunity windows emerge, particularly in markets with growing infrastructure for electric vehicle charging and support. This environment encourages investment in research and development, driving innovation within the segment. Capital investment outlooks reflect confidence in the potential growth of electric vehicles, signaling a promising future for the high voltage battery management system market in this application segment.
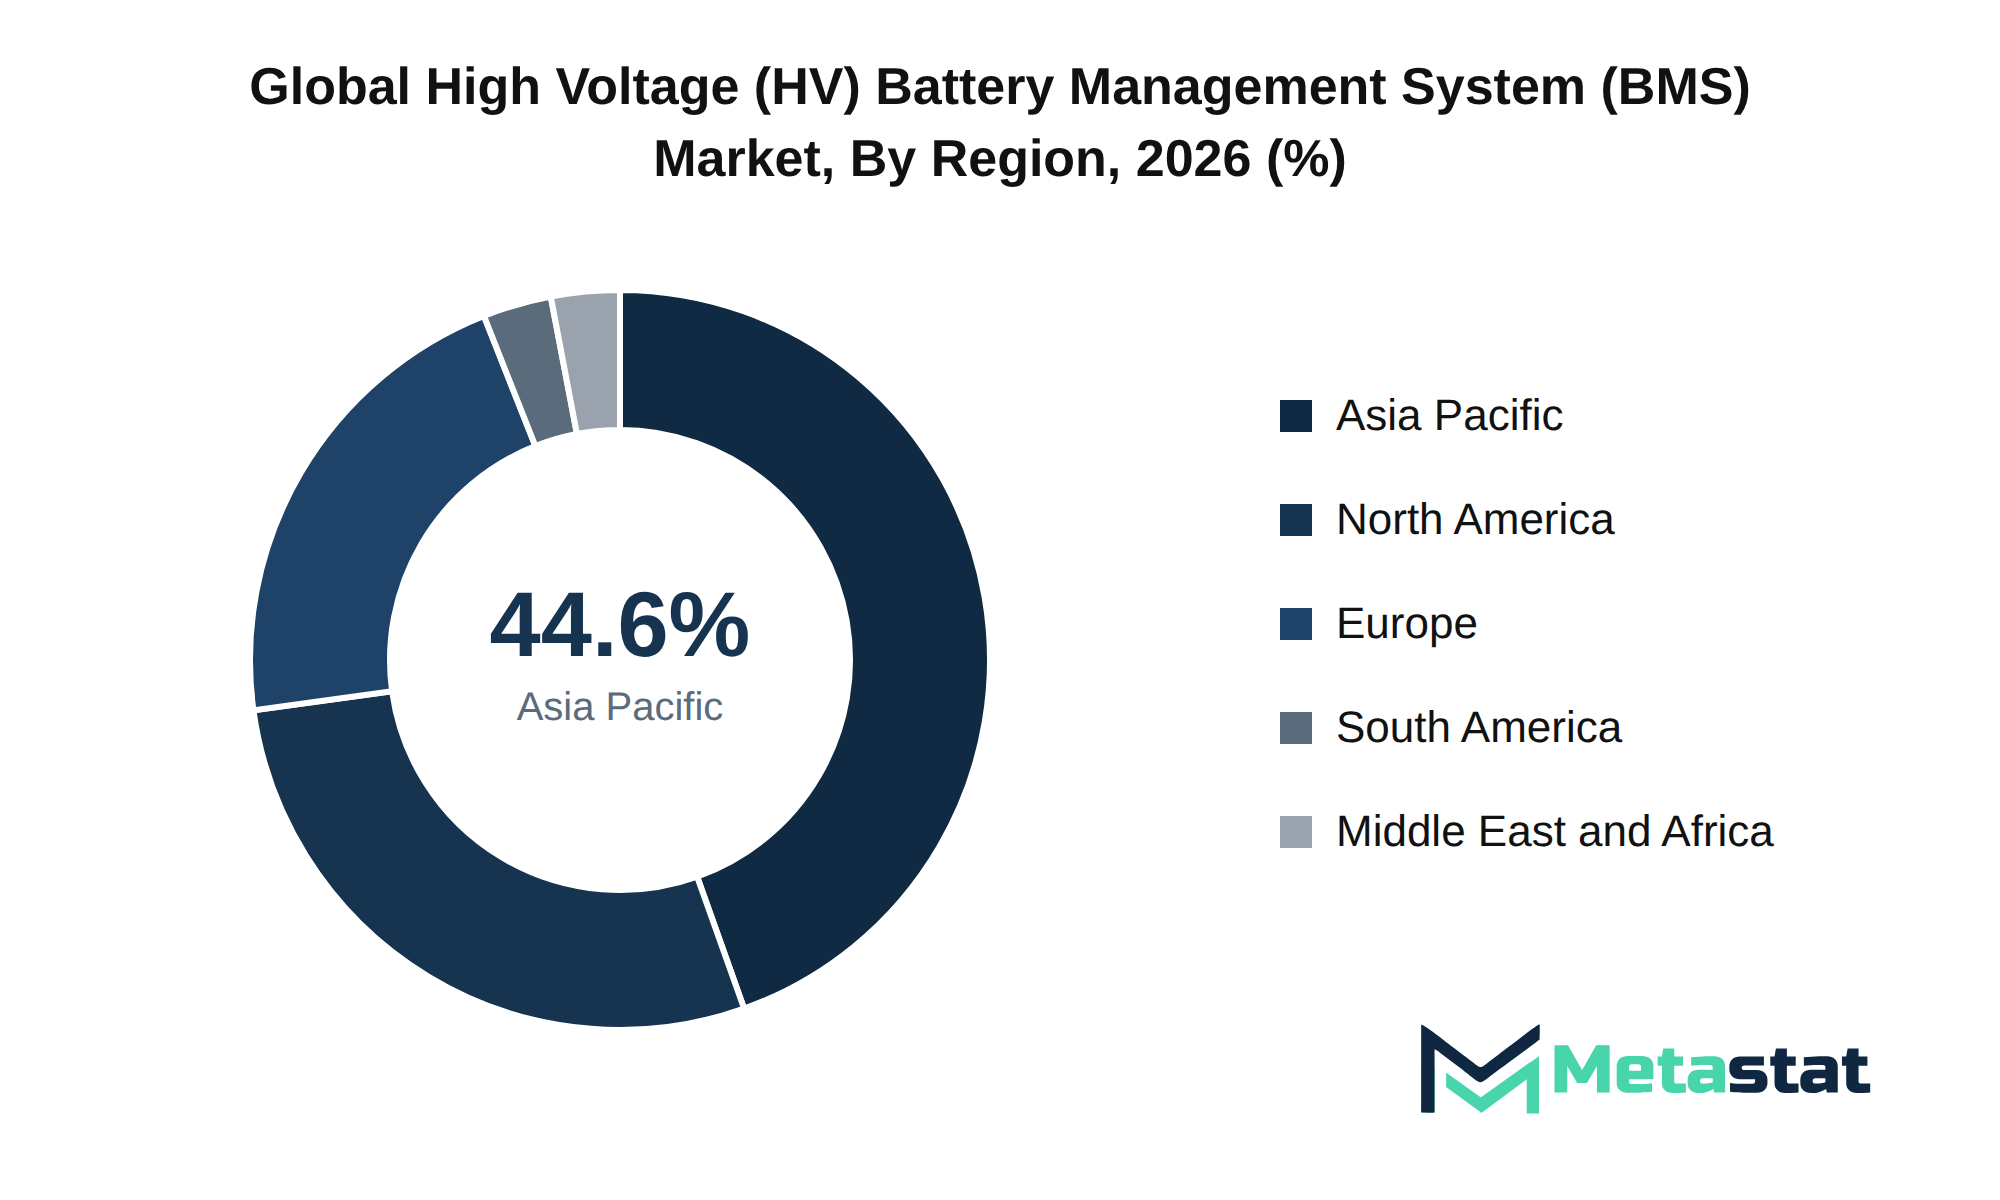
Based on geography, the Global High Voltage (HV) Battery Management System (BMS) market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America represents a significant portion of the High Voltage (HV) Battery Management System (BMS) market, holding a share of 28.3% in 2025. This region is set to expand at a CAGR of 9.8% within the forecast period, reaching a market size of USD 2,451.9 million by the end of 2033. Key demand drivers include the increasing adoption of electric vehicles (EVs) and the enhancement of battery technologies, particularly among manufacturers in the United States, Canada, and Mexico.
Infrastructure modernization supports the growth of the market, with investments aimed at improving energy grid resiliency and local infrastructure readiness. Regional competitive landscapes feature established domestic vendors including Infineon Technologies AG, NXP Semiconductors, and Texas Instruments, which are strategically positioned to capitalize on expanding market opportunities.
Localized procurement dynamics contribute to the market's growth, with a focus on nearshoring initiatives and regionalization of supply chains. The presence of high-value replacement cycles further influences adoption rates, driven by businesses seeking to upgrade aging battery management systems to meet evolving energy demands. The overall outlook for the North American market is strong, supported by incremental growth vectors and increasing stakeholder investment in advanced battery management solutions.
Europe's position in the High Voltage (HV) Battery Management System (BMS) market reflects a share of 21.2% in 2025. Countries including Germany, France, the UK, Italy, Spain, and Russia contribute to this robust market presence. The region's growth is fueled by increasing investments in electric vehicle (EV) infrastructure, including charging stations and grid enhancements, which facilitate the adoption of high voltage battery systems across various applications.
Strategic initiatives emphasize sustainability and environmental regulations, prompting European manufacturers to invest in localized production capabilities. This trend includes increased focus on domestic supply chains, which enhances resilience against global disruptions. Such investments contribute to the emergence of localized players alongside established international firms, creating a competitive landscape with diverse offerings.
Market analysis indicates a strong inclination towards passenger vehicles, which dominate the EV segment. This trend drives demand for advanced battery management solutions that ensure efficient energy usage and safety. In addition, buses and stationary energy storage systems present considerable growth opportunities, reflecting the region's commitment to reducing carbon footprints.
Projected growth rates for the market highlight the importance of ongoing investments in technology and infrastructure. A collaborative approach among regional stakeholders, including manufacturers and government entities, supports a favorable environment for innovation and market expansion. These factors collectively position Europe because an important player in the global high voltage BMS landscape.
Asia Pacific represents a significant region in the High Voltage (HV) Battery Management System (BMS) market, with a share of 44.6% projected for 2025. Strong demand arises from countries including China, Japan, India, South Korea, and Australia, where rapid advances in electric vehicle technology and increasing infrastructure investments are evident. The region experiences substantial growth driven by rising urbanization and the push for sustainable energy solutions, leading to heightened adoption of high voltage battery systems.
Infrastructure modernization plays an important role in shaping market dynamics, with significant investments directed toward upgrading energy grids and expanding charging networks. This transformation creates an environment conducive to the proliferation of high voltage battery technologies, particularly in passenger cars and stationary energy storage applications. Emerging market front-runners including China leverage their manufacturing capabilities to lead in production and innovation, positioning themselves strategically within the global market.
Localized procurement dynamics reflect the unique buying behaviors observed in the region, where cultural nuances influence purchasing decisions. Regional supply chain shifts toward nearshoring initiatives enhance operational efficiencies, allowing companies to respond swiftly to market demands. Domestic market participants, including major battery manufacturers and technology providers, contribute to competitive landscapes characterized by innovation and collaboration.
Investment in foreign direct investments (FDI) flows toward Asia Pacific illustrates the attractiveness of the market for global players. Cross-border trade corridors further facilitate the movement of goods and services, enhancing market accessibility. Geographic regulatory frameworks and local compliance mandates significantly dictate the operational landscape, emphasizing the importance of adherence to regional standards.
In South America, the High Voltage (HV) Battery Management System (BMS) market represents a relatively small share, accounting for 3.00% of the global market in 2025. Key players including Brazil and Argentina drive regional dynamics, influenced by rising demand for electric vehicles and energy storage solutions.
Infrastructure modernization presents opportunities for growth, particularly in urban centers where electric mobility gains traction. Regional supply chain challenges and localized manufacturing densities impact the market's growth trajectory. Domestic market participants focus on enhancing production capabilities while navigating the complexities of cross-border trade corridors.
Investment in renewable energy projects contributes positively to market expansion, driven by government incentives and a shift towards sustainable practices. Local compliance mandates and regulatory frameworks play critical roles in shaping strategic decisions for market participants, affecting both procurement strategies and product offerings.
Emerging trends highlight the importance of localized procurement dynamics, emphasizing the need for suppliers to adapt to cultural nuances and regional B2B buying behaviors. This strategic alignment strengthens relationships with buyers, enhancing competitive positioning within the market.
The Middle East and Africa represent a developing territory within the High Voltage (HV) Battery Management System (BMS) market, with a projected share of 3.00% in 2025. Investment in renewable energy infrastructure and energy storage solutions drives interest in high voltage systems, particularly in countries including Saudi Arabia and the UAE. An expanding electric vehicle sector, alongside government initiatives to reduce carbon emissions, supports the adoption of advanced battery management systems.
Infrastructure modernization remains critical for enhancing market penetration. Local compliance mandates and regulatory frameworks encourage investment in localized manufacturing and sourcing, reflecting a trend towards supply chain regionalization. South Africa's growing market presence highlights the importance of cultural nuances and regional B2B buying behaviors, which influence procurement dynamics.
Foreign direct investment flows into the region indicate confidence in future growth potential, with geopolitical stability influencing strategic entry barriers. The competitive landscape features both domestic market participants and international players, offering a diverse range of products tailored to local needs. Overall, the region presents significant opportunities for expansion within the market, driven by incremental growth vectors and a focus on high-value replacement cycles.
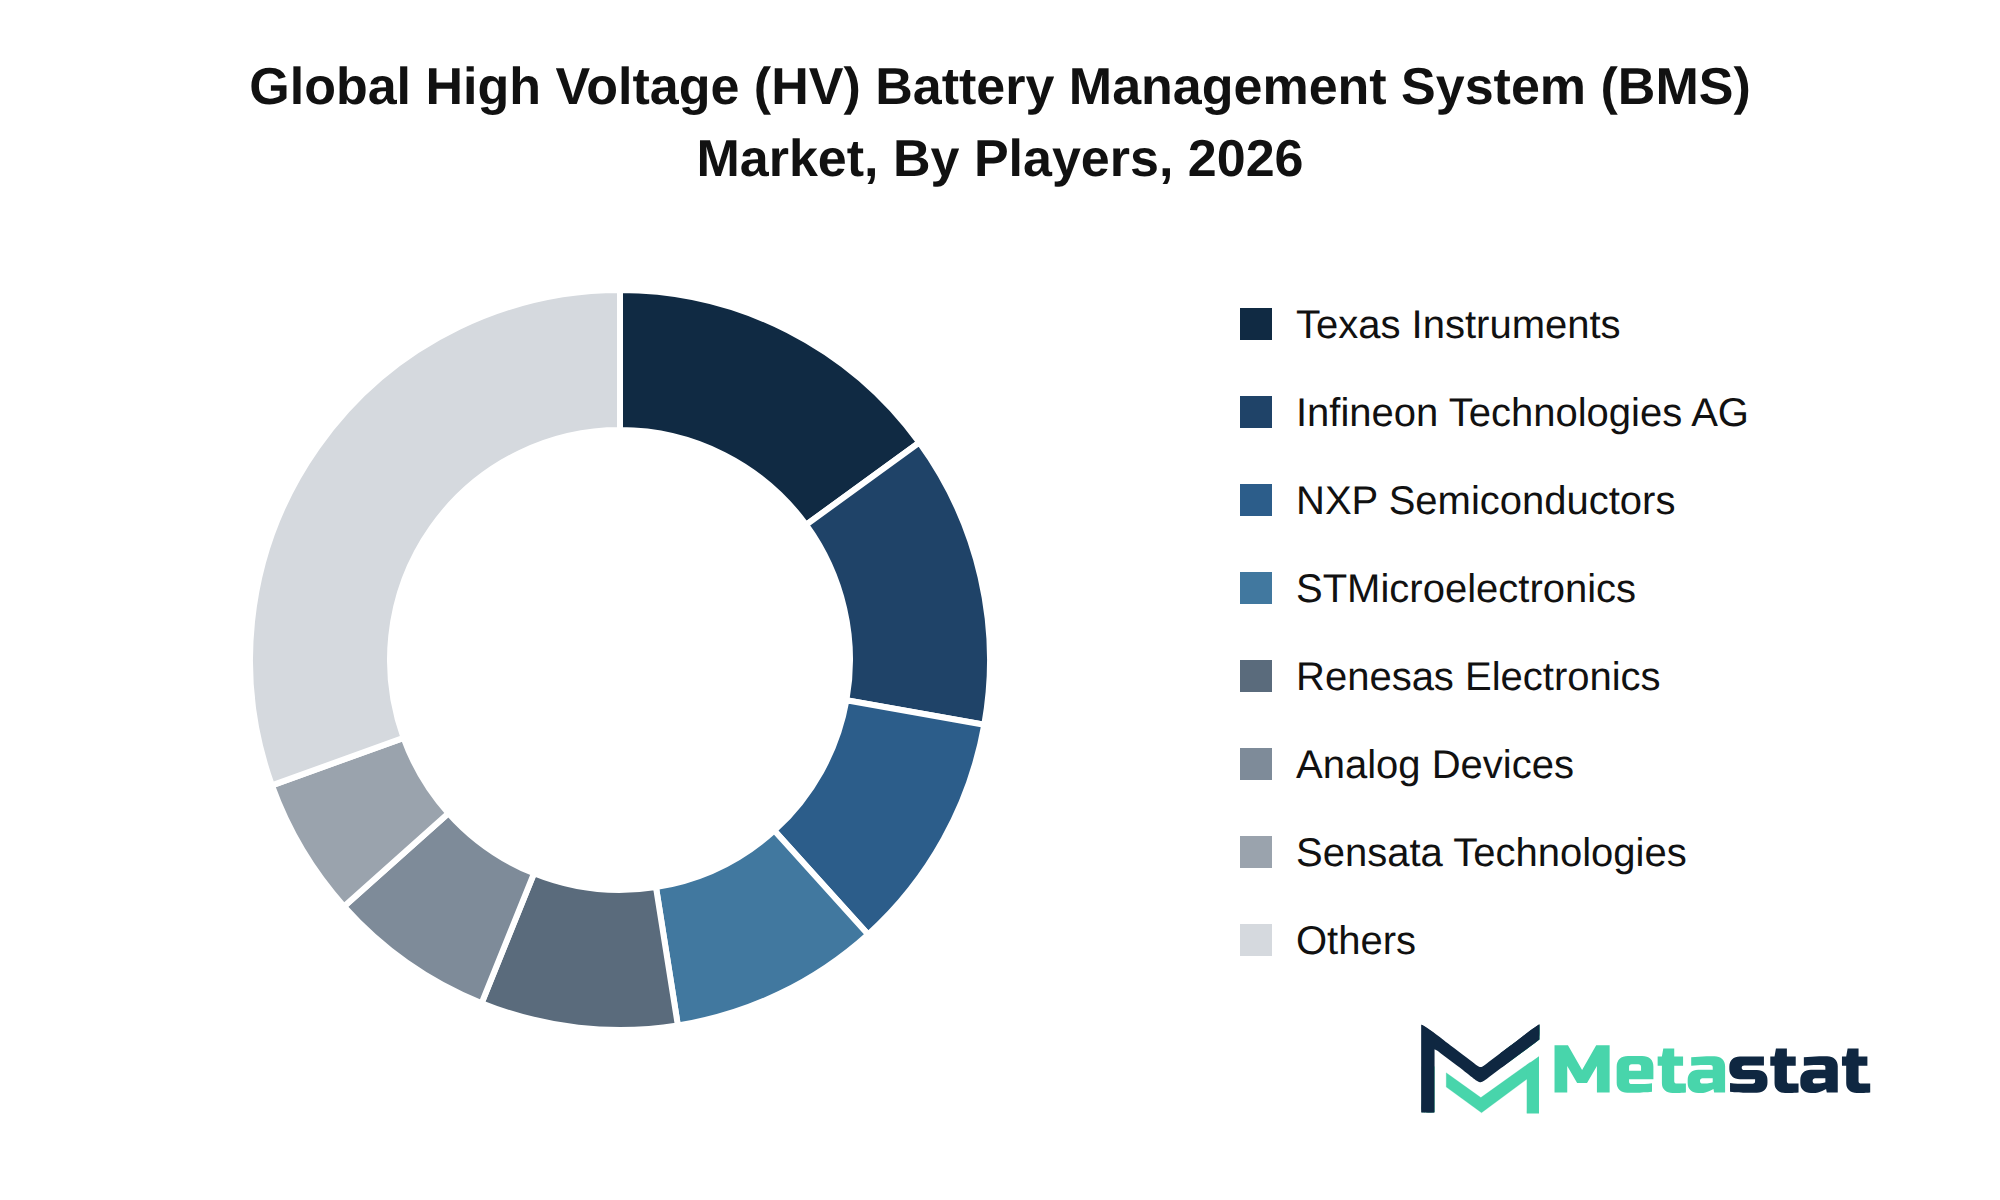
The High Voltage (HV) Battery Management System (BMS) market displays a dynamic competitive environment characterized by mergers and acquisitions, strategic alliances, and product differentiation. Companies including Infineon Technologies AG, NXP Semiconductors, and Texas Instruments engage in strategic consolidation to enhance their market presence and research and development capabilities. Collaborative efforts and joint ventures facilitate innovation, enabling participants to develop proprietary technologies and strengthen their product offerings.
Strategic growth vectors focus on value chain integration and supply chain dominance. Major players like Tesla and BYD Company Ltd. leverage strong brand equity to retain customers and mitigate switching costs. Competitive positioning is further reinforced through robust intellectual property portfolios that enhance technological defensibility. The future competitive outlook for the HV BMS market indicates an intensified focus on customer retention strategies and ongoing innovation to sustain market leadership.
Market size is forecast to rise from USD 4,479.7 million in 2025 to over USD 9,466.8 million by 2033. The base case reflects a growth trajectory from USD 4,479.7 million in 2025 to USD 9,466.8 million by 2033 at a 9.8% CAGR. Downstream demand remains influenced by several macroeconomic factors, including shifts in consumer preferences toward sustainable technologies and regulatory evolutions promoting electric vehicle adoption.
Future industry maturation relies on the integration of next-generation technologies, enhancing the performance and efficiency of High Voltage (HV) Battery Management System (BMS) market solutions. Continued investments in research and development will accelerate commercialization timelines, driving product life cycles and extending the market's appeal.
Geopolitical realignments and evolving trade corridors impact global supply chains, necessitating strategic capital allocation to support infrastructure commitments. Emerging white-space opportunities within the market arise from unmet enterprise needs, creating high-growth pockets for innovative solutions.
Executive-level strategic imperatives play a critical role in shaping corporate investment directives. Companies prioritize defensibility roadmaps and future growth recommendations to secure competitive advantages in a changing environment.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the High Voltage (HV) Battery Management System (BMS) market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 9.8% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Battery Capacity, Battery Type, Voltage, Application, and Region |
By Region | North America (By Battery Capacity, Battery Type, Voltage, Application, and Country)
|
Europe (By Battery Capacity, Battery Type, Voltage, Application, and Country)
| |
Asia Pacific (By Battery Capacity, Battery Type, Voltage, Application, and Country)
| |
South America (By Battery Capacity, Battery Type, Voltage, Application, and Country)
| |
Middle East and Africa (By Battery Capacity, Battery Type, Voltage, Application, and Country)
|
Find answers to common questions about this report
The High Voltage (HV) Battery Management System (BMS) market size was valued at USD 4,479.7 million in 2025, according to the Metastat Insights study.
The High Voltage (HV) Battery Management System (BMS) market is projected to grow at a CAGR of 9.8% during the forecast period from 2026 to 2033.
The North America High Voltage (HV) Battery Management System (BMS) market size is estimated to reach USD 2,451.9 million by 2033.
The Battery Type segment leads the High Voltage (HV) Battery Management System (BMS) market, with Lithium Iron Phosphate (LFP) projected to reach USD 4,733.4 million by 2033. This figure surpasses other battery types, indicating strong demand in this category.
Key drivers for the High Voltage (HV) Battery Management System (BMS) market include increased capital investment across sectors, particularly in automotive and energy storage, which supports the development and adoption of advanced battery technologies. The focus on operational productivity, cost efficiency, and sustainability enhances demand for sophisticated battery management solutions.
Asia Pacific holds the dominant share of the High Voltage (HV) Battery Management System (BMS) market, accounting for 44.6% of the total market. This region is projected to reach significant value by 2033, driven by increasing demand in various applications.
High capital investment requirements and infrastructure gaps significantly restrain the High Voltage (HV) Battery Management System (BMS) market growth. The financial burden creates barriers for new entrants and delays project timelines, while insufficient charging infrastructure limits the adoption of electric vehicles and energy storage systems. These factors hinder investment returns and affect the overall market trajectory.
Increased capital investment across various sectors, characterized by favorable interest rates and rising GDP, supports the development and adoption of advanced battery management technologies. the focus on operational productivity and cost-efficiency drives demand for battery management systems, ensuring continued market growth through 2033.
The High Voltage (HV) Battery Management System (BMS) market is estimated to reach a valuation of USD 9,466.8 million by 2033.
Top players operating in the High Voltage (HV) Battery Management System (BMS) market include Infineon Technologies AG, NXP Semiconductors, Texas Instruments, STMicroelectronics, Renesas Electronics Corporation, and Analog Devices, Inc.
Choose Your License
Global High Voltage (HV) Battery Management System (BMS) Market
The analysts below cover Automotive and Transportation research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.
Tracking capacity expansion in single-use bioprocessing requires dependable data on raw material availability and cleanroom-grade polymer supply chains. The competitive landscape chapter gave a grounded evaluation of secondary component suppliers across North America and Asia-Pacific rather than simply reprinting press releases. Having that level of supplier benchmarking helped clarify dual-sourcing considerations for our clinical pipeline planning.
When evaluating distributed energy resource management systems, standard research summaries tend to gloss over the operational differences between front-of-the-meter utility deployments and behind-the-meter industrial sites. The MetaStat Insight report addressed those distinctions directly, especially regarding software interoperability standards and grid interconnection backlogs. The five-year market sizing across regional transmission organizations provided actionable context for our grid modernization strategy.
Most industry reports on warehouse automation bundle autonomous mobile robots and fixed conveyor installations into the same top-level numbers, which complicates advisory work. This study split the market cleanly by payload tiers, navigation technology, and fleet management software layers. The regional forecast for Western Europe gave our team defensible adoption benchmarks when evaluating capital allocation for logistics clients, saving us days of secondary data scrubbing.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950