
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Industrial and Logistics Real Estate Market Size, Share, By Property Type (Warehouses and Distribution Centers, Manufacturing and Production Facilities, Cold Storage and Temperature-Controlled Facilities, Flex, R&D and Light Industrial Facilities, Industrial Outdoor Storage and Yard Facilities, Others (Cleanrooms, Hazardous-Material Storage, Aerospace-Specialty Facilities)), By Ownership (Owner-Occupied and Leased), By End-Use Industry (E-commerce, Third-Party Logistics, Freight and Express, Retail and Consumer Goods, Automotive and Mobility, Food and Beverage, Pharmaceuticals and Healthcare, Electronics and High-Tech, Industrial Manufacturing and Engineering, Renewable Energy and Clean Technology, Others (Aerospace, Chemicals, Textiles)), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5263
September 16, 2026
297 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $579.5 Million in 2025, projected to reach $1,011 Million by 2033 at a 7.2% CAGR.
Dominant Segment: The Warehouses & Distribution Centers segment leads the market, driven by the rise of e-commerce and just-in-time inventory practices. This segment is projected to grow significantly, reflecting the increasing demand for efficient storage solutions.
Geographic Lead: The Asia Pacific region is expected to experience the fastest growth, fueled by rising consumer expectations for rapid delivery and significant investments in logistics infrastructure.
What's Inside: This report provides a comprehensive analysis of the Global Industrial and Logistics Real Estate market, including competitive coverage, market dynamics, and detailed forecasts from 2026 to 2033.
Emerging Demands: The market is expanding due to shifts in regional demands and infrastructure modernization, particularly in response to the growing e-commerce sector and technological advancements in logistics.
Industrial Property Leasing Demand: The resurgence of manufacturing activities is driving demand for industrial property leasing, particularly in sectors like automotive and electronics, which require additional space for production and distribution.
The global Industrial and Logistics Real Estate market was valued at USD 579.5 million in 2025 and is projected to reach USD 1,011 million by 2033, growing at a CAGR of 7.2% over the forecast period.
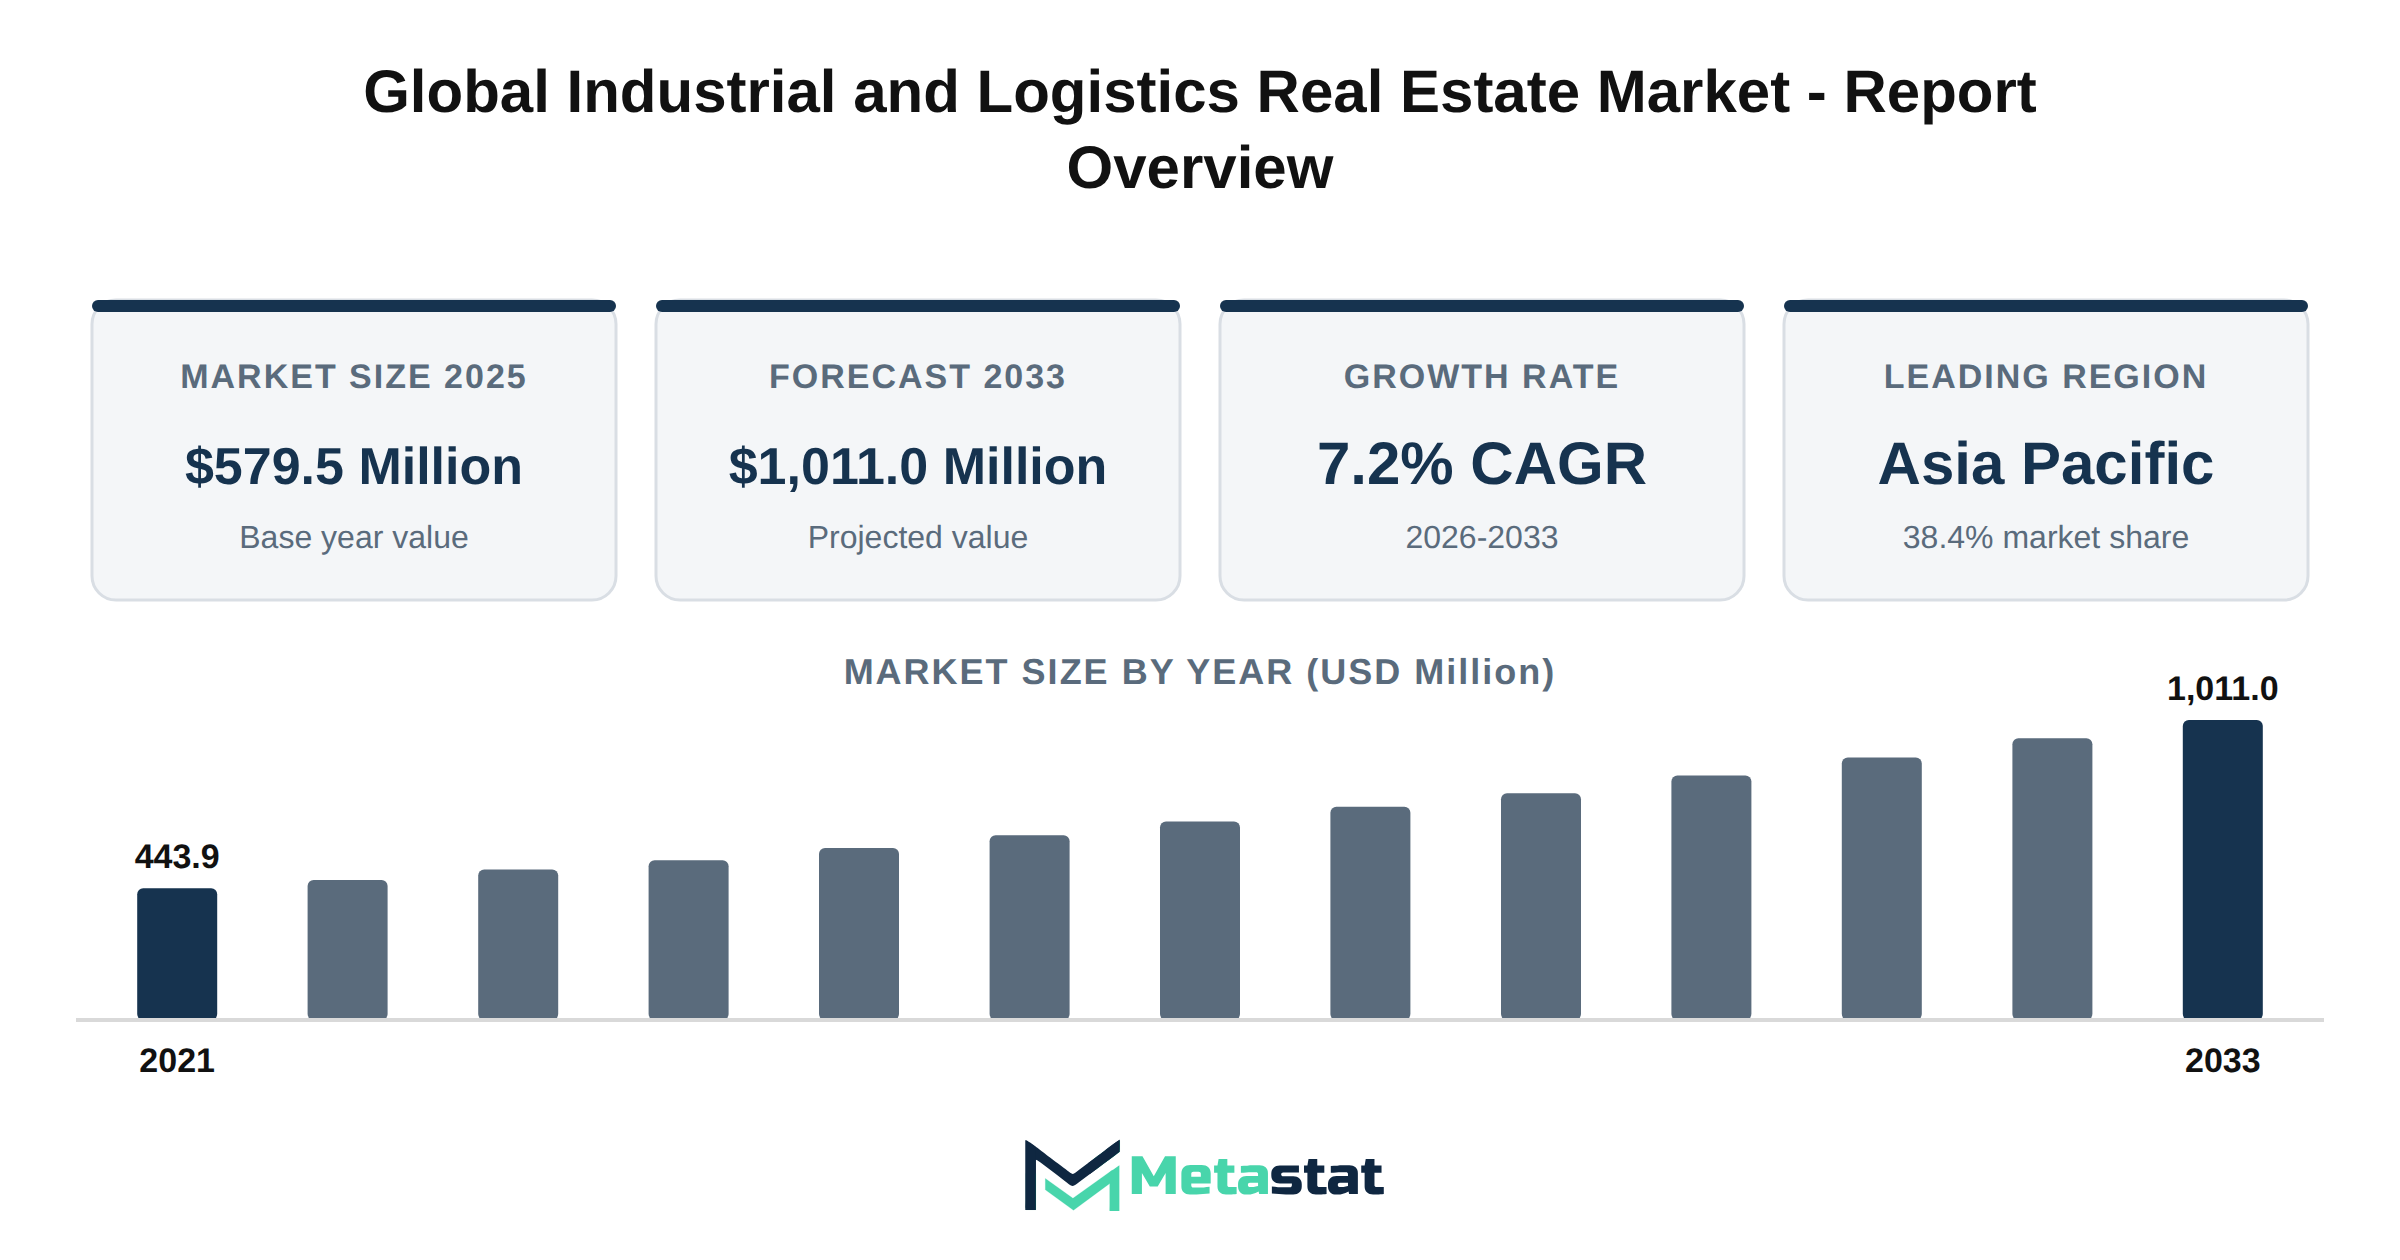
The Industrial and Logistics Real Estate market demonstrates significant growth potential, with a projected market value reaching USD 1,011 million by 2033, up from USD 579.5 million in 2025. An annual growth rate of 7.2 percent highlights the increasing demand for logistics and industrial properties, driven by several key factors reshaping the industry landscape.
The rise of e-commerce and omnichannel retailing fuels demand for logistics spaces, particularly warehouses and distribution centers. Businesses increasingly seek to optimize fulfillment strategies, resulting in heightened requirements for advanced logistics facilities that support rapid order processing and delivery.
Warehouse automation technologies enhance operational efficiency and reduce labor costs. The integration of robotics and automated systems in logistics facilities influences their design and layout, promoting the development of next-generation warehouses equipped to accommodate these innovations.
Growing consumer preferences for fresh and frozen goods contribute to an increase in cold storage facilities. The demand for temperature-controlled real estate expands owing to food and beverage sectors requiring specialized storage solutions to maintain product quality and safety.
Nearshoring and reshoring trends emerge because companies prioritize supply chain resilience. This shift generates new industrial real estate hotspots, particularly in regions closer to end consumers, enhancing logistical efficiency and reducing delivery times.
The demand for last-mile logistics solutions drives urban warehouse development. Proximity to urban centers enables faster delivery times, leading to increased investment in warehouse spaces strategically located to meet consumer needs.
The resurgence of manufacturing activities positively influences industrial property leasing demand. Sectors including automotive and electronics experience growth, necessitating additional space for production and distribution operations.
The expansion of third-party logistics (3PL) providers increases warehouse occupancy rates. Companies increasingly rely on 3PL services to manage inventory and distribution, leading to heightened demand for flexible warehouse spaces capable of accommodating diverse logistics needs.
Rental rates in the Industrial and Logistics Real Estate market exhibit upward trends due to heightened demand for quality spaces. Competitive leasing terms attract businesses seeking to establish or expand their operations within strategically located facilities.
Supply constraints and limited land availability significantly impact warehouse development. Investors and developers face challenges in acquiring suitable sites, which influence the pace of new projects and overall market growth.
Build-to-suit development models gain traction because companies seek tailored solutions that meet specific operational requirements. This approach allows businesses to optimize their logistics capabilities while enhancing efficiency and reducing costs associated with standard properties.
Smart warehouse technologies transform logistics operations, enhancing visibility and control over inventory. The integration of Internet of Things (IoT) devices and data analytics enables real-time decision-making, promoting operational efficiency and reducing errors in warehouse management.
The incorporation of artificial intelligence and robotics into warehouse operations influences design requirements. Facilities increasingly feature layouts optimized for automated workflows, catering to the evolving needs of modern logistics.
E-commerce and omnichannel strategies significantly reshape the Industrial and Logistics Real Estate market. The surge in online shopping demands efficient distribution networks, prompting businesses to invest in strategically located warehouses. This transition enhances the need for flexible spaces that accommodate various logistics operations, driving occupancy rates and rental prices upward.
Warehouse automation enhances the development of next-generation logistics facilities. Advanced technologies streamline operations, reduce labor costs, and improve accuracy in inventory management. This trend attracts significant investment, positioning automated warehouses because essential assets in the market.
Cold storage expansion accelerates demand for temperature-controlled real estate. The growth of online grocery shopping and pharmaceuticals contributes to the rising need for facilities equipped to handle perishable goods. This sector experiences robust investment, further emphasizing its importance within the broader market.
Nearshoring and reshoring initiatives create new hotspots for industrial real estate. Companies relocating production closer to end-users benefit from reduced shipping costs and enhanced supply chain resilience. This shift drives demand for industrial properties in regions that support these operations.
Last-mile logistics demand increases urban warehouse development. The necessity for rapid delivery services drives the need for strategically located facilities within urban areas. This trend presents opportunities for developers focusing on smaller, easily accessible sites that cater to this growing consumer expectation.
Manufacturing expansion supports industrial property leasing demand. Increased production activities across various sectors necessitate additional space, leading to rising occupancy levels. This trend further enhances the attractiveness of industrial real estate investments.
Third-party logistics growth strengthens warehouse occupancy. Many businesses outsource their logistics functions, increasing reliance on third-party providers for efficient supply chain management. This trend increases demand for warehouse spaces, contributing positively to market dynamics.
Industrial real estate rental growth follows leasing trends that reflect a robust demand environment. Rising interest from businesses seeking functional spaces results in upward pressure on rental rates. This dynamic encourages investors to explore opportunities within the market.
Supply constraints and limited land availability shape warehouse development strategies. Developers face challenges in acquiring suitable sites, leading to increased competition for existing properties. This scarcity drives up prices and influences the overall market landscape.
Build-to-suit development gains momentum across industrial real estate. Tailored facilities designed to meet specific tenant needs attract interest from businesses looking for customized solutions. This trend enhances the flexibility and appeal of the market for both developers and tenants.
Smart warehouses transform logistics real estate operations, integrating advanced technologies that enhance efficiency and reduce operational costs. The adoption of IoT devices and data analytics creates opportunities for improved inventory management and real-time decision-making.
AI and robotics integration influences warehouse design requirements. Facilities are increasingly designed to accommodate automated systems, optimizing space and enhancing productivity. This trend reflects the industry's shift toward innovative solutions that support operational efficiency.
Industrial outdoor storage emerges because a high-growth property segment, driven by increasing demand for outdoor space to accommodate various industrial activities. This segment provides flexibility for businesses seeking additional operational areas without the complexities of indoor facilities.
Sustainable warehouses and green building adoption gain traction in logistics real estate. Companies prioritize environmentally friendly practices, pushing developers to incorporate sustainable materials and energy-efficient systems into their projects. This shift aligns with broader corporate sustainability goals, influencing market dynamics.
Renewable energy integration transforms industrial property infrastructure. Facilities equipped with solar panels and energy-efficient systems attract tenants focused on reducing their carbon footprint. This trend enhances the appeal of properties within the market, positioning them favorably for environmentally conscious businesses.
Investment and capital flow trends in the Industrial and Logistics Real Estate market reflect a growing appetite for logistics assets. Institutional investors increasingly seek exposure to this sector, recognizing its potential for stable returns and resilience in fluctuating economic conditions.
Institutional investment in logistics real estate assets continues to rise, driven by favorable market conditions and strong demand. This trend encourages competition among investors, creating a robust investment environment that benefits property owners and developers alike.
Mergers, acquisitions, and portfolio consolidation characterize the industrial real estate landscape. Companies pursue strategic partnerships to enhance operational capabilities and expand market reach. This trend influences competitive dynamics and shapes future growth opportunities within the market.
Supply chain regionalization drives new logistics hub development. Businesses increasingly focus on localizing supply chains to enhance efficiency and responsiveness. This shift results in the emergence of new logistics centers, creating opportunities for developers and investors.
Growth opportunities within the Asia Pacific region present significant potential for the Industrial and Logistics Real Estate market. Rapid urbanization and rising consumer demand drive expansion in logistics infrastructure, positioning the region because a key player in the global market.
North America experiences ongoing warehouse demand and industrial development trends. The region benefits from established logistics networks and a favorable business environment, attracting both domestic and international investment in industrial properties.
Europe faces unique logistics real estate demand and supply dynamics. Regulatory frameworks and varying economic conditions across countries influence investment strategies and property development, presenting both challenges and opportunities for stakeholders in the market.
Emerging markets create new industrial real estate investment opportunities. Economic growth and increasing consumer demand in these regions encourage investment in logistics infrastructure, positioning them because attractive destinations for developers and investors.
Zoning, land-use, and environmental regulations significantly impact industrial development. Compliance with local regulations influences project feasibility and timelines, shaping strategic decisions for developers operating in the market.
Future growth opportunities in the Industrial and Logistics Real Estate market align with evolving consumer preferences and technological advancements. Stakeholders focusing on innovation and adaptability will likely capture emerging trends and sustain competitive advantages.
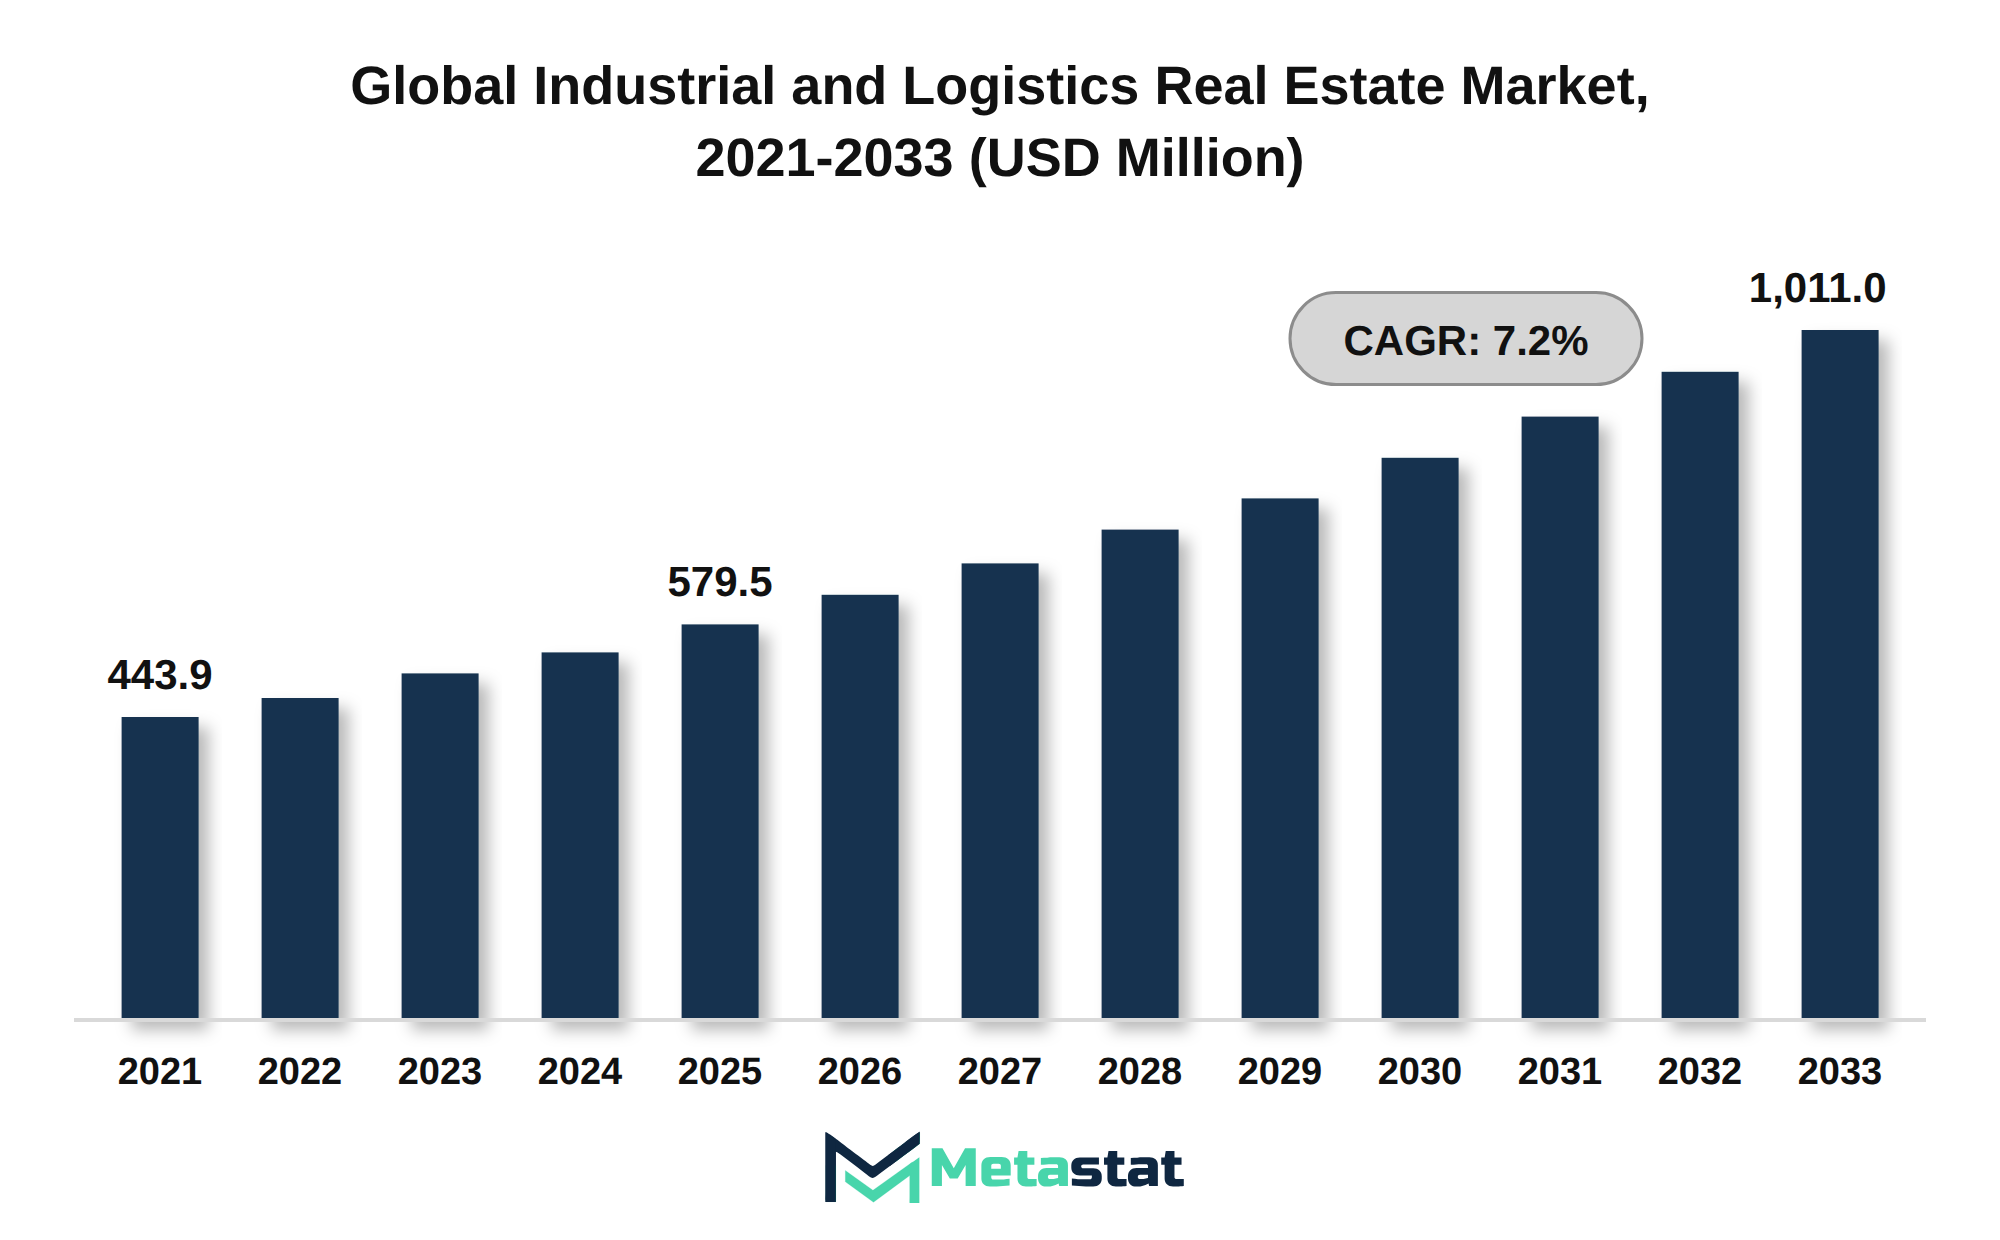
The Industrial and Logistics Real Estate market benefits from strengthening capital investment environments, characterized by rising GDP growth and increased venture funding. These macroeconomic factors stimulate demand for industrial properties, particularly in regions with robust economic activity. Investors seeking opportunities in this sector often prioritize logistics and industrial real estate, drawn by favorable interest rates and the potential for long-term appreciation.
The expansion of e-commerce further accelerates growth in the market. Retailers increasingly prioritize efficient logistics operations, leading to higher demand for warehouses and distribution centers. This shift requires significant capital investment in logistics infrastructure to accommodate changing consumer behaviors and expectations.
Technological integration plays a crucial role in enhancing operational productivity within the market. Investments in automation and AI drive efficiency, allowing companies to streamline processes and reduce costs. This trend influences the need for modern facilities capable of supporting advanced technologies, positioning industrial real estate because a critical component of supply chain resilience.
Overall, the combination of capital investment environments, economic growth, and technological advancements creates a favorable landscape for the Industrial and Logistics Real Estate market. This trajectory signals continued expansion through 2033, supported by ongoing investments in infrastructure and modernization initiatives.
The Industrial and Logistics Real Estate market experiences accelerated growth driven by ongoing infrastructure development and asset modernization. Investments in upgrading physical and digital capabilities enhance operational efficiency across various sectors. Modernizing distribution centers and warehouses improves logistics, enabling faster delivery times and reduced operational costs, attracting businesses seeking competitive advantages.
Significant capital allocates towards upgrading facilities with advanced technologies that streamline processes and incorporate automation. Enhanced digital infrastructure supports the adoption of smart technologies, optimizing inventory management and fulfilling customer expectations in real-time. These advancements improve operational productivity and align with evolving consumer behaviors, particularly in the e-commerce sector, where rapid fulfillment and responsiveness are essential.
The focus on asset modernization contributes to sustainability initiatives by reducing energy consumption and minimizing carbon footprints. Facilities equipped with energy-efficient systems appeal to environmentally-conscious investors and tenants. This trend drives growth in the Industrial and Logistics Real Estate market, ensuring that investments remain relevant in a dynamic economic environment while addressing the demands of modern businesses.
The Industrial and Logistics Real Estate market faces significant constraints from regulatory compliance and macroeconomic pressures. Regulatory tightening on environmental standards and building codes raises costs for developers and investors. These compliance hurdles result in delays, complicating project timelines and reducing overall market efficiency.
Macroeconomic headwinds, including inflationary pressures, create an environment where rising costs of construction materials and labor impact profitability. Increasing operational expenses challenge developers to maintain competitive pricing while meeting consumer demand, leading to stagnation in market expansion.
Supply chain disruptions, driven by geopolitical instability and resource scarcity, hinder growth in the market. These factors lead to unpredictable project timelines and cost overruns, creating an atmosphere of uncertainty. Caution among investors affects capital flow towards new projects and contributes to a slowdown in overall market activity.
High capital investment requirements and escalating operating costs highlight the challenges faced by stakeholders. Developers require substantial financial resources to comply with new regulations while adapting to inflationary pressures and market conditions. This scenario leads to a re-evaluation of investment strategies, impacting overall growth potential.
The combination of these factors results in a constrained operational environment for the Industrial and Logistics Real Estate market, forcing companies to navigate a complex environment of compliance and economic challenges. Addressing these issues is crucial for sustaining growth and competitiveness in the evolving market.
Geopolitical fragmentation creates challenges for the Industrial and Logistics Real Estate market. Volatility stemming from trade deficits and tariff friction disrupts established supply chains, leading to increased operational risks and costs for stakeholders. These conditions affect investment decisions, driven by market participants seeking to mitigate exposure to fluctuating regulations and tariffs.
Supply chain instability arises from technological disruptions and complex research and development integrations, leading to interoperability friction. Market players face difficulties in aligning diverse systems and processes, resulting in increased time and costs for project execution. Such disruptions hinder the timely delivery of products and services, directly impacting profitability in the market.
Rising input cost structures and margin pressures contribute to an unfavorable economic environment for developers and investors. Increased expenses associated with sourcing materials and labor challenge profit margins, compelling firms to reassess pricing strategies. The market confronts environmental lifecycle footprints and decarbonization mandates, driving the need for sustainable practices that complicate operational costs.
Workforce skill gaps exacerbate challenges in talent retention, particularly in an industry that increasingly relies on automation and advanced technologies. The lack of skilled labor limits the capacity of companies to innovate and remain competitive. This situation leads to a talent shortage that constrains growth opportunities within the Industrial and Logistics Real Estate market.
Infrastructure gaps and retrofitting barriers create implementation bottlenecks, delaying project timelines and increasing costs. Stakeholders in the market navigate these challenges effectively to maintain competitiveness and meet evolving client demands. The confluence of these factors necessitates strategic adaptation to enhance resilience in the face of ongoing market pressures.
The Industrial and Logistics Real Estate market experiences notable opportunities due to shifts in regional demands and infrastructure modernization. Growing consumer expectations for faster delivery times fuel investments in warehouse and distribution facilities, particularly in regions like Asia Pacific and North America. With the e-commerce sector expanding, companies increasingly require advanced logistics solutions to meet customer needs, driving significant growth in this area.
Technological disruptions enhance operational efficiency through automation and digital transformation. The introduction of advanced logistics technologies facilitates streamlined operations, allowing developers and operators to optimize supply chains and improve service delivery. Consequently, organizations that adopt innovative practices position themselves competitively within the market.
Sustainability imperatives influence investment decisions, driven by businesses aligning with eco-friendly practices. The demand for green transformations in facilities, including cold storage and temperature-controlled environments, rises because companies prioritize Environmental, Social, and Governance (ESG) criteria. This shift toward sustainability correlates with increasing consumer preference for environmentally conscious products.
Strategic consolidation and cross-industry mergers contribute to market growth. Companies seek synergies through partnerships and acquisitions, enabling them to expand their service offerings and geographical reach. This trend facilitates diversification of product lines and enhances competitive positioning, creating further opportunities within the market.
The evolving buying behaviors, influenced by digital procurement shifts, reshape market dynamics. Buyers leverage online platforms for acquiring logistics properties, enhancing transaction speed and efficiency. This digital shift promotes a more agile market, allowing stakeholders to respond effectively to changing demands.
Value-chain optimization and asset life-cycle extensions present additional opportunities. Companies invest in maintenance upgrades and retrofitting older facilities to enhance operational yield. This focus on maximizing existing assets contributes to the overall growth and sustainability of the Industrial and Logistics Real Estate market.
The Global Industrial and Logistics Real Estate market is segmented based on Property Type, Ownership, and End-Use Industry.
Valued at USD 284.7 million in 2026, the Warehouses & Distribution Centers segment is projected to reach USD 447.4 million by 2033, at a CAGR of 6.7% during the forecast period. This growth stems from the increasing demand for efficient storage solutions driven by the rise of e-commerce and just-in-time inventory practices. Industries including retail, consumer goods, and third-party logistics contribute to this demand, with their need for strategic locations that optimize distribution networks.
Adoption of advanced technologies, including automation and robotics, enhances operational efficiency within these facilities. Next-generation upgrades focus on energy efficiency and sustainability, aligning with broader regulatory compliance standards and consumer expectations. Regulatory policies favoring sustainability in construction and operation support newer facilities that appeal to environmentally conscious businesses.
Supply chain resilience is significant, with businesses looking to minimize disruptions through strategically located warehouses. The logistics vulnerabilities exposed during recent global events have prompted companies to reassess their distribution strategies, leaning towards increased capacity in well-connected areas. Pricing volatility in construction materials influences investment decisions, compelling developers to explore flexible financing and innovative materials.
End-use dynamics reflect a shift towards more flexible space utilization, with a growing interest in facilities that accommodate diverse operational needs. This evolution in consumption patterns emphasizes the importance of adaptability in warehouse design, catering to both traditional storage and modern distribution methods. Strategic opportunity windows arise from companies investing in facilities that incorporate next-generation technologies, enhancing their competitive edge in the Industrial and Logistics Real Estate market.
Growing industrial production and a focus on efficiency drive demand for manufacturing and production facilities within the Industrial and Logistics Real Estate market. Companies prioritize automation, leading to a shift towards facilities that support advanced manufacturing techniques. Enhanced productivity and operational flexibility attract investments in this segment.
The Manufacturing & Production Facilities segment is estimated to reach USD 222.4 million by 2033, at a CAGR of 6.1% during the forecast period. This growth reflects rising demand for specialized properties that accommodate evolving manufacturing processes and meet stringent quality standards. The sector benefits from heightened investments in technology and infrastructure, facilitating the integration of next-generation upgrades.
End-use dynamics significantly influence this segment, with industries including automotive, consumer goods, and pharmaceuticals driving the need for efficient manufacturing environments. Regulatory compliance standards shape facility design and operational protocols, ensuring adherence to safety and environmental regulations. Companies with strategic investments in these facilities are positioned for growth within the competitive landscape.
Cold Storage & Temperature-Controlled Facilities play a critical role in the Industrial and Logistics Real Estate market, driven by increasing demand for fresh and perishable goods. Rising consumer preferences for convenience and quality lead to heightened requirements for temperature-sensitive storage solutions. The expansion of e-commerce channels intensifies this demand, particularly for groceries and pharmaceuticals, necessitating the development of specialized facilities equipped with advanced refrigeration technologies.
Technological maturation significantly influences the segment by enabling innovative cooling systems and automation in storage management. Investments in energy-efficient technologies enhance operational efficiency and reduce cost structures, while regulatory compliance standards around food safety and health regulations stimulate facility upgrades. These pressures create strategic opportunity windows, encouraging investment in next-generation cold storage solutions that cater to evolving consumer demands.
Industry players are expanding their portfolios to include more Cold Storage & Temperature-Controlled Facilities, reflecting a strategic alignment with market growth trends. The segment is projected to reach USD 141.5 million by 2033, highlighting its importance within the broader Industrial and Logistics Real Estate market. Prioritizing supply chain resilience, the adoption of dedicated cold storage facilities is essential for businesses seeking to mitigate risks associated with temperature-sensitive products.
Growth in the Flex, R&D & Light Industrial Facilities segment reflects strong demand driven by the rising need for versatile spaces that support research and development, light manufacturing, and warehousing operations. This segment is projected to grow at a CAGR of 8.4% during the forecast period. Factors influencing this growth include the increasing integration of technology in manufacturing processes and a shift towards agile supply chains, which facilitate rapid product development and delivery. Businesses seeking to adapt to changing market conditions invest in flexible spaces that accommodate diverse operational needs, reduce overhead costs, and enhance efficiency.
The ongoing evolution of product offerings within this sub-segment aligns with trends in automation and digital transformation. Expansion in e-commerce activities necessitates facilities that provide logistical support and enable rapid turnaround times, promoting the design of modern spaces equipped with smart technologies. End-use industries, particularly technology-driven sectors, significantly influence the demand dynamics in this segment, driving investment and development in the market. This alignment with industry trends indicates strong potential for sustained market growth in the coming years.
Increasing demand for efficient storage solutions drives interest in Industrial Outdoor Storage & Yard Facilities within the Industrial and Logistics Real Estate market. Growing urbanization and space constraints push businesses to optimize land use, making outdoor storage a viable option for various industries. Businesses involved in construction, automotive, and retail sectors require outdoor storage for excess inventory and equipment, enhancing operational flexibility and enabling better inventory management.
Technological advancements influence the development of these facilities. Innovations in site management and tracking systems allow for better utilization of outdoor spaces. This evolution meets the requirements of industries prioritizing speed and efficiency in their supply chains. Companies adopting just-in-time inventory practices highlight the need for accessible outdoor storage solutions that support rapid fulfillment and operational efficiency.
Shifts in consumption patterns, particularly the rise of e-commerce, prompt businesses to seek additional storage capacity. The surge in online shopping results in increased demand for temporary storage for goods before reaching consumers. Outdoor facilities provide a cost-effective solution to meet these storage challenges, reinforcing their role in the market because essential components of logistics strategies.
Regulatory compliance and environmental considerations shape the design and operation of Industrial Outdoor Storage & Yard Facilities. Adhering to zoning laws and environmental regulations ensures sustainable operations, appealing to socially responsible investors. Facilities that integrate green practices gain an advantage in attracting tenants focused on sustainability and operational efficiency.
Investment in Industrial Outdoor Storage & Yard Facilities reflects broader trends in the Industrial and Logistics Real Estate market. Capital allocation towards these facilities signals confidence in their potential to meet future storage needs. This investment not only enhances capacity but strengthens resilience within supply chains, positioning businesses to respond effectively to market fluctuations and logistical challenges.
Growth in the Industrial and Logistics Real Estate market is heavily influenced by specialized requirements in sectors including cleanroom technology, hazardous-material storage, and aerospace facilities. Increasing regulations and standards for safety and environmental compliance drive demand for facilities that accommodate stringent requirements. Industries focused on pharmaceuticals, biotechnology, and aerospace technologies prioritize state-of-the-art facilities to meet high-quality standards, resulting in a strong need for tailored real estate solutions.
Adoption of advanced technologies in construction and facility management enhances operational efficiency, prompting investments in specialized properties. Technological maturation in automation and energy efficiency contributes to the appeal of these facilities, driven by companies seeking to improve their overall productivity. Strategic opportunities arise through partnerships between real estate developers and technology providers, yielding innovative solutions that meet specific industry needs.
Market players face challenges including pricing volatility and margin pressures stemming from fluctuating raw material costs. The potential for long-term capital investments in regulated industries supports continued growth. Regulatory compliance remains a critical factor, influencing facility design and operational protocols to align with national and international standards.
The emerging focus on sustainability and environmental responsibility in the Industrial and Logistics Real Estate market encourages the development of green-certified facilities. This trend positions companies to appeal to environmentally-conscious clients while optimizing operational costs. Overall, the segment of Others (Cleanrooms, Hazardous-Material Storage, Aerospace-Specialty Facilities) actively shapes the strategic directions of the market.
Valued at USD 273.6 million in 2026, the Owner-Occupied segment is projected to reach USD 404.4 million by 2033, at a CAGR of 5.7% during the forecast period. Primary demand drivers include the increasing emphasis on operational efficiency and the desire for companies to maintain control over their real estate assets. Industries including manufacturing, logistics, and retail contribute significantly to this segment, because businesses seek to align property ownership with strategic operational goals.
Adoption of advanced technologies enhances the functionality of owner-occupied facilities. Next-gen upgrades, including automation and smart building technologies, improve space utilization and energy efficiency, leading to cost savings. Regulatory compliance continues to shape investment decisions, with stricter environmental standards driving the need for upgraded facilities that meet sustainability targets. This focus on compliance further influences capital investment outlook, compelling businesses to allocate funds towards modernizing their properties.
Consumption shifts towards e-commerce and rapid delivery services necessitate flexible facility designs that accommodate changing operational requirements. The market benefits from the resilience of supply chains, because companies invest in owner-occupied spaces to mitigate logistics vulnerabilities. This investment in property not only secures a physical footprint but enhances control over logistics processes, reducing dependency on third-party logistics providers.
Increasing reliance on leased facilities among businesses drives strong demand within the Industrial and Logistics Real Estate market. The growth trajectory reflects a strategic shift in operational models, particularly among e-commerce and third-party logistics providers, who prioritize flexibility and scalability. This shift stems from the necessity to optimize supply chains and manage costs effectively, resulting in projected segment revenue reaching USD 606.6 million by 2033, at a compound annual growth rate (CAGR) of 8.2% during the forecast period.
Pressure on businesses to enhance operational efficiency and reduce overheads fuels the transition toward leased spaces. Rising property costs make leasing a viable solution, allowing firms to allocate capital more strategically. This dynamic attracts a wide range of end-use industries, including automotive, retail, and food and beverage sectors, which benefit from the adaptability that leased properties provide.
The Industrial and Logistics Real Estate market will continue to evolve, influenced by regulatory frameworks and market trends. Compliance with evolving standards enhances operational viability, while technological advancements in property management and logistics further stimulate growth in the leased segment. The proliferation of digital platforms increases the demand for flexible, high-quality leased facilities, reinforcing the segment's role in the market's overall expansion.
Valued at USD 117.6 million in 2026, the E-commerce segment projects a significant increase to USD 216.2 million by 2033, reflecting a CAGR of 9.1% during the forecast period. Growth in this segment stems from heightened consumer preference for online shopping, resulting in increased investment in digital platforms and last-mile delivery infrastructures. The expansion of E-commerce directly influences the demand for logistics facilities designed to accommodate high-volume storage and efficient distribution processes.
Technological advancements contribute to the segment's growth, with innovations in automation and artificial intelligence enhancing operational efficiencies. These technologies enable retailers to optimize inventory management and improve delivery times, appealing to consumers seeking convenience. The rise of mobile commerce and personalized shopping experiences drives further investments in logistics real estate, ensuring alignment with evolving consumer expectations.
Regulatory compliance standards related to safety, sustainability, and environmental impact increasingly shape the operational landscape for E-commerce businesses. Adhering to these standards necessitates investment in infrastructure that meets modern requirements, influencing the overall cost structures within the market. E-commerce players face pricing volatility while balancing operational costs against consumer demand, driving strategic planning and investment in resilient supply chains.
With the continuous shift toward digital shopping, capital investment in E-commerce logistics facilities is expected to rise. This investment enhances supply chain resilience, mitigates risks associated with market fluctuations, and addresses potential vulnerabilities within logistics networks. Overall, the E-commerce segment's growth trajectory contributes to the overall dynamics of the Industrial and Logistics Real Estate market.
Increasing interest in Third-Party Logistics, Freight & Express services significantly influences the Industrial and Logistics Real Estate market. This segment is projected to reach USD 182 million by 2033, at a CAGR of 7.8% during the forecast period. E-commerce expansion serves because a primary demand driver, leading to heightened requirements for efficient and scalable logistics solutions. The growing complexity of supply chains emphasizes the importance of third-party logistics providers in facilitating smooth operations.
Adoption of advanced technologies, including automation and digital platforms, enhances service efficiency and reliability in this sector. These technological advancements support operational improvements and reduce costs, allowing providers to offer competitive pricing. The increasing focus on sustainability within the logistics field drives investment in eco-friendly practices and green technologies, further influencing segment growth.
Consumption shifts toward online shopping and rapid delivery services compel companies to optimize their logistics strategies. Regulatory compliance standards regarding transportation and warehousing impact operational frameworks, necessitating investment in facilities that meet such requirements. Strategic opportunity windows arise from the need for modernized infrastructure, enabling players in the market to capitalize on evolving consumer demands.
The growth prospects for Third-Party Logistics, Freight & Express services highlight the segment's vital role in the overall expansion of the Industrial and Logistics Real Estate market. While businesses adapt to changing market dynamics, third-party logistics providers remain essential in navigating complexities and ensuring efficient supply chain management.
Demand for retail and consumer goods significantly influences the Industrial and Logistics Real Estate market. Growth in e-commerce and shifting consumer preferences toward online shopping drive the need for more logistics space dedicated to this sector. Retailers prioritize efficient distribution networks and flexible storage solutions to accommodate rapid delivery timelines. This transition necessitates investments in properties that support advanced supply chain operations, enhancing operational efficiency and responsiveness to market demands.
Regulatory compliance standards regarding sustainability and environmental impact shape the development of facilities catering to retail and consumer goods. Companies face pressures to adopt green technologies that promote energy efficiency and reduce operational costs. These factors contribute to the growing appeal of modern facilities designed with sustainability in mind, aligning with consumer expectations and regulatory requirements.
This segment reflects the increasing importance of specialized logistics solutions tailored to the retail sector. Businesses within this market segment continuously seek ways to enhance their competitive edge through improved logistics capabilities, which further drives investments in industrial real estate. The demand for dedicated retail and consumer goods facilities is projected to strengthen throughout the forecast period, presenting a robust opportunity for stakeholders in the market.
Investment in electric vehicles and advancements in mobility solutions underpin growth in the Automotive & Mobility segment. Increasing urbanization and shifting consumer preferences toward sustainable transport options drive demand for facilities tailored to automotive manufacturing and logistics. The segment is projected to grow at a CAGR of 5.9% during the forecast period, reflecting a robust increase in capital investment aimed at enhancing production capabilities and supply chain efficiency.
Technological maturation enhances segment expansion, with innovations in automation and digitalization improving operational efficiency. Automotive companies increasingly adopt smart logistics solutions, streamlining inventory management and reducing costs associated with storage and distribution. The need for flexible and adaptive facilities aligns with the rapid evolution of vehicle technologies, necessitating upgraded infrastructure to accommodate electric and autonomous vehicles.
Regulatory compliance standards influence facility development within the segment. Stricter emissions regulations and safety standards compel manufacturers to invest in modern facilities that meet industry requirements. Capital investment in new properties creates a favorable environment for growth in the Automotive & Mobility segment by supporting compliance with these regulations.
The Automotive & Mobility segment within the Industrial and Logistics Real Estate market represents a sector characterized by technological advancements and regulatory pressures. The focus on sustainable practices and enhanced operational efficiency positions this segment for continued growth during the forecast period.
Interest in the Food & Beverage segment stems from rising consumer demand for fresh and processed food products. This trend highlights the necessity for efficient storage and distribution, ensuring that perishable goods reach consumers swiftly. The increasing prevalence of e-commerce in the food sector further drives the need for specialized facilities that maintain product integrity while enhancing delivery speed.
Regulatory compliance influences the market for Food & Beverage facilities. Strict health and safety standards necessitate investments in temperature-controlled environments and advanced storage solutions. These requirements challenge operators to adopt innovative technologies that ensure compliance while optimizing operational efficiency.
Supply chain resilience remains crucial for the Food & Beverage segment. Disruptions in logistics often affect the availability of key ingredients and finished products. Companies prioritize partnerships and strategic investments to enhance their supply chains, focusing on reducing vulnerabilities that could impact overall performance.
Pricing volatility, particularly in raw materials, exerts pressure on profit margins within the market. Fluctuations in commodity prices lead to increased operational costs, prompting companies to explore cost-effective solutions. This dynamic environment encourages innovation in logistics strategies to maintain competitiveness while managing expenses.
Strategic opportunity windows arise from the ongoing evolution in consumer preferences towards sustainability and health-conscious options. Investments in environmentally friendly practices and technology-driven solutions position companies favorably in a transforming market. These advancements contribute to long-term growth prospects in the Industrial and Logistics Real Estate market.
Investment in the Pharmaceuticals & Healthcare segment reflects a commitment to addressing the increasing demand for advanced medical solutions and efficient distribution channels. This sector benefits from heightened investment in research and development, which creates a robust requirement for specialized logistics facilities that ensure safe and timely delivery of critical products. Regulatory compliance standards drive the need for facilities that adhere to stringent healthcare guidelines, influencing infrastructure design and operational practices across the market.
Technological maturation within the industry encourages the adoption of innovative solutions in logistics and supply chain management. The integration of automation and real-time tracking enhances operational efficiency, enabling firms to respond rapidly to changing market conditions. Consumption shifts toward personalized medicine and specialized healthcare products necessitate flexible storage solutions that adapt to diverse inventory requirements.
Strategic opportunity windows arise from the ongoing expansion of healthcare services and the increasing prevalence of e-health solutions. Companies involved in pharmaceuticals and healthcare leverage logistics vulnerabilities in traditional supply chains to optimize their operations, ensuring resilience against disruptions. The ongoing evolution of healthcare products alongside advancements in technology positions the market for sustained growth. Robust infrastructure supports the increasing complexity of distribution networks.
Investment in cold storage and temperature-controlled facilities remains critical for safeguarding products that require strict environmental conditions. Cost structures in this segment reflect the need for enhanced security and compliance measures, influencing pricing strategies across the market. Overall, the Pharmaceuticals & Healthcare segment significantly contributes to the broader growth trajectory of the Industrial and Logistics Real Estate market.
Investment in the Electronics & High-Tech sector influences the Industrial and Logistics Real Estate market significantly. The ongoing transition towards advanced technologies accelerates the need for specialized facilities that accommodate the storage, manufacturing, and distribution of high-tech products. Companies in this sector focus on adopting next-generation upgrades and enhancing operational efficiency. Compliance with regulatory standards shapes facility specifications, affecting design and construction processes.
Technological maturation supports the establishment of smart warehouses and automated fulfillment centers. These developments enhance supply chain resilience by streamlining processes and reducing inefficiencies. The growing demand for rapid delivery services drives the need for strategically located logistics facilities, ensuring that products reach consumers swiftly and reliably. Consumption shifts towards smart devices and electronics necessitate innovative storage solutions, prompting investments in flex spaces and specialized environments that cater to cleanroom standards.
Raw material sourcing remains vital for companies operating in this sub-segment, determining pricing strategies and supply chain dynamics. The evolving landscape creates opportunities for new entrants, with strategic windows open for firms that adapt to changing market conditions. Disruptive alternatives, including sustainable practices, push traditional models to evolve, leading to enhanced margins and competitive advantages. Overall, the Electronics & High-Tech sub-segment contributes to substantial growth within the Industrial and Logistics Real Estate market.
Investment in industrial manufacturing and engineering reflects the increasing focus on innovative production techniques and efficiency improvements. The growing need for advanced manufacturing processes drives demand for specialized facilities tailored to support high-value production activities. Regulatory compliance standards play a crucial role in shaping facility requirements, influencing investment in upgraded infrastructure to meet environmental and safety regulations.
Consumption shifts towards customized products create opportunities for facilities designed to support agile manufacturing processes. These dynamics channel capital investment into next-generation upgrades and technological maturation, creating environments that enhance productivity. Strategic opportunities exist for operators who identify white-space in emerging markets, particularly in regions with evolving demand patterns.
Supply chain resilience emerges because a key factor in facility planning, requiring investments in robust infrastructure to mitigate vulnerabilities. Raw material sourcing challenges necessitate efficient logistics solutions, compelling operators to adapt facility designs that streamline operations. Cost structures increasingly reflect the need for facilities that integrate advanced technologies, driving operational efficiency and reducing pricing volatility. The industrial manufacturing and engineering segment significantly influences the overall landscape of the industrial and logistics real estate market, shaping its future trajectory.
Increased focus on sustainability and environmental responsibility drives demand for Renewable Energy and Clean Technology facilities within the Industrial and Logistics Real Estate market. Adoption of green technologies and renewable energy sources leads to significant investment in specialized facilities designed to support production and storage of clean energy solutions. Regulatory frameworks emphasizing carbon reduction and sustainability push industries to seek compliance through the establishment of innovative facilities. Companies prioritize energy-efficient designs, which lower operational costs and enhance profitability over time.
Consumption shifts towards environmentally friendly products influence the layout and design of logistics facilities. Companies targeting eco-conscious consumers invest in sustainable practices, including energy-efficient warehouses and distribution centers. These investments enhance brand reputation and meet growing expectations for corporate responsibility. Technological advancements in energy storage and management systems support this trend, allowing firms to optimize their operations while contributing to a greener future.
Strategic opportunity windows emerge owing to governments worldwide introducing incentives for renewable energy investments and infrastructure development. Companies capable of adapting to these changes gain a competitive edge in the market. Capital investment outlook remains positive, because firms recognize the importance of aligning their operations with sustainability goals. This focus on renewable energy and clean technology reinforces the segment's role within the broader Industrial and Logistics Real Estate market.
Growing demand for specialty materials across industries drives interest in the Others (Aerospace, Chemicals, Textiles) segment. The need for innovative solutions and heightened compliance with regulatory standards fuels segment expansion. Industries seeking to enhance operational efficiency increasingly rely on adaptable real estate solutions, resulting in increased investment in specialized facilities. The market reacts to shifts in consumption patterns and technological advancements, creating opportunities for growth in this sub-segment.
Focus on sustainability and environmental compliance significantly influences the design and functionality of new facilities. Companies in the aerospace, chemicals, and textiles sectors prioritize supply chain resilience and logistical efficiency, which drives demand for strategically located industrial real estate. Robust capital investments in these areas reflect the commitment to adapting to evolving market conditions, reinforcing the significance of the Industrial and Logistics Real Estate market.
Based on geography, the Global Industrial and Logistics Real Estate market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
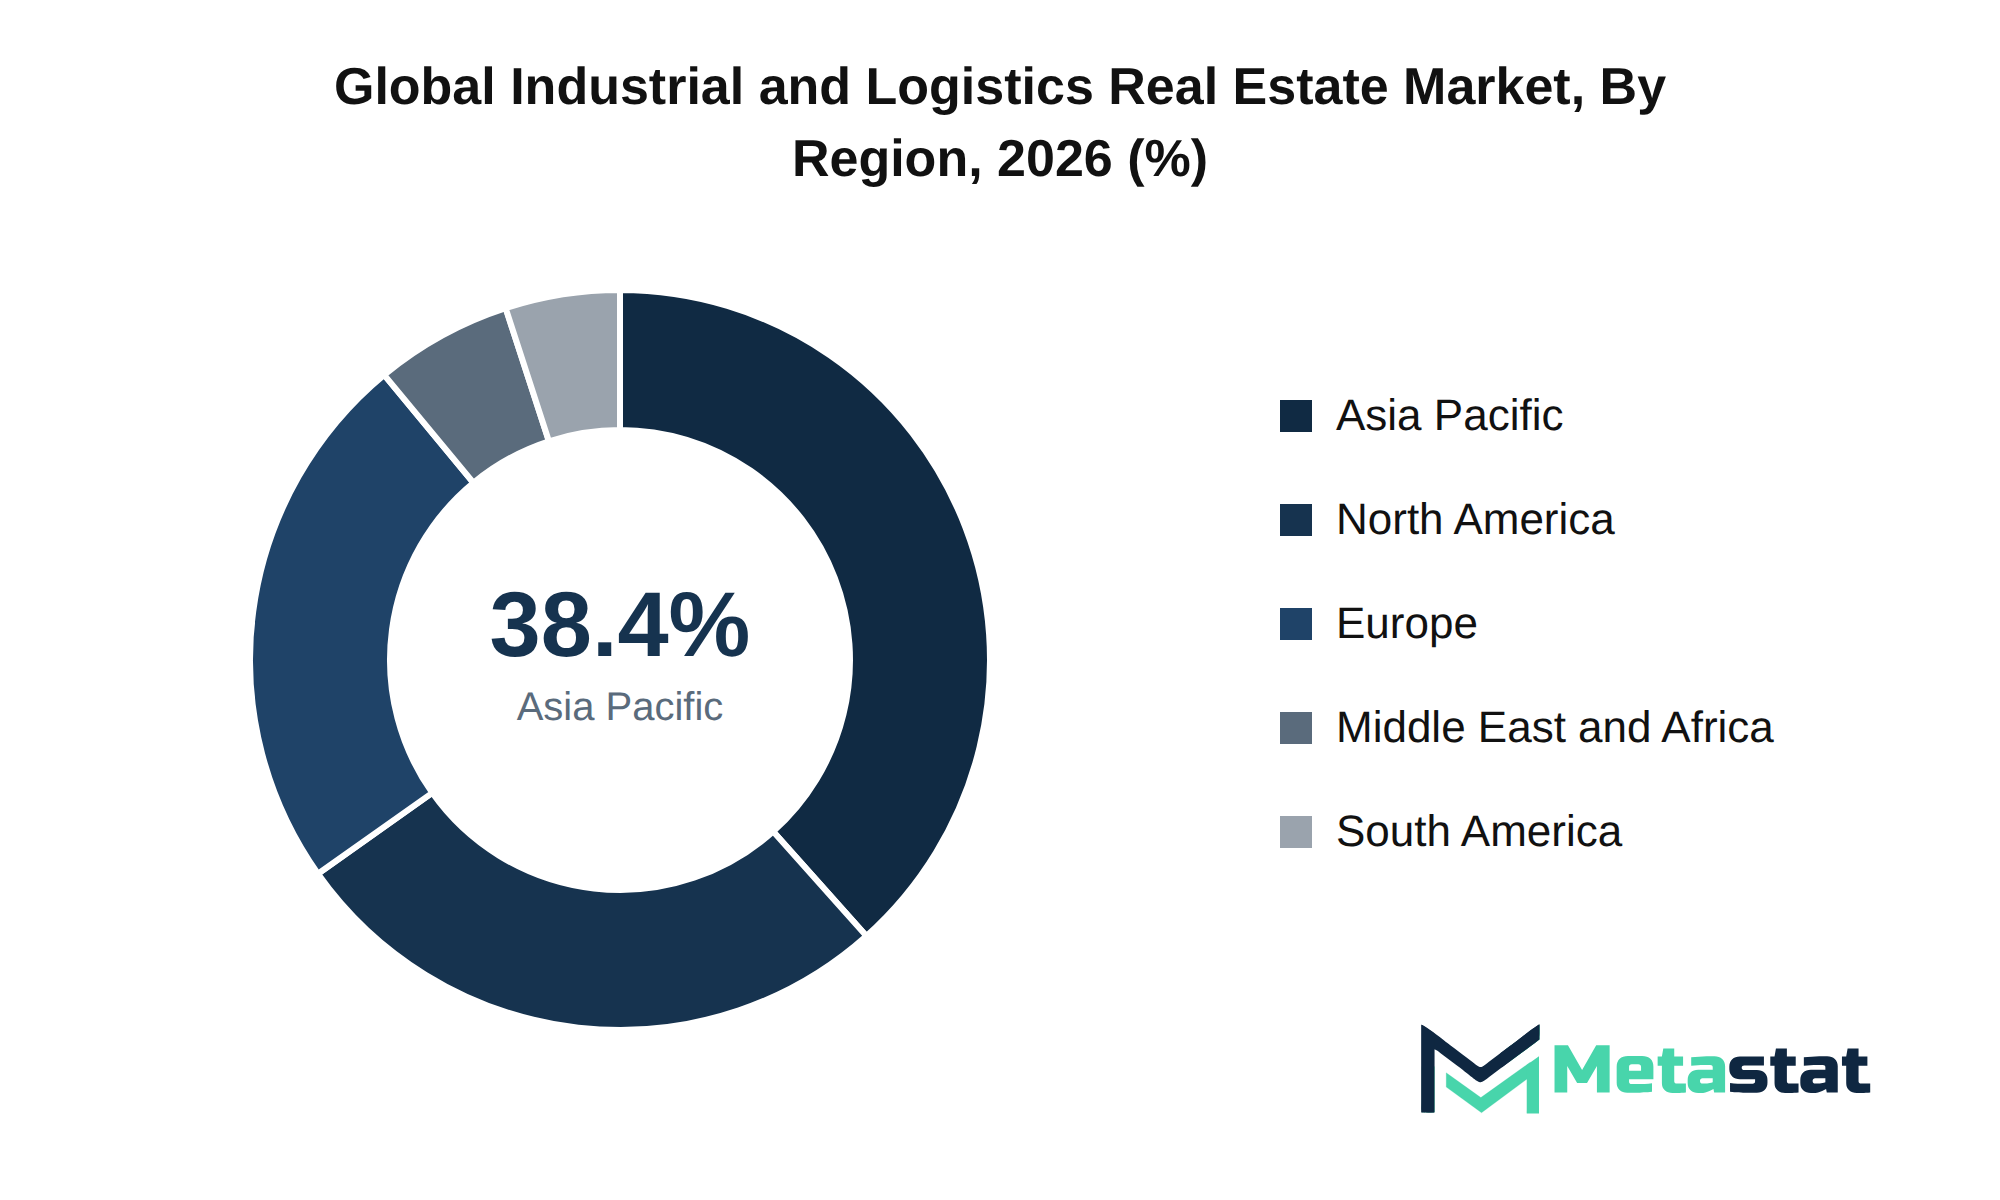
North America emerges because a significant player in the Industrial and Logistics Real Estate market, projected to expand at a CAGR of 7.2% within the forecast period, reaching a market size of USD 255 million by the end of 2033. The region holds a 26.8% share of the global market in 2025, reflecting the robust demand for industrial space driven by increasing e-commerce and logistics sectors.
Investment in infrastructure modernization and localized manufacturing densities supports the expansion of warehouses and distribution centers across the United States, Canada, and Mexico. The trend toward nearshoring initiatives enhances supply chain regionalization, allowing companies to streamline operations and reduce lead times.
Geopolitical factors, including changes in cross-border trade corridors and domestic market dynamics, influence the competitive landscape in North America. The presence of several domestic market participants encourages healthy competition and innovation, which further enhances the market's prospects.
Regional compliance mandates and localized procurement dynamics play critical roles in shaping investment strategies. Companies invest in facilities that align with local regulations, ensuring operational efficiency while meeting the increasing demand for industrial real estate.
North America's Industrial and Logistics Real Estate market experiences significant growth driven by evolving consumer behaviors, strategic infrastructure investments, and the dynamic relationship of regional economic factors.
The Industrial and Logistics Real Estate market in Europe holds a substantial share of the global market. The region benefits from strong demand drivers, including an increasing focus on e-commerce and advancements in supply chain efficiency. Countries including Germany, France, the UK, Italy, Spain, and Russia contribute to this demand, driven by robust consumer spending and a growing population.
Infrastructure modernization supports the growth of the market. Investments in logistics and transportation networks enhance regional connectivity, facilitating the movement of goods and services. This improvement is essential for emerging market front-runners, because localized manufacturing densities and nearshoring initiatives drive operational efficiency and reduce lead times.
The competitive landscape in Europe consists of various domestic market participants that adapt to regional nuances and procurement dynamics. Vendors focus on consolidating their positions while responding to local compliance mandates and regulatory frameworks that shape market behavior. This competitive environment prompts businesses to invest in high-value replacement cycles, ensuring that facilities meet contemporary standards and demands.
Geopolitical factors influence the Industrial and Logistics Real Estate market in Europe. Cross-border trade corridors enhance trade opportunities while adding complexity to supply chains. Companies operating within these corridors navigate varying regulatory environments, which impacts operational strategies. Regional resource availability and energy grid resiliency become critical, and businesses optimize their investments to adapt to changing market conditions.
Asia-Pacific represents a growing share of the global Industrial and Logistics Real Estate market, accounting for 38.4% in 2025. The region benefits from rapid urbanization and a growing middle class, driving demand for logistics capabilities. E-commerce continues to thrive in markets including China and India, prompting increased investments in warehouses and distribution centers. Countries like Japan and South Korea demonstrate advanced infrastructure, enhancing operational efficiency and attracting foreign investment.
Modernization of supply chains has become a focal point for businesses across the region. Local manufacturers increasingly adopt nearshoring initiatives to reduce lead times and enhance responsiveness to consumer demands. This shift has prompted new opportunities in localized manufacturing densities, particularly in Southeast Asia, where labor costs remain competitive.
Geopolitical fragmentation influences trade corridors, reshaping logistics networks. Trade policies and compliance regulations vary among countries, necessitating a nuanced understanding of local market dynamics. Domestic market leaders leverage these conditions to gain competitive advantages and consolidate vendor relationships, creating a robust ecosystem within the market.
Energy grid resiliency and resource availability play crucial roles in determining market readiness. Regions with well-established infrastructure attract foreign direct investment, further stimulating growth. Sustained interest in warehousing and distribution properties drives incremental growth vectors, positioning Asia-Pacific because a key player in the global Industrial and Logistics Real Estate market.
The Industrial and Logistics Real Estate market in South America presents unique characteristics influenced by regional demand and supply dynamics. Brazil and Argentina serve because the primary markets, with a notable focus on urban logistics and the e-commerce sector, which is expanding rapidly in these countries. The increasing adoption of localized manufacturing strategies enhances the growth potential within the region, driven by businesses seeking to optimize supply chains and respond effectively to consumer demand.
Infrastructure development plays an important role in supporting the market's growth. Investments in transportation and logistics networks enable greater connectivity, facilitating efficient distribution channels. The region's logistics capabilities are evolving, driven by a mix of domestic investments and foreign direct investment inflows aimed at enhancing operational efficiency and expanding capacity.
Cross-border trade corridors have become increasingly important, especially for Brazil and Argentina, helping to enhance trade and logistics activities. The Industrial and Logistics Real Estate market benefits from geopolitical factors, with local compliance mandates encouraging businesses to adapt their strategies to meet regulatory requirements. These developments create opportunities for domestic market leaders to improve their positions amid competitive pressures.
Localized procurement dynamics and cultural nuances influence B2B buying behaviors, shaping the strategies of suppliers and investors within the market. Companies are keen to establish a presence in underpenetrated territories, acknowledging the growth vectors that lie ahead. With a share of 5.00% in the global market in 2025, the South American segment reflects a significant opportunity for continued expansion and investment in the Industrial and Logistics Real Estate market.
The Industrial and Logistics Real Estate market in the Middle East and Africa exhibits potential for growth driven by various factors, including increasing foreign direct investment (FDI) flows and a focus on localized manufacturing. Countries including Saudi Arabia and the UAE enhance their infrastructure to facilitate supply chain regionalization, positioning themselves because attractive investment destinations. South Africa's strategic location and established trade corridors support this growth trajectory, enabling greater connectivity within the region.
Regional market dynamics reflect a shift towards modernization, with emerging market front-runners prioritizing infrastructure development and compliance with local regulations. Demand for industrial facilities, particularly in warehousing and distribution, aligns with the rising need for efficient logistics solutions. Cultural nuances and regional B2B buying behaviors influence procurement strategies, encouraging suppliers to adapt to the unique needs of local markets.
Despite challenges, including geopolitical fragmentation and varying regulatory frameworks, opportunities remain for growth in underpenetrated territories. The competitive landscape features both domestic market participants and international entrants, contributing to vendor consolidation trends that enhance service delivery. Overall, the Industrial and Logistics Real Estate market stands poised for continued expansion, driven by strategic investments and evolving consumer demands.
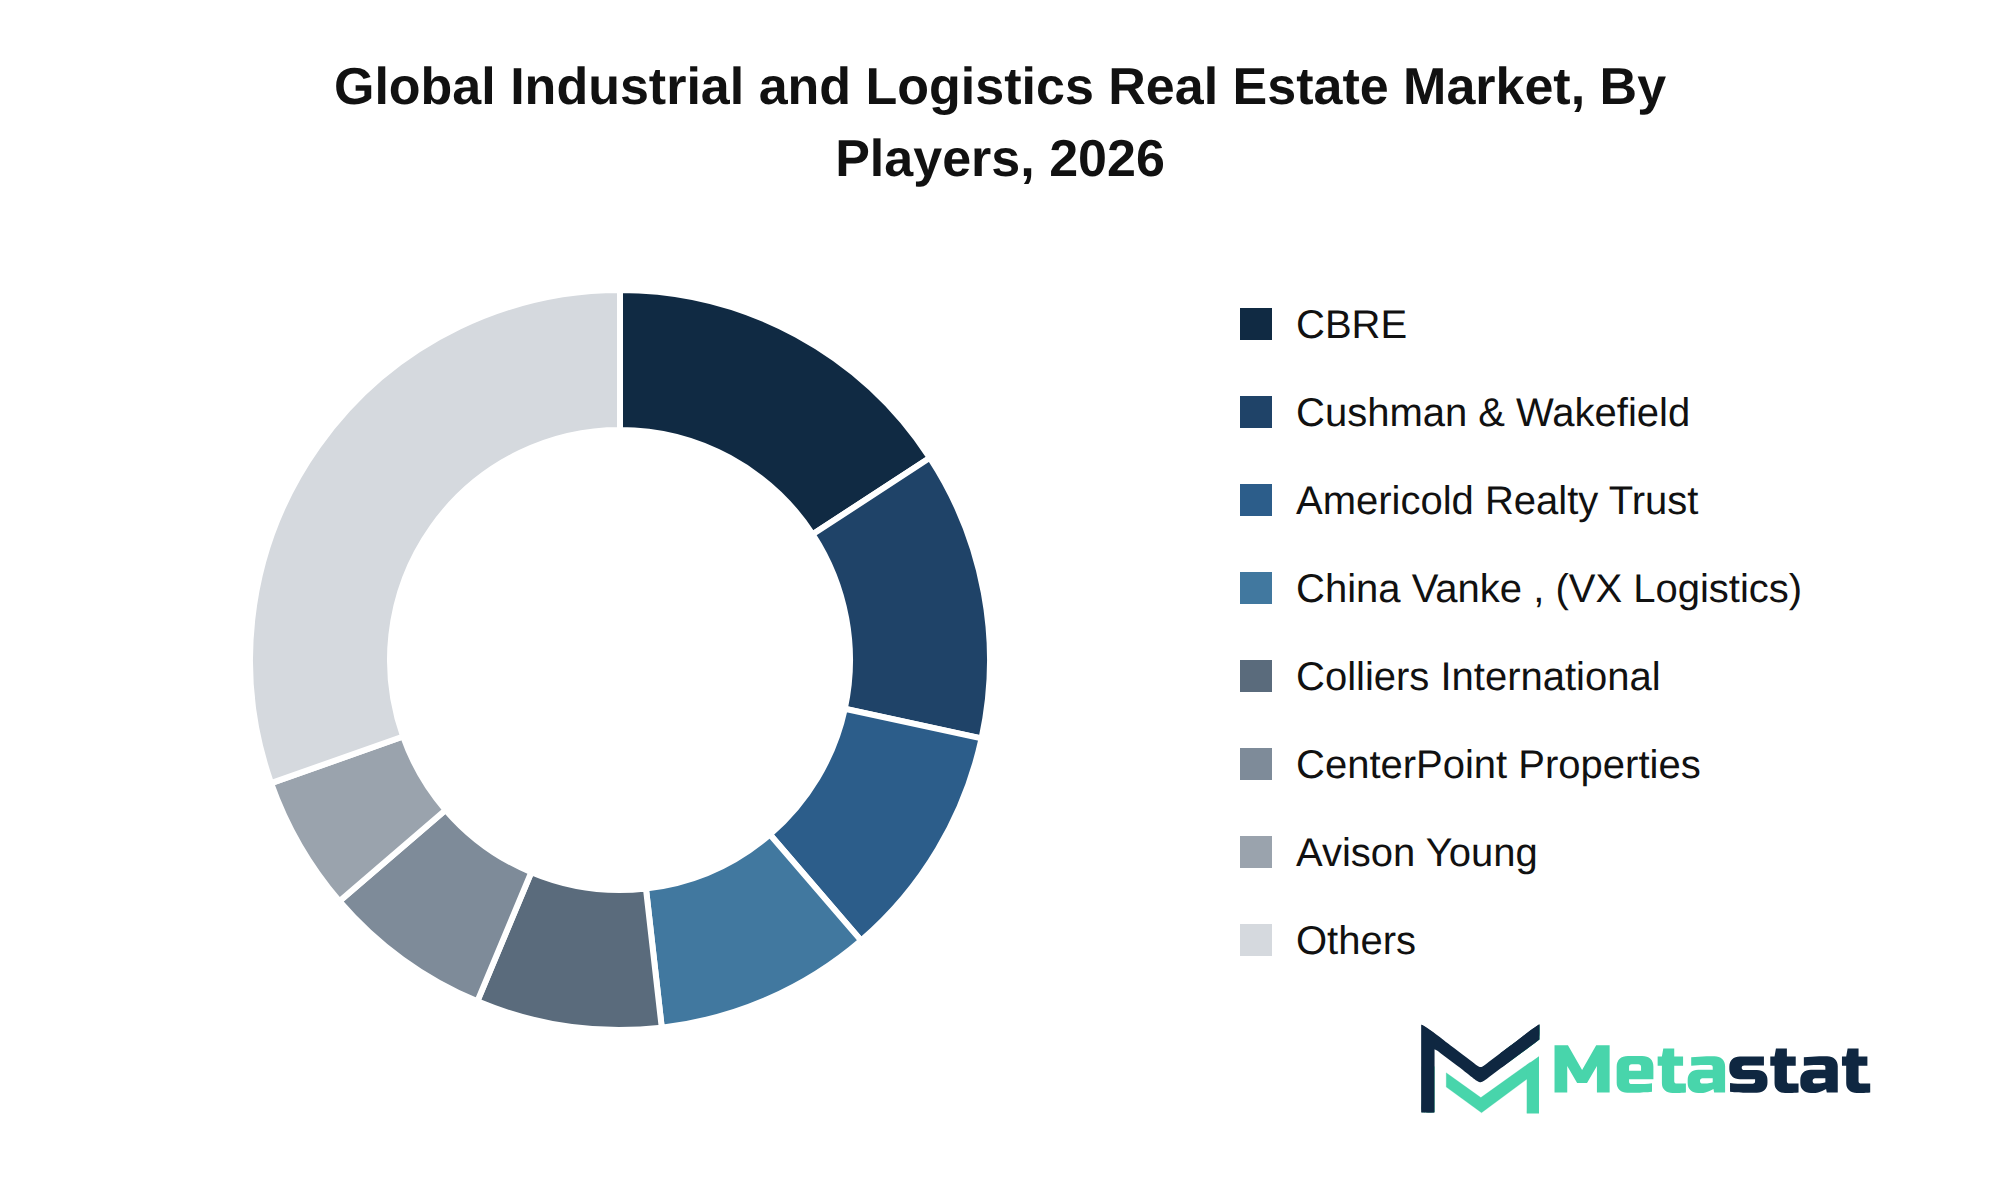
The Industrial and Logistics Real Estate market exhibits significant activity in mergers, acquisitions, and strategic consolidations. Key players including Prologis, Inc. and CBRE Group Inc. engage in strategic alliances to enhance their market positioning. These collaborations enable sharing of resources and expertise, increasing operational efficiency and market reach.
Product differentiation remains vital, with companies focusing on innovative property types and industry-specific solutions. Players including ESR Group and Goodman Group implement unique offerings tailored to diverse sectors including e-commerce and automotive. This strategic focus contributes to enhanced customer retention and brand equity within the market.
Barriers to entry for new entrants influence market dynamics, with established companies leveraging their intellectual property and technological advancements. Firms like Americold Realty Trust, Inc. and Cushman & Wakefield maintain competitive advantages through proprietary technologies and extensive IP portfolios. This defensibility supports growth and mitigates the threat of disruption from startups.
The future competitive outlook for the market hinges on effective go-to-market strategies and value chain integration. Established players dominate supply chains, ensuring procurement leverage and operational control. This strategic approach positions them favorably to adapt to changing market demands and enhances profitability.
Market size is forecast to rise from USD 579.5 million in 2025 to over USD 1,011 million by 2033. The base case demonstrates a growth trajectory characterized by a 7.2% CAGR, reflecting solid underlying demand and investment within the Industrial and Logistics Real Estate market.
Economic cycles influence market dynamics, with potential downturns posing challenges to growth. Conversely, periods of economic expansion create favorable conditions for capital investment in infrastructure development and logistics capabilities. Strategic capital allocation prioritizes sectors poised for growth, particularly E-commerce and Third-Party Logistics, which exhibit robust demand drivers.
Technological advancements reshape operational frameworks, enhancing efficiency in logistics processes. Next-generation technology integration, including automation and data analytics, streamlines operations and optimizes resource allocation. Companies investing in R&D enhance competitive positions, aligning product life cycles with evolving market needs.
Regulatory evolution continues to impact operational landscapes. Emerging compliance milestones focus on sustainability practices, prompting investments in eco-friendly facilities and operations. Geopolitical realignments shift trade corridors, altering supply chain dynamics. Industries adapt to these changes, ensuring resilience against global disruptions.
Unmet enterprise needs and high-growth pockets present significant opportunities within the market. Identifying and addressing these gaps through innovative solutions drives sustainable growth. Executive-level strategic imperatives prioritize adaptability and responsiveness to market shifts, enhancing defensibility and long-term viability. Continuous evaluation of infrastructure commitments supports future growth recommendations.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Industrial and Logistics Real Estate market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 7.2% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Property Type, Ownership, End-Use Industry, and Region |
By Region | North America (By Property Type, Ownership, End-Use Industry, and Country)
|
Europe (By Property Type, Ownership, End-Use Industry, and Country)
| |
Asia Pacific (By Property Type, Ownership, End-Use Industry, and Country)
| |
South America (By Property Type, Ownership, End-Use Industry, and Country)
| |
Middle East and Africa (By Property Type, Ownership, End-Use Industry, and Country)
|
Find answers to common questions about this report
The Industrial and Logistics Real Estate market size was valued at USD 579.5 million in 2025, according to the Metastat Insights study.
The Industrial and Logistics Real Estate market is projected to grow at a CAGR of 7.2% during the forecast period from 2026 to 2033.
The North America Industrial and Logistics Real Estate market size is estimated to reach USD 255 million by 2033.
The segment leading the Industrial and Logistics Real Estate market is Warehouses & Distribution Centers, with a projected value of USD 447.4 million by 2033. This segment demonstrates significant growth potential compared to other property types.
The Industrial and Logistics Real Estate market experiences growth driven by strengthening capital investment environments, rising GDP growth, and increased venture funding. The expansion of e-commerce accelerates demand for logistics infrastructure, while technological integration enhances operational productivity, positioning modern facilities because critical components of supply chain resilience.
The Industrial and Logistics Real Estate market faces constraints from regulatory compliance, macroeconomic pressures, and geopolitical fragmentation. Regulatory tightening raises costs and complicates project timelines, while inflationary pressures increase operational expenses. supply chain disruptions and workforce skill gaps exacerbate challenges, limiting growth opportunities within the market.
Strengthening capital investment environments, rising GDP growth, and increased venture funding favor product adoption in the Industrial and Logistics Real Estate market. The expansion of e-commerce and the need for efficient logistics operations drive demand for warehouses and distribution centers, necessitating significant investments in logistics infrastructure.
The Industrial and Logistics Real Estate market is estimated to reach a valuation of USD 1,011 million by 2033.
Key players in the Industrial and Logistics Real Estate market include Americold Realty Trust, Inc., CBRE Group Inc., Cushman & Wakefield, Duke Realty Corporation, Goodman Group, Jones Lang LaSalle Incorporated, and Prologis, Inc.
The Warehouses & Distribution Centers segment is projected to grow from USD 284.7 million in 2026 to USD 447.4 million by 2033, reflecting a compound annual growth rate of 6.7%.
Choose Your License
Global Industrial and Logistics Real Estate Market
The analysts below cover Automotive and Transportation research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.
Evaluating secondary resin quality across post-consumer packaging streams requires reliable technical segmentation. MetaStat Insight delivered an objective assessment that distinguished between extrusion-grade flake pricing and optical sorting throughput limitations across Western Europe. The competitive positioning breakdown for licensed depolymerization technology providers answered several questions during our feedstock feasibility audit. Their team clarified regional trade restrictions on mixed plastic scrap quickly when our team submitted follow-up requests.
Evaluating sovereign cloud deployments for core banking platforms demands a clear view of data residency regulations and migration exit strategies. MetaStat Insight delivered an exhaustive review of regional latency tolerances, mainframe decommission milestones, and third-party vendor concentration risk. The regulatory compliance mapping across European and Asian financial jurisdictions gave our team a dependable baseline for multi-cloud infrastructure discussions.
Replacing petrochemical surfactants with bio-based alternatives requires realistic timelines on industrial precision fermentation scaling. The market research broke down commercialization timelines, feedstock sugar price sensitivities, and regional cosmetic ingredient regulatory approvals in Europe and East Asia. That supplier readiness mapping gave our formulations team reliable context when comparing renewable chemical sourcing roadmaps.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950
Starting from
$2950