
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Precision Machining Market Size, Share, By Type (Manual Operation and CNC Operation), By Machining Type (Milling Machining, Laser Machining, Electric Discharge Machining, Turning, Grinding, and Others), By End-use Industries (Automotive, Aerospace & Defense, Medical, Industrial Machinery, Electronics, and Others), By Precision Level (Standard Precision, High Precision, and Ultra-Precision / Micro-Machining), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5195
September, 2026
305 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
The global Precision Machining market was valued at USD 123.4 billion in 2025 and is projected to reach USD 235.4 billion by 2033, growing at a CAGR of 8.4% over the forecast period.
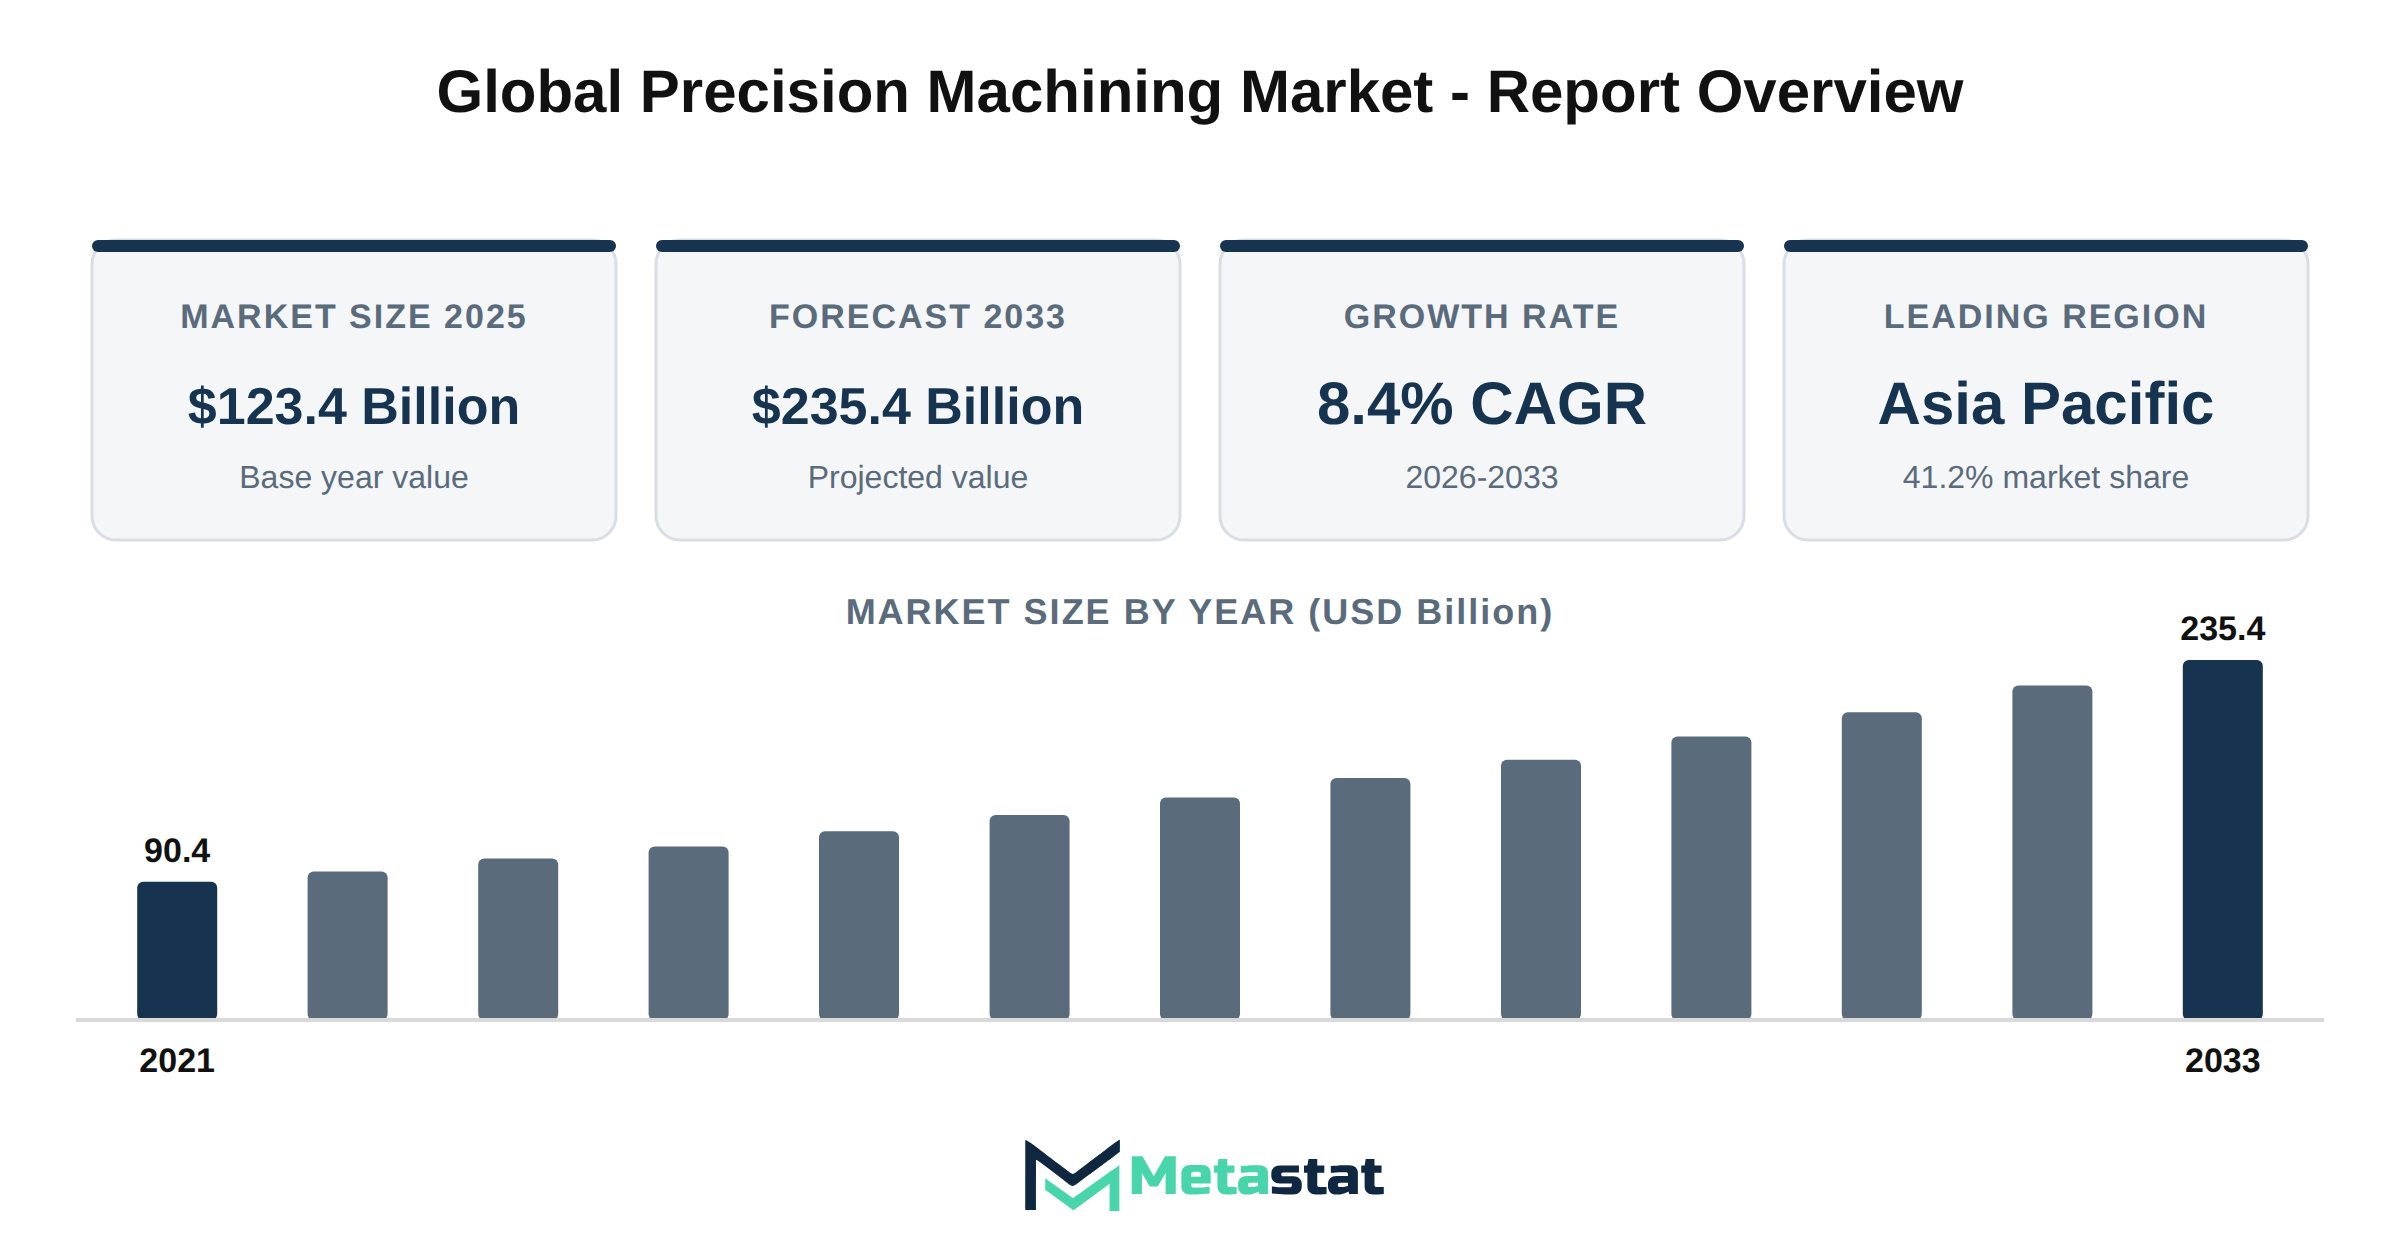
The Precision Machining market reached a value of USD 123.4 billion in 2025, reflecting a steady increase from USD 90.4 billion in 2021. This growth trajectory is projected to continue, with an estimated value of USD 235.4 billion by 2033, resulting in a compound annual growth rate (CAGR) of 8.4% during the forecast period from 2026 to 2033. The market demonstrates robust demand driven by various factors, including advancements in manufacturing technologies and a shift toward high-precision applications.
Shop-floor economics play a crucial role in the market, with manufacturers focusing on capital expenditures (CapEx) and machine utilization metrics to enhance operational efficiency. Investments in smart manufacturing and Industry 4.0 integration facilitate real-time data analytics and automation, allowing manufacturers to optimize production processes and reduce waste. This integration supports the shift toward "lights-out" automation, where minimal human intervention is required, thereby increasing productivity and lowering operational costs.
Advanced material machinability influences tool wear dynamics, impacting overall productivity and cost-efficiency for manufacturers. The increasing use of composite materials in aerospace and medical applications necessitates specialized machining techniques and tools that withstand higher wear rates. The market is moving toward the development of advanced tools and technologies that enhance machinability, ensuring consistent quality and precision in high-value applications.
High-value end-market shifts, particularly in aerospace, medical technology, and the electric vehicle (EV) sector, drive demand for precision machining services. The aerospace and defense industries emphasize lightweight components and complex geometries, requiring high-precision machining capabilities. Similarly, the medical sector demands stringent tolerances and specialized manufacturing processes for medical devices, further fueling growth in the Precision Machining market.
Supply chain dynamics, including reshoring and nearshoring trends, significantly impact the market landscape. Manufacturers increasingly prioritize local sourcing to enhance supply chain resilience and reduce lead times. Regulatory compliance related to quality standards and material specifications shapes operational strategies, compelling manufacturers to adopt advanced machining technologies that ensure compliance in various industries.
The Precision Machining market faces significant changes driven by advancements in shop-floor economics, capital expenditures, and machine utilization metrics. Improved efficiency metrics enable manufacturers to optimize operational costs while enhancing productivity. This focus allows companies to invest in innovative technologies that streamline workflows and enhance the value proposition for their customers.
Integration of smart manufacturing technologies and "lights-out" automation significantly shapes the market landscape. Companies leveraging Industry 4.0 principles, including IoT and data analytics, experience improved machine connectivity and real-time monitoring capabilities. This approach facilitates proactive maintenance and minimizes downtime, leading to enhanced operational efficiency and competitiveness.
Advanced material machinability and tool wear dynamics significantly impact production processes within the market. The continual evolution of materials requires precision machining companies to adapt their tooling strategies to ensure optimal performance and longevity. Understanding these dynamics is essential for maintaining quality standards and meeting the demands of high-performance applications.
High-value end-market shifts, particularly in aerospace, medical technology, and electric vehicle transitions, drive increased demand for precision machining services. These industries require superior quality and precision, compelling manufacturers to invest in advanced machining solutions that cater to these specific needs. Growth in these sectors presents opportunities for market participants to expand their offerings and enhance revenue streams.
Supply chain reshoring and nearshoring trends significantly influence the market's dynamics. Companies increasingly prioritize local sourcing and production to mitigate risks associated with global supply chains. Regulatory compliance further shapes the market landscape, with manufacturers adapting to evolving standards and requirements. This shift emphasizes the need for precision machining companies to maintain flexibility and responsiveness in their operations.
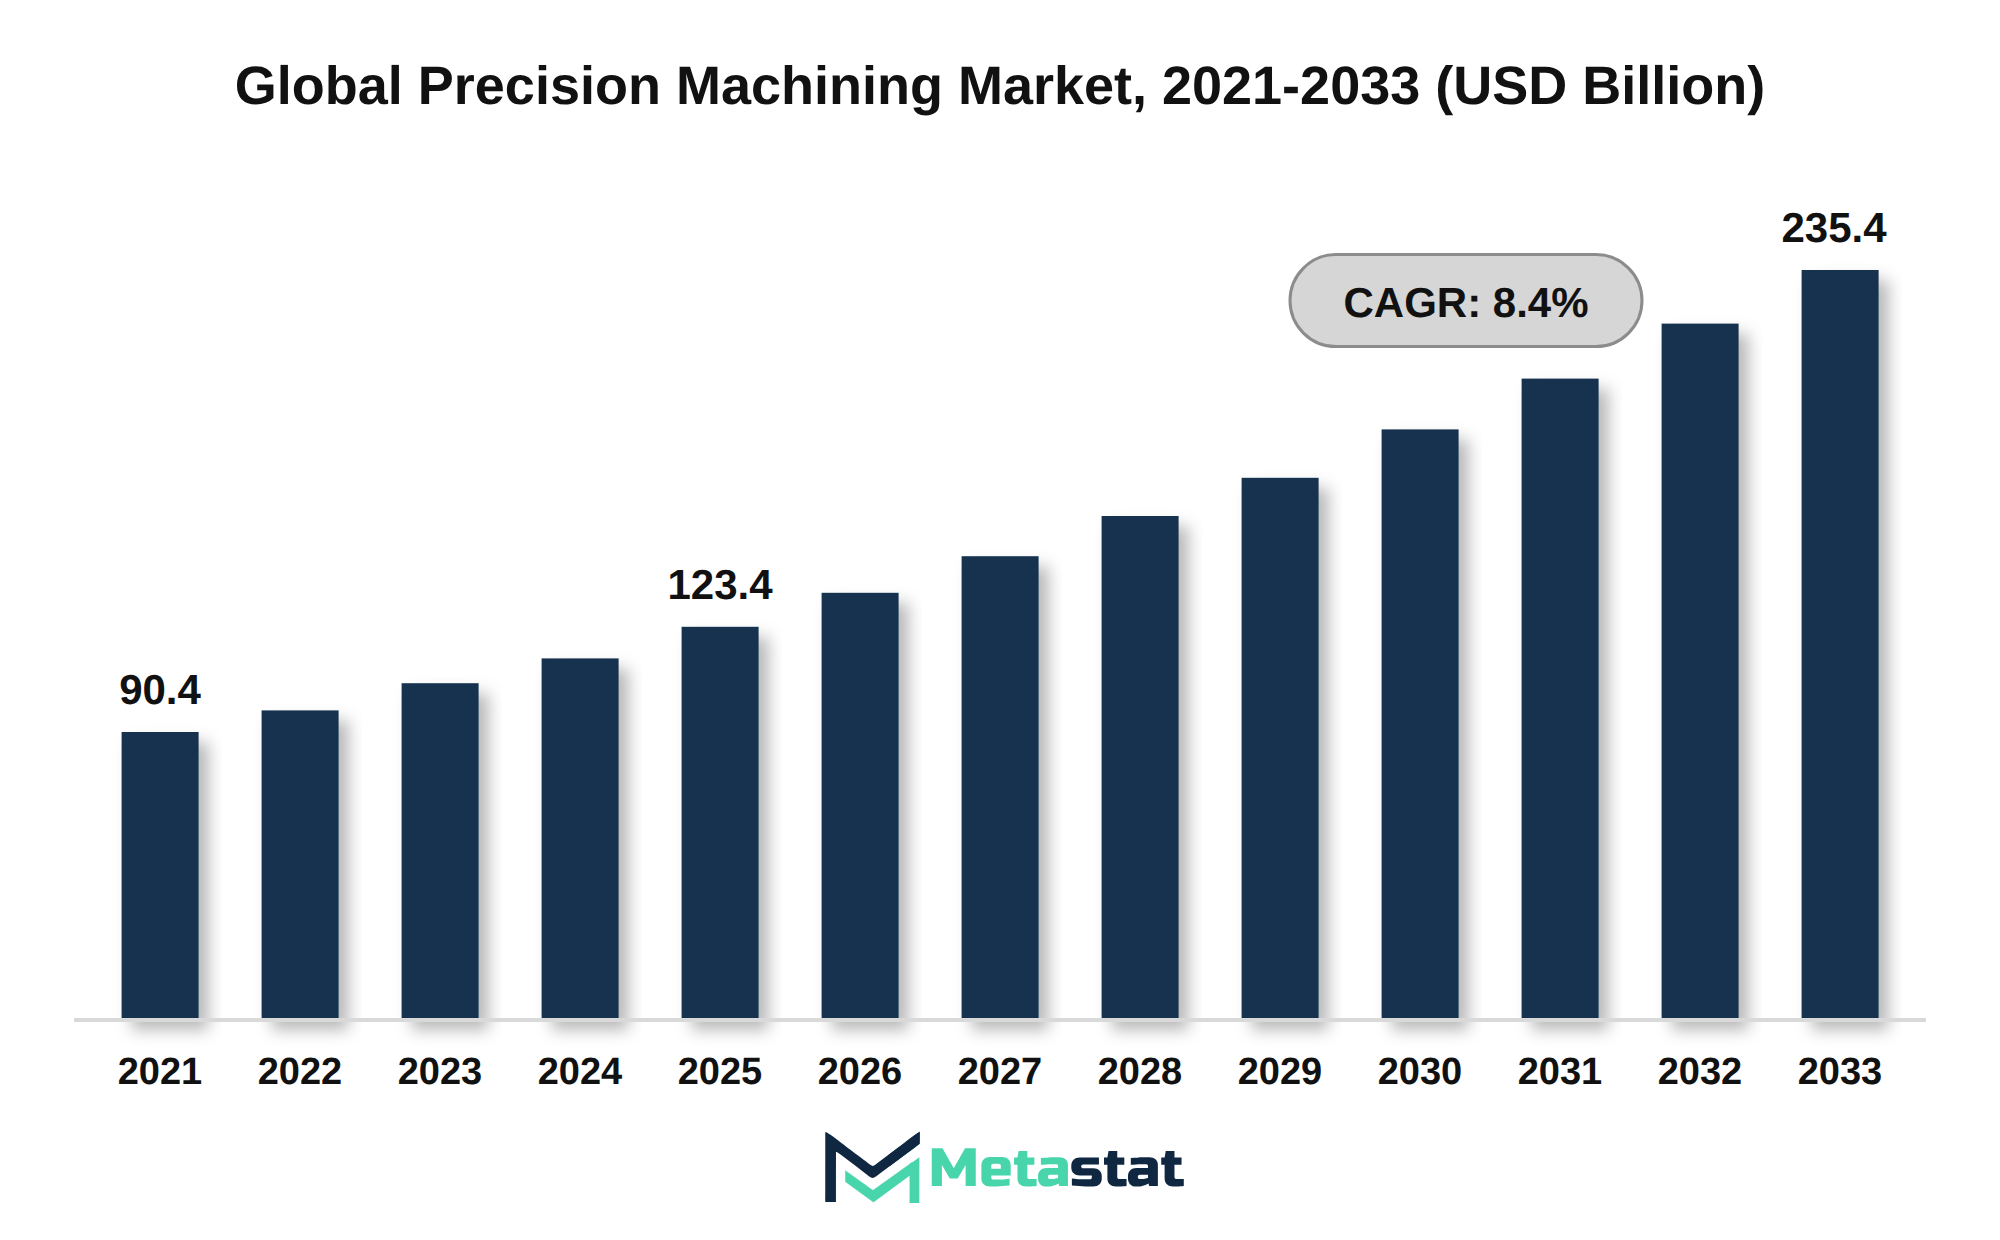
The Precision Machining market experiences growth driven by substantial investments in advanced manufacturing technologies. Companies increasingly prioritize automation and artificial intelligence to enhance operational efficiency and productivity. The integration of smart technologies allows manufacturers to streamline processes, reduce lead times, and achieve higher precision in production. This trend aligns with the broader digital transformation occurring across various industries, where digitizing legacy processes is essential for maintaining competitiveness.
Rising demand for customized solutions in sectors including automotive and aerospace pushes manufacturers to adopt flexible machining solutions. Investment in state-of-the-art equipment supports this shift, enabling firms to respond swiftly to changing consumer preferences and market dynamics. Manufacturers improve their ability to meet diverse client needs while optimizing production capabilities.
Emphasis on sustainable manufacturing practices influences investment decisions. Companies increasingly seek technologies that reduce waste and energy consumption, aligning with environmental, social, and governance mandates prevalent in many industries. This focus on sustainability addresses regulatory expectations and enhances brand reputation and customer loyalty.
Overall, the Precision Machining market stands to benefit from these investment trends, reinforcing growth prospects through enhanced productivity, operational efficiency, and sustainability initiatives.
The Precision Machining market experiences growth driven by technological integration, particularly automation and artificial intelligence (AI). Investments in smart manufacturing technologies enhance operational efficiency, reduce production costs, and improve product quality. Increasingly complex manufacturing processes necessitate advanced machinery and software solutions capable of managing and optimizing production workflows.
Industries including automotive and aerospace benefit significantly from these advancements. Enhanced automation facilitates faster production cycles and enables customization of products to meet specific client requirements. This trend provides a competitive edge among manufacturers, allowing them to respond swiftly to market demands and evolving consumer preferences.
The digital transformation of legacy processes supports the Precision Machining market's expansion. Companies that digitize their operations gain access to real-time data analytics, improving decision-making and operational productivity. This shift reduces costs and enhances supply chain resilience, positioning businesses to capitalize on emerging opportunities in a globally competitive landscape.
The Precision Machining market experiences constraints due to high capital investment requirements, which deter potential entrants and existing players from expanding operations. The need for advanced machinery, technology, and facilities leads to substantial initial costs that burden smaller manufacturers. This financial barrier limits market participation, particularly for new companies and startups attempting to establish a foothold in the industry.
Ongoing operational costs contribute to market challenges. Maintenance, workforce training, and adherence to quality standards require continuous investment, which strains financial resources. Companies with limited budgets struggle to keep pace with technological advancements, risking obsolescence in a sector that evolves rapidly. Consequently, this situation leads to slower adoption of innovative practices and equipment that could enhance efficiency and productivity.
The combination of these factors results in a constrained growth trajectory for the Precision Machining market. Companies facing these financial hurdles prioritize short-term profitability over long-term investment in emerging technologies, ultimately affecting their competitive standing. The market's reliance on capital-intensive processes necessitates a careful balance between operational efficiency and investment in future capabilities.
The Precision Machining market encounters challenges due to geopolitical fragmentation, which leads to supply chain instability and trade deficits. Variability in international relations creates tariff friction and complicates trade agreements, impacting cost structures and production timelines. Suppliers across various regions face increased operational uncertainties, directly affecting their capabilities to deliver components on time and within cost parameters.
Technological disruptions introduce additional complexities within the market. Rapid advancements in manufacturing techniques often necessitate significant investments in research and development, while interoperability issues arise from integrating new technologies into existing systems. This situation complicates the development landscape for many companies, straining resources and affecting overall market productivity.
Price pressures exert a notable influence on profit margins throughout the Precision Machining market. Increasing input costs from raw materials along with the volatility of feedstock present a challenge for manufacturers aiming to maintain competitive pricing. Companies balance margin pressures with the need for continuous innovation and productivity improvements to sustain their market position.
Workforce skill gaps emerge because a significant challenge, particularly in adapting to advancing automation technologies. Talent retention pressures compound this issue, because experienced professionals transition to sectors offering better compensation or job security. This workforce dynamic affects the ability of companies to implement new manufacturing technologies efficiently, ultimately slowing down progress within the market.
Regulatory standards increasingly shape operational landscapes, demanding higher compliance overheads from manufacturers. Tightening global regulations regarding environmental standards necessitate a focus on sustainability and the impact of operations on the lifecycle footprint. Companies face the dual challenge of meeting these standards while managing the associated costs, further complicating their strategic planning.
The Precision Machining market experiences significant opportunities driven by accelerating technological innovations. Emerging trends in automation and digital transformation enhance productivity and efficiency across manufacturing processes. Industries increasingly adopt advanced solutions including CNC operation and laser machining, leading to increased operational precision and reduced lead times. These innovations attract investment and drive growth, particularly among manufacturers seeking to improve their competitive positions.
Infrastructure modernization presents further opportunities for the market. Upgrades to existing manufacturing facilities facilitate the integration of next-generation technologies, aligning production capabilities with evolving market demands. This modernization supports the expansion of precision machining applications across various sectors, including automotive, aerospace, and medical, where precision components are critical for performance and safety.
Geographical expansion enhances market reach owing to companies entering emerging regions. Increased demand for precision machining services in Asia Pacific, driven by rapid industrialization and technological adoption, offers substantial growth potential. Companies focusing on localizing supply chains and adapting to regional market dynamics capture significant market share in these developing economies.
Sustainability imperatives shape the Precision Machining market. Companies increasingly prioritize eco-friendly practices and compliance with environmental standards, which influences operational strategies and product offerings. This shift encourages investments in sustainable technologies and processes, ultimately making the market more attractive to environmentally conscious consumers and businesses.
Strategic consolidation through mergers and acquisitions strengthens competitive positions within the market. Companies leveraging synergies from strategic partnerships enhance their product portfolios and expand their market presence, contributing to increased revenue generation. This trend promotes innovation and accelerates the development of integrated solutions that meet diverse consumer needs.
The evolving buying behaviors of customers drive the need for more personalized solutions. Digital procurement shifts enable manufacturers to engage with clients more effectively, facilitating tailored offerings that meet specific requirements. This shift enhances customer relationships and encourages loyalty, further supporting growth within the Precision Machining market.
The Global Precision Machining market is segmented based on Type, Machining Type, End-use Industries, and Precision Level.
Valued at USD 27.8 billion in 2026, the Manual Operation segment is projected to reach USD 45.5 billion by 2033, reflecting a CAGR of 7.3% during the forecast period. Demand for manual machining operations arises primarily from industries requiring skilled labor and highly customized solutions. The automotive and aerospace sectors significantly drive this demand due to their emphasis on precision and quality in component production.
Technological maturation contributes to the segment's growth, with traditional machining practices evolving to incorporate improved techniques and tools. Manufacturers invest in next-generation upgrades that enhance operational efficiency while adhering to stringent regulatory compliance standards. End-use dynamics, particularly in industries including medical and industrial machinery, influence consumption patterns and lead to a shift toward precision-focused applications.
Pricing volatility presents challenges, impacting the segment's cost structures and margin pressures. Fluctuations in raw material prices necessitate strategic sourcing and effective supply chain management. New product evolution within the segment highlights the introduction of innovative technologies that address rising efficiency demands and increase competition.
Strategic opportunity windows exist for businesses willing to invest in advanced capabilities that meet emerging market needs. The focus on supply chain resilience and mitigating substitution risks strengthens the segment's growth outlook. Manufacturers continue to adapt to changing market conditions, and the Manual Operation segment within the Precision Machining market is projected to thrive.
CNC Operation segment is estimated to reach USD 189.8 billion by 2033, at a CAGR of 8.6% during the forecast period. This segment experiences robust demand from various end-use industries, driven by the increasing need for high precision and efficiency in manufacturing processes. The automotive and aerospace sectors significantly influence adoption, seeking advanced solutions to enhance productivity and meet stringent regulatory standards.
Technological maturation supports the expansion of CNC Operation, with ongoing innovations leading to enhanced machine capabilities and improved software integration. Next-gen upgrades, including automation and real-time monitoring, support operational efficiencies, allowing manufacturers to reduce waste and optimize production timelines. These advancements create a competitive environment, pushing firms to invest in advanced technologies.
Product evolution further contributes to market dynamics, with manufacturers focusing on developing versatile CNC machines capable of handling diverse materials and complex geometries. This adaptability positions the segment favorably within the broader Precision Machining market, catering to a wide range of applications, from intricate components in medical devices to robust parts in industrial machinery.
Consumption shifts toward high-precision solutions have become evident, particularly in industries demanding exact specifications for safety and performance. Regulatory compliance standards increasingly dictate operational protocols, compelling manufacturers to adopt CNC technologies that meet these requirements. In this context, the segment stands to benefit from heightened investments focused on enhancing quality assurance processes.
Cost structures within the segment demonstrate pressures stemming from raw material sourcing and fluctuating prices, necessitating strategic sourcing and cost management practices. Despite challenges, the market outlook remains positive, driven by strategic opportunity windows for investment in CNC technologies across various sectors. While firms navigate these dynamics, CNC Operation is positioned for sustained growth, reflecting the ongoing transformation within the Precision Machining market.
Milling Machining segment is valued at USD 42.4 billion in 2026 and is projected to reach USD 70.6 billion by 2033, at a CAGR of 7.5% during the forecast period. This segment benefits from several demand drivers, including rising needs for precision and efficiency in manufacturing processes. Industries including automotive and aerospace increasingly adopt milling techniques due to their capacity for high precision and complex geometries. Enhancements in machine tools and the integration of advanced technologies, including robotics and automation, lead to improved operational efficiency and productivity.
Product evolution in milling machining emphasizes the development of next-generation tools designed for specific applications, addressing growing customization demands in various sectors. This evolution aligns with increased usage rates in end-use industries, including medical and industrial machinery, where precision is critical. Rising consumption shifts toward high-precision components across these industries further fuel segment growth.
Regulatory compliance standards governing manufacturing processes drive investments in advanced milling technologies, ensuring adherence to safety and quality benchmarks. Such compliance often translates into significant capital expenditures, impacting overall cost structures within the market. Pricing volatility, driven by fluctuations in raw material costs and supply chain dynamics, influences margin pressures across manufacturers, necessitating strategic adjustments to maintain competitiveness.
Strategic opportunity windows emerge for players to invest in innovative milling solutions that enhance efficiency and reduce waste. Continuous technological maturation fuels interest in milling operations, with firms focusing on developing cost-effective solutions that meet evolving market demands. While the Precision Machining market expands, the milling segment stands to gain substantial traction due to its essential role in delivering precision-engineered components necessary for modern manufacturing processes.
In the Precision Machining market, demand for Laser Machining emerges from various industries seeking precision and efficiency in their production processes. This segment's growth accelerates due to the increasing adoption of advanced technologies, which enhance productivity and reduce operational time. The need for high-quality components in sectors including aerospace, automotive, and medical drives manufacturers to implement laser machining capabilities, enabling the creation of intricate designs and superior finishes.
The Laser Machining segment is projected to reach USD 47.1 billion by 2033, expanding at a CAGR of 10.3% during the forecast period. The expanding applications of laser technology, including cutting, welding, and engraving, contribute to its rising popularity. The shift toward automation and smart manufacturing supports the integration of laser machining systems, improving overall operational efficiency. This evolution aligns with the market's trend toward heightened precision and reduced manufacturing waste.
Regulatory compliance standards requiring improved product quality enhance the adoption of laser machining processes across industries. Manufacturers prioritize investments in this technology to achieve compliance while meeting customer expectations for high-performance products. The segment benefits from a robust capital investment outlook, encouraging innovation and technological advancements that further cement its position within the precision machining ecosystem.
Significant advancements in Electric Discharge Machining technology drive market growth, particularly in industries requiring high precision and intricate designs. This segment capitalizes on its ability to produce complex geometries, attracting demand from sectors including aerospace and automotive. The sector's technological maturation enhances its competitiveness, with next-generation upgrades focusing on efficiency and cost-effectiveness. Increasing automation and integration of Artificial Intelligence streamline operations, expanding market reach.
The Electric Discharge Machining segment is projected to reach USD 31.8 billion by 2033. End-use dynamics reflect a shift toward lightweight materials and advanced alloys, necessitating more sophisticated machining solutions. Regulatory compliance standards, particularly in aerospace and medical applications, push manufacturers to adopt high-quality processes, reinforcing the segment's growth trajectory. Strategic opportunities arise from a focus on electric vehicle production, where precision machining plays a critical role in component manufacturing.
Cost structures within the segment remain challenging, driven by fluctuations in raw material prices and the need for specialized equipment. Pricing volatility influences profit margins, prompting manufacturers to optimize production processes. Supply chain resilience becomes essential, with firms seeking to mitigate risks associated with sourcing and logistics. The market demonstrates strong potential for capital investment, particularly from players looking to expand technological capabilities and market share.
Growth in the Turning segment of the Precision Machining market aligns with increasing demand for precision components across various applications. Industries including automotive and aerospace prioritize high-quality, accurate parts, driving significant interest in turning technologies. This segment's projected growth at a CAGR of 7.3% during the forecast period reflects a broader trend towards enhanced manufacturing capabilities and efficiency.
Investment in next-generation upgrades contributes to the segment's expansion, with manufacturers adopting advanced CNC turning machines that improve production speed and accuracy. Technological maturation facilitates greater precision and automation, reducing cycle times and enhancing product quality. End-use dynamics highlight a shift towards more complex geometries in component design, necessitating sophisticated turning processes to meet these requirements.
Regulatory compliance standards within industries including medical and aerospace further fuel demand for turning services, driven by manufacturers adhering to stringent quality specifications. Pricing volatility in raw materials impacts cost structures, prompting firms to optimize their turning operations to maintain margins while meeting rising production costs.
Strategic opportunity windows arise from the increasing trend towards lightweight materials in automotive and aerospace applications. Turning operations capable of handling these materials position firms favorably in the competitive environment. Overall, the Turning segment plays a critical role in the ongoing evolution of the Precision Machining market, driving innovation and supporting diverse industry needs.
Demand for Grinding in the Precision Machining market stems from its critical role in achieving precise dimensions and surface finishes in various components. Industries including automotive, aerospace, and medical increasingly adopt Grinding techniques to enhance product quality and performance. Technological maturation within grinding processes, including the integration of advanced abrasives and automation, supports segment expansion. Continuous improvements in grinding equipment, including CNC grinders, enable manufacturers to achieve higher efficiency and accuracy, aligning production capabilities with evolving market demands.
End-use dynamics reflect a shift toward greater precision across sectors. The automotive industry, for example, prioritizes grinding for manufacturing parts including gears and bearings, which require stringent tolerances for optimal performance. Regulatory compliance standards further push manufacturers to adopt high-precision machining techniques, making grinding essential for meeting quality certifications. Cost structures associated with grinding are influenced by the need for high-quality raw materials and advanced machinery, resulting in pricing volatility and margin pressures for suppliers.
Supply chain resilience becomes crucial in managing raw material sourcing for abrasives used in grinding. Fluctuations in material availability create vulnerabilities, prompting manufacturers to explore alternative sourcing strategies. Strategic opportunities arise from technological obsolescence in older grinding machines, pushing companies to invest in next-generation upgrades to maintain competitiveness. This evolution within the Grinding segment of the market presents significant potential for growth and adaptation to industry needs.
Recent trends in the Precision Machining market highlight the increasing adoption of specialized machining processes including drilling, boring, reaming, broaching, honing, lapping, and waterjet machining. These processes cater to diverse end-use applications, including automotive and aerospace industries, where precision and quality are critical. The demand for advanced machining technologies drives investment in innovation and product development across various sectors.
Technological maturation significantly influences segment expansion. The integration of automation and CNC technologies enhances operational efficiency and precision in machining processes. This evolution facilitates the production of intricate components that meet stringent quality standards, aligning with the regulatory compliance requirements prevalent in industries including medical and aerospace.
Consumption shifts towards more complex and precise components generate opportunities for growth within this segment. Industries increasingly prioritize high-quality machining solutions to address the rising demand for customized products. The focus on optimizing manufacturing processes encourages manufacturers to explore innovative machining techniques, influencing market dynamics.
Strategic opportunity windows emerge because manufacturers seek to enhance their capabilities. Investments in next-generation upgrades and disruptive technologies strengthen competitive positions in the market. The ongoing exploration of alternatives to traditional machining methods enables firms to optimize their operational frameworks, ensuring adaptability to evolving market demands.
Valued at USD 41.3 billion in 2026, the automotive segment is projected to reach USD 69.8 billion by 2033, at a CAGR of 7.8% during the forecast period. This growth stems from rising demand for more efficient and technologically advanced vehicles, driven by increasing consumer expectations and regulatory standards aimed at emissions reduction. Major automotive manufacturers increasingly adopt precision machining techniques to enhance the performance and reliability of vehicle components, contributing to the segment's expansion.
Technological maturation plays a critical role in this segment, with innovations in automation and robotics streamlining manufacturing processes. The transition towards electric and hybrid vehicles further influences precision machining. These vehicles require specialized components that demand high precision. Investment in next-gen upgrades, including advanced CNC machines and laser machining, enhances production capabilities, ensuring manufacturers meet strict quality and performance standards.
Consumption shifts towards advanced safety and entertainment features in vehicles necessitate high-quality components, leading to increased adoption of precision machining. Regulatory compliance standards focused on safety and environmental impact compel manufacturers to invest in precision machining technologies, driving segment growth. Cost structures reflect ongoing investments in technology, while pricing volatility in raw materials impacts margins.
With ongoing advancements and strategic opportunity windows, the automotive segment of the precision machining market is poised for substantial growth. Increasing complexity in vehicle design and functionality dictates the need for sophisticated machining solutions, positioning this segment because a crucial component of the overall market evolution.
A strong push toward modernization within the aerospace and defense sectors drives demand for precision machining technology. Significant investments in advanced aircraft, military vehicles, and defense systems contribute to this trend. The sector emphasizes high precision and reliability, necessitating machining processes that meet stringent requirements and certifications.
Technological advancements play a critical role in the aerospace and defense segment's evolution. Continuous improvements in CNC operation and next-generation machining technologies enhance production capabilities, resulting in increased efficiency and reduced lead times. This evolution aligns with the industry's focus on innovation and cost-effectiveness, establishing it because a priority for manufacturers.
Valued at USD 47.1 billion by 2033, the aerospace and defense segment is projected to achieve a CAGR of 9.6% during the forecast period. This growth reflects the increasing demand for precision components in various applications, including commercial aviation and military equipment. The market's expansion hinges on technological maturation and the adoption of advanced machining solutions.
Regulatory compliance and certifications remain essential factors influencing market dynamics. Manufacturers adhere to strict quality standards to secure contracts in the aerospace and defense industries. This focus on compliance impacts cost structures and pricing volatility, prompting companies to invest in robust quality control systems and processes.
Strategic opportunity windows arise from the ongoing shift toward sustainability and environmentally friendly practices in manufacturing. Companies positioned to innovate and adapt to these shifts are likely to capture greater market share in the precision machining market. The emphasis on advanced materials and manufacturing techniques will shape future growth trajectories.
Demand for precision machining services within the medical sector exhibits strong growth driven by advancements in healthcare technology and increasing requirements for high-quality medical devices. The rise in chronic diseases and an aging population fuels the need for innovative medical solutions, intensifying demand for precision-engineered components. Compliance with stringent regulatory standards and certifications necessitates suppliers to maintain high-quality manufacturing processes, further supporting market expansion. Continuous improvements in machining technologies, including CNC operations, enhance production efficiency and precision, leading to increased adoption in medical applications.
Investment in research and development within the medical industry accelerates the evolution of medical devices, creating a strategic opportunity for precision machining companies. This segment is projected to reach USD 35.3 billion by 2033, reflecting a robust market trajectory. Collaboration between manufacturers and healthcare providers drives innovation and supports the introduction of next-generation medical technologies, which in turn influences consumption shifts in the market. Cost structures and pricing volatility in raw materials impact operational efficiencies, compelling companies to adopt sustainable sourcing strategies to mitigate risks. Overall, the medical segment represents a critical component of the precision machining market, contributing significantly to its overall growth.
Growth in the Industrial Machinery segment aligns with increasing demand for automation and precision in manufacturing processes. This demand arises from the need for higher efficiency and productivity, pushing manufacturers to adopt advanced machining solutions. Technological maturation, particularly in CNC operations, drives the segment forward, enabling manufacturers to achieve improved precision and reduced lead times.
Investment in next-generation upgrades significantly influences the segment's expansion. Companies seek to modernize their equipment to enhance capabilities and meet evolving industry standards. Regulatory compliance, particularly for safety and environmental considerations, necessitates the adoption of advanced machining technologies, propelling market growth.
Valued at USD 41.3 billion in 2026, the Industrial Machinery segment is projected to grow at a CAGR of 6.9% during the forecast period. This growth reflects strong demand for precision machining solutions capable of meeting the rigorous quality standards of various end-use applications.
Consumption shifts towards automated solutions, driven by the growing focus on operational efficiency, support the segment’s growth trajectory. Manufacturers committed to enhancing their production processes find strategic opportunities in the adoption of innovative machining technologies. This growth highlights the importance of precision machining in supporting the evolving needs of the Industrial Machinery sector, contributing significantly to the overall Precision Machining market.
Electronics represents a growing sector within the Precision Machining market, driven by the increasing demand for high-performance components across various applications. The proliferation of consumer electronics, including smartphones, wearables, and smart home devices, significantly influences the adoption of precision machining technologies. Manufacturers require intricate components that meet stringent quality and performance specifications, compelling suppliers to enhance their capabilities and invest in advanced machining solutions.
Technological maturation in the electronics industry promotes innovation and efficiency, prompting manufacturers to upgrade their machinery and processes. Next-generation upgrades focus on automation and digitization, allowing for improved precision, speed, and scalability. Product evolution in the electronics sector emphasizes miniaturization, requiring precision machining processes to adapt and deliver components that align with compact designs.
Downstream applications in sectors including telecommunications and computing drive consumption shifts, leading to heightened expectations for quality and durability. Regulatory compliance standards and certifications continue to play a critical role, ensuring that products meet safety and environmental requirements. While demands increase for sustainable practices, manufacturers face pressure to optimize cost structures and navigate pricing volatility while maintaining quality.
Supply chain resilience becomes essential owing to fluctuations in raw material sourcing that impact the market landscape. The threat of substitution risks from emerging technologies necessitates a focus on disruptive alternatives that provide competitive advantages. Strategic opportunity windows arise because market players leverage advancements in technology and explore new applications, strengthening their positions in the Precision Machining market.
Investment in capital continues to shape prospects for growth, with stakeholders prioritizing funding for innovations that enhance production capabilities. The electronics sector's dynamic nature presents both challenges and opportunities, driving continuous evolution in precision machining practices.
Demand for precision machining within the Energy & Power, Oil & Gas, Marine, Railways, Telecommunications, and General Engineering sectors involves several dynamics. Primary demand drivers include the need for enhanced efficiency and reliability in equipment used across these industries. Regulatory compliance standards often dictate the adoption of advanced machining techniques, pushing manufacturers to invest in high-quality precision machining solutions. The evolution of technology in these sectors, particularly in telecommunications and renewable energy, emphasizes the necessity for precise components, encouraging greater adoption of modern machining processes.
Segment expansion drives interest in innovative applications, influenced by the increasing complexity of machinery and the demand for customized solutions. Adoption of next-generation upgrades in machinery leads to improved operational performance and reduced downtime, ultimately influencing the purchasing decisions of end-users. Consumption shifts toward sustainable practices in energy generation and reduced emissions in marine applications create opportunities for precision machining to support environmental compliance. Investments in infrastructure development within the railways and energy sectors further enhance demand, positioning the market for growth.
Cost structures remain a critical consideration in the precision machining market, influenced by raw material sourcing and pricing volatility. Fluctuations in material costs compel manufacturers to optimize their supply chains and explore alternative materials that deliver comparable performance. Strategic opportunity windows arise from technological advancements that facilitate the development of disruptive alternatives, allowing manufacturers to enhance margins while meeting industry standards. Overall, the integration of precision machining services across these sectors supports the drive for modernization and efficiency, reinforcing its vital role in the market.
Valued at USD 58.7 billion in 2026, the Standard Precision segment is projected to reach USD 91.8 billion by 2033, at a CAGR of 6.6% during the forecast period. Demand drivers include the increasing need for high-quality manufacturing processes across various industries. Advancements in technology and the growing emphasis on precision across sectors including aerospace, automotive, and medical influence adoption rates. The segment expands due to the rising application of standard precision components in critical end-use industries, enhancing overall product reliability and performance.
Technological maturation significantly enhances the capabilities of standard precision machining techniques. The evolution of next-generation upgrades contributes to improved efficiency and cost-effectiveness for manufacturers. Steady growth in downstream applications, alongside consumption shifts towards more precise components, reinforces the segment's importance within the Precision Machining market. Regulatory compliance and certifications establish trust and reliability, driving continued investment and innovation.
Cost structures in the Standard Precision segment remain competitive; however, pricing volatility presents challenges that require strategic management by manufacturers. Margin pressures arise from fluctuations in raw material prices and the need for continuous technological upgrades. Supply chain resilience is critical in mitigating logistics vulnerabilities and maintaining consistent quality standards. Substitution risks from emerging technologies pose challenges, necessitating a focus on innovation and adaptation within the market.
Strategic opportunity windows arise from the increasing demand for high-precision components, positioning the Standard Precision segment for sustained growth. The capital investment outlook remains positive, with industry players focusing on expanding operational capabilities and enhancing product portfolios. These dynamics collectively support the segment's growth trajectory and reinforce its position within the broader Precision Machining market.
Growth in the High Precision segment aligns with advancements in technology, leading to a surge in demand across various end-use industries. Increasing requirements for accuracy and quality in sectors including aerospace and defense, automotive, and medical drive market expansion. Manufacturers prioritize high precision machining to meet rigorous standards and enhance product performance, contributing to the segment's estimated value of USD 94.1 billion by 2033, at a CAGR of 9% during the forecast period.
Technological maturation plays a significant role in the adoption of high precision machining techniques, enabling the introduction of next-generation upgrades. Enhanced machining capabilities, including multi-axis CNC machines and sophisticated software solutions, enable manufacturers to achieve tighter tolerances and complex geometries. This evolution in product offerings meets the diverse needs of industries and positions the segment favorably for sustained growth.
End-use dynamics within the Precision Machining market reflect shifting consumption patterns, with industries increasingly leaning towards high precision solutions to maintain competitiveness. Regulatory compliance standards necessitate adherence to stringent metrics, pushing manufacturers to invest in high precision technologies. These trends contribute to robust demand for high precision machining services, creating a positive outlook for market participants.
Pricing volatility and margin pressures specific to the high precision segment impact the operational strategies of manufacturers. Fluctuations in raw material costs and the competitive landscape necessitate strategic planning and investment to enhance supply chain resilience. Focusing on high precision capabilities allows suppliers to differentiate themselves and capture emerging opportunities, driving growth within the Precision Machining market.
Technological advancements in Ultra-Precision / Micro-Machining drive significant demand within the Precision Machining market. Industries including aerospace, medical, and electronics increasingly rely on ultra-precision components for applications that require exacting tolerances and intricate designs. The segment is expected to reach USD 49.4 billion by 2033, reflecting a growing emphasis on high-precision manufacturing processes.
Adoption of ultra-precision techniques is fueled by the need for enhanced performance and efficiency in end-use applications. The increasing complexity of products across various sectors necessitates improved machining capabilities, which in turn influences manufacturers to invest in advanced machinery and technologies. This trend signifies a shift towards higher-value production processes, contributing to overall market growth.
Regulatory compliance standards and certification requirements play a vital role in shaping the Ultra-Precision / Micro-Machining segment. Manufacturers are obligated to adhere to stringent quality measures, enhancing the demand for reliable and certified machining processes. Increased scrutiny in the aerospace and medical industries particularly increases the necessity for ultra-precision solutions.
Cost structures and pricing volatility present challenges specific to this segment. Fluctuations in raw material costs impact overall production expenses, compelling manufacturers to optimize their operations. Strategic investment in advanced technology serves because a countermeasure against these pressures, allowing companies to maintain competitive pricing while ensuring quality and precision.
Strategic opportunities within the market continue to emerge, particularly in response to evolving consumer demands for high-performance products. Manufacturers capable of leveraging innovations in ultra-precision technologies are well-positioned to capture increased market share. This trajectory highlights the critical importance of continuous improvement and adaptation in the Precision Machining market.
Based on geography, the Global Precision Machining market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
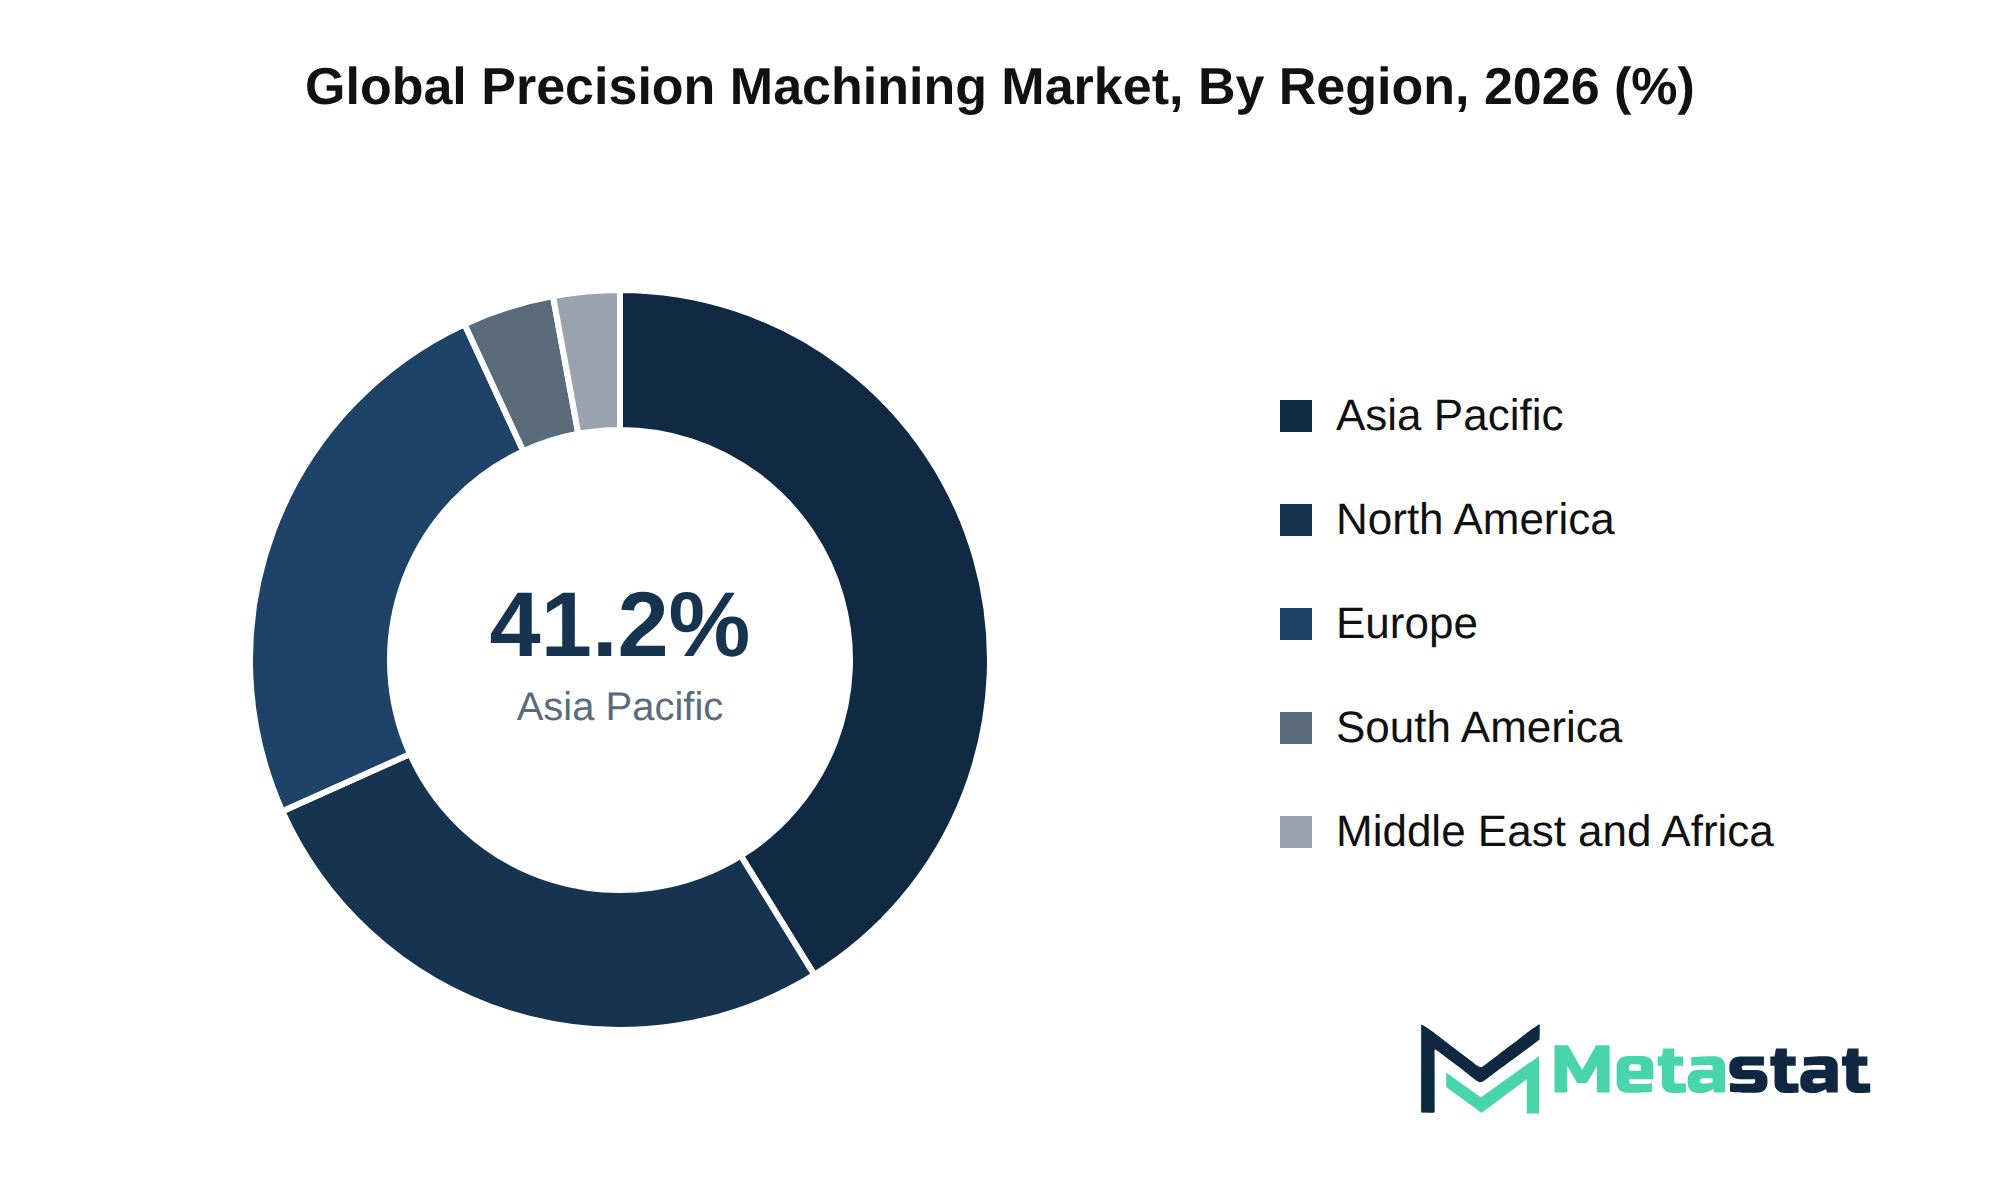
North America Precision Machining Market is set to expand at a CAGR of 8.4% within the forecast period, reaching a market size (TAM) of USD 57.9 billion by the end of 2033. The region's significant share of the global market, accounting for 27.1% in 2025, indicates strong demand driven by various factors.
Growth in the Precision Machining market in North America stems from the region's robust industrial base, particularly in sectors including automotive and aerospace. These industries increasingly require high-precision components, resulting in heightened demand for advanced machining technologies, including CNC operations and laser machining. The strong focus on innovation and modernization within manufacturing processes drives the expansion of these segments.
Infrastructure modernization enhances production capabilities. Investments in advanced manufacturing technologies, combined with localized manufacturing densities, contribute to improved efficiency and cost-effectiveness. This trend promotes the adoption of precision machining solutions across various sectors, further driving market growth.
Emerging market front-runners within North America benefit from the region's favorable business environment and access to advanced technologies. Domestic market leaders leverage foreign direct investment flows to enhance production capacities and expand their service offerings. Increased competition among local vendors encourages innovation, resulting in the development of advanced machining solutions tailored to meet specific industry demands.
The localized procurement dynamics in North America reflect the cultural nuances and regional B2B buying behaviors that influence purchasing decisions. Manufacturers prioritize sourcing from nearby suppliers to streamline operations and reduce lead times. This trend enhances regional supply chain regionalization and nearshoring initiatives, further enhancing market attractiveness.
The Precision Machining market in Europe exhibits significant growth potential, driven by advancements in various end-use industries, particularly automotive and aerospace. Notable countries in this region, including Germany, France, the UK, Italy, Spain, and Russia, contribute to a substantial market share in 2025. The automotive sector's escalating demand for high-precision components influences operational strategies among manufacturers, encouraging investment aimed at enhancing production capabilities.
Technological innovations and a robust supply chain system strengthen the regional competitive landscape. Local manufacturers prioritize efficiency through nearshoring initiatives, adapting to changing market demands while capitalizing on geographic advantages. Infrastructure modernization remains a priority, with investments in advanced machining technologies expected to facilitate growth across various segments, including CNC operation and laser machining.
In response to evolving regulatory frameworks and compliance mandates, companies in Europe focus on local procurement dynamics. The presence of domestic market participants creates a competitive environment that encourages continuous improvement and innovation. The Precision Machining market in Europe is characterized by a blend of mature and emerging segments, with opportunities for incremental growth through high-value replacement cycles and targeted investments in underpenetrated territories.
Asia Pacific holds a dominant position in the Precision Machining market, accounting for 41.2% of the global market share in 2025. The high demand for advanced manufacturing technologies in countries like China and Japan fuels market growth, driven by expanding industries including automotive and electronics. China's significant investment in automation and smart manufacturing enhances the adoption of precision machining technologies, leading to improved operational efficiencies.
India's growing manufacturing sector, supported by government initiatives and foreign direct investment, positions it because an emerging market front-runner. The country's focus on becoming a global manufacturing hub attracts investments in precision machining capabilities. South Korea benefits from its robust electronics industry, where precision machining is essential in producing high-quality components.
Infrastructure modernization across Southeast Asia contributes to the Precision Machining market's expansion, with countries investing heavily in upgrading facilities and equipment. The region's increasing emphasis on quality and precision in manufacturing creates opportunities for advanced machining solutions. Local compliance mandates and regulatory frameworks further drive the need for high-precision machining technologies.
Market dynamics in Asia Pacific demonstrate a blend of mature and emerging market characteristics. High-value replacement cycles for aging machinery present incremental growth vectors, encouraging manufacturers to seek modern precision machining solutions. The regional competitive landscape features a mix of domestic leaders and international players, driving innovation and enhancing service offerings.
Localized procurement dynamics, coupled with cultural nuances influencing B2B buying behaviors, shape the market landscape. While the region sees a rise in localized manufacturing densities, companies increasingly focus on regional supply chains, enhancing responsiveness to market demands. This trend benefits regional players by allowing them to tailor solutions to specific local needs and facilitating stronger customer relationships.
The Precision Machining market in South America reflects a growing interest in advanced manufacturing technologies, particularly in Brazil and Argentina. The region's market share stands at 4.00% of the global total in 2025. Factors influencing growth include increasing local manufacturing capabilities and investments in infrastructure modernization. Emerging domestic players contribute to a competitive landscape that supports innovation and efficiency.
Brazil and Argentina exhibit significant potential in precision machining, driven by expanding end-use industries including automotive and aerospace. Local compliance mandates encourage investments in technology, enhancing production capabilities and operational efficiency. The market benefits from cross-border trade corridors that facilitate the flow of goods, enabling easier access to advanced machining solutions.
Continued foreign direct investment (FDI) flows support the development of localized manufacturing densities. This trend highlights the importance of strategic entry barriers and geographic expansion windows favoring new entrants. Regional resource availability and energy grid resiliency are crucial factors enabling the market's growth trajectory, aligning with broader economic trends across South America.
The Precision Machining market in the Middle East and Africa accounts for a share of 2.9% of the global market in 2025. Growth in this region is driven by increasing investments in infrastructure modernization, particularly in Saudi Arabia and the UAE, because local governments prioritize development projects. Emerging industries, including aerospace and defense, contribute to the demand for precision machining services. South Africa, with its established manufacturing base, significantly enhances market growth.
Localized manufacturing densities drive supply chain regionalization, with companies focusing on nearshoring initiatives to capitalize on proximity to key markets. The market benefits from foreign direct investment flows, which further support the establishment of manufacturing capabilities across the region. Cross-border trade corridors facilitate access to essential resources, while geopolitical factors influence trade dynamics.
Domestic market leaders, including established firms in Saudi Arabia and the UAE, contribute to shaping competitive landscapes, prompting vendor consolidation trends. Cultural nuances and regional B2B buying behaviors impact procurement dynamics, leading companies to adapt their strategies for effective market engagement. Regional resource availability and energy grid resiliency remain critical factors in enhancing operational capabilities for precision machining firms.
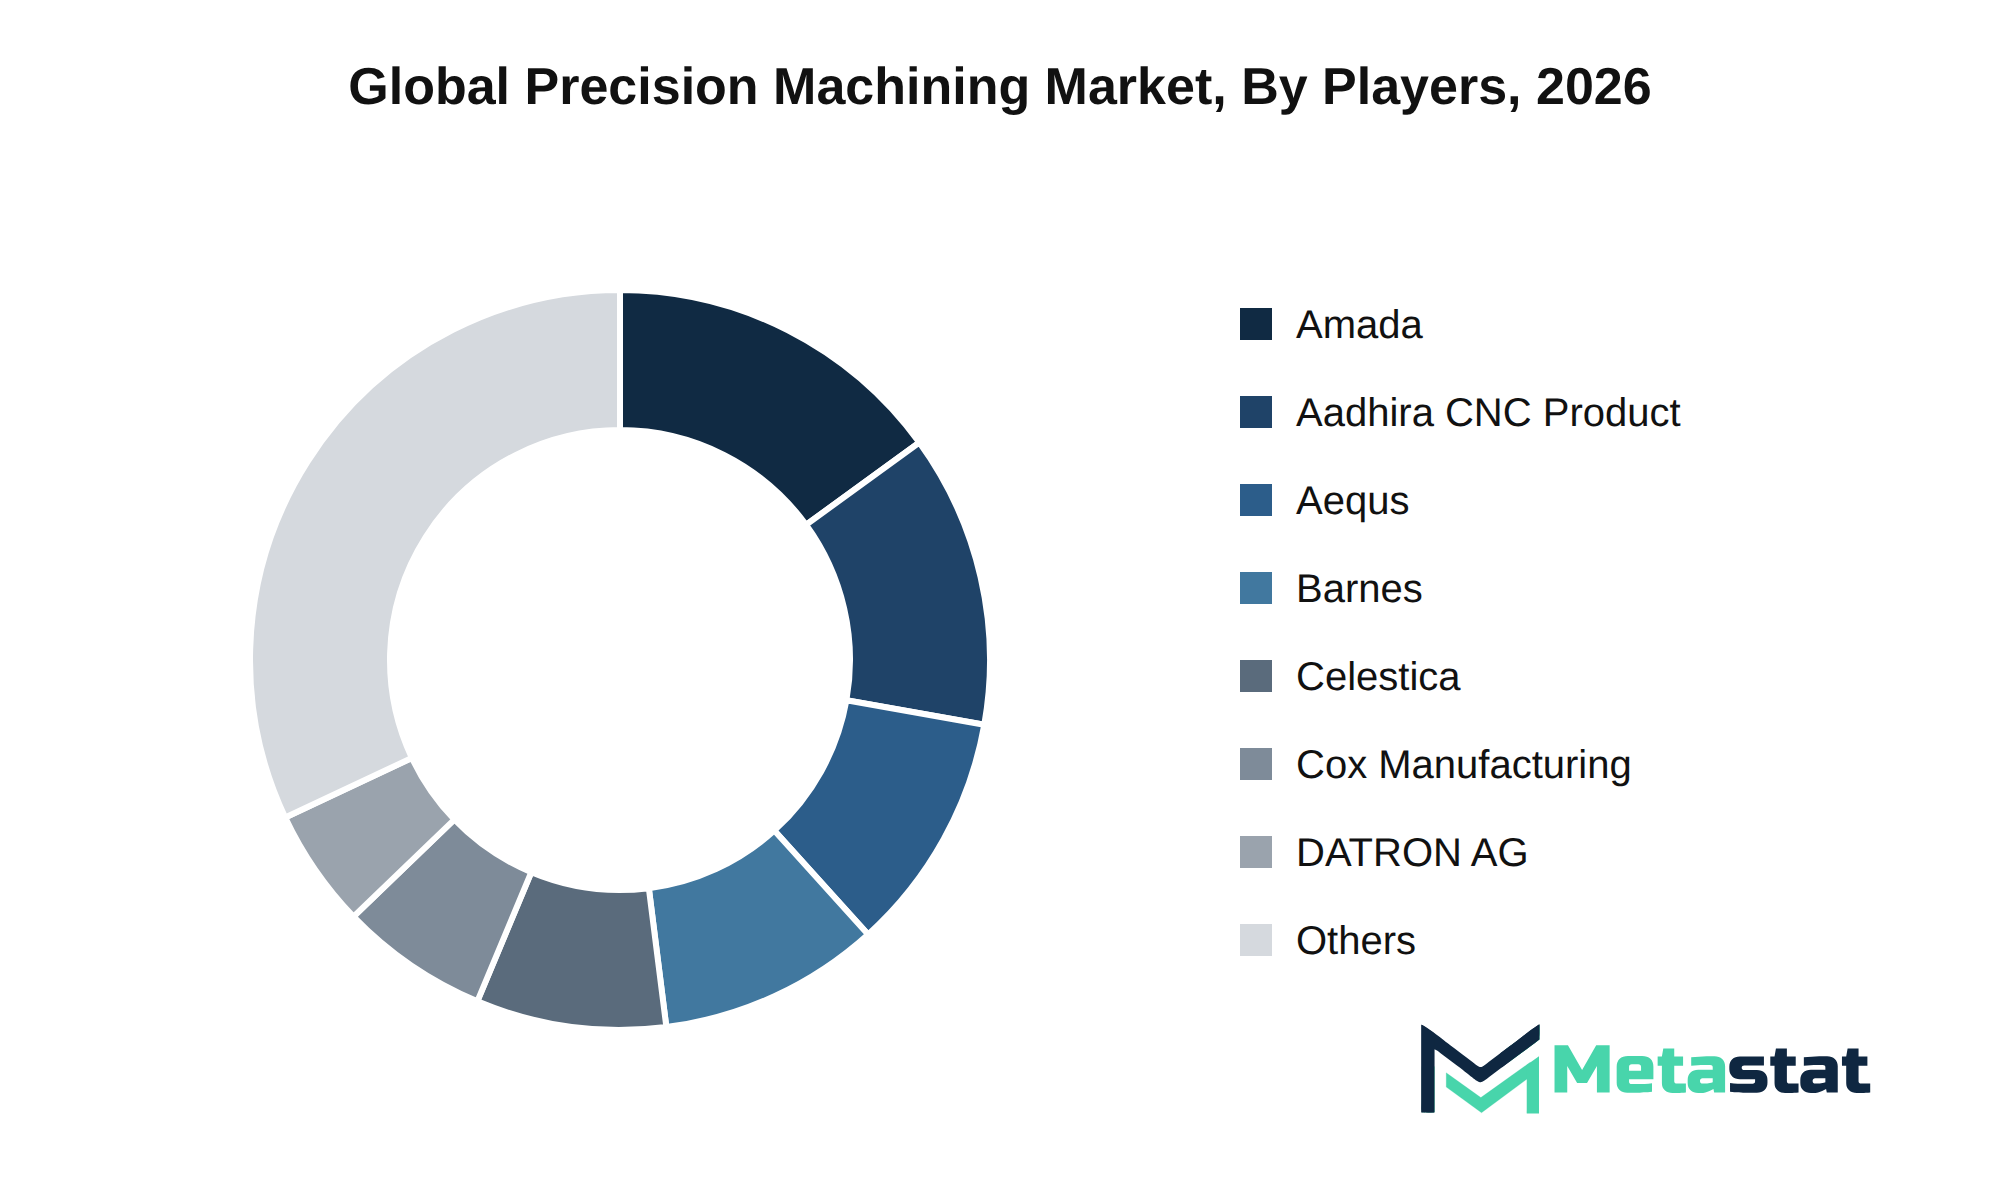
The Precision Machining market experiences a dynamic environment characterized by significant mergers and acquisitions that enhance market share and broaden capabilities among key players. Companies like DMG Mori Co., Ltd. and Haas Automation, Inc. focus on strategic consolidation, which increases operational efficiencies and expands technological portfolios.
Strategic alliances and partnerships play a vital role in shaping the competitive framework. Firms including FANUC Corporation and Amada Co., Ltd. collaborate with various industries to leverage technological advancements and enhance product differentiation. Their focus on research and development drives innovation, enabling maintenance of a competitive edge in the market.
Barriers to entry create challenges for new entrants, particularly in technology-intensive segments. Established firms benefit from strong brand equity and customer retention strategies that strengthen market positions. The presence of robust intellectual property portfolios enhances competitive stances, providing a technological moat against potential disruptors.
The future competitive outlook in the Precision Machining market indicates a continued focus on integrating value chains and optimizing supply chains to achieve procurement leverage. Key players are investing in proprietary technologies and expanding commercial models, positioning themselves to capitalize on emerging opportunities while navigating the complexities of the market landscape.
Market size is projected to rise from USD 123.4 billion in 2025 to over USD 235.4 billion by 2033. This growth reflects an 8.4% compound annual growth rate (CAGR). A robust macroeconomic environment supports this expansion, characterized by increased downstream demand across various industries including automotive and aerospace. Next-generation technology integration influences product innovation cycles, facilitating advancements in precision machining capabilities.
In this evolving landscape, regulatory evolution and compliance milestones drive manufacturers to adapt operations to meet emerging standards. Geopolitical realignments and shifting trade corridors impact supply chain dynamics, creating both challenges and opportunities. Strategic capital allocation directives emphasize the importance of investing in infrastructure and R&D to enhance productivity and operational efficiency.
Emerging white-space opportunities prompt players in the precision machining market to address unmet enterprise needs, particularly in high-growth sectors. Executive-level strategic imperatives guide firms in navigating these complexities, ensuring defensibility and long-term growth. While the market matures, identifying high-growth pockets becomes essential for sustaining competitive advantages in an increasingly interconnected global economy.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Precision Machining market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 8.4% from 2026 to 2033 |
|
Revenue Unit |
USD billion |
|
Segmentation |
By Type, Machining Type, End-use Industries, Precision Level, and Region |
|
By Region |
North America (By Type, Machining Type, End-use Industries, Precision Level, and Country)
|
|
Europe (By Type, Machining Type, End-use Industries, Precision Level, and Country)
|
|
|
Asia Pacific (By Type, Machining Type, End-use Industries, Precision Level, and Country)
|
|
|
South America (By Type, Machining Type, End-use Industries, Precision Level, and Country)
|
|
|
Middle East and Africa (By Type, Machining Type, End-use Industries, Precision Level, and Country)
|
Find answers to common questions about this report
The Precision Machining market size was valued at USD 123.4 billion in 2025, according to the Metastat Insights study.
The Precision Machining market is projected to grow at a CAGR of 8.4% during the forecast period from 2026 to 2033.
The North America Precision Machining market size is estimated to reach USD 57.9 billion by 2033.
CNC Operation leads the Precision Machining market with a projected value of USD 189.8 billion by 2033, surpassing Manual Operation, which is expected to reach USD 45.5 billion in the same year.
Key drivers for the Precision Machining market include substantial investments in advanced manufacturing technologies, particularly automation and artificial intelligence, which enhance operational efficiency and productivity. The rising demand for customized solutions in sectors including automotive and aerospace encourages manufacturers to adopt flexible machining solutions.
High capital investment requirements deter potential entrants and existing players from expanding operations, limiting market participation. Ongoing operational costs, including maintenance and workforce training, strain financial resources, hindering the adoption of innovative practices. workforce skill gaps and regulatory standards create further challenges for growth within the Precision Machining market.
Substantial investments in advanced manufacturing technologies, particularly automation and artificial intelligence, favor product adoption in the Precision Machining market. The integration of smart technologies enhances operational efficiency and productivity, allowing manufacturers to respond swiftly to evolving consumer preferences and market dynamics.
The Precision Machining market is estimated to reach a valuation of USD 235.4 billion by 2033.
Key players in the Precision Machining market include Aadhira CNC Product, Ace Precision Machining, Amada Co., Ltd., DMG Mori Co., Ltd., FANUC Corporation, Haas Automation, and HERMLE AG.
Demand in the Precision Machining market is driven by advancements in automation and artificial intelligence, which enhance operational efficiency and productivity across various industries.
Choose Your License
Global Precision Machining Market
The analysts below cover Machinery & Equipment research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
INDUSTRY CONSULTANT - CHEMICALS & ADVANCED MATERIALS
Chemicals and Materials · Machinery & Equipment · Packaging
Amit Gadhekar Consultant for Chemicals and Materials at MetaStat Insight, directing sector-specific intelligence, research, and strategic consulting across global chemical and processing markets.
PRINCIPAL CONSULTANT - QUALITY SYSTEMS & COMPLIANCE
Electronics and Semiconductor · Machinery & Equipment · Professional Services
Omkar Phadtare is an Industry Consultant at MetaStat Insight, specializing in quality systems, regulatory compliance, and standards benchmarking to drive data-driven market intelligence and strategic industry research.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Ambulatory surgical centers have very different purchasing cycles for robotic-assisted surgery platforms than major hospital networks. The MetaStat Insight study focused squarely on capital expenditure depreciation, procedural reimbursement pathways, and surgeon training overhead. That operational clarity made it much simpler to validate multi-year procedure growth forecasts against actual ambulatory center adoption patterns.
When planning edge sensor rollouts across refinery environments, generic IoT reports typically miss the harsh-environment certification bottlenecks. MetaStat Insight gave an objective evaluation of ATEX and Class 1 Division 2 hardware availability, along with realistic five-year maintenance cycle cost projections. The comparison of wireless mesh versus private cellular backhaul helped our team pressure-test network reliability models for remote processing facilities.
In the biological seed treatment space, registration timelines vary drastically between the European Union, Brazil, and North America. The MetaStat Insight research handled these cross-border regulatory barriers with genuine nuance, mapping commercialization pathways alongside historical field adoption rates. The segmentation between microbial strains and biochemical active ingredients was particularly well structured.
Explore related market intelligence reports worth reading alongside this one.