
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global 5G Smartphones MLCC Market Size, Share, By MLCC Product Type (General-Purpose MLCCs, High-Q / RF MLCCs, Low-ESL / Multi-Terminal MLCCs, High-Capacitance MLCCs, Ultra-Small / Low-Profile MLCCs, Others), By Dielectric / Temperature Characteristic (C0G/NP0, X5R, X6S, X7R, X7S, Others), By Case Size (008004 (0201 Metric), 01005 (0402 Metric), 0201 (0603 Metric), 0402 (1005 Metric), 0603 (1608 Metric), 0805 and Larger), By Smartphone Circuit Application (Cellular RF Front-End and Antenna Matching, Application Processor and Baseband, Power Management and DC-DC Conversion, Memory and Storage, Display and Touch, Camera and Imaging, Non-Cellular Wireless Connectivity, Audio and Haptics, Charging and Battery Management, Others), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5303
September 18, 2026
287 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $3,913 Million in 2025, projected to reach $7,914.5 Million by 2033 at a 9.2% CAGR.
Dominant Segment: The General-Purpose MLCCs segment leads the market, driven by the increasing complexity of electronic circuits in 5G smartphones, which require robust capacitors for power management and signal processing.
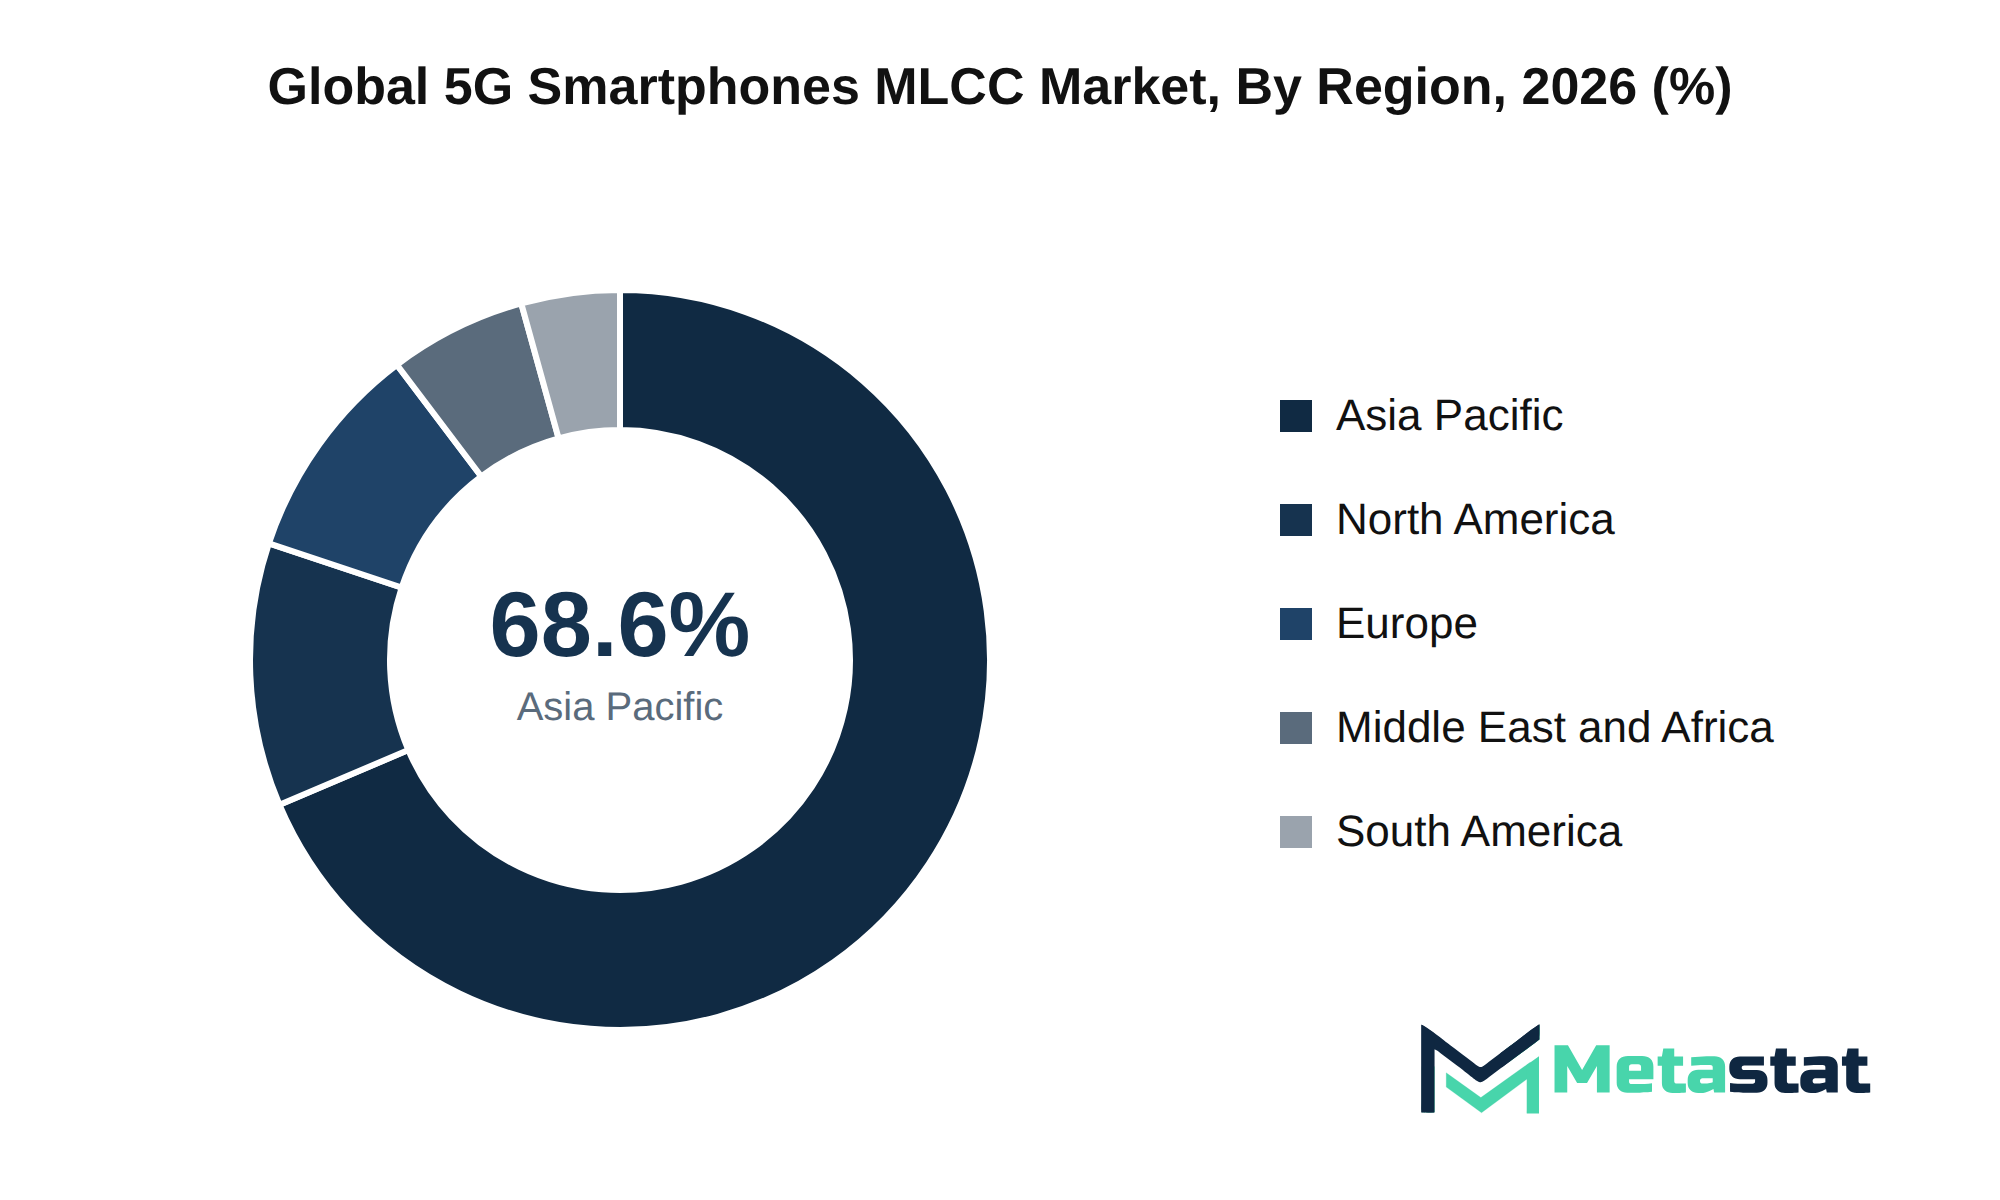
Geographic Lead: Asia Pacific dominates the market, holding 68.6% of the share, fueled by rising smartphone penetration and consumer preference for advanced mobile connectivity.
What's Inside: The report includes detailed competitive coverage, market segmentation by product type, dielectric characteristics, case sizes, and smartphone circuit applications, along with industry analysis and growth forecasts.
Emerging Trends: The shift towards ultra-small and low-profile MLCCs is transforming circuit designs, enabling compact and efficient smartphone architectures essential for advanced 5G functionalities.
The global 5G Smartphones MLCC market was valued at USD 3,913 million in 2025 and is projected to reach USD 7,914.5 million by 2033, growing at a CAGR of 9.2% over the forecast period.
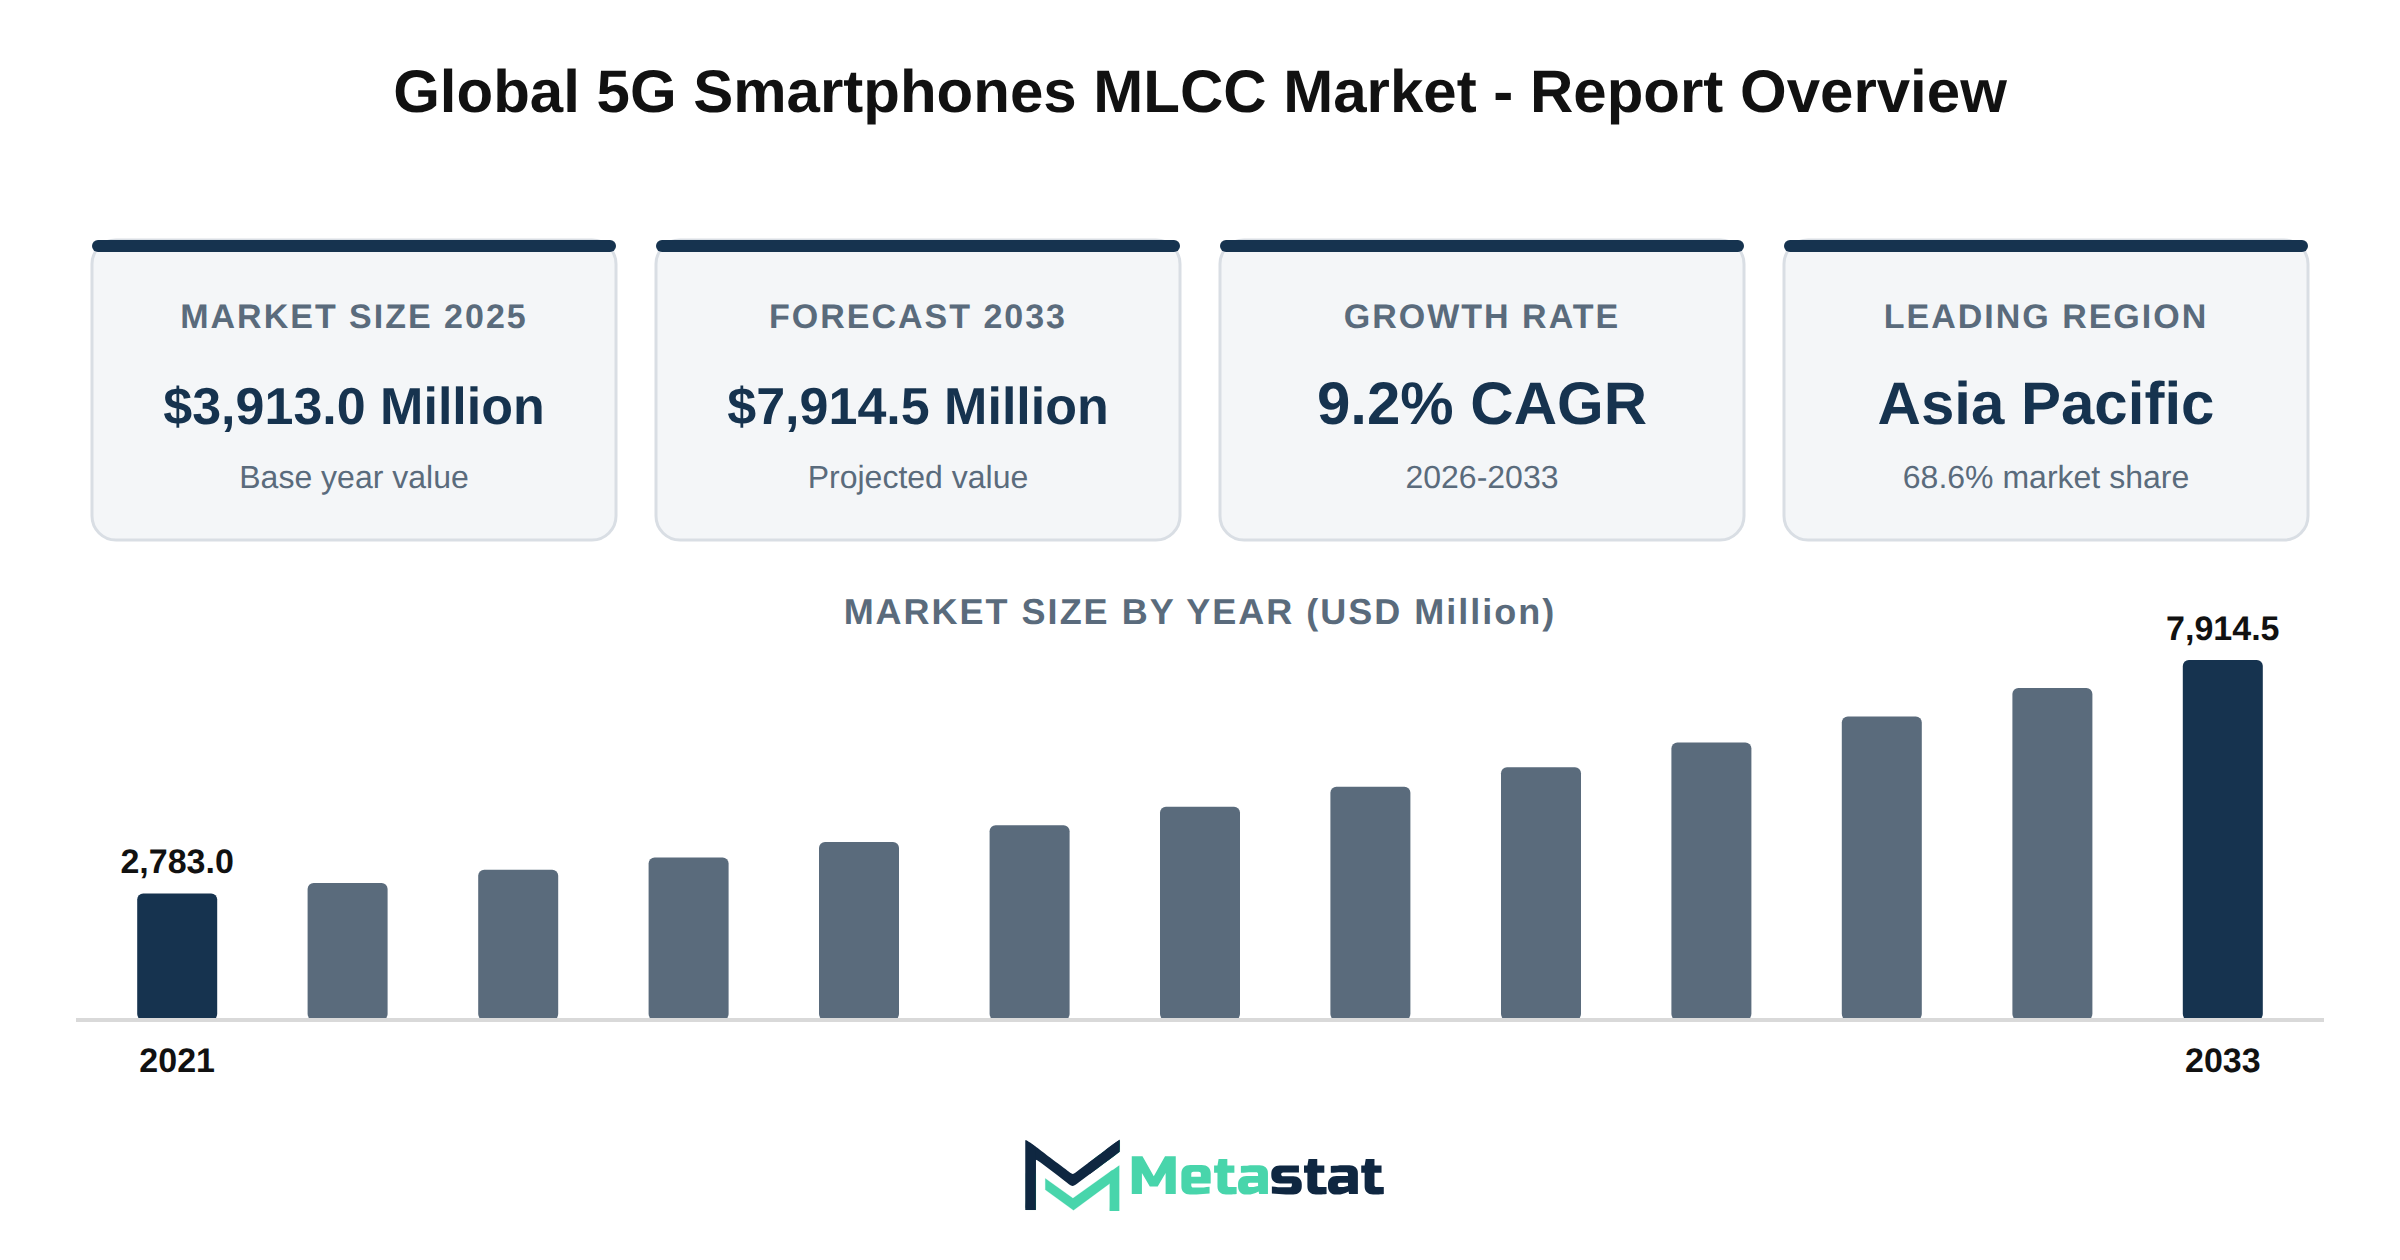
The 5G Smartphones MLCC market experiences significant demand driven by rising capacitor content per device. The increasing complexity of 5G smartphones correlates with a higher integration of capacitors in their designs, leading to an upward trend in MLCC consumption. Premium smartphone models, particularly, demonstrate a notable increase in MLCC requirements, supporting the overall growth of the market.
Ultra-miniature MLCC adoption is transforming 5G smartphone circuit designs. The integration of ultra-small MLCCs allows for more compact and efficient circuitry, crucial for the advanced functionalities of 5G smartphones. A shift towards high-Q and RF MLCCs is evident, driven by the need for enhanced performance in 5G front-end architectures.
Low-ESL MLCCs experience growth within advanced smartphone power delivery networks, meeting the demand for efficient power management solutions. High-capacitance MLCC integration plays a critical role in application processors and baseband systems, ensuring optimal performance in 5G devices.
The market shows significant trends in case size miniaturization, with 01005 and 008004 MLCCs becoming increasingly prevalent in premium 5G smartphones. This miniaturization trend supports the overall reduction in device size while maintaining performance standards. The complexity of 5G RF front-end designs is escalating, resulting in increased MLCC content per handset, which further contributes to the market’s expansion.
Power management and DC-DC conversion applications are expanding, leading to increased MLCC consumption across various smartphone segments. MLCC requirements for connectivity technologies, including Wi-Fi, Bluetooth, GNSS, and NFC, continue to rise, reflecting the growing demand for efficient communication in 5G smartphones.
Advanced camera systems drive higher MLCC density in smartphones, resulting from manufacturers integrating more sophisticated imaging technologies. Demand for X5R and X7R dielectrics in high-density 5G smartphone electronics highlights the need for stable performance under varying conditions. C0G and NP0 MLCCs remain critical for high-frequency RF applications, ensuring reliability in performance.
Smartphone PCB miniaturization reshapes MLCC case size demand, challenging manufacturers to adapt to evolving specifications. Thermal performance and capacitance stability requirements in 5G smartphones become increasingly important, prompting innovations in MLCC technology.
Production trends in the 5G smartphone sector influence global MLCC demand. Asia Pacific holds a leadership position in both manufacturing and consumption of MLCCs, highlighting regional strengths in production capabilities and market engagement. Supplier capacity, localization, and procurement strategies play significant roles in the dynamics of smartphone MLCCs, affecting pricing and availability.
Competitive innovation among leading smartphone MLCC manufacturers drives advancements in technology. High-layer-count MLCC technology supports greater capacitance density, enabling manufacturers to meet the demands for high-performance 5G smartphones. Low-profile MLCC development caters to the trend of thinner smartphone designs, ensuring manufacturers deliver on consumer expectations for sleek devices.
Rising capacitor content per device drives demand in the 5G Smartphones MLCC market. The increasing complexity and advanced functionalities of 5G smartphones necessitate a higher number of MLCCs per unit, particularly in premium models.
Ultra-miniature MLCCs find significant adoption in 5G smartphone circuit design. These components enable manufacturers to optimize space while enhancing performance, a critical factor for the compact architecture of modern smartphones.
High-Q and RF MLCCs experience heightened demand across 5G front-end architectures. Their role in ensuring efficient signal processing and transmission aligns with the requirements set by evolving 5G technologies.
Low-ESL MLCC growth emerges in advanced smartphone power delivery networks. These components support efficient power management, crucial for high-performance devices that require reliable energy distribution.
High-capacitance MLCCs integrate into application processors and baseband systems, facilitating improved processing capabilities and connectivity features. This integration enhances overall device performance, contributing to the market's growth trajectory.
The miniaturization trends for 01005 and 008004 MLCCs significantly impact premium 5G smartphone designs. These smaller components allow for more efficient layouts, accommodating the increasing demand for advanced functionalities.
The complexity of 5G RF front-end designs increases MLCC content per handset. This trend reflects the need for enhanced performance and reliability in 5G applications, further supporting market expansion.
Power management and DC-DC conversion processes expand MLCC consumption in smartphones. This growing reliance on efficient energy management systems drives the demand for specialized components tailored for these applications.
MLCC requirements for Wi-Fi, Bluetooth, GNSS, and NFC connectivity remain critical in the 5G Smartphones MLCC market. The integration of various wireless technologies necessitates a diverse range of MLCCs to ensure robust performance.
Advanced camera systems contribute to higher MLCC density in smartphones. The increasing demand for superior imaging capabilities drives the need for more complex circuitry, resulting in increased MLCC integration.
X5R and X7R dielectrics gain traction for use in high-density 5G smartphone electronics. These materials provide the necessary performance characteristics to meet the demands of advanced electronic systems.
C0G and NP0 MLCCs experience sustained demand for high-frequency RF applications. Their stability and reliability make them ideal for critical functions in 5G devices.
Smartphone PCB miniaturization reshapes MLCC case size demand. The trend towards thinner and lighter devices influences the specifications and requirements for MLCCs, promoting further innovation in this area.
Thermal performance and capacitance stability requirements in 5G smartphones drive technological advancements in MLCC production. Manufacturers prioritize these attributes to align with the stringent performance expectations of modern devices.
5G smartphone production trends influence global MLCC demand patterns. The shift towards increased production volumes aligns with the anticipated rise in smartphone adoption, thereby impacting the supply chain dynamics.
Asia Pacific leads in 5G smartphone MLCC manufacturing and consumption. This region's established production capabilities and large consumer base support its dominance in the global market.
MLCC supply chain capacity expansion occurs across Asian manufacturing hubs. Increased demands for MLCCs compel manufacturers to enhance their production capabilities, ensuring they meet market needs effectively.
Nickel electrode and ceramic material cost trends affect MLCC pricing. Fluctuations in raw material prices directly influence the overall cost structure of MLCCs, impacting market pricing strategies.
Manufacturing yield challenges at ultra-small case sizes present significant obstacles. These challenges necessitate ongoing innovation in manufacturing processes to ensure quality and reliability in MLCC production.
Competitive innovation among leading smartphone MLCC manufacturers shapes the market. Companies invest in research and development to introduce advanced solutions that cater to the evolving needs of smartphone manufacturers.
High-layer-count MLCC technology supports greater capacitance density. This advancement enables manufacturers to produce more compact and efficient components, essential for modern 5G smartphones.
Low-profile MLCC development addresses the demand for thinner 5G smartphone designs. Manufacturers focus on creating components that fit seamlessly into the sleek profiles of contemporary devices.
AI-enabled smartphones drive increased processor and memory MLCC requirements. The integration of AI capabilities necessitates advanced circuitry, subsequently boosting the demand for high-performance MLCCs.
On-device AI and edge computing expand smartphone power circuit complexity. This trend results in higher MLCC consumption due to devices requiring enhanced power management solutions for efficient operation.
mmWave and sub-6 GHz 5G architectures shape RF MLCC demand. These emerging technologies necessitate specialized MLCCs to ensure optimal performance across various frequency bands.
Premium smartphone adoption supports high-value MLCC content growth. Consumers increasingly seek advanced features, leading to a rise in demand for specialized MLCCs that enhance device performance.
Mid-range 5G smartphone expansion broadens MLCC volume demand. The growing popularity of mid-range devices stimulates market activity, further driving the need for diverse MLCC solutions.
Smartphone charging technology influences battery management MLCC requirements. The evolution of charging systems necessitates specific MLCCs that ensure efficient power delivery and management.
MLCC reliability requirements for high-power 5G smartphone applications drive component innovation. Manufacturers focus on enhancing durability and performance to meet the demands of advanced applications.
Supplier capacity, localization, and procurement strategies significantly impact smartphone MLCCs. Companies strategically position themselves to navigate supply chain complexities and meet market demands effectively.
Future growth opportunities in next-generation 5G advanced smartphone MLCCs present promising prospects. Continued advancements in technology will shape the direction of the market, influencing investment and development strategies.
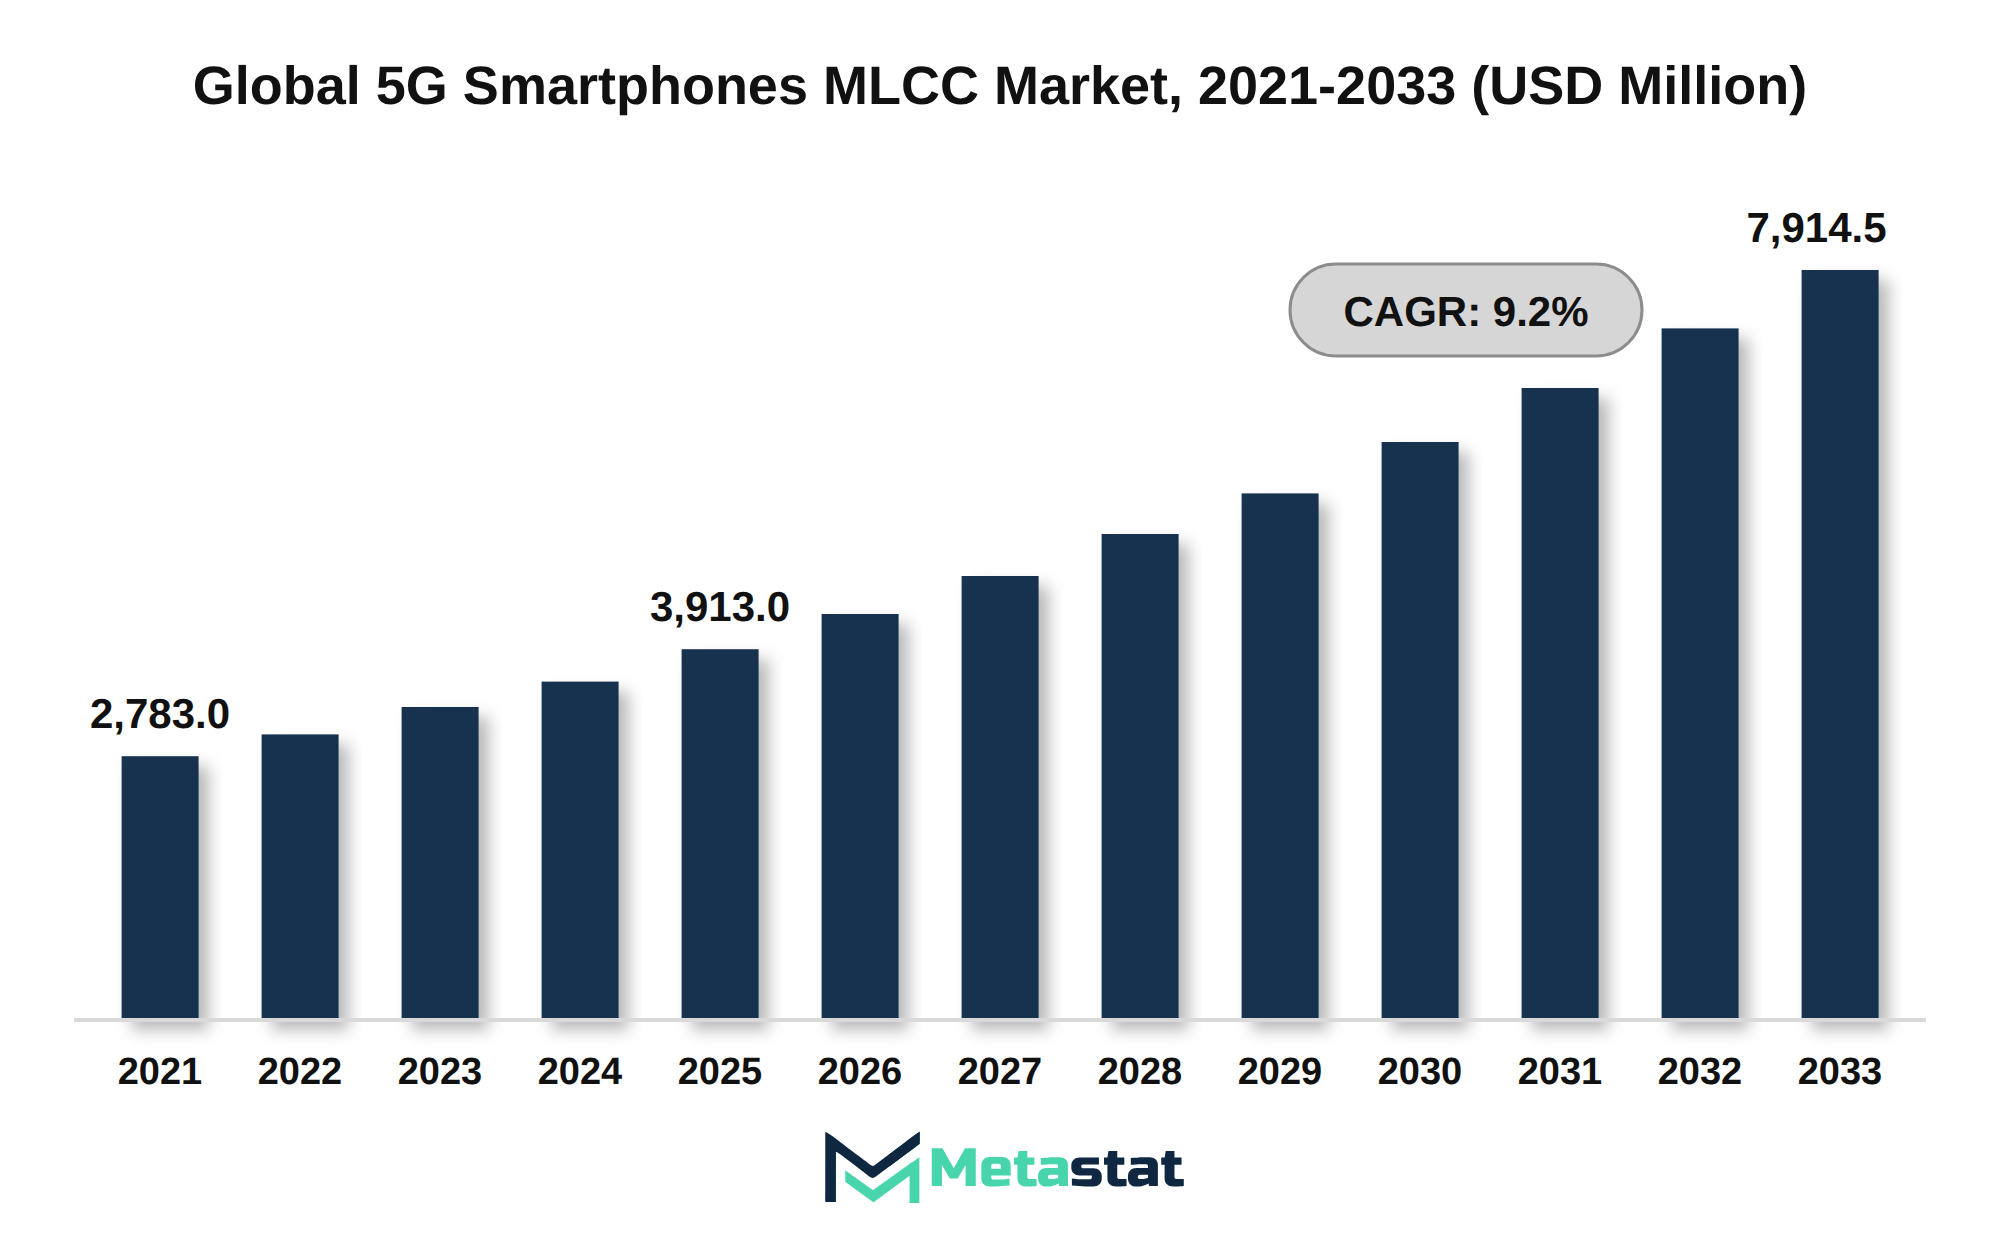
The demand for the 5G Smartphones MLCC market experiences significant growth due to the increasing global adoption of 5G technology in smartphones. Enhanced connectivity, faster data speeds, and improved user experiences associated with 5G-enabled devices drive this trend. Consumers increasingly prefer smartphones that support advanced features, contributing to heightened demand for high-quality multi-layer ceramic capacitors (MLCCs) essential for 5G functionality.
Mobile network operators invest significantly in upgrading infrastructure to support extensive 5G rollout. This investment leads to increased production and sales of 5G smartphones, generating demand for MLCCs. While smartphone manufacturers incorporate more advanced technologies into their devices, the need for higher-capacitance and more efficient capacitors continues to grow, further boosting the market.
Adoption of 5G technology within various sectors, including automotive, healthcare, and smart home applications, enhances overall market expansion. Industries integrating 5G capabilities into their products highlight the relevance of high-performance MLCCs. This integration drives innovation and supports diverse applications, propelling demand within the 5G Smartphones MLCC market.
Investment in digital transformation significantly influences the growth of the 5G Smartphones MLCC market. Enterprises prioritize upgrading technological capabilities to enhance operational efficiency and meet consumer expectations. This shift results from broader macroeconomic trends, including GDP growth and venture funding, which create an environment conducive to innovation and technological integration.
The expansion of 5G technology necessitates advanced components, including multilayer ceramic capacitors, to support enhanced functionality in smartphones. Rising smartphone adoption rates drive manufacturers to integrate higher quality and more capacitors within devices to improve performance and reliability. This pattern indicates a correlation between digital transformation initiatives and the demand for the market.
Investment in infrastructure modernization further supports the growth trajectory of the market. Businesses adopt advanced technologies and digitize legacy processes, increasing the need for components that facilitate these advancements. Consequently, manufacturers focusing on innovation-led product diversification enhance their market positioning, capturing an increasing share of the 5G Smartphones MLCC market.
High capital investment requirements hinder growth in the 5G Smartphones MLCC market. The production of 5G smartphones necessitates advanced materials and technologies, driving up initial costs for manufacturers. Firms face substantial expenses related to research and development and the acquisition of state-of-the-art equipment for MLCC production. This financial burden disproportionately affects smaller companies, limiting their ability to compete effectively.
Escalating operating costs contribute to market challenges. Fluctuating raw material prices and increased labor expenses further strain manufacturers' margins. While firms strive to maintain profitability, many prioritize cost-cutting measures that slow innovation and reduce product quality. This scenario impacts overall market competitiveness and restricts the introduction of new technologies in 5G smartphones.
The combination of high capital investment requirements and rising operational costs creates barriers for market entrants and existing players. Consequently, these factors lead to market fragmentation, where only a few large manufacturers dominate while smaller entities struggle to achieve market penetration. This imbalance stifles advancements in MLCC technology and limits the overall growth potential of the 5G Smartphones MLCC market.
The geopolitical landscape experiences heightened tensions, resulting in various supply chain pressures impacting the 5G Smartphones MLCC market. Trade deficits and tariff friction disrupt established relationships between suppliers and manufacturers. Volatility in feedstock and component availability raises costs and complicates procurement strategies, ultimately affecting production schedules.
Technological disruptions introduce additional complexity, particularly for firms striving to integrate advanced features in their products. The rapid pace of innovation in smartphone technology necessitates significant research and development investments to stay competitive. Complex R&D integrations strain resources and delay market entry for new products.
Market saturation presents another challenge, with numerous competitors vying for market share in an already crowded field. The emergence of alternative technologies and materials intensifies substitution pressures, compelling producers to innovate continually. Fluctuations in consumer preferences require constant adaptation in product offerings, adding to operational stress.
Environmental sustainability demands complicate the operational landscape. Increasing requirements for decarbonization and reduced environmental footprints influence production processes and materials sourcing. These considerations require manufacturers to invest in cleaner technologies and practices, inflating operational costs and exerting pressure on profit margins in the market.
Finally, workforce skill gaps challenge the market's ability to maintain a skilled labor force capable of adapting to new technologies. Automation displacements exacerbate talent retention pressures, driven by the need for highly skilled workers. Addressing these workforce challenges is essential for sustaining momentum in the 5G Smartphones MLCC market.
The 5G Smartphones MLCC market experiences growth driven by emerging regional demands, particularly in Asia Pacific and North America. Asia Pacific contributes significantly, representing 68.6% of the overall market share, fueled by increasing smartphone penetration and consumer preference for advanced mobile connectivity. North America follows, with expectations for market value reaching USD 831.8 million by 2033, demonstrating a solid compound annual growth rate of 9.2%.
Infrastructure modernization significantly shapes demand within the market. Countries prioritizing the upgrade of telecommunications infrastructure enable increased deployment of 5G technologies, enhancing the functionality and efficiency of smartphones. This transition creates opportunities for manufacturers to innovate and integrate advanced MLCC solutions that meet the requirements of next-generation devices.
Technological disruptions and digital transformation support the growth trajectory of the market. The evolution of smartphone applications and functionalities necessitates higher capacitor content in devices, enabling manufacturers to offer enhanced performance and reliability. Consequently, increased investments in MLCCs designed for specific applications expand market presence and consumer adoption.
The market benefits from strategic consolidation and cross-industry mergers, which enhance product offerings and operational efficiencies. Collaborations between companies streamline supply chains, reduce costs, and improve access to new technologies. This strategic alignment strengthens the ability to respond to rapidly changing consumer preferences, thus driving market expansion.
Finally, evolving buying behaviors, characterized by a shift towards digital procurement channels, transform how consumers and businesses acquire 5G Smartphones MLCCs. This transition leads to heightened competition among suppliers, compelling them to innovate continuously and adapt their commercial models to meet the demands of a diverse customer base. Such adaptations position the market for sustained growth through 2033.
The Global 5G Smartphones MLCC market is segmented based on MLCC Product Type, Dielectric / Temperature Characteristic, Case Size, and Smartphone Circuit Application.
General-Purpose MLCCs segment is valued at USD 1,274.1 million in 2026 and is projected to reach USD 2,133 million by 2033, at a CAGR of 7.6% during the forecast period. The increasing integration of general-purpose MLCCs within 5G smartphones results from the rising complexity of electronic circuits, which require robust and reliable capacitors. This segment benefits from a diverse range of applications, including power management, signal processing, and filtering functions, essential for high-performance devices.
Shifts in consumer preferences towards feature-rich smartphones drive demand within the 5G Smartphones MLCC market. Manufacturers focus on enhancing device performance, leading to a surge in capacitor content per unit, which directly influences the growth rate of general-purpose MLCCs. The adoption of advanced technologies, including Internet of Things (IoT) applications and artificial intelligence, further increases the necessity for efficient capacitors in the evolving smartphone landscape.
Technological maturation significantly influences the expansion of the general-purpose MLCCs segment. Ongoing innovations in design and materials improve capacitor efficiency and reliability, appealing to smartphone manufacturers aiming to meet stringent performance requirements. Regulatory compliance standards necessitate adherence to safety and environmental guidelines, influencing production processes and material sourcing strategies. Consequently, manufacturers invest in R&D to enhance product offerings, ensuring alignment with market demands.
Pricing volatility significantly affects the cost structures underpinning general-purpose MLCCs. Fluctuations in raw material costs, driven by global supply chain dynamics, impact profit margins for manufacturers. Strategic opportunities arise for suppliers capable of optimizing production processes and securing stable supply chains. Efforts to mitigate substitution risks through product differentiation position manufacturers competitively within the market, enhancing overall market resilience.
Growth in the High-Q / RF MLCCs segment aligns with increasing demand for advanced communication technologies, primarily driven by the expansion of 5G networks. Enhanced performance requirements, including greater bandwidth and lower latency, necessitate the use of high-quality capacitors in smartphones, contributing to the segment's expansion. The adoption of these components benefits smartphone manufacturers and technology developers, who rely on superior RF performance to enhance device capabilities.
The High-Q / RF MLCCs segment is projected to reach USD 1,546.5 million by 2033, with a CAGR of 10.3% during the forecast period. Technological maturation and the introduction of next-generation smartphones significantly influence the development of this segment. Consumer preferences for high-performance devices lead to increased investments in research and development, promoting innovation in the market.
Regulatory compliance and industry standards play a vital role in shaping product evolution and adoption within the High-Q / RF MLCCs segment. While end-use dynamics shift towards more sophisticated applications, manufacturers face pressure to meet stringent performance criteria. This transition drives firms to invest in advanced materials and production techniques, enabling them to maintain a competitive edge in a changing market.
Growth in the Low-ESL / Multi-Terminal MLCCs segment aligns with the increasing complexity and performance requirements of 5G smartphones. Factors including heightened demand for high-frequency applications and enhanced signal integrity significantly drive the adoption of these components. The ability of Low-ESL / Multi-Terminal MLCCs to support the advanced functionalities of 5G devices positions them well within the market. The continuous evolution of smartphone technologies further drives the expansion of this segment, driven by manufacturers seeking to optimize power efficiency and performance in their devices.
With advancements in technology, these capacitors are becoming essential for applications requiring compact design and high reliability. Regulatory compliance standards related to electronic devices reinforce the need for advanced capacitors, pushing manufacturers towards Low-ESL / Multi-Terminal MLCCs. The segment is expected to reach USD 1,245 million by 2033, reflecting significant growth because manufacturers increasingly incorporate these capacitors to enhance overall device performance. This growth trajectory emphasizes the strategic opportunity for players invested in the 5G Smartphones MLCC market, highlighting the importance of innovation and technological advancement in meeting evolving consumer demands.
Growth in the High-Capacitance MLCCs segment aligns with the expanding demand for advanced features in 5G smartphones. This segment is projected to grow at a CAGR of 10.1% during the forecast period, driven by increasing integration of high-capacitance components in various smartphone applications. Rising consumer preferences for high-performance devices fuel the adoption of these capacitors, enabling enhanced functionalities including faster processing speeds and improved battery efficiency. The market benefits from technological advancements that facilitate the miniaturization of components, allowing for greater capacitance in smaller form factors.
End-use dynamics highlight the shift towards sophisticated smartphone circuit applications, where high-capacitance MLCCs play a crucial role in managing power and signal integrity. Manufacturers enhance consumer experiences through investments in next-gen upgrades. Regulatory compliance standards emphasize the need for reliable and efficient components, placing high-capacitance MLCCs in a favorable position within the overall 5G Smartphones MLCC market. This segment's growth trajectory reflects the ongoing evolution of smartphone technology and the increasing complexity of electronic circuits, resulting in sustained demand for these critical components.
Demand for Ultra-Small / Low-Profile MLCCs reflects the increasing miniaturization of electronic components within the 5G Smartphones MLCC market. Shrinking device sizes drive manufacturers to seek compact solutions that deliver high performance without compromising functionality. The continuous evolution of smartphones, particularly with the integration of advanced technologies, necessitates capacitors that fit into limited spaces while maintaining efficiency.
Technological maturation drives innovation in the development of Ultra-Small / Low-Profile MLCCs. Manufacturers invest in research to enhance capacitance levels while reducing the physical dimensions of the components. Such advancements lead to improvements in power management and signal integrity, crucial for high-performance smartphones.
End-use dynamics highlight a shift toward more sophisticated smartphone applications that require reliable and compact capacitors. The demand for enhanced features, including improved camera functionality and advanced connectivity options, emphasizes the need for efficient power management solutions. This trend increases the adoption of Ultra-Small / Low-Profile MLCCs across various smartphone models.
Cost structures associated with these components influence pricing strategies within the market. The pressure to maintain competitive pricing while ensuring quality contributes to complexities in production. Manufacturers balance sourcing raw materials and managing operational costs to optimize profit margins.
The 5G Smartphones MLCC market experiences strategic opportunity windows driven by manufacturers responding to evolving consumer preferences. The growing demand for high-capacity, space-efficient components positions Ultra-Small / Low-Profile MLCCs favorably within the broader market. While smartphone technology advances, continued investment in this segment remains vital for capturing market share and driving growth.
Development of the Others (Soft-Termination MLCCs, MLCC Arrays) sub-segment focuses on increasing demand for multifunctional components in 5G smartphones. The growth of advanced smartphone applications, emphasizing compact size and high performance, drives the need for small form-factor MLCCs. The shift towards enhanced connectivity features in devices contributes to the expansion of this sub-segment. Technological advancements in materials science enable higher capacitance and lower equivalent series resistance, providing competitive advantages in the market. End-use dynamics reflect a preference for components that support fast charging, higher energy efficiency, and improved overall device performance.
Pricing pressures remain a significant concern, influenced by fluctuating raw material costs and market competition. Suppliers face challenges in maintaining margins while meeting the demands of evolving technologies. Regulatory compliance standards further impact production processes, necessitating adherence to environmental and quality certifications. Strategic opportunity windows emerge for manufacturers who innovate and adapt product offerings to meet the specific requirements of next-generation smartphones. The 5G Smartphones MLCC market continues to develop, with a strong focus on integrating advanced functionalities within a compact design, positioning this sub-segment for substantial growth in the coming years.
Valued at USD 525.6 million in 2026, the C0G/NP0 segment is projected to reach USD 900.7 million by 2033, reflecting a CAGR of 8% during the forecast period. This growth results from increasing demand for high-frequency applications where stability and low losses are essential. The segment benefits from the proliferation of advanced telecommunications technologies, particularly in the 5G Smartphones MLCC market, driving manufacturers to enhance performance and reliability.
Technological maturation within the capacitor industry accelerates the adoption of C0G/NP0 capacitors, contributing to favorable market conditions. Innovations in materials and processes improve performance characteristics, enabling designs that support next-generation applications. The enhanced efficiency of these components positions them favorably in various downstream applications, including cellular RF front-end systems, application processors, and power management circuits.
End-use dynamics reflect a shift towards compact, high-performance devices, prompting manufacturers to prioritize the integration of C0G/NP0 capacitors in their products. This trend influences consumption patterns, reflecting a strong preference for components that offer superior thermal stability and minimal signal distortion. Compliance with stringent regulatory standards regarding electronic device performance provides further impetus for the adoption of high-quality dielectric materials.
Supply chain resilience remains crucial for sustaining growth within this segment. Raw material sourcing strategies and logistics planning are essential in addressing potential vulnerabilities, ensuring a steady supply of high-grade materials. Manufacturers invest in strategic opportunity windows, and the C0G/NP0 segment stands to benefit from competitive pricing and improved margins, strengthening its position in the evolving landscape of the 5G Smartphones MLCC market.
Strong demand for X5R capacitors drives growth within the 5G Smartphones MLCC market. This specific dielectric type exhibits excellent performance in terms of capacitance stability, making it suitable for various applications. The segment is projected to reach USD 2,922 million by 2033, at a CAGR of 9.9% during the forecast period. Increased adoption in smartphones supports the expansion of X5R offerings. Manufacturers focus on meeting the growing needs for miniaturization and improved energy efficiency in mobile devices.
Technological advancements in the semiconductor sector accelerate the evolution of X5R capacitors. Enhanced performance characteristics position these capacitors favorably for integration into next-generation smartphones. Market players allocate significant resources towards R&D activities to refine product features and explore innovative applications. The ongoing shift towards high-performance electronics contributes to the increasing consumption of X5R capacitors within the market.
While regulatory compliance standards become more stringent, manufacturers emphasize the importance of adhering to these guidelines. Consistent advancements in production processes help ensure that products meet the required certifications, enabling smoother market access. Pricing volatility in raw materials influences cost structures, prompting suppliers to adopt strategic sourcing methods. This dynamic environment highlights the necessity for supply chain resilience within the X5R segment.
Growing interest in the X6S sub-segment aligns with advancements in smartphone technology, pushing consumer demand for higher performance and efficiency in mobile devices. The shift towards increased functionality in smartphones necessitates components with superior dielectric properties, which enhance performance in various applications. The segment is projected to reach USD 1,045.5 million by 2033, driven by rising adoption of 5G smartphones and their associated technologies within the broader 5G smartphones MLCC market.
This growth reflects the trend towards integrating more sophisticated features, where components like X6S capacitors play a crucial role in ensuring reliability and improved performance. Manufacturers invest in developing high-quality X6S capacitors to meet stringent consumer expectations while navigating pricing volatility and raw material sourcing challenges. The evolving landscape of consumer electronics and telecommunications creates strategic opportunities for players in this segment, enhancing their contribution to the overall market.
X7R capacitors play a significant role in the 5G Smartphones MLCC market, primarily due to their favorable performance characteristics in various applications. This segment is projected to grow at a CAGR of 7.7% during the forecast period. Increasing demand for energy-efficient and compact electronic devices drives the adoption of X7R capacitors, contributing to robust market growth.
The evolving technological landscape supports the integration of X7R capacitors in advanced applications, enhancing the overall functionality of smartphones. While manufacturers strive to meet consumer expectations for performance and efficiency, the utilization of X7R capacitors becomes essential in applications including power management and RF front-end circuits. The consistent performance of X7R capacitors under varying temperature conditions further reinforces their position in the market.
Investment in research and development facilitates the evolution of X7R capacitors, enabling manufacturers to enhance capacitance values and reduce size, which aligns with industry trends toward miniaturization. Such advancements position the X7R segment favorably for future growth, driven by smartphone manufacturers prioritizing high-performance components to support next-generation functionalities.
Overall, the X7R capacitors segment significantly influences the 5G Smartphones MLCC market, with its projected growth aligning with broader trends in the electronics industry. This demand trajectory highlights the importance of X7R capacitors in meeting the challenges posed by evolving technological requirements and consumer preferences.
Interest in the X7S segment arises from its ability to provide superior performance in specific applications. Technological maturation within the segment results in increased efficiency and effectiveness in electronic devices, enhancing the overall user experience. This characteristic aligns seamlessly with advancements in 5G smartphone technology, where demands for higher performance components escalate.
Demand drivers for the X7S segment include the need for enhanced reliability and stability in high-frequency applications. Such requirements lead to substantial interest from manufacturers seeking to optimize smartphone functionalities. Adoption within the segment reflects a shift in consumer expectations, with users demanding devices capable of handling complex tasks without compromising performance.
Expansion catalysts include ongoing investments in research and development, which drive innovations tailored to the X7S capabilities. Manufacturers prioritize this segment to address evolving market dynamics and competition, ensuring they maintain relevance in the rapidly advancing 5G Smartphones MLCC market. Strategic partnerships and collaborations within the supply chain enhance resilience, further supporting growth opportunities.
Cost structures have become increasingly significant due to manufacturers navigating pricing volatility. Effective management of these factors contributes to maintaining margins, which remains critical for long-term sustainability. Regulatory compliance standards and certifications associated with the X7S segment ensure that products meet stringent quality expectations, enhancing overall market confidence.
Downstream applications benefit from the enhanced performance characteristics inherent to the X7S segment. The integration of these components into various smartphone functionalities creates increased competitive advantage within the market. Continuous product evolution aligns with consumer preferences, facilitating consumption shifts toward devices equipped with advanced capabilities.
Strategic opportunity windows emerge because technological advancements lead to disruptive alternatives in the broader market. Suppliers in the X7S segment leverage these developments to capture emerging trends, reinforcing their positions. Capital investment outlook remains optimistic, with stakeholders committing resources to explore innovative solutions that reinforce the segment's growth trajectory.
Increasing demand for specialized dielectric materials within the 5G Smartphones MLCC market supports the development of the Others (X6T, X7T, U2J and Specialty Dielectrics) sub-segment. These dielectrics cater to specific applications that require enhanced performance characteristics, including higher reliability and thermal stability. Technological maturation in electronics and telecommunication sectors drives interest in these materials, driven by manufacturers seeking to optimize performance while maintaining competitive pricing.
Adoption of advanced dielectric materials aligns with the push for next-generation upgrades in smartphone technology. Manufacturers prioritize components that meet stringent regulatory compliance standards and certifications, ensuring that products remain viable in a highly competitive market. The evolving preferences of consumers influence manufacturers to integrate innovative materials that enhance device capabilities.
Product evolution continues to play a critical role in shaping market dynamics. Innovations in electrical properties and thermal management capabilities of specialty dielectrics enable manufacturers to meet growing consumer expectations for performance and efficiency. This shift influences downstream applications, where enhanced functionalities contribute to improved user experiences.
Supply chain resilience remains essential for maintaining a steady flow of raw materials required for production. Fluctuations in raw material availability and pricing volatility exert pressure on profit margins for manufacturers. Strategic opportunity windows emerge for companies that efficiently navigate sourcing challenges while pursuing cost-effective solutions.
While demand for the Others (X6T, X7T, U2J and Specialty Dielectrics) sub-segment evolves, competitive pressure increases among suppliers to differentiate their offerings. Investment in research and development drives innovation, leading to the introduction of disruptive alternatives that align with market trends. Continued advancements will shape the future of the 5G Smartphones MLCC market, creating opportunities for companies to capitalize on emerging technologies.
Valued at USD 237.7 million in 2026, the 008004 (0201 Metric) segment is projected to reach USD 576.2 million by 2033, at a CAGR of 13.5% during the forecast period. This growth results from increasing miniaturization trends within the 5G Smartphones MLCC market, where compact design requirements drive demand for smaller case sizes. The shift towards advanced smartphone features, including improved functionality and performance, prioritizes the integration of high-density components, benefiting this specific sub-segment.
Technological advancements in manufacturing processes enhance production capabilities for the 008004 (0201 Metric) components, allowing for improved performance characteristics and reliability. The surge in demand for 5G smartphones correlates with rising consumer expectations for enhanced connectivity and multi-functionality. Consequently, manufacturers focus on developing innovative solutions to meet these challenges, addressing both performance and cost efficiency.
End-use dynamics further influence the growth trajectory of the segment. Smartphone manufacturers increasingly adopt advanced materials and components, making the 008004 (0201 Metric) capacitors essential in applications requiring compact size without compromising electrical performance. This evolution in product offerings substantially contributes to the segment's expansion within the broader 5G Smartphones MLCC market.
Strong growth in the 01005 (0402 Metric) segment aligns with the rising demand for smaller capacitors in the 5G Smartphones MLCC market. The miniaturization trend in smartphone designs fuels the need for compact components, enhancing the adoption of this specific case size. The segment is estimated to reach USD 1,928 million by 2033, at a CAGR of 11.3% during the forecast period. Rapid advancements in manufacturing technologies contribute to improved efficiency and performance, attracting manufacturers seeking to optimize production processes and reduce costs. The strategic focus on enhancing power management applications further drives the expansion of this segment, driven by device manufacturers prioritizing energy efficiency and performance in their product lines. Overall, these factors create a favorable environment for growth in the 5G Smartphones MLCC market.
High demand for the 0201 (0603 Metric) segment results from the continued trend towards miniaturization in electronic devices, particularly in smartphones. This segment addresses the increasing need for compact, efficient components within the 5G Smartphones MLCC market, enabling enhanced performance and functionality. The expected advancement in device capabilities drives the adoption of smaller MLCCs, because manufacturers strive to optimize space and improve power efficiency.
Technological maturation significantly shapes the 0201 (0603 Metric) segment. Continuous innovations in manufacturing techniques and materials contribute to the development of high-performance capacitors that meet the rigorous standards of modern smartphones. The evolution of 5G technology necessitates upgrades in components, creating a strong demand for these capacitors in various applications.
End-use dynamics indicate a strong inclination towards integrating 0201 (0603 Metric) MLCCs in critical smartphone functions, including power management and connectivity solutions. This trend aligns with the overall growth of the 5G Smartphones MLCC market, because manufacturers prioritize high-quality, reliable components to enhance user experiences. Adoption of these capacitors in high-speed data applications and advanced smartphone features significantly drives segment expansion.
Market analysts project that the 0201 (0603 Metric) segment is expected to reach USD 2,781.2 million by 2033, highlighting the increasing focus on miniaturized components in the tech industry. The growing importance of regulatory compliance standards regarding component sizes and performance specifications further influences this segment's trajectory. These factors collectively create a favorable environment for investment and innovation within the 5G Smartphones MLCC market.
Projected growth at a CAGR of 7.2% during the forecast period illustrates the expanding significance of the 0402 (1005 Metric) segment within the 5G Smartphones MLCC market. The increasing demand for compact components in smartphone manufacturing drives this growth, facilitating enhanced device performance and functionality. Technological maturation in mobile applications compels manufacturers to integrate these smaller capacitors, aligning with consumer preferences for lightweight and slim devices. Continuous product evolution leads to innovations, ensuring that manufacturers remain competitive. Strategic opportunity windows in this segment reflect a robust investment outlook, encouraging players to enhance production capabilities and introduce next-generation solutions. With growing adoption rates in smartphone circuit applications, the market anticipates a sustained increase in demand for the 0402 (1005 Metric) segment, resulting in a positive impact on overall growth in the 5G Smartphones MLCC market.
Increased adoption of 0603 (1608 Metric) capacitors aligns with the trend toward narrower designs in 5G Smartphones. This segment responds to heightened demand for compact electronic components, facilitating slimmer device profiles. Technological advancements in manufacturing processes enhance the precision and performance of these MLCCs, making them suitable for diverse applications, including high-frequency circuits and power management systems.
Market players invest in the development of 0603 MLCCs, targeting improved dielectric performance and reliability. Enhanced performance characteristics enable manufacturers to meet the rigorous requirements of modern smartphones, including energy efficiency and signal integrity. This segment's evolution reflects broader trends within the 5G Smartphones MLCC market, emphasizing innovation and adaptability in product offerings.
Consumer preferences shift towards devices that combine functionality with aesthetic appeal, influencing the demand for smaller MLCCs. The 0603 (1608 Metric) capacitors contribute significantly to this evolution, allowing manufacturers to optimize space within complex circuit designs. These dynamics create strategic opportunities for suppliers to enhance their market position through tailored offerings and technical innovations.
Regulatory compliance and certification processes shape the landscape, ensuring that 0603 MLCCs adhere to safety and performance standards. Compliance impacts production costs and pricing strategies while reinforcing the importance of quality assurance in the supply chain. The ongoing development within this sub-segment reflects a commitment to advancing technology in the 5G Smartphones MLCC market.
Interest in the 0805 and Larger (2012 Metric and Above) sub-segment reflects the increasing demand for larger capacitor sizes in advanced smartphone designs. This sub-segment is essential for supporting the functionality of high-performance mobile devices, particularly with the expansion of features including enhanced connectivity, improved audio quality, and advanced imaging capabilities. While smartphone manufacturers pursue innovations in design and functionality, the demand for higher capacity and specialized capacitors intensifies.
Technological advancements in manufacturing processes contribute to the growth of this segment, enabling the production of capacitors that meet stringent performance requirements. The 5G Smartphones MLCC market experiences pressure to deliver components that offer high reliability and efficiency, driving investments in R&D and production capabilities. Supply chain resilience remains vital for ensuring consistent availability of raw materials suited for larger capacitors, especially in the context of increased global demand.
Downstream applications in the 5G Smartphones MLCC market heavily influence the evolution of this sub-segment. The integration of larger MLCCs supports various advanced functionalities required by modern smartphones, including high-speed data transmission and better power management. Smartphone manufacturers prioritize user experience, making the need for larger capacitors integral to overall device performance and longevity.
Strategic opportunities for growth emerge within this segment, driven by manufacturers exploring innovative designs and enhanced product features. Capital investment in this area facilitates advancements in production technology and capacity expansion, positioning stakeholders to better address the evolving needs of the market. Overall, the 0805 and Larger (2012 Metric and Above) sub-segment serves because an essential element in the broader scope of the 5G Smartphones MLCC market, reflecting the industry's commitment to meeting the demands of modern mobile technology.
Significant growth in the Cellular RF Front-End and Antenna Matching segment reflects the increasing integration of advanced communication technologies in smartphones. Valued at USD 815.2 million in 2026, this segment is projected to reach USD 1,571.8 million by 2033, achieving a CAGR of 9.8% during the forecast period. The demand arises from the necessity for enhanced signal quality and reliability, which are crucial for effective 5G connectivity.
Technological advancements in antenna design and RF components drive the expansion of this segment. Innovations enable better performance and efficiency, catering to the rising expectations of consumers for reliable connectivity. Smartphone manufacturers invest in high-performance components to meet these demands, creating a competitive landscape within the 5G Smartphones MLCC market.
End-use dynamics play a critical role, reflecting that smartphone applications increasingly rely on robust RF front-end solutions. Enhanced functionalities including real-time data processing and improved multimedia capabilities contribute to the rising demand. Manufacturers focusing on integrating these advanced features into their devices capitalize on shifting consumer preferences towards high-performance smartphones.
Regulatory compliance standards regarding electromagnetic interference and device safety create additional factors influencing market dynamics. Manufacturers prioritize compliance to ensure product acceptance in various global markets, which leads to increased investment in R&D for compliant solutions. This focus sustains growth momentum within the segment and the overall 5G Smartphones MLCC market.
In an evolving environment, the Application Processor and Baseband sub-segment of the 5G Smartphones MLCC market experiences significant growth driven by the increasing complexity of smartphone technologies. The demand arises from the need for enhanced processing capabilities, which integrate more advanced features including high-speed connectivity and improved user experiences. The segment is projected to reach USD 1,124.7 million by 2033, at a CAGR of 8.8% during the forecast period.
Technological maturation in smartphone architecture supports expansion, allowing processors to handle greater workloads and support next-generation applications. This growth reflects broader trends in the smartphone industry, where manufacturers prioritize performance and efficiency in circuit design. End-use dynamics indicate a transition towards high-performance mobile applications that require robust processing power, influencing purchasing decisions among consumers and manufacturers.
Regulatory compliance standards and certifications play a crucial role in shaping the market. Adherence to these standards ensures that products meet safety and performance requirements, essential for building consumer trust and facilitating market entry. Competitive pricing strategies amid margin pressures stimulate innovation, compelling manufacturers to invest in R&D for next-generation technologies.
Strategic opportunity windows emerge from shifts in consumption patterns, with consumers increasingly seeking devices capable of supporting emerging technologies like augmented reality and advanced gaming. The Application Processor and Baseband sub-segment significantly influences this trend, contributing to the overall growth of the 5G Smartphones MLCC market.
Demand for Power Management and DC-DC Conversion components in the 5G Smartphones MLCC market reflects increasing smartphone functionality and energy efficiency requirements. The growing emphasis on advanced power management systems enhances the need for efficient DC-DC converters, directly influencing the demand for MLCCs designed for this application.
Technological advancements fuel segment expansion, driven by manufacturers developing more compact and efficient solutions. Enhanced performance characteristics and miniaturization in the power management domain drive adoption among smartphone producers, resulting in a significant increase in the market size.
The segment is projected to reach USD 1,755.4 million by 2033, benefiting from a concurrent rise in smart device applications and the necessity for efficient energy management solutions. This trend indicates a robust future for companies supplying MLCCs in power management applications.
The evolving nature of smartphone applications influences the consumption patterns of power management components. Increasing reliance on features including high-resolution displays and advanced processing capabilities drives energy consumption, necessitating improved DC-DC conversion technologies. This shift emphasizes the importance of the Power Management and DC-DC Conversion segment within the broader 5G Smartphones MLCC market.
Growth in the Memory and Storage segment aligns with rising requirements for efficient data processing and storage capabilities within 5G smartphones. The segment is projected to grow at a CAGR of 8.5% during the forecast period, highlighting the increasing reliance on high-performance memory solutions. This expansion reflects advancements in semiconductor technology, enhancing performance and energy efficiency for mobile devices.
Demand for memory components evolves alongside the smartphone market, particularly driven by manufacturers prioritizing higher storage capacities and faster access speeds. Increased consumer expectations for effective multitasking and high-quality applications drive manufacturers to enhance memory solutions. Consequently, the Memory and Storage segment becomes integral to the overall functionality of devices in the 5G Smartphones MLCC market.
Smartphone applications grow more sophisticated, increasing the necessity for robust memory solutions and prompting innovation in component design and manufacturing. This trend encourages investments in advanced memory technologies, supporting the overall growth trajectory of the market.
Consumption shifts in the 5G Smartphones MLCC market increasingly favor advanced display technologies, driving demand for capacitors that enhance touch sensitivity and overall performance. Technological maturation in display and touch interfaces aligns with consumer expectations for high-resolution screens and responsive touch functionalities. Manufacturers investing in next-gen upgrades recognize the importance of integrating high-quality capacitors to meet these standards, supporting enhanced device performance.
Product evolution in display technology, including OLED and MicroLED, necessitates improved MLCCs that withstand fluctuating electrical demands while maintaining reliability. End-use dynamics reflect the industry's transition toward devices with larger screens and multifaceted display capabilities, further driving the need for sophisticated capacitor solutions. Strategic opportunities emerge for suppliers capable of delivering tailored products that meet stringent performance criteria, enabling competitive differentiation.
Regulatory compliance standards influence the manufacturing processes of components in the display and touch segment, ensuring safety and durability. Cost structures are impacted by the need for high-quality raw materials, resulting in pricing volatility and margin pressures across the supply chain. Suppliers focusing on sustainable sourcing practices enhance their market position while minimizing potential disruptions, reflecting a commitment to environmental responsibility.
Downstream applications for display and touch MLCCs span various consumer electronics, emphasizing the interconnectedness of technology trends and customer demands. Innovations in touch technology prompt a reevaluation of existing product lines to accommodate evolving specifications and performance standards. Strategic investments in research and development from key players support market growth while addressing emerging challenges, reinforcing the industry's adaptability.
Growing integration of advanced camera technologies into smartphones directly influences demand within the Camera and Imaging sub-segment. Rising consumer expectations for high-resolution photography and videography drive manufacturers to employ sophisticated components, including MLCCs, to enhance performance and image quality. The proliferation of social media and content sharing increases the necessity for superior camera capabilities, propelling investments in this area.
Technological advancements in image processing and sensor technologies promote product evolution in the market. Enhanced image stabilization, low-light performance, and multi-lens setups create new opportunities for MLCC applications, particularly in high-capacitance variants designed to support intricate electronic systems. Iterative upgrades driven by competitive pressures further contribute to ongoing demand for innovative solutions.
Regulatory compliance standards surrounding electronic components and environmental impacts play a role in shaping the market dynamics. Manufacturers face pressure to meet certifications that reflect evolving consumer safety and environmental considerations. Adherence to these standards influences pricing structures and margin pressures, necessitating strategic adjustments by players within the segment.
Shifts in consumption patterns toward multifunctional devices increase the importance of the Camera and Imaging sub-segment. Consumers increasingly favor smartphones that merge advanced imaging capabilities with other functionalities, requiring manufacturers to invest in robust supply chain resilience to ensure consistent raw material sourcing. Disruptive alternatives in the imaging technology space, coupled with rising consumer expectations, compel companies to prioritize innovation and adaptability.
Strategic opportunity windows emerge because manufacturers seek to optimize their presence in the 5G Smartphones MLCC market. The focus on integrating AI-driven features into camera systems presents avenues for growth, encouraging capital investments in research and development. This trend highlights the necessity for sustained technological maturation and responsiveness to consumer preferences within the segment.
Non-Cellular Wireless Connectivity, encompassing Wi-Fi, Bluetooth, GNSS, and NFC technologies, is essential to the functionality of modern smartphones, driving significant demand within the 5G Smartphones MLCC market. The escalating requirement for reliable connectivity solutions continues to influence the adoption of high-performance MLCCs, optimizing device performance and user experience.
Advancements in wireless technology, including the emergence of next-generation standards, support the evolution of these connectivity solutions. Enhanced data rates and lower latency improve user interactions, making integration of these technologies vital for manufacturers aiming to remain competitive. Increasing consumer expectations for connectivity reliability and speed further drive the demand for sophisticated MLCC solutions.
The incorporation of Non-Cellular Wireless Connectivity solutions aligns with trends in mobile device applications, where users increasingly rely on real-time data exchange. Various industries, including automotive, healthcare, and consumer electronics, benefit from these connectivity options, highlighting the growing interconnectivity of devices in everyday life. This integration encourages the development of smart environments that enhance operational efficiency and user convenience.
Technological maturation within this sub-segment is evident, driven by manufacturers investing in innovative MLCC designs that support diverse applications. Compliance with regulatory standards is critical, ensuring that products meet safety and performance guidelines while maintaining competitive pricing structures. The ongoing evolution of product specifications reflects the market's responsiveness to changing consumer preferences and technological advancements.
Investment in research and development creates opportunities for firms to enhance their offerings in the Non-Cellular Wireless Connectivity space, emphasizing the strategic significance of this segment within the broader 5G Smartphones MLCC market. While companies focus on resilience in supply chains and raw material sourcing, they address the challenges posed by market dynamics and capitalize on emerging opportunities effectively.
Consumer interest in high-quality audio experiences drives demand for the Audio and Haptics sub-segment within the 5G Smartphones MLCC market. Enhanced audio capabilities in smartphones contribute to a superior user experience, prompting manufacturers to prioritize audio performance. The integration of advanced haptic feedback technology further enhances user interaction, creating a more immersive experience that appeals to consumers.
The segment benefits from continuous technological maturation, with advancements in components that deliver improved sound quality and more responsive haptic feedback. Manufacturers invest in next-generation upgrades, ensuring that devices feature audio technologies that respond to consumer preferences. This trend supports segment expansion, driven by evolving consumer expectations that influence manufacturers to innovate.
Product evolution aligns with the rising demand for smartphones featuring sophisticated audio capabilities. Enhanced sound systems and precise haptic responses improve overall functionality, making devices more attractive to buyers. Downstream applications in gaming, multimedia, and communication increasingly require advanced audio and haptic technologies, positioning this segment favorably within the market.
Regulatory compliance standards and certifications regarding audio quality and safety further shape the segment dynamics. Manufacturers focus on adhering to these standards to ensure consumer trust and product reliability. Fluctuations in raw material sourcing and cost structures affect pricing volatility and margin pressures specific to this sub-segment, necessitating strategic approaches to maintain competitiveness.
Technological obsolescence presents challenges, prompting continual investment in research and development to stay ahead of disruptive alternatives. Strategic opportunity windows exist for manufacturers who effectively leverage advancements while mitigating risks associated with supply chain vulnerabilities. The Audio and Haptics sub-segment holds potential within the 5G Smartphones MLCC market, driven by shifting consumer preferences towards devices that prioritize audio quality and tactile responsiveness.
Increasing reliance on efficient battery management systems drives demand for components within the Charging and Battery Management sub-segment. Factors including enhanced energy efficiency, longer battery life, and improved charging speeds contribute to this trend. The proliferation of 5G technology in smartphones necessitates advanced battery solutions, aligning with consumer expectations for high-performance devices. While smartphone manufacturers focus on optimizing battery performance, investments in innovative technologies and materials emerge, supporting segment expansion.
The evolution of charging technologies, including rapid and wireless charging, influences the demand dynamics in the market. Continuous advancements in battery management systems enhance operational efficiency and safety, addressing the challenges associated with lithium-ion battery usage. An emphasis on regulatory compliance and environmental sustainability encourages the adoption of efficient charging solutions, aligning with global energy initiatives.
Competition among players in the Charging and Battery Management segment intensifies due to brands striving to differentiate their offerings. Manufacturers face pressure to innovate while managing costs, leading to strategic investment opportunities in research and development. This competitive landscape encourages a proactive approach to identifying emerging technologies and potential disruptive alternatives in the market, ensuring sustained relevance because consumer preferences evolve.
Market growth hinges on ongoing technological maturation, particularly because next-gen upgrades in battery technology become available. Strategic opportunity windows arise from heightened consumer demand for smartphones with robust charging capabilities. The ability to adapt to shifting consumption patterns and regulatory frameworks will shape the future trajectory of the 5G Smartphones MLCC market, emphasizing the importance of agility and innovation in the Charging and Battery Management sub-segment.
Innovation within smartphone technology drives interest in the Others (Sensors and Peripheral Interfaces) segment, enhancing user experience and device functionality. The integration of advanced sensors and interfaces, including gesture recognition, environmental sensing, and biometric capabilities, increases demand within the 5G Smartphones MLCC market. Evolving smartphone applications reflect a reliance on these components, indicating a shift towards multifunctional devices that support varied consumer needs.
Adoption of sophisticated sensing technologies drives segment expansion, particularly with the rise of augmented reality applications and advanced gaming experiences. This trend necessitates advanced circuit solutions that support higher performance levels and ensure effective interaction. Regulatory compliance and certification standards dictate the design and manufacturing of components, influencing market dynamics associated with sensors and peripheral interfaces.
Price volatility in raw materials impacts production costs, compelling manufacturers to explore innovative sourcing strategies and enhance supply chain resilience. Technological obsolescence poses challenges, yet firms investing in next-generation upgrades gain a competitive edge, enhancing product offerings while navigating margin pressures. Strategic opportunity windows exist for companies willing to adapt to these market shifts, strengthening their position in the evolving 5G Smartphones MLCC market.
Based on geography, the Global 5G Smartphones MLCC market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America shows a robust trajectory in the 5G Smartphones MLCC market, with expectations for significant expansion at a CAGR of 9.2% during the forecast period, ultimately reaching a market size of USD 831.8 million by 2033. This growth is driven by rising demand for advanced smartphone functionalities, which increasingly require high-performance MLCCs.
Key players in the United States, Canada, and Mexico facilitate a competitive landscape that encourages innovation and product diversification. Manufacturers in this region focus on developing high-Q and RF MLCCs, which cater to the specific needs of 5G smartphones, enhancing their market presence.
Infrastructure modernization efforts in North America, particularly in urban areas, support the deployment of 5G technology. Telecommunication companies invest heavily in upgrading networks, driving demand for high-capacitance MLCCs essential for advanced cellular RF front-end applications. This trend positions the market favorably for sustained growth.
Localized manufacturing densities enhance the region's supply chain efficiency, reducing lead times and enabling better responsiveness to market demands. Geopolitical factors influence cross-border trade, impacting the sourcing of raw materials and components necessary for MLCC production.
The market benefits from incremental growth vectors, including increased smartphone penetration and a growing preference for high-quality audio and video experiences. These factors stimulate demand for specialized MLCC configurations that support advanced multimedia applications.
North America's 5G Smartphones MLCC market is characterized by competitive dynamics, infrastructure advancements, and evolving consumer preferences. These elements fuel ongoing investment and innovation, reinforcing the region's position within the global market.
The 5G Smartphones MLCC market in Europe presents a unique landscape characterized by growing demand driven by smartphone manufacturers focused on leveraging enhanced connectivity features. Countries including Germany, France, UK, Italy, and Spain play important roles in this market due to their established telecommunications infrastructure and high smartphone penetration rates. The region’s market share reflects a solid foundation supported by a robust consumer base seeking advanced technology.
Demand in Europe stems from increasing investments in 5G infrastructure, creating a favorable environment for growth. The focus on replacing legacy systems with high-capacity solutions enhances opportunities for MLCC suppliers. The emergence of localized manufacturing in response to geopolitical factors and supply chain disruptions creates a competitive advantage for regional players. This shift positions Europe because an attractive market for foreign direct investment (FDI), stimulating innovation and technological advancements.
The expansion of the 5G Smartphones MLCC market aligns with the region's commitment to modernizing its telecommunications capabilities, leading to high-value replacement cycles and incremental growth vectors. While manufacturers adapt to changing consumer preferences for high-performance smartphones, the demand for advanced MLCC types, including High-Q / RF MLCCs and High-Capacitance MLCCs, rises. Regional compliance mandates and trade policy shifts further influence procurement strategies, shaping the competitive dynamics within the market.
Europe’s focus on infrastructure modernization, localized manufacturing, and strategic entry barriers positions the region to capture significant growth in the 5G Smartphones MLCC market. With domestic market leaders and emerging players reinforcing their presence, the market is set for continuous evolution in response to the demands of modern telecommunications.
Asia Pacific represents a dominant force in the 5G Smartphones MLCC market, accounting for 68.6% of global share in 2025. This robust presence results from the region's extensive smartphone manufacturing capabilities and advanced technological landscape, particularly in countries like China, Japan, and South Korea. Increasing investment in 5G infrastructure significantly drives demand, accelerating the rapid adoption of high-performance MLCC products.
The diverse smartphone market in Asia Pacific features extensive applications for MLCCs, with components like Cellular RF Front-End and Antenna Matching experiencing heightened demand due to the region's growing emphasis on connectivity and wireless technologies. Japan and South Korea lead advancements in high-quality smartphone features, further stimulating demand for specialized MLCC types including High-Q / RF MLCCs and Low-ESL / Multi-Terminal MLCCs.
Infrastructure modernization initiatives in India and Southeast Asia enhance the market environment, promoting increased smartphone penetration and expanding the reach of 5G technologies. These developments create opportunities for local manufacturers and suppliers to engage effectively with domestic markets, supported by regional procurement dynamics and investment from multinational corporations.
Emerging market front-runners like China continue to drive competition among local vendors, reinforcing the competitive landscape within the region. Established players, including Murata Manufacturing Co., Ltd. and Samsung Electro-Mechanics Co., Ltd., benefit from high-value replacement cycles associated with evolving consumer preferences toward advanced technology integration in smartphones.
Overall, the Asia Pacific region will experience sustained growth in the 5G Smartphones MLCC market, driven by infrastructure investments, increasing smartphone adoption, and rising consumer demand for innovative features across various smartphone applications.
The 5G Smartphones MLCC market in South America is characterized by a share of 4.3% in 2025. Brazil and Argentina serve because primary contributors to market dynamics, with increasing smartphone penetration rates influencing demand for MLCCs. The region's infrastructure modernization efforts support the adoption of advanced technologies, enhancing the market's growth potential.
Localized manufacturing densities emerge because a significant factor, with manufacturers establishing operations in response to regional demand. Domestic market leaders demonstrate a commitment to innovation, strengthening their competitive positions. Understanding cultural nuances and regional B2B buying behaviors impacts procurement dynamics within the market.
Investment in energy grid resiliency ensures the operational stability of manufacturers. Strategic entry barriers present opportunities for foreign direct investment flows, facilitating geographic expansion in territories including Brazil and Argentina. The evolving supply chain regionalization trends offer pathways for cross-border trade, enhancing market accessibility.
The 5G Smartphones MLCC market in the Middle East and Africa experiences steady growth driven by increasing smartphone adoption across the region. Rising demand for advanced connectivity technologies drives investment in 5G infrastructure, particularly in countries like Saudi Arabia and the UAE. These nations exhibit strong efforts toward infrastructure modernization, enhancing their market positions.
Local markets in South Africa and the rest of the Middle East and Africa contribute significantly to the overall growth of the market. Emerging players focus on localized manufacturing and procurement strategies to meet the specific requirements of regional buyers. The evolution of consumer preferences for high-performance smartphones leads to increased demand for various MLCC product types.
Investment in cross-border trade corridors strengthens the competitiveness of the regional supply chain. Geopolitical factors and localized compliance mandates impact market dynamics and necessitate adaptive strategies from domestic vendors. Competitive landscapes evolve because market leaders leverage their expertise to capture share in an expanding market. By 2025, the region is projected to account for 6.0% of the global market.
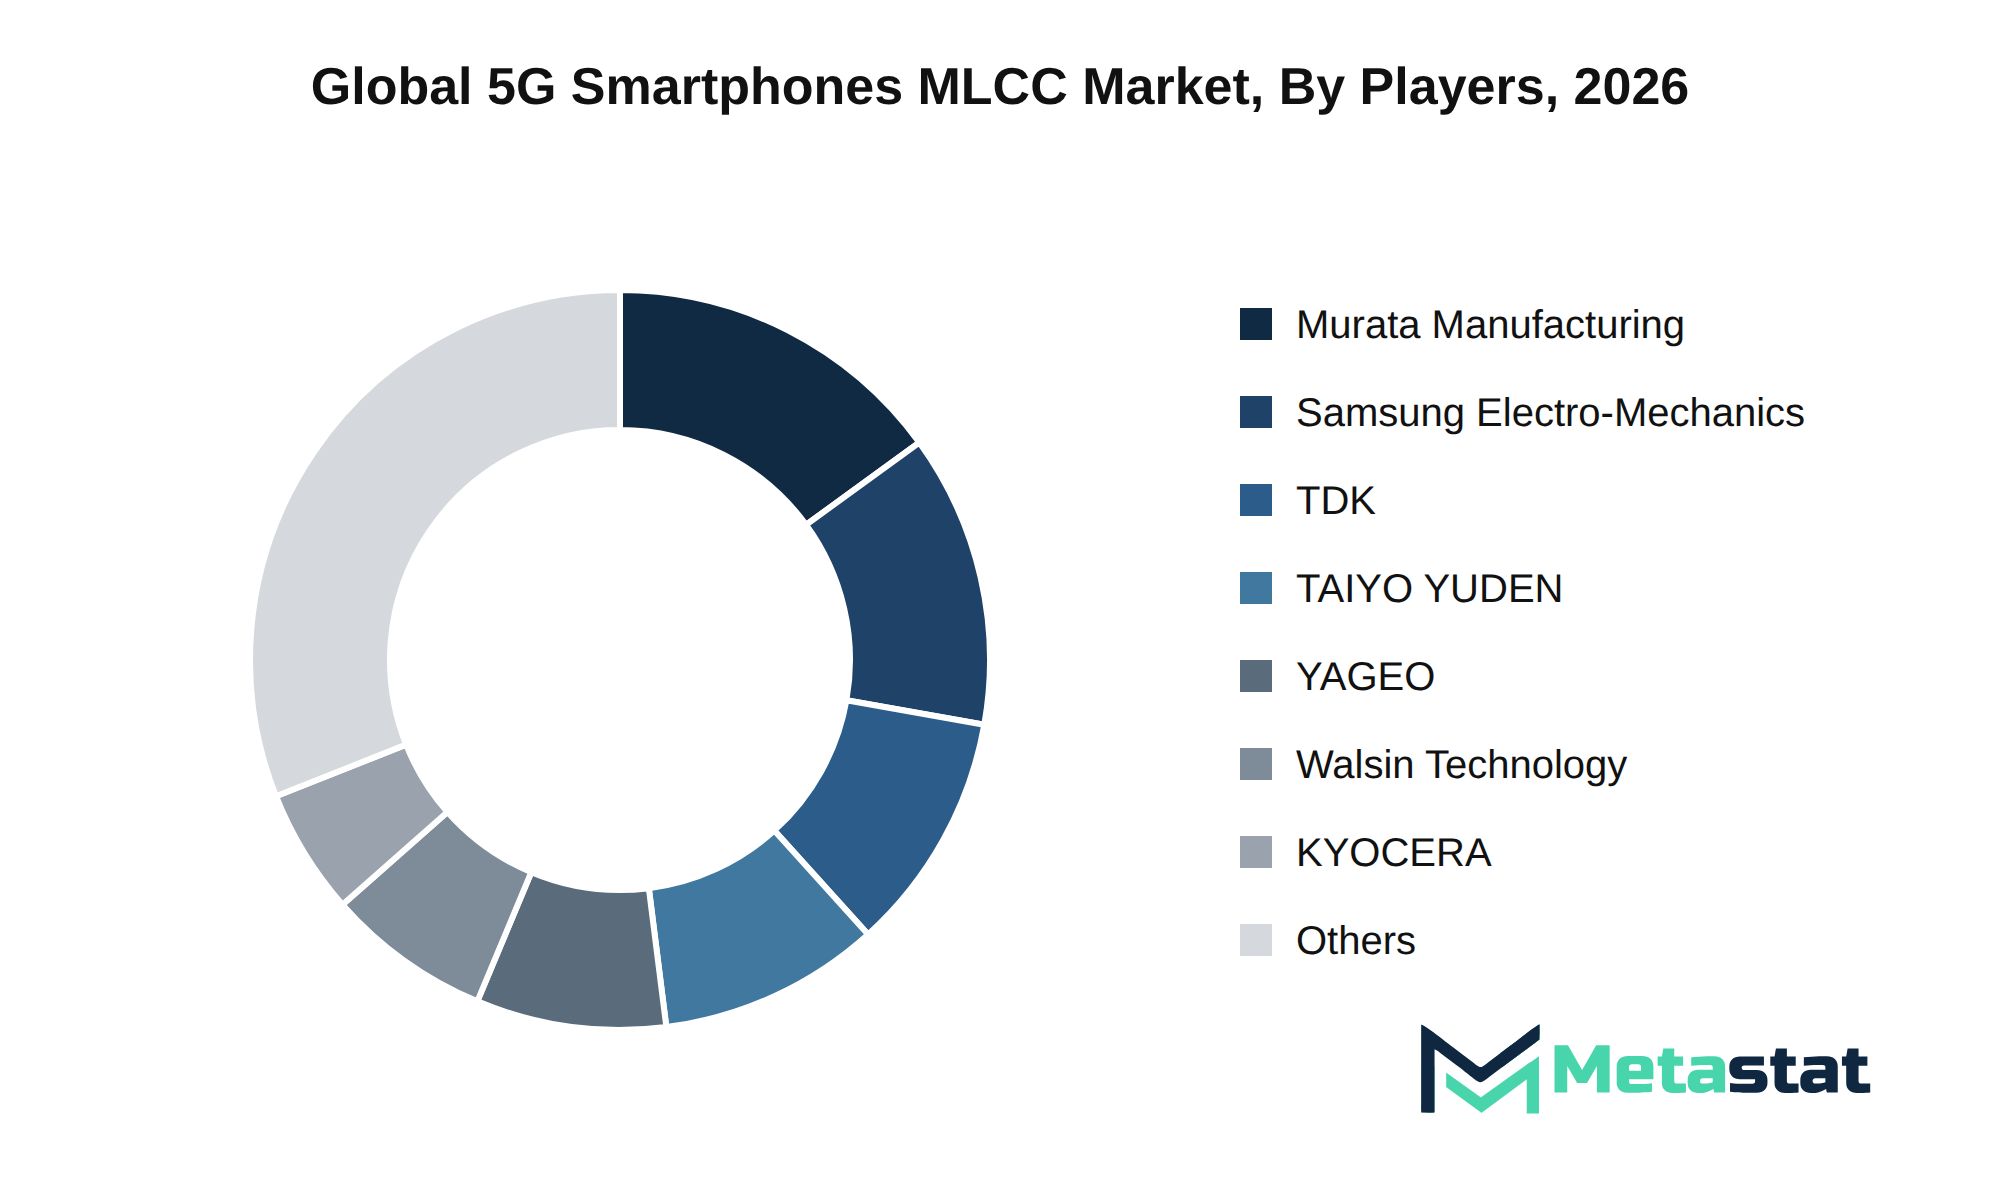
The 5G Smartphones MLCC market features significant activity from key players employing diverse strategies to enhance their market positions. Strategic alliances and joint ventures facilitate collaboration in technology development and production efficiencies. Companies like Murata Manufacturing Co., Ltd. and Samsung Electro-Mechanics Co., Ltd. leverage their extensive research and development pipelines to introduce innovative products and maintain technological defensibility.
Pricing architectures in the market reflect competitive pressures, with manufacturers including TDK Corporation and TAIYO YUDEN CO., LTD. focusing on value chain integration to optimize procurement leverage and customer retention strategies. The competition intensifies because companies like YAGEO Corporation and Walsin Technology Corporation create differentiation through proprietary technology moats, enhancing their brand equity and market appeal.
Barriers to entry persist, discouraging new entrants in the 5G Smartphones MLCC market. Established firms like KYOCERA Corporation and Guangdong Fenghua Advanced Technology Holding Co., Ltd. dominate supply chains, applying their scale and experience to navigate potential startup disruptions effectively. The future competitive outlook suggests continued strategic consolidation and growth vectors, positioning these players favorably in an evolving market landscape.
Market size is forecast to rise from USD 3,913 million in 2025 to over USD 7,914.5 million by 2033. This growth trajectory reflects a 9.2% CAGR, driven by increasing adoption of 5G technologies and innovations in smartphone capabilities. Bull case scenarios suggest accelerated growth due to heightened consumer demand and rapid technological advancements, while bear case scenarios indicate potential market constraints stemming from geopolitical uncertainties or supply chain disruptions. The 5G Smartphones MLCC market stands at a critical juncture, with companies focusing on next-generation technology integration and strategic capital allocation to seize emerging white-space opportunities. R&D commercialization timelines shorten, and firms prioritize addressing unmet enterprise needs, leading to higher growth pockets. Regulatory evolution and compliance milestones shape the landscape, influencing investment decisions and operational strategies across the industry.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the 5G Smartphones MLCC market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 9.2% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By MLCC Product Type, Dielectric / Temperature Characteristic, Case Size, Smartphone Circuit Application, and Region |
By Region | North America (By MLCC Product Type, Dielectric / Temperature Characteristic, Case Size, Smartphone Circuit Application, and Country)
|
Europe (By MLCC Product Type, Dielectric / Temperature Characteristic, Case Size, Smartphone Circuit Application, and Country)
| |
Asia Pacific (By MLCC Product Type, Dielectric / Temperature Characteristic, Case Size, Smartphone Circuit Application, and Country)
| |
South America (By MLCC Product Type, Dielectric / Temperature Characteristic, Case Size, Smartphone Circuit Application, and Country)
| |
Middle East and Africa (By MLCC Product Type, Dielectric / Temperature Characteristic, Case Size, Smartphone Circuit Application, and Country)
|
Find answers to common questions about this report
The 5G Smartphones MLCC market size was valued at USD 3,913 million in 2025.
The 5G Smartphones MLCC market is projected to grow at a CAGR of 9.2% during the forecast period from 2026 to 2033.
The North America 5G Smartphones MLCC market size is estimated to reach USD 831.8 million by 2033.
The High-Q / RF MLCCs segment leads the 5G Smartphones MLCC market with a projected value of USD 1,546.5 million by 2033. This segment demonstrates the highest growth potential compared to other product types.
Key drivers for the 5G Smartphones MLCC market include increasing global adoption of 5G technology, enhanced connectivity, and faster data speeds. Investment by mobile network operators in infrastructure upgrades further increases demand for high-quality multi-layer ceramic capacitors essential for 5G functionality.
High capital investment requirements and rising operational costs restrain growth in the 5G Smartphones MLCC market. Substantial expenses related to research, development, and advanced equipment limit competition, particularly for smaller manufacturers. geopolitical tensions and supply chain pressures complicate procurement strategies, further impacting production schedules and market dynamics.
The demand for 5G Smartphones MLCCs is favorably influenced by the increasing global adoption of 5G technology, enhanced connectivity, and faster data speeds. significant investments by mobile network operators in infrastructure upgrades support the rollout of 5G smartphones, further driving the need for high-quality multi-layer ceramic capacitors.
The 5G Smartphones MLCC market is estimated to reach a valuation of USD 7,914.5 million by 2033.
Key players in the 5G Smartphones MLCC market include Murata Manufacturing Co., Ltd., Samsung Electro-Mechanics Co., Ltd., TDK Corporation, TAIYO YUDEN CO., LTD., YAGEO Corporation, Walsin Technology Corporation, and KYOCERA Corporation.
The 5G Smartphones MLCC market is projected to reach USD 4,284.5 million by 2026.
Choose Your License
Global 5G Smartphones MLCC Market
The analysts below cover Electronics and Semiconductor research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.
PRINCIPAL CONSULTANT - QUALITY SYSTEMS & COMPLIANCE
Electronics and Semiconductor · Machinery & Equipment · Professional Services
Omkar Phadtare is an Industry Consultant at MetaStat Insight, specializing in quality systems, regulatory compliance, and standards benchmarking to drive data-driven market intelligence and strategic industry research.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Assessing commercial microgrid software adoption requires looking past top-level installation numbers and examining utility interconnection queues. The research provided verifiable data on average permitting timelines, tariff structures, and battery storage integration costs across regional utility territories. That grounded perspective was valuable for our team when building five-year demand projections for industrial microgrid controllers.
Ambulatory surgical centers have very different purchasing cycles for robotic-assisted surgery platforms than major hospital networks. The MetaStat Insight study focused squarely on capital expenditure depreciation, procedural reimbursement pathways, and surgeon training overhead. That operational clarity made it much simpler to validate multi-year procedure growth forecasts against actual ambulatory center adoption patterns.
When planning edge sensor rollouts across refinery environments, generic IoT reports typically miss the harsh-environment certification bottlenecks. MetaStat Insight gave an objective evaluation of ATEX and Class 1 Division 2 hardware availability, along with realistic five-year maintenance cycle cost projections. The comparison of wireless mesh versus private cellular backhaul helped our team pressure-test network reliability models for remote processing facilities.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950
Starting from
$2950