
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Commercial and Institutional Interior Design Services Market Size, Share, By Service Type (Interior Space Planning & Programming, Interior Architecture & Detailing, Materials, Finishes & Color Design, Furniture, Fixtures & Equipment (FF&E) Design & Specification, Lighting Design & Coordination, Signage, Wayfinding & Environmental Graphics, Branded & Experiential Interior Design, Sustainable, Wellness & Accessibility Design, Construction Documentation & Administration, Visualization & Digital Design Services), By Project Type (New Construction Interiors, Renovation & Modernization, Interior Fit-Out & Tenant Improvement, Adaptive Reuse & Change-of-Use Conversion, Expansion & Addition Interiors, Refurbishment & Rebranding), By End-Use Sector (Corporate & Office, Hospitality, Retail & Consumer Experience, Healthcare & Life Sciences, Education, Government, Civic & Public Facilities, Sports, Recreation & Wellness, Transportation & Aviation, Cultural & Entertainment Facilities, Others (Religious Facilities, Specialized Community Facilities)), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5247
September 15, 2026
250 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $52.2 Billion in 2025, projected to reach $81.3 Billion by 2033 at a 5.7% CAGR.
Dominant Segment: The Interior Space Planning & Programming segment leads the market, driven by increasing investments in corporate infrastructure and a focus on optimizing workspace efficiency.
Geographic Lead: The Asia Pacific region shows the fastest growth, fueled by rapid urbanization and significant investments in infrastructure modernization.
What's Inside: The report includes detailed competitive coverage, market segmentation analysis by service type, project type, and end-use sector, along with insights into growth trends and forecasts through 2033.
Emerging Regional Demands: Emerging regional demands present significant growth opportunities, particularly as firms engage in strategic consolidation and adapt to unique local requirements.
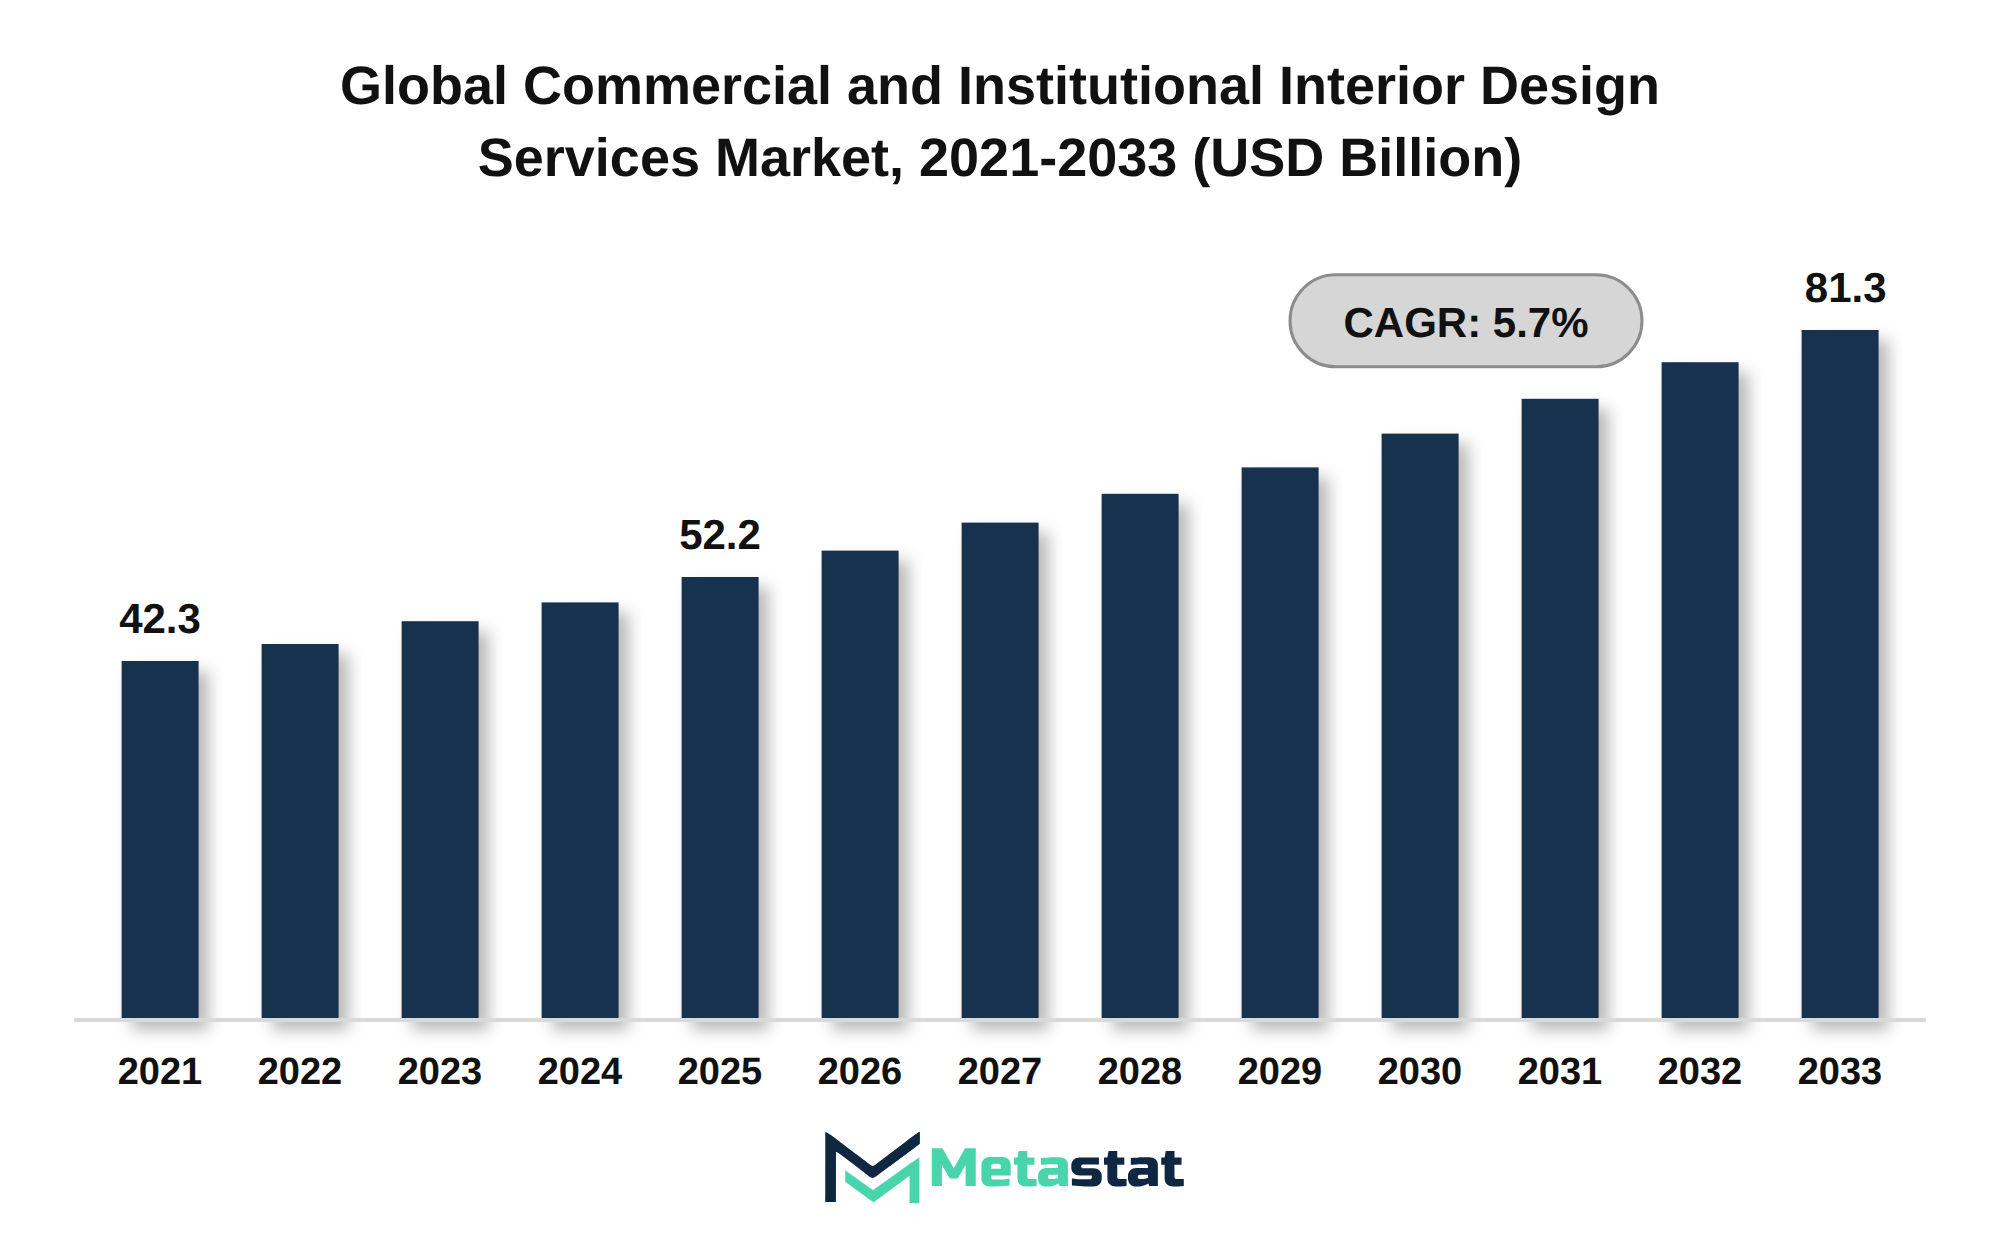
The global Commercial and Institutional Interior Design Services market was valued at USD 52.2 billion in 2025 and is projected to reach USD 81.3 billion by 2033, growing at a CAGR of 5.7% over the forecast period.
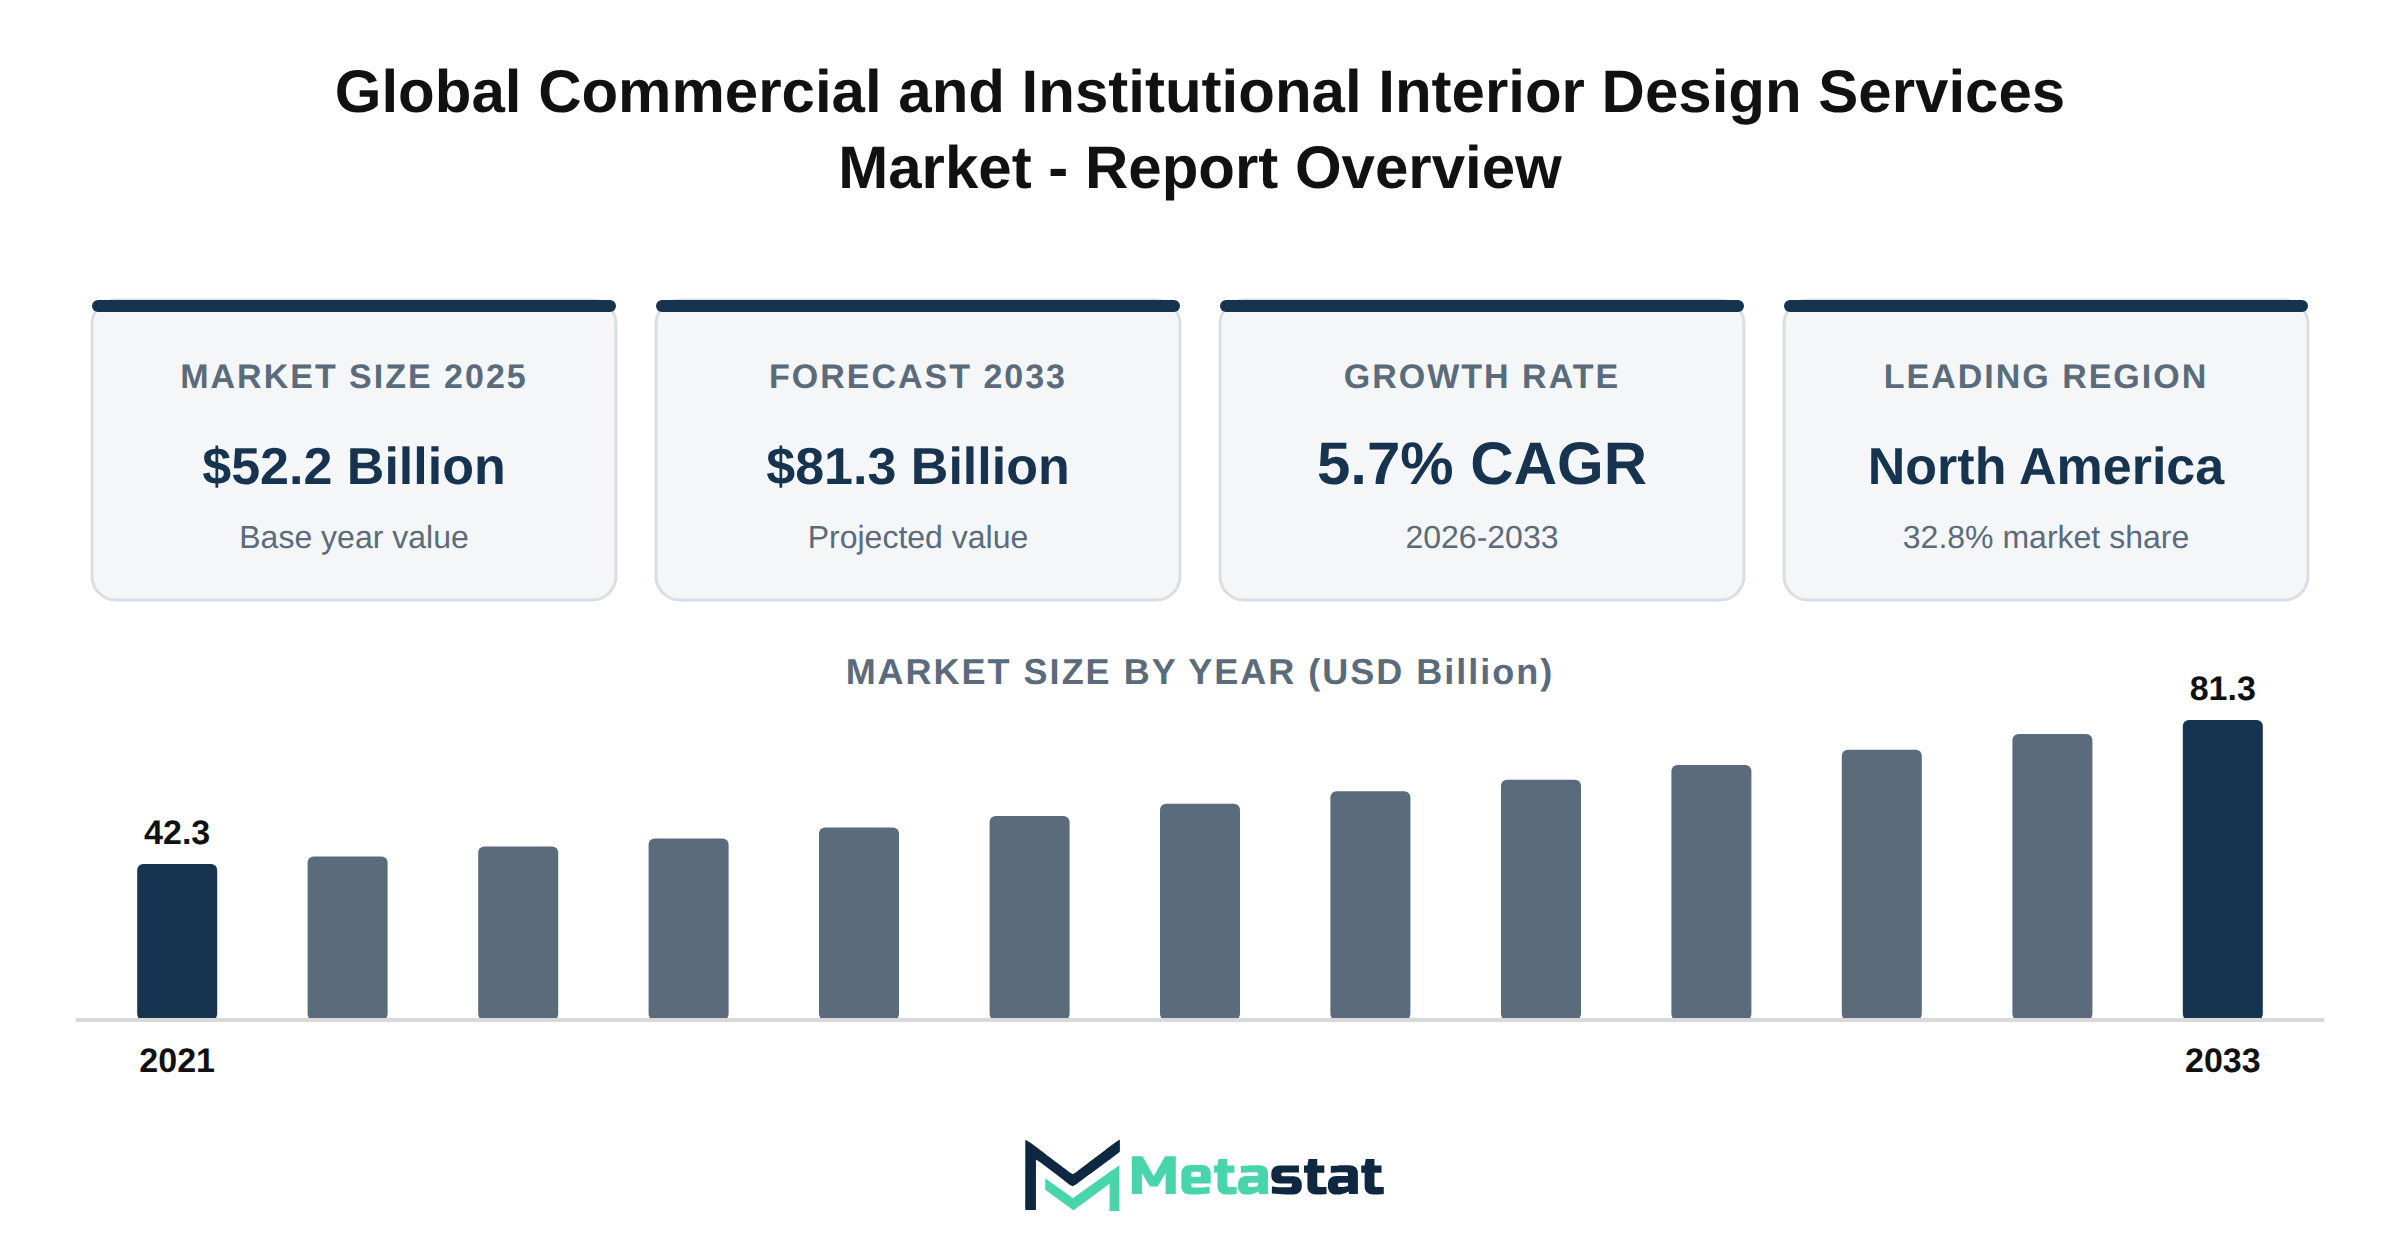
The Commercial and Institutional Interior Design Services market reached a value of USD 52.2 billion in 2025, showing significant growth from USD 42.3 billion in 2021. This upward trajectory continues, with projections estimating the market will expand to USD 81.3 billion by 2033, reflecting a compound annual growth rate (CAGR) of 5.7%. This growth is driven by increasing investment in interior design across various sectors, including corporate, hospitality, and healthcare.
Key developments in the market include the adoption of advanced technologies including Building Information Modeling (BIM), virtual reality (VR), and artificial intelligence (AI) to enhance design workflows. These innovations improve efficiency and facilitate collaboration among stakeholders. A growing emphasis on sustainability and wellness is reshaping design practices, with designers focusing on embodied carbon and material circularity to minimize environmental impact.
Public-sector procurement and tendering processes influence market dynamics, especially in large-scale projects where compliance with accessibility and wellness standards becomes essential. Interior design fee benchmarking has gained traction, providing a framework for pricing strategies in this competitive landscape. The market experiences fragmentation, with numerous players operating across various regions and sectors, leading to unique challenges and opportunities for growth.
Investments in infrastructure and capital allocation towards innovative design solutions contribute to the market's expansion. The impact of regulatory compliance and regional risk frameworks remains critical, because firms navigate evolving standards and regulations. The Commercial and Institutional Interior Design Services market is expected to witness ongoing transformation, adapting to these shifts and emphasizing the importance of strategic planning and high-value recommendations for industry stakeholders.
Community engagement in design practices plays an important role in shaping the market. Stakeholders, including local communities and clients, increasingly prioritize participatory approaches, ensuring that the design process reflects the needs and values of the users. This trend enhances user-centered design, contributing to satisfaction and functionality in the built environment.
Public-sector procurement and tendering processes significantly influence market dynamics. Government contracts often dictate design standards and requirements, affecting which firms secure projects. Competitive bidding processes encourage innovation and cost-effective solutions. Firms adopt advanced technologies and sustainable practices to meet increasingly stringent criteria.
Interior design fee benchmarking provides insight into pricing strategies within the market. Firms analyze their fee structures against industry standards to remain competitive while ensuring profitability. Understanding regional variations in fee structures allows firms to position themselves effectively and adjust their offerings based on local market conditions.
The adoption of Building Information Modeling (BIM), virtual reality (VR), and artificial intelligence (AI) in workflow processes transforms project management and design efficiency. These technologies enhance collaboration among stakeholders, streamline communication, and reduce errors during the design and construction phases. Firms leveraging these innovations gain a competitive edge by delivering projects faster and with improved accuracy.
Embodied carbon and material circularity have become critical considerations in design projects. Clients increasingly demand sustainable materials and construction practices, pushing firms to adopt eco-friendly approaches. This shift aligns with regulatory requirements and meets the expectations of environmentally conscious consumers, enhancing brand reputation and marketability.
Accessibility and wellness standards continue to evolve, impacting design criteria across various sectors. Compliance with these standards ensures that spaces are inclusive and promote well-being for all users. Firms prioritizing these aspects in their projects attract clients seeking to create environments that support health and accessibility. This focus drives demand in the market.
Regulatory compliance, standards, and regional risk frameworks shape the operational landscape within the market. Adhering to these regulations is essential for securing contracts and avoiding legal issues. Firms that proactively manage compliance mitigate risks and enhance their reputation among clients and stakeholders.
Market fragmentation presents both challenges and opportunities within the industry. A diverse range of players, from small boutiques to large firms, results in varied service offerings and pricing strategies. This fragmentation encourages innovation and specialization. Firms differentiate themselves and cater to specific client needs.
Mergers and acquisitions (M&A) dynamics influence competitive positioning within the market. Strategic partnerships and consolidations enable firms to expand their service offerings, geographic reach, and technological capabilities. These activities reshape the competitive landscape and drive investment and resource allocation in key areas.
The value chain and procurement strategies impact the efficiency and effectiveness of project delivery. Firms optimizing their supply chain and sourcing practices enhance operational performance and reduce costs. Strategic capital allocation towards research and development drives innovation, ensuring firms remain competitive in a rapidly changing market environment.
Infrastructure investments are crucial for future growth in the market. Public and private sectors increasing their spending on infrastructure projects stimulate demand for interior design services. This trend drives long-term strategic outlooks and provides opportunities for firms to engage in high-value projects that align with urban development and sustainability goals.
Corporate imperatives drive firms to adopt sustainable transformation and decarbonization practices. These initiatives comply with regulatory pressures and meet client expectations for environmental responsibility. Firms that integrate these values into their operations strengthen their market position and contribute to a more sustainable future.
Urbanization influences the Commercial and Institutional Interior Design Services market significantly. Increasing populations in urban areas create a higher demand for residential, commercial, and public spaces. Cities expand, which raises the need for innovative and functional interior design services, prompting investment in projects that enhance living and working environments.
The trend toward urban living encourages developers and businesses to invest in new construction and renovation projects. This investment aligns with consumer preferences for modern, well-designed spaces that focus on efficiency and sustainability. Enhanced living conditions within urban centers lead to higher property values, driving demand for professional interior design services.
Evolving consumer behaviors reflect a desire for personalized and adaptable spaces. Interior design firms respond by offering tailored solutions that cater to specific client needs, including environmental concerns and lifestyle preferences. This personalized approach enhances client satisfaction and positions firms competitively within the market.
The combination of urbanization and changing consumer expectations creates a robust environment for growth in the market. Firms that adapt to these dynamics by investing in innovative design techniques and technologies secure their positions, reflecting the importance of agility in the evolving interior design sector.
The expansion of infrastructure and modernization of assets significantly influences the Commercial and Institutional Interior Design Services market. Upgrading physical and digital capacities, including facilities and network capabilities, aligns with the demands of a growing economy and urban environments. Increased capital investments in infrastructure projects drive the need for innovative interior design solutions that optimize functionality and aesthetics.
Developing infrastructure enhances the appeal of commercial spaces, attracting businesses that prioritize design quality and operational efficiency. This trend generates opportunities for interior design firms to engage in high-profile projects, resulting in increased market demand. The market benefits from collaborations with construction and architectural firms, ensuring design strategies complement broader development initiatives.
Asset modernization reflects evolving consumer preferences, where contemporary design significantly enhances user experience. Companies increasingly prioritize energy-efficient and sustainable design solutions, aligning with corporate social responsibility goals. This shift directs attention toward innovative materials and technologies, further driving the evolution of the market.
Investment in infrastructure and asset modernization is projected to strengthen growth in the Commercial and Institutional Interior Design Services market. The integration of advanced technologies, including smart building systems and environmentally friendly materials, provides a competitive edge for design firms. Consequently, firms that adapt to these changes position themselves strategically within the marketplace, capturing greater revenue opportunities.
Regulatory compliance represents a significant challenge within the Commercial and Institutional Interior Design Services market. Increasingly stringent regulations impose a higher burden on firms to meet safety, accessibility, and environmental standards, resulting in increased operational costs. Compliance challenges particularly affect smaller design firms, which lack the resources required to navigate complex legal frameworks, limiting their competitiveness.
Macroeconomic pressures, including inflationary trends and rising material costs, complicate the market landscape. Firms encounter escalating operating expenses, which hinder investment in new projects and design innovations. High capital investment requirements dominate the sector, often leading to hesitance among stakeholders to initiate ambitious projects. This situation slows growth within the market.
Supply chain disruptions and geopolitical instability contribute to market restraints by creating unpredictability in sourcing materials and managing project timelines. Increased costs associated with delays erode profit margins, forcing design firms to reassess project feasibility. These disruptions disproportionately impact projects reliant on timely deliveries of specialty materials, common in high-end interior design.
Technological obsolescence presents another restraint, driven by the rapid pace of innovation that necessitates continuous investment in the latest tools and technologies. Firms that fail to adapt risk falling behind competitors, leading to market fragmentation. Talent gaps in skilled labor exacerbate these issues, because the shortage of qualified professionals limits the capacity of firms to execute projects efficiently.
Cultural barriers and regional adoption resistors complicate the market dynamics because firms seek to enter new geographical areas. Understanding and aligning with local design preferences and practices is crucial, yet challenging for many. The overall maturation of the industry cycle and market saturation further contribute to a competitive environment where differentiation becomes increasingly critical.
Geopolitical fragmentation poses significant challenges for the Commercial and Institutional Interior Design Services market. Trade deficits and tariff frictions disrupt supply chains, complicating the procurement of materials necessary for various design projects. Increased costs associated with tariffs affect pricing strategies, leading to tighter margins for design firms. This situation pressures companies to explore alternative sourcing strategies, which hinder project timelines and increase operational complexities.
Technological disruptions further complicate the market. Advancements in design technology necessitate complex research and development integrations, which require significant investment. Firms face challenges in adopting new technologies while managing interoperability friction among existing systems. This friction delays project execution and inflates costs, decreasing competitiveness in a market characterized by innovation.
Logistics disruptions and supply chain instability compound these challenges. Volatility in feedstock and component availability demands that firms maintain flexible supply chains; however, this flexibility leads to increased overhead costs. Workforce skill gaps arise from the evolution of design technologies, leading to talent retention pressures in an industry that relies heavily on specialized skills. These factors collectively impact operational efficiency and profitability within the market.
Environmental sustainability demands impose additional pressures on design firms. Increasing expectations for reduced environmental footprints necessitate investments in sustainable design practices and materials. These investments often involve higher upfront costs, which deter firms from adopting greener practices. The challenge of meeting decarbonization mandates further complicates compliance efforts, creating a landscape where design firms balance financial viability with environmental responsibility.
Changing downstream demands influence the market. Market saturation in certain segments leads to intensified competition, forcing design firms to innovate continually to differentiate themselves. Substitution pressures from alternative design solutions challenge traditional offerings, requiring firms to adapt their services to remain relevant. The combination of these factors illustrates the complexity of navigating the Commercial and Institutional Interior Design Services market in an environment that evolves continuously.
In the Commercial and Institutional Interior Design Services market, emerging regional demands present significant growth opportunities. Rapid urbanization, particularly in Asia Pacific, drives the need for modernized commercial spaces. Increased investment in infrastructure modernization across various countries enhances the demand for interior design services, particularly in new construction and renovation projects.
Geographical expansion into underserved markets results in heightened competition among service providers. Firms engaging in strategic consolidation and cross-industry mergers enhance their capabilities and resource availability. This trend increases demand for specialized services, catering to unique regional requirements and encouraging innovation in design approaches.
Technological disruptions facilitate the integration of advanced design tools and sustainable practices. Digital transformation reshapes procurement processes, allowing for more efficient project management and collaboration. The adoption of eco-friendly materials and practices aligns with sustainability imperatives, meeting the expectations of environmentally conscious clients.
Downstream market diversification indicates a shift in client preferences, with increased interest in niche applications including wellness-focused designs and adaptive reuse projects. The focus on asset life-cycle extensions, maintenance upgrades, and retrofitting dynamics enhances operational efficiency and value optimization within the market. These factors contribute to the positive growth trajectory expected within the Commercial and Institutional Interior Design Services market through 2033.
The Global Commercial and Institutional Interior Design Services market is segmented based on Service Type, Project Type, and End-Use Sector.
Valued at USD 7.7 billion in 2026, the Interior Space Planning & Programming segment is projected to reach USD 11 billion by 2033, at a CAGR of 5.2% during the forecast period. Demand for interior space planning and programming continues to grow owing to increasing investments in corporate infrastructure and an emphasis on optimizing workspace efficiency. Enhanced focus on employee wellness and productivity drives demand for versatile interior spaces that support collaboration and innovation.
Industry players actively adopt advanced design technologies, including Building Information Modeling (BIM) and 3D visualization tools, to streamline workflows and improve design accuracy. The integration of these technologies allows designers to create adaptive and functional spaces, resulting in a more responsive approach to client needs. Growing awareness of sustainable design practices influences the market, driven by organizations seeking innovative solutions to meet regulatory compliance and improve their environmental footprint.
End-use sectors including corporate offices, healthcare, and education exhibit a strong demand for effective space planning solutions. Corporate clients increasingly recognize the importance of well-designed interiors in enhancing employee satisfaction and retention. This trend drives investment in comprehensive interior design services that focus on functionality and aesthetics. The Commercial and Institutional Interior Design Services market experiences a shift toward hybrid work models, leading to higher expectations for adaptable and multifunctional spaces.
Market participants face challenges related to pricing volatility due to fluctuating material costs and supply chain disruptions. Strategic investments in supply chain resilience and raw material sourcing mitigate these risks and sustain operational efficiency. Competitive pressures compel firms to innovate continuously and deliver high-quality services while managing cost structures effectively.
The outlook for the Interior Space Planning & Programming segment appears robust, supported by a favorable investment climate and increasing domestic and international demand. While the market progresses, the ongoing evolution of design trends and technologies will create new opportunities for growth and differentiation.
Growing demand for innovative design solutions significantly influences the Interior Architecture & Detailing segment of the Commercial and Institutional Interior Design Services market. This demand arises from the need for aesthetically pleasing and functional spaces that enhance user experience across various industries. Urban development, coupled with rising investments in commercial real estate, drives expansion within this segment. Firms adopt advanced design methodologies and technologies to meet these evolving requirements.
Technological advancements facilitate the integration of sustainable practices and smart building solutions into design projects. Increased focus on energy efficiency, wellness, and accessibility shapes design approaches, with architects prioritizing environmentally friendly materials and practices. These factors contribute to a competitive market environment where firms strive to differentiate their offerings, enhancing their market positions and operational efficiencies.
The Interior Architecture & Detailing segment is projected to reach USD 14.7 billion by 2033, at a CAGR of 5.1% during the forecast period. The increasing importance of branding in commercial spaces necessitates design solutions that reflect corporate identity while meeting functional requirements. This trend encourages architects to engage in creative processes that align aesthetic goals with organizational values, ultimately supporting long-term demand.
End-use sectors including corporate, hospitality, and healthcare exhibit heightened demand for tailored design solutions. These sectors prioritize unique spatial experiences, leading to innovations in interior architecture that cater to specific user needs. Consequently, firms within the segment experience growth opportunities through strategic partnerships and collaborations, enhancing service offerings and driving competitive advantages in the market.
Growing demand for innovative and aesthetically pleasing interior spaces drives the Materials, Finishes & Color Design segment within the Commercial and Institutional Interior Design Services market. Factors fueling this growth include the increasing emphasis on sustainable and wellness-oriented designs, which require the incorporation of eco-friendly materials and appealing color schemes that enhance the overall ambiance of spaces.
By 2033, the segment is expected to reach USD 8.5 billion, signifying significant growth opportunities. The evolving preferences of end-users, particularly in the corporate, hospitality, and healthcare sectors, significantly influence design choices. These sectors prioritize environments that enhance productivity, comfort, and well-being, necessitating advanced materials and finishes that cater to these needs.
Technological advancements in product development and a focus on customization further enhance the segment's appeal. Innovations in materials, along with the rise of digital design tools, enable designers to create tailored solutions that align with client visions. This trend drives the adoption of unique finishes and color palettes that reflect brand identity and enhance user experiences.
Regulatory standards concerning sustainability and health impact material selection, influencing design decisions across various sectors. Compliance with these standards encourages the adoption of environmentally friendly materials, reinforcing the commitment to sustainable design practices.
Increased investment in commercial real estate and ongoing renovation projects across multiple sectors contribute to the segment's expansion. While organizations seek to modernize their interiors, the demand for expert design services in materials and finishes continues to rise, shaping the trajectory of the market.
Significant investment in the Furniture, Fixtures & Equipment (FF&E) Design & Specification segment reflects the growing importance of tailored environments in enhancing user experience within various settings. This segment is projected to grow at a CAGR of 5.6% during the forecast period. Demand stems from the need for functional, aesthetically pleasing, and sustainable interior solutions across multiple end-use sectors, including corporate, hospitality, and healthcare. Technological advancements continue to drive product evolution, with innovative materials and design practices enhancing durability and user comfort. The shift towards sustainable and wellness-oriented design in the market further increases adoption of furniture and fixtures that comply with environmental standards and certifications. Competition intensifies because firms innovate to create differentiated offerings, capitalizing on strategic opportunity windows. Companies that effectively leverage current trends in workplace wellness and sustainability will find significant growth potential in this segment. The ongoing transformation within the commercial and institutional interior design services market highlights the necessity for firms to align their strategies with changing consumer preferences and industry standards.
Incorporating effective lighting design and coordination into interior projects enhances both functionality and aesthetics. The demand for well-lit spaces continues to rise, driven by the need for improved energy efficiency and occupant comfort. Technological advancements in lighting solutions, including LED technologies and smart lighting systems, contribute to this trend by providing innovative options that integrate seamlessly with various design concepts. Increased awareness of the psychological effects of lighting on productivity and well-being in workspaces and public areas fuels adoption across multiple sectors.
The evolution of design standards and sustainability regulations further influences the market, encouraging designers to prioritize energy-efficient lighting solutions. Compliance with these regulations ensures that projects meet the expectations of modern consumers, particularly in sectors including hospitality and corporate environments. These end-use dynamics define market growth, with a focus on creating environments that align with changing consumer preferences and corporate responsibility goals.
Investments in this segment present strategic opportunities for product innovation and differentiation. Designers frequently explore next-generation upgrades that enhance user experience and environmental impact. Focus on aesthetics remains critical, driven by unique lighting solutions that contribute to branding and user engagement in commercial spaces. The integration of technology in lighting design encourages a collaborative approach, benefiting not only designers but stakeholders throughout the project lifecycle. Overall, the segment is significant within the broader Commercial and Institutional Interior Design Services market, addressing consumer demands while facilitating sustainable design practices.
Signage, Wayfinding & Environmental Graphics plays an essential role in enhancing the user experience within various environments, including corporate offices, healthcare facilities, and educational institutions. Increasing urbanization and demographic shifts drive the demand for effective wayfinding solutions, improving navigation in complex spaces. These factors lead to a heightened focus on user-centered design, which promotes accessibility and enhances visitor satisfaction.
Technological advancements significantly influence the evolution of this sub-segment. The integration of digital displays and interactive signage provides dynamic information to users, improving engagement and facilitating communication. Innovations in materials and printing techniques contribute to the development of more durable and environmentally friendly signage solutions. This technological maturation supports the expansion of product offerings and enhances operational efficiencies across the market.
End-use dynamics demonstrate distinct preferences among different sectors. In corporate environments, the focus lies on branding and creating a cohesive identity through signage. Healthcare facilities emphasize clear wayfinding solutions to improve patient navigation and reduce anxiety. Educational institutions prioritize informative and engaging graphics that support learning. These varying demands create strategic opportunity windows for firms specializing in signage, wayfinding, and environmental graphics within the Commercial and Institutional Interior Design Services market.
Regulatory compliance standards regarding accessibility and safety heighten the importance of effective signage. Meeting these requirements ensures that spaces are navigable for all users, contributing to overall satisfaction and compliance. The market faces challenges related to pricing volatility and margin pressures, driven by fluctuations in raw material costs and competition among providers. Addressing supply chain resilience remains vital to ensure timely delivery and maintain quality standards in this evolving segment.
Consumer preferences for unique and immersive spaces influence the demand for branded and experiential interior design within the Commercial and Institutional Interior Design Services market. Businesses increasingly recognize the importance of creating environments that align with their brand identity, promote engagement and enhance customer experiences. This demand drives interior designers to incorporate unique elements that reflect brand values, offering tailored solutions that support branding initiatives.
Technological advancements enhance the capabilities of designers in delivering experiential spaces. Tools including virtual reality and advanced visualization techniques enable designers to create dynamic environments that engage users and provide a sense of place. These innovations improve the exploration of design concepts, allowing stakeholders to experience spaces before implementation, thus enhancing decision-making processes.
The rise of e-commerce and digital interaction prompts companies to rethink the physical presence of their brands. Businesses seek to create experiential environments that encourage foot traffic and customer interaction, further driving the demand for this design segment. The shift towards experiential commerce reflects a broader movement within the market, emphasizing the value of physical spaces in an increasingly digital world.
Regulatory compliance and standards related to sustainability and accessibility remain critical factors in shaping design initiatives. Adhering to these standards not only aligns with consumer expectations but strengthens brand reputation. Designers integrating sustainable materials and practices into their work enhance their marketability, appealing to environmentally conscious consumers.
Shifts in workplace dynamics, particularly the rise of hybrid work models, create opportunities for innovative interior solutions. Companies seek to adapt their environments to accommodate both collaborative and individual work, leading to an increased focus on flexible and multifunctional spaces. This evolution within workplaces highlights the importance of thoughtful design in enhancing productivity and employee satisfaction.
Growing awareness of sustainable practices significantly shapes the design choices within the Commercial and Institutional Interior Design Services market. Clients increasingly demand environments that enhance well-being and accessibility, driving the adoption of strategies focused on health, comfort, and inclusivity. This trend aligns with broader societal shifts towards responsible consumption and environmentally friendly practices, positioning sustainable, wellness, and accessibility design because essential considerations for modern interior projects.
The segment experiences considerable interest due to regulatory compliance standards that advocate for sustainable and accessible environments. Designers utilize innovative materials and techniques to align with these standards, enhancing the market's appeal. The focus on wellness informs not only aesthetic choices but operational efficiencies, creating spaces that promote productivity and well-being for occupants.
Technological maturation supports segment expansion. Advanced design software and tools facilitate the integration of sustainable practices, enabling designers to visualize complex ideas and execute them effectively. The ongoing evolution of product offerings, including eco-friendly materials and adaptive solutions, further enriches the design landscape, catering to a diverse clientele.
Consumption shifts highlight the importance of user experience, making wellness and accessibility key priorities in interior design. Companies increasingly recognize the value of creating spaces that meet diverse needs, reflecting demographic trends and societal expectations. This recognition stimulates demand and encourages investment in innovative solutions.
Strategic opportunity windows for suppliers emerge through collaborations that promote sustainable practices and enhance market offerings. By investing in research and development, companies capitalize on evolving consumer preferences for environmentally responsible design. The focus on sustainability, well-being, and accessibility in the market creates a strong framework for future growth, influencing investment strategies and shaping competitive dynamics.
Demand for Construction Documentation & Administration services stems from the need for precise planning and quality assurance in interior design projects. Regulatory compliance standards drive the implementation of thorough documentation processes, ensuring that all designs meet local building codes and safety regulations.
Technological advancements enhance the efficiency of documentation practices, with software solutions improving collaboration and streamlining workflows. The integration of Building Information Modeling (BIM) systems supports accurate project visualization, aiding in the detection of potential issues before construction begins.
Increased focus on sustainability impacts the evolution of documentation practices. Clients prioritize environmentally friendly designs, prompting designers to incorporate sustainable materials and specify eco-friendly practices within their documentation. This shift influences project dynamics across various end-use sectors, particularly in corporate, hospitality, and healthcare environments.
Consumption shifts towards flexible and adaptable interior spaces require comprehensive documentation that captures evolving client expectations. Organizations seek innovative solutions, and the demand for specialized documentation services grows, reflecting broader trends in the Commercial and Institutional Interior Design Services market.
Strategic opportunity windows arise from the ongoing need for renovations and modernizations within existing structures. Clients seek to enhance functionality while addressing aesthetic concerns, necessitating detailed documentation to guide these transformations. This trend contributes to the overall growth of the market, creating a favorable environment for firms specializing in construction documentation.
Raw material sourcing challenges and demands for cost-effective solutions pressure designers to optimize their documentation processes. Effective cost management within the documentation phase influences overall project budgets, prompting firms to adopt innovative practices that reduce waste and enhance efficiency.
Technological obsolescence remains a concern, compelling firms to adapt their documentation approaches continuously. Staying current with the latest advancements ensures that designers remain competitive and capable of meeting client demands, driving growth in the segment.
Increased adoption of Visualization & Digital Design Services reflects the shift towards digitalization in the Commercial and Institutional Interior Design Services market. This segment benefits from advancements in technology and software that enhance design processes, enabling architects and designers to create accurate visual representations of interior spaces. Strong collaboration with clients throughout the design phase enhances project outcomes, improving client satisfaction and trust in design capabilities.
Emerging trends in the market include a growing focus on immersive experiences, which drives demand for advanced visualization tools. Clients increasingly seek designs that not only fulfill functional requirements but create engaging environments. This trend drives the expansion of visualization services, reflecting firms' efforts to differentiate their offerings in a competitive landscape.
Technological maturation significantly influences the evolution of visualization services. Innovations including virtual reality (VR) and augmented reality (AR) facilitate interactive client presentations, allowing for real-time modifications and immediate feedback. This capability enhances the design experience, aligning with the market's drive towards greater efficiency and responsiveness to client needs.
Strategic investment in next-generation upgrades remains crucial for firms competing in the visualization space. Enhancements in software capabilities, including improved rendering speeds and more sophisticated modeling tools, enable designers to improve the quality of their work. Such improvements contribute to higher client retention rates and the ability to secure new projects within the market.
Consumption shifts towards sustainable design solutions impact the demand for visualization services. Clients increasingly prioritize eco-friendly practices and materials, influencing design choices. Visualization services that emphasize sustainability align with these preferences, capturing the attention of environmentally conscious clients.
End-use dynamics illustrate a diverse array of applications for visualization services across various sectors, including corporate, hospitality, and healthcare. Each sector exhibits unique design needs, prompting firms to tailor their offerings accordingly. This adaptability strengthens the overall service proposition, providing opportunities for growth within the market.
New Construction Interiors segment is valued at USD 14.4 billion in 2026 and is projected to reach USD 20.9 billion by 2033, at a CAGR of 5.5% during the forecast period. Demand for this segment arises primarily from the growing focus on developing modern infrastructure in both urban and suburban areas. Increased construction activities in commercial, residential, and institutional sectors drive this demand, necessitating comprehensive design solutions that facilitate efficient space utilization and enhance aesthetic appeal.
Investment in new construction projects continues to accelerate, influenced by rising urbanization rates and economic expansion in various regions. The push for sustainable and eco-friendly construction practices shapes design considerations. Customers prioritize sustainable materials and energy-efficient designs, aligning with global trends toward environmental consciousness. This evolution in demand necessitates adaptation from service providers focused on New Construction Interiors, pushing them to innovate and refine their offerings.
Technological advancements in design software and Building Information Modeling (BIM) enhance project execution efficiency and accuracy. These advancements support designers in creating customized solutions tailored to specific client needs. The integration of advanced technologies positively influences the market, promoting growth opportunities for firms that leverage these tools effectively.
End-use sectors including corporate offices and healthcare facilities increasingly invest in new construction projects to improve operational efficiency and enhance user experience. This trend reinforces the value of comprehensive interior design services tailored to specific functional requirements. The Commercial and Institutional Interior Design Services market stands to expand significantly due to these ongoing shifts within various sectors.
Growing interest in upgrading existing facilities drives investment in the Renovation & Modernization segment of the Commercial and Institutional Interior Design Services market. Clients prioritize enhancing the functionality and aesthetics of aging spaces, creating a significant opportunity for designers specializing in this area. This segment is expected to reach USD 20.2 billion by 2033, at a CAGR of 6% during the forecast period, reflecting strong demand for design solutions that adapt to evolving user needs.
Factors contributing to this growth include the increasing focus on sustainability and energy efficiency in redesign projects. Businesses, particularly in the corporate and office sector, incorporate eco-friendly materials and practices, contributing to a more sustainable future. Regulatory compliance regarding updated safety standards and accessibility features necessitates renovations, particularly in healthcare and public facilities. The demand for modernized spaces extends beyond aesthetics, emphasizing functional design that meets current operational requirements.
Technological advancements significantly influence the Renovation & Modernization segment. Integration of smart building technologies enhances operational efficiency and user experience. Clients seek designs that incorporate these technologies, facilitating effective interactions and improved building performance. The market's evolution towards next-generation upgrades creates a strategic opportunity for interior designers to leverage innovative solutions in their projects.
Demographic shifts and changes in work patterns, including the rise of remote and hybrid work environments, drive the need for adaptable spaces. Organizations aim to create flexible interiors that support diverse work styles, motivating investments in renovation projects. This shift in consumption patterns indicates a strong preference for spaces that promote collaboration, productivity, and employee well-being.
The Commercial and Institutional Interior Design Services market continues to experience a dynamic range of factors shaping the Renovation & Modernization segment. Designers respond to shifting consumer preferences and industry demands, while the segment's growth trajectory aligns with broader market trends, ensuring its relevance in the years to come.
Increasing investment in commercial spaces drives the Interior Fit-Out & Tenant Improvement segment, aligning with trends toward enhancing workplace functionality and aesthetics. Demand arises from enterprises seeking to adapt spaces for evolving work environments, incorporating flexible layouts and modern amenities. This segment is characterized by a projected value of USD 18.1 billion by 2033, reflecting a compound annual growth rate of 6.7 percent. Strategic initiatives aimed at increasing productivity and employee satisfaction drive growth, particularly in corporate offices and retail settings.
Technological advancements support the integration of smart systems and sustainable materials within tenant improvement projects. Adoption of innovative design solutions enhances operational efficiency and reduces long-term costs. Regulatory compliance and sustainability certifications influence decision-making, motivating stakeholders to invest in projects that align with environmental standards. Changing consumer preferences for dynamic spaces emphasize the importance of interior design that facilitates collaboration and creativity.
The competitive landscape within the Commercial and Institutional Interior Design Services market highlights the necessity for firms to differentiate through unique offerings and specialized expertise. Providers focusing on adaptive reuse and modernization strategies capture a growing share of the market, repurposing existing structures for new applications. Increasing urbanization and population growth further necessitate investments in interior fit-out projects, reinforcing the segment's critical role in the broader design services market.
Increasing focus on sustainability drives interest in the Adaptive Reuse & Change-of-Use Conversion segment within the Commercial and Institutional Interior Design Services market. This segment effectively repurposes existing structures, reducing environmental impact and conserving resources. Growing urbanization trends lead to a higher demand for innovative solutions that transform underutilized spaces into functional environments. The preservation of historical buildings, along with adaptive reuse, aligns with evolving community values and preferences for unique environments.
Adaptive Reuse & Change-of-Use Conversion segment is projected to grow at a CAGR of 6.7% during the forecast period. This growth results from regulatory pressures emphasizing sustainable practices and community revitalization efforts. Significant investment in enhancing existing infrastructures presents ample opportunities for designers engaged in this segment. Clients increasingly seek design services that reflect their commitment to sustainability, prompting firms to innovate and integrate modern aesthetics with preservation.
End-use dynamics play a crucial role in shaping demand within this segment. The Corporate & Office sector shows notable interest in transforming older buildings into collaborative workspaces, while the Hospitality sector invests in repurposing historical properties to create unique guest experiences. Shifts in consumption patterns, driven by the desire for personalized and distinctive spaces, emphasize the importance of this segment in the broader market. The Commercial and Institutional Interior Design Services market continues to evolve owing to firms adapting to these trends, ensuring relevance and growth.
Investment in Expansion & Addition Interiors is driven by a rising trend among businesses to optimize space utilization and enhance operational efficiency. Enterprises prioritize adapting existing spaces to accommodate growth, evolving workforce needs, and technological advancements. This trend aligns with the demand for flexible spaces that support collaboration and innovative work environments, which directly influences growth within the Commercial and Institutional Interior Design Services market.
Technological maturation in design tools and methodologies facilitates the adoption of advanced design concepts. Innovations in materials, finishes, and design processes significantly improve the quality of interior environments, enabling designers to create functional, aesthetically pleasing, and sustainable spaces. These developments create an environment conducive to the expansion of the market.
Regulatory compliance and sustainability standards increasingly shape design decisions. The implementation of green building certifications encourages businesses to invest in environmentally friendly renovation and addition projects, promoting overall market expansion. Clients actively seek design services that align with these standards, reinforcing the relevance of Expansion & Addition Interiors within the broader interior design sector.
Cost structures in this segment reflect the need for a balance between quality and budget. Designers face increasing pricing volatility from raw material sourcing and labor costs, which directly influences project outcomes and timelines. Businesses navigate these challenges, and the emphasis on strategic investment in high-quality design services remains crucial for enhancing operational margins and overall project success.
Consumption shifts toward adaptive reuse and renovation initiatives signal a significant opportunity window for design firms. Clients prioritize projects that transform underutilized spaces into functional areas catering to modern demands. This strategic focus allows designers to contribute to the ongoing evolution of the Commercial and Institutional Interior Design Services market, ensuring sustainable growth and continued relevance in a dynamic environment.
Investment in the Refurbishment & Rebranding segment reflects strong demand for updated and modernized spaces within existing structures. A focus on enhancing aesthetics and functionality drives this trend across various end-use sectors, particularly in Corporate & Office and Hospitality environments. The market observes a significant push towards creating flexible, adaptive spaces that cater to evolving consumer preferences and operational needs. This shift supports opportunities for interior design services prioritizing innovative design solutions and adaptive reuse strategies, ensuring spaces remain competitive and relevant.
Increasing regulatory compliance standards and sustainability practices shape design approaches in the refurbishment sector. Compliance with updated building codes and environmental regulations influences design decisions, prompting firms to incorporate sustainable materials and practices in their projects. These factors enhance the overall appeal of refurbished spaces, aligning them with contemporary expectations for functionality and environmental responsibility within the Commercial and Institutional Interior Design Services market. Stakeholders recognize these dynamics to navigate the complexities of refurbishment and rebranding effectively.
Investment in workplace design prioritizes functionality and employee well-being, driving growth in the Corporate & Office segment. Flexible workspaces and collaboration areas enhance productivity, leading organizations to explore innovative design solutions. Companies focus on integrating technology within their environments, promoting efficiency and connectivity. The shift toward remote and hybrid work models influences design strategies, emphasizing adaptable spaces that cater to evolving workforce needs.
The Corporate & Office segment is valued at USD 13.2 billion in 2026 and is projected to reach USD 18.6 billion by 2033, at a CAGR of 5.1% during the forecast period. Increased demand for modernized office interiors drives investment in renovation and modernization initiatives. The market's expansion aligns with rising corporate budgets for interior design services, emphasizing aesthetics and functionality. Organizations prioritize employee engagement, and the emphasis on appealing workspaces intensifies, propelling demand within the Corporate & Office segment of the Commercial and Institutional Interior Design Services market.
Regulatory compliance standards and certifications related to workplace safety and accessibility influence design choices. Companies adopt sustainable practices, integrating eco-friendly materials and energy-efficient solutions into their office interiors. These trends create strategic opportunities for designers, positioning them to deliver innovative solutions that meet both aesthetic and functional requirements. The evolving landscape of workplace design reflects a commitment to enhancing employee satisfaction and operational efficiency, contributing to the overall growth of the market.
Investment in the hospitality sector drives robust demand for interior design services, reflecting evolving consumer preferences and the need for enhanced guest experiences. The hospitality segment is estimated to reach USD 11.9 billion by 2033, at a CAGR of 6.1% during the forecast period. Renovation and modernization projects increasingly prioritize immersive and aesthetically pleasing environments, significantly influencing design strategies. Adoption of sustainable materials and practices aligns with consumer expectations, prompting businesses to invest in eco-friendly designs that enhance market appeal. Collaboration among interior designers, architects, and hospitality professionals is essential in delivering innovative solutions tailored to client needs.
Regulatory compliance and certification standards impact design choices, especially in sectors where safety and accessibility are critical. These regulations create a competitive environment, prompting firms to enhance service offerings. The market experiences price volatility due to fluctuations in raw material costs, prompting firms to optimize cost structures while maintaining design quality. Strategic investment in technology and digital design services promotes efficiency and responsiveness to market trends, enabling operators to capture emerging opportunities in the hospitality sector. Continuous evaluation of consumption shifts enhances alignment with customer needs, supporting sustainable growth within the Commercial and Institutional Interior Design Services market.
Growing consumer demand for engaging and memorable retail experiences drives the Retail & Consumer Experience segment within the Commercial and Institutional Interior Design Services market. This segment reflects a shift towards creating immersive environments that enhance customer interaction and satisfaction. Retailers increasingly prioritize unique store designs that align with brand identity. These designs not only attract foot traffic but increase dwell time, enhancing sales potential.
Investment in this segment is expected to reach USD 7.4 billion by 2033, indicating a positive growth trajectory. Technological advancements, including augmented reality and interactive displays, play a critical role in evolving retail spaces. These technologies enhance consumer engagement and provide innovative ways for brands to connect with their audience, establishing a competitive edge in the market.
The ongoing trend towards e-commerce has prompted brick-and-mortar retailers to differentiate their physical spaces. The focus shifts towards experiential design, where retail environments serve because destinations rather than mere shopping venues. This transformation leads to increased capital investment in design services tailored to enhance customer experience, driving the overall market forward.
Investment in the Healthcare & Life Sciences segment reflects a growing emphasis on patient-centered design and innovative healthcare environments. This shift arises from the need for facilities that promote healing and wellness while enhancing operational efficiencies. Healthcare providers prioritize environments that improve patient outcomes and staff productivity, driving demand for specialized interior design services tailored to medical facilities.
The segment is projected to grow at a CAGR of 6.7% during the forecast period. Strategies for integrating technology into healthcare environments influence design trends, focusing on efficient workflows and advanced medical technologies. The need for regulatory compliance and adherence to healthcare standards significantly shapes the design processes in this sector, ensuring facilities meet both operational and safety requirements.
Downstream applications of design in healthcare extend beyond traditional patient care areas, encompassing research facilities and outpatient centers. This expansion highlights the importance of versatile design that accommodates evolving healthcare practices. The focus on sustainability and wellness in design further addresses the increasing demand for environments that enhance the overall experience for patients and staff. Overall, growth within the Healthcare & Life Sciences segment contributes to the broader dynamics of the Commercial and Institutional Interior Design Services market.
Investments in educational facilities focus on creating engaging and adaptable learning environments. This trend aligns with the increasing emphasis on enhancing student experiences and improving educational outcomes. Educational institutions are adopting innovative design strategies that prioritize flexibility, technology integration, and sustainability. These design approaches create collaborative learning spaces that accommodate diverse instructional methods and learning styles.
Regulatory compliance plays a critical role in shaping design practices within the education sector. Adhering to safety standards and accessibility regulations ensures that spaces serve all students effectively. Institutions increasingly prioritize designs that support wellness and accessibility, aligning with broader societal goals for inclusivity. This regulatory focus enhances the overall quality of educational environments.
Shifts in educational paradigms drive demand for specialized design services that cater to modern teaching methodologies. The integration of technology necessitates spaces that support digital learning and collaboration. Designers increasingly focus on creating environments that facilitate active learning, reflecting a transformation in how education occurs. These dynamics position the education segment because a significant component of the Commercial and Institutional Interior Design Services market.
Strategic investment in educational facilities represents an opportunity for designers to expand their portfolios. The focus on innovative learning environments opens avenues for collaboration between educational institutions and design professionals. This collaborative approach improves the design process, ensuring that spaces are tailored to the specific needs of educational communities. Consequently, the education sector stands out because a vital area for growth within the market.
Investment in Government, Civic & Public Facilities generates substantial opportunities within the Commercial and Institutional Interior Design Services market. Increasing demand for modern public spaces enhances the need for innovative design solutions that address functionality, accessibility, and sustainability. Regulatory pressures to meet compliance standards significantly influence design choices, compelling firms to adapt their strategies and offerings.
Technological advancements fuel next-generation upgrades that enhance user experiences within government and civic spaces. The integration of smart technologies enables better resource management and operational efficiency, resulting in heightened interest among stakeholders. Design firms benefit from collaborating with public sector entities, leveraging their expertise to meet evolving expectations and design requirements.
Budget constraints often impact project timelines and scopes, prompting a focus on efficient cost structures and strategic resource allocation. Public entities seek to maximize the value of their investments, leading to innovative financing models and partnerships with private firms. This approach creates a resilient supply chain that enhances the ability to address challenges in raw material sourcing and logistical vulnerabilities.
While public awareness of environmental sustainability grows, demand for eco-friendly materials and practices in design projects strengthens. Stakeholders prioritize sustainable designs that promote well-being and community engagement, aligning with broader societal goals. This trend positions firms specializing in sustainable design solutions favorably within the market, driven by increasing expectations of clients in the public sector.
Overall, the Government, Civic & Public Facilities segment emphasizes the importance of adaptability and innovation in the face of shifting demands. This dynamic environment offers strategic opportunity windows for firms ready to invest in their capabilities and expand their service offerings within the Commercial and Institutional Interior Design Services market.
Increasing investment in sports, recreation, and wellness facilities reflects a shift towards enhancing community engagement and promoting active lifestyles. Demand arises from municipalities, educational institutions, and private entities prioritizing facilities that encourage physical activity and social interaction. Adoption of innovative design solutions addresses the need for multifunctional spaces that accommodate a variety of activities. The market experiences expansion due to increased awareness of health and well-being benefits associated with well-designed recreational spaces.
Technological advancements play a significant role in shaping this segment, with next-gen upgrades focused on sustainable materials and smart design features. Trends towards eco-friendly practices influence project specifications, aligning with regulatory compliance and consumer preferences for sustainable options. Consumption shifts towards experiences that blend leisure and wellness, encouraging investments in facilities that promote both physical and mental health. This evolving environment presents strategic opportunities for designers to create environments that enhance community connection and individual well-being.
Capital investment in this segment remains robust, driven by public-private partnerships and funding from health initiatives. The focus on creating adaptable and inclusive environments enhances market appeal while addressing diverse community needs. Participants in the Commercial and Institutional Interior Design Services market are positioned to leverage these trends, driving innovation and growth within the sports, recreation, and wellness sub-segment.
Demand for interior design services in the Transportation & Aviation sub-segment reflects the need for enhanced passenger experiences and operational efficiencies. Evolving consumer expectations drive airlines and airport authorities to invest in innovative design solutions that facilitate travel and improve overall satisfaction. Strategic upgrades focus on creating functional and aesthetic environments, catering to both leisure and business travelers.
Investments in sustainable practices contribute to the attractiveness of Transportation & Aviation design projects. Regulatory compliance and evolving environmental standards push organizations to adopt design practices that prioritize energy efficiency and reduced carbon footprints. This shift aligns with the broader goals of the Commercial and Institutional Interior Design Services market, encouraging firms to explore sustainable materials and methods.
Technological advancements accelerate design processes and enhance the functionality of transportation spaces. The integration of smart technologies into design projects improves operational efficiency and customer engagement. Airports increasingly adopt digital signage and interactive kiosks, promoting a more navigable environment for travelers and enhancing their overall experience.
Competition among design firms intensifies due to rising project complexity. Organizations adapt to rapidly changing market demands, often leading to strategic partnerships and collaborations that enhance design offerings. This dynamic encourages continuous innovation and differentiation within the Transportation & Aviation segment, positioning firms to capture emerging opportunities in the evolving landscape of commercial and institutional design.
Investment in Cultural & Entertainment Facilities reflects a growing trend toward creating immersive environments that enhance guest experiences. This segment benefits from rising consumer engagement in cultural and entertainment activities, prompting stakeholders to prioritize innovative design and functionality. Increased funding for entertainment venues, theaters, museums, and cultural centers drives demand for specialized interior design services, emphasizing unique aesthetics and user-friendly spaces.
Technological maturation influences design strategies within this segment. Advances in design software, virtual reality, and augmented reality tools enable designers to create interactive and engaging experiences, providing a competitive edge in the market. Next-generation upgrades focus on integrating sustainable materials and energy-efficient solutions, catering to environmentally conscious consumers and regulatory compliance standards.
Changes in consumer preferences influence design decisions in cultural and entertainment facilities. A shift toward multifunctional spaces that accommodate various events encourages designers to innovate layouts and functionalities. These evolving dynamics create opportunities for interior designers to offer tailored solutions that enhance both aesthetic appeal and practicality.
Investment in this sub-segment strengthens supply chain resilience by emphasizing partnerships with local artisans and manufacturers, promoting regional craftsmanship. Strategic opportunity windows arise from the increasing demand for experiential design, creating a favorable environment for interior design services tailored to cultural and entertainment venues. Overall, the Cultural & Entertainment Facilities segment within the Commercial and Institutional Interior Design Services market presents significant potential for growth and innovation.
Investment in religious facilities and specialized community facilities reflects a growing emphasis on creating spaces that promote community engagement and spiritual well-being. These facilities require careful consideration of design elements that reflect their unique cultural and functional requirements, ensuring they meet the needs of diverse user groups. This demand arises from broader societal trends prioritizing inclusivity and accessibility, driving efforts to create welcoming environments for all users.
Technological advancements play a significant role in shaping the design of these spaces, with innovations enhancing user experience through improved acoustics, lighting, and environmental comfort. Adoption of sustainable design practices aligns with the increasing focus on environmental responsibility, influencing the selection of materials and building techniques. Regulatory compliance standards and certifications further guide the design process, ensuring facilities adhere to necessary codes while promoting safety and accessibility.
Investment in these specialized facilities contributes to the overall growth of the Commercial and Institutional Interior Design Services market. The sector's evolution reflects changing consumption patterns. A shift toward designing spaces that support not only functionality but community interaction and cultural expression is evident.
Based on geography, the Global Commercial and Institutional Interior Design Services market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
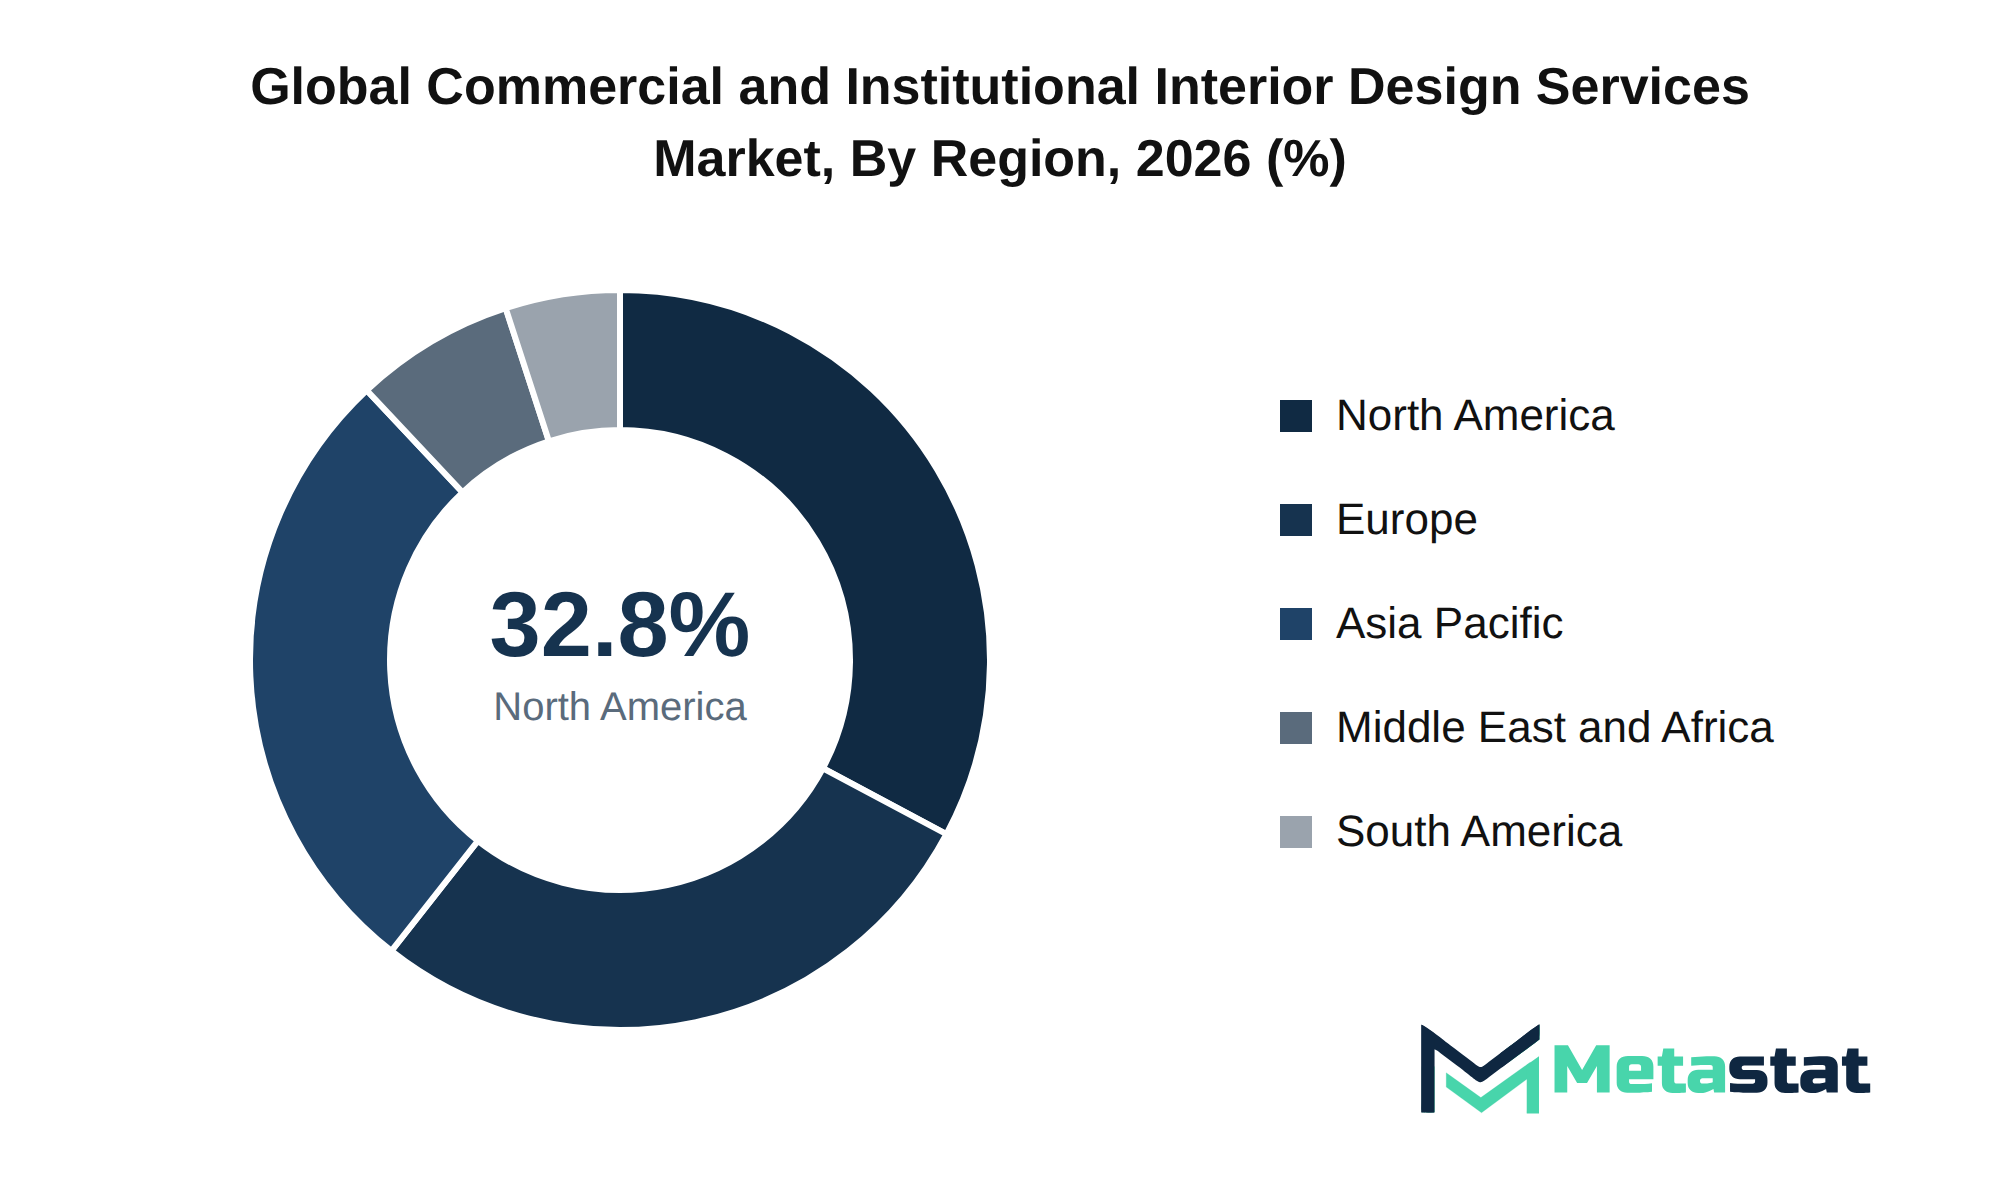
North America Commercial and Institutional Interior Design Services Market is set to expand at a CAGR of 5.7% within the forecast period, reaching a market size (TAM) of USD 24.9 billion by the end of 2033. The region encompasses the United States, Canada, and Mexico, contributing significantly to the global market. Several factors drive the growth of the market, including increasing corporate investment in modern workspace design, reflecting a focus on employee satisfaction and productivity.
Corporations prioritize workspace functionality alongside aesthetic appeal, leading to a notable rise in demand for innovative interior design solutions. The renovation and modernization segment is experiencing notable growth, attributed to ongoing efforts to enhance existing facilities, ensuring they meet contemporary standards and occupant needs. Factors including aging infrastructure and evolving client demands contribute to this segment's expansion.
The healthcare sector presents strong potential, with investments directed toward creating patient-centric environments. Healthcare facilities increasingly emphasize wellness, driving demand for specialized design services that enhance the patient experience. The retail and consumer experience segment thrives on the need for engaging environments that promote brand loyalty and customer interaction.
Local compliance mandates and regulatory frameworks further shape the market dynamics in North America. Companies actively adapt to evolving standards for sustainability and accessibility, influencing design strategies. The region's competitive landscape highlights key players including Gensler, Perkins&Will, and HOK, who operate in the market through innovation and strategic partnerships, ensuring relevance in a rapidly changing environment.
Regional supply chain factors, including localized manufacturing densities and nearshoring initiatives, contribute to operational efficiency. These trends enable companies to respond swiftly to market needs while maintaining quality and cost-effectiveness. Overall, the North American Commercial and Institutional Interior Design Services market reflects a positive growth trajectory driven by a combination of strategic investments and evolving consumer preferences.
In Europe, the Commercial and Institutional Interior Design Services market benefits from a diverse range of drivers. Key countries including Germany, France, the UK, Italy, and Spain contribute significantly to market growth through investments in infrastructure modernization and urban development. These nations display a strong commitment to enhancing public and private spaces, reflecting changing consumer preferences and evolving work environments.
The market experiences robust demand owing to increasing urbanization, which spurs the need for innovative design solutions across various sectors. Corporate and office spaces drive substantial growth, influenced by a focus on employee well-being and productivity. The hospitality sector in Europe prioritizes unique and experiential design elements, creating a competitive edge in attracting visitors and clients.
Cultural nuances and regional B2B buying behaviors significantly shape the market landscape. Each country's unique regulatory frameworks and compliance mandates affect procurement processes, creating opportunities for localized procurement strategies. Domestic market leaders adapt to these dynamics, ensuring alignment with consumer expectations and regulatory requirements.
Germany and France emerge because key front-runners, with their mature market dynamics supporting high-value replacement cycles. Continuous investment in new construction interiors supports this trend, enhancing the market's overall growth trajectory. The competitive landscape in Europe includes a blend of established players and innovative newcomers, driving advancements in sustainable and wellness-focused design.
Local compliance and trade policy shifts influence cross-border trade corridors, while geopolitical factors introduce complexities in the supply chain. Manufacturers and designers engage in strategic nearshoring initiatives, optimizing logistics and production capabilities closer to key markets. This regionalization enhances resilience within the market, ensuring adaptability to changing economic conditions.
Overall, the European segment of the Commercial and Institutional Interior Design Services market demonstrates strong growth potential, driven by emerging opportunities and evolving consumer demands. While the market progresses, a focus on sustainability and innovative design practices will likely shape future developments, supporting continued expansion and collaboration across the region.
The Asia-Pacific region holds a share of the Commercial and Institutional Interior Design Services market, accounting for 27.4% in 2025. Rapid urbanization, coupled with a growing middle class, fuels a strong demand for innovative and functional interior design solutions across various sectors.
China, Japan, India, and South Korea emerge because key players in this landscape, supported by robust economic growth and substantial investments in infrastructure modernization. The expansion of the corporate sector in these countries leads to increased demand for office spaces, necessitating strategic interior design services that enhance productivity and employee satisfaction.
Australia’s hospitality sector presents substantial opportunities for interior design firms, focusing on creating unique experiences that attract tourists and locals alike. Southeast Asia features an underpenetrated market, with increasing investments in commercial and institutional projects providing fertile ground for market growth.
Competitive dynamics in the region include a blend of established players and emerging firms, encouraging innovation and pushing for higher standards in service delivery. Local compliance mandates and evolving trade policies shape the operational environment, influencing design trends and procurement strategies.
Cost-effective solutions and sustainable design practices gain traction, aligning with regional resource availability and energy grid resiliency initiatives. The Commercial and Institutional Interior Design Services market in Asia-Pacific is poised for steady growth, with expected expansion driven by investment in new construction and renovation projects across various end-use sectors.
The Commercial and Institutional Interior Design Services market in South America presents unique growth opportunities, driven by an expanding urban population and increased consumer spending. Brazil and Argentina play significant roles in this development, exhibiting rising demand for modern and sustainable interior design solutions across various sectors, particularly in corporate, hospitality, and retail. Infrastructure modernization initiatives in these countries enhance the market's potential, focusing on improving public spaces and commercial environments.
Localized procurement dynamics significantly influence market trends, reflecting businesses' efforts to align with regional cultural nuances and B2B buying behaviors. Expansion in urban centers prompts a higher demand for renovation and modernization projects, alongside new construction efforts that prioritize innovative design. The emerging market front-runners highlight the importance of adaptive reuse and tenant improvement strategies, which cater to changing consumer preferences and sustainability goals.
The South American market's share of the global landscape is projected at 5.00% in 2025, indicating a solid foothold in the international Commercial and Institutional Interior Design Services market. Competitive landscapes evolve with domestic market leaders driving the sector's growth, while foreign direct investment (FDI) flows contribute to the region's overall economic vitality. Ongoing modernization efforts and increased local manufacturing densities position South America's market for sustained growth through 2033.
The Middle East and Africa region presents notable growth opportunities within the Commercial and Institutional Interior Design Services market. Countries including Saudi Arabia and the UAE actively invest in infrastructure modernization and urban development projects, resulting in heightened demand for innovative interior design solutions. Rising population and urbanization in South Africa further contribute to the expansion of this market segment.
Emerging market front-runners in the region include Saudi Arabia and the UAE, which have established ambitious development plans that drive demand for comprehensive design services. The increasing focus on cultural aesthetics and functionality in commercial spaces influences interior design preferences and practices. Local compliance mandates and regulations enhance the need for professionals adept in navigating regional requirements, ensuring projects meet specific standards.
Supply chain regionalization and nearshoring initiatives facilitate localized manufacturing capabilities, contributing to operational efficiency and cost-effectiveness. The regional competitive landscape features a combination of established players and new entrants, enhancing service diversity and innovation. Domestic market participants adapt to emerging trends, reflecting unique cultural nuances and regional B2B buying behaviors that characterize this market.
Overall, the Commercial and Institutional Interior Design Services market in the Middle East and Africa is poised for steady growth, driven by infrastructure developments and changing consumer preferences. The region's focus on enhancing public and private spaces aligns with global trends, creating a favorable environment for investment and expansion.
Competition in the Commercial and Institutional Interior Design Services market involves several strategic behaviors among key players. Companies focus on mergers, acquisitions, and strategic consolidation to enhance their service capabilities and market reach. For instance, the integration of resources among firms like Gensler, HOK, and AECOM strengthens their position in delivering comprehensive design solutions.
Strategic alliances and joint ventures emerge because significant tactics for companies aiming to expand their service offerings and enter new markets. Partnerships among firms including Perkins&Will and HDR, Inc. facilitate the sharing of expertise and resources, driving innovation in project delivery. Firms emphasize product differentiation through unique design approaches and proprietary technologies to create competitive advantages.
Barriers to entry remain high due to established brand equity and strong customer retention strategies employed by major players. The presence of technologically defensible intellectual property portfolios enhances competition, making it challenging for new entrants to disrupt the market. The future competitive outlook indicates ongoing strategic growth vectors, particularly in emerging sectors like healthcare and hospitality, which present significant opportunities for market expansion.
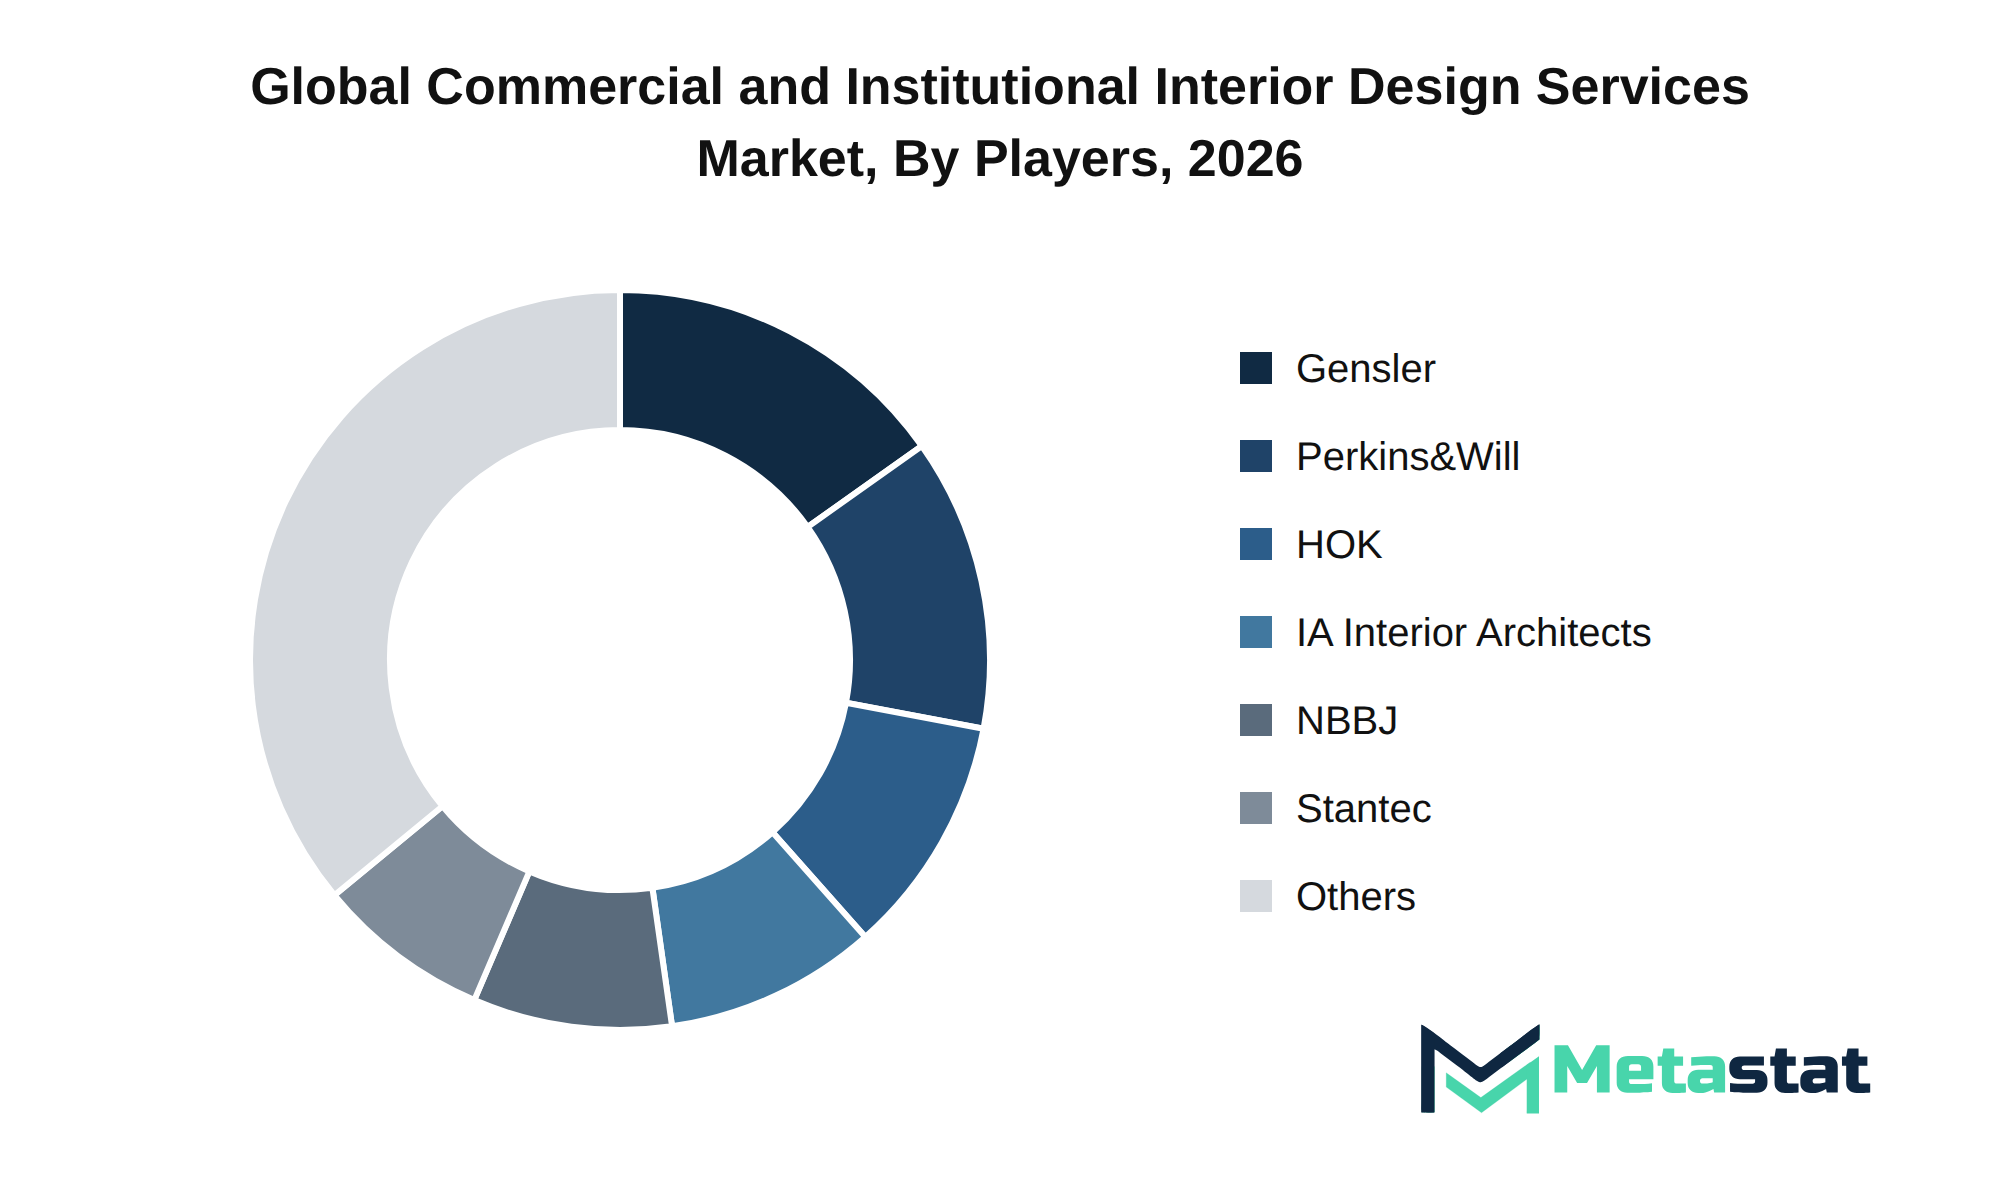
Market size is forecast to rise from USD 52.2 billion in 2025 to over USD 81.3 billion by 2033. The base case anticipates a compound annual growth rate (CAGR) of 5.7%. This growth reflects various macroeconomic factors, including economic cycle dynamics and changing downstream demand. Core industry maturation coupled with structural consumption shifts supports the evolving landscape of the Commercial and Institutional Interior Design Services market.
Next-generation technology integration enhances service offerings, while ongoing research and development (R&D) commercialization timelines drive innovation. Regulatory evolution and compliance milestones influence operational frameworks, shaping industry standards. Geopolitical realignments and shifting trade corridors affect supply chain dynamics, leading to strategic capital allocation directives and infrastructure commitments that further impact the market.
Emerging white-space opportunities highlight unmet enterprise needs, presenting high-growth pockets that attract investment. Executive-level strategic imperatives focus on defensibility roadmaps and growth recommendations, aligning with the market's evolving demands. Overall, the forecast signals a positive trajectory, reinforced by robust investment in infrastructure and strategic initiatives across sectors.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Commercial and Institutional Interior Design Services market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 5.7% from 2026 to 2033 |
Revenue Unit | USD billion |
Segmentation | By Service Type, Project Type, End-Use Sector, and Region |
By Region | North America (By Service Type, Project Type, End-Use Sector, and Country)
|
Europe (By Service Type, Project Type, End-Use Sector, and Country)
| |
Asia Pacific (By Service Type, Project Type, End-Use Sector, and Country)
| |
South America (By Service Type, Project Type, End-Use Sector, and Country)
| |
Middle East and Africa (By Service Type, Project Type, End-Use Sector, and Country)
|
Find answers to common questions about this report
The Commercial and Institutional Interior Design Services market size was valued at USD 52.2 billion in 2025, according to the Metastat Insights study.
The Commercial and Institutional Interior Design Services market is projected to grow at a CAGR of 5.7% during the forecast period from 2026 to 2033.
The North America Commercial and Institutional Interior Design Services market size is estimated to reach USD 24.9 billion by 2033.
The segment "New Construction Interiors" leads the Commercial and Institutional Interior Design Services market, with a projected value of USD 20.9 billion by 2033. This segment demonstrates significant growth potential compared to other segments.
Urbanization significantly drives the Commercial and Institutional Interior Design Services market, with increasing urban populations creating demand for innovative and functional spaces. Investment in infrastructure and asset modernization aligns with consumer preferences for modern, efficient designs, enhancing market growth opportunities.
North America holds the dominant share of the Commercial and Institutional Interior Design Services market, with a value of USD 24.9 billion in 2033, representing 32.8 percent of the total market.
Several factors restrain growth in the Commercial and Institutional Interior Design Services market. Increasingly stringent regulations raise operational costs, particularly impacting smaller firms. macroeconomic pressures, supply chain disruptions, and talent gaps in skilled labor complicate project execution and limit competitiveness.
Urbanization significantly influences product adoption in the Commercial and Institutional Interior Design Services market. Growing demand for innovative and functional design solutions arises from increased investments in urban construction and renovation projects, aligning with consumer preferences for modern, efficient, and sustainable spaces. This trend creates a robust environment for growth and adoption of tailored interior design services.
The Commercial and Institutional Interior Design Services market is estimated to reach a valuation of USD 81.3 billion by 2033.
Key players in the Commercial and Institutional Interior Design Services market include Gensler, Perkins&Will, IA Interior Architects, HOK, HKS, Inc., and Stantec Inc.
Choose Your License
Global Commercial and Institutional Interior Design Services Market
The analysts below cover Professional Services research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.
PRINCIPAL CONSULTANT - QUALITY SYSTEMS & COMPLIANCE
Electronics and Semiconductor · Machinery & Equipment · Professional Services
Omkar Phadtare is an Industry Consultant at MetaStat Insight, specializing in quality systems, regulatory compliance, and standards benchmarking to drive data-driven market intelligence and strategic industry research.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Evaluating sovereign cloud deployments for core banking platforms demands a clear view of data residency regulations and migration exit strategies. MetaStat Insight delivered an exhaustive review of regional latency tolerances, mainframe decommission milestones, and third-party vendor concentration risk. The regulatory compliance mapping across European and Asian financial jurisdictions gave our team a dependable baseline for multi-cloud infrastructure discussions.
Replacing petrochemical surfactants with bio-based alternatives requires realistic timelines on industrial precision fermentation scaling. The market research broke down commercialization timelines, feedstock sugar price sensitivities, and regional cosmetic ingredient regulatory approvals in Europe and East Asia. That supplier readiness mapping gave our formulations team reliable context when comparing renewable chemical sourcing roadmaps.
Tracking ceramic matrix composite adoption in high-bypass aero engines requires strict attention to material qualification cycles and FAA airworthiness testing milestones. The MetaStat Insight team provided a detailed timeline of silicon carbide fiber manufacturing capacity and commercial foundry lead times. Having clear visibility into upstream thermal barrier coating supply helped us stress-test our long-term component procurement strategy.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950
Starting from
$2950