
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Hyaluronic Acid-based Dermal Fillers Market Size, Share, By Gel Structure (Monophasic HA Fillers and Biphasic HA Fillers), By Product Phase (Single-Phase and Duplex), By Application (Wrinkle & Fold Correction, Lip Augmentation & Contouring, Cheek & Midface Volumization, Chin & Jawline Contouring, Periorbital Hollows & Tear Trough Correction, Non-Surgical Rhinoplasty, Hand Rejuvenation, Body Contouring & Volumization), By End User (Dermatology Clinics, Plastic & Cosmetic Surgery Clinics, Hospitals & Ambulatory Surgical Centers, Dental Aesthetic Practices), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5378
September, 2026
262 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $5,541.5 Million in 2025, projected to reach $12,682.6 Million by 2033 at a 10.9% CAGR.
Dominant Segment: Monophasic HA Fillers lead the market, driven by their effectiveness in wrinkle and fold correction, which has increased adoption in both aesthetic and medical applications.
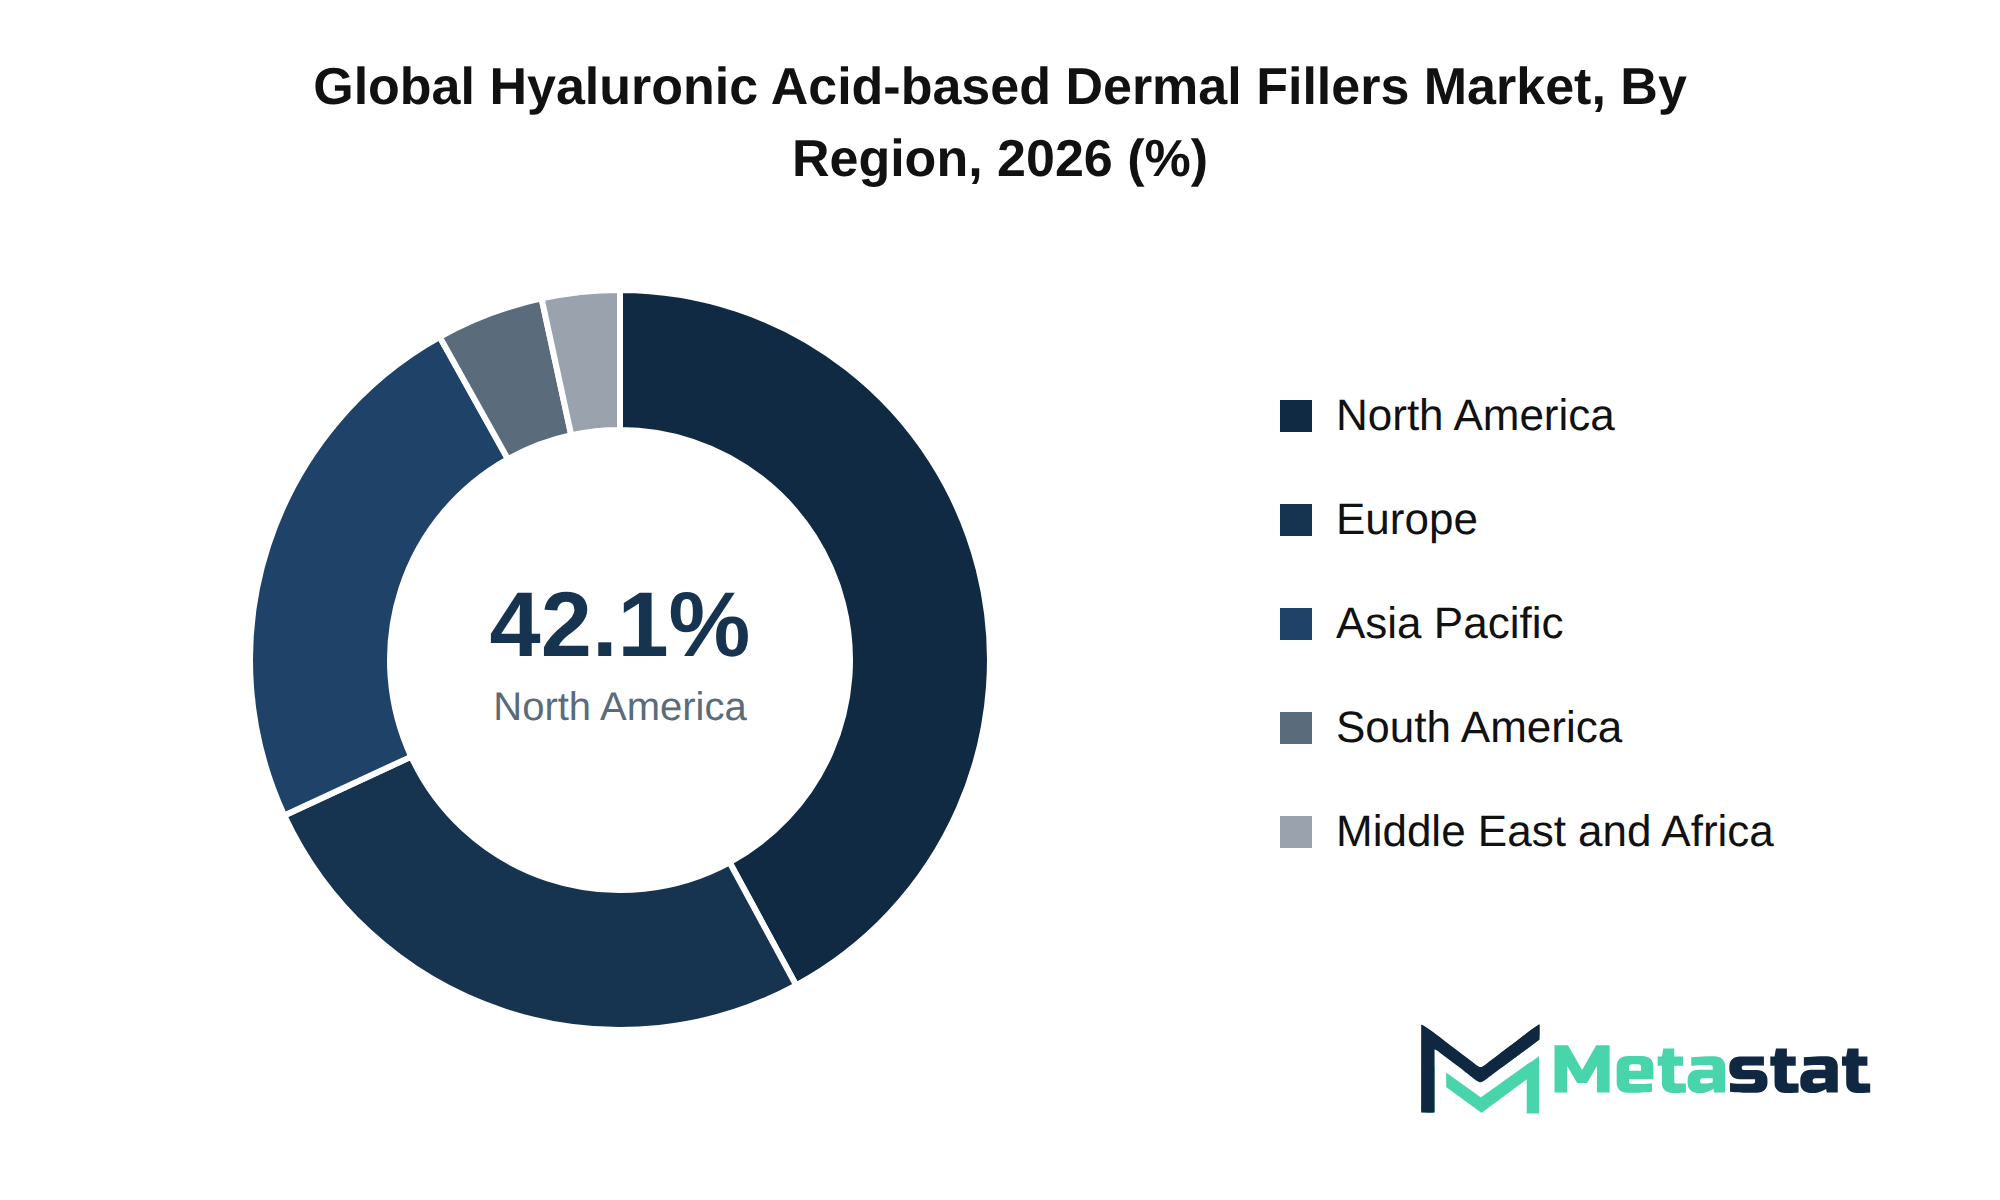
Geographic Lead: North America holds the largest market share at 42.1%, supported by rising consumer demand for non-invasive aesthetic procedures and a well-established healthcare infrastructure.
What's Inside: The report provides comprehensive coverage of market dynamics, competitive landscape, and detailed segmentation by gel structure, product phase, application, and end user, along with growth forecasts through 2033.
Emerging Technologies: Technological advancements in formulation and delivery methods are enhancing product efficacy and safety, driving market growth and attracting a broader customer base.
The global Hyaluronic Acid-based Dermal Fillers market was valued at USD 5,541.5 million in 2025 and is projected to reach USD 12,682.6 million by 2033, growing at a CAGR of 10.9% over the forecast period.
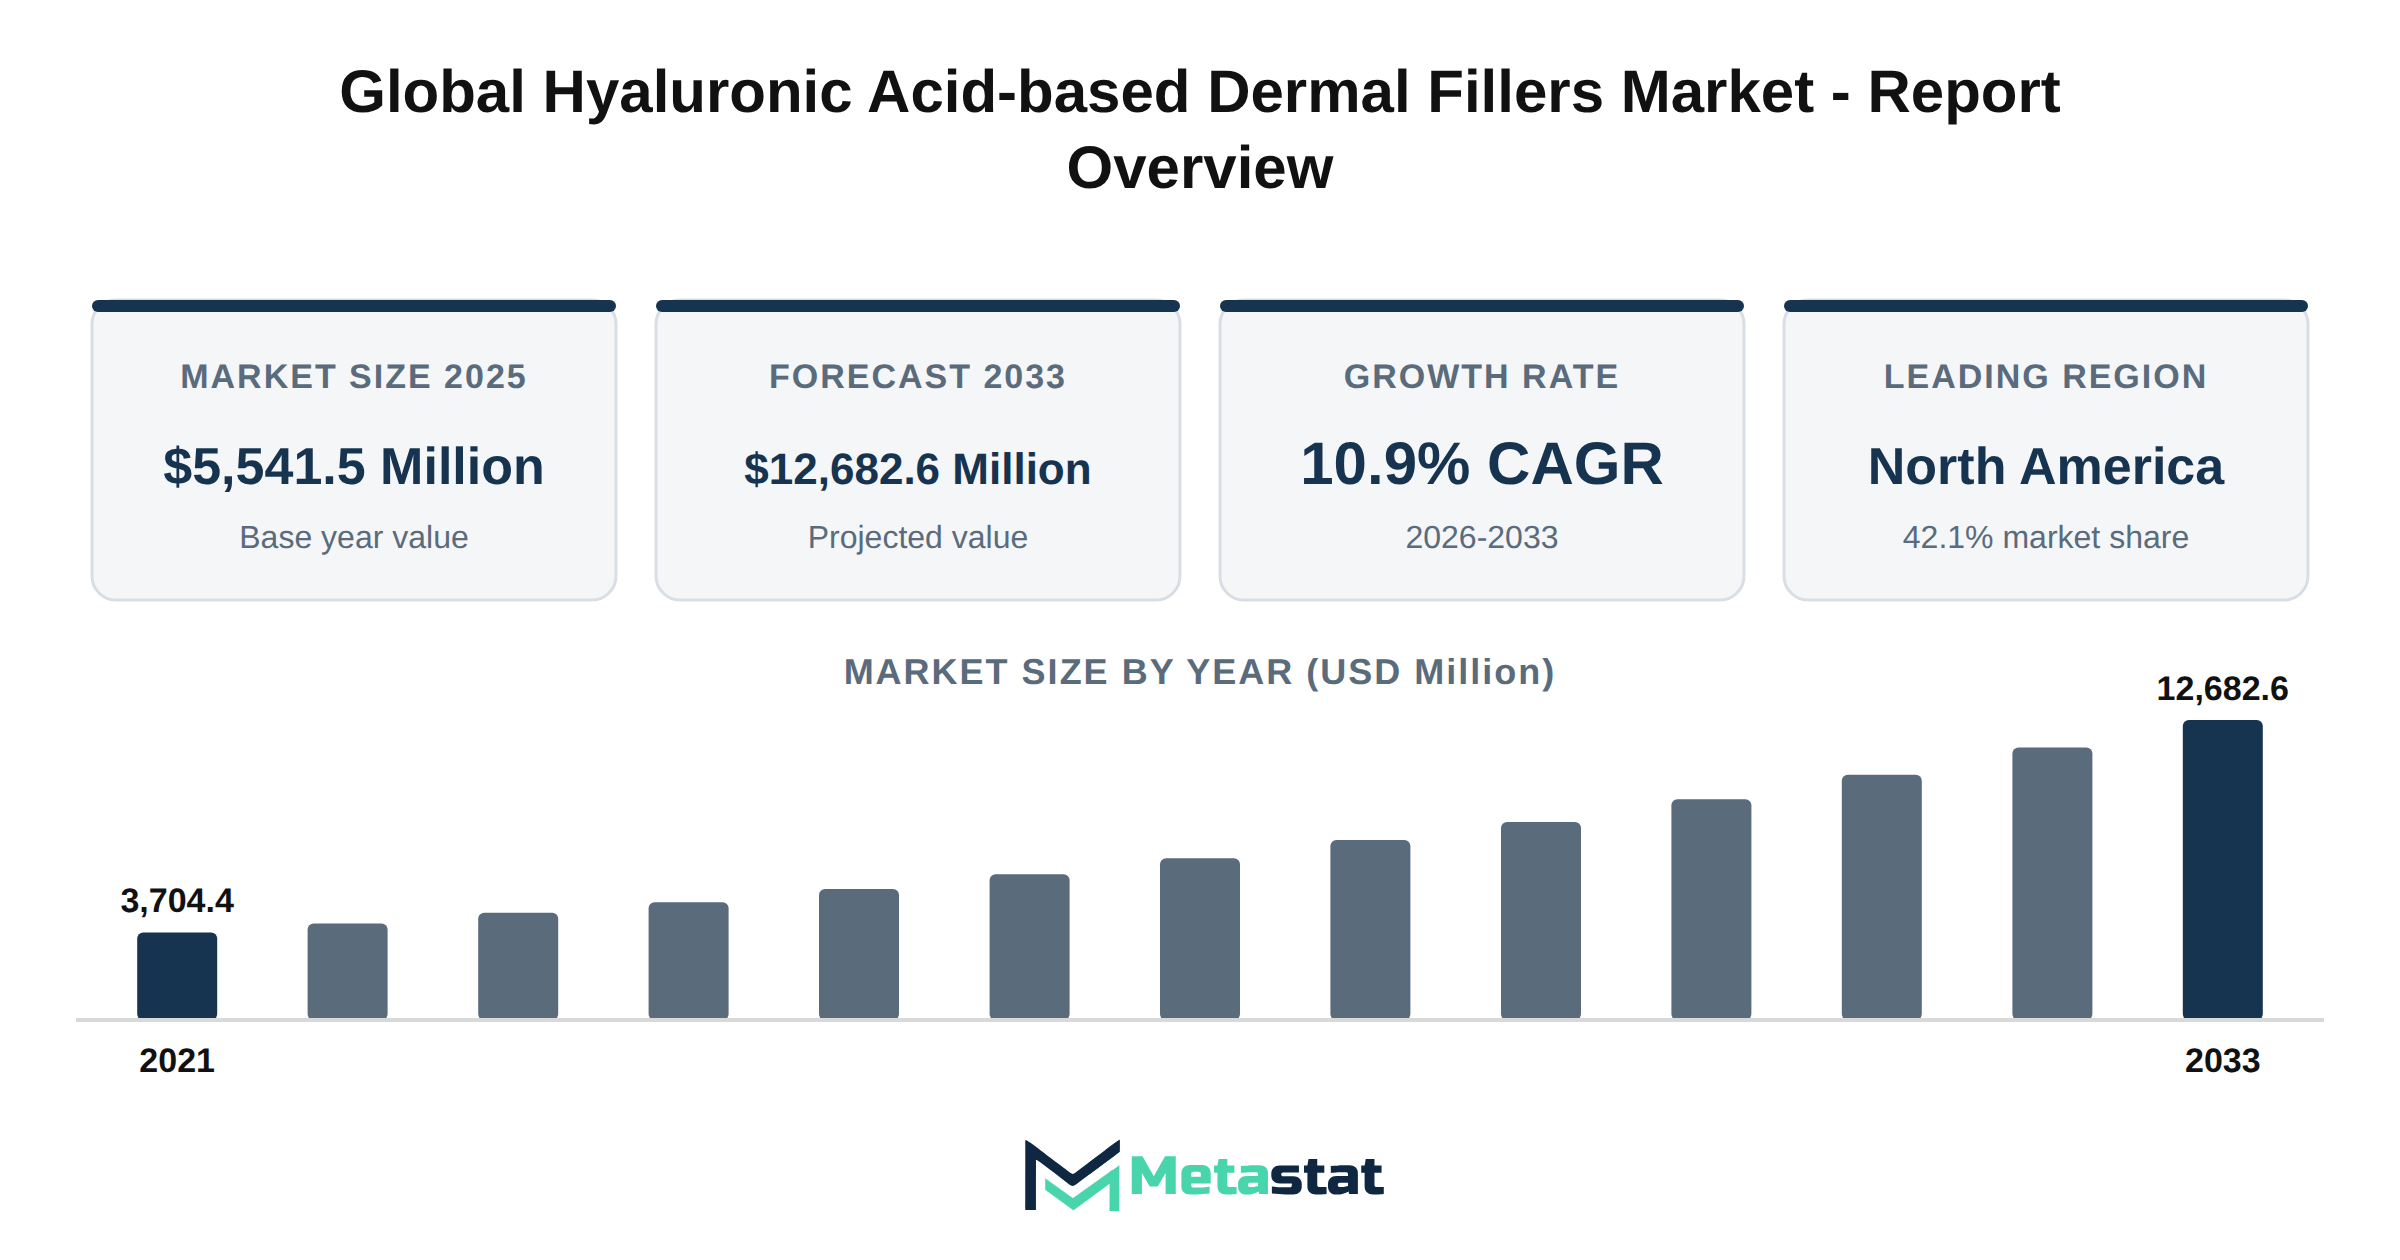
The Hyaluronic Acid-based Dermal Fillers market is poised for substantial growth, with projections indicating an increase from USD 5,541.5 million in 2025 to USD 12,682.6 million by 2033, representing a compound annual growth rate (CAGR) of 10.9%. This growth trajectory is driven by rising consumer demand for minimally invasive aesthetic procedures, reflecting a shift towards non-surgical options in facial rejuvenation. The increasing preference for natural-looking results contributes significantly to this upward trend.
Innovations in cross-linking, rheology, and network technology enhance the performance of hyaluronic acid fillers. Monophasic and biphasic formulations demonstrate unique properties, catering to diverse application needs. Continuous advancements in gel formulation lead to long-lasting results, further promoting market adoption. The competition among manufacturers intensifies with the launch of new products, presenting an array of technological advancements and improved safety profiles.
The market environment is characterized by a dynamic distributor channel and direct sales strategies, enabling broader access to consumers. Regulatory environments in various regions impact product availability and market growth. North America holds a market share of 42.1%, while Europe and Asia Pacific follow with 26% and 23.8% respectively. Emerging markets in Latin America and the Middle East present new opportunities for expansion, driven by increasing awareness and accessibility of aesthetic treatments.
Demand for lip augmentation and facial contouring procedures continues to rise, with specific trends indicating growth in cheek, chin, and jawline volumization. Wrinkle correction procedures remain a key aspect of the market, reflecting consumer priorities in facial aesthetics. The adoption of hyaluronic acid fillers for non-surgical rhinoplasty and periorbital treatments further diversifies application areas, enhancing overall market penetration.
The Hyaluronic Acid-based Dermal Fillers market experiences significant growth driven by rising demand for minimally invasive facial aesthetic procedures. The increasing preference for non-surgical options aligns with consumer desires for natural-looking results. Innovations in monophasic and biphasic HA filler technologies enhance product offerings, enabling practitioners to cater to diverse aesthetic needs.
Advancements in cross-linking and gel rheology contribute to the development of long-lasting hyaluronic acid filler formulations. These innovations improve the stability and longevity of fillers, meeting the expectations of patients seeking durable aesthetic enhancements. Demand for lip augmentation and facial contouring continues to rise, supported by trends that emphasize sculpted facial features and proportional aesthetics.
Growth opportunities in cheek, chin, and jawline volumization further reflect the evolving preferences of consumers. The market sees increasing adoption of wrinkle correction and facial rejuvenation procedures, driven by an aging population and heightened awareness of aesthetic treatments. Trends in periorbital and tear trough filler applications illustrate the expanding reach of hyaluronic acid-based solutions in addressing specific facial concerns.
The popularity of non-surgical rhinoplasty using hyaluronic acid fillers demonstrates the versatility of these products in enhancing facial profiles without invasive techniques. Emerging body contouring applications for HA dermal fillers present additional avenues for market growth, appealing to a broader range of patients and practitioners.
Patients increasingly prioritize personalized aesthetic outcomes, creating a demand for tailored treatment plans that consider individual features and preferences. Safety and biocompatibility remain critical factors influencing consumer choices, with ongoing efforts in adverse event management enhancing confidence in product use. Regulatory approval trends for hyaluronic acid injectable fillers reflect a commitment to maintaining high standards within the industry.
The competitive landscape of the market features numerous manufacturers striving to differentiate their offerings through innovative product launches and next-generation filler portfolios. Medical aesthetic clinic and dermatology channel expansion drives market penetration, while distributor and direct sales strategies play vital roles in reaching a diverse clientele. Pricing and premiumization trends in hyaluronic acid dermal fillers highlight the evolving market dynamics, with consumers willing to invest in high-quality products that deliver desirable results.
North America remains a key region in HA dermal filler demand and procedure trends, driven by a robust aesthetic industry and increasing consumer spending. Europe witnesses significant regulatory and competitive developments, influencing market access and product adoption. The Asia Pacific region shows promising growth, with medical aesthetics expanding rapidly and creating opportunities for new entrants. Emerging market opportunities in Latin America and the Middle East present avenues for growth, supported by rising disposable incomes and changing beauty standards.
Physician training and injector expertise serve because critical drivers for market adoption, ensuring practitioners deliver safe and effective treatments. Future growth opportunities in personalized injectable aesthetics highlight the industry's adaptability to consumer preferences, positioning the market for continued expansion.
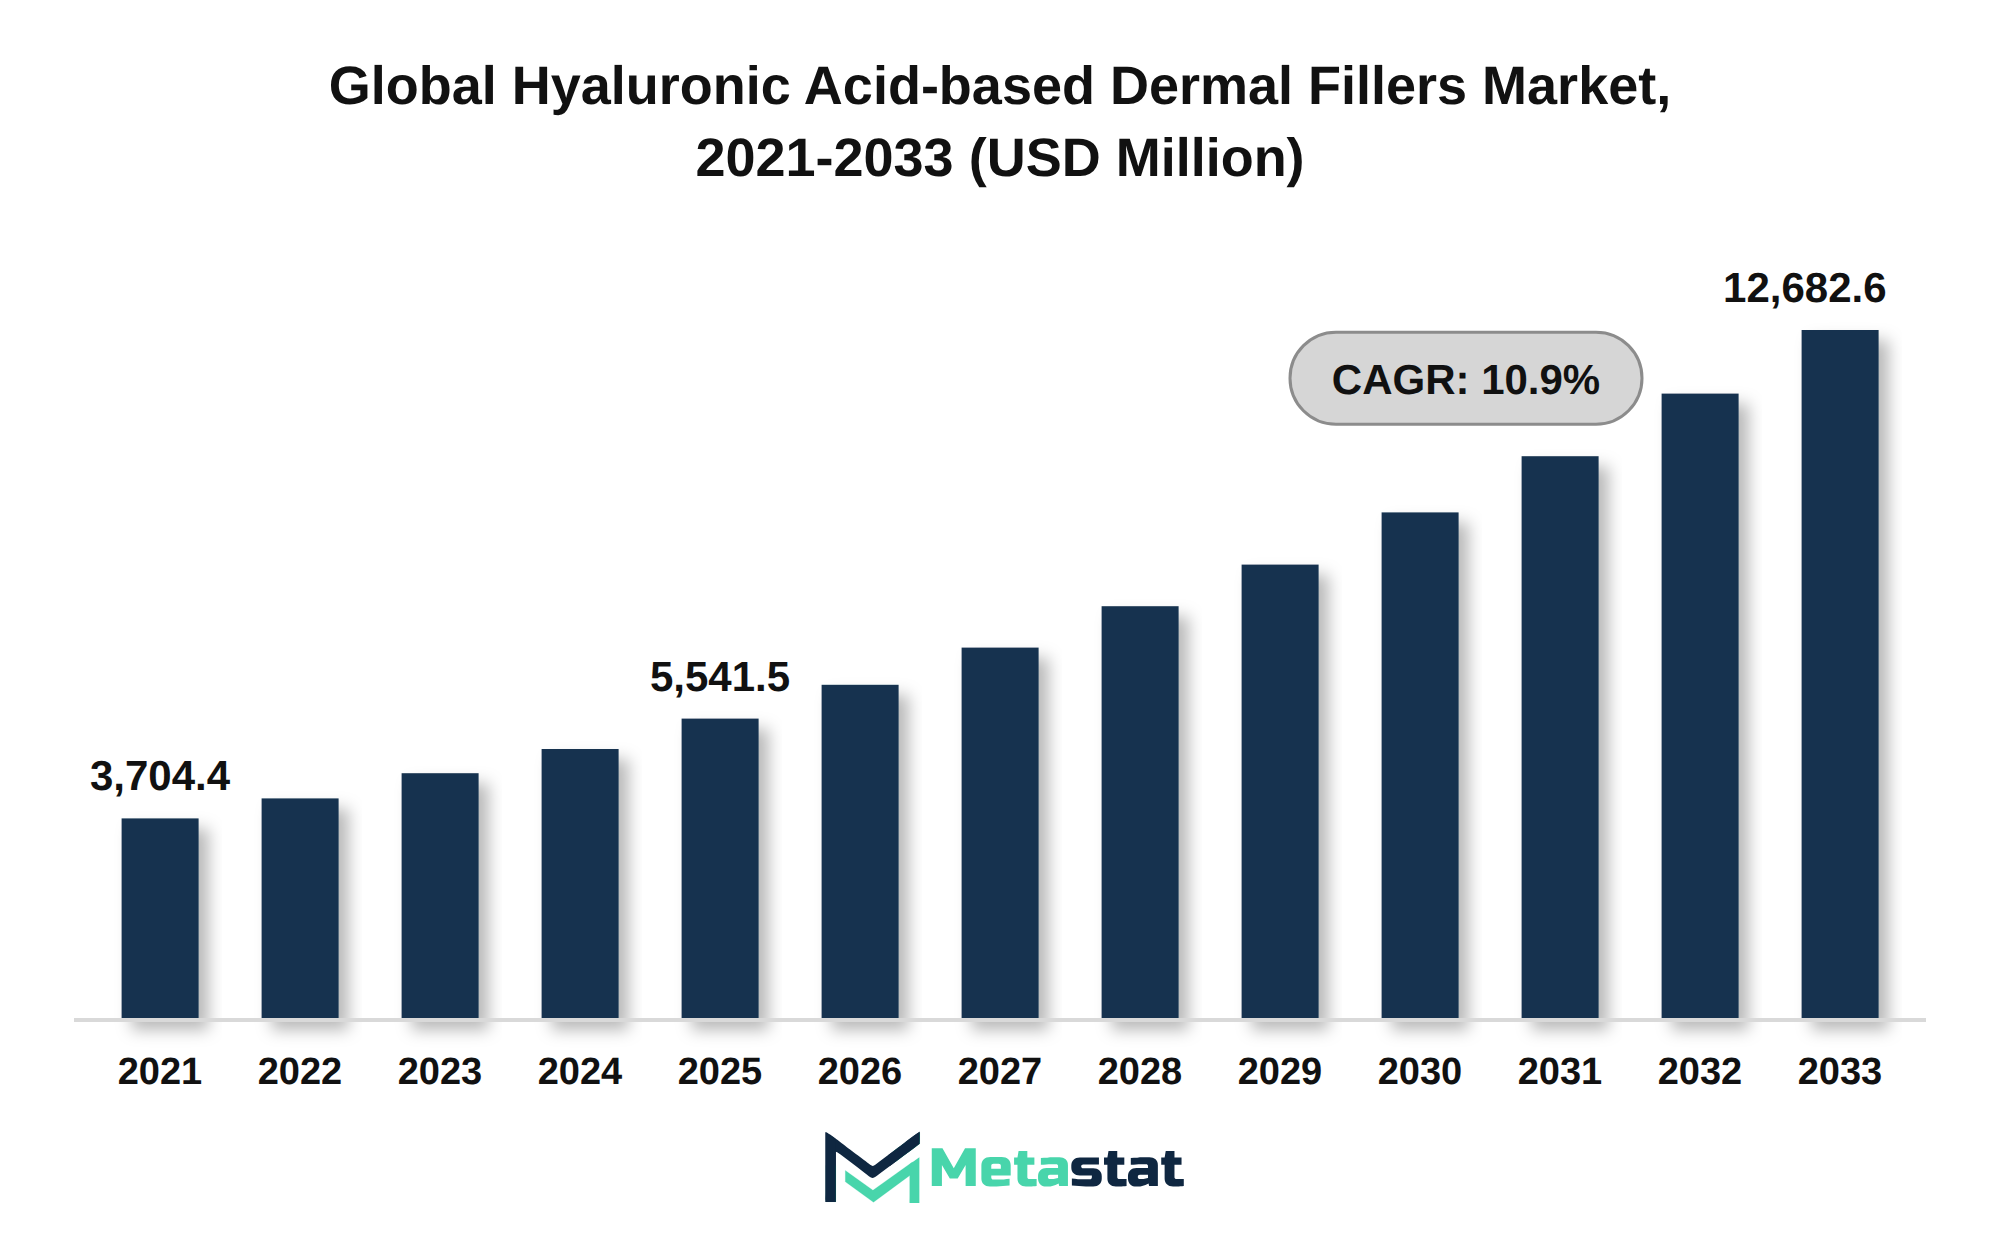
Demographic shifts, particularly aging populations, significantly influence the Hyaluronic Acid-based Dermal Fillers market. A growing number of consumers seeking non-invasive procedures to maintain youthfulness fuels market expansion. Increased awareness of aesthetic treatments, combined with a rise in disposable incomes, further encourages spending on dermal fillers. Urbanization and lifestyle changes contribute to heightened interest in personal appearance, leading to greater market penetration.
The demand for wrinkle and fold correction applications grows due to consumers prioritizing facial rejuvenation. This focus on aesthetics promotes market opportunities for various applications, including lip augmentation and midface volumization. The trend of self-care and wellness continues to gain traction, resulting in increased investment in cosmetic procedures. While consumers become more informed about the benefits of these treatments, the market experiences significant growth.
Growing emphasis on sustainability and resource stewardship significantly impacts the Hyaluronic Acid-based Dermal Fillers market. Increasing awareness around environmental responsibility drives organizations to adopt practices that minimize carbon footprints and support circular economy initiatives. This shift influences production methods, with firms exploring biodegradable materials and sustainable sourcing of raw components, thereby enhancing brand reputation and attracting environmentally-conscious consumers.
Investment in sustainable practices leads to improved operational efficiencies driven by firms streamlining processes and reducing waste. Companies focusing on eco-friendly solutions benefit from cost savings in the long term while positioning themselves favorably in a competitive landscape. Consequently, sustainability acts not only because a differentiator but because a driver of market expansion in the Hyaluronic Acid-based Dermal Fillers sector.
Consumer preferences increasingly favor products that align with environmental values, compelling manufacturers to innovate with green technologies. The integration of these principles into product offerings strengthens market growth by appealing to a broader demographic seeking aesthetic solutions that reflect their sustainability ethos. This alignment with consumer values supports the overall growth trajectory of the market.
Regulatory compliance presents significant hurdles for the Hyaluronic Acid-based Dermal Fillers market. Stricter guidelines surrounding the safety and efficacy of these products require extensive testing and documentation, which leads to increased timeframes for market entry. The burden of compliance impacts smaller manufacturers disproportionately, limiting their ability to compete effectively with larger firms that possess substantial resources.
Macroeconomic headwinds contribute to market challenges owing to rising inflationary pressures that increase production costs and reduce consumer spending power. These economic conditions create uncertainty among buyers, influencing their willingness to invest in aesthetic procedures involving dermal fillers. This restraint affects revenue growth potential for suppliers, because demand stagnates in a less favorable economic environment.
Supply chain disruptions exacerbate operational difficulties within the market. Delays in raw material availability create production setbacks, impacting product availability and extending lead times for clients. Such disruptions create barriers to meeting consumer demand consistently, which diminishes customer satisfaction and brand loyalty.
Geopolitical instability influences market dynamics through fluctuations in trade policies and tariffs. These variances add complexity to international supply chains, driving up costs and complicating logistics for companies operating across borders. Firms involved in the Hyaluronic Acid-based Dermal Fillers market navigate a landscape of uncertainty, which hinders strategic growth initiatives.
Finally, competition from alternative offerings introduces substitution risks that threaten market stability. The emergence of new aesthetic treatments diverts consumer interest away from traditional dermal fillers, placing additional pressure on market participants to innovate continuously. Maintaining relevance amid an evolving aesthetic environment remains crucial for sustaining growth in the Hyaluronic Acid-based Dermal Fillers market.
The Hyaluronic Acid-based Dermal Fillers market faces challenges stemming from geopolitical fragmentation and trade deficits. Such conditions limit access to vital raw materials, resulting in increased costs for suppliers. Tariff friction complicates international trade, impacting pricing strategies and profit margins. While firms encounter these challenges, the pressure on pricing and operational costs intensifies.
Technological disruptions further complicate market dynamics. Innovations require significant investment in research and development, leading to complex integration processes that strain resources. Limited compatibility among new technologies hinders efficiency, impacting production timelines and product availability. Consequently, firms experience heightened operational overhead, affecting overall market performance.
Logistics disruptions and supply chain instability emerge due to critical challenges, particularly in response to recent geopolitical events. Transportation delays and fluctuating shipping costs disrupt timely product delivery. Tightening global regulatory standards introduce additional compliance overhead. Organizations allocate resources to navigate these evolving legal liabilities, which detract from core business activities.
Rising input costs and workforce skill gaps present substantial obstacles. The market demands skilled professionals familiar with advanced technologies, yet firms struggle to attract and retain talent. Automation displacements contribute to workforce challenges, driven by transitions to more automated processes. This shift enhances the environmental lifecycle footprint, prompting calls for sustainable practices.
Changing downstream demands and market saturation introduce added pressure on the Hyaluronic Acid-based Dermal Fillers market. Substitution vectors, including alternative treatments, challenge product differentiation. Companies innovate continuously to maintain competitive advantage in an increasingly crowded marketplace. These factors create a complex environment for growth and stability.
Technological disruptions in the Hyaluronic Acid-based Dermal Fillers market significantly influence growth trajectories. Innovations in formulation and delivery methods enhance product efficacy, attracting a broader customer base. The integration of next-generation technologies, including biocompatible materials and advanced injection techniques, enhances patient outcomes, positively impacting demand.
Digital transformation reshapes consumer engagement and purchasing behaviors in the market. Increased online channels and digital procurement strategies facilitate easier access to products, promoting market penetration. Enhanced customer experiences through personalized offerings and virtual consultations drive demand for aesthetic enhancements, particularly among younger demographics.
Infrastructure modernization significantly contributes to expanding the market. Investments in state-of-the-art medical facilities and aesthetic clinics improve service delivery. These advancements enable practitioners to adopt new technologies, ensuring competitive advantages through superior treatment options.
Geographical expansion into emerging markets represents a significant opportunity for stakeholders within the Hyaluronic Acid-based Dermal Fillers market. Regions including Asia Pacific exhibit increasing disposable incomes and evolving beauty standards, leading to heightened demand for aesthetic procedures. This trend invites investment and strategic partnerships aimed at capturing market share in these developing economies.
The convergence of various industries through strategic consolidations and cross-industry mergers presents a unique opportunity for growth. Collaborations between biotech firms and aesthetic practitioners encourage the development of innovative products and services, allowing companies to diversify their portfolios. This trend fosters a more resilient market structure capable of adapting to shifting consumer preferences.
The Hyaluronic Acid-based Dermal Fillers market benefits from a confluence of technological advancements, digital transformation, infrastructure modernization, and geographical expansion. These factors collectively enhance adoption rates and drive revenue growth, positioning the market for sustained development in the coming years.
The Global Hyaluronic Acid-based Dermal Fillers market is segmented based on Gel Structure, Product Phase, Application, and End User.
Monophasic HA Fillers segment is valued at USD 4,219.1 million in 2026 and is projected to reach USD 9,113.8 million by 2033, at a CAGR of 11.6% during the forecast period. Demand for Monophasic HA Fillers primarily arises from their effectiveness in wrinkle and fold correction, leading to increased adoption in both aesthetic and medical applications. The segment benefits from advancements in formulation technologies, enhancing the product's features, safety, and efficacy. These improvements build consumer trust and encourage healthcare providers to recommend these fillers more frequently.
Key factors driving expansion within the Monophasic HA Fillers segment include increasing acceptance of cosmetic procedures coupled with rising disposable incomes. Patients increasingly seek non-surgical options for facial rejuvenation, contributing to the segment's growth. Educational initiatives and marketing efforts by manufacturers strengthen consumer awareness and confidence in the effectiveness of these fillers. The presence of established brands enhances competition while encouraging innovation in product formulation and delivery methods.
Regulatory compliance shapes the market landscape, ensuring safety and efficacy standards for Monophasic HA Fillers. Manufacturers invest in research and development to align with these standards while exploring next-generation upgrades and formulations. This approach aligns with evolving consumer preferences for long-lasting results and minimal downtime, significantly influencing end-user dynamics in dermatology and cosmetic surgery clinics.
Cost structures within the Monophasic HA Fillers segment reflect both raw material sourcing and production methodologies. Fluctuations in pricing for key ingredients affect profit margins, compelling companies to streamline operations and optimize supply chains. Strategic partnerships and investments in emerging markets facilitate growth opportunities, allowing companies to tap into new customer bases and expand their geographical reach. Overall, the Monophasic HA Fillers segment remains a dynamic component of the Hyaluronic Acid-based Dermal Fillers market, positioned for continued growth through the forecast period.
Biphasic HA Fillers segment is estimated to reach USD 3,568.9 million by 2033, at a CAGR of 9.1% during the forecast period. The growing demand for these fillers stems from their dual-phase structure, which offers enhanced stability and longer-lasting results compared to other filler types. Features including ease of integration into various applications drive adoption across dermatology, plastic surgery, and aesthetic practices, positioning this segment favorably within the broader Hyaluronic Acid-based Dermal Fillers market.
Technological maturation influences the development of Biphasic HA Fillers, with advancements leading to improved formulation and safety profiles. This progression facilitates the introduction of innovative products that address diverse consumer needs, including lip augmentation and wrinkle correction. The market benefits from strategic partnerships between manufacturers and healthcare providers, enhancing distribution channels and expanding access to these products.
Consumer preferences increasingly shift towards minimally invasive procedures, further supporting the growth of the Biphasic HA Fillers segment. With rising awareness of aesthetic treatments, more patients seek options that deliver immediate and enduring results. This trend emphasizes the importance of product evolution, where new formulations that enhance efficacy and safety are in high demand, influencing purchasing decisions.
Regulatory compliance continues to shape the landscape of the Hyaluronic Acid-based Dermal Fillers market, ensuring that products meet stringent safety and quality standards. Manufacturers actively pursue certifications that validate product quality, further enhancing consumer confidence in Biphasic HA Fillers. Such compliance helps mitigate risks associated with adverse reactions, essential for maintaining market integrity and ensuring long-term growth.
Overall, the Biphasic HA Fillers segment is well-positioned for expansion, driven by robust demand, technological advancements, and a dynamic regulatory environment. This segment's resilience is notable, attributed to its adaptation to evolving consumer preferences and market trends, ensuring sustained interest and investment in innovative solutions.
Valued at USD 4,183.6 million in 2026, the Single-Phase segment is projected to reach USD 9,035.1 million by 2033, at a CAGR of 11.6% during the forecast period. Market expansion reflects strong demand from cosmetic procedures focused on enhancing facial aesthetics. Increasing consumer awareness regarding the benefits of these fillers drives adoption across various demographics, particularly among middle-aged individuals seeking anti-aging solutions.
Technological advancements play a crucial role in product evolution within the Single-Phase segment. Innovations in formulation and delivery systems enhance the efficacy and safety profiles of these products, contributing to higher consumer satisfaction. The rising trend of minimally invasive procedures supports segment growth, because patients prefer options with reduced recovery times and lower risks associated with surgical interventions.
End-user dynamics, particularly from dermatology and cosmetic surgery clinics, significantly influence market trends. These facilities report increasing client inquiries for Single-Phase fillers, reflecting a shift towards personalized aesthetic treatments. Regulatory compliance and certification standards drive quality assurance, building consumer trust and boosting market penetration. This segment is poised for significant growth, backed by ongoing investment and strategic initiatives across the industry.
Robust demand for advanced cosmetic solutions drives the Duplex segment within the Hyaluronic Acid-based Dermal Fillers market. Growth in this sub-segment stems from an increasing preference for minimally invasive procedures that yield natural-looking results. A rising trend in aesthetic treatments generates consumer interest, particularly in facial volumization and contouring. This segment is expected to benefit from technological advancements, enhancing product effectiveness and safety while appealing to a broader demographic.
Market estimates indicate that the Duplex segment is estimated to reach USD 3,647.5 million by 2033, at a CAGR of 9.1% during the forecast period. Escalating adoption among dermatology and cosmetic surgery clinics contributes significantly to this growth trajectory. Evolving patient preferences for personalized treatment options further strengthens the potential for expansion within the market. The combination of these factors positions the Duplex segment because a vital component of the overall market.
Valued at USD 1,732.7 million in 2026, the Wrinkle & Fold Correction segment is projected to reach USD 3,286.1 million by 2033, reflecting a CAGR of 9.6% during the forecast period. This growth stems from a growing demand for non-invasive cosmetic procedures, driven by an increasing focus on aesthetic appearance and the desire for youthful skin. The aging population plays a critical role in expanding the customer base, because older individuals seek effective solutions for wrinkle reduction and skin rejuvenation.
Innovations in product formulations and techniques enhance the efficacy and safety of Hyaluronic Acid-based dermal fillers, encouraging greater adoption within the market. The introduction of next-generation upgrades, including improved injection methods and customizable treatment options, caters to individual patient needs, promoting higher satisfaction rates. This segment benefits from advanced technologies that streamline application processes, further boosting its appeal among practitioners and patients.
Consumption shifts reflect a preference for minimally invasive treatments over surgical options. This trend encourages patients to explore effective solutions for wrinkle and fold correction, contributing to the segment's growth. Regulatory compliance within the market ensures product safety and effectiveness, encouraging consumer trust. This trust translates into increased market demand, because patients feel more confident in the treatments available to them.
With increasing competition among key industry players, pricing strategies evolve to enhance market access while maintaining quality. The segment's growth potential attracts significant capital investment, enabling further research and development initiatives. This investment drives innovation and positions the Wrinkle & Fold Correction segment to capitalize on emerging trends within the expanding Hyaluronic Acid-based Dermal Fillers market.
Increasing aesthetic consciousness among consumers drives demand for the Lip Augmentation & Contouring segment within the Hyaluronic Acid-based Dermal Fillers market. The rising popularity of cosmetic procedures aimed at enhancing lip volume and shape fuels market expansion. Advanced formulations and innovative techniques contribute to the appeal of these products, attracting a diverse clientele. Enhanced safety profiles and longer-lasting results from modern fillers encourage more individuals to seek these treatments. The segment is projected to reach USD 2,610.1 million by 2033, growing at a CAGR of 11.6% during the forecast period. The growing influence of social media plays a significant role in shaping beauty standards, propelling demand.
Increasing interest in facial aesthetics drives demand for Cheek & Midface Volumization in the Hyaluronic Acid-based Dermal Fillers market. This segment benefits from rising consumer awareness about facial rejuvenation and the desire for enhanced features. Practitioners adopt advanced volumization techniques to meet client expectations.
The Cheek & Midface Volumization segment is projected to reach USD 2,364 million by 2033. This growth reflects the segment's appeal, supported by advancements in product formulations and application methods. The evolution of safe and effective dermal fillers enhances the capacity of medical professionals to deliver desirable results, thereby attracting a broader clientele.
Changing consumer preferences toward non-surgical procedures significantly influence the market. Clients increasingly prefer minimally invasive treatments that offer immediate results with minimal downtime. This shift in consumer behavior aligns with the ongoing development of innovative hyaluronic acid formulations designed for facial volumization.
End-user dynamics play a crucial role in shaping demand within the segment. Dermatology clinics and plastic surgery centers are key players, employing advanced techniques to optimize patient outcomes. The competitive landscape encourages ongoing investment in training and technology, allowing clinics to enhance their service offerings and attract new customers.
In light of these factors, the outlook for the Cheek & Midface Volumization segment remains positive. The segment's growth potential aligns with the broader expansion of the Hyaluronic Acid-based Dermal Fillers market, creating opportunities for established and emerging players alike. Continuous innovation and strategic marketing will be essential to leverage this demand effectively.
Increasing consumer interest in aesthetic procedures significantly influences the demand for chin and jawline contouring. The market experiences heightened adoption driven by trends in facial aesthetics, with individuals seeking defined jawlines and enhanced facial profiles. This demand is closely tied to social media and celebrity influence, where prominent jawlines signify attractiveness and youthfulness.
The Chin & Jawline Contouring segment is projected to grow at a CAGR of 11.5% during the forecast period. Expansion is supported by advancements in injection techniques and product formulations, which enhance safety and efficacy. Dermatology and cosmetic surgery clinics serve because primary end-users, leveraging these fillers to meet customer expectations for aesthetic enhancement.
Increased awareness regarding minimally invasive procedures contributes to market growth. The rise in non-surgical options aligns with consumer preferences for less invasive interventions, reducing recovery time while achieving desired aesthetic results. Consequently, the market experiences a shift toward products specifically designed for chin and jawline applications, enhancing revenue opportunities in this segment.
Increasing awareness of aesthetic treatments drives demand for Periorbital Hollows & Tear Trough Correction within the Hyaluronic Acid-based Dermal Fillers market. Consumers increasingly seek solutions to address under-eye hollows, contributing to the segment's popularity. Aesthetic enhancement trends support growth, with patients prioritizing facial rejuvenation processes that include tear trough correction.
Technological advancements in formulation and application methods facilitate the adoption of these fillers. Innovations target safety and efficacy, enhancing patient satisfaction. The segment benefits from the rising number of dermatology clinics and cosmetic surgery practices offering specialized treatments, creating more options for consumers.
Regulatory compliance standards influence product development and market entry strategies, with companies focusing on meeting safety and quality requirements. Intensifying competition drives brands to invest in marketing, informing potential users about the benefits of treatments targeting periorbital areas.
Shifts in consumer preferences toward less invasive procedures encourage investment in this segment. The growing trend for non-surgical aesthetic solutions attracts a diverse demographic, expanding the consumer base and driving market growth.
Consumer interest in aesthetic procedures significantly enhances the demand for non-surgical rhinoplasty within the Hyaluronic Acid-based Dermal Fillers market. This sub-segment benefits from an increasing preference for minimally invasive treatments that offer immediate results with reduced recovery time, appealing to a broad demographic seeking facial enhancements. The growing acceptance of cosmetic procedures among diverse age groups contributes to its expansion, with younger consumers seeking subtle enhancements and older individuals aiming for rejuvenation.
Technological advancements play a vital role in shaping this segment. Innovations in filler formulations improve safety and effectiveness, leading to greater patient satisfaction and repeat procedures. The availability of next-generation fillers with advanced properties, including smoother injection and longer-lasting results, attracts practitioners and patients alike.
Market dynamics indicate a shift toward personalized treatment plans, allowing professionals to cater to individual aesthetic goals. This trend drives product evolution and enhances the overall consumer experience. The market exhibits resilience against economic fluctuations, supported by the aesthetic industry's growth and the increasing willingness of individuals to invest in their appearance.
Regulatory compliance continues to influence the landscape, with growing emphasis on safety standards and product efficacy. Meeting these standards ensures consumer confidence and builds brand loyalty among practitioners. While the market matures, strategic opportunity windows emerge for companies to introduce innovative products and expand their market presence.
Growing awareness of hand rejuvenation procedures influences the demand for Hyaluronic Acid-based Dermal Fillers. Patients increasingly seek non-invasive solutions to address signs of aging, including volume loss and skin laxity in the hands. Aesthetic providers report a rise in requests for treatments that enhance hand appearance, supporting the segment's growth.
Advancements in formulation and application techniques contribute to the segment's expansion. Enhanced product safety, effectiveness, and comfort drive adoption among consumers and practitioners. The presence of various aesthetic clinics and skilled professionals facilitates access to treatments, further boosting market penetration.
Consumer preferences shift toward minimally invasive procedures with immediate results, positioning Hyaluronic Acid-based Dermal Fillers favorably within the market. Treatments that offer quick recovery times and long-lasting effects appeal to a broad demographic, including younger individuals and older patients seeking to rejuvenate their hands.
Regulatory frameworks surrounding cosmetic procedures shape market dynamics. Compliance with safety standards ensures product integrity and builds consumer trust in treatment options. Consequently, aesthetic practitioners benefit from a well-regulated environment, enhancing service offerings and driving market growth.
Strategic partnerships among manufacturers and clinics play a crucial role in expanding the application of Hyaluronic Acid-based Dermal Fillers for hand rejuvenation. Collaborations lead to innovative treatment protocols and improved patient education, enhancing overall satisfaction and treatment outcomes.
Investment in marketing strategies targeting potential consumers reinforces the segment's growth trajectory. Educational campaigns highlighting the benefits and safety of hand rejuvenation procedures contribute to increasing demand, positioning the Hyaluronic Acid-based Dermal Fillers market for sustained expansion in the coming years.
Consumer preference for non-surgical body enhancement procedures significantly increases demand for body contouring and volumization treatments within the Hyaluronic Acid-based Dermal Fillers market. This segment benefits from the growing inclination toward minimally invasive aesthetic solutions that provide instant results with reduced recovery times compared to surgical alternatives.
Innovative formulations and delivery methods continuously improve the efficacy of body contouring procedures, driving market evolution. Manufacturers focus on developing next-generation products that offer improved longevity, safety, and natural aesthetics, catering to rising consumer expectations for effective solutions in body shaping.
Adoption of these dermal fillers spans various demographics, appealing to a diverse clientele that values body image and appearance. The segment observes higher uptake among younger individuals seeking preventative treatments alongside older consumers looking for rejuvenation, thereby supporting substantial growth in the market.
Regulatory standards surrounding the quality and safety of dermal fillers influence market dynamics. Compliance with stringent regulations ensures consumer confidence, while ongoing certifications and safety assessments contribute to market legitimacy. These factors play a critical role in shaping body contouring and volumization procedures.
Strategic investment within this segment reflects a broader trend of aesthetic practices incorporating advanced technologies. Investments in research and development facilitate the introduction of enhanced formulations and techniques that align with evolving consumer expectations while providing lucrative growth opportunities in the market.
Emerging applications for scar correction and earlobe augmentation significantly influence demand within the Hyaluronic Acid-based Dermal Fillers market. Rising consumer awareness regarding non-surgical options for scar treatments drives adoption across diverse demographics seeking cosmetic solutions. Increased interest in enhancing earlobes, particularly due to the popularity of body modification trends, further supports market growth.
Technological advancements in filler formulations enhance treatment outcomes while minimizing side effects, contributing to the overall acceptance of these procedures. Consumers prioritize safety and efficacy, prompting manufacturers to innovate and comply with evolving regulatory standards. This dynamic creates a competitive environment that encourages providers to offer enhanced services and products tailored to specific consumer needs.
Shifts in consumption patterns reflect a growing acceptance of aesthetic procedures, promoting broader market penetration. Educational initiatives from clinics and practitioners on the benefits of these treatments play a crucial role in shaping consumer perceptions. Investment in training and certification programs ensures that practitioners remain informed about best practices, ultimately benefiting patients seeking these specialized services.
Cost structures and pricing dynamics within this sub-segment influence accessibility and consumer choices. Providers face pressures related to sourcing high-quality raw materials while maintaining competitive pricing strategies. Sustained demand for these procedures creates strategic opportunities for companies to capture market share through targeted marketing and innovative product offerings.
Valued at USD 2,443.8 million in 2026, the Dermatology Clinics segment is projected to reach USD 5,175.8 million by 2033, at a CAGR of 11.3% during the forecast period. Rising consumer awareness regarding skin health and aesthetic enhancements drives significant demand for Hyaluronic Acid-based Dermal Fillers in dermatology clinics. This segment benefits from the increasing prevalence of aesthetic procedures that focus on skin rejuvenation, wrinkle reduction, and overall cosmetic improvements, establishing a strong foundation for growth in the market.
The evolving landscape of dermatological practices, coupled with advancements in filler technology, enhances the attractiveness of procedures performed in these clinics. Innovations in formulations and application techniques allow for improved results, thereby increasing patient satisfaction and encouraging repeat visits. These factors contribute to a favorable environment for the Dermatology Clinics segment, resulting in sustained revenue growth and heightened competition among service providers.
The rising trend of non-invasive aesthetic treatments, driven by younger demographics seeking preventative skincare solutions, further supports the market's expansion. Dermatology clinics play a crucial role in meeting this demand, facilitating access to high-quality, safe treatments. Regulatory compliance and adherence to certifications ensure that these clinics maintain high standards of care, enhancing consumer trust and contributing to positive market dynamics.
While the Hyaluronic Acid-based Dermal Fillers market progresses, strategic opportunities arise for clinics to diversify their service offerings and incorporate advanced technologies. This adaptability positions dermatology clinics favorably, allowing them to capture a larger share of the growing market while addressing the evolving preferences of their clientele.
Valued at USD 3,820 million by 2033, the Plastic & Cosmetic Surgery Clinics segment experiences a CAGR of 10.2% during the forecast period. Increasing consumer interest in aesthetic enhancements drives significant demand for Hyaluronic Acid-based Dermal Fillers in this segment. The adoption of advanced techniques and innovative products enhances the treatment options available, supporting market growth. More consumers seeking non-invasive solutions prompt clinics to expand their service offerings, boosting revenue opportunities. Competitive pricing and the introduction of next-generation products encourage clinics to incorporate these fillers into their procedures. This segment's growth reflects broader trends in aesthetic medicine, emphasizing safety, effectiveness, and patient satisfaction, which influences market dynamics.
Demand for aesthetic procedures in hospitals and ambulatory surgical centers continues to rise, driven by an increasing emphasis on minimally invasive treatment options among consumers. Advancements in technology and product formulation enhance the effectiveness and safety of Hyaluronic Acid-based Dermal Fillers, broadening their appeal within the medical community. These developments attract a wider patient base seeking cosmetic enhancements, thus improving revenue streams for healthcare facilities involved in aesthetic treatments.
Valued at USD 1,768 million by 2033, this segment benefits from the growing acceptance of aesthetic procedures, which align with consumer preferences for non-surgical enhancements. The competitive landscape within this segment experiences consistent pressure to innovate, compelling manufacturers to invest in next-generation solutions. Regulatory compliance standards ensure safety and efficacy, building trust and encouraging further adoption within hospitals and ambulatory surgical centers. Overall, the Hyaluronic Acid-based Dermal Fillers market reflects a robust trajectory, driven by evolving consumer expectations and technological advancements.
Demand for aesthetic procedures continues to increase the significance of the Dental Aesthetic Practices segment within the Hyaluronic Acid-based Dermal Fillers market. Projected growth at a CAGR of 13% during the forecast period reflects robust adoption of dermal filler treatments among dental practitioners, driven by an increasing number of patients seeking cosmetic enhancements. The integration of innovative technologies and advanced formulations in this segment contributes to enhanced treatment outcomes, improving consumer confidence and satisfaction.
Shifts in consumer preferences toward minimally invasive procedures create substantial opportunities for dental aesthetic practices to expand their service offerings. The emphasis on facial aesthetics and rejuvenation procedures promotes higher demand for lip augmentation, wrinkle correction, and other cosmetic enhancements. Increased patient footfall and repeat treatments drive revenue growth for practitioners.
Regulatory compliance standards and certifications play a crucial role in shaping market dynamics, ensuring product safety and efficacy. Dental aesthetic practices adopting high-quality, approved dermal fillers position themselves competitively within the market, building trust with patients and enhancing their brand reputation. Strategic investments in training and technology further enable practitioners to stay ahead in a changing environment.
Valued at USD 2,443.8 million in 2026, the segment's revenue is expected to reach USD 5,175.8 million by 2033. This upward trajectory illustrates a strong market outlook driven by consumer demand for aesthetic treatments and the continuous evolution of product offerings tailored to meet diverse patient needs.
Demand for aesthetic treatments within multispecialty and independent medical practices presents unique dynamics in the Hyaluronic Acid-based Dermal Fillers market. These practices cater to diverse patient needs, driving interest in customized treatments beyond traditional offerings. Enhanced patient engagement, coupled with the rise of social media highlighting aesthetic results, increases foot traffic in these practices.
Technological advancements significantly influence adoption rates. Innovations in filler formulations and application techniques enhance safety and efficacy, encouraging practitioners to incorporate these products. Continuous education and training in the latest techniques further support growth in this segment, ensuring practitioners remain competitive. This ongoing development is essential for maintaining high standards.
Regulatory compliance standards play a crucial role in shaping market dynamics. Adherence to safety and quality regulations builds consumer trust, directly impacting demand for treatments offered in multispecialty and independent medical practices. The necessity for certifications influences how these practices operate and market their services, ensuring alignment with industry standards.
Pricing volatility poses challenges that these practices navigate effectively. Fluctuations in raw material costs affect pricing strategies, prompting practices to adapt their service offerings. Careful management of cost structures ensures profitability while maintaining competitive pricing. This adaptability enables practices to thrive in a dynamic environment.
Strategic opportunities arise from the growing trend of aesthetic services among diverse demographics. Targeted marketing efforts and community engagement help practices expand their reach, attracting new clientele seeking personalized treatment plans. Such initiatives enhance revenue potential, contributing to overall growth in the Hyaluronic Acid-based Dermal Fillers market.
Based on geography, the Global Hyaluronic Acid-based Dermal Fillers market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
With a significant market share of 42.1% in 2025, the Hyaluronic Acid-based Dermal Fillers market in North America demonstrates strong growth potential. The region is set to expand at a CAGR of 10.9% during the forecast period, reaching a market size (TAM) of USD 5,052.8 million by the end of 2033. This growth results from increasing consumer demand for aesthetic procedures driven by evolving beauty standards and an aging population.
The United States, Canada, and Mexico constitute the primary markets within North America. Regulatory frameworks in these countries support market growth by streamlining approval processes for new products, thereby encouraging innovation and facilitating entry for emerging players. Enhanced awareness of the benefits of hyaluronic acid-based treatments and the rising popularity of non-surgical procedures contribute to increasing adoption rates.
Market dynamics reveal a competitive landscape, featuring several established players committed to expanding their product offerings. Localized procurement dynamics influence purchasing decisions, with a preference for suppliers that provide high-quality products with proven efficacy. The presence of advanced healthcare infrastructure in the region facilitates the distribution and administration of these aesthetic treatments, further boosting market growth.
Emerging trends focus on cross-border trade corridors and supply chain regionalization, which optimize access to raw materials and streamline distribution channels. This shift toward localized manufacturing enhances operational efficiency while reducing dependency on external sources. Consequently, the market positions itself for sustained growth driven by strategic investments and innovative product development.
The Hyaluronic Acid-based Dermal Fillers market in Europe accounts for 26.0% of the global share in 2025, driven by strong consumer interest in aesthetic treatments. Countries including Germany, France, the UK, Italy, Spain, and Russia exhibit significant adoption rates, fueled by increasing disposable income and evolving beauty standards. The presence of well-established dermatology and cosmetic surgery clinics enhances the competitive landscape, improving access to advanced filler technologies.
Market growth is supported by the rising popularity of non-surgical procedures, particularly in urban areas where aesthetic awareness is high. The demand for wrinkle correction and lip augmentation treatments is expected to expand, influenced by cultural factors that prioritize youthful appearances. Localized manufacturing densities and supply chain regionalization contribute to the operational efficiency of market players, allowing for responsive product distribution and innovation.
High-value replacement cycles for existing dermal filler products create incremental growth vectors, with patients often seeking touch-ups and maintenance treatments. Strategic entry barriers in the form of regulatory compliance and local mandates further shape the competitive dynamics, because market participants navigate varied regional policies. Overall, the Hyaluronic Acid-based Dermal Fillers market in Europe demonstrates robust development potential, driven by evolving consumer preferences and a supportive business environment.
The Hyaluronic Acid-based Dermal Fillers market in the Asia-Pacific region demonstrates significant growth potential. Countries including China, Japan, India, and South Korea drive this expansion, benefiting from rising disposable incomes and increased consumer awareness regarding aesthetic procedures.
Infrastructure modernization plays a critical role in enhancing access to aesthetic treatments across the region. Urbanization and improved healthcare facilities in major cities, coupled with a growing number of dermatology clinics and cosmetic surgery centers, facilitate higher adoption rates of these products. This trend is supported by cultural acceptance of cosmetic enhancements, particularly in urban areas.
Emerging market front-runners like China and India exhibit rapid advancements in technological capabilities and localized manufacturing densities. These developments enable the production of high-quality Hyaluronic Acid-based Dermal Fillers, catering to increasing consumer demand while reducing logistical challenges and associated costs.
The market experiences incremental growth vectors driven by high-value replacement cycles of existing products. Increasingly sophisticated formulations and product innovations attract consumers seeking enhanced outcomes, further propelling market dynamics. Awareness campaigns and consumer education regarding the benefits of these fillers contribute to market expansion.
Regional competitive landscapes highlight the presence of various domestic market participants, with several players focusing on vendor consolidation trends to strengthen their market position. Strategic entry barriers, including regulatory compliance and local procurement dynamics, influence market accessibility while creating opportunities for firms willing to adapt to regional requirements.
The Asia-Pacific region exhibits significant growth in the Hyaluronic Acid-based Dermal Fillers market, driven by urbanization, technological advancements, and evolving consumer preferences. Strategic investments and localized manufacturing initiatives position this region favorably for sustained market expansion.
The Hyaluronic Acid-based Dermal Fillers market in South America demonstrates significant potential for growth, driven by increasing consumer interest in aesthetic treatments, particularly in Brazil and Argentina. The region's share of the global market highlights opportunities for market expansion. Local clinics and aesthetic practices increasingly adopt these products, reflecting a shift in consumer attitudes towards non-invasive procedures.
Infrastructure modernization in South America contributes to market growth, with enhanced accessibility to aesthetic services. The rising number of dermatology clinics and plastic surgery centers facilitates increased usage of hyaluronic acid-based fillers, catering to a growing demand for facial rejuvenation and contouring. Cultural nuances in beauty standards motivate consumers to pursue these enhancements, creating a favorable environment for market development.
Despite existing competition, the market remains underpenetrated compared to other regions, presenting incremental growth vectors. Emerging players are set to capitalize on unmet demand, while established domestic companies continue to expand their offerings. Localized procurement dynamics and strategic vendor consolidation trends support the overall market landscape, reinforcing the significance of the Hyaluronic Acid-based Dermal Fillers market in the region.
The Hyaluronic Acid-based Dermal Fillers market in the Middle East and Africa faces unique challenges and opportunities. Growth in this region stems from increasing aesthetic awareness and rising disposable income among consumers. Countries like Saudi Arabia and the UAE experience significant demand, driven by a growing interest in non-surgical cosmetic procedures.
Infrastructure modernization supports market growth, enhancing the availability of aesthetic services in urban areas. Local compliance mandates and regulatory frameworks shape market dynamics, requiring companies to align with regional standards. Cultural nuances in beauty perceptions contribute to the adoption of Hyaluronic Acid-based Dermal Fillers, tailoring offerings to meet diverse consumer preferences.
In South Africa and the Rest of Middle East and Africa, the market remains underpenetrated. Increased investments in healthcare infrastructure and aesthetic services present significant growth vectors, leveraging foreign direct investment and local procurement strategies. Consolidation among local market players strengthens their positions, ensuring competitive advantages in the evolving market.
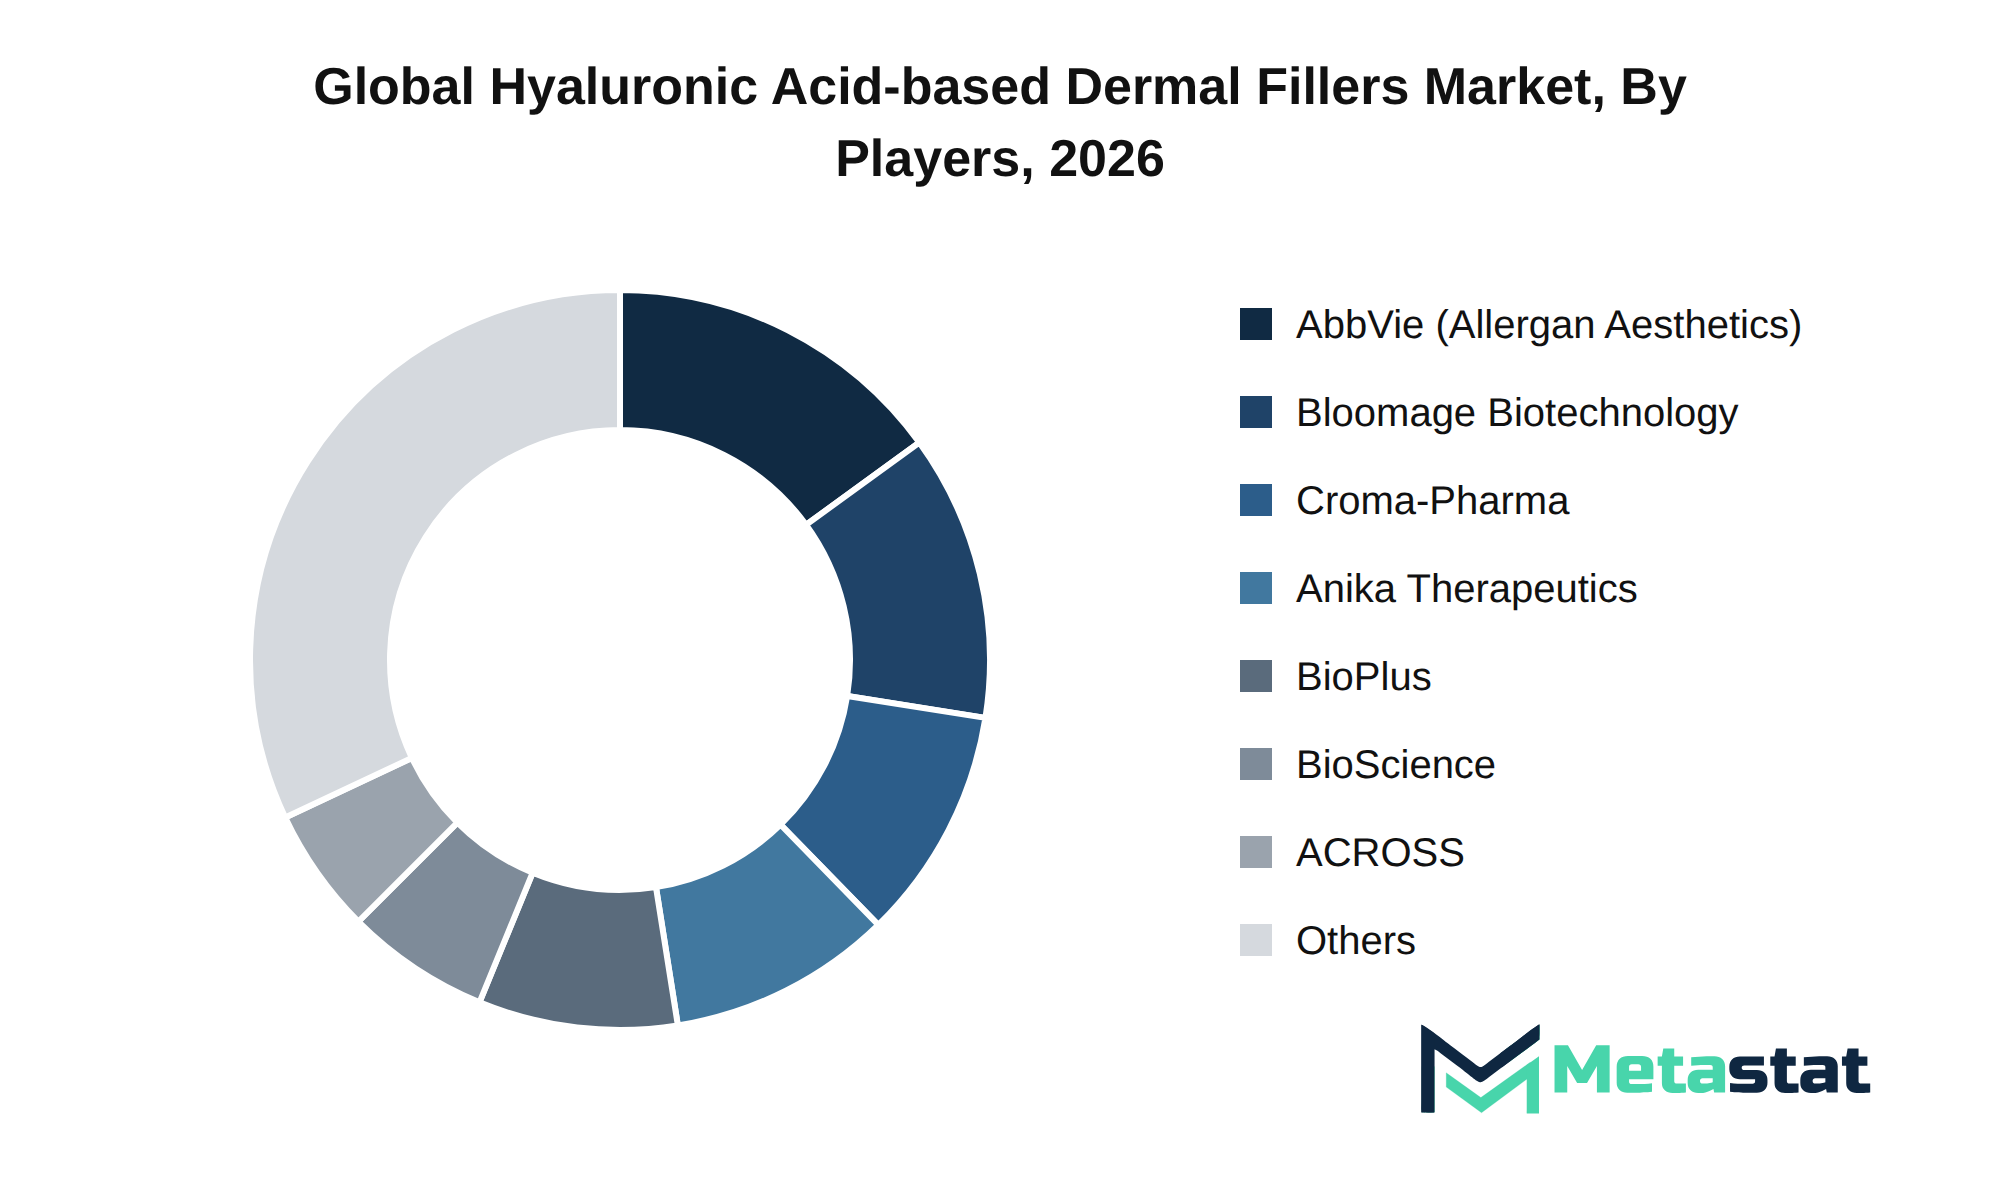
The Hyaluronic Acid-based Dermal Fillers market features a diverse group of players focusing on strategic consolidation and innovative product differentiation. Companies including AbbVie Inc. (Allergan Aesthetics), Galderma S.A., and Merz Aesthetics prioritize research and development to enhance their product offerings and maintain competitive advantage. Investments in proprietary technology and robust intellectual property portfolios strengthen their market positions, allowing for differentiation in an increasingly crowded field.
Strategic alliances and joint ventures have emerged because key tactics for growth in the market. Partnerships among players including BioPlus Co., Ltd. and Aimeik Technology Development Co., Ltd. facilitate the sharing of resources and expertise, enhancing their collective capabilities in production and marketing. These collaborations contribute to a more integrated value chain, improving procurement leverage and operational efficiency.
The threat of new entrants remains notable, driven by startup disruption dynamics that introduce innovative solutions and competitive pricing strategies. Established players maintain customer retention strategies, leveraging brand equity and switching costs to secure their positions in the market. Ongoing monitoring of these dynamics proves essential for companies aiming to navigate the evolving landscape of the Hyaluronic Acid-based Dermal Fillers market.
Market size is forecast to rise from USD 5,541.5 million in 2025 to over USD 12,682.6 million by 2033. This growth trajectory reflects a compound annual growth rate (CAGR) of 10.9%. Factors influencing this expansion include macroeconomic stability and increasing consumer awareness around aesthetic procedures, driving demand for Hyaluronic Acid-based Dermal Fillers.
The bull case scenario suggests robust market dynamics, propelled by technological advancements and regulatory support that promote innovation in product formulations. In contrast, the bear case highlights potential challenges, including economic downturns and shifts in consumer spending patterns, which could impact demand for aesthetic treatments. Such variability highlights the need for strategic capital allocation and adaptability among stakeholders in the market.
Shifting consumer preferences towards non-surgical aesthetic solutions and an aging population contribute to structural consumption shifts. Integration of next-generation technologies in product development enhances efficacy and safety profiles, positioning key players advantageously. Regulatory evolution and compliance milestones shape the competitive landscape, necessitating proactive strategies to align with evolving policy frameworks.
The Hyaluronic Acid-based Dermal Fillers market is poised for significant growth, supported by a combination of favorable demographic trends, technological innovation, and strategic investments in R&D. Stakeholders should remain vigilant to emerging opportunities and adaptable to changing market conditions.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Hyaluronic Acid-based Dermal Fillers market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 10.9% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Gel Structure, Product Phase, Application, End User, and Region |
By Region | North America (By Gel Structure, Product Phase, Application, End User, and Country)
|
Europe (By Gel Structure, Product Phase, Application, End User, and Country)
| |
Asia Pacific (By Gel Structure, Product Phase, Application, End User, and Country)
| |
South America (By Gel Structure, Product Phase, Application, End User, and Country)
| |
Middle East and Africa (By Gel Structure, Product Phase, Application, End User, and Country)
|
Find answers to common questions about this report
The Hyaluronic Acid-based Dermal Fillers market size was valued at USD 5,541.5 million in 2025, according to the Metastat Insights study.
The Hyaluronic Acid-based Dermal Fillers market is projected to grow at a CAGR of 10.9% during the forecast period from 2026 to 2033.
The North America Hyaluronic Acid-based Dermal Fillers market size is estimated to reach USD 5,052.8 million by 2033.
The Monophasic HA Fillers segment leads the Hyaluronic Acid-based Dermal Fillers market, with a projected value of USD 9,113.8 million by 2033, compared to USD 3,568.9 million for the Biphasic HA Fillers segment in the same year.
Demographic shifts, particularly aging populations, significantly influence the Hyaluronic Acid-based Dermal Fillers market. Increased awareness of aesthetic treatments, coupled with rising disposable incomes, drives consumer spending on non-invasive procedures. The growing trend of self-care and wellness supports investment in cosmetic procedures, further promoting market expansion.
North America holds the dominant share of the Hyaluronic Acid-based Dermal Fillers market, with a projected value of USD 5,052.8 million in 2033, representing 42.1 percent of the total market.
Several factors restrain the growth of the Hyaluronic Acid-based Dermal Fillers market. Stricter regulatory compliance increases testing and documentation requirements, disproportionately affecting smaller manufacturers. Macroeconomic headwinds, including rising inflation and supply chain disruptions, raise production costs and reduce consumer spending power, leading to stagnated demand.
Demographic shifts, particularly aging populations, drive product adoption in the Hyaluronic Acid-based Dermal Fillers market. Increased consumer awareness of aesthetic treatments and a growing focus on personal appearance further enhance demand. the trend towards self-care and wellness encourages investment in non-invasive cosmetic procedures, promoting market growth.
The Hyaluronic Acid-based Dermal Fillers market is estimated to reach a valuation of USD 12,682.6 million by 2033.
Key players in the Hyaluronic Acid-based Dermal Fillers market include AbbVie Inc. (Allergan Aesthetics), Galderma S.A., Merz Aesthetics, Anika Therapeutics Inc., and Bloomage Biotechnology Corporation Limited.
Choose Your License
Global Hyaluronic Acid-based Dermal Fillers Market
The analysts below cover Medical Devices research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

LEAD PRINCIPAL ANALYST, PHARMA AND HEALTHCARE
Food and Beverages · Healthcare · Healthcare IT · Medical Devices
Ajay Devgire is the Lead Healthcare Analyst at MetaStat Insight, leading strategic research and market intelligence initiatives across the global healthcare domain.
SENIOR RESEARCH ANALYST
Biotechnology · Food and Beverages · Medical Devices · Packaging
Snehal Pasalkar is a Research Analyst at MetaStat Insight, operating at the intersection of life sciences research, competitive strategy, and market intelligence.
Assessing 200mm wafer transition schedules and substrate supply bottlenecks requires precise technical intelligence. MetaStat Insight supplied an actionable breakdown comparing planar and trench MOSFET architectures across automotive and industrial drive markets. The regional capacity estimates for Asia-Pacific foundries helped clarify lead-time uncertainties during our strategic planning session. When we needed additional clarification on high-purity raw material sourcing, their analyst team responded with helpful context within twenty-four hours.
Tracking maintenance cycle demand for secondary flight display units and terrain collision avoidance systems across regional jet fleets involves complex aftermarket dynamics. MetaStat Insight provided practical analysis separating airline retrofit programs from OEM forward-fit production schedules in North America and Southeast Asia. The supplier matrix highlighted component obsolescence timelines without resorting to vague generalizations. The dataset served as a dependable reference during our annual program review meetings.
Evaluating secondary resin quality across post-consumer packaging streams requires reliable technical segmentation. MetaStat Insight delivered an objective assessment that distinguished between extrusion-grade flake pricing and optical sorting throughput limitations across Western Europe. The competitive positioning breakdown for licensed depolymerization technology providers answered several questions during our feedstock feasibility audit. Their team clarified regional trade restrictions on mixed plastic scrap quickly when our team submitted follow-up requests.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950