
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Industrial Power Supply Market Size, Share, By Power Supply Type (AC-DC Power Supplies and Rectifier Systems, DC-DC Converter Systems, DC-AC Inverter Systems, Industrial UPS and Battery-Backed Power Systems), By Output Power (Below 1 kW, 1-10 kW, 10-100 kW, 100-500 kW, Above 500 kW), By Phase (Single Phase and Three Phase), By End-Use Industry (Power Generation and Utilities, Chemicals and Hydrogen, Metals and Mining, Automotive and General Manufacturing, Electronics and Semiconductors, Marine and Shipbuilding, Oil and Gas, Cement and Minerals Processing), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5273
September 16, 2026
277 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $13.5 Billion in 2025, projected to reach $21.7 Billion by 2033 at a 6.1% CAGR.
Dominant Segment: The AC-DC Power Supplies & Rectifier Systems segment leads the market, driven by continuous demand for reliable power conversion solutions across various industries.
Geographic Lead: The Asia Pacific region is experiencing the fastest growth, fueled by rapid industrialization and significant investments in infrastructure and technology in countries like China and India.
What's Inside: This report provides a comprehensive analysis of the competitive landscape, market segmentation by power supply type, output power, phase, and end-use industry, along with forecasts from 2026 to 2033.
High-growth Applications: Three-phase industrial power supplies are in high demand, particularly in automotive and general manufacturing, due to their capability to handle substantial loads and support critical operations.
Technological Innovations: Advancements in SiC and GaN power electronics are reshaping the market, enhancing efficiency and performance in industrial power supply systems.
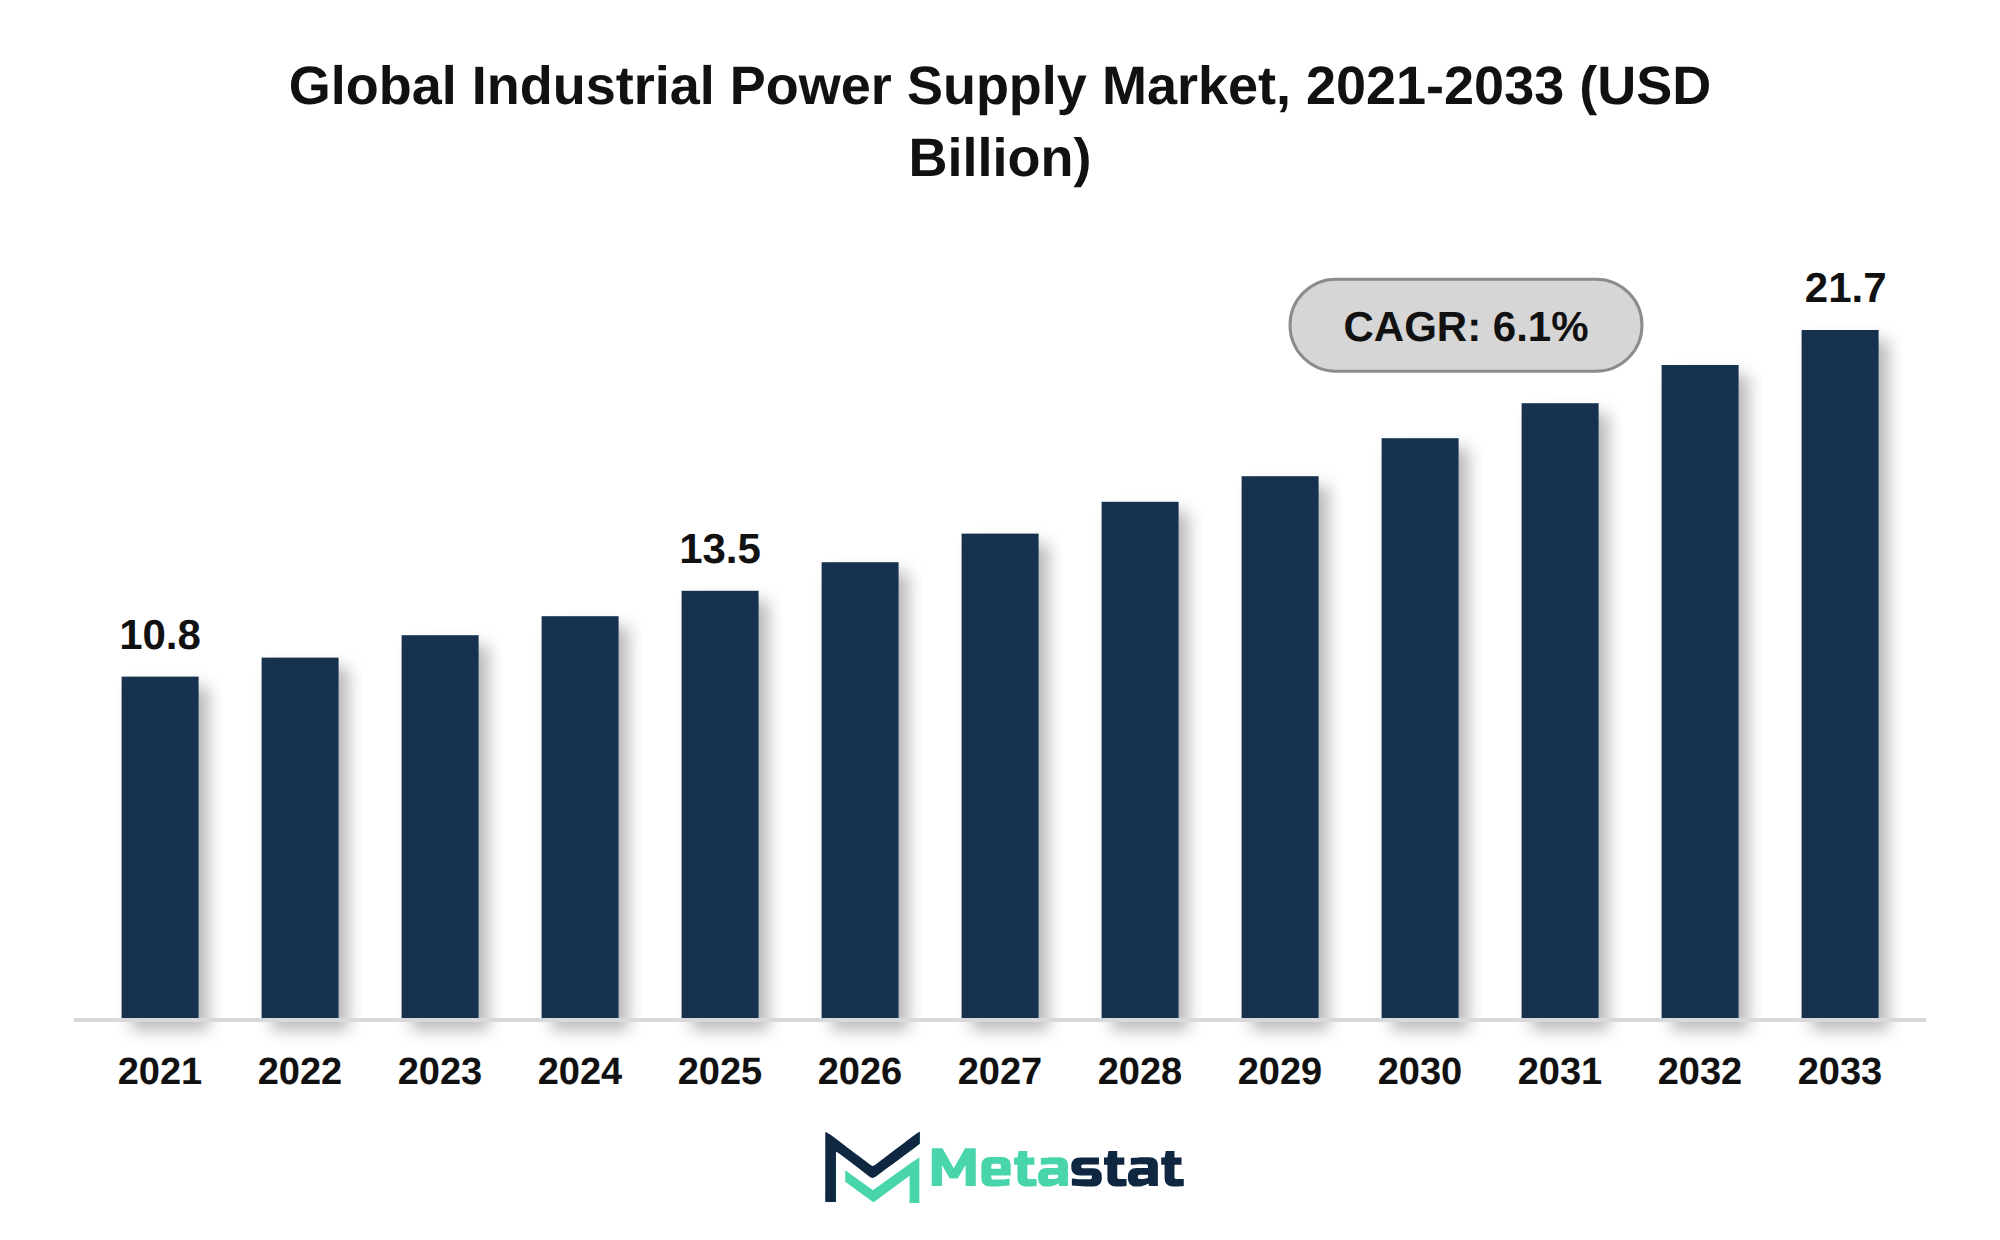
The global Industrial Power Supply market was valued at USD 13.5 billion in 2025 and is projected to reach USD 21.7 billion by 2033, growing at a CAGR of 6.1% over the forecast period.
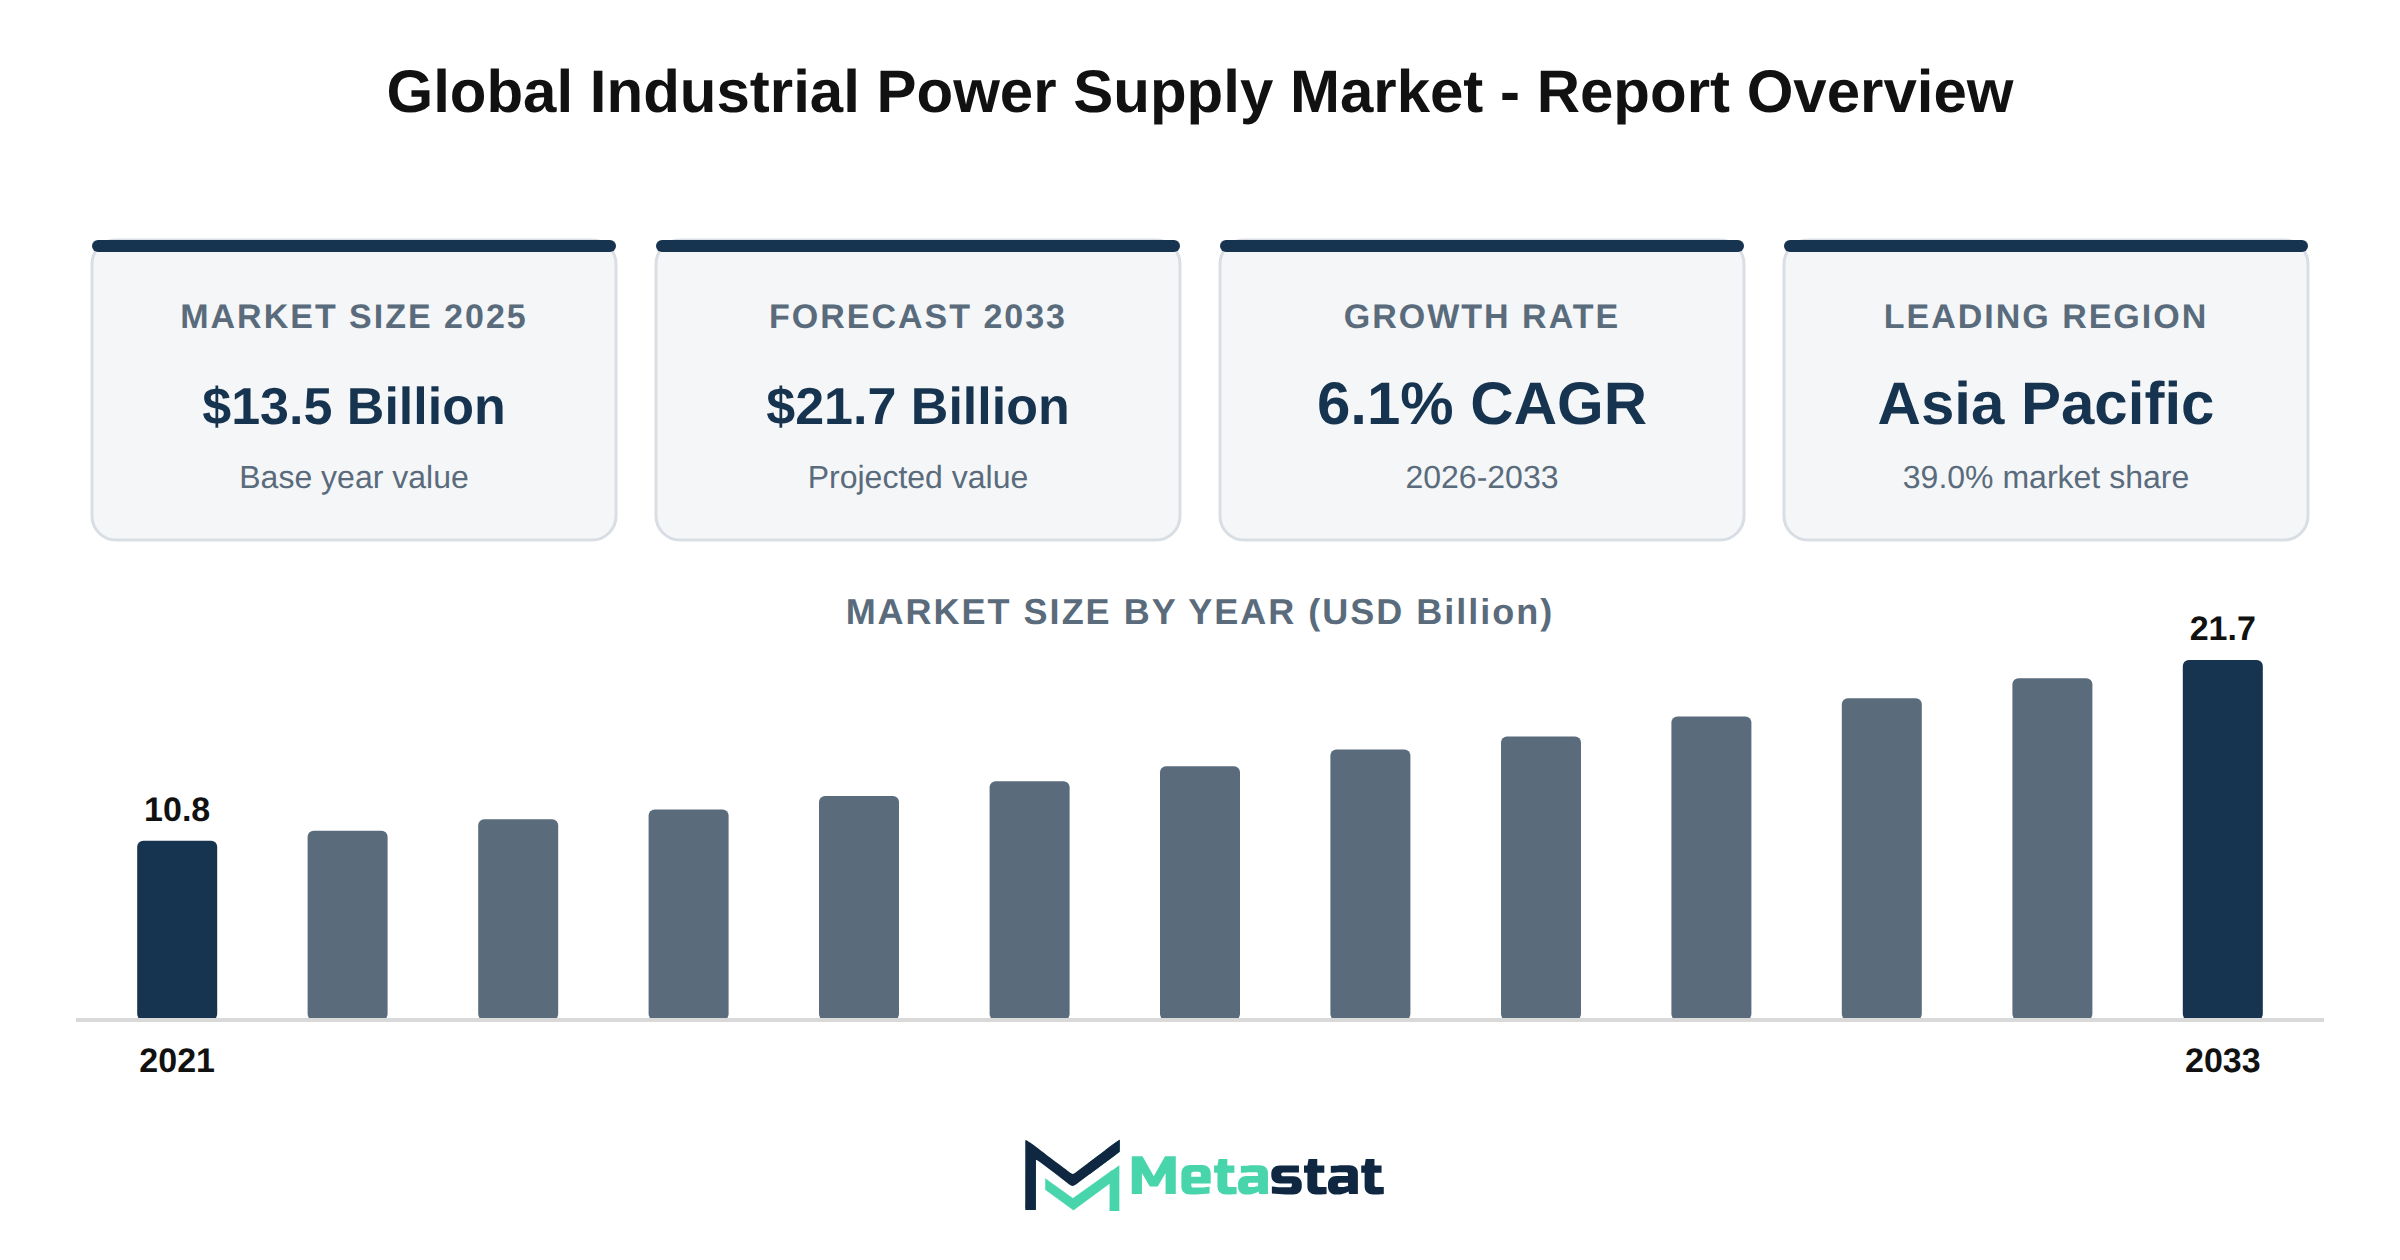
The Industrial Power Supply market is poised for significant growth, with a projected increase in value from USD 13.5 billion in 2025 to USD 21.7 billion by 2033, representing a compound annual growth rate (CAGR) of 6.1%. Demand for industrial power supply solutions is driven by the expansion of manufacturing capabilities, technological advancements, and the need for reliable power in various sectors.
Adoption trends highlight a strong preference for high-efficiency AC-DC and DC-DC power supplies, particularly in sectors requiring reliable and efficient energy conversion. The shift towards renewable energy sources further contributes to the increasing demand for these solutions. Industries focusing on power generation, automotive, and smart manufacturing lead this trend, pushing for innovations that enhance power efficiency and reliability.
In high-power applications, the demand for three-phase industrial power supplies continues to rise, driven by their ability to handle larger loads and provide stable power for critical operations. This trend is particularly evident in sectors including metals and mining, where high-power rectifier systems are essential for processes like electrolysis and hydrogen production.
The growth of industrial UPS and battery-backed power systems reflects the increasing importance of uninterrupted power supply in critical operations. These systems safeguard against power interruptions, ensuring operational continuity in manufacturing and process industries. The need for reliable backup power solutions is heightened by the rising complexity of industrial operations and the integration of automation technologies.
Power supply demand from electronics and semiconductor manufacturing demonstrates significant growth, influenced by the surge in consumer electronics and the ongoing digital transformation. The market for industrial power supplies benefits from the expanding requirements in these sectors, which prioritize high performance and energy efficiency.
In the metals and mining sector, the demand for industrial power supplies grows alongside the need for efficient electrochemical processing. The increasing focus on sustainable mining practices and energy-efficient technologies drives investments in advanced power supply solutions. This trend is likely to enhance the overall market landscape, creating opportunities for innovations in power electronics.
The automotive industry, with its shift towards electrification and smart manufacturing, presents expanding power supply requirements. The integration of advanced technologies in automotive production necessitates reliable and efficient power solutions, further propelling growth in the industrial power supply market.
Emerging technologies including SiC and GaN power electronics are transforming industrial power conversion, offering improvements in efficiency and thermal performance. The adoption of these technologies aligns with the industry's goals of enhancing energy density and reducing power losses, thereby contributing to the overall growth of the market.
Modular and programmable industrial power supply technologies are gaining traction, enabling greater flexibility and scalability in power solutions. These innovations cater to the evolving demands of diverse industries, facilitating efficient energy management and customization of power systems.
Industrial power demand is experiencing growth driven by the increasing need for efficient and reliable power solutions across various industries. The rising adoption of high-efficiency AC-DC and DC-DC industrial power supplies supports this trend, particularly within sectors including electronics and semiconductor manufacturing. This shift enhances energy efficiency and meets the stringent power requirements posed by modern applications.
High-power applications generate significant demand for three-phase industrial power supplies, particularly in sectors like automotive and general manufacturing. These applications require dependable power systems capable of handling substantial loads, which aligns with the growing trend towards high-power rectifier systems for electrolysis and hydrogen production. Such developments indicate a shift towards sustainable energy solutions, further stimulating market growth.
The expansion of power supply requirements in automotive and smart manufacturing illustrates the increasing complexity of industrial processes. Manufacturers in these sectors seek advanced power solutions that offer modular and programmable features, enabling them to adapt to evolving production demands. This trend aligns with the broader movement towards Industry 4.0 and automation, resulting in enhanced operational efficiency and productivity.
Innovations in energy efficiency and power density are reshaping the industrial power supply landscape. Developments in SiC and GaN power electronics facilitate improved power conversion, driving demand for next-generation power supplies. The market's focus on reliable solutions that operate efficiently in harsh environments further supports this transformation, leading to enhanced product offerings and competitive advantages for manufacturers.
The integration of renewable energy sources into industrial power systems generates new demand for advanced power conversion solutions. This trend reflects the industry's commitment to sustainability and the transition towards cleaner energy sources. Manufacturers are increasingly investing in technologies that enhance the reliability and efficiency of power supplies, ensuring compatibility with renewable energy systems.
Competitive dynamics in the industrial power supply market intensify, driven by manufacturers' focus on innovation and differentiation. Companies are investing in research and development to create advanced power supply solutions that meet the evolving needs of end-users. This environment encourages collaboration and strategic partnerships, enhancing market positioning and driving growth across various segments.
The Asia Pacific region presents significant growth opportunities within the industrial power supply market, driven by rapid industrialization and increasing energy demands. Countries including China and India are making substantial investments in infrastructure and technology. These developments create a favorable environment for manufacturers to capitalize on emerging market trends and expand their presence in this dynamic region.
Investment in infrastructure development acts because a critical growth driver for the Industrial Power Supply market. Governments and private entities allocate significant resources to enhance physical and digital capabilities, which includes upgrading power generation facilities and expanding transmission networks. This trend aligns with the increasing need for reliable power supply systems across various sectors, including utilities, manufacturing, and transportation.
While countries invest in modernizing their infrastructure, demand for advanced power supply solutions grows, particularly those that enhance efficiency and support renewable energy integration. Industries including power generation and utilities, chemicals, and general manufacturing exhibit heightened interest in power supply technologies that improve operational productivity and align with sustainability goals. In this context, investments in infrastructure significantly contribute to the market's expansion through 2033.
With rising urbanization and population growth, the pressure on existing infrastructure increases, necessitating upgrades and the implementation of innovative power supply systems. This trend creates opportunities for manufacturers and suppliers within the Industrial Power Supply market, encouraging technological advancements and promoting a shift towards more efficient energy solutions.
The Industrial Power Supply market experiences significant growth driven by advancements in automation and digital technologies. The integration of artificial intelligence, software adoption, and the digitization of legacy processes enhances operational efficiency across various industries. Manufacturers meet the demand for innovative power solutions tailored to specific applications.
Automation facilitates improved precision and reliability in industrial processes, attracting investment in advanced power supply systems. The rising need for adaptable and efficient power solutions encourages companies to upgrade their existing infrastructure, creating opportunities for market players. Industries prioritizing the integration of smart technologies drive demand for high-quality power supply options, contributing to overall market growth.
The ongoing digital transformation in sectors including manufacturing, automotive, and energy drives the need for sophisticated power management systems. A focus on data-driven decision-making optimizes energy consumption and enhances productivity. This shift in consumer behavior toward sustainability and efficiency advances the Industrial Power Supply market.
Increased investment in technology and the pursuit of operational excellence support market growth throughout the forecast period. Companies prioritizing modernization and efficiency improvements find that technological integration plays a critical role in shaping a competitive landscape and driving investment in the Industrial Power Supply market.
Regulatory challenges significantly impact the Industrial Power Supply market, creating compliance hurdles that slow adoption and integration. Strict compliance requirements often necessitate substantial investments in technology and infrastructure, leading to increased operational costs for manufacturers and users. This financial burden hinders the ability of smaller market players to compete effectively with larger firms that possess the capital necessary to meet regulatory standards.
Macroeconomic headwinds, including inflationary pressures and fluctuating material costs, contribute to rising operating expenses. These economic factors strain profit margins and lead to reduced investment in new technologies, further limiting market growth. Supply chain disruptions and geopolitical instability create uncertainty in sourcing components, which delay product availability and project timelines.
High capital investment requirements present another significant barrier. The necessity for advanced equipment and systems often deters potential entrants and restricts the expansion capabilities of existing players. The market faces risks related to technological obsolescence; rapid advancements render existing solutions inadequate, prompting continual reinvestment in R&D.
Market fragmentation complicates the competitive environment. Diverse regional requirements and varying levels of technological adoption contribute to inconsistent demand across different markets. Cultural barriers and regional adoption resistors further challenge uniform growth, creating disparities that several companies find difficult to navigate.
Lastly, concerns surrounding data security and privacy have emerged, reflecting critical considerations. With the rise of digital solutions in power supply systems, vulnerabilities to cyber threats undermine user confidence and slow the uptake of innovative products. The culmination of these factors highlights the various challenges facing the Industrial Power Supply market, necessitating strategic navigation by stakeholders to ensure sustained growth.
Geopolitical fragmentation and trade deficits present significant challenges for the Industrial Power Supply market. Increasing tariffs and trade barriers disrupt supply chains, heightening costs and leading to increased prices for consumers. Manufacturers face tighter profit margins while navigating complex international trade regulations. This situation influences production schedules and planning, complicating the ability to meet demand in a timely manner.
Technological disruptions further complicate market dynamics, necessitating ongoing investments in research and development. Companies encounter hurdles when integrating new technologies into existing systems, leading to interoperability friction. These challenges delay product launches and hinder adoption rates among end-users, impacting overall market growth. Rising input costs driven by unstable feedstock prices create budgetary constraints for manufacturers, compelling them to find innovative solutions while maintaining competitiveness.
The Industrial Power Supply market faces workforce skill gaps and talent retention pressures. A shortage of skilled professionals limits operational efficiency and slows the pace of technological advancement. Companies invest in training programs and incentives to attract and retain talent, which adds to operational costs and stresses resources. In tandem, environmental lifecycle footprints and decarbonization mandates increase pressure on manufacturers to adopt sustainable practices, complicating production and operational strategies.
Logistical disruptions and supply chain instability exacerbate these issues. Natural disasters, geopolitical tensions, and global health crises disrupt transportation networks and constrain material availability. Manufacturers develop robust contingency plans to mitigate these risks, requiring additional investment and strategic planning. These factors collectively challenge the Industrial Power Supply market, creating a complex environment that demands agility and resilience from industry players.
Growing industrialization and urbanization across developing regions significantly influence the Industrial Power Supply market. Emerging economies, particularly in Asia Pacific and South America, demonstrate heightened demand for reliable power solutions. Robust infrastructure development, coupled with rising energy consumption, necessitates advanced power supply systems to address these challenges and support continuous operations in various industries.
Technological disruptions, including the shift toward renewable energy sources, create substantial opportunities within the market. The increasing integration of sustainable practices and eco-friendly solutions aligns with global sustainability imperatives. This trend encourages manufacturers to innovate and develop next-generation power supply systems that support energy efficiency and reduce environmental impact, ultimately enhancing their competitive positioning.
Digital transformation reshapes the procurement and supply chain management landscape. Evolving buying behaviors characterized by the adoption of digital procurement platforms enhance accessibility to a wide range of products in the Industrial Power Supply market. Strategic consolidation through partnerships and mergers enables businesses to offer integrated solutions that cater to diverse customer needs, expanding their market reach and driving revenue growth.
Adapting to regulatory shifts and eco-friendly compliance requirements positions firms favorably within the competitive environment. Companies focusing on sustainability and green transformations enhance brand reputation and appeal to environmentally conscious clients. This alignment with Environmental, Social, and Governance (ESG) principles drives demand for innovative power solutions that meet stringent compliance standards, fostering long-term customer loyalty.
Overall, the Industrial Power Supply market benefits from these regional demands and technological advancements. The push for modernization and sustainable practices supports growth and enhances investment opportunities, delivering significant returns in the foreseeable future and reinforcing the market's resilience against potential disruptions.
The Global Industrial Power Supply market is segmented based on Power Supply Type, Output Power, Phase, and End-Use Industry.
Valued at USD 5.9 billion in 2026, the AC-DC Power Supplies & Rectifier Systems segment is projected to reach USD 8.6 billion by 2033, at a CAGR of 5.5% during the forecast period. This segment benefits from continuous demand for reliable and efficient power conversion solutions across various industries. The trend towards electrification and automation drives the adoption of AC-DC power supplies, particularly in manufacturing, automotive, and telecommunications.
Technological advancements in power electronics and rectification techniques contribute to improved efficiency and performance, enhancing the segment's appeal. Innovations in design and materials facilitate next-generation upgrades, allowing manufacturers to offer products that meet the evolving requirements of end-users. Regulatory compliance standards regarding energy efficiency and safety influence product development and market dynamics.
Downstream applications, particularly in renewable energy systems and electric vehicles, create substantial growth opportunities within the segment. These trends lead to shifts in consumption patterns, with increasing demand for products capable of supporting high-efficiency standards. Overall cost structures and pricing volatility in raw materials present challenges and opportunities, compelling manufacturers to optimize their supply chains for resilience against fluctuations.
The strategic capital investment outlook remains positive. Participants in the market focus on expanding their product portfolios and enhancing manufacturing capabilities. This proactive approach positions the AC-DC Power Supplies & Rectifier Systems segment to capitalize on emerging opportunities within the broader Industrial Power Supply market.
Investment in DC-DC Converter Systems reflects increasing demand for efficient power management solutions. This segment is estimated to reach USD 5.6 billion by 2033, at a CAGR of 6.8% during the forecast period. The rise in demand stems from various industries seeking compact and efficient power solutions for their applications, particularly in telecommunications and automotive sectors. Technological advancements improve the performance and reliability of DC-DC converters, driving adoption in high-density power environments.
End-use industries are shifting towards energy-efficient solutions driven by regulatory standards that become more stringent. This transition aligns with a global push for reduced energy consumption and carbon footprints. Supply chain resilience supports the segment's growth, with manufacturers focusing on sustainable practices and alternative sourcing strategies to mitigate risks. The Industrial Power Supply market experiences substantial momentum, supported by innovations that enhance product offerings and provide competitive advantages.
Strategic opportunities exist in next-generation upgrades, which include integration with renewable energy systems and smart grid technologies. The evolution of products addressing emerging consumer demands reflects the market's responsiveness to technological maturation. While manufacturers invest in research and development, the landscape for DC-DC Converter Systems expands, addressing evolving market needs and reinforcing the segment's position within the broader Industrial Power Supply market.
Demand for DC-AC Inverter Systems is fueled by increasing reliance on renewable energy sources and the growing need for efficient energy conversion solutions across various industries. These systems play a crucial role in converting direct current (DC) into alternating current (AC), essential for applications in renewable energy, electric vehicles, and various industrial equipment. The rising adoption of solar energy systems and electric vehicles drives the need for advanced inverter technologies, enhancing efficiency and performance.
Technological maturation in the field of inverters has led to significant improvements in efficiency, size, and cost-effectiveness. Innovations in semiconductor technology and control algorithms enable manufacturers to produce more compact and efficient devices. Continuous advancements in power electronics contribute to the expansion of the market. Industries increasingly adopt these technologies for improved energy management.
End-use dynamics reflect a growing emphasis on sustainable practices, with industries including power generation, automotive, and manufacturing implementing DC-AC inverter systems. The transition toward electrification in transportation and sustainable energy generation influences demand, positioning these systems because integral components in achieving energy efficiency goals. Regulatory compliance standards related to energy efficiency and emissions encourage the adoption of these systems, aligning with global sustainability initiatives.
Market projections indicate that the DC-AC Inverter Systems segment is projected to reach USD 3.1 billion by 2033. This growth arises from a combination of rising energy demands, technological advancements, and the shift toward more sustainable energy solutions. Companies within the Industrial Power Supply market have opportunities to capitalize on these trends by investing in innovative products and enhancing their offerings to meet evolving consumer needs.
Growth in the Industrial UPS & Battery-Backed Power Systems segment reflects the increasing demand for reliable and uninterrupted power solutions across various industries. Factors driving this demand include heightened reliance on digital infrastructure and the need for uninterrupted power supply during outages. Industries including healthcare, telecommunications, and data centers prioritize system reliability, further cementing the role of UPS systems. This segment is projected to grow at a CAGR of 5.7% during the forecast period, emphasizing the vital role these systems play in ensuring operational continuity.
Technological advancements significantly contribute to the evolution of Industrial UPS & Battery-Backed Power Systems. Innovations focus on improving energy efficiency, reducing noise levels, and enhancing battery life, aligning with the growing emphasis on sustainability in the market. These advancements enable industries to adopt UPS solutions with lower operational costs and reduced environmental impact. Regulatory compliance and standards regarding energy efficiency drive manufacturers to invest in upgrading existing systems, ensuring they meet the latest requirements while enhancing performance.
Companies operating within this segment benefit from strategic opportunity windows, driven by the development of next-generation products that address emerging challenges. Trends including the increasing integration of renewable energy sources further influence the design and functionality of UPS systems. The market landscape experiences a growing emphasis on modular systems, which provide flexibility and scalability for end-users. This adaptability aligns with diverse customer requirements and encourages wider adoption across various sectors, ultimately enhancing the market's growth potential.
Investment in raw material sourcing remains crucial for manufacturers in this segment. Supply chain resilience is essential for maintaining consistent production levels while mitigating the risks associated with material shortages. In this context, strategic partnerships with suppliers enhance the procurement process, ensuring a stable flow of quality materials. These dynamics influence pricing structures, with companies seeking to balance cost pressures against the need for high-quality components.
While adoption of Industrial UPS & Battery-Backed Power Systems expands, considerations surrounding disruptive alternatives and technological obsolescence gain importance. Companies remain vigilant to emerging technologies that could reshape the competitive landscape, ensuring they remain relevant and innovative. Continuous investment in research and development supports a proactive approach to market changes, enabling firms to adapt and thrive in the evolving Industrial Power Supply market.
Valued at USD 2.7 billion in 2026, the Below 1 kW segment is projected to reach USD 3.7 billion by 2033, at a CAGR of 5% during the forecast period. Demand for power supplies below 1 kW primarily arises from sectors with low power requirements, including telecommunications, consumer electronics, and medical devices. These industries increasingly adopt small-scale power solutions to enhance efficiency and reduce energy consumption. Technological advancements continue to drive product evolution within this segment, focusing on improving energy density, compactness, and reliability.
End-use dynamics significantly influence this segment's growth trajectory. The rising importance of reliable power sources in critical applications, including medical equipment and communication systems, drives demand for efficient solutions. Regulatory compliance standards compel manufacturers to enhance their product offerings, ensuring they meet stringent guidelines for safety and performance.
Cost structures within the Below 1 kW segment reflect a balance between component sourcing and manufacturing efficiencies. Suppliers emphasize sustainable practices while evolving raw material sourcing strategies, impacting pricing volatility. Strategic opportunity windows exist for providers investing in next-gen upgrades and disruptive alternatives that meet changing end-user needs.
The Industrial Power Supply market increasingly reflects a shift toward integrated solutions that combine power supplies with advanced monitoring and control systems. This integration aligns with broader consumption shifts toward smart technologies, promoting energy-saving innovations. Overall, the Below 1 kW segment exemplifies a dynamic environment driven by technological maturation and evolving industry demands.
Estimations indicate the 1-10 kW segment reaches USD 5.7 billion by 2033, at a CAGR of 5.5% during the forecast period. This segment experiences a surge in demand driven by increased adoption across various end-use industries, including automotive and general manufacturing. Heightened industrial automation and the growing need for reliable power supply systems increase the uptake of these power solutions. Technological advancements enable more efficient and compact designs, catering to the evolving needs of manufacturers aiming for enhanced operational efficiency.
Demand patterns reflect a shift towards smaller, more flexible power solutions, aligning with modern manufacturing processes that emphasize agility. The emphasis on energy efficiency and sustainability within industries influences purchasing decisions, leading to a preference for systems that provide optimal performance while minimizing environmental impact. Regulatory compliance requirements further stimulate growth, because organizations seek to meet established standards for energy usage.
Investment in next-generation upgrades shifts the competitive landscape, allowing established players to fortify market positions while new entrants introduce innovative solutions. This dynamic creates a healthy environment for competition, because firms strive to differentiate their offerings. The Industrial Power Supply market benefits from a diverse supplier ecosystem, ensuring resilience in sourcing raw materials and mitigating the impact of potential disruptions. The segment's outlook remains promising, with ongoing developments driving continuous improvements in product evolution and performance metrics.
Growing adoption of energy-efficient technologies supports demand for the 10-100 kW segment in the Industrial Power Supply market. This segment is projected to reach USD 6.9 billion by 2033, driven by advancements in power management systems and increasing applications across various industries. The shift toward automation and digitalization enhances the need for reliable power supply solutions, particularly in manufacturing and process-driven sectors.
Technological maturation in power supply systems emphasizes reliability and efficiency, driving investment into next-generation upgrades. Industries including automotive and general manufacturing prioritize power supply solutions that ensure operational integrity and sustainability. Consequently, firms investing in this segment benefit from improved energy utilization and reduced operational costs, enhancing overall competitiveness.
Regulatory compliance with energy efficiency standards encourages industry players to innovate within this segment. Adaptation to these regulations drives the development of advanced power supply technologies that minimize energy consumption. End-use industries expanding their focus on sustainability align demand for products within the 10-100 kW range with these evolving compliance frameworks.
Strategic opportunity windows arise from the escalating need for robust power solutions across diverse applications. Increasing consumption shifts towards higher efficiency ratings and expanded functionality create avenues for manufacturers to capture market share. The competitive landscape reflects a strong inclination toward value-added features that cater to evolving customer requirements, particularly in sectors like chemicals and hydrogen production.
Demand for the 100-500 kW segment demonstrates strong potential, with projections indicating growth at a CAGR of 6.7% during the forecast period. This surge originates from increasing energy efficiency requirements and the transition towards more sustainable energy sources across various industries. Manufacturers in sectors including power generation, automotive, and general manufacturing increasingly adopt higher capacity industrial power supplies to meet operational demands and enhance productivity.
Technological advancements play a significant role in the evolution of this segment, with innovations in power electronics and energy storage solutions driving product development. Enhanced system configurations and integration with renewable energy sources support the growing reliance on advanced power supply systems. This transition aligns with the trends of industrial automation and digitalization, shaping the consumption patterns within the market.
Regulatory compliance standards significantly influence market dynamics, compelling manufacturers to adopt advanced technologies that meet stringent energy efficiency regulations. The rise in certifications and quality standards contributes to increased investments in the 100-500 kW segment, driven by companies prioritizing compliance to maintain competitive positioning. This trend encourages a proactive approach toward product lifecycle management and operational excellence.
Cost structures within the segment are evolving, influenced by fluctuating raw material prices and supply chain resilience. Companies strategize to mitigate risks associated with pricing volatility by exploring alternative sourcing methods and forging strategic partnerships. This strategic direction enhances operational agility and positions manufacturers to respond effectively to market demands.
Overall, the 100-500 kW segment remains integral to the Industrial Power Supply market's growth narrative. The confluence of demand drivers, technological maturation, and regulatory pressures creates strategic opportunity windows for stakeholders aiming to capture market share and drive innovation.
Demand for power supplies exceeding 500 kW derives primarily from large-scale industrial operations that require robust energy solutions to support extensive machinery and production lines. Industries including manufacturing, oil and gas, and power generation rely on these high-capacity systems to ensure uninterrupted operations and compliance with stringent regulatory standards.
Adoption of advanced technologies contributes significantly to the segment's growth. Enhanced efficiency and reliability of high-capacity power supplies drive manufacturers to seek next-generation upgrades featuring improved energy conversion rates and reduced operational downtime. These factors align with the growing emphasis on sustainable practices and energy efficiency across various sectors.
The industrial power supply market experiences shifts in consumption patterns, with companies prioritizing energy resilience and reliability. Organizations invest in systems that provide backup and continuous power during outages, driven by the need for operational continuity and safety standards in critical applications.
Regulatory compliance mandates surrounding emissions and energy efficiency reinforce the demand for high-capacity power supply solutions. Companies adhering to these regulations benefit from improved reputation and market positioning while avoiding potential fines. The development of compliant products represents a strategic opportunity for manufacturers aiming to capture market share.
Technological advancements in power supply systems lead to continual product evolution. Innovations in materials and design allow for more compact and efficient systems, enhancing performance while reducing overall costs. This trend presents a strategic opportunity for players in the market, enabling them to capitalize on emerging technologies and meet evolving customer needs.
Valued at USD 5.4 billion in 2026, the Single Phase segment is projected to reach USD 7.6 billion by 2033, at a CAGR of 4.9% during the forecast period. Growth in this segment stems from increasing demand across various applications, particularly in residential and light commercial sectors. The transition towards more energy-efficient systems drives adoption rates, allowing for effective power distribution in smaller installations. Technological advancements in power supply designs contribute to enhanced performance and reliability, attracting investments from manufacturers eager to capture market share. End-use industries including automotive and general manufacturing increasingly favor single-phase systems due to their lower installation and operational costs compared to three-phase systems. Overall, the dynamics within the Industrial Power Supply market highlight the importance of the Single Phase segment, reflecting a key driver of growth.
Significant growth opportunities exist within the Three Phase segment of the Industrial Power Supply market. This segment is estimated to reach USD 14.2 billion by 2033, at a CAGR of 6.7% during the forecast period. Increased demand for robust power systems across various industries drives adoption, particularly in sectors including manufacturing and energy generation. The transition towards more efficient and sustainable energy solutions serves because a catalyst for segment expansion. Technological advancements enhance performance and reliability, ensuring these systems meet the rigorous demands of modern applications.
Downstream applications, including automation and renewable energy integration, exhibit a growing reliance on Three Phase power solutions. The continuous evolution of these technologies aligns with industry standards and regulatory compliance, ensuring operational efficiency and safety. Cost structures influence raw material prices and supply chain dynamics, impacting pricing strategies and profit margins. Overall, the Three Phase segment is positioned to capitalize on strategic opportunities within the evolving landscape of the Industrial Power Supply market.
Valued at USD 2.3 billion in 2026, the Power Generation & Utilities segment is projected to reach USD 3.4 billion by 2033, at a CAGR of 5.4% during the forecast period. Increased investment in renewable energy sources significantly influences demand for power supply solutions. Governments and regulatory bodies worldwide push for cleaner energy alternatives, driving the need for advanced power supply systems in this segment. Technological advancements lead to improved efficiency and reliability, creating strong adoption rates among end-users in the utilities sector. The transition to smart grids promotes the integration of innovative power solutions, which further expands the market. The continuous evolution of industry standards and compliance requirements necessitates ongoing upgrades to equipment, presenting opportunities for manufacturers to innovate and enhance product offerings. Energy consumption patterns shifting towards greater sustainability drive transformation in the Industrial Power Supply market, aligning with broader environmental goals.
Rising investments in the Chemicals & Hydrogen sector drive demand for reliable power supply systems. Focus on clean energy and sustainability enhances the need for advanced technologies within this industry. Regulatory pressures and environmental standards fuel adoption of efficient power solutions, leading to innovation in product development and upgrades. Market participants engage in developing next-generation systems to meet evolving compliance requirements and enhance operational efficiencies.
Segment expansion arises from increasing applications in electrolysis, hydrogen production, and chemical processing, which require robust power solutions. The Chemicals & Hydrogen segment is projected to reach USD 2.4 billion by 2033, at a CAGR of 9% during the forecast period. Demand in this segment reflects the growth trajectory of the wider Industrial Power Supply market and highlights its strategic importance in achieving sustainable industrial practices and energy efficiency.
Technological advancements contribute significantly to product evolution, with innovations in energy storage and power management systems enhancing performance and reliability. Market players focus on developing scalable solutions to address diverse operational needs across various applications. Strategic opportunities arise from the shift toward renewable energy sources and the increasing use of hydrogen in industrial applications, further influencing the growth of the market.
Investments in the Metals & Mining segment of the Industrial Power Supply market reflect heightened demand for reliable and efficient power solutions. Technological advancements enable equipment to function seamlessly under challenging conditions, increasing operational efficiency. The growing need for automation and enhanced productivity in mining operations drives demand for advanced power supply systems. Manufacturers of industrial power supplies experience significant opportunities for expansion due to the sector's evolving infrastructure and requirements.
Valued at USD 2.5 billion by 2033, this segment experiences strong growth driven by the integration of innovative technologies and a focus on sustainable operations. Regulatory compliance standards promote the adoption of environmentally friendly practices within the industry, creating a favorable environment for market players to offer tailored solutions. Fluctuations in raw material sourcing and logistics vulnerabilities present strategic opportunities for suppliers who offer resilient and cost-effective products. The market's outlook remains positive, reflecting the evolving demand for power supply solutions in the Metals & Mining segment.
Strong demand for power supplies in the Automotive & General Manufacturing segment drives growth, supported by increasing production rates in the automotive sector and advancements in manufacturing technologies. Automotive manufacturers require reliable and efficient power supply solutions to meet production demands, particularly with the rapid shift towards electric vehicles, which necessitates specialized power systems. General manufacturing industries, encompassing a range of applications from assembly lines to robotic automation, experience heightened demand for industrial power supplies that enhance operational efficiency.
The Automotive & General Manufacturing segment is projected to grow at a CAGR of 5.4% during the forecast period. This growth reflects the industry's ongoing transition towards automation and smart manufacturing processes, which rely heavily on robust power supply systems. Regulatory compliance related to energy efficiency and emissions standards drives manufacturers to adopt advanced power supply solutions, further influencing market dynamics.
Investment in next-generation technologies, including energy-efficient DC-DC converter systems and AC-DC power supplies, significantly enhances production capabilities. Manufacturers prioritize these solutions to reduce operational costs and improve system reliability. The evolving landscape of the Industrial Power Supply market aligns with these trends, positioning the Automotive & General Manufacturing segment for sustained expansion.
Investment in the Electronics & Semiconductors sector reflects a strong demand for advanced power supply solutions. Rapid technological advancements drive this demand, resulting from manufacturers seeking efficient and reliable power supply systems to cater to increasingly complex electronic devices. Adoption of innovative technologies, including AI and IoT, necessitates robust power solutions, creating significant opportunities within the Industrial Power Supply market.
Next-generation upgrades in equipment and production processes fuel market growth. Stringent regulatory compliance standards and certifications for electronic components push manufacturers toward adopting high-performance power supply systems. This shift leads to heightened demand for products that meet both operational efficiency and regulatory requirements.
Consumption patterns within the Electronics & Semiconductors sector illustrate a transition toward sustainable and energy-efficient solutions. Manufacturers prioritize power supplies that enhance productivity while reducing environmental impact. This trend aligns with global initiatives aimed at minimizing carbon footprints, positioning the market for further expansion.
Strategic opportunities arise from the need for enhanced supply chain resilience. Manufacturers focus on securing reliable raw material sourcing and mitigating logistics vulnerabilities, ensuring that production processes remain uninterrupted. Companies within the Industrial Power Supply market explore innovative solutions to address these challenges, strengthening their competitive positions.
Disruptive alternatives and technological obsolescence represent significant considerations for stakeholders. Evolving technologies necessitate continuous adaptation and innovation within product lines. Companies remain agile to capture market share, requiring ongoing investment in research and development to meet the changing needs of end-users.
Recent developments in the Marine & Shipbuilding segment highlight various primary demand drivers influencing the market. Increased focus on sustainability and the push for cleaner energy sources drive investments in advanced power supply solutions, helping to meet stringent regulatory compliance standards. Adoption of next-generation upgrades in electrical systems enhances efficiency and reliability, promoting growth in this segment.
Technological maturation enables enhanced performance in marine applications, with innovations in power supply systems. The continuous evolution of products supports enhanced integration with advanced ship systems, improving operational dynamics. Consumption shifts toward more efficient technologies align with environmental regulations, compelling shipbuilders to upgrade their power supply solutions.
Cost structures present challenges, attributed to fluctuations in raw material prices impacting overall project expenses. However, strategic opportunity windows arise, allowing players to optimize supply chain resilience and explore innovative alternatives. The market remains sensitive to these dynamics, where manufacturers that effectively manage pricing volatility improve their competitive position.
The Marine & Shipbuilding segment within the Industrial Power Supply market displays significant potential for expansion. Investments in innovative technologies and adherence to regulatory requirements will shape the future landscape, driving demand for efficient power supply systems in marine applications.
Investment in the Oil & Gas sector drives demand for reliable and efficient power supply solutions. This industry requires consistent power for exploration, production, and refining processes, creating a foundation for growth within the Industrial Power Supply market. Adoption of next-generation technologies enhances operational efficiency and reduces environmental impact, prompting investments in advanced power systems.
Regulatory compliance standards strongly influence the sector, necessitating adherence to safety and environmental regulations. These standards often lead to the adoption of innovative power solutions that ensure operational compliance while optimizing performance. Companies focus on integrating renewable energy sources and energy-efficient systems to align with evolving regulatory frameworks, which enhances their competitive positioning.
Technological advancements in power supply systems provide strategic opportunities for players targeting the Oil & Gas segment. The shift towards digital technologies in power management allows for improved monitoring, diagnostics, and predictive maintenance, enhancing reliability and reducing operational downtime. Consequently, manufacturers emphasizing technological maturation position themselves favorably within the sector, supporting long-term growth.
Price volatility in raw materials affects cost structures within the industry. Fluctuations in the prices of inputs including metals and components exert pressure on profit margins, prompting companies to explore alternative sourcing strategies or invest in more efficient supply chain solutions. This situation encourages innovation and drives the evolution of product offerings tailored to meet the unique requirements of the Oil & Gas sector, ultimately supporting market resilience.
Consumption shifts and demand dynamics create a robust environment for growth in the Industrial Power Supply market. Companies are increasingly focused on optimizing energy consumption patterns and minimizing waste, enhancing the attractiveness of advanced power supply solutions. This strategic focus not only aligns with sustainability goals but supports long-term operational efficiency in the sector, reinforcing demand for innovative power systems.
Investment in the Cement & Minerals Processing sector reflects a growing recognition of the need for reliable and efficient power supply solutions. Demand for industrial power supplies in this segment is driven by the ensure continuous operations in processing facilities and the integration of advanced technologies that improve energy efficiency. The transition to sustainable practices influences end-use dynamics, prompting investment in more efficient power solutions.
Technological advancements contribute significantly to product evolution within the Cement & Minerals Processing segment. The adoption of next-generation power supply systems enables improved performance and energy efficiency, offering operational advantages to manufacturers. Competitive pressures compel firms to enhance their capabilities, aligning with regulatory compliance standards aimed at reducing emissions and increasing sustainability across industries.
Cost structures in this sector reflect the impact of raw material sourcing and the complexities of logistics. Fluctuations in material prices, along with logistical vulnerabilities, affect overall operational costs. Strategic opportunities exist for investments in innovative technologies that mitigate these challenges, enhancing supply chain resilience while addressing margin pressures. The capital investment outlook remains robust, supported by anticipated growth in the Industrial Power Supply market.
Investment in transportation, research, and infrastructure projects contributes significantly to the demand for power supplies within the Industrial Power Supply market. The focus on enhancing transportation networks and advancing research facilities creates a need for reliable power solutions that ensure operational efficiency and safety. Technological maturation across these sectors enables the integration of advanced power supply systems that improve energy management and reduce operational costs.
Investment trends in infrastructure development reflect an emphasis on sustainability and energy efficiency. Government policies promoting clean energy initiatives drive adoption, necessitating innovative power solutions that align with regulatory compliance standards. Consumption shifts occur, with organizations seeking versatile power supplies capable of supporting diverse applications within transportation and research environments.
Strategic opportunities arise from the necessity for reliable power systems that mitigate risks associated with technological obsolescence. Investments in next-generation upgrades aid in maintaining competitive advantages and meeting evolving consumer demands. The dynamic nature of research applications and transportation logistics necessitates a focus on power supply resilience, ensuring that systems adapt to varying load requirements and operational challenges. The need for adaptable power solutions remains critical.
Downstream applications in transportation logistics depend on robust power solutions that enhance performance and reliability. The integration of advanced technologies, including smart grid capabilities and IoT connectivity, highlights the growing importance of adaptable power supplies in addressing complex operational needs. Continued investments in these sectors will likely shape the future of the Industrial Power Supply market.
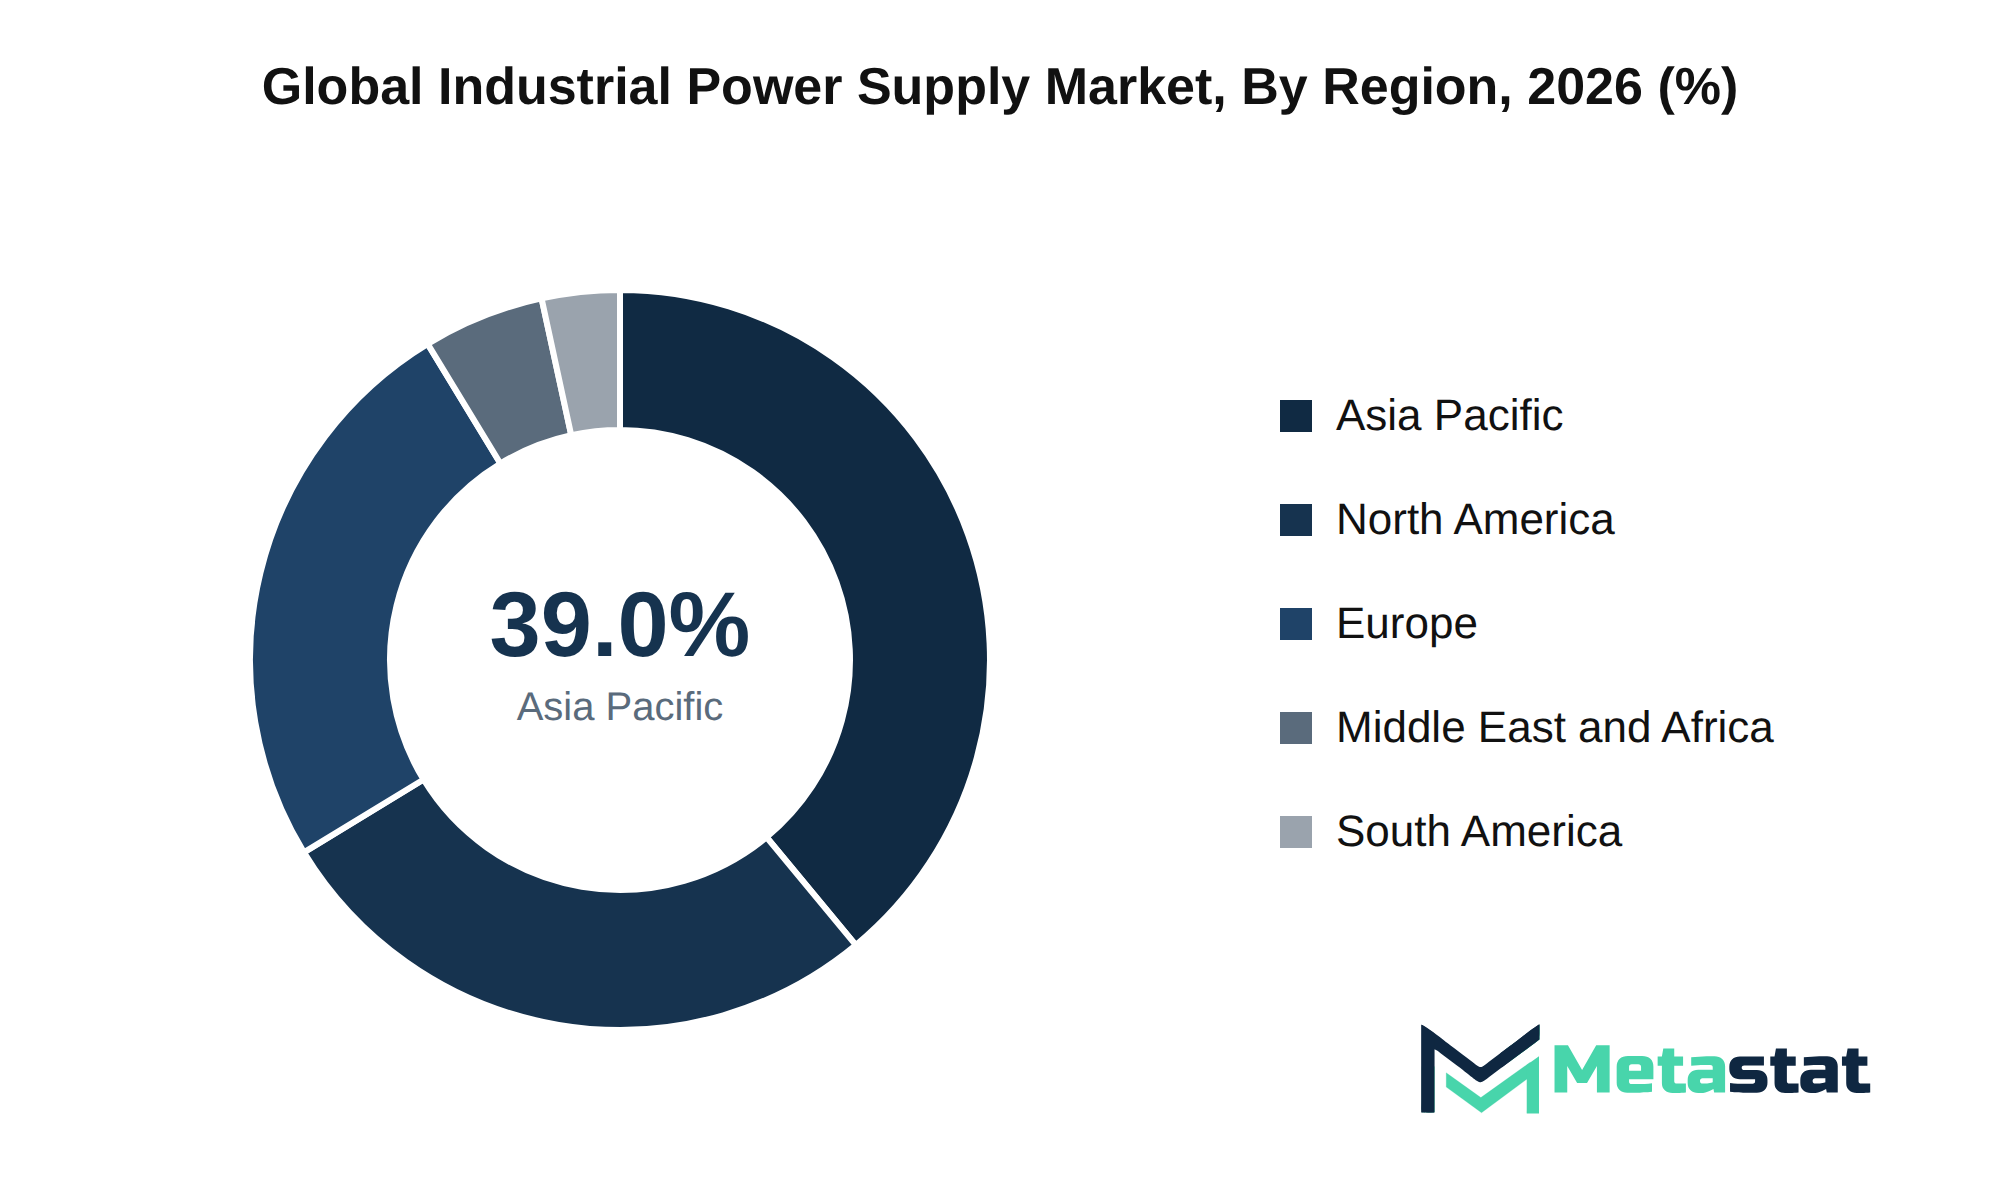
Based on geography, the Global Industrial Power Supply market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
The North America Industrial Power Supply market exhibits robust prospects for growth, driven by an expanding industrial base and increasing energy demands. Significant investments in infrastructure modernization, particularly in the United States, Canada, and Mexico, support the market's growth trajectory. This modernization prioritizes enhanced energy grid resiliency and local infrastructure readiness.
North America accounts for 27.3% of the global industrial power supply market in 2025. The region's domestic market participants maintain their positions through localized manufacturing densities and regional procurement dynamics. Cross-border trade corridors contribute to market fluidity, enabling the transfer of goods and services across borders.
Emerging market participants indicate a transition towards localized production and nearshoring initiatives, enhancing supply chain regionalization. High-value replacement cycles within established industries create incremental growth vectors, driving demand for advanced power supply solutions. Overall, the market is projected to expand at a CAGR of 6.1% during the forecast period, reaching a market size of USD 5.6 billion by the end of 2033.
The Industrial Power Supply market in Europe is expected to account for 25.0% of the global market in 2025. Factors driving this market include infrastructure modernization and local manufacturing densities. Countries including Germany, France, the UK, Italy, and Spain demonstrate robust demand for various power supply solutions, with industries across these nations increasingly adopting advanced systems to enhance energy efficiency.
Germany stands out due to its strong industrial base, while France demonstrates a growing focus on renewable energy applications. The UK continues to invest heavily in upgrading its energy infrastructure, leading to increased demand for high-quality power supply systems. Italy and Spain, with their expanding industrial sectors, employ power supplies to support manufacturing processes and enhance energy reliability.
The market benefits from localized procurement dynamics, where companies seek to source power supplies closer to their operations. This shift in supply chain strategies aligns with a broader trend in nearshoring initiatives aimed at reducing lead times and enhancing responsiveness to market changes. Regional competitive landscapes highlight the presence of several domestic vendors, creating a collaborative environment that drives innovation and product development within the Industrial Power Supply market.
Challenges including geopolitical fragmentation and evolving regulatory frameworks continue to shape market dynamics. Nevertheless, strategic entry barriers and foreign direct investment (FDI) flows indicate a resilient market poised for growth. With increasing adoption of advanced technologies and a focus on energy efficiency, the Industrial Power Supply market in Europe is anticipated to expand significantly through the forecast period.
The Asia-Pacific region, accounting for 39.0% of the global Industrial Power Supply market in 2025, exhibits significant growth potential driven by rapid industrialization and increasing energy demands. Countries including China and India serve because primary demand drivers, with substantial investments in infrastructure modernization and energy generation projects. The need for reliable power supply systems across various sectors, including manufacturing and utilities, fuels ongoing market expansion.
Emerging market front-runners in the region, particularly Southeast Asia, exhibit high growth rates in power supply adoption, supported by government initiatives and foreign direct investment. Localized manufacturing densities enhance production capabilities, aligning with increasing demand for customized power solutions. Cultural nuances influence B2B buying behaviors, prompting suppliers to adapt their offerings to meet regional expectations.
Energy grid resiliency remains a critical factor, especially in areas undergoing significant upgrades to their infrastructure. This ongoing modernization presents valuable replacement cycles, driving the transition from outdated systems to advanced power supply technologies. Competitive dynamics in the market reflect consolidation trends among domestic players, resulting in improved service offerings and enhanced operational efficiencies.
Strategic entry barriers exist, including regulatory frameworks and compliance mandates that vary across countries. These factors shape the competitive landscape, influencing how vendors approach market entry and expansion. Overall, the Asia-Pacific region demonstrates a strong trajectory for growth within the Industrial Power Supply market, driven by diverse economic factors and strategic initiatives aimed at enhancing energy reliability and efficiency.
The Industrial Power Supply market in South America reflects a developing landscape with significant potential. Brazil and Argentina represent the primary markets in the region, with a projected market share of 3.4% of the global total by 2025. Infrastructure modernization efforts in these countries contribute to increased demand for power supply solutions, particularly in sectors including power generation and utilities.
Localized manufacturing densities and regional procurement dynamics influence market growth. Companies focus on adapting their offerings to meet specific regional requirements, including compliance with local regulations and energy efficiency standards. Political and economic factors within South America create challenges and opportunities for market players, emphasizing the need for strategic entry barriers and foreign direct investment flows.
Ongoing industrial activities and emerging market front-runners drive demand for industrial power supplies in South America. The market's growth trajectory benefits from incremental growth vectors and high-value replacement cycles across various segments.
The Industrial Power Supply market in the Middle East and Africa presents unique opportunities driven by ongoing infrastructure modernization and regional energy demands. Countries including Saudi Arabia, UAE, and South Africa are investing in energy grid resiliency and enhancing local infrastructure readiness, which directly influences the adoption of advanced power supply solutions.
In this region, cultural nuances and specific B2B buying behaviors shape procurement strategies, leading to localized demand patterns. The market benefits from domestic players who understand regional challenges and tailor offerings accordingly. Enhanced competitive dynamics emerge because local vendors consolidate to strengthen their market presence.
Regulatory frameworks and compliance mandates in the Middle East and Africa require adherence to local standards, influencing overall market growth. The share of the global market in 2025 for this region indicates potential for future expansion because the market adapts to evolving geopolitical landscapes and local demands.
Emerging markets within this region highlight the potential for growth, particularly in underpenetrated territories. Strategic entry barriers and foreign direct investment flows into the market further support the establishment of localized manufacturing densities, promoting sustainable development.
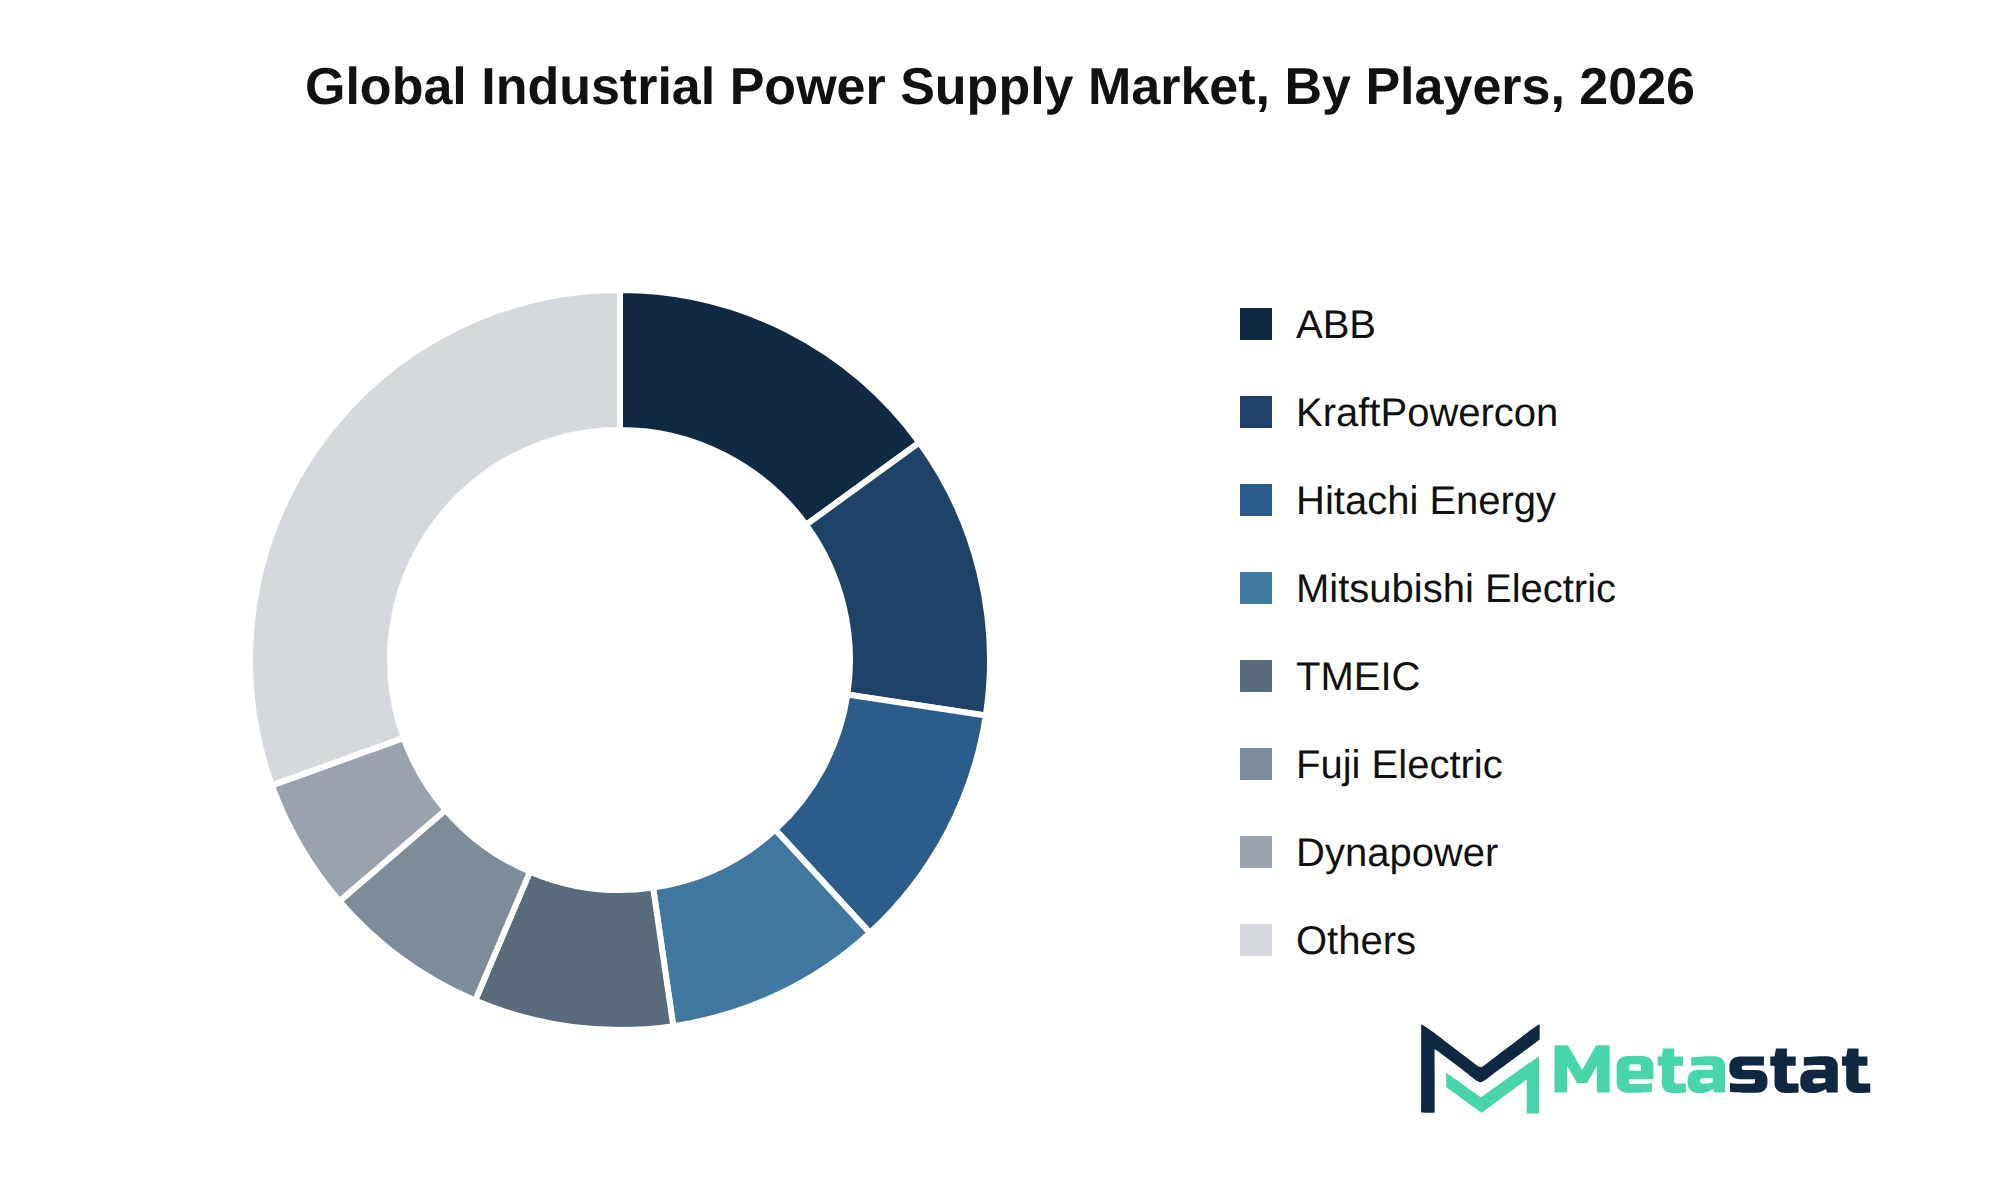
The Industrial Power Supply market features a dynamic competitive environment shaped by strategic consolidations and product differentiation efforts. Companies including ABB Ltd, Siemens AG, and Schneider Electric SE emphasize innovation through robust R&D pipelines, developing proprietary technologies that enhance their market positions.
Strategic alliances and cross-industry partnerships enhance supply chain dominance and procurement leverage. Players like Hitachi Energy Ltd and TMEIC Corporation engage in partnerships to optimize their product offerings and expand market reach. This collaboration drives customer retention strategies and reinforces brand equity within the market.
Barriers to entry remain significant due to established players’ intellectual property portfolios, which provide technological defensibility against new entrants. Companies including KraftPowercon and Fuji Electric Co., Ltd continue to fortify their positions, emphasizing value chain integration and strategic growth vectors to capture expanding market opportunities.
The future competitive outlook for the Industrial Power Supply market projects ongoing strategic behavior among existing players, focusing on innovation and market responsiveness. This environment encourages firms to prioritize operational excellence while navigating evolving customer needs and demands.
Market size is projected to rise from USD 13.5 billion in 2025 to over USD 21.7 billion by 2033. The base case anticipates growth at a compound annual growth rate (CAGR) of 6.1%, reflecting strong demand across various industrial segments driven by increased automation and the need for reliable power solutions.
The bull case envisions heightened investments in next-generation technologies and infrastructure, driving accelerated adoption of industrial power supply solutions. Enhanced R&D commercialization timelines will likely introduce innovative products, aligning with evolving enterprise needs and regulatory compliance mandates, thereby supporting market expansion.
In contrast, the bear case considers potential disruptions from geopolitical realignments and global supply chain shifts. Economic cycles and structural consumption changes could negatively impact demand, potentially slowing growth in the market. Strategic capital allocation remains critical for navigating these challenges and identifying high-growth pockets in the industrial power supply market.
Overall, the market environment presents both challenges and opportunities, highlighting the importance of defensibility roadmaps and future growth recommendations for stakeholders in this sector.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Industrial Power Supply market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 6.1% from 2026 to 2033 |
Revenue Unit | USD billion |
Segmentation | By Power Supply Type, Output Power, Phase, End-Use Industry, and Region |
By Region | North America (By Power Supply Type, Output Power, Phase, End-Use Industry, and Country)
|
Europe (By Power Supply Type, Output Power, Phase, End-Use Industry, and Country)
| |
Asia Pacific (By Power Supply Type, Output Power, Phase, End-Use Industry, and Country)
| |
South America (By Power Supply Type, Output Power, Phase, End-Use Industry, and Country)
| |
Middle East and Africa (By Power Supply Type, Output Power, Phase, End-Use Industry, and Country)
|
Find answers to common questions about this report
The Industrial Power Supply market size was valued at USD 13.5 billion in 2025.
The Industrial Power Supply market is projected to grow at a CAGR of 6.1% during the forecast period from 2026 to 2033.
The North America Industrial Power Supply market size is estimated to reach USD 5.6 billion by 2033.
The segment leading the Industrial Power Supply market is AC-DC Power Supplies & Rectifier Systems, with a projected value of USD 8.6 billion by 2033. This segment's growth reflects its significant demand compared to other power supply types.
Key drivers for the Industrial Power Supply market include significant investments in infrastructure development and advancements in automation and digital technologies. These factors enhance operational efficiency, support renewable energy integration, and create demand for innovative power solutions across various sectors, including manufacturing and utilities.
Regulatory challenges create compliance hurdles that slow adoption and integration in the Industrial Power Supply market. Strict requirements lead to increased operational costs, hindering competition for smaller players. macroeconomic headwinds, including inflation and fluctuating material costs, strain profit margins and limit investment in new technologies, further restricting market growth.
Investment in infrastructure development and advancements in automation favor product adoption in the Industrial Power Supply market. Increased demand for reliable power supply systems across various sectors, combined with the integration of smart technologies, enhances operational efficiency and aligns with sustainability goals, driving growth through 2033.
The Industrial Power Supply market is estimated to reach a valuation of USD 21.7 billion by 2033.
Key players in the Industrial Power Supply market include ABB Ltd, AEG Power Solutions, Fuji Electric Co., Ltd., Hitachi Energy Ltd., Mitsubishi Electric, Schneider Electric SE, Siemens AG, and Delta Electronics, Inc.
The Industrial Power Supply market is projected to grow at a compound annual growth rate (CAGR) of 6.1% from 2026 to 2033.
Choose Your License
Global Industrial Power Supply Market
The analysts below cover Energy and Power research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.
When planning edge sensor rollouts across refinery environments, generic IoT reports typically miss the harsh-environment certification bottlenecks. MetaStat Insight gave an objective evaluation of ATEX and Class 1 Division 2 hardware availability, along with realistic five-year maintenance cycle cost projections. The comparison of wireless mesh versus private cellular backhaul helped our team pressure-test network reliability models for remote processing facilities.
In the biological seed treatment space, registration timelines vary drastically between the European Union, Brazil, and North America. The MetaStat Insight research handled these cross-border regulatory barriers with genuine nuance, mapping commercialization pathways alongside historical field adoption rates. The segmentation between microbial strains and biochemical active ingredients was particularly well structured.
Our team was tracking whether regional recycling infrastructure could realistically absorb the growing volume of lithium iron phosphate batteries over the next decade. The report did a solid job separating announced hydrometallurgical plant capacity from active, permitted operational throughput. That distinction made the feedstock availability projections and regional recovery rate models far more credible than standard commercial overviews.
Explore related market intelligence reports worth reading alongside this one.