
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Luxury Cosmetics Market Size, Share, By Product Type (Skin Care, Hair Care, Makeup, and Others), By Type (Organic and Convectional Products), By Demographics (Women, Men, and Unisex), By Distribution Channel (Department Stores, Specialty Stores (Beauty Boutiques), Online Retail (E-commerce), and Others), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-4077
January 13, 2026
Updated
302 Pages
Report Details
Comprehensive Market Analysis And Insights
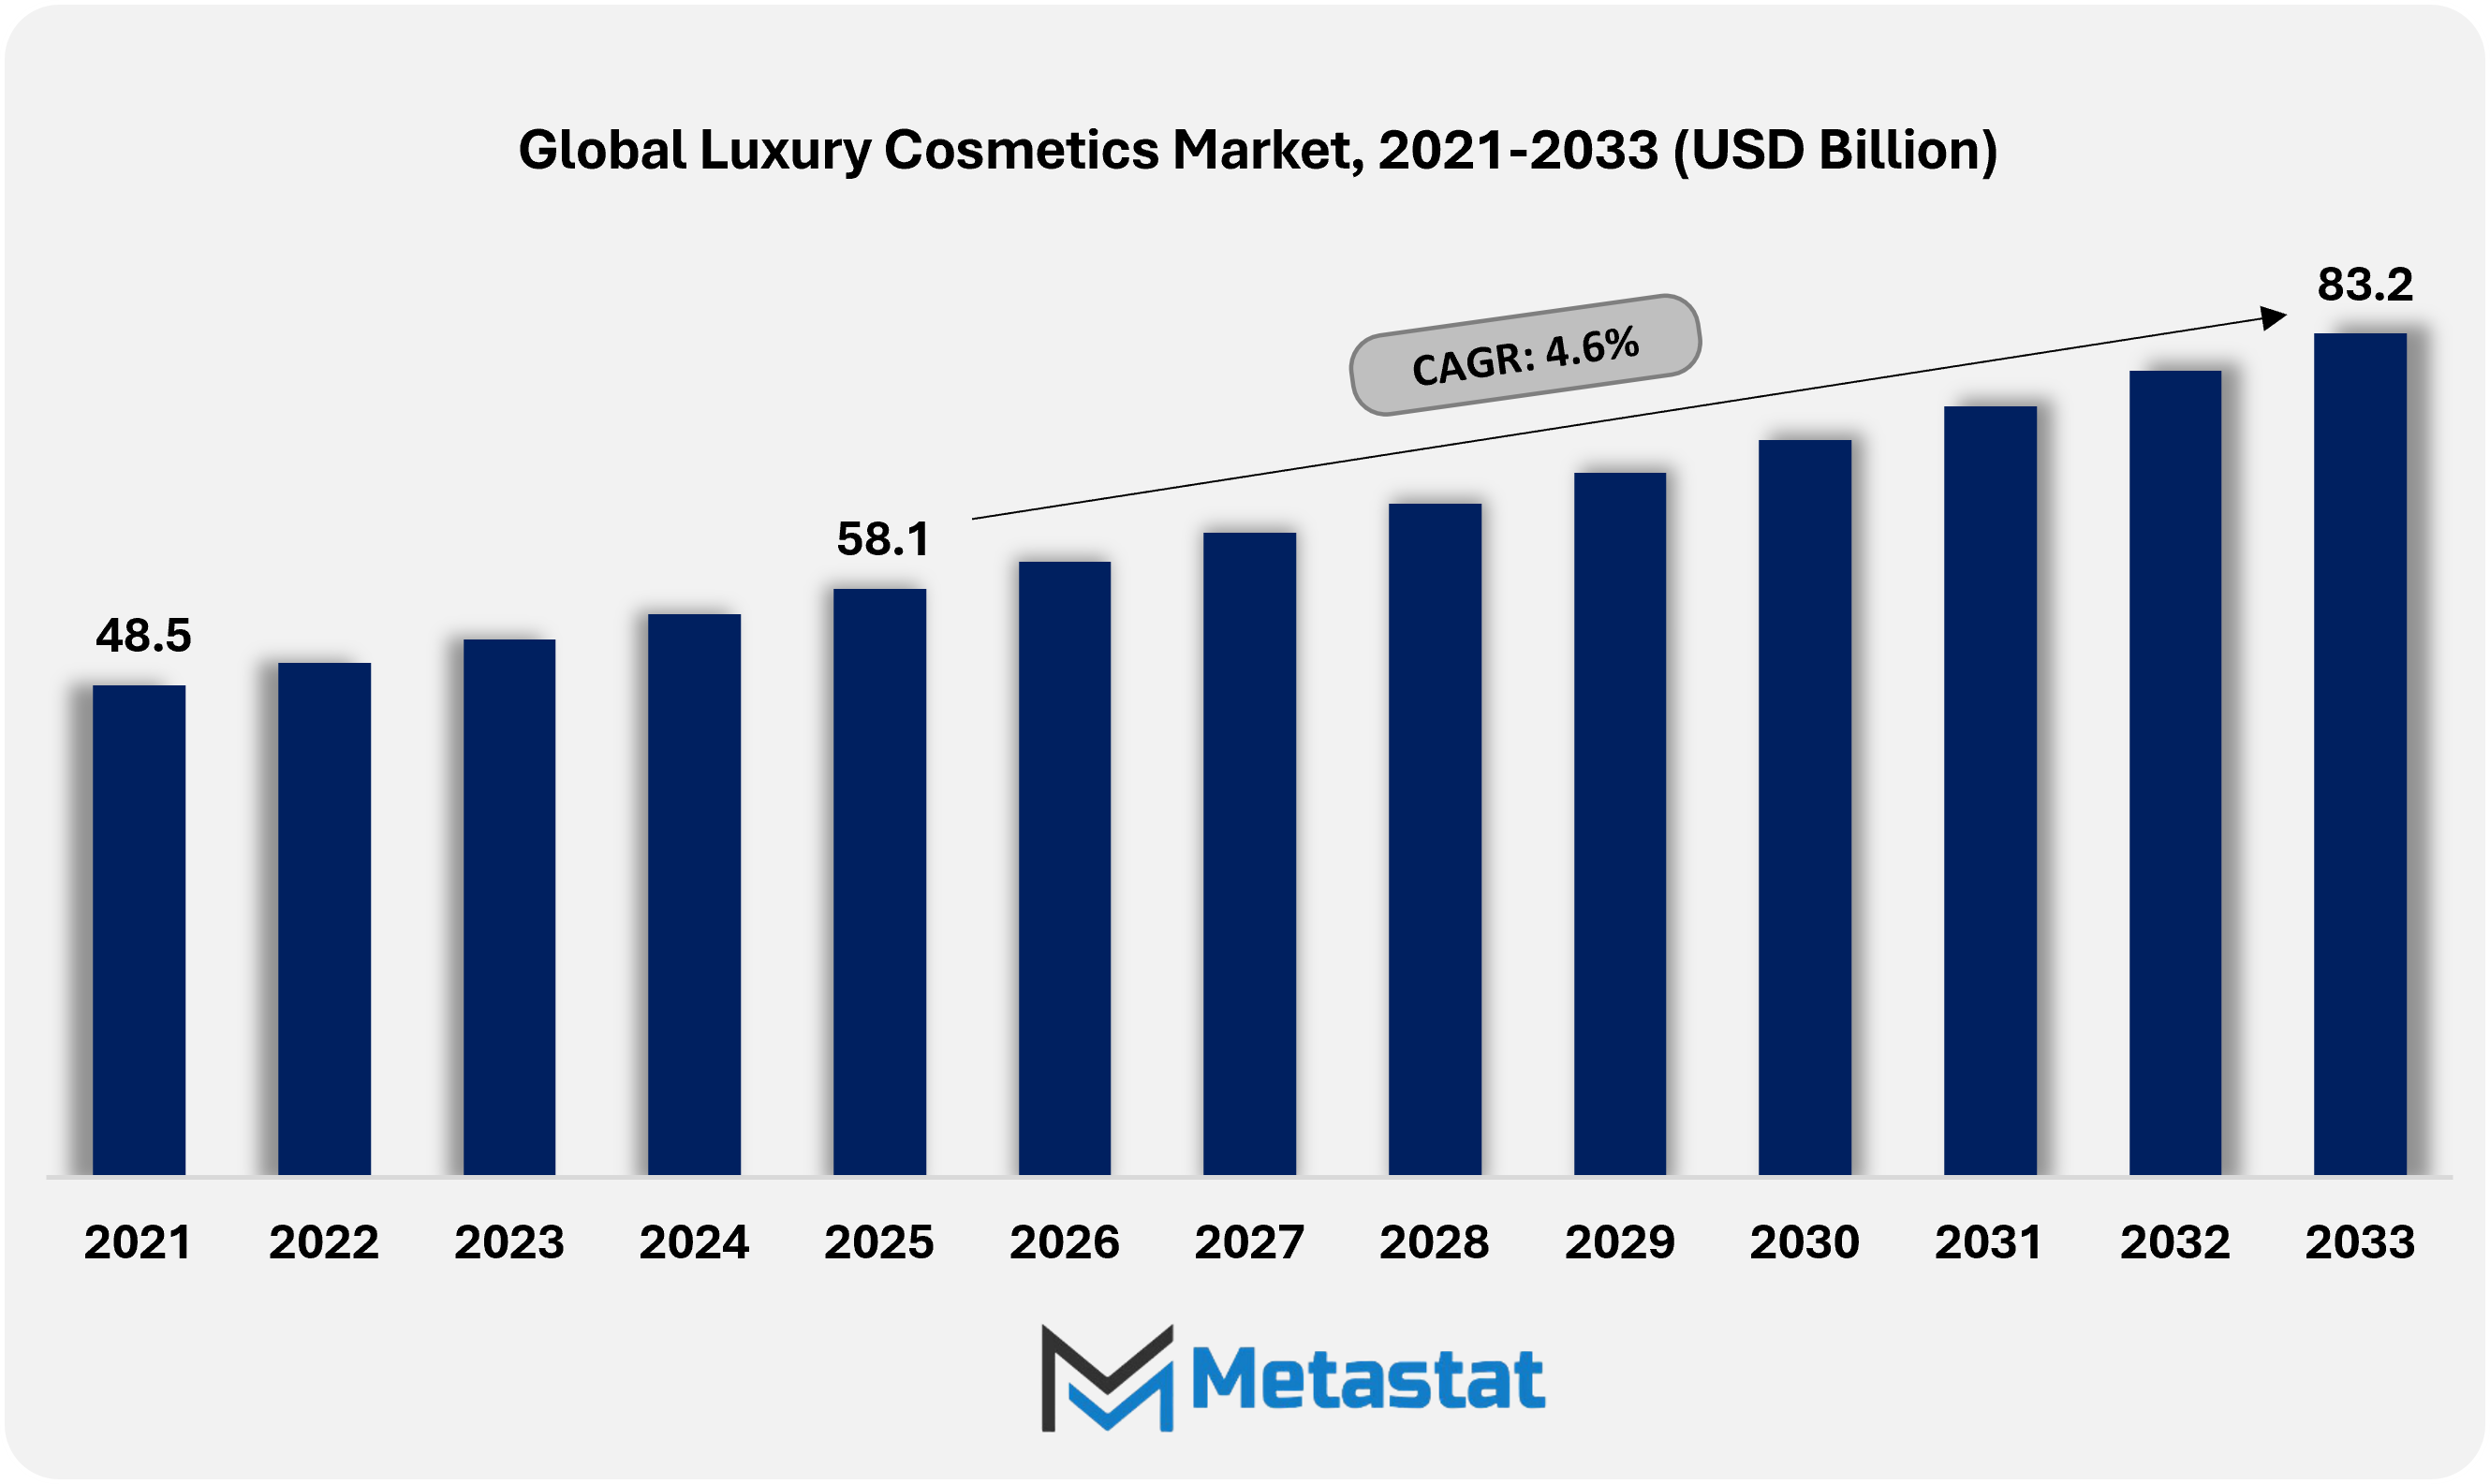
Global Luxury Cosmetics market size was valued at USD 58.1 billion in 2025. The market is projected to grow from USD 60.7 billion in 2026 to USD 83.2 billion by 2033, exhibiting a CAGR of 4.6% during the forecast period.
The global luxury cosmetics market is predicted to interrupt unfastened from traditional norms, dictating a future wherein innovation and class converge in approaches now not but visible. This marketplace will now not be restricted to high-stop packaging and emblem picture; it's going to look to create studies that marry exclusivity with a experience of purpose. As customers are seeking for out merchandise that communicate to their specialty in greater numbers, the luxurious cosmetics marketplace can be all approximately personalization on a scale that become as soon as unimaginable. Luxury splendor can be not most effective approximately looks but approximately identity, in order that each buy is an confirmation, not a transaction.
Technology might be a figuring out thing in where this marketplace is headed. More state-of-the-art solutions like AI-primarily based skincare advice and virtual make-up checks will become the norm, permitting brands to offer rather customized stories inside the comfort of one's personal home. This new movement could be one wherein convenience and customization move hand in hand with out sacrificing what luxury is all about. Aside from the seduction of luxury, there will be a deeper story of efficacy and innovation that will resonate with an audience of today looking for value in exclusivity.
Sustainability will also be an integral component of this future. Luxury beauty will not be viewed as hedonism at someone else's expense. Rather, it will take the lead in responsible sourcing, environmentally friendly packaging, and open supply chains. This transition will not be handled as a marketing strategy but as a necessary platform for brand trust. The new luxury will honor eco-awareness in addition to sophistication, with high-end beauty set in accordance with moral principles.
Cultural impact will continue to redefine the limits of this market. Globalization will introduce consumers to varied beauty customs and prompt brands to weave multicultural nuances into their products. From formulations derived from ancient rituals to packaging inspired by international artistry, high-end cosmetics will be telling borderless stories. This narrative way of thinking will turn products into symbols of heritage and refinement, resonating with consumers who prize authenticity at least as much as they prize extravagance.
Experiential retail will also change dramatically. Physical boutiques will no longer exist as just points of sale; instead, they will become destinations for immersion where art, technology, and beauty overlap. Consumers will enter spaces that are set up to stimulate the senses so that they can connect with products on a more emotional basis. This experiential cognizance will create a new trendy for what luxury looks like in cosmetics.
As the global luxury cosmetics market evolves, it's going to reinvent itself by way of combining artistry, innovation, sustainability, and personalization. The enterprise will now not just reply to call for; it'll encourage aspiration, determining how clients think about beauty in an international in which luxurious is as a great deal revel in and an ethic as it is an aesthetic.
The Luxury Beauty Market, also referred to as the Luxury Cosmetic Market, covers premium-priced beauty and personal care products positioned around brand heritage, high-performance formulations, and elevated consumer experience. In industry usage, the Luxury Beauty Market and Luxury Cosmetic Market are used interchangeably to denote prestige segments across skincare, makeup, fragrance, and haircare sold through selective retail and brand-owned channels.
The global luxury cosmetics market is undergoing swift transformations, driven by economic patterns and consumer trends. Perhaps the most robust growth driver is increased disposable incomes in most regions. With greater profits, people are satisfied to spend on high give up beauty merchandise which might be exclusive and of higher high-quality. Consumers are not looking for ordinary products; they are searching for something special and costly, which has contributed to excessive-quit logo call for. The other key motive force is the upward thrust in interest for bespoke cosmetics. Customers nowadays choose merchandise customs designed for his or her skin type, tone, and fashion. This power towards exclusivity has created customization as a key aspect of luxurious splendor, fueling innovation and allowing manufacturers to differentiate themselves within a crowded sector.
Even with these possibilities, there are significant limitations in the market. Most immediately, there is the prohibitively high cost of luxury cosmetics, which keeps them out of reach of the mass market. They are aspirational to most consumers, but they are still out of reach on affordability grounds, particularly in growth economies where incomes are still on the rise. A second challenge is ingredient and animal testing restrictions. Adherence to these policies is time-consuming and calls for significant funding, which undermines new product launches. Brands want to discover a balance between innovation and compliance with safety and moral requirements, which makes the development procedure more complex.
There are, alternatively, exciting possibilities so as to maintain dictating the shape of this industry. E-trade has created new avenues for luxurious cosmetic manufacturers to faucet into, enabling them to promote their merchandise to customers across the globe without the confines of physical retailers. Online channels simplify the presentation of excessive-stop products and offer a personalized shopping experience that is appealing to ultra-modern tech-conscious and convenience-orientated clients. Moreover, with the increasing fashion in the direction of sustainability and cruelty-unfastened merchandise, purchasers consider a logo's environmental responsibility earlier than shopping. Firms adopting green packaging, moral sourcing, and cruelty-loose trying out can be at a bonus in attractive to conscious purchasers.
In general, the global luxury cosmetics market is heading in the direction of a future in which personalization, sustainability, and connectivity may be instrumental. Although high expenses and regulatory challenges pose obstacles, opportunities afforded by evolving patron values and advances in technology will generate strong boom possibilities. Those manufacturers that evolve in those guidelines will no longer simply benefit client loyalty but additionally redefine luxurious in beauty.
The Premium Skincare Market continues to expand within luxury cosmetics, propelled by performance-led innovation, elevated brand equity, and higher consumer spending on high-efficacy routines. The Premium Skincare Market is increasingly shaped by derm-grade positioning, clinically recognised actives, barrier-repair formulations, and premium anti-aging regimens that support visible results and long-term skin health. In the Premium Skincare Market, product differentiation is strengthening through advanced delivery systems, refined sensorial textures, refillable luxury packaging, and curated multi-step routines spanning serums, eye care, moisturisers, and daily SPF. Omnichannel execution also reinforces the Premium Skincare Market, with prestige retail driving discovery while brand e-commerce and social commerce accelerate education-led conversion and replenishment. Looking ahead, the Premium Skincare Market is expected to remain a core growth engine for premium beauty, supported by science-backed claims, personalised skincare journeys, and sustained premiumisation across global luxury consumers.
Luxury cosmetic manufacturers face notable margin pressures arising from volatile raw material costs, specialized packaging glass shortages, and elevated global logistics expenses. Concurrently, the pervasive proliferation of sophisticated counterfeit cosmetics across gray-market digital storefronts poses severe threats to brand equity, intellectual property, and end-user safety. Protecting distribution integrity requires constant capital deployment toward anti-counterfeit serial packaging, blockchain verification, and aggressive brand-protection legal operations.
Uncertain macroeconomic conditions, high living costs, and fluctuating consumer confidence test the resilience of premium cosmetics pricing. While the affluent consumer base provides stability, aspirational shoppers—who fuel entry-level prestige volumes—exhibit greater price sensitivity. Brands that implement excessive price increases without visible improvements in product performance risk alienating aspirational buyers to high-performing mass-prestige alternatives.
The luxury cosmetics market experienced substantial realignment through major licensing agreements and brand acquisitions. Conglomerates moved aggressively to secure heritage luxury licenses and scale specialized prestige houses. L'Oréal Luxe strengthened its ultra-premium fragrance and beauty footprint through landmark licensing developments, reinforcing its focus on high-margin artisanal segments. Concurrently, Coty Inc. renewed key multi-decade prestige partnerships while actively expanding its high-end skincare offerings to diversify beyond fragrance. These portfolio moves highlight an industry-wide pivot toward high-retention beauty categories with proven margin stability.
Product innovation shifted firmly toward bioscience, advanced molecular biology, and regenerative beauty. Luxury beauty houses replaced conventional synthetic emollients with bio-fermented actives, biomimetic peptides, and cellular longevity complexes. Prestige skincare portfolios integrated targeted delivery mechanisms such as encapsulation and liposome systems to substantiate high price tags. The convergence of clinical dermatology and luxury positioning proved essential as discerning consumers demanded verifiable efficacy rather than purely aesthetic or status-driven propositions.
Artificial intelligence transitioned from an experimental marketing tool into an operational foundation across the prestige beauty sector. Brands accelerated investments in proprietary skin diagnostic tools, hyper-personalized shade-matching engines, and augmented reality virtual try-ons. These interactive platforms elevated remote consultation standards, reduced product return rates in digital retail channels, and gave prestige houses direct access to granular consumer biometric data.
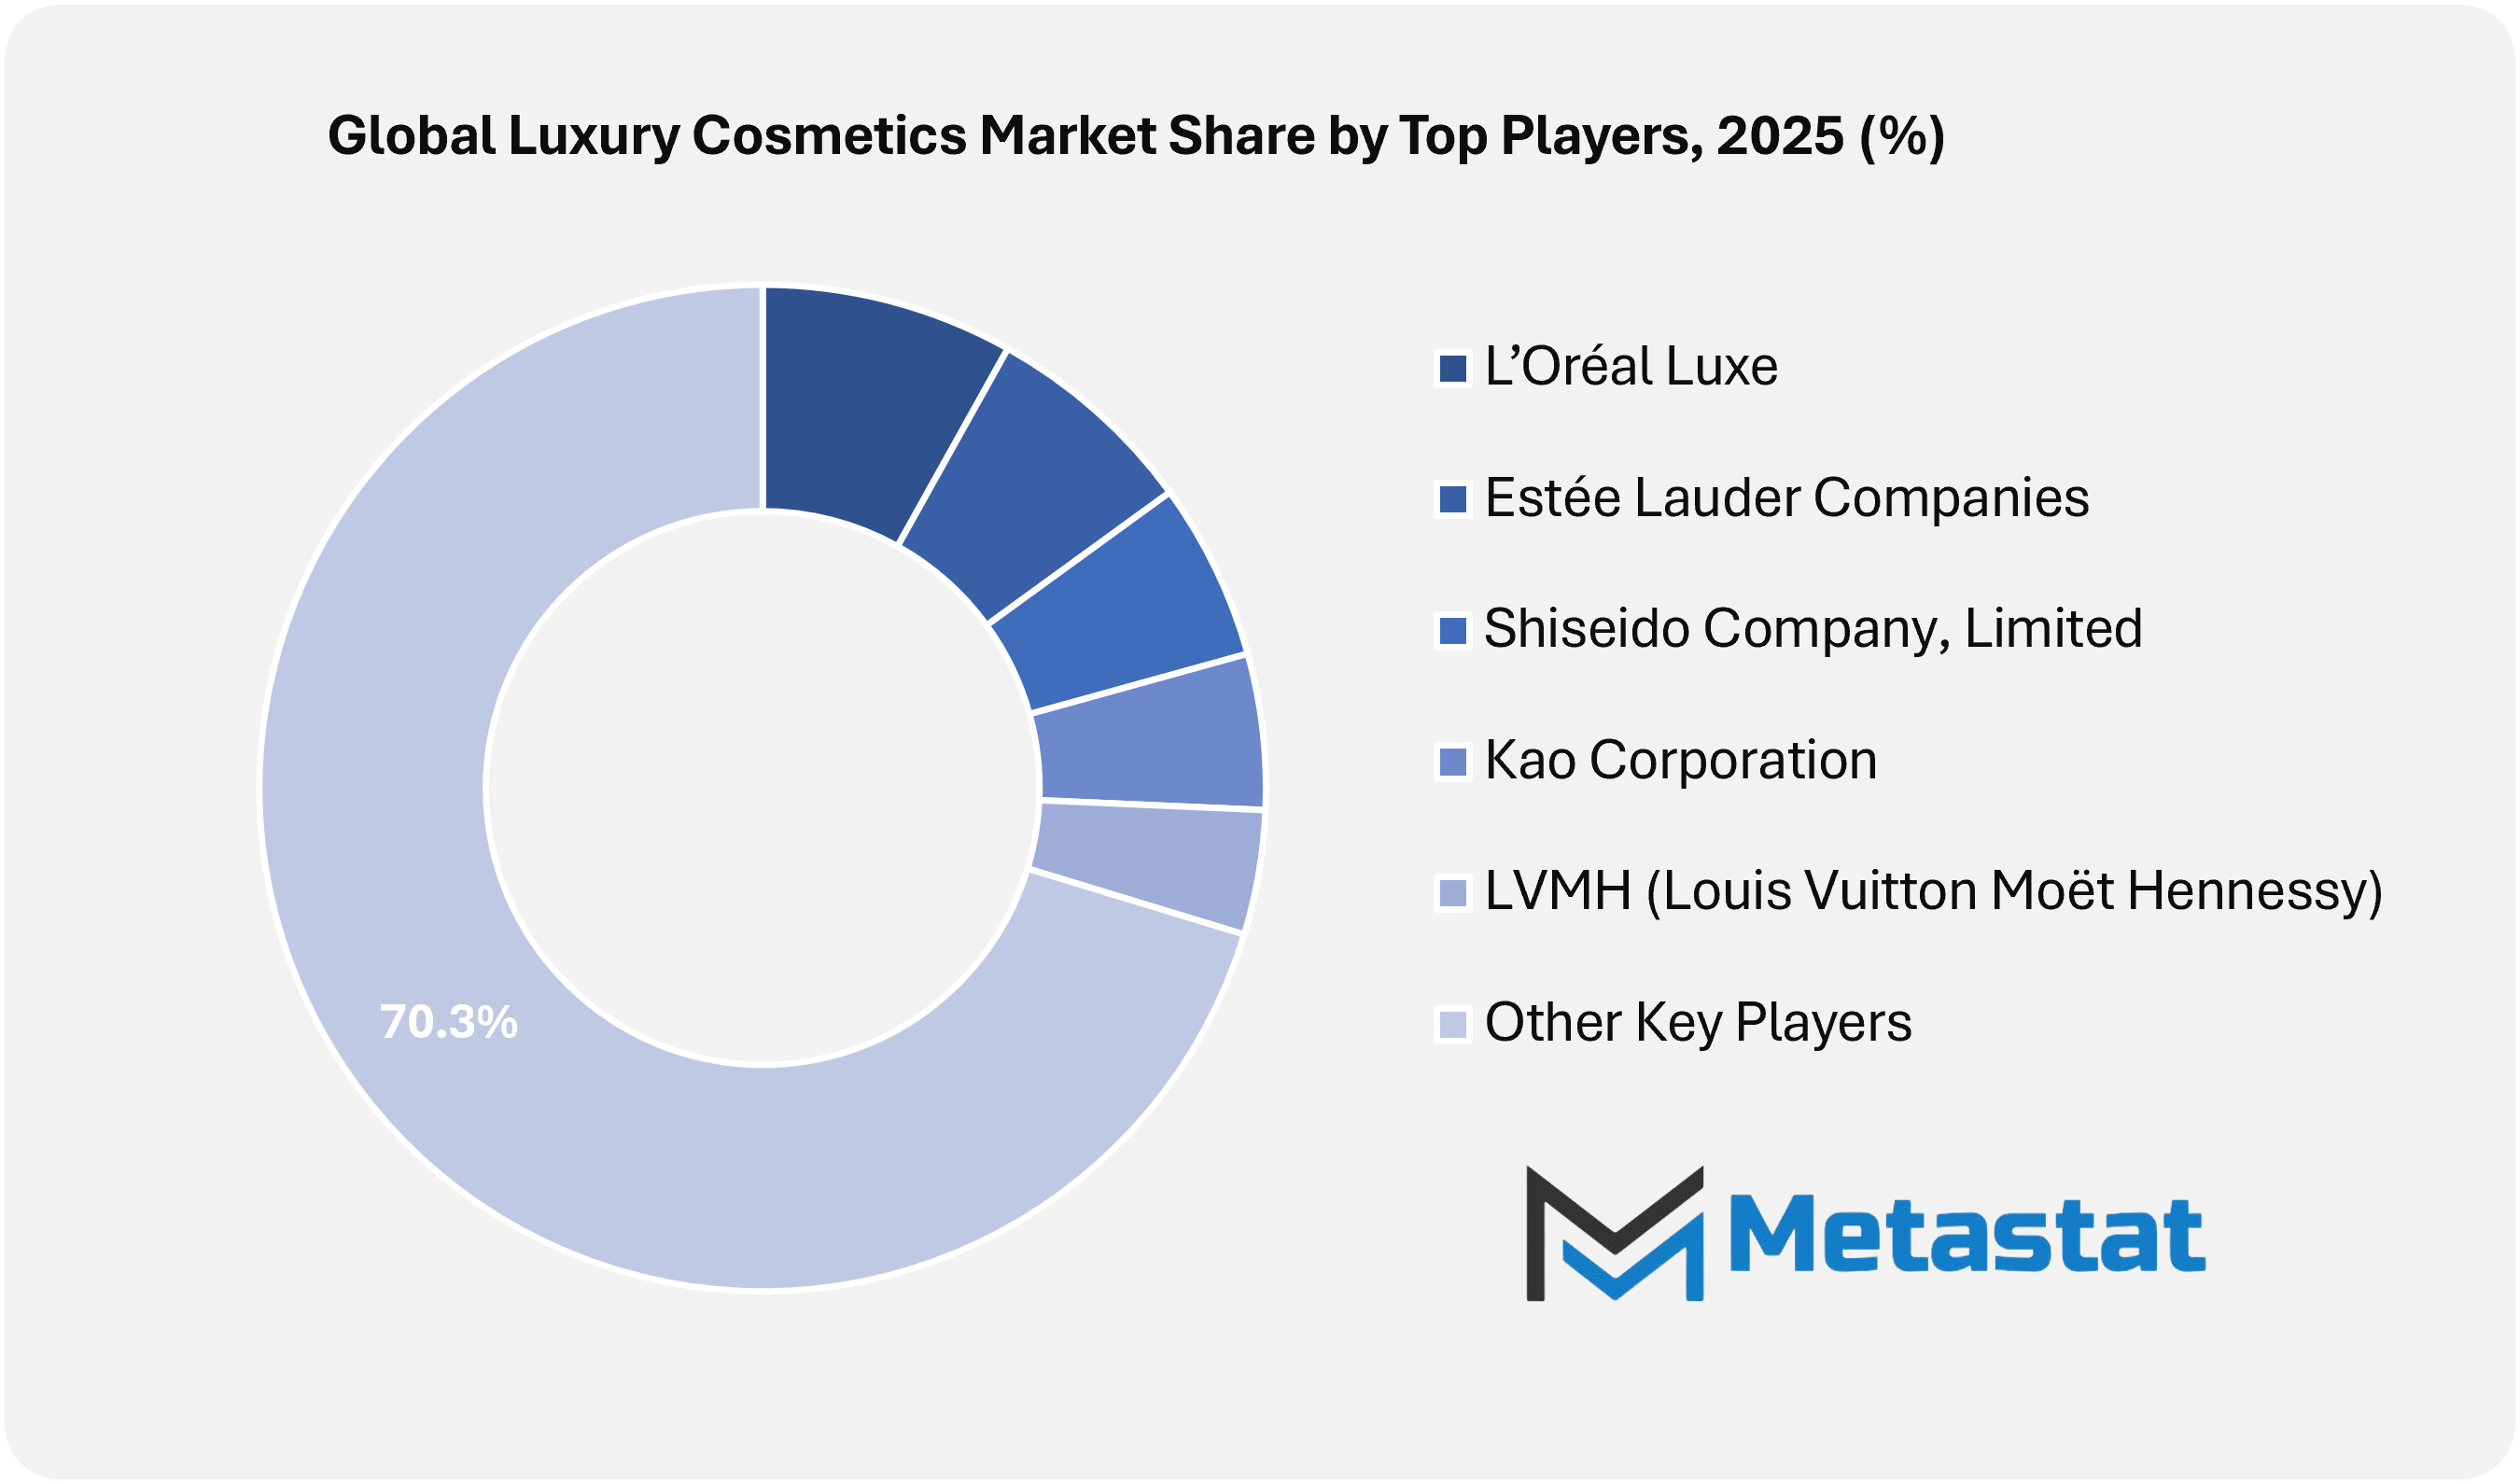
A concentrated group of multinational corporations defines the upper tiers of prestige cosmetics. L'Oréal Luxe and Estée Lauder Companies anchor significant global market share across luxury skincare, makeup, and fragrance. L'Oréal Luxe leverages its balanced global distribution, extensive consumer health science footprint, and elite licensed portfolio to protect its leading competitive position. Estée Lauder Companies maintains a massive international presence driven by iconic heritage brands and selective acquisitions, focusing heavily on clinical luxury and travel retail.
LVMH (Moët Hennessy Louis Vuitton) drives substantial competitive influence through its dedicated perfumes and cosmetics division, uniting historic couture maisons such as Christian Dior and Guerlain with modern disruptors like Fenty Beauty. Chanel remains a formidable independent force, strictly controlling its distribution architecture, pricing power, and brand equity to preserve an air of exclusivity. Shiseido combines Japanese precision technology with premium aesthetics, concentrating on premium skincare science across key Asian and Western markets. Coty Inc. continues its prestige turnaround by scaling high-fashion beauty licenses, while Procter & Gamble Prestige addresses targeted luxury niches through selective, science-backed skincare lines.
Independent clean beauty brands and direct-to-consumer innovators consistently pressure legacy market incumbents. Agile challenger labels capture younger consumer segments by showcasing pure ingredient provenance, certified ethical credentials, and modern aesthetic packaging. While traditional conglomerates retain market volume, independent innovators continue to dictate product narratives, often becoming prime targets for strategic acquisitions by legacy conglomerates.
The clean beauty movement has decisively expanded beyond indie niche channels to reshape product development across global luxury portfolios. Discerning luxury consumers increasingly expect absolute ingredient transparency, excluding controversial silicones, parabens, phthalates, and synthetic musks. Formulators are tasked with matching the sensory richness, stability, and velvet glide of legacy formulations using certified clean, non-toxic, and bio-derived raw materials.
Sustainable packaging has become an essential baseline for luxury tier branding. Legacy beauty consumers no longer tolerate disposable single-use plastic, prompting luxury houses to engineer weighted, decorative aluminum and glass cases designed for lifelong refillability. Moreover, independent cruelty-free certification and ethical supply chain audits are mandatory trust markers, especially among younger luxury buyers seeking alignment between aesthetic indulgence and social responsibility.
The digital acceleration of prestige cosmetics has transformed traditional distribution hierarchies. While tactile counter interactions remain vital for sensory discovery, luxury e-commerce has evolved from a transactional tool into an elevated brand immersion environment. Multi-brand luxury platforms such as Net-a-Porter have established curated beauty portals that sit alongside haute couture, introducing luxury cosmetics to high-net-worth fashion shoppers.
DTC (direct-to-consumer) brands and brand-owned flagship websites have redefined customer acquisition and retention strategies. By managing proprietary online channels, prestige beauty companies maintain absolute control over pricing, brand storytelling, and user experience. Brand-owned digital storefronts facilitate exclusive sample discovery sets, personalized loyalty programs, and high-touch concierge services that recreate boutique white-glove hospitality online.
Compelling capital deployment opportunities exist within high-performance longevity skincare and niche luxury fragrances. The global convergence of preventative health, regenerative medicine, and cosmetic science drives premium demand for cellular-repair formulations. In fragrance, bespoke artisanal perfumes characterized by rare extraction profiles, gender-neutral positioning, and rich narrative heritage continue to capture high-margin market share.
For emerging players and prospective investors, entering the luxury cosmetics arena requires focused differentiation rather than broad-spectrum launches. Successful entry strategies focus on addressing verified clinical efficacy gaps, building around clean, ethically certified formulations, or deploying localized digital-first models. Establishing strategic wholesale relationships with prestige beauty retailers like Sephora and Ulta Beauty provides immediate distribution reach and retail authority while direct-to-consumer platforms build high-margin customer retention.
The COVID-19 pandemic severely disrupted physical retail channels, closed department store counters, and halted international travel retail, causing an immediate contraction in decorative cosmetic sales. However, this crisis accelerated a consumer pivot toward personal wellness, skin health, and home-spa self-care. Consumers reallocated disposable income away from occasion-based color makeup toward high-end skincare treatments, nourishing scalp serums, and home aromatics.
The post-pandemic recovery demonstrated the structural resilience of luxury cosmetics, validating the enduring "lipstick effect". As social environments, physical workplaces, and global travel resumed, prestige cosmetics rebounded rapidly across key regions. Consumers re-entered physical beauty halls with renewed enthusiasm for sensory discovery, supporting a balanced omnichannel ecosystem where online convenience and physical retail consultation actively complement one another.
The global luxury cosmetics market will remain to gain interest with its emphasis on high-quality products and the experience they give to customers. The merchandise aren't just about splendor but additionally approximately exclusivity and sophistication. The luxurious brands are seeking to deliver an identity and lifestyle this is extra than capability, and for this reason humans are equipped to pay more. With evolving patron perceptions, the marketplace will similarly recognition on authenticity, craftsmanship, and novel formulations to sustain its recognition.
Among the product classes, skin care has the biggest segment and will remain a strong segment. It is really worth $28,918.19 million, witnessing the growing demand for products that offer advanced advantages like moisturization, anti-ageing, and well-known skin health. Individuals have become increasingly privy to their skin's requirements and are spending on excessive-performance merchandise that produces tangible effects. This section will continue to increase with fresh generation and natural activities, as clients require effective and gentle products.
Hair care items in the luxury class are also on the upward thrust, propelled via the quest for wholesome, brilliant, and nicely-groomed locks. Today's clients seek high-cease shampoos, conditioners, and treatments for addressing precise issues along with dryness, frizz, or shade safety. Rare oils, botanical extracts, and specialized remedies will continue to outline luxurious hair care from mainstream merchandise. Makeup is a declaration class inside the luxury facet of cosmetics. It is not only approximately color but texture, end, and skin compatibility. Consumers preference cosmetics that carry out their exceptional products without compromising consolation and wear.
Fragrances and body care products are also expected to drive the development of the global luxury cosmetics market. These products are usually regarded as personal treats and emblems of prestige, an introduced size to the luxury way of life. Luxury cosmetics are appealing due to the fact they're capable of emotionally engaging consumers and supplying higher overall performance. As more individuals look for merchandise which might be compatible with their character and values, luxurious cosmetics will in addition consolidate their position within the global marketplace.
Hair Care segment was valued at USD 7.3 Million in 2026 and is projected to reach USD 10.6 Million by 2033, at a CAGR of 5.4% during the forecast period.
The global luxury cosmetics market has developed into the maximum colourful segment of the beauty enterprise, shooting transferring customer behaviors and changing life. Luxury cosmetics are no longer anything extra than symptoms of repute; they're now linked to self-expression, health, and personal care. This alternate in wondering will keep to fuel innovation and the release of excessive-cease products that appeal to a greater aware and discerning set of customers. The growth in disposable earning and an increasing problem with excessive-end splendor solutions have helped gas the developing call for high-cease cosmetics, making the market more aggressive and diverse than ever.
Organic and Conventional Products categorize the market by using kind, every pleasant varying expectancies. Organic luxury skincare is becoming increasingly popular as buyers grow to be more informed about ingredients and how they affect the condition of their skin. These merchandises utilizes natural extracts and environmentally pleasant techniques and appeals to clients who search for sustainability and clean beauty. On the alternative hand, traditional merchandise continues to enjoy a strong presence because of their state-of-the-art formulations, enduring results, and emblem credibility. Although organic variants will make awesome boom in the future, traditional merchandise will maintain keep on markets where overall performance and premium innovation are paramount.
The luxury cosmetics demand also is driven by the aid of the increasing need for exclusivity and customization. Modern consumers need merchandise that no longer handiest enhance looks, however also delivers indulgent enjoy. From state-of-the-art packaging to special formulations, brands are emphasizing the creation of an experience of refinement and strong point. Limited-edition collections and bespoke solutions will be key to acquiring and holding onto high-end customers. This approach makes luxurious cosmetics appealing past practical appeal, making them life-style statements.
As the era proceeds to transform the splendor sector, the global luxury cosmetics market will see more incorporation of online platforms. Virtual attempt-on, AI-powered guidelines, and online consultations will render luxury merchandise more accessible to hundreds throughout the globe without diluting exclusivity. Simultaneously, social media and influencer advertising will increase logo visibility, linking top class products to a international target market. With a robust balance of subculture and innovation, the marketplace will keep growing, putting new benchmarks for nice, safety, and patron revel in.
Organic segment is projected to reach USD 13.1 Million by 2033, at a CAGR of 8.1% during the forecast period.
The global luxury cosmetics market has emerged as a benchmarking fashion inside the beauty and personal care space, providing high-quit products targeted round great, exclusivity, and luxury revel in. While mass-marketplace cosmetics spotlight marketability and affordability, luxurious merchandise spotlight craftsmanship and brilliant elements, which come to be extremely attractive to customers who are searching for status. This sector has received ongoing attention as it signifies not only beauty but also a choice of lifestyle. Individuals buy these products for the confidence and sophistication they instill; hence luxury cosmetics are beyond their mere usefulness.
In demographic market analysis, women have controlled the segment traditionally, and they will account for a large portion of demand. Skincare products, makeup, and female cosmetics command the biggest share, with many seeking products that claim to provide long-term effects and high-quality. This is spurred on by increasing knowledge of grooming, social media influence, and the need to stay young. Women opt to try out a very high range of luxury choices, ranging from niche foundations to premium serums, which stimulates innovation and diversification in the category.
Men are becoming a significant target demographic in the Global Luxury Cosmetics industry. The growing reputation of grooming and skin care products among men has redefined the conventional photograph of cosmetics. High-stop brands have released guys-centric lines with moisturizers, anti-ageing creams, fragrances, and grooming care merchandise. This fashion is driven by means of expanded cognizance about self-care, expert standards of grooming, and the influence of influencers encouraging guys' grooming behavior. As this fashion goes on, luxury cosmetics for guys will come to be a completely beneficial area.
The unisex section is also choosing up steam, in particular among young clients who like gender-free products. This age organization appreciates inclusivity and gravitates in the direction of merchandise that can be utilized by all and sundry, like scents, skincare products, and primary makeup. Unisex luxury splendor merchandise enchantment to individuals who desire simplicity without sacrificing first-rate, which makes this class an rising player in the industry. Since brands will emphasize personalization and environmentally friendly practices, unisex offerings also are predicted to appeal to extra shoppers within the years in advance.
In general, the global luxury cosmetics market is one that mirrors patron tastes and desires which might be transferring as a feature of life-style, self-expression, and individuality. No rely on whether appealing to girls, men, or unisex customers, luxury brands will remain innovation, ethics, and custom experience focused. All of these demographic shifts will affect destiny boom, and this makes this market a colorful and aggressive market for better-cease splendor gadgets.
Men Demographics segment is projected to reach USD 11.8 Million by 2033 with a share of 12% in 2025.
The global luxury cosmetics market will keep increasing as the possibilities of purchasers exchange toward top rate splendor stories and individualized care. Luxury cosmetics are not simply cosmetics; they symbolize satisfactory, exclusivity, and status. Consumers search for merchandise that produces superior outcomes, be it in skincare, makeup, or fragrance. With growing disposable incomes and life, humans are inclined to put money into premium beauty products. The presence of luxury manufacturers on numerous structures makes those products extra handy than ever, attractive to unswerving clients and new buyers who choice a touch of exclusivity.
Department shops are perhaps one of the most traditional techniques of luxurious cosmetics. They had been a favorite purchasing destination for customers that experience having an offline buying enjoy. The purpose is straightforward: they provide a space in which purchasers can attempt out merchandise, engage with beauty specialists, and receive custom designed recommendations. For many excessive-give up consumers, the experiential issue complements the purchase, and branch stores are consequently a critical channel on this class. Yet the channel has struggled in recent years as consumers increasingly seek to use digital media for ease and convenience.
Specialty retail stores, like beauty boutiques, are also a critical sales channel. Beauty and luxury care products are all these stores sell, generating a beauty-centric environment that appeals to passion players. Boutiques usually deliver high-end customer service and special collections not readily available anywhere else. The customized attention and handpicked product line cause them to the cross-to for customers who need a specific and top class enjoy. Their capability to offer emblem-unique reports sets them aside in maintaining dependable customers.
E-trade, or online retail, has revolutionized the manner wherein luxurious cosmetics are bought and sold. Online systems provide unheard of comfort for customers to store, examine, and purchase merchandise from the consolation of their homes. Virtual strive-on features, particular product descriptions, and influencer advertising and marketing have all contributed to more suitable shopping and truthful revel in on the internet. Most of those luxury manufacturers additionally deliver a great deal significance to their internet site, having specific launches and club rewards to entice consumers. This channel will hold developing as era improves the purchasing revel in.
Online Retail (E-commerce) segment is projected to grow at a CAGR of 7.6% during the forecast period.
The other distribution channels, such as multi-brand stores and duty-free stores, also account for the market. These stores tend to target travelers and customers looking for variety within a single shopping area. Although they cannot provide the bespoke experience of boutiques, they give ready access to several luxury brands. All these channels together form a dynamic framework that fuels growth in the global luxury cosmetics market so that customers can access luxury in their most preferred manner.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 4.6% from 2026 to 2033 |
|
Revenue Unit |
USD billion |
|
Segmentation |
By Product Type, Type, Demographics, Distribution Channel, and Region |
|
By Region |
North America (By Product Type, Type, Demographics, Distribution Channel, and Country)
|
|
|
Europe (By Product Type, Type, Demographics, Distribution Channel, and Country)
|
|
|
Asia Pacific (By Product Type, Type, Demographics, Distribution Channel, and Country)
|
|
|
South America (By Product Type, Type, Demographics, Distribution Channel, and Country)
|
|
|
Middle East and Africa (By Product Type, Type, Demographics, Distribution Channel, and Country)
|
The global luxury cosmetics market will go on to experience strong growth as consumer demand moves towards higher-end beauty items. The market will serve customers who are quality-conscious, exclusive, and innovative in the skincare, makeup, and perfume they use. Demand for luxury cosmetics will not just increase in established economies but also across emerging economies where increasing income levels and social status dominate the decision to buy. Premium brands will invest heavily in personalization, sustainability, and technology-led solutions to address these changing expectations.
Geographically, the market will be divided among North America, Europe, Asia-Pacific, South America, and the Middle East & Africa. North America, comprising the U.S., Canada, and Mexico, will retain its strong position because of the presence of well-established luxury brands and a mature customer base that is willing to pay for high-end products. The U.S. will be the leader in the region with dynamic retail and strong consumer influence of celebrities and beauty influencers on buying decisions. Canada and Mexico will also experience steady demand fueled by urbanization and global beauty awareness.
Europe will continue to be another significant contributor, with the UK, Germany, France, Italy, and the Rest of Europe driving growth. The area boasts a strong tradition of luxury beauty and fashion, which will further consolidate the market. France and Italy, where some of the most recognized cosmetic companies are based, will lead the pack with innovation in skin care and perfumes. Germany and the UK will be hot on their heels as they enjoy high purchasing power and a preference for premium and eco-friendly products. The cultural preference for refinement and excellence will ensure that Europe is a consistent market for high-end cosmetics.
Asia-Pacific will experience the most rapid growth, with China, Japan, India, and South Korea at the fore. Growing disposable income, higher global beauty standards awareness, and high demand for luxury items will render the region highly lucrative for companies. Japan and South Korea will continue to hold sway because of their credibility as having the most advanced beauty technology, whereas China and India will experience exponential expansion from the demographic dividend of a young, aspiring consumer population. South America, representing Brazil and Argentina, will demonstrate gradual progress as urban beauty awareness increases. Likewise, Middle East & Africa will offer opportunities, particularly in GCC nations, where affluent consumers will fuel premium beauty product demand. Egypt and South Africa will contribute to growth in the region as luxury items become more affordable.
As a whole, the global luxury cosmetics market will keep on flourishing in these markets based on a combination of tradition, creativity, and consumer desire. Companies that are able to conform to regional tastes while retaining their international draw will be leaders in this extremely competitive industry.
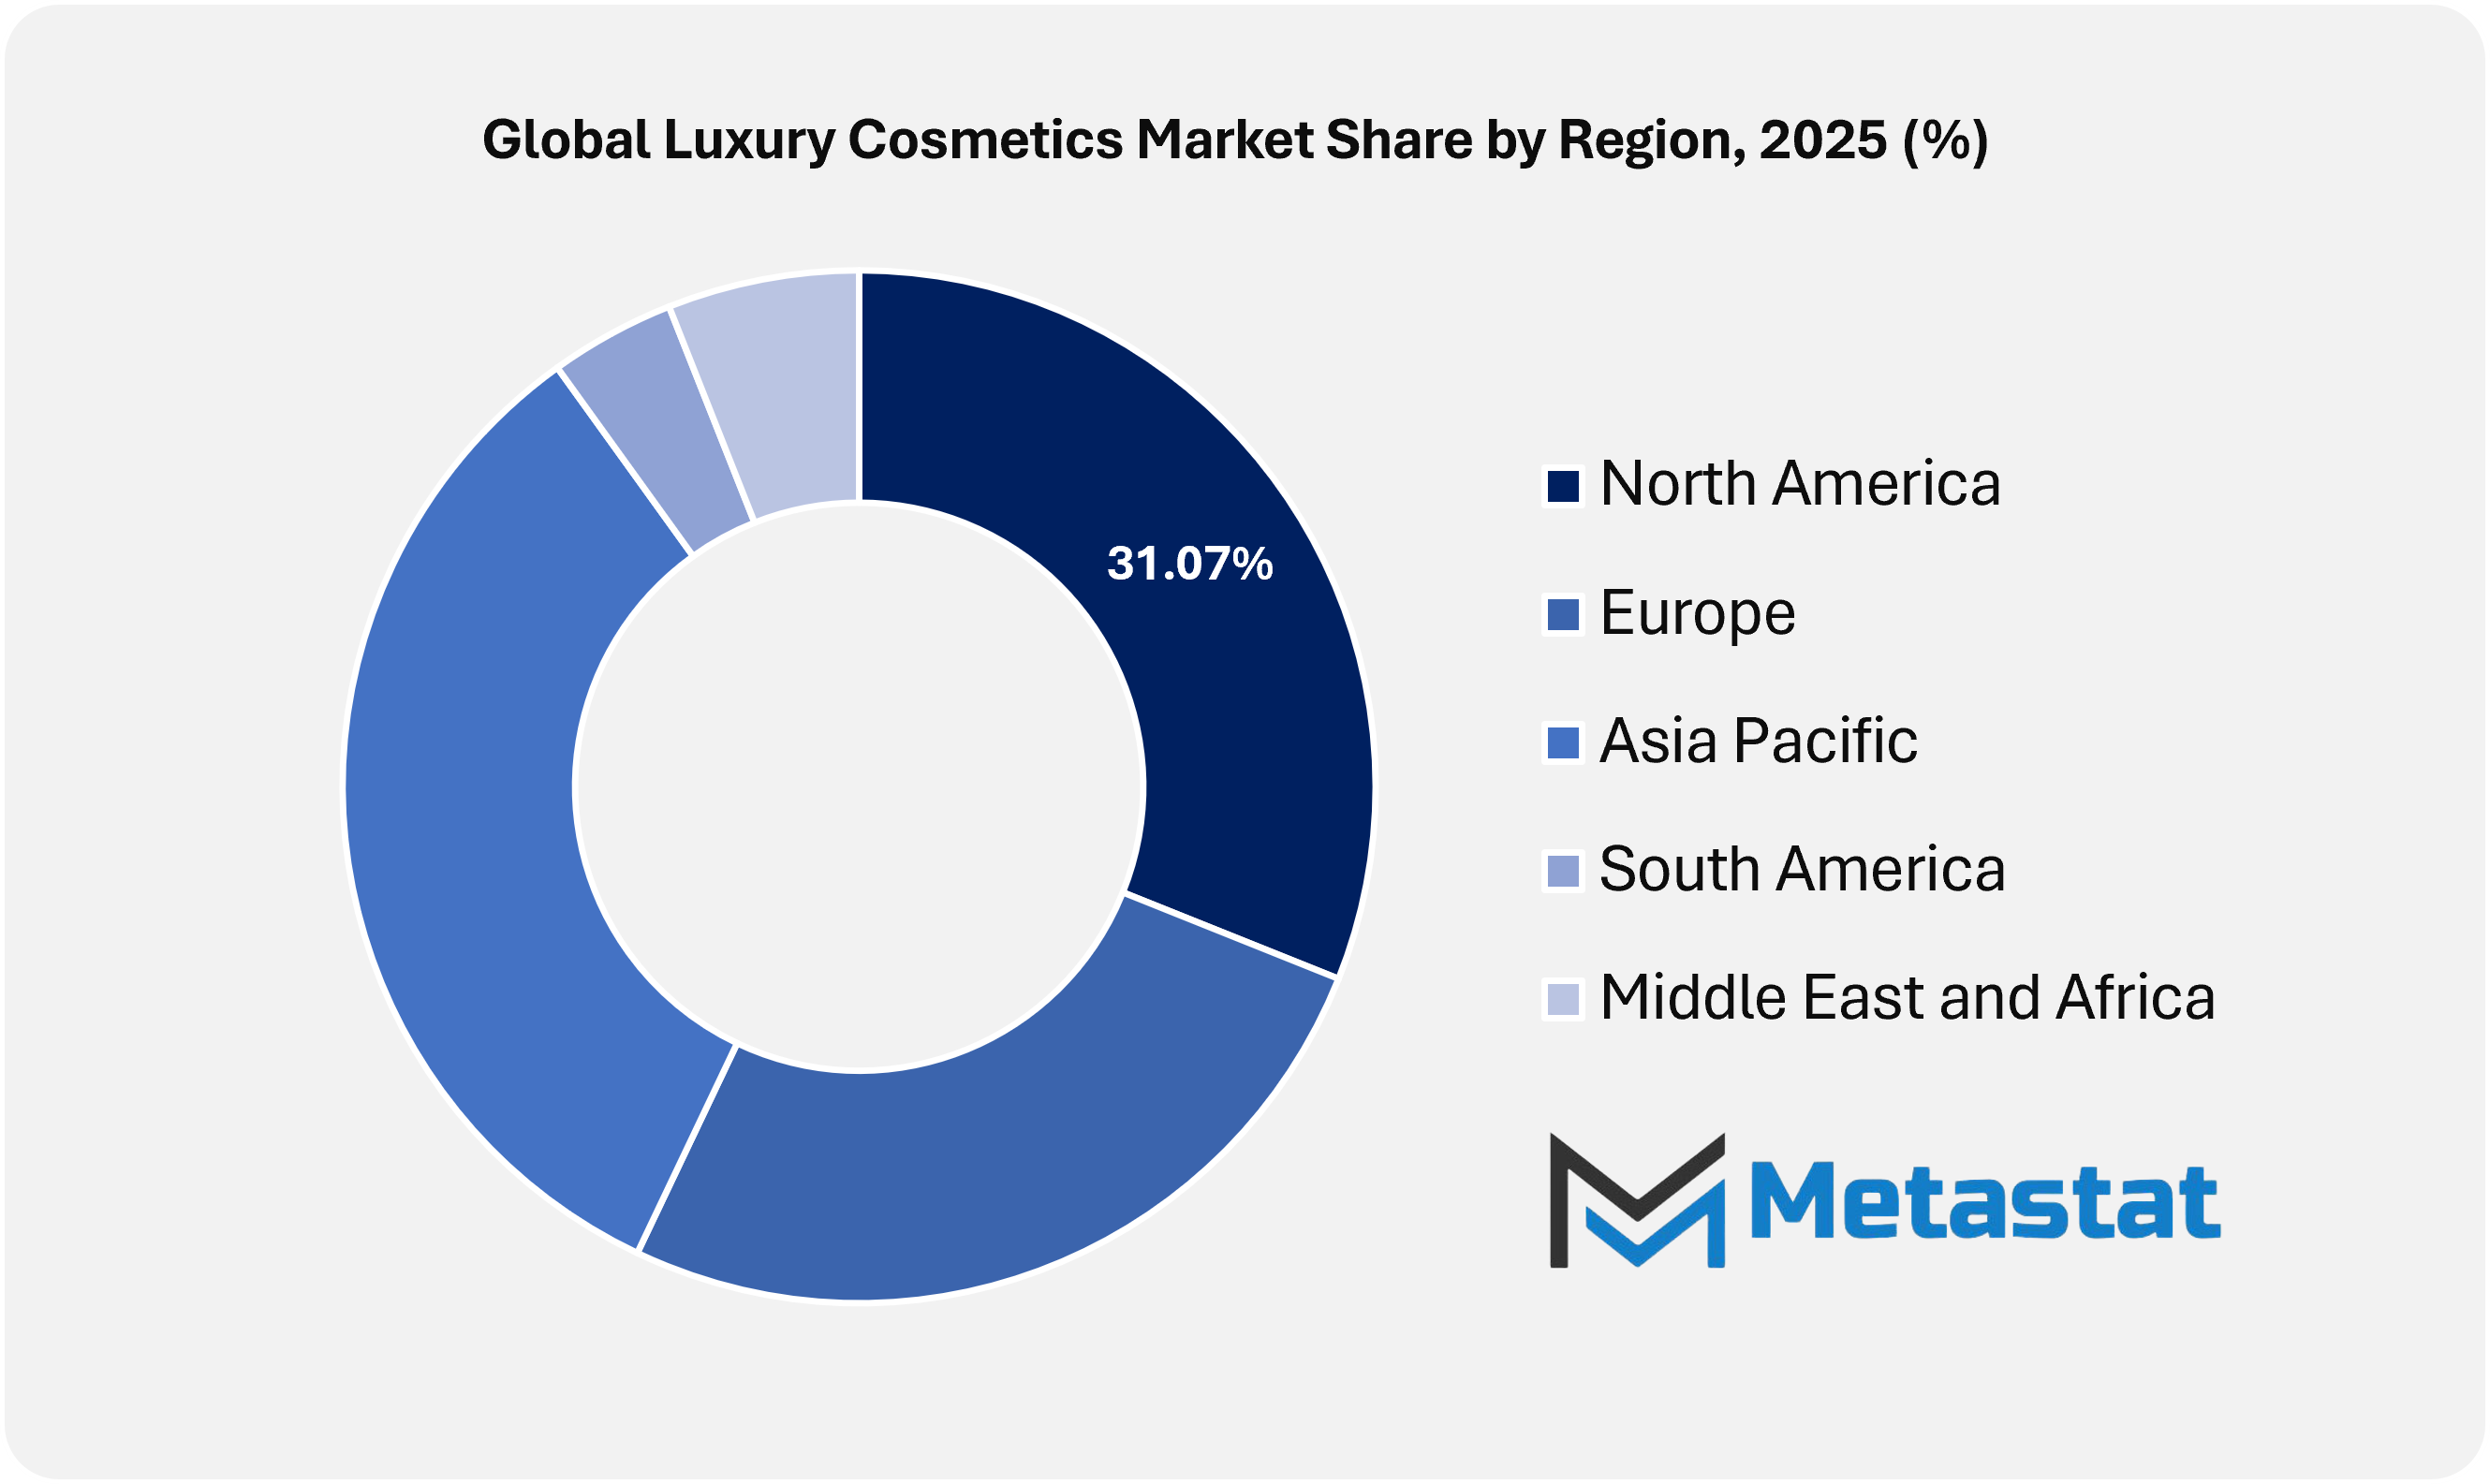
North America represents one of the largest regional markets for prestige cosmetics, underpinned by strong disposable income and high per-capita spending on personal care. The region exhibits a mature omnichannel retail environment where specialized beauty purveyors drive extensive consumer footfall. Sephora and Ulta Beauty serve as critical retail gateways for established luxury brands and emerging prestige labels alike, offering interactive discovery hubs that blend physical testing with digitized loyalty rewards.
Consumer behavior across the United States and Canada increasingly emphasizes hybrid makeup-skincare products and clinical-grade formulations. Modern consumers allocate higher budgets to dermatological prevention, sun protection serums, and complexion barrier repair over traditional decorative cosmetics. This structural demand shift has compelled prestige brands to reformulate color cosmetics with active hydrators, botanicals, and high-performance SPF shields.
Europe holds a premier position in global luxury cosmetics revenue, anchored by iconic beauty capitals in France, Italy, Switzerland, and the United Kingdom. The continent benefits from established manufacturing expertise, centuries-old fragrance heritage, and the operational headquarters of global luxury leaders like Chanel and LVMH. High local purchasing power coupled with constant international tourism inflows sustains continuous demand across department stores, exclusive flagship boutiques, and duty-free travel nodes.
European market dynamics are tightly governed by the European Union’s rigorous Cosmetics Regulation framework. Stricter controls on synthetic preservatives, chemical microplastics, and environmental disclosures require ongoing reformulations from luxury houses. European consumers also demonstrate acute sensitivity to environmental ethics, driving swift regional adoption of refillable vessels, FSC-certified secondary cartons, and certified organic ingredient sourcing.
Asia-Pacific serves as the most dynamic growth engine in the global luxury cosmetics market. The expansion is propelled by rising middle-class affluence, rapid urbanization, and a deep-seated cultural reverence for meticulous skincare rituals. Markets such as South Korea and Japan continue to define global skincare trends through regional aesthetics and cutting-edge texture technologies. The sustained international appeal of K-beauty frameworks has elevated consumer expectations regarding product layering, brightening actives, and soothing plant-based ferments.
China remains a central pillar of regional demand, though consumer spending patterns have matured significantly. Discerning Chinese buyers increasingly evaluate luxury products based on functional efficacy, verified dermatological research, and authentic cultural alignment. Simultaneously, the rapid rise of premium domestic Chinese beauty brands creates genuine competitive pressure on Western heritage houses, forcing international conglomerates to localize marketing campaigns and modernize digital channel distribution.
COMPETITIVE PLAYERS
The global luxury cosmetics market will keep expanding as beauty and personal care become an increasingly significant aspect of lifestyle globally. Consumers are no longer restricting themselves to minimum skincare or makeup; they are gravitating toward high-end solutions that amalgamate quality, selectivity, and experience. This transformation is catalyzed to a large extent by shifting attitudes about beauty, where consumers see it as self-expression and self-care instead of a routine requirement. Premium cosmetics extend beyond performance in the product to deliver sophistication, high-end packaging, and an emotional connection that induces the consumer to feel special. The desire for uniqueness and customization will encourage brands to develop collections that celebrate individuality and authenticity.
High-performing companies are raising the bar through innovation and brand positioning. L'Oréal Luxe, Estée Lauder Companies, and Shiseido Company, Limited will continue to lead with their wide product offerings and global presence. LVMH, through its Dior Beauty and Guerlain brands, continues to merge tradition with contemporary fashions, producing products that are both vintage and cutting-edge in their feel. Chanel International B.V. and Hermès Beauty make it even more exclusive through a commitment to craftsmanship and refined design, equating their products as much to prestige as to performance. These brands are also spending big on technology to create sophisticated formulations that provide visible benefits while staying luxury attractive.
Consumer behavior in the market is defined by aspiration and awareness. Consumers are more aware of ingredients and sustainability, and this is informing purchasing decisions. Luxury labels like Sisley Paris, Charlotte Tilbury Beauty Ltd., and Tatcha are countering this by espousing transparency and sustainability without diluting luxury standards. Social media and online platforms are also increasingly playing a part. Influencers and beauty bloggers are highlighting premium products, which become coveted and accessible to more consumers. Online shopping has also emerged as a major platform, but physical outlets retain their importance due to the experiential advantage and effortless personal attention that luxury counters provide.
Going forward, the global luxury cosmetics market will prosper with a harmony of tradition and modernity. Long-standing brands such as Guerlain, Clarins Group, and KOSÉ Corporation will further enhance their heritage while adopting contemporary tastes. Concurrently, newer brands such as MPLUS COSMETICS SRL, H.S.A. Hair Styling Applications S.p.a, and niche labels such as Chantecaille Beauté are making their mark by tapping specific consumer requirements and luxury niches. As consumers seek products that bring more than beauty namely confidence, exclusivity, and a sense of identity luxury cosmetics will continue to be a dynamic segment within the global beauty market.
Find answers to common questions about this report
The Metastat Insights study shows that the Global Luxury Cosmetics market size was USD 58.1 billion in 2025
The Global Luxury Cosmetics market is likely to grow at a CAGR of 4.6% over the forecast period (2026-2033)
The Metastat Insights analysis shows that the North America Luxury Cosmetics market size is estimated to be USD 24.4 billion by 2033.
Global Luxury Cosmetics market is estimated to reach USD 83.2 billion by 2033.
Influencer marketing acts as a primary discovery and conversion engine by demystifying complex formulations and demonstrating visual cosmetic performance in real time. Luxury brands increasingly collaborate with credible dermatologists, professional makeup artists, and aesthetic tastemakers on social video platforms, transforming high-end cosmetic education into immediate retail sales.
Luxury cosmetics manufacturers navigate tightening international regulations surrounding ingredient safety, microplastic bans, and environmental claims. Key examples include the European Union's rigorous chemical and preservative restrictions under the EU Cosmetics Regulation and modern regulatory enforcement frameworks in the United States and China, which require extensive safety dossiers and supply chain traceability.
While the female segment accounts for the dominant total revenue volume in luxury cosmetics, the male segment is recording a faster relative annual growth rate. Growth in the male sector is driven by the destigmatization of male grooming, targeted launches in prestige skincare, and growing consumer interest in premium beard oils, anti-fatigue serums, and discreet complexion enhancers.
Gen Z and Millennial demographics prioritize verifiable product efficacy, ethical ingredient sourcing, and environmental sustainability over traditional luxury brand heritage alone. These younger buyers demand direct social engagement, rely heavily on peer reviews and digital creator content, and strongly favor refillable packaging designs and certified cruelty-free labels.
The Asia-Pacific region demonstrates the highest compound annual growth rate (CAGR) for luxury cosmetics, propelled by expanding middle-class affluence in China, India, and Southeast Asia. Strong cultural dedication to skincare rituals, high digital commerce penetration, and increasing demand for premium K-beauty formulations reinforce the region's accelerated growth trajectory.
E-commerce and brand-owned direct-to-consumer (DTC) channels represent the fastest-growing avenues for luxury cosmetics distribution, driven by AI skin analysis and interactive virtual try-on tools. Despite online acceleration, omnichannel specialty retailers such as Sephora, Ulta Beauty, and curated fashion portals like Net-a-Porter continue to gain market share by offering blended physical and digital shopping journeys.
The clean beauty movement is compelling traditional luxury cosmetics brands to reformulate iconic products to exclude controversial synthetic chemicals, parabens, and microplastics while preserving luxurious sensory textures. Established brands are acquiring clean indie startups, securing cruelty-free certification, and adopting sustainable packaging to retain credibility among ingredient-conscious consumers.
L'Oréal Luxe and The Estée Lauder Companies hold the largest market shares in the global luxury cosmetics sector, supported by their expansive portfolios across skincare, makeup, and designer fragrances. They are closely followed by luxury conglomerates such as LVMH (Moët Hennessy Louis Vuitton), independent heritage houses like Chanel, and diversified beauty groups including Shiseido and Coty Inc.
Choose Your License
Luxury Cosmetics Market
The analysts below cover Consumer Goods research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
Last Updated: September 2026
Tracking maintenance cycle demand for secondary flight display units and terrain collision avoidance systems across regional jet fleets involves complex aftermarket dynamics. MetaStat Insight provided practical analysis separating airline retrofit programs from OEM forward-fit production schedules in North America and Southeast Asia. The supplier matrix highlighted component obsolescence timelines without resorting to vague generalizations. The dataset served as a dependable reference during our annual program review meetings.
Evaluating secondary resin quality across post-consumer packaging streams requires reliable technical segmentation. MetaStat Insight delivered an objective assessment that distinguished between extrusion-grade flake pricing and optical sorting throughput limitations across Western Europe. The competitive positioning breakdown for licensed depolymerization technology providers answered several questions during our feedstock feasibility audit. Their team clarified regional trade restrictions on mixed plastic scrap quickly when our team submitted follow-up requests.
Evaluating sovereign cloud deployments for core banking platforms demands a clear view of data residency regulations and migration exit strategies. MetaStat Insight delivered an exhaustive review of regional latency tolerances, mainframe decommission milestones, and third-party vendor concentration risk. The regulatory compliance mapping across European and Asian financial jurisdictions gave our team a dependable baseline for multi-cloud infrastructure discussions.
Explore related market intelligence reports worth reading alongside this one.