
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Smart Electric Actuator Market Size, Share, By Actuator Motion Type (Multi-Turn Electric Actuators, Part-Turn / Quarter-Turn Electric Actuators, and Linear Electric Actuators), By Application (Valve Actuation, Damper Actuation, Industrial Motion Control, Robotics and Automation, and Material Handling and Machinery), By Power Supply Type (DC Electric Actuator and AC Electric Actuator), By End-Use Industry (Oil & Gas, Power Generation, Water & Wastewater, Chemicals & Petrochemicals, Mining & Metals, Pharmaceutical & Biotechnology, Food & Beverage, Marine & Shipbuilding, HVAC & Building Automation, and Others), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5387
September, 2026
267 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $3,484.6 Million in 2025, projected to reach $5,514 Million by 2033 at a 5.9% CAGR.
Dominant Segment: The Multi-Turn Electric Actuators segment leads the market, driven by increasing demand in oil and gas, power generation, and water management sectors, where precise control is essential.
Geographic Lead: The Asia Pacific region is experiencing the fastest growth due to rapid industrialization and urbanization, necessitating advanced automation solutions.
What's Inside: This report includes comprehensive competitive coverage, detailed market segmentation, and analyses of trends and forecasts from 2026 to 2033.
Emerging Trends: Digital transformation and the integration of IoT technologies are key trends driving the adoption of smart electric actuators across various industries.
Investment Drivers: Increased capital investment in infrastructure development and a focus on sustainability are propelling demand for smart electric actuators in multiple sectors.
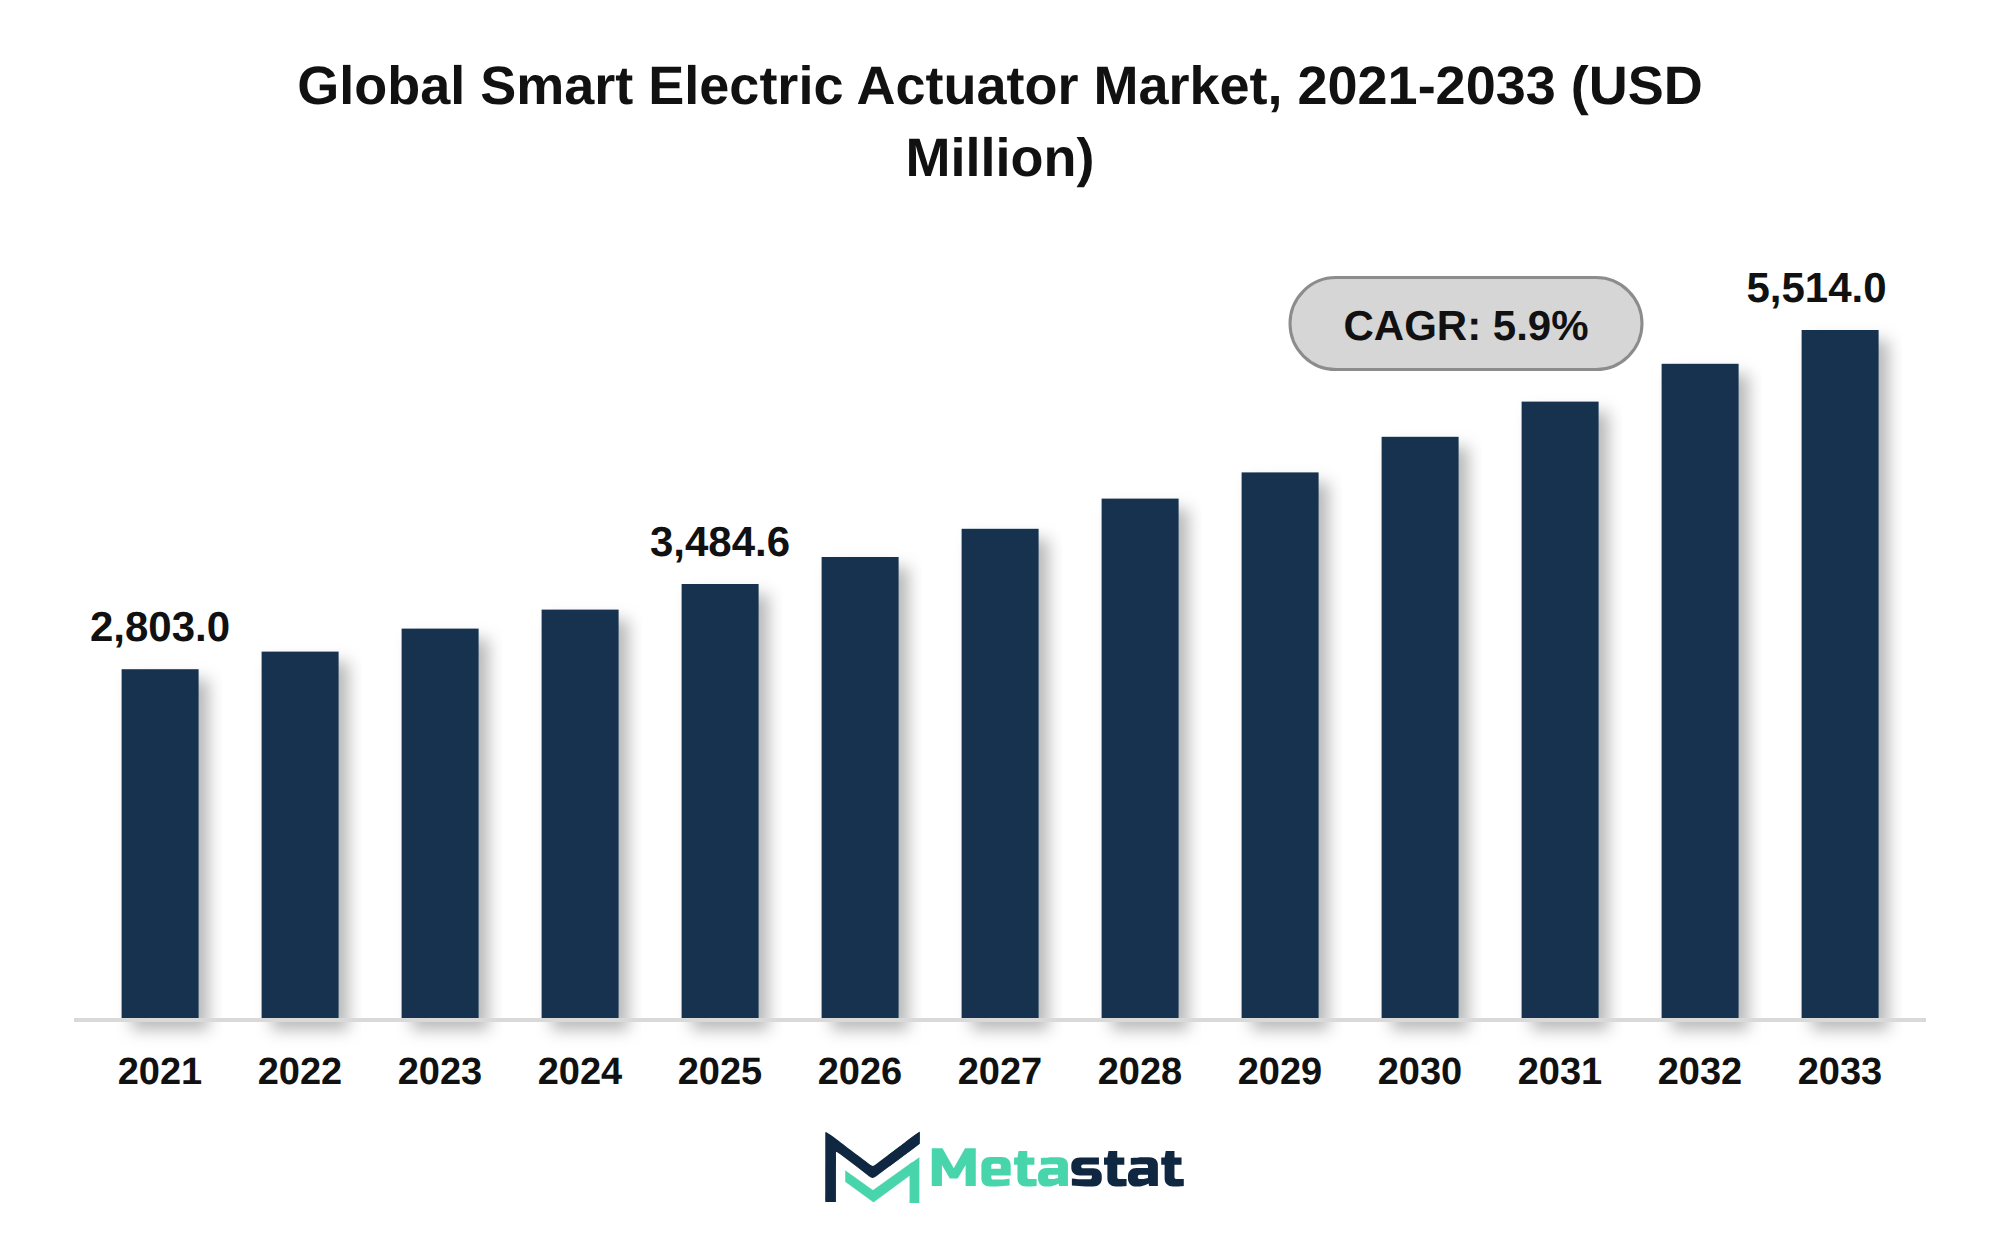
The global Smart Electric Actuator market was valued at USD 3,484.6 million in 2025 and is projected to reach USD 5,514 million by 2033, growing at a CAGR of 5.9% over the forecast period.
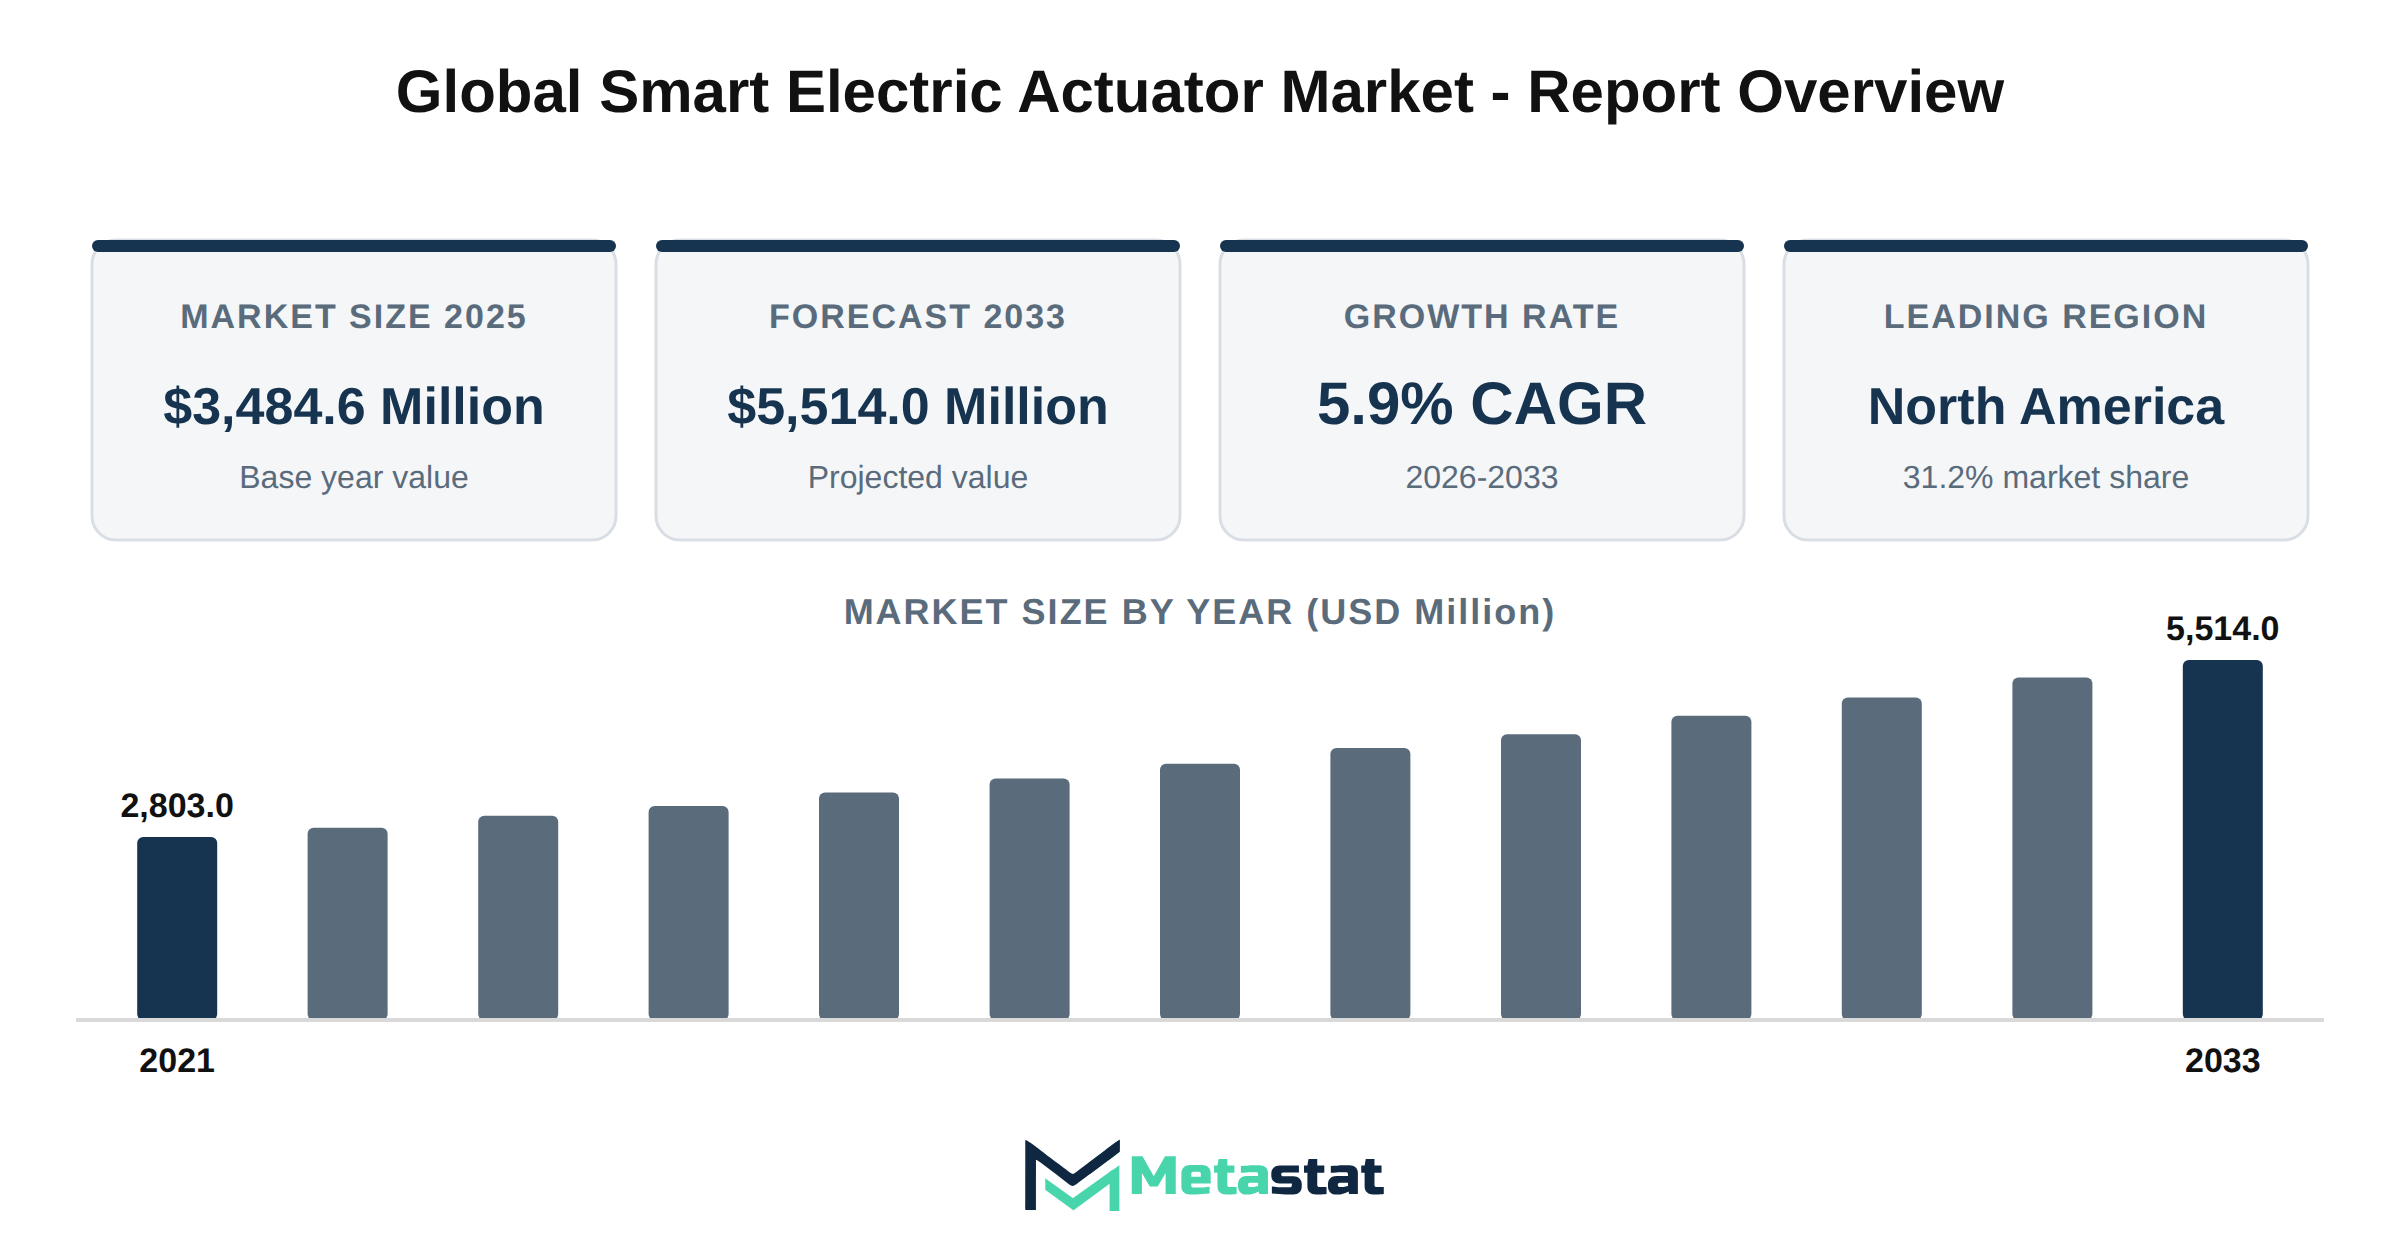
The Smart Electric Actuator market reached USD 3,484.6 million in 2025, with an anticipated growth to USD 5,514 million by 2033. This represents a compound annual growth rate (CAGR) of 5.9% during the forecast period from 2026 to 2033. Key drivers behind this growth include the rising adoption of intelligent electric valve actuators, which enhance operational efficiency across various industries.
Integration of smart actuators with industrial IoT platforms facilitates improved monitoring and control, leading to significant operational benefits. Predictive maintenance and embedded diagnostics in electric actuators contribute to minimizing downtime and enhancing reliability, thus appealing to industries focused on maximizing productivity.
Growing demand for multi-turn and quarter-turn smart actuators reflects the need for precision in industrial applications. Trends in digital position feedback and precision motion control support the adoption of advanced actuator technologies. The oil and gas sector increasingly employs smart electric actuators to enhance process control and safety, driving substantial market growth.
Automation in water and wastewater management boosts actuator demand owing to municipalities seeking efficient solutions for resource management. In power generation, the push for intelligent electric actuation systems leads to advancements in energy efficiency and reliability. The chemicals and petrochemicals industry benefits from expanding smart actuator applications, enhancing process automation and control.
Robotics and factory automation accelerate demand for electric actuators, driven by the need for precise control in manufacturing environments. Industrial Ethernet and fieldbus connectivity in smart actuators enable integration with modern automation systems, enhancing operational flexibility. Energy efficiency benefits from electric actuation systems appeal to organizations aiming to reduce operational costs.
Transition from pneumatic to smart electric actuation reflects the industry’s focus on innovation and efficiency. Innovations in fail-safe and safety-integrated electric actuators address safety concerns in various applications, reinforcing market confidence. Remote monitoring and non-intrusive actuator configuration improve operations, ensuring higher levels of control and responsiveness.
In HVAC and building automation, the demand for smart electric actuators grows owing to systems becoming more sophisticated. The industrial expansion in the Asia Pacific region supports actuator growth, with investments in infrastructure and technology driving demand. Competitive innovation in intelligent electric actuation technologies creates a competitive environment, positioning key players to capture emerging opportunities in connected and autonomous actuation systems.
The Smart Electric Actuator market experiences significant growth driven by the increasing trend toward industrial automation. Industries are adopting intelligent electric valve actuators to enhance operational efficiency and reduce manual intervention. This trend reflects the broader movement towards automation across various sectors, facilitating integration and control.
Integration of smart actuators with industrial IoT platforms improves operational efficiency through real-time monitoring and data analytics. This connection allows for advanced functionalities including predictive maintenance and embedded diagnostics, which contribute to minimizing downtime and enhancing reliability.
The demand for multi-turn and quarter-turn smart actuators continues to grow due to their versatility in various applications. This trend aligns with digital position feedback and precision motion control requirements, ensuring accuracy and reliability in actuation processes.
In the oil and gas sector, smart electric actuator adoption enhances operational safety and efficiency. These actuators enable precise control of processes and equipment, leading to improved performance and reduced operational risks.
Water and wastewater automation drives actuator demand, highlighting the importance of reliable and efficient systems in managing resources. Advanced actuation solutions optimize operations in this critical sector, ensuring compliance with environmental regulations.
Power generation applications increasingly leverage intelligent electric actuation, contributing to improved efficiency and reliability in energy production. While energy demands rise, the market for smart electric actuators expands to meet evolving requirements.
The chemicals and petrochemicals industry recognizes the benefits of smart actuators, leading to their growing usage in various applications. Enhanced process control and safety measures provide substantial operational advantages.
Robotics and factory automation significantly accelerate electric actuator demand, reflecting the shift towards automated and intelligent manufacturing processes. Innovations in actuator technology support these advancements, ensuring adaptability to evolving production needs.
Connectivity through industrial Ethernet and fieldbus systems enhances the functionality of smart actuators, allowing for integration within automated environments. This advancement plays a critical role in optimizing performance across various applications.
Energy efficiency benefits of electric actuation systems contribute to their increasing adoption. Organizations prioritize sustainable practices, prompting a shift from traditional pneumatic systems to smart electric actuation solutions.
Innovation in fail-safe and safety-integrated electric actuators addresses industry demands for enhanced safety measures. These advancements improve trust in actuator technologies, promoting wider acceptance across sectors.
Remote monitoring and non-intrusive actuator configuration capabilities enhance operational flexibility and efficiency. This trend reflects the ongoing evolution of smart electric actuator solutions, aligning with the needs of modern industries.
The HVAC and building automation sectors demonstrate rising demand for smart electric actuators, driven by the need for energy-efficient and automated climate control systems. This trend indicates a growing recognition of the importance of integrated solutions in building management.
Asia Pacific's industrial expansion supports actuator growth, with investments in automation technologies creating significant opportunities within the region. This market development aligns with broader trends in manufacturing and infrastructure development.
Competitive innovation in intelligent electric actuation technologies continues to shape the market landscape. Ongoing advancements ensure organizations remain competitive in operational efficiency and technological integration.
Future opportunities in connected and autonomous actuation systems present exciting prospects for the Smart Electric Actuator market. Increased connectivity and intelligence in actuation solutions position the market for sustained growth and evolution.
Digital transformation significantly influences the Smart Electric Actuator market, with industries increasingly relying on automated solutions to enhance efficiency and reduce operational costs. The integration of advanced technologies, including artificial intelligence and automation software, facilitates control and monitoring of processes. This shift is particularly evident in sectors including oil and gas, power generation, and water management, where the demand for precise control and real-time data analytics drives the adoption of smart electric actuators.
Investment in digital technologies aligns with evolving consumer behaviors, particularly in urbanized areas where automation enhances productivity and sustainability efforts. The market benefits from a growing emphasis on reducing carbon footprints, leading companies to prioritize smart actuator solutions that optimize energy consumption and minimize waste. This trend provides a competitive edge among businesses focusing on innovation and efficiency.
While organizations digitize legacy processes, they position themselves to capitalize on the advantages offered by smart electric actuators. Enhanced operational productivity and cost-efficiency initiatives emerge owing to key objectives, further stimulating market growth. Companies leveraging these technologies streamline operations, maintain competitiveness, and adapt to shifting market demands, ensuring a robust trajectory for the smart electric actuator market.
High capital investment requirements present a significant restraint in the Smart Electric Actuator market. Industries investing in electric actuators face substantial upfront costs associated with purchasing, installing, and maintaining these advanced systems. This financial commitment restricts entry for smaller players and hinders expansion for existing firms, particularly in developing regions where budget constraints are prevalent.
Escalating operating costs challenge profitability for organizations in the market. Rising costs, driven by factors including labor shortages and increased material prices, impact operational budgets and resources available for technology upgrades. Manufacturers experience pressure to maintain competitive pricing while ensuring product quality, which adversely affects their market positioning.
Supply chain disruptions create additional hurdles, leading to delays in the procurement of necessary components for smart electric actuators. Geopolitical instability and global economic fluctuations contribute to uncertainties in sourcing materials and components, complicating production schedules. These challenges lead to increased lead times and reduced reliability in delivery, impacting customer satisfaction and long-term contracts.
Infrastructure gaps in certain regions create obstacles for widespread deployment of smart electric actuators. Inadequate infrastructure limits the potential for technology integration in various applications, particularly in emerging markets. This disparity in regional development results in market fragmentation, where advanced solutions remain concentrated in developed economies while other areas lag behind.
Technological obsolescence poses a risk to firms operating in the market. Rapid advancements in related technologies render existing products outdated, compelling manufacturers to invest in new solutions frequently. This constant need for innovation strains financial resources and planning efforts for organizations seeking to stay competitive.
The Smart Electric Actuator market experiences competitive pressures from alternative offerings, impacting demand. Emerging technologies and substitutes attract customers seeking cost-effective or innovative solutions. This competition hinders market growth, driven by firms striving to differentiate their products in a crowded landscape.
The Smart Electric Actuator market faces challenges from geopolitical tensions, which contribute to supply chain instability. Disruptions in trade relations lead to increased tariffs and trade deficits, complicating the procurement of components essential for actuator production. These factors raise operational costs, impacting pricing strategies across various applications.
Technological disruptions, including rapid advancements in automation, intensify competitive pressures within the market. Companies navigate complex research and development integrations, which strain resources and extend project timelines. The requirement for interoperability among diverse systems adds another layer of complexity for manufacturers seeking to enhance product offerings.
Fluctuating feedstock prices and component volatility hinder consistent production capabilities. Companies within the market face rising input costs, which place pressure on profit margins and pricing structures. This environment complicates long-term strategic planning and results in reduced competitiveness, particularly for smaller players.
Environmental concerns, including decarbonization mandates and sustainability demands, impose additional operational challenges. Companies invest in environmentally friendly technologies while ensuring compliance with evolving legal liabilities. The focus on reducing environmental footprints further compounds the financial burden on manufacturers, necessitating a delicate balance between compliance and market viability.
Workforce skill gaps and talent retention pressures continue to impact the ability of firms to adapt to innovative technologies. Skilled labor shortages limit operational efficiency and slow down the adoption of advanced solutions, affecting overall market growth. Addressing these workforce challenges remains crucial for companies striving to maintain competitiveness in the Smart Electric Actuator market.
Geopolitical tensions, technological disruptions, environmental mandates, and workforce challenges represent significant hurdles in the Smart Electric Actuator market. These factors collectively influence production capabilities, pricing strategies, and market competitiveness, shaping the industry landscape through 2033.
The Smart Electric Actuator market experiences substantial opportunities from emerging regional demands, particularly in Asia Pacific and South America. Rapid industrialization and urbanization in these regions necessitate advanced automation solutions, propelling the adoption of smart electric actuators in various applications including water management and power generation. Infrastructure modernization efforts, especially in developing countries, enhance operational efficiencies and support sustainable practices, further driving demand.
Technological disruptions significantly impact the market, with advancements in smart technologies enabling improved performance and efficiency. Innovations in actuator designs and control systems lead to enhanced functionality and reliability, attracting investment from key sectors. Industries increasingly shift towards automation and digital solutions, creating fertile ground for the Smart Electric Actuator market to expand.
Sustainability imperatives and eco-friendly compliance requirements shape purchasing decisions across various sectors. Companies prioritizing environmental, social, and governance (ESG) criteria integrate smart electric actuators to reduce energy consumption and minimize emissions. This trend aligns with global movements towards greener technologies, supporting long-term growth in the market.
Strategic consolidation and cross-industry collaborations facilitate knowledge sharing and resource optimization among players. Mergers and acquisitions within the sector strengthen the competitive landscape, enabling firms to access new markets and leverage complementary technologies. These dynamics create a more integrated approach to developing innovative solutions that cater to diverse customer needs.
Ultimately, evolving buying behaviors driven by digital procurement shifts and commercial model transitions reflect the changing landscape of the Smart Electric Actuator market. Companies increasingly adopt digital channels for sourcing and procurement, enhancing operational efficiencies and reducing lead times. This evolution highlights the market's adaptability to emerging trends, providing a pathway for sustained growth and diversification opportunities.
The Global Smart Electric Actuator market is segmented based on Actuator Motion Type, Application, Power Supply Type, and End-Use Industry.
Valued at USD 1,473.3 million in 2026, the Multi-Turn Electric Actuators segment is projected to reach USD 2,085.4 million by 2033, registering a CAGR of 5.1% during the forecast period. This growth stems from increasing demand across various industries, including oil and gas, power generation, and water and wastewater management. The need for precise control and automation in these sectors drives the adoption of Multi-Turn Electric Actuators, which offer enhanced performance and reliability. Advancements in technology, including better materials and designs, contribute to the segment's evolution, enabling manufacturers to create more efficient and durable products.
Demand drivers include the rising focus on automation and the efficiency improvements associated with Multi-Turn Electric Actuators. Industries seek to optimize operations, reduce downtime, and enhance productivity, all of which align with the capabilities of these actuators. Regulatory compliance standards further influence the market, driven by the implementation of stringent policies to improve safety and operational standards, necessitating reliable actuation solutions. The ability to integrate with modern control systems enhances the appeal of Multi-Turn Electric Actuators, allowing for connectivity and real-time monitoring.
Cost structures in this segment often reflect the investments required for research and development, because companies prioritize innovation to meet evolving demands. Pricing volatility remains a challenge, influenced by fluctuating raw material costs and supply chain dynamics. Manufacturers maintain focus on supply chain resilience, ensuring consistent access to quality components while mitigating risks associated with sourcing and logistics. Strategic opportunities arise from market expansion into emerging economies, where infrastructure development boosts demand for automation solutions. Overall, Multi-Turn Electric Actuators play a critical role in enhancing operational efficiency and supporting growth in the Smart Electric Actuator market.
Increasing demand for efficient and reliable control systems drives the growth of the Part-Turn / Quarter-Turn Electric Actuators segment within the Smart Electric Actuator market. This segment experiences significant expansion, fueled by the need for precise and automated solutions in various applications, particularly in industries including oil and gas, chemicals, and wastewater management. The market is expected to reach USD 1,971.8 million by 2033, at a CAGR of 6.4% during the forecast period.
Technological advancements play a crucial role, with innovations enhancing the performance and capabilities of actuators. The shift towards automation and digitalization in industrial processes necessitates the adoption of responsive and adaptable actuator systems. The integration of smart technologies, including IoT, allows for better monitoring, control, and maintenance. This capability increases efficiency and reduces downtime.
Regulatory compliance standards further promote the adoption of Part-Turn / Quarter-Turn Electric Actuators, driven by increasing scrutiny regarding operational safety and environmental impact. These compliance requirements compel businesses to upgrade their systems and ensure they are equipped with reliable and efficient actuation solutions. The segment's ability to enhance operational performance while meeting stringent regulations positions it favorably within the broader Smart Electric Actuator market.
The shift towards renewable energy sources and sustainable practices creates new opportunities for Part-Turn / Quarter-Turn Electric Actuators. Increasing investment in smart infrastructure and automation across various sectors enhances demand for these actuators. While industries evolve and embrace advanced technologies, the segment's growth trajectory remains strong, reflecting its significance in the overall market.
Increasing demand for automation across various industries drives growth in the Linear Electric Actuators segment. Enhancements in technologies including robotics and industrial motion control create significant opportunities for adoption. Industries including oil and gas, power generation, and water and wastewater lead the way in applying these actuators for precise control and efficient operation. More companies seek to improve operational efficiencies and reduce energy consumption, expanding the market for linear electric actuators.
Regulatory compliance standards push manufacturers to adopt advanced control solutions, making linear electric actuators essential in meeting performance metrics. Price stability in raw materials, combined with improved supply chain resilience, supports manufacturers in controlling costs and maintaining competitive pricing. By 2033, the segment is projected to reach USD 1,456.8 million, reflecting an anticipated increase in investment and technology advancement specific to the Smart Electric Actuator market.
Valuable applications in various sectors fuel the demand for valve actuation within the Smart Electric Actuator market. This segment is valued at USD 1,410.9 million in 2026 and is projected to reach USD 1,977.3 million by 2033, at a CAGR of 4.9% during the forecast period. Growth stems from an increased focus on automation, which enhances operational efficiency and reliability across industries including oil and gas, water and wastewater management, and power generation.
Technological maturation contributes significantly to the expansion of this segment. Innovations in electric actuators improve precision, performance, and integration with control systems. These advancements enable organizations to implement more sophisticated automation solutions. While industries prioritize sustainability and energy efficiency, valve actuation systems equipped with modern technologies are increasingly adopted to adhere to environmental regulations.
Evolving regulatory compliance standards drive investments in valve actuation systems. Industries face pressure to meet stringent environmental and safety regulations, prompting the adoption of advanced electric actuators. The capability to control fluid flow accurately and safely positions these systems because essential components in production processes.
Cost structures and pricing volatility create challenges in the segment. The increasing prices of raw materials and the need for high-quality components affect overall pricing strategies. Companies in the market adapt to these fluctuations while maintaining competitive pricing to attract and retain customers. Strategic opportunities arise through investment in research and development to mitigate these cost pressures, ensuring sustained growth.
The valve actuation segment within the Smart Electric Actuator market thrives on advancements in technology, regulatory compliance, and the growing demand for automation. Investments in innovative solutions position key players to capitalize on emerging opportunities in this evolving landscape.
Increasing focus on energy efficiency and environmental sustainability drives demand for damper actuation systems in various industries, including HVAC and industrial applications. These systems optimize airflow and enhance temperature control, aligning with regulatory compliance standards that promote energy-efficient solutions. The pursuit of improved operational performance and reduced energy consumption influences the adoption of smart electric actuators, which offer precise control and reliability.
Technological maturation supports the integration of advanced features into damper actuation systems, including digital controls and connectivity options that facilitate integration into smart building management systems. This evolution leads to enhanced user experience and operational efficiency, attracting investments in next-generation upgrades. The rising trend of automation across industries emphasizes the need for intelligent control solutions, which propel the growth of this segment.
Valued at USD 867.3 million by 2033, with a CAGR of 5.3% during the forecast period, the damper actuation segment demonstrates robust potential for expansion. Stricter environmental regulations and increasing awareness of energy conservation contribute to its growth, providing strategic opportunity windows for manufacturers. While companies strive to enhance their sustainability profiles, demand for innovative damper actuation solutions continues to rise, affirming their significance in the broader Smart Electric Actuator market.
Strong demand for automation drives growth in the Industrial Motion Control segment of the Smart Electric Actuator market. Industries pursuing increased efficiency prioritize this segment, leveraging advanced electric actuators for enhanced control and performance in various applications. Investment in automation technologies serves because a significant expansion catalyst, aligning with trends in manufacturing, robotics, and energy management.
Regulatory compliance standards within sectors including oil and gas, chemicals, and wastewater management necessitate reliable and efficient solutions, reinforcing the demand for electric actuators. The transition towards more sustainable practices promotes the adoption of electric alternatives over pneumatic or hydraulic systems, ensuring a robust competitive advantage for players focused on innovation and product evolution.
Technological maturation facilitates the integration of smart features into electric actuators, offering improved connectivity and data analytics capabilities. This evolution enables more precise control, further enhancing operational efficiency and performance. With a market value reaching USD 1,060.9 million by 2033, investment opportunities in this segment signify a positive outlook for stakeholders.
Growing demand for automation technologies supports the Robotics and Automation segment of the Smart Electric Actuator market, which is projected to grow at a CAGR of 7.8% during the forecast period. Companies seek enhanced efficiency and reliability in operations, driving investment in advanced actuator solutions. Key applications in robotics and automation sectors necessitate precision control, which directly influences the adoption of electric actuators.
Technological advancements contribute significantly to market dynamics, with innovations in actuator designs improving performance and integration capabilities. The increasing sophistication of automation systems encourages manufacturers to enhance product features, thereby expanding the market. Evolving regulatory standards around energy consumption and safety procedures influence demand, prompting suppliers to invest in compliant and efficient actuator technologies.
End-use industries including manufacturing, logistics, and healthcare increasingly adopt robotics, necessitating effective motion control and actuation solutions. This trend supports substantial investment in the segment, enhancing manufacturers’ ability to capture emerging market opportunities. The expansion of this sector aligns with broader movements toward smart manufacturing, positioning the market for sustained growth in the coming years.
Automation trends continue to advance the relevance of the Material Handling and Machinery sub-segment within the Smart Electric Actuator market. Increased adoption of automated solutions across industries drives demand for innovative actuation systems that enhance operational efficiency and reliability. Companies prioritize the integration of smart actuators in their machinery to optimize processes, reduce downtime, and lower operational costs.
Technological maturation plays a significant role in driving segment expansion. Developments in actuator technologies lead to improved performance, enabling greater precision and responsiveness. Next-generation upgrades, including integration with Internet of Things (IoT) devices, facilitate real-time monitoring and control, further enhancing operational capabilities.
End-use dynamics significantly influence market growth. Industries including manufacturing, logistics, and construction require advanced actuation solutions to streamline their operations. Consumption shifts towards more flexible and efficient machinery align with the expanding scope of applications for smart electric actuators, enabling greater adaptability in diverse operational environments.
Regulatory compliance standards increasingly emphasize energy efficiency and environmental sustainability, impacting supplier strategies and product offerings. Adhering to these standards enhances market competitiveness, encouraging manufacturers to innovate and improve their product lines, ultimately benefiting end-users.
Supply chain resilience remains a crucial factor for maintaining consistent production levels. Ensuring reliable raw material sourcing and addressing logistical vulnerabilities are essential components of strategic planning for companies in this sub-segment. Effective management of these aspects allows producers to meet the growing demand for smart electric actuators within the market.
Strategic opportunity windows arise from the market's evolving landscape. Industries adopting more sophisticated technologies create a need for high-quality electric actuators. Manufacturers prioritizing research and development efforts position themselves favorably within the competitive environment, capitalizing on the growth potential of the Material Handling and Machinery segment.
Valued at USD 1,571.6 million in 2026, the DC Electric Actuator segment is projected to reach USD 2,430.6 million by 2033, at a CAGR of 6.4% during the forecast period. This growth reflects increasing adoption across industries, particularly within automation processes that require precise control and reliability. Demand arises from sectors including oil and gas, where efficient actuation is critical for operational success. Ongoing technological evolution enhances the performance and capabilities of DC Electric Actuators, driving investments in next-generation solutions.
Adoption patterns indicate a shift toward more energy-efficient systems, aligning with regulatory compliance and sustainability initiatives. Industries increasingly integrate DC Electric Actuators into their operations, responding to the need for improved energy efficiency and reduced operating costs. The segment benefits from advancements in power supply technologies, enabling greater versatility and functionality in varied applications. Investment in research and development fuels product evolution, resulting in innovative solutions that meet the dynamic requirements of end-users.
Fluctuations in raw material costs and supply chain resilience shape the market landscape. Manufacturers navigate these challenges while capitalizing on strategic opportunities to enhance competitive positioning. The DC Electric Actuator segment occupies a crucial role in the broader Smart Electric Actuator market, reflecting a strong trajectory driven by technological maturation and increasing demand for automation across multiple industries.
Growth in the Smart Electric Actuator market aligns closely with the increasing adoption of automation across various sectors. The AC Electric Actuator segment, valued at USD 3,083.4 million by 2033, at a CAGR of 5.4% during the forecast period, reflects this trend driven by industries investing heavily in energy-efficient systems. Enhanced reliability and control provided by AC Electric Actuators underpin their integration into critical applications, particularly in industrial automation and process control. The growing focus on energy efficiency, paired with stringent regulatory compliance standards, drives the demand for such technologies.
Technological advancements play a significant role in shaping product offerings within the segment. Continuous innovation in actuator design and control systems enhances performance and expands application potential, driving widespread use across end-use industries including oil and gas, power generation, and water management. These industries prioritize operational efficiency and reliability, which directly influences their investment in smart actuator solutions.
Market dynamics indicate a strong shift towards adopting advanced control technologies to meet the evolving needs of industrial applications. The demand for AC Electric Actuators continues to rise because businesses seek smarter and more adaptable solutions to enhance their operational protocols. This trend positions the segment because a key player in the broader Smart Electric Actuator market, reflecting both current and future capacity for growth in diverse applications.
Valued at USD 759.9 million in 2026, the Oil & Gas segment is projected to reach USD 1,064.7 million by 2033, at a CAGR of 4.9% during the forecast period. Demand in this segment derives from the need for efficient and precise control of operational processes in exploration, drilling, and production activities. Increasing adoption of automation technologies within the oil and gas sector enhances operational efficiency while reducing operational risks. Stringent regulations surrounding environmental safety and emissions create a necessity for advanced control systems to ensure compliance, propelling investments in smart electric actuators.
Investment in infrastructure upgrades stimulates growth in the market. Oil and gas companies transition towards more intelligent and integrated systems that provide real-time monitoring and control. The evolution of these technologies supports the development of next-generation actuators, enhancing performance and reliability. Fluctuations in oil prices drive companies to focus on cost-effective solutions. This focus increases demand for smart electric actuators that provide improved control and automation.
Collaboration between technology providers and oil and gas operators advances the development of tailored solutions that address specific operational challenges. Integration of smart electric actuators with IoT and AI technologies creates more advanced monitoring systems that predict maintenance needs and optimize performance. Overall, these trends contribute to strong growth potential for the smart electric actuator market within the oil and gas sector.
Significant investments in infrastructure and technology influence the Power Generation segment's growth within the Smart Electric Actuator market. An increasing focus on renewable energy sources drives demand for efficient automation solutions that enhance operational reliability. Utilities modernize their systems, and the adoption of smart actuators facilitates improved control and monitoring, aligning with regulatory compliance and sustainability goals.
The Power Generation segment is estimated to reach USD 717.9 million by 2033, at a CAGR of 5.2% during the forecast period. Demand for innovative technologies to enhance efficiency and reduce emissions shapes the market. Transitioning to advanced control systems impacts operational effectiveness, promoting investments in electric actuators that deliver precise performance.
Technological advancements in electric actuators enhance their capabilities across various applications, supporting the shift towards automation in power plants. This evolution contributes to increased efficiency, reduced downtime, and lower maintenance costs, making smart electric actuators essential for utilities seeking competitive advantages. The market's expansion reflects the ongoing transformation within the energy sector, where effective automation solutions play a critical role.
Increased focus on sustainable water management strategies drives the demand for Smart Electric Actuators within the Water & Wastewater segment. Regulatory compliance standards, including stricter environmental regulations, prompt investments in advanced technologies that enhance operational efficiency and reliability. The need for real-time monitoring and control systems in water treatment and distribution further stimulates market growth, because utilities seek to optimize resource management and reduce operational costs.
The segment is expected to reach USD 897.1 million by 2033. Technological maturation in actuator design and integration with smart grid technologies enhances the appeal of Smart Electric Actuators. Adoption of next-generation upgrades, including IoT-enabled devices, supports improved data analytics and proactive maintenance solutions.
End-use dynamics indicate a shift toward automation in municipal and industrial water applications, leading to increased demand for actuators that facilitate valve and damper actuation. The market continues to expand because operators seek reliable solutions that reduce downtime and enhance process automation. Overall, the Water & Wastewater segment represents a critical area of growth within the Smart Electric Actuator market.
Expansion in the Chemicals & Petrochemicals sector drives demand for smart electric actuators, with the segment projected to grow at a CAGR of 5.5% during the forecast period. Technological advancements in automation and control systems enhance operational efficiency, directly impacting production processes within this industry. Increasing complexity in chemical processing and the need for precise control systems drive automation adoption, benefiting smart electric actuator applications.
Regulatory compliance standards significantly influence market dynamics, because companies strive to meet safety and environmental regulations. These factors contribute to the growing need for reliable, efficient control systems in the Chemicals & Petrochemicals segment. The market reflects a commitment to innovation, with manufacturers investing in next-generation upgrades and product evolution to enhance performance and reliability.
Integration of advanced technologies, including IoT and AI, enables improved monitoring and control of chemical processing, further propelling the demand for smart electric actuators. End-use dynamics highlight the importance of automation in enhancing productivity and reducing operational costs, which is crucial for maintaining competitive advantages in the market. Growth in this segment continues to align with broader trends in industrial automation and digital transformation.
Increasing focus on automation within the Mining & Metals sector enhances the relevance of smart electric actuators. The drive towards operational efficiency and productivity improvements motivates companies to adopt advanced control systems that optimize processes and reduce downtime. These systems provide precise motion control, which is important for applications including conveyor systems and material handling equipment.
Investment in technological upgrades remains a key factor in segment expansion. Companies prioritize the integration of next-generation electric actuators that offer improved performance and energy efficiency. These advancements align with industry trends towards automation and smart manufacturing, pushing the boundaries of traditional practices.
Regulatory compliance and environmental standards influence the sector, requiring mining operations to adopt technologies that minimize environmental impact. Smart electric actuators contribute to these efforts by enabling precise control of machinery and processes, which reduces waste and energy consumption. This alignment with regulatory frameworks supports growth in the market.
Consumption shifts toward automation and digitization in the Mining & Metals sector necessitate robust actuator solutions that enhance operational capabilities. Companies increasingly look to smart electric actuators for reliable performance. This focus creates strategic opportunities for suppliers in the market. Enhancing product offerings positions firms to capitalize on emerging trends in automation technology.
Growth in the Pharmaceutical & Biotechnology sector relies heavily on automation, enhancing efficiency and ensuring precision in processes. The integration of smart electric actuators supports advanced manufacturing practices, which are critical for maintaining high standards in drug production and laboratory environments. A rise in demand for consistent quality and regulatory compliance intensifies the need for reliable actuation solutions.
Investments in research and development continue to drive technological maturation, with a focus on next-generation upgrades that improve performance and reliability. The adoption of smart electric actuators in this sector facilitates integration into existing systems, enabling pharmaceutical companies to enhance operational efficiency. While competition increases, the evolution of products becomes essential to meet the specific needs of this industry.
Regulatory compliance standards in the Pharmaceutical & Biotechnology sector necessitate stringent testing and validation, where smart electric actuators play a key role. Ensuring that processes meet these standards contributes to overall market stability and reliability. The market's expansion is further supported by ongoing shifts in consumption patterns, highlighting the demand for innovative solutions that respond effectively to emerging challenges.
Strategic opportunity windows arise because companies seek to differentiate their offerings through enhanced performance and adaptability. Understanding the dynamics within the sector allows suppliers to position their products effectively, capitalizing on the growing need for automation technologies. Continued growth in the Pharmaceutical & Biotechnology sector contributes positively to the overall Smart Electric Actuator market.
Increasing investments in the Food & Beverage industry contribute to the growth of the Smart Electric Actuator market. The sector demands precise control of processes including mixing, filling, and packaging, where electric actuators provide enhanced efficiency and accuracy. The adoption of automation technologies in food production requires reliable actuation solutions to maintain product quality and compliance with food safety standards.
Technological advancements in actuator design and integration enable improvements in production efficiency and process control. The push for automation in food processing facilities drives a transition from traditional mechanical systems to electric solutions, enhancing operational capabilities and reducing labor costs. Regulatory compliance regarding food safety and environmental impacts drives the need for innovative solutions in actuator technology.
End-use dynamics reflect a shift towards smart manufacturing practices, where the integration of actuators in process control systems supports traceability and monitoring capabilities. Consumption shifts towards healthier and sustainably produced food products increase demand for automated systems that ensure consistency and safety throughout production lines. Manufacturers face strategic opportunities to upgrade existing equipment to meet evolving industry standards and consumer preferences.
Supply chain resilience remains vital in the Food & Beverage sector, influencing sourcing strategies for raw materials and component availability. Pricing volatility in raw materials impacts the cost structures of actuators, necessitating strategic adjustments. The competitive landscape presents disruptive alternatives, particularly in pneumatic and hydraulic systems, pushing for continuous innovation and adaptation in actuator technologies.
Growing investments in the Marine & Shipbuilding sector drive the demand for smart electric actuators. Companies increasingly adopt automation technologies to enhance operational efficiency and reduce labor costs. Advanced electric actuators provide precision control and reliability, which are essential for marine applications including steering and throttle control.
Technological maturation in actuator design supports the transition to next-generation electric actuators, driving innovation in product offerings. The trend toward greener technologies influences manufacturers to develop solutions that meet environmental standards, aligning with global sustainability goals. Compliance with safety and environmental regulations shapes product development in this segment.
Market dynamics emphasize the importance of supply chain resilience, especially in sourcing raw materials. Fluctuations in pricing and availability impact cost structures and margins within the market. Companies face challenges related to logistics vulnerabilities and substitution risks. Strategic planning is necessary to mitigate potential disruptions.
Investment in upgrading existing facilities with smart electric actuators presents strategic opportunity windows for industry players. Innovations in actuator technology contribute to more efficient marine operations, enhancing competitiveness in the market. The growth potential of the Marine & Shipbuilding segment aligns closely with overall trends observed in the smart electric actuator market.
Increased emphasis on energy efficiency and smart building technologies drives significant interest in HVAC & Building Automation applications. These systems enhance control over heating, ventilation, and air conditioning systems, thus maximizing energy savings and operational efficiency. The growing trend towards sustainable building practices influences the adoption of advanced automation solutions within this sector.
Technological advancements in actuator design and control systems play a crucial role in segment growth. Innovations including IoT-enabled actuators and advanced control algorithms lead to improved performance and flexibility, allowing for real-time monitoring and management of HVAC systems. This evolution aligns with the broader trends in the Smart Electric Actuator market, enhancing competitiveness and driving investment.
Regulatory compliance regarding energy efficiency standards fuels demand for sophisticated HVAC solutions. Stricter regulations compel building owners and operators to adopt advanced technologies that reduce energy consumption. These factors contribute to an increase in demand for smart electric actuators, positioning them because a vital component within the HVAC & Building Automation segment.
Market dynamics reflect a shift towards integrated solutions that combine HVAC efficiency with automation capabilities. This alignment creates opportunities for collaboration among manufacturers, technology providers, and end-users. The ongoing evolution of building systems toward greater integration augments market potential and opens strategic opportunity windows for stakeholders.
Interest in automation within various industries drives demand for smart electric actuators in the Others sub-segment, which encompasses pulp and paper, district energy, and general industry applications. These sectors increasingly adopt electric actuators to enhance operational efficiency and reduce manual intervention.
Technological maturation influences product evolution, leading to advanced features that promote integration with existing systems. Enhanced capabilities, including improved precision and reliability, contribute to the attractiveness of smart electric actuators for end users.
Regulatory compliance standards shape the dynamics of the market, because companies seek to align with environmental regulations and sustainability goals. This focus leads to an increase in the adoption of energy-efficient solutions, positioning smart electric actuators because a key component in meeting these objectives.
Cost structures and pricing volatility play significant roles in shaping investment strategies within this sub-segment. Manufacturers navigate these challenges by developing innovative products that offer competitive pricing while maintaining high quality. This approach enhances the appeal of smart electric actuators within the market.
Strategic opportunity windows arise from ongoing shifts in consumption patterns, with industries increasingly favoring automation and digitalization. Investments in smart electric actuators align with these trends, because companies prioritize technologies that enhance productivity and operational resilience.
Based on geography, the Global Smart Electric Actuator market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
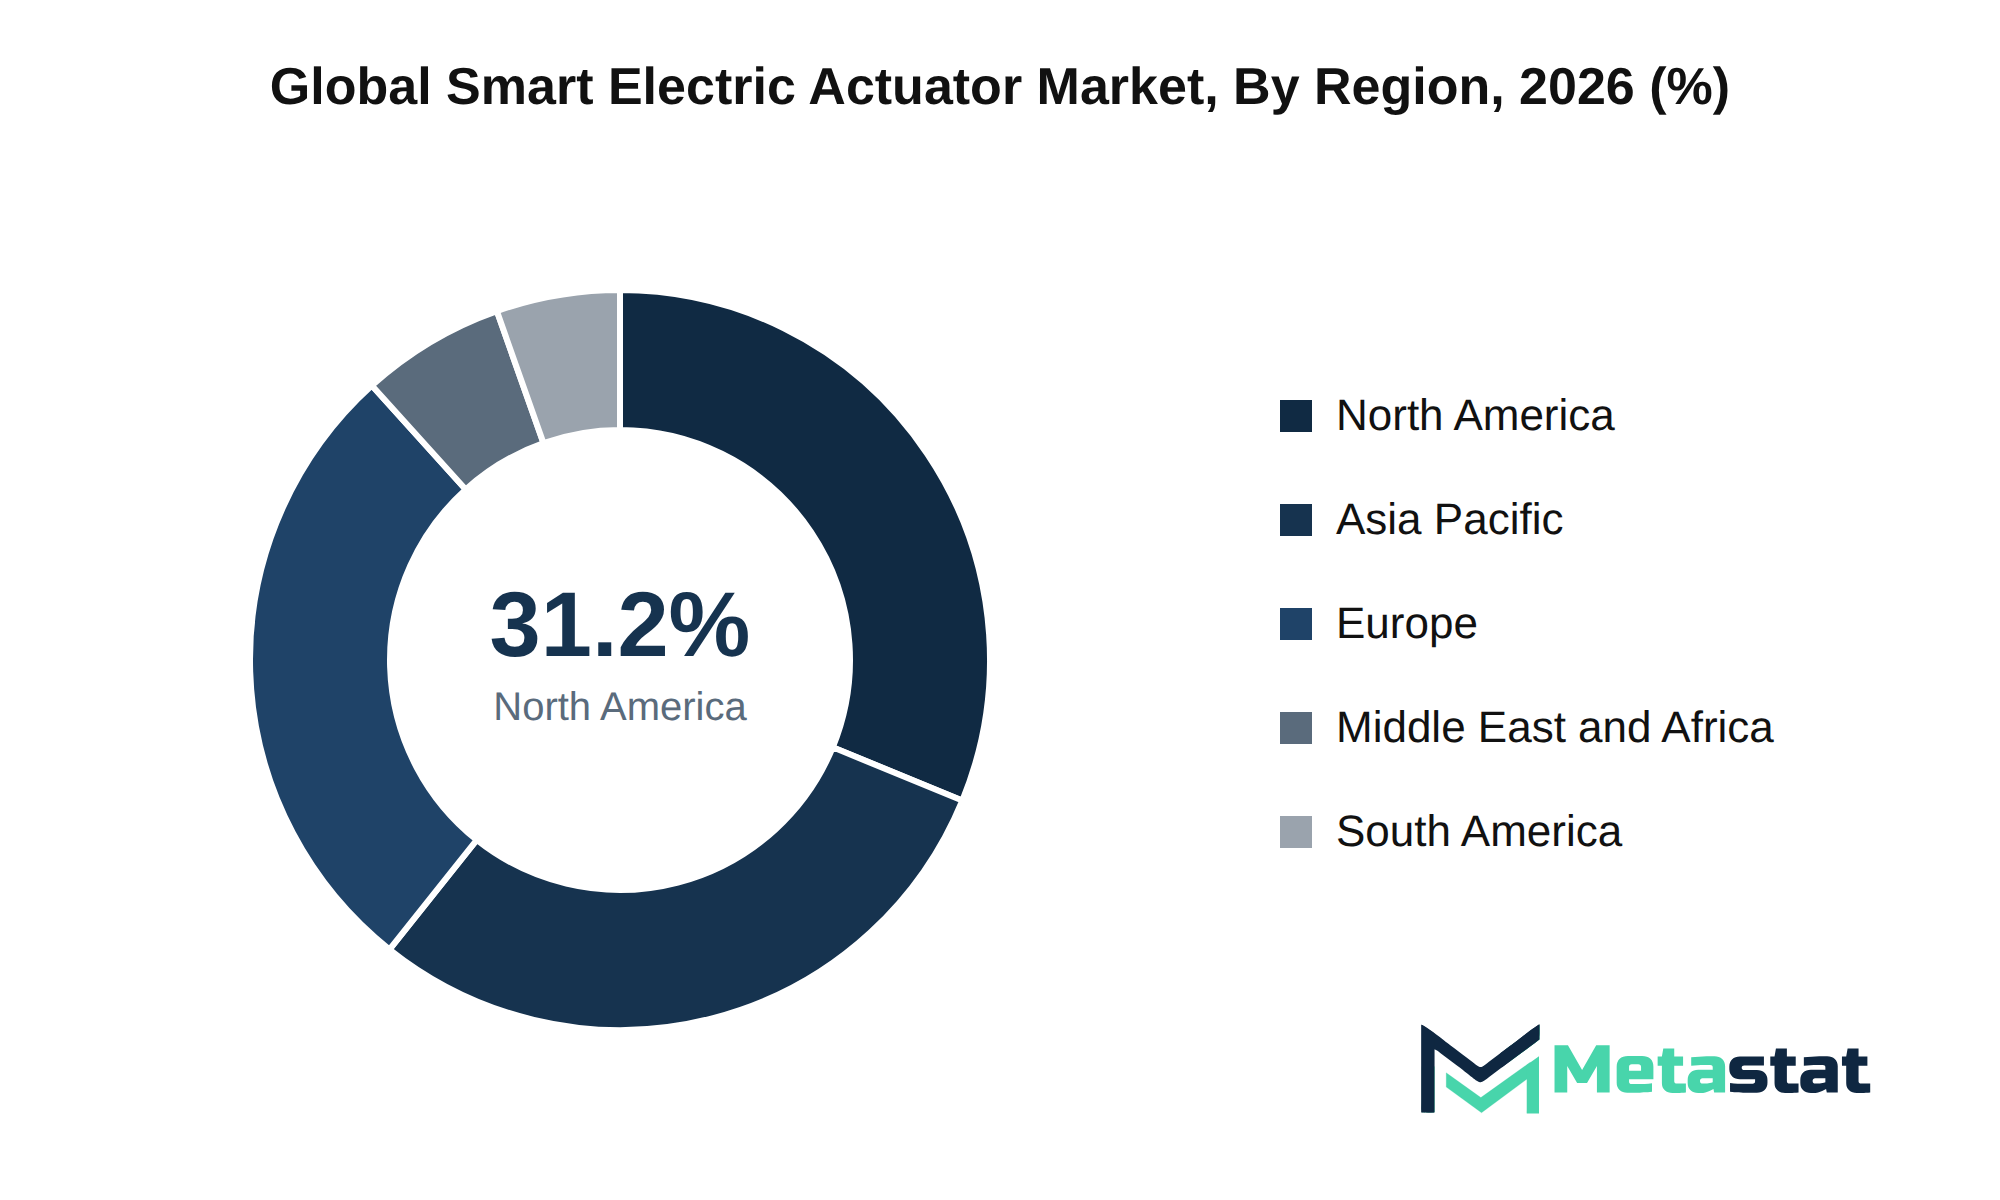
Demand for smart electric actuators in North America benefits from substantial investments in automation technologies across various industries. The region's focus on modernizing infrastructure, particularly in oil and gas, power generation, and water management, fuels this demand. North America accounts for a considerable share of the global market, reflecting its vital role in the sector. The Smart Electric Actuator market is projected to reach USD 1,609 million by the end of 2033, with a compound annual growth rate (CAGR) of 5.9% during the forecast period.
Countries including the United States, Canada, and Mexico exhibit a high demand for efficient motion control solutions, driven by the need for enhanced operational efficiency and reliability. The oil and gas sector, valued at USD 759.9 million in 2026, reflects strong growth potential due to ongoing projects and asset modernization efforts. Increased focus on sustainability and energy-efficient practices further advances the market, creating opportunities for innovative solutions.
Regional vendors leverage localized manufacturing capabilities to enhance supply chain efficiencies and reduce lead times. This regionalization aligns with nearshoring initiatives that prioritize local production, thereby addressing challenges associated with global supply chain disruptions. Enhanced infrastructure readiness and regulatory frameworks support the expansion of the smart electric actuator market in North America while creating a competitive landscape characterized by established players and emerging entrants.
The Smart Electric Actuator market in Europe benefits from a robust industrial infrastructure and a significant push towards automation across various sectors. Countries including Germany, France, and the UK exhibit strong demand stemming from advanced manufacturing capabilities and ongoing investments in technology enhancements. The region's focus on environmental sustainability drives the adoption of smart solutions, including electric actuators, particularly in industries like oil and gas, power generation, and water management.
Investment in smart technologies evolves alongside stringent regulatory frameworks aimed at improving energy efficiency and reducing carbon emissions. This regulatory environment encourages innovation within the market, motivating manufacturers to develop more efficient and sustainable solutions. Emerging market front-runners in Europe, particularly in Germany and France, lead the way in implementing smart electric actuators across diverse applications, including robotics, automation, and damper actuation.
Localized procurement dynamics and cultural nuances influence B2B buying behaviors within the region, with companies prioritizing suppliers that offer innovative and compliant products. While the market matures, high-value replacement cycles emerge, driving consistent revenue opportunities for established players while enabling newer entrants to capture market share. Continued investment in infrastructure modernization supports growth because industries seek to upgrade legacy systems with advanced smart electric actuators.
European manufacturers focus on localized manufacturing densities to enhance supply chain efficiency and reduce lead times. This regionalization strategy aligns with cross-border trade corridors that facilitate the movement of goods across countries. The competitive landscape features several domestic market participants, including Rotork plc, Emerson Electric Co., and Flowserve Corporation, who actively pursue foreign direct investment opportunities to expand their geographic presence and technological capabilities within the smart electric actuator market.
The Asia-Pacific region is integral to the Smart Electric Actuator market, driven by the rapid adoption of automation technologies across various industries. Countries including China, Japan, and India exhibit strong demand for smart electric actuators, influenced by increased focus on efficiency and process optimization. Infrastructure modernization initiatives contribute to the expansion of the market, with investments aimed at enhancing operational capabilities and reducing energy consumption.
In South Korea and Australia, advancements in industrial automation and robotics significantly drive the adoption of smart electric actuators. The integration of these technologies within manufacturing processes improves productivity and minimizes operational costs. Emerging markets within Southeast Asia show potential for growth, attributed to local industries increasingly recognizing the benefits of automation and smart technologies.
Market dynamics in the region reflect a combination of mature sectors and emerging opportunities. High-value replacement cycles characterize established industries, while incremental growth vectors emerge from new applications in robotics and automation. The regional competitive landscape features both domestic market participants and international players, creating a dynamic environment for innovation and collaboration.
Localized procurement dynamics and cultural nuances shape B2B buying behaviors in this region. Companies prioritize suppliers that demonstrate reliability, compliance with local regulations, and strong service support. The continuing evolution of energy grid resiliency and local infrastructure readiness supports the market's growth trajectory, ensuring that smart electric actuators align with regional requirements.
Overall, the Asia-Pacific region is expected to maintain a significant share of the global Smart Electric Actuator market, leveraging both technological advancements and evolving industry demands to drive future growth.
The Smart Electric Actuator market in South America is projected to experience growth driven by increased adoption across various industries, including oil and gas, resulting from companies modernizing their operations. Brazil and Argentina represent the primary markets within the region, characterized by a focus on enhancing infrastructure and energy efficiency, which supports demand for smart electric actuators.
Investment in local manufacturing and supply chain regionalization contributes to competitive advantages for domestic players. Efforts to meet local compliance mandates and regulatory frameworks will influence procurement dynamics in the market. By leveraging geographical advantages and enhancing energy grid resiliency, stakeholders improve operational efficiency and reduce costs.
Looking ahead, the market is expected to benefit from cross-border trade corridors and strategic foreign direct investment (FDI) initiatives, which will facilitate further expansion. The growing emphasis on automation initiatives highlights opportunities for localized vendors to capture market share in this underpenetrated territory.
Overall, sustained interest in advanced automation solutions within South America positions the Smart Electric Actuator market for incremental growth, supported by evolving regional dynamics.
The Smart Electric Actuator market in the Middle East and Africa exhibits distinct characteristics influenced by various factors. The region's market share accounted for 6.3% in 2025, reflecting a growing interest in automation and efficiency across several key industries. Countries including Saudi Arabia and the UAE are increasing investments in infrastructure modernization and technological advancements, positioning themselves because emergent leaders in the market.
Demand for smart electric actuators is driven by the expansion of sectors including oil and gas, power generation, and water management. Saudi Arabia's focus on diversifying its economy and reducing dependency on oil revenues enhances the adoption of automation technologies. The UAE's initiatives in renewable energy and smart city projects further stimulate market growth.
South Africa presents opportunities for growth through its ongoing industrialization efforts. The country's drive towards modernizing its infrastructure aligns with the increasing demand for smart electric actuators. Regional supply chain dynamics, including localized manufacturing, play a significant role in meeting market demands effectively.
Geopolitical factors and trade policies significantly impact the competitive landscape of the market. Localized procurement dynamics and cultural nuances influence B2B buying behaviors, requiring vendors to tailor their approaches for effective market entry. Strategic foreign direct investment flows into the region contribute to the development and consolidation of domestic vendors, creating a competitive environment.
The Smart Electric Actuator market stands to benefit from the region's resource availability and energy grid resiliency, which support the implementation of advanced automation solutions. Continued investments and a focus on technological innovation are expected to drive growth in this market segment.
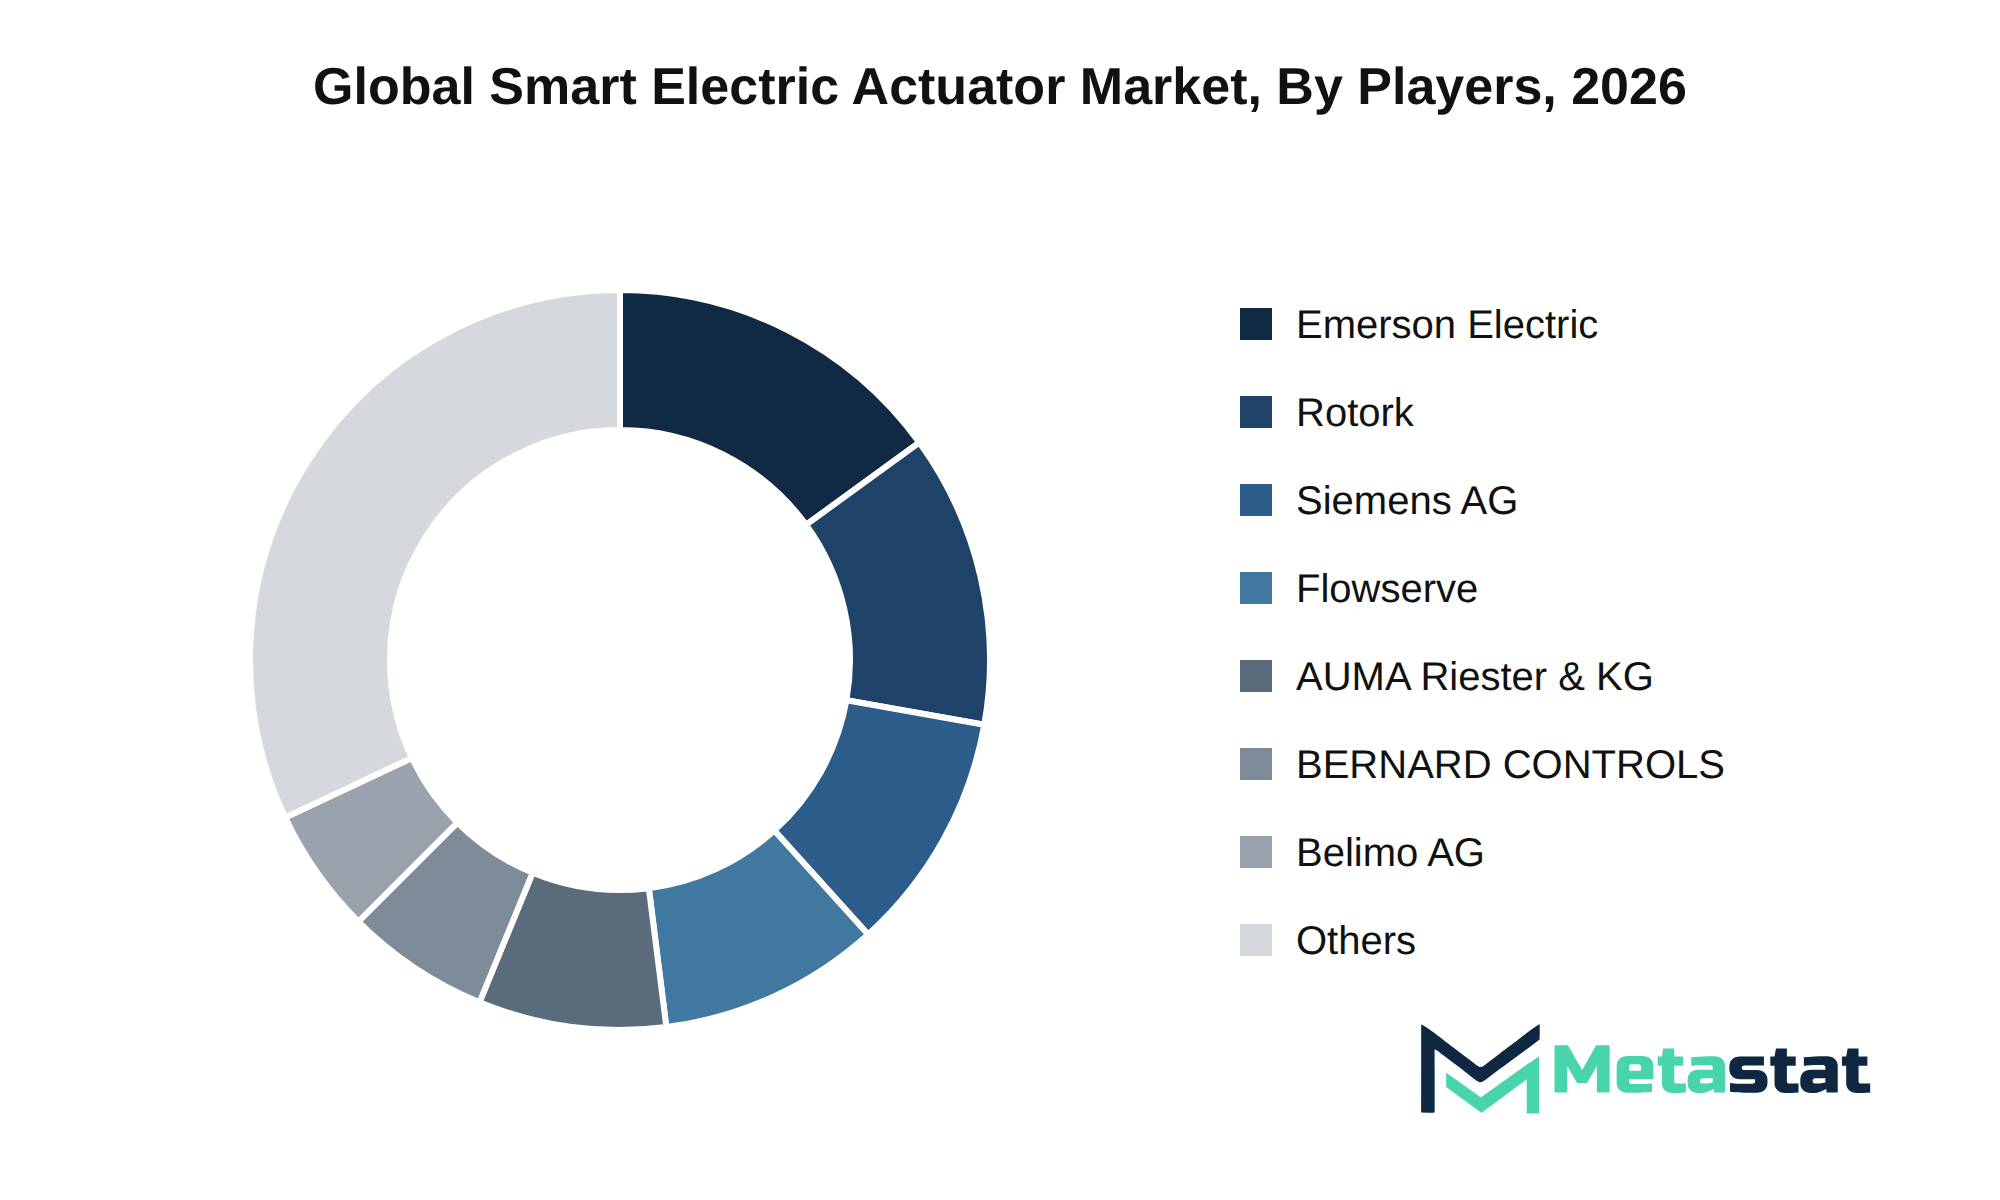
The Smart Electric Actuator market experiences significant strategic dynamics driven by mergers, acquisitions, and alliances among key players. Companies including Rotork plc and Emerson Electric Co. engage in strategic consolidation to enhance their market presence and drive innovation. Collaborations with firms like AUMA Riester GmbH & Co. KG and Flowserve Corporation strengthen product offerings, allowing for more comprehensive solutions across various applications.
Product differentiation is essential for maintaining competitive advantages in the market. Companies invest in research and development to create unique capabilities, exemplified by BERNARD CONTROLS and Valmet Corporation, which focus on proprietary technologies and advanced actuator functionalities. These innovations directly address the varying demands of industries including oil and gas, power generation, and water and wastewater management.
Pricing architectures and commercial models adopted by players including Bray International, Inc. and SAMSON AG reflect the value perceived by customers. Competitive pricing, combined with strong customer retention strategies, fortifies brand equity and switching costs for end-users. Future competitive outlooks indicate an ongoing emphasis on developing robust supply chain management and procurement leverage, setting the stage for sustained growth in the Smart Electric Actuator market.
Market size is forecast to rise from USD 3,484.6 million in 2025 to over USD 5,514 million by 2033. The base case reflects a growth trajectory with a compound annual growth rate (CAGR) of 5.9%. This forecast aligns with anticipated developments across various sectors influencing the Smart Electric Actuator market.
Downstream demand changes, driven by the maturation of core industries, highlight increased adoption of smart electric actuators for improved efficiency and automation. The integration of next-generation technologies and rapid advancements in research and development (R&D) commercializations lead to enhanced product offerings and shorter life cycles, creating a dynamic environment for market participants.
Regulatory evolution and compliance milestones will continue shaping the competitive landscape. Increased scrutiny on environmental and efficiency standards pushes manufacturers to adapt and innovate. Geopolitical realignments and evolving trade corridors impact global supply chain structures, necessitating strategic capital allocation and infrastructure commitments.
Emerging white-space opportunities arise from unmet enterprise needs, particularly in sectors including robotics and automation. Integration of smart electric actuators significantly enhances operational performance. Identifying high-growth pockets within these segments provides a roadmap for future growth recommendations, enabling companies to capitalize on strategic imperatives for sustained market presence.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Smart Electric Actuator market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 5.9% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Actuator Motion Type, Application, Power Supply Type, End-Use Industry, and Region |
By Region | North America (By Actuator Motion Type, Application, Power Supply Type, End-Use Industry, and Country)
|
Europe (By Actuator Motion Type, Application, Power Supply Type, End-Use Industry, and Country)
| |
Asia Pacific (By Actuator Motion Type, Application, Power Supply Type, End-Use Industry, and Country)
| |
South America (By Actuator Motion Type, Application, Power Supply Type, End-Use Industry, and Country)
| |
Middle East and Africa (By Actuator Motion Type, Application, Power Supply Type, End-Use Industry, and Country)
|
Find answers to common questions about this report
The Smart Electric Actuator market size was valued at USD 3,484.6 million in 2025, according to the Metastat Insights study.
The Smart Electric Actuator market is projected to grow at a CAGR of 5.9% during the forecast period from 2026 to 2033.
The North America Smart Electric Actuator market size is estimated to reach USD 1,609 million by 2033.
The segment of Part-Turn / Quarter-Turn Electric Actuators leads the Smart Electric Actuator market, with a projected value of USD 1,971.8 million by 2033. This segment demonstrates the highest growth potential compared to others in the market.
Key drivers for the Smart Electric Actuator market include technological integration, advancements in automation and artificial intelligence, and a focus on sustainability. Industries are prioritizing smart electric actuators for improved efficiency, performance, and reliability, while digital transformation enhances operational productivity and reduces costs across various sectors.
North America holds the dominant share of the Smart Electric Actuator market, with a value of USD 1,609 million projected for 2033, representing 31.2 percent of the total market.
High capital investment requirements present a significant restraint in the Smart Electric Actuator market, limiting entry for smaller players and hindering expansion for existing firms. escalating operating costs, driven by labor shortages and increased material prices, challenge profitability and restrict available resources for technology upgrades. Supply chain disruptions further complicate production schedules and customer satisfaction.
Technological integration, sustainability concerns, and the shift towards automation are favoring product adoption in the Smart Electric Actuator industry. Industries increasingly invest in smart electric actuators to enhance efficiency, reduce operational costs, and align with environmental mandates, driving growth across sectors including oil and gas, power generation, and water management.
The Smart Electric Actuator market is estimated to reach a valuation of USD 5,514 million by 2033.
Key players operating in the Smart Electric Actuator market include Rotork plc, AUMA Riester GmbH & Co. KG, Flowserve Corporation, Emerson Electric Co., BERNARD CONTROLS, and Valmet Corporation.
Choose Your License
Global Smart Electric Actuator Market
The analysts below cover Machinery & Equipment research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
INDUSTRY CONSULTANT - CHEMICALS & ADVANCED MATERIALS
Chemicals and Materials · Machinery & Equipment · Packaging
Amit Gadhekar Consultant for Chemicals and Materials at MetaStat Insight, directing sector-specific intelligence, research, and strategic consulting across global chemical and processing markets.
PRINCIPAL CONSULTANT - QUALITY SYSTEMS & COMPLIANCE
Electronics and Semiconductor · Machinery & Equipment · Professional Services
Omkar Phadtare is an Industry Consultant at MetaStat Insight, specializing in quality systems, regulatory compliance, and standards benchmarking to drive data-driven market intelligence and strategic industry research.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Assessing commercial microgrid software adoption requires looking past top-level installation numbers and examining utility interconnection queues. The research provided verifiable data on average permitting timelines, tariff structures, and battery storage integration costs across regional utility territories. That grounded perspective was valuable for our team when building five-year demand projections for industrial microgrid controllers.
Ambulatory surgical centers have very different purchasing cycles for robotic-assisted surgery platforms than major hospital networks. The MetaStat Insight study focused squarely on capital expenditure depreciation, procedural reimbursement pathways, and surgeon training overhead. That operational clarity made it much simpler to validate multi-year procedure growth forecasts against actual ambulatory center adoption patterns.
When planning edge sensor rollouts across refinery environments, generic IoT reports typically miss the harsh-environment certification bottlenecks. MetaStat Insight gave an objective evaluation of ATEX and Class 1 Division 2 hardware availability, along with realistic five-year maintenance cycle cost projections. The comparison of wireless mesh versus private cellular backhaul helped our team pressure-test network reliability models for remote processing facilities.
Explore related market intelligence reports worth reading alongside this one.