
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Ultrasound Image Analysis Software Market Size, Share, By Software type (Integrated software and Standalone software), By Analytical technology (AI-enabled analysis and Conventional analysis), By Clinical application (Cardiology, Obstetrics and gynecology, Abdominal imaging, Breast and thyroid imaging, Vascular imaging, Musculoskeletal imaging and Others), By End user (Hospitals, Diagnostic imaging centers, Specialty clinics and Academic and research institutions), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-5614
Published
October, 2026
Pages
279 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
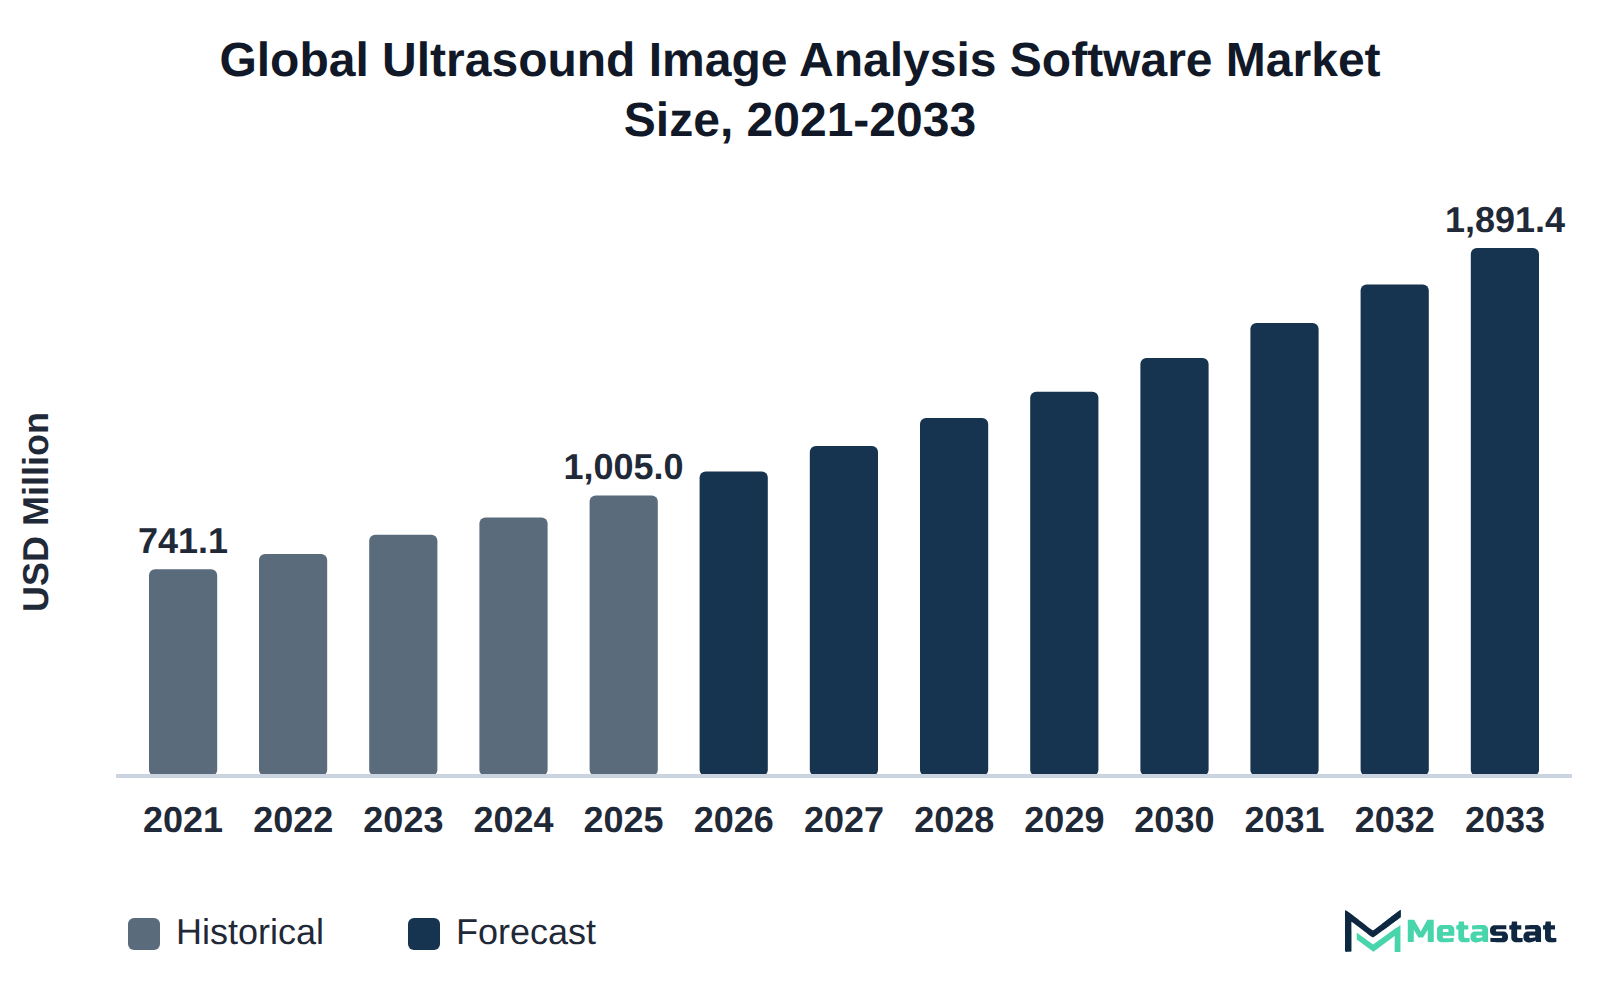
Market Valuation: Valued at $1,005 Million in 2025, projected to reach $1,891.4 Million by 2033 at a 8.2% CAGR.
Dominant Segment: Integrated software leads the Ultrasound Image Analysis Software market, driven by its ability to streamline workflows and enhance diagnostic accuracy for healthcare providers.
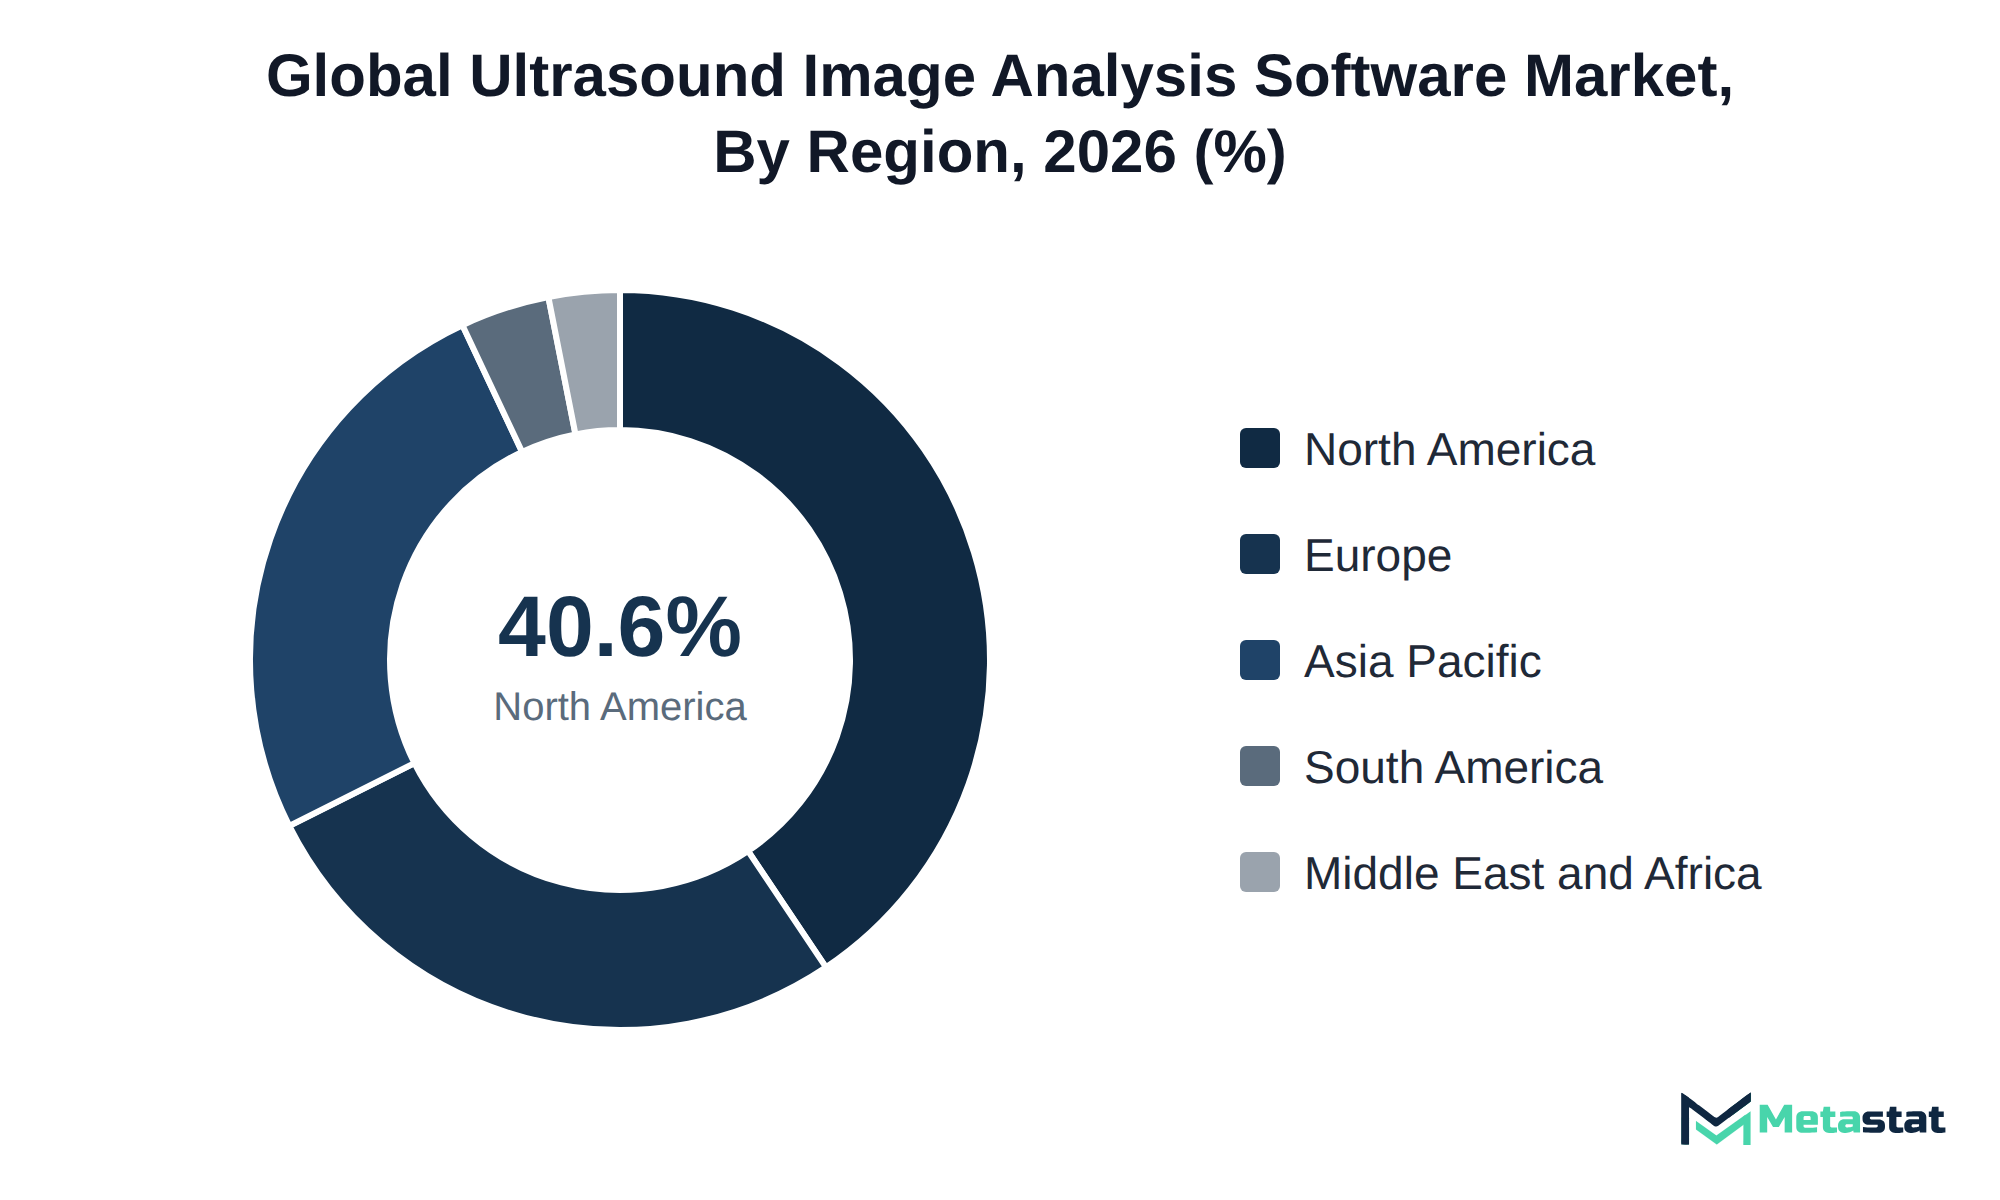
Geographic Lead: North America is the leading region, accounting for 40.6% of the market in 2025, with the US projected to maintain its dominance through 2026 due to established healthcare infrastructure.
What's Inside: The report provides a comprehensive analysis of the market, covering software types, analytical technologies, clinical applications, and end users, along with competitive insights and growth forecasts.
Emerging Technologies: The integration of AI-enabled analysis is a key growth driver, with this segment expected to reach USD 1,057.9 million by 2033, reflecting a significant shift towards advanced imaging capabilities.
Market Dynamics: Challenges such as high costs and margin pressures are impacting software adoption, particularly among smaller healthcare providers, highlighting the need for cost-effective solutions.
Choose Your License
Global Ultrasound Image Analysis Software Market
The global Ultrasound Image Analysis Software market was valued at USD 1,005 million in 2025 and is projected to reach USD 1,891.4 million by 2033, growing at a CAGR of 8.2% over the forecast period.
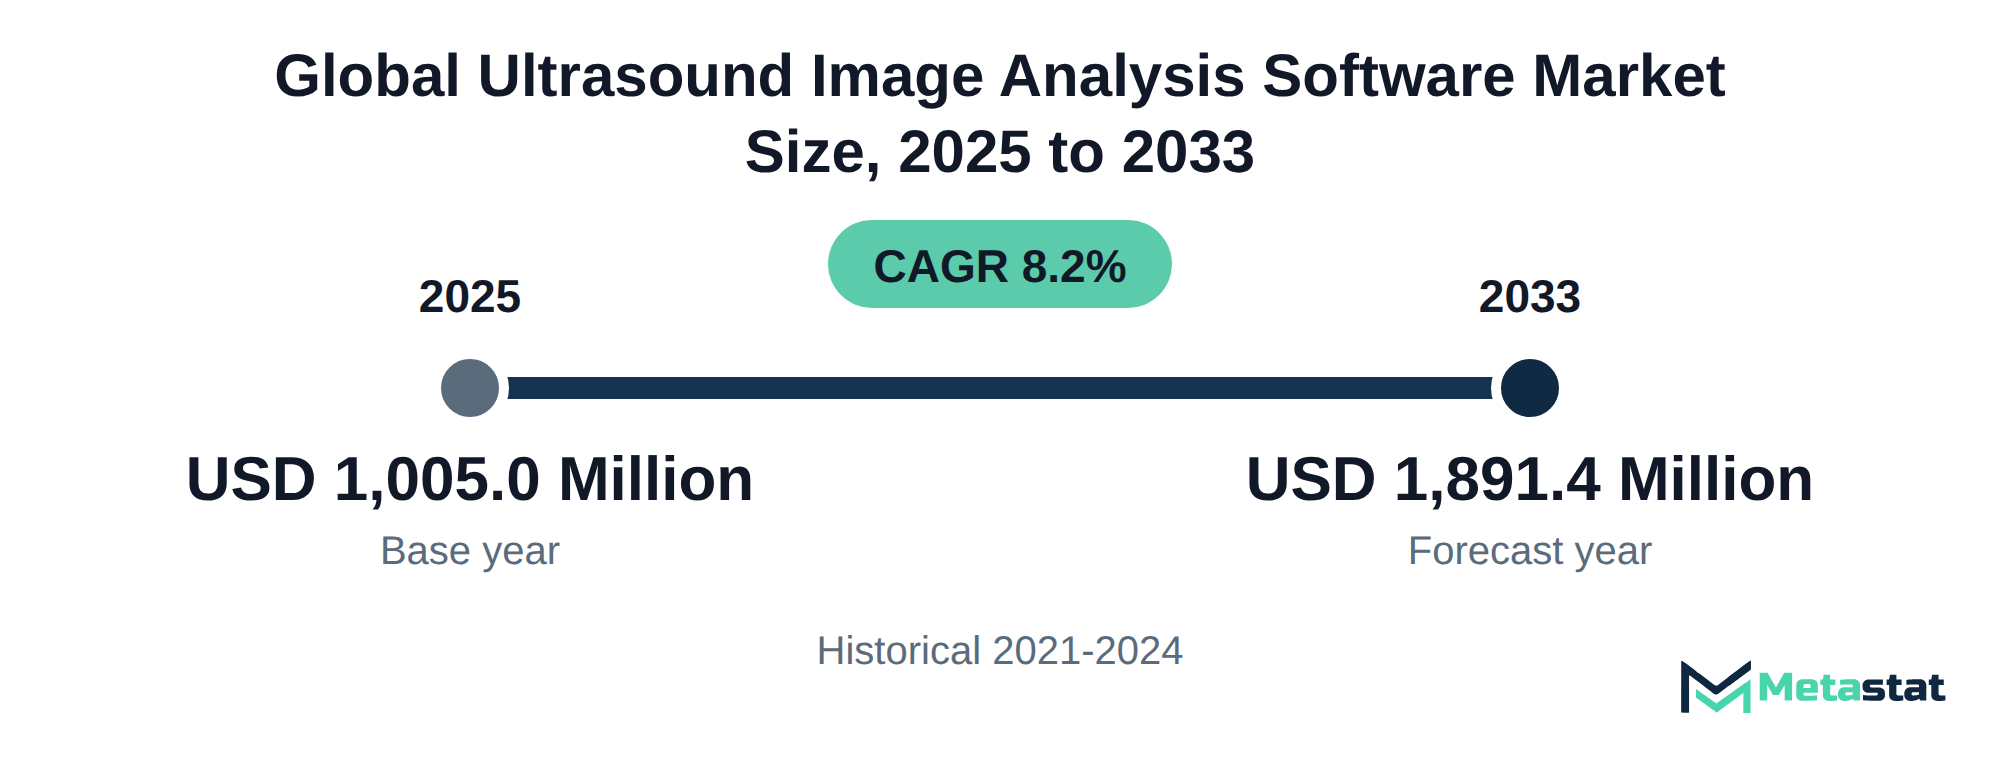
The Ultrasound Image Analysis Software market encompasses software solutions designed to enhance and interpret ultrasound imaging. Buyers invest in these solutions to improve diagnostic accuracy and streamline clinical workflows. Hospitals, diagnostic imaging centers, and specialty clinics form the primary customer base, driven by increasing demand for effective imaging solutions in various clinical applications.
Growth in the market is propelled by technological advancements, particularly in AI-enabled analysis, which enhances image interpretation and diagnostic capabilities. North America holds 40.6% of the market in 2025, with the US leading in 2026. Integrated software is the highest-value segment, reflecting a trend toward single platforms that combine multiple functions.
The demand for efficient and accurate imaging technologies remains a critical factor influencing market expansion. Healthcare providers prioritize investments that improve patient outcomes, raise operational efficiency, and connect easily to existing systems. This focus on quality and efficiency supports a strong growth trajectory in the Ultrasound Image Analysis Software market.
The Ultrasound Image Analysis Software market facilitates improved diagnostic capabilities for healthcare providers, addressing critical needs in patient care and clinical efficiency. Buyers invest in these solutions to enhance diagnostic accuracy, streamline workflows, and reduce operational costs. Growing adoption among hospitals and diagnostic imaging centers reflects the increasing reliance on advanced imaging technologies to support clinical decisions and improve patient outcomes.
Key market growth is driven by rising demand for AI-enabled analysis, which significantly enhances image interpretation and diagnostic precision. Hospitals represent the largest segment within the market, reflecting the critical role these institutions play in healthcare delivery. This region's established healthcare infrastructure and investment in innovative technologies contribute to its dominant market position.
Increasing awareness of the benefits of early disease detection and monitoring drives the market forward. The need for more efficient imaging processes to handle the growing patient population creates opportunities for market expansion. Enhanced analytical capabilities and integration with existing healthcare systems further drive demand for advanced ultrasound image analysis solutions through the forecast period.
Automated fetal biometry represents a significant advancement in the Ultrasound Image Analysis Software market, enhancing the accuracy and efficiency of prenatal ultrasound examinations. This technology streamlines the measurement of fetal parameters, which are critical for assessing fetal growth and development. The integration of automated systems into ultrasound workflows reduces the time required for manual measurements, allowing healthcare professionals to focus on patient care.
In 2026, the market for integrated software, a key segment in this evolution, is projected to reach USD 645.1 million, growing to USD 1,054.3 million by 2033, reflecting a compound annual growth rate (CAGR) of 7.3%. Such growth highlights the increasing adoption of advanced imaging technologies by hospitals and diagnostic imaging centers. The automation of processes enhances workflow efficiency and improves image quality control, ensuring consistent and reliable results across various applications.
Implementing automated systems raises the standard of care in prenatal imaging, directly impacting patient outcomes and operational effectiveness. As healthcare places more emphasis on technology-driven solutions, demand for ultrasound image analysis software with automated biometry is expected to increase and shape purchasing decisions.
Vendor-independent cardiac strain analysis is gaining traction within the Ultrasound Image Analysis Software market, largely driven by the increasing demand for precise cardiac evaluation. This analytical approach enhances the interpretation of echocardiography data, allowing clinicians to quantify cardiac strain without reliance on proprietary software from specific vendors. The expansion of this capability aligns with market forecasts of USD 1,891.4 million by 2033, a compound annual growth rate (CAGR) of 8.2% from the base year of 2025.
Pricing models for these software solutions often feature both subscription-based and one-time payment options. Subscription models appeal to hospitals and diagnostic imaging centers seeking to manage costs over time, while one-time purchases suit institutions desiring ownership of the software. Flexible pricing structures support broader adoption among hospitals, specialty clinics, and other end users, widening access to advanced cardiac analysis tools.
Automated echocardiography quantification represents a significant development within this landscape, promoting efficiency in cardiac assessments. Cardiovascular image fusion software addresses a related need by combining imaging data from different sources to support cardiac assessment. The increasing engagement of healthcare providers in adopting these systems contributes to improved patient outcomes and operational efficiency. Enhanced analytical capabilities support market growth, driven by evolving clinical needs and technological advancements in ultrasound imaging.
The integration of embedded AI within portable ultrasound devices significantly enhances access to image interpretation, particularly for specialty clinics. This shift also relies on the medical ultrasound probe, which captures the images that the software analyzes. This segment, characterized by unique operational needs, often seeks solutions that provide both mobility and advanced analytical capabilities. The rising adoption of AI-enabled analysis, projected to reach USD 1,057.9 million by 2033, highlights increasing demand for innovative technology in the Ultrasound Image Analysis Software market.
Specialty clinics, tasked with delivering immediate care in diverse settings, prioritize systems that offer rapid diagnostics without sacrificing accuracy. Teleradiology services also rely on timely image interpretation. The availability of portable devices equipped with embedded AI facilitates timely interpretation of ultrasound images, enabling practitioners to make informed decisions at the point of care. This shift streamlines workflows and supports improved patient outcomes, driven by timely diagnosis in various medical scenarios.
Portable ultrasound technology with embedded AI capabilities gives specialty clinics effective access to advanced imaging solutions, supporting quality of care and operational efficiency.
Hospitals frequently evaluate the benefits of integrated versus standalone ultrasound image analysis software to enhance operational efficiency and improve patient care outcomes. Integrated software, projected to reach USD 1,054.3 million by 2033, offers interaction with existing hospital systems, thereby streamlining workflows. Hospitals often weigh this against how the software connects to their electronic medical records. This integration enables hospitals to consolidate data management and enhance communication among departments, which is vital for effective patient monitoring and diagnosis.
In contrast, standalone software, estimated to achieve USD 837.1 million by 2033, provides flexibility for hospitals that prioritize specific functionalities without the need for full integration. Standalone solutions often cater to specialized departments, including cardiology or obstetrics and gynecology, where tailored features enhance diagnostic accuracy and efficiency. The rising preference for AI-enabled analysis further influences the decision-making process, with hospitals recognizing the potential for improved diagnostic insights.
The choice between integrated and standalone ultrasound analysis software impacts operational costs, resource allocation, and the overall quality of care within hospitals. The right software type supports the strategic goal of stronger diagnostic capabilities while keeping budgets under control in an increasingly competitive healthcare sector.
The integration of advanced AI techniques transforms ultrasound image analysis in various healthcare settings. The same techniques are part of the wider field of AI in medical imaging. Hospitals, diagnostic imaging centers, and specialty clinics embrace AI-enabled analysis for its potential to improve diagnostic accuracy and efficiency. Increased demand for precise and timely interpretations drives investments in these AI solutions. The AI-enabled analysis segment is expected to increase from USD 445.6 million in 2026 to USD 1,057.9 million by 2033, a compound annual growth rate of 13.1%. This rapid expansion highlights the shift towards technology-driven approaches in image interpretation, enhancing the overall quality of patient care while optimizing operational workflows. Buyers prioritize solutions that streamline processes and improve diagnostic capabilities in a competitive healthcare landscape.
Advancements in imaging technologies drive significant enhancements in ultrasound analysis. The introduction of high-resolution imaging systems allows for detailed visualization of anatomical structures, improving diagnostic accuracy. Increased demand for precision in clinical settings results from a growing emphasis on patient outcomes and the adoption of personalized medicine. Healthcare providers benefit from effective tools that enable accurate diagnoses and treatment plans, addressing the complexities of various medical conditions. The capacity to integrate these advanced technologies into existing systems streamlines workflows, ultimately reducing time spent on image interpretation. While the market evolves, the demand for sophisticated ultrasound image analysis software continues to rise, creating opportunities for innovation in feature sets and capabilities.
Healthcare institutions strive for tools that enhance efficiency and patient care, leading to a proactive approach toward upgrading diagnostic imaging equipment and software. Integrating these technologies supports clinical objectives and strengthens an institution's competitive position in the healthcare sector. This heightened focus on technological capabilities creates an environment conducive to growth within the Ultrasound Image Analysis Software market.
High costs associated with ultrasound image analysis software limit uptake among hospitals and diagnostic imaging centers. Initial investment and ongoing maintenance expenses present barriers that delay implementation. Many facilities face budget constraints, leading to smaller orders and slower transitions to advanced technologies. This situation particularly affects smaller healthcare providers and specialty clinics, which often lack the financial resources for full upgrades. These buyers experience extended replacement cycles, opting to maintain existing systems rather than invest in newer, more efficient software solutions. Overcoming these financial hurdles is essential for enhancing adoption rates and driving growth in the ultrasound image analysis software market in the coming years.
Suppliers in the Ultrasound Image Analysis Software market face significant margin pressure due to increasing competition and rising costs of development and talent. The need for continuous software upgrades and enhancements to meet evolving customer demands results in escalating operating costs. In response, several suppliers are diversifying their product offerings and focusing on niche markets to maintain competitive pricing while shielding profit margins from external pressures. This strategy enables them to target specific segments, including hospitals and diagnostic imaging centers, which prioritize cost-effective solutions. Investments in automated processes and artificial intelligence contribute to reducing operational expenses, allowing suppliers to offer more competitive pricing structures. Streamlined development processes and more efficient marketing further help suppliers manage margin pressure. Adapting their business models helps suppliers sustain profitability in a highly competitive market.
AI-enabled analysis demonstrates the highest growth potential within the Ultrasound Image Analysis Software market, reflecting a CAGR of 13.1% from 2026 to 2033. This segment addresses the increasing demand for advanced diagnostic capabilities, positioning itself as a critical tool for healthcare professionals. The ongoing integration of artificial intelligence into ultrasound imaging enhances the accuracy and speed of analyses, leading to improved patient outcomes. Hospitals and diagnostic imaging centers represent key buyer groups, driven by the need for efficient and precise imaging solutions. The anticipated adoption of AI-enabled analysis is projected to reach USD 1,057.9 million by 2033, highlighting the growing reliance on technology for clinical applications. This shift supports ongoing innovation and investment in the market, creating a competitive environment for suppliers focused on developing advanced solutions.
The Global Ultrasound Image Analysis Software market is segmented based on Software type, Analytical technology, Clinical application, and End user.
This segment primarily aids healthcare providers in performing advanced ultrasound imaging tasks, enhancing diagnostic accuracy and workflow efficiency. Hospitals, diagnostic imaging centers, and specialty clinics apply integrated software for its ability to streamline processes and improve patient outcomes. Growth in the integrated software segment is driven by increasing demand for automated solutions that reduce manual errors and enhance image analysis. Compared to standalone software, which exhibits a higher CAGR of 9.4%, integrated software offers a more comprehensive solution but typically at a lower price point. This price differentiation influences buyer preferences, with healthcare facilities balancing cost and functionality when implementing ultrasound image analysis solutions.
Standalone software segment is estimated to reach USD 837.1 million by 2033, at a CAGR of 9.4% during the forecast period. This software type provides specialized analysis for ultrasound images, serving a variety of healthcare settings, including hospitals and diagnostic imaging centers. The growth of this segment is driven by increasing demand for efficient diagnostic tools that enhance clinical decision-making. Hospitals frequently adopt standalone software due to its flexibility and capability to integrate with existing systems without the extensive overhaul that integrated software requires. The distinct growth trajectory, indicated by a higher CAGR compared to integrated software, reflects a strong preference among certain buyer groups for specialized, standalone solutions. A notable driver within this segment involves advancements in user-friendly interfaces, enhancing workflow efficiency and overall diagnostic accuracy. This focus on usability differentiates standalone software from integrated options, appealing to environments where rapid analysis and deployment are critical.
This technology employs artificial intelligence to enhance diagnostic accuracy and efficiency in ultrasound imaging. Digital pathology is another diagnostic field where AI-based image analysis is applied. It is predominantly used by healthcare facilities, including hospitals and diagnostic imaging centers, which seek to improve patient outcomes and streamline workflow processes. The rapid advancement of AI technologies drives adoption, resulting in a significant competitive advantage for providers adopting these solutions. Compared to conventional analysis, which shows a CAGR of 3.7%, AI-enabled analysis stands out with its faster growth rate, reflecting increasing demand for sophisticated imaging capabilities. The rising emphasis on personalized medicine and early diagnosis fuels the expansion of this segment, further distinguishing it within the market.
Conventional analysis segment is estimated to reach USD 833.6 million by 2033, at a CAGR of 3.7% during the forecast period. This segment involves traditional ultrasound imaging techniques that healthcare providers use to assess and diagnose various medical conditions. Hospitals and diagnostic imaging centers primarily rely on this segment for routine examinations, focusing on established methods of image interpretation. The segment experiences slower growth compared to AI-enabled analysis, which has a CAGR of 13.1% during the same period. One factor influencing conventional analysis is the ongoing demand for cost-effective solutions in imaging, while advancements in AI-driven technologies create competition. These dynamics result in a need for conventional analysis to maintain relevance in an evolving market.
The cardiology segment is valued at USD 296.2 million in 2026 and is projected to reach USD 501 million by 2033, at a CAGR of 7.8% during the forecast period. This segment serves critical functions in diagnosing and managing cardiovascular conditions, primarily used by hospitals and diagnostic imaging centers. The increasing prevalence of heart diseases drives demand for advanced imaging solutions, enabling better diagnostic accuracy and treatment planning. Compared to other segments, cardiology exhibits steady growth, influenced by patient demographics and rising healthcare investments. The shift towards AI-enabled analysis enhances the capabilities of ultrasound imaging, resulting in improved patient outcomes and operational efficiency for healthcare providers. With a focus on integrating innovative technologies, the market is positioned for sustainable expansion throughout the forecast period.
The obstetrics and gynecology segment is estimated to reach USD 507.1 million by 2033, at a CAGR of 8.8% during the forecast period. This segment primarily focuses on prenatal care, maternal health monitoring, and gynecological evaluations. Healthcare providers, including hospitals and specialty clinics, use this software to enhance diagnostic accuracy and patient outcomes. The growing demand for early detection of complications during pregnancy and advancements in imaging technologies drive increased adoption in this area. Compared to other clinical applications, the obstetrics and gynecology segment experiences significant growth due to heightened awareness and the need for comprehensive maternal care. Its growth rate exceeds that of conventional analysis, projected at a CAGR of 3.7%. This distinctiveness shows how obstetrics and gynecology software addresses the evolving demands practitioners face.
Abdominal imaging segment is expected to reach USD 331.4 million by 2033. This segment focuses on imaging techniques used to diagnose and monitor conditions affecting organs in the abdominal cavity, including the liver, kidneys, and pancreas. Healthcare providers, including hospitals and diagnostic imaging centers, apply abdominal imaging to enhance patient outcomes through accurate assessments. The increasing prevalence of chronic diseases drives demand for effective imaging solutions, with a growing emphasis on early detection and monitoring. Growth in this segment is supported by advancements in imaging technology and rising awareness among patients regarding the benefits of regular health check-ups. Compared to other clinical applications, abdominal imaging experiences modest growth rates, reflecting a different pace relative to segments like obstetrics and gynecology, which shows a CAGR of 8.8% during the forecast period. The unique clinical applications and specific diagnostic needs differentiate this segment from others in the market.
Breast and thyroid imaging segment is projected to grow at a CAGR of 10.2% during the forecast period. This segment is essential for detecting abnormalities in breast and thyroid tissues, primarily used by healthcare providers including hospitals and specialty clinics. Increasing awareness of breast cancer and thyroid disorders drives significant demand for advanced imaging solutions. Breast cancer mammography screening programs reflect the same emphasis on early detection. The growing emphasis on early diagnosis supports adoption among patients and healthcare practitioners. Compared to other clinical applications, this segment exhibits faster growth, reflecting higher demand for precise imaging technologies. The focus on enhancing diagnostic accuracy and patient outcomes positions this segment favorably within the Ultrasound Image Analysis Software market, allowing for expansion in product offerings and technological advancements.
Vascular imaging involves the use of ultrasound technologies to visualize and evaluate blood vessels and circulatory conditions. This clinical application serves hospitals and diagnostic imaging centers, enabling healthcare professionals to diagnose vascular diseases and assess blood flow. The growing prevalence of vascular disorders drives demand for advanced imaging solutions. Diagnostic findings also guide the use of peripheral vascular devices in treatment. Enhanced accuracy in diagnosing conditions including arterial blockages and venous insufficiencies significantly impacts patient outcomes. Compared to other clinical applications, vascular imaging experiences unique demand dynamics, reflecting increasing adoption of sophisticated imaging software. This segment stands out due to its specialized nature, requiring advanced analytical capabilities to interpret complex vascular data effectively. The distinct needs of clinicians and institutions employing vascular imaging set it apart from broader ultrasound applications, emphasizing the segment's critical role in comprehensive patient care.
Musculoskeletal imaging focuses on the assessment of muscle and skeletal conditions through ultrasound technology. This application is primarily used by hospitals and specialty clinics, enabling healthcare professionals to diagnose injuries, monitor conditions, and guide treatments effectively. Demand for this segment grows due to the increasing incidence of musculoskeletal disorders, including injuries and chronic conditions. Technological advancements in imaging techniques enhance diagnostic capabilities and improve patient outcomes. Compared to other clinical applications, musculoskeletal imaging experiences slower growth, while the cardiology and obstetrics segments expand at faster rates. Specialized equipment for musculoskeletal analysis often incurs higher costs, impacting uptake. The ultrasound image analysis software market recognizes the significance of this segment in delivering targeted solutions for specific healthcare needs.
Others (Urology, Ophthalmology, Lung imaging) encompasses applications that extend ultrasound imaging capabilities into specialized areas. This segment serves healthcare providers in diagnosing and managing conditions affecting the urinary tract, eyes, and lungs. Demand within this segment is driven by the increasing prevalence of urological disorders and pulmonary diseases, alongside the growing emphasis on early detection and prevention strategies. Unlike larger segments, this sub-segment often encounters challenges related to the integration of advanced technologies, resulting in a slower growth trajectory compared to broader applications including cardiology and obstetrics. The market for ultrasound image analysis software experiences varying degrees of adoption influenced by specific clinical needs and technological advancements, highlighting the essential role of continued innovation in enhancing diagnostic capabilities.
Hospitals segment is valued at USD 674.1 million in 2026 and is projected to reach USD 1,103.1 million by 2033, at a CAGR of 7.3% during the forecast period. This segment primarily serves healthcare facilities providing patient diagnostics and treatment through ultrasound technology. Increasing demand for efficient diagnostic tools drives investments in advanced software solutions to enhance imaging capabilities. Hospitals seek reliable and integrated software systems to improve workflow and patient outcomes. Compared to diagnostic imaging centers, which see a higher growth rate of 10%, hospitals exhibit steady growth, reflecting a more established infrastructure and funding sources. The adoption of innovative analytical technologies, particularly AI-enabled solutions, significantly influences performance in this segment, distinguishing it from others by focusing on comprehensive patient care and extensive use of ultrasound technologies in clinical settings.
Diagnostic imaging centers segment is estimated to reach USD 449.4 million by 2033, at a CAGR of 10% during the forecast period. This segment serves facilities that specialize in imaging services, providing detailed diagnostic support to physicians and patients. Rising demand for accurate and efficient imaging techniques drives growth in this segment, with more patients seeking imaging services for various medical conditions. The shift towards outpatient care models boosts the utilization of diagnostic imaging centers compared to hospitals, which offer a broader range of services. The market for diagnostic imaging centers exhibits a faster growth rate than other segments due to increasing preference for specialized facilities and technological advancements enhancing imaging capabilities.
The specialty clinics segment is expected to reach USD 253.3 million by 2033. This segment provides focused healthcare services, often specializing in specific medical fields including dermatology, cardiology, and orthopedics. Demand for ultrasound image analysis software in specialty clinics arises from the increasing need for precise diagnostics and personalized patient care. The growth of this segment reflects a CAGR of 10% during the forecast period, indicating a faster pace compared to other end-user segments. Preference for advanced imaging solutions drives investment, particularly in clinics aiming to enhance service offerings. Specialty clinics typically invest in standalone software solutions due to budget considerations, differentiating them from hospitals, which lean towards integrated systems for broad operational needs. Overall, the growth in specialty clinics highlights a shift towards specialized diagnostic capabilities within the broader market.
Academic and research institutions segment is projected to grow at a CAGR of 7.7% during the forecast period. This segment primarily focuses on the application of ultrasound image analysis software for educational and research purposes, used by universities, medical schools, and research organizations. The demand for advanced imaging technologies drives this segment, with institutions seeking enhanced tools for research in diagnostics and clinical practices. Compared to hospitals, which emphasize immediate clinical utility, academic institutions prioritize innovation and education, leading to different purchasing decisions. This segment experiences slower growth relative to diagnostic imaging centers, which exhibit a CAGR of 10%, reflecting the more constrained budgets typical of educational settings. Increased interest in AI-enabled analysis contributes to advancements in research capabilities, influencing investment decisions in technology and software development. The market recognizes the unique role of academic and research institutions in shaping future applications of ultrasound image analysis software.
Based on geography, the Global Ultrasound Image Analysis Software market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Demand in North America for the Ultrasound Image Analysis Software market is driven by a significant presence of hospitals and diagnostic imaging centers across the United States, Canada, and Mexico. These facilities require advanced imaging solutions to enhance diagnostic accuracy and improve patient outcomes. The Federal Drug Administration (FDA) in the United States plays a critical role in regulating software applications in this sector, ensuring that products meet safety and efficacy standards. By the end of 2033, North America is projected to reach USD 715.3 million, reflecting a strong growth trajectory supported by technological advancements. The market holds a 2025 share of USD 1,004.1 million, highlighting the region's importance in the global market for ultrasound image analysis.
Europe's share of the market reaches 27.0% in 2025, supported by advancements in healthcare technology and a growing preference for non-invasive diagnostic methods. Countries including Germany, France, the UK, Italy, and Spain exhibit strong demand for ultrasound image analysis solutions, driven by the increasing prevalence of chronic diseases and the need for accurate diagnostic tools in medical settings. Regulatory frameworks in Europe emphasize high standards for medical devices, ensuring quality and safety. Enhanced investment in healthcare infrastructure and a focus on improving patient outcomes contribute to the region's growth. The integration of AI-enabled analysis technologies increases efficiency and accuracy in clinical applications, particularly in cardiology and obstetrics and gynecology.
With a 25.4% share of the global market in 2025, Asia-Pacific contributes to the growth of the Ultrasound Image Analysis Software market. Demand for this technology is driven by increasing healthcare investments and advancements in medical imaging infrastructure, particularly in countries like China and India. Rapid urbanization, coupled with a growing population and rising awareness of diagnostic imaging, fuels the adoption of ultrasound solutions across various clinical applications. Australia and Japan emphasize integrating AI-enabled analysis, which enhances diagnostic capabilities. The region's diverse healthcare landscape, supported by government initiatives and funding programs, further supports market expansion. Specialty clinics and diagnostic imaging centers emerge as key users, seeking advanced solutions to improve patient outcomes and streamline operations.
In South America, the market experiences unique challenges and opportunities. Brazil and Argentina serve as the primary drivers of demand for ultrasound technologies. The healthcare infrastructure in these countries faces constraints, including limited access to advanced diagnostic tools and a growing need for improved healthcare outcomes. Investment in healthcare initiatives aims to enhance diagnostic capabilities, directly influencing the adoption of ultrasound image analysis software. The market is projected to contribute 3.9% to the global landscape by 2025. Growing awareness of non-invasive procedures and the effectiveness of ultrasound imaging in various clinical applications strengthens market growth in this region. The ultrasound image analysis software market benefits from targeted investments and initiatives aimed at improving healthcare delivery in South America.
Demand for the Ultrasound Image Analysis Software market in the Middle East and Africa stems primarily from hospitals and diagnostic imaging centers focusing on advanced imaging solutions. Countries including Saudi Arabia and the UAE invest in healthcare infrastructure improvements, driven by initiatives aimed at enhancing diagnostic capabilities. South Africa contributes to demand through a growing emphasis on innovative healthcare technologies to address local health challenges. This regional market represents a 3.1% share of the global market in 2025, reflecting strong interest in ultrasound technologies across various medical applications. The market experiences a gradual shift towards AI-enabled analysis, supporting improved diagnostic accuracy and efficiency in clinical practices.
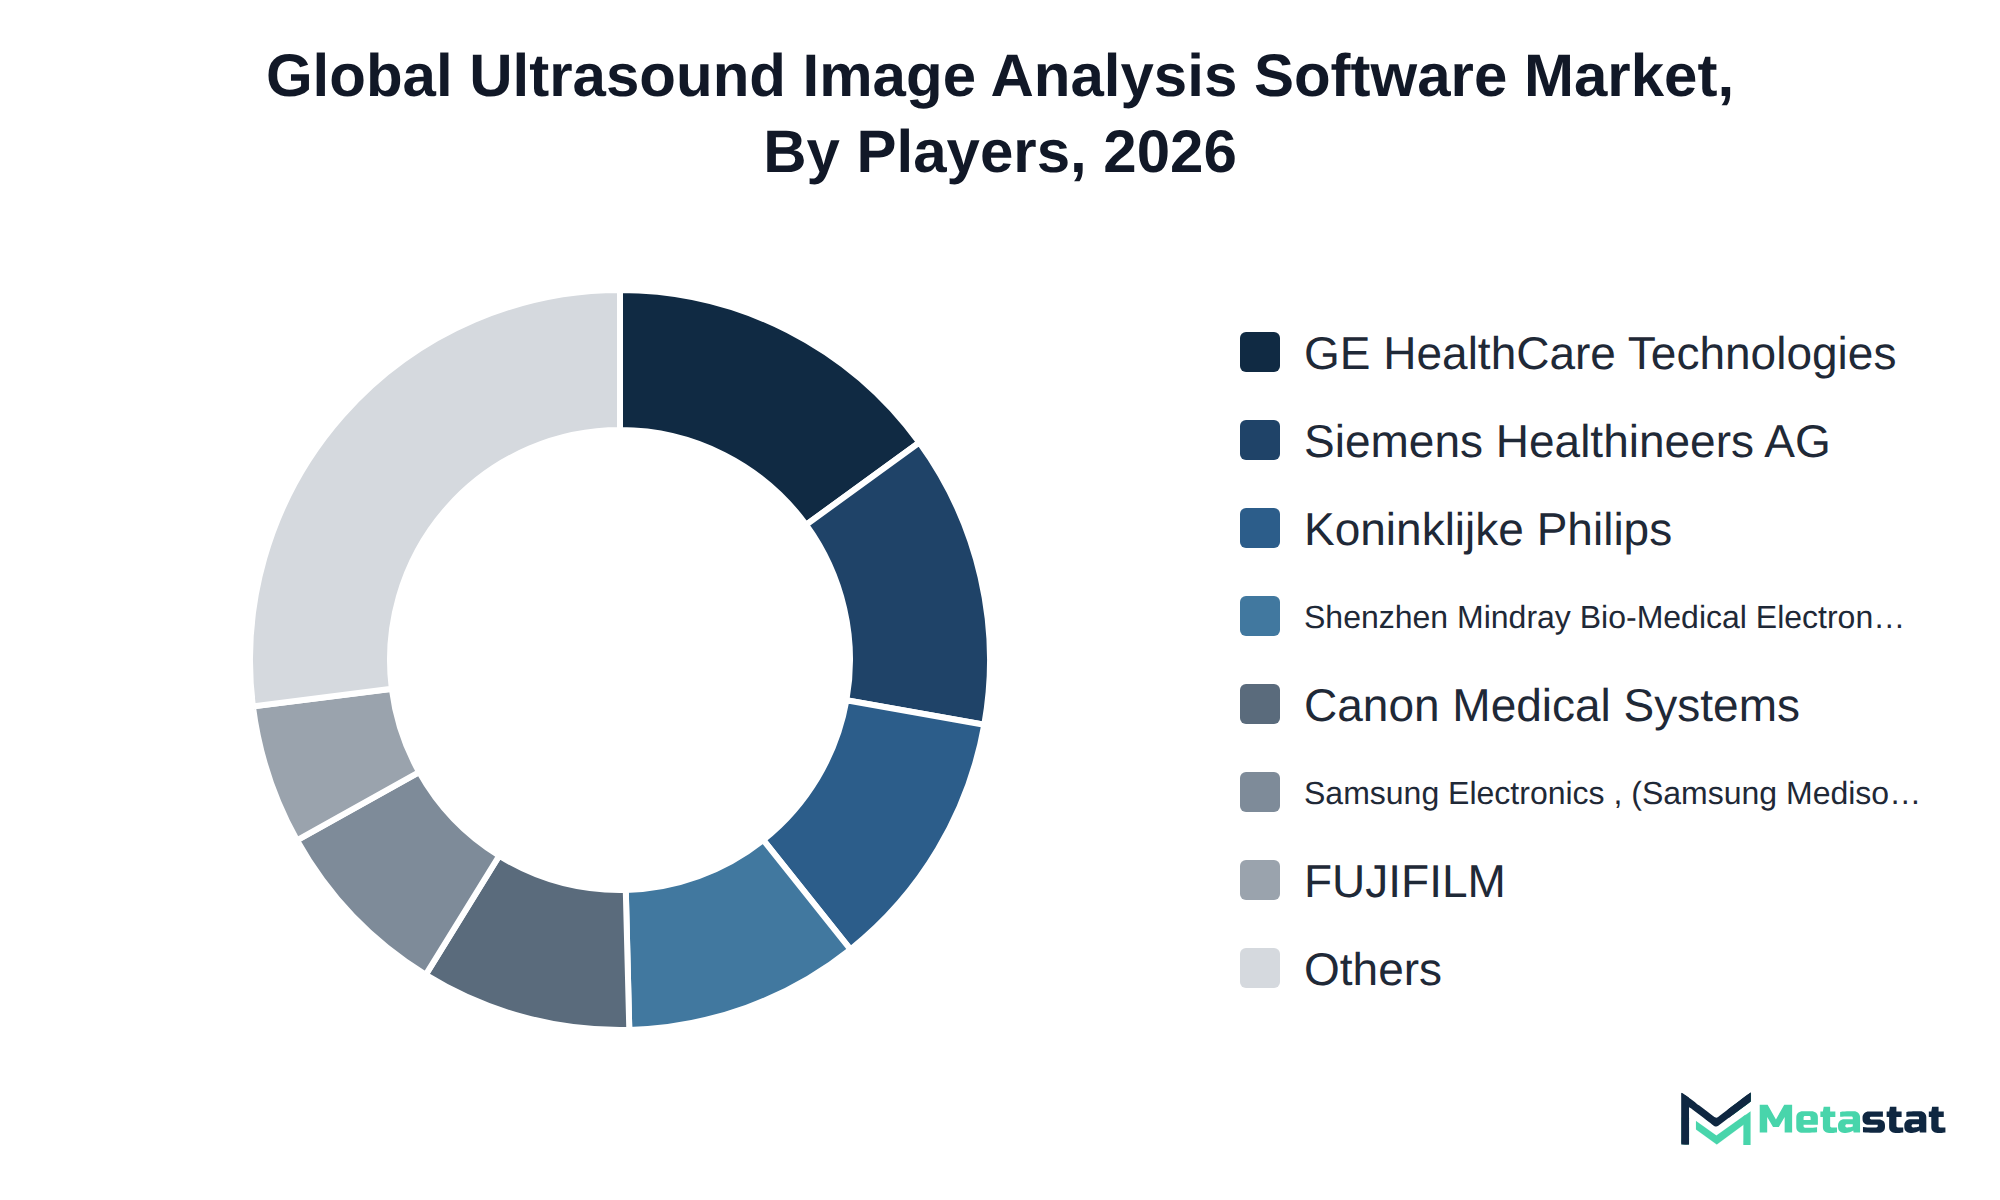
The Ultrasound Image Analysis Software market features diverse competitive dynamics among key players, segmented primarily by software type and analytical technology. Companies employ various strategies to differentiate themselves, focusing on integrated and standalone software solutions, alongside AI-enabled and conventional analysis methods.
Buyers select products based on price, certification, customization, and support services. For instance, GE HealthCare Technologies Inc. emphasizes integrated solutions, using its extensive ecosystem to attract hospitals and diagnostic centers. Siemens Healthineers AG focuses on AI-enabled analysis, appealing to organizations seeking advanced functionalities. In contrast, Canon Medical Systems Corporation prioritizes standalone solutions, catering to specialty clinics and academic institutions with a strong emphasis on customization and support services.
The growth trajectory of the Ultrasound Image Analysis Software market is driven by several key developments. Firstly, the increasing demand for AI-enabled analysis is expected to enhance adoption across clinical applications, particularly in cardiology and obstetrics. This segment is projected to show significant growth, reflecting the greater integration of advanced analytical technologies in healthcare settings.
Secondly, the rise of standalone software solutions will cater to various end users, including hospitals and diagnostic imaging centers, enhancing operational efficiency and patient outcomes. The expansion of integrated software is anticipated to further strengthen the market's growth, with hospitals investing in comprehensive systems to improve diagnostic capabilities.
However, economic constraints and potential regulatory challenges pose risks that could decelerate market momentum. Limited budgets in certain regions, including South America and parts of the Middle East, hinder investments in advanced ultrasound image analysis solutions. These factors will influence the overall market trajectory while stakeholders navigate the evolving landscape.
By Software type: Integrated software, Standalone software
By Analytical technology: AI-enabled analysis, Conventional analysis
By Clinical application: Cardiology, Obstetrics and gynecology, Abdominal imaging, Breast and thyroid imaging, Vascular imaging, Musculoskeletal imaging, Others (Urology, Ophthalmology, Lung imaging)
By End user: Hospitals, Diagnostic imaging centers, Specialty clinics, Academic and research institutions
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Ultrasound Image Analysis Software market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 8.2% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Software type, Analytical technology, Clinical application, End user, and Region |
By Region | North America (By Software type, Analytical technology, Clinical application, End user, and Country)
|
Europe (By Software type, Analytical technology, Clinical application, End user, and Country)
| |
Asia Pacific (By Software type, Analytical technology, Clinical application, End user, and Country)
| |
South America (By Software type, Analytical technology, Clinical application, End user, and Country)
| |
Middle East and Africa (By Software type, Analytical technology, Clinical application, End user, and Country)
|
Find answers to common questions about this report
The Ultrasound Image Analysis Software market size was valued at USD 1,005 million in 2025.
The market is projected to grow at a CAGR of 8.2% during the forecast period from 2026 to 2033.
The North America Ultrasound Image Analysis Software market size is estimated to reach USD 715.3 million by 2033.
Integrated software leads the Ultrasound Image Analysis Software market with a value of USD 645.1 million in 2026. This segment outpaces standalone software, which is projected to reach USD 837.1 million by 2033.
Increased demand for precise and timely interpretations drives investments in AI-enabled analysis. Advancements in imaging technologies improve diagnostic accuracy, leading healthcare providers to seek effective tools that facilitate accurate diagnoses and treatment plans.
North America holds the dominant share of the Ultrasound Image Analysis Software market, with a projected value of USD 715.3 million in 2033, representing 40.6 percent of the total market.
High costs associated with ultrasound image analysis software limit uptake among hospitals and diagnostic imaging centers. Initial investment and ongoing maintenance expenses present barriers that delay implementation, particularly affecting smaller healthcare providers and specialty clinics.
Factors favoring adoption in the ultrasound image analysis software industry include the integration of advanced AI techniques that enhance diagnostic accuracy and operational efficiency. Hospitals and diagnostic imaging centers prioritize solutions that streamline workflows and improve patient outcomes, creating a competitive environment for technological advancements.
The Ultrasound Image Analysis Software market is estimated to reach a valuation of USD 1,891.4 million by 2033.
Key players operating in the Ultrasound Image Analysis Software market include GE HealthCare Technologies Inc., Koninklijke Philips N.V., Siemens Healthineers AG, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Canon Medical Systems Corporation, and Agfa-Gevaert N.V. (AGFA HealthCare).
The analysts below cover Medical Devices research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

LEAD PRINCIPAL ANALYST, PHARMA AND HEALTHCARE
Food and Beverages · Healthcare · Healthcare IT · Medical Devices
Ajay Devgire is the Lead Healthcare Analyst at MetaStat Insight, leading strategic research and market intelligence initiatives across the global healthcare domain.
SENIOR RESEARCH ANALYST
Biotechnology · Food and Beverages · Medical Devices · Packaging
Snehal Pasalkar is a Research Analyst at MetaStat Insight, operating at the intersection of life sciences research, competitive strategy, and market intelligence.
Evaluating secondary resin quality across post-consumer packaging streams requires reliable technical segmentation. MetaStat Insight delivered an objective assessment that distinguished between extrusion-grade flake pricing and optical sorting throughput limitations across Western Europe. The competitive positioning breakdown for licensed depolymerization technology providers answered several questions during our feedstock feasibility audit. Their team clarified regional trade restrictions on mixed plastic scrap quickly when our team submitted follow-up requests.
Evaluating sovereign cloud deployments for core banking platforms demands a clear view of data residency regulations and migration exit strategies. MetaStat Insight delivered an exhaustive review of regional latency tolerances, mainframe decommission milestones, and third-party vendor concentration risk. The regulatory compliance mapping across European and Asian financial jurisdictions gave our team a dependable baseline for multi-cloud infrastructure discussions.
Replacing petrochemical surfactants with bio-based alternatives requires realistic timelines on industrial precision fermentation scaling. The market research broke down commercialization timelines, feedstock sugar price sensitivities, and regional cosmetic ingredient regulatory approvals in Europe and East Asia. That supplier readiness mapping gave our formulations team reliable context when comparing renewable chemical sourcing roadmaps.
Explore related market intelligence reports worth reading alongside this one.