
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Atopic Dermatitis Market Size, Share, By Drug Class (Corticosteroids, PDE4 Inhibitors, Biologics, Skin Barrier Emollients, CNI Immunosuppressants, JAK Inhibitors and Others), By Distribution Channel (Hospital Pharmacies, Retail Pharmacies and Online Pharmacies), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-2536
Published
October, 2026
Pages
261 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
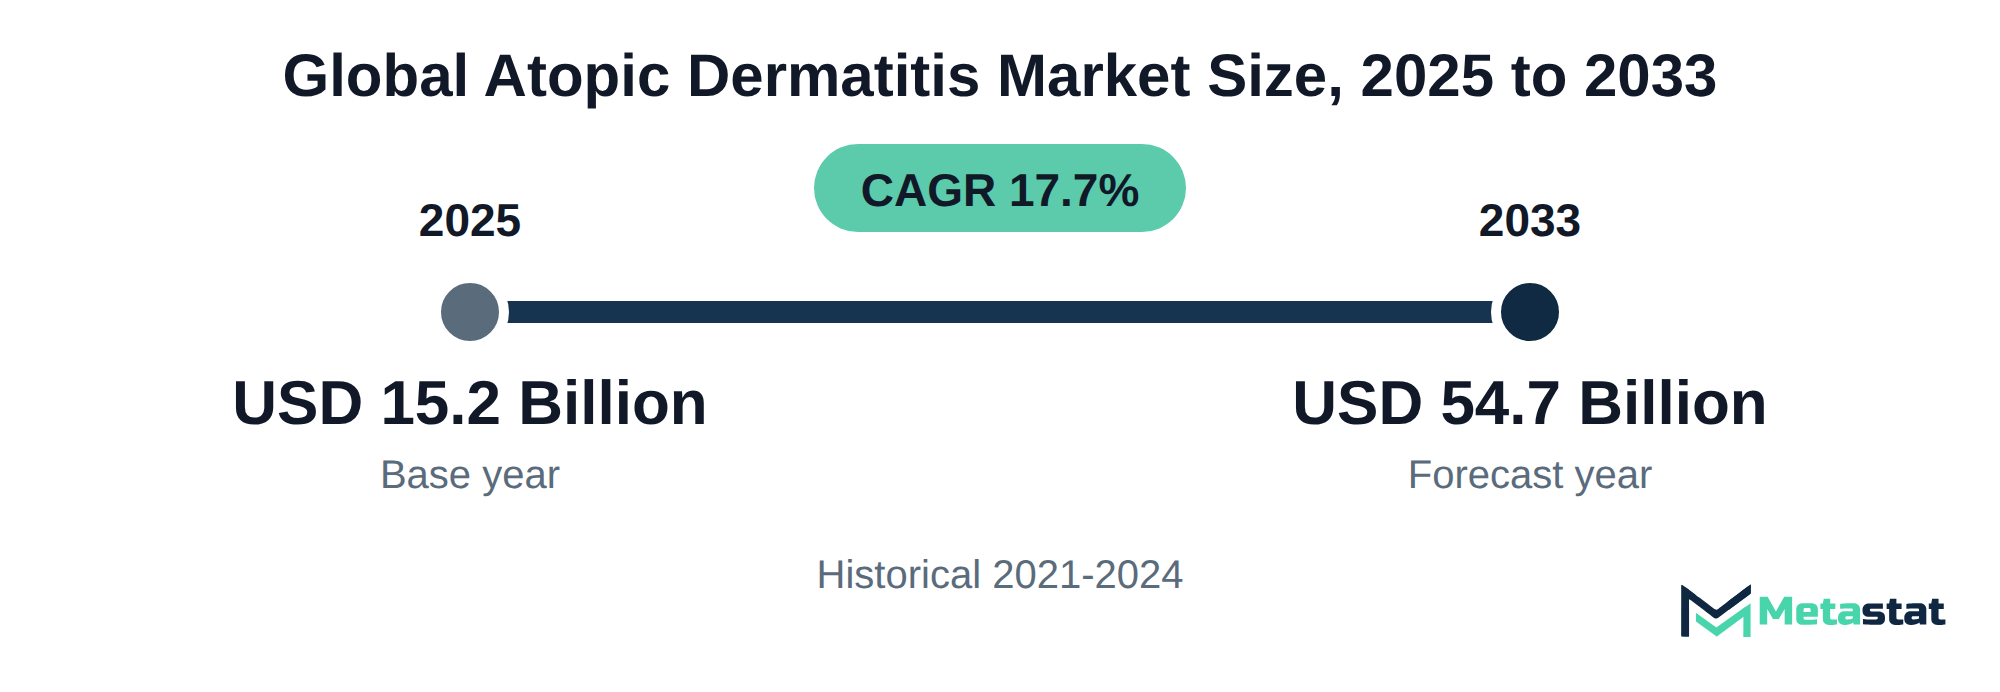
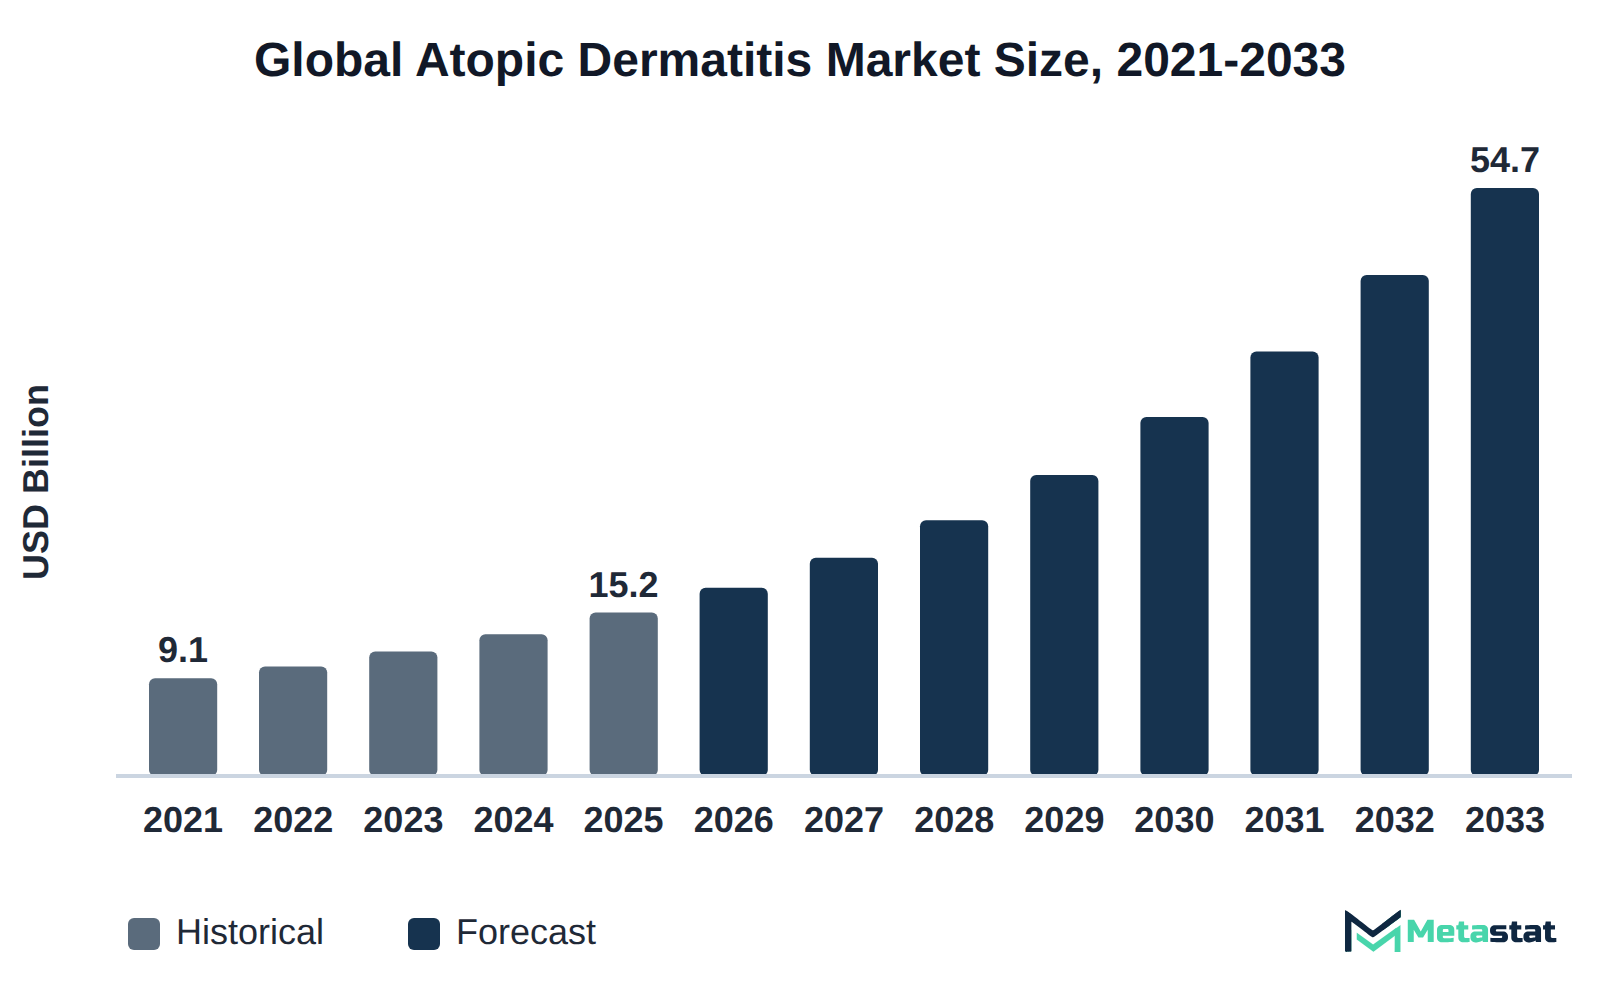
Market Valuation: Valued at $15.2 Billion in 2025, projected to reach $54.7 Billion by 2033 at a 17.7% CAGR.
Dominant Segment: Biologics lead the atopic dermatitis market, driven by their targeted therapies that effectively manage moderate-to-severe cases. This segment is projected to reach USD 37.6 billion by 2033, reflecting a strong preference for advanced treatment options.
Geographic Lead: North America is the leading region, capturing 37.4% of the market in 2025, with the United States driving growth due to its robust healthcare infrastructure and high adoption of innovative therapies.
What's Inside: The report provides a comprehensive analysis of the atopic dermatitis market, including competitive coverage, detailed segmentation by drug class and distribution channel, and forecasts extending to 2033.
Emerging Trends: Steroid-free topical formulations are gaining popularity for mild disease management, reflecting a shift towards gentler treatment options. This trend is fueled by increasing awareness of corticosteroid side effects among patients and healthcare professionals.
Market Dynamics: The increasing prevalence of atopic dermatitis and rising consumer awareness of skin health significantly drive market growth, leading to heightened demand for effective and innovative treatment alternatives.
Choose Your License
Global Atopic Dermatitis Market
The global Atopic Dermatitis market was valued at USD 15.2 billion in 2025 and is projected to reach USD 54.7 billion by 2033, growing at a CAGR of 17.7% over the forecast period.
The Atopic Dermatitis market encompasses a range of treatments aimed at managing this chronic inflammatory skin condition. Buyers invest in these products to alleviate symptoms, improve skin health, and enhance the quality of life for patients affected by the disease. The significance of effective therapies drives spending, with a focus on innovations that deliver better outcomes for individuals suffering from atopic dermatitis.
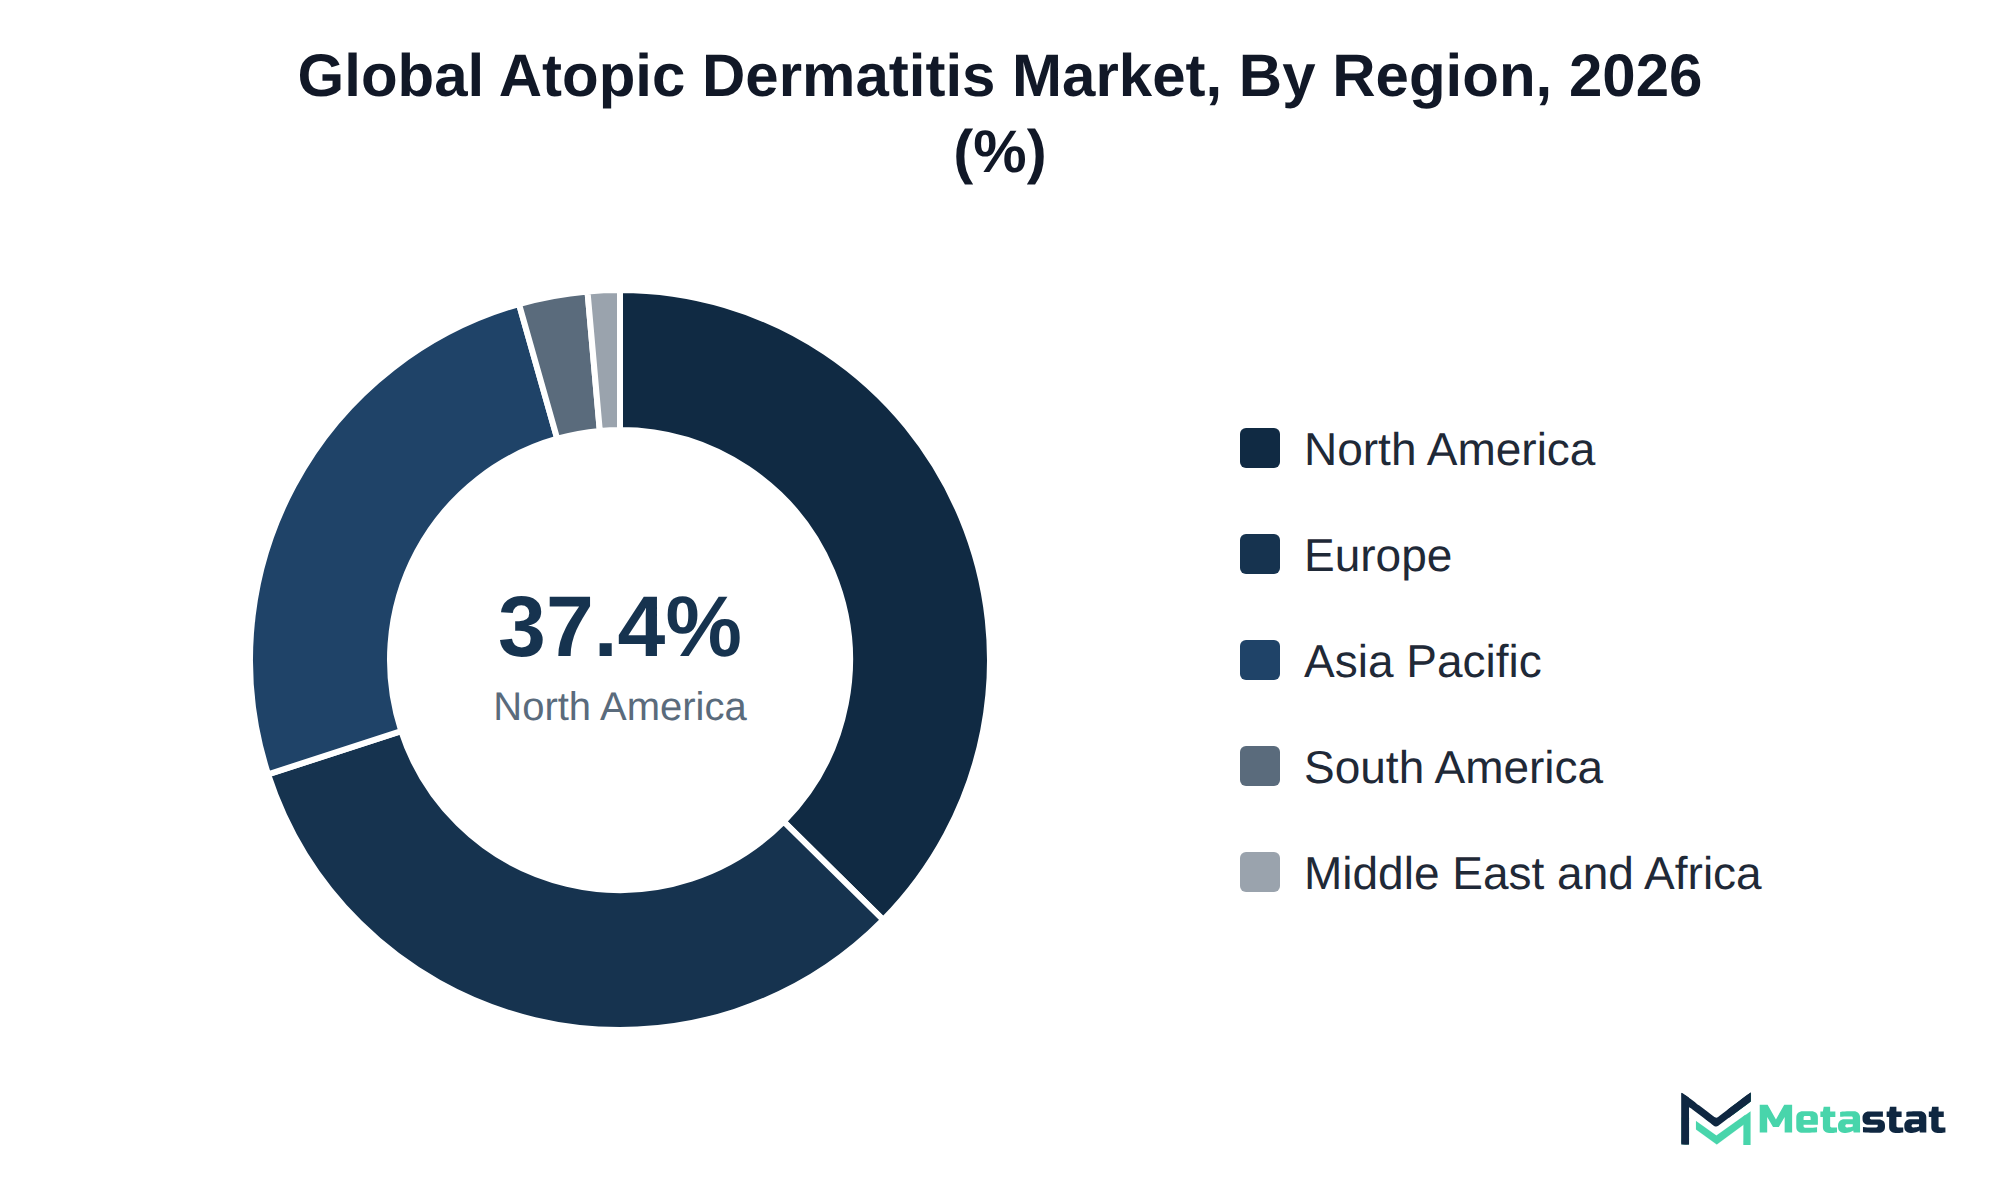
Growth in the market is propelled by increasing prevalence rates and heightened awareness regarding skin health. Among the various drug classes, biologics represent the segment with the most significant value. North America holds 37.4% of the market in 2025, with the US leading in 2026. This dominance reflects strong healthcare infrastructure and a higher willingness to adopt advanced treatment options.
Ongoing research and development into more effective therapies contribute to expanding market opportunities. The Asia Pacific region follows closely and comprises 25.6% of the market, reflecting a growing demand driven by rising healthcare expenditure and an expanding patient population. Enhanced distribution channels, particularly through retail pharmacies, support accessibility and affordability of treatments.
The Atopic Dermatitis market includes various therapeutic options designed to alleviate symptoms and improve patients' quality of life. Buyers invest in these treatments primarily due to the increasing prevalence of atopic dermatitis and the significant impact it has on daily activities and mental well-being. The ongoing demand for effective management solutions encourages spending on innovative therapies that address the needs of patients suffering from this condition.
Growth in the market is driven by advancements in drug development, including the introduction of biologics and new treatment classes that offer enhanced efficacy. Among the segments, biologics represent the most valuable category, catering to patients who require more targeted therapies. This region's strong share is supported by higher healthcare spending and a robust regulatory framework that facilitates the rapid introduction of new therapies.
Investment in the Atopic Dermatitis market reflects the urgency to address unmet medical needs and improve treatment outcomes. The increasing awareness of the condition and its implications creates a favorable environment for market expansion. Continued innovation in drug classes, especially biologics, supports sustained growth in the coming years.
Biologics, a class of biopharmaceuticals, represent a significant advancement in the treatment of moderate-to-severe atopic dermatitis, providing targeted therapies that focus on specific pathways involved in the inflammatory response. This innovation stems from a deeper understanding of the pathophysiology of atopic dermatitis, which has traditionally been treated with broad-spectrum therapies including corticosteroids. The introduction of biologics has created a significant shift in how clinicians approach treatment, allowing for more personalized and effective care for patients.
In the atopic dermatitis market, biologics are projected to dominate treatment options, with an expected value of USD 37.6 billion by 2033. This figure highlights the increasing reliance on advanced therapies that focus on biologic mechanisms, reflecting a shift toward precision medicine. The rise of biologics enhances patient outcomes and drives competition among pharmaceutical companies to develop new and improved formulations.
Healthcare providers experience enhanced treatment options that lead to improved patient adherence and satisfaction. The ongoing development and approval of new biologics will likely accelerate market growth, with increased clinical efficacy and safety profiles transforming the standard of care in atopic dermatitis management.
Steroid-free topical drug formulations are gaining traction in the management of mild atopic dermatitis. The increasing awareness among healthcare professionals and patients regarding the potential side effects of corticosteroids drives this trend. Many patients prefer these formulations for their non-steroidal properties, which align with a growing demand for gentler treatment options. The market for corticosteroids is projected to expand, with a compound annual growth rate (CAGR) of 17% from a value of USD 0.7 billion in 2026 to USD 2.2 billion by 2033.
Pricing strategies for steroid-free topical formulations have become an important consideration. Many manufacturers adopt competitive pricing models that highlight affordability and accessibility, particularly in retail pharmacies where patients frequently make purchases. The projected value for retail pharmacies is anticipated to reach USD 18.9 billion by 2033, indicating strong growth potential for affordable treatment options. Such models align with consumer preferences for cost-effective solutions, positioning manufacturers favorably in the market.
The trend towards steroid-free formulations significantly influences purchasing decisions among buyers in the atopic dermatitis market. With a focus on efficacy and minimal side effects, these products attract healthcare providers and patients seeking safer alternatives. Companies prioritizing the development and promotion of these formulations stand to enhance their market share and build long-term relationships with consumers.
Oral Janus kinase (JAK) inhibitors are experiencing accelerating adoption among patients with atopic dermatitis, particularly among those with moderate to severe conditions. This growth stems from the increasing prevalence of atopic dermatitis, which has prompted healthcare providers to seek effective treatment options. The atopic dermatitis market is projected to see the oral JAK inhibitor segment gain significant traction, contributing substantially to overall market expansion.
By 2033, the adoption of oral JAK inhibitors is expected to enhance treatment options for patients seeking alternatives to traditional therapies. This shift reflects a broader trend toward personalized medicine, enabling practitioners to tailor treatment plans based on individual patient needs. These therapies mark an important advance, especially for individuals unresponsive to conventional treatments.
With evolving treatment paradigms, healthcare providers are prioritizing medications that demonstrate efficacy and improved safety profiles. Consequently, oral JAK inhibitors are gaining attention due to their favorable pharmacokinetic properties and their ability to address unmet patient needs. This trend is expected to enhance competitive positioning for companies engaged in the atopic dermatitis market, ultimately driving sales and revenue growth.
Expanding pediatric approvals significantly influence commercial dermatology portfolios for atopic dermatitis. The inclusion of younger patients in clinical trials for atopic dermatitis treatments allows manufacturers to broaden their product offerings. Trial design and execution for these pediatric programs can draw on the services of contract research organizations. Pediatric-focused formulations drive innovations in drug development, catering to the unique needs of children suffering from this condition.
In the atopic dermatitis market, the segment of biologics is projected to reach USD 37.6 billion by 2033, reflecting increasing investment in advanced treatments that target this demographic. Pharmaceutical companies actively seek to develop formulations that demonstrate safety and efficacy in pediatric populations, which broadens their portfolio of treatment options.
This strategic shift enhances a company's market presence and aligns with regulatory trends favoring pediatric research. Companies that prioritize pediatric approvals position themselves to capture a growing segment of the patient population, ultimately driving revenue growth and enhancing competitive advantage within the market.
Growing awareness of skin health, driven by rising prevalence of atopic dermatitis, prompts consumers to seek effective treatment options. Patients, particularly those suffering from moderate to severe conditions, increasingly invest in high-quality therapies to alleviate symptoms and improve overall quality of life. This shift in consumer behavior results in heightened demand for innovative treatment alternatives, significantly influencing purchasing decisions. In the atopic dermatitis market, the increasing focus on skin care has led to a notable expansion in the adoption of biologics, reflecting a CAGR of 17.7% between 2026 and 2033. The upward trend in consumer spending on dermatological solutions supports market growth and drives competition among suppliers to meet evolving patient needs.
Healthcare providers respond to this heightened demand by expanding their treatment portfolios, offering a wider range of options to address diverse patient requirements. Consequently, the market experiences an influx of new and effective treatments, enhancing patient outcomes and engagement. This dynamic environment ensures that the market continues to evolve, focusing on improving patient care and satisfaction.
Advancements in drug development have introduced targeted therapies that significantly enhance treatment options within the atopic dermatitis market. These therapies focus on specific pathways involved in the inflammatory process, offering improved efficacy and safety profiles compared to traditional treatments. Key classes include biologics and PDE4 inhibitors, providing alternative options for patients with moderate-to-severe atopic dermatitis. Similar targeted approaches are also applied in psoriasis treatment, which addresses another chronic inflammatory skin condition. The increasing adoption of these targeted therapies results from their ability to deliver more personalized treatment approaches, addressing the unique needs of patients.
The availability of new treatments has transformed the competitive dynamics in the market, prompting existing players to innovate and expand their product portfolios. Pharmaceutical companies invest heavily in research and development to create effective therapeutics, ensuring they meet the growing demand for advanced solutions. Targeted therapies have the potential to reduce overall healthcare costs by minimizing the need for multiple treatments and improving patient outcomes. Consequently, the rise of targeted therapies is expected to fuel substantial growth in the market during the forecast period.
Rising treatment costs present a significant restraint in the market, particularly impacting patients and healthcare providers seeking effective management options for atopic dermatitis. The increasing prices of innovative therapies, especially biologics, contribute to slower uptake among patients facing financial barriers. Many patients, particularly those with limited health insurance coverage, delay seeking treatment due to concerns over out-of-pocket expenses. This hesitance reduces demand for advanced treatments, as patients often opt for more affordable alternatives that do not provide the same level of efficacy. Healthcare providers, while aware of the benefits of newer therapies, face budget constraints that limit their ability to prescribe these costly options. Rising treatment costs lead to smaller orders and delayed adoption of advanced solutions, which in turn influences growth trajectories and the competitive landscape.
Rising input costs present significant challenges for suppliers within the market. The increase in raw material prices, particularly for biologics and emollients, directly impacts profit margins. Heightened production expenses prompt suppliers to enhance operational efficiency and cost management. In response, companies invest in advanced manufacturing technologies and seek sustainable sourcing options to mitigate these costs. Collaboration with suppliers and vertical integration are strategies employed to stabilize pricing and healthcare supply chains. The introduction of innovative formulations that require fewer resources for production gains momentum. These approaches aim to offset the effects of rising costs while maintaining product quality, crucial for sustaining growth in the competitive landscape of the Atopic Dermatitis market. Suppliers continue to balance cost control with demand for high-quality, effective treatments.
The biologics segment presents a substantial opportunity within the Atopic Dermatitis market, with a projected value reaching USD 37.6 billion by 2033. This figure indicates strong demand and increasing adoption among patients. The growth is driven by the effectiveness of biologics in targeting the underlying mechanisms of atopic dermatitis, offering a solution for patients with moderate to severe cases. Healthcare providers prioritize treatment efficacy, and the shift towards biologics becomes evident.
Physicians and patients increasingly seek therapies that provide long-lasting relief and reduce the frequency of flare-ups. The expanding pipeline of biologic therapies enhances treatment options available to both healthcare providers and patients. Producing these biologics at scale can also draw on large molecule drug substance CDMO services. This segment's growth signifies a promising trend in the market, with the potential to transform patient outcomes significantly.
The Global Atopic Dermatitis market is segmented based on Drug Class, Distribution Channel.
These medications represent the first-line treatment for managing the symptoms of atopic dermatitis, primarily used by dermatologists and healthcare professionals to reduce inflammation and alleviate itching. Strong demand for corticosteroids stems from their effectiveness in controlling flare-ups, leading to high adoption rates among patients. Growth of this segment is driven by an increasing prevalence of atopic dermatitis and rising awareness of effective treatment options. In comparison to other drug classes including PDE4 inhibitors and biologics, corticosteroids exhibit a solid market presence with significant sales but experience relatively slower growth, with PDE4 inhibitors projected to achieve a CAGR of 18.5%. This differing growth trajectory highlights the dynamic nature of treatment preferences in the market.
PDE4 Inhibitors segment is estimated to reach USD 3.9 billion by 2033, at a CAGR of 18.5% during the forecast period. This class of medications primarily targets inflammation and itching experienced by individuals with atopic dermatitis, offering an effective treatment option. Healthcare providers prescribe PDE4 inhibitors to patients requiring alternative therapies, particularly those who do not respond well to standard treatments. The increasing prevalence of atopic dermatitis is a significant driver for this segment, reflecting rising demand for innovative solutions. Compared to corticosteroids, which exhibit a CAGR of 17%, PDE4 inhibitors demonstrate faster growth potential. This heightened growth reflects the market's shift toward non-steroidal options, providing healthcare professionals and patients with broader therapeutic choices to manage atopic dermatitis effectively.
These treatments focus on targeting specific pathways involved in the inflammatory response of atopic dermatitis, effectively managing moderate-to-severe cases. Patients suffering from more severe manifestations of the condition primarily adopt biologics, which offer an alternative to traditional treatments. The segment experiences significant growth, driven by increasing demand for effective therapies that minimize side effects associated with conventional options. With a compound annual growth rate (CAGR) of 18.5%, biologics significantly outpace alternatives in the drug class segment. Healthcare professionals seek more effective solutions, and the trend toward personalized medicine further supports adoption. Investment in clinical trials and research enhances the development of new biologics, further differentiating this segment from others that do not experience the same levels of innovation or demand.
Skin Barrier Emollients segment is projected to grow at a CAGR of 15.9% during the forecast period. These formulations provide essential moisture to the skin, helping to restore the skin barrier and alleviate symptoms for individuals suffering from atopic dermatitis. Patients, particularly those with mild forms of the condition, frequently apply skin barrier emollients to prevent flare-ups and maintain skin hydration. The growing demand for non-steroidal options drives the segment, with patients seeking effective alternatives to corticosteroids to manage their condition. Compared to other drug classes, skin barrier emollients offer broader accessibility and affordability, appealing to a diverse consumer base. The relatively stable pricing of these products contrasts with the more fluctuating costs seen in biologics and PDE4 inhibitors, enhancing their attractiveness in the market.
CNI Immunosuppressants represent a treatment option targeting immune response in patients with atopic dermatitis. As immunosuppressants, these drugs belong to the broader immunology therapeutic area. This class of drugs is commonly prescribed for individuals with moderate to severe forms of the condition, particularly when other treatments prove ineffective. Demand for this segment increases due to rising prevalence rates of atopic dermatitis and a shift toward more targeted therapies. The higher cost of CNI immunosuppressants compared to other drug classes, including corticosteroids, influences buyer decisions, often limiting access to these medications for several patients. Adoption of CNI immunosuppressants is typically slower than in other segments because of concerns about side effects and the need for careful patient monitoring. The atopic dermatitis market continues to evolve, with ongoing research focused on enhancing the efficacy and safety of CNI immunosuppressants.
JAK inhibitors represent a novel approach in the treatment of atopic dermatitis, specifically targeting the underlying inflammatory pathways associated with this condition. Patients with moderate to severe cases frequently rely on these therapies for effective management. Demand for JAK inhibitors is driven by their ability to provide rapid symptom relief, enhancing overall patient satisfaction. This sub-segment differentiates itself through its targeted mechanism, contrasting with broader categories like corticosteroids and biologics, which have a wider spectrum of use but do not provide the same level of specificity. While corticosteroids are often used as first-line treatments, JAK inhibitors offer an alternative for patients seeking more advanced options. The efficacy and convenience of oral JAK inhibitors position them as attractive choices for patients and healthcare providers seeking effective solutions in the market.
This segment includes various treatment options that do not fall into the traditional categories of corticosteroids and biologics. Such products often employ alternative mechanisms of action or delivery methods, appealing to patients seeking diverse therapeutic options for managing atopic dermatitis symptoms. Healthcare professionals frequently prescribe these treatments to patients who prefer alternatives to conventional therapies or require adjunctive care not met by other sub-segments. The segment benefits from increasing interest in personalized medicine, influencing the development of tailored therapies that address specific patient needs. Compared to biologics and PDE4 inhibitors, which exhibit higher market value and more rapid growth, this segment experiences slower adoption rates due to limited awareness and marketing. Continued research and education surrounding these options will be essential for driving adoption and improving patient outcomes in the market.
Hospital Pharmacies segment is valued at USD 9.1 billion in 2026 and is projected to reach USD 27.3 billion by 2033, at a CAGR of 17% during the forecast period. This segment caters primarily to hospitals and healthcare facilities, providing essential medications for patients diagnosed with atopic dermatitis. A significant driver for this segment stems from the increasing number of patients requiring specialized treatments, leading to a surge in demand for medications supplied through hospital pharmacies. Compared to retail and online pharmacies, this segment experiences faster growth due to its focus on providing advanced therapies and personalized care. The projected growth rate reflects growing investment in hospital-based healthcare infrastructure and increasing adoption of new treatment modalities targeting atopic dermatitis, positioning this segment favorably within the market.
Retail Pharmacies segment is estimated to reach USD 18.9 billion by 2033, at a CAGR of 18.5% during the forecast period. This segment serves patients seeking over-the-counter and prescription treatments for atopic dermatitis, facilitating easier access to a variety of therapeutic options. Increasing consumer awareness about skin health significantly influences demand for retail pharmacy offerings. Unlike Hospital Pharmacies, which primarily cater to inpatient treatments, this segment targets outpatient and self-care markets. The growing trend of consumers preferring convenient access to medications through retail outlets drives adoption. Retail Pharmacies benefit from a wider range of products at competitive prices, enhancing their appeal to patients. In comparison with other distribution channels, the Retail Pharmacies segment demonstrates faster growth rates, reflecting shifts in consumer purchasing behavior and preferences.
The Online Pharmacies segment is expected to reach USD 8.6 billion by 2033. This distribution channel provides convenient access to various treatments for patients suffering from atopic dermatitis, allowing them to purchase medications from the comfort of their homes. The increasing trend of online shopping among consumers drives growth in this segment, reflecting a shift in purchasing behavior. Unlike Hospital and Retail Pharmacies, which have limited stock and require physical visits, Online Pharmacies offer a broader selection of products. The anticipated CAGR for this segment stands at 18.5% during the forecast period, indicating a stronger growth rate compared to other distribution channels. This growth is driven by the rising prevalence of atopic dermatitis and a growing preference for online shopping, positioning Online Pharmacies as a critical channel for delivering treatments to consumers.
Based on geography, the Global Atopic Dermatitis market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Demand for treatments within the atopic dermatitis market in North America experiences significant growth, driven by an increasing prevalence of the condition, particularly in the United States. Healthcare infrastructure, including advanced medical facilities and access to a variety of treatment options, supports this demand. Patients in this region benefit from well-established healthcare policies that facilitate access to innovative therapies. The market is projected to reach USD 20.1 billion by the end of 2033. With a 37.4% share of the global market in 2025, North America remains a leading region for investment and development within the market, highlighting the importance of addressing unmet treatment needs among affected populations.
Market dynamics in Europe reflect a significant demand for innovative treatments driven by increasing awareness of atopic dermatitis among healthcare providers and patients. The high prevalence of atopic dermatitis in countries including Germany, France, and the UK further stimulates the market. Regulatory frameworks, particularly those focused on patient access to advanced therapies, play a critical role in shaping the landscape. This region is projected to account for 32.6% of the global market in 2025, highlighting the importance of European contributions to overall growth. The emergence of new drug classes, particularly biologics and PDE4 inhibitors, enhances treatment options and accessibility. Rising demand for effective solutions results in considerable investment in research and development across the region, supporting advancements within the Atopic Dermatitis market.
Strong demand for innovative therapies drives the atopic dermatitis market in Asia-Pacific, particularly in China, Japan, and India. Increasing awareness of skin conditions among patients contributes to higher treatment rates. A growing population suffering from atopic dermatitis requires effective management solutions. Rising disposable incomes in these countries enable greater access to advanced treatment options, including biologics and PDE4 inhibitors. Investment in healthcare infrastructure enhances availability of medications through various distribution channels, including hospital and retail pharmacies. The region's market share accounted for 25.6% of the global total in 2025, highlighting its significance in the overall landscape. Factors including improving healthcare policies and supportive regulatory environments further support the market's growth trajectory.
Brazil and Argentina are key markets in South America, driven by rising awareness of dermatological conditions and an increasing prevalence of atopic dermatitis. Growth in healthcare infrastructure enhances accessibility to treatments, with patients seeking innovative therapies for effective management. Market dynamics in South America reflect a demand for affordable and efficient treatment options, while healthcare providers navigate budget constraints in both public and private sectors. The market in South America holds a 3.00% share of the global market in 2025, highlighting the region’s potential yet still limited scope compared to larger markets. Ongoing research and development efforts support the introduction of newer treatment modalities, enhancing competitive dynamics among local and international players.
Growth within the atopic dermatitis market in the Middle East and Africa reflects specific cultural and healthcare dynamics unique to the region. Increased awareness of atopic dermatitis among patients and healthcare providers drives demand for effective treatment options. Countries like Saudi Arabia and the UAE display a rising focus on healthcare infrastructure improvements, contributing to enhanced access to therapeutic solutions. South Africa's expanding pharmaceutical sector and government health initiatives further support market growth. Despite representing only 1.4% of the global market in 2025, this region's potential for innovation and healthcare advancement signals an emerging opportunity for pharmaceutical companies. Investments in research and development are expected to strengthen market presence, enabling access to advanced therapies within the local healthcare systems.
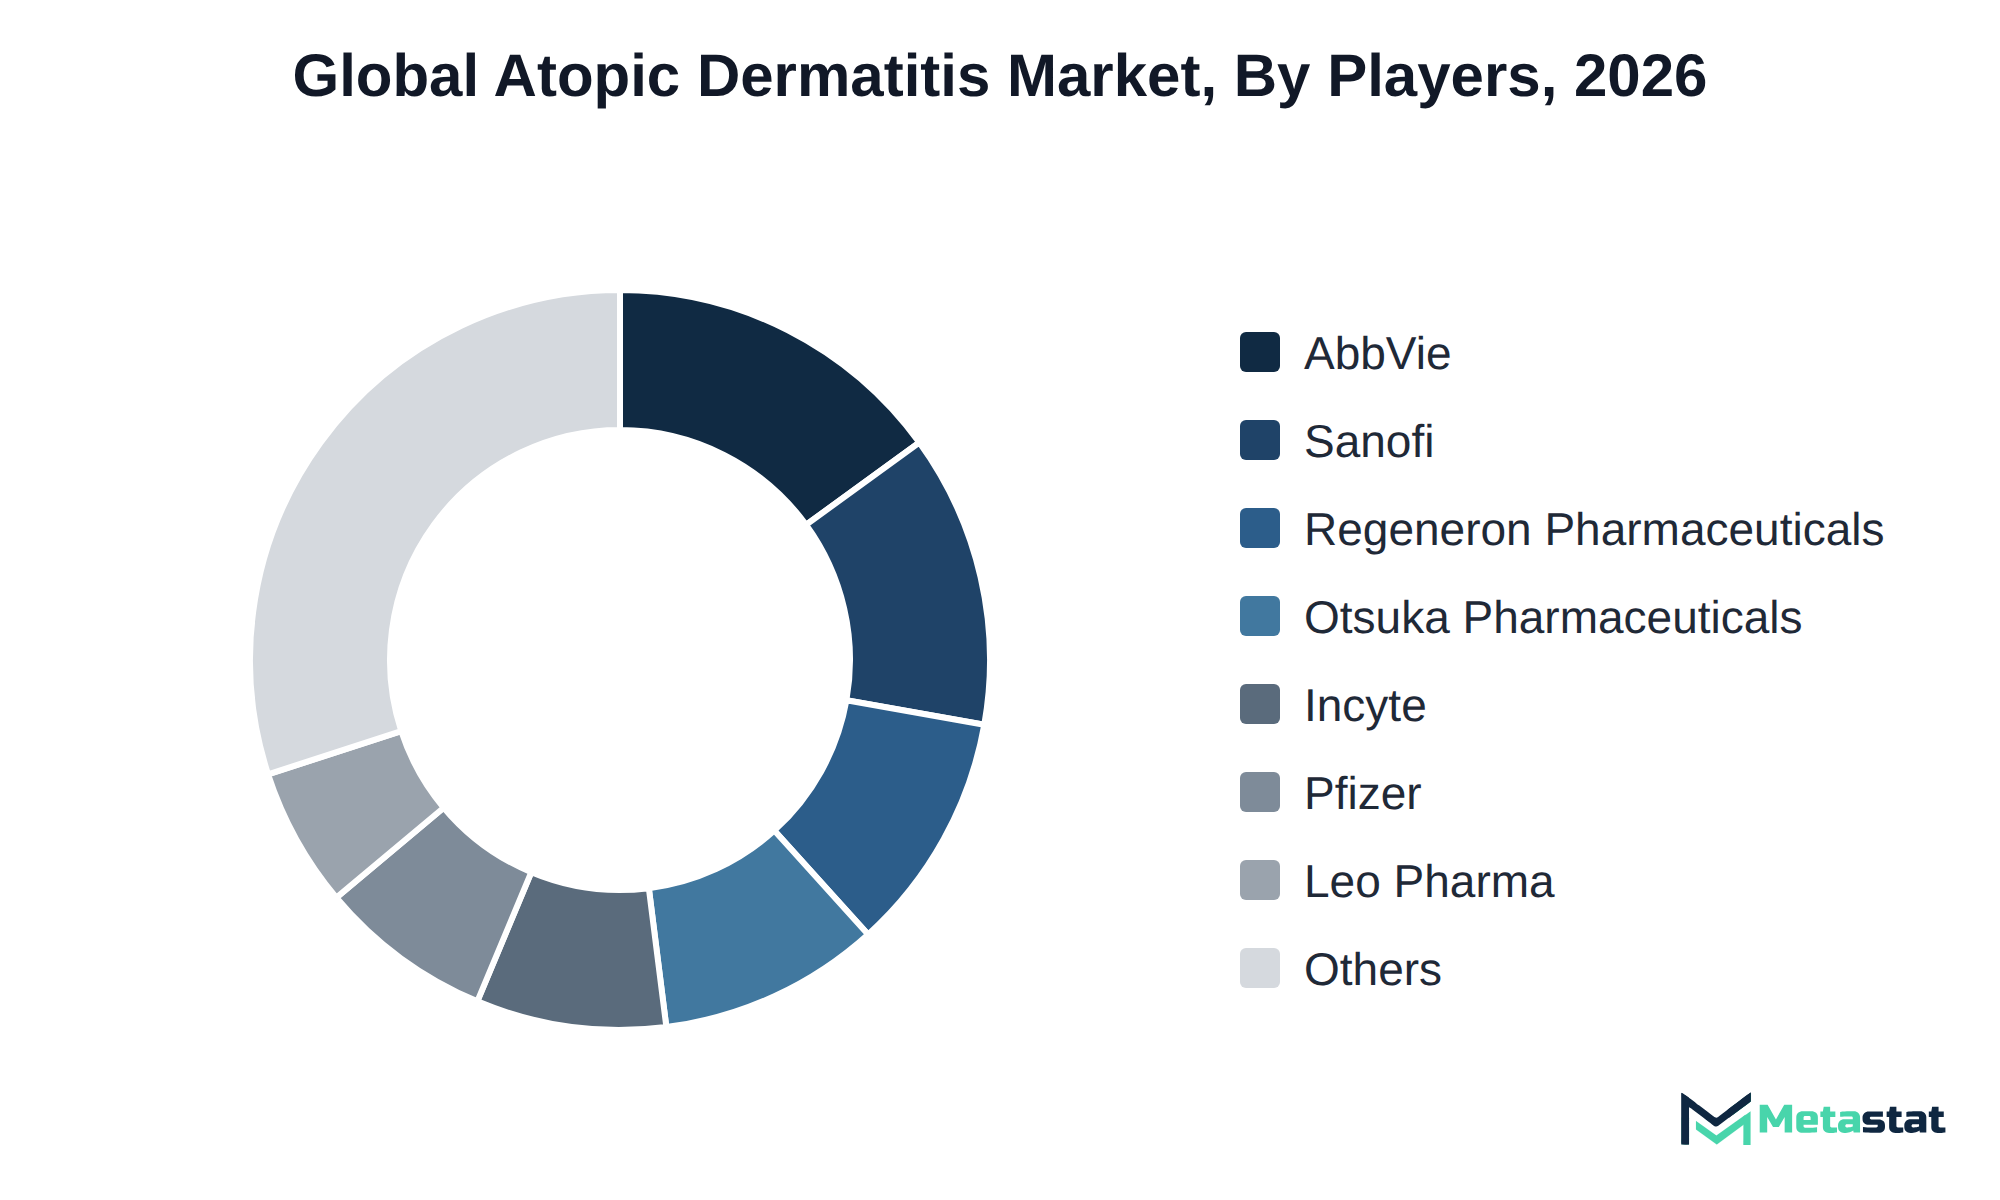
The Atopic Dermatitis market features a variety of companies competing on the basis of drug class, distribution channel, and therapeutic innovation. Key players including AbbVie Inc. and Sanofi S.A. focus on biologics and PDE4 inhibitors, offering advanced treatment options that appeal to healthcare providers and patients seeking effective solutions. Price competitiveness and clinical efficacy serve as significant factors driving buyer decisions.
Companies differentiate themselves through specialized product lines and distribution strategies. For instance, Incyte Corporation emphasizes its PDE4 inhibitors, while Leo Pharma, Inc. concentrates on corticosteroid formulations. Retail and hospital pharmacies remain the primary distribution channels, with companies like Pfizer Inc. and Regeneron Pharmaceuticals, Inc. using these platforms to extend market reach and support healthcare providers.
Growth in the atopic dermatitis market relies on several key developments. Firstly, the increasing adoption of biologics, projected to reach USD 37.6 billion by 2033, will significantly contribute to market expansion. Secondly, the rise in the use of PDE4 inhibitors, anticipated to grow at a CAGR of 18.5%, will enhance treatment options, particularly in North America and Europe, where the highest demand exists. However, challenges including rising costs of advanced therapies could impede market growth, particularly affecting patient access in regions with lower healthcare spending. The North American market, projected to account for USD 20.1 billion by 2033, faces pressure from increasing competition and pricing strategies. Strengthening distribution channels, including hospital and online pharmacies, will facilitate broader access to treatments. Reliable pharmaceutical logistics support this access by moving treatments from manufacturers to pharmacies. Overall, while developments in drug classes and distribution strategies support growth in the market, careful management of cost-related challenges will be essential to achieve the projected market size.
By Drug Class: Corticosteroids, PDE4 Inhibitors, Biologics, Skin Barrier Emollients, CNI Immunosuppressants, JAK Inhibitors, Others
By Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Atopic Dermatitis market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 17.7% from 2026 to 2033 |
|
Revenue Unit |
USD billion |
|
Segmentation |
By Drug Class, Distribution Channel, and Region |
|
By Region |
North America (By Drug Class, Distribution Channel, and Country)
|
|
Europe (By Drug Class, Distribution Channel, and Country)
|
|
|
Asia Pacific (By Drug Class, Distribution Channel, and Country)
|
|
|
South America (By Drug Class, Distribution Channel, and Country)
|
|
|
Middle East and Africa (By Drug Class, Distribution Channel, and Country)
|
Find answers to common questions about this report
The Atopic Dermatitis market size was valued at USD 15.2 billion in 2025.
The market is projected to grow at a CAGR of 17.7% during the forecast period from 2026 to 2033.
The North America Atopic Dermatitis market size is estimated to reach USD 20.1 billion by 2033.
Biologics lead the Atopic Dermatitis market with a projected value of USD 37.6 billion by 2033, significantly surpassing other drug classes.
Growing awareness of skin health and the rising prevalence of atopic dermatitis drive demand for effective treatment options. The increasing focus on high-quality therapies, particularly biologics, reflects a significant shift in consumer behavior and purchasing decisions.
North America holds the dominant share of the Atopic Dermatitis market, accounting for USD 20.1 billion in 2033. This region represents 37.4 percent of the total market share.
Rising treatment costs present significant restraints on the Atopic Dermatitis market growth. Increasing prices of innovative therapies, particularly biologics, contribute to slower uptake among patients facing financial barriers.
The biologics segment is experiencing significant growth, with a projected value of USD 37.6 billion by 2033, driven by their effectiveness in addressing the underlying mechanisms of atopic dermatitis. The expanding pipeline of biologic therapies enhances treatment options, leading to increased adoption among patients and healthcare providers seeking long-lasting relief.
The Atopic Dermatitis market is estimated to reach a valuation of USD 54.7 billion by 2033.
Key players operating in the Atopic Dermatitis market include AbbVie Inc., Incyte Corporation, Leo Pharma, Inc., Otsuka Pharmaceuticals Co., Ltd., Pfizer Inc., Regeneron Pharmaceuticals, Inc., Sanofi S.A., and Viatris, Inc.
The analysts below cover Healthcare research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

LEAD PRINCIPAL ANALYST, PHARMA AND HEALTHCARE
Food and Beverages · Healthcare · Healthcare IT · Medical Devices
Ajay Devgire is the Lead Healthcare Analyst at MetaStat Insight, leading strategic research and market intelligence initiatives across the global healthcare domain.
Scaling antibody-drug conjugate manufacturing hinges on contract manufacturing availability for high-potency active ingredients. The MetaStat Insight analysis looked closely at global cleanroom slot constraints, bioconjugation batch failure rates, and supply chain redundancies between the US, Europe, and India. The supplier capability matrix proved genuinely useful for our team when mapping secondary source options across our clinical pipeline.
Floating offshore wind feasibility relies heavily on specialized installation vessel availability and port crane limits, which most broad renewable energy forecasts ignore. The report delivered a thorough analysis of dry dock capacity, mooring chain supply constraints, and raw material pricing trends for deepwater anchor installations. It served as a solid independent sanity check for our offshore project capital expenditure assumptions.
Assessing commercial microgrid software adoption requires looking past top-level installation numbers and examining utility interconnection queues. The research provided verifiable data on average permitting timelines, tariff structures, and battery storage integration costs across regional utility territories. That grounded perspective was valuable for our team when building five-year demand projections for industrial microgrid controllers.
Explore related market intelligence reports worth reading alongside this one.