
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global EMC Shielding and Test Equipment Market Size, Share, By Product Type (EMI Shielding Gaskets & Conductive Elastomers, Shielding Tapes, Foils, Films & Conductive Fabrics, Conductive Coatings, Adhesives & Caulks, Board-Level Shields & Shielding Cans, EMI Absorbers & Ferrite Materials, Shielded Vents, Windows, Cable Shields & Enclosures, EMI Receivers & Spectrum Analyzers, EMC Immunity Generators, Simulators & RF Amplifiers, EMC Antennas, Probes, LISNs & Coupling Networks, EMC Test Systems, Chambers, Software & Automation), By Application (Electronic Enclosure & Cabinet Shielding, PCB & Component-Level Shielding, Cable & Interconnect Shielding, Display, Window & Vent Shielding, Radiated Emissions Testing, Conducted Emissions Testing, Radiated Immunity Testing, Conducted Immunity Testing, ESD, EFT/Burst & Surge Immunity Testing, Shielding Effectiveness & EMC Site Validation), By End-Use Industry (Consumer Electronics & Computing, Telecommunications & Networking, Automotive & Electric Vehicles, Aerospace & Defense, Medical Devices & Healthcare, Industrial Automation & Machinery, Energy & Power Electronics, Semiconductor & Electronic Components, Others), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5289
September 17, 2026
308 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $7,751.6 Million in 2025, projected to reach $11,282.8 Million by 2033 at a 4.8% CAGR.
Dominant Segment: The EMI Shielding Gaskets & Conductive Elastomers segment leads the market, driven by the increasing need for effective electromagnetic interference protection in consumer electronics and telecommunications.
Geographic Lead: North America is the leading region, propelled by stringent regulatory requirements and a focus on high-quality EMC validation and compliance systems.
What's Inside: The report provides comprehensive competitive coverage, detailed analyses of market dynamics, and forecasts from 2026 to 2033, covering various product types, applications, and end-use industries.
Emerging Regional Demands: Significant growth opportunities arise from changing regional demands, particularly in North America and Asia Pacific, driven by rising electronic device usage and infrastructure modernization initiatives.
Regulatory Compliance Challenges: Stringent regulatory compliance requirements pose challenges for manufacturers, leading to operational complexities and increased costs that hinder market growth.
The global EMC Shielding and Test Equipment market was valued at USD 7,751.6 million in 2025 and is projected to reach USD 11,282.8 million by 2033, growing at a CAGR of 4.8% over the forecast period.
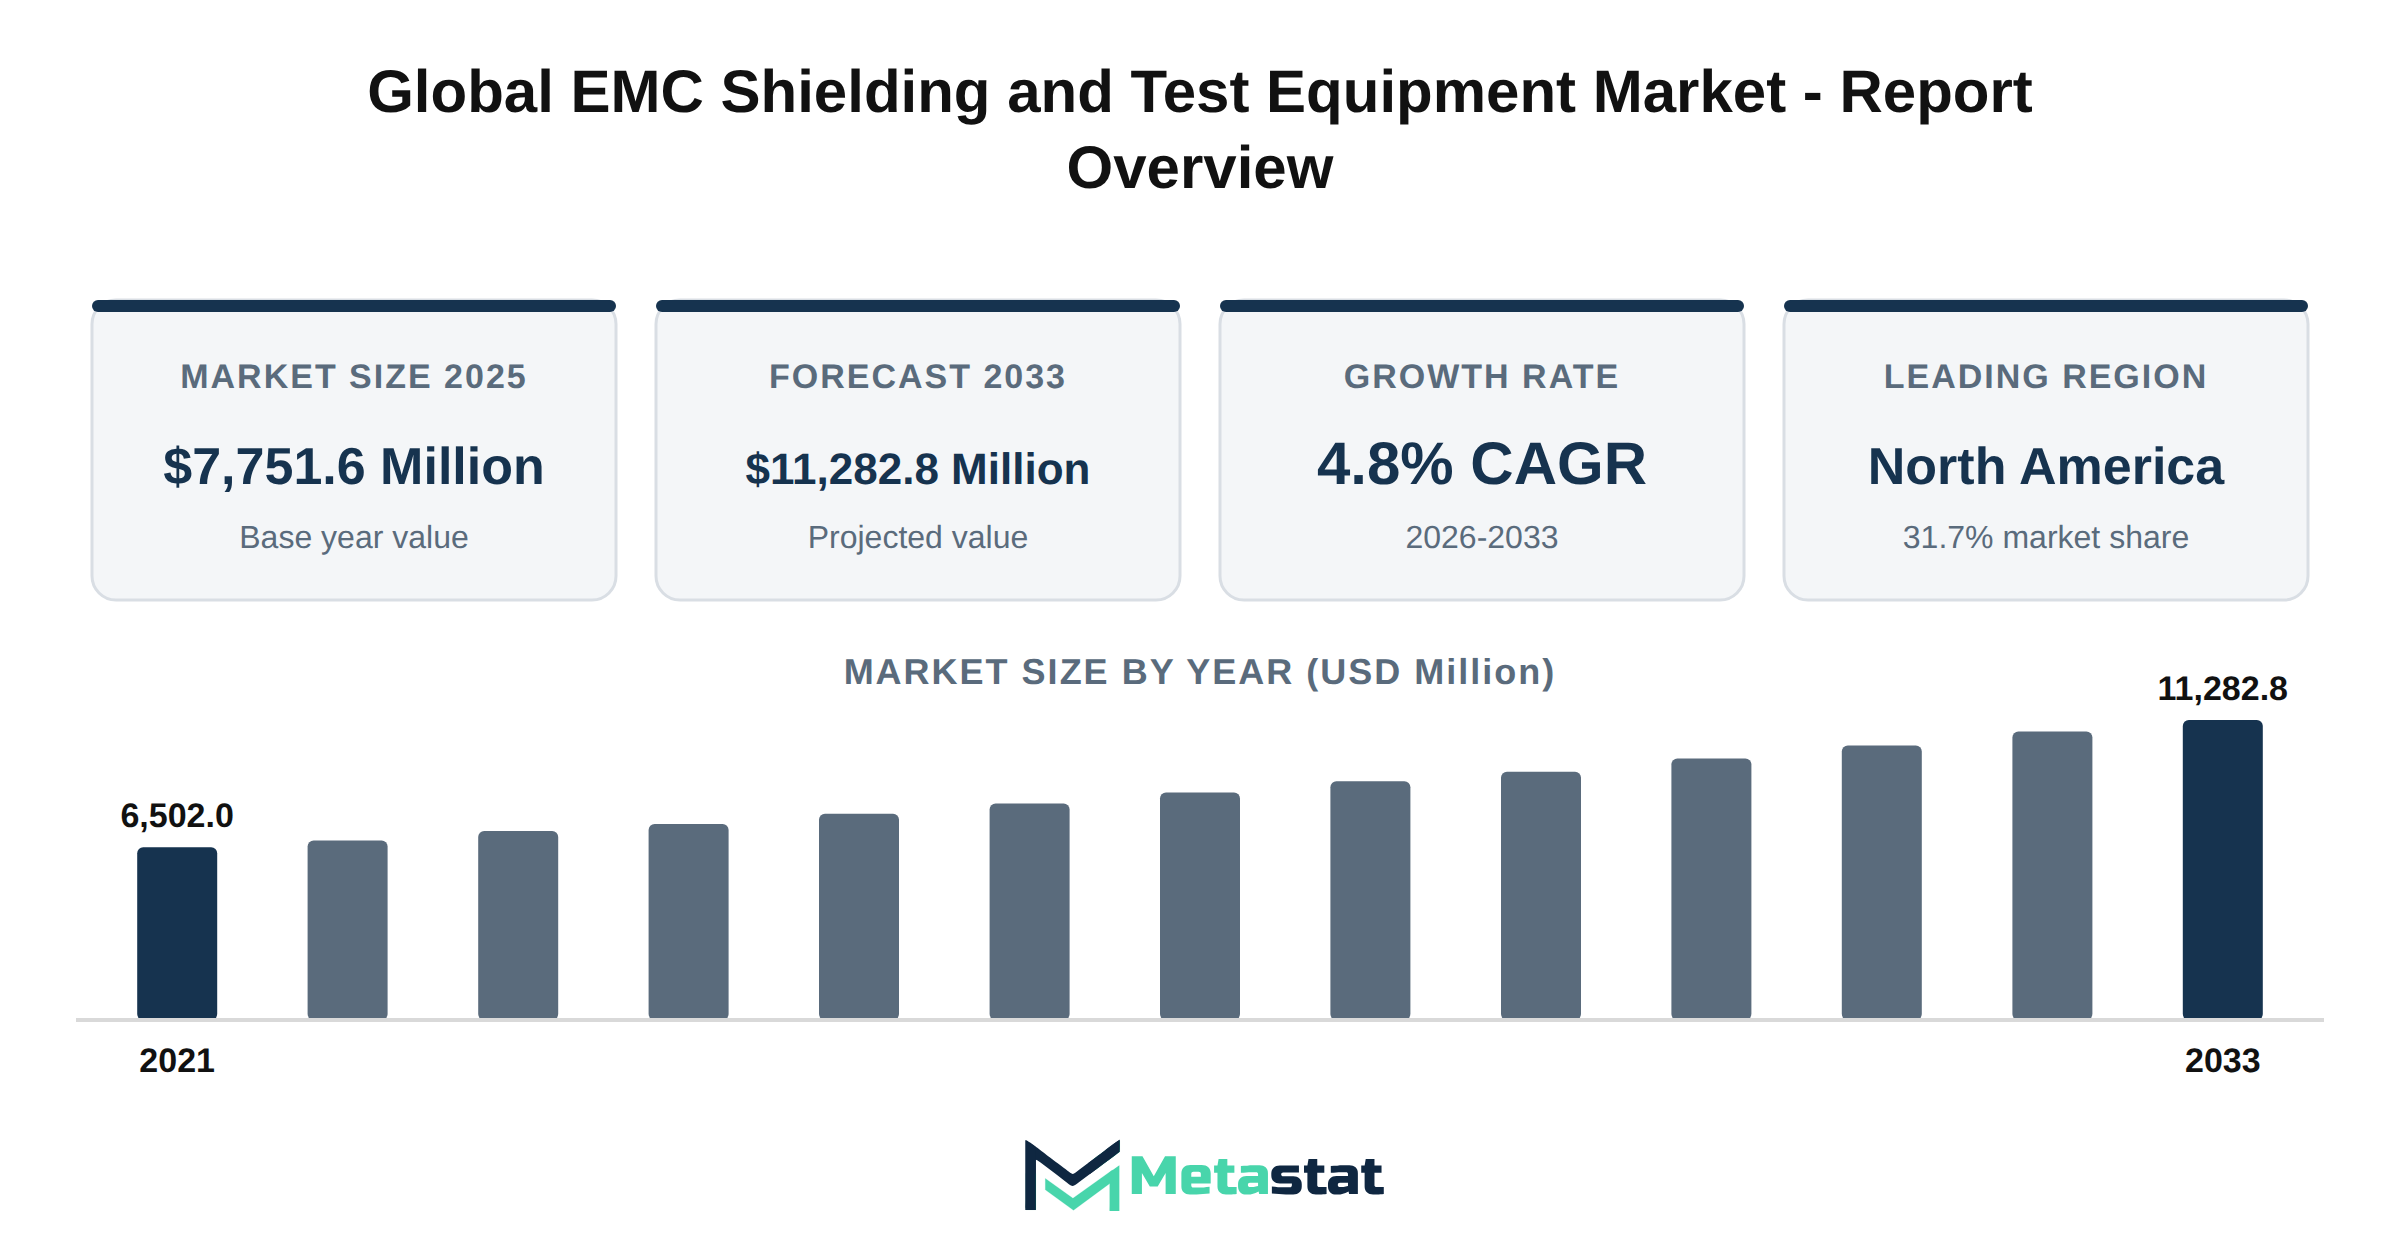
The EMC Shielding and Test Equipment market is experiencing significant growth driven by rising electromagnetic interference (EMI) risks associated with high-density electronic systems. The increasing complexity of electronic devices and the demand for higher performance levels drive the necessity for effective EMC shielding solutions. This trend strongly influences various end-use sectors, including consumer electronics, telecommunications, and automotive industries, which comply with stringent EMI regulations to ensure product reliability and safety.
Advancements in 5G, 6G, and high-frequency electronics reshape EMC testing requirements, necessitating enhanced testing capabilities and methodologies. These developments increase the demand for sophisticated testing equipment that handles elevated frequencies and complex signal environments. The growing integration of electric vehicles and advanced driver assistance systems expands the need for rigorous EMC compliance, driven by the requirement for robust shielding to prevent interference within their sensitive components.
The adoption of board-level EMI shielding solutions in compact electronic devices continues to grow, supported by the miniaturization of components and the increasing demand for high-performance applications. Automated EMC test systems accelerate compliance and product development, allowing manufacturers to streamline their testing processes while maintaining high accuracy and reliability. The importance of EMI pre-compliance testing in electronics design workflows has risen, ensuring that products meet regulatory standards before entering the market.
Advanced EMI receivers enhance the speed and accuracy of emissions testing, leading to improved product performance and compliance rates. Conductive elastomers and gaskets remain critical for enclosure-level EMI shielding, providing effective protection against external interference. The market sees a growing interest in EMI absorbers and ferrite materials, particularly in high-frequency applications, where these materials help mitigate unwanted emissions and enhance overall device performance.
Conductive coatings and shielding films enable lightweight EMI protection, addressing the needs of industries focused on reducing weight without compromising functionality. Increasing semiconductor integration drives innovation in component-level EMC shielding, leading to the development of new materials and technologies that enhance device performance. Demand for high-reliability EMC solutions continues to strengthen in aerospace and defense electronics, where stringent compliance and reliability standards apply.
The medical electronics sector creates new requirements for EMC shielding and immunity testing, driven by the need for safe and effective medical devices. Evolving EMC standards increase the demand for radiated and conducted compliance testing, compelling manufacturers to invest in advanced testing solutions. Higher test frequencies drive investment in advanced EMC chambers and antennas, improving testing capabilities and ensuring compliance with emerging regulatory frameworks.
EMC test automation software reduces testing time and compliance costs, enabling manufacturers to bring products to market more efficiently. Supply chain localization shapes the availability of EMC shielding materials and components, impacting production timelines and costs. The expansion of electronics manufacturing in the Asia Pacific region significantly boosts demand for EMC shielding and test equipment, reflecting the growing industrial capabilities in this area.
North America leads the adoption of advanced EMC validation and compliance systems, driven by stringent regulatory requirements and a focus on high-quality manufacturing. Competitive innovation intensifies across EMC shielding materials and test platforms, pushing manufacturers to develop more effective and efficient solutions. Integrated shielding and thermal management solutions gain commercial relevance, addressing the dual needs of EMI protection and thermal efficiency in modern electronic designs.
The miniaturization of electronic devices creates new challenges for EMI mitigation, requiring innovative approaches to shielding and testing. Connected vehicles and automotive Ethernet increase the complexity of EMC testing, necessitating sophisticated methodologies that ensure interoperability and compliance. AI-enabled and connected devices introduce new electromagnetic compatibility challenges, highlighting the need for continuous advancements in EMC shielding and testing technologies.
Future growth opportunities in the EMC Shielding and Test Equipment market through 2033 will stem from ongoing technological advancements, regulatory changes, and the evolving needs of various industries.
Rising risks associated with electromagnetic interference (EMI) from high-density electronic systems significantly enhance demand for EMC shielding solutions. Industries focused on compact electronic devices, including telecommunications and consumer electronics, face heightened challenges in managing EMI risks, prompting investment in advanced shielding technologies.
The transition to 5G, 6G, and high-frequency electronics reshapes EMC testing requirements. These technologies introduce new operational frequencies and necessitate more rigorous compliance testing, compelling manufacturers to adopt innovative testing methods and equipment within the EMC Shielding and Test Equipment market.
Electric vehicles and advanced driver assistance systems expand requirements for EMC compliance. The increasing complexity of electrical systems in vehicles necessitates thorough testing to ensure functionality and safety, driving demand for specialized shielding solutions.
Growing adoption of board-level EMI shielding in compact electronics reflects the market's evolution. Manufacturers implement these shielding solutions to mitigate interference in densely packed circuits, enhancing the performance and reliability of electronic devices.
Automated EMC test systems accelerate compliance and product development processes. The integration of automation in testing environments enhances efficiency, reducing time and costs associated with compliance checks and enabling faster time-to-market for new products.
The importance of EMI pre-compliance testing increases within electronics design workflows. Early identification of potential EMI issues allows developers to address concerns proactively, streamlining the design process and ensuring regulatory compliance before final testing.
Advanced EMI receivers improve both the speed and accuracy of emissions testing. Enhanced measurement capabilities enable manufacturers to meet stringent compliance standards, instilling confidence in product performance and reliability.
Conductive elastomers and gaskets remain critical for enclosure-level EMI shielding. Their effectiveness in providing reliable seals against interference is essential for protecting sensitive electronic components, reinforcing their role in the market.
EMI absorbers and ferrite materials gain traction in high-frequency applications. These materials contribute to effective energy dissipation, ensuring compliance with evolving EMI standards and enhancing product performance.
Conductive coatings and shielding films enable lightweight EMI protection. These solutions offer manufacturers the flexibility to integrate shielding without compromising on weight, addressing the needs of industries focused on miniaturization.
Increasing semiconductor integration drives innovation in component-level EMC shielding. The need for effective shielding solutions addresses the challenges posed by densely integrated circuits, ensuring compliance in advanced electronic designs.
Aerospace and defense electronics strengthen demand for high-reliability EMC solutions. Stringent requirements for mission-critical applications necessitate robust shielding technologies to ensure operational integrity in challenging environments.
Medical electronics introduce new EMC shielding and immunity testing requirements. Ensuring safe and effective operation of medical devices mandates compliance with strict regulatory standards, influencing demand for specialized solutions.
Evolving EMC standards increase demand for both radiated and conducted compliance testing. Manufacturers adapt to these changes, ensuring that testing protocols align with the latest regulatory requirements.
Higher test frequencies drive investment in advanced EMC chambers and antennas. Facilities equipped with advanced technology enhance testing capabilities, enabling more accurate assessments of product compliance.
EMC test automation software reduces testing time and compliance costs. Streamlined processes facilitate quicker evaluations, allowing manufacturers to allocate resources more efficiently while maintaining compliance.
Supply chain localization shapes the availability of EMC shielding materials and components. Regional sourcing strategies enhance reliability in supply chains, addressing potential disruptions and ensuring timely access to essential materials.
The expansion of electronics manufacturing in the Asia Pacific region significantly boosts demand for EMC shielding and test equipment. This growth reflects the increasing focus on advanced technologies and compliance within regional markets.
North America leads in the adoption of advanced EMC validation and compliance systems. The region's emphasis on regulatory compliance drives investment in innovative testing solutions to meet evolving standards.
Competitive innovation intensifies across materials and test platforms within the market. Manufacturers strive to differentiate themselves through advanced technologies and superior performance, creating a dynamic competitive environment.
Integrated shielding and thermal management solutions gain commercial relevance. The convergence of these technologies addresses multiple challenges within electronic design, enhancing overall product performance.
Miniaturization of electronic devices creates new challenges for EMI mitigation. Manufacturers develop innovative strategies to address the complexities of smaller components while ensuring compliance with EMI standards.
Connected vehicles and automotive Ethernet increase the complexity of EMC testing. The integration of sophisticated communication systems within vehicles necessitates comprehensive testing to ensure functionality and safety.
AI-enabled and connected devices introduce new challenges for electromagnetic compatibility. The evolving landscape of technology requires continuous adaptation of shielding solutions to address emerging issues related to connectivity and interference.
Future growth opportunities in the EMC Shielding and Test Equipment market extend through 2033. Ongoing advancements in technology and regulatory frameworks will continue to shape the market, driving innovation and investment in this critical sector.
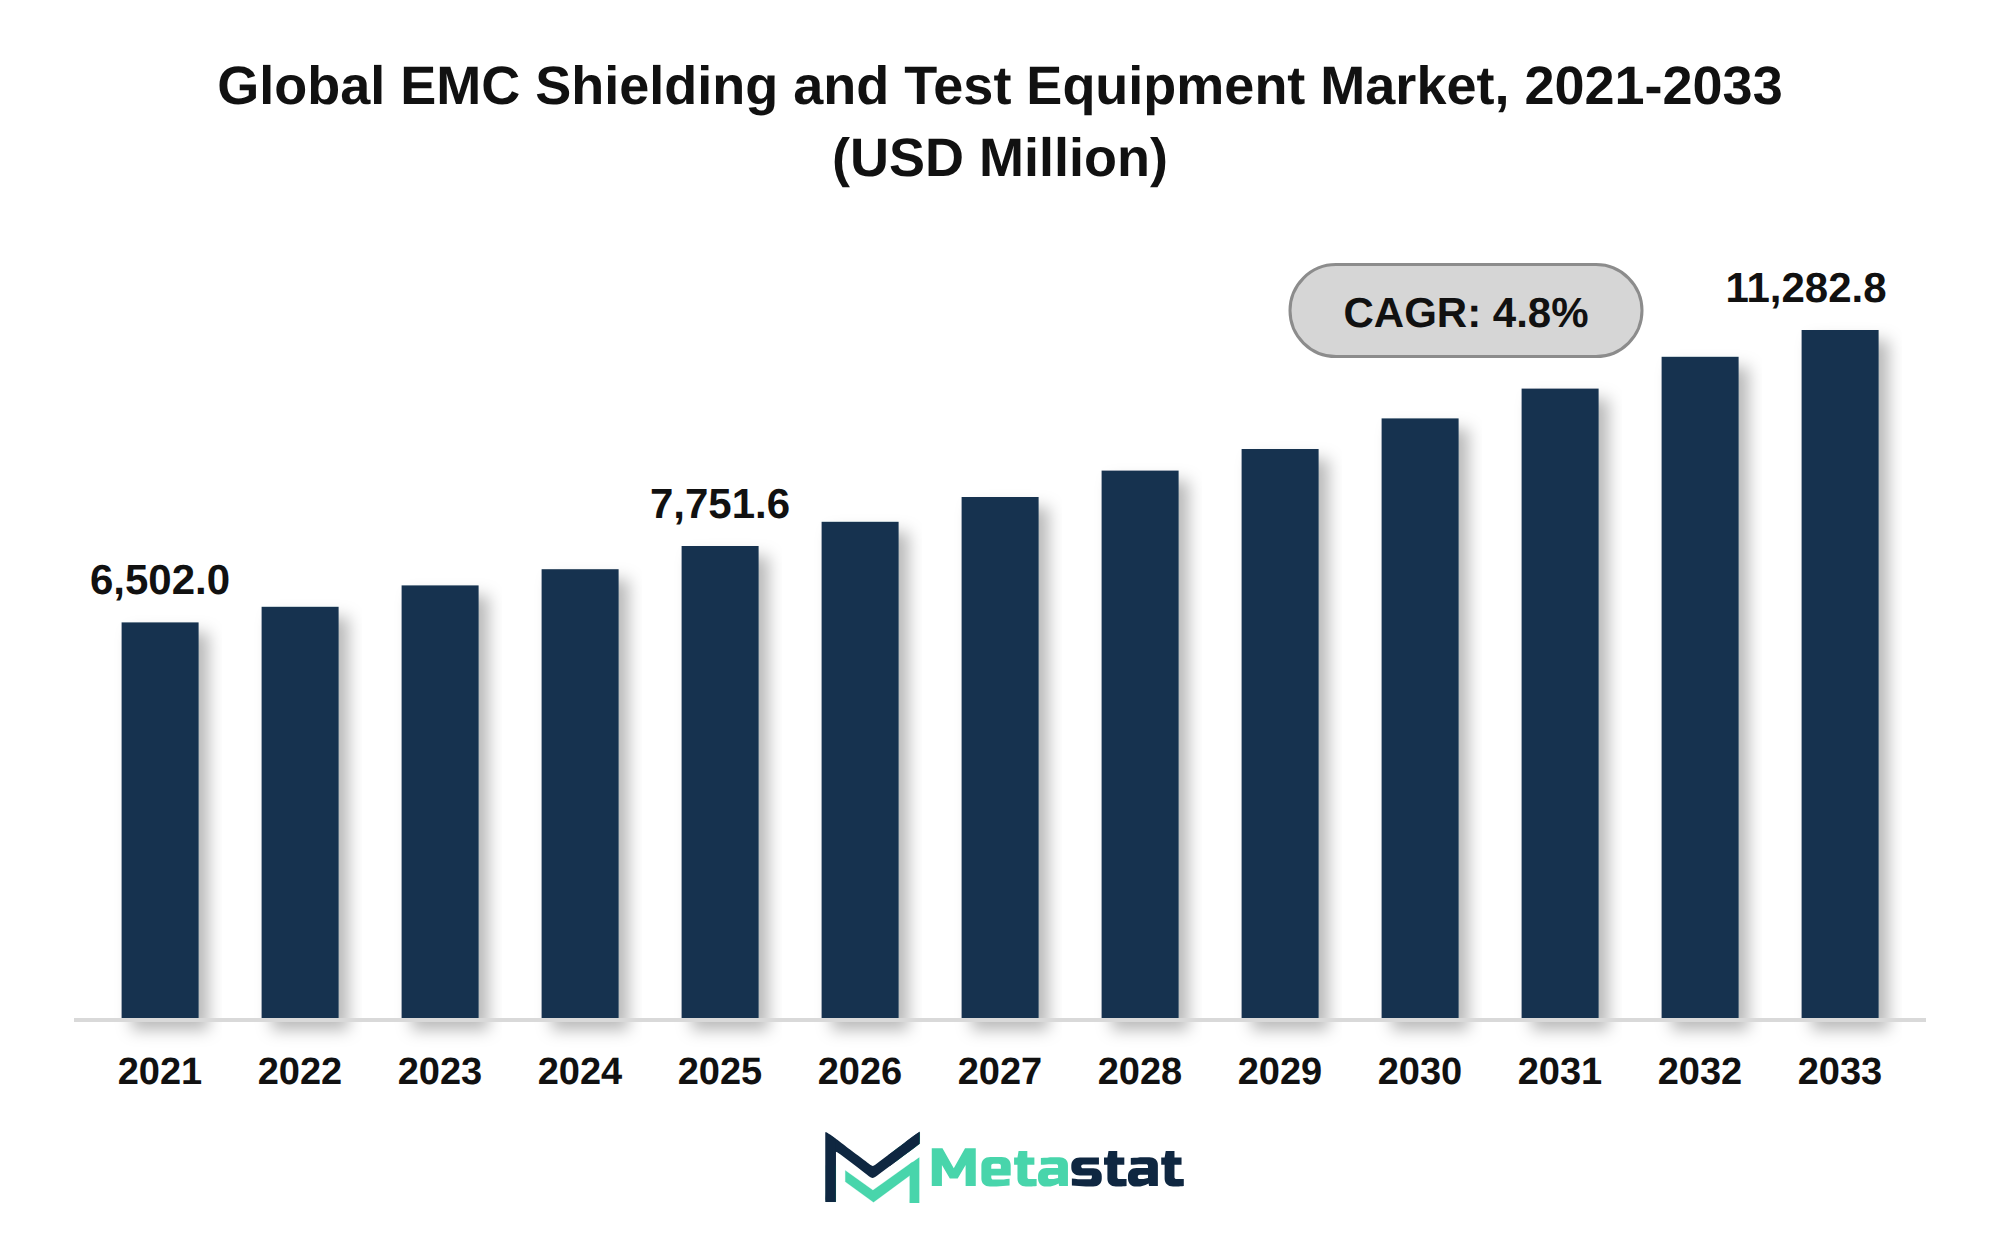
The adoption of closed-loop systems in the EMC Shielding and Test Equipment market reflects growing concerns over electromagnetic interference (EMI) and its regulatory implications. Enhanced emission limits require manufacturers to ensure compliance, influencing production processes and materials used in shielding solutions. Industries including consumer electronics, telecommunications, and automotive are among the primary sectors responding to these mandates, leading to increased investments in shielding technologies.
Operational costs associated with achieving compliance drive demand for advanced EMC shielding solutions. Manufacturers experience pressure to maintain product quality while simultaneously reducing costs, prompting the integration of innovative materials and design techniques. Consequently, investments in EMC Shielding and Test Equipment become critical to sustaining market competitiveness and operational efficiency.
Tightening emission limits globally support market expansion. Companies that proactively adapt their shielding strategies enhance compliance and position themselves favorably within their respective industries. This proactive approach supports revenue growth while encouraging a culture of innovation in product development.
Investment in infrastructure development drives modernization within the EMC Shielding and Test Equipment market. Upgrading physical and digital capacities encourages manufacturers to enhance their operational capabilities, leading to improved product offerings that address growing consumer demands. This trend results from increasing public-private collaboration and investment aimed at supporting economic growth, ultimately creating a favorable environment for market expansion.
In numerous industries, the push for modernization translates into enhanced productivity and operational efficiency. Companies prioritize automation and the digitization of legacy processes, allowing for faster adaptation to changing technological landscapes. This shift reduces costs and improves the quality and efficacy of EMC shielding solutions, positioning firms competitively in the market.
The focus on infrastructure development has facilitated better access to advanced technologies. Integration of advanced materials and testing techniques improves product performance, helping vendors meet stringent customer requirements. Consequently, the market experiences significant growth driven by increased confidence in new technologies and the capacity to innovate in response to evolving consumer preferences.
The EMC Shielding and Test Equipment market faces considerable challenges due to stringent regulatory compliance requirements. Manufacturers experience difficulty in adapting to evolving regulations, resulting in delays and increased operational complexities. Different regions impose unique standards, leading to a fragmented market where compliance hurdles deter new entrants and complicate the operations of existing players.
High capital investment requirements for compliance with these regulations strain resources, particularly for smaller firms. These firms encounter challenges in allocating sufficient funds for technological upgrades or necessary certifications, which restricts market accessibility and slows down product innovation. Escalating operating costs associated with maintaining compliance standards further exacerbate these financial pressures.
Geopolitical instability influences regulatory environments, often leading to unpredictable shifts in compliance requirements across different regions. This uncertainty poses risks for investments in the EMC Shielding and Test Equipment market, where firms hesitate to commit resources without clear regulatory guidance. Such volatility stifles growth opportunities and creates barriers for companies seeking to expand their market presence.
The EMC Shielding and Test Equipment market experiences challenges stemming from geopolitical fragmentation and supply chain instability. Escalating trade deficits and tariff friction disrupt established supply routes, complicating access to essential components and materials. This situation leads to increased costs for manufacturers, affecting pricing strategies and profit margins.
Technological disruptions contribute to market pressures. Companies strive to integrate complex research and development efforts while maintaining interoperability across diverse systems. This complexity raises the cost of innovation and slows product development cycles, impacting overall market growth.
Escalating input cost structures and rising workforce skill gaps create operational challenges. Companies face difficulties attracting and retaining skilled labor necessary for advanced production techniques, which directly influences competitive positioning in the EMC Shielding and Test Equipment market. Talent retention pressures constrain companies' abilities to execute growth strategies effectively.
Environmental and sustainability demands exert additional strain on the market, pushing firms to adopt decarbonization mandates and address lifecycle footprints. Compliance overhead related to tightening global regulatory standards adds to operational complexity, diverting resources from product development and market expansion efforts. This multifaceted backdrop significantly influences market trajectory and growth potential.
Changing regional demands present significant growth opportunities within the EMC Shielding and Test Equipment market. Geographical expansion, particularly in North America and Asia Pacific, significantly influences market dynamics, driven by rising electronic device usage and stringent compliance requirements.
Infrastructure modernization initiatives enhance the adoption of advanced EMC shielding technologies across sectors including automotive, telecommunications, and consumer electronics. Digital transformation accelerates the integration of innovative solutions, aligning with the shift toward next-generation applications. Sustainability imperatives encourage the development of eco-friendly products.
Strategic consolidation and cross-industry mergers create pathways for new product development and diversification within the market. Evolving buying behaviors, influenced by digital procurement shifts, drive demand for integrated solutions that cater to specific industry needs. This transition creates an environment conducive to innovation, with a focus on niche applications and operational yield maximization.
Value-chain optimization becomes critical because companies seek to enhance competitiveness. Supply chain localization strategies and import substitution frameworks support resilience against market fluctuations. These factors collectively create an environment ripe for investment, propelling the EMC Shielding and Test Equipment market toward sustained growth through 2033.
The Global EMC Shielding and Test Equipment market is segmented based on Product Type, Application, and End-Use Industry.
Valued at USD 1,189.7 million in 2026, the EMI Shielding Gaskets & Conductive Elastomers segment is projected to reach USD 1,514.2 million by 2033, at a CAGR of 3.5% during the forecast period. Demand for EMI shielding gaskets and conductive elastomers is driven by the increasing need for effective electromagnetic interference (EMI) protection in various electronic applications. The rapid expansion of the consumer electronics sector, along with the growing reliance on advanced telecommunications systems, fuels this demand.
Emerging trends in technology, including the Internet of Things (IoT) and smart devices, contribute to significant growth in the market. These advancements create a need for enhanced EMI shielding solutions that ensure reliable performance in compact and densely packed electronic designs. In addition, the automotive and aerospace industries emphasize the importance of EMI shielding, leading to increased investments and innovations in conductive elastomers and gaskets.
Regulatory compliance standards drive market dynamics, because manufacturers seek materials that meet stringent safety and performance requirements. Certifications for EMI shielding products enhance credibility and support competitive positioning within the market. Cost structures related to raw material sourcing and production processes play a vital role in shaping pricing strategies, impacting overall market stability. The forecasted growth of the EMI Shielding Gaskets & Conductive Elastomers segment reflects a robust trajectory, ensuring it remains a key component of the EMC Shielding and Test Equipment market.
Growth in the Shielding Tapes, Foils, Films & Conductive Fabrics segment results from increasing demand for advanced electromagnetic compatibility solutions across various industries. The surge in consumer electronics and automotive applications drives the need for effective EMI shielding solutions, enhancing product performance and safety. Regulatory compliance standards in sectors including telecommunications and automotive significantly influence adoption rates, pushing manufacturers to incorporate shielding materials in their designs.
Technological maturation in materials used for shielding contributes to the segment's expansion. Innovations in conductive fabrics and films facilitate lighter, more efficient solutions for EMI protection, appealing to manufacturers focusing on reducing weight and improving performance in their products. Strategic investments in R&D lead to the introduction of next-generation upgrades, ensuring that products remain competitive in a changing marketplace.
By 2033, the segment is projected to reach USD 1,317.8 million at a CAGR of 4% during the forecast period. The growing emphasis on product evolution and downstream applications further enhances its relevance in the EMC Shielding and Test Equipment market. Industries increasingly recognize the importance of shielding in safeguarding electronic systems, and demand for these materials is expected to strengthen.
Market dynamics for conductive coatings, adhesives, and caulks reflect a growing focus on effective EMI shielding solutions across various electronic applications. Increasing electronic device integration and the demand for miniaturization drive significant interest in this segment. Regulatory compliance and the need for reliable performance in critical applications reinforce the push toward high-quality conductive materials.
The projected market value for conductive coatings, adhesives, and caulks is USD 1,098.9 million by 2033. This growth reflects the ongoing evolution of materials that enhance performance in areas including consumer electronics, telecommunications, and automotive industries. Innovations in formulation and application methods contribute to improved efficacy and ease of use, appealing to manufacturers looking to optimize production processes.
Heightened importance on sustainable practices influences raw material sourcing and product formulation. Manufacturers prioritize environmentally friendly materials, aligning with broader industry trends toward sustainability. Compliance with evolving regulations enhances the competitive landscape, driven by firms striving to develop solutions that meet stringent performance and environmental standards.
Successful players within the EMC Shielding and Test Equipment market focus on strategic collaborations, enhancing their product portfolios and market reach. While technology matures, investment in research and development remains critical for maintaining competitive advantages within this segment. Adapting to shifting consumer preferences and technological advancements continues to shape the trajectory of conductive coatings, adhesives, and caulks.
Growing awareness of electromagnetic interference (EMI) mitigation influences demand for Board-Level Shields & Shielding Cans within the EMC Shielding and Test Equipment market. This segment is projected to grow at a CAGR of 5.3% during the forecast period. Increased electronic device integration in various industries, including telecommunications and consumer electronics, drives the need for enhanced shielding solutions that protect sensitive components from EMI.
Technological maturation supports innovation in materials and designs for Board-Level Shields & Shielding Cans. The evolution of compact electronic systems enhances the demand for efficient shielding solutions, enabling manufacturers to meet stringent regulatory compliance standards and certifications. Investments in next-generation upgrades ensure that products maintain relevance against disruptive alternatives.
End-use dynamics play a significant role in shaping market trends. The telecommunications and automotive sectors particularly benefit from advancements in shielding technologies. Enhanced performance in electromagnetic compatibility (EMC) testing is vital for manufacturers aiming to achieve compliance and improve product reliability.
Pricing volatility and margin pressures characterize the landscape of Board-Level Shields & Shielding Cans. Fluctuations in raw material costs influence pricing strategies. Strategic opportunity windows arise for manufacturers focused on developing cost-effective solutions while ensuring compliance with industry standards.
Overall, sustained capital investment outlooks in the electronics industry support growth prospects for the Board-Level Shields & Shielding Cans segment, driving expansion within the broader EMC Shielding and Test Equipment market.
Electromagnetic interference (EMI) poses challenges across numerous industries, driving demand for EMI absorbers and ferrite materials within the EMC Shielding and Test Equipment market. These materials effectively mitigate EMI, enhancing the performance and reliability of electronic devices. Industries including telecommunications, automotive, and aerospace adopt these solutions, influenced by growing regulatory compliance standards and consumer expectations for device reliability.
Technological maturation plays a critical role in the evolution of EMI absorbers and ferrite materials. Continuous advancements in material science lead to the development of more efficient and cost-effective products, facilitating their integration into next-generation electronic systems. The downstream application of these materials extends to consumer electronics, medical devices, and industrial automation, where reliable performance remains essential.
Consumption shifts, spurred by increased electronic device usage and the proliferation of smart technologies, impact the market. Manufacturers prioritize high-performance and efficient shielding solutions, resulting in strategic investments in research and development. These investments focus on improving product attributes, including weight reduction and enhanced shielding effectiveness, addressing evolving market demands.
Pricing volatility and margin pressures arise from fluctuations in raw material costs and supply chain dynamics. Sourcing high-quality ferrite materials requires careful management to ensure cost efficiency while maintaining product integrity. Strategic opportunity windows emerge for companies that successfully navigate these challenges, establishing themselves because leaders in the production of advanced EMI shielding solutions.
The emphasis on sustainability and regulatory compliance continues to shape the market. Certifications that validate the effectiveness of EMI absorbers and ferrite materials influence purchasing decisions among end-users. While industries evolve, investment in innovative solutions that meet stringent regulations becomes crucial for long-term success in the EMC Shielding and Test Equipment market.
Growing concerns regarding electromagnetic interference (EMI) impact various sectors, propelling demand for effective shielding solutions. This heightened focus on protecting sensitive electronic components drives the adoption of shielded vents, windows, cable shields, and enclosures. Industries including telecommunications, consumer electronics, and automotive emphasize minimizing EMI risks, creating a favorable environment for segment growth.
Technological advancements contribute to the evolution of shielding products. Innovations in materials and design enhance the effectiveness of shielded vents, windows, cable shields, and enclosures, ensuring compliance with stringent regulatory standards. Manufacturers prioritize advanced materials, while the market experiences heightened investment in research and development to integrate next-generation upgrades into existing offerings.
Consumer expectations for high-performance electronic devices fuel changes in end-use dynamics. The demand for lightweight, compact, and durable solutions influences design strategies among manufacturers. These shifts result in an increased focus on the integration of shielding solutions that meet both functional and aesthetic requirements. The market reflects this trend by evolving products that cater to specific industry needs while maintaining performance integrity.
Cost structures play a crucial role in shaping market dynamics. Fluctuations in raw material prices have implications for manufacturers, impacting overall pricing strategies. Companies in the market navigate these challenges by optimizing supply chain resilience and sourcing strategies. Strategic partnerships with suppliers ensure a steady flow of high-quality materials, mitigating potential disruptions and supporting competitive pricing in the market.
Compliance with regulatory standards remains a critical factor influencing the market. Organizations adhere to various certifications and guidelines to ensure product reliability and performance. This regulatory landscape drives manufacturers to invest in quality assurance processes, promoting trust among end-users and encouraging brand loyalty. While the market evolves, regulatory compliance continues to shape product development strategies within the segment.
Technological advancements in EMI receivers and spectrum analyzers drive the expansion of this segment within the EMC Shielding and Test Equipment market. The increase in high-frequency applications across telecommunications and consumer electronics creates demand for precise measurement equipment. Regulatory compliance regarding electromagnetic compatibility (EMC) significantly influences the adoption of these devices, reflecting stringent industry standards that manufacturers meet.
The evolution of wireless technologies, including 5G, increases the need for sophisticated testing equipment to ensure signal integrity and compliance. Manufacturers focus on enhancing device capabilities, leading to product evolution in response to market demands. Supply chain resilience remains crucial, particularly in sourcing high-quality materials essential for producing advanced testing equipment.
Emerging markets present strategic opportunities for growth, especially in regions investing heavily in telecommunications infrastructure. Market dynamics encourage collaboration among key players, driving innovation and addressing diverse customer needs. While regulatory standards continue to evolve, the emphasis on performance testing and compliance reinforces the role of EMI receivers and spectrum analyzers within the broader EMC Shielding and Test Equipment market.
Growing demand for EMC immunity generators, simulators, and RF amplifiers stems from the increasing complexity of electronic systems, which require robust solutions to ensure compliance with stringent electromagnetic compatibility (EMC) standards. Industries including telecommunications, aerospace, and automotive heavily rely on these technologies to maintain functionality and performance in environments susceptible to electromagnetic interference (EMI).
Technological maturation in this segment promotes enhanced capabilities, allowing for more accurate testing and simulation of electromagnetic environments. These advancements drive adoption rates among manufacturers aiming for certification and compliance with regulatory standards. Enhanced product evolution aligns with the industry's continuous shift towards miniaturization and increased performance in electronic devices.
End-use dynamics show a strong emphasis on reliable performance in safety-critical applications, generating significant consumption shifts towards high-quality EMC immunity testing solutions. The establishment of rigorous regulatory compliance standards necessitates that manufacturers adopt these advanced testing solutions, ensuring their products meet required specifications.
Raw material sourcing and supply chain resilience impact the availability and cost structure of these technologies. Strategic opportunity windows arise from manufacturers investing in innovative solutions that address existing gaps in performance and efficiency. A focus on sustainability within the EMC Shielding and Test Equipment market encourages manufacturers to explore eco-friendly alternatives in product development.
Technological advancements drive the adoption of EMC antennas, probes, LISNs, and coupling networks within various sectors. These components play a crucial role in ensuring compliance with strict regulatory standards, which influences demand across industries that require effective electromagnetic compatibility solutions.
A surge in electronic devices across consumer electronics, telecommunications, and automotive sectors increases the necessity for reliable EMC testing solutions. Consequently, manufacturers prioritize the incorporation of advanced testing equipment to mitigate risks associated with electromagnetic interference, resulting in heightened focus on product development and innovation.
Shifts in consumption patterns toward smarter technologies and IoT applications intensify the need for highly efficient EMC testing solutions. The market experiences continuous change, with manufacturers focusing on enhancing product capabilities to provide comprehensive testing and shielding solutions.
Regulatory compliance drives manufacturers to invest in next-gen upgrades and certifications, ensuring that their products meet the latest industry standards. This emphasis on compliance increases competition among players within the EMC Shielding and Test Equipment market, pushing them to develop innovative solutions that cater to diverse customer needs.
Strategic opportunity windows arise due to industries increasingly recognizing the importance of electromagnetic compatibility. Capital investment in this segment is projected to grow, reflecting the industry's commitment to innovation and meeting the demands of a changing technological environment.
Strong demand for EMC Test Systems, Chambers, Software & Automation arises from increasing regulatory compliance requirements across various industries. These systems facilitate thorough testing and validation of electronic components against electromagnetic interference (EMI), ensuring products meet established standards. The market experiences notable expansion catalysts driven by innovations in technology, including automation in testing processes, which enhances efficiency and accuracy. The evolution of next-generation upgrades positions these products because essential in maintaining competitive advantage within the evolving environment of electromagnetic compatibility.
End-use dynamics highlight the crucial role of these systems in sectors including telecommunications, automotive, and aerospace. While industries prioritize the integrity of their electronic devices, the need for reliable testing solutions increases. Consumption shifts towards integrated solutions that offer comprehensive testing capabilities further drive demand within the market. Regulatory compliance standards continue to influence purchasing decisions, with organizations investing in advanced testing systems to mitigate risks associated with electromagnetic interference.
The environment for EMC Test Systems, Chambers, Software & Automation is characterized by pricing volatility and margin pressures due to fluctuating raw material costs. Strategic opportunity windows arise for manufacturers who innovate and adapt to both technological obsolescence and the introduction of disruptive alternatives. Maintaining supply chain resilience is critical, particularly in the sourcing of specialized components necessary for these systems. While these factors coalesce, the EMC Shielding and Test Equipment market reflects a robust commitment to advancing testing technologies and meeting the increasing demands of diverse industries.
Valued at USD 1,270.4 million in 2026, the Electronic Enclosure & Cabinet Shielding segment is projected to reach USD 1,649.6 million by 2033, at a CAGR of 3.8% during the forecast period. Strong demand for robust shielding solutions in electronic enclosures arises from heightened concerns regarding electromagnetic interference (EMI) and the necessity for regulatory compliance across various sectors. Industries including telecommunications, automotive, and consumer electronics drive adoption, prioritizing the protection of sensitive components housed in enclosures and cabinets.
Technological maturation plays a critical role in shaping market dynamics. Advances in materials and manufacturing techniques lead to the development of high-performance shielding solutions that meet stringent EMI regulations. Next-generation upgrades in shielding technologies enhance the effectiveness of these products, addressing the evolving challenges posed by increasingly sophisticated electronic devices.
Growth in the market is supported by a shift towards compact and efficient designs in electronic equipment, necessitating effective shielding solutions that do not compromise space or performance. Regulatory compliance standards further influence segment expansion, driven by manufacturers seeking to adhere to guidelines that mandate EMI protection in various applications. Increased investment in research and development drives innovation, resulting in product evolution that aligns with changing market demands.
While various industries experience digital transformation and increased connectivity, the need for effective EMC shielding solutions becomes more pronounced. Market players are expected to capitalize on strategic opportunity windows, focusing on enhancing supply chain resilience and raw material sourcing strategies to mitigate potential disruptions. Continuous monitoring of pricing volatility and margin pressures remains essential, with companies strategizing to maintain competitive advantage in the evolving EMC Shielding and Test Equipment market.
Growth in the PCB & Component-Level Shielding segment reflects the increasing complexity of electronic devices and the subsequent need for effective EMI protection. This segment is projected to reach USD 1,614.6 million by 2033, at a CAGR of 5.6% during the forecast period. The rise in consumer electronics and computing applications, along with advancements in telecommunications and networking, drives demand for robust shielding solutions. Manufacturers prioritize the development of high-performance materials and innovative designs that enhance shielding effectiveness while maintaining compact form factors.
Technological maturation facilitates next-generation upgrades, enabling products to meet stringent regulatory compliance standards. Evolving industries and shifts in consumption patterns emphasize the necessity for high-quality shielded components in various applications. End-use dynamics highlight the critical role of effective shielding in ensuring reliable performance across devices, particularly in sectors including automotive and aerospace, where electromagnetic interference poses significant risks. Pricing volatility and cost structures influence manufacturers' strategies, encouraging investments in research and development to maintain competitive advantage in the market.
Increasing reliance on sophisticated electronic systems drives demand for Cable & Interconnect Shielding within the EMC Shielding and Test Equipment market. While networks expand and devices become more interconnected, the requirement for effective shielding solutions that minimize electromagnetic interference (EMI) continues to rise. This segment is expected to reach USD 1,096.7 million by 2033, reflecting steady growth attributed to advancements in technology and a focus on regulatory compliance across various industries.
Manufacturers within the market face pressures related to cost structures and pricing volatility, impacting their strategies for product development. Innovations in materials and design techniques enhance the effectiveness of shielding solutions, supporting adoption across sectors including telecommunications, consumer electronics, and automotive. With an emphasis on high-performance applications, stakeholders seek products that deliver both reliability and compliance with industry standards, driving investment in the development of next-generation shielding products.
End-use dynamics indicate a shift toward greater integration of shielding solutions into new electronic designs. This evolution not only addresses existing challenges but anticipates future requirements driven by technology maturation. Such proactive approaches ensure that manufacturers maintain competitiveness while responding to the increasing complexity of electronic components. Strategic opportunities arise from the need for enhanced shielding performance and the continuous development of innovative solutions within the EMC Shielding and Test Equipment market.
Increasing demand for effective electromagnetic shielding in various applications drives growth in the Display, Window & Vent Shielding segment. This segment is projected to grow at a CAGR of 3.7% during the forecast period. Rising awareness of electromagnetic interference (EMI) among end-users influences the adoption of advanced shielding solutions. Industries including consumer electronics, telecommunications, and automotive emphasize enhanced performance and safety, further boosting market demand. Regulatory compliance standards, particularly in the automotive and aerospace sectors, necessitate robust shielding solutions to ensure product safety and reliability.
Technological maturation facilitates product evolution, with manufacturers integrating next-generation materials and designs to enhance shielding effectiveness. Innovations in conductive coatings and elastomers contribute to the segment's growth by providing lightweight and efficient solutions. The market benefits from a shift in consumption patterns toward more sophisticated electronic devices that require reliable EMI shielding to meet performance expectations. This trend highlights the importance of product development focused on high-performance shielding solutions in the EMC Shielding and Test Equipment market.
Regulatory compliance standards significantly influence demand for radiated emissions testing. Industries including telecommunications and consumer electronics impose strict guidelines that require rigorous testing to ensure product safety and functionality. This requirement drives investments in testing equipment and methodologies, ultimately driving growth within the EMC Shielding and Test Equipment market.
End-use dynamics illustrate a strong focus on product reliability and performance, compelling manufacturers to prioritize radiated emissions testing during the product development phase. This emphasis on quality assurance leads to increased adoption of advanced testing equipment, enhancing overall market competitiveness. Technological maturation in testing solutions facilitates more efficient processes, encouraging firms to invest in next-generation upgrades.
Consumption shifts towards high-performance electronic devices contribute to expanding market opportunities for radiated emissions testing. While consumers demand more sophisticated features in their devices, manufacturers ensure compliance with stringent electromagnetic compatibility requirements. This scenario creates a favorable environment for the EMC Shielding and Test Equipment market, enhancing potential revenue streams for companies involved in this segment.
Strategic opportunity windows emerge because organizations seek to mitigate risks associated with electromagnetic interference. Continuous advancements in technology and testing methodologies open pathways for product evolution, enabling firms to address emerging challenges effectively. Capital investment outlook remains positive, with stakeholders recognizing the critical role of radiated emissions testing in maintaining market relevance.
Demand for effective testing methods in the EMC Shielding and Test Equipment market stems from regulatory requirements and the need for compliance with industry standards. Heightened scrutiny on product safety and performance leads companies to invest in conducted emissions testing to mitigate risks associated with electromagnetic interference (EMI).
Technological maturation in testing equipment enhances the accuracy and efficiency of conducted emissions testing. Innovations in testing methodologies and equipment support the evolving landscape, enabling companies to address compliance challenges effectively. This evolution drives adoption across various industries, including consumer electronics and telecommunications, where ensuring product performance is critical.
End-use dynamics play a crucial role in shaping the conducted emissions testing segment. Industries increasingly recognize the importance of EMI testing in safeguarding product integrity and reliability, leading to higher consumption of testing services and equipment. Shifts in consumer preferences towards high-quality electronic products push manufacturers to prioritize compliance, driving growth within the segment.
Regulatory compliance standards significantly impact investment in conducted emissions testing. Companies prioritize adherence to these standards, understanding the potential for penalties or product recalls due to non-compliance. This focus on regulatory alignment drives growth in the market, driven by organizations seeking to enhance their testing capabilities and ensure product safety.
Strategic opportunity windows arise from the increasing complexity of electronic systems and the corresponding demand for comprehensive EMI testing solutions. The market responds with advanced offerings that address specific testing needs, promoting further investment and expansion. The focus on next-generation upgrades and product evolution strengthens the segment's position within the broader EMC Shielding and Test Equipment market.
The landscape of conducted emissions testing reflects a synthesis of rigorous compliance demands and technological advancements. Companies are well-positioned to capitalize on these trends, enhancing their market presence through improved testing methodologies and robust product offerings.
Rising awareness surrounding the importance of radiated immunity testing drives its adoption across various sectors, particularly in industries including telecommunications and consumer electronics. The necessity for compliance with stringent regulatory standards increases demand for these tests, ensuring that products perform reliably in electromagnetic environments.
The evolution of testing methodologies and technologies supports the segment's growth. Innovation in EMC testing equipment enhances effectiveness, allowing for more comprehensive assessment of electromagnetic compatibility. Timely upgrades to testing apparatus ensure that manufacturers maintain compliance with evolving industry regulations.
Increased investment in research and development by key players within the EMC Shielding and Test Equipment market strengthens the capabilities of radiated immunity testing. This investment leads to the introduction of next-generation testing solutions, enabling more precise measurements and greater confidence in product performance.
Industry dynamics, including the push for advanced electronics and the proliferation of smart devices, necessitate robust testing protocols. Such trends drive manufacturers to prioritize radiated immunity testing, embedding it within their product development lifecycle to mitigate risks associated with electromagnetic interference.
Cost structures in radiated immunity testing reflect the complexity and precision required for effective assessment. While initial investments in advanced testing technologies are substantial, the long-term benefits of improved product reliability and compliance with regulations contribute to overall operational efficiency.
Strategic opportunity windows emerge owing to evolving regulatory frameworks and industries seeking to enhance product performance and safety. The demand for reliable electromagnetic compatibility testing solutions positions the segment favorably for continued growth within the EMC Shielding and Test Equipment market.
Increased focus on compliance with regulatory standards for electromagnetic compatibility (EMC) significantly influences demand for conducted immunity testing within the EMC Shielding and Test Equipment market. Industries including telecommunications, automotive, and aerospace require thorough testing to ensure that their products meet stringent safety and performance standards, mitigating risks associated with electromagnetic interference (EMI). Technologies evolve, and manufacturers develop advanced testing solutions that enhance accuracy and reliability, supporting the growing need for compliance in a competitive landscape.
Technological maturation in testing equipment drives efficiency and effectiveness in conducted immunity assessments. Investment in next-generation upgrades and product evolution provides manufacturers with tools to conduct more precise testing, ensuring their products perform optimally in real-world conditions. Enhanced testing capabilities facilitate widespread adoption across various applications, including consumer electronics and industrial automation.
End-use dynamics play a crucial role in shaping the demand for conducted immunity testing. Electronic systems become more intricate, increasing the potential for EMI-related issues and prompting manufacturers to prioritize testing to safeguard product integrity. The market's response to these dynamics emphasizes the importance of robust testing methodologies and compliance with industry standards, positioning conducted immunity testing because a critical component of the EMC Shielding and Test Equipment market.
Consumption shifts toward environmentally sustainable practices further impact testing requirements. Manufacturers increasingly seek solutions that comply with regulations and align with eco-friendly initiatives. This trend is driving innovation in testing methodologies and materials, addressing both performance and environmental considerations. Strategic opportunity windows arise for companies that adapt to these shifts, highlighting the need for ongoing investment in research and development.
Growing emphasis on robust ESD, EFT/Burst and Surge Immunity Testing reflects the increasing sophistication of electronic devices and systems. Manufacturers require reliable methods to assess device resilience against electrical disturbances, which drives demand in the EMC Shielding and Test Equipment market. Regulatory requirements play a crucial role in shaping testing protocols, enhancing the adoption of comprehensive testing solutions that ensure compliance with industry standards.
The segment benefits from advancements in testing technologies, enabling more accurate and efficient assessments. Enhanced product evolution within the segment pushes manufacturers to invest in next-generation testing equipment that improves overall performance. This focus on technological maturation supports the growth of the overall market, driven by companies seeking to mitigate risks associated with electromagnetic interference.
Shifting end-use dynamics across numerous industries, including telecommunications and automotive, increase the necessity for effective surge immunity solutions. Increased integration of electronics in various applications intensifies the demand for stringent testing processes. Consequently, investment in high-quality ESD, EFT/Burst and Surge Immunity Testing becomes essential for maintaining operational integrity and product reliability.
Strategic opportunity windows arise from evolving consumption patterns, where manufacturers prioritize safety and compliance. These trends create a competitive environment where companies continuously innovate to stay ahead. The focus on regulatory compliance alongside technological advancements highlights the potential for growth within this segment of the EMC Shielding and Test Equipment market.
Heightened focus on ensuring compliance with regulatory standards drives the demand for Shielding Effectiveness & EMC Site Validation. Organizations recognize the necessity of conducting thorough validations to ensure that products meet electromagnetic compatibility requirements across various applications. This validation process directly impacts the quality and reliability of electronic systems, enhancing confidence among manufacturers and end-users.
Technological maturation within the EMC Shielding and Test Equipment market creates opportunities for advancements in testing methodologies and equipment capabilities. Innovations contribute to more efficient testing processes, improving the accuracy and repeatability of results. Growing complexity in electronic devices heightens the necessity for comprehensive testing, further fueling demand within this segment.
End-user dynamics play a critical role in shaping the market for Shielding Effectiveness & EMC Site Validation. Increased adoption of advanced technologies in sectors including telecommunications, automotive, and consumer electronics necessitates rigorous validation processes. This trend highlights the importance of robust testing protocols to mitigate risks associated with electromagnetic interference.
Consumption shifts towards more sophisticated electronic solutions drive the need for effective validation methods. While industries evolve, the requirement for reliable and efficient EMC testing becomes essential. This shift presents strategic opportunities for stakeholders to invest in innovative solutions that enhance testing efficiency and accuracy.
Regulatory compliance standards and certifications significantly influence the operational landscape. Organizations face pressure to meet stringent requirements, leading to heightened investments in validation processes. Staying abreast of regulatory changes remains essential for ensuring ongoing compliance and competitiveness.
Valued at USD 1,474.8 million in 2026, the Consumer Electronics & Computing segment is projected to reach USD 1,888.7 million by 2033, at a CAGR of 3.6% during the forecast period. Demand in this segment stems from the increasing reliance on advanced consumer electronics, including smartphones, laptops, and gaming devices. This growth leads to heightened requirements for effective electromagnetic compatibility, necessitating robust EMC shielding and test equipment to ensure device performance and reliability.
Technological maturation within consumer electronics drives the adoption of innovative shielding solutions that enhance product longevity and user experience. The segment benefits from continuous product evolution, with manufacturers integrating advanced materials and designs that improve electromagnetic interference resistance. Downstream applications across various consumer markets fuel demand, influencing the broader dynamics of the EMC Shielding and Test Equipment market.
Compliance with regulatory standards remains a critical factor, with manufacturers facing increasing pressure to meet stringent electromagnetic compatibility benchmarks. This regulatory landscape shapes investment strategies, directing capital towards advanced shielding technologies and testing methodologies. Evolving compliance requirements exert pressure on overall cost structures, impacting pricing strategies in the competitive market environment.
Increasing reliance on advanced communication technologies fuels growth in the Telecommunications & Networking segment of the EMC Shielding and Test Equipment market. Investments in 5G infrastructure and the growing demand for high-speed connectivity drive this segment's expansion. Effective electromagnetic shielding becomes essential to ensure compliance with stringent regulatory standards, which influences purchasing decisions across the industry. The segment is estimated to reach USD 1,366.4 million by 2033, at a CAGR of 4.1% during the forecast period. This growth positions the market favorably because telecommunications companies seek innovative solutions to mitigate electromagnetic interference, enhancing the performance and reliability of their products.
Demand for effective EMC shielding solutions within the Automotive & Electric Vehicles segment stems from the increasing integration of advanced electronic systems in vehicles. These systems require robust protection against electromagnetic interference to ensure functionality and safety. The growing trend towards electric vehicles further intensifies this demand, driven by the incorporation of multiple electronic components that necessitate effective shielding to operate optimally.
Automotive manufacturers prioritize compliance with regulatory standards for electromagnetic compatibility, driving investments in shielding and testing equipment. This focus on regulation contributes to market growth, attributed to the increasing criticality of adherence to these standards for market access and consumer safety. The segment is projected to reach USD 2,139.2 million by 2033, reflecting a robust trajectory defined by rapid technological advancements and evolving consumer expectations.
Strategic investment in next-generation upgrades and innovations enhances product evolution within this segment. Manufacturers explore new materials and technologies to improve shielding effectiveness while reducing costs. This evolution aligns with industry trends toward sustainability and efficiency, enabling automotive firms to meet both regulatory and consumer demands effectively.
Overall, the Automotive & Electric Vehicles segment significantly influences the EMC Shielding and Test Equipment market, demonstrating resilience and growth potential through evolving application dynamics and regulatory landscapes.
Significant advancements in technology within the Aerospace & Defense sector drive the demand for specialized EMC shielding solutions. This segment benefits from increasing investments in defense and aerospace projects, enhancing the need for reliable electromagnetic compatibility measures. The need for effective shielding methods arises from the critical nature of electronics used in aircraft and military equipment, where failure poses serious risks. Adoption of advanced materials and innovative designs enables manufacturers to develop products that meet stringent defense standards.
The Aerospace & Defense segment is projected to grow at a CAGR of 5.3% during the forecast period. This growth stems from rising government spending on defense systems and the increasing development of advanced aerospace technologies. In addition, regulatory compliance associated with electromagnetic interference (EMI) and the protection of sensitive electronic components contribute to the expansion of the market. An enhanced focus on product evolution and next-generation upgrades aligns with the sector's dynamics, ensuring that the solutions offered meet emerging requirements.
Investment in research and development drives innovation in EMC shielding technologies, allowing companies to deliver advanced products that address the complexities of modern aerospace applications. The emphasis on sustainability and the use of lightweight materials further supports the growth trajectory of the market within this end-use industry. While electronic systems in aircraft and defense applications become more complex, the demand for effective EMC shielding solutions continues to rise, positioning the market for robust expansion.
Advancements in medical technology prompt significant growth within the EMC Shielding and Test Equipment market, particularly for medical devices and healthcare applications. Demand for reliable shielding solutions arises from the necessity to protect sensitive electronic components in devices including imaging systems, diagnostic equipment, and patient monitoring devices, where electromagnetic interference could impact performance and patient safety.
Heightened focus on compliance with regulatory standards ensures that manufacturers adopt stringent EMC practices. These regulations dictate that medical devices meet specific electromagnetic compatibility criteria, building confidence among consumers and healthcare providers. The requirement for consistent performance in high-stakes environments drives manufacturers to invest in advanced EMC shielding technologies, improving product reliability.
Increased adoption of wireless technologies in healthcare applications influences the market, with devices interconnected for improved patient monitoring and data management. This trend necessitates effective shielding to mitigate interference that could disrupt communications between devices. The evolution of telemedicine and remote healthcare monitoring solutions further emphasizes the significance of robust electromagnetic shielding equipment.
Technological maturation presents strategic opportunities within the segment. Companies investing in next-generation shielding materials, including conductive coatings and specialized gaskets, prepare to meet the increasing demands of the healthcare industry. These innovations enhance product performance while addressing the specific needs of medical device manufacturers, potentially expanding market share.
The EMC Shielding and Test Equipment market for medical devices and healthcare reflects growth driven by technological advancements, stringent regulatory compliance, and evolving applications. Manufacturers will continue to seek effective solutions to enhance device reliability and ensure patient safety.
Industrial automation and machinery sectors increasingly require effective EMC shielding solutions to ensure the reliability and performance of electronic components. Key drivers behind this demand include the integration of advanced automation technologies, which generate higher levels of electromagnetic interference. Manufacturers adopting smart machinery and connected devices intensify the necessity for comprehensive shielding solutions, safeguarding sensitive electronics from disruptive interference.
Technological maturation within the industrial sector significantly influences the market, with ongoing advancements in automation and robotics enhancing the need for effective EMC solutions. Next-generation upgrades to machinery and equipment require compliance with stringent electromagnetic compatibility standards, driving investments in shielding materials and test equipment. Manufacturers prioritize shielding technologies that improve device performance and facilitate compliance with regulatory standards.
Increased focus on product evolution contributes to the growing adoption of innovative EMC shielding solutions. Manufacturers aim to enhance the durability and effectiveness of their products by incorporating advanced materials and design methodologies. The transition towards more connected and automated systems shifts consumption patterns, necessitating new approaches to electromagnetic interference management within the market.
End-use dynamics in industrial automation and machinery sectors highlight the importance of shielding solutions in maintaining operational efficiency. The demand for reliable and consistent performance of automated systems drives investments in comprehensive EMC testing and shielding strategies. Recognizing the significance of effective shielding solutions enables manufacturers to mitigate risks associated with electromagnetic interference, enhancing product reliability and customer satisfaction.
Regulatory compliance standards continue to evolve, prompting manufacturers to adopt innovative EMC shielding technologies. Certifications related to electromagnetic compatibility play a crucial role in influencing market dynamics, ensuring that products meet required performance criteria. Firms actively seek solutions that align with these standards, reinforcing market growth driven by firms prioritizing investments in EMC shielding and test equipment solutions.
Capital investment outlook remains positive, with manufacturers recognizing the strategic opportunity presented by advancements in EMC shielding technologies. Investment in innovative solutions positions firms to meet rising demands for reliable, high-performance products. Overall, the industrial automation and machinery segment within the EMC Shielding and Test Equipment market is poised for growth, driven by technological advancement, regulatory compliance, and evolving customer needs.
Growing investments in renewable energy sources and advancements in power electronics technology drive significant demand for EMC shielding solutions within the Energy and Power Electronics sector. Enhanced performance and reliability of electronic systems necessitate effective electromagnetic compatibility measures, ensuring proper functionality in diverse environments. The market experiences increased adoption of next-generation upgrades that leverage innovative materials and designs, contributing to improved shielding effectiveness.
Technological maturation has led to the development of advanced shielding materials that offer superior performance at lower costs. This evolution encourages product innovation, with manufacturers focusing on developing tailored solutions that meet specific industry requirements. End-use dynamics demonstrate a strong correlation between the demand for cleaner energy solutions and the need for reliable EMC shielding, particularly in applications involving sensitive electronic components.
Regulatory compliance standards surrounding electromagnetic compatibility in energy systems significantly influence market dynamics. The push for adherence to these standards promotes the adoption of rigorous testing methodologies, ensuring devices meet operational requirements. While consumption patterns shift toward more energy-efficient technologies, demand for specialized EMC shielding solutions is expected to increase, further propelling growth within the market.
Strategic opportunity windows arise from the need for enhanced energy management and the integration of smart technologies. Competitors within the market focus on expanding their capabilities to cater to this evolving landscape, addressing the challenges posed by supply chain resilience and raw material sourcing. The Energy and Power Electronics sector represents a vital area for growth, driven by ongoing investments and technological advancements within the EMC Shielding and Test Equipment market.
Technological advancements within the Semiconductor and Electronic Components sector drive the demand for advanced EMC shielding solutions. Increased complexity in electronic devices necessitates effective shielding against electromagnetic interference, ensuring optimal performance and reliability. The growing trend toward miniaturization of components increases the need for efficient shielding methods, enhancing product longevity and operational efficiency.
Regulatory compliance standards play a significant role in shaping the market landscape. Manufacturers are compelled to adhere to strict electromagnetic compatibility requirements, stimulating investments in innovative shielding technologies. The emphasis on product safety and reliability influences organizations to prioritize quality in their shielding solutions, reinforcing competitive positioning within the market.
Investments in research and development facilitate the introduction of next-generation upgrades. Innovations including advanced conductive materials and novel shielding designs enhance the effectiveness of EMC solutions. This evolution supports growth in downstream applications, ranging from consumer electronics to telecommunications, where effective shielding is critical for device performance.
Adoption of sophisticated testing equipment for evaluating electromagnetic compatibility is essential in ensuring product compliance. Organizations increasingly prioritize rigorous testing protocols to mitigate risks associated with electromagnetic interference. This focus on compliance increases demand for comprehensive EMC solutions, contributing to the overall growth of the EMC Shielding and Test Equipment market.
Growth in the Others (Home Appliances, Lighting, Research & Academia) segment of the EMC Shielding and Test Equipment market occurs due to increasing consumer demand for electronic products that require effective electromagnetic compatibility solutions. This demand arises from heightened global awareness of electromagnetic interference issues impacting product performance and safety. Adoption of advanced shielding solutions enhances product reliability and compliance with regulatory standards, driving market expansion.
Technological maturation significantly influences the segment, with innovations in materials and design enabling the development of efficient electromagnetic shielding solutions. Next-generation upgrades in home appliances and lighting systems increasingly incorporate advanced EMC shielding technologies, improving performance metrics and market competitiveness. The evolution of products in this segment aligns with consumer preferences for high-performance electronics that minimize interference.
End-use dynamics reflect a shift towards incorporating EMC shielding in diverse applications, particularly in smart home technologies and energy-efficient lighting solutions. Regulatory compliance standards drive investments in EMC test equipment, ensuring devices meet safety and performance benchmarks. This compliance influences manufacturers to adopt advanced testing methods, enhancing their market presence and operational efficiency.
Strategic opportunity windows exist for companies engaging in research and development of innovative EMC solutions tailored to the specific needs of the consumer electronics market. Continuous capital investment directed towards enhancing product performance and compliance with emerging standards supports segment growth. The evolving landscape necessitates robust supply chain resilience, focusing on sourcing high-quality raw materials to withstand technological obsolescence and competitive pressures.
Valued at USD 8,146.5 million in 2026, the segment projects to reach USD 11,282.8 million by 2033, at a CAGR of 4.8% during the forecast period. Increased reliance on EMC shielding and test equipment across various industries creates significant demand for this segment. Factors driving market growth include the need for improved electromagnetic compatibility in electronic devices and a surge in technological advancements across sectors including telecommunications, automotive, and consumer electronics.
Regulatory compliance standards surrounding electromagnetic interference continue to impact demand dynamics within the market. The push for enhanced product performance, coupled with growing consumer expectations for reliable electronic products, reinforces the importance of effective EMC shielding solutions. The demand for next-generation upgrades and product evolution contributes to market expansion, driven by companies seeking to integrate advanced technologies into their offerings.
Changes in consumption patterns, driven by increasing digitalization and automation, further influence the market landscape. Organizations invest in EMC shielding and test equipment to meet the challenges posed by modern electronic devices, which require higher performance standards. Emerging applications, particularly in the automotive sector with the rise of electric vehicles, necessitate advanced shielding solutions, propelling growth within this segment.
Based on geography, the Global EMC Shielding and Test Equipment market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Regional demand in the North America EMC Shielding and Test Equipment market stems from a combination of factors, including robust technological infrastructure and stringent regulatory requirements. The presence of key industries including telecommunications, automotive, and consumer electronics fuels the adoption of advanced EMC shielding solutions. By 2025, this region will account for 31.7% of the global market, reflecting its significant role in the overall growth trajectory.
Investment in infrastructure modernization and high-value replacement cycles drives market expansion. Increased focus on compliance with local and international standards influences procurement decisions across various sectors. The emphasis on localized manufacturing strengthens the market, driven by companies seeking to optimize supply chains while maintaining product quality.
In the context of geopolitical fragmentation, North America benefits from stable cross-border trade corridors, facilitating the movement of goods. Local procurement dynamics and energy grid resiliency contribute to the region's attractiveness for new investments. Vendors in the market adapt to evolving buying behaviors, emphasizing strategic entry barriers that promote long-term partnerships.
Emerging market front-runners highlight the need for innovation in the EMC Shielding and Test Equipment market. Domestic leaders, including established companies and new entrants, drive healthy competition, resulting in enhanced product offerings and improved service delivery. The forecasted CAGR of 4.8% through 2033 illustrates ongoing potential for growth and investment in North America.
Europe holds a significant position in the EMC Shielding and Test Equipment market, representing 27.2% of the global market share in 2025. Countries including Germany, France, the UK, Italy, Spain, and Russia contribute to this expansive market, driven by strong demand for advanced shielding solutions across various industries. The region's focus on compliance with stringent regulatory standards, particularly in the telecommunications, automotive, and aerospace sectors, necessitates high-quality shielding solutions to mitigate electromagnetic interference.
Investment in infrastructure modernization and localized manufacturing supports growth in the market. Several European countries prioritize nearshoring initiatives to enhance supply chain efficiency and ensure compliance with local regulations. The market benefits from a strong presence of domestic players and established vendor networks, which enhance competitive dynamics and support market entry for new participants.
Emerging market front-runners within Europe, particularly in consumer electronics and automotive sectors, drive demand for innovative shielding solutions. The market experiences incremental growth driven by high-value replacement cycles and evolving technological advancements. Cultural nuances and regional B2B buying behaviors influence procurement dynamics, prompting companies to develop tailored solutions that align with local preferences and requirements.
Strong energy grid resiliency and the availability of regional resources support the market's growth trajectory. Strategic entry barriers, including foreign direct investment flows and geographic expansion windows, contribute to a competitive landscape characterized by collaboration between market participants. Analyzing these factors reveals a complex relationship of regional dynamics that shapes the future of the EMC Shielding and Test Equipment market in Europe.
The Asia-Pacific region holds a notable share of 31.5% in the global EMC Shielding and Test Equipment market for 2025. Rapid industrialization and significant investments in electronics manufacturing drive the demand for EMC shielding solutions across countries like China, Japan, and India. The expanding telecommunications infrastructure in South Korea enhances the need for effective shielding to ensure compliance with stringent electromagnetic compatibility standards.
Emerging market front-runners including Southeast Asia experience growth in the market, largely due to increasing electronic device production and the subsequent need for reliable shielding solutions. This region benefits from modernization efforts in manufacturing processes, contributing to an environment conducive to localized production. Enhanced energy grid resiliency and improved infrastructure readiness support further market penetration.
Competition in Asia-Pacific intensifies, driven by domestic players who innovate and adapt to local procurement dynamics. Multinational corporations establish collaborations with local vendors to strengthen their foothold in the market, aiming to capitalize on existing supply chain regionalization trends. The shift towards localized manufacturing facilitates a more agile response to market demands, while foreign direct investment flows into the region reflect growing confidence in its potential.
The significant focus on regulatory compliance and adherence to local mandates influences market dynamics, with companies actively seeking to meet these requirements. This focus positions the EMC Shielding and Test Equipment market for growth, supported by emerging technologies and the increasing complexity of electronic systems across various industries.
The EMC Shielding and Test Equipment market in South America benefits from a growing focus on technological innovation within various sectors, particularly electronics and telecommunications. Brazil and Argentina are the primary markets driving demand, supported by increasing investments in local manufacturing capabilities and modernization efforts. The region's market share represents 5.1% of the global landscape in 2025, reflecting a steady growth trajectory fueled by enhancing communication infrastructure and rising awareness of electromagnetic interference challenges.
Adoption rates of advanced EMC shielding solutions within consumer electronics and telecommunications are climbing, with local firms increasingly recognizing the importance of effective shielding in product development. Emerging market front-runners including Brazil demonstrate a commitment to strengthening their manufacturing bases, which positions them favorably for future growth in the EMC Shielding and Test Equipment market.
Infrastructure modernization initiatives across South America contribute significantly to regional market expansion, driven by investments in energy and communication networks that create demand for advanced shielding technologies. Local compliance mandates and geographic regulatory frameworks further influence procurement dynamics, compelling companies to adopt higher standards for electromagnetic compatibility.
The competitive landscape in South America features both domestic and international players, with an emphasis on localized production and innovation. Companies actively engage in cross-border trade corridors, enhancing regional supply chain effectiveness while navigating geopolitical complexities. This strategic focus strengthens vendor relationships and positions South American firms to capitalize on growing regional demand.
The Middle East and Africa region, accounting for 4.5% of the global EMC Shielding and Test Equipment market in 2025, faces unique dynamics influencing its growth trajectory. Infrastructure modernization efforts across countries including Saudi Arabia and the UAE create demand for advanced EMC solutions, particularly in telecommunications and industrial applications. Rapid urbanization and technological adoption in these nations support rising investments in electronic devices, thereby driving the need for effective shielding solutions.
South Africa presents additional growth opportunities, with a focus on enhancing its manufacturing capabilities. The presence of local compliance mandates related to electromagnetic compatibility creates a conducive environment for market expansion. Geopolitical factors and localized procurement dynamics shape B2B buying behaviors within the region, compelling businesses to source from domestic suppliers to meet regulatory requirements.
Regional market players invest in localized manufacturing to enhance supply chain resilience and reduce operational costs. Increased foreign direct investment (FDI) flows into the region signify confidence in its market potential. The EMC Shielding and Test Equipment market is poised for steady growth driven by these factors converging, creating a landscape ripe for innovation and expansion.
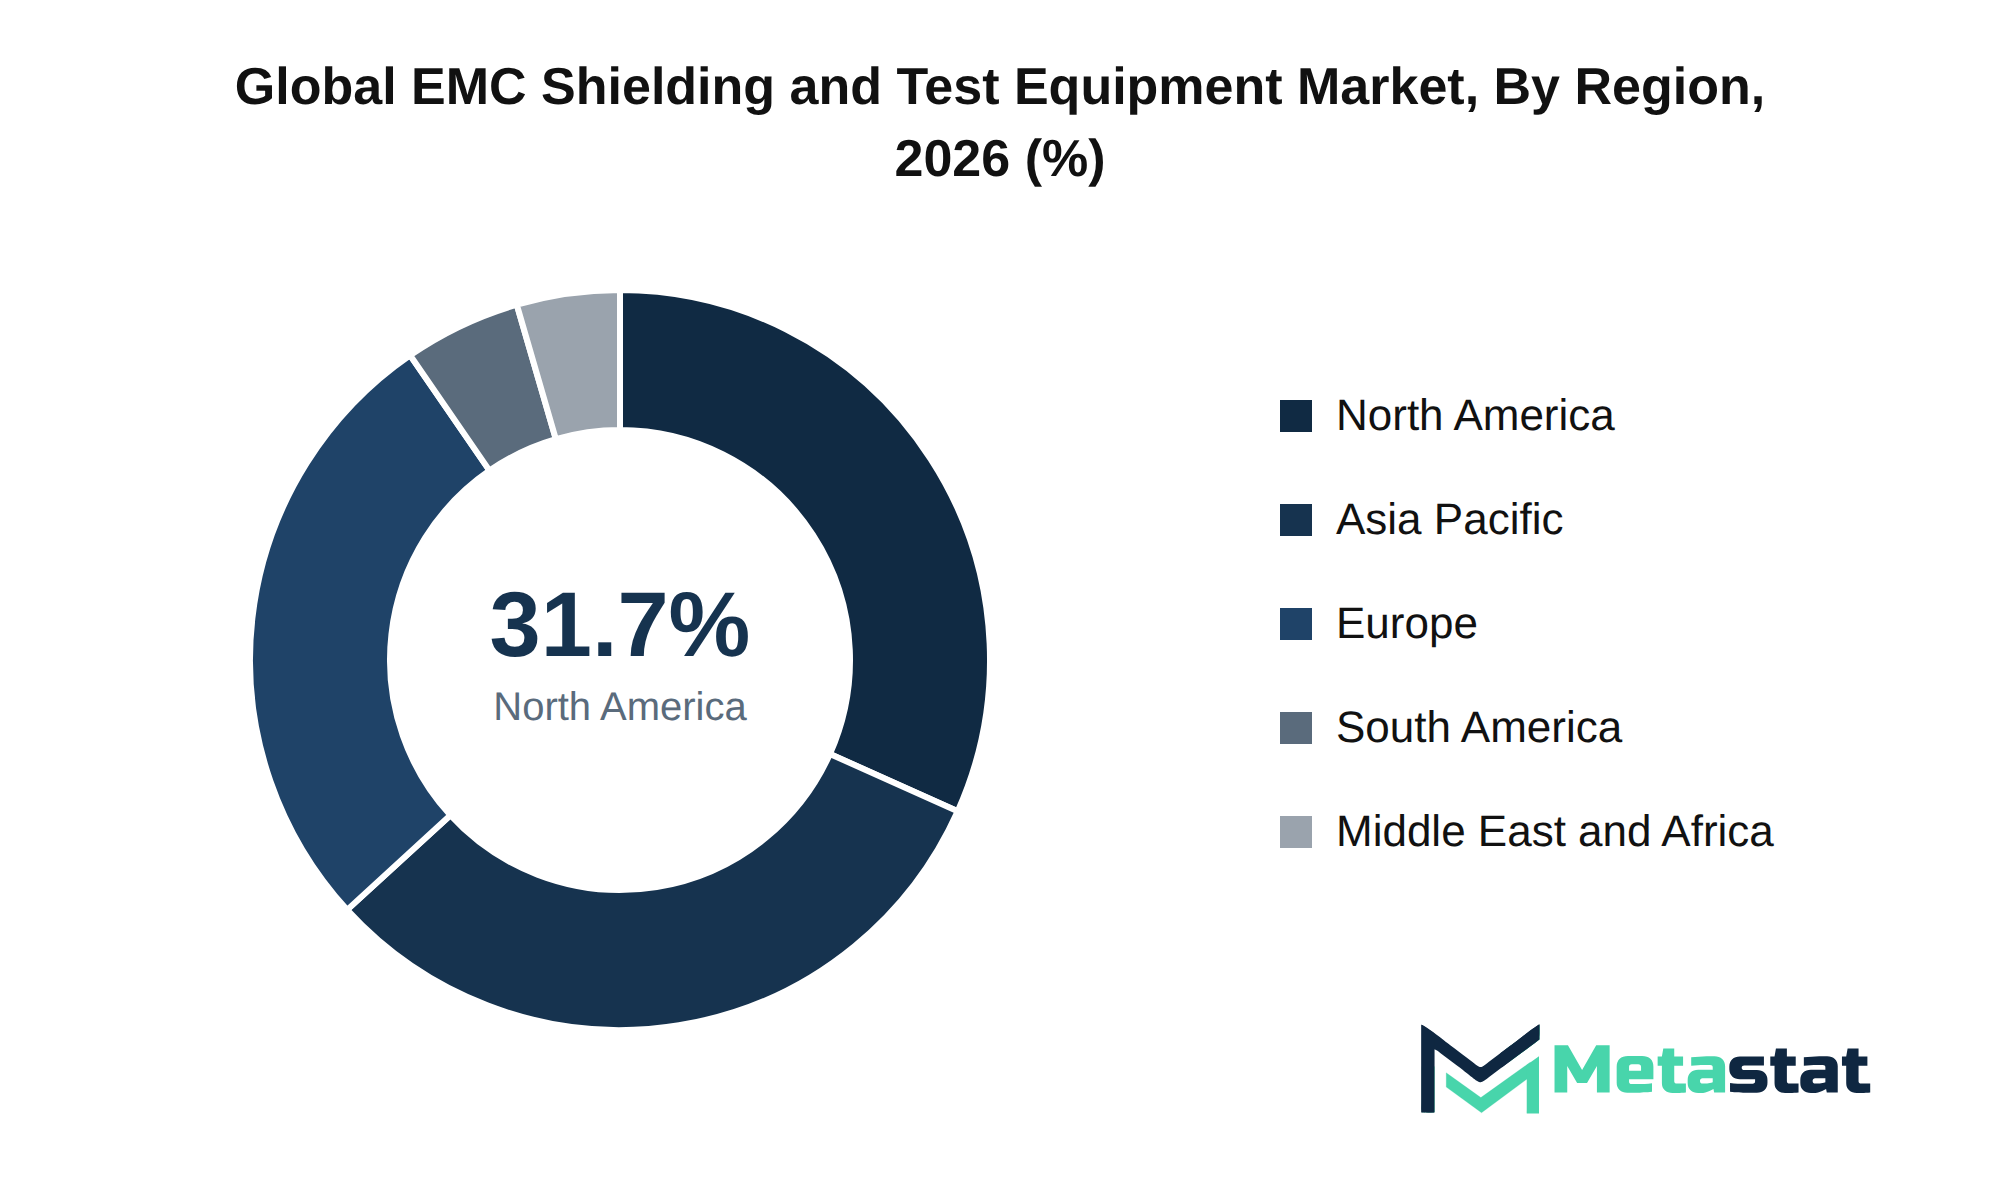
The EMC Shielding and Test Equipment market features a diverse range of players focusing on product differentiation and strategic alliances. Companies including Rohde & Schwarz GmbH & Co. KG, AMETEK, Inc., and Keysight Technologies, Inc. have established significant R&D pipelines that enhance their technological capabilities. This investment in proprietary technologies creates barriers to entry for new entrants, reinforcing their positions within the market.
Strategic partnerships and joint ventures characterize the competitive behavior among companies. Collaborations between leading players like 3M Company and TE Connectivity enable access to complementary resources, enhancing value chain integration. These alliances facilitate innovation and improve supply chain dominance, which reinforces their market presence.
The market's future competitive outlook hinges on customer retention strategies and brand equity dynamics. Companies including PPG Industries, Inc. and Microwave Vision Group (MVG) prioritize customer loyalty through tailored solutions, reducing switching costs for their clients. This focus on customer relationships helps maintain a stable revenue stream amid evolving market conditions.
Overall, the competitive landscape reflects a blend of strategic growth vectors, including defensive imperatives and technological defensibility, that shape the trajectory of the EMC Shielding and Test Equipment market.
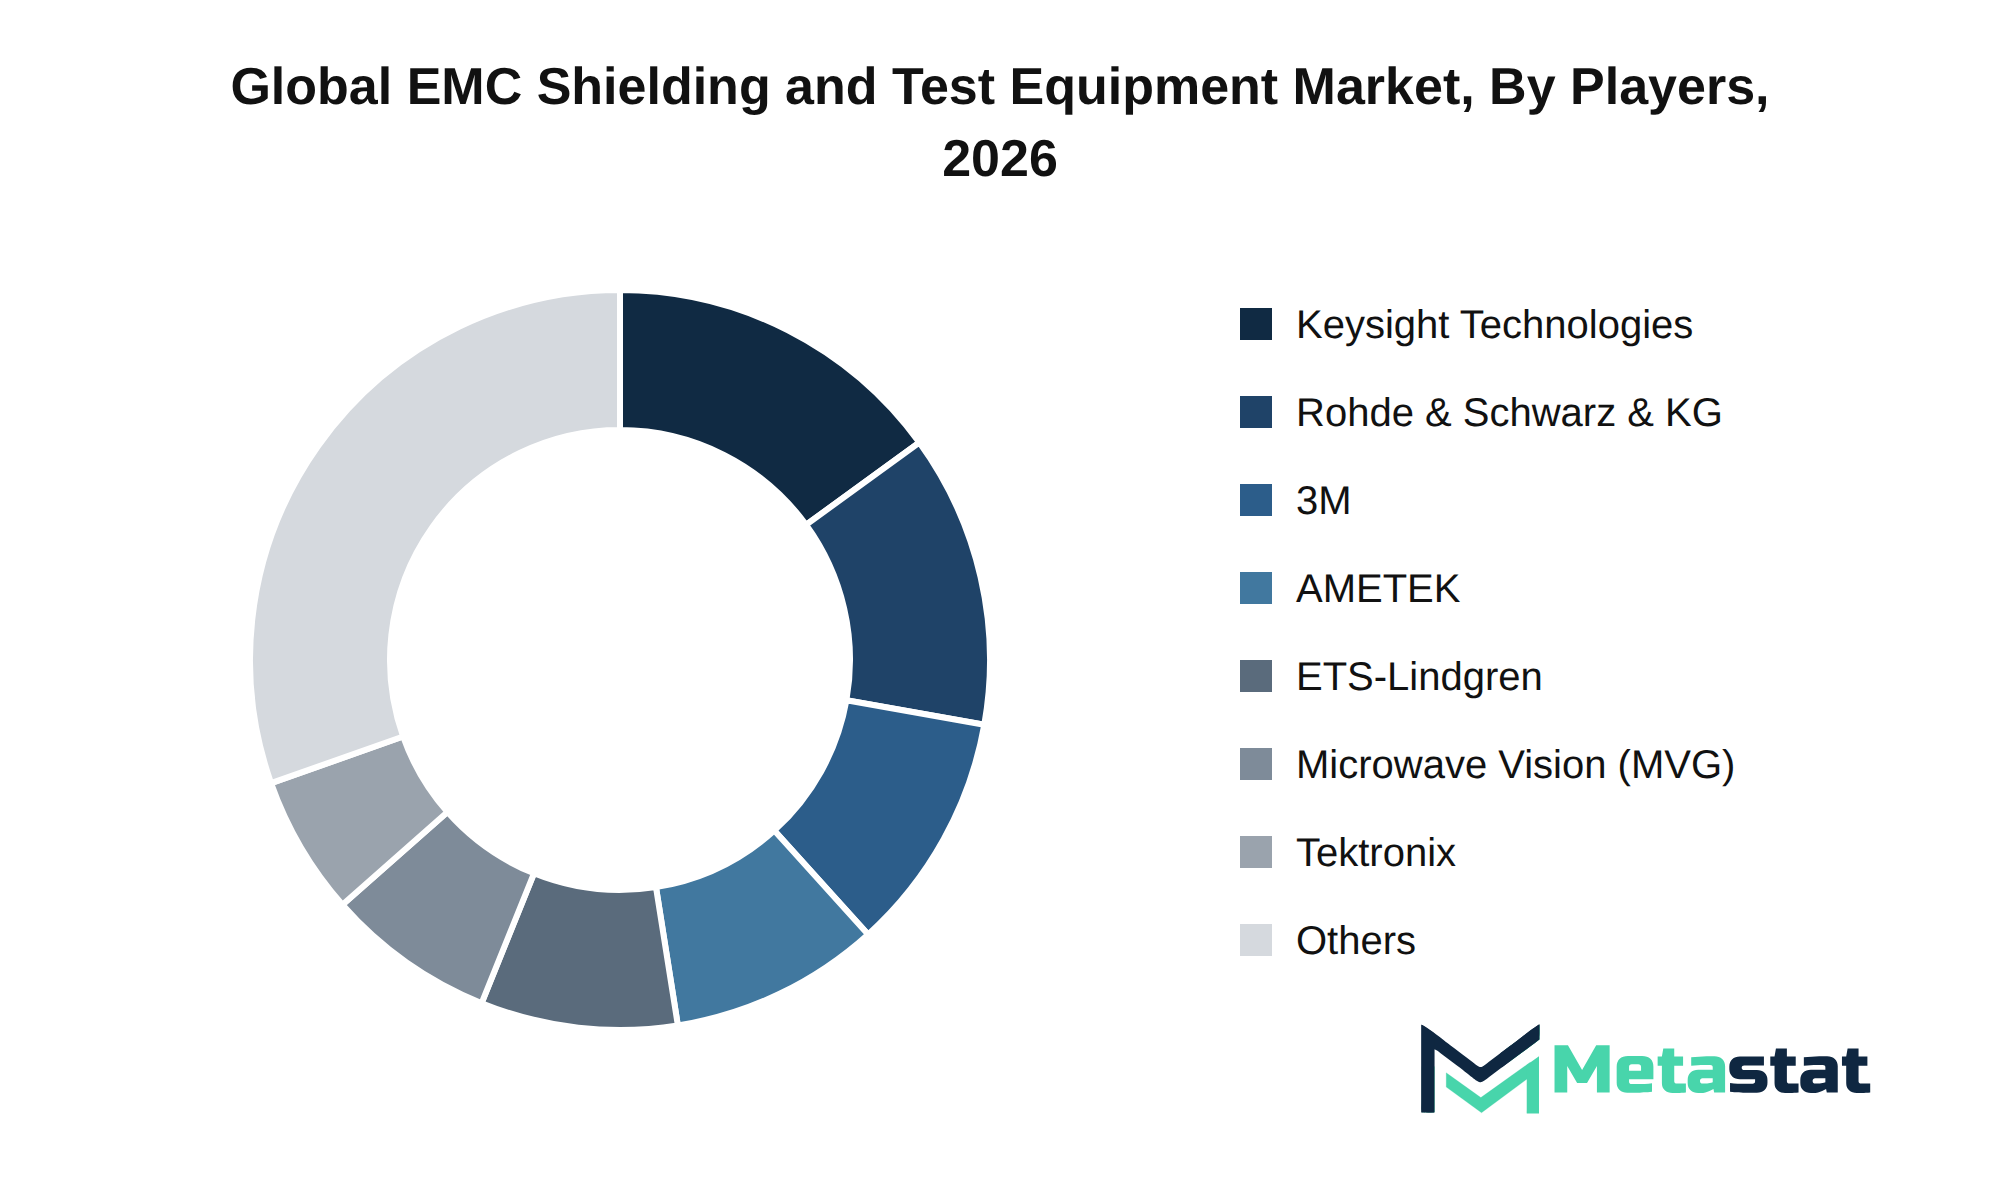
Market size is forecast to rise from USD 7,751.6 million in 2025 to over USD 11,282.8 million by 2033. The base case reflects a growth trajectory from USD 7,751.6 million in 2025 to USD 11,282.8 million by 2033 at a 4.8% CAGR. Bull cases indicate accelerated growth driven by robust advancements in next-generation technologies, increasing demand for compliance with evolving regulatory frameworks, and strategic capital allocation toward infrastructure investments. Conversely, bear cases highlight potential disruptions due to geopolitical realignments, supply chain shifts, and economic fluctuations, which could temper growth prospects.
The EMC Shielding and Test Equipment market experiences significant transformations influenced by macroeconomic factors. Structural consumption shifts and core industry maturation create evolving demand dynamics. Companies focusing on research and development (R&D) commercialization timelines adapt to faster product life cycles, enhancing competitive positioning. Regulatory evolution timelines and imminent compliance milestones drive manufacturers to innovate continuously, ensuring product relevance in diverse applications.
Emerging opportunities in the market arise from unmet enterprise needs and high-growth pockets across various sectors. The integration of advanced technologies serves because a critical driver for product development, meeting the demands of industries including telecommunications, automotive, and consumer electronics. Strategic imperatives emphasize the importance of aligning product offerings with executive-level directives, ensuring businesses remain defensible amid changing market conditions.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the EMC Shielding and Test Equipment market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 4.8% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Product Type, Application, End-Use Industry, and Region |
By Region | North America (By Product Type, Application, End-Use Industry, and Country)
|
Europe (By Product Type, Application, End-Use Industry, and Country)
| |
Asia Pacific (By Product Type, Application, End-Use Industry, and Country)
| |
South America (By Product Type, Application, End-Use Industry, and Country)
| |
Middle East and Africa (By Product Type, Application, End-Use Industry, and Country)
|
Find answers to common questions about this report
The EMC Shielding and Test Equipment market size was valued at USD 7,751.6 million in 2025, according to the Metastat Insights study.
The EMC Shielding and Test Equipment market is projected to grow at a CAGR of 4.8% during the forecast period from 2026 to 2033.
The North America EMC Shielding and Test Equipment market size is estimated to reach USD 3,378.1 million by 2033.
The segment "PCB & Component-Level Shielding" leads the EMC Shielding and Test Equipment market with a projected value of USD 1,614.6 million by 2033, based on its growth rate of 5.6%.
Key drivers for the EMC Shielding and Test Equipment market include heightened regulatory compliance requirements, which necessitate investments in advanced shielding technologies across industries including consumer electronics and automotive. Infrastructure modernization initiatives and the integration of innovative materials improve product performance, supporting market expansion.
North America holds the dominant share of the EMC Shielding and Test Equipment market, with a projected value of USD 3,378.1 million in 2033, representing 31.7 percent of the total market.
The EMC Shielding and Test Equipment market faces challenges from stringent regulatory compliance requirements, which complicate operations and increase costs. Geopolitical instability and supply chain disruptions further hinder growth by affecting access to essential components and materials, leading to higher operational expenses and impacting profit margins.
Increased regulatory compliance requirements and the need for advanced shielding technologies favor product adoption in the EMC Shielding and Test Equipment market. Industries including consumer electronics, telecommunications, and automotive are responding to these mandates, driving investments in innovative materials and design techniques to enhance operational efficiency and maintain product quality.
The EMC Shielding and Test Equipment market is estimated to reach a valuation of USD 11,282.8 million by 2033.
Key players in the EMC Shielding and Test Equipment market include Rohde & Schwarz GmbH & Co. KG, AMETEK, Inc., ETS-Lindgren, Keysight Technologies, Inc., 3M Company, and Anritsu Corporation.
Choose Your License
Global EMC Shielding and Test Equipment Market
The analysts below cover Electronics and Semiconductor research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.
PRINCIPAL CONSULTANT - QUALITY SYSTEMS & COMPLIANCE
Electronics and Semiconductor · Machinery & Equipment · Professional Services
Omkar Phadtare is an Industry Consultant at MetaStat Insight, specializing in quality systems, regulatory compliance, and standards benchmarking to drive data-driven market intelligence and strategic industry research.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
When planning edge sensor rollouts across refinery environments, generic IoT reports typically miss the harsh-environment certification bottlenecks. MetaStat Insight gave an objective evaluation of ATEX and Class 1 Division 2 hardware availability, along with realistic five-year maintenance cycle cost projections. The comparison of wireless mesh versus private cellular backhaul helped our team pressure-test network reliability models for remote processing facilities.
In the biological seed treatment space, registration timelines vary drastically between the European Union, Brazil, and North America. The MetaStat Insight research handled these cross-border regulatory barriers with genuine nuance, mapping commercialization pathways alongside historical field adoption rates. The segmentation between microbial strains and biochemical active ingredients was particularly well structured.
Our team was tracking whether regional recycling infrastructure could realistically absorb the growing volume of lithium iron phosphate batteries over the next decade. The report did a solid job separating announced hydrometallurgical plant capacity from active, permitted operational throughput. That distinction made the feedstock availability projections and regional recovery rate models far more credible than standard commercial overviews.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950
Starting from
$2950