
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Environmental, Social & Governance (ESG) Market Size, Share, By Solution Type (ESG Strategy & Transformation Advisory, Sustainability Reporting & Disclosure Advisory, ESG Assurance, Verification & Certification, Supply Chain ESG & Human Rights Due Diligence, Climate, Carbon & Decarbonization Advisory, ESG Risk & Regulatory Compliance Services, ESG Data, Measurement & Performance Management, Others (Sustainable Finance Advisory, ESG Training & Capacity Building)), By Service Type (Environmental Services, Social Services, Governance Services, Integrated ESG Services), By End-Use Industry (Banking, Financial Services & Insurance, Energy & Utilities, Manufacturing & Industrial, Consumer Goods & Retail, Technology, Media & Telecommunications, Healthcare & Life Sciences, Real Estate & Construction, Transportation & Logistics, Agriculture, Food & Beverage, Others (Public Sector, Education, Hospitality)), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5369
September, 2026
252 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $14.7 Billion in 2025, projected to reach $79.4 Billion by 2033 at a 23.5% CAGR.
Dominant Segment: The ESG Strategy & Transformation Advisory segment leads the market, projected to grow from USD 3.7 billion in 2026 to USD 15 billion by 2033, driven by increasing regulatory pressures and the need for effective ESG strategies.
Geographic Lead: North America holds the largest market share at 39%, with expectations to generate USD 29.3 billion by 2033, supported by robust regulatory frameworks and strong corporate sustainability initiatives.
What's Inside: The report provides a comprehensive analysis of the ESG market, including competitive coverage, detailed segmentation by solution and service types, and forecasts through 2033.
Increased Focus on Sustainability Initia: Heightened emphasis on sustainability initiatives across various sectors is driving significant growth, as organizations align operations with sustainable practices to enhance brand reputation and meet consumer expectations.
Investment in Digital Transformation Fue: Investment in digital transformation is significantly influencing the ESG market, as businesses adopt advanced technologies to enhance operational efficiency and integrate ESG principles into their digital strategies.
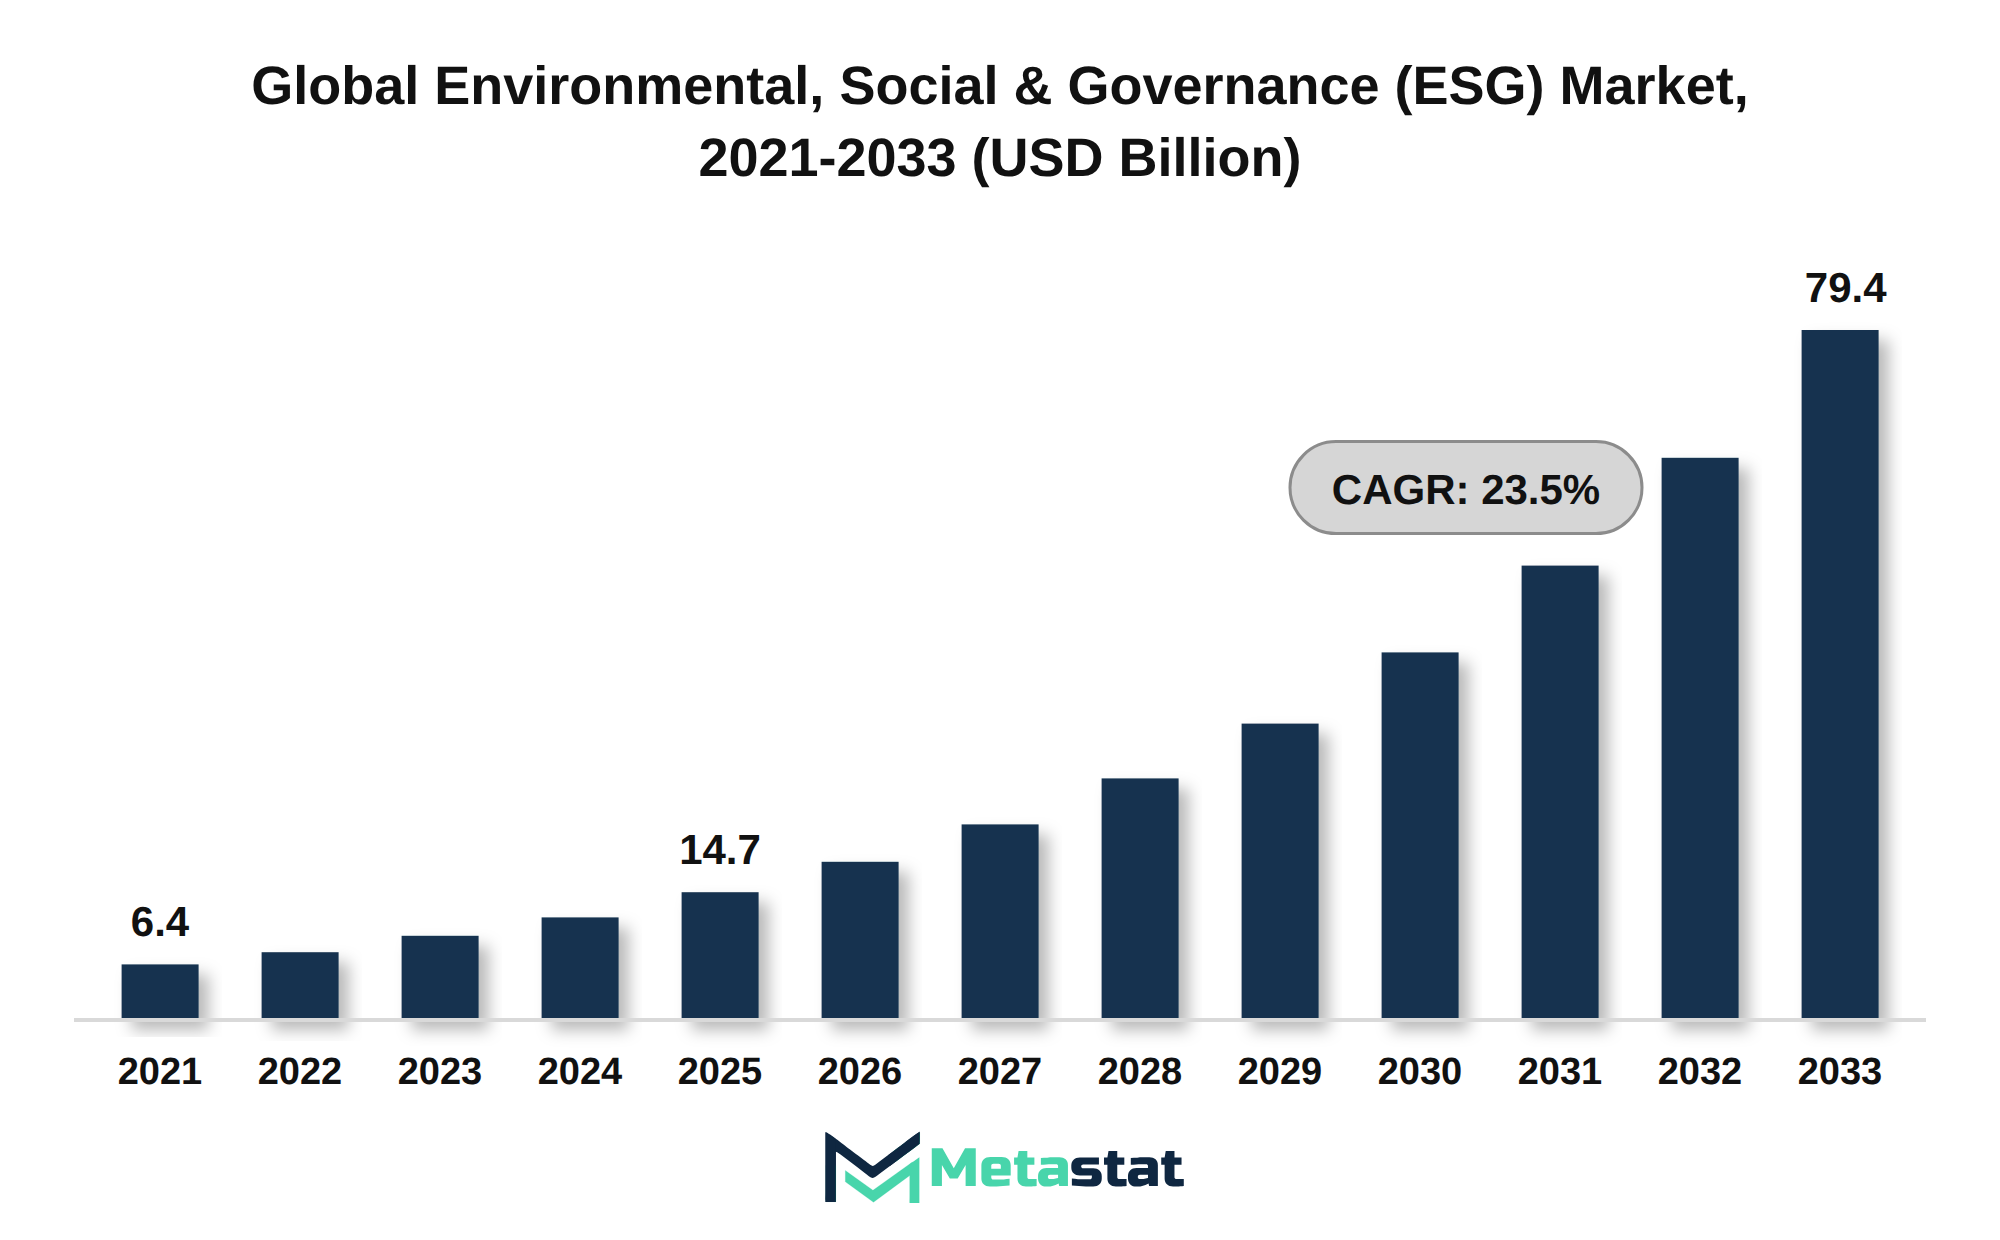
The global Environmental, Social & Governance (ESG) market was valued at USD 14.7 billion in 2025 and is projected to reach USD 79.4 billion by 2033, growing at a CAGR of 23.5% over the forecast period.
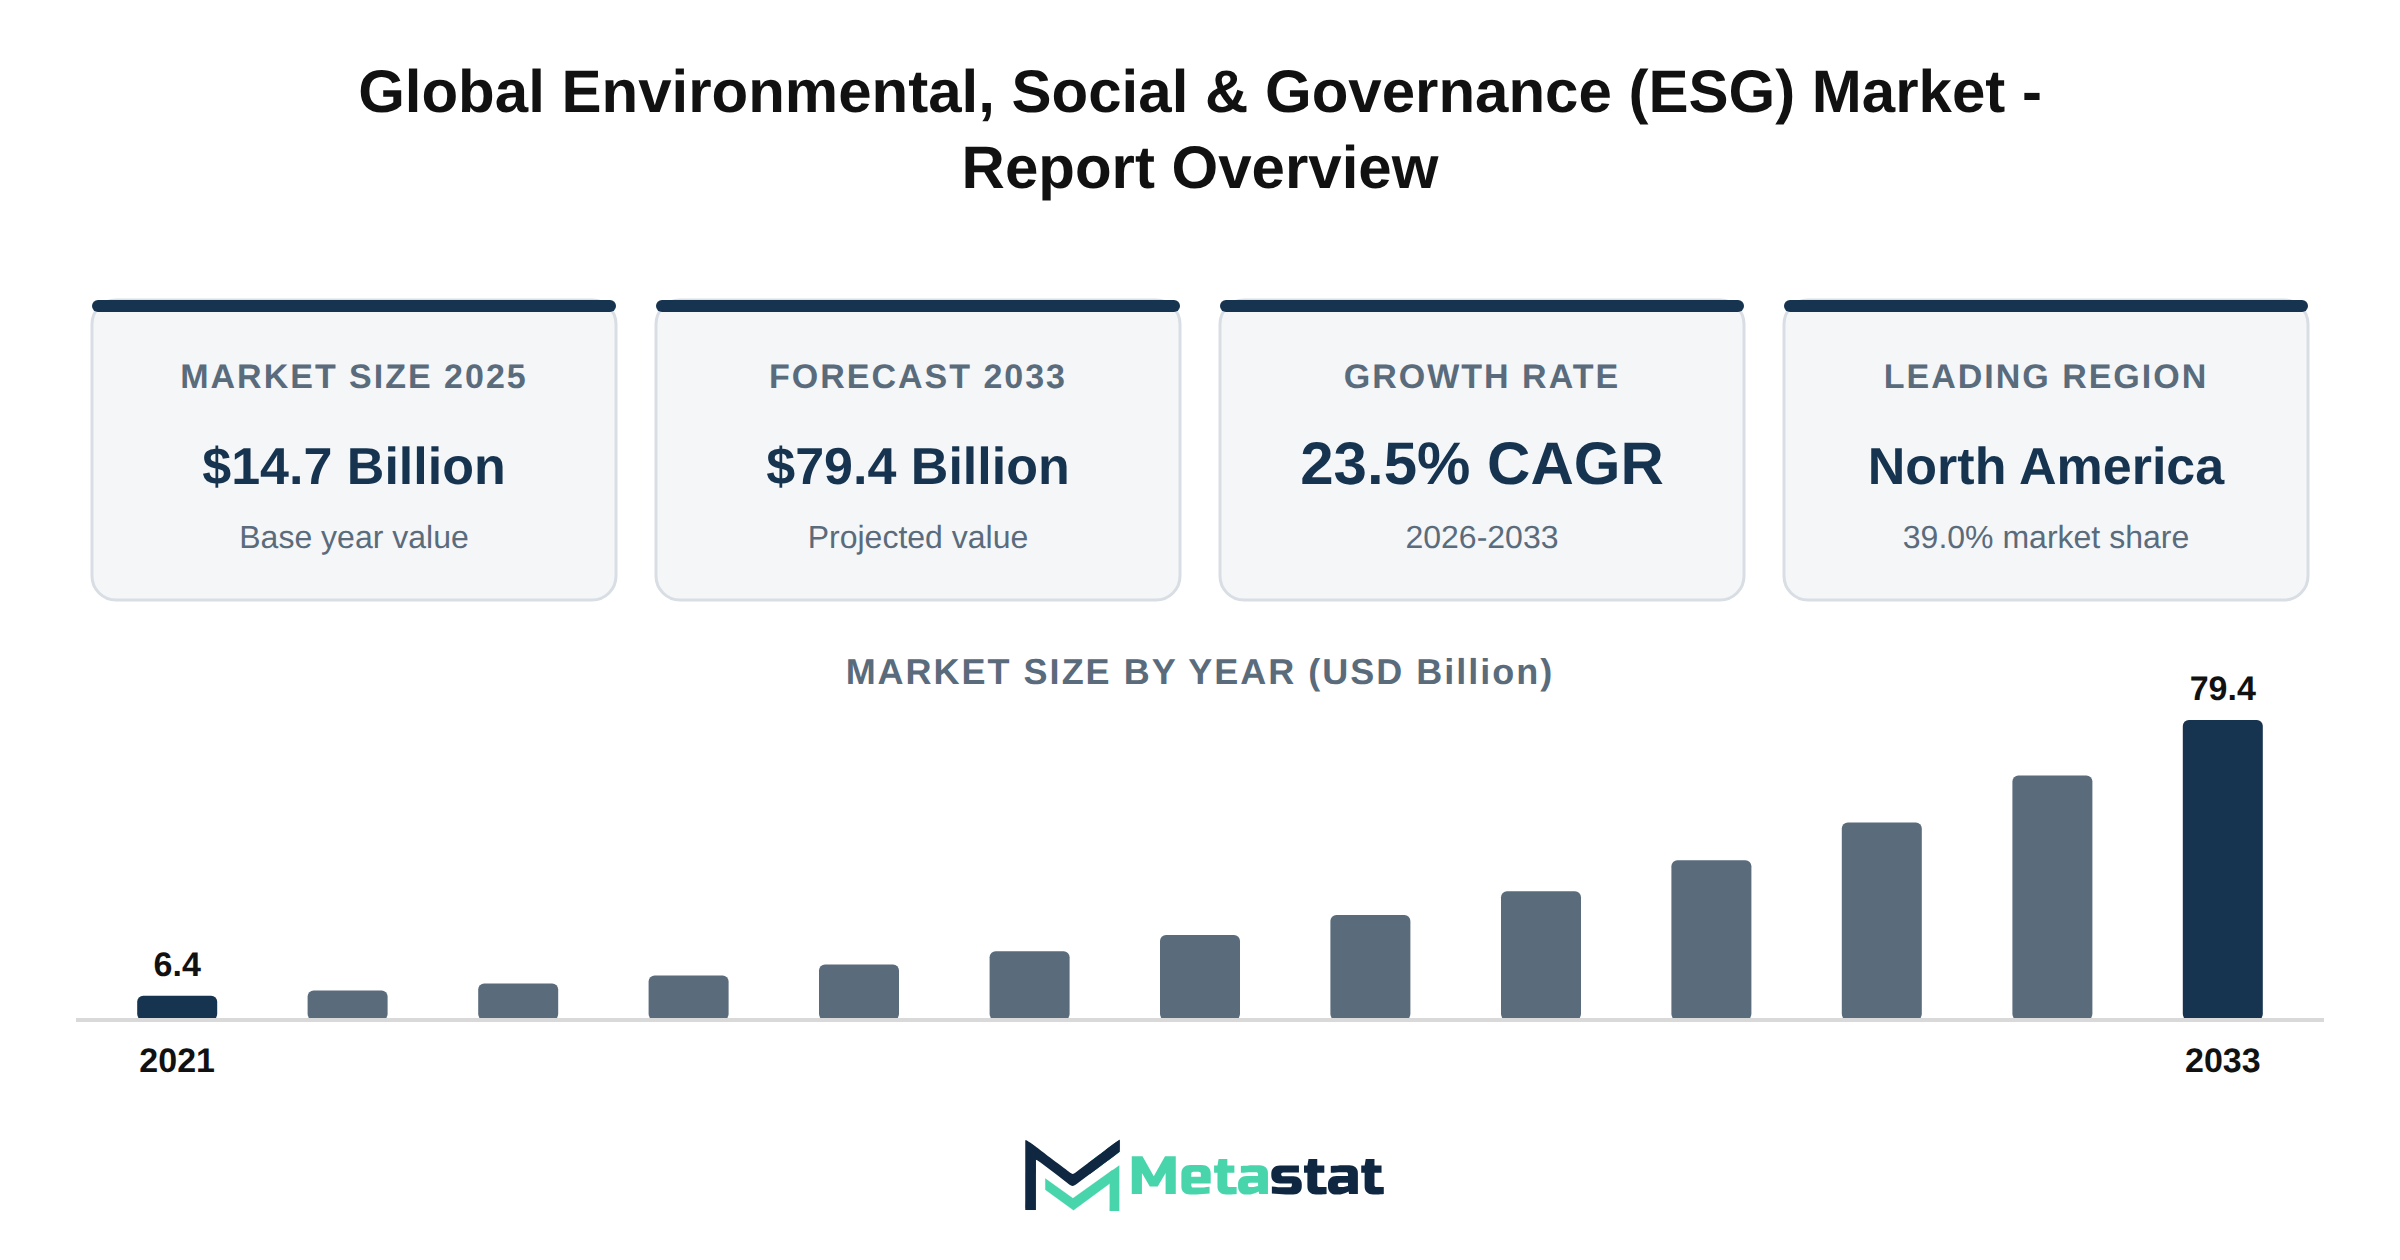
The Environmental, Social & Governance (ESG) market is experiencing significant growth, with a base value of USD 14.7 billion in 2025. By 2033, the market is projected to reach USD 79.4 billion, reflecting a compound annual growth rate (CAGR) of 23.5%. Historical data indicates steady growth from USD 6.4 billion in 2021, increasing to USD 11.8 billion in 2024. This upward trajectory highlights the rising prominence of ESG considerations across various sectors, driven by increasing regulatory demands and heightened investor awareness.
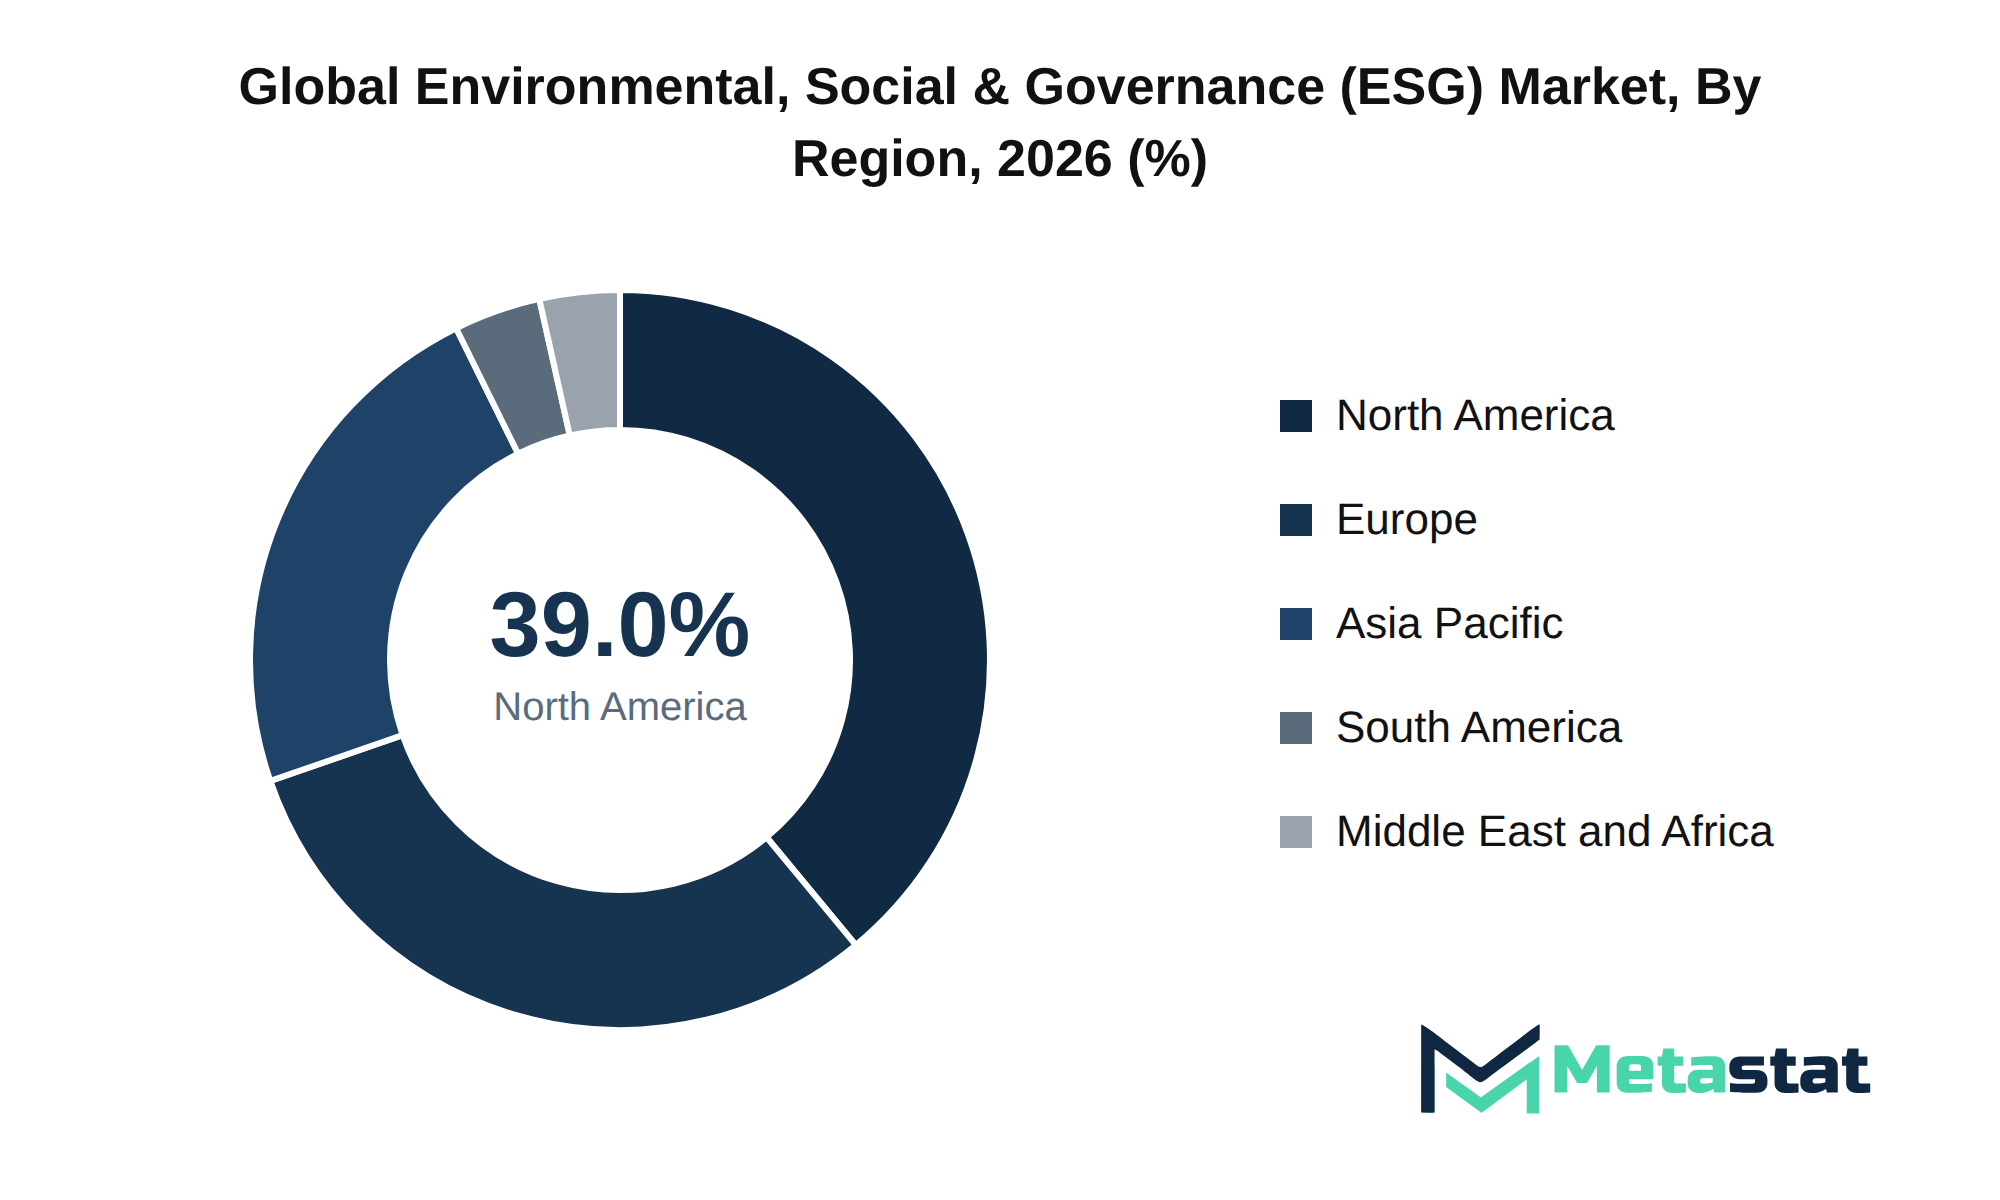
Regional analysis shows that North America holds the largest market share at 39%, followed by Europe at 30.7% and the Asia Pacific region at 23%. The Middle East and Africa account for 3.5%, while South America contributes 3.8%. By 2033, North America is expected to generate USD 29.3 billion in revenue, maintaining its leadership position with a CAGR of 23.5%, supported by robust regulatory frameworks and strong corporate sustainability initiatives.
In terms of solution types, the ESG Strategy & Transformation Advisory segment is expected to grow from USD 3.7 billion in 2026 to USD 15 billion by 2033, achieving a CAGR of 22.2%. The Sustainability Reporting & Disclosure Advisory segment is projected to reach USD 11.7 billion by 2033, with a CAGR of 22.5%. ESG Assurance, Verification & Certification services will see significant demand, further driving market growth because organizations seek to enhance transparency and accountability.
The Environmental Services segment is anticipated to grow from USD 6.3 billion in 2026 to USD 29.3 billion by 2033, reflecting a CAGR of 24.5%. Social Services are projected to reach USD 15.7 billion by 2033, while Governance Services will achieve a total value of USD 14 billion in the same period. Integrated ESG Services, with a CAGR of 23.2%, will contribute to the overall growth of the market, reflecting the increasing integration of ESG factors into business strategies.
The demand for Environmental, Social & Governance (ESG) services reflects a significant transformation in corporate governance practices and stakeholder expectations. Organizations increasingly recognize the importance of sustainability and ethical practices in driving long-term value. This shift is propelled by heightened regulatory scrutiny, investor preferences for sustainable investments, and consumer awareness regarding corporate responsibility.
Strategic advisory services within the market, including ESG strategy and transformation advisory, are projected to experience significant growth. From a base value of USD 3.7 billion in 2026, this segment is anticipated to reach USD 15 billion by 2033, translating to a compound annual growth rate (CAGR) of 22.2%. Sustainability reporting and disclosure advisory services are similarly set for expansion, reaching USD 11.7 billion by 2033, driven by the increasing demand for transparency and accountability in corporate operations.
In the environmental services domain, growth is driven by a projected increase from USD 6.3 billion in 2026 to USD 29.3 billion by 2033, marking a CAGR of 24.5%. The emphasis on environmental compliance and sustainability initiatives within various industries fuels this expansion. Similarly, social services are expected to grow to USD 15.7 billion by 2033, reflecting the growing importance of social responsibility in business practices.
The energy and utilities sector demonstrates a strong commitment to ESG principles, with an expected market value of USD 12.9 billion by 2033. This growth is attributed to organizations prioritizing sustainability in their operations and supply chains. The banking, financial services, and insurance sector shows significant momentum, projected to grow from USD 3.5 billion in 2026 to USD 14.6 billion by 2033, driven by increased regulatory requirements and the demand for sustainable financing options.
Overall, the Environmental, Social & Governance (ESG) market exhibits a trajectory of growth, influenced by evolving standards and expectations from various stakeholders. The expansion of service offerings and the integration of ESG principles across industries reflect a collective shift toward sustainable and responsible business practices, reinforcing the market's importance in shaping future corporate strategies.
Investment in digital transformation significantly influences the Environmental, Social & Governance (ESG) market. This transition involves adopting advanced technologies, including automation and artificial intelligence, which enhance operational efficiency and data management capabilities. Businesses increasingly recognize the importance of integrating ESG principles into their digital strategies, driving demand for ESG-related services.
The shift toward digital solutions aligns with evolving consumer expectations and regulatory pressures for greater transparency and accountability. Industries including banking, financial services, and insurance actively pursue technologies that support ESG initiatives, enabling improved reporting and compliance. This focus on technological integration directly impacts growth, with firms investing in enhanced analytics and reporting platforms for improved performance measurement and risk evaluation.
Organizations that streamline their legacy systems and digitize processes experience cost efficiencies that improve their competitive positioning. Increased emphasis on data-driven decision-making enhances the overall resilience of businesses while addressing stakeholder concerns related to sustainability and governance practices. These trends collectively promote growth within the market, with a projected compound annual growth rate (CAGR) of 23.5% through 2033.
The Environmental, Social & Governance (ESG) market experiences significant growth due to heightened emphasis on sustainability initiatives across various sectors. Organizations increasingly recognize the importance of aligning operations with sustainable practices to enhance brand reputation, meet consumer expectations, and mitigate risks associated with environmental impacts. This alignment drives investment in ESG strategies that prioritize environmental stewardship, ethical governance, and social responsibility.
The push towards sustainability is fueled by macro-economic factors including growing public awareness of climate change, shifting consumer preferences towards ethical products, and corporate pressures to demonstrate accountability in sustainability efforts. Industries including banking, financial services, and insurance lead by integrating ESG mandates into their business models, significantly influencing demand within the market. For example, commitments to reducing carbon footprints and enhancing resource stewardship translate into investments in innovative technologies that support these objectives.
The rise in regulatory compliance requirements enhances the urgency for firms to adopt comprehensive ESG strategies. Organizations that proactively embrace sustainability initiatives align with regulatory expectations and position themselves competitively in an evolving marketplace. This proactive approach drives long-term growth and resilience, resulting in substantial investment in the Environmental, Social & Governance (ESG) market over the forecast period.
Ongoing regulatory constraints significantly affect the Environmental, Social & Governance (ESG) market, creating hurdles for compliance and increasing operational complexity. Companies face challenges in adapting to evolving legal mandates, which often require substantial investments in compliance processes and systems. Rising costs associated with meeting these obligations deter market participation, particularly for smaller firms lacking the necessary resources to navigate stringent regulations.
Macroeconomic headwinds, including inflationary pressures, contribute to a challenging investment environment. Elevated costs for raw materials and labor lead to tighter margins for ESG services, hindering profitability and limiting operational expansion. These financial strains reduce the capacity of firms to adopt innovative practices that enhance service offerings and client engagement.
Supply chain disruptions and geopolitical instability further complicate the market. Uncertainty resulting from global tensions impacts the availability of essential resources and services, which affects project timelines and overall market stability. Companies in the ESG market struggle to maintain consistency in service delivery amid these fluctuations, leading to diminished client confidence.
Infrastructure gaps and connectivity deficits in various regions exacerbate the challenges faced by firms. Inadequate technological infrastructure limits the potential for effective implementation of ESG initiatives, resulting in slower market adoption rates. The lack of skilled labor in the ESG sector hinders the ability to execute projects efficiently, causing delays and increased operational costs.
Data security vulnerabilities and privacy concerns present additional obstacles for market growth. With the increasing reliance on digital solutions, firms face heightened risks related to information breaches and intellectual property theft. These threats necessitate additional investments in cybersecurity measures, diverting resources from core ESG initiatives and impacting overall market development.
Market fragmentation and cultural barriers further slow the adoption of ESG practices across different regions. Variances in regional regulations and perceptions of sustainability hinder the establishment of a unified market approach, resulting in inconsistent service delivery and client engagement. Consequently, these factors contribute to the overall maturation of the industry cycle, limiting growth potential in the Environmental, Social & Governance (ESG) market.
The Environmental, Social & Governance (ESG) market faces significant challenges from geopolitical fragmentation, which disrupts supply chain stability. Trade deficits and tariff friction contribute to increased costs and logistical complexities. These elements create hurdles for businesses striving to implement effective ESG strategies, leading to delays and inefficiencies in operational execution.
Technological disruptions introduce additional complexities, driven by companies navigating the integration of diverse systems and technologies. Companies encounter interoperability friction that complicates data sharing and collaboration, ultimately affecting their ability to meet evolving ESG demands. Supply chain instability exacerbates the volatility of feedstock and component availability, influencing production schedules and operational costs.
Compliance with tightening global regulatory standards imposes further strain on businesses. The overhead associated with ensuring adherence to these standards diverts resources from core activities, impacting profitability. Rising input costs and pricing compression create margin pressures, forcing companies to rethink their pricing strategies within the Environmental, Social & Governance (ESG) market.
Workforce skill gaps and challenges related to talent retention become more pronounced under these pressures. Automation displacements further complicate workforce dynamics, reducing the availability of skilled workers necessary for effective ESG implementation. This scenario necessitates investment in training and development, increasing operational expenditures for companies striving to maintain competitive advantages.
The market continues to grapple with the implications of environmental lifecycle footprints and decarbonization mandates. Organizations face the dual challenge of meeting sustainability demands while addressing infrastructure gaps and retrofitting barriers. Implementation bottlenecks hinder progress, stalling initiatives aimed at reducing environmental impact and enhancing social responsibility.
Intellectual property protection deficits and cybersecurity risks introduce additional vulnerabilities. Companies face growing data vulnerabilities that threaten the integrity of sensitive information, including ESG-related data. While these challenges mount, the Environmental, Social & Governance (ESG) market evolves to adapt to the complexities of a dynamic and fragmented geopolitical environment.
The Environmental, Social & Governance (ESG) market experiences significant opportunities driven by emerging regional demands that reshape service offerings and operational strategies. Countries increasingly prioritize sustainability, prompting industries to adopt ESG frameworks that align with national goals. This shift occurs across diverse regions, particularly in North America, where the market is projected to reach USD 29.3 billion by 2033, supported by heightened awareness and regulatory emphasis on sustainability.
Infrastructure modernization supports the adoption of advanced ESG solutions, enhancing companies' ability to integrate sustainability into their operations. Investments in renewable energy and sustainable practices accelerate this modernization, enabling organizations to optimize their processes and meet evolving consumer expectations. Such advancements contribute to a favorable environment for the market, driving growth and innovation.
Technological disruptions play a crucial role, with digital transformation enhancing data collection, reporting, and compliance capabilities. Companies employing innovative technologies including artificial intelligence and blockchain gain competitive advantages, streamlining ESG-related processes and improving transparency. This tech-driven approach attracts investments, further supporting the Environmental, Social & Governance (ESG) market.
Regional expansion strategies enable companies to tap into new markets, diversifying their portfolios and enhancing revenue streams. Firms focusing on niche applications, including supply chain ESG and human rights due diligence, address specific client needs, capturing untapped segments and driving growth. These strategic moves position organizations favorably within the market, aligning with changing consumer preferences and regulatory trends.
Strategic consolidation and cross-industry mergers strengthen market positioning, allowing firms to leverage complementary capabilities and enhance service offerings. Collaborations between technology providers and ESG service firms create synergies that improve operational efficiency, leading to increased market share and customer satisfaction. This collaborative approach enhances resilience in the market.
Shifts in buying behaviors and digital procurement trends further impact the market, with buyers seeking more sustainable and transparent solutions. Companies adapting their commercial models to reflect these changes position themselves strategically, meeting the demands of conscious consumers. This evolution highlights the importance of agility and responsiveness in the market.
The Global Environmental, Social & Governance (ESG) market is segmented based on Solution Type, Service Type, and End-Use Industry.
Valued at USD 3.7 billion in 2026, the ESG Strategy & Transformation Advisory segment is projected to reach USD 15 billion by 2033, at a CAGR of 22.2% during the forecast period. Key demand drivers include increasing regulatory pressures, necessitating organizations to enhance their ESG strategies. The push for sustainability across various industries, particularly in banking, financial services, and manufacturing, increases the importance of effective ESG strategies. Adoption of these advisory services expands due to businesses recognizing the financial and operational benefits of integrating ESG considerations into their core strategies.
Technological maturation and next-gen upgrades drive advancements in ESG Strategy & Transformation Advisory. Organizations increasingly employ data analytics and AI-driven insights to strengthen their ESG frameworks, enhancing decision-making processes. These technological advancements enable businesses to streamline reporting, identify risks, and assess compliance more efficiently. Ongoing evolution within the ESG landscape, driven by stakeholder expectations and market dynamics, increases the demand for sophisticated advisory services.
Downstream applications extend across various end-use industries, where the emphasis on ESG practices informs investment and operational decisions. Regulatory compliance standards and certifications create a competitive edge for firms that effectively implement ESG strategies. This trend highlights the growing significance of ESG considerations in shaping business practices. Cost structures and pricing volatility specific to this segment reflect the quality and depth of advisory services provided, influencing overall market dynamics.
Strategic opportunity windows arise for market participants seeking to capitalize on the increasing demand for ESG advisory services. Firms that demonstrate adaptability and innovative approaches position themselves favorably within the market. The outlook for capital investment remains strong, with organizations dedicating resources to enhance their ESG capabilities. The projected expansion of the ESG Strategy & Transformation Advisory segment aligns with the broader trends shaping the Environmental, Social & Governance (ESG) market, reinforcing the necessity for strategic advisory solutions.
Sustainability Reporting & Disclosure Advisory plays an important role in the expanding scope of the Environmental, Social & Governance (ESG) market. This segment is estimated to reach USD 11.7 billion by 2033, at a CAGR of 22.5% during the forecast period. The growing emphasis on corporate transparency and accountability drives demand for enhanced sustainability reporting solutions. Companies increasingly recognize the align their practices with stakeholder expectations, thereby fueling interest in effective sustainability disclosure frameworks.
Regulatory compliance standards exert significant influence on adoption rates within this segment. Stricter regulations and guidelines necessitate comprehensive reporting mechanisms, compelling organizations to invest in advisory services that ensure compliance. The financial services sector, in particular, demonstrates heightened demand for tailored sustainability reporting solutions, driven by investors increasingly prioritizing environmental and social factors in their decision-making processes.
Technological maturation supports the evolution of sustainability reporting tools, enabling organizations to streamline data collection and reporting processes. Advanced analytics and performance management systems enhance the quality of insights derived from sustainability data, allowing companies to make informed strategic decisions. This evolution aligns with a broader trend towards integrated ESG services, where organizations seek comprehensive solutions that encompass environmental, social, and governance considerations.
Strategic opportunity windows in the market arise from the shift in consumer preferences towards sustainable business practices. Brands that effectively communicate their sustainability efforts not only strengthen their market position but attract a loyal customer base. Supply chain resilience is important in this context, because organizations strive to ensure that sustainability extends throughout their operations, including sourcing and logistics.
The Sustainability Reporting & Disclosure Advisory segment reflects a dynamic intersection of regulatory pressures, technological advancements, and shifting consumer expectations, positioning it for significant growth within the Environmental, Social & Governance (ESG) market.
Growing focus on corporate governance and accountability drives demand for ESG Assurance, Verification & Certification services. Increasing regulatory pressures compel organizations to demonstrate compliance and transparency in their environmental and social impact. This segment addresses the necessity for independent verification in sustainability practices, enhancing credibility among stakeholders. The market experiences significant growth driven by companies prioritizing ESG strategies and seeking to mitigate risks associated with non-compliance.
Investments in technology including blockchain and AI contribute to refining verification processes, leading to more efficient audits and certifications. The shift toward digital solutions enhances trust and reliability, catering to evolving consumer preferences for sustainable practices. ESG Assurance, Verification & Certification services are crucial for organizations across diverse sectors, including finance, energy, and manufacturing, aligning with their strategic objectives in the Environmental, Social & Governance (ESG) market.
This segment is projected to reach USD 11.4 billion by 2033. Compliance with international standards and certification frameworks further influences growth, positioning organizations to access new markets and enhance their brand reputation. This segment benefits from heightened awareness of climate change and social responsibility, creating strategic opportunity windows for firms specializing in ESG services.
With a projected CAGR of 24.7% during the forecast period, significant growth in the Supply Chain ESG & Human Rights Due Diligence segment reflects an increasing emphasis on ethical sourcing and sustainable practices. Mounting pressure from regulators and consumers compels companies to ensure transparency and accountability in supply chains, driving demand for these services. The integration of advanced technologies, including blockchain and AI, enhances monitoring capabilities, enabling organizations to effectively manage risks associated with supply chain disruptions and human rights violations.
Adoption of these services aligns with evolving regulatory compliance standards, which require organizations to demonstrate their commitment to ethical practices. Firms invest in comprehensive ESG strategies to mitigate risks, improve brand reputation, and meet stakeholder expectations. Consequently, organizations operating within the Environmental, Social & Governance (ESG) market prioritize due diligence measures that incorporate sustainability and human rights considerations, facilitating navigation through complex global supply chains.
This segment's growth trajectory indicates a strategic opportunity window for service providers to expand their offerings and develop innovative solutions tailored to the unique challenges of various industries. Companies leveraging insights from data analytics and risk assessment tools enhance their supply chain resilience, ultimately leading to improved operational performance in an increasingly competitive market.
Increased emphasis on environmental impact and sustainable practices drives demand for Climate, Carbon & Decarbonization Advisory services. Organizations seek to address carbon footprints and adapt to climate change through strategic planning and implementation of sustainable practices. This segment aligns with the broader objectives of the Environmental, Social & Governance (ESG) market, because companies recognize the necessity of integrating climate considerations into their operational frameworks.
Regulatory compliance standards significantly impact this advisory sector. Legislation promoting carbon neutrality and emissions reductions compels firms to adopt comprehensive decarbonization strategies. The need for certifications related to environmental performance and sustainability further increases the demand for specialized advisory services. Firms investing in these initiatives enhance their competitive positioning and stakeholder trust.
Technological maturation significantly influences segment expansion. Advancements in data analytics, modeling software, and carbon tracking tools facilitate more effective assessments of environmental impact. Integration of innovative technologies enables firms to implement next-generation upgrades that improve efficiency and reduce costs associated with carbon management.
Downstream application of climate advisory services influences various end-use industries, including energy and utilities, manufacturing, and transportation. Each industry faces unique challenges and opportunities related to carbon emissions. Customized strategies developed through advisory services help clients navigate these complexities while contributing to the overall growth of the market.
Strategic opportunity windows arise because businesses prioritize sustainability and resilience within supply chains. The push for responsible sourcing and sustainable logistics enhances demand for advisory services focused on climate considerations. Addressing these factors positions firms to capitalize on evolving market dynamics and consumer preferences.
Capital investment outlook remains robust, with organizations allocating budgets toward climate initiatives. Financial commitment toward decarbonization enhances operational capabilities and supports broader ESG goals. This strategic focus ultimately shapes the future trajectory of the Climate, Carbon & Decarbonization Advisory segment within the Environmental, Social & Governance (ESG) market.
Regulatory compliance standards significantly influence the demand for ESG Risk & Regulatory Compliance Services. Heightened scrutiny from investors and stakeholders drives organizations to adopt stringent compliance frameworks, ensuring adherence to environmental regulations and social responsibilities. Companies face increasing pressure to demonstrate transparency and accountability in their operations, boosting demand for specialized advisory services aimed at navigating complex regulatory landscapes.
The evolution of ESG standards contributes to the expansion of this segment within the Environmental, Social & Governance (ESG) market. Organizations incorporate advanced risk management frameworks to address regulatory requirements and mitigate potential liabilities. This proactive approach creates opportunities for service providers to enhance their offerings and develop tailored solutions that align with the specific needs of different industries, particularly because regulations evolve.
Technological advancements facilitate improvements in data collection, reporting, and compliance monitoring. Investments in innovative technologies enable companies to streamline compliance processes and reduce operational risks associated with regulatory violations. The continuous maturation of these technologies supports the segment's growth and responds effectively to evolving compliance requirements.
End-use dynamics reflect a growing commitment to sustainability across various sectors, including banking, energy, and manufacturing. Organizations prioritize ESG factors in their operational strategies, leading to an uptick in demand for ESG Risk & Regulatory Compliance Services. This trend indicates a shift toward integrating ESG considerations into core business practices.
Growing reliance on data analytics shapes the demand for ESG Data, Measurement & Performance Management. Businesses apply this segment to enhance their decision-making processes and measure sustainability performance effectively. Corporate stakeholders increasingly recognize the importance of transparent data collection and reporting to meet stakeholder expectations and enhance corporate governance.
Technological maturation influences the segment's expansion. Advanced analytics tools and frameworks enable organizations to track and assess their ESG metrics accurately. The development of sophisticated software solutions for data measurement supports businesses in aligning their strategies with regulatory compliance standards and achieving sustainable performance goals.
Downstream application of ESG Data, Measurement & Performance Management influences various industries, including banking, financial services, and manufacturing. These sectors prioritize accurate data management practices to comply with evolving regulations and meet investor demands for transparency. Enhanced data capabilities drive long-term value creation through improved risk management and operational efficiencies.
Regulatory compliance continues to be a primary demand driver in the Environmental, Social & Governance (ESG) market. Stricter regulations regarding disclosures and sustainability reporting enforce organizations to invest in robust data management systems. The shift towards more stringent certifications and transparency standards increases the need for effective ESG data practices.
Investment in this segment reflects a strategic opportunity window driven by organizations seeking to improve their overall ESG performance. Companies that prioritize ESG data management strengthen their competitive position while meeting stakeholder expectations. This focus contributes to the segment’s growth trajectory within the market, aligning corporate strategies with sustainability objectives.
Growing interest in sustainable finance and education in Environmental, Social & Governance (ESG) practices fuels demand for advisory services in the segment of Sustainable Finance Advisory and ESG Training & Capacity Building. Stakeholders actively seek guidance related to integrating ESG principles into their business models. This emphasis on capacity building aligns with global trends prioritizing sustainability and social responsibility.
Investment firms, corporations, and non-profit organizations drive adoption by seeking expertise in navigating ESG frameworks and standards. Demand for training programs that enhance understanding of ESG criteria strengthens, focusing on compliance issues and best practices across various industries. Educational initiatives enable organizations to adapt and innovate, ensuring alignment with evolving regulatory landscapes.
Forward-looking companies recognize the strategic value of integrating ESG principles into their operations. By investing in these advisory services, organizations enhance risk management and build stronger relationships with stakeholders. This proactive approach ensures long-term sustainability and resilience against market fluctuations.
The Sustainable Finance Advisory and ESG Training & Capacity Building segment reflects broader trends within the Environmental, Social & Governance (ESG) market, representing a commitment to ethical practices and social responsibility. Initiatives undertaken in this segment support industry efforts toward comprehensive ESG integration, enhancing overall market growth and stability.
Valued at USD 6.3 billion in 2026, the Environmental Services segment is projected to reach USD 29.3 billion by 2033, at a CAGR of 24.5% during the forecast period. Strong regulatory compliance standards drive the adoption of environmental services, because organizations prioritize sustainable practices to meet increasingly stringent regulations. Companies across multiple industries, including Banking, Financial Services & Insurance and Energy & Utilities, actively seek these services to enhance their operational sustainability and mitigate environmental risks. The growing recognition of the environmental impact of business operations fuels demand for comprehensive environmental services that not only ensure compliance but promote long-term sustainability. This trend leads to significant capital investment in technologies and processes that support the development of innovative environmental solutions within the Environmental, Social & Governance (ESG) market.
Investment in advanced technologies enhances service offerings, driving differentiation within the market. Organizations investing in next-gen upgrades, including digital tools for monitoring and reporting environmental performance, strengthen their competitive positioning while complying with evolving regulations. While businesses shift towards more sustainable practices, those not adapting to these changes face potential reputational and financial risks. The Environmental Services segment, therefore, positions itself because a critical area of growth, aligning with global sustainability goals and responding to increasing consumer and investor pressures for transparency in environmental impacts.
Strong demand for Social Services stems from increasing corporate accountability and an enhanced focus on social equity. Organizations across various sectors invest in programs addressing community engagement, employee well-being, and human rights initiatives. Stakeholders demand higher transparency and ethical practices, prompting firms to prioritize social responsibility within their operational frameworks. This trend boosts the growth of the Environmental, Social & Governance (ESG) market, specifically within the Social Services segment.
The Social Services segment is estimated to reach USD 15.7 billion by 2033, reflecting a compound annual growth rate (CAGR) of 22.7% during the forecast period. The expansion of this market segment aligns with the growing importance of social governance in business strategies. Companies increasingly seek to integrate social impact assessments into their decision-making processes, leading to greater investment in social performance metrics and reporting.
Technological advancements contribute to the evolution of Social Services, enabling better measurement of social impact and enhancing reporting standards. Firms leverage technology to streamline their social initiatives, making them more efficient and effective. This technological maturation creates a competitive edge among organizations, attracting favorable attention from investors and consumers.
The demand for social services is expected to escalate further, driven by changing societal expectations and evolving regulatory landscapes. Organizations facing stringent compliance requirements on social factors will invest more heavily in related services. Firms that prioritize social governance are positioned to capture significant market share within the Environmental, Social & Governance (ESG) market.
Growing attention on corporate governance practices influences the Governance Services segment within the Environmental, Social & Governance (ESG) market. This segment focuses on ensuring organizations adhere to regulations, manage risks effectively, and enhance stakeholder engagement. Regulatory bodies introduce stricter compliance measures, prompting organizations to invest in governance solutions to align with these standards. The projected value of the segment is USD 14 billion by 2033.
Demands for transparency and accountability continue to escalate, prompting firms to adopt improved governance frameworks. New technologies enhance governance practices through better data management and reporting capabilities. Firms that implement these solutions achieve operational efficiencies and strengthen investor confidence, promoting a more sustainable business environment.
Governance Services play a crucial role in shaping the strategic direction of organizations. Firms face heightened scrutiny from investors and consumers, and effective governance structures directly impact market positioning. The segment's growth trajectory aligns with broader trends in the Environmental, Social & Governance (ESG) market, reflecting an ongoing commitment to responsible corporate behavior.
Strong demand for Integrated ESG Services drives growth in the Environmental, Social & Governance (ESG) market. Organizations prioritize sustainable practices and regulatory compliance, intensifying the need for comprehensive ESG solutions. Businesses seek to enhance their environmental and social performance, aligning with modern stakeholder expectations while mitigating risks associated with non-compliance.
The Integrated ESG Services segment is projected to grow at a CAGR of 23.2% during the forecast period. This expansion results from increasing awareness of sustainability and the need for transparent reporting mechanisms. Companies across various industries, including banking, financial services, and manufacturing, recognize the value of integrating ESG considerations into their operations and strategies.
Regulatory compliance standards substantially influence demand dynamics. Stricter regulations and policies require organizations to adopt robust ESG frameworks, creating a competitive landscape where service providers offering integrated solutions gain a distinct advantage. Technological advancements contribute to the evolution of these services, facilitating data management, reporting, and performance tracking.
Looking ahead, strategic investment opportunities arise within this segment, with market players focused on enhancing service offerings to meet evolving client needs. The capital investment outlook reflects a commitment to developing innovative and effective Integrated ESG Services, reinforcing their role in the overall growth trajectory of the Environmental, Social & Governance (ESG) market.
Valued at USD 3.5 billion in 2026, the Banking, Financial Services & Insurance segment is projected to reach USD 14.6 billion by 2033, with a CAGR of 22.5% during the forecast period. Increased regulatory compliance requirements act because a primary demand driver for financial institutions striving to enhance their ESG practices. The evolving landscape of responsible investing further strengthens the emphasis on sustainable finance within the sector. Financial services firms increasingly adopt robust ESG strategies to meet investor expectations and societal demands, leading to greater investment in ESG-related services.
Technological maturation, including advanced data analytics and reporting tools, supports the segment's growth by enabling better measurement and management of ESG performance. Next-gen upgrades in compliance technologies facilitate adherence to new regulations, enhancing the operational efficiency of financial institutions. The demand for transformation in banking practices creates strategic opportunities for players in the Environmental, Social & Governance (ESG) market, allowing them to offer innovative solutions tailored to the unique challenges faced by this sector.
The influence of sustainability trends drives consumption shifts, with companies moving towards more transparent reporting and accountability frameworks. Regulatory compliance standards, including certifications and guidelines, shape the adoption of ESG strategies across the industry. Firms that successfully integrate ESG principles into their operations experience enhanced reputation and increased investor confidence, ultimately boosting their market performance.
Overall, the Banking, Financial Services & Insurance segment exemplifies the dynamic relationship of regulatory pressure, technological advancements, and evolving consumer expectations, all contributing to the growth trajectory of the Environmental, Social & Governance (ESG) market. Investments in ESG practices not only fulfill regulatory requirements but align with broader societal values, supporting a sustainable financial future.
Investment in renewable energy sources and the shift toward sustainable practices drive significant growth in the Energy & Utilities segment of the Environmental, Social & Governance (ESG) market. The segment is estimated to reach USD 12.9 billion by 2033, at a CAGR of 24% during the forecast period. Regulatory frameworks increasingly emphasize sustainable energy practices, compelling companies within the sector to adopt ESG strategies to comply with environmental legislation and societal expectations. This regulatory pressure enhances the integration of ESG criteria into core business operations, influencing decisions across project development and energy generation.
Firms increasingly recognize the importance of transparent sustainability reporting and stakeholder engagement within their corporate strategy. Adoption of innovative technologies in energy management systems supports efficiency and reduces carbon footprints, further aligning operations with ESG objectives. These advancements not only facilitate compliance but enhance competitiveness in a market that increasingly prioritizes sustainability. The sector’s evolution reflects a broader trend toward decarbonization, requiring firms to invest in next-generation upgrades and sustainable solutions.
Growing consumer awareness and demand for cleaner energy alternatives result in a substantial shift in consumption patterns. This transition influences traditional energy utilities to diversify their portfolios, integrating renewable sources and emphasizing social responsibility in their business models. Such adaptations within the Energy & Utilities segment contribute to a more resilient supply chain and reduce vulnerability to market fluctuations.
The Energy & Utilities segment serves because a key driver within the Environmental, Social & Governance (ESG) market, with ongoing regulatory compliance and technological advancements shaping the future landscape. Strategic investments aligned with evolving consumer preferences and regulatory requirements position firms for sustained growth in this dynamic environment.
Increased regulatory scrutiny and the pursuit of sustainable practices drive significant growth within the Manufacturing & Industrial segment of the Environmental, Social & Governance (ESG) market. Companies in this sector focus on enhancing operational efficiency while adhering to stringent compliance standards, creating an environment where ESG strategies thrive. The demand for ESG-related services stems from the necessity to mitigate risks associated with environmental impacts, worker rights, and supply chain integrity.
The Manufacturing & Industrial segment is projected to reach USD 11.2 billion by 2033. Investment in ESG initiatives aligns with broader corporate strategies aimed at enhancing brand reputation and stakeholder trust. The integration of next-generation technologies and data analytics enables firms to achieve improved sustainability outcomes while optimizing resource allocation and operational processes.
Heightened emphasis on sustainable sourcing and transparent supply chains influences consumption patterns, pushing industry players to adopt ESG frameworks that connect with consumers and investors alike. While the market evolves, companies face both opportunities and challenges related to pricing volatility and margin pressures, necessitating agile strategies that align with market dynamics and regulatory requirements.
Overall, the Manufacturing & Industrial segment leads the ESG market transformation, where capital investment outlook reflects a strong commitment to integrating environmental, social, and governance principles across operations.
Growing consumer awareness regarding sustainability significantly influences the demand for Environmental, Social & Governance (ESG) practices in the Consumer Goods & Retail segment. Brands focusing on sustainable sourcing and environmentally friendly products gain competitive advantages, attracting environmentally conscious consumers. Regulatory compliance standards shape the strategies of firms within this segment, ensuring that organizations align with environmental regulations and social responsibility expectations.
Investment in sustainable practices leads to improved operational efficiencies, reducing long-term costs while enhancing brand reputation. Companies prioritizing ESG initiatives experience stronger consumer loyalty, driving revenue growth. The Consumer Goods & Retail segment is projected to grow at a CAGR of 22.8% during the forecast period.
Technological advancements facilitate transparency in supply chains, allowing firms to demonstrate their commitment to sustainability. Enhanced tracking and reporting mechanisms strengthen consumer trust, enabling brands to differentiate themselves in a crowded market. Increasing pressure from stakeholders encourages firms to adopt innovative practices that contribute to the overall growth of the Environmental, Social & Governance (ESG) market.
The expansion of this segment reflects a broader trend toward responsible consumption patterns and ethical business practices. While the market evolves, organizations prioritizing ESG principles find strategic opportunity windows, positioning themselves for success in an increasingly competitive environment.
Growing emphasis on sustainable practices in the Technology, Media & Telecommunications sector influences demand for Environmental, Social & Governance (ESG) services. Increasing public awareness and regulatory frameworks drive companies within this industry to enhance their ESG strategies. A focus on digital transformation and data-driven decision-making encourages innovation in ESG reporting and compliance solutions, promoting growth in the market.
Technological advancements significantly shape ESG practices, with firms leveraging artificial intelligence and big data analytics to streamline operations and improve transparency. This evolution leads to enhanced consumer trust and loyalty, positively impacting brand reputation. The industry's continuous investment in next-gen technologies enables companies to meet regulatory expectations and stakeholder demands effectively.
While organizations prioritize ESG criteria in their operations, the integration of sustainable practices across various business functions becomes critical. The shift towards a circular economy and sustainable production processes creates opportunities for growth within the market. Successful adaptation to these trends enhances competitive positioning and financial performance.
Increased regulatory pressures compel businesses to adopt comprehensive ESG frameworks, ensuring compliance with evolving standards. This necessity encourages a proactive approach towards sustainability and social responsibility, leading to greater investments in ESG initiatives. The industry's focus on environmental stewardship and social equity contributes to the long-term resilience of the Technology, Media & Telecommunications sector.
Overall, the drive towards heightened ESG engagement creates significant strategic opportunity windows for companies operating within this segment. By aligning their business models with sustainable practices, organizations enhance operational efficiencies while meeting the expectations of stakeholders. Such alignment supports the ongoing expansion of the Environmental, Social & Governance (ESG) market.
Increasing focus on health outcomes and patient safety drives demand in the Healthcare & Life Sciences segment of the Environmental, Social & Governance (ESG) market. The integration of ESG principles into healthcare practices enhances operational efficiency and cultivates trust among stakeholders. Regulatory compliance standards exert significant influence, compelling organizations to adopt sustainable practices that align with national and international guidelines.
Technological maturation in the sector facilitates next-gen upgrades, enabling healthcare providers to implement advanced data management systems and enhance reporting mechanisms. This trend fuels the evolution of products and services tailored to ESG objectives, promoting transparency and accountability. End-use dynamics shift towards eco-friendly solutions, impacting consumption patterns. Healthcare entities prioritize sustainability in their operations.
Strategic opportunity windows manifest for firms that effectively leverage ESG frameworks to improve patient care and operational performance. Investments in green technologies and environmentally responsible practices enhance competitiveness while mitigating risks associated with non-compliance. The market presents prospects for capital investment, driven by the demand for innovation and sustainable practices within the Healthcare & Life Sciences sector.
Increasing emphasis on sustainable development fuels demand within the Real Estate & Construction sector. This trend arises from heightened awareness regarding environmental impact, prompting stakeholders to adopt comprehensive ESG strategies. Regulatory compliance standards, particularly in building codes and land use, drive investment in green technologies and practices. These shifts align with corporate sustainability goals and enhance competitive positioning within the market.
Investment in energy-efficient building materials and sustainable construction practices expands throughout the segment. Technological maturation in areas including smart building systems supports this transition, leading to improved operational efficiency and lower long-term costs. Next-gen upgrades, including sustainable energy solutions and waste reduction strategies, attract attention from stakeholders aiming for long-term viability.
Increased scrutiny from investors and regulatory bodies mandates adherence to ESG principles, resulting in a shift in consumption patterns towards more sustainable practices. Certifications related to sustainability validate claims and provide a competitive advantage, influencing developers and construction firms to prioritize ESG compliance. This dynamic enhances the overall growth potential of the Environmental, Social & Governance (ESG) market.
Strategic opportunity windows arise due to companies innovating and adapting to emerging technologies, creating disruptive alternatives that challenge traditional construction methods. The focus on sustainability reshapes investment strategies, encouraging capital allocation toward environmentally friendly projects. A resilient supply chain supports these initiatives, ensuring that raw material sourcing aligns with regulatory standards and sustainability goals.
In the Transportation & Logistics sector, increasing regulatory compliance standards drive the adoption of Environmental, Social & Governance (ESG) practices. A heightened focus on reducing carbon emissions and improving supply chain transparency influences companies to prioritize sustainable logistics strategies. Corporate stakeholders demand accountability in environmental practices, encouraging service providers to integrate ESG frameworks into their operations.
Technological maturation plays a critical role in segment expansion, enabling advancements in logistics management systems and data analytics that enhance decision-making processes. Adoption of next-generation technologies including artificial intelligence and blockchain provides opportunities for improved efficiency, accuracy, and sustainability across transportation networks.
Shifts in consumer preferences toward environmentally friendly products create downstream application opportunities, prompting logistics providers to adjust their strategies. Increased awareness regarding the environmental impact of logistics operations necessitates investments in sustainable solutions, reinforcing the need for continuous innovation in transportation and logistics services.
Cost structures associated with implementing ESG practices exhibit variability, particularly regarding investment in technology and training. Pricing volatility in raw materials and fuel exerts pressure on margins, compelling logistics companies to seek efficiencies through sustainable practices. Strategic opportunity windows arise from shifting market dynamics, providing avenues for growth and differentiation in the competitive environment.
Supply chain resilience reflects a critical focus area, particularly in addressing vulnerabilities exposed by recent disruptions. By enhancing their ESG initiatives, organizations strengthen their ability to respond to challenges while adhering to evolving certifications and policy standards. The Environmental, Social & Governance (ESG) market evolves, driven by the intersection of regulatory demands, stakeholder expectations, and an increasing commitment to sustainability within the Transportation & Logistics sector.
Rising consumer preferences for sustainable products drive demand within the Agriculture, Food & Beverage sub-segment. Increasing awareness regarding environmental impacts influences companies to adopt sustainable practices and enhance transparency in sourcing and production processes. This trend aligns with broader shifts within the Environmental, Social & Governance (ESG) market, where stakeholders prioritize ethical sourcing and sustainability.
Regulatory compliance standards significantly impact the Agriculture, Food & Beverage sector. Stricter regulations concerning agricultural practices and food safety prompt companies to invest in ESG strategies to meet these requirements. Certifications related to sustainability enhance brand reputation and improve market competitiveness. This emphasis on compliance presents challenges and opportunities for firms operating in this sub-segment.
Technological advancements play a crucial role in the evolution of sustainable practices in agriculture and food production. Innovations in precision agriculture, alternative protein sources, and waste reduction technologies enhance operational efficiency while addressing environmental concerns. Adoption of these technologies contributes to enhanced productivity and reduced environmental footprints, aligning with expectations from consumers and regulatory bodies.
Investments directed towards sustainability initiatives within the Agriculture, Food & Beverage sector reflect a strategic opportunity window. Companies leveraging ESG practices differentiate themselves, attract eco-conscious consumers, and enhance long-term viability. The shift towards sustainable business models presents a significant growth avenue within the overall ESG market.
Increasing demand for transparency and accountability within public sector organizations drives interest in the Environmental, Social & Governance (ESG) market. This segment encompasses various stakeholders, including government entities, educational institutions, and hospitality businesses, all seeking to integrate ESG principles into their operations. The growing importance of regulatory compliance and sustainability initiatives influences the adoption of ESG practices across these sectors.
Investment in training and capacity-building programs enhances the ability of public sector organizations to implement effective ESG strategies. Education institutions prioritize sustainability in their curricula, creating a generation of professionals equipped to address environmental and social challenges. The hospitality sector focuses on minimizing its environmental footprint, promoting responsible consumer practices, and enhancing community engagement.
The complexity of ESG requirements adds to the urgency for organizations to adopt comprehensive frameworks for compliance and reporting. In response to rising scrutiny from stakeholders and regulatory bodies, public sector entities increasingly prioritize ESG criteria in decision-making processes. The integration of ESG considerations not only fulfills compliance obligations but strengthens organizational resilience and brand reputation.
The emphasis on transparency, regulatory alignment, and sustainable practices drives significant engagement with the Environmental, Social & Governance (ESG) market among public sector, education, and hospitality stakeholders. This segment presents opportunities for growth driven by organizations striving to meet evolving expectations from the public and regulatory authorities.
Based on geography, the Global Environmental, Social & Governance (ESG) market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America holds a significant share of the Environmental, Social & Governance (ESG) market, contributing 39% to the global market in 2025. This region is set to expand at a CAGR of 23.5% within the forecast period, reaching a market size of USD 29.3 billion by the end of 2033. The demand for ESG services in the United States, Canada, and Mexico stems from heightened consumer expectations regarding sustainability and corporate responsibility.
Infrastructure modernization drives growth, supported by companies investing in technologies that align with ESG principles. The banking, financial services, and insurance sectors lead in adopting ESG practices, reflecting a broader trend towards integrating sustainability into business operations. The presence of established domestic market participants enhances competitive dynamics, encouraging innovation and service diversification.
Localized procurement dynamics influence buying behaviors, with businesses increasingly favoring vendors that demonstrate compliance with regional regulations and sustainability commitments. The ESG market benefits from foreign direct investment (FDI) flows, which support the development of new services and capabilities. Emerging trends in supply chain regionalization and localized manufacturing further enhance market access and operational efficiency.
Regulatory frameworks across North America shape the market dynamics, with compliance mandates driving the adoption of ESG strategies. Companies prioritize ESG reporting and assurance services to address these requirements, enhancing their reputation and market position. Overall, the Environmental, Social & Governance (ESG) market in North America is poised for significant growth, driven by evolving consumer expectations, regulatory pressures, and a commitment to sustainable development.
The Environmental, Social & Governance (ESG) market in Europe represents a significant portion of the global landscape, capturing 30.7% of the market share in 2025. Countries including Germany, France, and the UK lead in the adoption of ESG practices, driven by increasing regulatory pressures and heightened public awareness of sustainability issues. The focus on Environmental Services and Sustainability Reporting has driven growth, creating an environment that encourages companies to integrate ESG principles into their operations.
Investment in ESG Strategy & Transformation Advisory services stands out because a crucial driver, enhancing corporate transparency and accountability. France and Germany have emerged because front-runners, with many organizations prioritizing compliance with local regulations and aligning with international standards. This trend influences the expansion of ESG Assurance and Verification services, addressing the need for firms to demonstrate adherence to sustainability commitments.
Challenges including geopolitical fragmentation impact cross-border collaborations within Europe, affecting the flow of investments and trade. Localized procurement dynamics and cultural nuances shape B2B buying behaviors, enabling regional players to adapt their strategies accordingly. The interaction of these factors contributes to the market's overall growth trajectory, presenting ample opportunities for vendors with robust portfolios in ESG-related services.
Infrastructure modernization efforts across the region further enhance the potential for ESG adoption, with new technologies facilitating better data management and reporting frameworks. The focus on localized manufacturing densities and nearshoring initiatives supports companies in addressing supply chain challenges while meeting regional compliance mandates. These elements position the Environmental, Social & Governance (ESG) market in Europe for sustained growth and increased investment.
The Asia-Pacific region holds a significant share of the Environmental, Social & Governance (ESG) market, accounting for 23% in 2025. Rapid urbanization and economic growth in countries including China, India, and South Korea drive heightened awareness around sustainability, compelling businesses to adopt ESG frameworks. Government initiatives promoting environmental responsibility and social equity further support the momentum in this sector.
Investment in ESG solutions aligns with the increasing demand for transparency and regulatory compliance across various industries. The financial services sector, particularly in Australia and Japan, increasingly emphasizes sustainability reporting and verification services. Growth in renewable energy adoption across the region influences the demand for ESG services related to carbon management and sustainability advisory.
Emerging markets within Southeast Asia exhibit strong potential for growth, driven by rising foreign direct investments and a shift toward localized manufacturing densities. Companies operating in these regions are expected to enhance their ESG strategies to meet both local compliance mandates and global standards, aligning with the growing expectations of stakeholders.
While organizations prioritize ESG initiatives, increased competition among service providers is likely, driving innovation in ESG solutions. The Asia-Pacific market will experience incremental growth driven by these factors, reinforcing its position because a key contributor to the overall global Environmental, Social & Governance (ESG) market.
The Environmental, Social & Governance (ESG) market in South America experiences growth driven by increasing regulatory frameworks and local compliance mandates that encourage sustainable practices across various sectors. Brazil and Argentina lead the region, with companies in these countries focusing on ESG initiatives to meet both domestic and international expectations. The emphasis on ethical investments and corporate social responsibility significantly influences market dynamics, prompting firms to adopt comprehensive ESG strategies.
Infrastructure modernization efforts within South America support the expansion of the market by improving energy grid resiliency and enhancing resource availability. These initiatives create a stronger commitment to sustainability, particularly in sectors including energy and finance. The adoption rates for ESG practices reflect heightened awareness among consumers and corporations alike, reinforcing the need for transparency and responsible governance.
The market's growth potential remains significant, with emerging players establishing a foothold in various industries, including banking, financial services, and energy. Regional competitive landscapes indicate a trend towards vendor consolidation, where established firms collaborate with local entities to enhance service delivery and compliance with ESG standards. While the market matures, firms increasingly prioritize localized procurement dynamics and cultural nuances that shape B2B buying behaviors.
Market participants actively engage in strategic initiatives that promote foreign direct investment flows, further stimulating growth opportunities. While cross-border trade corridors remain essential for connecting regional markets, the focus on localized manufacturing densities positions South America because an attractive destination for ESG-focused investments. Overall, the Environmental, Social & Governance (ESG) market in this region is expected to undergo considerable transformation, driven by these multifaceted dynamics.
The Environmental, Social & Governance (ESG) market in the Middle East and Africa demonstrates a relatively small share of the global market, accounting for 3.5% in 2025. This region exhibits unique demand drivers, influenced by evolving regulatory frameworks and compliance mandates that shape local market dynamics. Countries including Saudi Arabia and the UAE lead initiatives to enhance their sustainability profiles, with significant investments aimed at modernizing infrastructure and increasing transparency in governance practices.
Emerging market front-runners exhibit strong growth potential, particularly in sectors including energy and utilities, where initiatives focus on integrating sustainable practices. South Africa's growing emphasis on social services and human rights within business operations reflects a rising awareness of ESG principles among organizations. Local compliance mandates and cultural nuances play crucial roles in shaping B2B buying behaviors, resulting in the establishment of regional competitive landscapes that prioritize sustainability.
Strategic entry barriers and foreign direct investment flows into the region contribute to the expansion of the market, providing opportunities for international players. Localized procurement dynamics facilitate closer collaboration among businesses, further driving growth. Investment in renewable energy and sustainable practices highlights the commitment of these nations to meet global ESG standards, positioning the market for significant growth through 2033.
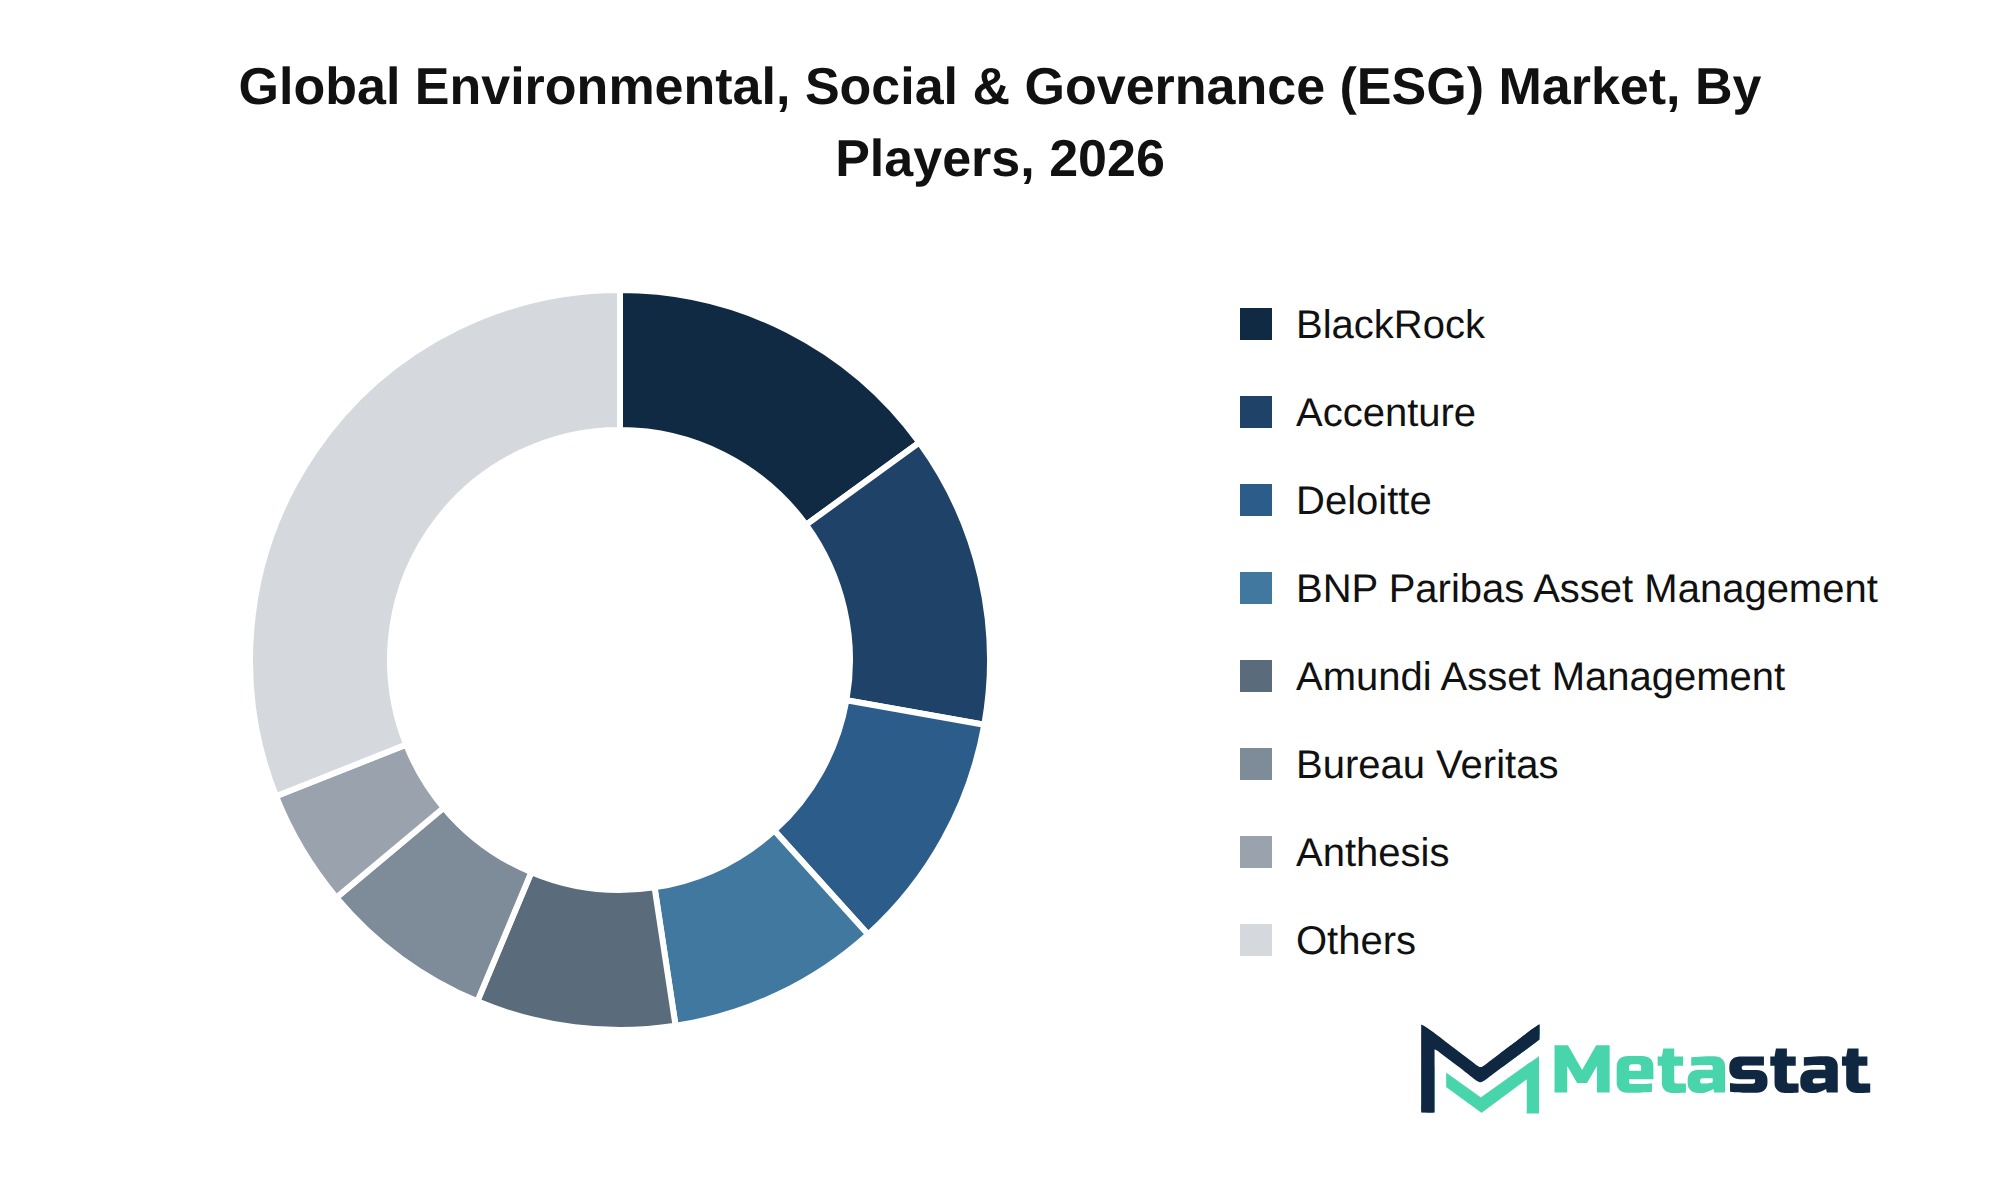
Competitive dynamics in the Environmental, Social & Governance (ESG) market illustrate a landscape shaped by strategic consolidation and partnerships. Leading firms including Accenture plc, Deloitte, and EY engage in acquisitions to enhance their service offerings and expand their reach within the market. These companies utilize their expertise to provide comprehensive ESG strategies and transformation advisory services, critical for clients facing increasing regulatory pressures.
Pricing architectures vary among providers, with competition driving pricing innovations. Firms like BlackRock Inc. and BNP Paribas Asset Management adopt value-based pricing models to differentiate their services. The emphasis on product differentiation drives a robust research and development pipeline, allowing firms to introduce innovative solutions that align with evolving client expectations.
Strategic alliances play a significant role in the market, with companies including KPMG International Limited and PwC forming cross-industry partnerships to enhance their service capabilities. These collaborations enable firms to access new client segments, enhancing customer retention strategies. Barriers to entry remain significant, with established players benefiting from economies of scale and strong brand equity, creating challenges for new entrants and startups.
The future competitive outlook for the Environmental, Social & Governance (ESG) market anticipates ongoing industry restructuring driven by companies responding to shifting client demands and regulatory environments. Firms will continue to invest in technological advancements to strengthen their intellectual property portfolios and ensure technological defensibility. This proactive approach positions them to capitalize on growth vectors within the evolving market.
Market size is forecast to rise from USD 14.7 billion in 2025 to over USD 79.4 billion by 2033. The base case indicates a substantial growth trajectory with a compound annual growth rate (CAGR) of 23.5%. This growth reflects heightened awareness of Environmental, Social & Governance (ESG) factors among stakeholders, driving demand across diverse industries.
Downstream demand will experience shifts influenced by macroeconomic trends and evolving regulatory landscapes. Companies prioritizing ESG compliance are likely to allocate strategic capital towards adopting next-generation technologies that enhance sustainability and operational efficiency. These investments are essential to meet imminent compliance milestones and evolving policy enforcement horizons.
Core industries are undergoing maturation, leading to structural consumption shifts. Organizations increasingly recognize the value of ESG integration into their business models, resulting in heightened competition for resources and investment opportunities in high-growth pockets. The market shows potential for new entrants to capitalize on unmet enterprise needs and emerging white-space opportunities.
Geopolitical realignments and evolving trade corridors will reshape global supply chains, impacting how organizations approach ESG initiatives. Strategic capital allocation and infrastructure commitments will focus on resilience and sustainability, reinforcing the importance of ESG frameworks in navigating these changes. Regulatory evolution is expected to stimulate further market growth, compelling firms to enhance their ESG strategies.
Future growth recommendations entail developing defensibility roadmaps that align with executive-level strategic imperatives. Firms will benefit from proactive engagement in ESG initiatives, driving innovation and long-term value creation in the Environmental, Social & Governance (ESG) market.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Environmental, Social & Governance (ESG) market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 23.5% from 2026 to 2033 |
Revenue Unit | USD billion |
Segmentation | By Solution Type, Service Type, End-Use Industry, and Region |
By Region | North America (By Solution Type, Service Type, End-Use Industry, and Country)
|
Europe (By Solution Type, Service Type, End-Use Industry, and Country)
| |
Asia Pacific (By Solution Type, Service Type, End-Use Industry, and Country)
| |
South America (By Solution Type, Service Type, End-Use Industry, and Country)
| |
Middle East and Africa (By Solution Type, Service Type, End-Use Industry, and Country)
|
Find answers to common questions about this report
The Environmental, Social & Governance (ESG) market size was valued at USD 14.7 billion in 2025.
The Environmental, Social & Governance (ESG) market is projected to grow at a CAGR of 23.5% during the forecast period from 2026 to 2033.
The North America Environmental, Social & Governance (ESG) market size is estimated to reach USD 29.3 billion by 2033.
The segment leading the Environmental, Social & Governance (ESG) market is ESG Strategy & Transformation Advisory, with a projected value of USD 15 billion by 2033. This segment demonstrates significant growth potential, driven by increasing demand for strategic ESG initiatives.
Key drivers for the Environmental, Social & Governance (ESG) market include the increasing emphasis on sustainability initiatives, regulatory compliance requirements, and the integration of ESG principles into digital transformation strategies. These factors stimulate investment in innovative technologies and enhance operational efficiency, ultimately promoting robust market growth.
North America holds the dominant share of the Environmental, Social & Governance (ESG) market, with a value of USD 29.3 billion projected for 2033, representing 39 percent of the total market.
Ongoing regulatory constraints significantly affect the Environmental, Social & Governance (ESG) market by creating compliance hurdles and increasing operational complexity. Companies face rising costs associated with meeting evolving legal mandates, which deter market participation, particularly among smaller firms. geopolitical fragmentation disrupts supply chain stability, leading to increased costs and logistical complexities.
Investment in digital transformation and the increasing emphasis on sustainability initiatives drive product adoption in the Environmental, Social & Governance (ESG) market. Organizations recognize the importance of integrating ESG principles into their digital strategies, enhancing operational efficiency and aligning with evolving consumer expectations and regulatory pressures.
The Environmental, Social & Governance (ESG) market is estimated to reach a valuation of USD 79.4 billion by 2033.
Key players operating in the Environmental, Social & Governance (ESG) market include Accenture plc, BlackRock Inc., Deloitte, EY, KPMG International Limited, PwC, and State Street Global Advisors (SSGA).
Choose Your License
Global Environmental, Social & Governance (ESG) Market
The analysts below cover Banking & Finance research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.
In the biological seed treatment space, registration timelines vary drastically between the European Union, Brazil, and North America. The MetaStat Insight research handled these cross-border regulatory barriers with genuine nuance, mapping commercialization pathways alongside historical field adoption rates. The segmentation between microbial strains and biochemical active ingredients was particularly well structured.
Our team was tracking whether regional recycling infrastructure could realistically absorb the growing volume of lithium iron phosphate batteries over the next decade. The report did a solid job separating announced hydrometallurgical plant capacity from active, permitted operational throughput. That distinction made the feedstock availability projections and regional recovery rate models far more credible than standard commercial overviews.
Tracking capacity expansion in single-use bioprocessing requires dependable data on raw material availability and cleanroom-grade polymer supply chains. The competitive landscape chapter gave a grounded evaluation of secondary component suppliers across North America and Asia-Pacific rather than simply reprinting press releases. Having that level of supplier benchmarking helped clarify dual-sourcing considerations for our clinical pipeline planning.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950