
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Finished Vehicles Logistics Market Size, Share, By Service Type (Primary Transport, Secondary/Last-mile Distribution, Port & Terminal Services, Storage & Yard Management, Value-added Services), By Transportation Mode (Road Vehicle Carrier, Driven/Driveaway Movement, Rail, Maritime RoRo/PCTC, Inland Waterway, Air and Specialist Transport), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Medium and Heavy Commercial Vehicles, Two-Wheelers, Specialty and Performance Vehicles), By Destination (Domestic and International), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5396
September, 2026
307 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $157.4 Billion in 2025, projected to reach $223.7 Billion by 2033 at a 4.5% CAGR.
Dominant Segment: The Primary Transport segment leads the market, driven by increasing vehicle production and the need for efficient logistics solutions. Its projected growth reflects a strong demand for streamlined transportation processes.
Geographic Lead: Asia Pacific is the fastest-growing region, bolstered by significant investments in infrastructure and technology that enhance logistics capabilities. This growth is fueled by rising vehicle sales and modernization of transportation networks.
What's Inside: The report provides comprehensive coverage of market dynamics, competitive landscape, and detailed segmentation by service type, transportation mode, vehicle type, and destination. It includes forecasts and insights from 2026 to 2033.
Emerging Regional Demands: Emerging markets, particularly in Asia Pacific and South America, are driving demand for expanded logistics services due to enhanced consumer preferences and economic growth. This trend necessitates efficient logistics solutions to support increased vehicle sales.
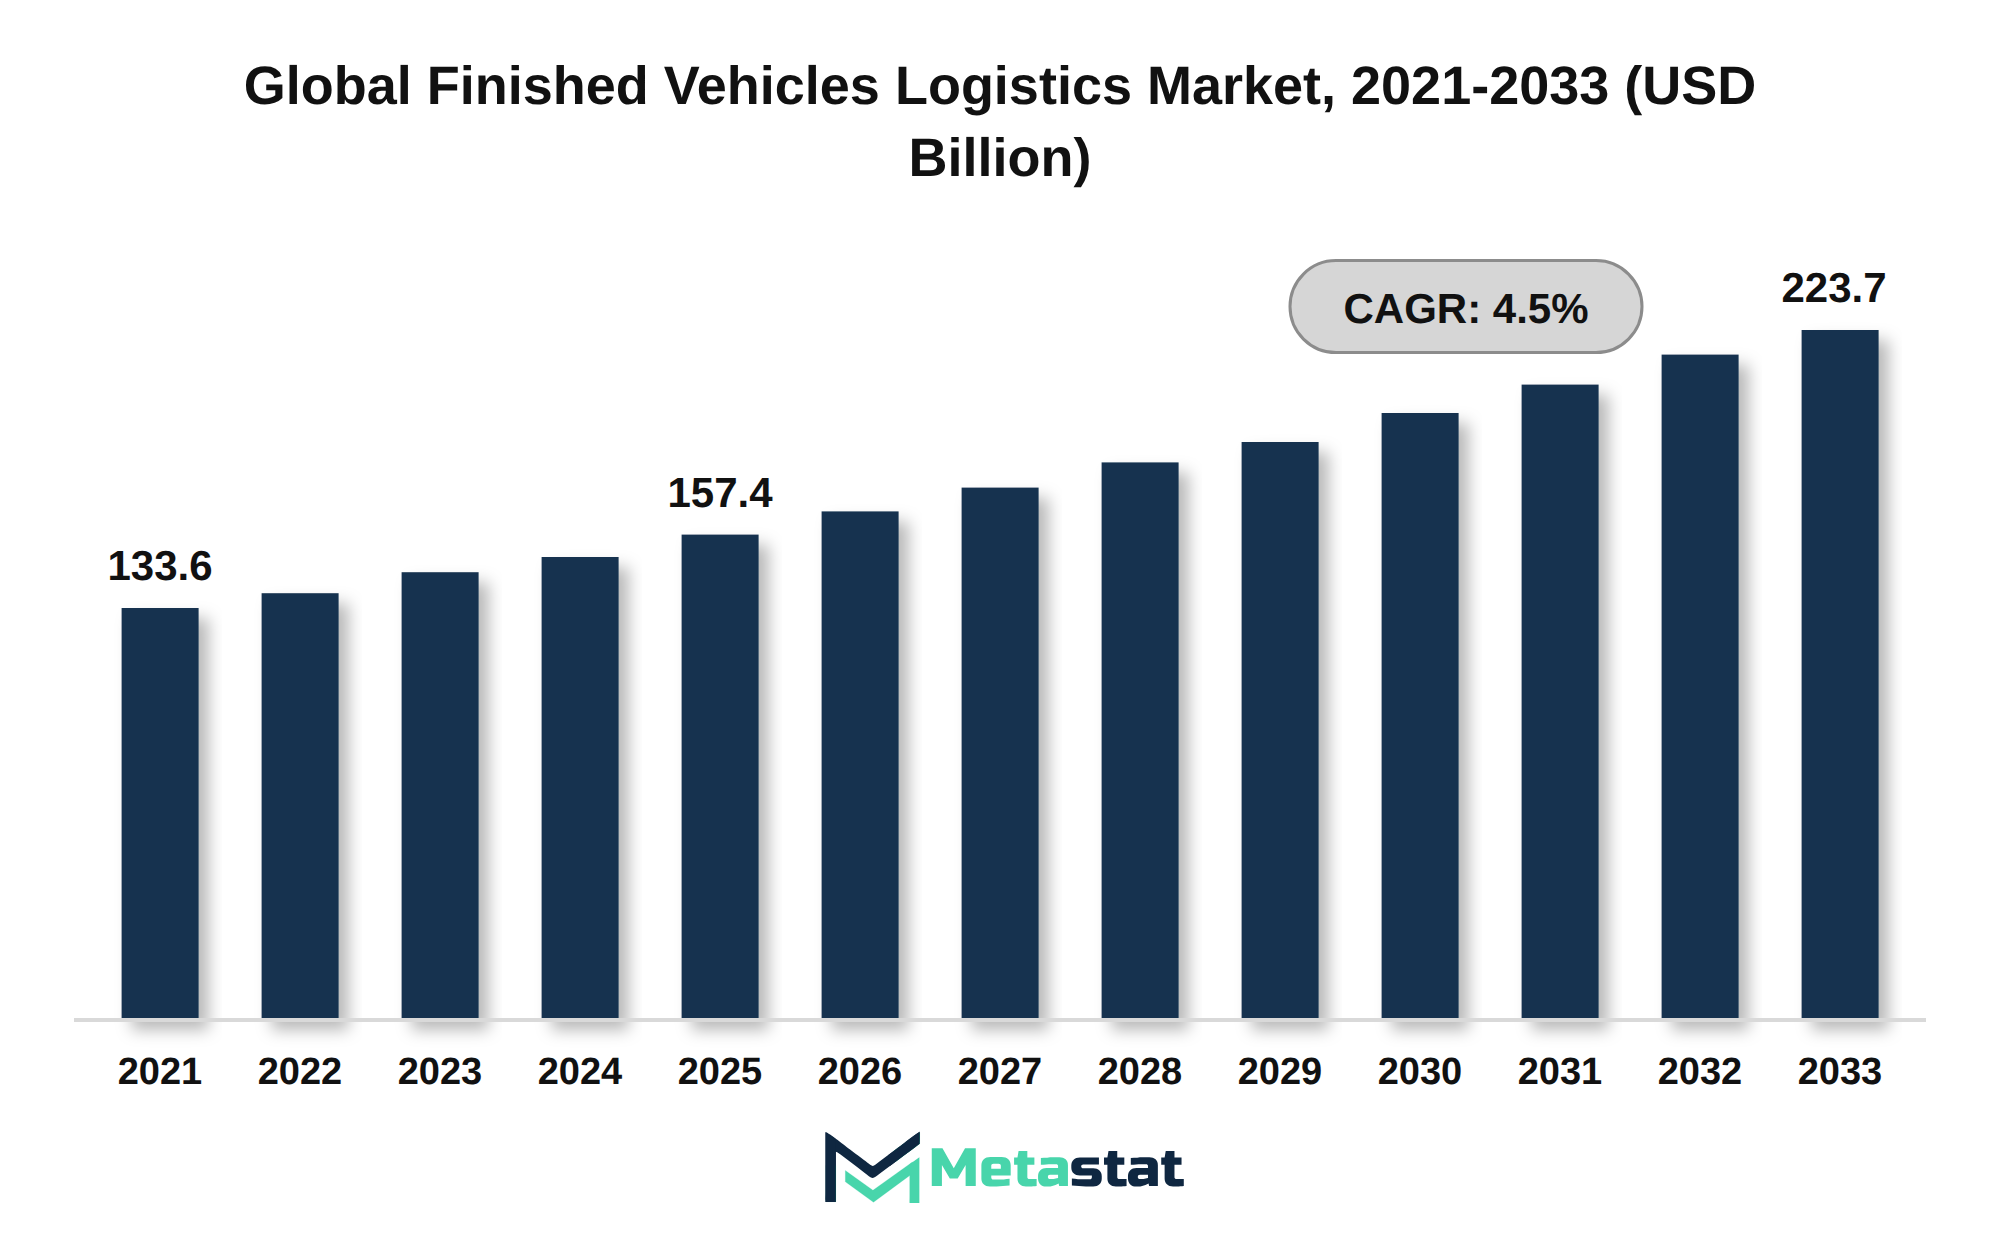
The global Finished Vehicles Logistics market was valued at USD 157.4 billion in 2025 and is projected to reach USD 223.7 billion by 2033, growing at a CAGR of 4.5% over the forecast period.
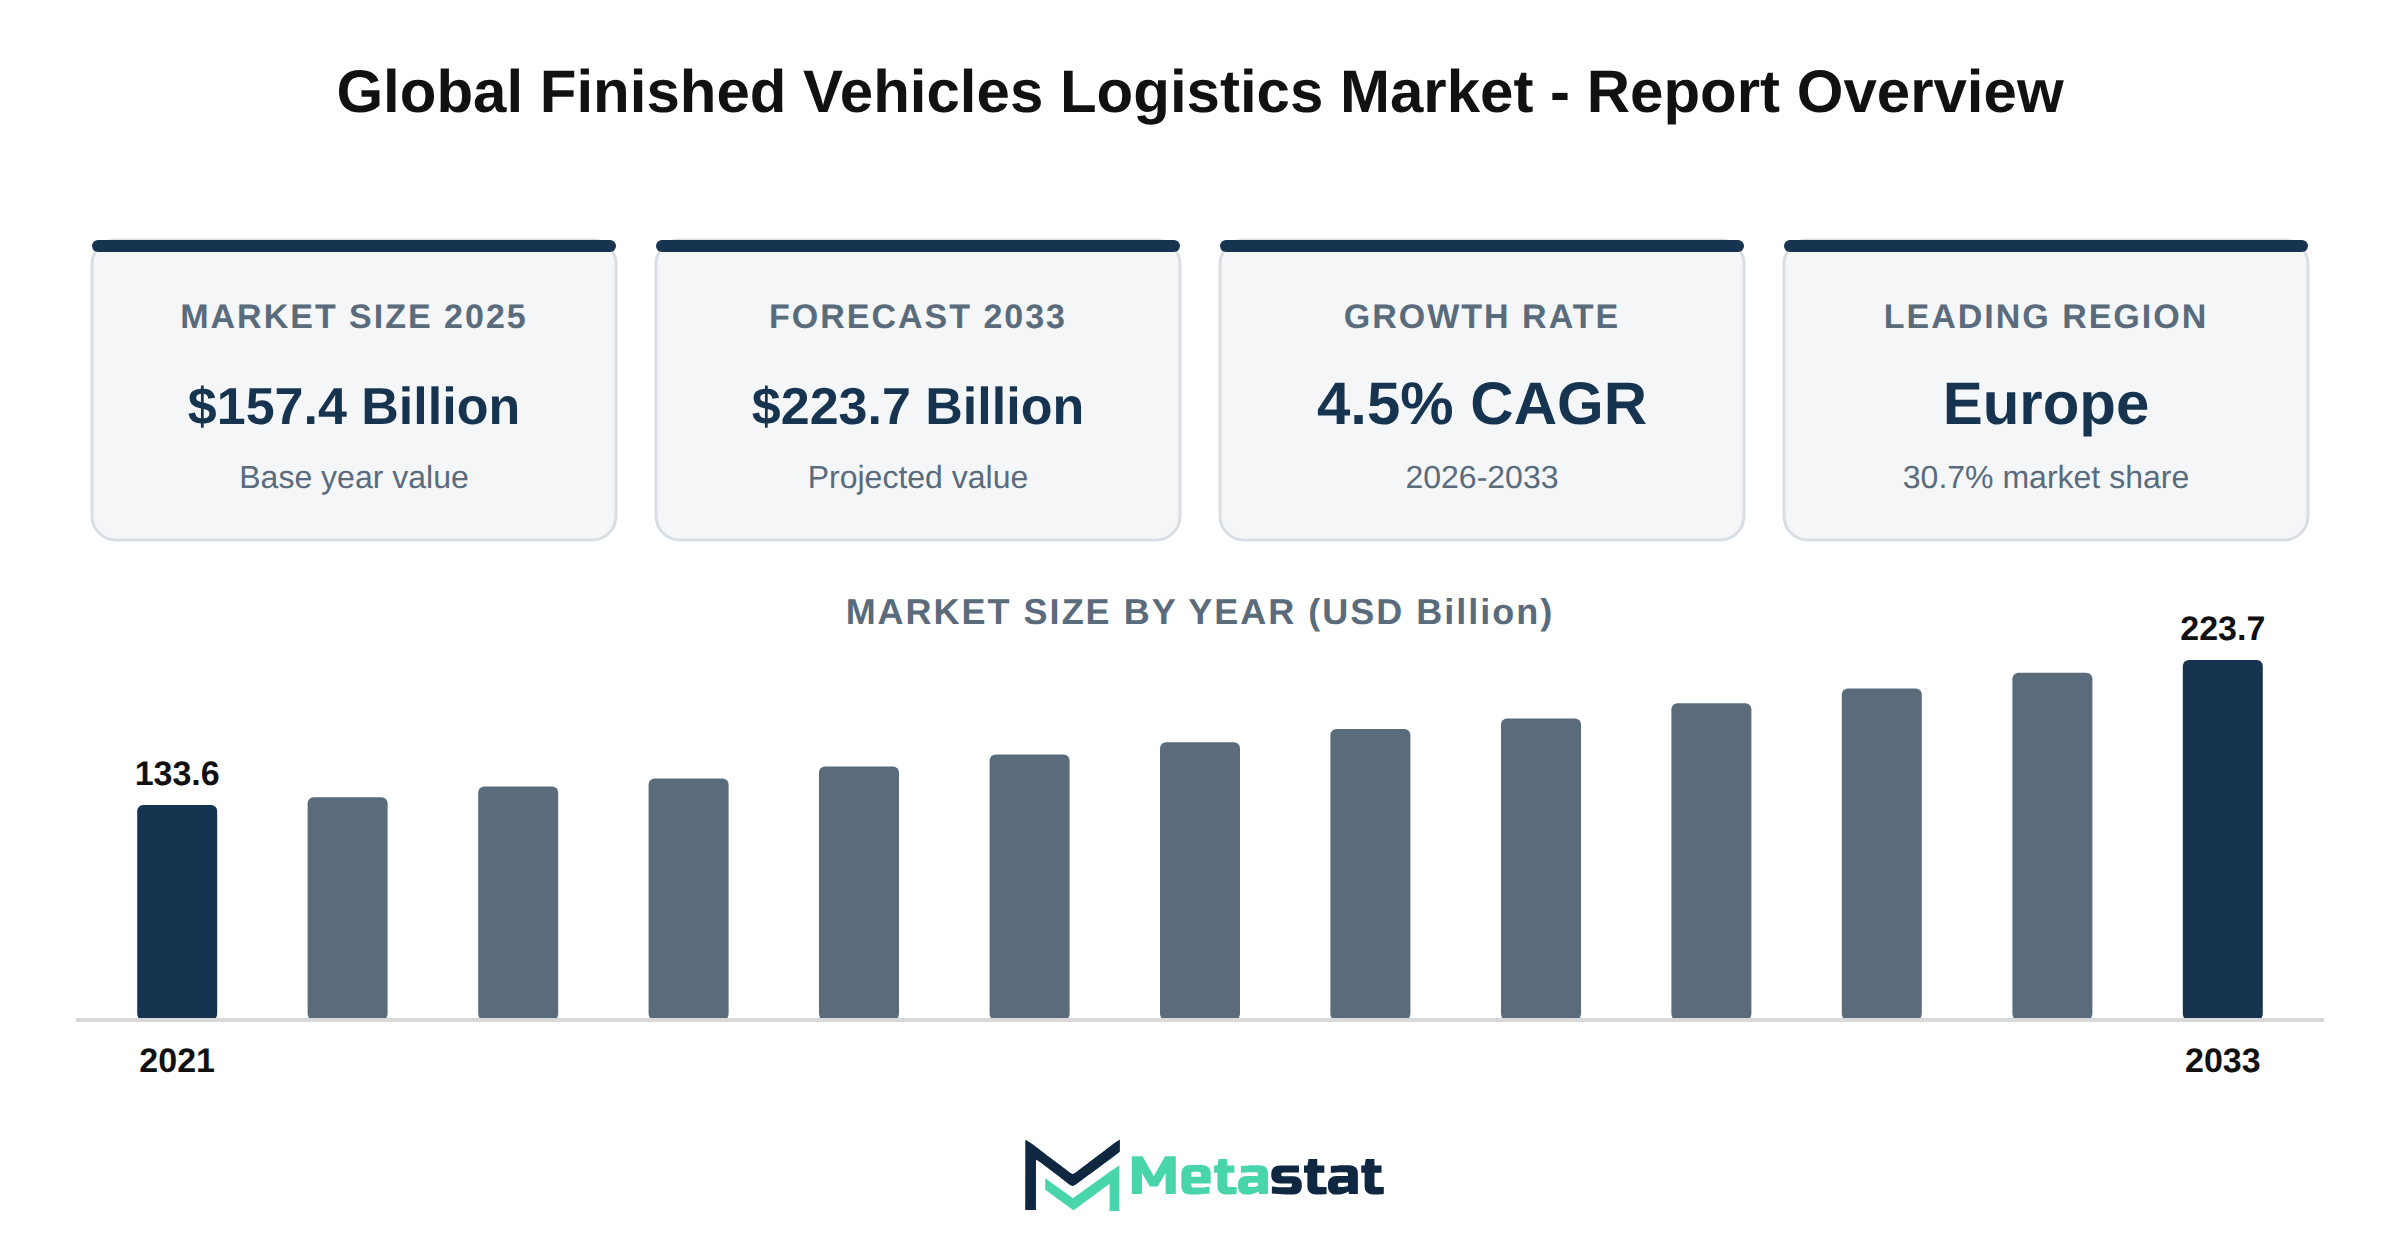
The Finished Vehicles Logistics market reached a value of USD 157.4 billion in 2025, with expectations of growth to USD 223.7 billion by 2033. This expansion reflects a compound annual growth rate (CAGR) of 4.5% during the forecast period from 2026 to 2033. The market's trajectory is influenced by several factors, including increasing global automotive production and rising demand for end-to-end finished vehicle transportation services.
Digital vehicle movement platforms significantly enhance logistics efficiency by offering improved tracking and visibility throughout the supply chain. These platforms facilitate real-time vehicle tracking, gaining strategic importance for logistics operators and automotive manufacturers. The integration of artificial intelligence in route optimization further improves logistics efficiency and reduces costs.
Road vehicle carriers remain central to finished vehicle distribution, supporting the growing need for efficient transportation solutions. The expansion of maritime RoRo and PCTC vehicle shipping networks accommodates the rising volume of vehicle trade. Growth in last-mile vehicle delivery and direct-to-customer logistics reflects changing consumer preferences and the need for timely delivery services.
Continued investment in port and terminal capacity expansion supports global vehicle trade, allowing for smoother operations and increased throughput. Vehicle storage and yard management have become critical logistics functions, necessitating advanced management systems to optimize space and enhance operational efficiency. Value-added vehicle processing services are gaining commercial importance, offering OEMs a competitive edge through enhanced service offerings.
The competitive landscape in the market is evolving with strategic partnerships expanding finished vehicle logistics network coverage. Automotive OEMs are increasing outsourcing of finished vehicle logistics to focus on core competencies while leveraging specialized service providers. This trend indicates a shift towards integrated vehicle logistics platforms that improve overall service delivery.
Asia Pacific is strengthening its role in global finished vehicle logistics, driven by significant investments in infrastructure and technology. Europe advances multimodal and rail-based finished vehicle distribution, optimizing logistics networks across the region. North America is expanding technology-enabled vehicle transportation networks, enhancing efficiency and responsiveness in logistics operations.
Digital vehicle-movement platforms emerge because critical tools in optimizing logistics processes. These platforms enhance communication and coordination among supply chain stakeholders, facilitating smoother operations and improved tracking of vehicle movements. With their integration into logistics workflows, companies enhance visibility, streamline operations, and respond promptly to market demands.
Real-time vehicle tracking and visibility gain strategic importance in the Finished Vehicles Logistics market. Companies leverage advanced tracking technologies to monitor vehicle locations and condition throughout the transportation process. This capability not only increases operational efficiency but builds customer trust through transparency in delivery timelines.
Pricing dynamics within vehicle logistics face pressures from various factors, including fuel costs, labor rates, and capacity constraints. The evolving landscape compels logistics providers to develop pricing strategies that reflect these challenges while remaining competitive. Companies that adapt pricing models effectively position themselves for sustained growth in the market.
Route and load optimization significantly impact efficiency across logistics operations. Advanced algorithms and AI-driven technologies enable logistics providers to analyze traffic patterns and vehicle capacities, resulting in improved delivery times and reduced operational costs. This optimization becomes essential in meeting the rising expectations of customers for timely deliveries.
Low-emission vehicle logistics emerge in response to growing environmental concerns. The market adapts to increasing regulations aimed at reducing carbon footprints, prompting logistics providers to adopt sustainable practices in vehicle transportation. This shift supports broader industry efforts toward sustainability and compliance with environmental standards.
Driver and transporter network models evolve to address challenges in workforce availability and capacity. Enhanced recruitment strategies, training programs, and incentive structures attract and retain skilled drivers, ensuring that logistics operations remain efficient and responsive to demand fluctuations.
Electric vehicle (EV) handling and charging requirements reshape logistics operations. Companies invest in infrastructure to accommodate the unique needs of EVs, including specialized charging stations and updated training for personnel. This adaptation reflects the market's commitment to supporting the transition toward electric mobility.
The Finished Vehicles Logistics market experiences growth driven by global automotive production trends. Increasing vehicle manufacturing activities across regions stimulate demand for efficient logistics solutions, prompting investments in transportation networks and service capabilities.
Rising demand for end-to-end finished vehicle transportation services highlights the importance of comprehensive logistics solutions. Customers increasingly seek integrated services that encompass every aspect of the supply chain, from production to delivery, enhancing overall satisfaction and operational efficiency.
Road vehicle carriers remain central to finished vehicle distribution. These carriers provide vital transportation services, ensuring timely delivery across various regions. Their role expands because logistics providers enhance fleet capabilities and optimize routes to meet customer expectations.
The expansion of maritime RoRo and PCTC vehicle shipping networks supports international trade. Enhanced shipping routes and terminal capabilities facilitate the movement of vehicles across borders, aligning with the growing needs of global automotive manufacturers and distributors.
Last-mile vehicle delivery and direct-to-customer logistics experience significant growth. The rise of e-commerce and changing consumer preferences drive logistics providers to develop efficient last-mile solutions, ensuring that vehicles reach customers promptly and reliably.
Digital vehicle movement platforms transform the logistics landscape. By centralizing data and facilitating communication, these platforms enable logistics providers to enhance operational performance and deliver superior customer experiences.
Real-time vehicle tracking and visibility play a crucial role in ensuring effective logistics management. Enhanced tracking capabilities contribute to improved operational efficiency and customer satisfaction, reinforcing their importance in the market.
AI-enabled route optimization improves vehicle logistics efficiency. By analyzing vast datasets, AI solutions identify optimal routes, reducing transit times and costs. This advancement positions logistics providers to respond swiftly to market demands.
EV adoption reshapes finished vehicle handling and transportation requirements. Logistics providers adapt to the unique characteristics of EVs, ensuring that infrastructure and processes align with the needs of this growing segment of the automotive market.
Port and terminal capacity expansion supports global vehicle trade. Enhanced facilities accommodate increasing volumes of vehicle shipments, facilitating smoother logistics operations and reducing congestion in critical transport hubs.
Vehicle storage and yard management become critical logistics functions. Efficient management of storage facilities and yard operations ensures timely processing of vehicles, supporting overall supply chain efficiency.
Value-added vehicle processing services gain commercial importance. Logistics providers expand their service offerings to include additional processing capabilities, enhancing value for customers and differentiating themselves in a competitive market.
Cross-border vehicle trade expands international logistics demand. While global trade increases, logistics providers strengthen their networks to accommodate the complexities of international vehicle transportation.
Automotive OEMs increase outsourcing of finished vehicle logistics. This trend allows manufacturers to focus on core competencies while leveraging the expertise of logistics providers to enhance efficiency and reduce operational costs.
Driver availability and transport capacity constraints affect vehicle movements. The logistics sector faces challenges in maintaining adequate driver resources, impacting overall supply chain performance and necessitating strategic workforce management.
Sustainable vehicle logistics accelerate low-emission transport adoption. Companies increasingly implement practices that reduce environmental impacts, aligning with regulatory requirements and consumer expectations for greener logistics solutions.
Finished vehicle logistics pricing reflects fuel, labor, and capacity pressures. Providers navigate these challenges while maintaining competitive pricing structures that meet customer needs in a dynamic market environment.
Asia Pacific strengthens its role in global finished vehicle logistics. Rapid economic growth and increasing automotive production in the region contribute to expanding logistics capabilities and infrastructure development.
Europe advances multimodal and rail-based finished vehicle distribution. This approach enhances efficiency and reduces environmental impacts, aligning with the region's sustainability goals and regulatory frameworks.
North America expands technology-enabled vehicle transportation networks. Investments in technology and infrastructure support the evolving needs of the logistics market, enhancing operational efficiency and service delivery.
Used vehicle and remarketing flows create new logistics opportunities. The growth of the used vehicle market prompts logistics providers to develop tailored solutions that address the specific needs of this segment.
Fleet, leasing, and rental vehicle movements support defleet logistics growth. Increased activity in these sectors drives demand for efficient logistics solutions, contributing to overall market expansion.
Competitive differentiation shifts toward integrated vehicle logistics platforms. Companies that offer comprehensive solutions stand out in a crowded market, attracting customers seeking streamlined logistics services.
Strategic partnerships expand finished vehicle logistics network coverage. Collaborations among logistics providers enhance service offerings and geographic reach, supporting the growing demand for efficient vehicle transportation.
Future growth opportunities in finished vehicle logistics through 2033 hinge on innovation and adaptability. Providers that embrace technology and sustainable practices position themselves for success in an evolving market environment.
Urbanization significantly influences the Finished Vehicles Logistics market by increasing demand for efficient transportation solutions. The growing population in urban areas necessitates streamlined logistics to meet rising consumer expectations for timely deliveries. This demographic shift promotes investment in advanced logistics frameworks, enhancing operational efficiency throughout the supply chain.
Investment in digital transformation strategies, including automation and software adoption, facilitates the optimization of logistics processes. Companies increasingly use technology to improve tracking, reduce transit times, and enhance overall service quality. The integration of these technologies enhances competitiveness in the market, addressing consumer demands for faster and more reliable vehicle delivery.
Focusing on operational productivity is critical in urban settings, where congestion and limited infrastructure present challenges. Companies adopt cost-efficiency initiatives to navigate these obstacles effectively. Streamlined operations lower overhead costs while maintaining high service levels in the Finished Vehicles Logistics market.
This environment creates opportunities for innovation in service offerings, enabling logistics providers to differentiate themselves. Advanced analytics and data-driven decision-making allow firms to respond swiftly to market changes, ensuring they meet evolving consumer preferences in urban areas. The emphasis on urbanization, combined with technological integration, positions the market for sustained growth through 2033.
Growth in the Finished Vehicles Logistics market correlates with increased capital investment in infrastructure development. Upgrading physical and digital capacities significantly enhances logistics operations, enabling firms to streamline their processes. Investments in modern facilities, network capabilities, and technological integration support better service delivery, reducing operational costs and improving efficiency.
Ongoing infrastructure projects involving transportation networks facilitate efficient vehicle movement. Enhanced roads, ports, and terminals contribute to reduced transit times and improved reliability, directly impacting customer satisfaction. These developments attract additional investments, creating a competitive environment in the market.
The relationship between infrastructure improvement and market access leads to broader service offerings. Firms equipped with advanced capabilities are more responsive to customer needs, driving demand for innovative logistics solutions. This dynamic contributes to the market's projected growth and encourages substantial investments in both existing and emerging logistics players.
The Finished Vehicles Logistics market experiences significant constraints due to regulatory tightening and compliance hurdles. Increasing demand for adherence to environmental standards imposes additional costs on logistics providers, discouraging investment in capacity expansion and efficiency improvements. This situation particularly affects smaller firms that struggle to meet stringent requirements while incurring substantial financial burdens.
Macroeconomic headwinds, including inflationary pressures and supply chain disruptions, contribute to operational challenges within the market. Rising costs of materials and labor negatively impact profitability, forcing companies to adjust pricing strategies. These adjustments reduce competitiveness, especially in a market where margins are already under pressure.
Geopolitical instability complicates logistics operations by introducing uncertainty and unpredictability in trade routes. Such factors lead to increased operational costs and delays, impeding the ability of logistics providers to maintain timely delivery schedules. Resulting inefficiencies hinder customer satisfaction and loyalty, ultimately impacting demand within the Finished Vehicles Logistics market.
High capital investment requirements for technology adoption and infrastructure improvements present additional restraints. Companies face challenges in allocating resources to upgrade existing systems and equipment, resulting in technological obsolescence. Without modernized capabilities, logistics providers risk losing their competitive edge and market share.
Market fragmentation and cultural barriers create further difficulties in achieving streamlined operations. Varied regulatory environments across regions complicate logistics strategies, making it challenging for providers to implement uniform practices. Consequently, the market faces significant barriers to achieving efficiency and scalability.
Talent gaps and skilled labor deficiencies exacerbate these challenges, leading to increased workforce overhead. Struggles to attract and retain qualified personnel impact operational performance, directly influencing the ability of firms to meet growing demand in the Finished Vehicles Logistics market.
Geopolitical fragmentation presents significant challenges for the Finished Vehicles Logistics market, introducing unpredictability in global trade dynamics. Heightened trade tensions and tariff friction create barriers to efficient logistics operations, leading to increased costs for manufacturers and logistics providers. This environment complicates supply chain strategies, forcing stakeholders to adapt to rapidly changing regulations and market conditions.
Logistics disruptions resulting from geopolitical instability weaken the reliability of transportation networks, impacting delivery timelines and operational efficiency. Market players face rising input costs due to supply chain instability, which directly affects profitability. Workforce skill gaps exacerbate these challenges, because companies struggle to find qualified personnel equipped to manage complex logistics scenarios effectively.
Technological disruptions further complicate the situation, with rapid advancements in logistics technology necessitating significant investments in research and development. Companies operating in the market navigate the intricacies of interoperability between emerging technologies and existing systems, which introduce delays and increase implementation costs. These factors contribute to an overall environment of pricing compression and margin pressures, highlighting the need for strategic adaptability.
Environmental sustainability demands intensify because stakeholders prioritize decarbonization mandates. Companies in the Finished Vehicles Logistics market face pressures to reduce their environmental footprint, which often requires retrofitting existing infrastructure and processes. Such initiatives involve substantial investments, creating additional operational challenges. Overall, the combination of geopolitical uncertainty, technological changes, and sustainability demands shapes a complex environment for the market, influencing future growth trajectories.
Growing regional demands significantly influence the Finished Vehicles Logistics market. Enhanced consumer preferences and economic growth in emerging markets, particularly in Asia Pacific and South America, drive expanded logistics services. Increased vehicle sales in these regions necessitate efficient logistics solutions, supporting growth opportunities for service providers.
Infrastructure modernization enhances logistics efficiency. Investments in transportation networks, including highways and ports, facilitate smoother vehicle movements and optimize logistics operations. This modernization supports demand for advanced logistics services in both domestic and international markets.
Technological disruptions contribute to the evolution of the market. Advancements in digital platforms and automated logistics solutions streamline processes, reduce costs, and improve service delivery. Adoption of these technologies enhances operational efficiency and strengthens competitive positioning among logistics providers.
Sustainability imperatives generate significant market opportunities. Increasing emphasis on environmentally friendly practices encourages logistics firms to adopt green transformations and align with ESG-driven strategies. This alignment attracts clients prioritizing sustainability, driving growth in the Finished Vehicles Logistics market.
Strategic consolidation through cross-industry mergers enhances market capabilities. M&A initiatives enable logistics providers to diversify service offerings and strengthen market presence. This diversification positions firms to effectively respond to the evolving needs of clients across various sectors.
Shifts in buying behaviors reflect evolving market dynamics. Digital procurement trends influence purchasing patterns, necessitating logistics firms to adapt their commercial models. Enhanced customer engagement through digital channels improves service accessibility and drives demand for logistics solutions.
The Global Finished Vehicles Logistics market is segmented based on Service Type, Transportation Mode, Vehicle Type, and Destination.
Valued at USD 69.4 billion in 2026, the Primary Transport segment is projected to reach USD 91.5 billion by 2033, exhibiting a CAGR of 4% during the forecast period. Demand for efficient logistics solutions drives this segment, with increasing vehicle production and sales worldwide requiring streamlined transportation processes. The ongoing shift towards electric vehicles, along with stricter regulations regarding emissions, influences logistics strategies and service offerings. Providers invest in advanced technologies like route optimization software and real-time tracking systems to enhance efficiency and reduce delays. These developments enhance reliability in delivery timelines, a crucial factor for manufacturers and dealerships in the Finished Vehicles Logistics market. The growing emphasis on sustainability and cost-efficiency shapes operational practices, compelling logistics providers to adopt eco-friendly transport options. Shifts in consumer behavior towards online vehicle purchases influence last-mile delivery requirements, pushing logistics firms to adapt their services accordingly. Market players face pressures from rising fuel costs and labor shortages, necessitating innovative solutions to maintain margins. Overall, the Primary Transport segment plays a critical role in ensuring the effective movement of finished vehicles, contributing significantly to the overall growth of the Finished Vehicles Logistics market.
Significant growth in the Secondary/Last-mile Distribution segment reflects increasing demand for efficient delivery solutions in the Finished Vehicles Logistics market. This segment is projected to reach USD 56.7 billion by 2033, at a CAGR of 5.2% during the forecast period. The rise in e-commerce and online vehicle sales drives the need for effective last-mile logistics, prompting investment in technology and infrastructure to support this growth.
Rapid urbanization and changing consumer preferences contribute to heightened expectations for timely deliveries, encouraging companies to enhance last-mile logistics capabilities. Increasing emphasis on sustainability and carbon footprint reduction influences the adoption of eco-friendly transportation solutions, stimulating innovation in this segment. New entrants and established players invest in advanced technologies, including route optimization software and electric vehicle fleets, to meet evolving consumer demands and regulatory requirements.
Supply chain resilience plays a critical role in shaping strategies within the market. Companies adapt to disruptions and enhance operational efficiencies. Strategic partnerships among logistics providers and vehicle manufacturers create synergies that improve service offerings and reduce costs. The growing focus on customer experience and satisfaction drives firms to explore new last-mile delivery models, enhancing competitive positioning.
Increasing reliance on global trade and cross-border transportation drives demand for Port & Terminal Services in the Finished Vehicles Logistics market. Efficient management of shipping logistics and customs clearance enhances operational effectiveness, attracting automotive manufacturers and logistics firms. This segment is projected to reach USD 29.2 billion by 2033.
Technological advancements, including automation and digital integration, contribute to segment growth by streamlining port operations and improving turnaround times. Enhanced data analytics enable better forecasting and inventory management, which are crucial for meeting fluctuating demand. Investment in next-gen upgrades creates competitive advantages in service delivery.
Regulatory compliance standards and environmental policies influence operational practices within port and terminal services. Adhering to these standards incurs costs but opens opportunities for investment in sustainable technologies. Companies focusing on sustainability position themselves favorably in an increasingly eco-conscious market.
Pricing volatility and margin pressures in the sector remain a concern, primarily driven by fluctuating fuel prices and changing tariffs. Strategic opportunity windows arise for providers who adapt to these challenges through innovative solutions and flexible pricing strategies. The segment's resilience against supply chain vulnerabilities enhances its attractiveness to investors.
Investment in the Storage & Yard Management segment of the Finished Vehicles Logistics market emphasizes the necessity for efficient space utilization and management of vehicle inventory. The growing complexity of vehicle handling operations drives demand for robust storage solutions that enhance the organization and accessibility of vehicles. Technological advancements in automation and data analytics facilitate streamlined operations, ensuring timely inventory updates and optimal space allocation.
Increased demand for just-in-time delivery influences market growth, pushing companies to adopt advanced yard management systems. These systems improve operational efficiency by reducing manual handling and optimizing vehicle flow within storage areas. The segment is projected to grow at a CAGR of 4% during the forecast period. Market players focus on implementing technologies that enable real-time monitoring and tracking of vehicles, reducing delays while improving service quality.
Shifting consumer preferences towards faster and more reliable delivery services compel logistics providers to enhance their storage and yard management capabilities. Investments in infrastructure and advanced management solutions create opportunities for growth, enabling market participants to respond effectively to evolving demand dynamics. The ongoing evolution of regulations surrounding vehicle storage practices further shapes operational standards, ensuring compliance and safety within the market.
Strategic collaborations among industry players drive innovation in storage and yard management solutions. Leveraging shared expertise enables companies to improve their competitive positioning while meeting emerging consumer expectations. Overall, the Storage & Yard Management segment continues to adapt to changing market conditions, highlighting its critical role in the broader Finished Vehicles Logistics market.
Value-added Services within the Finished Vehicles Logistics market encompasses a range of offerings that enhance the overall customer experience and operational efficiency. Drivers for this segment include increasing consumer expectations for customized services and the need for companies to differentiate themselves in a competitive environment. Enhanced tracking and monitoring capabilities, along with real-time communication, represent key advancements in this area, leading to improved service delivery.
Adoption of value-added services is propelled by technological maturation. Logistics providers integrate advanced software solutions and data analytics into their operations. Investments in next-generation upgrade capabilities support service enhancement, enabling companies to offer tailored solutions that address specific customer needs. These developments align with evolving end-use dynamics, where businesses increasingly seek comprehensive logistics solutions that encompass not just transportation but additional services including inventory management and compliance handling.
This segment experiences pressure from cost structures tied to service innovation and delivery. Companies balance these costs while maintaining competitive pricing strategies to attract customers. Regulatory compliance standards impact the segment, necessitating adherence to stringent guidelines that govern logistics practices, particularly concerning safety and environmental impacts.
Despite these challenges, strategic opportunity windows exist, particularly for firms that invest in automation and technology-driven solutions. Enhanced supply chain resilience becomes critical. Disruptions in logistics significantly affect service delivery and customer satisfaction. Companies that successfully navigate these complexities secure a competitive advantage in the Finished Vehicles Logistics market.
Valued at USD 71.3 billion in 2026, the Road Vehicle Carrier segment is projected to reach USD 93.4 billion by 2033, at a CAGR of 3.9% during the forecast period. Increasing demand for efficient transportation solutions drives growth in this segment, driven by automakers prioritizing timely delivery and cost-effective logistics. The expanding automotive sector, particularly in emerging markets, contributes to rising vehicle production and sales, necessitating robust logistics solutions.
Technological advancements play a critical role in enhancing operational efficiency within the market. Innovations in tracking systems, route optimization software, and vehicle maintenance technologies improve service reliability and reduce operating costs. While firms adopt advanced analytics and real-time monitoring, the capability to streamline operations and respond to challenges increases, enhancing market growth.
Shifting consumer preferences toward online vehicle purchasing further influences the Road Vehicle Carrier segment. This trend enhances demand for reliable last-mile delivery solutions, requiring logistics players to adapt swiftly to evolving customer expectations. Regulatory compliance regarding emissions and safety standards necessitates significant investments in fleet upgrades, directly impacting operational costs and pricing strategies.
Supply chain resilience becomes increasingly vital, particularly in the context of disruptions caused by global events. Firms enhance their logistics networks to mitigate risks associated with sourcing and transportation. The ongoing shift towards sustainable practices, including the use of eco-friendly vehicles and technologies, shapes the competitive landscape of the market. Strategic opportunity windows will emerge because companies align with sustainability goals while striving to improve margins during pricing volatility.
The integration of innovative solutions, combined with a focus on environmental compliance, positions the Road Vehicle Carrier segment for sustained growth. Firms that capitalize on next-generation upgrades while addressing logistical vulnerabilities will likely seize a competitive advantage in the Finished Vehicles Logistics market.
Growing interest in the Driven / Driveaway Movement segment reflects a shift toward efficient vehicle transportation solutions. This trend emerges from the increasing need for flexible logistics options, driven by the rise of e-commerce and changing consumer preferences. Companies seek to optimize delivery times and reduce operational costs, enhancing the attractiveness of driveaway services. The evolution of technology supports this segment's expansion, with advancements in tracking and logistics management streamlining operations. The Driven / Driveaway Movement segment is projected to reach USD 39.9 billion by 2033, at a CAGR of 5.5% during the forecast period. This growth signals robust demand for specialized transportation solutions, catering to both domestic and international markets. The Finished Vehicles Logistics market experiences heightened competition because players invest in innovative service offerings and infrastructure to capture market share. Addressing regulatory compliance and safety standards remains crucial for companies operating within this sub-segment, impacting their operational costs and service delivery timelines.
Recent trends in the Finished Vehicles Logistics market show a growing preference for the Rail transportation mode, driven by environmental considerations and cost efficiency. Rail offers a sustainable alternative to road transport, significantly reducing carbon emissions associated with vehicle logistics. Adoption of rail transport aligns with regulatory compliance standards that increasingly emphasize sustainability.
Investment in rail infrastructure contributes to segment expansion, allowing for increased capacity and improved efficiency in vehicle transport. This investment signals confidence in the long-term viability of rail logistics, enhancing supply chain resilience across the market. Enhanced rail networks facilitate more reliable logistics solutions, positioning rail because a key player in the overall Finished Vehicles Logistics market.
Technological maturation in rail systems, including advanced tracking and automated logistics solutions, supports operational efficiency. These next-gen upgrades improve service delivery and contribute to cost reductions that positively impact profit margins. Efficient rail logistics provide a competitive edge in the market, appealing to businesses seeking reliable and cost-effective solutions.
Valued at USD 30.5 billion by 2033, the rail segment reflects a strategic opportunity window for logistics players. A focus on optimizing rail transport addresses ongoing shifts in consumption patterns, particularly because consumers and businesses prioritize sustainable practices. This demand for greener logistics solutions will influence investment decisions and operational strategies in the market.
Growth in the Maritime RoRo / PCTC segment aligns with the increasing need for efficient maritime transportation solutions within the Finished Vehicles Logistics market. Companies prioritize this mode for its ability to accommodate a wide range of vehicle types and ensure secure handling during transit. The projected CAGR of 4.2% during the forecast period reflects strong demand driven by rising international trade and the continuous expansion of automotive manufacturing.
The evolution of shipping technologies facilitates enhanced operational efficiency and cost control. Investment in next-generation vessels equipped with advanced safety features and sustainability measures supports competitive positioning among maritime logistics providers. Regulatory compliance related to environmental standards drives innovation in cleaner and more efficient shipping methods, further driving market growth.
Pricing volatility in fuel costs influences profitability within this segment, necessitating strategic management of operational expenses. The market benefits from increased supply chain resilience attributed to logistics providers investing in diversified shipping routes and partnerships. This approach mitigates risks posed by disruptions in global trade and enhances overall service reliability.
Investment in infrastructure development, including ports and terminals, supports an efficient flow of goods, impacting the overall dynamics of the Finished Vehicles Logistics market. The adoption of digital tracking solutions and data analytics improves visibility across the supply chain, leading to better decision-making and enhanced customer satisfaction.
Inland waterway transportation offers a unique approach within the Finished Vehicles Logistics market, leveraging waterways to enhance the distribution of vehicles. Factors driving demand include environmental considerations and cost-effectiveness, prompting industries to explore sustainable transportation methods. The fluid nature of waterways enables flexible routing options, which positively impacts logistics efficiency.
Technological advancements in vessel design and navigation systems further contribute to segment expansion. Enhanced operational capabilities allow for quicker and safer transport of vehicles, meeting rising consumer expectations for delivery timelines. While industries adapt to evolving market conditions, the integration of advanced technologies positions the inland waterway segment favorably for growth.
Shifts toward domestic production and consumption patterns influence demand dynamics. Industries focusing on local sourcing and distribution benefit from the reduced congestion often experienced on road networks. This aspect enhances the market's resilience, supporting key stakeholders in optimizing their supply chains.
Regulatory compliance significantly shapes the inland waterway segment. Increasingly stringent environmental regulations compel logistics providers to pursue greener alternatives, positioning waterway transportation because a viable option. Adopting eco-friendly practices and technologies contributes to meeting regulatory demands while improving operational performance.
Investment in infrastructure is critical for realizing the full potential of the inland waterway segment. Strategic development of ports, terminals, and related facilities facilitates the efficient movement of vehicles. This infrastructure strengthens the market's overall effectiveness, supporting various stakeholders in addressing logistics vulnerabilities and enhancing delivery capabilities.
Air and Specialist Transport within the Finished Vehicles Logistics market ensures the efficient movement of vehicles, especially in scenarios where road transport is not feasible. Increasing demand for expedited delivery methods drives adoption, benefiting sectors that require rapid shipping solutions, including luxury and specialty vehicle manufacturers. The segment positions itself because a critical component for firms focused on maintaining competitive edge through timely delivery.
Advancements in technology enhance operational efficiency within this segment, enabling firms to implement more precise tracking and handling procedures. The incorporation of state-of-the-art logistics solutions results in improved service quality, attracting clients who prioritize reliability and speed in their supply chains. This focus on technological maturation fuels competitive advantages, pushing firms to innovate further.
The regulatory landscape impacts operational practices, with compliance to international transport standards becoming increasingly stringent. Firms that align their processes with these regulations benefit from enhanced credibility in the market. Strategic partnerships with certification bodies ensure that service providers maintain high standards, building trust among consumers and stakeholders alike.
Pricing volatility presents challenges to firms engaged in Air and Specialist Transport, influenced by fluctuating fuel costs and geopolitical tensions. These factors create margin pressures that necessitate agile pricing strategies, which adapt to market conditions while sustaining profitability. Flexibility in pricing models allows companies to navigate these challenges effectively.
Supply chain resilience remains a critical concern, with firms focusing on mitigating logistics vulnerabilities. Establishing diversified transportation routes and alternative supplier partnerships enhances security against disruptions. This proactive approach captures strategic opportunity windows while reinforcing the market position of service providers in Air and Specialist Transport.
Valued at USD 92.5 billion in 2026, the Passenger Cars segment is projected to reach USD 122.6 billion by 2033, at a CAGR of 4.1% during the forecast period. Several factors drive growth in this segment, including rising consumer preference for personal vehicles and increasing disposable income levels across various regions. The ongoing transition towards electric vehicles (EVs) fuels demand, supported by government incentives and consumer awareness of environmental sustainability.
Technological advancements play a crucial role in shaping the Passenger Cars segment, particularly through innovations in autonomous driving, connectivity, and safety features. Automakers invest heavily in next-gen technologies, enhancing value propositions and attracting tech-savvy consumers. The integration of smart technologies transforms vehicle usage, leading to shifts in consumer behavior and expectations, influencing logistics strategies within the market.
Regulatory compliance standards significantly impact vehicle production and logistics operations, necessitating adherence to emissions regulations and safety certifications. Manufacturers adopting eco-friendly practices and efficient supply chain management strategies gain competitive advantages, meeting evolving consumer demands while ensuring compliance with stringent regulations. This aspect enhances the overall resilience of the market, positioning it well for future growth.
Pricing volatility and margin pressures challenge the Passenger Cars segment, influenced by fluctuating raw material costs and supply chain vulnerabilities. Strategic opportunity windows emerge for players navigating these challenges effectively, focusing on supply chain optimization and cost-efficient logistics solutions. This adaptability strengthens the market's capacity to respond to disruptions while maintaining profitability.
Investment in the Passenger Cars segment continues to rise, with stakeholders recognizing the potential for long-term returns driven by sustained consumer interest and evolving market dynamics. The Finished Vehicles Logistics market is projected to expand significantly, driven by continuous innovation and strategic investments within the segment.
Growth within the Light Commercial Vehicles segment reflects increasing demand for efficient transport solutions across various industries. Factors driving this demand include the expansion of e-commerce and the need for last-mile delivery services, which require reliable and versatile vehicles. Technological advancements in vehicle design and fuel efficiency enhance the segment's appeal, enabling businesses to improve operational efficiency while minimizing costs.
Investment in infrastructure and logistics capabilities supports segment expansion, directly impacting the Finished Vehicles Logistics market. Regulatory compliance with emissions standards influences vehicle production, prompting manufacturers to innovate within this segment. Shifts in consumer preferences towards greener and more fuel-efficient options further stimulate growth.
The segment is projected to reach USD 45.8 billion by 2033, with a CAGR of 5.1% during the forecast period. Companies within the market face margin pressures due to fluctuating raw material costs, prompting them to streamline operations and adopt cost-effective solutions. Strategic opportunities arise from investments in next-generation vehicle technologies, positioning players to capture market share effectively.
Increasing demand for efficient transportation and logistics solutions drives growth in the Medium and Heavy Commercial Vehicles segment. This growth results from rising e-commerce activities and the expansion of various industries relying on freight transport. The market for these vehicles is expected to reach USD 35.2 billion by 2033, reflecting a significant need for robust logistics capabilities.
Technological advancements play a crucial role in this segment. The shift towards automation and electrification in vehicle design influences market dynamics, encouraging adoption of next-generation upgrades. Manufacturers focusing on improving fuel efficiency and reducing emissions respond to regulatory compliance standards, promoting an environmentally friendly approach in the logistics sector.
End-use dynamics demonstrate a shift towards increased utilization of medium and heavy commercial vehicles in construction, retail, and food distribution. This trend highlights how diverse applications within the finished vehicles logistics market contribute to a sustainable growth trajectory. The emphasis on supply chain resilience and effective raw material sourcing enhances the operational efficiency of logistics providers.
Pricing volatility remains a concern, with fluctuating fuel prices impacting operational margins in this segment. Strategic opportunity windows arise from the need for enhanced logistics solutions, encouraging investments in infrastructure and technology. Addressing these challenges positions stakeholders favorably within the evolving market.
In the Finished Vehicles Logistics market, the Two-Wheelers segment reflects significant growth potential. Primary demand drivers include increasing urbanization and rising environmental concerns, which drive consumers towards more sustainable transportation options. This shift fuels adoption of two-wheelers, driven by a cost-effective and efficient mode of transport, particularly in densely populated areas.
Segment expansion catalysts encompass technological maturation, with advancements in electric two-wheelers enhancing appeal among environmentally conscious consumers. Manufacturers increasingly invest in next-gen upgrades, focusing on battery technology and smart features that improve user experience. These innovations contribute to evolving product offerings, aligning with changing consumer preferences and enhancing market attractiveness.
Downstream applications highlight the versatility of two-wheelers in logistics, facilitating last-mile delivery services and personal mobility solutions. Regulatory compliance standards addressing emissions and safety will influence market dynamics, driving manufacturers to adapt to stringent requirements. Pricing volatility and margin pressures specific to the segment result from fluctuating raw material costs, impacting overall profitability.
While the segment is projected to grow at a CAGR of 4.2% during the forecast period, strategic opportunity windows emerge for companies to capitalize on shifting consumption patterns. Supply chain resilience becomes crucial, with logistics vulnerabilities demanding attention from industry players. In this competitive environment, effective raw material sourcing and management practices will enhance operational efficiency and support growth.
Investment in this segment remains robust, with stakeholders recognizing the long-term benefits of two-wheelers in the evolving transportation ecosystem. Disruptive alternatives, including shared mobility platforms, present both challenges and opportunities, encouraging continuous innovation. The outlook for the Two-Wheelers segment within the Finished Vehicles Logistics market remains positive, driven by consumer trends and technological advancements.
Increasing interest in specialty and performance vehicles drives demand within the Finished Vehicles Logistics market. This segment captures attention due to its association with high-value assets and a dedicated consumer base seeking unique features and enhanced performance. The growing trend toward customization, alongside rising disposable incomes, fuels demand for these specialized vehicles.
Technological maturation plays a critical role in segment expansion. Advancements in manufacturing processes and materials enhance the capabilities of specialty vehicles, allowing for more efficient production and better performance. Adoption of next-generation upgrades focuses on integrating smart technologies, attracting tech-savvy consumers seeking enhanced connectivity and user experiences.
Downstream applications of specialty and performance vehicles extend beyond personal use. These vehicles find utility in various sectors, including motorsports, luxury services, and promotional events, increasing the segment's appeal. The regulatory landscape influences design and production processes, necessitating compliance with stringent safety and environmental standards, impacting cost structures and pricing strategies.
Cost pressures related to raw material sourcing and production challenge market players. Fluctuations in material prices affect profit margins, while logistics vulnerabilities impact timely delivery and inventory management. Strategic opportunity windows arise from consumer trends favoring sustainable practices, prompting manufacturers to adopt eco-friendly technologies and production methods.
Investment in research and development remains crucial for maintaining a competitive edge within this segment. Companies explore innovative solutions to address substitution risks and disruptive alternatives in the automotive industry. Shifts in consumer preferences toward electric and hybrid vehicles reshape the landscape, prompting manufacturers to pivot their offerings and strategies accordingly.
Valued at USD 102.4 billion in 2026, the Domestic segment reaches USD 136.1 billion by 2033, at a CAGR of 4.1% during the forecast period. Increased consumer demand for personal and commercial vehicles drives growth in this segment. The expansion of e-commerce and the need for efficient delivery systems contribute to heightened logistics activities within domestic markets. Investment in technology to enhance operational efficiency aligns with rising expectations for quick and reliable vehicle deliveries.
Regulatory compliance and environmental considerations influence market dynamics, prompting businesses to adopt sustainable practices. Cost structures reflect pressures associated with rising fuel prices and labor costs, impacting overall profitability. Strategic opportunities emerge because companies seek innovative solutions to streamline logistics processes, emphasizing the importance of adaptability in meeting shifting consumer preferences.
Technological advancements play a critical role in transforming domestic logistics, with automation and digitalization enhancing efficiency. The market experiences a notable shift toward data-driven decision-making, enabling companies to optimize their supply chain operations. While competition intensifies, businesses that leverage next-gen technologies will capture larger market shares, further propelling the growth of the Finished Vehicles Logistics market.
International market demand for finished vehicles logistics is estimated to reach USD 87.7 billion by 2033, at a CAGR of 5% during the forecast period. This growth results from increasing globalization and the expansion of international trade, which compels manufacturers and distributors to seek efficient logistics solutions across borders. Evolving automotive markets require logistics service providers to adapt to diverse regulatory environments and varying compliance standards in different countries. This landscape encourages innovations in tracking technologies and documentation processes that streamline cross-border transportation.
The rise in e-commerce and online vehicle sales significantly influences the international logistics segment. Consumers increasingly prefer purchasing vehicles remotely, necessitating robust logistics frameworks for delivery. This shift emphasizes the need for enhanced supply chain resilience and faster response times, driving investment in technological advancements and process optimization. Logistics vulnerabilities, including port congestion and changing tariffs, critically affect operational efficiency and cost structures. Companies in the market actively seek opportunities to enhance competitive positions through strategic collaborations and investments in next-generation logistics solutions.
Based on geography, the Global Finished Vehicles Logistics market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America presents a robust environment for the Finished Vehicles Logistics market, driven by a combination of strategic regional characteristics and evolving consumer demands. Historical growth trends indicate a significant uptrend, with a market size projected to reach USD 63.3 billion by the end of 2033, reflecting a CAGR of 4.5% during the forecast period.
The market's development hinges on several primary demand drivers, including the increasing adoption of advanced logistics technologies and the rising complexity of supply chains. This evolution enhances operational efficiency and boosts service delivery, aligning with the region's strong automotive manufacturing base. The United States, Canada, and Mexico lead the charge, demonstrating a mature market dynamic characterized by high-value replacement cycles and incremental growth vectors.
Infrastructure modernization acts because a catalyst for segment expansion, with investments in transportation networks and distribution systems facilitating improved logistics capabilities. Cross-border trade corridors between the United States, Canada, and Mexico create an integrated logistics environment, enhancing trade efficiencies and reducing transit times. The emphasis on localized manufacturing densities and supply chain regionalization supports the market's resilience against global disruptions.
Geopolitical factors contribute to market dynamics, influencing trade policies and compliance mandates that shape operational frameworks across borders. Domestic market leaders leverage these conditions to strengthen their competitive position, while ongoing vendor consolidation trends improve resource allocation and operational efficiencies within the market.
Regional resource availability, energy grid resiliency, and local infrastructure readiness play crucial roles in determining the market's growth trajectory. Strategic entry barriers and foreign direct investment flows further influence the competitive landscape, enabling companies to capitalize on geographic expansion windows and local procurement dynamics. The evolving B2B buying behaviors reflect cultural nuances that shape procurement strategies, ultimately driving demand within the Finished Vehicles Logistics market.
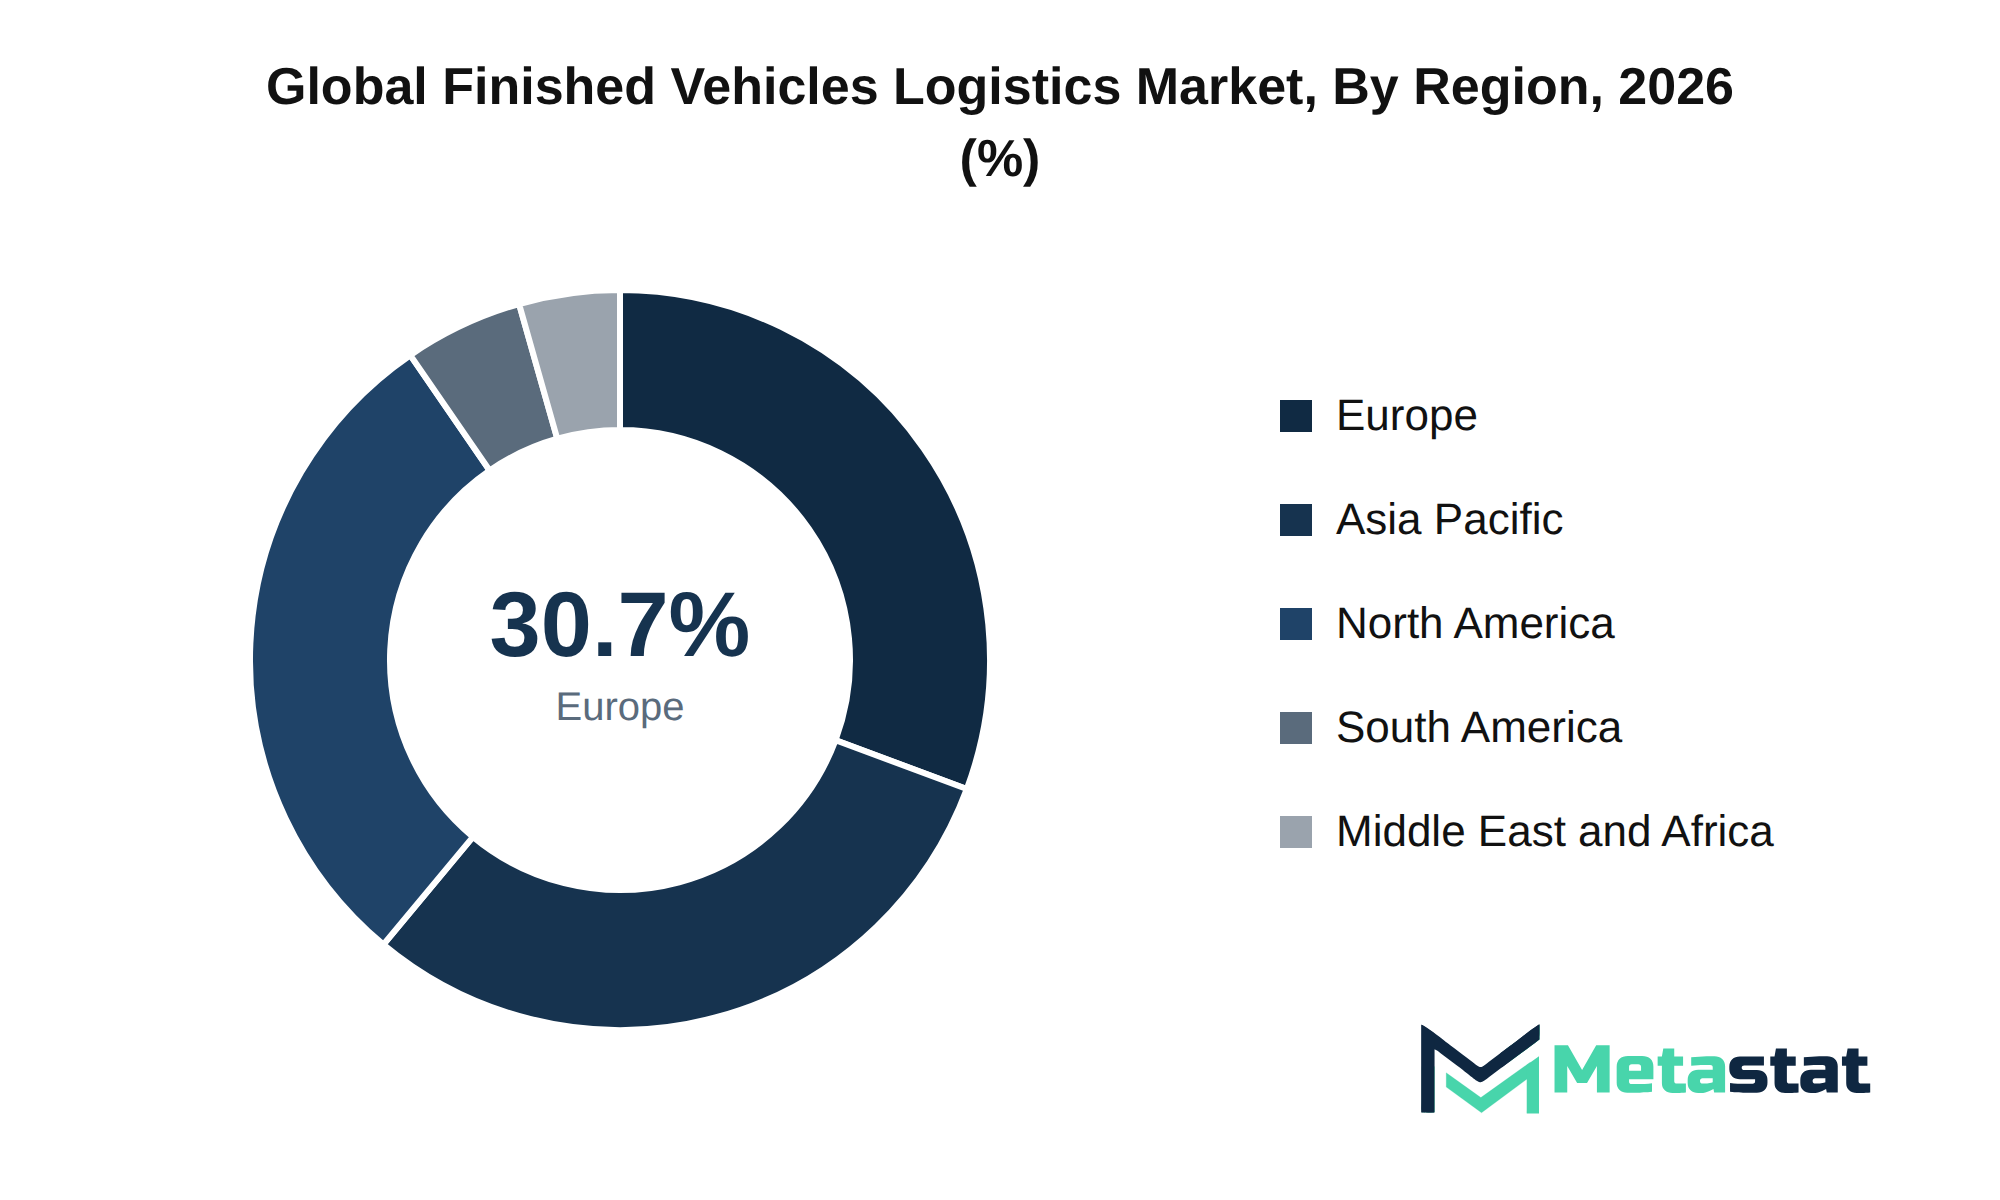
The Finished Vehicles Logistics market in Europe represents 30.7% of the global market in 2025. Key countries contributing to this market include Germany, France, the UK, Italy, Spain, and Russia. Demand for logistics services in this region is driven by the growing automotive industry and the need for efficient supply chain management. Infrastructure modernization initiatives across Europe enhance the capacity for transportation and logistics solutions, facilitating the movement of finished vehicles.
Regional market participants leverage advanced technologies and optimized logistics networks to enhance operational efficiency. Established companies adapt to evolving customer preferences, pushing for innovations that streamline processes and improve service offerings. The segment experiences growth through high-value replacement cycles, with established automotive manufacturers investing heavily in logistics capabilities to maintain a competitive edge.
Localized procurement dynamics influence sourcing strategies, with companies emphasizing domestic suppliers to reduce lead times and improve flexibility. Cultural nuances shape B2B buying behaviors, with European customers displaying a preference for reliable and sustainable logistics partners. Geopolitical fragmentation impacts cross-border trade, prompting firms to reassess trade corridors and adapt to shifting regulations.
Energy grid resiliency and local infrastructure readiness play crucial roles in the overall market, impacting the efficiency of logistics operations. The commitment to sustainability and emissions reduction influences investment in greener transportation methods. Overall, the Finished Vehicles Logistics market in Europe anticipates steady growth, driven by regional competitive landscapes and ongoing investments in infrastructure and technology.
The Asia-Pacific region accounts for 30.4% of the Finished Vehicles Logistics market in 2025. Rapid industrialization and urbanization in countries including China, India, and South Korea drive demand for effective logistics solutions. The increasing volume of finished vehicles produced and consumed necessitates enhanced logistical capabilities, especially in urban areas, where last-mile deliveries play a crucial role.
Investment in infrastructure modernization supports expansion within the market. Governments in the region prioritize the development of transportation networks, facilitating smoother logistics operations and cross-border trade. Enhanced connectivity through rail and road networks, along with port upgrades, aids in meeting growing consumer demands and enhances operational efficiency.
Emerging market front-runners in the region, particularly China and India, present strong growth prospects due to their expanding automotive industries. This growth creates opportunities for logistics providers specializing in primary transport and last-mile distribution. Regional players focus on localized manufacturing densities to streamline supply chains and reduce transportation costs, further enhancing competitive advantages.
Geopolitical fragmentation influences market dynamics, leading to localized procurement strategies. Companies adopt nearshoring initiatives to mitigate risks associated with international supply chains. This shift results in an increased focus on regional partnerships and vendor consolidation within the logistics sector, allowing for improved responsiveness to market demands.
Cultural nuances shape regional B2B buying behaviors, necessitating tailored approaches by logistics providers. Understanding local preferences and practices enables firms to build strong relationships with clients, driving market share growth. Energy grid resiliency and resource availability factor into operational strategies, ensuring logistics providers maintain efficiency and reliability in their services.
The potential for incremental growth vectors exists through technological advancements and automation in logistics operations. Investment in digital solutions enhances transparency and efficiency within the supply chain, shaping the future of the market. These developments not only address current challenges but position firms to capitalize on upcoming opportunities in the Finished Vehicles Logistics market.
The Finished Vehicles Logistics market in South America experiences distinct dynamics influenced by local economic factors and market infrastructure developments. Brazil and Argentina represent the primary markets within this region, characterized by growing demand for efficient logistics solutions to support vehicle distribution. Infrastructure modernization efforts in these countries facilitate improved transportation networks, enhancing the movement of finished vehicles through various modes, including road and rail.
The market holds a notable share of the global landscape in 2025, with emerging trends in localized manufacturing and regional procurement strategies contributing to the evolution of domestic supply chains. Investment in cross-border trade corridors aims to improve trade efficiency, allowing for increased vehicle movement between neighboring countries. The expansion of these corridors aligns with regional economic integration efforts, enhancing collaboration and improving logistics capabilities.
Vendor consolidation trends within the South American market promote competitive advantages for leading logistics providers. Domestic market participants invest in developing localized solutions tailored to the unique needs of Brazilian and Argentine customers. These strategies improve service delivery and address cultural nuances in regional B2B buying behaviors, influencing operational efficiencies across the market.
The Finished Vehicles Logistics market in South America demonstrates growth potential through strategic investments in infrastructure, regional collaboration, and tailored logistics solutions. Ongoing developments present opportunities for market players to leverage localized dynamics and enhance their competitive positioning within this evolving market.
The Middle East and Africa region holds a share of 4.4% of the global Finished Vehicles Logistics market in 2025. Rapid urbanization and population growth in countries including Saudi Arabia and the UAE drive demand for efficient logistical solutions. Infrastructure modernization initiatives within these nations enhance connectivity, facilitating more efficient distribution channels. Supply chain regionalization trends encourage local manufacturing and procurement, contributing to market development. These dynamics support the emergence of domestic players competing effectively in the market.
Significant investments in logistics infrastructure create opportunities for expansion in previously underpenetrated territories. Countries including South Africa exhibit potential growth vectors through improved cross-border trade corridors. Local compliance mandates and regulatory frameworks influence operational standards, impacting how companies engage in the market. Cultural nuances and regional B2B buying behaviors shape procurement strategies, necessitating tailored approaches from service providers.
Geographic expansion windows arise from foreign direct investment flows, which enhance logistics capabilities in the region. Increased focus on localized manufacturing and nearshoring initiatives serves to enhance the resiliency of supply chains. The market experiences evolving competitive landscapes driven by domestic leaders consolidating their positions while navigating geopolitical fragmentation and tariff impacts. Overall, the Middle East and Africa represent a landscape of opportunities driven by strategic investments and unique market dynamics.
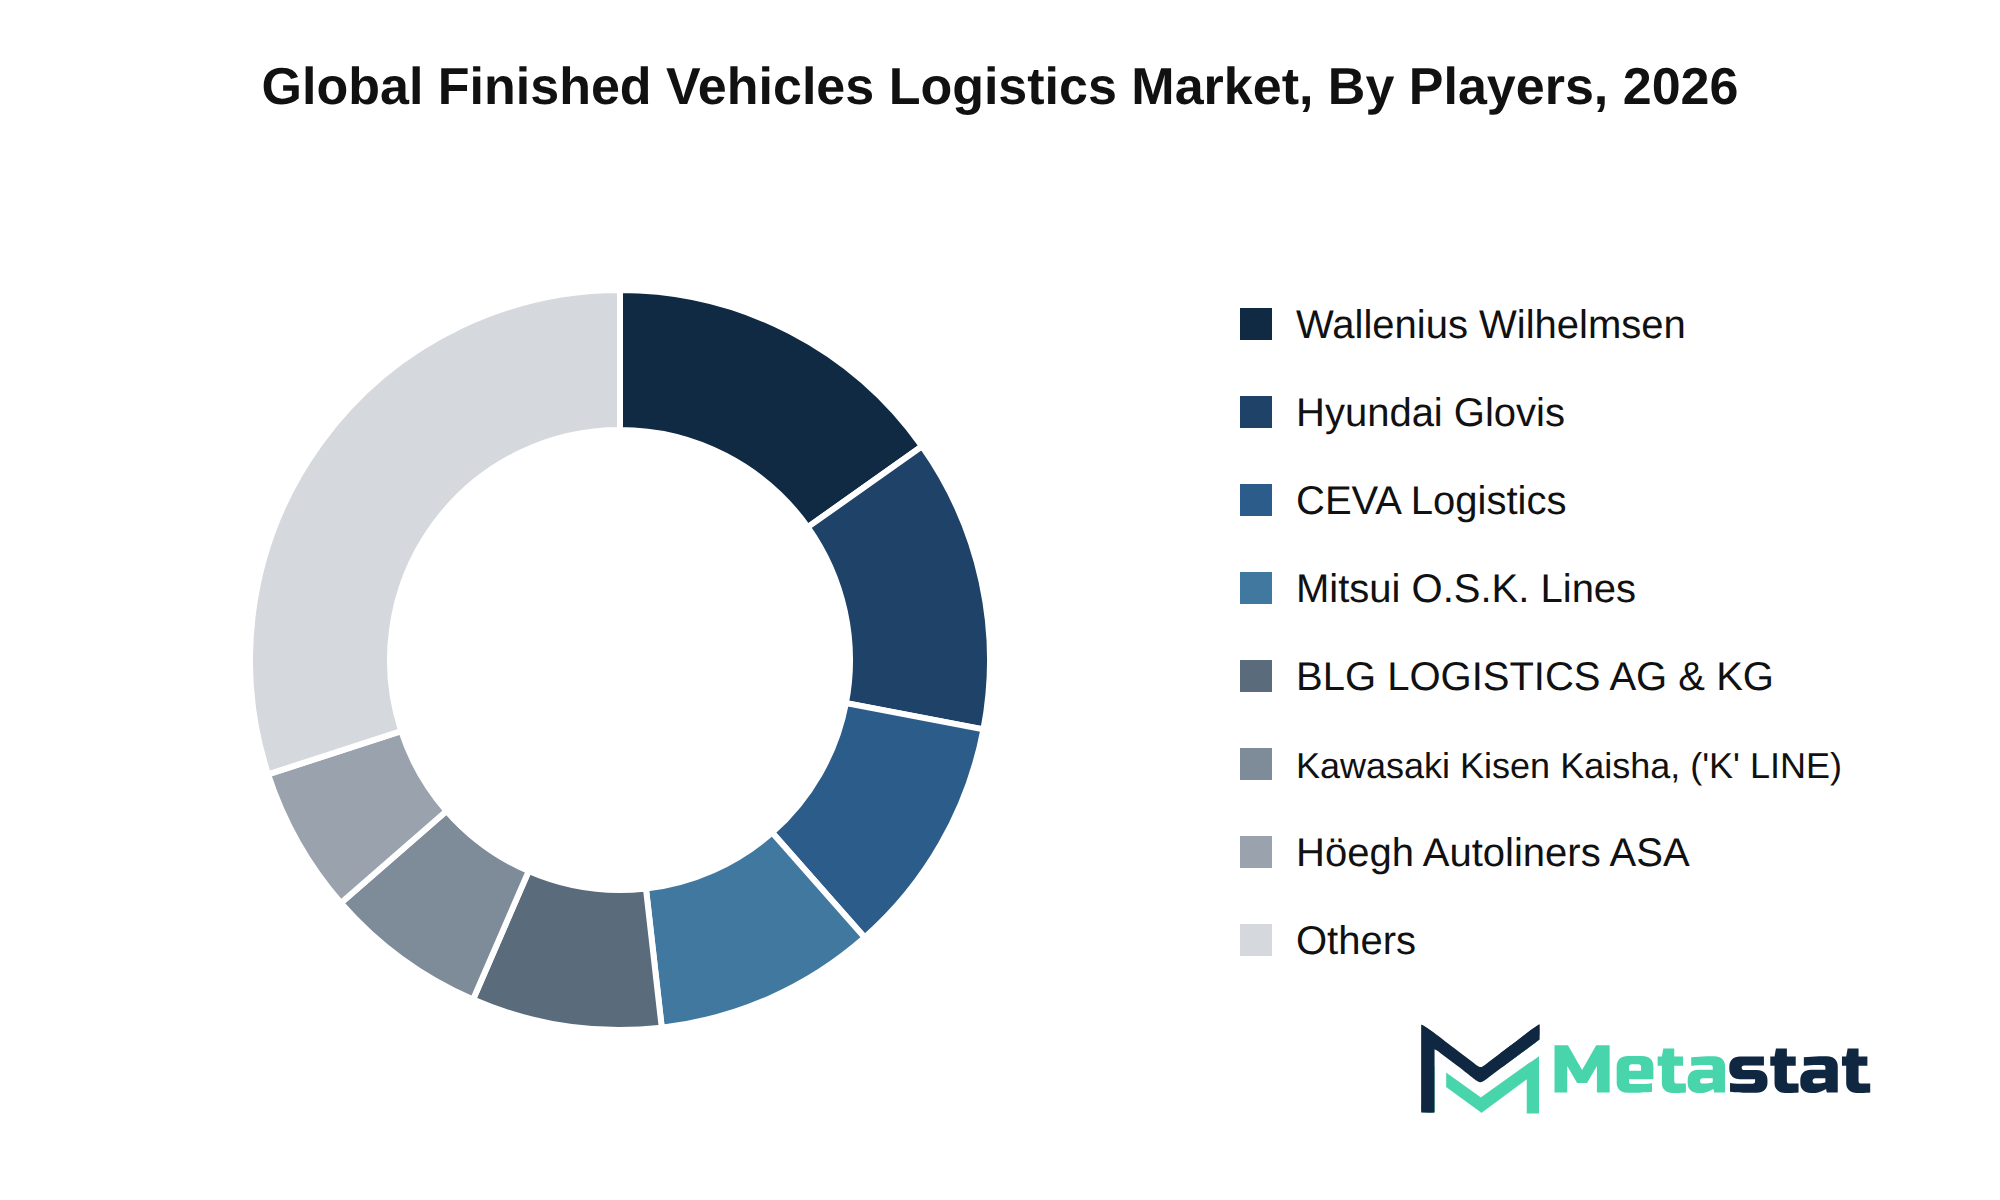
The Finished Vehicles Logistics market experiences significant activity through mergers, acquisitions, and strategic consolidation. Major players including Wallenius Wilhelmsen, CEVA Logistics, and Hyundai Glovis Co., Ltd. engage in partnerships and joint ventures to enhance market presence and expand service offerings. Companies leverage strengths in supply chain dominance and procurement leverage to create barriers to entry for potential new entrants.
Competition within the Finished Vehicles Logistics market drives continuous innovation and differentiation in services. Companies like Mitsui O.S.K. Lines, Ltd. and BLG LOGISTICS GROUP AG & Co. KG focus on product differentiation and proprietary technology to strengthen market position. The growing emphasis on customer retention strategies and brand equity influences how firms navigate the competitive landscape. The future competitive outlook highlights strategic growth vectors, emphasizing enhanced operational efficiencies and expanded geographic reach.
Market size is forecast to rise from USD 157.4 billion in 2025 to over USD 223.7 billion by 2033. This growth reflects a robust 4.5% CAGR, driven by several macroeconomic factors affecting the Finished Vehicles Logistics market. Economic cycles influence demand patterns, with periods of economic expansion typically resulting in higher vehicle production and distribution activities. Conversely, economic downturns lead to reduced demand for logistics services, impacting revenue growth.
Structural shifts in consumer behavior toward e-commerce and online vehicle purchasing models continue to reshape logistics requirements. Increased reliance on technology integration enhances operational efficiencies, influencing market dynamics. The introduction of next-generation technologies, including automation and real-time tracking systems, supports demand by improving service delivery and reducing operational costs.
Regulatory evolution plays a critical role in shaping the logistics landscape. Compliance milestones, particularly related to environmental standards and safety regulations, affect operational practices. Companies investing in compliance face increased initial costs but benefit from improved market positioning and consumer trust.
Geopolitical realignments and evolving trade corridors reshape supply chain strategies. Logistics providers adapt to new trade agreements and tariffs, which significantly influence operational frameworks. Strategic capital allocation is essential for addressing emerging white-space opportunities, particularly in underserved regions, allowing for expansion into high-growth pockets within the market.
Investment in infrastructure and capital expenditures remains vital for supporting future growth. Commitment to improving logistics networks enhances service capacity and responsiveness, meeting increasing demand from diversified vehicle types and distribution channels. Executives focus on defensibility roadmaps, ensuring alignment with industry trends and consumer expectations while continuously adapting to market shifts.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Finished Vehicles Logistics market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 4.5% from 2026 to 2033 |
Revenue Unit | USD billion |
Segmentation | By Service Type, Transportation Mode, Vehicle Type, Destination, and Region |
By Region | North America (By Service Type, Transportation Mode, Vehicle Type, Destination, and Country)
|
Europe (By Service Type, Transportation Mode, Vehicle Type, Destination, and Country)
| |
Asia Pacific (By Service Type, Transportation Mode, Vehicle Type, Destination, and Country)
| |
South America (By Service Type, Transportation Mode, Vehicle Type, Destination, and Country)
| |
Middle East and Africa (By Service Type, Transportation Mode, Vehicle Type, Destination, and Country)
|
Find answers to common questions about this report
The Finished Vehicles Logistics market size was valued at USD 157.4 billion in 2025, according to the Metastat Insights study.
The Finished Vehicles Logistics market is projected to grow at a CAGR of 4.5% during the forecast period from 2026 to 2033.
The North America Finished Vehicles Logistics market size is estimated to reach USD 63.3 billion by 2033.
The Primary Transport segment leads the Finished Vehicles Logistics market, with a projected value of USD 91.5 billion by 2033. This segment's growth reflects its significant role in the overall logistics framework.
Urbanization drives the Finished Vehicles Logistics market by increasing demand for efficient transportation solutions and necessitating streamlined logistics. Investment in advanced logistics frameworks and digital transformation enhances operational efficiency, enabling firms to meet rising consumer expectations for timely deliveries.
Europe holds the largest share of the Finished Vehicles Logistics market, accounting for 30.7 percent of the total market. This significant share reflects the region's strong logistics infrastructure and demand for vehicle transportation services.
Regulatory tightening and compliance hurdles significantly restrain growth in the Finished Vehicles Logistics market. Adherence to environmental standards increases operational costs, particularly affecting smaller firms. macroeconomic pressures, geopolitical instability, and talent gaps further complicate logistics operations, leading to inefficiencies and decreased competitiveness.
Investment in advanced logistics frameworks and digital transformation strategies drives product adoption in the Finished Vehicles Logistics market. The integration of technology enhances operational efficiency, improves tracking, and reduces transit times, addressing consumer demands for faster and more reliable vehicle delivery. This focus on innovation positions companies to meet evolving consumer preferences effectively.
The Finished Vehicles Logistics market is estimated to reach a valuation of USD 223.7 billion by 2033.
Top players operating in the Finished Vehicles Logistics market include Wallenius Wilhelmsen, CEVA Logistics, Hyundai Glovis Co., Ltd., BLG LOGISTICS GROUP AG & Co. KG, Mitsui O.S.K. Lines, Ltd., and DP World.
Choose Your License
Global Finished Vehicles Logistics Market
The analysts below cover Automotive and Transportation research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.
Integrating zero-trust access controls across legacy electronic health record systems involves complex compliance overhead. Team produced an analysis that clearly separated identity governance and administration tools from privileged access management platforms. Their evaluation of HIPAA and GDPR compliance features across cloud native solutions gave our architecture group clear baseline criteria. The custom data request regarding biometric authentication adoption in hospital networks was returned promptly with clear documentation.
Evaluating calorific value requirements and air permit compliance across municipal waste facilities requires localized data. Metastat Insight structured their analysis around operational throughput capacity and feedstock composition variations in Latin America and Eastern Europe. Their competitive mapping of sorting equipment vendors helped clarify technology differences between optical separators and heavy media systems. The study provided an objective baseline during our capital expenditure reviews.
Decarbonizing industrial thermal processes hinges on refrigerant regulations and compressor efficiency limits. Metastat Insights delivered a thorough market analysis that evaluated natural refrigerants like CO2 and hydrocarbons against synthetic low-GWP alternatives. The breakdown of utility incentives and grid capacity constraints across key European manufacturing hubs offered valuable perspective. The follow-up conversation with their sector analysts addressed our specific questions on mechanical vapor recompression systems efficiently.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950
Starting from
$2950