
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Fixed-Line Broadband Access Equipment Market Size, Share, By Equipment Type (Optical Line Terminals (OLTs), Optical Network Terminals (ONTs) and Optical Network Units (ONUs), Digital Subscriber Line Access Multiplexers (DSLAMs) and Multi-Service Access Nodes (MSANs), Cable Modem Termination Systems (CMTS) and Converged Cable Access Platforms (CCAPs), Cable Modems and Gateways, Broadband Access Switches and Aggregation Equipment, Others), By Technology (Gigabit Passive Optical Network (GPON), Ethernet Passive Optical Network (EPON), 10-Gigabit Symmetric Passive Optical Network (XGS-PON), Next-Generation Passive Optical Network 2 (NG-PON2), Data Over Cable Service Interface Specification (DOCSIS), Digital Subscriber Line (DSL), Others), By Application (High-Speed Internet Access, Voice Over Internet Protocol (VoIP), Video Streaming and Video on Demand (VoD), Smart Home Connectivity, Cloud and Enterprise Connectivity, Remote Work and Digital Education, Internet of Things (IoT) Connectivity), By End User (Residential, Commercial, Industrial, Government, Data Centers), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-5776
Published
November, 2026
Pages
281 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
Market Valuation: Valued at $13.3 Billion in 2025, projected to reach $19.5 Billion by 2033 at a 4.9% CAGR.
Dominant Segment: Optical Network Terminals (ONTs) and Optical Network Units (ONUs) lead the market, driven by the increasing demand for high-speed internet access and enhanced connectivity solutions.
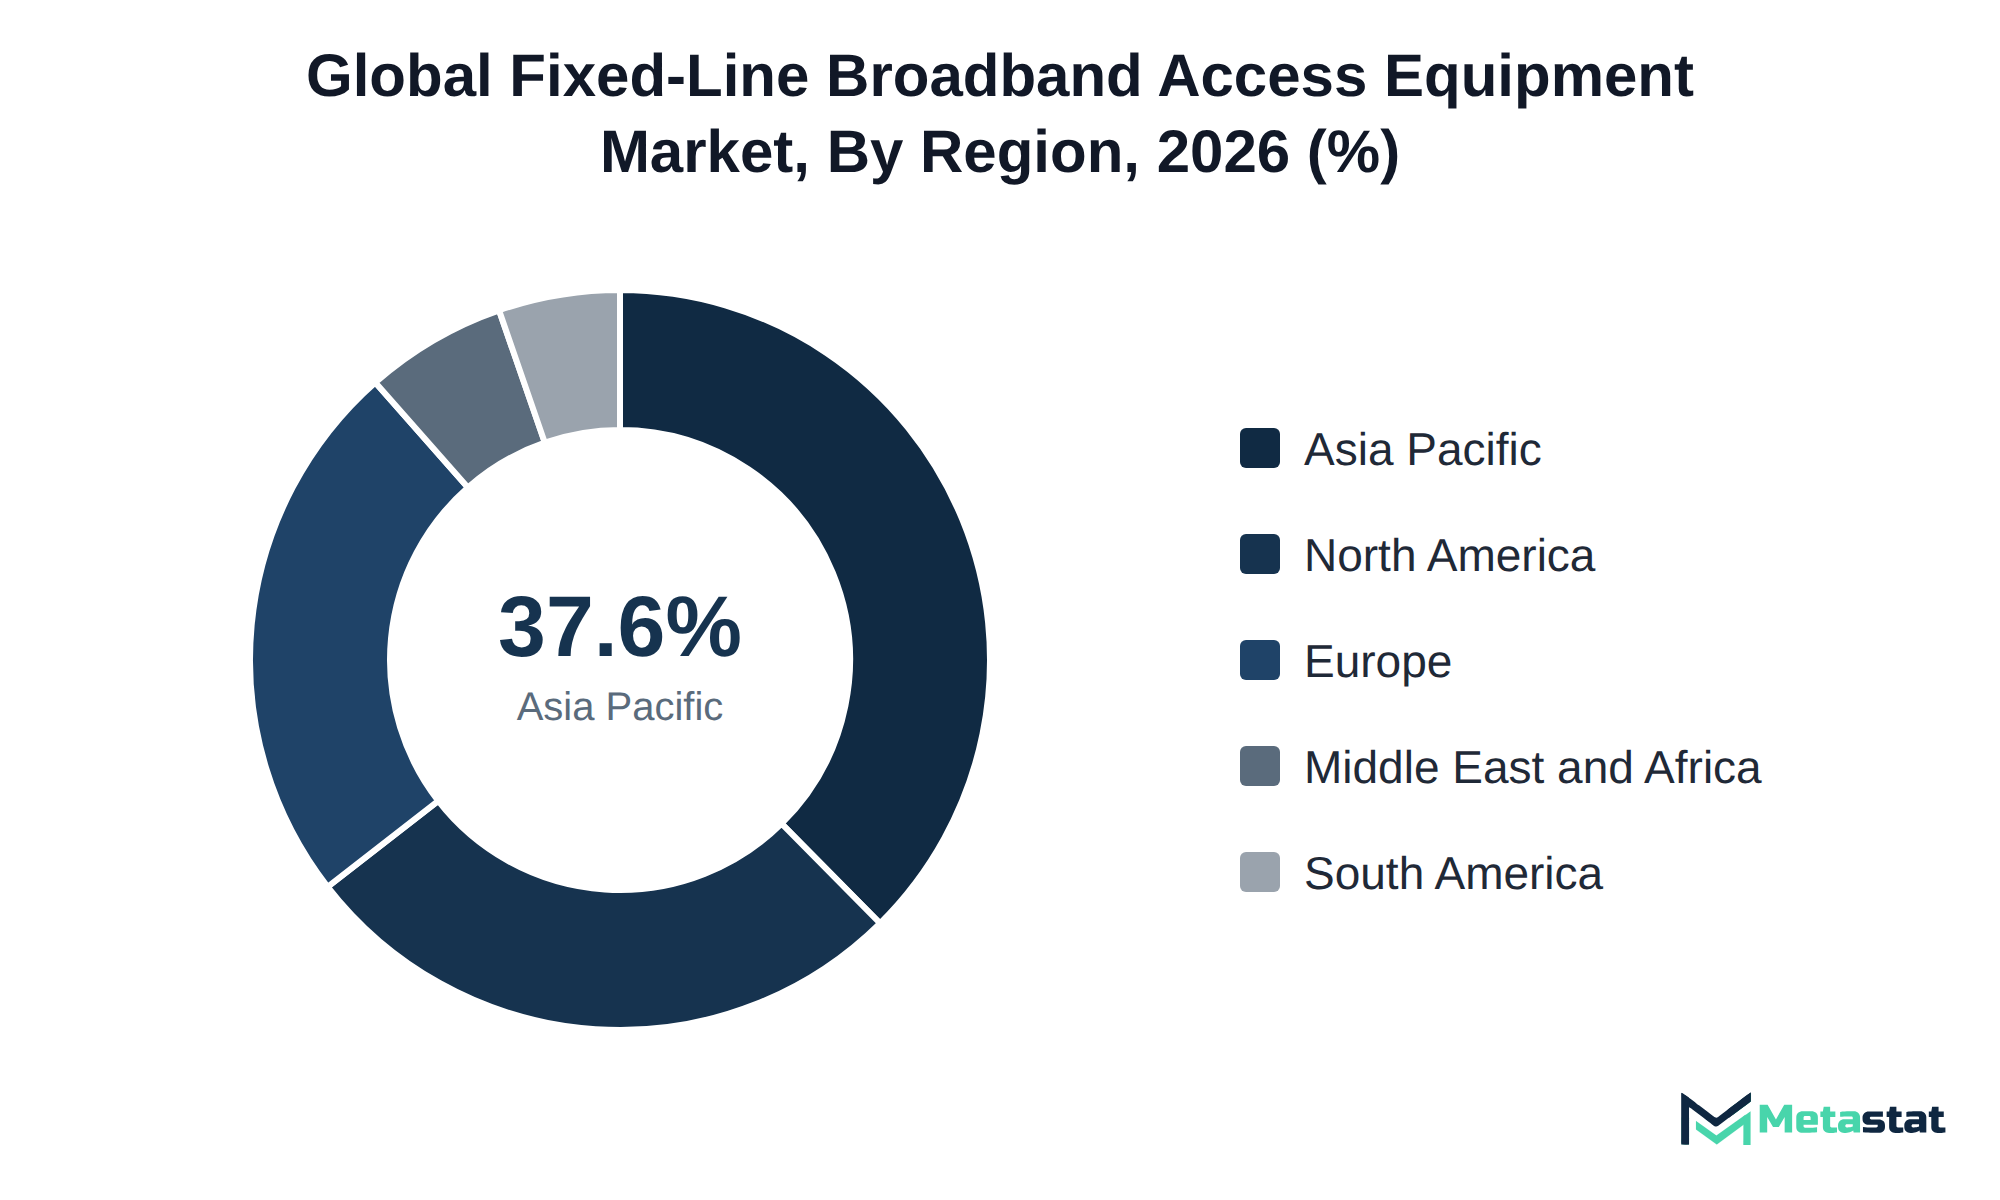
Geographic Lead: Asia Pacific holds the largest market share at 37.6%, fueled by robust demand for advanced broadband solutions and ongoing digital infrastructure expansion.
What's Inside: The report provides comprehensive competitive coverage, detailed analyses of market dynamics, and forecasts extending to 2033 across various segments and technologies.
Emerging Technology Trends: The market is witnessing a significant shift towards Next-Generation Passive Optical Network 2 (NG-PON2), projected to grow at a CAGR of 7.7%, reflecting the demand for scalable and flexible broadband solutions.
Sector Demand Insights: The residential sector is expected to see substantial growth, with demand for high-capacity fixed broadband equipment projected to increase from USD 6.6 billion in 2026 to USD 8.8 billion by 2033.
Choose Your License
Global Fixed-Line Broadband Access Equipment Market
The global Fixed-Line Broadband Access Equipment market was valued at USD 13.3 billion in 2025 and is projected to reach USD 19.5 billion by 2033, growing at a CAGR of 4.9% over the forecast period.
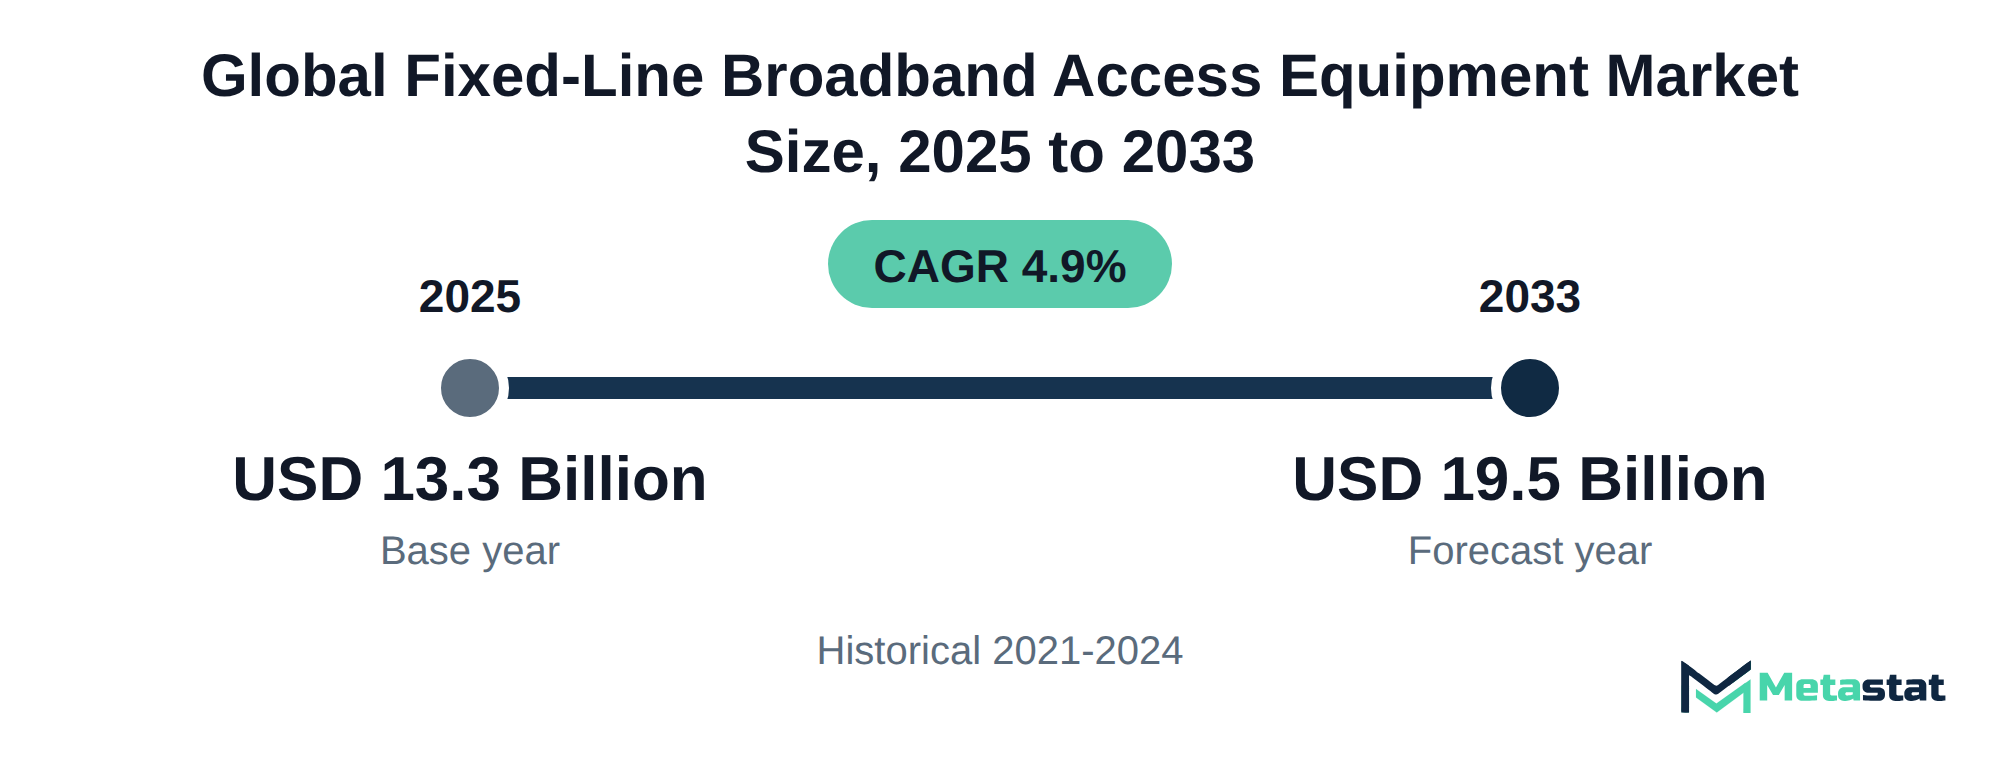
The Fixed-Line Broadband Access Equipment market encompasses a range of devices and technologies that facilitate fixed broadband connectivity. Buyers invest in this market primarily to enhance internet access, improve data transmission speeds, and support the growing demand for high-capacity communication services. Key buyers include telecommunications providers, enterprises, and government agencies, all seeking reliable solutions to meet increasing connectivity demands.
Growth in the market is driven by the escalating need for high-speed internet access, particularly in residential and commercial sectors. Optical Network Terminals (ONTs) and Optical Network Units (ONUs) form the highest-value segment and contribute significantly to market revenue. Asia Pacific holds the largest regional share at 37.6%, reflecting strong demand for advanced broadband solutions.
North America holds 26.9% of the market in 2025, with the US leading in 2026. The ongoing expansion of digital infrastructure and the rise of smart home technologies further support market growth. Investment in fixed-line broadband access equipment allows service providers to improve their offerings, stay competitive, and meet changing consumer needs.
The Fixed-Line Broadband Access Equipment market encompasses various technologies and components that enable high-speed internet connectivity. Spending is driven by rising demand for reliable, high-capacity internet services across residential, commercial, and industrial sectors. The rapid expansion of digital services and the rising need for reliable fixed telecommunications infrastructure drive spending in this area.
Growth in the market is fueled by the escalating adoption of high-speed internet services, particularly in the Asia Pacific region, which holds 37.6% of the market share in 2025. The segment featuring the most value within the market comes from Optical Network Terminals (ONTs) and Optical Network Units (ONUs), reflecting a significant shift towards advanced optical technologies. The US is expected to lead the North American market in 2026.
Increased investment in smart home technology and Internet of Things (IoT) applications enhances demand for fixed-line broadband access equipment. The growing emphasis on connectivity across devices and platforms makes this equipment essential to modern communication needs. The focus on enhancing internet access and performance remains a priority for both consumers and service providers.
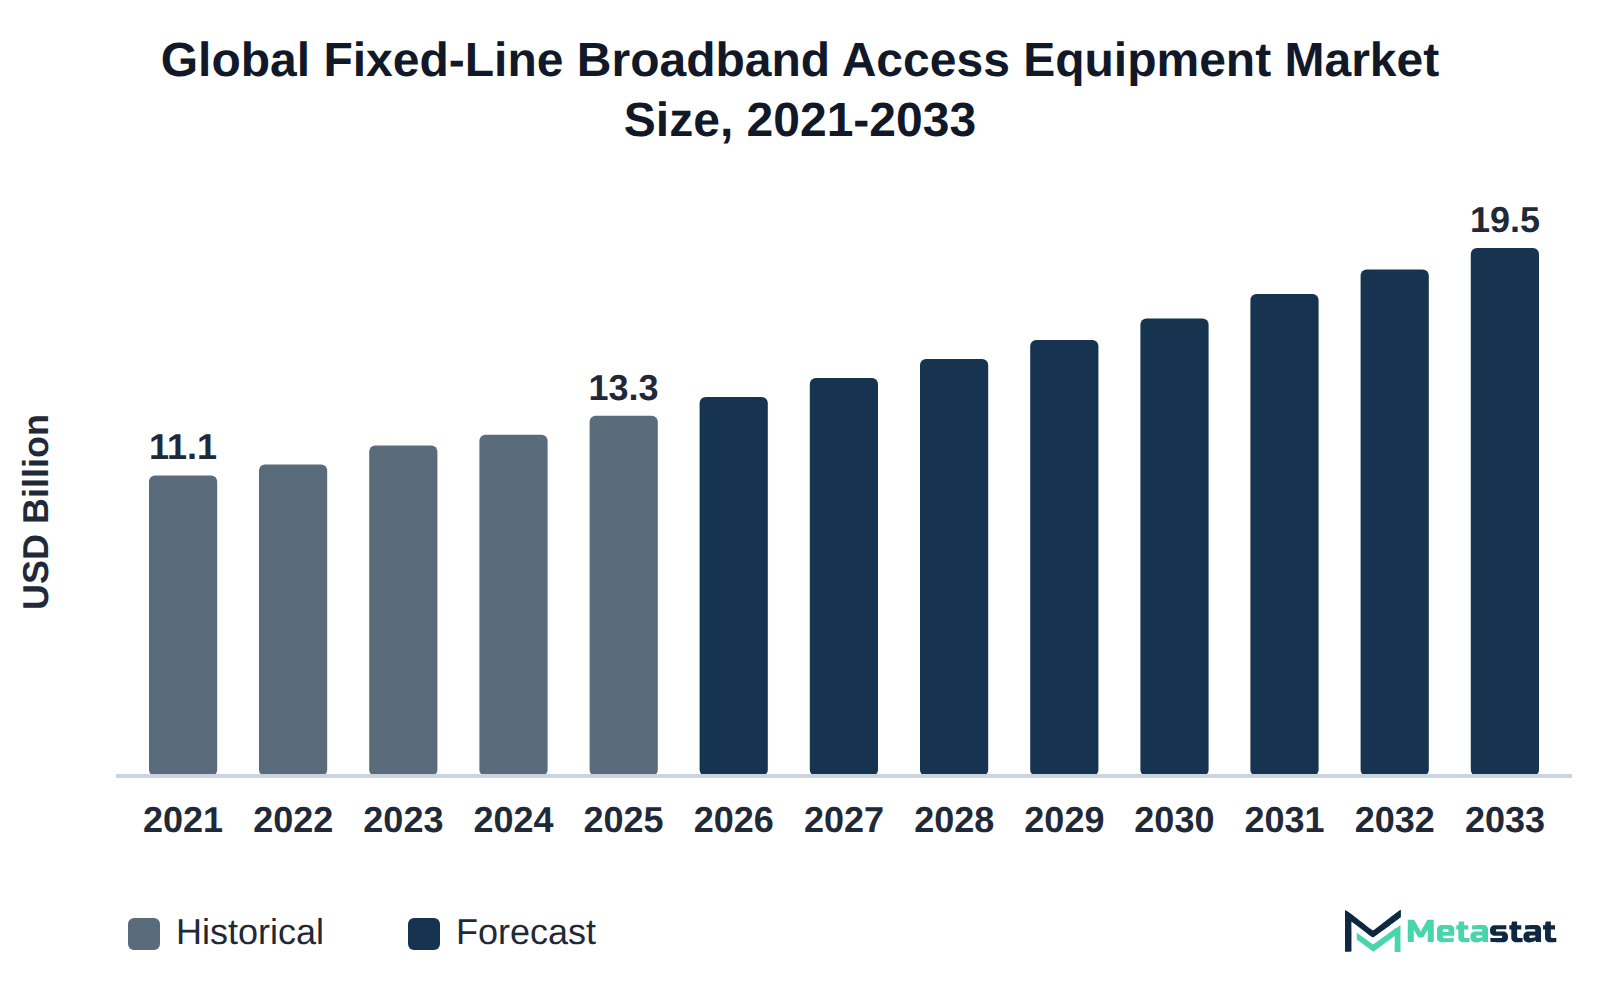
The Fixed-Line Broadband Access Equipment market experiences a significant transition from Gigabit Passive Optical Network (GPON) technology to 10-Gigabit Symmetric Passive Optical Network (XGS-PON) systems. This shift responds to the growing demand for higher bandwidth and improved internet performance among residential and commercial users. XGS-PON systems are projected to reach USD 4.4 billion by 2033 and to become central to expanding network capacity and efficiency.
The ongoing upgrades in fiber access infrastructure emphasize the necessity for service providers to adopt XGS-PON technology to stay competitive. Transitioning to advanced optical networks enables operators to offer better services, meeting the increasing expectations of users for high-speed connectivity. This advancement in technology aligns with the upward trajectory of the market, which is expected to grow at a compound annual growth rate (CAGR) of 4.9% from 2025 to 2033.
Investments in XGS-PON infrastructure will significantly impact operational efficiency and customer satisfaction in the Fixed-Line Broadband Access Equipment market. User needs continue to evolve, and embracing this technology is critical for providers aiming to enhance service offerings and maintain market share.
Recent advancements in the Data Over Cable Service Interface Specification (DOCSIS) have transformed the purchasing dynamics within the Fixed-Line Broadband Access Equipment market. Operators increasingly seek to upgrade their cable broadband infrastructure to enhance service delivery and meet growing consumer demand for higher speeds. The anticipated value of the optical network terminals segment is projected to reach USD 5.1 billion by 2033, reflecting a strategic pivot towards high-capacity solutions.
Service providers typically engage in long-term contracts with equipment suppliers, creating a stable revenue stream for manufacturers. These contracts often include provisions for periodic upgrades and maintenance, ensuring that operators adapt to technological advancements without incurring significant upfront costs. Pricing structures vary, with several vendors offering subscription models that align equipment costs with service revenue, allowing operators to manage capital expenditures more effectively.
This evolving pricing strategy enhances competitiveness in the market, enabling small and medium-sized operators to access advanced technologies previously limited to larger players. By streamlining capital allocation, firms invest in network expansion and improve customer satisfaction. More flexible payment models support market growth by increasing adoption of advanced fixed-line broadband solutions.
Residential demand for high-capacity fixed broadband equipment is rising in step with digital content consumption and connectivity requirements. The Fixed-Line Broadband Access Equipment market anticipates significant growth driven by the residential segment, which is projected to expand from USD 6.6 billion in 2026 to USD 8.8 billion by 2033, achieving a compound annual growth rate (CAGR) of 4.1%. This demand stems from the rising need for reliable internet services that support streaming, online gaming, and smart home applications.
In the enterprise sector, demand for high-capacity fixed broadband access equipment remains robust due to the growing reliance on cloud services and remote work solutions. The market reports a projected demand increase for commercial applications, expecting to reach USD 5.5 billion by 2033 with a CAGR of 5.4%. Enterprises require efficient and scalable broadband solutions to maintain productivity and ensure reliable connectivity across various business operations.
Data centers, crucial for supporting digital infrastructure, exhibit escalating demand for high-capacity fixed broadband equipment. The increasing adoption of technologies including Internet of Things (IoT) connectivity and digital education drives the necessity for reliable and high-speed connections. This trend reflects the broader shift toward data-centric operations and positions fixed-line broadband access equipment for long-term demand as technology advances.
The expansion of fiber networks and the deployment of next-generation Passive Optical Networks (PON) significantly influence the Fixed-Line Broadband Access Equipment market. Growth in fiber-optic infrastructure enhances internet connectivity and supports the increasing demand for high-speed data services. By 2033, the market for Optical Line Terminals (OLTs) is projected to reach USD 3.2 billion, reflecting a compound annual growth rate (CAGR) of 5.7% from 2026. This expansion demonstrates the urgency for operators to modernize their networks to meet consumer expectations for speed and reliability.
Next-generation PON technologies, including Next-Generation Passive Optical Network 2 (NG-PON2), offer higher bandwidth and improved efficiency, attracting substantial investment from telecommunications companies. These advancements allow service providers to deliver enhanced services, including ultra-high-definition video streaming and smart home connectivity. The demand for Optical Network Terminals (ONTs) and Optical Network Units (ONUs) is set to reach USD 5.1 billion by 2033, with a CAGR of 5.9%. As these deployments take hold, competition among service providers intensifies, pushing prices down and encouraging wider adoption of these technologies.
The surge in demand for high-speed internet access has prompted significant investments in Fixed-Line Broadband Access Equipment, particularly among residential users. The shift toward remote work, online education, and video streaming has driven an increase in data consumption, resulting in heightened expectations for reliable and fast internet connections. Consumers now require enhanced bandwidth and lower latency, leading to higher spending on broadband infrastructure. This trend highlights the critical need for service providers to upgrade existing networks and adopt advanced technologies, ensuring they meet customer demands effectively. The evolving landscape of the digital economy reinforces the urgency for improved access solutions and robust infrastructure development in the market.
NG-PON2 technology supports multiple wavelengths simultaneously, allowing operators to offer differentiated services including high-speed internet, video streaming, and advanced enterprise connectivity. The increasing adoption of NG-PON2 is driven by demand for scalable and flexible broadband solutions, particularly in urban and densely populated areas.
Service providers view NG-PON2 implementation as a strategic move to enhance competitive positioning and improve customer satisfaction. Residential and commercial sectors benefit from the higher bandwidth and lower latency that NG-PON2 provides, accommodating growing data consumption patterns. The Fixed-Line Broadband Access Equipment market anticipates sustained growth in this segment, with significant investments directed towards infrastructure upgrades and technology integration.
Operators focus on NG-PON2 to future-proof networks and meet the evolving demands of consumers and businesses alike. The move towards this next-generation technology signals a shift in the market towards more robust, high-capacity solutions that address increasing reliance on digital services across various sectors.
High costs associated with Fixed-Line Broadband Access Equipment hinder adoption among residential users. Budget constraints among these buyers lead to slower uptake of advanced technologies, impacting overall market growth. Many consumers prioritize cost-effective solutions over high-end equipment, resulting in smaller orders and delayed replacement cycles. This trend becomes pronounced in regions where economic conditions restrict affordability, leading to prioritization of essential services over equipment upgrades. The resulting hesitance to invest in advanced broadband solutions poses challenges to suppliers, who face difficulty achieving expected revenue targets. While consumers weigh costs against benefits, the market encounters obstacles that influence demand dynamics and overall growth projections.
Rising material costs present significant challenges for suppliers in the Fixed-Line Broadband Access Equipment market. Price fluctuations in raw materials, including fiber optics and electronic components, drive up expenses and squeeze profit margins. Suppliers respond through strategic partnerships with manufacturers to secure favorable pricing and ensure a steady supply of materials. Many suppliers pursue vertical integration, allowing them to control more of their supply chain and mitigate external cost pressures. Collaboration with technology providers enables suppliers to enhance product efficiency and reduce production costs. These strategies help suppliers stay competitive and deliver quality products while managing financial sustainability in a challenging economic environment.
Optical network terminals (ONTs) exhibit significant growth potential within the Fixed-Line Broadband Access Equipment market. This growth is driven by increasing consumer demand for high-speed internet access and enhanced connectivity solutions. Residential, commercial, and industrial users seeking improved broadband performance prioritize ONTs in their infrastructure investments. ONTs serve essential roles in facilitating faster data transmission and supporting a range of applications, including video streaming and smart home connectivity. The ongoing digital transformation, characterized by heightened online content consumption, fuels the urgency for advanced optical network solutions. This market expansion is expected to attract investments from suppliers focusing on innovative ONT technologies, thereby enhancing competitive dynamics in the sector.
The Global Fixed-Line Broadband Access Equipment market is segmented based on Equipment Type, Technology, Application, and End User.
Optical Line Terminals (OLTs) are critical components in fiber-optic communication systems, connecting end-users to the broader network infrastructure. They primarily target service providers seeking to expand access to high-speed internet, voice services, and video streaming. Demand for OLTs is driven by the increasing need for high-bandwidth applications, particularly in residential and commercial sectors. This segment distinguishes itself from others through its relatively faster growth rate compared to technologies including Digital Subscriber Line Access Multiplexers (DSLAMs), which experience slower growth. Service providers prioritize investments in OLTs to enhance service delivery and meet consumer expectations.
These devices function as critical components in fiber optic networks, converting optical signals into electrical signals for end-user connectivity. Primarily used by residential and commercial customers, the segment supports high-speed internet access, video streaming, and VoIP services. The increasing demand for high-speed connectivity drives growth, with residential users leading the adoption trends. This segment differentiates itself from others within the Equipment Type classification by exhibiting higher growth rates, fueled by the need for enhanced broadband speeds and network reliability. Comparatively, segments including Digital Subscriber Line Access Multiplexers (DSLAMs) experience slower growth due to the transition toward fiber-based technologies. Such dynamics position the ONTs and ONUs segment favorably within the competitive landscape of the Fixed-Line Broadband Access Equipment market.
Digital Subscriber Line Access Multiplexers (DSLAMs) and Multi-Service Access Nodes (MSANs) segment is expected to reach USD 1.9 billion by 2033. These devices play a vital role in connecting multiple digital subscriber lines to a digital backbone network, facilitating broadband access for residential, commercial, and industrial users. Increasing demand for internet connectivity, driven by the proliferation of digital services and remote work, is driving growth in this segment. The segment's growth rate differs from that of Optical Line Terminals (OLTs) and Optical Network Terminals (ONTs), which exhibit higher growth rates. The focus on upgrading existing infrastructure to support higher bandwidth requirements contributes to a competitive environment, compelling service providers to invest in advanced DSLAMs and MSANs. The evolution of technology and the push toward faster internet access are driving market dynamics, ensuring growth in the segment through 2033.
Cable Modem Termination Systems (CMTS) and Converged Cable Access Platforms (CCAPs) segment is projected to grow at a CAGR of 3.5% during the forecast period. This segment is important for delivering high-speed internet and multimedia services to residential and commercial customers. Service providers manage data traffic effectively with CMTS and CCAPs, enabling stable and reliable broadband access. Continuous advancements in technology push operators to upgrade their systems, enhancing service quality and capacity. The segment’s growth is primarily driven by the rising demand for high-speed internet and video streaming services. Compared to other segments, including Optical Line Terminals (OLTs), which exhibit a higher growth rate, CMTS and CCAPs experience slower growth, reflecting their maturity with established technologies in the market. Investment in this segment remains significant, targeting improved service delivery and customer satisfaction.
Cable modems and gateways facilitate high-speed internet access for residential, commercial, and industrial users. These devices connect end-user equipment to the internet through existing cable infrastructure, making them essential for a variety of applications, including streaming media and online gaming. The increasing demand for reliable internet services drives growth in the segment, particularly among residential consumers seeking uninterrupted connectivity. Compared to other equipment types, cable modems and gateways experience slower growth rates, influenced by the adoption of fiber-based solutions that outperform traditional cable technologies in terms of speed and efficiency. Pricing strategies in this segment vary, reflecting the competitive landscape and technological advancements that shape market dynamics.
Broadband access switches and aggregation equipment manage and direct traffic across broadband networks. These devices facilitate efficient data flow between various components in networking environments, ensuring smooth connectivity for end users. Telecommunications providers and internet service companies apply this equipment primarily to improve network performance and manage bandwidth effectively. Demand for such equipment is driven by increasing data traffic resulting from higher consumption of online services and applications. The growing trend of remote work further increases the requirement for reliable and efficient network management solutions. Compared to other segments, this sub-segment generally experiences steady growth, focusing on operational efficiency rather than rapid technological advancements. The market reflects a broader trend toward upgrading existing infrastructure to cope with new demands rather than adopting entirely new technologies.
Others (Fiber Distribution Nodes, Remote PHY Devices, and Broadband Access Extenders) represent critical components in fixed-line broadband infrastructure, enhancing connectivity and efficiency. These devices typically support high-capacity data transfers and are used by various telecommunications providers and internet service companies to improve network performance. The segment experiences growth driven by increasing demand for high-speed internet and the ongoing transition toward fiber optic technology. Unlike other equipment types, this segment demonstrates a lower cost profile due to its specific applications rather than general broadband demands. Connectivity solutions provided by these devices cater to both residential and commercial clients, making them versatile in their deployment. The Fixed-Line Broadband Access Equipment market continues to evolve, with innovations and consumer needs shaping the direction of products within this segment.
Gigabit Passive Optical Network (GPON) segment is valued at USD 4.8 billion in 2026 and is projected to reach USD 5.8 billion by 2033, at a CAGR of 2.7% during the forecast period. GPON technology serves high-speed internet access, primarily serving residential users and commercial establishments seeking reliable broadband solutions. In commercial buildings, GPON also underpins passive optical LAN solutions. The increasing demand for bandwidth-intensive applications including video streaming and online gaming drives growth in this segment. In comparison to other technologies, GPON experiences slower growth due to the emergence of alternatives like Next-Generation Passive Optical Network 2 (NG-PON2), which offer superior performance. Cost considerations influence adoption rates, with GPON infrastructure presenting a significant investment for service providers. While GPON remains a vital component of the Fixed-Line Broadband Access Equipment market, the evolving technology landscape necessitates ongoing adaptation to maintain competitive relevance.
Ethernet Passive Optical Network (EPON) segment is estimated to reach USD 1.7 billion by 2033, at a CAGR of 3.3% during the forecast period. This technology serves high-speed internet access, particularly favored by residential and commercial users, due to its efficient data transmission capabilities. The increasing demand for reliable broadband connectivity stimulates the growth of this segment. EPON distinguishes itself from other technologies within the Fixed-Line Broadband Access Equipment market primarily through its cost-effectiveness and ability to support multiple services over a single fiber connection. Its growth trajectory remains moderate compared to other segments, including Optical Line Terminals (OLTs) and Optical Network Terminals (ONTs), which experience higher CAGRs. The market's focus on cost-efficient infrastructure development drives the adoption of EPON solutions, making it an attractive option for telecom operators aiming to enhance service offerings while minimizing costs.
10-Gigabit Symmetric Passive Optical Network (XGS-PON) segment is expected to reach USD 4.4 billion by 2033. This technology facilitates high-speed data transmission, optimizing bandwidth for residential and commercial users. Adoption of XGS-PON is driven by increasing demand for high-bandwidth applications including video streaming and cloud services. Compared to other technologies, XGS-PON offers symmetric data rates, allowing for faster upload speeds, which appeals to content creators and remote workers. The segment's growth is anticipated to outpace others in the Technology category due to evolving connectivity requirements and the transition towards more robust broadband networks. Consequently, heightened interest from service providers seeking to enhance infrastructure capabilities and meet consumer expectations for faster, reliable connections supports market expansion.
Next-Generation Passive Optical Network 2 (NG-PON2) segment is projected to grow at a CAGR of 7.7% during the forecast period. This technology significantly enhances broadband capacity and network performance, catering to service providers aiming to deliver high-speed internet and support for the increasing number of connected devices. Key drivers for this segment include rising demand for bandwidth-intensive applications including video streaming and smart home connectivity. Unlike other technologies, NG-PON2 offers a compelling option for service providers looking to future-proof their infrastructure due to its ability to support multiple services simultaneously. This segment's growth trajectory stands out compared to alternatives like GPON, which experiences a slower CAGR of 2.7%. Investment in NG-PON2 technology reflects the ongoing transformation in the Fixed-Line Broadband Access Equipment market, aligning with the needs of both commercial and residential users seeking enhanced connectivity solutions.
Data Over Cable Service Interface Specification (DOCSIS) focuses on standardizing communication over coaxial cable systems, enabling high-speed data transfer. This technology finds extensive use among internet service providers and cable operators to deliver broadband services to residential and commercial customers. Adoption remains strong due to increasing demand for reliable and high-speed internet connections, particularly in urban areas. The segment distinguishes itself from others within the technology category by catering specifically to cable network infrastructure, which supports a different user base compared to fiber-optic solutions. Demand for DOCSIS technology benefits from ongoing advancements that improve performance and reduce latency, positioning it favorably against competing technologies. While other segments experience varied growth rates, DOCSIS remains a preferred choice due to its established presence in the market, creating unique opportunities for service providers to enhance customer offerings.
Digital Subscriber Line (DSL), including G.fast, provides high-speed internet connectivity primarily through existing copper telephone lines. This technology targets residential users, small businesses, and organizations seeking reliable broadband access. Demand for DSL services grows due to the increasing need for high-speed internet, particularly in areas where fiber optics are not yet deployed. Compared to other technologies, DSL offers a lower-cost solution for internet service providers, allowing them to use existing infrastructure. The segment faces competition from faster alternatives like fiber-based solutions, which limit its growth potential. However, ongoing advancements in DSL technology, including G.fast, enhance speeds significantly and attract users seeking affordable options within the Fixed-Line Broadband Access Equipment market. This segment's adaptability in using current infrastructure differentiates it from newer technologies that require complete overhauls of existing systems.
Others (25G-PON and 50G-PON) play significant roles in providing advanced optical networking solutions. This sub-segment targets high-capacity broadband connectivity, essential for both residential and commercial users who require high internet speeds. Demand for these technologies arises from a growing need for enhanced bandwidth and reliable connections, driven by increasing digital consumption and the proliferation of high-definition content. The sub-segment distinguishes itself from others through its specific focus on next-generation optical networks, which cater to more demanding applications including 5G mobile backhaul and ultra-high-speed internet access. Adoption of these technologies reflects the market's shift toward integrating advanced fiber-optic solutions, highlighting the importance of remaining competitive in the evolving telecommunications environment.
The high-speed internet access segment is essential for delivering reliable, fast connectivity to residential, commercial, and industrial users globally. The demand for high-speed internet continues to rise due to increasing use of online services, remote work, and streaming platforms. While this segment experiences steady growth, it operates at a slower pace compared to other segments including Smart Home Connectivity, which is projected to grow at a CAGR of 7.7%. Competitive pricing strategies adopted by suppliers, along with advancements in technology, influence the dynamics of this segment significantly. Investments in infrastructure enhancement remain critical to support increasing bandwidth requirements of users.
This technology facilitates voice communication over broadband connections, primarily used by residential and commercial customers seeking cost-effective communication solutions. Growth in this segment stems from increased demand for voice services integrated with high-speed internet access. Unlike other applications including High-Speed Internet Access, which targets a broader audience, VoIP appeals specifically to users focused on enhancing communication efficiency. The segment's growth reflects a shift towards more affordable and flexible telephony options, significantly impacting purchasing decisions. While competition from mobile communication technologies exists, VoIP thrives due to its ability to offer lower rates for long-distance calls and additional features.
Video Streaming and Video on Demand (VoD) segment is expected to reach USD 4.4 billion by 2033. This segment provides users with the ability to stream video content over the internet, catering to both residential and commercial end-users. A significant driver of this segment involves increasing demand for high-quality video content, particularly as consumers shift toward on-demand viewing habits. Compared to other segments, VoD benefits from a rapid growth rate, supported by advancements in broadband technology and changes in consumer preferences. While segments like High-Speed Internet Access demonstrate a CAGR of 2.7%, VoD’s specific growth trajectory emphasizes the rising importance of streaming services in the broader context of the Fixed-Line Broadband Access Equipment market. Investments in infrastructure to enhance video delivery further promote the segment's expansion, differentiating it from traditional applications reliant on fixed-line broadband technology.
Smart Home Connectivity segment is projected to grow at a CAGR of 7.7% during the forecast period. This segment focuses on providing reliable connectivity for devices within residential environments, enhancing user experiences through automation and intelligent management. Consumers and businesses seeking integrated solutions for their smart devices are the primary users of this technology. The demand for smarter home solutions drives growth, influenced by rising consumer interest in home automation and energy efficiency. Compared to other applications within the market, Smart Home Connectivity stands out due to its higher growth potential, reflecting increased consumer investment in connected devices and networks. The emphasis on convenience and efficiency in residential settings differentiates this segment from others, leading to sustained interest and adoption in the market.
Cloud and Enterprise Connectivity enables organizations to access high-speed internet for a variety of applications, including cloud services, remote work, and digital education. Businesses and government entities engage with this segment to improve operational efficiency and enhance communication. The push towards digital transformation drives demand for robust connectivity solutions, ensuring reliable access to cloud resources and enterprise applications. Compared to other applications, Cloud and Enterprise Connectivity experiences a different growth trajectory, focusing on enterprise-level demands. This segment faces unique challenges, including the need for reliable infrastructure and higher bandwidth capacity. Regulatory requirements around data security and privacy further influence adoption, pushing enterprises to adopt more advanced broadband access solutions. The market for Fixed-Line Broadband Access Equipment is evolving, with increasing competition and technological advancements shaping the market.
Remote Work and Digital Education represents an essential segment that facilitates online learning and telecommuting efforts. This segment finds significant application among educational institutions and corporate environments, ensuring reliable connectivity for remote activities. Key drivers influencing this segment include the increasing demand for flexible learning models and the rising trend of remote work strategies. Comparatively, this segment experiences growth at a different pace than others within the market, focusing on meeting specific connectivity needs rather than competing on price. Organizations in the education and corporate sectors prioritize robust and high-quality internet connections to support their operational requirements, highlighting the necessity of efficient broadband access solutions. The market adapts to the evolving technological landscape, aligning with the heightened focus on integrated digital solutions.
Internet of Things (IoT) Connectivity encompasses the integration of internet-enabled devices, enhancing communication and data exchange. This segment finds application in various environments, including residential, commercial, and industrial sectors, where connectivity facilitates automation, remote monitoring, and operational efficiencies. The escalating demand for smart devices and automation drives significant growth, reflecting the evolving digital landscape. The market shows robust interest from technology-savvy consumers and businesses aiming to leverage IoT capabilities for innovative solutions. Compared to other segments, IoT Connectivity experiences faster growth due to its increasing relevance in modern applications and investments in smart infrastructure, differentiating it from traditional broadband services.
This segment primarily serves households requiring stable and high-speed internet connectivity for daily activities including remote work, streaming, and online gaming. Rising demand for internet services fuels growth, driven by increasing digitalization and the expanding number of connected devices in homes. These devices typically connect to the fixed-line network through home networking hardware such as gateways. Compared to other segments, the residential sector exhibits moderate growth, distinguishing itself from commercial and industrial segments, which experience higher demand due to larger-scale deployments. The market shows a preference for advanced technologies including fiber optics to meet consumer expectations for speed and reliability.
This segment supports businesses, providing essential connectivity for internet services, VoIP, and data transfer. Companies in various industries, including retail, finance, and healthcare, leverage fixed-line broadband for reliable communication and data management. Demand drives growth in this area, particularly due to increased remote work and digital transformation initiatives. Unlike the residential segment, which experiences a lower growth rate of 4.1%, the commercial segment's robust CAGR reflects heightened investment in technological infrastructure. Businesses prioritize high-speed and stable internet access, differentiating them from other end users. The Fixed-Line Broadband Access Equipment market is expected to see continued advancements in equipment types and technologies, fueling further expansion and investment in this segment.
The industrial segment is expected to reach USD 2.1 billion by 2033. This segment finds application primarily in manufacturing, utilities, and various industrial processes requiring robust connectivity and reliable systems. Demand arises from the increasing adoption of automation and smart technologies within manufacturing environments. The segment experiences a CAGR of 5.0%, positioning it for steady growth that aligns with trends in industrial digitization. Compared to the residential segment, which grows at a CAGR of 4.1%, the industrial segment presents opportunities for higher investment due to the need for specialized equipment and infrastructure development. The market's trajectory reflects a growing emphasis on digital transformation initiatives across industrial sectors, driving demand for advanced broadband solutions. Investment in cyber-physical systems continues to enhance operational efficiencies, further supporting the segment’s expansion in the coming years.
Government segment is projected to grow at a CAGR of 5% during the forecast period. This segment typically serves public institutions at various levels, facilitating critical services including digital communication, emergency response, and public administration. Increasing demand for enhanced cybersecurity and reliable communication systems drives investment in broadband access technologies within this sector. Compared to other end-user segments, the government engages in larger-scale procurement, resulting in higher overall contract values. This segment's growth trajectory is somewhat slower than the commercial segment, which exhibits a CAGR of 5.4%. The Fixed-Line Broadband Access Equipment market sees unique dynamics in government spending, influenced by regulatory requirements and funding allocations that differ from private sector purchasing behavior.
Data Centers encompass facilities that house computer systems and associated components, including telecommunications and storage systems. These facilities employ Fixed-Line Broadband Access Equipment to enable high-speed connectivity essential for data processing and storage solutions. The demand for this segment grows driven by the increasing reliance on cloud services and data management across various industries. Data Centers represent a higher investment compared to other end-user segments, reflecting their critical role in supporting large-scale data processing needs. This segment experiences significant growth relative to others due to the escalating demand for efficient data handling and the shift towards digitalization. Advancements in technology and the rising requirement for faster data transmission fuel this growth, differentiating it from segments serving residential or commercial users, which do not experience similar demand dynamics.
Based on geography, the Global Fixed-Line Broadband Access Equipment market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Demand for fixed-line broadband access equipment in North America derives from the expanding need for high-speed internet and reliable connectivity solutions. The growing adoption of digital technologies across residential, commercial, and government sectors fuels this demand, with the region's share of the global market projected at 26.9% in 2025. Infrastructure investment remains crucial, supported by initiatives aimed at enhancing broadband access and lowering costs for consumers. Advancements in optical networking technologies, including GPON and XGS-PON, serve essential roles in meeting increasing data consumption needs. North America is projected to reach USD 4.9 billion by the end of 2033, reflecting ongoing expansion in the fixed-line broadband access equipment market and its importance in supporting economic activities.
Europe represents a significant portion of the Fixed-Line Broadband Access Equipment market, accounting for 24.00% of the global share in 2025. Countries including Germany, France, and the UK drive demand through their robust telecommunications infrastructure and increasing focus on high-speed internet connectivity. Adoption of advanced technologies is essential for addressing growing consumer expectations for reliable and fast internet services. Regulatory frameworks and government initiatives aimed at enhancing broadband access contribute to market expansion. The competitive landscape features local and international players, all vying for a share of this lucrative market. High demand for Optical Line Terminals (OLTs) and Optical Network Terminals (ONTs) reflects the shift towards fiber-optic solutions, essential for meeting increasing data consumption in the region.
Asia-Pacific represents a significant portion of the Fixed-Line Broadband Access Equipment market, accounting for 37.6% of the global share in 2025. Rapid urbanization and increasing internet penetration drive demand across various countries, particularly in China, Japan, and India. The region's strong focus on digital transformation initiatives influences substantial investments in broadband infrastructure, enhancing access to high-speed internet services. Countries like South Korea and Australia exhibit advanced telecommunications infrastructure, which supports the need for high-performance equipment. Emerging technologies, including Gigabit Passive Optical Network (GPON) and Next-Generation Passive Optical Network 2 (NG-PON2), find extensive applications in residential and commercial segments. The market is projected to continue its upward trajectory, driven by increasing connectivity requirements and the ongoing shift towards smart home solutions.
Brazil and Argentina represent significant markets for fixed-line broadband access equipment, driven by growing digital transformation initiatives and increasing demand for high-speed internet connectivity. A focus on expanding telecommunications infrastructure boosts opportunities for equipment suppliers in the region. Innovations in smart home technology and connectivity requirements further drive demand in South America. The market share for South America is projected at 5.3% in 2025, reflecting potential for growth in the upcoming years. Investments in broadband deployment, supported by government initiatives, enhance the competitive landscape and facilitate market expansion.
The market experiences distinct dynamics in the Middle East and Africa, driven primarily by increasing demand for reliable internet connectivity across various sectors. Countries including Saudi Arabia and the UAE focus on expanding their digital infrastructure, enhancing internet accessibility for both residential and commercial users. South Africa contributes to the market through initiatives aimed at improving broadband services, which support economic growth and technological advancements. The region shows potential for growth in fixed-line broadband access equipment, reflecting ongoing commitment to enhancing connectivity solutions. The emphasis on high-speed internet and innovative applications directly influences adoption rates of fixed-line broadband access equipment across various user categories. The market in this region operates within a context prioritizing digital transformation and infrastructure development.
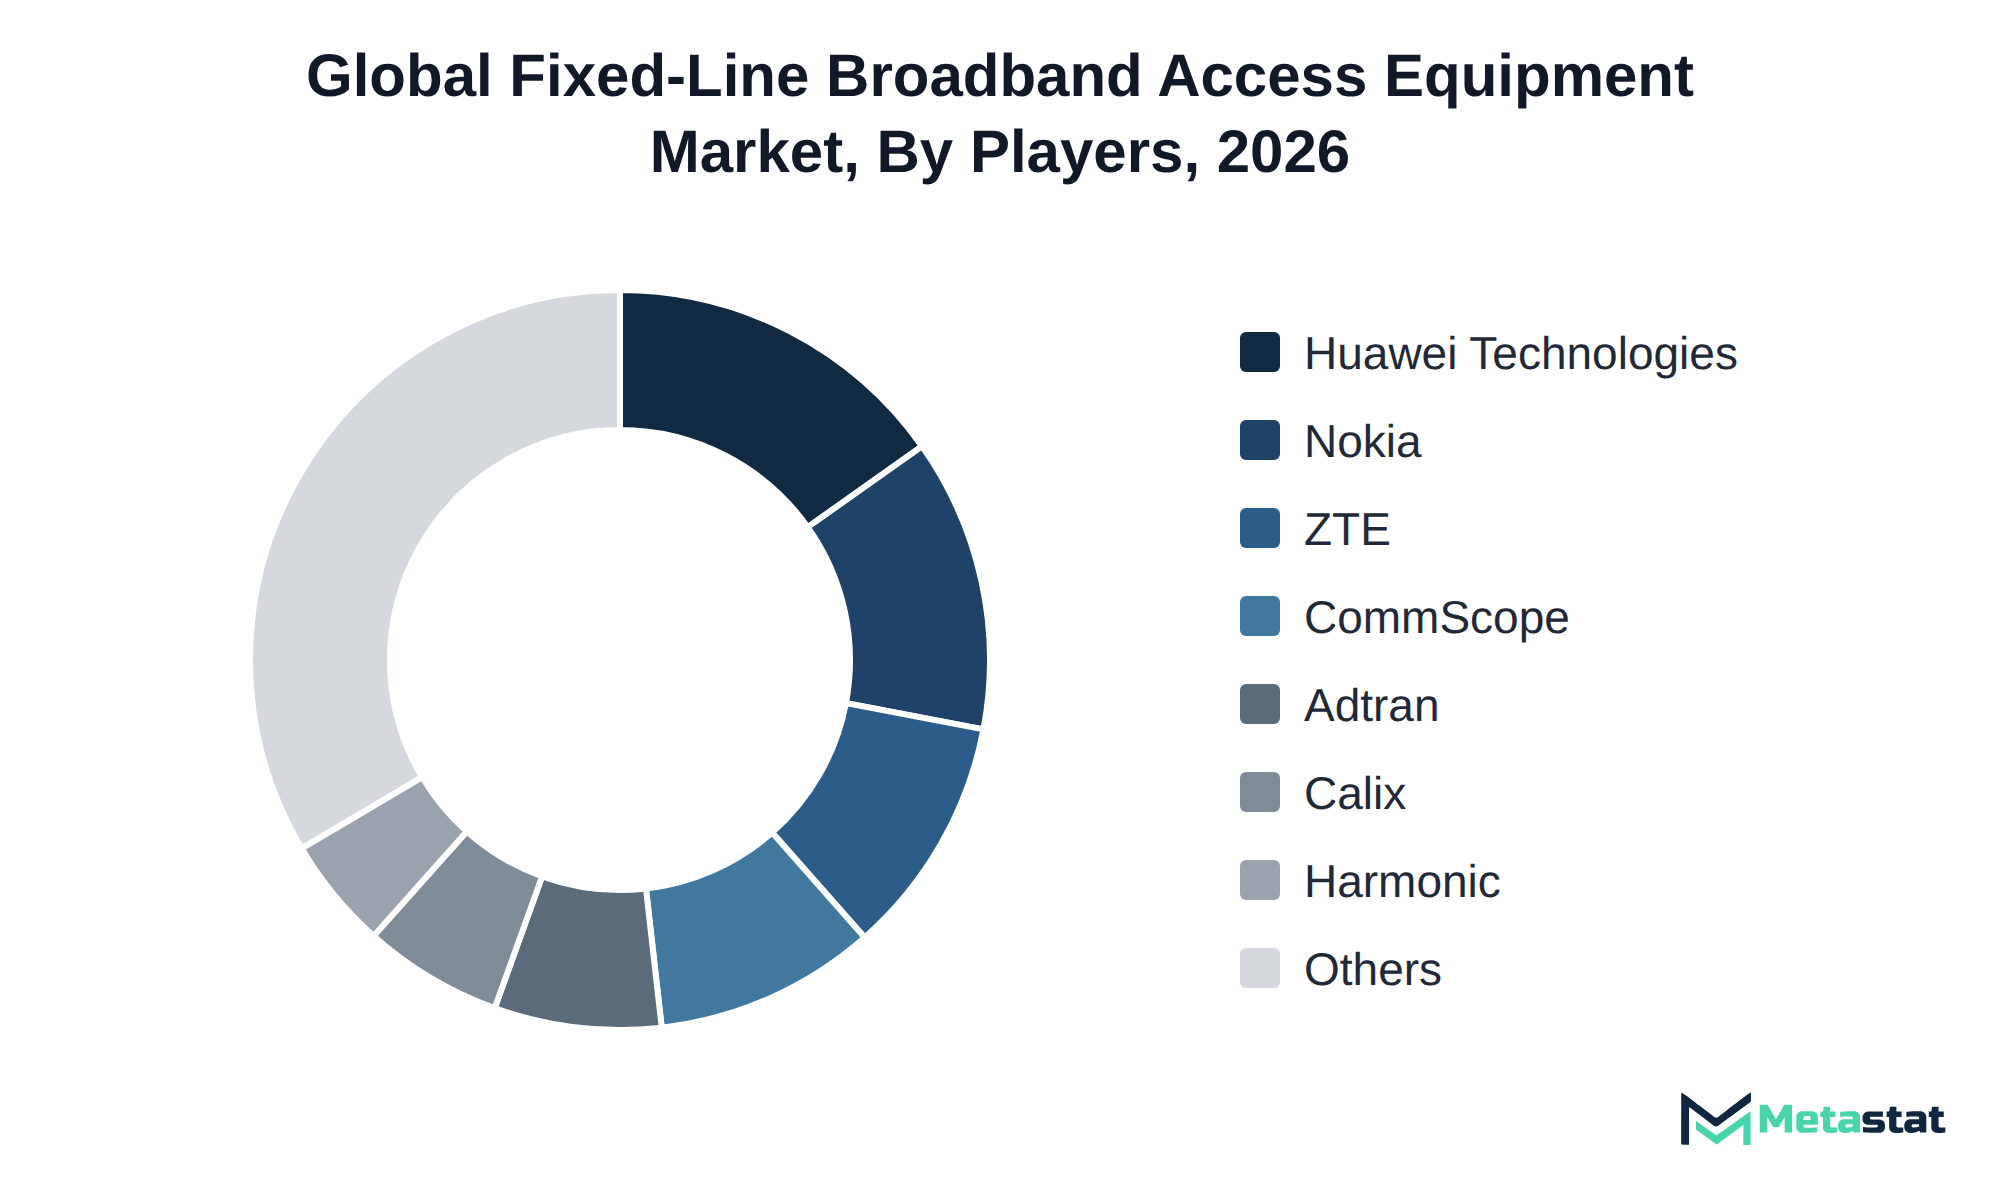
Competition within the Fixed-Line Broadband Access Equipment market aligns with various strategic behaviors and focuses. Companies emphasize aspects including pricing, certification, and service quality to attract buyers. The market comprises several players who prioritize different product types and technological advancements that cater to specific buyer needs.
Nokia Corporation and Huawei Technologies focus on developing advanced optical networking solutions that support high-speed internet and enhance overall network capacity. Adtran specializes in providing customized broadband access solutions that address specific customer requirements in diverse environments. ZTE Corporation emphasizes cost-effective offerings while maintaining sufficient quality, appealing to price-sensitive buyers in the market.
Achieving this growth relies on several key developments. First, the increasing adoption of Optical Network Terminals (ONTs) and Optical Network Units (ONUs) will drive market expansion, with expected revenue reaching USD 5.1 billion by 2033. This segment will primarily serve residential users seeking enhanced internet connectivity. Second, demand for Smart Home Connectivity is projected to rise, supporting overall growth in the market. A compound annual growth rate of 7.7% reflects the demand from residential end users integrating smart devices into their homes. Third, advancements in technology including Next-Generation Passive Optical Network 2 (NG-PON2) will enhance network capabilities, facilitating higher speeds and improved service delivery. The Asia Pacific region, accounting for 37.6% of the market share, will continue to lead due to its large population and growing infrastructure. However, potential risks including regulatory hurdles and economic downturns impede market growth. Addressing these challenges will be crucial for the market to realize its forecasted potential.
By Equipment Type: Optical Line Terminals (OLTs), Optical Network Terminals (ONTs) and Optical Network Units (ONUs), Digital Subscriber Line Access Multiplexers (DSLAMs) and Multi-Service Access Nodes (MSANs), Cable Modem Termination Systems (CMTS) and Converged Cable Access Platforms (CCAPs), Cable Modems and Gateways, Broadband Access Switches and Aggregation Equipment, Others (Fiber Distribution Nodes, Remote PHY Devices, and Broadband Access Extenders)
By Technology: Gigabit Passive Optical Network (GPON), Ethernet Passive Optical Network (EPON), 10-Gigabit Symmetric Passive Optical Network (XGS-PON), Next-Generation Passive Optical Network 2 (NG-PON2), Data Over Cable Service Interface Specification (DOCSIS), Digital Subscriber Line (DSL), including G.fast, Others (25G-PON and 50G-PON)
By Application: High-Speed Internet Access, Voice Over Internet Protocol (VoIP), Video Streaming and Video on Demand (VoD), Smart Home Connectivity, Cloud and Enterprise Connectivity, Remote Work and Digital Education, Internet of Things (IoT) Connectivity
By End User: Residential, Commercial, Industrial, Government, Data Centers
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Fixed-Line Broadband Access Equipment market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 4.9% from 2026 to 2033 |
Revenue Unit | USD billion |
Segmentation | By Equipment Type, Technology, Application, End User, and Region |
By Region | North America (By Equipment Type, Technology, Application, End User, and Country)
|
Europe (By Equipment Type, Technology, Application, End User, and Country)
| |
Asia Pacific (By Equipment Type, Technology, Application, End User, and Country)
| |
South America (By Equipment Type, Technology, Application, End User, and Country)
| |
Middle East and Africa (By Equipment Type, Technology, Application, End User, and Country)
|
Find answers to common questions about this report
The Fixed-Line Broadband Access Equipment market size was valued at USD 13.3 billion in 2025.
The market is projected to grow at a CAGR of 4.9% during the forecast period from 2026 to 2033.
The North America Fixed-Line Broadband Access Equipment market size is estimated to reach USD 4.9 billion by 2033.
Optical Network Terminals (ONTs) and Optical Network Units (ONUs) lead the Fixed-Line Broadband Access Equipment market with a projected value of USD 5.1 billion by 2033. This segment surpasses others in terms of revenue generation within the market.
The surge in demand for high-speed internet access driven by remote work, online education, and video streaming significantly boosts investments in Fixed-Line Broadband Access Equipment. The increasing adoption of Next-Generation Passive Optical Network 2 (NG-PON2) enhances network efficiency and accommodates growing data consumption patterns.
Asia Pacific holds the dominant share of the Fixed-Line Broadband Access Equipment market, with a regional share of 37.6 percent. This position reflects its leading status compared to North America and Europe.
High costs associated with Fixed-Line Broadband Access Equipment hinder adoption among residential users. Budget constraints lead to slower uptake of advanced technologies, impacting overall market growth.
The increasing consumer demand for high-speed internet access and enhanced connectivity solutions is driving the adoption of Optical Network Terminals (ONTs). This trend is further supported by the ongoing digital transformation, which emphasizes the need for advanced optical network solutions to accommodate heightened online content consumption.
The Fixed-Line Broadband Access Equipment market is estimated to reach a valuation of USD 19.5 billion by 2033.
Key players operating in the Fixed-Line Broadband Access Equipment market include Nokia Corporation, Huawei Technologies, ZTE Corporation, Adtran, Calix, CommScope, Harmonic Inc., and TP-Link.
The analysts below cover Information & Technology research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Most industry reports on warehouse automation bundle autonomous mobile robots and fixed conveyor installations into the same top-level numbers, which complicates advisory work. This study split the market cleanly by payload tiers, navigation technology, and fleet management software layers. The regional forecast for Western Europe gave our team defensible adoption benchmarks when evaluating capital allocation for logistics clients, saving us days of secondary data scrubbing.
Standard industry briefs frequently blur the operational distinctions between isobaric pressure exchangers and centrifugal turbines. In this study, MetaStat Insight categorized mega-scale desalination tenders across the GCC and Mediterranean basins by membrane replacement frequencies and salinity tolerances. Their primary research helped us evaluate local content requirements in Saudi Arabia and the UAE without relying on marketing literature. We found the segment-level equipment replacement estimates grounded and well-reasoned throughout.
The technical breakdown of ISO 20022 migration readiness across correspondent banking corridors was remarkably thorough. Rather than treating cross-border corporate payments as a single block, the report drew a useful distinction between multilateral netting platforms and domestic instant payment rails across ASEAN economies. MetaStat Insight highlighted regulatory constraints on foreign exchange liquidity management that many publications gloss over. The research material offered practical clarity for our platform development roadmap.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950
Starting from
$2950