
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Internet Services Market Size, Share, By Access Technology (Fiber Optic, Cable, Digital Subscriber Line (DSL), Fixed Wireless Access, Mobile Broadband, Satellite and Others (Power-Line Broadband and Legacy Access)), By Customer Type (Residential, Business and Government), By Service Level (Best-Effort Internet Access and Guaranteed-Bandwidth Internet Access), By Billing Model (Postpaid Subscription and Prepaid Access), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-5687
Published
November, 2026
Pages
293 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
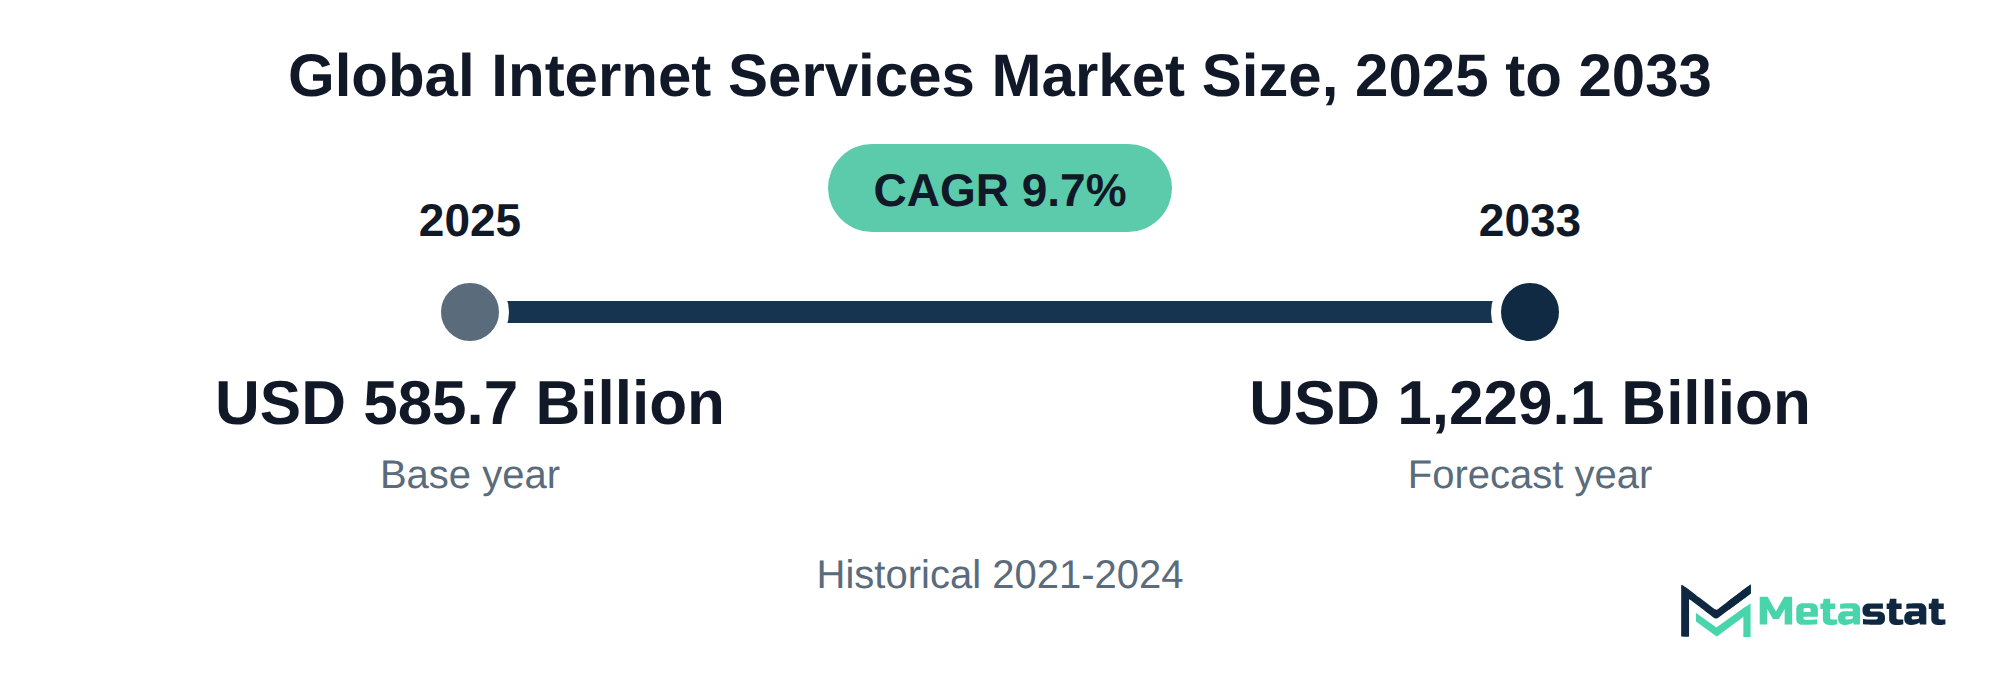
Market Valuation: Valued at $585.7 Billion in 2025, projected to reach $1,229.1 Billion by 2033 at a 9.7% CAGR.
Dominant Segment: Fiber Optic technology leads the market, driven by the increasing demand for high-speed internet and reliable connectivity, particularly in residential and business sectors.
Geographic Lead: North America is the leading region in the Internet Services market, holding 28.1% of the market in 2025, with the US expected to maintain its dominance in 2026 due to robust infrastructure and consumer readiness.
What's Inside: The report provides a comprehensive analysis of the competitive landscape, detailed segment breakdowns by access technology, customer type, service level, and billing model, along with growth forecasts through 2033.
Emerging Opportunities: The growing demand for fiber optic access presents significant opportunities for service providers to enhance connectivity and capture a larger market share, particularly in underserved regions.
Price Sensitivity Impact: Price sensitivity among consumers poses challenges for adoption, particularly for higher-tier services, which may slow growth in segments like Guaranteed-Bandwidth Internet Access.
Choose Your License
Global Internet Services Market
The global Internet Services market was valued at USD 585.7 billion in 2025 and is projected to reach USD 1,229.1 billion by 2033, growing at a CAGR of 9.7% over the forecast period.
The Internet Services market includes offerings that provide connectivity and access to information. Buyers invest in these services for various reasons, including the necessity for reliable communication, enhanced business operations, and the growing demand for online content. This investment reflects an ongoing shift toward digitalization across multiple sectors, driving expenditures on internet services to support both personal and professional needs.
Growth in the market is fueled by several factors, including increasing internet penetration and the demand for faster and more reliable services. The segment with the most substantial value is Fiber Optic technology, which is expected to see considerable expansion. North America holds 28.1% of the market in 2025, with the US leading in 2026. This regional dominance highlights the significance of robust infrastructure and consumer readiness to adopt advanced internet solutions.
One primary growth driver stems from the rising need for high-speed internet, particularly in residential and business sectors. Enhanced bandwidth capabilities support the proliferation of streaming services, remote work, and online gaming, contributing to the overall market expansion. Numerous players compete for market share by innovating and enhancing their service offerings.
The Internet Services market addresses the increasing demand for reliable and high-speed connectivity across various sectors. Buyers invest in this market to enhance operational efficiency, improve customer experiences, and leverage digital technologies for business growth. Factors including remote work, e-commerce expansion, and the integration of smart technologies contribute to heightened spending on internet services.
Growth in the market is driven primarily by the rising adoption of fiber optic technology, which offers superior speed and reliability compared to traditional access methods. Among the segments, fiber optic stands out with significant value, reflecting the shift towards advanced connectivity solutions. North America holds 28.1% of the market in 2025, with the US leading in 2026, while Asia Pacific follows closely, representing a substantial portion of overall demand.
Investment in infrastructure and technological advancements fuels the expansion of the Internet Services market. Continuous changes in consumer expectations and the demand for higher bandwidth support ongoing growth. Service providers increasingly focus on enhancing their offerings to meet these demands, ensuring a competitive edge in a digital environment.
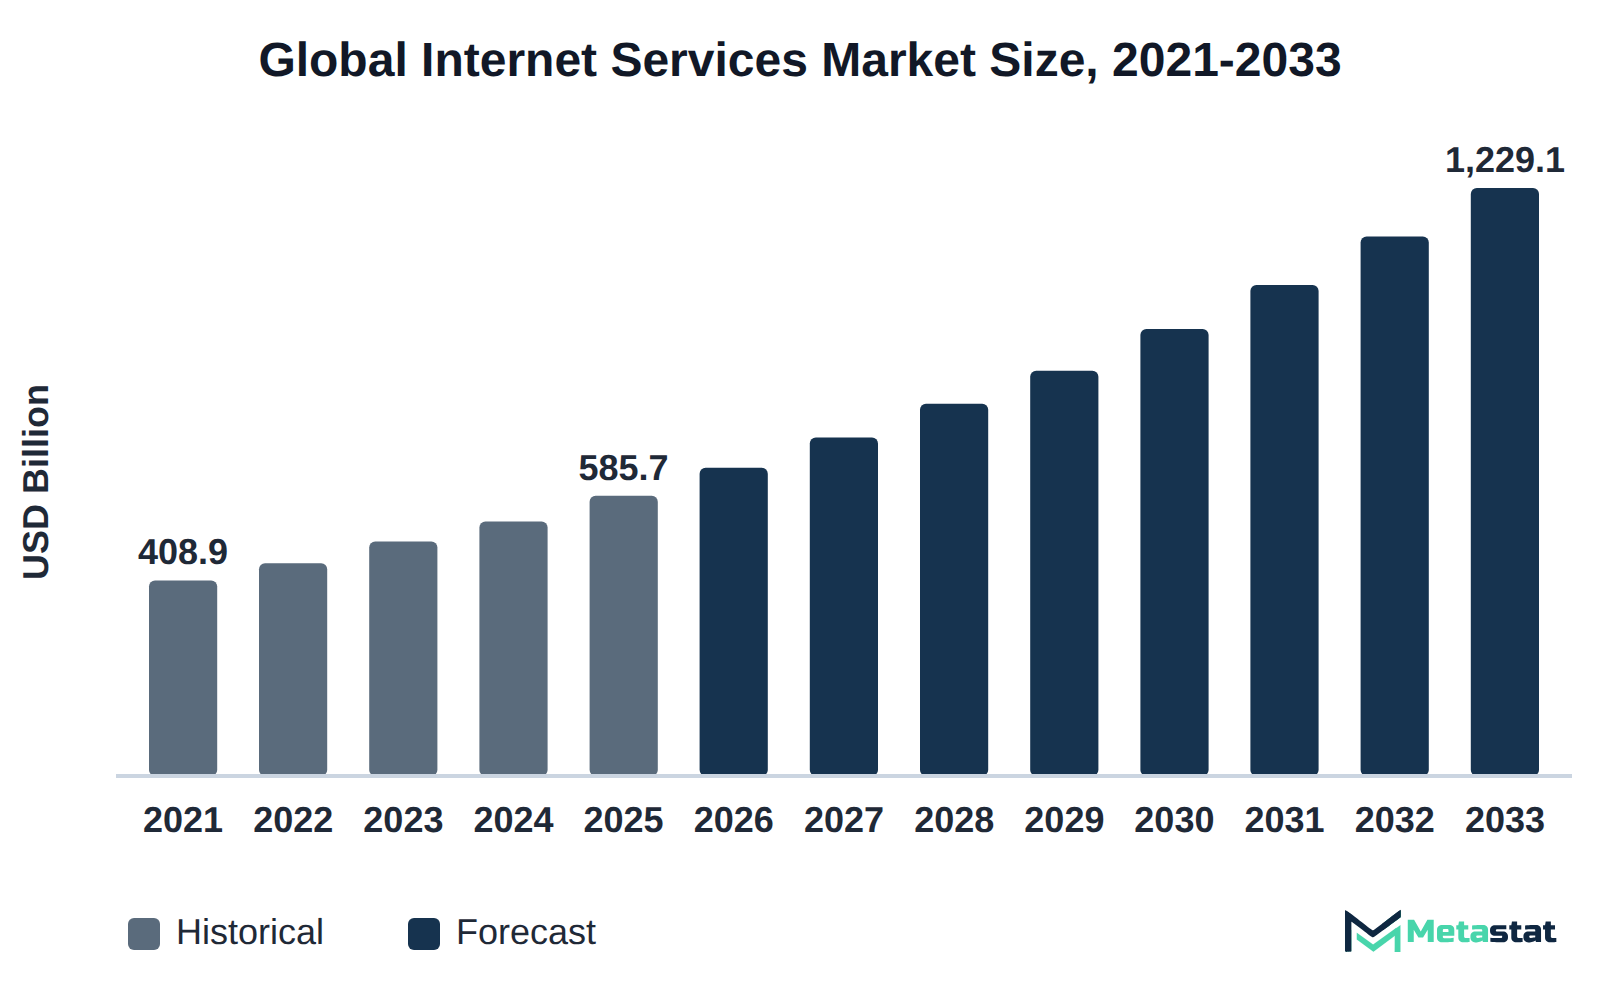
The shift towards fiber optic upgrades and the deployment of 5G fixed wireless technology significantly transforms broadband delivery in the Internet Services market. Fiber optic connections are expected to grow from USD 236.9 billion in 2026 to USD 462.4 billion by 2033, enhancing speed and reliability for users. This transition supports increased demand for high-bandwidth applications, including video streaming and cloud services.
5G fixed wireless access, with an anticipated compound annual growth rate (CAGR) of 15.2%, offers an alternative to traditional wired connections, especially in underserved areas. This technology enables high-speed internet access without extensive infrastructure investments, appealing to both residential and business customers. The integration of these technologies expands market reach and enhances consumer satisfaction by providing scalable and efficient solutions.
These advancements have significant implications for network operators and service providers. Upgrading to fiber and implementing 5G technologies allows companies to capture a larger share of the market, aligning with consumer expectations for faster and more dependable internet services. This evolution shapes the competitive landscape for Internet Services, pushing providers to innovate continuously and invest in next-generation infrastructure.
Managed security bundles represent a crucial enhancement in the offerings of Internet Service Providers (ISPs), enhancing their competitive positioning within the Internet Services market. These bundles typically incorporate cybersecurity features, providing customers with comprehensive protection against various online threats. In 2025, the market value reached USD 585.7 billion, highlighting the increasing demand for integrated services that combine traditional internet access with enhanced security measures.
The pricing structures for these managed security bundles vary significantly. Most ISPs adopt a tiered pricing model, aligning costs with the level of service provided. For example, offerings often range from basic protections to advanced cybersecurity services, enabling customers to select packages that suit their specific needs and budget. This flexibility in pricing encourages wider adoption among several customer types, including residential and business segments.
Differentiating their services through managed security bundles allows ISPs to attract new customers and retain existing ones, creating long-term relationships. The introduction of such packages signals a shift toward more value-added services in the market, ultimately enhancing revenue streams and driving growth. The prevalence of cyber threats also underlines the need for strong internet security, which supports demand for these integrated service offerings.
Enterprise customers increasingly demand strong Service Level Agreements (SLAs) to support their cloud and distributed workloads. These SLAs ensure reliable performance and faster recovery times, critical for businesses that rely on uninterrupted Internet connectivity. The segment for Guaranteed-Bandwidth Internet Access is projected to reach USD 311.2 billion by 2033, reflecting significant demand for high-performance services that enterprise buyers require.
With the growth of remote work and cloud applications, organizations prioritize Internet Services that provide guaranteed performance metrics. This demand arises from the need for effective collaboration and efficient operation across distributed teams. Enterprise customers often seek providers who deliver consistent bandwidth and low latency, which are essential for applications including video conferencing and large file transfers.
The push towards more reliable performance directly impacts the competitive landscape, as providers enhance their service offerings to meet these specific enterprise needs. Companies that successfully deliver comprehensive SLAs position themselves favorably within the Internet Services market, facilitating long-term partnerships and customer retention.
ISPs face critical decisions when selecting between Fiber, Fixed Wireless, and Satellite Broadband technologies. The choice heavily influences service delivery, customer satisfaction, and overall market competitiveness. Fiber Optic technology stands out with a projected growth rate of 10% CAGR, increasing from USD 236.9 billion in 2026 to USD 462.4 billion by 2033. This technology offers high-speed connections and high reliability, making it attractive to both residential and business customers.
In contrast, Fixed Wireless Access features a substantial growth trajectory of 15.2% CAGR, reflecting its cost-effective deployment in underserved areas. This technology serves customers where traditional infrastructure proves challenging. Satellite Broadband provides an alternative solution, particularly in remote regions, enabling accessibility in locations lacking adequate terrestrial infrastructure.
The decision between these technologies ultimately hinges on factors including installation costs, customer demand, and geographic considerations. The evolving landscape of the Internet Services market necessitates that ISPs assess their strategic priorities, ensuring they remain competitive while meeting diverse customer needs.
Rapid increases in remote work and online activities drive heightened demand from residential customers. The pandemic led to significant lifestyle shifts, with more individuals relying on stable internet connections for work, education, and entertainment. This change in behavior results in higher volumes of internet subscriptions and a willingness to invest in enhanced service levels. Residential internet services are projected to grow from USD 310.2 billion in 2026 to USD 580.5 billion in 2033, reflecting a compound annual growth rate of 9.4%. This substantial growth emphasizes the ongoing shift towards advanced connectivity solutions, ultimately benefiting service providers within the Internet Services market.
Advancements in fiber optic technology and fixed wireless access significantly enhance broadband connectivity options. The transition towards high-capacity fiber networks allows providers to offer faster and more reliable internet services, catering to increasing demand for reliable online experiences. In parallel, fixed wireless access technology provides an alternative for underserved regions, enabling connectivity without the extensive infrastructure required for traditional wired networks.
These technologies attract a diverse range of customers, including residential users seeking high-speed internet and businesses requiring dependable connections for operations. The Internet Services market benefits from this dual growth, with fiber optic services projected to reach USD 462.4 billion by 2033, reflecting a CAGR of 10%. Fixed wireless access, characterized by its scalability, supports rapid deployment in areas lacking robust broadband infrastructure. Such innovations help providers maintain their competitive advantage and sustain investment in network capabilities.
Price sensitivity represents a significant barrier for residential and business customers within the Internet Services market. Rising costs associated with high-speed internet packages result in slower uptake among price-conscious consumers, leading to smaller order volumes and delayed service upgrades. Many buyers prioritize affordable options, limiting their willingness to commit to premium services that offer enhanced features. This trend particularly affects the adoption of guaranteed-bandwidth internet access, which typically comes at a higher price point compared to best-effort internet access. Increased competition among service providers drives pricing pressures, impacting profitability and potential investments in infrastructure. Consequently, the market experiences restrained growth due to this price sensitivity, influencing customer choices and overall service demand.
Challenges related to talent acquisition and retention create pressure on profitability within the Internet Services market. Suppliers face increasing competition for skilled labor, particularly in technical roles, where demand for expertise in network management and cybersecurity escalates. The shortage of qualified professionals results in high labor costs, which restrict operational margins for providers. To address these challenges, companies invest in training and development programs to enhance workforce skills and productivity. Several firms explore partnerships with educational institutions to secure a steady pipeline of new talent. These strategies aim to mitigate talent-related expenses while maintaining competitive service levels, which are crucial for sustaining growth in a changing market. The financial implications of talent acquisition represent a significant concern for businesses, directly influencing their ability to adapt to evolving customer needs and enhance service offerings.
Growth in the Fiber Optic segment presents substantial opportunities within the market. Businesses and residential customers increasingly demand high-speed connectivity, driving investments in advanced fiber optic infrastructure. The transition to fiber optics enables Internet Service Providers (ISPs) to offer superior bandwidth, enhancing customer satisfaction and operational efficiency.
The rising emphasis on high-performance internet solutions encourages businesses to adopt fiber optic technology, particularly in regions with underdeveloped access options. This creates a significant opportunity for ISPs to capture a larger market share through targeted offerings. The expansion of fiber optic networks supports the overall growth of the Internet Services market, with improved connectivity capabilities driving digital transformation across various industries.
The Global Internet Services market is segmented based on Access Technology, Customer Type, Service Level, and Billing Model.
This technology primarily serves residential and business customers, facilitating high-speed internet access and enhancing overall connectivity. Demand for fiber optic services is driven by the increasing need for reliable and high-speed internet, particularly owing to the rise of remote work and digital services. Compared to other access technologies, including Cable and Digital Subscriber Line (DSL), the Fiber Optic segment exhibits a higher growth rate, reflecting its advantages in bandwidth and speed. The anticipated expansion in this segment highlights its critical role in meeting the evolving demands of customers and supports strengthening long-term demand within the market.
Cable technology is estimated to reach USD 210.5 billion by 2033, at a CAGR of 6.4% during the forecast period. Factors including increased demand for reliable connectivity and the growing number of internet-connected devices contribute to the expansion of the cable segment. Unlike fiber optic, which experiences a higher growth rate due to its superior performance, cable offers a more established infrastructure and often lower installation costs. The price point for cable services typically remains competitive compared to emerging alternatives, appealing to budget-conscious consumers. While fiber optic technology is projected to grow at a CAGR of 10%, the cable segment's gradual growth reflects stable demand from a broad customer base. The continuing reliance on cable for high-speed internet access highlights its vital role in the market.
Digital Subscriber Line (DSL) segment is expected to reach USD 71.8 billion by 2033. This technology facilitates high-speed internet access over traditional telephone lines, serving residential and small business customers. Market demand stems from the need for reliable internet connectivity, particularly in areas where fiber optic infrastructure is limited. DSL offers a compelling alternative, especially in rural regions, where other high-speed options are not available. Compared to other access technologies, DSL has a slower growth rate, indicating that advancements in fiber optic and cable technology are more appealing to users seeking faster internet speeds. Despite its slower growth trajectory, DSL continues to play a vital role in the overall Internet Services market, providing essential connectivity for millions of users globally.
Fixed Wireless Access is projected to grow at a CAGR of 15.2% during the forecast period. This technology provides broadband connectivity through radio signals, commonly found in rural and underserved urban areas where traditional wired infrastructure lacks feasibility. The segment sees strong demand driven by the need for reliable internet access amid increasing online activities and remote work trends. Compared to other segments including Fiber Optic, which is expected to achieve a CAGR of 10%, Fixed Wireless Access offers a faster growth trajectory due to its ability to rapidly deploy in areas with limited existing infrastructure. This segment appeals predominantly to residential users requiring flexible and accessible internet solutions.
Mobile Broadband is a crucial technology for users seeking flexible and portable internet access. It primarily benefits consumers and businesses that require connectivity while on the move, facilitating activities including streaming, online communication, and cloud access. Rapid advancements in mobile technology and the expansion of 4G and 5G networks significantly drive growth in this segment. The increasing demand for high-speed internet among urban populations enhances mobile broadband adoption, distinguishing it from other access technologies including Fiber Optic or Cable, which typically offer more stable but less portable connections. Competitive pricing strategies employed by mobile service providers improve affordability, making mobile broadband an attractive option for a wider audience, including residential customers and small businesses.
Satellite technology provides internet connectivity through satellites orbiting the Earth, serving various users including residential customers in remote areas and businesses requiring reliable communication solutions. This segment sees demand driven by the necessity for internet access in regions lacking infrastructure for traditional broadband services. Satellite technology differs from other access technologies including fiber optic and cable in that it offers wider coverage, particularly in rural and underserved locations. However, this segment typically faces challenges related to latency and higher costs compared to terrestrial options. While growth for satellite technology is expected to proceed at a slower rate, its unique positioning fills critical gaps in connectivity that other technologies struggle to address. The Internet Services market continues to evolve, with satellite technology maintaining relevance amid growing competition from other access technologies.
Others (Power-Line Broadband and Legacy Access) encompasses technologies like power-line communication and older access methods that continue to serve specific markets. These solutions typically cater to both residential users in areas lacking modern infrastructure and businesses seeking cost-effective options. Demand for these technologies arises largely from the need for connectivity in underserved regions. Adoption faces challenges due to competition from newer technologies like fiber optics, which offer higher speeds and reliability. While this segment grows at a slower pace compared to fiber optic solutions, its unique positioning allows it to maintain relevance among certain buyer groups prioritizing affordability over performance. Consequently, the Internet Services market experiences varied growth dynamics across its segments.
This segment serves individual households, providing essential internet connectivity for daily activities including work, education, and entertainment. Factors driving this segment include the growing reliance on digital platforms and robust demand for high-speed internet access. Compared to business and government sectors, residential customers exhibit unique purchasing behavior, focusing on affordability and ease of access. The growth of the residential segment reflects a steady increase in broadband subscriptions and a shift towards higher-quality service levels. The transition from lower-speed connections to fiber optic and high-capacity broadband highlights the evolving needs of consumers in an increasingly digital world. The Internet Services market benefits from these trends, shaping competitive dynamics and service offerings.
Business segment is estimated to reach USD 538.6 billion by 2033, at a CAGR of 9.5% during the forecast period. This segment serves a diverse range of enterprises, including small businesses, large corporations, and various public institutions. Businesses rely on robust internet services for critical operations, including data management, online communication, and cloud computing. Growth in this segment is driven by increasing digital transformation initiatives and heightened demand for reliable connectivity solutions. Compared to residential services, business internet services typically command higher prices due to enhanced performance and support levels required. This segment grows at a CAGR of 9.5%, making it a key area of focus within the Internet Services market. It reflects the evolving needs of organizations pursuing efficient online operations.
The Government and Public Institutions segment is expected to reach USD 110 billion by 2033. This segment serves various governmental entities and public organizations that rely on stable and secure internet connectivity for operations, communication, and public service delivery. A growing emphasis on digital transformation within the public sector drives demand for reliable internet services to support initiatives including e-governance and smart city projects. This segment's growth rate is lower compared to the Business segment, which is projected to reach USD 538.6 billion by the same year, with a CAGR of 9.5%. Unique regulatory requirements and budget constraints faced by government entities often result in longer procurement processes, impacting the speed of adoption relative to other customer types. The Internet Services market continues to adapt to these factors, reflecting the specific needs and challenges of the Government and Public Institutions segment.
Best-Effort Internet Access segment is valued at USD 495.1 billion in 2026 and is projected to reach USD 917.9 billion by 2033, at a CAGR of 9.2% during the forecast period. This segment primarily serves residential and small business customers who prioritize affordability and basic internet connectivity. Demand for this service is driven by increasing reliance on internet access for daily activities and entertainment. Compared to Guaranteed-Bandwidth Internet Access, this segment typically offers a lower price point, making it attractive for cost-conscious users. However, the lack of guaranteed speeds creates challenges for users requiring more reliable performance. While demand for Best-Effort Internet Access continues to grow steadily, it faces competition from higher-tier service options that provide enhanced performance and reliability.
Guaranteed-Bandwidth Internet Access segment is estimated to reach USD 311.2 billion by 2033, at a CAGR of 11.1% during the forecast period. This segment primarily serves businesses and government institutions requiring reliable and consistent internet connectivity for operations and services. Key growth drivers include the increasing demand for high-quality streaming, online gaming, and telecommuting, which necessitate greater bandwidth consistency. Unlike Best-Effort Internet Access, which does not guarantee specific performance levels, Guaranteed-Bandwidth Internet Access ensures dedicated bandwidth, making it a superior option for users needing stable connections. The segment's growth rate of 11.1% surpasses the 9.2% CAGR of its counterpart, reflecting the heightened focus on service quality in the Internet Services market. This focus aligns with the broader market trend toward enhanced service levels and customer satisfaction, further validating the strategic importance of this segment.
Postpaid Subscription segment is valued at USD 528 billion in 2026 and is projected to reach USD 988.4 billion by 2033, at a CAGR of 9.4% during the forecast period. This segment provides internet access to customers under a contractual agreement, primarily appealing to residential and business users. The steady demand from these customer types drives growth, owing to their desire for reliable internet services with predictable monthly costs. This segment stands out with a significant growth rate compared to other billing models, including Prepaid Access, which is projected to grow at a CAGR of 11% but with a lower anticipated total value of USD 240.6 billion by 2033. Key factors influencing the segment include the increasing adoption of smart home technology and the demand for reliable connectivity, which enhance the user experience and encourage long-term subscriptions. The market continues to evolve, responding to these trends through competitive pricing and service offerings.
This segment serves consumers and businesses seeking flexibility and budget control in their internet services. Demand for prepaid options arises from customers who prefer to avoid long-term contracts and upfront fees associated with traditional billing models. The growth of this segment is driven by increasing consumer awareness of cost-effective solutions and the rise of digital payment methods. Unlike postpaid subscriptions, which experience a CAGR of 9.4%, prepaid access shows faster growth. This rapid expansion reflects a shift in consumer preferences, influencing the overall dynamics of the Internet Services market.
Based on geography, the Global Internet Services market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
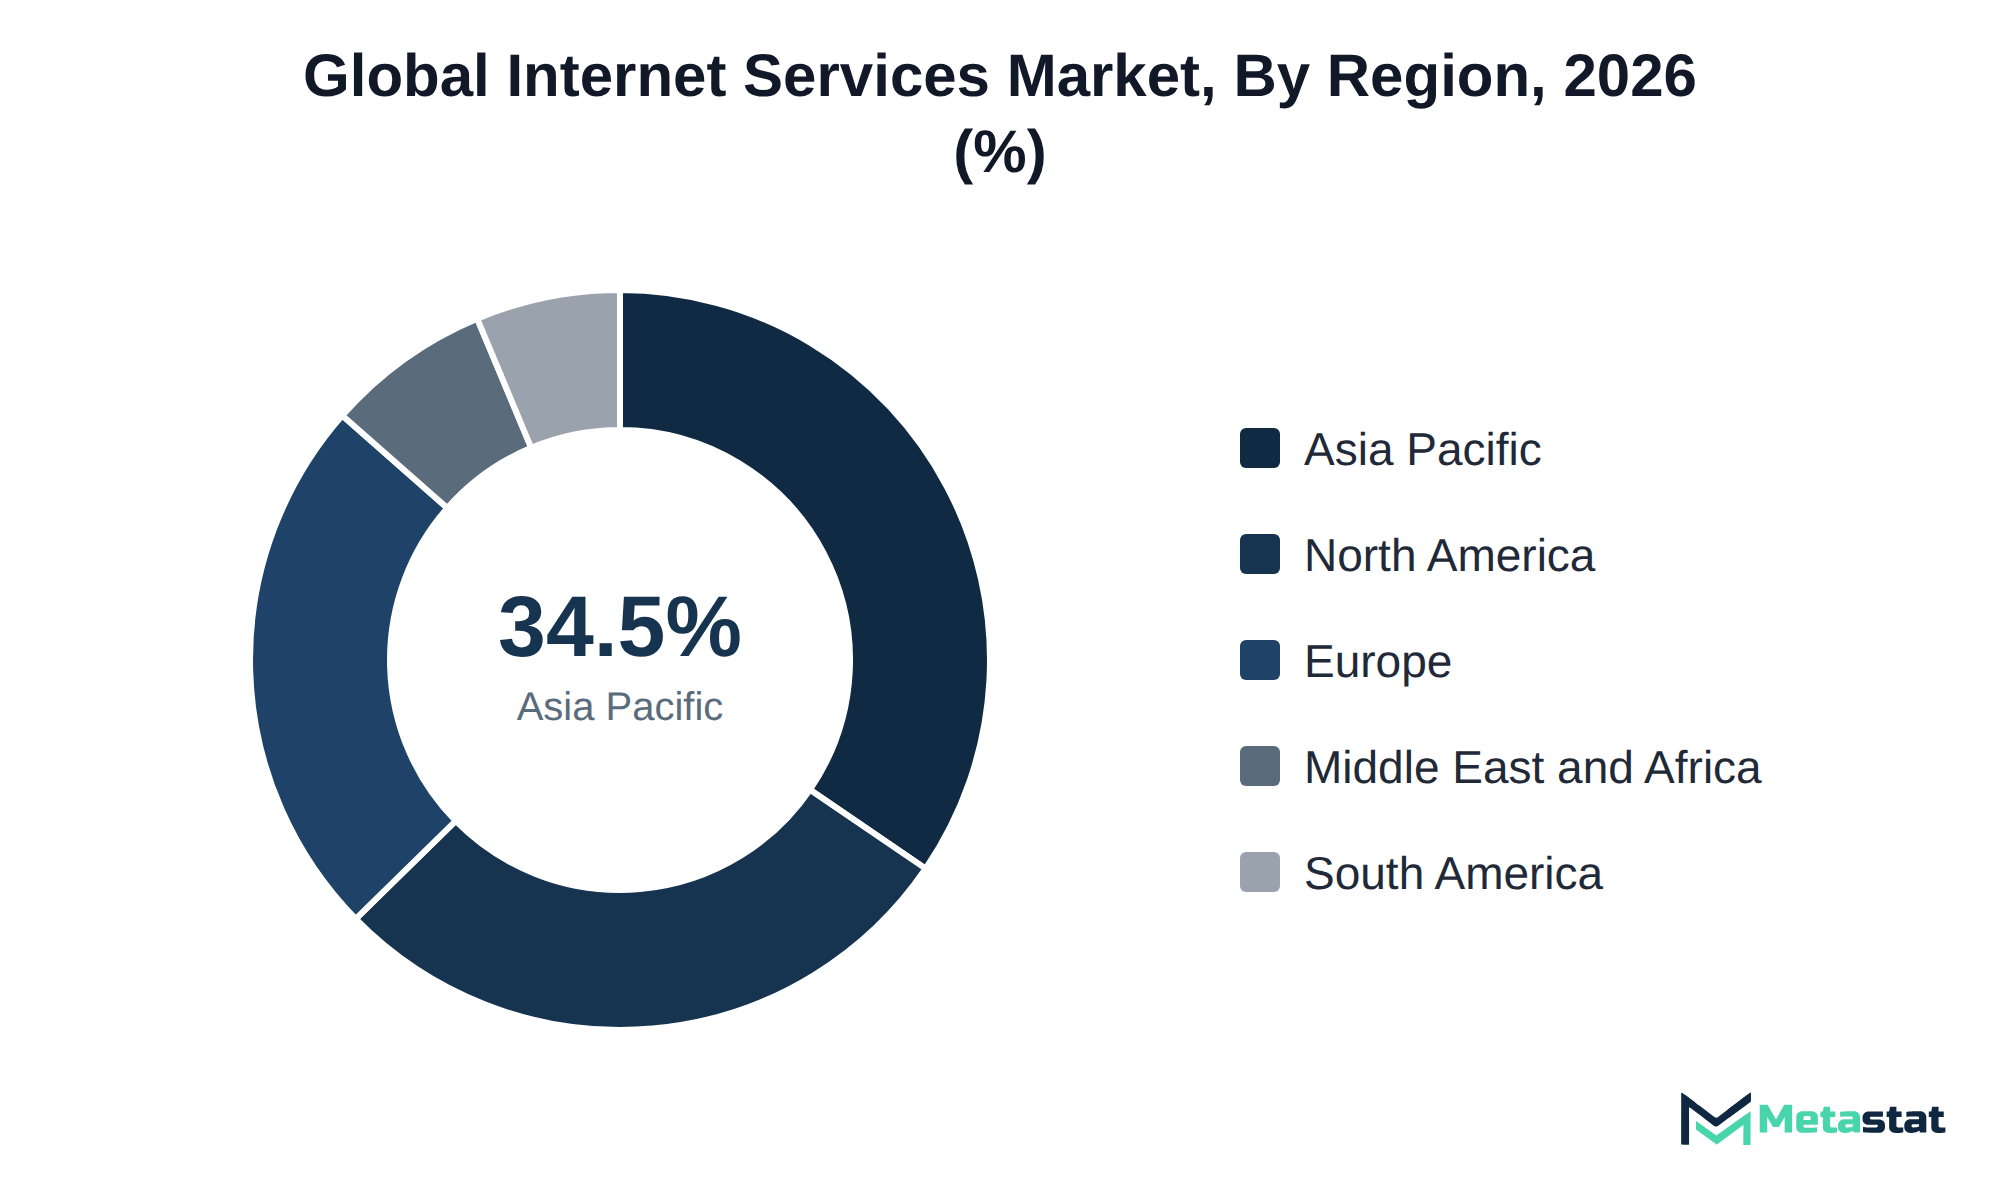
North America represents a significant market for internet services, projected to reach USD 312.5 billion by the end of 2033. The United States, Canada, and Mexico are key players driving demand across various segments, including residential and business sectors. A robust infrastructure, characterized by high-speed fiber optic networks, underpins this growth. Investment in advanced broadband technologies continues to enhance connectivity, catering to the increasing need for reliable internet access among consumers and enterprises. Regulatory support encourages competition among service providers, facilitating innovative pricing models and service offerings. With a market share of 28.1% in 2025, the internet services market in North America is projected for sustained expansion, driven by both residential and commercial adoption of advanced technologies.
Demand for internet services in Europe reflects a growing reliance on digital connectivity across various sectors, particularly in Germany, France, the UK, Italy, and Spain. The region's diverse industries, including finance, e-commerce, and entertainment, drive significant investment in high-speed internet infrastructure. The European market benefits from robust regulatory frameworks that encourage competition and innovation among service providers. Key players focus on enhancing fiber optic networks to meet the increasing demand for high bandwidth. The market share in Europe is projected at 23.8% in 2025, indicating a strong position within the overall global internet services market. Rising consumer expectations and the push for digital transformation across governments and businesses further support this growth trajectory.
The Asia-Pacific region stands out in the Internet Services market, driven by high demand for digital connectivity across various sectors. Key players in this region include China, Japan, India, South Korea, and Australia, where technology adoption rapidly accelerates. The region accounts for 34.5% of the global market share in 2025. Significant investments in infrastructure development enhance access to high-speed internet, particularly through Fiber Optic and Fixed Wireless Access technologies. Rapid urbanization and a growing middle class contribute to rising demand from residential consumers, while businesses increasingly seek reliable internet solutions to support their operations. Government initiatives aimed at expanding broadband access further stimulate growth in this market. The competitive environment intensifies as local providers innovate to capture evolving consumer and business needs.
In South America, the Internet Services market experiences demand driven by the growing need for reliable connectivity in Brazil and Argentina. Expanding digital infrastructure, particularly in urban areas, supports the adoption of various internet services. The region's unique economic conditions, including fluctuating currency values and diverse pricing strategies, influence service accessibility. By 2025, the market accounts for 6.3% of the global share, with expectations for continued growth due to improving access. Rising interest in e-commerce and digital services among consumers and businesses heightens the urgency for enhanced internet connectivity and bandwidth capabilities. Investments in fiber optic technology and mobile broadband create opportunities for players in this evolving market.
The growth of the Internet Services market in the Middle East and Africa is driven by increasing demand for digital solutions among various sectors, particularly in Saudi Arabia and the UAE. Regional infrastructure improvements support the expansion of internet services, with government initiatives focused on enhancing connectivity. South Africa experiences rising adoption of high-speed internet services, catering to both residential and business customers. Market players invest in technologies that improve service delivery and address the unique needs of local consumers. The Internet Services market in this region reflects an evolving consumer base seeking reliable and high-speed connectivity.
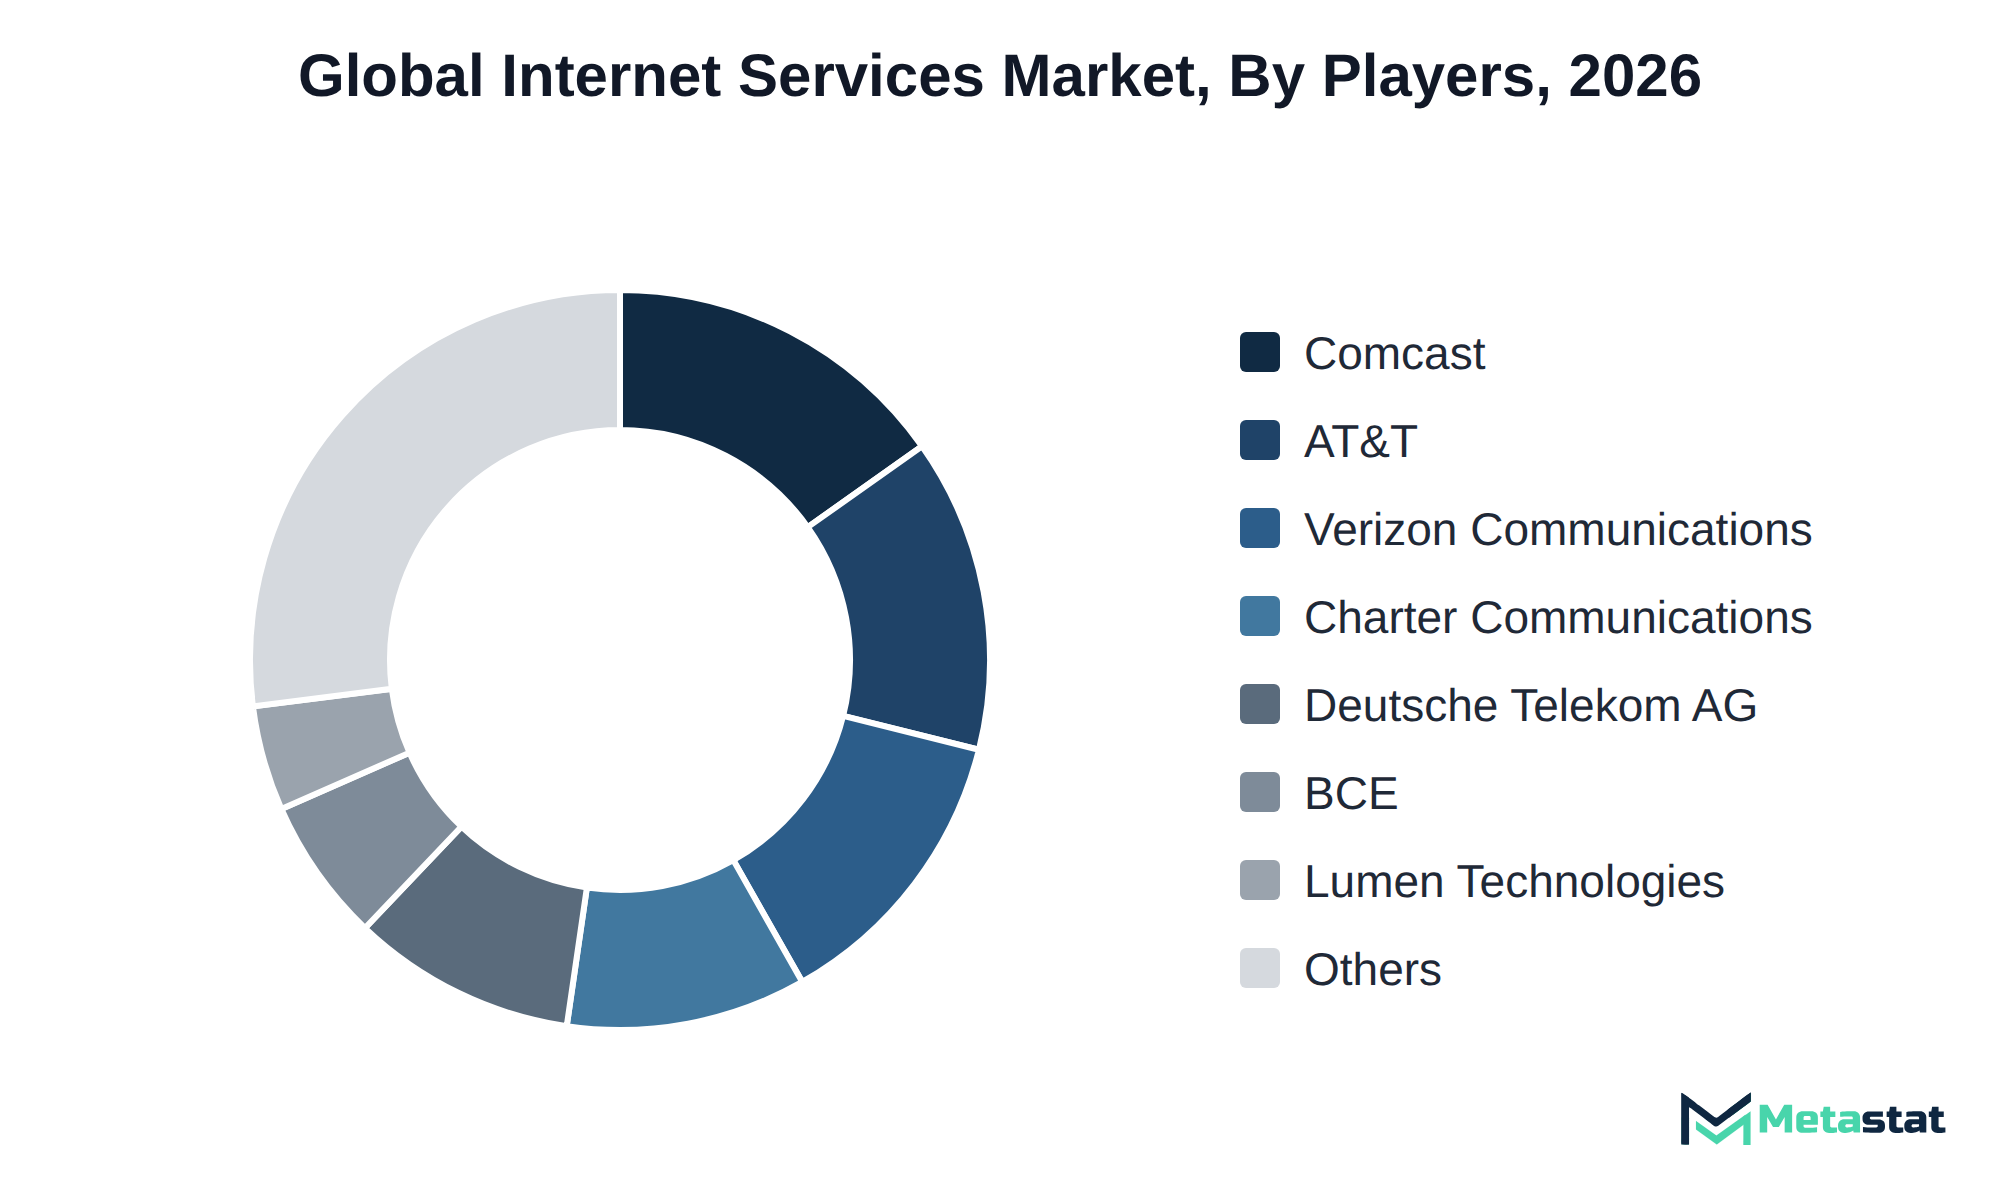
Companies in the Internet Services market use several competitive strategies to differentiate themselves. Many focus on specific segments including Fiber Optic, Cable, and DSL, tailoring their offerings to meet the needs of residential, business, and governmental customers. For instance, AT&T Inc. emphasizes its investment in Fiber Optic technology, while Comcast Corporation prioritizes its Cable services to capture a substantial customer base.
Buyers select services based on price, customization, and service reliability. The market features a variety of service levels, including Best-Effort Internet Access and Guaranteed-Bandwidth Internet Access, which influence buyer decisions. Companies like Verizon Communications Inc. and Charter Communications, Inc. excel in delivering tailored solutions that enhance customer satisfaction and build loyalty.
This growth relies on several key developments within the Internet Services market. The rising demand for Guaranteed-Bandwidth Internet Access will support growth, aiming for USD 311.2 billion by 2033, with a CAGR of 11.1%. However, a primary risk that could slow market growth lies in regulatory challenges across various regions, particularly in North America, which holds a share of 28.1% of the market. Market players must navigate these regulatory hurdles to capture the anticipated growth opportunities.
By Access Technology: Fiber Optic, Cable, Digital Subscriber Line (DSL), Fixed Wireless Access, Mobile Broadband, Satellite, Others (Power-Line Broadband and Legacy Access)
By Customer Type: Residential, Business, Government and Public Institutions
By Billing Model: Postpaid Subscription, Prepaid Access
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Internet Services market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 9.7% from 2026 to 2033 |
Revenue Unit | USD billion |
Segmentation | By Access Technology, Customer Type, Service Level, Billing Model, and Region |
By Region | North America (By Access Technology, Customer Type, Service Level, Billing Model, and Country)
|
Europe (By Access Technology, Customer Type, Service Level, Billing Model, and Country)
| |
Asia Pacific (By Access Technology, Customer Type, Service Level, Billing Model, and Country)
| |
South America (By Access Technology, Customer Type, Service Level, Billing Model, and Country)
| |
Middle East and Africa (By Access Technology, Customer Type, Service Level, Billing Model, and Country)
|
Find answers to common questions about this report
The Internet Services market size was valued at USD 585.7 billion in 2025.
The market is projected to grow at a CAGR of 9.7% during the forecast period from 2026 to 2033.
The North America Internet Services market size is estimated to reach USD 312.5 billion by 2033.
Fiber Optic leads the Internet Services market with a projected value of USD 462.4 billion by 2033, reflecting the highest growth rate among access technologies.
Key drivers for the Internet Services market include increased demand from residential customers due to remote work and online activities, along with substantial growth in the Fiber Optic segment. Investments in advanced fiber optic infrastructure enhance customer satisfaction and operational efficiency, supporting overall market expansion.
Price sensitivity represents a significant barrier, with rising costs associated with high-speed internet packages leading to slower uptake among price-conscious consumers. Challenges related to talent acquisition and retention create pressure on profitability, with the shortage of qualified professionals resulting in increased labor costs that restrict operational margins for providers.
The growth in the Fiber Optic segment presents significant opportunities, driven by increasing demand for high-speed connectivity from both businesses and residential customers. Investments in advanced fiber optic infrastructure enhance customer satisfaction and operational efficiency, facilitating broader adoption across various industries.
The Internet Services market is estimated to reach a valuation of USD 1,229.1 billion by 2033.
Key players operating in the Internet Services market include AT&T Inc., Verizon Communications Inc., Comcast Corporation, Charter Communications, Inc., Deutsche Telekom AG, Orange S.A., Telefónica, S.A., and Vodafone Group Plc.
The Fiber Optic segment is projected to grow from USD 236.9 billion in 2026 to USD 462.4 billion by 2033, reflecting a compound annual growth rate of 10%.
The analysts below cover Information & Technology research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Most industry reports on warehouse automation bundle autonomous mobile robots and fixed conveyor installations into the same top-level numbers, which complicates advisory work. This study split the market cleanly by payload tiers, navigation technology, and fleet management software layers. The regional forecast for Western Europe gave our team defensible adoption benchmarks when evaluating capital allocation for logistics clients, saving us days of secondary data scrubbing.
Standard industry briefs frequently blur the operational distinctions between isobaric pressure exchangers and centrifugal turbines. In this study, MetaStat Insight categorized mega-scale desalination tenders across the GCC and Mediterranean basins by membrane replacement frequencies and salinity tolerances. Their primary research helped us evaluate local content requirements in Saudi Arabia and the UAE without relying on marketing literature. We found the segment-level equipment replacement estimates grounded and well-reasoned throughout.
The technical breakdown of ISO 20022 migration readiness across correspondent banking corridors was remarkably thorough. Rather than treating cross-border corporate payments as a single block, the report drew a useful distinction between multilateral netting platforms and domestic instant payment rails across ASEAN economies. MetaStat Insight highlighted regulatory constraints on foreign exchange liquidity management that many publications gloss over. The research material offered practical clarity for our platform development roadmap.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950