
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Streaming Services Market Size, Share, By Media Type (Video Streaming, Audio Streaming, Game Streaming, Others), By Content Type (Live Streaming, On-Demand Streaming, Live and On-Demand Streaming), By Platform (Smartphones, Laptops & Desktops, Smart TVs, Tablets, Others), By Revenue Model (Subscription-Based, Advertisement-Based, Transaction-Based, Hybrid), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-4032
Published
October, 2026
Pages
286 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
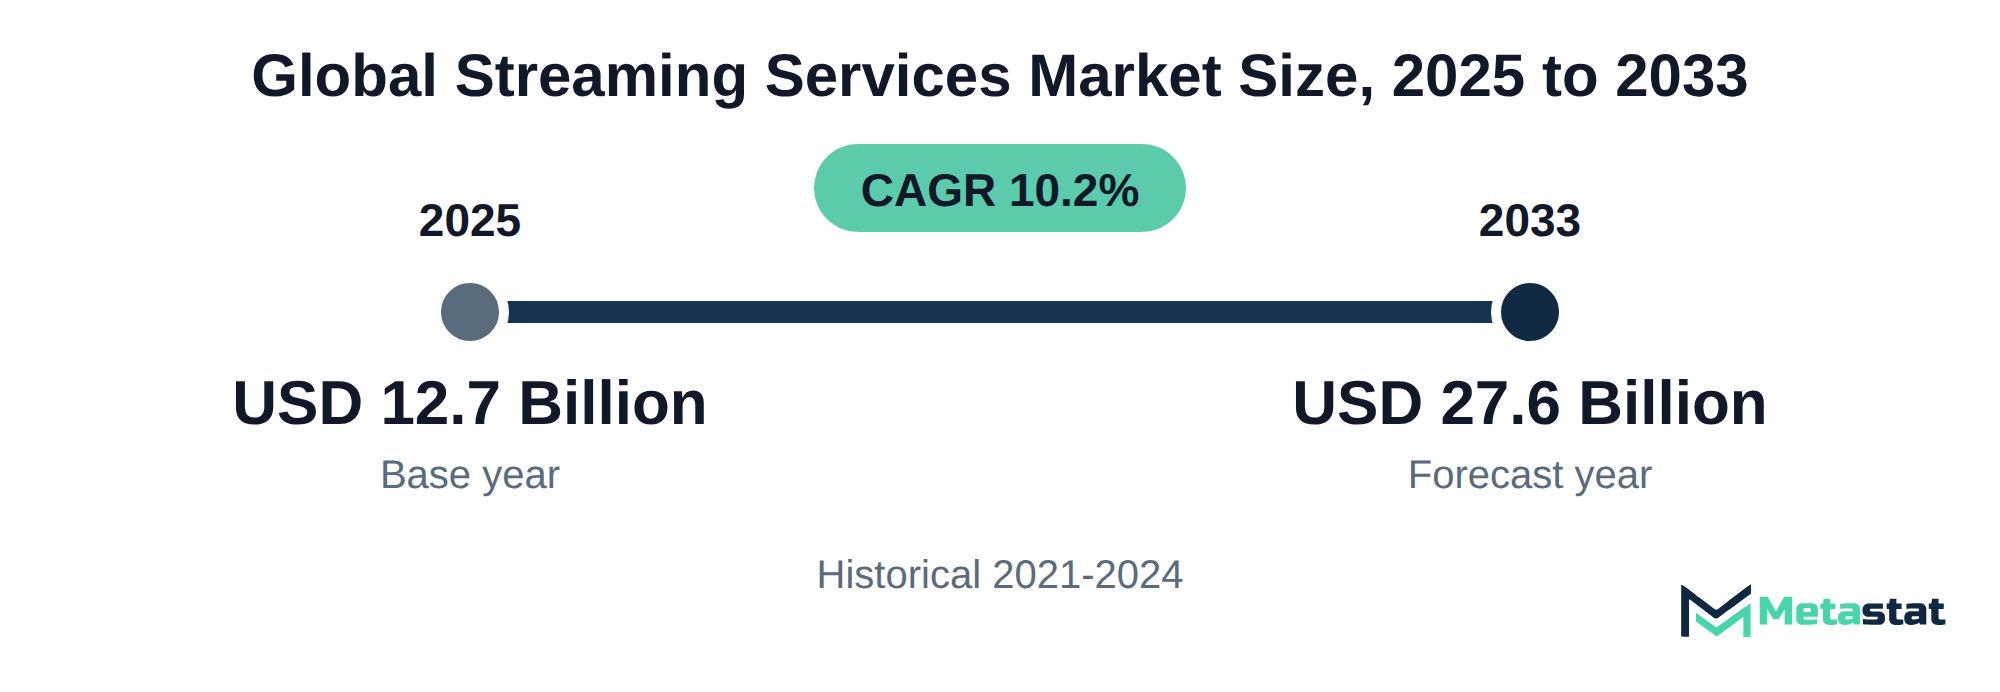
Market Valuation: Valued at $12.7 Billion in 2025, projected to reach $27.6 Billion by 2033 at a 10.2% CAGR.
Dominant Segment: Video streaming leads the market, driven by increasing consumer preference for on-demand content and the convenience of digital platforms.
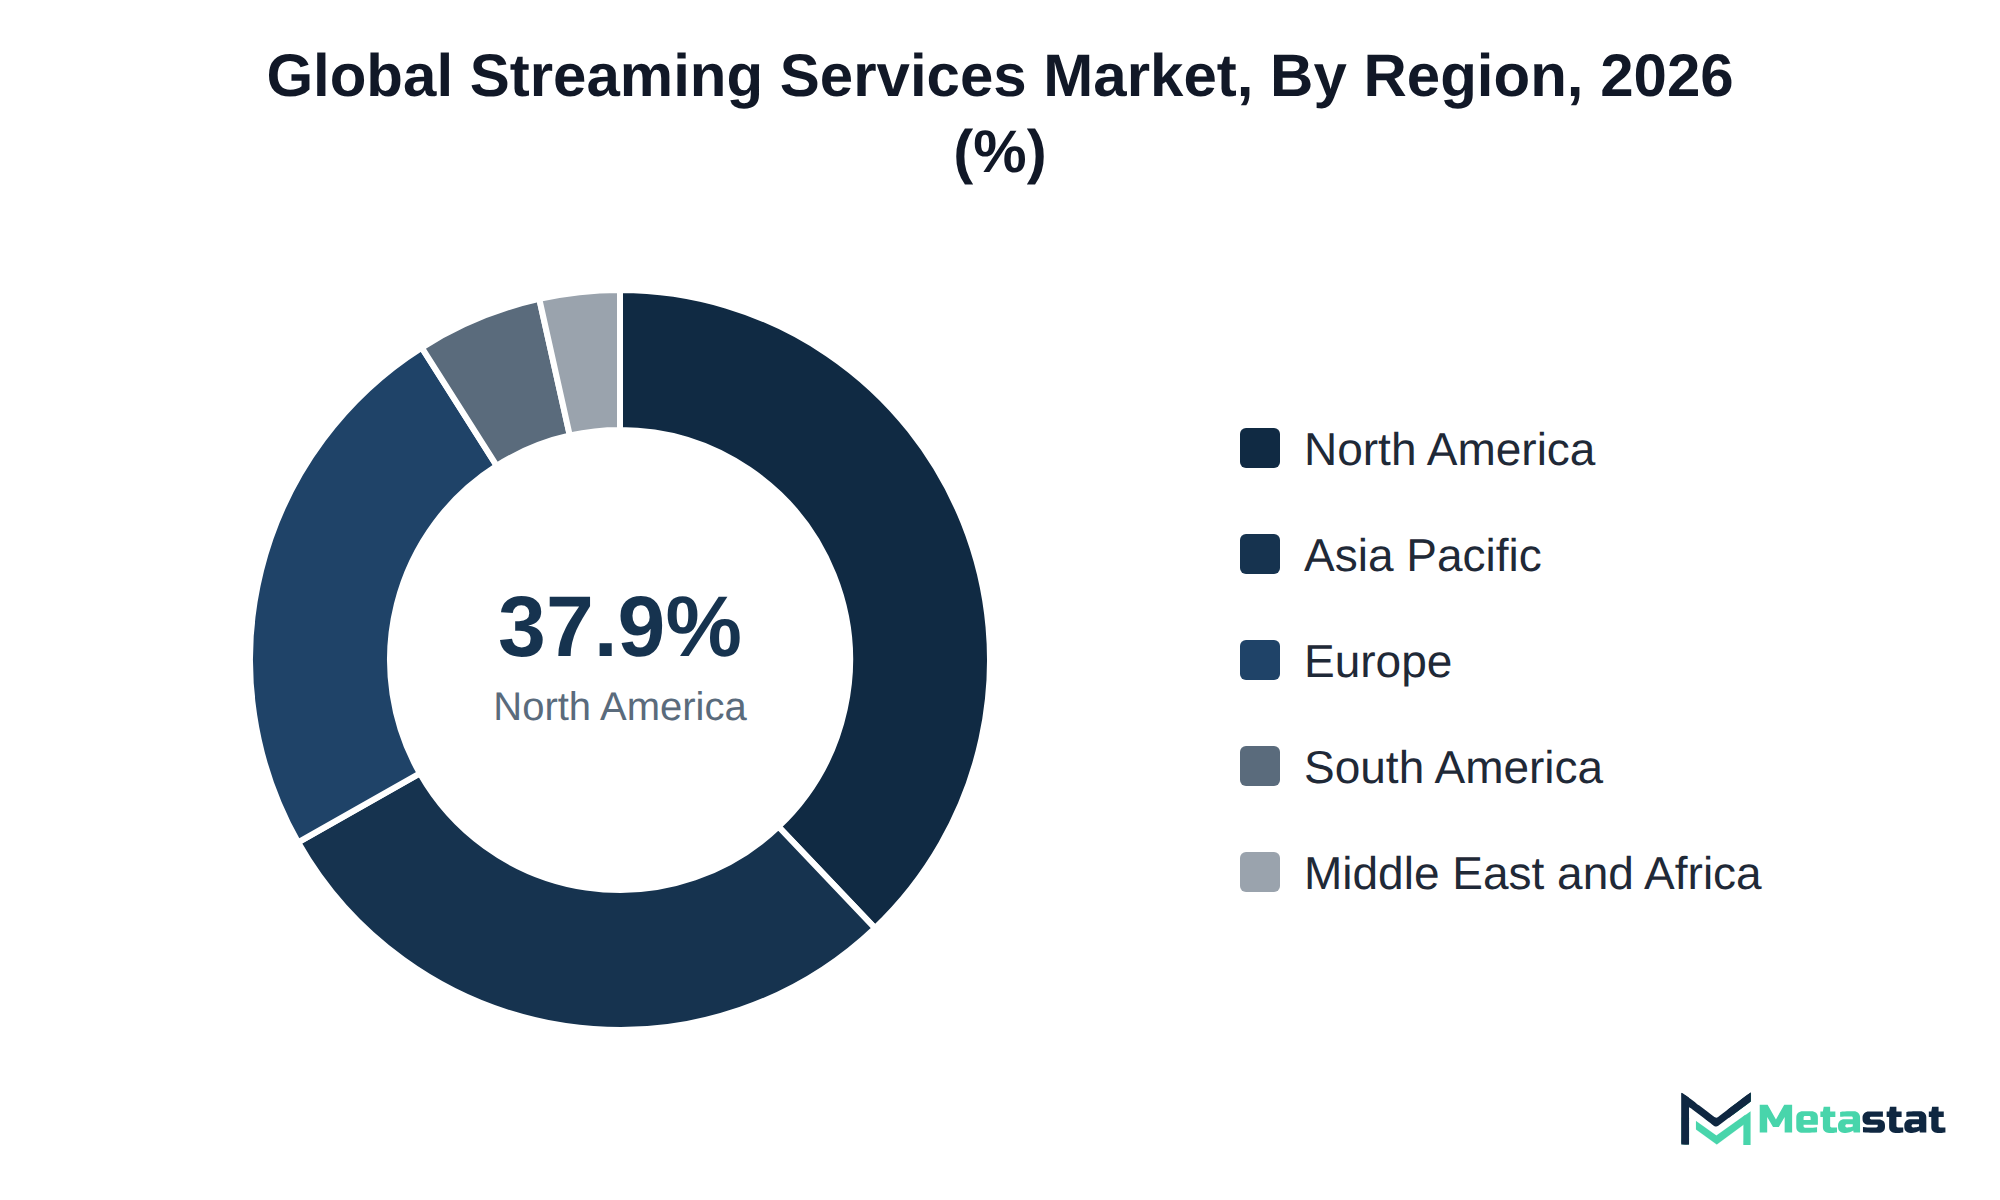
Geographic Lead: North America is the leading region, capturing 37.9% of the market in 2025, with the U.S. expected to maintain its dominance through 2026.
What's Inside: The report provides a comprehensive analysis of market dynamics, competitive landscape, and detailed forecasts across various segments and regions.
Emerging Trends: Audio streaming is experiencing rapid growth, projected to reach USD 2.7 billion by 2033, fueled by the demand for mobile and on-the-go content consumption.
Investment Insights: Investment in live sports rights is surging, with the video streaming segment expected to generate USD 11.8 billion in 2026, reflecting a strong focus on exclusive content.
Choose Your License
Global Streaming Services Market
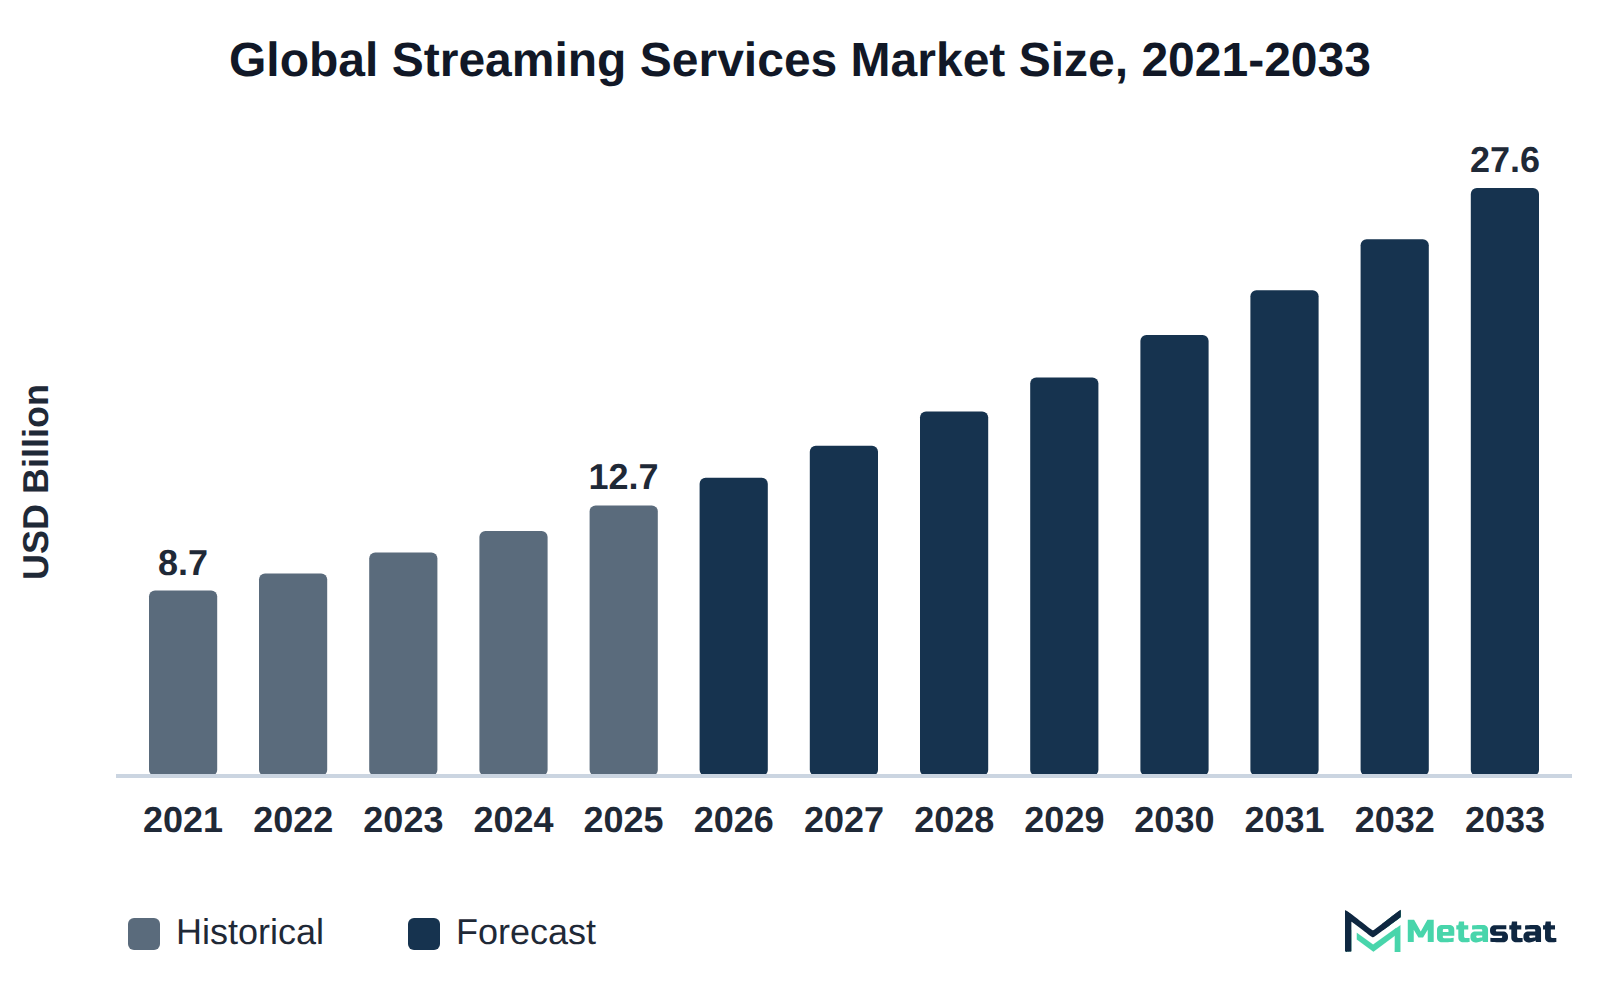
The global Streaming Services market was valued at USD 12.7 billion in 2025 and is projected to reach USD 27.6 billion by 2033, growing at a CAGR of 10.2% over the forecast period.
The Streaming Services market encompasses various forms of content delivery, including video, audio, and game streaming, catering to diverse consumer preferences. Buyers invest in these services due to increasing demand for on-demand entertainment and the convenience offered by digital platforms. The availability of high-quality content and the ability to access it across multiple devices further enhance the appeal of these services.
Growth in the market is driven by rising penetration of high-speed internet and growing adoption of smart devices. Video streaming stands out as the most valuable segment, contributing significantly to overall market revenue. North America holds 37.9% of the market in 2025, with the US leading in 2026. The Asia Pacific region follows closely, capturing 28.9% of the market.
The need for continuous innovation in content offerings and user experience serves as a primary growth driver for the Streaming Services market. Increasing consumer engagement and shifting viewing habits accelerate demand for diverse content types, including live and on-demand streaming. Providers focus on enhancing their platforms to cater to evolving consumer preferences, reinforcing their positions in this expanding market.
The Streaming Services market provides a range of digital content options, fulfilling consumer demand for on-the-go entertainment. Buyers invest in these services to access diverse programming, including movies, music, and live events, which enhances their viewing experience. This demand is supported by the increasing integration of streaming into daily routines, reflecting a shift in consumer entertainment preferences.
Growth in the market is driven by technological advancements and the proliferation of internet connectivity, enabling easy access to streaming platforms. Video streaming represents the largest segment, showing significant revenue potential, while North America holds 37.9% of the market in 2025, with the US leading in 2026. The Asia Pacific region follows closely, demonstrating a strong growth trajectory fueled by a growing middle class and increasing smartphone penetration.
Investment in original content and subscription models drives market expansion. Companies prioritize unique offerings to attract and retain subscribers, resulting in competitive pricing strategies. Diverse revenue models and a broad user base support further growth in the Streaming Services market.
The rise of ad-supported streaming services significantly changes viewer engagement and monetization strategies within the Streaming Services market. Revenue generated through advertisement-based models is projected to reach USD 11.2 billion by 2033, reflecting a compound annual growth rate of 10.5%. This shift results from evolving consumer preferences for more flexible options, allowing access to content without a full subscription fee.
Hybrid subscription plans that combine traditional ad-free models with ad-supported tiers appeal to various audience segments, enhancing subscriber acquisition while maintaining profitability. This dual approach caters to budget-conscious consumers who prioritize content access over premium viewing experiences.
The integration of ad-supported options allows streaming platforms to diversify revenue streams, providing advertisers with targeted reach while enhancing overall platform engagement. Connected TV advertising is one channel through which advertisers reach these streaming audiences. Streaming services adopting these innovative models expand their market presence, adapting to evolving consumer demands and increasing competition.
Investment in live sports rights has surged within the Streaming Services market, driven by increasing demand for exclusive content. The competitive landscape intensifies as streaming platforms strive to secure broadcasting agreements for popular sports events, positioning themselves as primary destinations for sports enthusiasts. In 2026, the video streaming segment is projected to generate USD 11.8 billion, escalating to USD 22.5 billion by 2033, reflecting a compound annual growth rate (CAGR) of 9.7%. This substantial growth demonstrates the financial viability of investing in live sports rights.
Buyers in the market typically engage in multi-year contracts, which provide a steady stream of revenue for content providers. These agreements often involve substantial upfront payments, reflecting the high value associated with exclusive rights to major sporting events. Such investments attract subscribers and raise user engagement, which leads to higher retention rates. Platforms focused on sports content differentiate themselves from competitors through unique offerings, including live game broadcasts, highlights, and in-depth analysis.
While demand for live sports content continues to rise, platforms are likely to recalibrate their pricing strategies to maximize profitability while remaining competitive. The increasing value of sports rights has significant implications for revenue generation, influencing how platforms structure subscription models and advertising opportunities. Live sports therefore drive growth and engagement in the Streaming Services market.
Music streaming subscription pricing strategies shape user engagement and retention in the Streaming Services market. The growth of subscription-based revenue models, projected to reach USD 8.7 billion by 2033, highlights the increasing reliance on this approach. Bundling services with other offerings, including video streaming or exclusive content, raises perceived value for customers seeking all-in-one entertainment.
Consumers, particularly millennials and Generation Z, seek affordable options that provide access to vast music libraries alongside additional benefits. The music publishing industry manages the rights to many of the works in these libraries. Tailoring pricing strategies to meet these distinct needs strengthens customer loyalty and drives subscription growth. For example, a successful bundling strategy that includes music streaming alongside video services attracts diverse user demographics, resulting in a broader market presence.
The competitive nature of the Streaming Services market drives companies to innovate continuously, refining their pricing models to capture larger segments of the audience. Organizations that adapt their offerings to consumer preferences position themselves for sustained revenue growth.
Bundling services effectively reduces subscriber churn in the Streaming Services market. This strategy combines multiple offerings, including video, audio, and game streaming, into a single package, enhancing the perceived value for consumers. The approach reflects strong demand for bundled services that provide diverse content options at competitive pricing.
By offering bundled packages, streaming platforms address a key consumer desire for convenience and variety, which increases customer loyalty. This approach leads to greater retention rates, enabling platforms to maintain a steady revenue stream. Customer loyalty and retention software gives providers a way to measure and manage that retention. Companies achieve operational efficiencies through streamlined marketing and distribution efforts, further enhancing profitability. The flexibility of bundling allows service providers to capture distinct segments of the market, responding to varying customer preferences effectively.
Shifts in consumer behavior drive increased spending on video streaming platforms, particularly among younger demographics. Users prioritize on-demand content and convenience, leading to a significant rise in subscriptions. The growing preference for streaming services over traditional cable television has resulted in a continuous increase in engagement and spending. The transition to online content delivery models positions video streaming services as the preferred choice for entertainment.
A strong focus on content diversity and accessibility strengthens the competitive landscape. Users increasingly seek varied programming, including original productions, live events, and interactive content, which fuels the market's overall expansion. Investment in quality content and innovative features positions platforms to capture a larger share of consumer interest and spending.
Advancements in streaming technology drive significant growth within the Streaming Services market. Enhanced internet connectivity, particularly the rollout of 5G, allows for faster data transmission and improved streaming quality, appealing to consumers seeking high-quality viewing experiences. The introduction of adaptive bitrate streaming optimizes video delivery, adjusting to varying bandwidth conditions, which enhances user satisfaction. Content delivery networks support this delivery by serving video from servers located closer to viewers. Innovations in compression algorithms reduce file sizes while maintaining high video quality, enabling broader access to high-definition content across diverse devices.
These technological improvements attract various buyer groups, including entertainment enthusiasts, gamers, and casual viewers, all eager for high-quality experiences. The increased demand for devices supporting these technologies, including smart TVs and gaming consoles, contributes to market expansion. Ultimately, investment in these innovative streaming technologies encourages competition among service providers, promoting the development of unique features and content offerings. This competitive environment supports the market's growth trajectory.
Low awareness of available streaming options restricts growth in the Streaming Services market, particularly among older demographics and less tech-savvy users. This group exhibits slower uptake and smaller orders due to unfamiliarity with various platforms and content types. Insufficient marketing efforts targeting these demographics result in limited knowledge of subscription models, unique content offerings, and technological advancements. Consequently, this lack of awareness leads to delayed decision-making regarding service subscriptions, impacting overall market penetration. Educational initiatives and targeted advertising campaigns could enhance market visibility. Their absence continues to hinder expansion. The ongoing challenge of bridging this awareness gap remains critical for suppliers aiming to reach a broader audience and maximize revenue opportunities in the market.
Suppliers within the Streaming Services market face significant margin pressure, primarily driven by escalating content acquisition costs. Competition for exclusive programming intensifies as various platforms strive to attract and retain subscribers. High-profile partnerships and licensing agreements contribute to increased expenditures, affecting profitability across the sector. Consequently, platforms explore strategies to streamline content costs while enhancing viewer engagement. Analyzing data allows platforms to assess viewer preferences, enabling targeted investments in content that appeals to audiences.
Several suppliers implement innovative revenue models, including bundling services with popular offerings to increase perceived value without significantly raising costs. The shift toward hybrid subscription plans has emerged as a strategic response to balance content costs while maintaining subscriber growth. Platforms that adapt in this way manage margin pressure effectively and position themselves for sustained success.
Rapid growth within audio streaming reflects changing consumer preferences, particularly for on-the-go content consumption. This segment is projected to reach USD 2.7 billion by 2033, demonstrating a compound annual growth rate (CAGR) of 11.6%. The increasing accessibility of music and podcast platforms drives demand, particularly among younger audiences who prioritize mobile listening experiences. Companies that adopt subscription-based and advertisement-based revenue models effectively capture this emerging market. The differentiation between free and premium offerings enhances user acquisition efforts and engagement levels. The expanding integration of audio streaming into daily routines confirms its role as a preferred entertainment choice. Increasing investments in exclusive music content and podcast series further enhance the perceived value of audio streaming services. Evolving consumer habits and technological advancements in streaming platforms support continued market growth.
The Global Streaming Services market is segmented based on Media Type, Content Type, Platform, and Revenue Model.
This segment caters to a wide range of consumers seeking digital entertainment, including films, television shows, and original content produced by various streaming platforms. A significant force driving growth in this segment stems from increasing consumer preference for on-demand content, which allows users to access entertainment at their convenience. This trend contrasts with audio streaming, which has a higher CAGR of 11.6%, highlighting a notable difference in demand dynamics. The competitive landscape within video streaming encompasses a variety of pricing models, with subscription-based options being predominant. The market for video streaming continues to evolve, influenced by technological advancements and changing viewer habits.
This segment serves music lovers and content creators who prioritize convenient access to a vast library of audio content. Growing consumer demand for personalized playlists and podcasts drives this segment, with platforms offering tailored experiences to enhance user engagement. Audio Streaming stands out from the video segment in terms of growth rate, showing a faster CAGR compared to video streaming's 9.7%. The flexibility of audio content consumption on various devices, including smartphones and smart speakers, supports its adoption among diverse age groups. Advancements in technology and greater integration with social media platforms facilitate deeper connections between users and audio content, further enhancing competitive dynamics within the market.
Game Streaming segment is expected to reach USD 1.9 billion by 2033. This segment appeals to gamers who seek live streaming of gameplay, providing an interactive experience that differs from traditional gaming formats. Cloud gaming services, which run games on remote servers and stream them to the player's device, are a closely related offering. Increasing smartphone penetration and improved internet infrastructure drive growth in this segment, facilitating access for a broader audience. The demographic primarily includes younger consumers, who actively engage in gaming and seek community interaction through streaming platforms. Compared to video streaming, which has a CAGR of 9.7%, game streaming is projected to exhibit a higher growth rate, driven by technological advancements and an expanding gaming culture. Game streaming offers unique monetization strategies, including subscription models and interactive advertisements, distinguishing it from other media types in the market.
Others (Interactive and Specialty Streaming) segment is projected to grow at a CAGR of 14% during the forecast period. This segment encompasses various niche offerings that cater to specific audience interests, including live interactive events and specialized content not typically found in mainstream streaming services. Consumers engage with this type of content for entertainment, education, or unique experiences, appealing particularly to diverse demographics seeking alternatives to conventional media. Rising demand for innovative and interactive experiences fuels growth in this area, differentiating it from mainstream video and audio streaming segments, which have lower CAGRs of 9.7% and 11.6%, respectively. The segment's unique offerings allow for premium pricing strategies, often resulting in higher revenue per user compared to traditional subscription models, which strengthens its market position.
Live Streaming segment is valued at USD 3 billion in 2026 and is projected to reach USD 6.2 billion by 2033, at a CAGR of 10.7% during the forecast period. This segment caters to consumers seeking real-time content delivery for events including sports, concerts, and live shows. Engaging younger audiences through interactive formats significantly influences demand, with many providers integrating social features and audience participation. Compared to On-Demand Streaming, which is anticipated to reach USD 11.6 billion by 2033 at a CAGR of 8.5%, Live Streaming demonstrates a faster growth trajectory, appealing to a demographic that prioritizes immediacy and real-time engagement. The increasing popularity of live sports, gaming events, and social media interactions drives this segment's expansion, distinguishing it from other content types in the market.
This segment focuses on audio and video on-demand streaming, where viewers access content at their convenience, making it popular among consumers seeking flexibility in their viewing habits. Users typically include individuals preferring to curate their entertainment experiences without the constraints of scheduled programming. One driving force for this segment involves the increasing demand for diverse content offerings, which allows viewers to choose from various genres and formats. Compared to other segments, including Live Streaming, this segment reflects slower growth due to market saturation and established player dominance. Live Streaming is expected to grow at a CAGR of 10.7%, showing a stronger appeal among audiences seeking real-time content, thus carving a distinct competitive space in the Streaming Services market.
Live and On-Demand Streaming segment is expected to reach USD 9.8 billion by 2033. This segment serves users seeking both live events and on-demand viewing options, appealing to a broad audience that includes sports fans, entertainment enthusiasts, and casual viewers. Increased demand for flexible viewing options drives growth, with audiences gravitating toward platforms that offer live broadcasts alongside extensive libraries of on-demand content. The segment exhibits a CAGR of 10.7%, which positions it favorably compared to other content types. Unlike On-Demand Streaming, which focuses strictly on pre-recorded content, Live and On-Demand Streaming combines real-time events with the convenience of on-demand playback, enhancing user engagement. The unique blend of immediacy and flexibility differentiates it from segments that prioritize single content formats, ensuring sustained interest and investment in the market.
Smartphones segment is valued at USD 5.4 billion in 2026 and is projected to reach USD 10.3 billion by 2033, at a CAGR of 9.7% during the forecast period. This segment serves a significant portion of users accessing streaming services on mobile devices, driven by increasing smartphone penetration and the desire for convenient, on-the-go entertainment. The segment experiences strong growth due to the rise of mobile data networks and improved streaming quality, attracting consumers who prioritize accessibility. Compared to other platforms, including Smart TVs and Laptops & Desktops, the smartphone segment offers unique advantages in terms of portability and user engagement. The growth trajectory of smartphones distinguishes it from segments like Laptops & Desktops, which exhibit a slower CAGR of 8% during the same period. Users heavily employ smartphones for both video and audio streaming, reflecting a broader trend toward mobile-first content consumption in the Streaming Services market.
Laptops and desktops segment is estimated to reach USD 4.5 billion by 2033, at a CAGR of 8% during the forecast period. This platform is widely used for video streaming, gaming, and remote work by consumers and businesses alike. Growing internet accessibility and enhanced user experiences drive demand for this segment, particularly among professionals and students who require robust streaming capabilities. Compared to other platforms, laptops and desktops offer larger screens and better processing power, which enhance the viewing experience and attract a different user demographic. This segment’s growth rate is slower than smartphones, which are projected to experience a CAGR of 9.7% during the same period. While competition from mobile devices exists, the need for high-quality content consumption on larger displays ensures steady demand, reinforcing the segment’s role in the Streaming Services market.
Smart TVs segment is expected to reach USD 9.5 billion by 2033. This segment serves consumers seeking enhanced viewing experiences through larger screens and higher resolution formats. Growth in this area is driven by increasing consumer preference for home entertainment systems that offer convenient access to streaming platforms. Unlike other platforms, Smart TVs attract buyers looking for convenience and superior visual quality, setting them apart from devices including laptops and smartphones. The segment experiences steady growth, supported by technological advancements in display quality and integration with popular streaming services. While the CAGR for Smart TVs aligns with the broader market growth, it highlights a robust consumer shift toward immersive viewing experiences, unlike tablets which show slower growth due to a focus on portability.
The tablets segment is projected to grow at a CAGR of 7.1% during the forecast period. This segment appeals to users seeking convenient streaming options, particularly for multimedia consumption including videos, music, and games. The rise in mobile device usage among consumers, particularly students and professionals, strengthens demand for streaming content on tablets. Compared to other platforms, the tablets segment experiences lower projected revenues, with a total value anticipated to reach USD 9.5 billion by 2033. Users often prefer tablets for their larger screens compared to smartphones, enhancing the viewing experience for video content. However, the higher price point of tablets compared to smartphones contributes to slower growth relative to that segment, which is projected to reach USD 10.3 billion in the same timeframe. In the context of the Streaming Services market, tablets enable on-the-go access to diverse content, catering to a growing segment of mobile users.
Others (Streaming Media Players and Set-Top Boxes) comprise devices that facilitate the streaming of content onto televisions or other displays. This segment appeals to consumers seeking enhanced viewing experiences and greater access to a variety of content. Adoption of streaming media players and set-top boxes is driven by the growing demand for high-definition content and the convenience of accessing multiple streaming services on one device. Unlike smartphones and laptops, which are more personal and portable, this segment serves households, focusing on larger screen experiences. The integration of voice control and smart technology in these devices further distinguishes them from other platforms, enhancing user engagement and satisfaction. Although specific figures for this sub-segment are unavailable, its role in the broader Streaming Services market continues to evolve, reflecting trends in user preferences and technological advancements.
Subscription-Based segment is valued at USD 5 billion in 2026 and is projected to reach USD 8.7 billion by 2033, at a CAGR of 8.4% during the forecast period. This revenue model primarily appeals to consumers seeking uninterrupted access to content, with major players offering diverse libraries that enhance user engagement. A significant driver of growth stems from increasing consumer preference for ad-free experiences, further influenced by shifts toward premium content production. Compared to other revenue models, including Advertisement-Based, which is projected to reach USD 11.2 billion by 2033, this segment experiences slower growth due to initial resistance to subscription fees among potential users. However, the demand for high-quality content continues to rise, and a broader consumer base is expected to adopt subscription services, contributing positively to growth in the Streaming Services market.
This segment serves advertisers aiming to reach a wide audience through streaming platforms, providing a cost-effective alternative to traditional advertising methods. Growth in this segment is driven by increasing demand for ad-supported content, particularly among consumers who prefer free access to services. A shift in advertising strategies reflects a broader trend towards digital platforms, enhancing engagement metrics for brands. Compared to other revenue models, including Subscription-Based, which is projected to grow at a CAGR of 8.4%, the Advertisement-Based segment demonstrates faster growth, appealing to different buyer demographics. Advertisers leverage data analytics within these platforms to optimize campaigns, ensuring a competitive edge in the market.
Transaction-Based segment is expected to reach USD 1.2 billion by 2033. This model allows consumers to make one-time payments for specific content, appealing to users who prefer not to commit to ongoing subscriptions. In video, this model is known as transactional video on demand. Engagement with this segment often stems from the desire for flexibility in accessing content without long-term financial commitments. Demand is driven by a growing trend in pay-per-view offerings and exclusive content access. Compared to other revenue models, including Subscription-Based, which is projected to reach USD 8.7 billion by 2033, Transaction-Based presents a slower growth trajectory, reflecting a more niche market position. Buyers in this sub-segment typically seek unique or limited-time content that justifies individual purchases, differentiating it from mainstream subscription-based services.
Hybrid revenue models are projected to grow at a CAGR of 13.3% during the forecast period. This model combines subscription and advertisement-based services, appealing to diverse consumer preferences and maximizing revenue opportunities. Companies leverage hybrid models to attract both users seeking ad-free experiences and those open to advertisements in exchange for lower subscription fees. The increasing demand for cost-effective streaming solutions drives growth in this segment, particularly among budget-conscious consumers. Compared to pure subscription or advertisement-based models, hybrid offerings often capture a broader audience, enhancing engagement and retention rates. This differentiation drives competition among providers striving to deliver compelling content while optimizing their revenue streams in the market. Hybrid models support flexibility for consumers, creating a balance between content access and pricing strategies.
Based on geography, the Global Streaming Services market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Strong demand for streaming services stems from a tech-savvy population in the United States, Canada, and Mexico, driving industry growth. The widespread availability of high-speed internet enhances content accessibility, supporting user engagement across various platforms. In North America, major players invest heavily in original content, further contributing to the market expansion. By 2033, this region is projected to reach USD 9.6 billion, holding a 37.9% share of the global market in 2025. The rising popularity of subscription models and the shift towards ad-supported content are reshaping revenue structures within the market. Overall, the North American streaming services market exhibits significant growth potential, driven by evolving consumer preferences and increased competition for audience attention.
Growth in the Streaming Services market within Europe is driven by a diverse array of content preferences and increasing internet penetration rates. Countries including Germany, France, and the UK lead in adopting innovative streaming technologies, reflecting rising demand for both video and audio content. Specific regulatory frameworks supporting digital content delivery enhance this trend, resulting in significant investments from local and international players. The market benefits from established infrastructure that facilitates smooth streaming experiences, encouraging user engagement. With a projected market share of 24.2% in 2025, Europe represents an important region for streaming services. Increased interest in subscription-based models highlights consumer willingness to invest in premium content, further strengthening the region’s position in the global landscape.
Asia-Pacific captures 28.9% of the global Streaming Services market in 2025. Rapid growth in internet connectivity and smartphone penetration in countries like India and Southeast Asia drives increased demand for streaming content. The region benefits from a diverse consumer base, with preferences ranging from video streaming to audio streaming. Evolving content consumption habits, including a strong inclination toward on-demand content, influence market dynamics. In addition, the rise of local content providers enhances competition, providing consumers with a wider array of choices. Investment in digital infrastructure, including the expansion of 5G networks, further fuels growth, enabling access to streaming services across various platforms. Innovations in revenue models, particularly subscription-based and advertisement-based approaches, contribute to the market's robust expansion. By 2033, the market is projected to reach USD 27.6 billion, reflecting an ongoing shift in consumer behavior.
Increasing interest in streaming services emerges from a growing population of internet users in South America, particularly in Brazil and Argentina. The market generates significant demand from younger demographics seeking diverse content and entertainment options. Infrastructure improvements and greater accessibility to high-speed internet support this trend. In 2025, South America will represent 5.5% of the global market, highlighting its potential for growth. Local content providers play a crucial role in driving user engagement, tailoring offerings to regional tastes. The unique blend of cultural preferences shapes content consumption patterns across the region. The Streaming Services market is projected to expand rapidly, reflecting a notable shift in entertainment consumption among South American audiences.
Emerging trends in the Middle East and Africa signal increasing interest in the Streaming Services market. Rapid smartphone adoption in countries including Saudi Arabia and the UAE drives demand, while enhanced internet infrastructure supports content access. South Africa shows a growing preference for on-demand services, reflecting shifting consumer behaviors. Regional players focus on localized content strategies to attract diverse audiences. The share of the global market for this region stands at 3.5% in 2025, highlighting potential for expansion. Investment in platforms catering to both entertainment and educational content will enhance engagement and viewership across demographics. While consumers seek tailored experiences, services that adapt to local cultures and preferences are likely to flourish within the market.
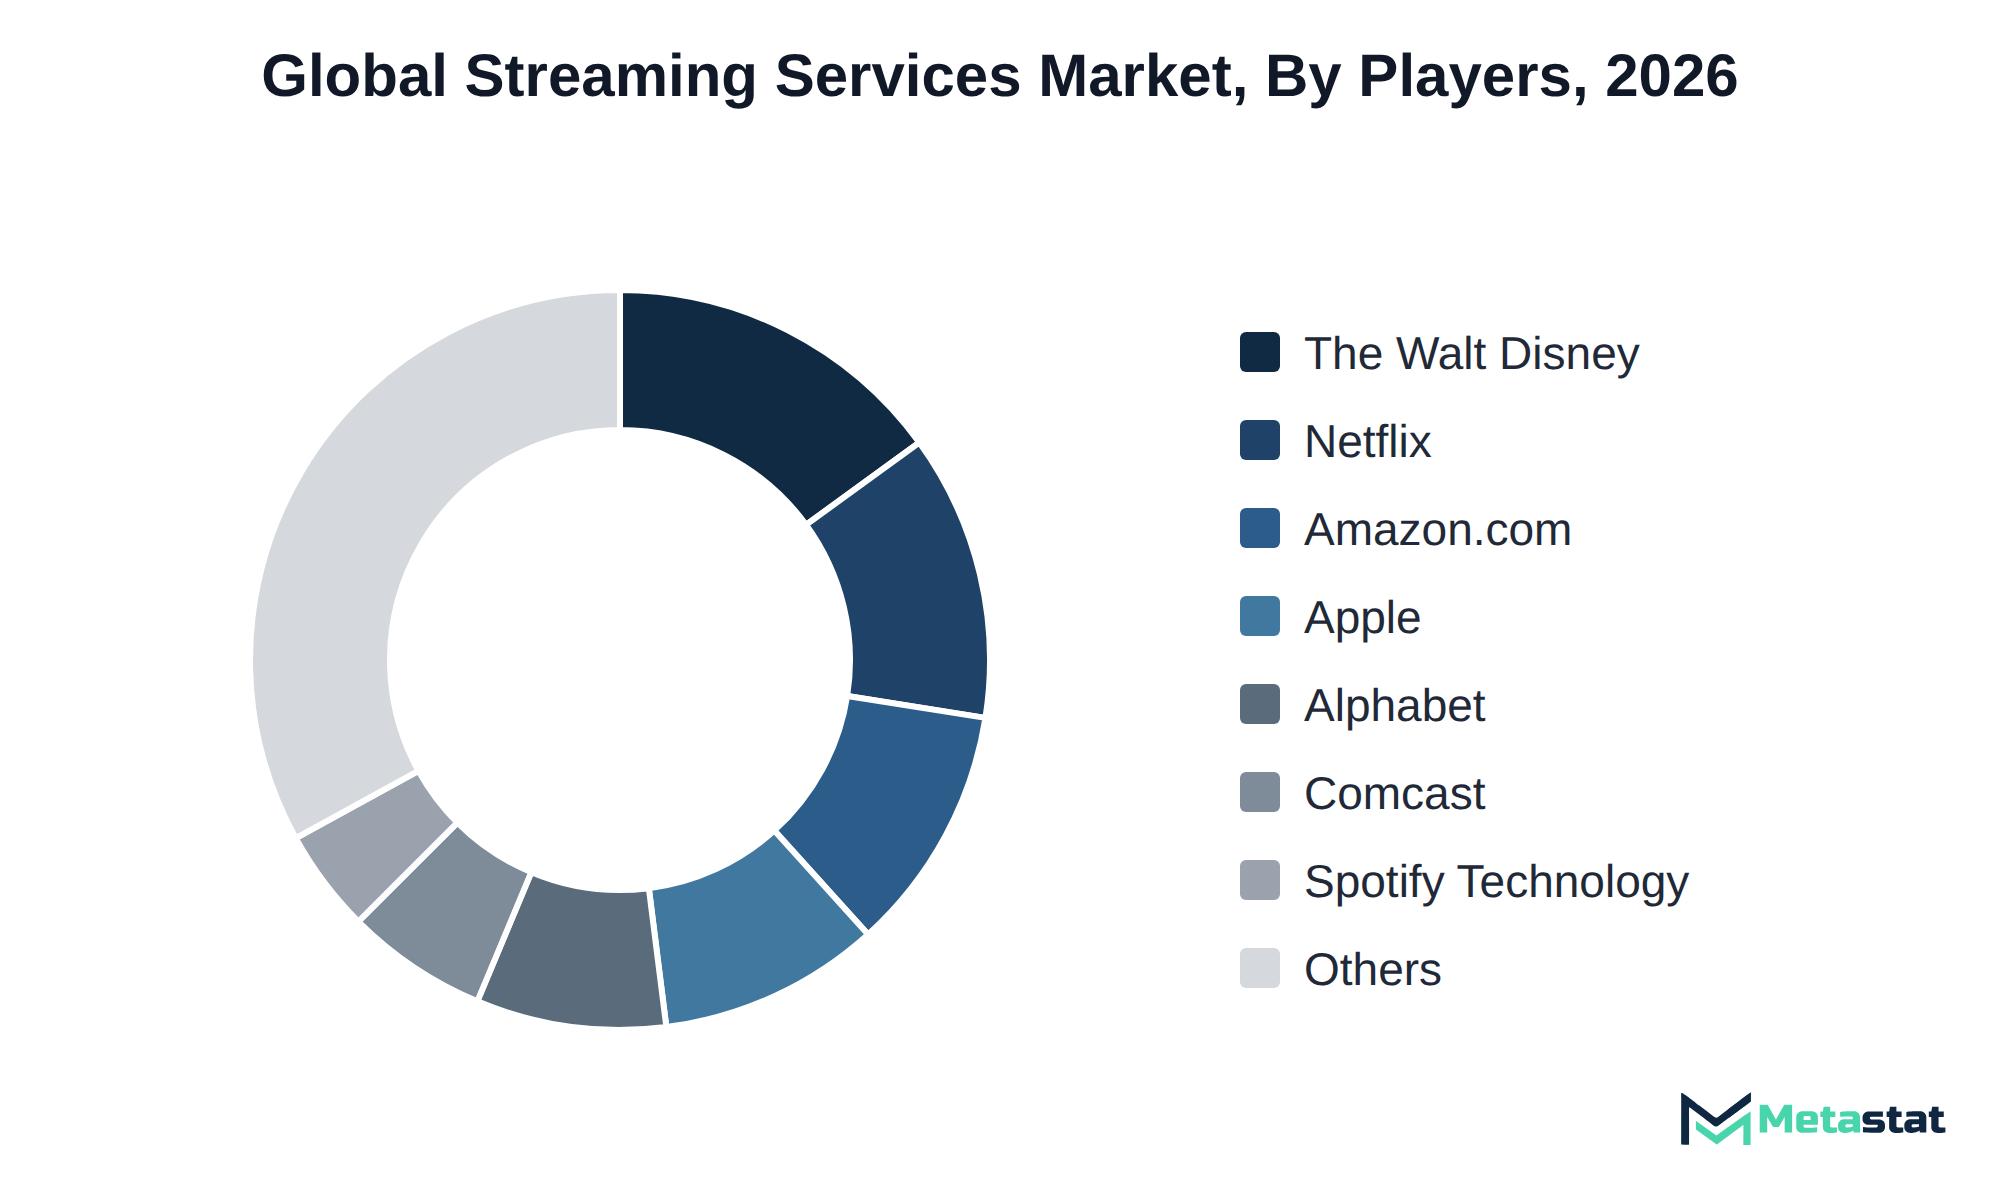
Competition within the Streaming Services market centers on media type, content type, platform, and revenue model. Companies differentiate through pricing strategies, user experience, content quality, and technological capabilities.
Video streaming remains a dominant segment, with Netflix, Inc. focusing on original content and diverse programming to attract subscribers. The Walt Disney Company leverages its extensive library and franchises to enhance its offering, while Amazon.com, Inc. integrates streaming with its broader e-commerce platform, providing added value to users.
Smartphones and Smart TVs represent key platforms where companies optimize their services. Apple Inc. emphasizes integration of its streaming services with its devices, while Roku, Inc. offers a platform that aggregates various streaming services to enhance user choice. This focus on platform compatibility and user accessibility drives engagement and retention in the market.
The growth of the Streaming Services market relies on several key developments. Firstly, the expansion of video streaming, projected to increase from USD 11.8 billion in 2026 to USD 22.5 billion by 2033, will significantly drive overall market revenue. This increase reflects a growing consumer preference for on-demand content across various platforms. Secondly, the rise of audio streaming, with an expected value of USD 2.7 billion by 2033, contributes to heightened engagement and revenue diversification within the market. Thirdly, the demand for subscription-based revenue models is anticipated to grow, enhancing overall profitability and market penetration. However, a primary risk that could hinder progress includes the saturation of the market in North America, where competition is intense, potentially slowing growth rates. To achieve the forecasted USD 27.6 billion, the market navigates these dynamic factors while capitalizing on emerging opportunities in regions like Asia Pacific, where adoption rates remain strong.
By Media Type: Video Streaming, Audio Streaming, Game Streaming, Others (Interactive and Specialty Streaming)
By Platform: Smartphones, Laptops & Desktops, Smart TVs, Tablets, Others (Streaming Media Players and Set-Top Boxes)
By Revenue Model: Subscription-Based, Advertisement-Based, Transaction-Based, Hybrid
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Streaming Services market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 10.2% from 2026 to 2033 |
|
Revenue Unit |
USD billion |
|
Segmentation |
By Media Type, Content Type, Platform, Revenue Model, and Region |
|
By Region |
North America (By Media Type, Content Type, Platform, Revenue Model, and Country)
|
|
Europe (By Media Type, Content Type, Platform, Revenue Model, and Country)
|
|
|
Asia Pacific (By Media Type, Content Type, Platform, Revenue Model, and Country)
|
|
|
South America (By Media Type, Content Type, Platform, Revenue Model, and Country)
|
|
|
Middle East and Africa (By Media Type, Content Type, Platform, Revenue Model, and Country)
|
Find answers to common questions about this report
The Streaming Services market size was valued at USD 12.7 billion in 2025.
The market is projected to grow at a CAGR of 10.2% during the forecast period from 2026 to 2033.
The North America Streaming Services market size is estimated to reach USD 9.6 billion by 2033.
Video Streaming leads the Streaming Services market with a projected value of USD 22.5 billion in 2033. This segment outpaces other media types in terms of revenue growth.
Shifts in consumer behavior drive increased spending on video streaming platforms, particularly among younger demographics, who prioritize on-demand content and convenience. Advancements in streaming technology, including enhanced internet connectivity and innovations in compression algorithms, attract various buyer groups seeking high-quality experiences.
North America holds the dominant share of the Streaming Services market, with a value of USD 9.6 billion in 2033, representing 37.9 percent of the total market.
Low awareness of available streaming options restricts growth, particularly among older demographics and less tech-savvy users. Insufficient marketing efforts targeting these groups result in limited knowledge of subscription models and content offerings, impacting overall market penetration.
Increasing demand for diverse programming, including original productions and interactive content, supports adoption in the streaming services industry. Enhanced internet connectivity and advancements in streaming technology further appeal to consumers seeking high-quality viewing experiences, driving engagement and subscriptions.
The Streaming Services market is estimated to reach a valuation of USD 27.6 billion by 2033.
Key players operating in the Streaming Services market include Netflix, Inc., Amazon.com, Inc., Alphabet Inc., The Walt Disney Company, Apple Inc., Comcast Corporation, Spotify Technology S.A., and Roku, Inc.
The analysts below cover Information & Technology research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Our team was tracking whether regional recycling infrastructure could realistically absorb the growing volume of lithium iron phosphate batteries over the next decade. The report did a solid job separating announced hydrometallurgical plant capacity from active, permitted operational throughput. That distinction made the feedstock availability projections and regional recovery rate models far more credible than standard commercial overviews.
Tracking capacity expansion in single-use bioprocessing requires dependable data on raw material availability and cleanroom-grade polymer supply chains. The competitive landscape chapter gave a grounded evaluation of secondary component suppliers across North America and Asia-Pacific rather than simply reprinting press releases. Having that level of supplier benchmarking helped clarify dual-sourcing considerations for our clinical pipeline planning.
When evaluating distributed energy resource management systems, standard research summaries tend to gloss over the operational differences between front-of-the-meter utility deployments and behind-the-meter industrial sites. The MetaStat Insight report addressed those distinctions directly, especially regarding software interoperability standards and grid interconnection backlogs. The five-year market sizing across regional transmission organizations provided actionable context for our grid modernization strategy.
Explore related market intelligence reports worth reading alongside this one.