
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Passive Optical LAN (POL) Solution Market Size, Share, By End User (Hospitality, Healthcare, Education, Government, and Others), By Type (GPON and EPON), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-4551
February, 2026
311 Pages
Report Details
Comprehensive Market Analysis And Insights
The global Passive Optical LAN (POL) Solution market size is valued at USD 31.1 billion in 2025 and is projected to grow from USD 35.3 billion in 2026 to USD 86.7 billion by 2033.
Global Passive Optical LAN (POL) Solution market valued at USD 31.1 billion in 2025, growing at a CAGR of 13.7% by 2033, with potential to exceed USD 86.7 billion.
North America holds 28.3% share in 2025, with the US leading within the region.
Hospitality segment accounts for 18.7% share in 2025, propelled by hotel and resort network upgrades supporting smart rooms and high-speed guest connectivity.
Key trend driving growth: Increased demand for high-bandwidth, future-proof LAN infrastructure across large sites (campuses, hotels, hospitals, airports).
Opportunities include rising adoption of smart buildings and loT-heavy environments creates strong opportunities for POL as a scalable, fiber-deep digital backbone.
Key insight: The global Passive Optical LAN (POL) solutions market is witnessing a steady shift toward fiber-based network architectures as organizations prioritize long-term efficiency and scalable connectivity.
The global Passive Optical LAN (POL) solutions market within enterprise networking and optical communications will experience growth beyond current deployment patterns, moving toward digital infrastructure designed for long-term utility rather than short-term technology upgrades. The market will be shaped by architectural thinking that considers connectivity as a silent backbone supporting automation, spatial intelligence, and adaptive building ecosystems. Optical LAN frameworks will no longer be planned solely for data transfer requirements, and will support how the environment senses, responds, and self-regulates.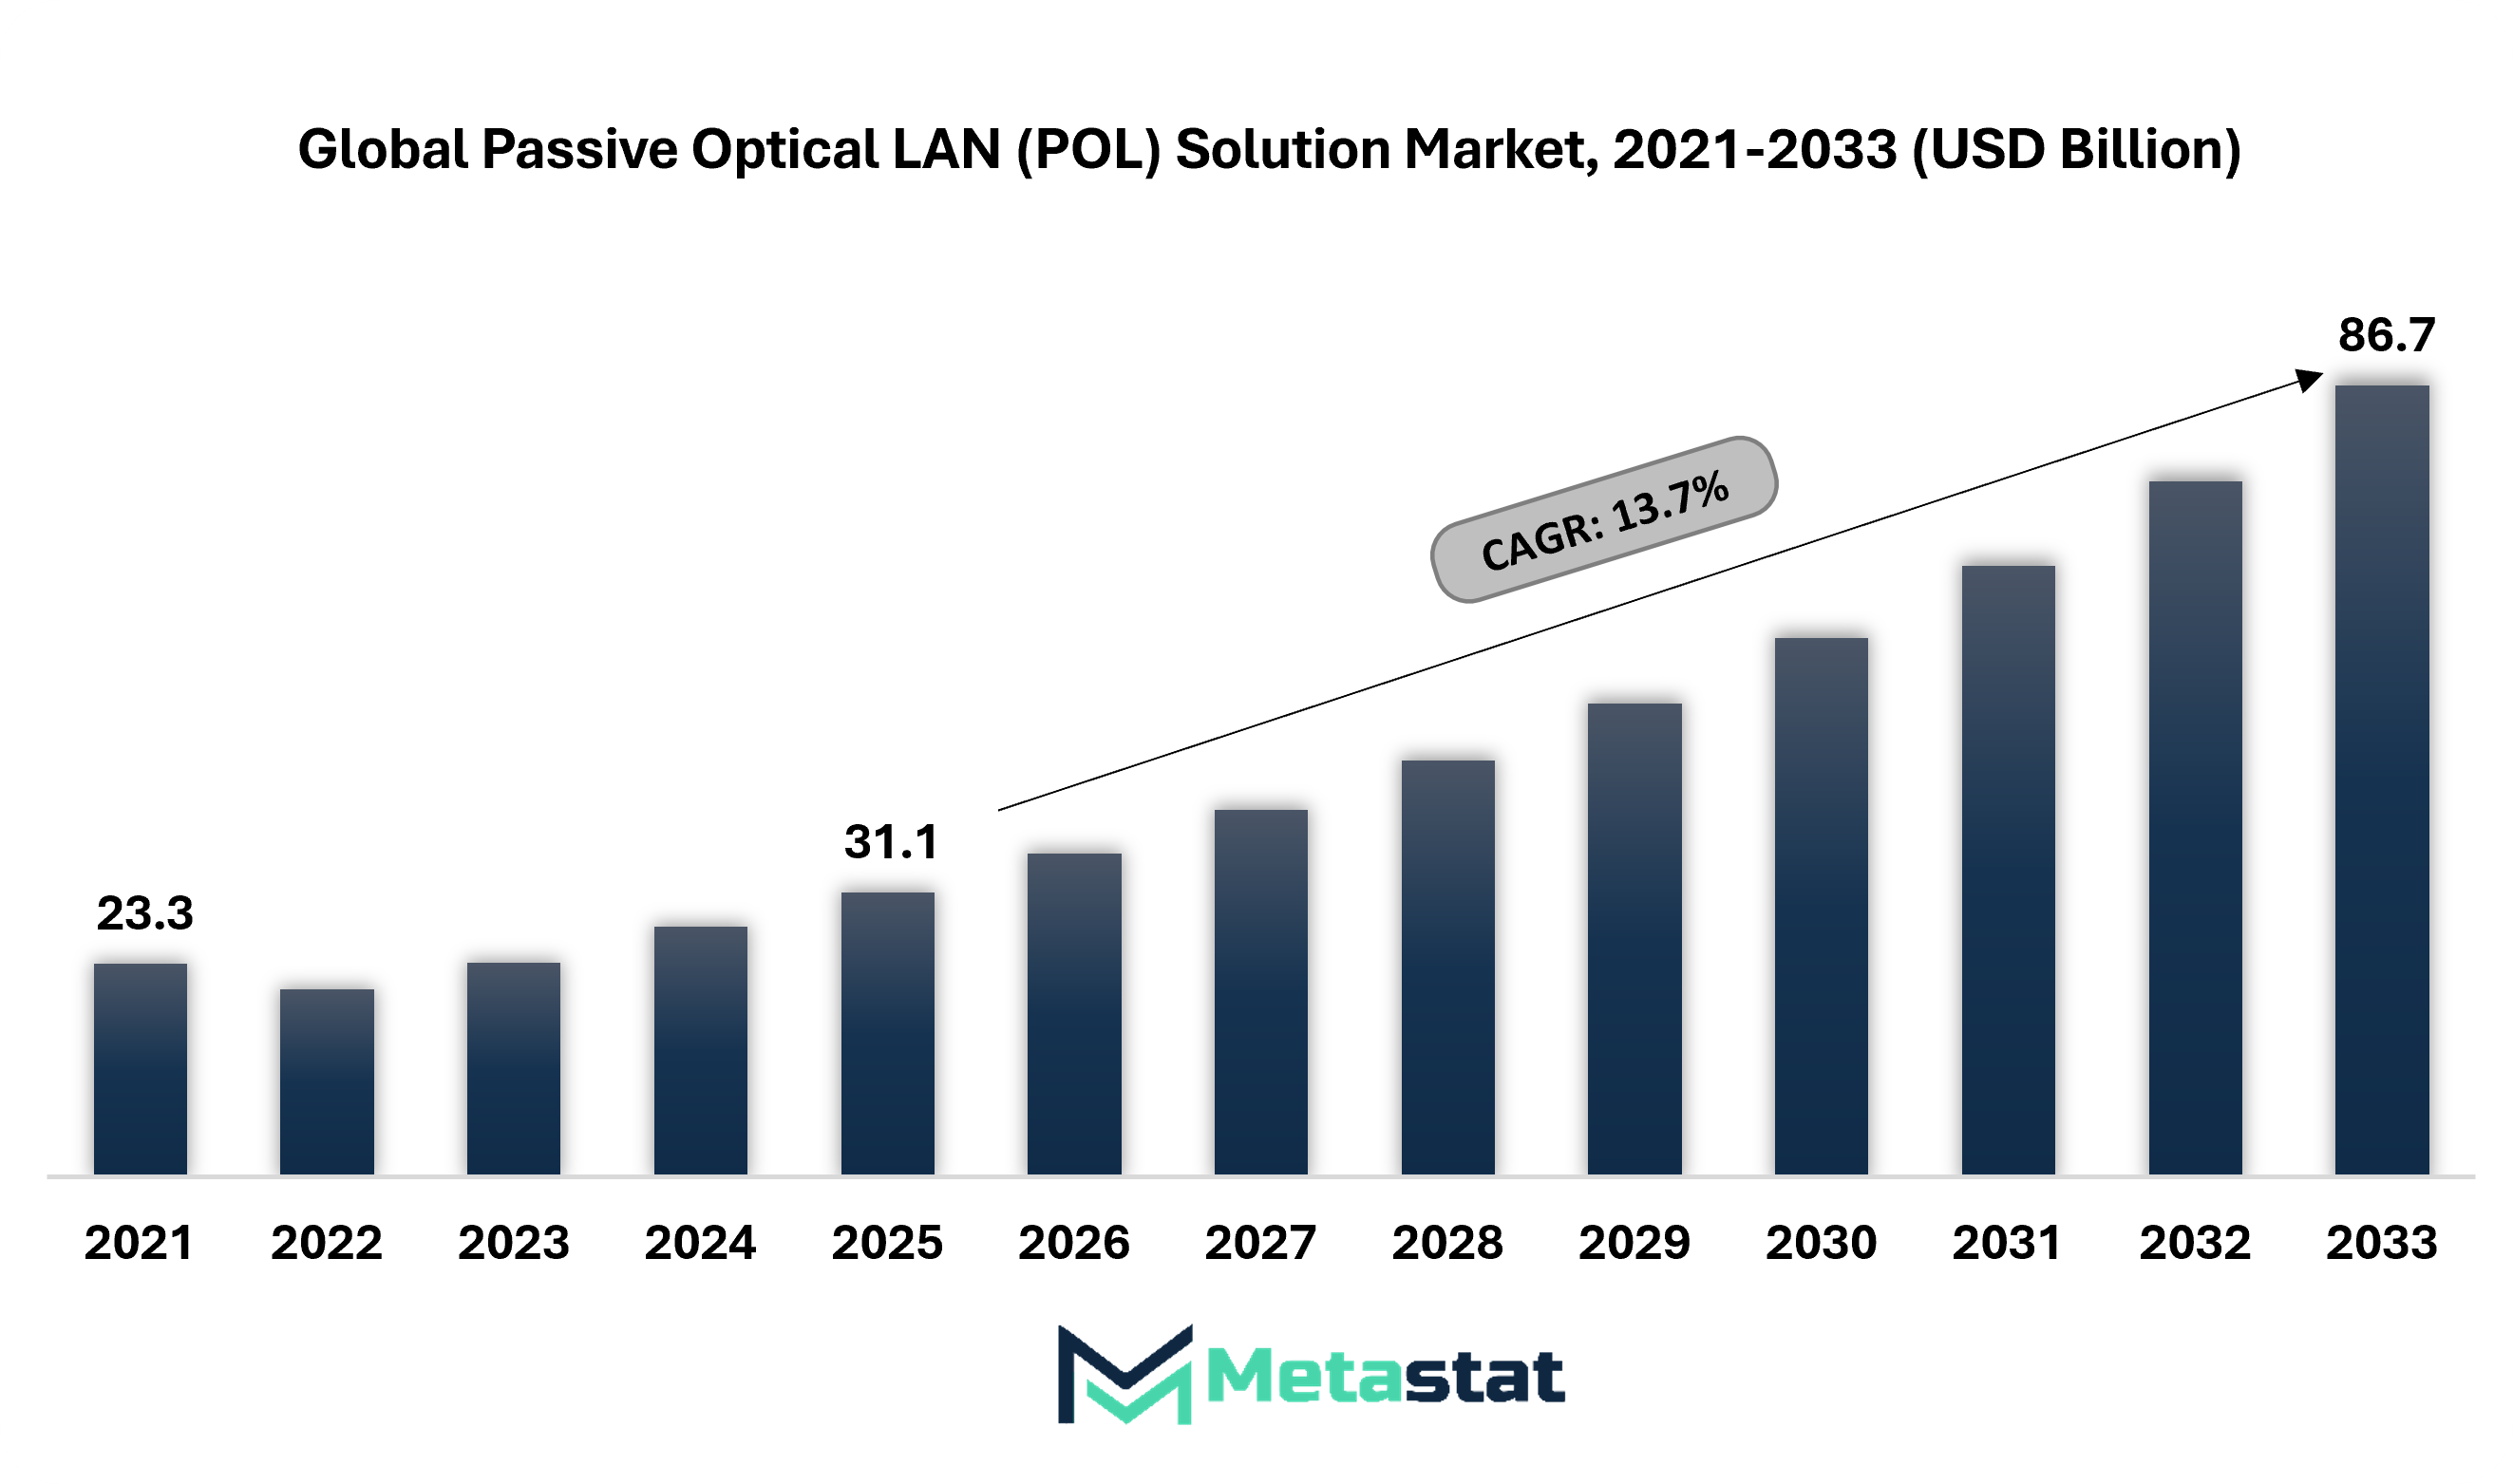
Future implementations will closely align with intelligent campuses, large-scale public infrastructure, and hyperconnected industrial spaces where centralized controls will be operated with minimal physical intervention. Decision-makers will increasingly view optical LAN layouts as foundational infrastructure, positioned to support future software layers rather than isolated networking initiatives. Such a shift will encourage longer planning cycles, deeper integration with building design, and closer collaboration among network engineers, city planners, and systems architects.
Large-scale facilities will continue to move towards networked systems that aid growing data loads, linked offerings, and virtual operations. Fiber-based LAN architecture supports long-term bandwidth scaling, stable connectivity, and simplified network layout. Planning for future-equipped infrastructure across campuses, health care centres, and transportation hubs will force persistent adoption.
Operational planning increasingly favors network models that minimize power use and equipment volume. Fiber-centric LAN deployments will reduce cabling requirements, reduce active components, and cut cooling requirements across access layers. Extended lifecycle, cost efficiency and sustainability goals will influence procurement decisions in enterprise and public infrastructure projects.
Initial transition planning often highlights capital expenditure concerns associated with fiber rollout and system redesign. Network modernization projects will face hiccups where existing copper layouts remain functional. Budget cycles and short-term return expectations will slow the pace of decision-making despite long-term efficiency gains.
Technical teams often rely on established skill sets focused on traditional Ethernet systems. Training lag and change management challenges will restrict rapid progress toward optical LAN adoption. Comfort with known technologies continues to shape infrastructure choices in risk-averse organizational environments.
The development of smart infrastructure will require sensors, automation platforms, and networks capable of supporting real-time analytics. Fiber-based LAN frameworks will align with intelligent building design by offering scalability, stability, and simplified expansion. Urban development and digital convenience planning will open avenues for sustained growth for the global Passive Optical LAN (POL) solutions market.
The global Passive Optical LAN (POL) Solution market is mainly classified based on Type, End User and Region.
Hospitality segment was valued at USD 6.6 billion in 2026 and is projected to reach USD 16.1 billion by 2033, at a CAGR of 13.7% during the forecast period.
The hospitality sector will see the increasing adoption of fiber-based LAN solutions for supporting smart rooms, high-speed networking, and digital guest services. Hotels and resorts will benefit from the easier management of networks, minimized cabling, and future scalability for supporting digital experience applications within the overall Passive Optical LAN solutions market.
Healthcare segment was valued at USD 8.7 billion in 2026 and is projected to reach USD 23.0 billion by 2033, at a CAGR of 14.9% during the forecast period.
Healthcare institutions will be dependent on sophisticated optical LAN infrastructures that can handle real-time access to data as well as ensure reliable communication. Hospitals and healthcare institutions will focus on ensuring a stable bandwidth and minimizing latency to optimize efficiency, as well as develop a platform for technology-based healthcare service provision.
Education segment was valued at USD 5.4 billion in 2026 and is projected to reach USD 13.4 billion by 2033, at a CAGR of 13.8% during the forecast period.
Universities, K-12 school districts, and multi-building campuses are adopting POL to support high-density Wi-Fi, unified communications, security and surveillance, and cloud-first learning platforms. Campus network refresh cycles are increasingly aligned with smart classroom upgrades, digital administration, and centralized IT operations, owing to the need for scalable bandwidth, simplified cabling, and long lifecycle infrastructure.
Government segment was valued at USD 4.2 billion in 2026 and is projected to reach USD 9.9 billion by 2033, at a CAGR of 13.1% during the forecast period.
Government infrastructure is moving more towards optical LAN solutions that can help establish secure communications, smart city initiatives, and the digitization of public services. The management and administrative buildings, data centres, and public facilities within these will seek reliable network systems that can be used for long-term planning and developing digital governance requirements.
Others segment was valued at USD 10.2 billion in 2026 and is projected to reach USD 23.4 billion by 2033, at a CAGR of 12.7% during the forecast period.
Optical LAN systems will assist commercial spaces, transportation hubs, and enterprise campuses to meet high data demand and automation requirements. Centralized control, energy efficiency, and simplified maintenance will support future-ready operations across applications beyond traditional target environments.
GPON segment is projected to reach USD 45.4 Billion by 2033, at a CAGR of 13% during the forecast period.
GPON technology will remain among the priorities owing to its high bandwidth capacity and efficient delivery of data. Enterprises will move toward GPON to support their ever-expanding digital workload, centrally designed infrastructure, and a scalable network design in line with long-term connectivity plans.
EPON segment is projected to reach USD 40.5 Billion by 2033, at a CAGR of 14.5% during the forecast period.
The Ethernet passive optical network technology will grab attention owing to its flexibility and compatibility with Ethernet. Organizations will select EPON to integrate existing Ethernet environments with optical access systems for cost control and phased upgrades, aligned with future data transmission and performance requirements.
Based on geography, the global Passive Optical LAN (POL) Solution market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America Passive Optical LAN (POL) Solution Market is set to expand at a CAGR of 13.7% within the forecast period, reaching a market size (TAM) of USD 26.1 billion by the end of 2033.
In North America, large-scale modernization of enterprise and government campuses and data-intensive centers will accelerate adoption of POL solutions across public and private sectors.
North America is likely to see continued demand, with hyperscale data centers and smart industrial buildings shifting toward fiber-centric LAN frameworks for performance and scalability.
Asia Pacific will present strong opportunities, with rapid urban infrastructure projects integrating POL solutions into smart cities, airports, and major transportation hubs.
The expansion of digitalization in education, healthcare, and manufacturing will open avenues for POL deployment in cost-sensitive but high-growth economies in the Asia-Pacific region.
In the Middle East, Africa, and South America, POL adoption will progress selectively, shaped by infrastructure readiness and project-led investment cycles. The Middle East will remain the lead adoption pocket, owing to smart government facilities and high-capacity requirements across hospitality and aviation. Africa and South America will advance through targeted campus, public sector, and enterprise modernization deployments, supported by expanding fiber footprints in dense urban nodes.
The market for Global Passive Optical LAN (POL) Solution has been receiving increased attention as a network solution positioned to accommodate high data requirements while maintaining efficient operations. The adoption of POL solutions is increasing in both commercial buildings and healthcare institutions that require high levels of reliable connectivity. POL solutions use fiber-based infrastructure that will help to alleviate the issue of complex cabling and maintenance costs. With increasing dependency on digital services, Passive Optical LAN Solution is set to remain a popular option for any environment that demands high performance alongside efficient network management.
The market is largely influenced by the technological advancements brought along by established tech firms specializing in optical solutions. Huawei Technologies Co., Ltd., Nokia, and ZTE Corporation are some of the key players that have contributed to the development of POL solutions with the help of integrated systems that are suitable for large-scale implementations. The innovation, research, optimization, and adaptability to the latest information technologies will help in the further implementation of POL solutions across various geographies. Suppliers are, in most cases, preferred for implementations that require a high level of dependability, security, and longevity.
Along with these global giants, many niche and medium-sized companies contribute strongly to the market by catering to specific networking needs. Adtran, Inc., Zyxel Communications, EdgeCore Networks Corporation, FS.Com Inc., and Tellabs Access, LLC are known for delivering flexible POL components and access solutions that can be tailored to suit a variety of customer needs. CommScope, Inc., Corning Incorporated, Prysmian Group, and OFS Fitel, LLC (Lightera) strengthen the ecosystem through high-quality fiber, cabling and connectivity solutions that form the backbone of POL networks.
Regional players and diverse technology companies further expand the competitive landscape of the global Passive Optical LAN (POL) Solutions market. Tejas Networks Limited, TP-Link Systems Inc., and Zone Technologies, Inc. focuses on cost-effective and scalable solutions suitable for emerging and developed markets. These companies often meet the needs of enterprises seeking reliable POL deployment without excessive changes to the infrastructure. Through continued product development and strategic partnerships, all these industry players will collectively influence how POL solutions are implemented and adopted around the world in the years to come.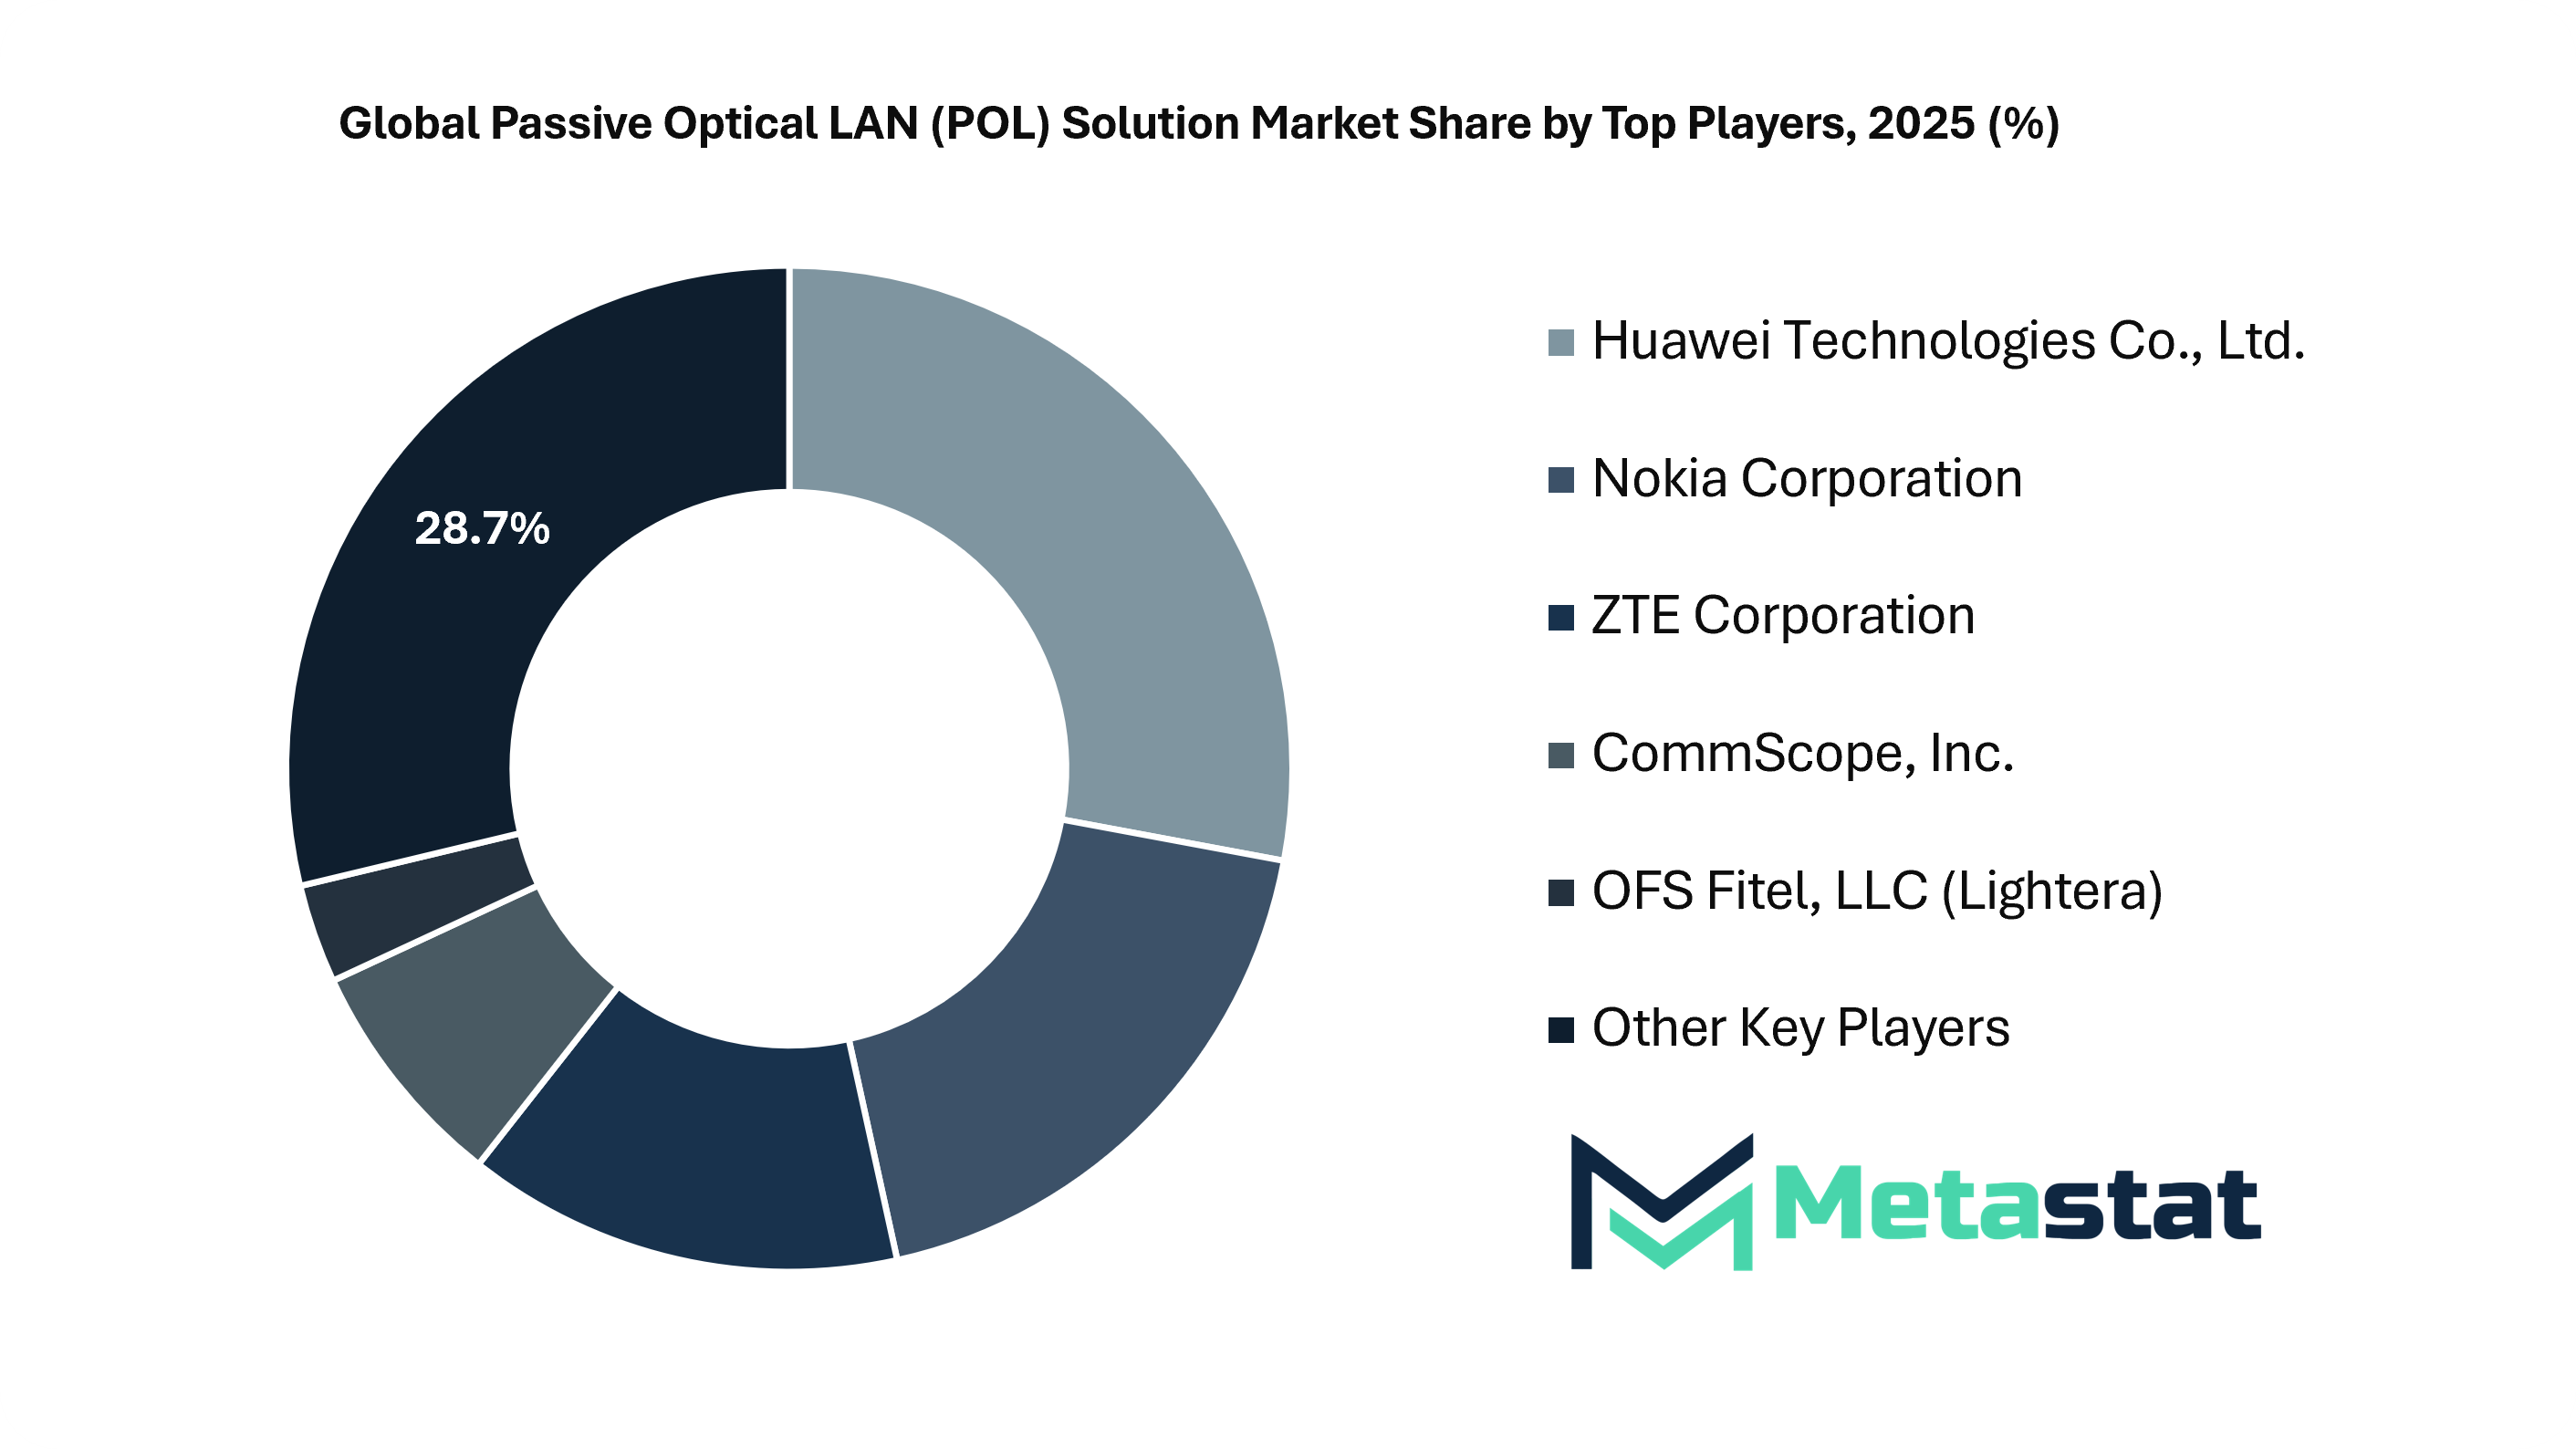
Market size is forecast to rise from USD 31.1 billion in 2025 to over USD 86.7 billion by 2033.
With advancements in digital working, optical network solutions will come into play for flexible space reconfiguration, whereby designing new space without reshaping basic infrastructure will become possible. These flexible solutions will apply to health facilities, transport infrastructure, and learning environments, where predictability and reliability with minimum changes will become more important than mere network speeds. Here again, value propositions will be more related to predictability rather than speeds. Besides the conventional applications of the technology found within the enterprise setting, there will be its applications within smart governance architecture, where there will be a significant need for standardization and management. In the future, the deployment of optical LANs will represent a paradigm shift in how people think of infrastructure as quiet, sustainable, and beyond the lifespan of various technological generations, ensuring its positioning as a future foundational infrastructure rather than a temporary solution for networking.
This research report categorizes the Passive Optical LAN (POL) Solution market based on key segments and regions, forecasts revenue growth, and analyses trends in each submarket. The report analyses the key growth drivers, opportunities, and challenges influencing the Passive Optical LAN (POL) Solution market. Recent market developments and competitive strategies such as expansion, type launch, development, partnership, merger, and acquisition have been included to draw the competitive landscape in the market.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Passive Optical LAN (POL) Solution market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 13.7% from 2026 to 2033 |
|
Revenue Unit |
USD Billion |
|
Sales Volume Unit |
Units |
|
Segmentation |
By End User, Type, and Region |
|
By Region |
North America (By End User, Type, and Country)
|
|
|
Europe (By End User, Type, and Country)
|
|
|
Asia Pacific (By End User, Type, and Country)
|
|
|
South America (By End User, Type, and Country)
|
|
|
Middle East and Africa (By End User, Type, and Country)
|
WHAT REPORT PROVIDES
Find answers to common questions about this report
The Metastat Insights study shows that the global Passive Optical LAN (POL) Solution market size was USD 31.1 billion in 2025.
The global Passive Optical LAN (POL) Solution market is likely to grow at a CAGR of 13.7% over the forecast period (2026-2033).
The Metastat Insights analysis shows that the North America Passive Optical LAN (POL) Solution market size is estimated to be USD 26.1 billion by 2033.
The GPON is the leading type segment in the global market.
Growing demand for high-bandwidth, future-proof LAN infrastructure in large venues (campuses, hotels, hospitals, airports) and Lower total cost of ownership (TCO) and energy savings versus traditional copper-based, multi-switch Ethernet LANs are key driving factors, boosting the market.
Asia Pacific is projected to hold a leading share during the forecast period.
High upfront investment and perceived migration complexity from legacy Ethernet architectures will hamper market growth within the forecast period.
The Global Passive Optical LAN (POL) Solution market is estimated to reach USD 86.7 billion by 2033.
Top players operating in the Passive Optical LAN (POL) Solution industry include Huawei Technologies Co., Ltd., Nokia Corporation, ZTE Corporation, Adtran, Inc., and Zyxel Communications.
Choose Your License
Passive Optical LAN Solution Market
The analysts below cover Information & Technology research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Tracking ceramic matrix composite adoption in high-bypass aero engines requires strict attention to material qualification cycles and FAA airworthiness testing milestones. The MetaStat Insight team provided a detailed timeline of silicon carbide fiber manufacturing capacity and commercial foundry lead times. Having clear visibility into upstream thermal barrier coating supply helped us stress-test our long-term component procurement strategy.
Transitioning ultra-class mining haul trucks to alternative power requires concrete data on remote hydrogen refueling infrastructure economics. The report evaluated megawatt-scale electrolyzer installation expenses, onsite storage safety mandates, and heavy-duty fuel cell stack degradation under continuous duty cycles. That technical rigor helped our engineers benchmark realistic total operating cost horizons for off-highway fleet decarbonization.
Enterprise zero-trust network rollouts are often slowed down by multi-cloud transit latency and proprietary hardware retirement schedules. This study provided realistic total cost of ownership models comparing cloud-delivered security edge solutions against traditional hardware refreshes. The analysis of contract renewal lengths and software maintenance fees gave us clear visibility into enterprise replacement cycles over the next three to five years.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950
Starting from
$2950