
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Industrial Mats Market Size, Share, By Material Type (Rubber and Nitrile Rubber, PVC and Vinyl, Polyurethane, Foam-Based Materials, Polypropylene, Polyethylene, Nylon and Polyamide, Polyester, Aluminium, and Others (EPDM, Silicone, and Natural Rubber Blends)), By Product Type (Anti-Fatigue Mats, Entrance Mats, Logo Mats, Anti-Slip Mats, Kitchen Mats, Welding Mats, Sticky Mats, Chemical Resistant Mats, and Others (Interlocking Mats, ESD Mats, and Safety Mats)), By Distribution Channel (Direct and Indirect), By End-Use Industry (Manufacturing, Oil and Gas, Construction, Healthcare and Pharmaceuticals, Food Processing and Agriculture, Warehousing and Logistics, Automotive, Mining, Hospitality, and Others (Retail, Education, and Aviation)), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5347
September 23, 2026
Updated
259 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
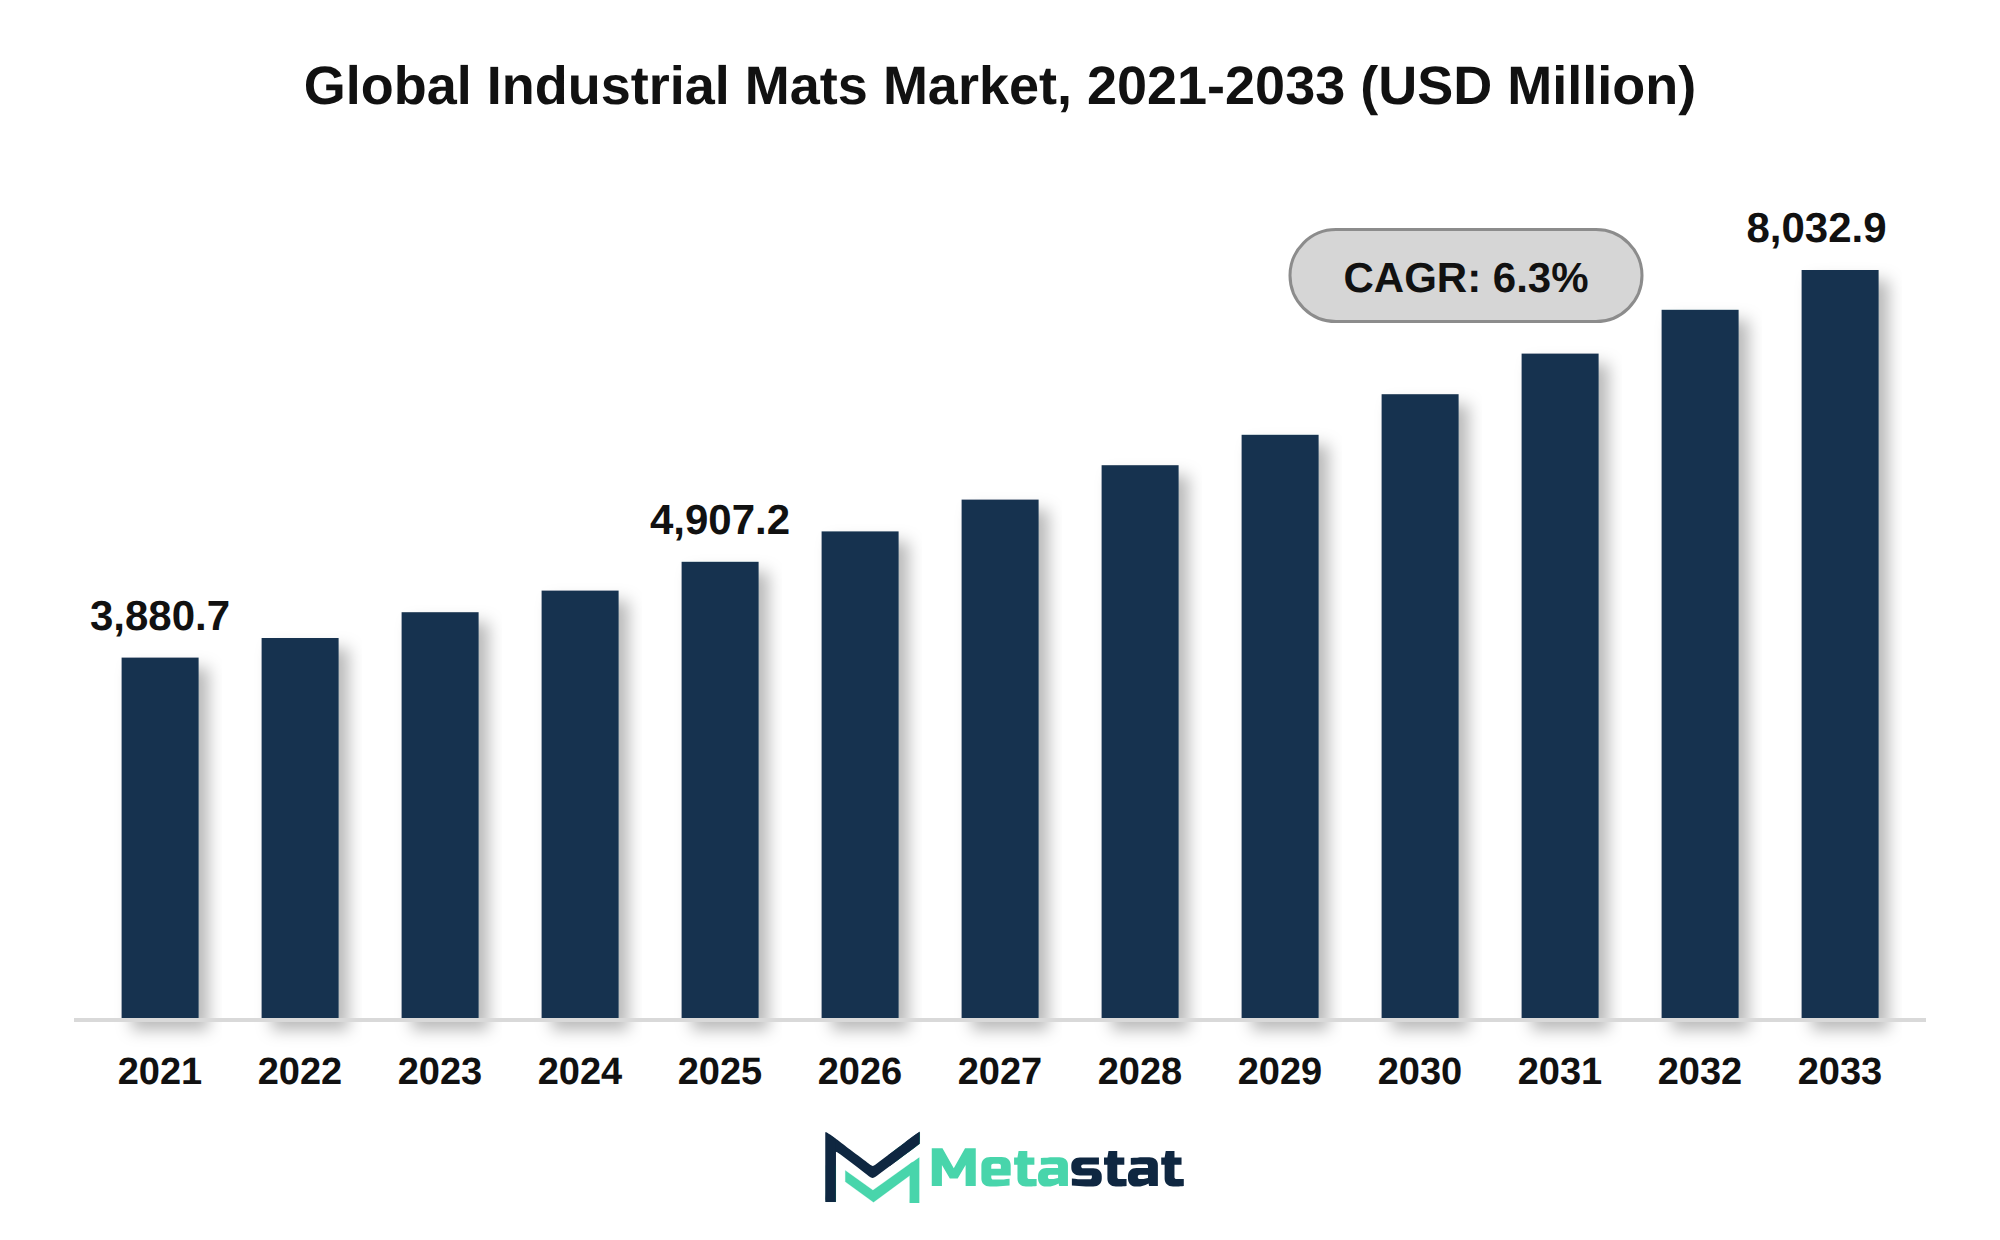
Market Valuation: Valued at $4,907.2 Million in 2025, projected to reach $8,032.9 Million by 2033 at a 6.3% CAGR.
Dominant Segment: The Rubber and Nitrile Rubber segment leads the market, driven by demand from the manufacturing and oil and gas industries for durable and chemical-resistant mats.
Geographic Lead: North America is the leading region in the Industrial Mats market, benefiting from significant investments in infrastructure and a strong focus on workplace safety.
What's Inside: The report provides comprehensive insights into market segmentation by material type, product type, distribution channel, and end-use industry, along with competitive analysis and forecasts through 2033.
Emerging Demands: Growing industrial activity in Asia Pacific and South America is driving demand for specialized mats, particularly in manufacturing and healthcare sectors, emphasizing safety and ergonomic solutions.
The global Industrial Mats market was valued at USD 4,907.2 million in 2025 and is projected to reach USD 8,032.9 million by 2033, growing at a CAGR of 6.3% over the forecast period.
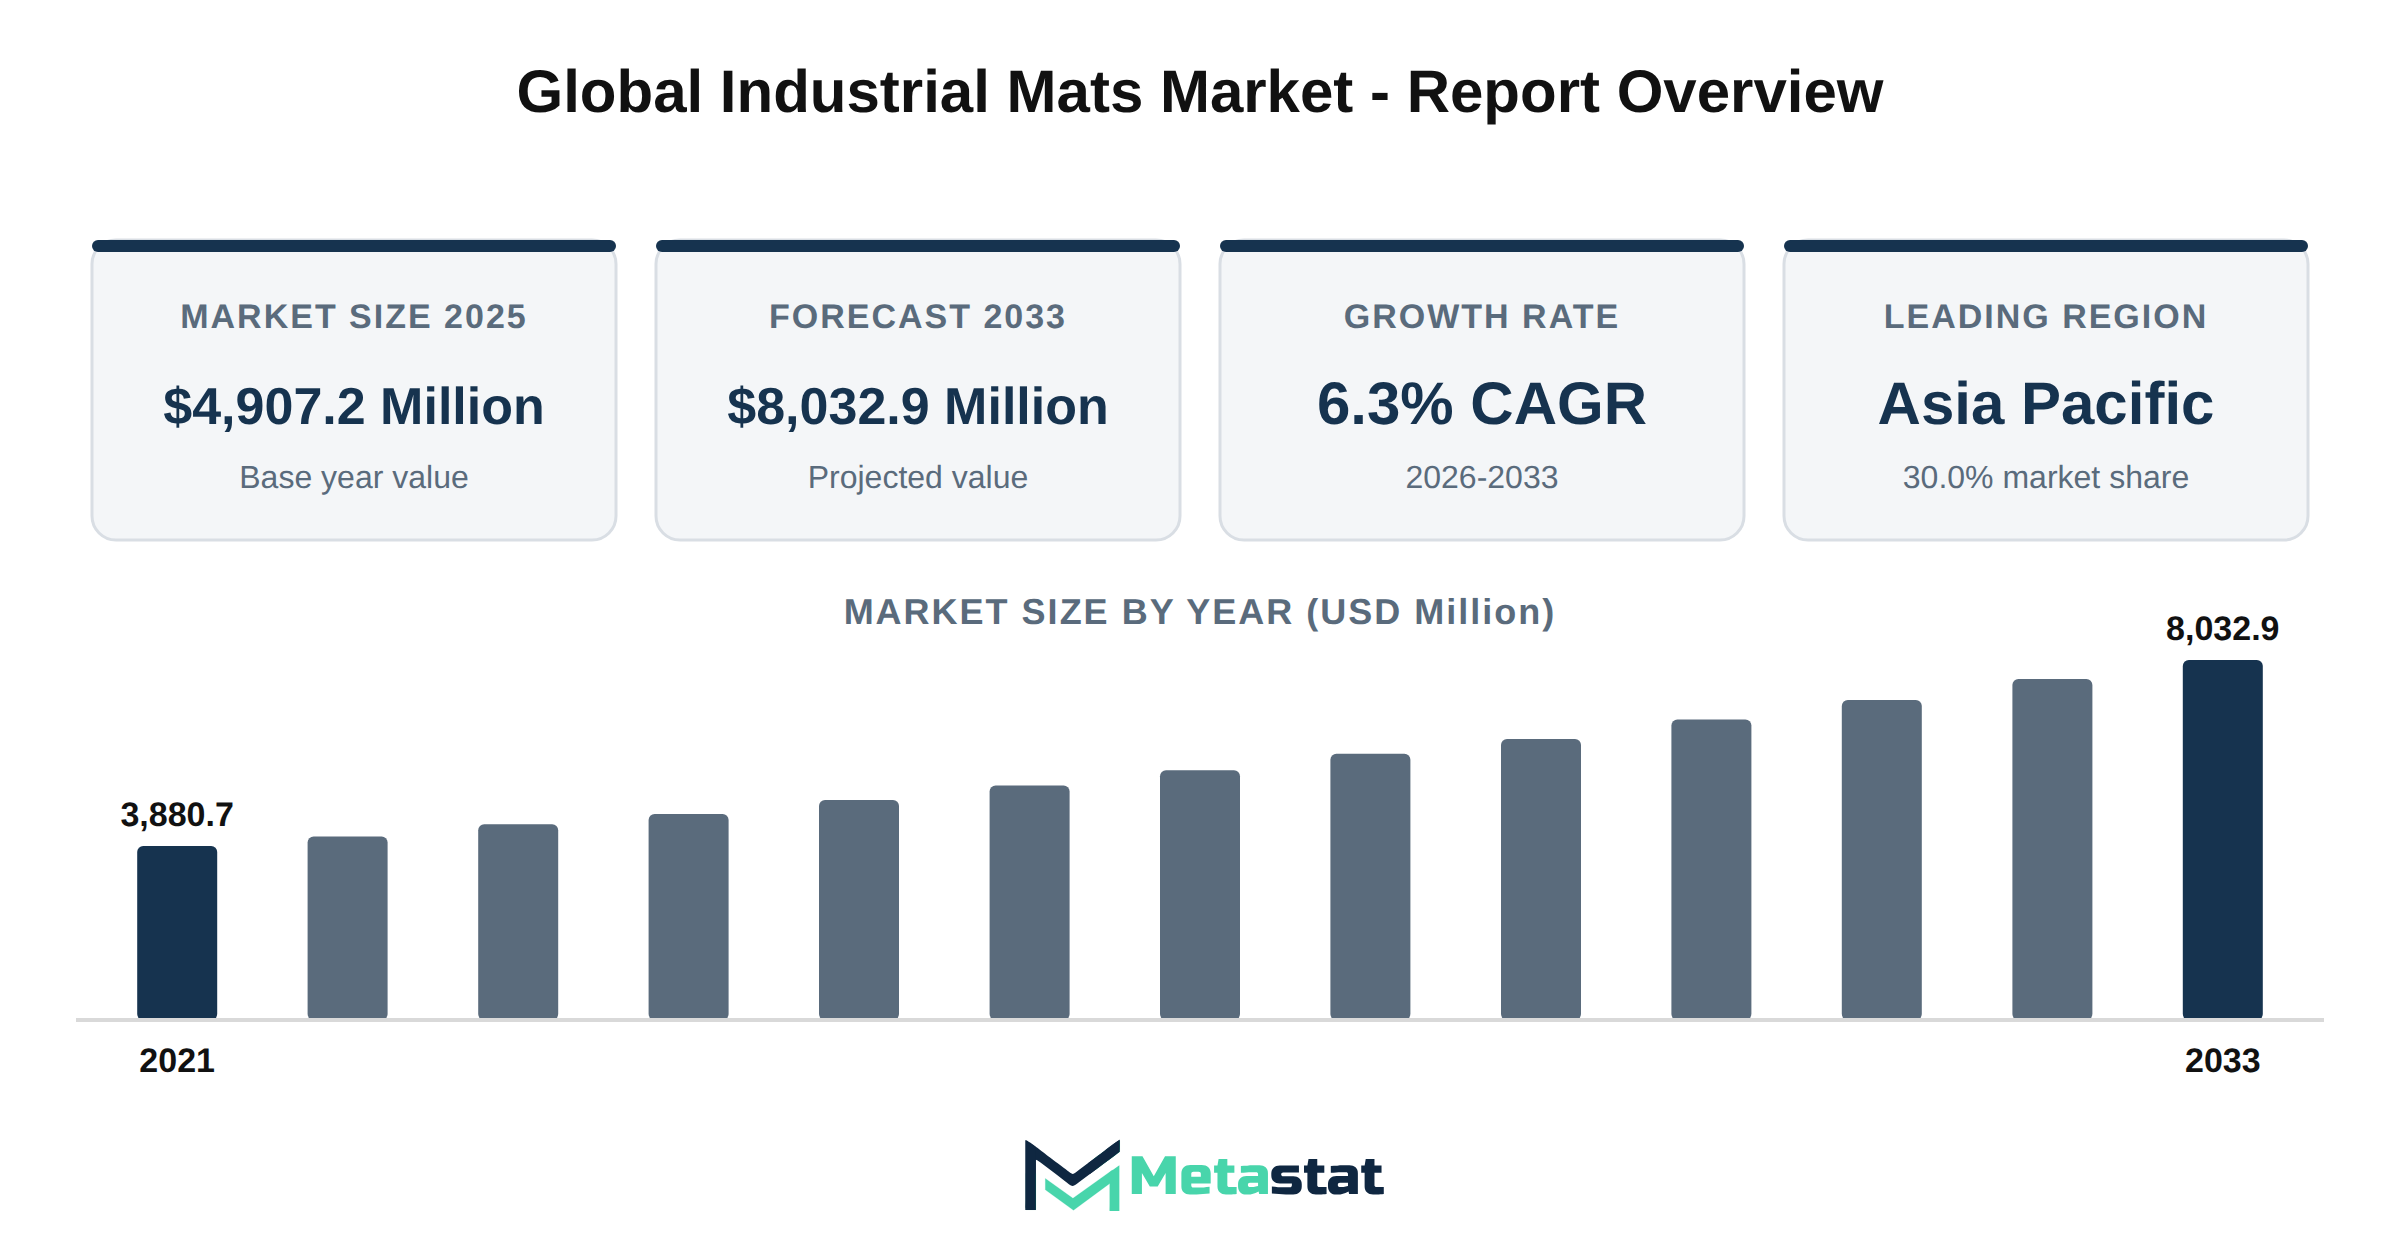
The global Industrial Mats market is poised for significant growth, with a projected value increase from USD 4,907.2 million in 2025 to USD 8,032.9 million by 2033, reflecting a compound annual growth rate (CAGR) of 6.3%. This upward trajectory signals robust demand for industrial matting solutions across various sectors.
Key drivers fueling the adoption of industrial mats include heightened awareness of workplace safety and ergonomic solutions. Industries including manufacturing and logistics prioritize anti-fatigue mats to enhance employee well-being and productivity. The demand for electrostatic discharge (ESD) matting in electronics assembly highlights the necessity for protective solutions in sensitive environments.
Slip-resistant and drainage mats are essential in wet, chemical, and oil-heavy environments, addressing the need for safety and maintenance in these sectors. Innovations in materials, particularly in nitrile rubber, polyurethane, and PVC, along with a growing focus on recycled polymer mats, reshape product offerings in the market.
Regulatory compliance and workplace ergonomics standards significantly influence industrial mat specifications, driving manufacturers to innovate and enhance product performance. Demand analysis shows strong interest in applications across automotive, aerospace, warehousing, and food processing facilities, highlighting the diverse end-use landscape.
Emerging technologies, including smart industrial mats equipped with embedded sensors for traffic tracking and hazard monitoring, are expected to transform the market. Supply chain dynamics and raw material price volatility remain critical factors for stakeholders, influencing global sourcing strategies.
Regional growth corridors indicate high demand in North America, Europe, and Asia-Pacific, with each region contributing to the overall expansion of the industrial mats market. The competitive landscape includes strategic mergers, product launches, and OEM supply partnerships aimed at enhancing industrial floor safety.
The Industrial Mats market experiences significant growth driven by various factors across multiple industries. Increasing awareness of workplace safety and ergonomic solutions drives demand for mats that reduce fatigue and enhance productivity. Anti-fatigue mats are particularly valued in sectors including manufacturing and logistics, where prolonged standing is common. The emphasis on employee well-being aligns with the growing trend of creating safer work environments, leading to substantial revenue potential.
In the electronics assembly sector, the demand for electrostatic discharge (ESD) and high-voltage switchboard matting continues to rise. These specialized mats protect sensitive electronic components from static electricity, contributing to the overall efficiency and reliability of manufacturing processes. This trend reflects the critical need for safety measures in high-tech environments, further shaping the market's dynamics.
Slip-resistant and drainage industrial mats are essential in wet, chemical, and oil-heavy environments. These mats minimize the risk of slips and falls, ensuring safety in sectors like food processing and chemical manufacturing. The ability to maintain a clean and safe workspace drives the adoption of such mats, highlighting their importance in operational safety and compliance.
Material innovations play a crucial role in the market landscape. Nitrile rubber, polyurethane, PVC, and recycled polymer mats are increasingly favored for their durability, resistance to chemicals, and environmental sustainability. These advancements assist manufacturers in meeting diverse customer needs while enhancing product performance and longevity.
Regulatory compliance and workplace ergonomics standards significantly influence industrial mat specifications. Adhering to safety regulations ensures that products meet industry requirements, building trust among buyers. Compliance with these standards not only enhances marketability but promotes a culture of safety across various sectors.
End-use demand analysis shows significant uptake in automotive, aerospace, warehousing, and food processing facilities. Each of these industries requires tailored solutions to address specific operational challenges, driving custom mat designs and materials. This targeted approach facilitates stronger market penetration and revenue growth.
Smart industrial mat technologies are emerging, featuring embedded sensors for traffic tracking and hazard monitoring. These innovations enable real-time data collection, enhancing safety protocols and operational efficiency. The integration of technology into industrial mats represents a progressive step towards modernizing workplace safety solutions.
Supply chain dynamics, raw material price volatility, and global sourcing strategies impact the market's stability and growth prospects. Fluctuations in raw material prices necessitate adaptive sourcing strategies, influencing production costs and pricing models. This complexity requires manufacturers to remain agile and responsive to market changes.
Regional growth corridors indicate high-growth industrial mat markets across North America, Europe, and Asia-Pacific. Each region presents unique characteristics and demands, with North America leading in market share. Understanding these regional nuances allows manufacturers to optimize their strategies for increased competitiveness and market reach.
The competitive landscape of the Industrial Mats market features strategic mergers, product launches, and OEM supply partnerships. Companies continuously seek to enhance their product offerings and expand market presence through collaboration and innovation. This competitive environment encourages ongoing advancements, positioning the market for sustained growth.
Strong capital investment environments significantly contribute to the growth of the Industrial Mats market. Increased spending power from both public and private sectors stimulates demand for various types of industrial mats, particularly in manufacturing and construction industries. Factors including GDP growth and favorable interest rates enhance investment capacity, encouraging companies to upgrade facilities and improve operational efficiency.
This trend reflects a growing emphasis on operational productivity and cost-efficiency initiatives. Businesses prioritize investments that streamline processes and reduce overhead, leading to higher adoption of specialized industrial mats. The need for enhanced workplace safety and employee well-being drives demand for anti-fatigue mats, further propelling market growth.
Investment in infrastructure development and modernization initiatives significantly expands the market. Organizations upgrade both physical and digital capacities while increasingly incorporating industrial mats into their facilities. This alignment with technological advancement facilitates greater durability and functionality of mats, catering to evolving consumer preferences.
Overall, the strengthening capital investment climate directly influences the market, shaping trends and driving growth opportunities across various sectors. With increasing focus on sustainability and resource stewardship, investments in eco-friendly materials for industrial mats further support market expansion. Economic factors and consumer behavior position the Industrial Mats market for sustained growth in the coming years.
The Industrial Mats market experiences expansion driven by ongoing infrastructure development across various sectors. Governments and private entities increasingly invest in upgrading physical facilities and transportation networks, enhancing demand for materials that improve safety and operational efficiency. Robust infrastructure projects necessitate the use of industrial mats, particularly in manufacturing, construction, and logistics, where worker safety and productivity are critical.
Significant growth in urbanization contributes to the market, resulting from the construction of new facilities and public spaces that generate demand for high-performance mats. Emerging demographic patterns, including a focus on aging populations, result in evolving safety standards and heightened awareness of occupational health. This shift leads to increased adoption of anti-fatigue and anti-slip mats, essential for mitigating workplace injuries.
Investment in infrastructure modernization not only aligns with government initiatives but responds to market needs for sustainability and resource stewardship. Companies increasingly seek mats that support their environmental goals, driving demand for products made from eco-friendly materials. The Industrial Mats market expects sustained growth fueled by these infrastructure investments, with opportunities for innovation and diversification of product offerings to meet changing consumer preferences.
Regulatory compliance poses significant challenges to the Industrial Mats market, creating hurdles for manufacturers and suppliers aiming to meet stringent standards. Compliance with various legal mandates requires companies to invest in advanced technologies and training, raising operational costs. The capital necessary for compliance diverts resources from other critical business areas, resulting in reduced competitiveness.
In addition to compliance costs, macroeconomic headwinds contribute to market constraints. Inflationary pressures increase material costs, impacting profitability and consumer purchasing power. This economic environment leads to reduced demand for industrial mats, driven by businesses prioritizing essential expenditures over discretionary investments in flooring solutions.
Supply chain disruptions exacerbate these challenges, creating bottlenecks in the availability of raw materials and finished products. Geopolitical instability complicates sourcing strategies, causing uncertainty in supply chains that manufacturers rely on. Delays and increased costs significantly affect the market's operational efficiency and customer satisfaction.
In light of these factors, the Industrial Mats market faces pressure from technological obsolescence and competition from alternative offerings. Innovations in flooring technology render traditional mats less appealing, requiring manufacturers to adapt or risk losing market share. Consequently, businesses navigate these challenges effectively to sustain growth and maintain relevance.
Geopolitical fragmentation creates significant challenges for the Industrial Mats market, particularly in terms of supply chain stability. Trade deficits and tariff friction disrupt the flow of materials and finished products, impacting manufacturers' ability to maintain consistent production levels. Ongoing volatility in feedstock and component availability influences pricing strategies and profit margins. Suppliers adapt to changing dynamics, which creates additional costs and operational complexities.
Technological disruptions further complicate the market landscape, where companies face pressures to integrate advanced solutions into existing systems. Complex research and development integrations increase the time and resources required for innovation, leading to heightened risks of project delays. These challenges hinder the competitive position of firms within the market, owing to agility being essential in responding to evolving consumer demands.
Environmental sustainability demands influence market dynamics significantly, with decarbonization mandates requiring firms to rethink their production processes. Compliance overhead associated with tightening global regulatory standards adds to operational difficulties, especially for smaller players who lack the necessary resources to meet these requirements. Such pressures lead to pricing compression, affecting the overall profitability of the market.
The workforce skill gaps present another challenge, owing to automation displacements creating talent retention pressures. Firms that struggle to attract and retain skilled workers face difficulties in maintaining operational efficiency. This issue, combined with infrastructure gaps and retrofitting barriers, constrains the growth potential of the market in certain regions.
Market saturation and the presence of substitution vector pressures create competitive challenges. While alternative solutions gain traction, maintaining market share becomes increasingly difficult. Companies within the Industrial Mats market navigate these complexities while managing their operations and ensuring they remain responsive to market trends and consumer needs.
Demand for industrial mats expands significantly owing to emerging regional market dynamics. Regions including Asia Pacific and South America experience increasing industrial activity, leading to heightened investment in manufacturing and construction. The growing focus on safety and ergonomics in workplaces, particularly in manufacturing and healthcare, drives the requirement for anti-fatigue mats and other specialized products. In addition, the shift toward sustainability influences the market because companies prioritize eco-friendly materials, prompting manufacturers to innovate with sustainable options.
Infrastructure modernization efforts act because a catalyst for market growth. Upgrading facilities to meet contemporary standards necessitates the integration of durable flooring solutions, including industrial mats that enhance operational efficiency and safety. Geographical expansion of industries into developing regions promotes the need for versatile products tailored to various local conditions, resulting in increased market penetration.
Technological disruptions play a critical role by enabling digital transformation across sectors. Enhanced manufacturing processes, automation, and smart technology integration increase the demand for specialized mats that support operational yield maximization. Niche applications, including mats for logistics and warehousing, attract attention because companies seek solutions that cater to specific operational challenges.
Strategic consolidation and cross-industry mergers contribute to the Industrial Mats market's evolution. Collaborations between key players facilitate resource sharing, allowing for improved product development and distribution efficiency. The ongoing trend toward digital procurement shifts purchasing behaviors, enabling businesses to streamline their sourcing processes and enhance competitiveness.
Value chain optimization remains essential, particularly with the need for localized supply chains in response to global disruptions. Manufacturers focus on maintaining quality while ensuring that supply chain localization reduces risks associated with reliance on international sources. These strategies enhance resilience and create opportunities for growth within the market.
The Global Industrial Mats market is segmented based on Material Type, Product Type, Distribution Channel, and End-Use Industry.
Valued at USD 2,173.8 million in 2026, the Rubber and Nitrile Rubber segment is projected to reach USD 3,200.3 million by 2033, achieving a CAGR of 5.7% during the forecast period. Demand for rubber and nitrile products arises primarily from the manufacturing and oil and gas industries, where durability and resistance to chemicals and physical wear are critical. These attributes drive adoption across various applications, including anti-fatigue and anti-slip mats, which enhance workplace safety and comfort. Segment expansion receives impetus from technological advancements in material composition, leading to improved performance characteristics that encourage end-users to invest in higher-quality solutions. Downstream applications in healthcare and pharmaceuticals highlight the importance of regulatory compliance, which mandates specific safety standards that rubber and nitrile mats satisfy effectively. Pricing volatility and margin pressures persist due to fluctuations in raw material costs, impacting manufacturers' profitability. Strategic opportunities arise through innovation in product offerings, focusing on sustainability and eco-friendly materials, aligning with market trends emphasizing environmental responsibility. The Industrial Mats market remains resilient, with manufacturers enhancing supply chain strategies to mitigate risks associated with raw material sourcing and logistics vulnerabilities. Continuous investments in research and development facilitate next-generation upgrades and product evolution, ensuring the segment remains competitive and aligned with market demands.
Growth in the PVC and Vinyl segment of the Industrial Mats market is projected to reach USD 1,172.8 million by 2033, at a CAGR of 6% during the forecast period. Increasing demand for durable, easy-to-clean surfaces across various industries drives the adoption of PVC and vinyl mats. These materials offer excellent resistance to moisture, chemicals, and abrasion, making them suitable for end-use applications in sectors including manufacturing, healthcare, and hospitality.
Technological advancements in the production of PVC and vinyl mats enhance performance characteristics. Innovations in formulation and manufacturing processes result in improved durability, aesthetic appeal, and slip resistance, meeting the evolving needs of consumers. The shift towards sustainable practices in the industry influences the development of more environmentally friendly options, further stimulating segment growth.
Market dynamics indicate a growing emphasis on regulatory compliance, driving manufacturers to adhere to safety and environmental standards. This trend increases investment in product development and certification processes to meet market expectations. Companies in the PVC and Vinyl segment benefit from enhanced credibility, which drives consumer confidence and adoption.
Competitive pressures within the market prompt companies to explore strategic partnerships and distribution channels to expand their reach. Direct sales channels gain traction, allowing manufacturers to connect with end-users more effectively. The PVC and Vinyl segment remains a critical component of the Industrial Mats market, characterized by steady growth driven by innovation, demand for performance, and compliance with regulatory standards.
Growth in the polyurethane segment of the Industrial Mats market stems from rising demand across various end-use industries. Increasing awareness of workplace safety and comfort drives organizations to adopt anti-fatigue mats made from polyurethane. Adoption of these products enhances employee productivity and reduces health-related expenses for businesses, contributing to market expansion.
Technological maturation plays a significant role in the evolution of polyurethane mats. Innovations in manufacturing processes have improved the durability and performance of these products, making them more appealing to customers. Enhanced product features, including improved slip resistance and chemical resistance, cater to specific industry needs, promoting consumption.
Market dynamics indicate a shift toward high-quality polyurethane mats in sectors including healthcare and pharmaceuticals. These industries increasingly prioritize hygiene and safety, resulting in heightened demand for mats that offer antimicrobial properties and ease of cleaning. The polyurethane segment is projected to reach USD 792 million by 2033, reflecting growth driven by these end-use dynamics.
Pricing volatility poses challenges within the polyurethane segment, particularly due to fluctuations in raw material costs. Companies operating in this market strategically manage their supply chains to maintain competitive pricing while ensuring quality. This balance influences margins and overall profitability in the polyurethane sector of the Industrial Mats market.
Growth in the Foam-Based Materials segment reflects increasing demand for lightweight and versatile materials across various industries. This segment is projected to grow at a CAGR of 7% during the forecast period. Application in sectors including manufacturing and healthcare drives adoption, emphasizing the need for mats that enhance safety and comfort in high-traffic areas. The segment benefits from technological advancements that improve product performance and durability.
Investment in research and development supports product evolution, leading to innovative foam-based solutions tailored for specific end-use applications. Regulatory compliance regarding workplace safety and ergonomic standards influences purchasing decisions, prompting industries to select high-quality mats. Price stability in raw materials contributes to maintaining competitive pricing in the market, ensuring these products remain attractive to end users.
Increased focus on environmental sustainability shapes consumer preferences, with manufacturers exploring eco-friendly materials for foam-based mats. This shift aligns with broader trends in the industrial mats market, where sustainable practices gain prominence. While the market evolves, strategic opportunities arise for companies that deliver innovative products meeting both performance and environmental criteria.
Polypropylene presents a strategic opportunity within the Industrial Mats market, driven by its favorable properties including durability, chemical resistance, and lightweight nature. These characteristics promote its adoption across various applications, particularly in environments requiring robust solutions for safety and comfort. The segment benefits from increasing demand in industries including manufacturing and oil and gas, where performance and longevity are critical.
Technological maturation further stimulates interest in polypropylene mats, enabling advancements in production techniques that enhance quality and reduce costs. Next-generation upgrades in polypropylene formulations lead to improved performance attributes, attracting manufacturers focused on delivering high-quality products. Shifts in consumption patterns toward sustainable materials influence the segment, with polypropylene offering recyclability and lower environmental impact compared to traditional materials.
Regulatory compliance standards increasingly influence the demand for polypropylene mats, especially in sectors prioritizing worker safety and environmental responsibility. Certifications related to performance and safety enhance confidence among end-users, reinforcing the segment's credibility in the market. Cost structures associated with polypropylene production remain favorable, allowing competitive pricing strategies while maintaining profit margins.
Supply chain resilience is vital for the polypropylene segment, particularly regarding raw material sourcing and logistics vulnerabilities. The need for consistent quality and availability shapes strategic decisions among manufacturers. Substitution risks from alternative materials present challenges; however, the distinct advantages of polypropylene maintain its position in the market. Overall, the outlook for polypropylene within the Industrial Mats market is bright, driven by ongoing innovations and evolving industry demands.
Polyethylene emerges because a relevant sub-segment within the Industrial Mats market, driven by its favorable properties including durability, chemical resistance, and lightweight nature. Rapid adoption occurs across various industries, including manufacturing and healthcare, where the demand for efficient flooring solutions is prevalent. Product evolution introduces innovations in polyethylene formulations, enhancing performance characteristics and broadening applications.
Downstream applications highlight the importance of polyethylene in creating mats suitable for diverse environments, particularly where safety and hygiene are critical. Increasing regulatory compliance standards in industries including food processing and pharmaceuticals influence the demand for mats that meet stringent safety requirements. These factors contribute to consumption shifts, pushing end-users toward materials that deliver both performance and compliance.
Cost structures associated with polyethylene production remain competitive, providing further impetus for its adoption in the market. Pricing volatility stemming from raw material sourcing impacts overall margins, but strategic sourcing solutions help mitigate these risks. Supply chain resilience is crucial in maintaining consistent availability, especially amid fluctuating demand patterns.
The strategic opportunity window for polyethylene within the market lies in leveraging technological advancements for next-generation upgrades. Developments in manufacturing technologies position polyethylene mats because alternatives to traditional materials, addressing substitution risks while offering enhanced functionality. This forward momentum supports continued investment in product development, ensuring that polyethylene remains a vital component of the Industrial Mats market.
Interest in nylon and polyamide materials continues to rise within the Industrial Mats market due to their unique properties, including durability and resistance to chemicals. Industries including manufacturing and healthcare prioritize these materials for their anti-slip and comfort features, driving adoption across various end-use applications. Technological advancements in production enhance the performance and versatility of nylon and polyamide mats, facilitating their use in demanding environments.
Shifting consumer preferences towards sustainable and high-performance materials encourage manufacturers to innovate in product design. Enhanced product performance increases competitiveness among suppliers aiming to capture a larger market share. Regulatory compliance regarding workplace safety emphasizes the importance of high-quality mats, pushing companies to invest in nylon and polyamide options that meet rigorous standards.
Supply chain resilience plays a critical role, with manufacturers focusing on securing reliable sources of raw materials for nylon and polyamide. This focus supports uninterrupted production processes, essential for meeting demand fluctuations in the market. While the market evolves, strategic opportunity windows arise, enabling firms to develop next-generation products that align with changing industry needs.
Increasing awareness regarding the benefits of polyester mats promotes their adoption across various end-use sectors. Key characteristics including durability, easy maintenance, and cost-effectiveness enhance appeal to industries including manufacturing, healthcare, and hospitality. These attributes drive demand among buyers seeking long-lasting solutions that improve workplace safety and aesthetics.
Technological advancements fuel product evolution, resulting in innovations that enhance the performance of polyester mats. Developments focused on improving resilience, comfort, and moisture resistance cater to the needs of specific applications, driving further adoption. Consequently, the market experiences growth driven by businesses looking for solutions that align with operational requirements and workplace standards.
Regulatory compliance with safety and environmental standards influences purchasing decisions significantly. Industries prioritize materials that meet emerging regulations, which enhances the market's attractiveness. Certifications related to performance, fire resistance, and eco-friendliness further strengthen polyester's position in the industrial mats market.
Fluctuations in raw material prices shape the cost structures of polyester mats, impacting pricing strategies. Manufacturers navigate these challenges by optimizing procurement and maintaining supply chain resilience. Continuous monitoring of market conditions enables producers to adjust pricing dynamically, ensuring competitiveness.
Strategic opportunity windows arise from shifting consumption patterns, because buyers increasingly prefer sustainable and versatile mat options. The growth of eco-friendly materials and practices supports the demand for polyester mats, aligning with broader industry trends. While environmental consciousness escalates, the market stands to benefit from innovations in sustainable production processes.
Aluminium serves because a specialized material type within the Industrial Mats market, appealing to industries that require durability and resistance to harsh environmental conditions. Applications in industrial settings, including manufacturing and construction, drive demand, owing to the material's strength and longevity.
The expansion of the aluminium segment aligns with advancements in manufacturing processes and increased focus on sustainability. Industries are increasingly adopting aluminium mats due to their lightweight nature, which facilitates transport and installation while ensuring compliance with regulatory standards. Enhanced performance characteristics, including resistance to corrosion and ease of maintenance, contribute to the appeal of aluminium mats in various applications.
Technological maturation influences the evolution of aluminium products, with ongoing innovations leading to improvements in design and functionality. Manufacturers focus on developing next-generation products that incorporate advanced features, including anti-slip surfaces and custom sizes, catering to specific end-use requirements.
Growing awareness regarding workplace safety, coupled with stringent compliance requirements, influences consumption patterns within the market. Industries place increasing emphasis on safety standards, further driving the adoption of aluminium mats in environments where slip resistance and durability are critical.
Supply chain resilience affects raw material sourcing for aluminium mats, because fluctuations in availability and pricing impact overall production costs. Strategic investments in sourcing practices help mitigate these challenges, ensuring stability in the supply of aluminium for manufacturing.
The market for aluminium mats reflects strategic opportunity windows, particularly because organizations increasingly prioritize sustainable practices. The transition toward eco-friendly materials, alongside the emphasis on reducing environmental footprints, positions aluminium because a favorable option in the evolving industrial landscape. Overall, the aluminium segment continues to emerge because a vital component in the broader context of the Industrial Mats market.
Unique materials including EPDM, silicone, and natural rubber blends contribute to niche applications within the Industrial Mats market. EPDM stands out due to its excellent resistance to heat, ozone, and weather, making it suitable for outdoor and industrial use. Silicone, known for its high-temperature resistance and flexibility, finds applications in environments requiring durable, heat-resistant mats. Natural rubber blends offer an eco-friendly alternative, appealing to environmentally conscious consumers and industries.
Demand for these materials stems from various end-use industries, including manufacturing and healthcare, where specific performance characteristics drive the choice of matting solutions. The market shows a growing trend towards customization, with manufacturers developing tailored products to meet specialized requirements. This evolution in product offerings aligns with broader industry dynamics, emphasizing sustainability and performance in material selection.
Technological advancements play a critical role in enhancing the properties of these materials, thereby expanding their utility in diverse applications. Continuous innovation in production techniques enables the development of mats that combine multiple materials, leading to improved performance characteristics including durability and comfort. Evolving industry needs drive the demand for versatile and high-performance mats, influencing the overall trajectory of the market.
Valued at USD 1,560.5 million in 2026, the Anti-Fatigue Mats segment is projected to reach USD 2,338.4 million by 2033, at a CAGR of 5.9% during the forecast period. Demand for anti-fatigue mats arises from their proven ability to enhance worker comfort and productivity in environments that require prolonged standing. Industries including manufacturing, healthcare, and retail increasingly adopt these mats to mitigate fatigue-related issues, contributing to their expansion. Growing awareness regarding employee health and safety drives investments in ergonomic solutions, accelerating market growth.
Technological advancements in material innovation enhance the performance and durability of anti-fatigue mats. Manufacturers incorporate features including anti-slip surfaces and easy-to-clean materials to meet rising consumer expectations. Expansion catalysts include an increasing focus on workplace wellness initiatives, which promote the adoption of products that contribute to employee well-being. Companies investing in high-quality anti-fatigue mats experience improved employee satisfaction and reduced absenteeism, resulting in operational benefits.
Compliance with health and safety regulations influences the acceptance of anti-fatigue mats within various sectors. Organizations recognize the importance of adhering to these standards, prompting a shift towards certified products that ensure safety and promote a healthy work environment. Cost structures associated with premium materials, including rubber and nitrile rubber, reflect a direct correlation with pricing strategies, emphasizing the value of quality in the market.
While the Industrial Mats market evolves, opportunities for next-generation upgrades in anti-fatigue mats present a strategic focus area. Innovations that integrate sustainability, including recyclable materials and environmentally friendly manufacturing processes, align with shifting consumer preferences towards eco-conscious products. This development attracts environmentally aware customers and positions companies favorably within competitive environments.
Demand for entrance mats is driven by increased focus on cleanliness and safety across various facilities, including commercial buildings, educational institutions, and healthcare facilities. These mats serve because the first line of defense against dirt, moisture, and debris, ensuring that indoor environments remain clean and safe. The expansion of the entrance mats segment is projected to reach USD 1,151.9 million by 2033, at a CAGR of 5.8% during the forecast period.
Technological advancements contribute significantly to product evolution within this segment. Innovations in materials, including improved durability and aesthetic appeal, enhance the performance of entrance mats while catering to consumer preferences. End-use dynamics reflect a growing demand for customizable options, enabling businesses to promote branding through logo mats while maintaining functionality.
Regulatory compliance standards increasingly influence the market, particularly concerning slip resistance and sustainability. Manufacturers focus on meeting these standards by integrating eco-friendly materials into their products. Consumption shifts toward products with longer lifespans and reduced environmental impact further drive demand for advanced entrance mats.
Investment in supply chain resilience has become crucial, particularly in raw material sourcing. Disruptive alternatives continue to emerge, prompting manufacturers to explore innovative materials that meet performance criteria while addressing cost pressures. The interconnectedness of global supply chains highlights the need for strategic opportunity windows to adapt to changing market conditions.
Overall, the entrance mats segment demonstrates significant growth potential within the broader Industrial Mats market. The combination of rising awareness of cleanliness, safety regulations, and technological advancements positions this segment favorably for sustained demand and market expansion.
Demand for Logo Mats, expected to reach USD 977.6 million by 2033, reflects a growing emphasis on branding and aesthetics in commercial spaces. Businesses increasingly recognize the value of customized logo mats in enhancing their corporate identity and improving customer experience. The increasing focus on branding drives adoption across various sectors, including retail, hospitality, and corporate offices, where creating a welcoming atmosphere is essential.
Technological advancements in printing and mat production have contributed to the segment's growth. Enhanced capabilities enable high-quality designs and durability, appealing to businesses seeking long-lasting, visually appealing solutions. Manufacturers continually invest in next-generation upgrades to improve product performance and customer satisfaction.
Consumption shifts towards sustainable and eco-friendly materials influence the Logo Mats segment. Companies and consumers prioritize environmentally responsible options, driving demand for mats made from recycled materials. This emphasis aligns with broader sustainability trends in the Industrial Mats market, presenting opportunities for companies that prioritize eco-friendly practices.
Regulatory compliance standards establish expectations for product safety and environmental impact. Adhering to these guidelines ensures that companies maintain their reputations while effectively meeting customer needs. Cost structures, pricing volatility, and margin pressures remain significant factors affecting the segment. Manufacturers face the challenge of balancing quality and affordability to remain competitive.
Overall, the Logo Mats sub-segment will continue to expand. Organizations recognize the importance of branding within their environments. Companies that leverage strategic opportunities and embrace innovation will enhance their market positions and contribute to the overall growth of the Industrial Mats market.
Anti-Slip Mats segment is projected to grow at a CAGR of 6.1% during the forecast period. This growth is attributed to heightened safety regulations across various industries, including manufacturing and healthcare, where slip hazards pose significant risks. The increasing focus on employee safety and productivity drives demand for anti-slip solutions, enhancing workplace environments.
Technological advancements contribute to product evolution, with innovations in materials and designs that improve performance and aesthetics. Enhanced durability and ease of maintenance further benefit end-users, leading to greater adoption in commercial and industrial sectors. The integration of anti-slip mats in high-traffic areas significantly reduces accidents, aligning with regulatory compliance standards.
In terms of downstream applications, the anti-slip mats find extensive usage in environments including restaurants, hospitals, and manufacturing facilities. This diverse application landscape supports market expansion, fueled by rising awareness of safety standards and the importance of workplace well-being. The Industrial Mats market continues to evolve, with anti-slip mats emerging because a crucial component in enhancing safety protocols.
Growing consumer preferences toward sustainable products enhance market dynamics, because manufacturers explore eco-friendly materials. This shift not only meets regulatory requirements but aligns with consumer demand for environmentally responsible solutions. Investments in research and development play a significant role in driving innovation, further strengthening the competitive landscape in the market.
Kitchen mats serve important roles in various environments, particularly in commercial kitchens and food processing areas. The demand for these mats largely stems from their ability to enhance safety by reducing slips and falls, a critical factor in high-traffic food service areas. Increasing awareness of the necessity for hygienic solutions in food handling drives the adoption of kitchen mats, which feature materials designed for easy cleaning and maintenance.
Innovation within the segment takes shape through advancements in material technology. Next-generation kitchen mats incorporate antimicrobial properties, which help inhibit the growth of bacteria and fungi, aligning with heightened regulatory compliance standards in the food industry. The evolution of product offerings includes mats specifically engineered for durability and comfort, catering to the needs of workers who spend extended periods standing.
Shifts in consumption patterns indicate a growing preference for environmentally sustainable materials. The market sees increasing interest in kitchen mats made from recycled or bio-based materials, reflecting broader trends toward sustainability and ecological responsibility in manufacturing. This shift presents strategic opportunities for manufacturers focused on sustainability, allowing them to differentiate their products in a competitive landscape.
Cost structures associated with kitchen mats reflect the balance between material quality and pricing strategy. Manufacturers focusing on high-performance mats experience margin pressures due to raw material costs, particularly for advanced materials including polyurethane. Logistics vulnerabilities, including supply chain disruptions, impact pricing volatility and availability, influencing overall market dynamics.
Investment in research and development shapes the future of kitchen mats, driving product evolution and enhancing offerings within the Industrial Mats market. Increased capital investment into innovation and technology creates a competitive environment, encouraging players to develop products that meet the diverse needs of end-users across various sectors.
Welding mats play a crucial role in various industrial applications, providing essential protection for workers in welding environments. The emphasis on safety and compliance with occupational health standards drives adoption within the manufacturing and construction sectors. Increased focus on worker safety regulations ensures that companies invest in high-quality mats that withstand the rigors of welding operations.
Technological advancements contribute to the evolution of welding mats, with manufacturers incorporating features including heat resistance and improved durability. Innovations in material science allow for the production of mats that offer enhanced thermal protection and longer lifespan, meeting the demands of modern industrial users. The shift towards next-generation upgrades highlights the ongoing commitment to improving worker safety and efficiency in the industrial mats market.
Downstream applications in industries like automotive and aerospace further stimulate demand for welding mats. These sectors require reliable solutions to protect workers and facilities during welding processes, ensuring compliance with stringent safety protocols. Consumption shifts towards more sustainable materials align with increasing environmental awareness in the market.
Regulatory compliance standards play a significant role in shaping the market landscape for welding mats. Adherence to guidelines from safety organizations influences purchasing decisions among end-users, ensuring that investments in protective equipment align with legal requirements. Companies focusing on certification find strategic opportunities to enhance their product offerings and gain a competitive edge.
Pricing volatility remains a consideration for manufacturers and end-users alike. Fluctuations in raw material costs impact the overall pricing structure of welding mats, pressuring profit margins. Strategic management of supply chain resilience becomes essential to mitigate potential risks associated with sourcing materials and delivering products to the market.
Within the industrial mats market, opportunities exist for companies that address substitution risks and disruptive alternatives through innovation. Continuous development in product offerings strengthens market presence and attracts a broader customer base. Capital investment in R&D is critical for firms aiming to stay ahead in this evolving segment.
The emergence of Sticky Mats within the Industrial Mats market aligns with growing concerns regarding cleanliness and hygiene across various industries. Demand for these mats arises from increased awareness surrounding the transmission of contaminants and pathogens, particularly in high-traffic areas. Industries including healthcare, food processing, and hospitality exhibit heightened interest in maintaining sanitized environments, driving the adoption of Sticky Mats.
Technological maturation in mat designs has led to advancements in adhesive properties and materials, enhancing performance characteristics. Manufacturers invest in next-generation upgrades to improve durability, ease of cleaning, and overall effectiveness. This evolution in product offerings expands applications and enhances usability in diverse environments.
Changes in consumption patterns reflect a shift towards prioritizing cleanliness and safety, particularly in settings with stringent regulatory compliance standards. The healthcare and food service sectors increasingly recognize the value of Sticky Mats in preventing slip hazards and maintaining sanitary conditions. This trend positions Sticky Mats because essential tools for businesses seeking compliance with health regulations.
Pricing volatility and margin pressures impact suppliers within this segment, owing to raw material sourcing and production costs fluctuating. Effective supply chain management becomes crucial in mitigating risks associated with logistics vulnerabilities and maintaining product availability. Strategic opportunity windows arise because businesses adapt to these changing dynamics, allowing for potential market expansion.
Overall, Sticky Mats play a significant role in enhancing safety and cleanliness across various industries. The Industrial Mats market recognizes this segment's importance, leading to increased investment and product innovation aimed at meeting evolving consumer demands.
Strong demand for Chemical Resistant Mats arises from their application in various environments where exposure to chemicals poses significant risks. Industries including manufacturing and oil and gas frequently use these mats to enhance workplace safety and protect surfaces from chemical spills. The continued emphasis on worker safety drives investment in products that minimize hazards and comply with stringent regulatory standards.
Technological advancements in materials science contribute to the evolution of Chemical Resistant Mats, enabling the development of next-generation products that offer superior protection and durability. Innovations focus on enhancing resistance to a wider range of chemicals while maintaining comfort and usability, appealing to end-users across diverse sectors. This evolution aligns with broader trends in the Industrial Mats market, where the integration of advanced materials is essential for meeting changing consumer preferences and regulatory requirements.
End-use dynamics reflect a notable shift towards environmentally friendly materials, increasing the importance of sustainable sourcing and production practices. Companies prioritizing eco-friendly options position themselves competitively in the market, responding to growing consumer awareness regarding environmental impact. This strategic positioning aligns with the increasing focus on compliance with environmental regulations, which further influences purchasing decisions.
While demand for Chemical Resistant Mats grows, manufacturers face challenges related to cost structures and pricing volatility. Fluctuations in raw material prices impact profitability, necessitating efficient supply chain management to mitigate risks. The market's response includes investing in supply chain resilience to ensure consistent product availability while navigating potential disruptions.
Strategic opportunity windows appear within the Chemical Resistant Mats segment, with market players focusing on niche applications that require specialized solutions. Identifying and addressing these white-space opportunities enhances competitive positioning, allowing companies to cater to specific end-user needs while capturing additional market share. Capital investment in product development and marketing campaigns strengthens brand visibility, supporting long-term growth within the Industrial Mats market.
Increased focus on safety and hygiene across various industries drives demand for mats that provide specialized protection. Interlocking mats, ESD mats, and safety mats serve diverse functions, enhancing safety in environments including manufacturing, healthcare, and logistics. Many organizations implement these mats to comply with regulatory standards, ensuring a safe working environment for employees. End-use industries prioritize these products to mitigate slip-and-fall incidents and protect sensitive components from electrostatic discharge, contributing to overall operational efficiency.
Technological advancements in materials enhance the performance of these mats, allowing for improved durability and easier maintenance. These developments lead to product evolution, catering to specific industry needs while providing cost-effective solutions for businesses. The market reflects a shift toward integrating next-generation upgrades that offer added value through innovative features. Industries adapt to changing safety regulations, making the adoption of interlocking mats, ESD mats, and safety mats crucial for maintaining workplace standards, ultimately influencing market growth.
Strategic opportunity windows arise from companies exploring new applications and markets for these products. Manufacturers invest in research and development to create mats that meet emerging demands, driving competition within the Industrial Mats market. This competitive landscape encourages players to differentiate their offerings, leveraging unique features and compliance with safety regulations to attract customers. Investment in marketing and distribution channels further enhances product visibility, reinforcing the position of these mats in the market.
Projected growth in the Direct segment reflects strong demand driven by businesses seeking efficient procurement strategies. Valued at USD 3,009 million in 2026, this segment is anticipated to reach USD 4,473.5 million by 2033, reflecting a CAGR of 5.8% during the forecast period. The shift towards direct purchases enables buyers to establish closer relationships with suppliers, thus enhancing negotiation capabilities and reducing lead times. This trend is particularly evident in sectors with high safety and operational standards, including manufacturing and healthcare, where reliable supply chains are crucial.
Regulatory compliance standards increasingly influence purchasing decisions, compelling companies to source materials that meet stringent safety requirements. While industries evolve, the focus on premium products with superior durability and functionality drives the demand for high-quality mats. The Industrial Mats market experiences a significant shift towards products that not only fulfill basic requirements but offer enhanced features, aligning with the expectations of end-users across various sectors.
Distribution through indirect channels is important in the Industrial Mats market. This channel enables suppliers to reach a wider customer base, leveraging existing retail networks and online marketplaces. Products offered through indirect channels often include specialty items that attract specific end-use industries, including healthcare, construction, and manufacturing.
Indirect segment is estimated to reach USD 3,559.4 million by 2033, at a CAGR of 6.9% during the forecast period. Key drivers for this growth include increasing demand for specialized mats that enhance safety and comfort in various settings. The expansion of both the construction and manufacturing sectors supports this upward trend, driven by companies continuously searching for solutions that improve workplace efficiency and worker well-being.
Technological advancements in material science have led to the development of high-performance mats that meet stringent regulatory compliance standards. These innovations facilitate the entry of new products into the market while driving competition among suppliers. Consequently, enhanced product offerings increase the appeal of indirect channels, supported by the growing variety of available options tailored to diverse customer needs.
Price sensitivity remains a critical factor affecting purchasing decisions. Fluctuations in raw material costs pressure margins, necessitating strategic pricing approaches to maintain competitiveness in the market. Companies that invest in supply chain resilience and efficient sourcing practices position themselves to respond proactively to market changes. This contributes to sustained growth in the indirect segment.
Valued at USD 1,559.3 million in 2026, the manufacturing segment is projected to reach USD 2,334.3 million by 2033, at a CAGR of 5.9% during the forecast period. Growth in this segment stems from heightened demand for durable flooring solutions that enhance safety and productivity in industrial settings. Increased investments in manufacturing facilities, particularly in regions including Asia Pacific and North America, drive the adoption of industrial mats across production lines and assembly areas, ensuring compliance with stringent safety regulations.
Technological advancements in mat materials, including rubber and nitrile rubber, improve product performance, contributing to rising customer expectations regarding durability and functionality. Manufacturers seek mats that offer anti-fatigue properties, slip resistance, and ease of maintenance, creating opportunities for innovation in product offerings. The focus on ergonomics within workplaces enhances the appeal of anti-fatigue mats, which significantly improve employee comfort and reduce workplace injuries.
Demand for industrial mats in manufacturing aligns with broader trends in sustainable practices, prompting manufacturers to evaluate eco-friendly material sourcing. This shift toward sustainability aligns with government regulations and corporate responsibility initiatives, further influencing purchasing decisions. Fluctuations in raw material prices impose cost structures that impact profitability, leading manufacturers to seek reliable suppliers capable of maintaining consistent quality and pricing.
While competition intensifies, players within the industrial mats market aim for differentiation through product evolution and strategic partnerships. Emphasis on end-use dynamics drives companies to adapt to specific industry requirements, creating a tailored approach to meet varying customer needs. The manufacturing segment's growth reflects a response to immediate safety concerns and a long-term commitment to enhancing operational efficiency and worker well-being.
Growth in the Oil and Gas segment stems from increasing investments in energy infrastructure and heightened safety regulations across the sector. Rising operational safety standards necessitate the use of high-quality industrial mats, which contribute to workplace safety and efficiency. Companies engaged in oil extraction and processing leverage specialized mats to ensure a secure working environment, mitigating hazards in potentially dangerous settings.
The Oil and Gas segment is projected to reach USD 948.7 million by 2033, at a CAGR of 6.1% during the forecast period. This growth reflects a significant opportunity for manufacturers and suppliers within the Industrial Mats market to innovate and expand their product offerings. Demand for mats tailored to the unique conditions of oil and gas operations emphasizes the importance of material durability and performance, driving advancements in product development.
Technological advancements play a critical role in the evolution of industrial mats used in this sector. Enhanced materials, including specialized rubber and foam composites, provide superior resistance to chemicals and wear, addressing the specific needs of oil and gas applications. This evolution facilitates the adoption of next-generation mats that improve safety and operational efficiency across various end-use scenarios.
Construction applications in the Industrial Mats market demonstrate strong growth potential. The segment is expected to reach USD 649.1 million by 2033, driven by increasing investments in infrastructure projects and renovation activities across various regions. Enhanced safety regulations and the need for durable flooring solutions in construction sites contribute to the rising demand for industrial mats.
Technological advancements in mat materials and manufacturing processes support the development of innovative products tailored for construction environments. These advancements include the integration of anti-slip features and improved durability, which enhance user safety and satisfaction. The shift towards environmentally friendly materials influences purchasing decisions, reflecting manufacturers' responses to growing sustainability concerns.
Opportunities arise from expanding construction activities worldwide, particularly in regions with developing economies. The need for flooring solutions across commercial, residential, and industrial projects fuels demand for mats that offer functionality and safety. Increased focus on regulatory compliance and safety standards further drives adoption in this segment.
Market participants are tailoring their product offerings to align with evolving consumer preferences and demand patterns. Strategic investments and collaborations within the supply chain enhance competitiveness and expand market reach. Factors including raw material sourcing, pricing volatility, and supply chain resilience remain critical considerations for stakeholders in the construction segment of the market.
In the Healthcare and Pharmaceuticals sector, safety and hygiene standards drive demand for specialized industrial mats. These mats enhance worker comfort and reduce fatigue in environments where employees spend extended periods on their feet. Regulatory compliance further influences purchasing decisions, compelling companies to adopt high-quality materials designed to meet stringent health and safety regulations.
The Healthcare and Pharmaceuticals segment is projected to grow at a CAGR of 6.3% during the forecast period. This growth aligns with increasing investments in healthcare infrastructure and the rising number of healthcare facilities. The expansion of hospitals and clinics increases the need for effective flooring solutions, ensuring a safe and comfortable environment for patients and staff.
Technological advancements contribute to the evolution of industrial mats, with innovations improving material durability and performance. The introduction of next-gen products that incorporate antimicrobial properties enhances their appeal in healthcare settings. Demand for these advanced solutions positions the Healthcare and Pharmaceuticals segment because a vital contributor to the overall Industrial Mats market.
Demand for mats in the Food Processing and Agriculture segment derives from increasing hygiene standards and safety regulations that emphasize the importance of maintaining clean working environments. The growing focus on food safety compliance drives adoption of high-quality mats that mitigate slip hazards and facilitate easy cleaning. Key end-users within this segment include food processing facilities, agricultural plants, and distribution centers, all of which prioritize maintaining sanitary conditions.
Innovation in mat materials enhances performance, focusing on features including durability, resistance to chemicals, and ease of cleaning to meet specific requirements in food production environments. The introduction of new technologies and upgraded materials strengthens the market position of players offering specialized mats for food processing applications. Evolving consumer preferences toward sustainable products influence purchasing decisions, prompting manufacturers to develop eco-friendly mat solutions that align with industry standards.
Regulatory compliance and certifications play important roles in shaping purchasing behavior within this segment, driven by companies seeking to ensure adherence to food safety regulations. The market landscape reflects ongoing shifts in consumption patterns, with a trend toward investing in products that enhance workplace safety and efficiency. Strategic opportunities arise from these dynamics, enabling suppliers to expand their offerings tailored to the unique demands of the Food Processing and Agriculture segment within the broader Industrial Mats market.
Growth in the warehousing and logistics sector drives substantial demand for industrial mats, with applications focused on enhancing safety and comfort in operational environments. The push for improved safety standards across various industries leads to increased utilization of anti-fatigue and anti-slip mats, which mitigate hazards associated with extended standing and movement in high-traffic areas. Adoption of these products aligns with ongoing efforts to ensure employee well-being and efficiency in warehousing operations.
Technological advancements contribute to the evolution of industrial mats, with manufacturers introducing next-generation materials that enhance durability and performance. Innovations in rubber and nitrile rubber formulations play a significant role, offering superior resistance to wear and tear while maintaining comfort levels. This product evolution aligns with the market's emphasis on sustainable practices, driven by eco-friendly materials gaining traction in the supply chain.
Supply chain resilience emerges because a critical factor influencing the warehousing and logistics segment. Fluctuations in raw material sourcing and logistics vulnerabilities prompt stakeholders to seek alternatives that ensure steady supply and cost-effectiveness. These dynamics impact pricing structures, compelling producers to optimize their operations and explore strategic partnerships to enhance procurement efficiency.
Regulatory compliance standards further shape purchasing behaviors within the market. Adherence to safety regulations necessitates investment in mats that meet specific certifications, affecting both upfront costs and long-term operational expenditures. Companies increasingly recognize that compliance-driven purchases contribute positively to their corporate reputation and operational integrity.
Strategic opportunity windows arise for manufacturers who navigate market dynamics effectively while addressing the evolving needs of the warehousing and logistics sector. Capital investments in research and development facilitate the introduction of innovative products that meet emerging consumer preferences, ultimately enhancing market share and competitiveness in the industrial mats market.
Increasing adoption of automotive mats in vehicle manufacturing results from heightened awareness of safety and comfort among consumers. Major automotive manufacturers prioritize ergonomic solutions, leading to a surge in demand for anti-fatigue and anti-slip mats that enhance driver and passenger experiences. Consumer expectations for durability and performance in automotive applications drive significant innovation and development within this segment. The integration of advanced materials in automotive mats promotes weight reduction and improved aesthetic appeal, appealing to both manufacturers and consumers.
Regulatory compliance standards significantly influence the automotive segment. Stringent guidelines surrounding environmental safety and material quality necessitate the use of compliant materials in manufacturing processes. This focus on sustainability encourages manufacturers to seek eco-friendly alternatives, resulting in a shift toward recyclable and biodegradable mat solutions. Increased emphasis on sustainability aligns with broader trends in the industrial mats market, creating growth opportunities for manufacturers prioritizing environmentally responsible practices.
Technological maturation within the automotive sector offers opportunities for next-generation upgrades in mat design. Innovations in material science enable the development of mats with enhanced properties, including resistance to chemicals and extreme temperatures. These advancements ensure that automotive mats meet the evolving demands of automotive applications, reinforcing their importance in the overall production process. Strategic investment in research and development allows manufacturers to explore white-space opportunities, further driving growth within this segment.
Mining operations require durable and reliable materials to ensure safety and efficiency in often hazardous environments. The adoption of Industrial Mats within this sector is driven by the need for mats that provide slip resistance and cushioning to workers, significantly reducing fatigue during prolonged standing. Increased investments in mining activities, coupled with heightened safety regulations, increase the demand for specialized mats designed for rugged terrains and heavy machinery operations.
Technological advancements in mat manufacturing enhance functionality, enabling the development of mats that resist chemicals and abrasions commonly found in mining environments. This evolution in products aligns with the growing focus on worker safety and compliance with stringent health regulations across the mining industry. The integration of innovative materials and designs presents strategic opportunities for manufacturers seeking to capture market share in this segment.
Continued expansion of mining projects across global regions further influences market dynamics. Countries rich in mineral resources actively pursue new extraction technologies, which in turn drive the need for reliable industrial solutions, including mats. Supply chain resilience is essential, with sourcing raw materials and managing logistics becoming critical considerations for firms operating within this segment.
Pricing volatility affects purchasing decisions, with operators increasingly seeking cost-effective yet high-quality solutions. This aspect highlights the importance of suppliers who provide durable mats without compromising safety standards. The balance between cost structures and performance remains important, encouraging innovation and product evolution within the Industrial Mats market.
Increasing focus on aesthetics and functionality drives demand for mats within the hospitality sector. Hotels, restaurants, and resorts prioritize floor safety, hygiene, and customer comfort, making high-quality mats essential in their operational environments. Adoption of anti-fatigue mats in standing areas supports employee comfort during extended hours, reflecting a significant trend in workspace ergonomics. The hospitality industry's commitment to providing clean and safe environments enhances the push for mats that adhere to regulatory compliance standards and industry certifications.
Technological advancements facilitate product evolution, resulting in mats that offer improved durability and enhanced slip resistance. Innovative designs cater to specific applications within hospitality settings, including entrance mats that trap dirt and moisture effectively. Consumption shifts toward eco-friendly materials align with an increasing number of establishments prioritizing sustainability efforts. Strategic opportunity windows emerge for manufacturers to invest in next-generation upgrades that align with the hospitality sector's evolving demands.
Market dynamics indicate significant potential for growth in the hospitality segment, driven by rising consumer expectations for cleanliness and safety. Cost structures related to mat production impact pricing strategies, influencing purchasing decisions across various establishments. Suppliers face logistics vulnerabilities, necessitating resilient supply chain strategies that ensure steady raw material sourcing. Overall, the hospitality segment within the Industrial Mats market presents a promising environment for ongoing investment and innovation.
Growth in the Others segment, encompassing Retail, Education, and Aviation, arises from increased emphasis on safety, cleanliness, and branding strategies. Diverse applications across these sectors drive demand for mats that enhance aesthetic appeal and functionality while ensuring user safety. Retail environments implement mats to create welcoming entrances and maintain hygiene. Educational institutions prioritize safety and comfort for students in various settings. In the aviation sector, mats contribute to safety protocols and branding initiatives, providing a cohesive look throughout airport facilities.
Challenges in the market include cost pressures stemming from raw material sourcing and pricing volatility. Substitutes, including generic mats, pose risks, potentially impacting market share for specialized products. Nevertheless, strategic opportunities exist in developing innovative materials and designs that cater to specific customer needs. Companies investing in next-generation upgrades frequently capture market attention, aligning offerings with evolving consumer preferences.
Technological maturation influences product evolution, with continuous advancements leading to more durable and sustainable options. Compliance with regulatory standards for safety and hygiene remains essential for all players in the Industrial Mats market. Adapting to these requirements builds confidence among customers and enhances brand reputation.
Based on geography, the Global Industrial Mats market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
The North America Industrial Mats market displays strong momentum, driven by heightened safety standards and robust industrial activity. The demand for industrial mats aligns with significant investments in manufacturing and infrastructure, particularly in the United States, Canada, and Mexico. In this region, the market benefits from established supply chains and localized manufacturing densities, facilitating efficient procurement and distribution strategies.
Emerging market front-runners, especially in the construction and healthcare sectors, contribute to the acceleration in demand. With construction projects increasing, investments in anti-fatigue and entrance mats rise to support workforce productivity and safety. The healthcare sector's focus on hygiene and safety drives the adoption of anti-slip and PVC mats.
The North America Industrial Mats market is projected to expand at a CAGR of 6.3% during the forecast period, reaching a market size (TAM) of USD 1,955.2 million by the end of 2033. The region's competitive landscape features established players leveraging regional procurement dynamics and localized strategies to enhance their market positions. Domestic market participants focus on innovation and product diversification to meet evolving customer needs.
Regional resource availability complements the market's growth, supported by energy grid resiliency and robust local infrastructure readiness. Strategic entry barriers, including compliance with geographic regulatory frameworks, shape competition, ensuring that only well-prepared entities succeed. Cross-border trade corridors facilitate the movement of goods, improving the overall market environment.
The Industrial Mats market in Europe exhibits strong potential driven by a combination of increasing safety regulations and the emphasis on workplace comfort. Countries like Germany, France, the UK, Italy, and Spain contribute significantly to the market, fueled by their robust manufacturing sectors and the growing focus on employee well-being. The presence of various local manufacturers and suppliers enhances competition, facilitating innovation that meets regional preferences.
The ongoing modernization of infrastructure in Europe supports the adoption of advanced materials in mats, particularly in sectors including healthcare, construction, and automotive. Regulatory frameworks across countries ensure compliance with safety and environmental standards, which influences material selection and design in the Industrial Mats market. In addition, localized procurement dynamics, driven by cultural nuances and regional buying behaviors, impact purchasing decisions, favoring domestically produced mats.
High-value replacement cycles characterize mature markets in Europe, with established businesses seeking to upgrade to more effective and durable mat solutions. This trend drives revenue growth and invites new entrants looking to capitalize on demand for innovative products. Strategic initiatives aimed at enhancing operational efficiencies within companies contribute to the overall expansion of the market.
While geopolitical factors and trade policy shifts influence market dynamics, businesses adapt to changing conditions by regionalizing their supply chains and exploring localized manufacturing opportunities. These developments create incremental growth vectors while addressing challenges posed by cross-border trade corridors and tariff impacts. The market's trajectory reflects these evolving conditions, presenting opportunities for established players and new market entrants.
The Asia Pacific region plays a significant role in the Industrial Mats market, contributing 30% of the global market share in 2025. Nations including China, Japan, India, South Korea, and Australia demonstrate robust demand for industrial mats, driven by industrialization and infrastructure development. Increased investments in manufacturing facilities across these countries support market growth, particularly in the manufacturing and healthcare sectors.
Emerging market front-runners in Southeast Asia exhibit strong adoption rates, influenced by rising consumer awareness regarding safety and hygiene. Local compliance mandates regarding workplace safety further enhance demand, especially in industries including healthcare and oil and gas. The region's economic growth supports localized manufacturing densities, driving both demand for mats and the potential for domestic production.
Geopolitical fragmentation and trade dynamics create opportunities for cross-border trade corridors, facilitating market expansion. Domestic market participants adapt to localized procurement dynamics, tailoring products to meet specific regional requirements. This strategic approach enhances competitive positioning and aligns offerings with cultural nuances prevalent in the region.
Energy grid resiliency and regional resource availability significantly impact market growth. Regions with established energy infrastructure and resource access experience higher levels of industrial activity, driving demand for high-performance mats. Strategic entry barriers, including foreign direct investment flows, further contribute to the market's growth trajectory.
The Industrial Mats market in South America is characterized by a growing demand for mats that cater to various industrial applications. Brazil and Argentina serve because the primary markets in this region, with an increasing focus on safety standards and durability in industrial settings driving adoption. The market share for South America is 9.00% in 2025, highlighting its role because an emerging player in the global landscape.
Infrastructure modernization efforts across South America contribute to market expansion, with significant investments directed towards enhancing local manufacturing capabilities. The region's resource availability and energy grid resiliency play crucial roles in supporting the growth of the Industrial Mats market. Local compliance mandates further influence procurement dynamics, because companies emphasize meeting regional standards for safety and performance.
The competitive landscape in South America includes several domestic vendors, each focusing on delivering products tailored to local market needs. Foreign direct investment (FDI) flows into the region facilitate the introduction of innovative materials and technologies, enhancing the overall market offering. Localized manufacturing densities strengthen supply chains and support nearshoring initiatives, aligning with the global trend toward regionalization.
Overall, the Industrial Mats market in South America demonstrates promising growth potential driven by evolving customer preferences, increased investments in infrastructure, and strategic entry barriers that favor both local and international players. Expansion efforts by market participants focus on addressing the specific demands of industries including construction, manufacturing, and healthcare, ensuring that the region remains competitive on a global scale.
The Industrial Mats market in the Middle East and Africa experiences a notable shift in demand driven by industrial sectors that expand and modernize. Countries including Saudi Arabia and the UAE significantly invest in infrastructure and commercial projects, driving the need for industrial mats. South Africa's diverse industrial base, including manufacturing and mining, contributes to increasing demand for these products.
Regional adoption rates reflect the growing recognition of safety, hygiene, and durability requirements in various applications. Manufacturers in this region focus on developing tailored solutions to meet the specific needs of industries including oil and gas, construction, and healthcare. The market sees incremental growth stemming from high-value replacement cycles, particularly in mature markets where existing mats require upgrades.
Emerging market front-runners leverage localized manufacturing densities and regional procurement dynamics, enhancing supply chain efficiency. Geopolitical fragmentation influences trade corridors, impacting cross-border trade and influencing regional partnerships that enable market entry for international players. Domestic companies lead efforts to consolidate vendor relationships and streamline procurement processes.
Energy grid resiliency in the region supports operational continuity, while local infrastructure readiness enhances the distribution capabilities of industrial mats. Foreign direct investment (FDI) flows into the Middle East and Africa signal confidence in long-term market potential, leading to increased competition among domestic and international players. These factors position the market for sustained growth through 2033.
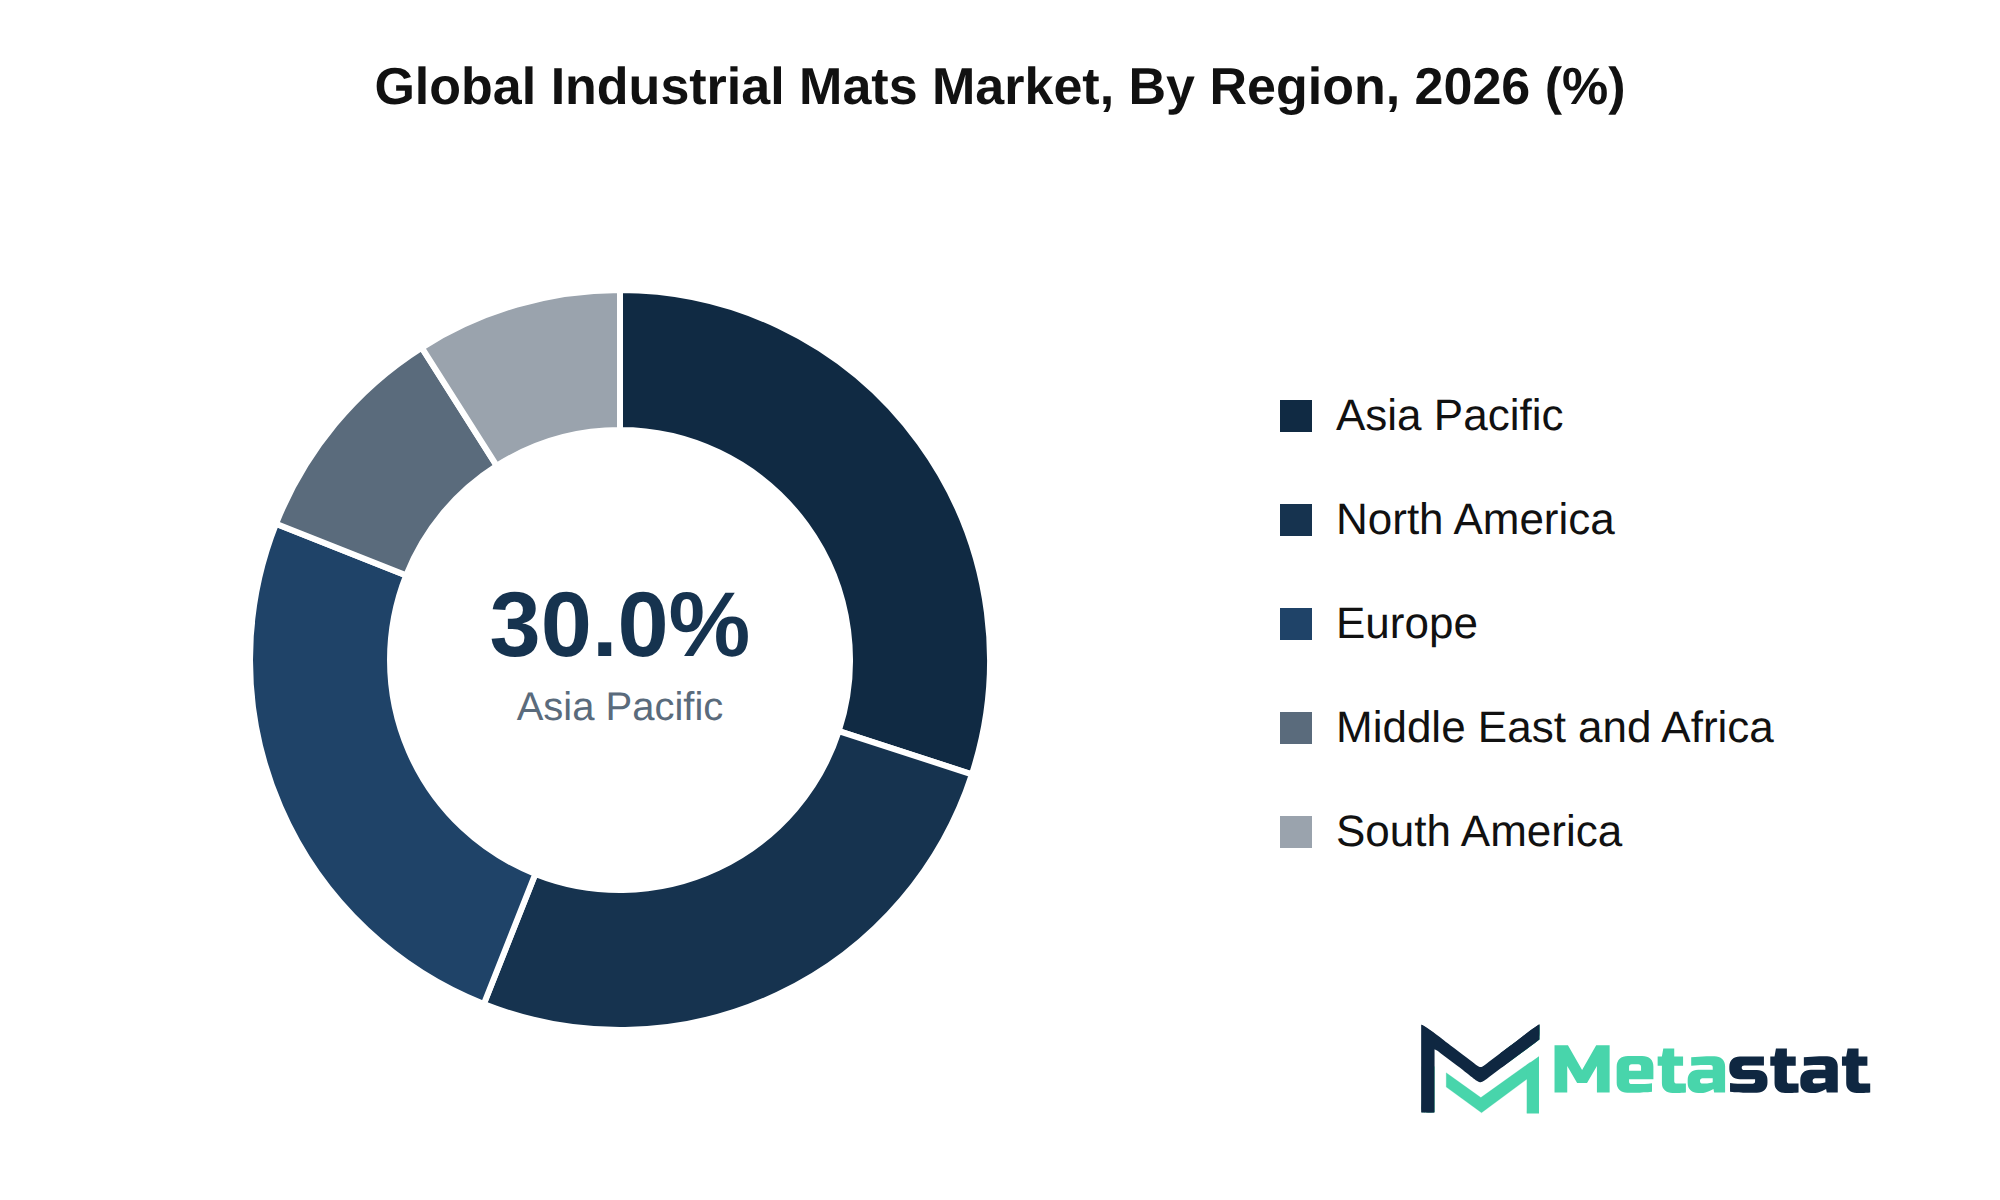
The Industrial Mats market experiences a dynamic competitive environment characterized by strategic consolidation and partnerships among key players. Companies like Kleen-Tex Europe, 3M, and Cintas Corporation actively pursue mergers and acquisitions to enhance market presence and product offerings. These strategic moves enable access to new markets and technologies, allowing firms to strengthen their competitive positioning.
Product differentiation plays a critical role in this market. Firms including M+A Matting and Wearwell LLC invest significantly in research and development to introduce innovative products tailored to diverse customer needs. This emphasis on innovation enhances brand equity and builds customer loyalty, creating a sustainable competitive advantage.
Pricing architectures within the Industrial Mats market reflect varied commercial models. Companies like NoTrax and Bergo Flooring AB implement competitive pricing strategies to attract customers across different segments. The presence of these established brands creates substantial barriers to entry for potential new entrants, influencing market dynamics and customer retention strategies.
Supply chain integration and procurement leverage are essential for maintaining operational efficiencies. Players including Eagle Mat and Floor Products and American Pro Marketing LLC focus on optimizing their supply chains to reduce costs and improve service delivery. This strategic approach enhances their capacity to respond to market demands effectively.
The future competitive outlook for the market hinges on the ability of firms to adapt to evolving customer expectations and technological advancements. Companies like Aramats and Durable Corporation are positioned to capitalize on these trends through strategic growth vectors and robust intellectual property portfolios, ensuring their place in the rapidly advancing market.
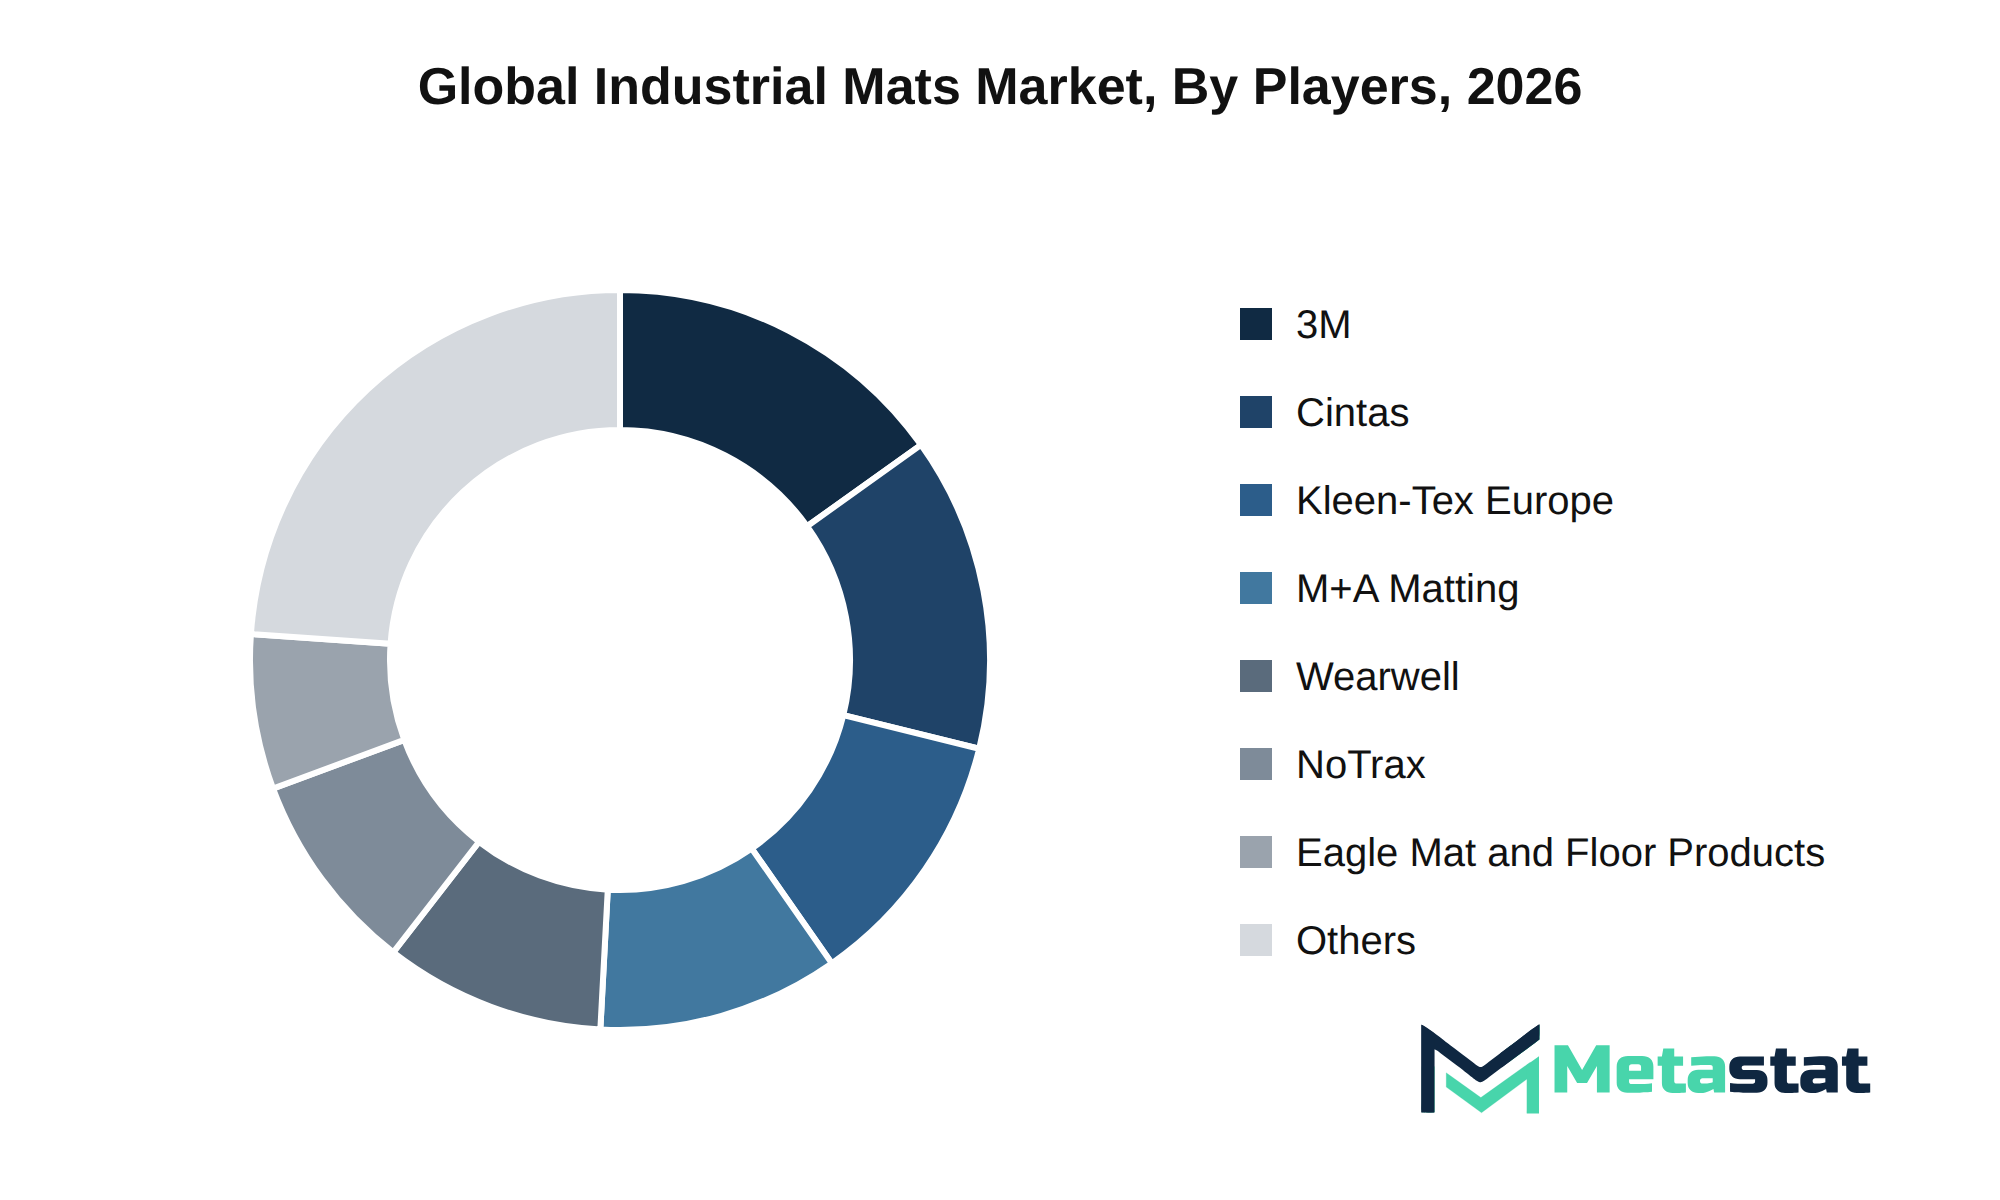
Market size is forecast to rise from USD 4,907.2 million in 2025 to over USD 8,032.9 million by 2033. The base case anticipates growth from USD 4,907.2 million in 2025 to USD 8,032.9 million by 2033 at a 6.3% CAGR. The bull case suggests accelerated growth driven by robust downstream demand, technological advancements, and increased capital allocation toward infrastructure projects. In contrast, the bear case highlights potential challenges, including geopolitical tensions, fluctuating raw material prices, and regulatory hurdles that could inhibit growth.
Key factors influencing the Industrial Mats market involve macroeconomic conditions, shifts in core industry dynamics, and changing consumer preferences. Economic cycles affect capital expenditure patterns and strategic investments, while the maturation of core industries prompts an urgent need for innovation and product lifecycle management. Regulatory evolution and compliance milestones introduce additional considerations, compelling manufacturers to adapt swiftly to maintain market relevance.
Next-generation technologies and R&D commercialization serve because critical drivers of future growth, presenting opportunities for firms to address unmet enterprise needs and tap into high-growth pockets. The strategic prioritization of capital allocation and infrastructure commitments will determine competitive positioning and operational effectiveness within the market. Emerging white-space opportunities provide avenues for expansion, promoting the development of specialized products tailored to unique industry demands.
Overall, an understanding of these factors will inform strategic decision-making and enhance the capacity of stakeholders to navigate the complexities of the Industrial Mats market, ensuring sustained growth and resilience in a dynamic environment.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Industrial Mats market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 6.3% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Material Type, Product Type, Distribution Channel, End-Use Industry, and Region |
By Region | North America (By Material Type, Product Type, Distribution Channel, End-Use Industry, and Country)
|
Europe (By Material Type, Product Type, Distribution Channel, End-Use Industry, and Country)
| |
Asia Pacific (By Material Type, Product Type, Distribution Channel, End-Use Industry, and Country)
| |
South America (By Material Type, Product Type, Distribution Channel, End-Use Industry, and Country)
| |
Middle East and Africa (By Material Type, Product Type, Distribution Channel, End-Use Industry, and Country)
|
Find answers to common questions about this report
The Industrial Mats market size was valued at USD 4,907.2 million in 2025.
The Industrial Mats market is projected to grow at a CAGR of 6.3% during the forecast period from 2026 to 2033.
The North America Industrial Mats market size is estimated to reach USD 1,955.2 million by 2033.
The leading segment in the Industrial Mats market is the Material Type segment, specifically Rubber and Nitrile Rubber, with a projected value of USD 3,200.3 million by 2033. This segment surpasses others in terms of market size and growth potential.
Strong capital investment environments and ongoing infrastructure development significantly drive the Industrial Mats market. Increased spending from public and private sectors enhances demand for various industrial mats, particularly in manufacturing and construction, while a focus on workplace safety and sustainability further supports growth.
North America holds the dominant share of the Industrial Mats market, accounting for 26 percent of the total market in 2025. This region's significant share reflects its strong industrial activity and demand for various mat types.
Regulatory compliance presents significant challenges, because manufacturers invest in advanced technologies and training to meet stringent standards, raising operational costs. Macroeconomic headwinds, including inflationary pressures and supply chain disruptions, further constrain the market by increasing material costs and reducing consumer purchasing power.
Increased capital investment from both public and private sectors enhances product adoption in the Industrial Mats market. This trend reflects a growing emphasis on operational efficiency, workplace safety, and sustainability, driving demand for specialized mats including anti-fatigue and eco-friendly options.
The Industrial Mats market is estimated to reach a valuation of USD 8,032.9 million by 2033.
Key players in the Industrial Mats market include Kleen-Tex Europe, 3M, Cintas Corporation, M+A Matting, Wearwell LLC, NoTrax, and Bergo Flooring AB.
Choose Your License
Global Industrial Mats Market
The analysts below cover Chemicals and Materials research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
INDUSTRY CONSULTANT - CHEMICALS & ADVANCED MATERIALS
Chemicals and Materials · Machinery & Equipment · Packaging
Amit Gadhekar Consultant for Chemicals and Materials at MetaStat Insight, directing sector-specific intelligence, research, and strategic consulting across global chemical and processing markets.
Last Updated: September 2026
When planning edge sensor rollouts across refinery environments, generic IoT reports typically miss the harsh-environment certification bottlenecks. MetaStat Insight gave an objective evaluation of ATEX and Class 1 Division 2 hardware availability, along with realistic five-year maintenance cycle cost projections. The comparison of wireless mesh versus private cellular backhaul helped our team pressure-test network reliability models for remote processing facilities.
In the biological seed treatment space, registration timelines vary drastically between the European Union, Brazil, and North America. The MetaStat Insight research handled these cross-border regulatory barriers with genuine nuance, mapping commercialization pathways alongside historical field adoption rates. The segmentation between microbial strains and biochemical active ingredients was particularly well structured.
Our team was tracking whether regional recycling infrastructure could realistically absorb the growing volume of lithium iron phosphate batteries over the next decade. The report did a solid job separating announced hydrometallurgical plant capacity from active, permitted operational throughput. That distinction made the feedstock availability projections and regional recovery rate models far more credible than standard commercial overviews.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950