
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Low-Carbon Ammonia Market Size, Share, By Production Pathway (Green Ammonia, Blue Ammonia, and Others (Bio-Ammonia, Circular Ammonia, Low-Carbon By-Product Hydrogen Ammonia)), By Application (Fertilizer Production, Industrial Chemicals, Power Generation, Hydrogen Carrier, Marine Fuel / Bunkering, Heavy-Duty Transportation, and Others (Energy Storage, Stationary Fuel Applications)), By Supply Model (Captive / Integrated Consumption, Domestic Merchant Sales, and International Merchant Trade / Export), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5389
September, 2026
295 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $686.7 Million in 2025, projected to reach $3,198.2 Million by 2033 at a 21.2% CAGR.
Dominant Segment: Fertilizer production leads the market, driven by increasing demand for environmentally friendly fertilizers that minimize carbon footprints. This segment is projected to grow from USD 450.2 million in 2026 to USD 1,271.6 million by 2033.
Geographic Lead: North America is a key market, holding a 22.3% share in 2025, supported by significant investments in sustainable energy and agricultural practices. Infrastructure modernization in the region enhances local production capabilities.
What's Inside: The report provides a comprehensive analysis of the competitive landscape, market dynamics, and detailed forecasts through 2033. It covers various production pathways, applications, and supply models.
Emerging Applications: The market is diversifying with new applications in power generation and hydrogen carriers, reflecting a growing focus on sustainability across industries and the need for cleaner energy solutions.
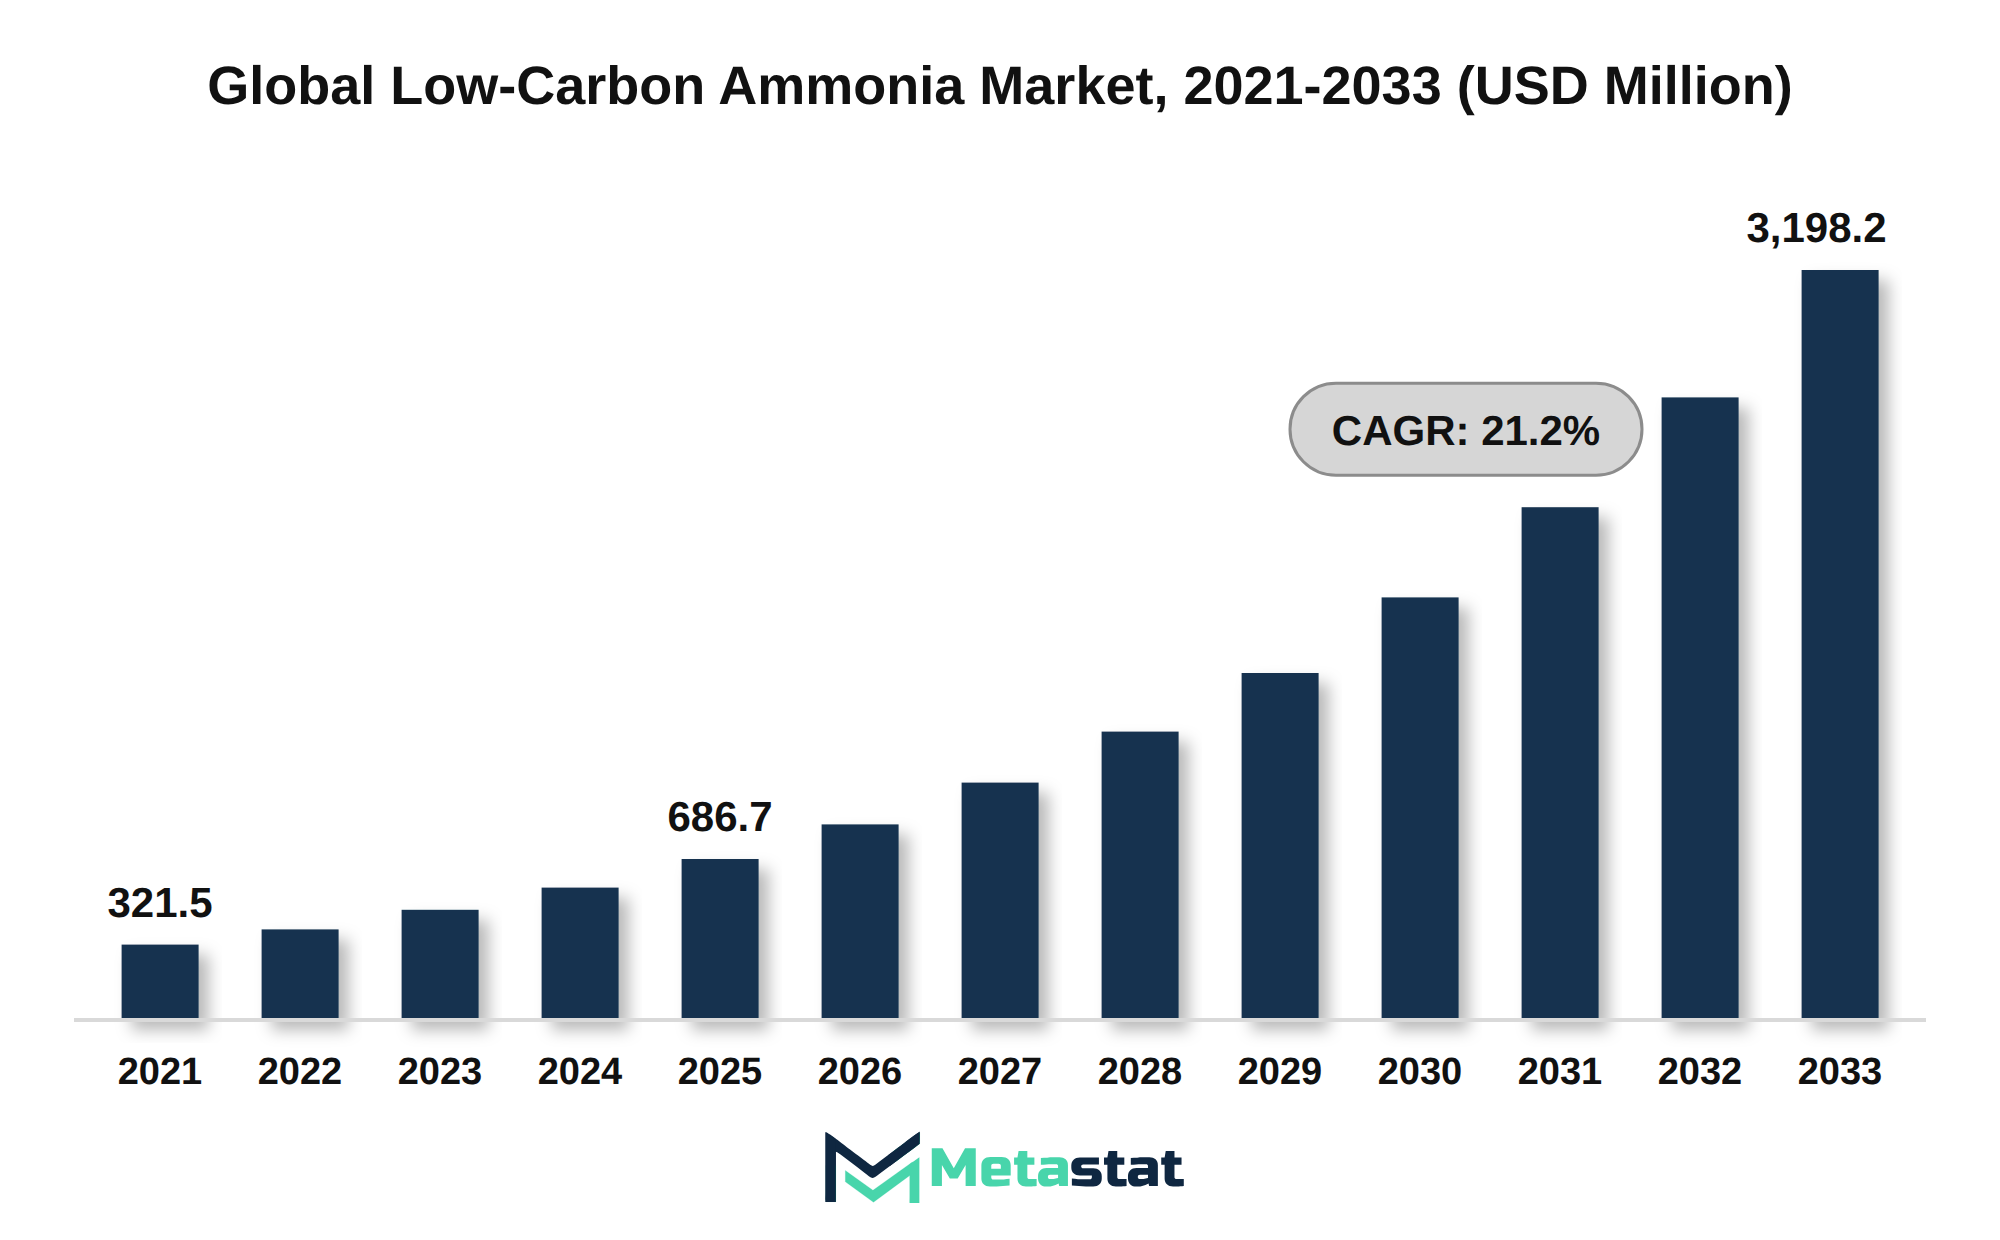
The global Low-Carbon Ammonia market was valued at USD 686.7 million in 2025 and is projected to reach USD 3,198.2 million by 2033, growing at a CAGR of 21.2% over the forecast period.
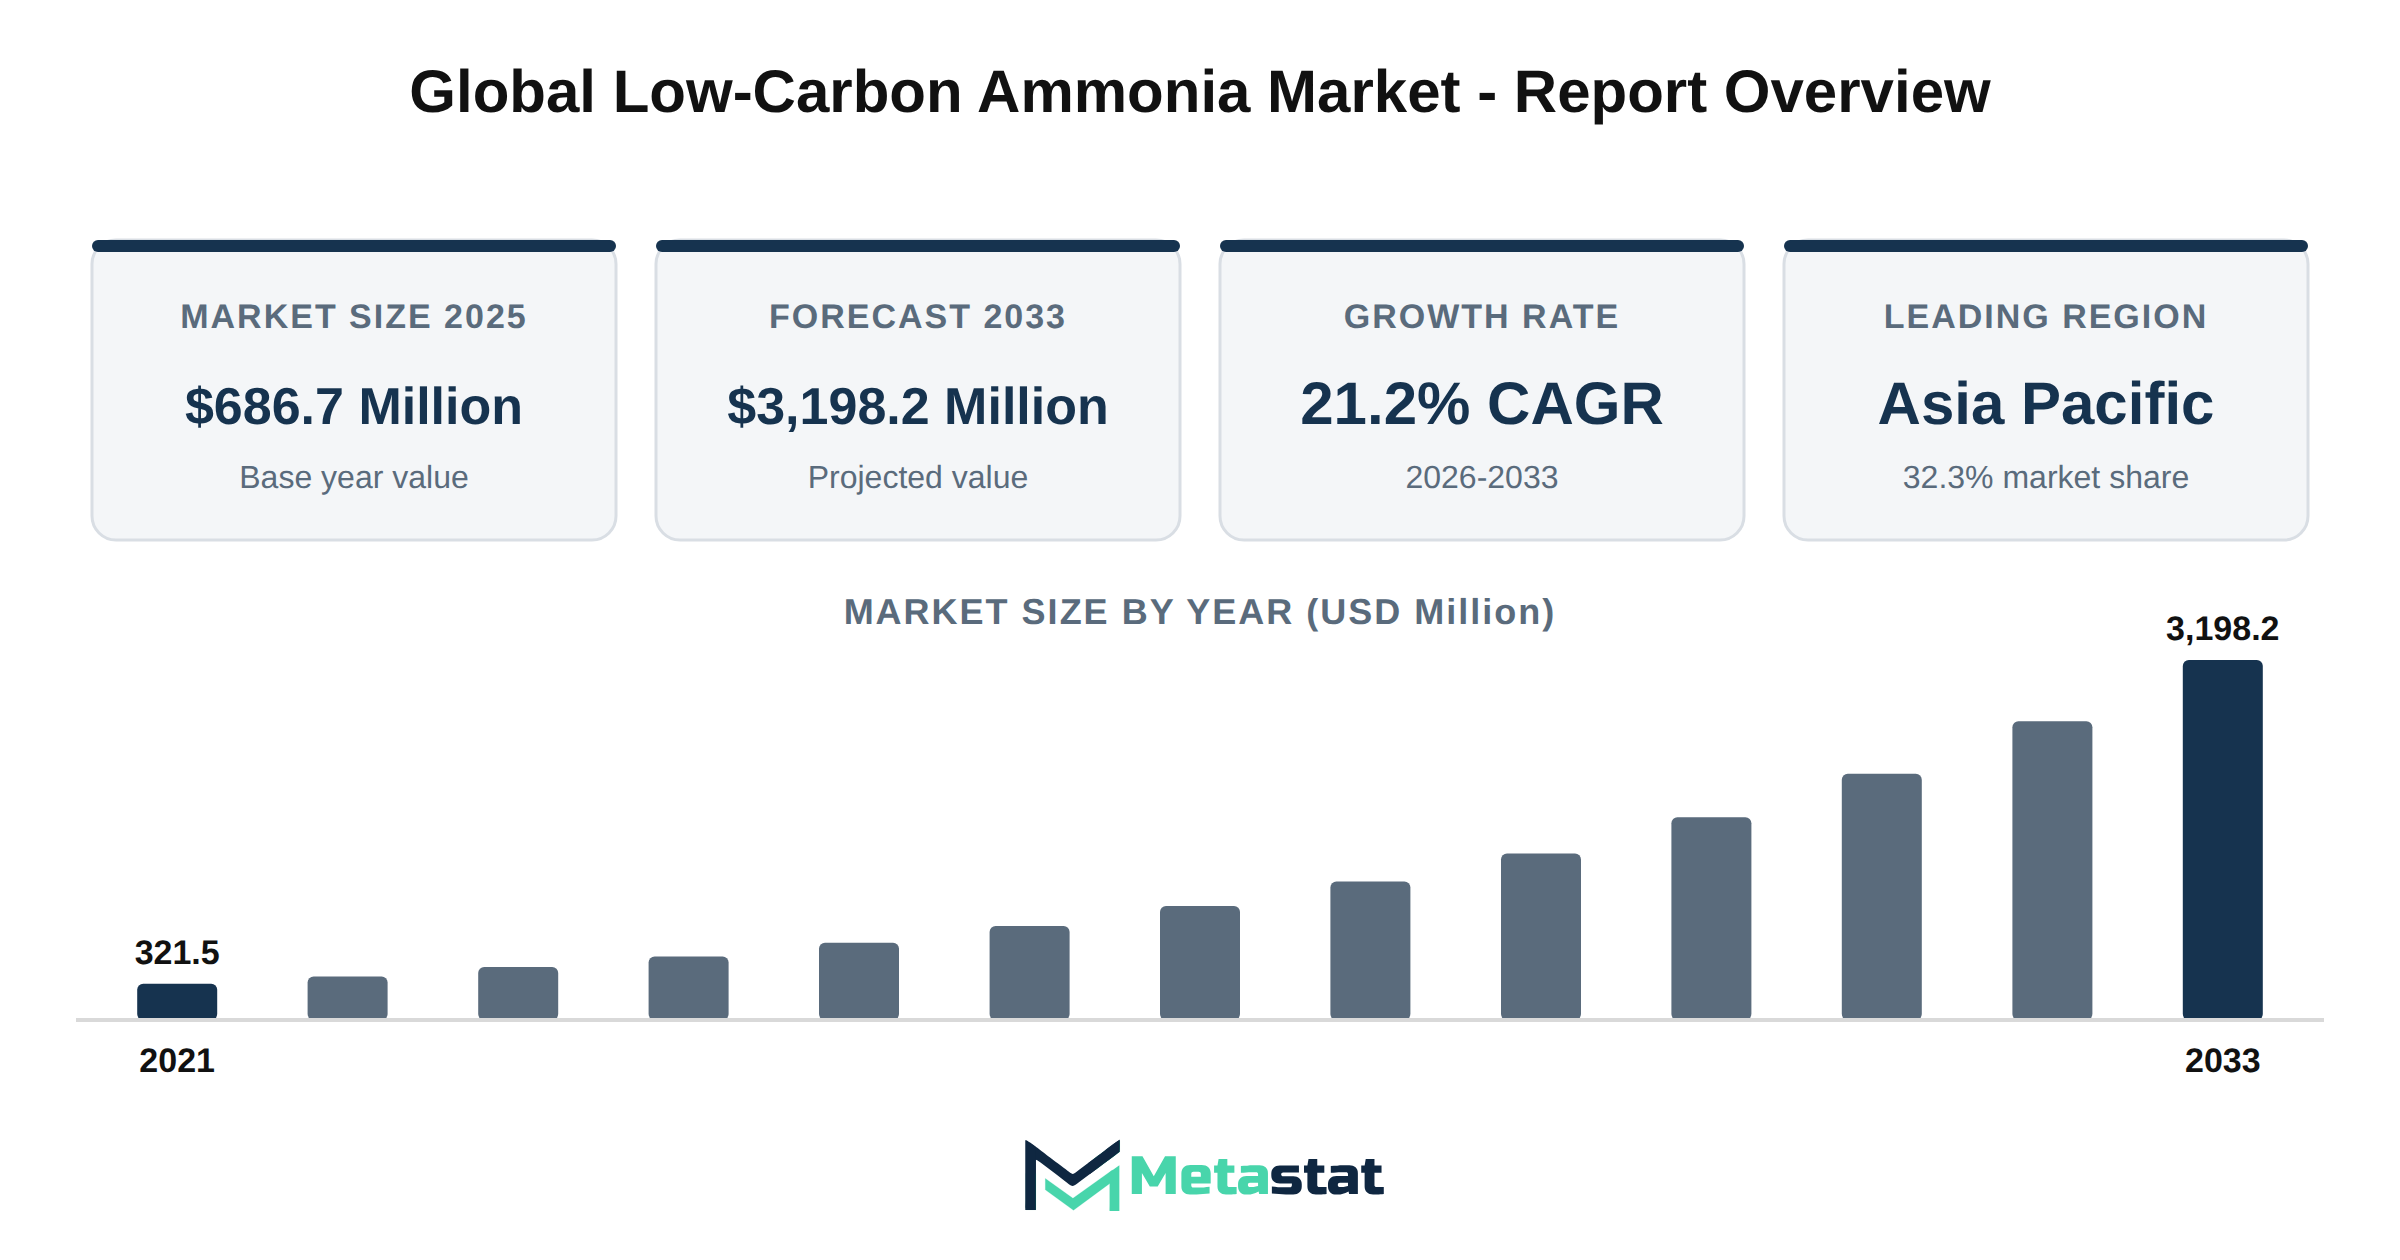
The global Low-Carbon Ammonia market is projected to experience significant growth, with a forecast value of USD 3,198.2 million by 2033, up from USD 686.7 million in 2025. This expansion represents a compound annual growth rate (CAGR) of 21.2% from the base year to the forecast period. The demand for low-carbon ammonia accelerates across various applications, particularly in fertilizer production and energy sectors. Fertilizer production alone is expected to grow from USD 450.2 million in 2026 to USD 1,271.6 million by 2033, illustrating a CAGR of 16%. The rise in demand for low-carbon ammonia in these applications reflects a broader trend toward decarbonization and sustainability within the agricultural and energy industries.
The production pathways for low-carbon ammonia, specifically green and blue ammonia, reshape supply growth within the market. Green ammonia, produced using renewable energy sources, is anticipated to increase from USD 409.2 million in 2026 to USD 1,831.3 million by 2033, achieving a CAGR of 23.9%. Blue ammonia, which incorporates carbon capture technology, will see its market value reach USD 1,212.4 million by 2033, with a CAGR of 17.7%. These innovations in production pathways drive new investment and development opportunities while improving the overall economics of low-carbon ammonia.
The economic viability of green ammonia production is significantly influenced by renewable power and hydrogen costs. The integration of renewable energy sources reduces overall production costs, enhancing the competitiveness of green ammonia against traditional ammonia production methods. The integration of carbon capture technologies strengthens the development of blue ammonia projects, positioning them because crucial components in the transition to lower carbon emissions in the ammonia sector.
Fertilizer decarbonization initiatives contribute to early adoption of low-carbon ammonia, with regulatory pressures and market incentives pushing producers toward sustainable practices. The marine bunkering sector emerges because a major growth area for low-carbon ammonia, driven by increasing demand for clean fuel alternatives in international shipping. Hydrogen carrier applications further expand the international ammonia trade, facilitating the use of ammonia because a transport medium for hydrogen fuel.
Growing demand for low-carbon ammonia across fertilizer and energy applications drives significant market expansion. Increased agricultural production, coupled with a global focus on sustainable practices, enhances the need for low-carbon solutions. The transition to low-carbon fertilizers aligns with regulatory pressures and environmental commitments, promoting higher adoption rates within the agricultural sector.
Production pathways, particularly green and blue ammonia, reshape supply dynamics, supporting substantial growth in the market. Green ammonia production leverages renewable energy sources, while blue ammonia employs natural gas with integrated carbon capture. These pathways diversify supply options and enhance market resilience, catering to various consumer needs.
Economic factors, including renewable power and hydrogen costs, significantly influence green ammonia production economics. Lower costs associated with renewable energy technologies enhance the feasibility of large-scale green ammonia projects. While production becomes more economically viable, greater investments flow into green ammonia initiatives, further supporting market growth.
Integration of carbon capture technologies strengthens blue ammonia development, improving its environmental profile and competitiveness. The ability to reduce carbon emissions during production enhances the attractiveness of blue ammonia for consumers seeking sustainable options. This trend aligns with global decarbonization efforts, promoting a robust development pipeline.
The drive for fertilizer decarbonization encourages early adoption of low-carbon ammonia solutions. Fertilizer manufacturers increasingly prioritize sustainability, aligning production practices with environmental goals. This strategic shift positions low-carbon ammonia because a preferred choice for forward-thinking agricultural stakeholders.
Emerging marine bunkering markets present new opportunities for low-carbon ammonia growth. While shipping industries seek alternative fuels, ammonia gains traction due to its low emissions profile. The establishment of ammonia bunkering infrastructure supports this transition, positioning the market favorably within the maritime sector.
Hydrogen carrier applications significantly expand international ammonia trade avenues. Ammonia's role because a hydrogen carrier facilitates its transportation and storage, enhancing its utility in global energy systems. This development promotes new trade routes and partnerships, leading to increased market accessibility.
Demand for low-carbon ammonia in power generation applications creates additional growth avenues. The fuel's versatility in generating clean energy aligns with global efforts to transition from fossil fuels. Investments in ammonia-based power generation technologies accelerate market penetration within this sector.
Challenges related to financial investment decisions (FID) and project bankability affect the low-carbon ammonia project pipeline. Developers face scrutiny regarding the economic viability of projects, impacting investment flows. Addressing these challenges will be crucial for realizing the full potential of the market.
Long-term offtake agreements provide essential support for commercial project development. Such agreements offer revenue certainty for producers, encouraging further investment in low-carbon ammonia projects. This financial backing strengthens market stability and growth prospects.
Carbon pricing mechanisms and policy incentives enhance the competitiveness of low-carbon ammonia solutions. Governments worldwide implement frameworks that promote sustainable practices, creating favorable conditions for market growth. These policies serve because catalysts for investment and innovation within the sector.
Certification and carbon intensity standards shape market access and consumer preferences. Producers adhering to stringent environmental standards differentiate themselves within the market. This focus on sustainability becomes a key selling point for buyers, driving demand for certified low-carbon ammonia products.
International ammonia trade corridors expand significantly across Europe and Asia. Enhanced trade relationships facilitate the movement of low-carbon ammonia, promoting collaboration among global players. This trend supports broader market integration and diversification of supply chains.
Investment in port infrastructure and storage capabilities strengthens ammonia supply chains. Improved logistics support the efficient distribution of low-carbon ammonia products, facilitating market access. This infrastructure development plays a critical role in meeting growing demand.
Asia Pacific emerges because a leader in new low-carbon ammonia demand opportunities. Rapid industrialization and urbanization in the region drive increased fertilizer and energy needs, positioning low-carbon ammonia because a strategic solution. This growth potential attracts significant investment and innovation in the market.
The Middle East and North America strengthen their positions because export-oriented ammonia suppliers. Access to abundant natural resources and established production facilities support this trend, positioning these regions because key players in the global market. Export growth contributes to increased competition and innovation.
Scale-up of electrolyzer technologies supports the expansion of green ammonia capacity. Advancements in electrolyzer efficiency reduce production costs, enhancing the attractiveness of green ammonia. This progress encourages investment in renewable energy projects, further driving market growth.
Development of ammonia shipping and bunkering infrastructure gains momentum. Enhanced logistics capabilities facilitate the transition to ammonia because a fuel alternative, supporting market expansion. This infrastructure development aligns with global sustainability goals, promoting low-carbon solutions.
Pricing dynamics in the low-carbon ammonia market reflect feedstock, power, and carbon costs. Fluctuations in these costs influence market pricing strategies, impacting consumer demand and producer profitability. Maintaining competitive pricing will be essential for sustaining market growth.
Competitive strategies increasingly focus on integrated hydrogen and ammonia projects. Collaborations among industry players enhance operational efficiency and market reach. This strategic alignment positions companies to capitalize on emerging opportunities within the low-carbon ammonia sector.
Future growth of the low-carbon ammonia market relies on cost reduction initiatives and supportive policy frameworks. Addressing financial and operational challenges will be critical for realizing potential in this evolving market. Long-term strategies that prioritize sustainability and innovation will drive continued expansion.
Increasing emission limits across multiple sectors drive the adoption of low-carbon ammonia because a key enabler for sustainability initiatives. Industries, particularly those in agriculture, energy, and chemicals, face pressures to reduce their carbon footprints, aligning with broader environmental, social, and governance mandates. This shift creates demand for low-carbon ammonia, which acts because a cleaner alternative to traditional ammonia production methods.
Investment in innovative technologies that enhance production efficiency and reduce environmental impact supports the market's growth trajectory. Capital investments facilitate the integration of advanced automation and digital solutions, enabling manufacturers to optimize processes while minimizing emissions. Sectors leveraging these advancements experience operational cost reductions and enhanced productivity, further incentivizing the transition to low-carbon ammonia.
Collaboration between private entities and public institutions creates an ecosystem conducive to the development and commercialization of low-carbon ammonia technologies. This partnership encourages venture funding and public-private spending, facilitating research and development aimed at improving the production pathways of low-carbon ammonia. Through these collaborative efforts, the market gains resilience against fluctuations in traditional ammonia supply chains, enhancing its competitive edge.
While requirements for emission reductions evolve, the low-carbon ammonia market is set to experience significant expansion. Stakeholders in agriculture, energy, and industrial applications increasingly prioritize sustainable solutions, effectively driving demand for low-carbon ammonia across diverse sectors. This growing focus on sustainability positions low-carbon ammonia because a critical component for achieving emissions targets and supporting a greener economy.
Shifts in capital investment environments significantly influence the Low-Carbon Ammonia market. Factors including interest rates, GDP growth, and public-private spending power play a crucial role in determining the pace and scale of investment in low-carbon technologies. Increased venture funding directed towards green technologies encourages innovation and the development of new production pathways for low-carbon ammonia, enhancing its availability in various applications.
The focus on sustainability and environmental, social, and governance (ESG) mandates increases investor interest in low-carbon ammonia. Industries seek to align their portfolios with sustainable practices, directing capital towards projects that support carbon footprint reduction and resource stewardship. This investment surge expands operational capacity and encourages technological integration, driving advancements in production methods for low-carbon ammonia.
Infrastructure development and asset modernization initiatives improve supply chain resilience for low-carbon ammonia production. Upgrading facilities and enhancing digital capabilities facilitate the efficient production and distribution of low-carbon ammonia, responding to rising demand across sectors including fertilizers and industrial chemicals. The combination of these factors positions the market for significant growth in the upcoming years.
High capital investment requirements present a significant restraint for the Low-Carbon Ammonia market. Many producers face substantial costs when establishing or upgrading facilities to meet the standards for low-carbon ammonia production. These financial barriers particularly impact smaller firms and new entrants that lack the resources to compete with larger, more established players. Consequently, the competitive landscape narrows, driven by well-capitalized entities that effectively invest in the necessary infrastructure and technology.
Rising operating costs compound the challenges associated with capital investments. Fluctuations in raw material prices, labor expenses, and maintenance costs escalate the financial burden on producers. This trend leads to reduced profit margins and discourages further investment in low-carbon technologies. Such economic pressures could hinder market growth, affecting the overall adoption rate of low-carbon ammonia across various applications.
Market fragmentation complicates the situation, with various players operating under different economic conditions and regulatory environments. This disparity creates inconsistencies in pricing and availability, which restrains consumer adoption. In regions where production costs remain high, demand for low-carbon ammonia experiences slower growth, impacting the market's expansion trajectory.
Geopolitical fragmentation introduces significant challenges for the Low-Carbon Ammonia market, affecting supply chain stability and trade dynamics. Nations prioritizing domestic production often implement trade barriers, creating tariff friction that hinders international collaboration. This environment disrupts the availability of critical feedstocks and components necessary for low-carbon ammonia production, leading to volatility in pricing and supply reliability.
Technological disruptions represent another challenge, particularly in research and development integrations. Innovation in low-carbon ammonia technologies progresses at varying rates, complicating interoperability between different systems and processes. Divergent technological standards limit the scalability of solutions and create knowledge gaps among workforce talent, contributing to skill shortages.
Rising input cost structures emerge because a pressing issue, with increasing prices for raw materials and energy impacting profit margins. The market faces pressure from intensifying competition and pricing compression, prompting producers to optimize costs while maintaining quality. Environmental lifecycle footprints influence operational protocols, necessitating investments in sustainable practices that further strain financial resources.
Infrastructure gaps introduce additional barriers, particularly in regions with limited investment in renewable energy sources and transportation networks. Retrofitting existing facilities to accommodate low-carbon ammonia production incurs high costs and implementation bottlenecks, which delay market entry for new players. Addressing these infrastructure challenges is essential for ensuring the market's growth and competitiveness.
Overall, geopolitical tensions, technological advancements, input price fluctuations, and infrastructural constraints significantly influence the Low-Carbon Ammonia market, shaping opportunities and risks for stakeholders. Companies navigate these complexities to establish resilient operations while meeting evolving market demands.
The Low-Carbon Ammonia market experiences opportunities through the emergence of novel applications across various industries. Increased focus on sustainable practices and environmental, social, and governance (ESG) criteria leads to diversification in end-user sectors. Fertilizer production remains a significant application; however, emerging demand in power generation, industrial chemicals, and hydrogen carriers expands market reach. Technological advancements enhance the capabilities of low-carbon ammonia, making it a versatile solution for multiple energy transitions.
Growing initiatives for digital transformation in procurement and supply chain management reshape buyer behaviors. Companies seek innovative solutions that enable streamlined processes and operational efficiency. The shift towards renewable energy sources reinforces the integration of low-carbon ammonia because a hydrogen carrier, while its use in marine fuel and heavy-duty transportation represents niche applications with significant growth potential. These trends position the market favorably for strategic consolidation through cross-industry mergers and partnerships, further driving innovation and value creation.
Infrastructural modernization aligns with evolving demands for localized supply chains and sustainable practices. Enhanced asset management and life-cycle extension strategies support the transition to low-carbon energy systems across regions. The market's growth correlates with increased investments in production capacity and technological innovations, providing a robust foundation for future development. With stakeholders focusing on greener transformations, the Low-Carbon Ammonia market stands poised for substantial advancement because diverse industries align their operational frameworks with sustainability imperatives.
The Global Low-Carbon Ammonia market is segmented based on Production Pathway, Application, and Supply Model.
Green ammonia represents a significant segment within the low-carbon ammonia market, valued at USD 409.2 million in 2026. Projections indicate growth to USD 1,831.3 million by 2033, achieving a CAGR of 23.9% throughout the forecast period. This robust expansion results from the increasing emphasis on sustainable agricultural practices and the necessity for cleaner energy sources.
The agricultural sector significantly stimulates the demand for green ammonia, particularly for fertilizer production. Farmers recognize the environmental benefits of adopting green ammonia, which offers a carbon-free alternative to traditional ammonia sources. This aligns with global trends toward reducing greenhouse gas emissions and promoting sustainable farming practices.
Technological advancements play a critical role in the maturation of the green ammonia segment. Innovations in electrolysis and renewable energy integration enhance the efficiency of ammonia production, reducing costs over time. These advancements attract investment and create a competitive landscape, encouraging new entrants and established players to focus on sustainable solutions.
Regulatory compliance and policy frameworks drive segment growth. Governments worldwide implement stricter emissions regulations, promoting the adoption of green technologies. Such policies create a favorable environment for producing and adopting green ammonia, contributing to its rising market share.
Investment in infrastructure remains essential for the segment's expansion. Enhanced production facilities and supply chain resilience increase accessibility and distribution capabilities for green ammonia. This results in a steady supply of the product, meeting the rising demand from various industries.
The green ammonia segment is poised for significant growth within the low-carbon ammonia market, driven by increasing demand for sustainable agricultural solutions, technological advancements, and supportive regulatory frameworks. The trajectory of this segment highlights its vital role in the transition toward a more sustainable and low-carbon future.
Demand for Blue Ammonia continues to increase, driven by its important role in reducing carbon emissions and meeting regulatory compliance standards. Industries including fertilizers and industrial chemicals seek low-carbon solutions to align with sustainability goals. This trend enhances the adoption of Blue Ammonia, especially in regions focused on decarbonization initiatives.
Blue Ammonia segment is estimated to reach USD 1,212.4 million by 2033, at a CAGR of 17.7% during the forecast period. Factors contributing to this growth include technological advancements in production pathways and the need for cleaner alternatives in energy generation. The increasing integration of Blue Ammonia because a hydrogen carrier further strengthens its market position, catering to the expanding hydrogen economy.
End-use dynamics reflect a notable shift toward sustainable practices, with Blue Ammonia emerging because a cost-effective solution for numerous applications. Regulatory frameworks supporting low-carbon technologies enhance the investment outlook, encouraging stakeholders to explore this segment actively. Supply chain resilience and raw material sourcing strategies are critical for maintaining competitive advantage in the evolving market of Low-Carbon Ammonia.
Strong interest in sustainable practices drives the adoption of alternatives including Bio-Ammonia, Circular Ammonia, and Low-Carbon By-Product Hydrogen Ammonia. Industries focused on reducing their carbon footprints actively seek solutions that align with regulatory compliance and environmental standards. This push reflects a broader trend toward sustainable development across various sectors, including agriculture and energy.
Technological advancements in production pathways enhance the viability of these alternatives. Innovations in catalyst efficiency and renewable energy integration contribute to more cost-effective production methods. This maturation of technology supports the expansion potential of the segment, improving reliability and performance while addressing the growing demand for cleaner ammonia sources.
Bio-Ammonia and Circular Ammonia present significant opportunities in the fertilizer production application, aligning with global initiatives to reduce reliance on fossil fuels. End-user dynamics reflect an increasing preference for sustainable products, prompting manufacturers to explore these low-carbon solutions. The segment is projected to reach USD 154.5 million by 2033, illustrating its potential growth trajectory within the Low-Carbon Ammonia market.
Supply chain resilience becomes vital for these alternatives, emphasizing the need for reliable raw material sourcing and distribution networks. An emphasis on sustainable practices encourages collaboration among stakeholders to ensure consistent access to inputs. Strategic opportunity windows arise for companies committed to investing in technologies that facilitate the shift toward low-carbon solutions.
Pricing volatility poses challenges, influenced by fluctuating raw material costs and demand dynamics. Companies within the segment navigate these pressures to maintain profitability while pursuing market share. The ongoing evolution of product offerings ensures competitiveness within the broader Low-Carbon Ammonia market, aligning with shifting consumer preferences and regulatory landscapes.
Increasing focus on sustainable agricultural practices drives significant growth in the Fertilizer Production segment of the Low-Carbon Ammonia market. This segment is valued at USD 450.2 million in 2026 and is projected to reach USD 1,271.6 million by 2033, at a CAGR of 16% during the forecast period. Rising demand for environmentally friendly fertilizers supports crop yield while minimizing the carbon footprint associated with traditional ammonia production. Technological advancements in the synthesis of low-carbon ammonia enhance its appeal among fertilizer manufacturers, facilitating its adoption in various agricultural applications.
Regulatory compliance standards increasingly prioritize low-emission solutions, further incentivizing the shift toward low-carbon ammonia in fertilizer production. The drive for cleaner alternatives aligns with global sustainability targets, creating a favorable market environment for low-carbon ammonia products. End-use dynamics reflect a growing preference among farmers for fertilizers that improve productivity while contributing to sustainable farming practices.
Consumption shifts toward green and blue ammonia illustrate the market's evolving landscape. Producers face pricing volatility and margin pressures, which affect operational strategies. Strategic opportunities emerge for stakeholders investing in advanced production technologies and supply chain resilience. The Fertilizer Production segment exemplifies the market's response to consumer demand and regulatory pressures, positioning it for significant growth in the coming years.
Demand for industrial chemicals remains strong within the Low-Carbon Ammonia market, driven by the increasing need for sustainable chemical production processes. This segment is estimated to reach USD 445.2 million by 2033, at a CAGR of 17.5% during the forecast period. Transitioning towards low-carbon solutions aligns with regulatory compliance standards and the global shift towards reduced carbon footprints, driving investment in cleaner technologies.
Competitive pressures within the industrial sector intensify the focus on innovative applications of low-carbon ammonia. The evolution of downstream applications, including its use in chemicals including plastics and solvents, creates significant opportunities for market participants. Technological maturation in production pathways, particularly in green ammonia processes, enhances production efficiency while reducing environmental impact.
Adoption of low-carbon ammonia in various industrial applications continues to gain traction, driven by consumers and businesses prioritizing sustainability. Regulatory frameworks increasingly favor low-carbon solutions, motivating companies to integrate these alternatives into their existing supply chains and production methodologies. This trend creates a resilient supply chain that capitalizes on cleaner production practices while addressing cost structures and pricing volatility.
Strategic opportunity windows emerge because companies explore partnerships and collaborations to streamline resource acquisition and enhance manufacturing capabilities. Investment in research and development of next-generation ammonia production techniques further differentiate players in the Low-Carbon Ammonia market. Overall, the industrial chemicals segment's evolution reflects broader trends toward sustainability in chemical manufacturing.
Interest in low-carbon ammonia because a fuel source in power generation continues to grow owing to its potential to significantly reduce greenhouse gas emissions. This trend aligns with global initiatives aimed at transitioning toward cleaner energy sources, driving a shift in energy policies and investment strategies. Governments and energy companies increasingly prioritize compliance with environmental regulations, driving demand for cleaner fuels including low-carbon ammonia.
Power Generation segment is expected to reach USD 394.7 million by 2033. This growth reflects advancements in technology that enhance the efficiency and viability of ammonia because a fuel alternative. Innovations in ammonia combustion processes and fuel cell technologies play a crucial role in expanding the applications of low-carbon ammonia in this domain.
Strategic investment in infrastructure supporting ammonia production and distribution further drives market expansion. The establishment of ammonia-fueled power plants and the integration of ammonia with existing energy systems contribute to a more resilient and sustainable energy framework. These developments align with broader consumption shifts toward cleaner energy solutions, ensuring that the low-carbon ammonia market continues to attract attention from stakeholders in the power generation sector.
Significant growth in the Hydrogen Carrier segment aligns with the increasing demand for effective hydrogen transport solutions, particularly in the context of energy transition efforts. This segment is projected to grow at a CAGR of 29.1% during the forecast period. Adoption derives from a variety of factors, including the urgent need for decarbonization across industries and advancements in hydrogen infrastructure. Technological maturation facilitates the enhanced feasibility of ammonia because a hydrogen carrier, offering advantages including higher energy density and easier handling compared to other storage methods.
The need for hydrogen carriers arises from the shift towards renewable energy applications, where hydrogen serves because a critical energy vector. Industries focused on sustainable energy solutions increasingly recognize the potential of low-carbon ammonia in supporting hydrogen delivery and storage systems. This trend reflects broader consumption shifts towards cleaner energy sources, with the Low-Carbon Ammonia market positioned to capitalize on these changes.
Regulatory compliance standards further drive interest in hydrogen carriers, because governments push for lower carbon emissions. Policies that favor the adoption of low-carbon technologies enhance market dynamics, promoting investments in hydrogen infrastructure. Capital investment outlooks remain optimistic, supported by strategic opportunities in the development of ammonia-based solutions for hydrogen transportation. With a focus on overcoming substitution risks, the Hydrogen Carrier segment reinforces its role within the broader low-carbon ammonia ecosystem.
Transitioning to low-carbon alternatives remains a critical focus for the maritime industry. The adoption of low-carbon ammonia because a marine fuel reflects the sector's commitment to reducing greenhouse gas emissions. This transition aligns with global regulatory frameworks aimed at minimizing the carbon footprint of shipping activities.
Stringent regulations implemented by international maritime organizations drive significant interest in low-carbon ammonia in bunkering operations. These regulations encourage shipowners and operators to explore cleaner fuel options, supporting the growth of the low-carbon ammonia market within marine applications. Technological advancements in ammonia handling and storage systems enhance the feasibility of its use in marine fuel applications.
Investment in infrastructure for bunkering facilities represents a crucial factor shaping the segment's expansion. Strategic partnerships among fuel suppliers, shipping companies, and port authorities facilitate the development of the necessary infrastructure to support the use of ammonia because a fuel source. This collaborative approach generates a more resilient supply chain while contributing to the overall growth of the low-carbon ammonia market.
Emerging challenges related to pricing volatility and margin pressures impact the segment's expansion. Potential fluctuations in raw material costs for ammonia production require careful management to maintain competitive pricing in the marine fuel market. The pursuit of technological upgrades and next-generation solutions enhances operational efficiency, supporting long-term profitability.
Investors increasingly recognize the opportunity presented by low-carbon ammonia in the marine fuel sector. Capital investment in the development of ammonia-powered vessels and related technologies highlights the segment's potential for growth. Continued advancements in ammonia synthesis and distribution technology will further strengthen its role because a key player in the evolving landscape of marine fuel applications.
Significant interest in heavy-duty transportation encourages the integration of low-carbon ammonia because a viable fuel alternative. The push for decarbonization across the transportation sector drives investments in technologies that support ammonia's role because a hydrogen carrier and energy source. This segment benefits from advancements in infrastructure and vehicle modifications, aligning with stringent regulatory compliance standards aimed at reducing emissions from heavy-duty vehicles.
Manufacturers continue to innovate, and the evolution of ammonia-powered engines and fuel systems facilitates adoption within logistics and freight industries. Increased emphasis on sustainability among end-users reinforces the necessity for cleaner fuel options, promoting a market that embraces low-carbon solutions. The potential for ammonia to replace conventional fossil fuels in heavy-duty transportation presents a strategic opportunity for stakeholders aiming to align with environmental policies and consumer preferences.
Cost structures associated with transitioning to low-carbon ammonia technology reflect the investment in next-generation upgrades and equipment. Pricing volatility in traditional fuel markets enhances the appeal of ammonia because a stable alternative. Supply chain resilience becomes essential because stakeholders navigate raw material sourcing and logistics vulnerabilities in the pursuit of sustainable practices. Overall, the heavy-duty transportation segment within the low-carbon ammonia market represents a vital avenue for growth driven by evolving demand dynamics and regulatory landscapes.
Growing adoption of low-carbon ammonia for energy storage and stationary fuel applications reflects increasing global focus on reducing carbon emissions. This segment aligns with the broader transition towards cleaner energy solutions, driving interest from industries committed to sustainability. Organizations explore the use of low-carbon ammonia because a versatile energy carrier, capable of facilitating energy storage and improving efficiency in power generation.
Technological advancements in ammonia synthesis and storage serve because key catalysts for segment expansion. Innovations in production methods make low-carbon ammonia more accessible and economically viable for various applications. Established companies and new entrants invest in research and development to enhance the efficiency and reliability of ammonia-based technologies.
End-use dynamics show a significant shift towards integrating low-carbon ammonia within energy systems. Increased focus on regulatory compliance and sustainability certifications influences purchasing decisions, encouraging companies to invest in low-carbon solutions for energy storage and stationary fuel applications. These shifts lead to a more resilient supply chain, with players adapting to evolving market demands.
Strategic opportunity windows emerge because industries recognize the potential of low-carbon ammonia in decarbonizing their operations. Organizations pursue additional capital investments to support the development of ammonia-based technologies. This trend indicates a strong outlook for the Low-Carbon Ammonia market, particularly within the energy storage and stationary fuel applications sub-segment.
Valued at USD 494.8 million in 2026, the Captive / Integrated Consumption segment is projected to reach USD 1,546.6 million by 2033, reflecting a CAGR of 17.7% during the forecast period. This growth stems from rising demand for low-carbon solutions within integrated production facilities, which enhance operational efficiency and reduce emissions. Industries focusing on sustainability increasingly adopt low-carbon ammonia in their processes, driving market expansion.
Technological advancements in ammonia production contribute significantly to this segment's growth. Improvements in production pathways, particularly in green ammonia synthesis, enable companies to achieve higher efficiency and lower costs. The focus on reducing carbon footprints within manufacturing and agricultural sectors aligns with broader trends in the low-carbon ammonia market.
Regulatory compliance influences the Captive / Integrated Consumption segment. Stringent environmental regulations and incentives for carbon reduction prompt industries to invest in low-carbon technologies. Compliance with these standards mitigates operational risks and enhances competitive positioning in a market prioritizing sustainability.
While companies transition toward integrated consumption models, the resilience of supply chains becomes vital. Effective raw material sourcing and distribution strategies ensure consistent availability and price stability. This adaptability enables firms to respond swiftly to fluctuations in demand while maintaining cost efficiency.
With a significant increase in capital investments directed toward next-generation production technologies, the segment stands poised for strong growth. Strategic opportunity windows arise from partnerships and collaborations focused on developing innovative low-carbon ammonia solutions, further emphasizing its importance within the broader low-carbon ammonia market.
Growing recognition of low-carbon solutions in various sectors drives demand for the Domestic Merchant Sales segment within the Low-Carbon Ammonia market. The estimated value of this segment is projected to reach USD 654.7 million by 2033, at a CAGR of 20.1% during the forecast period. This segment expands due to increasing investments in sustainable agricultural practices and the overall shift toward decarbonization in industrial processes.
Strong adoption of low-carbon ammonia for fertilizer production significantly influences growth in domestic merchant sales. Fertilizer producers seek reliable suppliers of low-carbon ammonia to meet regulatory standards and consumer expectations, fueling demand within this segment. The market benefits from emerging technologies that enhance production processes and reduce costs, making low-carbon ammonia more accessible to a broader audience.
Pricing volatility and margin pressures remain critical considerations for stakeholders in this segment. Fluctuations in raw material costs impact pricing strategies, necessitating agility in operations and supply chain management. End-use dynamics shift toward increased utilization of low-carbon ammonia in various applications, including industrial chemicals and energy storage, further supporting the expansion of domestic merchant sales.
Investment in infrastructure and strategic partnerships among key players enhances market resilience. Companies focus on expanding production capacities and developing innovative solutions to address changing market demands. The Domestic Merchant Sales segment plays a significant role in the overall growth trajectory of the Low-Carbon Ammonia market.
Growth in the International Merchant Trade / Export segment reflects rising global demand for low-carbon ammonia solutions. This trend arises from increased awareness of sustainability and the need for cleaner alternatives across various industries, particularly in agriculture and energy. Stricter environmental regulations implemented by various countries strengthen the demand for low-carbon ammonia products.
Valued at USD 996.9 million by 2033, this segment presents significant potential for expansion. The anticipated growth aligns with advancements in production technologies and the maturation of supply chains, allowing for efficient international distribution. Companies focusing on this sector are likely to benefit from favorable market conditions that support lower emissions and sustainable practices.
Strategic partnerships among key players in the low-carbon ammonia market enhance the segment's resilience and operational efficiency. The evolving environment promotes competitive pricing and innovation, resulting in improved margins. Global shifts towards sustainable and environmentally friendly practices accelerate the positioning of the International Merchant Trade / Export segment for significant growth.
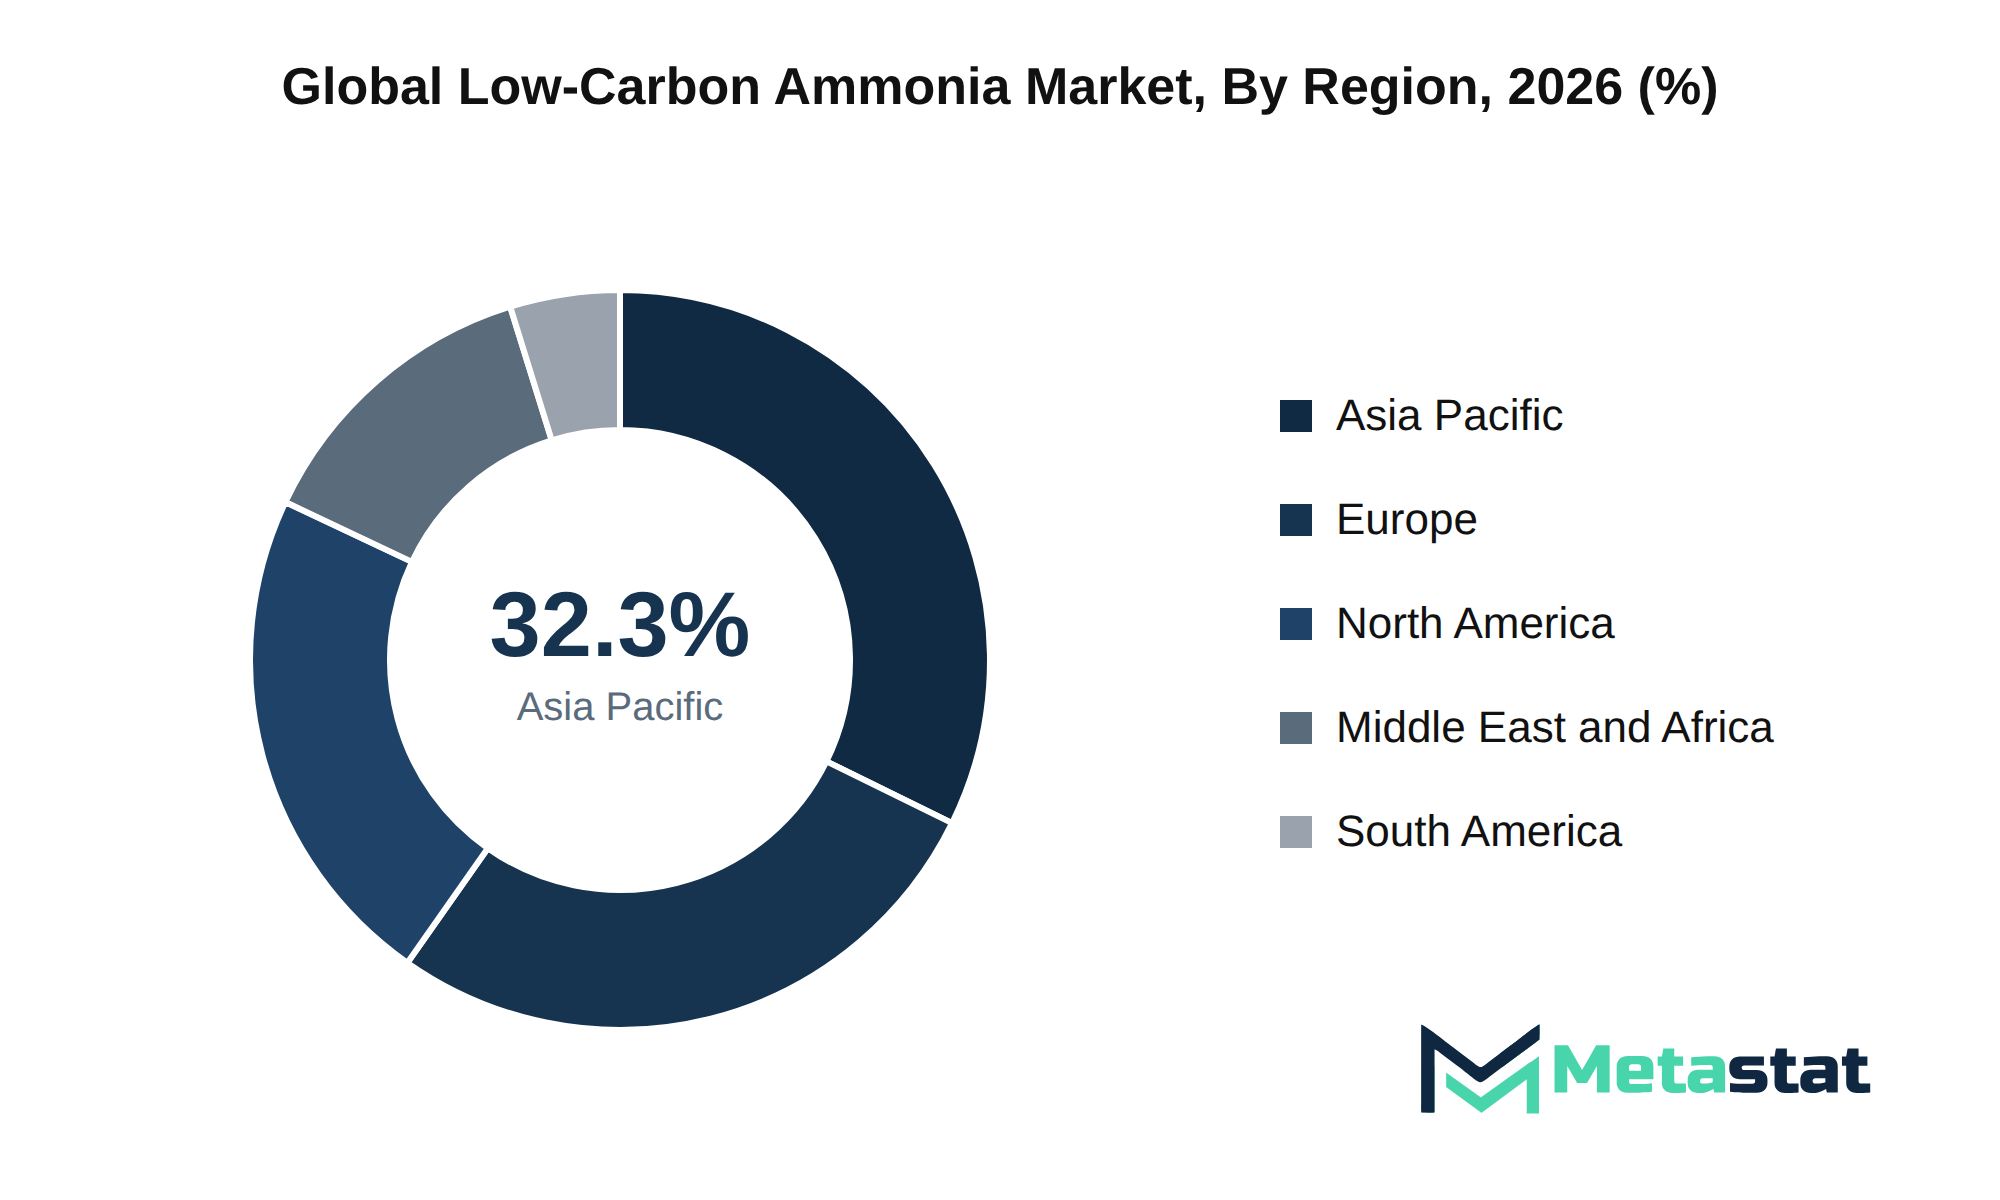
Based on geography, the Global Low-Carbon Ammonia market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America represents a significant market for low-carbon ammonia, driven by increasing investments in sustainable energy solutions and agricultural practices. The region's focus on reducing carbon emissions aligns with global trends toward decarbonization, propelling the market's growth. A notable share of 22.3% of the global market in 2025 emphasizes the importance of North America in this sector.
Key drivers include the presence of major players, including Fertiberia S.A., Yara International ASA, and CF Industries Holdings, Inc., which contribute to competitive dynamics. Infrastructure modernization initiatives across the United States, Canada, and Mexico enhance local production capabilities and support the adoption of low-carbon ammonia solutions. The Fertilizer Production application segment, valued at USD 450.2 million in 2026, indicates strong potential for expansion, with an increase to USD 1,271.6 million by 2033.
Regional characteristics, including resource availability and energy grid resilience, support the growth of the low-carbon ammonia market. Domestic market participants leverage localized procurement dynamics and adapt to cultural nuances in B2B buying behaviors. The market reflects the integration of advanced technologies in production pathways, including green and blue ammonia, creating a competitive environment that responds to evolving consumer demands.
The North America low-carbon ammonia market is set to expand at a CAGR of 21.2% during the forecast period, reaching a market size (TAM) of USD 677.4 million by the end of 2033. Emerging market front-runners, including Woodside Energy Group Ltd and SABIC Agri-Nutrients Company, highlight the region's potential for innovation and capacity development. The drive toward sustainability and compliance with local regulations will continue to shape market dynamics, providing a strong foundation for future growth within the low-carbon ammonia market.
The Low-Carbon Ammonia market in Europe demonstrates robust potential, driven by a combination of environmental policies and industrial demands. European countries, particularly Germany, France, the UK, Italy, Spain, and Russia, are prioritizing the transition to low-carbon solutions to align with stringent regulatory frameworks focused on reducing greenhouse gas emissions. This emphasis on sustainability creates a favorable environment for the growth of low-carbon ammonia applications, particularly in fertilizer production and industrial chemicals.
Technological advancements in production pathways, especially in green ammonia, contribute significantly to market expansion. Investments in infrastructure modernization and localized manufacturing enhance operational efficiencies and reduce dependency on traditional ammonia sources. Companies in the region are reevaluating their supply chain strategies, favoring nearshoring initiatives to capitalize on regional resources and improve responsiveness to market demands.
The presence of domestic market leaders strengthens competition within the Low-Carbon Ammonia market. Key players including Fertiberia S.A. and Yara International ASA leverage their established networks and expertise to consolidate their positions. This consolidation trend enables vendors to optimize procurement strategies and enhance their offerings, ultimately driving the overall growth of the market in Europe.
Increasing collaboration between public and private sectors encourages innovation and development of low-carbon technologies. These partnerships have the potential to advance local compliance mandates and trade policy shifts, streamlining the adoption of low-carbon ammonia solutions. The collective efforts in these areas position Europe because a frontrunner in the global low-carbon ammonia market.
The Asia-Pacific region accounts for 32.3% of the global Low-Carbon Ammonia market, projected in 2025. Countries including China, Japan, India, South Korea, and Australia exhibit strong growth potential, driven by a combination of increasing environmental regulations and government incentives promoting low-carbon technologies. The emphasis on sustainable agricultural practices in these countries contributes to the rising adoption of low-carbon ammonia in fertilizer production.
Infrastructure modernization in Asia-Pacific continues to support market expansion. Investments in renewable energy projects, along with enhanced energy grid resilience, promote the integration of low-carbon ammonia into various sectors, including industrial chemicals and power generation. Localized manufacturing densities facilitate supply chain regionalization, allowing for more efficient production and distribution of low-carbon ammonia products.
Emerging market front-runners like India and Southeast Asia exhibit notable demand for low-carbon solutions, with a growing focus on energy transition and sustainable industrial practices. The competitive landscape in this region features several domestic leaders, driving innovation and contributing to vendor consolidation trends. Cultural nuances and regional B2B buying behaviors influence procurement dynamics, encouraging local businesses to adopt environmentally friendly practices.
The Asia-Pacific Low-Carbon Ammonia market is anticipated to experience substantial growth through 2033, with evolving regulatory frameworks and local compliance mandates playing crucial roles in shaping market dynamics. Foreign direct investment flows into the region enhance opportunities for geographic expansion, enabling companies to capitalize on underpenetrated territories and high-value replacement cycles within the market.
South America represents a smaller segment within the Low-Carbon Ammonia market, accounting for 4.8% of the global market share in 2025. Brazil and Argentina are the primary countries contributing to this market, with specific opportunities arising from the agricultural sector's increasing shift towards sustainable practices. The Fertilizer Production application segment is expected to experience notable growth, influenced by regional agricultural demands and the need for enhanced crop yields.
Emerging market front-runners in South America, particularly Brazil, benefit from a growing emphasis on environmentally friendly production methods. Supportive government policies aimed at promoting low-carbon technologies contribute to market expansion. Ongoing investments in infrastructure modernization enhance the capacity for low-carbon ammonia production and distribution.
Localized procurement dynamics play a significant role in driving demand within the market. The cultural nuances of regional B2B buying behaviors shape the purchasing patterns for low-carbon ammonia, with businesses increasingly prioritizing sustainable sourcing. This trend aligns with global efforts to reduce carbon footprints and transition towards greener alternatives.
Overall, the Low-Carbon Ammonia market in South America is poised for incremental growth, driven by a combination of regional resource availability, evolving agricultural practices, and a commitment to sustainable development. Continued investment and strategic entry barriers will further influence the market’s trajectory in the coming years.
The Low-Carbon Ammonia market in the Middle East and Africa features considerable potential, driven by regional resource availability and a focus on sustainable energy solutions. Saudi Arabia and the UAE stand out because key players leverage their abundant natural resources to enhance production capacity for low-carbon ammonia. Investment in modern infrastructure aligns with growing global demand for cleaner alternatives in various industries.
The share of the market in this region is projected at 13.2% in 2025, reflecting a commitment to expanding industrial capabilities. In South Africa, efforts are underway to increase the adoption of low-carbon solutions, particularly in fertilizer production and energy generation. This trend indicates a shift towards more environmentally friendly practices among local industries.
Emerging market front-runners demonstrate a proactive approach to capturing opportunities within the Low-Carbon Ammonia market. Localized procurement dynamics and strategic entry barriers enhance the competitive landscape, allowing domestic market leaders to consolidate their positions. Geopolitical factors and regulatory frameworks shape trade relationships and impact market growth.
Through the integration of localized manufacturing densities and foreign direct investment flows, the region is expected to experience growth vectors. Continued focus on energy grid resiliency supports the ongoing transition towards low-carbon solutions in the Middle East and Africa.
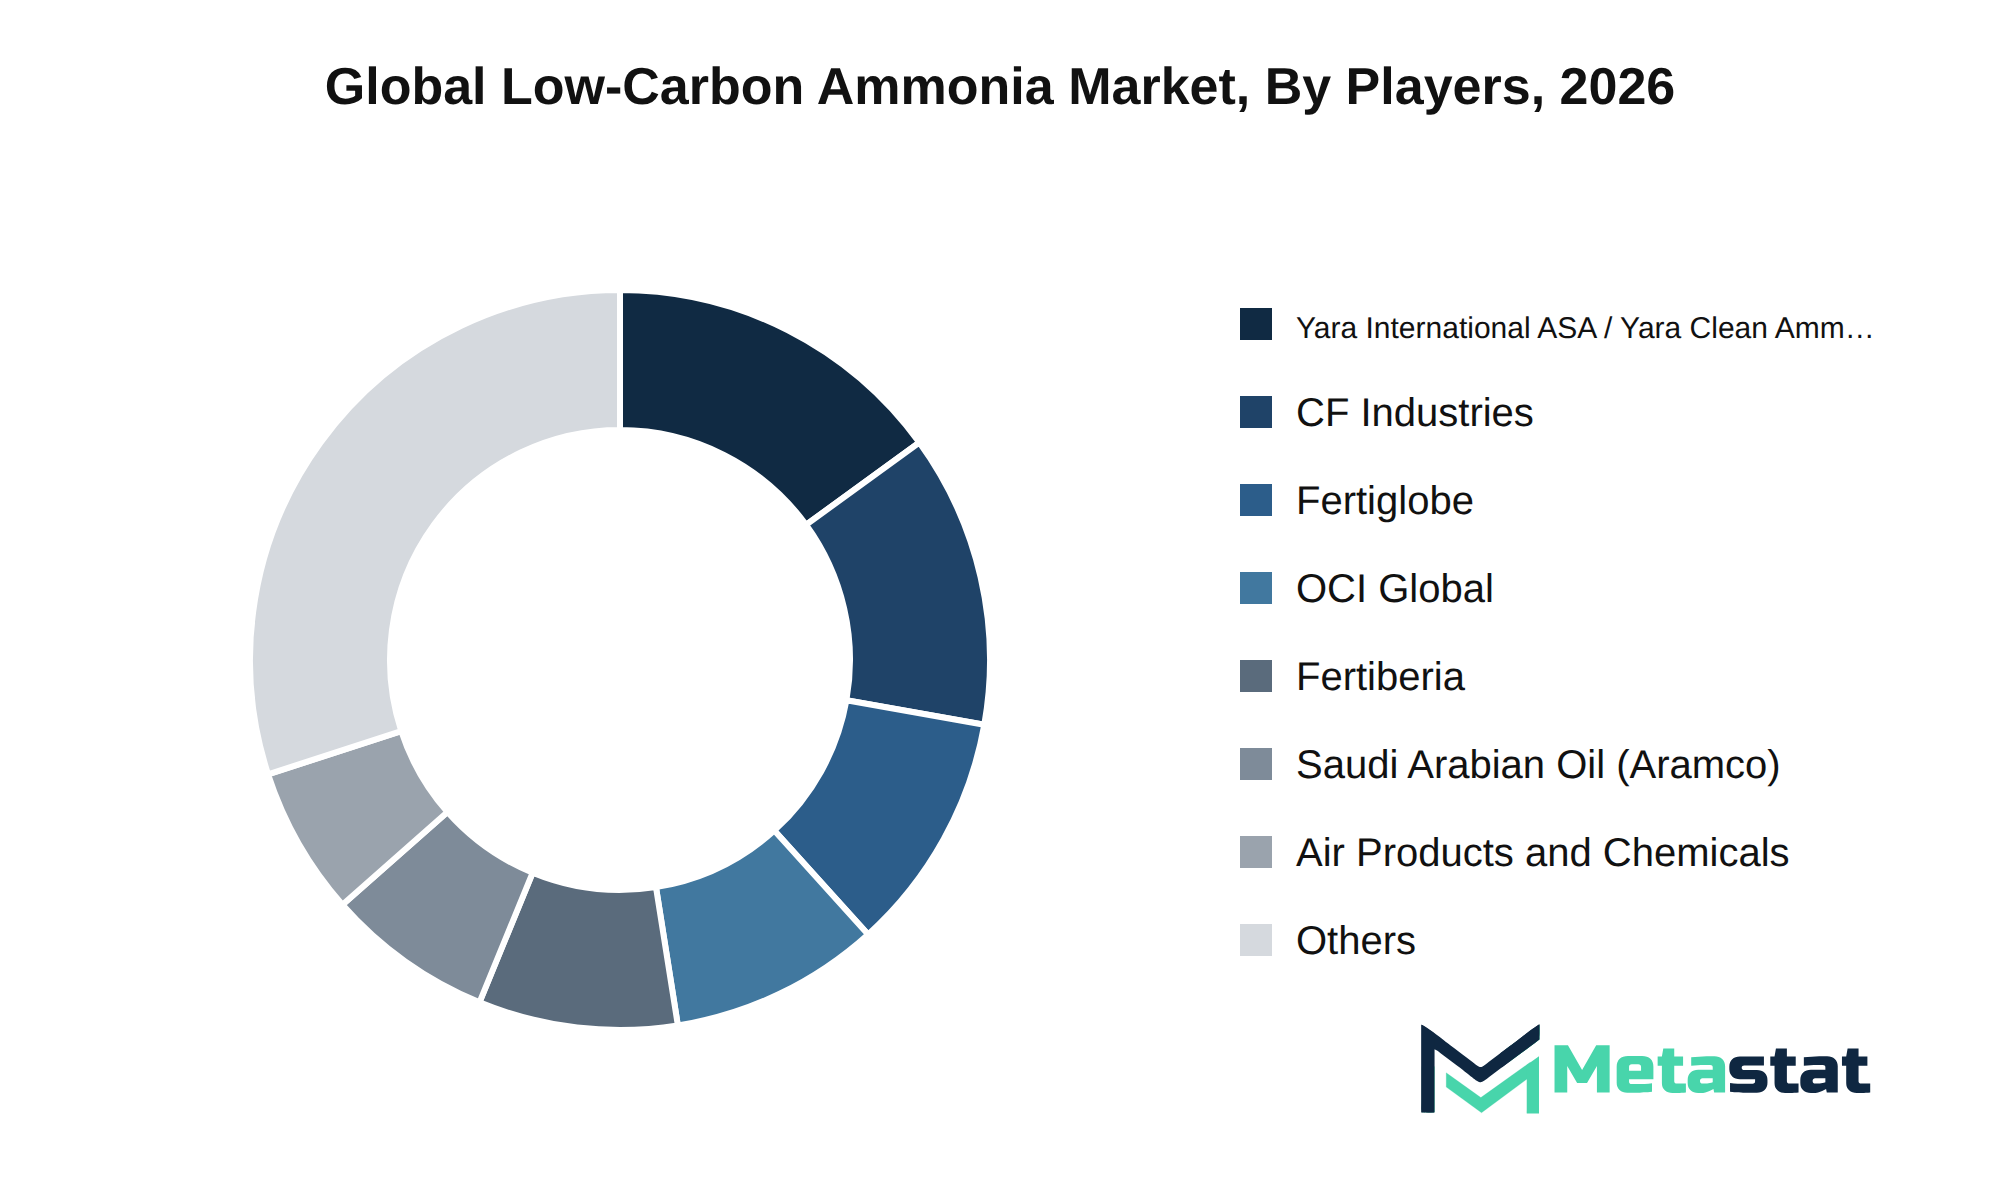
The Low-Carbon Ammonia market experiences significant competitive dynamics shaped by various strategic behaviors among key players. Mergers and acquisitions remain prevalent, driven by companies seeking to enhance their market positions and consolidate resources. Strategic alliances and joint ventures are essential for leveraging complementary technologies and expanding production capabilities, allowing firms to tap into new customer segments and regional markets.
Companies including Fertiberia S.A., Yara International ASA / Yara Clean Ammonia, and CF Industries Holdings, Inc. adopt competitive pricing architectures to attract customers in the fertilizer production application. Product differentiation through proprietary technologies and R&D pipelines is critical for maintaining a competitive edge. Firms including OCI Global and Fertiglobe plc focus on value chain integration to enhance procurement leverage and supply chain dominance.
Barriers to entry exist in the market, particularly regarding technological investments and regulatory compliance, which protect established players. New entrants face challenges in securing market share due to strong brand equity and customer retention strategies employed by established firms. The future competitive outlook presents opportunities for growth through innovation and sustainable practices, positioning the Low-Carbon Ammonia market for expansion.
Market size is forecast to rise from USD 686.7 million in 2025 to over USD 3,198.2 million by 2033. The base case projects growth at a compound annual growth rate (CAGR) of 21.2%. In a bullish scenario, heightened governmental support and advancements in technology could accelerate adoption, pushing growth beyond the current projections. Conversely, a bearish outlook arises from unexpected regulatory changes or geopolitical tensions that disrupt supply chains, potentially slowing growth.
Factors influencing the Low-Carbon Ammonia market include macroeconomic trends and evolving demand from core industries. The transition towards cleaner energy sources drives structural shifts in consumption patterns. Next-generation technology integration serves because a critical element, influencing research and development timelines and commercialization efforts in this sector.
Regulatory evolution shapes the market landscape. Compliance milestones and policy enforcement horizons will dictate the pace at which companies adapt. Geopolitical realignments and shifting trade corridors affect global supply chains, impacting operational efficiencies and cost structures across the industry.
Strategic capital allocation directives signal a focus on infrastructure commitments and capital expenditure investments. Emerging white-space opportunities present avenues for growth, particularly in sectors with unmet enterprise needs. High-growth pockets within the market encourage firms to develop defensibility roadmaps and identify future growth recommendations to secure competitive advantages.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Low-Carbon Ammonia market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 21.2% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Production Pathway, Application, Supply Model, and Region |
By Region | North America (By Production Pathway, Application, Supply Model, and Country)
|
Europe (By Production Pathway, Application, Supply Model, and Country)
| |
Asia Pacific (By Production Pathway, Application, Supply Model, and Country)
| |
South America (By Production Pathway, Application, Supply Model, and Country)
| |
Middle East and Africa (By Production Pathway, Application, Supply Model, and Country)
|
Find answers to common questions about this report
The Low-Carbon Ammonia market size was valued at USD 686.7 million in 2025, according to the Metastat Insights study.
The Low-Carbon Ammonia market is projected to grow at a CAGR of 21.2% during the forecast period from 2026 to 2033.
The North America Low-Carbon Ammonia market size is estimated to reach USD 677.4 million by 2033.
The Green Ammonia segment leads the Low-Carbon Ammonia market, with a projected value of USD 1,831.3 million by 2033, reflecting a compound annual growth rate of 23.9%. This growth outpaces other segments, establishing Green Ammonia because the dominant pathway in the market.
Increasing emission limits across multiple sectors drive the adoption of low-carbon ammonia because a cleaner alternative to traditional production methods. Industries, particularly agriculture, energy, and chemicals, prioritize sustainability initiatives, creating significant demand for low-carbon ammonia to reduce carbon footprints and align with environmental, social, and governance mandates.
Asia Pacific holds the dominant share of the Low-Carbon Ammonia market, accounting for 32.3% in 2025. This region's position reflects its significant contribution compared to North America, Europe, South America, and the Middle East and Africa.
High capital investment requirements and rising operating costs present significant restraints for the Low-Carbon Ammonia market. Smaller firms face challenges in competing with larger entities due to substantial financial barriers, while fluctuating raw material prices and labor expenses further compress profit margins, hindering investment in low-carbon technologies.
Increasing emission limits across multiple sectors drive the adoption of low-carbon ammonia because a cleaner alternative to traditional production methods. Industries including agriculture, energy, and chemicals face pressures to reduce carbon footprints, aligning with sustainability initiatives. Investment in innovative technologies enhances production efficiency and reduces environmental impact, further incentivizing the transition to low-carbon ammonia.
The Low-Carbon Ammonia market is estimated to reach a valuation of USD 3,198.2 million by 2033.
Key players operating in the Low-Carbon Ammonia market include Yara International ASA / Yara Clean Ammonia, CF Industries Holdings, Inc., OCI Global, Fertiglobe plc, Woodside Energy Group Ltd, and Saudi Arabian Oil Company (Aramco).
Choose Your License
Global Low-Carbon Ammonia Market
The analysts below cover Chemicals and Materials research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
INDUSTRY CONSULTANT - CHEMICALS & ADVANCED MATERIALS
Chemicals and Materials · Machinery & Equipment · Packaging
Amit Gadhekar Consultant for Chemicals and Materials at MetaStat Insight, directing sector-specific intelligence, research, and strategic consulting across global chemical and processing markets.
When planning edge sensor rollouts across refinery environments, generic IoT reports typically miss the harsh-environment certification bottlenecks. MetaStat Insight gave an objective evaluation of ATEX and Class 1 Division 2 hardware availability, along with realistic five-year maintenance cycle cost projections. The comparison of wireless mesh versus private cellular backhaul helped our team pressure-test network reliability models for remote processing facilities.
In the biological seed treatment space, registration timelines vary drastically between the European Union, Brazil, and North America. The MetaStat Insight research handled these cross-border regulatory barriers with genuine nuance, mapping commercialization pathways alongside historical field adoption rates. The segmentation between microbial strains and biochemical active ingredients was particularly well structured.
Our team was tracking whether regional recycling infrastructure could realistically absorb the growing volume of lithium iron phosphate batteries over the next decade. The report did a solid job separating announced hydrometallurgical plant capacity from active, permitted operational throughput. That distinction made the feedstock availability projections and regional recovery rate models far more credible than standard commercial overviews.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950