
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Recycled Textile Market Size, Share, By Material (Cotton, Polyester and Polyester Fiber, Wool, Nylon and Nylon Fiber, Others), By Textile Waste (Pre-consumer, Post-consumer, Production Overruns, Pullouts, Export Seconds, Others), By Process (Mechanical, Chemical), By End-use (Apparel, Home Furnishings, Industrial and Institutional, Others), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-2950
September, 2026
252 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $8,428 Million in 2025, projected to reach $13,515.9 Million by 2033 at a 6.2% CAGR.
Dominant Segment: The Cotton segment leads the market, driven by rising consumer preference for sustainable materials and projected to reach USD 6,482.6 million by 2033.
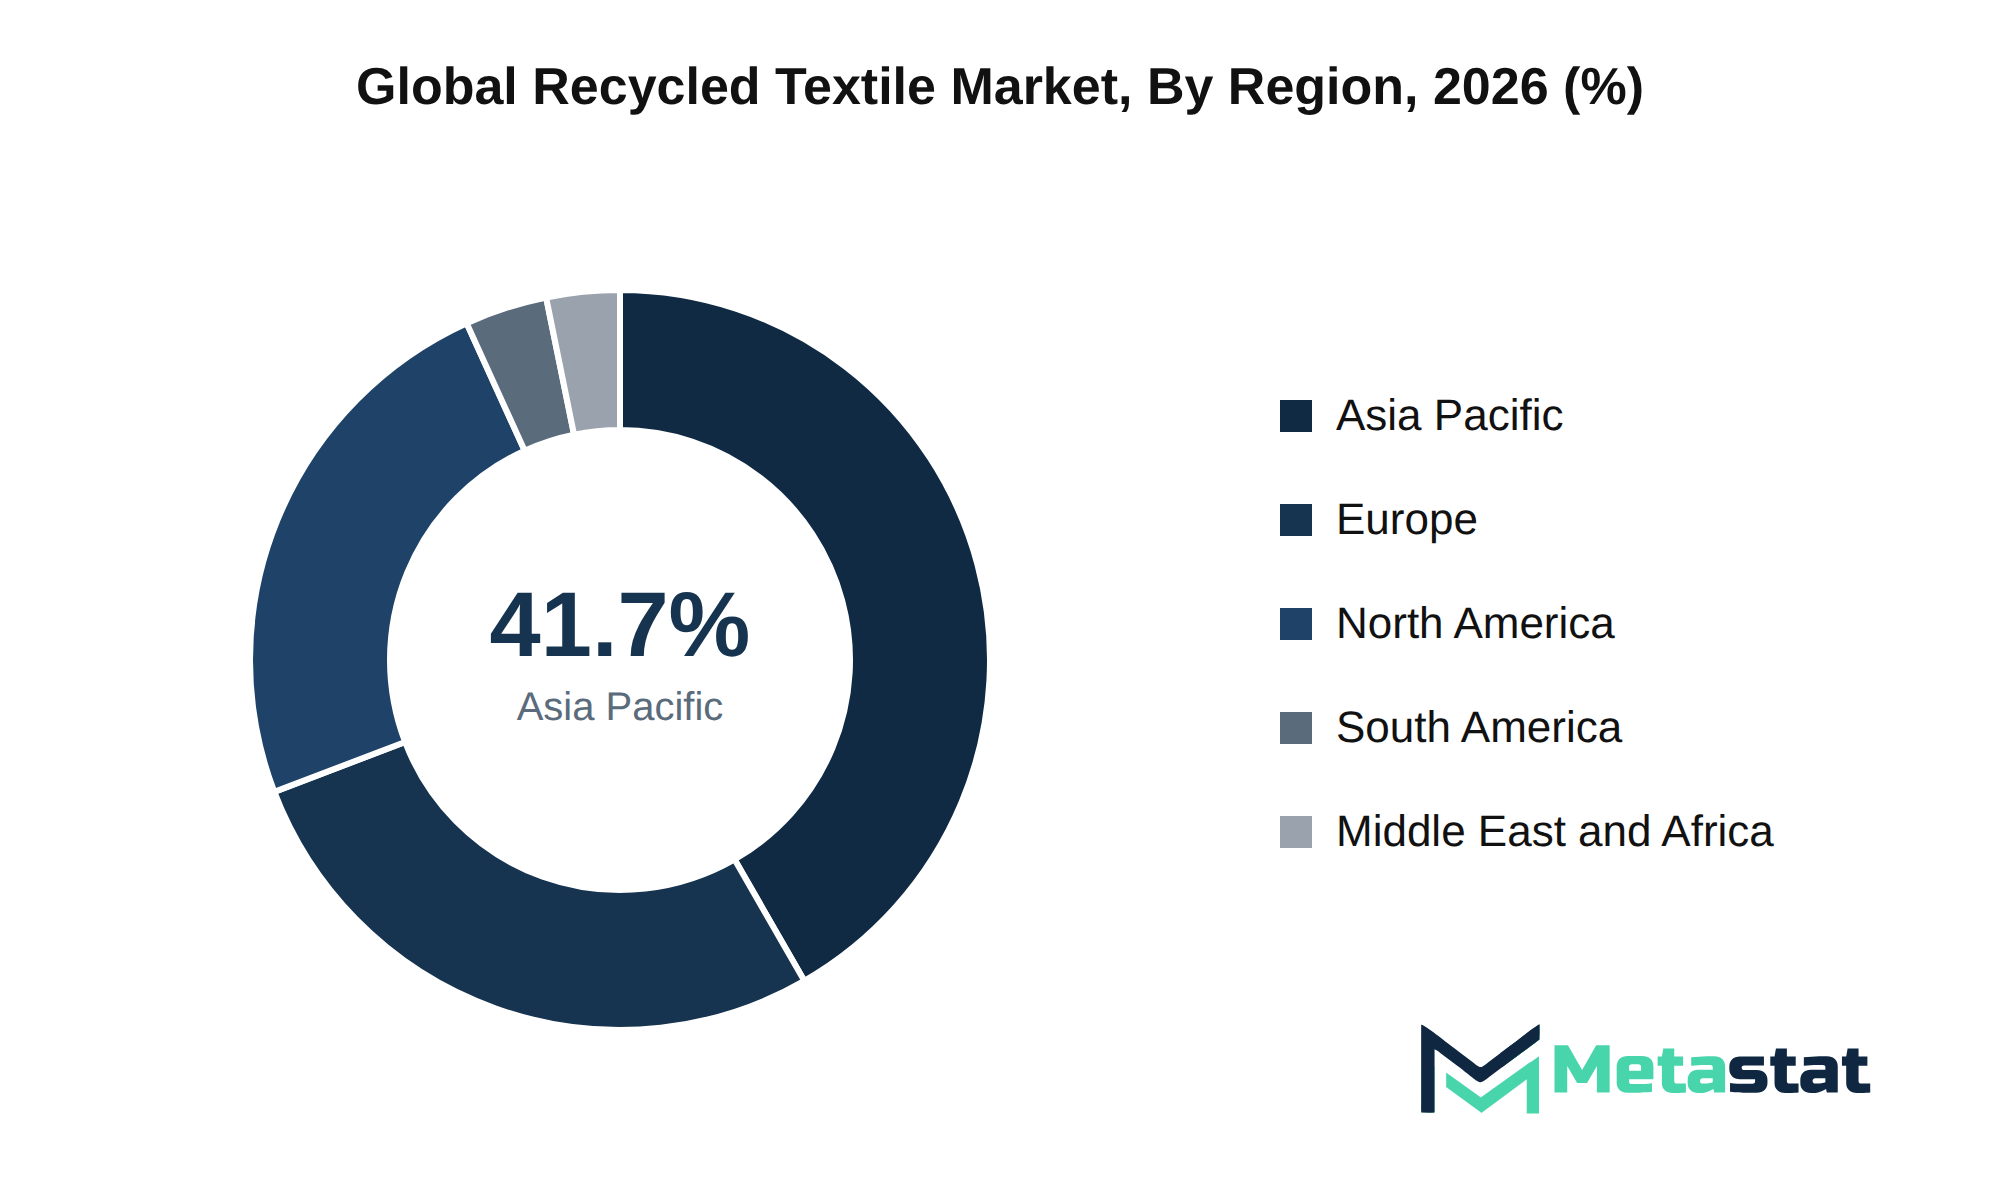
Geographic Lead: Asia-Pacific is the fastest-growing region, capturing a significant market share of 41.7%, fueled by increasing environmental consciousness and economic growth.
What's Inside: This report provides a comprehensive analysis of the competitive landscape, market segmentation by material, waste type, process, and end-use, along with forecasts through 2033.
Core Growth Catalysts: Key drivers include heightened consumer awareness of sustainability and regulatory pressures that encourage the adoption of recycled textiles across various industries.
The global Recycled Textile market was valued at USD 8,428 million in 2025 and is projected to reach USD 13,515.9 million by 2033, growing at a CAGR of 6.2% over the forecast period.
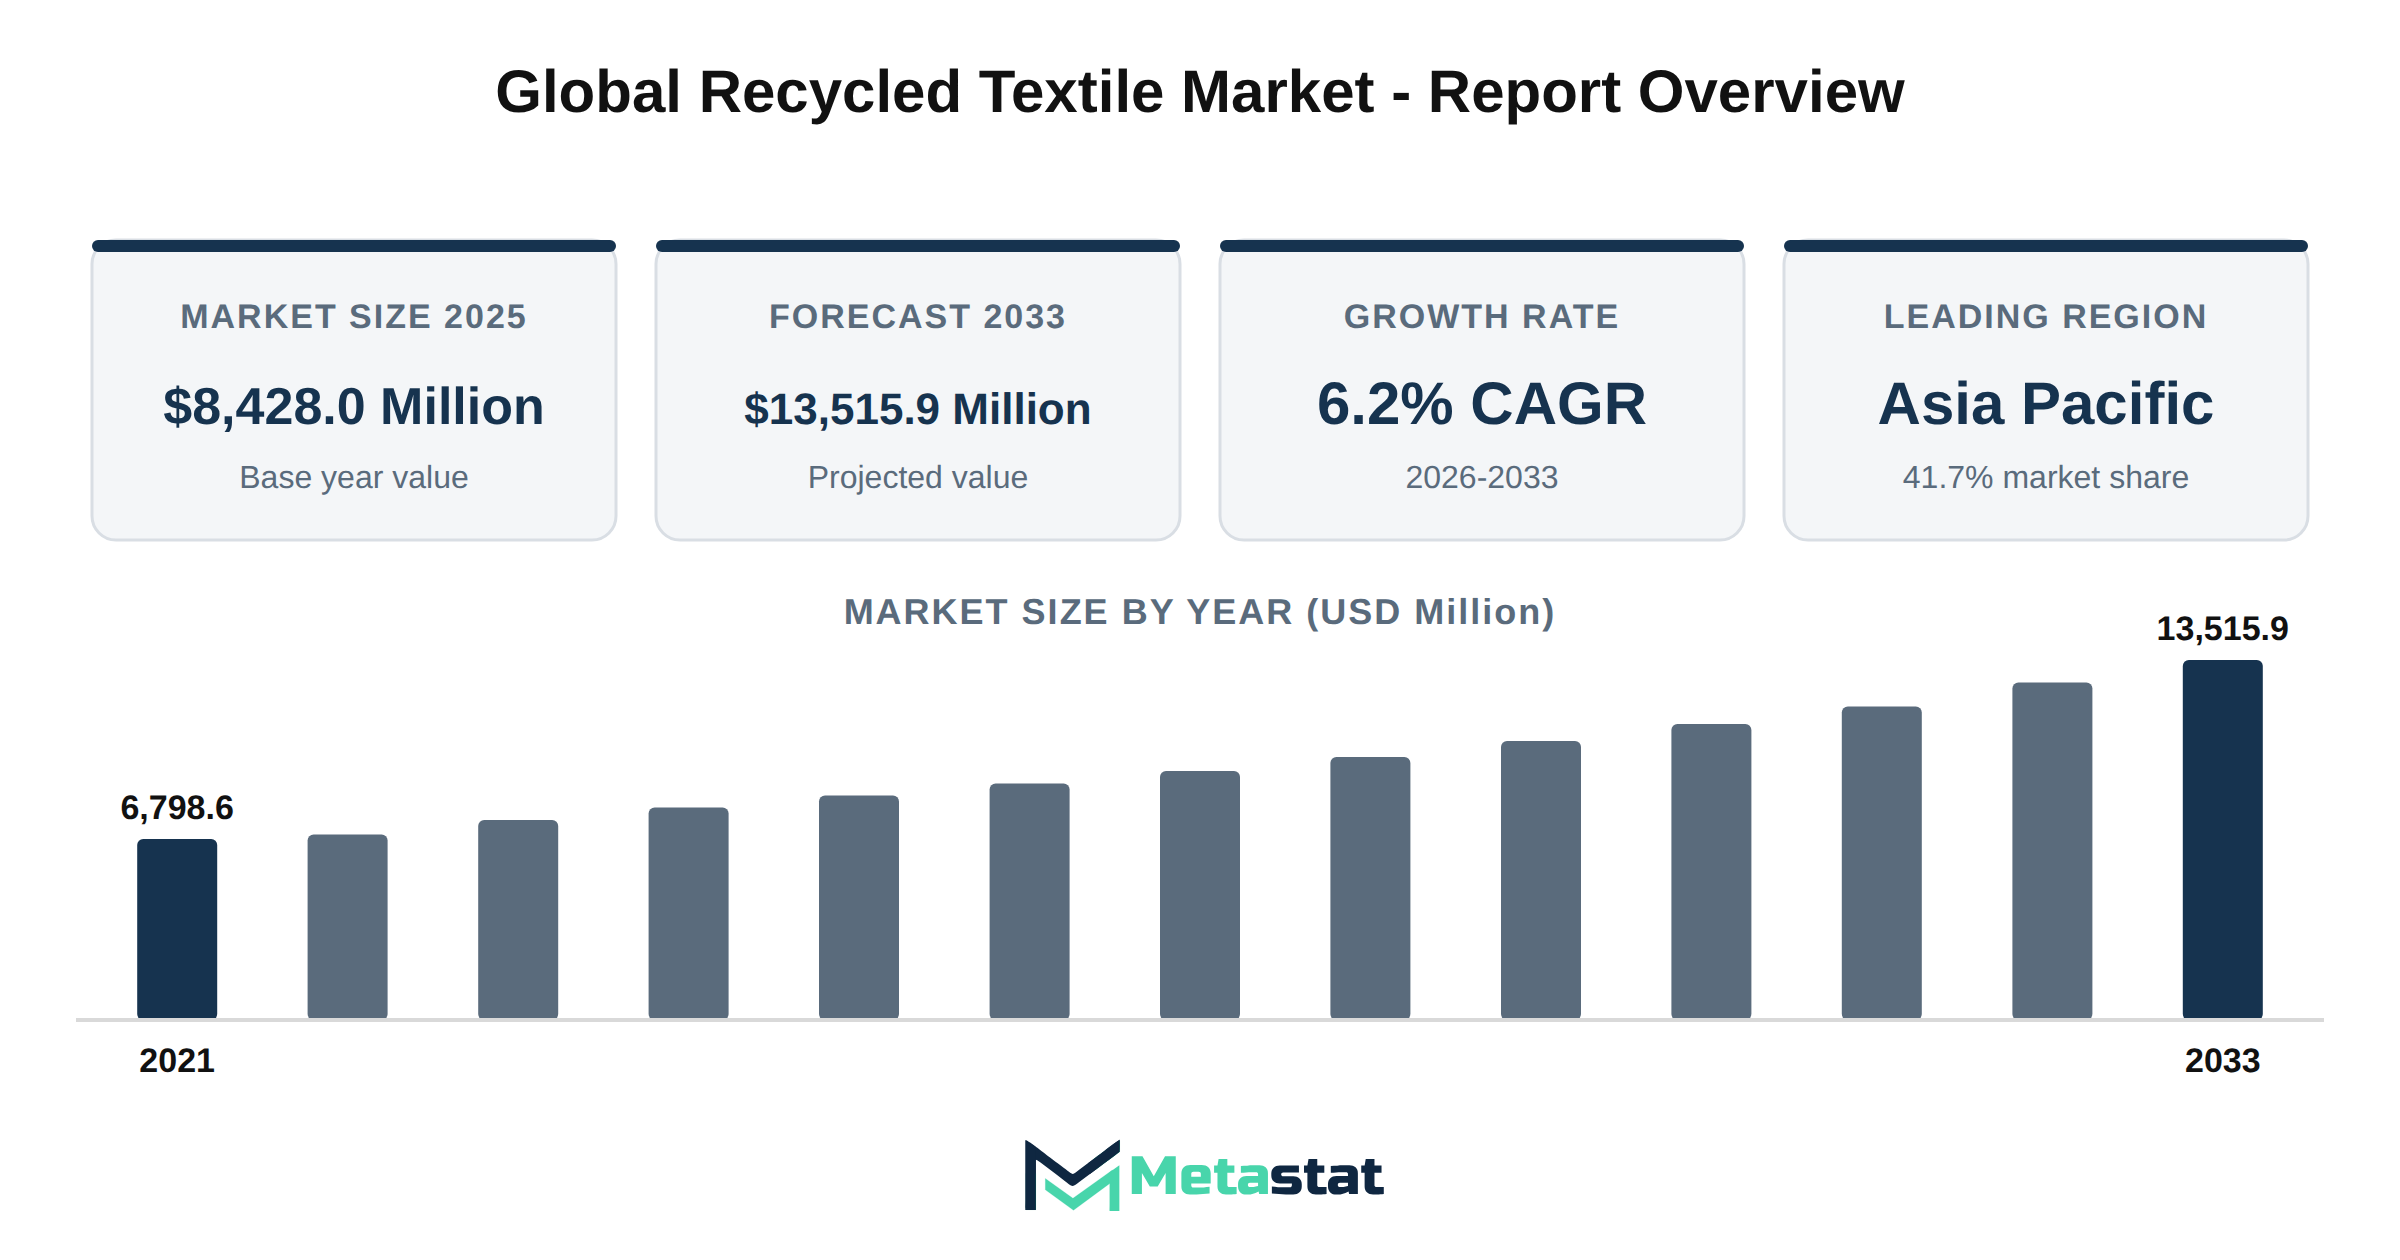
The global Recycled Textile market reached a value of USD 8,428 million in 2025 and is projected to grow significantly, reaching USD 13,515.9 million by 2033. This growth represents a compound annual growth rate (CAGR) of 6.2%. The trajectory of the market indicates a steady increase in demand for recycled textiles, driven by rising environmental awareness and regulatory pressures.
Core growth catalysts for accelerating recycled fiber adoption include the increasing need for sustainable materials in the fashion industry and the implementation of stringent regulations promoting circular economy practices. The European Union's extended producer responsibility initiatives exemplify efforts to enhance recycling rates and drive the transition towards a more circular economy on a global scale.
Technological advancements in mechanical versus chemical recycling processes contribute to the maturation of the market. Mechanical recycling remains prevalent due to its cost-effectiveness, while chemical recycling is gaining traction for its ability to separate blends and produce high-quality recycled fibers. This dual approach satisfies varying industry requirements and enhances the overall recycling process.
The dynamics of post-consumer versus pre-consumer feedstock supply play a critical role in shaping the market. Post-consumer feedstock, characterized by its availability and diversity, is essential for meeting the rising demand for recycled materials. Conversely, pre-consumer feedstock, stemming from production overruns, offers reliability in terms of quality and consistency.
Scaling the fiber-to-fiber recycling infrastructure presents opportunities for commercial offtake, particularly in the apparel sector. The fashion industry increasingly prioritizes recycled polyester and polyamide, with a notable emphasis on sustainability and performance. Automotive interiors and technical textiles emerge because high-volume outlets for recycled materials, further driving the market's expansion.
Innovations including AI-powered optical sorting and automated disassembly enhance the efficiency of recycling operations. These technologies improve the sorting process and enhance the quality of recycled fibers, supporting the overall growth of the market. Brand offtake agreements and corporate decarbonization commitments reinforce the shift towards recycled textiles, aligning with consumer demand for sustainable products.
Challenges in feedstock collection logistics and supply chain traceability necessitate strategic solutions. Addressing these challenges will facilitate the integration of recycled materials into production processes. Capital expenditure trends and venture investments in circular textile infrastructure indicate a commitment to developing sustainable solutions within the market.
Regional market expansion across North America, Europe, and Asia-Pacific manufacturing hubs enhances the competitive landscape. Strategic positioning and competitive benchmarking of leading recycled fiber producers play a critical role in capturing market share. Emerging circularity frameworks present high-growth opportunities through 2035, reflecting the evolving nature of the Recycled Textile market.
The Recycled Textile market value trajectory reflects significant growth potential, with expectations to reach USD 13,515.9 million by 2033. This growth results from increased awareness of sustainability and the rising demand for recycled materials across various industries.
Factors driving the adoption of recycled fibers include heightened consumer awareness regarding environmental impacts and corporate sustainability commitments. Industries including fashion and automotive increasingly pursue recycled options, enhancing market penetration.
The implementation of extended producer responsibility (EPR) regulations within the European Union promotes circularity in textiles. These mandates encourage manufacturers to incorporate recycled materials, thus establishing a sustainable lifecycle for textile products.
Technological advancements in both mechanical and chemical recycling methods significantly influence market dynamics. Mechanical recycling processes mature, while chemical recycling techniques enhance the ability to separate blends, improving the quality and diversity of recycled fibers.
Shifts in feedstock supply dynamics highlight a growing emphasis on both post-consumer and pre-consumer textile waste. Post-consumer waste offers substantial volumes for recycling, while pre-consumer waste presents opportunities for manufacturers seeking to optimize their sustainability efforts.
The establishment of robust fiber-to-fiber recycling infrastructure is essential for facilitating commercial offtake. Investments in recycling facilities and technologies enhance the market's capacity to meet growing demand from various sectors.
Fashion and performance apparel sectors exhibit strong demand for recycled polyester and polyamide materials. This trend reflects a broader commitment to sustainability and resource efficiency within the textile industry.
Automotive interiors and technical textiles represent significant outlets for high-volume recycled materials. The integration of recycled content in these applications supports the industry's shift toward more sustainable practices.
Innovations in AI-powered optical sorting and automated disassembly enhance the efficiency of recycling processes. These technologies streamline the separation of waste materials, increasing overall recycling rates and material recovery.
Brand offtake agreements contribute to the market’s growth by aligning corporate decarbonization commitments with sustainable sourcing strategies. These agreements ensure a steady demand for recycled textile products, reinforcing market stability.
Challenges related to feedstock collection logistics and supply chain traceability impact the efficiency of the recycling process. Addressing these challenges is vital for improving the reliability of recycled material supply chains.
Capital expenditure trends indicate increasing venture investments in circular textile infrastructure. These investments are critical for expanding recycling capabilities and driving innovation within the Recycled Textile market.
The Recycled Textile market experiences notable regional expansion, particularly in North America, Europe, and Asia-Pacific. Growth in these manufacturing hubs is supported by favorable policies and rising demand for sustainable textiles.
Strategic positioning among leading recycled fiber producers influences market competition. Competitive benchmarking highlights the strengths and weaknesses of various players, informing investment decisions and market strategies.
Emerging circularity frameworks present high-growth opportunities within the Recycled Textile market through 2035. Adoption of these frameworks aligns with global sustainability goals, driving innovation and investment in the sector.
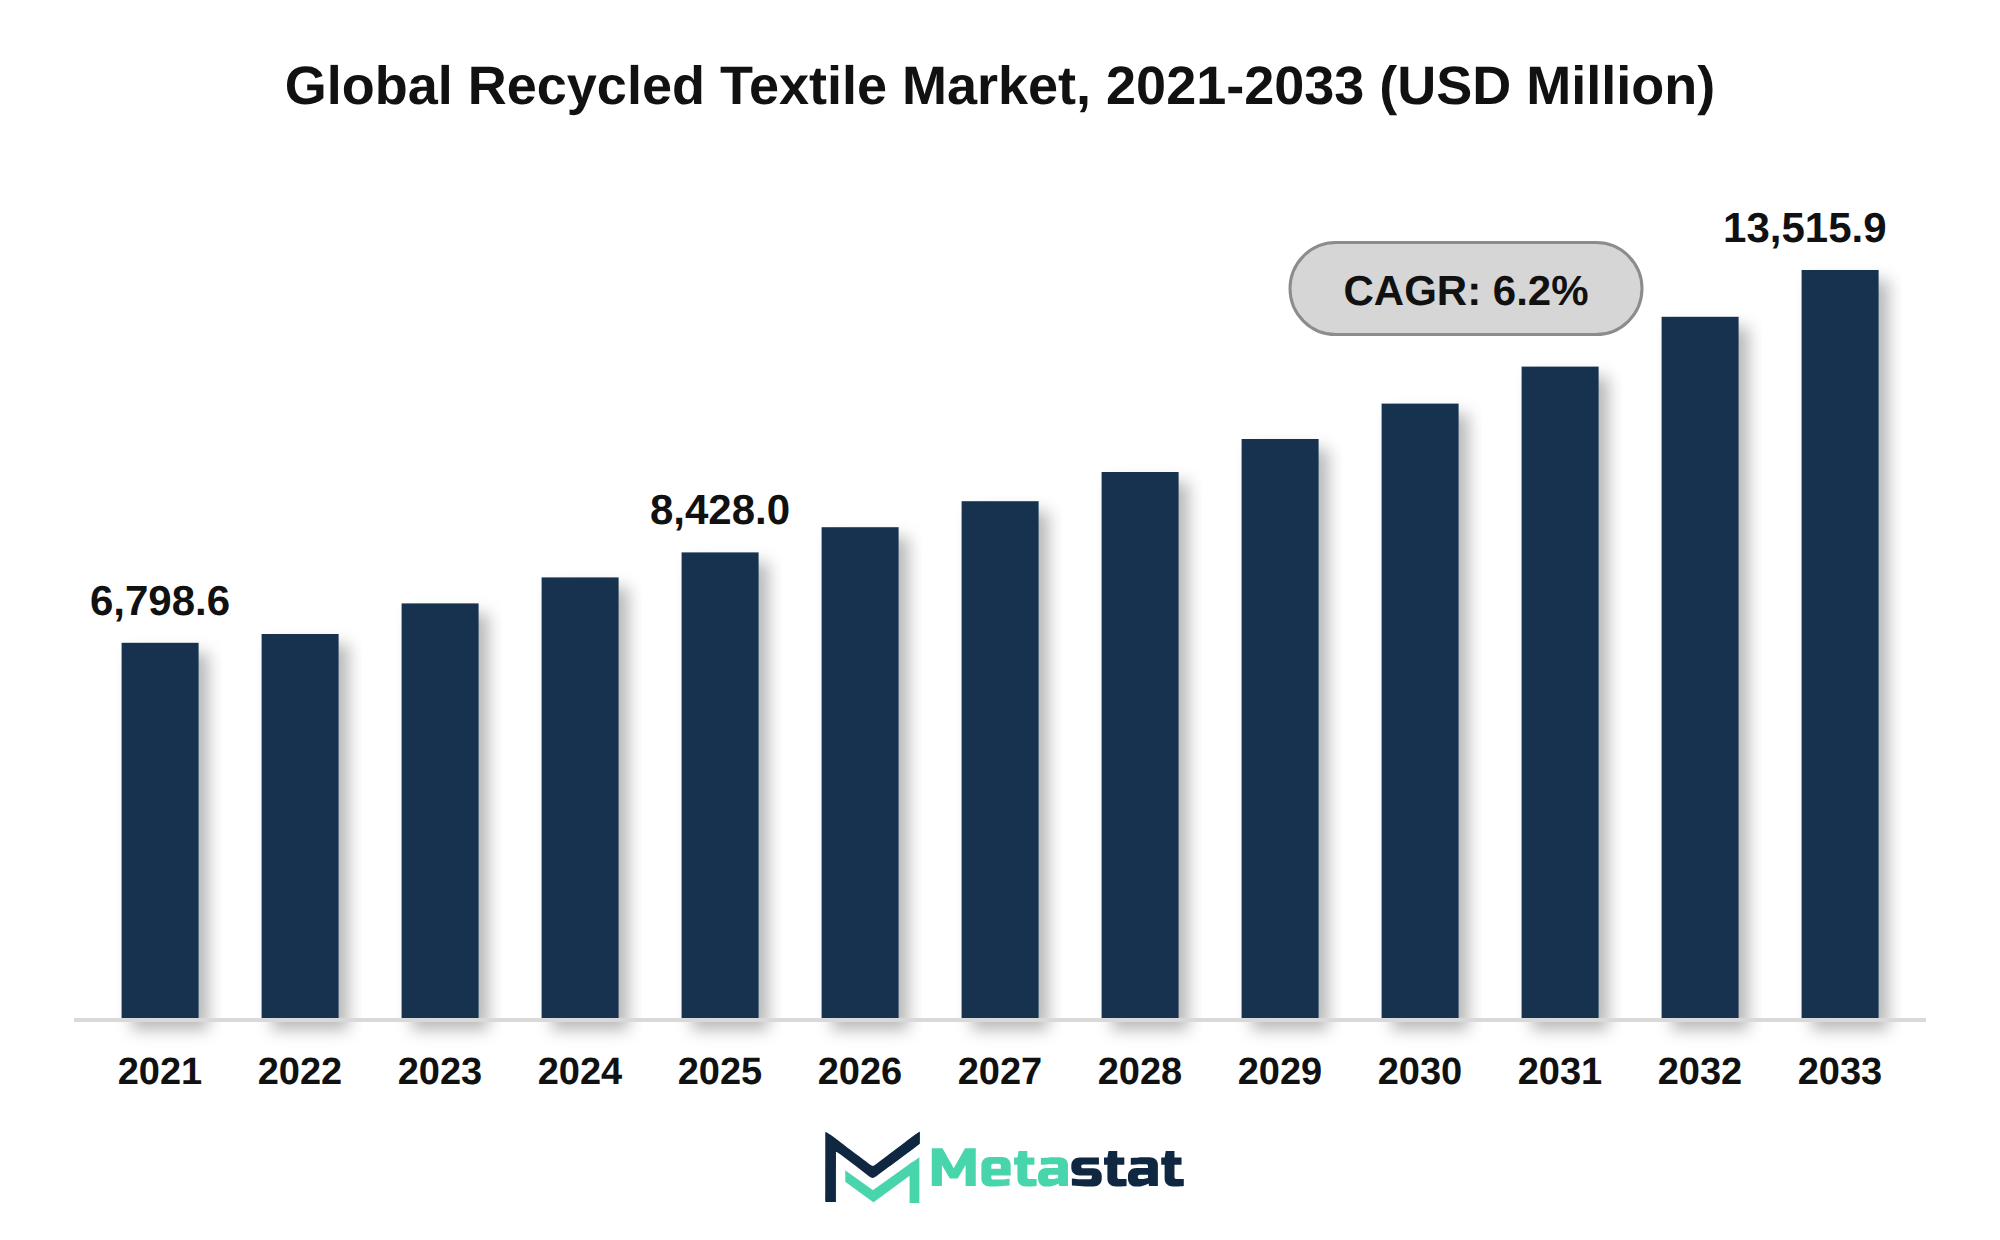
The Recycled Textile market experiences significant growth driven by advancements in technological integration. Automation and artificial intelligence streamline production processes, reducing waste and enhancing efficiency. Digitizing legacy systems supports the transition toward sustainable practices, enabling firms to optimize resource utilization and improve product quality.
Investment in innovative software solutions enhances operational productivity, facilitating data-driven decision-making and reducing operational costs. This technological evolution attracts venture funding, further stimulating market expansion. Enhanced production capabilities enable suppliers to respond effectively to rising consumer demand for sustainable textile solutions.
Adoption of new technologies drives a shift toward more efficient recycling methods, improving the quality of recycled materials. Such advancements position the market to capitalize on the growing trend of sustainability among consumers, whose preferences increasingly favor eco-friendly products. Overall, the integration of technology into the recycling process plays a significant role in driving growth within the Recycled Textile market.
Growing consumer awareness regarding environmental sustainability significantly influences the Recycled Textile market. This shift toward sustainability encourages brands to adopt resource stewardship practices, focusing on ethical governance and carbon footprint reduction. Companies increasingly prioritize circular economy initiatives, which emphasize the recycling of textile materials and the reduction of waste. These practices align with consumer expectations and enhance brand reputation, positioning companies favorably in a competitive landscape.
Investment in sustainable practices has become a central strategy among players in the market. Companies recognize that addressing environmental concerns leads to improved operational efficiency and cost savings, particularly through reduced material waste and energy consumption. The commitment to sustainability drives innovation, leading to the development of new products and processes that meet the evolving demands of consumers. The focus on resource stewardship serves because a critical growth driver in the Recycled Textile market.
With increasing regulatory pressures related to sustainability and environmental impact, organizations are compelled to integrate responsible practices into their operations. This compliance mitigates risks associated with regulatory violations and enhances customer loyalty. While consumers increasingly seek out sustainable options, companies that excel in resource stewardship capture greater market share and drive revenue growth.
Stringent regulatory compliance presents challenges for the Recycled Textile market, limiting operational flexibility for many suppliers. Legal mandates necessitate extensive documentation and adherence to evolving standards, creating barriers for smaller companies lacking the resources to navigate complex requirements. Compliance hurdles increase costs, deterring investment in new recycling technologies and processes.
Macroeconomic headwinds including inflationary pressures and economic uncertainty further complicate market conditions. Rising operational costs associated with energy and raw materials strain profitability, particularly for companies relying on outdated technologies that lack efficiency. This economic environment reduces the incentive for companies to invest in upgrading recycling capabilities.
Supply chain disruptions stemming from geopolitical instability and resource scarcity contribute additional challenges. These disruptions impact the availability of raw materials necessary for production, hindering the ability of companies to meet demand in the Recycled Textile market. Market fragmentation and cultural barriers complicate efforts to establish consistent supply chains across regions, limiting growth opportunities.
Infrastructure gaps and connectivity deficits in certain regions delay the deployment of recycling initiatives. Without adequate facilities and technology, the ability to process recycled textiles efficiently diminishes, impacting overall market performance. The shortage of skilled labor presents a significant challenge, with companies struggling to find qualified personnel capable of operating advanced recycling machinery or implementing innovative recycling techniques.
Geopolitical fragmentation contributes to market volatility, impacting supply chains and trade flows. Political tensions among nations result in trade deficits and tariff friction, which complicate the movement of recycled textiles across borders. These barriers create uncertainties for manufacturers and suppliers, leading to supply chain instability.
Technological disruptions challenge industry players by necessitating complex research and development integrations. Companies face hurdles in keeping pace with evolving technologies while managing interoperability between systems. This situation creates a gap that affects market competitiveness and innovation.
The Recycled Textile market encounters rising input costs, which put pressure on profit margins. Fluctuations in feedstock and component availability increase these cost challenges. This dynamic forces companies to reassess pricing strategies, potentially leading to pricing compression that impacts overall market health.
Workforce skill gaps pose a significant challenge, driven by the market's demand for specialized knowledge in textile recycling processes. Automation displacements further exacerbate this issue, leading to talent retention pressures. Companies invest in training and development to address these workforce challenges and maintain operational efficiency.
Environmental lifecycle footprints and decarbonization mandates require companies to adapt to sustainability demands. This evolution entails infrastructure gaps, retrofitting barriers, and implementation bottlenecks that hinder progress. Participants in the Recycled Textile market navigate these challenges effectively to ensure compliance and meet consumer expectations.
Intellectual property protection deficits and cybersecurity risks present additional concerns for firms operating in the market. Data vulnerabilities lead to significant operational disruptions, making it crucial for companies to strengthen their cybersecurity measures. Addressing these risks is vital for maintaining trust and ensuring the long-term viability of the market.
Changing downstream demands further complicate the market. Market saturation and substitution vector pressures require companies to innovate continuously and adapt their offerings. Failure to respond to these shifts results in decreased market share and reduced competitiveness in the evolving environment.
The Recycled Textile market experiences opportunities driven by increasing regional demands influenced by sustainability initiatives and consumer preferences for eco-friendly products. Regions like Asia Pacific, with a significant market share of 41.7%, demonstrate heightened interest in recycled textiles, reflecting growing environmental consciousness among consumers and businesses. This regional demand surge results from a combination of economic growth, urbanization, and a strong push towards sustainability, positioning the market for robust expansion.
Infrastructure modernization plays a critical role in enhancing the market landscape. Investments in recycling facilities and technology upgrades improve operational efficiencies, enabling higher quality outputs from recycled materials. These advancements contribute to lower production costs and increase the competitiveness of recycled textiles against conventional materials.
Geographical expansion represents another vital opportunity for the market. Emerging economies witness an increase in textile recycling initiatives, aligning with global sustainability trends. This shift enables companies to tap into new markets, increasing competition and innovation while diversifying their product offerings.
Technological disruptions offer avenues for growth through the integration of advanced recycling technologies and automation in production processes. These innovations enhance yield and reduce waste, enabling manufacturers to meet rising demand while ensuring environmental compliance.
Digital transformation facilitates new procurement methods and supply chain efficiencies. The Recycled Textile market leverages digital platforms for improved sourcing and distribution, aligning with evolving buyer behaviors that prioritize transparency and sustainability in supply chains.
Overall, the convergence of these factors creates a favorable environment for growth within the Recycled Textile market, enhancing its relevance in a rapidly changing global environment focused on sustainability and eco-friendly practices.
The Global Recycled Textile market is segmented based on Material, Textile Waste, Process, and End-use.
Cotton demonstrates strong demand within the Recycled Textile market, reflecting the increasing consumer preference for sustainable materials. This segment is valued at USD 4,334.8 million in 2026 and is projected to reach USD 6,482.6 million by 2033, growing at a CAGR of 5.9% during the forecast period. Rising awareness of environmental issues encourages brands to incorporate recycled cotton into their product lines, enhancing market adoption. Technological maturation enhances the expansion of the cotton segment. Innovations in recycling processes improve the quality and yield of recycled cotton, making it a viable alternative to virgin materials. Regulatory compliance standards promote the use of recycled textiles, particularly in regions with stringent environmental regulations. End-use dynamics further influence the growth of the cotton segment. The apparel industry, a significant consumer of cotton, prioritizes sustainability, driving demand for recycled options. Shifts in consumption patterns indicate a preference for eco-friendly products, further supporting growth in the recycled cotton market. Investments in supply chain resilience and raw material sourcing enhance the operational capabilities of producers. Strengthening these aspects contributes to more stable pricing structures and mitigates risks associated with raw material fluctuations. The cotton segment of the Recycled Textile market presents substantial growth opportunities, driven by evolving consumer preferences and advancements in recycling technologies.
Increasing demand for sustainable materials drives growth in the Polyester & Polyester Fiber segment of the Recycled Textile market. This segment is estimated to reach USD 3,109 million by 2033, at a CAGR of 7% during the forecast period. The adoption of recycled polyester aligns with consumer preferences for eco-friendly products, particularly in the fashion and home furnishings industries. Key end-users integrate recycled polyester into their product lines to enhance brand loyalty and meet sustainability goals.
Technological maturation in recycling processes enhances the quality and availability of recycled polyester products. Advances in mechanical and chemical recycling methods improve efficiency and reduce production costs, contributing to lower pricing volatility in the segment. Regulatory compliance standards encouraging the reduction of plastic waste and promoting recycled content support adoption among manufacturers.
Supply chain resilience remains vital for this segment, with raw material sourcing influenced by global trends in textile waste management. Competitors face substitution risks from virgin polyester, which presents higher performance characteristics. Strategic opportunities arise from innovations in next-generation upgrades and product evolution, focusing on the development of high-performance recycled polyester fibers.
Overall, the Polyester & Polyester Fiber segment within the Recycled Textile market reflects growth potential driven by evolving consumer preferences, technological advancements, and regulatory frameworks, positioning it favorably for future investments and expansion.
Interest in the wool segment stems from its natural properties, including durability and moisture-wicking capabilities, which attract consumers seeking sustainable and high-performance textiles. This segment is expected to reach USD 1,486.3 million by 2033, reflecting growing demand within the apparel and home furnishings sectors. The trend toward eco-friendly materials fuels adoption, particularly among brands emphasizing sustainable practices and responsible sourcing. Enhanced recycling technologies contribute to the segment's expansion, allowing for higher quality and more efficient processing of wool waste.
Regulatory frameworks that promote recycling and circular economies provide additional support for the wool segment, encouraging manufacturers to integrate recycled materials into their product lines. Consumer preferences increasingly shift toward sustainable options, driving the market owing to brands seeking to meet this demand. Competitive pricing pressures and cost structures associated with virgin wool drive further investment in recycled alternatives, enhancing profitability for manufacturers and suppliers.
Technological advancements and innovations in recycling processes play a significant role in the segment's future. Companies investing in next-generation upgrades achieve improved efficiency and lower operational costs, positioning themselves favorably in the market. The focus on reducing environmental impacts and ensuring compliance with regulations enhances the segment's resilience and opens strategic opportunity windows for growth.
Growth in the Nylon & Nylon Fiber segment aligns with increasing demand for sustainable textile solutions, reflecting heightened consumer awareness regarding environmental impact. This segment is projected to grow at a CAGR of 5.9% during the forecast period. The demand for recycled nylon arises from its applications in various end-use sectors, particularly in apparel, where brands emphasize sustainability in their product offerings. Fabric manufacturers recognize the economic and environmental benefits of recycling materials, leading to enhanced adoption rates.
Technological advancements in recycling processes facilitate the transformation of waste into high-quality nylon fibers, further driving the segment's growth. Innovations in mechanical and chemical processes allow for increased efficiency and reduced costs, supporting wider acceptance among manufacturers. Regulatory pressures regarding waste management and sustainability push companies toward incorporating recycled materials, making this segment an attractive option in the Recycled Textile market.
Focusing on circular economy principles, the market for recycled nylon experiences strong momentum. Consumer preferences shift toward brands committed to sustainability, encouraging investment in environmentally friendly practices. This shift contributes to the expansion of the market, creating opportunities for players focused on the production of recycled nylon and enhancing their competitive advantages.
Increasing attention on sustainable practices drives demand for recycled materials across various industries, including textiles. The Others sub-segment within the Recycled Textile market serves diverse applications, attracting attention from manufacturers seeking to improve their sustainability profiles. This sub-segment encompasses several materials beyond the primary categories, contributing to the growth of the overall market.
Technological maturation enables suppliers to develop innovative products, enhancing the appeal of recycled materials. Next-generation upgrades in recycling processes facilitate higher quality outputs, attracting brands committed to sustainability. This evolution in production techniques supports the market's expansion by ensuring that end-users receive high-quality textile products.
Downstream applications reflect a broadening acceptance of recycled textiles in sectors including fashion, interior design, and industrial uses. While consumers prioritize sustainability, brands increasingly incorporate recycled materials into their offerings. This shift in consumption patterns highlights the importance of the Others segment, which provides alternatives to traditional materials.
Regulatory compliance standards strengthen the market landscape, motivating businesses to adapt to sustainability mandates. This compliance influences product development and sourcing decisions within the Others sub-segment. Heightened awareness of environmental issues drives industry growth, pushing suppliers to innovate and diversify their material offerings.
Strategic opportunity windows exist due to stakeholders recognizing the potential of the Others segment to capture new markets and consumer bases. The evolving landscape creates avenues for investment and partnership, facilitating the development of innovative solutions that align with consumer preferences. Capital investment outlooks remain positive, reflecting confidence in the potential for growth within the Recycled Textile market.
Valued at USD 1,899.1 million in 2026, the Pre-consumer segment is projected to reach USD 2,886.9 million by 2033, at a CAGR of 6.2% during the forecast period. Demand for pre-consumer textile waste arises from manufacturers seeking to minimize waste and lower production costs. Adoption of pre-consumer recycling strategies enhances sustainability efforts, aligning with the growing consumer preference for eco-friendly products.
Expansion of the segment benefits from advancements in recycling technologies that improve efficiency and output. Increased focus on developing innovative processes boosts the volume of pre-consumer materials entering the market. Industries including apparel and home furnishings heavily rely on these materials, driving demand for sustainable sourcing options.
Regulatory compliance standards regarding waste management and sustainability practices influence growth in the Pre-consumer segment. Stringent regulations encourage manufacturers to incorporate recycled materials, thus improving their market positioning. Fluctuations in raw material prices present ongoing challenges, impacting cost structures and profit margins for businesses involved in the recycled textile market.
Strategic investments in recycling infrastructure and technologies enhance supply chain resilience, offering companies opportunities to differentiate themselves in a competitive environment. The transition towards circular economy principles drives growth within this segment, leading to increased collaboration among stakeholders to innovate and optimize processes in the recycling ecosystem.
Consumer habits increasingly shift towards sustainability, driving demand for recycled textiles. This trend aligns with heightened awareness regarding environmental impact and responsible consumption. The Post-consumer segment is projected to reach USD 2,028.6 million by 2033, at a CAGR of 6.4% during the forecast period. Regulatory compliance standards encourage brands to incorporate recycled materials into their offerings, reinforcing market growth. Heightened interest in circular economy models enables avenues for innovation in recycling technologies, enhancing the efficiency of post-consumer textile processing.
Challenges regarding pricing volatility and margin pressures persist within the market, impacting profitability for suppliers. Market players develop strategies to navigate these obstacles by optimizing supply chain resilience and improving raw material sourcing. The pursuit of disruptive alternatives continues to shape product evolution, with companies exploring new methods to integrate post-consumer textiles effectively. Downstream applications, particularly in apparel and home furnishings, capitalize on this growing segment, reflecting a strong alignment between market offerings and consumer preferences.
Increasing focus on sustainability drives demand for the Production Overruns segment within the Recycled Textile market. This segment reflects a shift toward waste reduction and efficient resource utilization, appealing to manufacturers aiming to enhance their environmental credentials. Regulatory compliance concerning waste management significantly influences this sub-segment, pushing producers to adopt recycling practices that minimize production waste.
The Production Overruns segment is projected to reach USD 3,011.2 million by 2033. This growth presents opportunities for investment in innovative recycling technologies that improve processing efficiencies and increase yield rates. While textile manufacturers face mounting pressure to reduce waste, adopting recycled materials becomes crucial for maintaining competitiveness while aligning with evolving consumer preferences for sustainable products.
Technological advancements in recycling processes enhance the market appeal of production overruns. Mechanically and chemically recycled textile waste offers potential for high-quality output, enabling manufacturers to meet the demands of various end-use applications effectively. This technical maturation creates a conducive environment for collaboration among industry players, expanding the market's overall growth potential.
Downstream applications, particularly in apparel and home furnishings, increasingly adopt recycled materials derived from production overruns. Consumer preferences for sustainable fashion and eco-friendly products strongly impact this trend, driving brands to source recycled textiles. Consequently, manufacturers prioritizing sustainability within their supply chains gain a competitive advantage in the market, further propelling growth in the Production Overruns segment.
Growing demand for the Pullouts segment, projected to expand at a CAGR of 6.1% during the forecast period, results from increasing consumer preference for sustainable textile solutions. This expansion correlates with the rising cost of raw materials, prompting manufacturers to seek alternative sourcing strategies that leverage recycled materials. The emphasis on sustainability influences end-use industries, particularly in apparel and home furnishings, where eco-friendly practices receive heightened attention.
Regulatory frameworks supporting recycling initiatives drive investment in Pullouts, enhancing the segment's attractiveness to key stakeholders. The evolving landscape includes technological advancements that streamline recycling processes, ensuring higher quality and efficiency. Increased collaboration among textile manufacturers, recyclers, and policymakers creates an environment conducive to innovation and growth within the Recycled Textile market.
While the market matures, heightened competition encourages companies to invest in next-generation upgrades, further enhancing product offerings. This strategic focus on innovation positions the Pullouts segment favorably within the broader context of the Recycled Textile market, driving adoption and revenue growth.
Interest in the Export Seconds segment reflects the growing emphasis on sustainability within the Recycled Textile market. This focus aligns with consumer preferences shifting towards environmentally friendly practices and the increasing integration of recycled materials in manufacturing processes. The segment benefits from expanding adoption across various industries, particularly within fashion and apparel, where companies aim to enhance their sustainable credentials.
Technological maturation supports this segment, with advancements in recycling technologies facilitating better quality recovery of textile waste. Enhanced processing methods improve the efficiency of converting substandard products into usable materials, broadening the market's appeal. These innovations encourage investment in infrastructure and capabilities, enabling firms to capture value from a previously underutilized resource.
Regulatory compliance standards advance the Export Seconds segment, with governments worldwide implementing policies that favor the use of recycled materials. This regulatory environment motivates companies to adapt their supply chains and sourcing strategies to align with new standards, ultimately creating a more sustainable production framework. Organizations striving to meet these requirements strengthen the segment's role within the broader Recycled Textile market, enhancing its competitive position.
Strategic opportunity windows arise from ongoing trends in environmental responsibility, encouraging businesses to explore new applications for export seconds. Continuous product evolution in response to consumer demands leads companies to innovate and diversify their offerings. This growth in downstream applications positions the segment favorably within the market, reinforcing its importance in achieving circular economy objectives.
Emerging trends in the Recycled Textile market highlight the significance of the "Others" sub-segment within Textile Waste. This category encompasses a variety of materials not classified under traditional categories, reflecting diverse sourcing practices in the textile recycling process. Demand for these materials stems from the growing focus on innovative recycling solutions and alternative fibers, which align with evolving consumer preferences for sustainable textiles.
Technological advancements in recycling processes significantly influence the segment's dynamics. Innovations in mechanical and chemical recycling enhance the efficiency of material recovery, minimizing waste and maximizing resource utilization. This progress supports the market's broader goals of achieving sustainability and reducing environmental impact.
Downstream applications for products sourced from the "Others" segment increasingly find relevance across various industries. Adaptation to changing consumer behaviors drives demand for recycled textiles in apparel, home furnishings, and industrial applications. The market experiences a notable shift towards adopting recycled materials, compelling manufacturers to incorporate these into their product lines.
Regulatory compliance standards increasingly shape the landscape for recycled textiles. Stringent policies aimed at reducing landfill waste and promoting circular economy initiatives encourage businesses to explore options for incorporating recycled materials. This regulatory environment encourages investment in innovative recycling technologies, further enhancing the segment's attractiveness to investors.
Logistics vulnerabilities, particularly concerning raw material sourcing, present challenges within the segment. Ensuring a steady supply of diverse and quality input materials proves essential for sustaining production levels. Companies engaging in this market segment focus on developing resilient supply chains to mitigate these risks effectively.
Competitive pressures exert influence over pricing strategies, with market players striving to maintain margins during fluctuating raw material costs. The "Others" segment requires strategic pricing to address these challenges while remaining appealing to environmentally conscious consumers. Investments in research and development for creating value-added recycled products offer strategic opportunities for differentiation in the marketplace.
The Recycled Textile market continues to evolve, with the "Others" sub-segment presenting unique opportunities for growth. Its alignment with sustainability initiatives and advancements in recycling technology positions it favorably in an increasingly eco-conscious consumer landscape.
Valued at USD 6,428.4 million in 2026, the Mechanical segment is projected to reach USD 10,032.4 million by 2033, at a CAGR of 6.6% during the forecast period. Demand for mechanical recycling processes continues to rise owing to their efficiency and effectiveness in handling various textile materials, particularly in the context of sustainability. The adoption of mechanical recycling aligns with increasing consumer awareness around environmental issues, which drives companies to seek out sustainable practices. Industries including apparel and home furnishings increasingly incorporate recycled fibers, with mechanical processing playing an essential role in meeting these needs.
Technological maturation within the mechanical recycling sector supports equipment advancements, improving the quality and consistency of recycled textiles. Enhanced processing capabilities allow for higher volumes of waste textiles to be efficiently transformed into reusable materials, contributing to a circular economy. In addition, the development of next-generation recycling technologies enhances operational efficiencies and reduces costs associated with textile waste disposal.
The regulatory environment increasingly emphasizes sustainability, pushing more companies to adopt mechanical recycling techniques. Compliance with environmental regulations influences investment decisions, encouraging players in the Recycled Textile market to explore innovative mechanical solutions. Cost structures are expected to adjust owing to more manufacturers integrating mechanical recycling into their operations, which leads to pricing stability in recycled textile products.
Supply chain resilience becomes crucial owing to raw material sourcing shifts to support mechanical recycling initiatives. Increased collaboration among stakeholders facilitates the development of efficient logistics networks, ensuring consistent supply and demand dynamics. While the market evolves, strategic opportunity windows emerge for players focusing on mechanical recycling to expand their offerings and capture emerging consumer preferences.
Technological advancements play a crucial role in the Chemical segment of the Recycled Textile market, driving the development of innovative methods for processing textile waste. Enhanced chemical recycling processes increase efficiency and reduce environmental impact, aligning with the growing emphasis on sustainability across various industries. This segment is projected to reach USD 3,483.5 million by 2033, at a CAGR of 5.1% during the forecast period.
Regulatory compliance standards significantly influence the Chemical segment, with stricter policies encouraging companies to adopt greener practices. The demand for recycled textiles reflects a broader shift towards sustainable consumption, pushing manufacturers to invest in chemical recycling technologies. End-users prioritize environmentally friendly products, and companies focusing on chemical recycling gain a competitive advantage in the marketplace.
Cost structures and pricing volatility directly impact the Chemical segment, prompting companies to streamline operations and optimize raw material sourcing. Volatility in raw material prices affects profit margins, making efficient chemical recycling processes crucial for maintaining competitiveness. Strategic investment in advanced technologies plays a significant part in addressing these challenges and enhancing overall margin resilience.
The growing demand for recycled textiles, particularly in the apparel and home furnishings sectors, drives the expansion of the Chemical segment. Increased consumer awareness regarding sustainability influences purchasing decisions, prompting brands to incorporate recycled materials into their products. This trend reinforces market growth and creates opportunities for innovation and development within the chemical recycling domain.
Valued at USD 3,433.3 million in 2026, the Apparel segment is projected to reach USD 5,262.2 million by 2033, with a CAGR of 6.3% during the forecast period. Factors driving demand within this segment include increasing consumer awareness regarding sustainable fashion and the growing preference for recycled materials in apparel production. The heightened focus on environmental sustainability compels manufacturers to integrate recycled textiles into their product lines, enabling them to meet consumer expectations and compliance with evolving regulatory standards.
Technological advancements in recycling processes enhance the quality of recycled fabrics, further driving adoption in the apparel sector, driven by brands striving to improve their sustainability credentials. Brands increasingly emphasize transparency in their sourcing strategies, leading to partnerships with recycled textile suppliers. This strategic alignment supports market growth by ensuring access to high-quality materials while promoting responsible production practices. Investment in innovative recycling technologies positions players favorably to capture emerging opportunities in the recycled textile market.
In addition, shifts in consumption patterns reflect a growing acceptance of second-hand and upcycled clothing among consumers, driven by both environmental and economic considerations. This trend aligns with the broader sustainability movement and reinforces the demand for recycled textiles in apparel. With regulatory frameworks supporting sustainable practices, the market for recycled textiles continues to expand, creating a conducive environment for investments in new product developments and operational efficiencies.
Growing interest in sustainability significantly influences the Home Furnishings segment within the Recycled Textile market. This segment reflects a rising consumer preference for eco-friendly and recycled materials, aligning with broader societal trends toward environmental responsibility. Increased awareness of the environmental impacts of textile production drives both consumers and manufacturers to seek sustainable alternatives for home furnishings. The segment is projected to reach USD 2,975.6 million by 2033, at a CAGR of 6% during the forecast period. Investment in innovative and sustainable production processes enhances product offerings, catering to the evolving demands of environmentally conscious consumers and contributing to segment growth. Collaboration among industry players to develop advanced recycling technologies strengthens the overall market position of recycled textiles in home furnishings.
Rising emphasis on sustainability in various industries drives demand for recycled textiles in the Industrial & Institutional segment. This segment is projected to reach USD 2,251.1 million by 2033, reflecting a strong market trend towards environmentally friendly materials. Organizations increasingly prioritize eco-friendly practices, enhancing the adoption of recycled materials within institutional applications.
Regulatory compliance standards regarding waste management and environmental impact further support growth in this segment. Stricter regulations on textile waste disposal prompt institutions to explore recycled options, reinforcing their commitment to sustainability. This shift results in higher consumption of recycled textiles across various institutional sectors, including government facilities and educational institutions.
Technological maturation plays a significant role in expanding the capabilities of recycled textiles. Advancements in processing technologies enable more efficient conversion of waste materials into high-quality textiles, thereby increasing product availability for industrial and institutional uses. Investments in innovative recycling technologies enhance product appeal by improving performance characteristics and reducing production costs.
Continued evolution in product offerings within the recycled textile market caters to diverse institutional needs. The development of specialized textiles for various applications, ranging from uniforms to facility maintenance, enhances market penetration. This diversification allows suppliers to tap into new revenue streams, aligning with institutional buyers' demand for sustainable solutions.
Market interest in the Others segment stems from the increasing diversity of applications for recycled textiles beyond traditional categories. This trend is driven by a shift towards sustainable practices across various industries seeking environmentally friendly materials. The potential for innovation in this segment encourages manufacturers to explore new product developments and marketing strategies, further enhancing adoption rates. Valued at USD 1,899.1 million in 2026, the Others segment is projected to grow at a CAGR of 6.3% during the forecast period, reflecting a robust response to changing consumer preferences and regulatory pressures. Continuous advancements in recycling technologies facilitate the transformation of waste into high-quality materials, broadening the scope of recycled textiles in end-use applications. Enhanced awareness of environmental impacts fuels demand, ensuring that the Others segment remains a vital component of the broader recycled textile market.
Based on geography, the Global Recycled Textile market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America demonstrates a growing interest in sustainability that drives the Recycled Textile market. The region benefits from a strong infrastructure for recycling initiatives, particularly in the United States, Canada, and Mexico, where consumer awareness of environmental issues continues to rise. The market is projected to expand at a CAGR of 6.2% during the forecast period, reaching a market size (TAM) of USD 3,164.3 million by the end of 2033.
North America's market share accounts for 24% of the global total in 2025. This solid position results from a combination of factors, including increased adoption of recycled materials in various industries, particularly in apparel and home furnishings. Local compliance mandates and cultural nuances influence buying behaviors, shaping regional procurement dynamics that favor sustainable materials.
The competitive landscape reflects strong domestic market participants committed to expanding their operations in recycled textiles. Strategic entry barriers for new firms focus on significant investment in technology and production capabilities. Existing players continue to consolidate their positions, ensuring a robust supply chain and enhancing localized manufacturing densities. This consolidation strengthens the market's overall competitive environment.
Emerging front-runners in the market leverage foreign direct investment (FDI) flows to capture opportunities in underpenetrated territories. Strategic initiatives that include nearshoring facilitate the establishment of localized manufacturing, ensuring timely production and reducing dependency on distant supply chains. Such measures contribute to the overall resilience and sustainability of the market in North America, enhancing its capacity to respond to evolving consumer demands.
Europe represents a significant portion of the global Recycled Textile market, accounting for 27.5% of market share in 2025. The region benefits from strong regulatory support for sustainable practices, which aligns with increasing consumer preferences for eco-friendly materials. Germany, France, and the UK lead in demand for recycled textiles, driven by robust manufacturing sectors and a growing focus on sustainability in apparel and home furnishings.
Investment in infrastructure modernization enhances the region's capacity to process textile waste, while localized manufacturing densities support efficient supply chains. The market experiences incremental growth vectors stemming from high-value replacement cycles, particularly in the apparel segment, which is projected to reach USD 5,262.2 million by 2033. Cultural nuances and regional B2B buying behaviors influence procurement dynamics, creating a competitive landscape where domestic market leaders thrive.
Geopolitical fragmentation affects cross-border trade corridors, creating opportunities for companies to capitalize on nearshoring initiatives. This trend allows for more localized production and efficient supply chains. The presence of influential vendors, including Birla Cellulose and Patagonia, contributes to market consolidation trends, encouraging new entrants to invest in the Recycled Textile market.
Overall, the European market demonstrates a strong framework for growth, characterized by regulatory compliance, competitive dynamics, and a commitment to sustainability that positions it because a key player in the global Recycled Textile market.
Asia Pacific represents a significant portion of the Recycled Textile market, accounting for 41.7% of the global market share in 2025. Demand for recycled textiles in this region arises from a combination of growing environmental awareness and increasing consumer preference for sustainable products. Countries like China, Japan, and India lead in adoption rates, driven by robust manufacturing capabilities and a rising middle class prioritizing eco-friendly practices.
The expansion of the market is driven by modernization efforts in infrastructure and manufacturing processes. Localized production and nearshoring initiatives contribute to increased efficiency and reduced logistics costs. Cultural nuances in the region influence B2B buying behaviors, driving market growth. Businesses seek suppliers that align with sustainability goals.
Emerging markets within Asia Pacific present opportunities for segment expansion, particularly in cotton and polyester recycling. The steady growth of urban populations contributes to increased textile waste generation, increasing the demand for recycled materials. Companies focus on innovative recycling technologies to optimize resource utilization and meet evolving consumer preferences.
With substantial foreign direct investment (FDI) flows and a favorable regulatory environment, the Asia Pacific region offers a promising environment for the Recycled Textile market. Domestic market participants capitalize on these favorable conditions, encouraging vendor consolidation trends that enhance competitive dynamics. The interaction between supply chain regionalization and local compliance mandates shapes market strategies, ensuring alignment with regional sustainability objectives.
In South America, the Recycled Textile market encapsulates a unique set of dynamics influenced by regional characteristics. Brazil and Argentina represent key players, contributing 3.6% of the global market share in 2025. The emphasis on sustainable practices among consumers increases demand for recycled textile products. Local manufacturers are adopting innovative recycling processes to meet this demand, reflecting a shift towards more environmentally friendly practices.
Infrastructure modernization in these countries supports growth in the market, with investments in recycling facilities and technology enhancing production capabilities. Regional supply chain dynamics, including nearshoring initiatives, encourage localized manufacturing, reducing dependence on imports and promoting domestic production. These trends are expected to drive competitive advantages for companies operating within the region.
Cultural nuances significantly impact B2B buying behaviors, with sustainability becoming an important factor in procurement decisions among businesses. The market observes a growing inclination towards collaboration among suppliers, enhancing product availability and market penetration. With ongoing developments, the Recycled Textile market in South America is projected for incremental growth, driven by both demand and supply-side factors.
The Recycled Textile market in the Middle East and Africa presents unique dynamics influenced by cultural nuances and regional procurement behaviors. Local demand drivers focus on sustainable practices, with countries including Saudi Arabia and the UAE prioritizing sustainability in various sectors. Segment expansion relies on strategic entry barriers, including regulatory frameworks that support sustainable initiatives.
Investment increases support localized manufacturing densities, particularly in South Africa, enhancing the market's infrastructure readiness. Geopolitical fragmentation within the region impacts cross-border trade corridors, creating opportunities for collaboration among local suppliers. The market structure features several domestic participants that contribute to vendor consolidation trends, promoting competitive landscapes.
The region shows potential for growth through emerging market front-runners. Growth vectors focus on high-value replacement cycles and localized supply chain regionalization initiatives. With increasing awareness of resource availability and energy grid resiliency, the Recycled Textile market is set to experience gradual but sustained development during the forecast period.
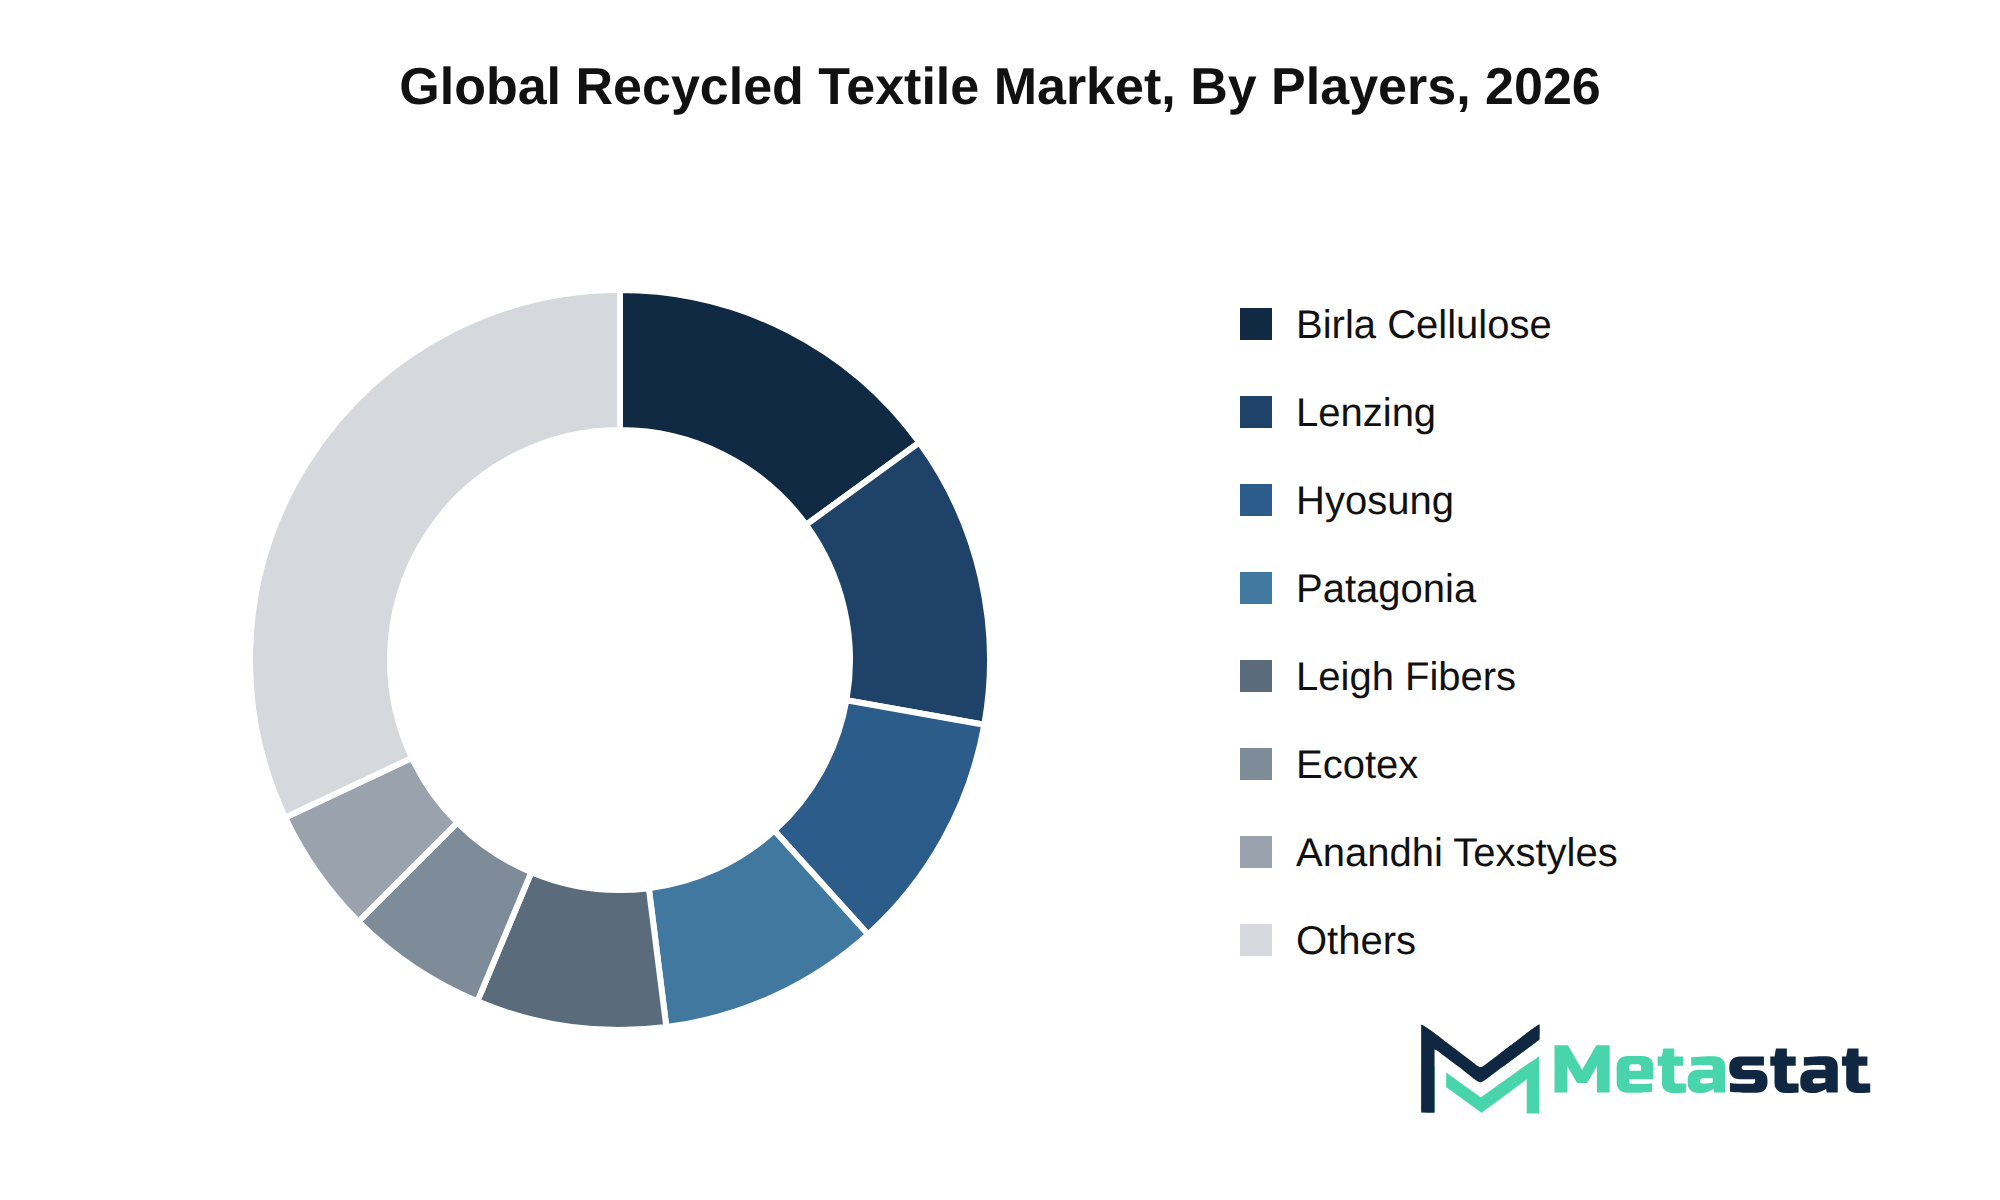
The Recycled Textile market experiences significant strategic activity, including mergers and acquisitions that facilitate consolidation among key players. Companies including Birla Cellulose and Lenzing Group enhance their market position through strategic partnerships and joint ventures, enabling them to leverage proprietary technologies and R&D pipelines for product differentiation. This strategic behavior provides a competitive edge, allowing firms to enhance their offerings and strengthen their market presence.
Value chain integration remains a crucial aspect of competition within the market. Major players including Unifi, Inc. and Patagonia, Inc. focus on supply chain dominance and procurement leverage to optimize operational efficiency. These strategies contribute to customer retention efforts by enhancing brand equity and lowering switching costs for consumers, reinforcing their competitive position.
The future competitive outlook indicates continued emphasis on innovation and technological defensibility. Firms including Hyosung Group and Worn Again Technologies prioritize intellectual property portfolios, ensuring robust patent landscapes that protect their advancements in recycled textile processes. The evolving landscape suggests an ongoing commitment to strategic growth vectors, further shaping the dynamics of the Recycled Textile market.
Market size is forecast to rise from USD 8,428 million in 2025 to over USD 13,515.9 million by 2033. The base case anticipates a growth trajectory at a 6.2% CAGR, reflecting robust demand across various sectors. Bull and bear cases highlight directional shifts, with bullish conditions reflecting increased investment in sustainable practices and consumer preference for eco-friendly products. Conversely, bearish scenarios arise from economic downturns or supply chain disruptions, impacting the growth of the market.
The evolving macroeconomic scenario emphasizes the integration of next-generation technologies, influencing production processes and resource allocation. R&D commercialization timelines and product life-cycles reflect a commitment to innovation, ensuring the market adapts to changing consumer expectations. Regulatory evolution shapes operational frameworks, while policy enforcement horizons dictate market entry strategies.
Geopolitical realignments and evolving trade corridors influence sourcing strategies and supply chain dynamics, compelling organizations to adapt to shifting global landscapes. Strategic capital allocation directives and infrastructure commitments support sustainable growth, identifying emerging opportunities and unmet enterprise needs. High-growth pockets within the market emerge owing to key players recognizing the importance of defensibility roadmaps and future growth recommendations.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Recycled Textile market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 6.2% from 2026 to 2033 |
|
Revenue Unit |
USD million |
|
Segmentation |
By Material, Textile Waste, Process, End-use, and Region |
|
By Region |
North America (By Material, Textile Waste, Process, End-use, and Country)
|
|
Europe (By Material, Textile Waste, Process, End-use, and Country)
|
|
|
Asia Pacific (By Material, Textile Waste, Process, End-use, and Country)
|
|
|
South America (By Material, Textile Waste, Process, End-use, and Country)
|
|
|
Middle East and Africa (By Material, Textile Waste, Process, End-use, and Country)
|
Find answers to common questions about this report
The Recycled Textile market size was valued at USD 8,428 million in 2025.
The Recycled Textile market is projected to grow at a CAGR of 6.2% during the forecast period from 2026 to 2033.
The North America Recycled Textile market size is estimated to reach USD 3,164.3 million by 2033.
The Cotton segment leads the Recycled Textile market with a projected value of USD 6,482.6 million by 2033. This figure represents the highest anticipated revenue among all material segments.
Key drivers for the Recycled Textile market include advancements in technological integration, which enhance production efficiency and reduce waste. Growing consumer awareness regarding environmental sustainability and the shift toward circular economy initiatives further motivate brands to adopt resource stewardship practices, positioning them favorably in a competitive landscape.
Asia Pacific holds the dominant share of the Recycled Textile market, accounting for 41.7% of the total market in 2025. This region's significant share reflects its strong position in the industry compared to others.
Rising operational costs, regulatory compliance challenges, and supply chain disruptions significantly restrain growth in the Recycled Textile market. These factors increase costs and limit operational flexibility, particularly for smaller companies, while geopolitical tensions and workforce skill gaps further complicate market dynamics.
Technological advancements significantly favor product adoption in the Recycled Textile market. Automation and artificial intelligence enhance production efficiency and reduce waste, while investments in innovative software solutions facilitate data-driven decision-making. growing consumer awareness of sustainability drives brands to adopt resource stewardship practices, aligning with market demand for eco-friendly products.
The Recycled Textile market is estimated to reach a valuation of USD 13,515.9 million by 2033.
Key players in the Recycled Textile market include Anandhi Texstyles Private Limited, Birla Cellulose, Ecotex Group, Hyosung Group, Lenzing Group, Patagonia, Inc., Renewcell AB, and Unifi, Inc.
Choose Your License
Global Recycled Textile Market
The analysts below cover Chemicals and Materials research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
INDUSTRY CONSULTANT - CHEMICALS & ADVANCED MATERIALS
Chemicals and Materials · Machinery & Equipment · Packaging
Amit Gadhekar Consultant for Chemicals and Materials at MetaStat Insight, directing sector-specific intelligence, research, and strategic consulting across global chemical and processing markets.
When evaluating distributed energy resource management systems, standard research summaries tend to gloss over the operational differences between front-of-the-meter utility deployments and behind-the-meter industrial sites. The MetaStat Insight report addressed those distinctions directly, especially regarding software interoperability standards and grid interconnection backlogs. The five-year market sizing across regional transmission organizations provided actionable context for our grid modernization strategy.
Most industry reports on warehouse automation bundle autonomous mobile robots and fixed conveyor installations into the same top-level numbers, which complicates advisory work. This study split the market cleanly by payload tiers, navigation technology, and fleet management software layers. The regional forecast for Western Europe gave our team defensible adoption benchmarks when evaluating capital allocation for logistics clients, saving us days of secondary data scrubbing.
Analyzing the transition from natural gas to green hydrogen in iron ore reduction requires realistic infrastructure timelines. Meta stat insight supplied a detailed regional assessment of DRI plant conversion costs and scrap metal availability in North America and Western Europe. Their report carefully examined pellet quality specs and electrical grid access constraints without making oversimplified market assumptions. The research material served as a practical reference during internal technology roadmap discussions.
Explore related market intelligence reports worth reading alongside this one.