
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Retail Construction Management Software Market Size, Share, By Project Type (New Construction Projects, Renovation & Retrofit Projects and Maintenance & Facility Upgrades), By Deployment (Cloud-based and On-premise), By Application (Project Planning and Scheduling, Budgeting and Cost Management, Document Management, Bid and Tender Management, Contractor and Vendor Management, Field Reporting and Site Coordination), By End User (Retail Chains and Franchise Operators, General Contractors, Construction Project Management Firms and Real Estate Developers), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5308
September 19, 2026
287 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $662.6 Million in 2025, projected to reach $1,390.7 Million by 2033 at a 9.8% CAGR.
Dominant Segment: The New Construction Projects segment leads the market, driven by rising demand for advanced construction methodologies and efficient project management tools.
Geographic Lead: The Asia-Pacific region is experiencing the fastest growth, fueled by increasing investments in infrastructure and modernization efforts across retail environments.
What's Inside: This report provides a comprehensive analysis of market dynamics, competitive landscape, and detailed segment breakdowns, covering project types, deployment methods, applications, and end users.
Emerging Technologies: Innovations such as AI and cloud-based solutions are transforming the market, enhancing project efficiency and enabling real-time collaboration among stakeholders.
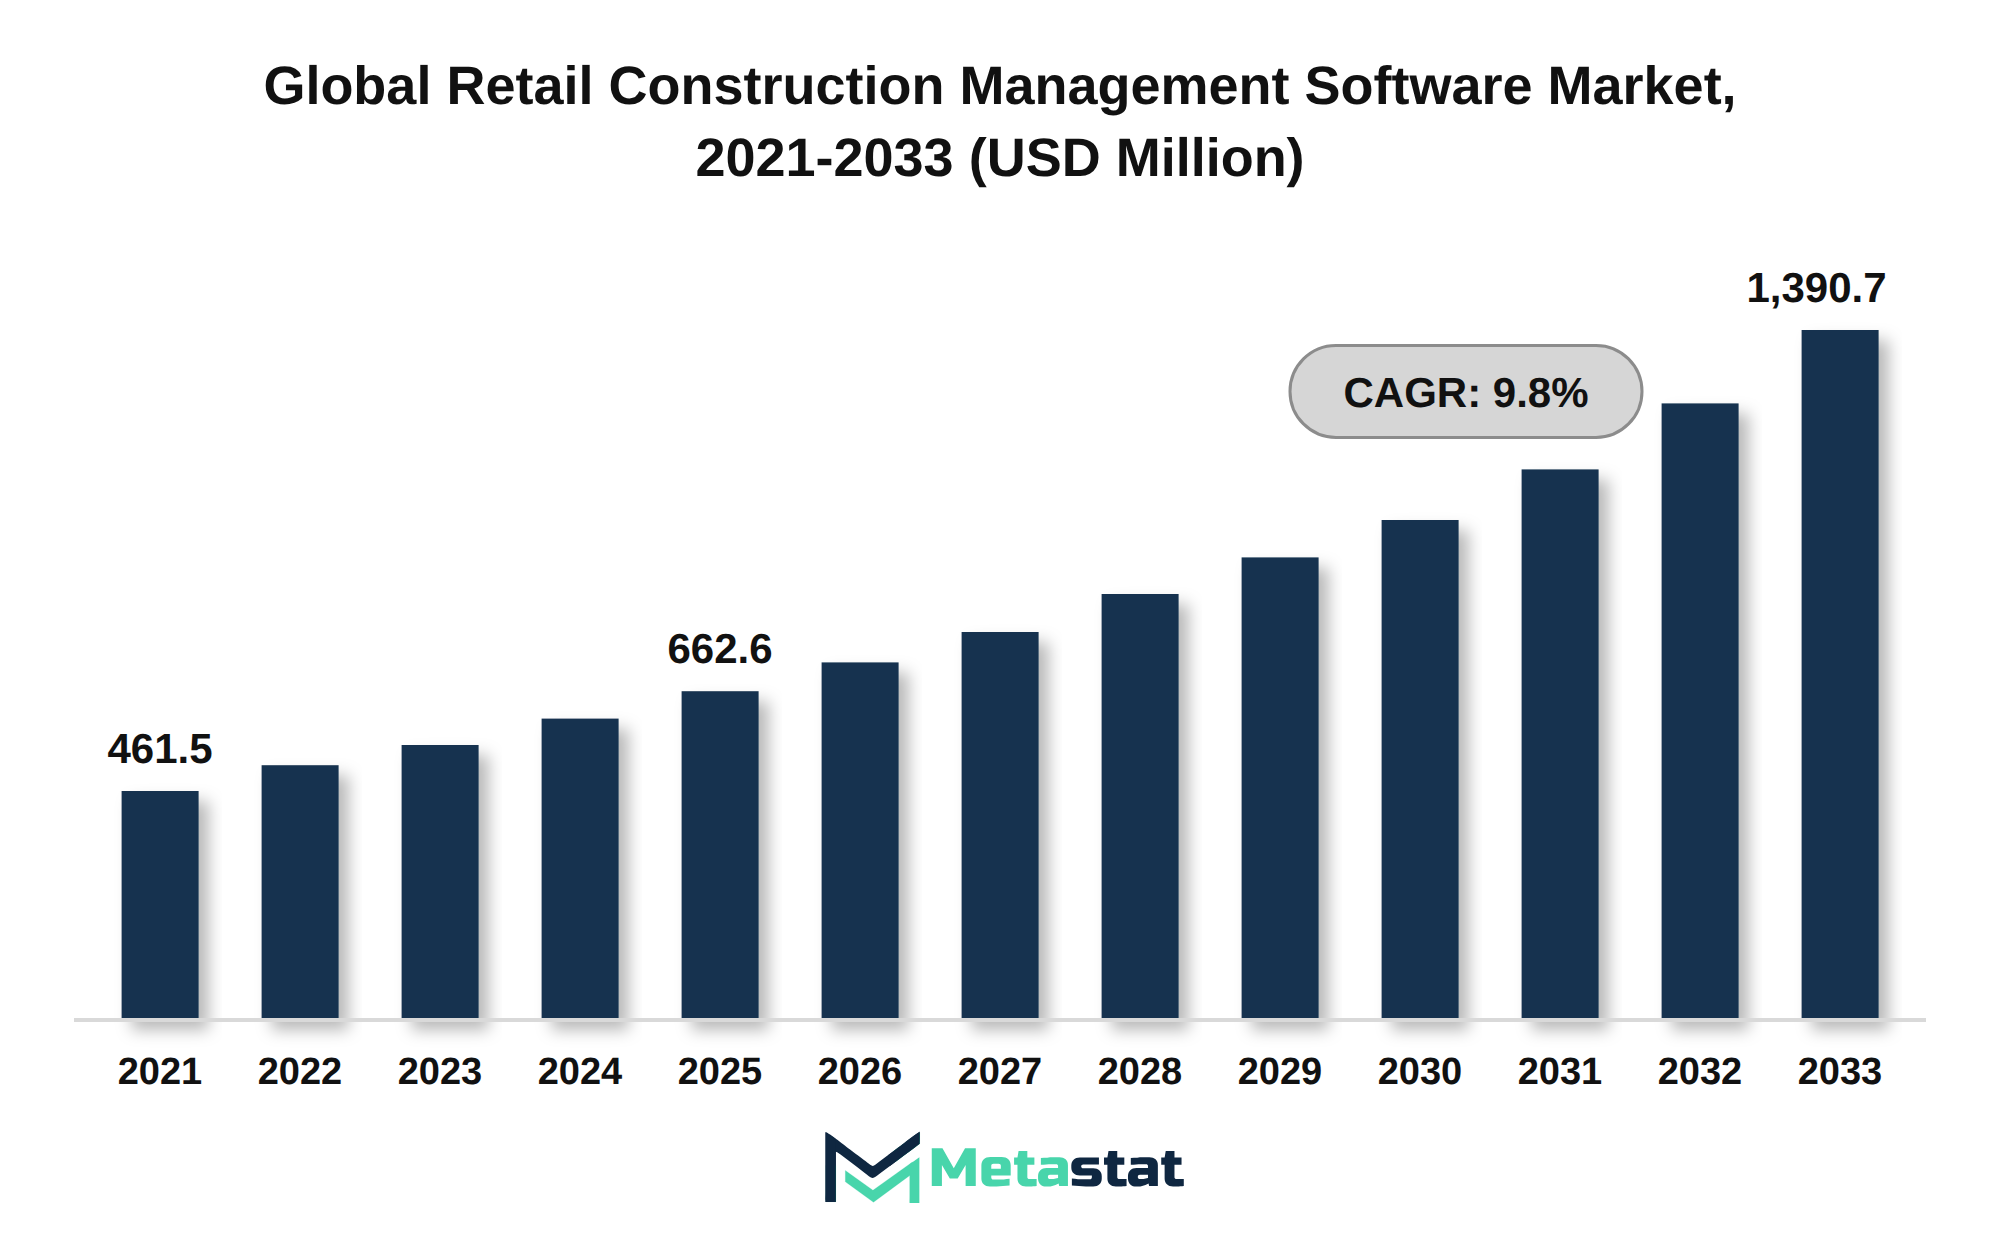
The global Retail Construction Management Software market was valued at USD 662.6 million in 2025 and is projected to reach USD 1,390.7 million by 2033, growing at a CAGR of 9.8% over the forecast period.
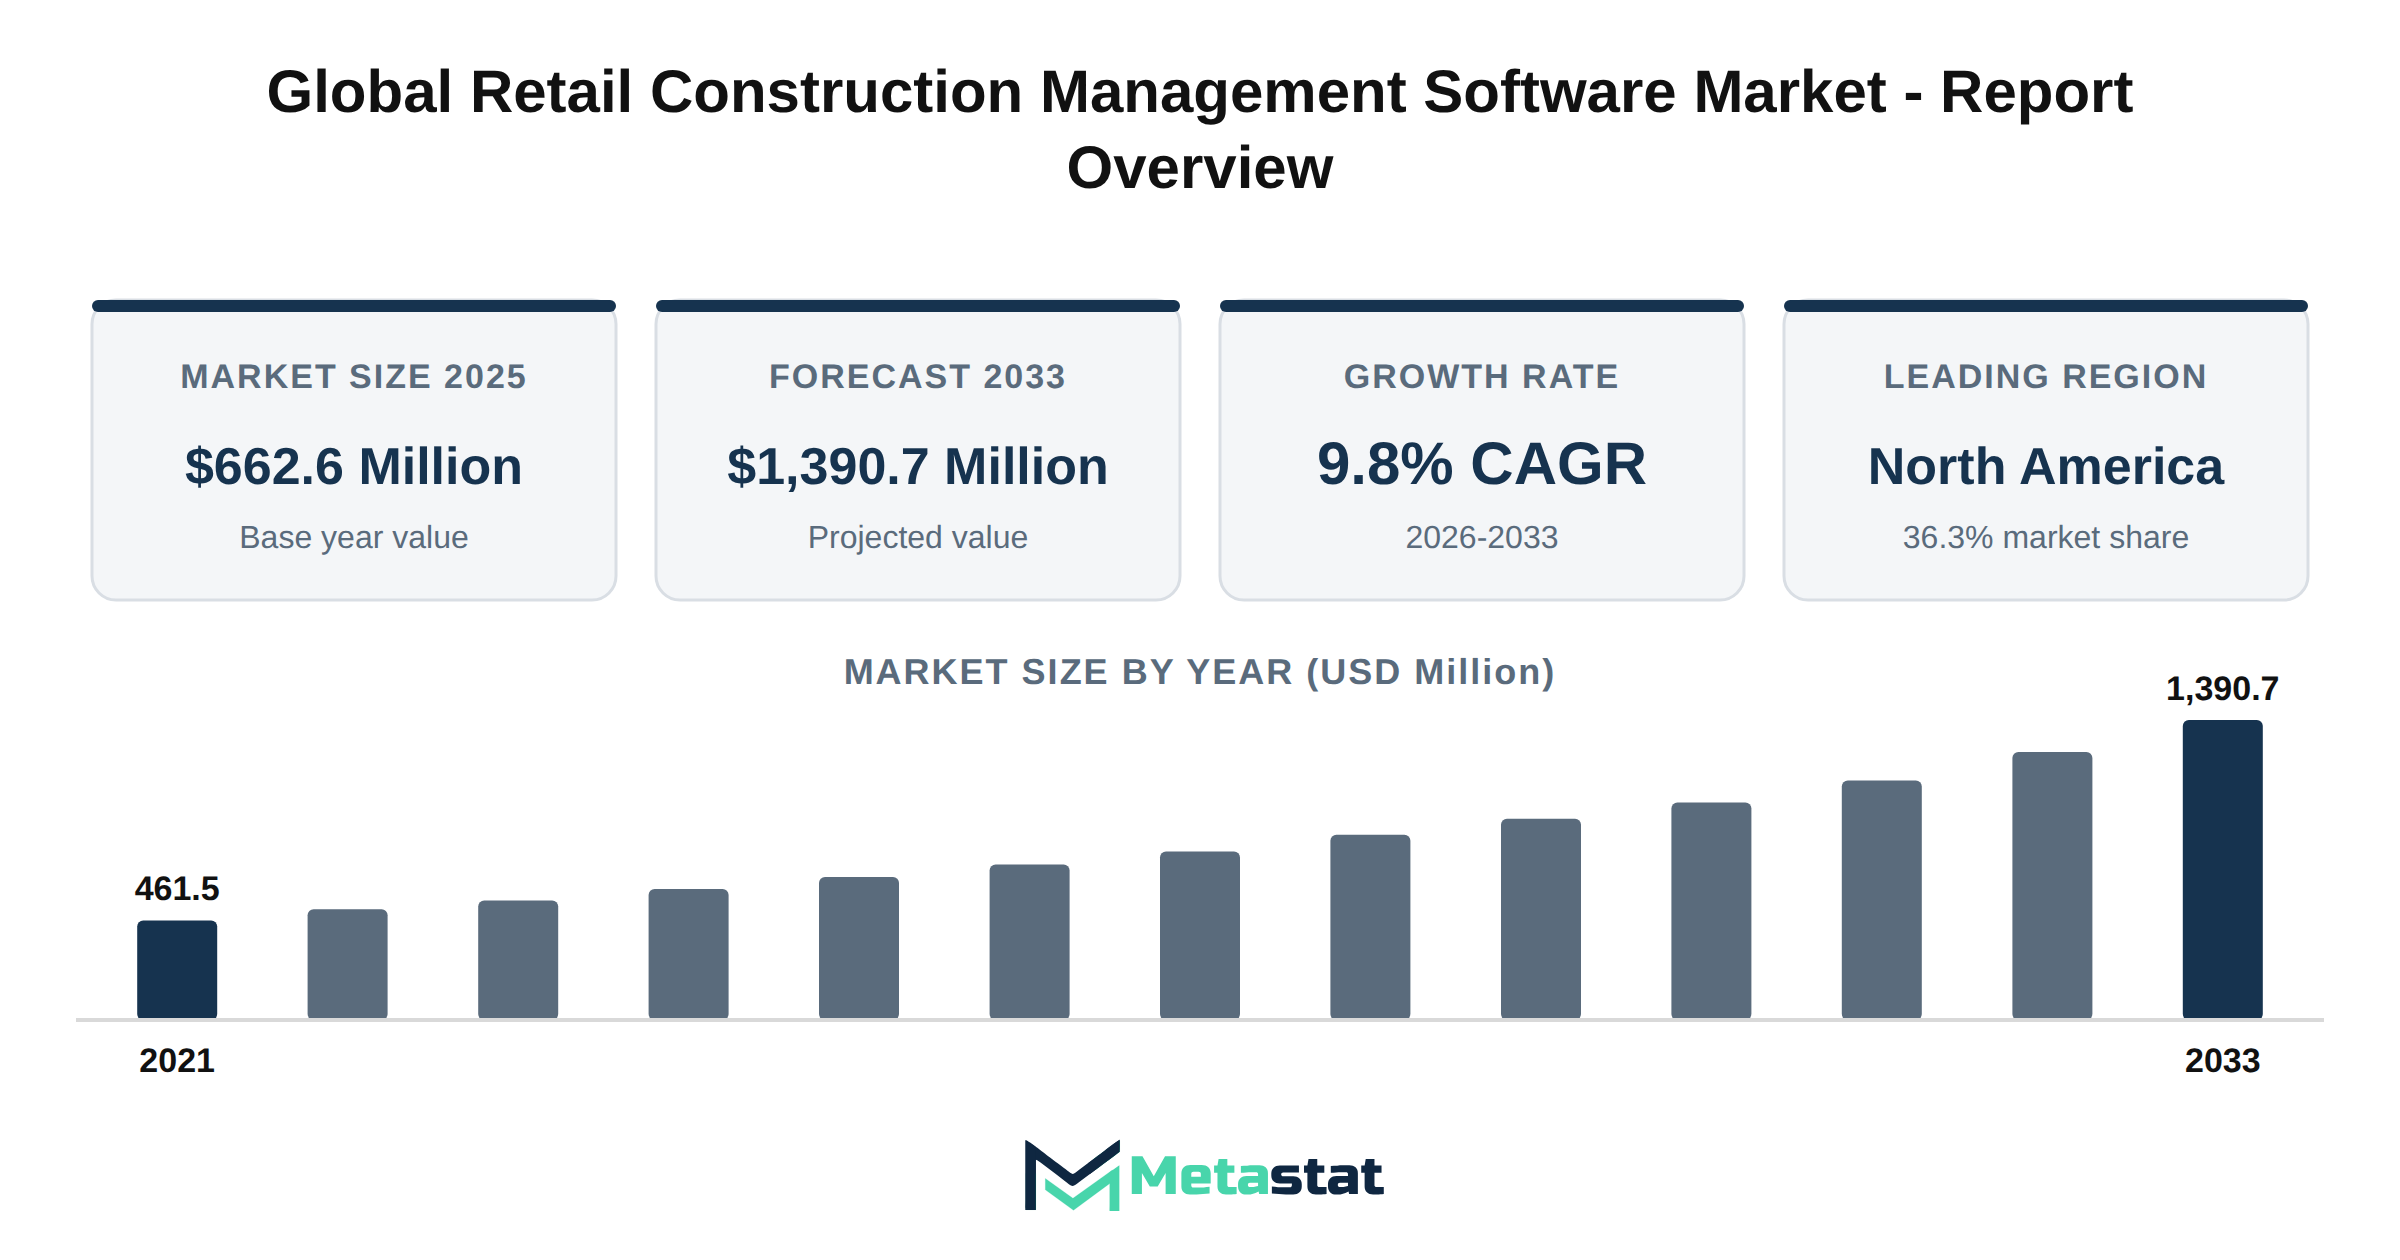
The Retail Construction Management Software market exhibited a base value of USD 662.6 million in 2025, with projections indicating growth to USD 1,390.7 million by 2033. This growth translates to a compound annual growth rate (CAGR) of 9.8% during the forecast period from 2026 to 2033.
Key demand drivers include the rapid expansion of cloud-based retail store buildout and remodeling platforms. These platforms improve project management and enhance collaboration among stakeholders in retail construction. The acceleration of digital transformation initiatives within the retail sector fuels this transition, prompting retailers to adopt advanced software solutions that improve efficiency and reduce costs.
Macroeconomic pressures, alongside shifts in commercial real estate dynamics, contribute to a growing emphasis on omnichannel retail expansion. Retailers face increasing competition and changing consumer preferences, necessitating the modernization of physical stores to provide effective customer experiences. The integration of digital construction workflows supports these efforts, enabling retailers to adapt quickly to market changes and consumer demands.
Omnichannel rollouts and the modernization of physical stores drive the adoption of digital construction workflows. Retailers prioritize efficient project planning, scheduling, and execution to meet the demands of an evolving market landscape. This shift encourages investment in technologies that enhance visibility and coordination among project teams, resulting in improved outcomes for retail construction projects.
Innovations in AI, predictive scheduling, and reality capture transform retail fit-out management. These technologies enhance project accuracy and efficiency, allowing retail chains to optimize resource allocation and reduce timelines. By leveraging advanced analytics and real-time data, retailers improve decision-making processes, driving overall project success.
The integration of Building Information Modeling (BIM), Digital Twins, and Internet of Things (IoT) technologies facilitates fast-track multi-store rollouts. These innovations enable retailers to visualize and simulate construction processes, leading to enhanced project planning and execution. The collaborative nature of these tools improves communication among stakeholders, enhancing project coordination and reducing delays.
Retail chains and specialty franchise fit-outs exhibit differing software adoption patterns and end-use demand. Larger enterprise retail chains invest significantly in comprehensive management solutions, while specialty franchise operators prioritize specific functionalities tailored to their unique operational needs. This divergence in software utilization highlights the importance of customizable solutions within the market.
Collaboration bottlenecks among retailers, contractors, and suppliers hinder effective project execution. Addressing these challenges requires the implementation of supply chain visibility solutions that facilitate communication and transparency throughout the construction process. Enhanced collaboration improves project timelines and outcomes, ultimately benefiting all stakeholders involved.
Regulatory compliance, sustainability mandates, and green building standards increasingly influence retail construction practices. Retailers actively seek software solutions that support adherence to these requirements, integrating environmentally friendly practices into their construction processes. This focus on sustainability enhances brand reputation and attracts environmentally conscious consumers.
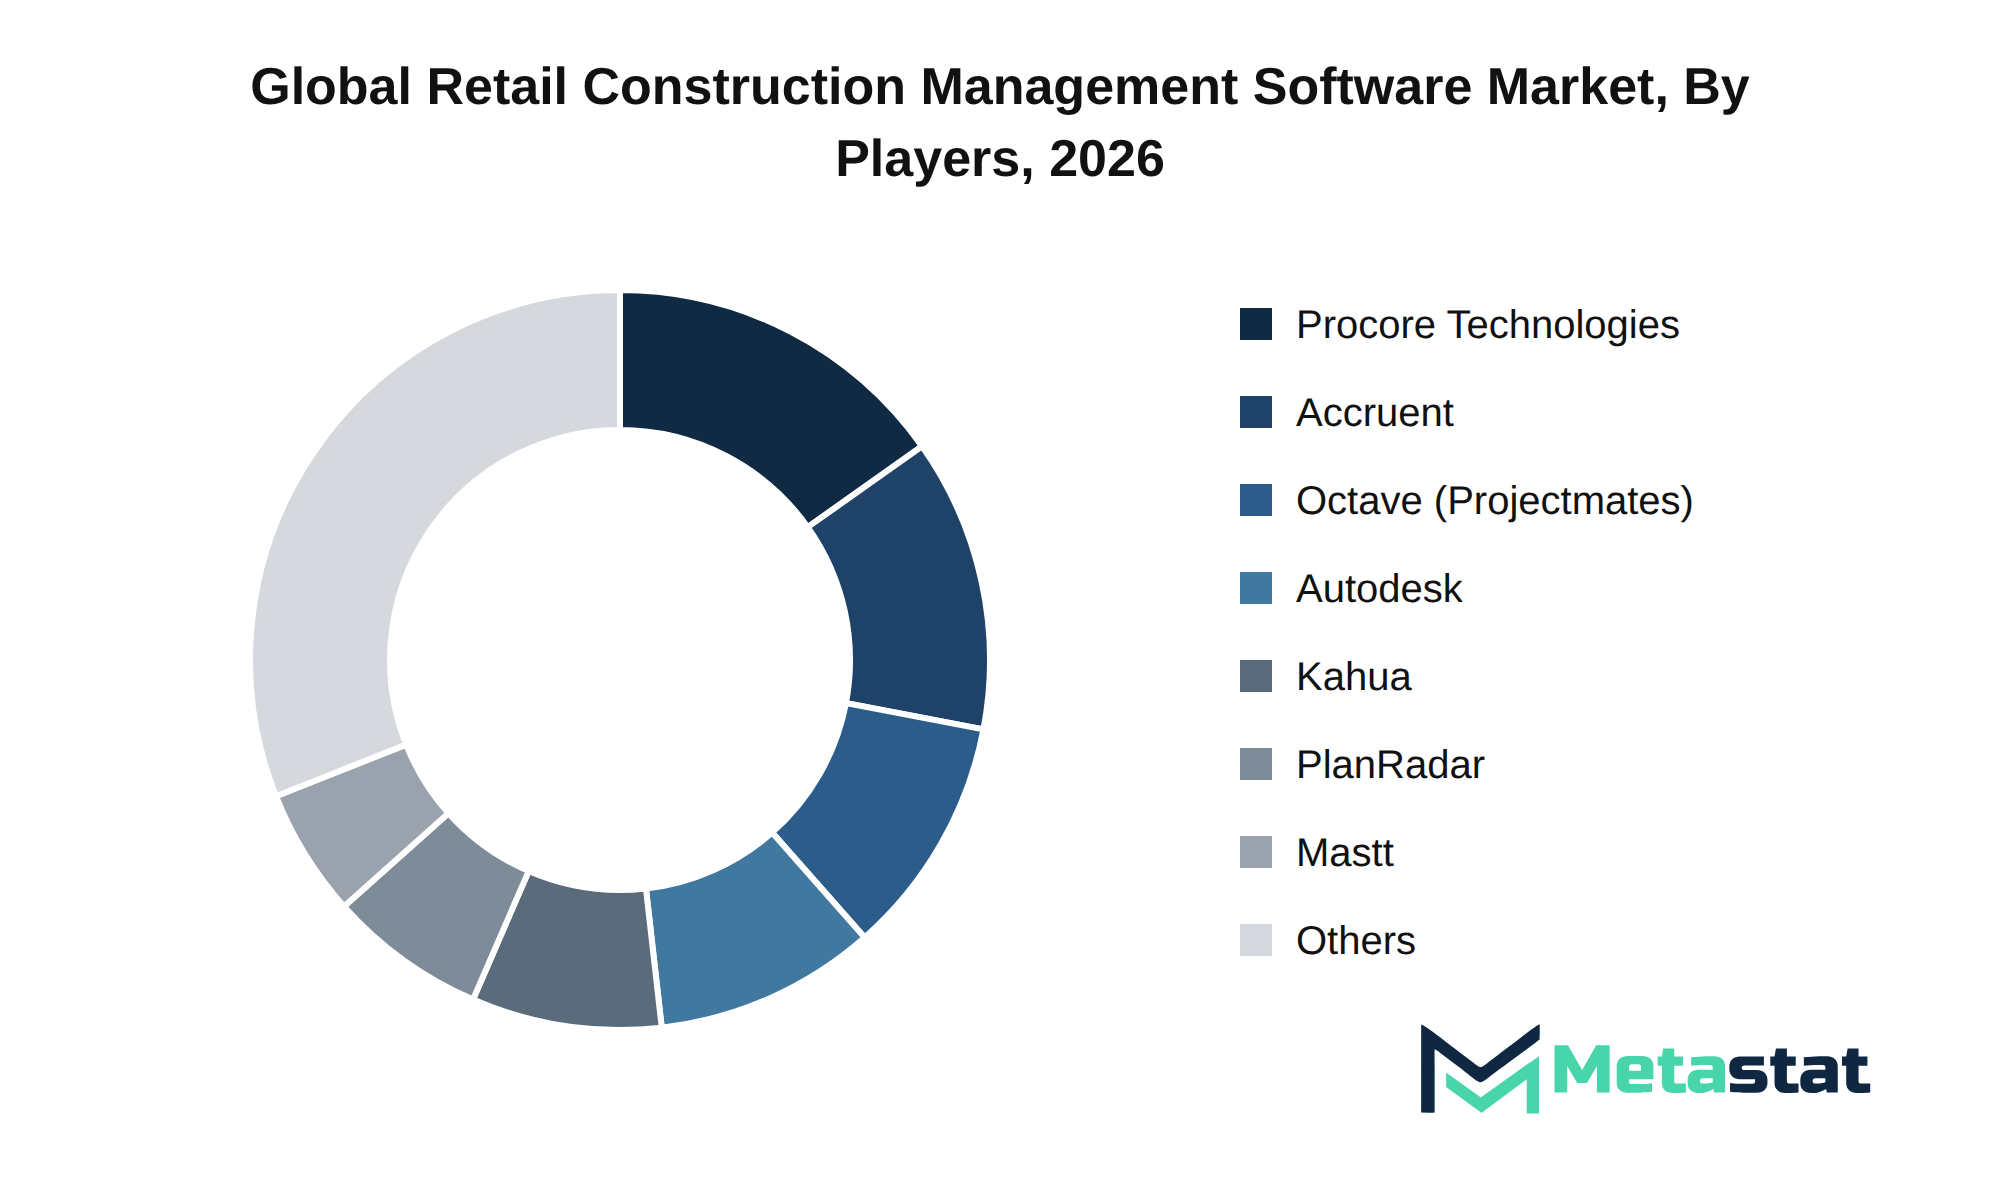
The competitive landscape of the Retail Construction Management Software market features several key players. Notable participants include Octave (Projectmates), Accruent, Eleco plc, Kahua, Inc., Procore Technologies, Inc., Mastt, PlanRadar GmbH, Autodesk, Inc., CIPO Cloud Software, Inc., Snaps Technologies Private Limited (Realx ERP), Netstech Software Solutions (Pvt.) Ltd, EMS Operations (UK) Ltd. (Archdesk), Oracle Corporation, STACK Construction Technologies, and Raken. These companies continuously innovate and consolidate their platforms to maintain competitive advantages in the market.
The ongoing expansion of the Retail Construction Management Software market aligns with the increasing demand for cloud-based platforms that facilitate retail store buildouts and renovations. Retailers adopt these solutions to streamline project management and enhance operational efficiency, particularly in response to the evolving nature of commercial real estate.
Macroeconomic pressures, including fluctuating consumer preferences and supply chain disruptions, significantly influence the market. The shift towards omnichannel retailing drives the need for modernized physical stores, necessitating advanced digital construction workflows that improve project delivery and reduce time-to-market.
Innovations in artificial intelligence, predictive scheduling, and reality capture technologies transform retail fit-out management. These advancements enable retailers to optimize resource allocation, enhance accuracy in project timelines, and improve collaboration among stakeholders, ultimately leading to more successful project outcomes.
The integration of Building Information Modeling (BIM), digital twins, and the Internet of Things (IoT) supports rapid multi-store rollouts. These technologies facilitate real-time data sharing and improve decision-making processes, allowing retailers to respond swiftly to market demands and operational challenges.
Different dynamics exist between enterprise retail chains and specialty franchise fit-outs regarding software adoption and end-use demand. Larger retail chains require comprehensive solutions that address their extensive project management needs, while franchise operators focus on tailored solutions suited to their specific operational models.
Collaboration bottlenecks between retailers, contractors, and suppliers hinder project efficiency, highlighting the necessity for enhanced supply chain visibility solutions. Addressing these challenges through effective software frameworks improves communication and coordination among all parties involved in the construction process.
Regulatory compliance, sustainability mandates, and green building standards increasingly shape the retail construction landscape. These factors compel retailers to adopt management software that aligns with environmental goals and regulatory requirements, driving demand for solutions that support sustainable practices.
The competitive landscape of the Retail Construction Management Software market features strategic consolidations among key players, driven by the need for integrated solutions. Mergers and acquisitions enhance product offerings and broaden market reach, positioning companies to capitalize on emerging opportunities.
Venture capital funding and private equity backing significantly influence market dynamics, with increasing investments directed towards innovative retail construction technologies. This financial support accelerates the development of advanced solutions, positioning firms to meet the growing demand for efficient and effective construction management.
Regional market performance shows high-growth opportunities across both developed and emerging retail hubs. While retailers continue to invest in infrastructure and expansion, the market anticipates growth driven by evolving consumer behaviors and technological advancements.
The long-term technology roadmap indicates significant potential for modular construction synergies and growth horizons extending beyond 2030. The retail sector's commitment to innovation and efficiency ensures sustained interest in advanced construction management solutions.
Increased investment in infrastructure and economic growth significantly influences the Retail Construction Management Software market. Capital investment environments, including GDP growth and venture funding, enhance the demand for efficient project management solutions. Businesses seek to optimize operations and reduce costs; the adoption of advanced software becomes essential for maintaining competitiveness in the evolving landscape.
Digital transformation initiatives push organizations to automate processes, integrate technology solutions, and digitize legacy systems. With growing pressure to enhance operational productivity and streamline workflows, businesses across various sectors increasingly rely on Retail Construction Management Software to achieve these objectives. Enhanced efficiency translates to improved profitability, driving further investments in software solutions.
The global shift towards sustainability and resource stewardship increases the need for software that supports environmental, social, and governance (ESG) mandates. Companies focusing on reducing their carbon footprint and modernizing their practices attract attention in the market. Consequently, software solutions that facilitate compliance with these initiatives gain traction.
Infrastructure development and asset modernization require sophisticated software tools to manage complex projects effectively. In regions experiencing rapid urbanization and demographic shifts, the demand for Retail Construction Management Software continues to rise. Organizations prioritize investments in technology to handle increased workloads and ensure project success in the dynamic construction environment.
Investment in infrastructure development drives the Retail Construction Management Software market. Growing public and private spending on infrastructure projects creates an environment conducive to software adoption. Increased capital allocation towards upgrading facilities and enhancing operational capabilities leads to higher demand for advanced software solutions that streamline project management processes and improve overall efficiency.
While regions focus on modernizing their infrastructure, construction firms seek solutions that support project planning, scheduling, and budgeting. These capabilities align with optimizing resources and enhancing operational productivity, particularly in competitive environments. The ongoing trend of digitizing legacy processes further complements this shift, driving the integration of cloud-based solutions and advanced analytics.
The growing emphasis on sustainability and ESG mandates encourages firms to adopt technologies that demonstrate efficient resource stewardship. This trend enhances compliance with safety standards and aligns with evolving consumer preferences for sustainable practices. With an anticipated compound annual growth rate of 9.8 percent, the market is projected to experience significant growth fueled by these infrastructure investments and the ongoing digital transformation in the construction sector.
The Retail Construction Management Software market faces significant restraints stemming from regulatory compliance challenges and high capital investment requirements. Regulatory environments vary widely across regions, creating hurdles that complicate software deployment for companies operating internationally. Compliance with differing standards incurs additional costs, delaying project timelines and increasing the financial burden on firms. These compliance hurdles lead to a decrease in the adoption rate of advanced software solutions that streamline construction management processes.
High capital investment requirements further complicate market dynamics. Many businesses encounter challenges in allocating sufficient budget for software procurement and implementation. The initial costs associated with deploying advanced construction management solutions deter smaller players from entering the market, resulting in reduced competition. This situation leads to market fragmentation, where a limited number of established providers dominate the market, stifling innovation and growth.
Inflationary pressures and macroeconomic headwinds exacerbate these challenges. Rising costs of materials and labor strain budgets, forcing companies to prioritize cost-cutting measures over software investments. In this economic climate, the focus shifts towards immediate operational resilience rather than long-term technological advancement. Consequently, the pace of digital transformation within the market slows, impacting overall growth potential.
The combination of regulatory compliance challenges, capital investment pressures, and macroeconomic factors creates a complex environment for the Retail Construction Management Software market. Addressing these restraints requires strategic planning and collaboration among stakeholders to create a more conducive landscape for software adoption and innovation.
The Retail Construction Management Software market confronts challenges due to geopolitical fragmentation and trade deficits, which disrupt supply chains and increase costs for manufacturers and suppliers. Trade tensions result in tariff friction, leading to higher prices for software and associated technologies. This situation complicates procurement processes for firms, impacting profitability and project timelines.
Technological disruptions introduce complexities in research and development integrations. Companies struggle to adapt new technologies while maintaining interoperability between existing systems and emerging solutions. Integration challenges lead to inefficiencies that affect project execution and overall market competitiveness.
Market participants face increased pressure from rising input costs and pricing compression, negatively impacting margins. Escalating prices for materials, labor, and logistics compound the financial burden on stakeholders in the retail construction sector. Talent retention pressures and workforce skill gaps hinder the ability of companies to leverage advanced software solutions effectively.
Environmental lifecycle footprints and decarbonization mandates impose new constraints on market operations. Firms navigate evolving sustainability demands while managing compliance overhead related to tightening global regulatory standards. These factors require substantial investment in upgrades and retrofitting, creating implementation bottlenecks that delay project delivery.
Finally, the Retail Construction Management Software market experiences instability due to cybersecurity risks and data vulnerabilities. The increasing prevalence of cyber threats necessitates robust protective measures, diverting resources from core business functions. Companies face heightened risks associated with intellectual property protection deficits, undermining competitive advantages in a crowded market.
Increased technological disruptions significantly enhance the Retail Construction Management Software market. Innovations including artificial intelligence, machine learning, and data analytics facilitate efficiencies in project planning and scheduling, driving demand across various segments. Retail chains and franchise operators increasingly adopt these technologies to streamline operations, improve budgeting, and enable cost management strategies. This growing reliance on technological integration aligns with trends in digital transformation and next-generation innovations.
Geographical expansion contributes to market growth, with regions including Asia Pacific and South America experiencing rising demands for advanced software solutions. The need for modernization of existing infrastructure and the implementation of eco-friendly practices influence investment in software that supports green transformations. Companies focused on sustainability imperatives and ESG-driven alignments gain competitive advantages by adopting solutions that optimize value chains and automate processes.
Evolving buying behaviors fuel a shift toward digital procurement models, prompting organizations to seek integrated solutions that cater to diverse applications. The presence of strategic consolidations and cross-industry mergers indicates a robust competitive environment within the market, driving innovation and enhancing service offerings. Overall, these emerging demands and disruptions provide extensive opportunities for growth in the Retail Construction Management Software market.
The Global Retail Construction Management Software market is segmented based on Project Type, Deployment, Application, and End User.
Valued at USD 347.9 million in 2026, the New Construction Projects segment is projected to reach USD 589.3 million by 2033, at a CAGR of 7.8% during the forecast period. Growth in this segment stems from rising demand for advanced construction methodologies and efficient project management tools. Retail construction increasingly emphasizes speed and cost efficiency, driving adoption of innovative software solutions that improve operations and enhance collaboration among stakeholders. Technological maturation, particularly in cloud-based platforms, supports the transition from traditional methods to digital solutions, increasing productivity and reducing delays in project delivery.
Investment in next-generation upgrades facilitates integration of data analytics and real-time reporting, allowing stakeholders to make informed decisions throughout the project lifecycle. The industry's focus on sustainability and regulatory compliance standards shapes the development of features that align with eco-friendly practices, thereby attracting environmentally conscious consumers and investors. The increasing complexity of construction projects necessitates robust management tools that address diverse project needs, increasing overall demand within the Retail Construction Management Software market.
Certain end-users, including retail chains and franchise operators, prioritize efficient management of new construction projects to maximize returns on investment. Competitive pressures compel firms to adopt innovative technologies that differentiate their offerings and enhance customer satisfaction. The segment's growth reflects a strategic opportunity window for software providers to expand their portfolios and cater to evolving market requirements, ultimately improving their position in the competitive environment.
Growing interest in urban revitalization and sustainable development drives demand for renovation and retrofit projects, contributing to increased investments in existing infrastructures. This segment benefits from changing consumer preferences, focusing on upgrading and repurposing older buildings rather than new constructions. Enhanced emphasis on sustainability underlines the importance of energy-efficient renovations, aligning with regulatory compliance standards that promote environmentally friendly practices. Companies prioritize software solutions that streamline project planning and management processes, ensuring timely completion and compliance with evolving regulations.
Adoption of advanced technologies, including Building Information Modeling (BIM) and project management tools, supports the effective execution of renovation and retrofit projects. These innovations enhance collaboration among stakeholders and improve accuracy in budgeting and scheduling. Such technologies facilitate real-time data sharing and informed decision-making, thus optimizing project outcomes. Increased competition among suppliers drives product evolution, offering robust solutions tailored for the unique needs of renovation projects.
The Renovation & Retrofit Projects segment is projected to reach USD 543.8 million by 2033, at a CAGR of 11.8% during the forecast period. The focus on improving existing structures rather than new builds positions this segment favorably within the Retail Construction Management Software market. Increased demand for customized solutions that address specific project challenges ensures ongoing growth, making this segment an essential area for investment and development within the overall market.
Investment in maintenance and facility upgrades continues to grow, reflecting an increasing recognition of the importance of sustaining operational efficiency within retail environments. Several factors drive this demand, including a rising emphasis on asset longevity and compliance with evolving regulatory standards. Retail chains and franchise operators increasingly prioritize upgrades and maintenance to enhance customer experiences and optimize store performance.
Technological advancements play a significant role in this segment, enabling more effective management of maintenance schedules and facility operations. The integration of sophisticated software solutions allows for improved tracking of asset conditions and timely interventions. Consequently, this trend reinforces the market's expansion. The Maintenance & Facility Upgrades segment is projected to reach USD 257.5 million by 2033.
Changing consumer preferences influence facility upgrades, compelling retailers to adapt spaces that align with modern shopping behaviors. Enhanced aesthetic appeal and functionality attract customers and support compliance with sustainability initiatives, further driving investment in upgrades. The competitive nature of the retail sector fuels ongoing enhancements, driven by businesses seeking to differentiate themselves through superior facility management.
The Maintenance & Facility Upgrades segment within the Retail Construction Management Software market experiences growth fueled by technological maturation, regulatory compliance, and evolving consumer demands. These factors collectively contribute to the segment's trajectory, positioning it because a vital component of overall market dynamics.
Valued at USD 528.5 million in 2026, the cloud-based segment is projected to reach USD 1,179.9 million by 2033, at a CAGR of 12.2% during the forecast period. The shift toward cloud-based solutions reflects a broader trend in various industries prioritizing flexibility, scalability, and cost-effectiveness. Retail chains and franchise operators increasingly adopt these solutions owing to their ability to facilitate real-time data access and enhance collaboration across teams.
Technological maturation drives the growth of this segment. Continuous advancements in cloud technology enable enhanced capabilities, including improved analytics, automation, and integrated project management. This evolution allows users to streamline operations, reduce manual errors, and improve overall project efficiency, making cloud solutions more attractive within the market.
Next-generation upgrades further stimulate demand, driven by suppliers introducing innovative features that cater to industry-specific needs. Enhanced security measures, compliance with regulatory standards, and advanced data management functionalities contribute to the appeal of cloud-based platforms. Such characteristics attract a wide range of end users, including general contractors and construction project management firms, who seek effective tools to manage complex projects.
Shifts in consumption patterns indicate a growing preference for subscription-based pricing models, which allow users to access the latest features without significant upfront investments. This trend supports wider adoption among small to medium-sized enterprises that previously avoided investing in comprehensive software solutions. Consequently, the cloud-based segment is well-positioned for sustained growth within the Retail Construction Management Software market.
Growth in the on-premise segment of the Retail Construction Management Software market is driven by organizations prioritizing data security and control over their systems. Many businesses, particularly in the retail sector, favor on-premise solutions for sensitive data management. This preference stems from regulatory compliance requirements and the need for customized software solutions tailored to specific operational workflows.
Market dynamics illustrate a gradual shift in investment toward on-premise software, reflecting the desire for enhanced control and integration with existing systems. Although cloud-based solutions dominate the discourse, the on-premise segment continues to attract interest due to its reliability and security features. The segment is projected to reach USD 210.8 million by 2033, registering a CAGR of 1.3% during the forecast period.
Technological maturation within the on-premise segment encourages investment in next-generation upgrades to improve functionality and user experience. Demand from end users, particularly general contractors and construction project management firms, enhances the segment’s growth. This segment's evolution aligns with the broader trend of digital transformation in the construction sector, capitalizing on strategic opportunities to address specific market needs.
Valued at USD 166.7 million in 2026, the Project Planning and Scheduling segment is projected to reach USD 334 million by 2033, at a CAGR of 10.4% during the forecast period. Demand drivers for this segment stem from the increasing complexity of construction projects and the necessity for enhanced coordination among various stakeholders, including contractors and subcontractors. Adoption of advanced software solutions facilitates streamlined project management processes, optimizing resource allocation and scheduling accuracy.
Technological maturation further accelerates growth within this segment, driven by innovations in cloud computing and mobile applications that enhance accessibility and collaboration in project planning. The emergence of next-generation upgrades, including artificial intelligence and machine learning, improves data-driven decision-making and predictive analytics, significantly improving project outcomes. Increased focus on regulatory compliance and adherence to industry standards drives organizations to invest in robust project management tools that ensure efficient planning and scheduling.
End-user dynamics highlight the growing reliance of retail chains and franchise operators on effective project planning and scheduling solutions. Enhanced visibility into project timelines and budgets allows these organizations to manage costs effectively while maximizing project efficiency. While the market expands, strategic investments in project planning and scheduling software will provide organizations with a competitive edge, enabling them to navigate the complexities of the retail construction management landscape effectively.
Growing emphasis on financial efficiency and project cost control drives demand for advanced solutions within the Budgeting and Cost Management segment of the Retail Construction Management Software market. This focus stems from rising project costs and the necessity for accurate budgeting, leading firms to seek innovative software to streamline financial operations. The integration of real-time data analytics enhances decision-making processes, allowing for more precise budgeting and cost management. The segment benefits from ongoing technological maturation, with software providers continuously enhancing features and usability.
Investments in next-generation upgrades significantly impact this segment, allowing for functionalities that cater to evolving market needs. User-friendly interfaces and cloud-based deployment options facilitate accessibility and collaboration among stakeholders, increasing adoption rates. While the market progresses, regulatory compliance standards around financial reporting and transparency exert additional pressure on businesses to adopt robust budgeting solutions, further propelling market growth.
The Budgeting and Cost Management segment is projected to reach USD 249.5 million by 2033, at a CAGR of 10.3% during the forecast period. This growth reflects the increasing need for detailed financial oversight and strategic cost control mechanisms in construction projects. Enhanced functionalities and capabilities of budgeting tools are expected to improve project outcomes and contribute positively to overall market expansion.
Growing emphasis on efficient information management fuels demand for solutions in the Document Management segment of the Retail Construction Management Software market. Organizations increasingly recognize the importance of streamlined document handling, especially in construction projects where accuracy and timeliness are critical. With the segment expected to reach USD 183.6 million by 2033, the focus shifts towards integrating advanced technologies that enhance functionality, improve user experience, and facilitate collaboration among teams.
Technological maturation, including advancements in cloud storage and mobile access, contributes to the segment's growth by offering scalable solutions that adapt to varying organizational sizes and complexities. Enhanced accessibility and real-time updates to documents enable stakeholders to make informed decisions swiftly. Increased regulatory compliance requirements across the construction sector further drive adoption, because companies seek solutions that ensure adherence to local and international standards.
Investment in innovative features, including automated workflows and advanced analytics, strengthens the Document Management segment's appeal. These next-generation upgrades support efficient project execution, reduce manual errors, and enhance overall productivity. The ongoing evolution of these applications aligns with broader trends in the Retail Construction Management Software market, where digital transformation is reshaping operations and driving demand for integrated solutions.
Investment in Bid and Tender Management solutions optimizes procurement processes within the Retail Construction Management Software market. Organizations recognize the importance of efficient bidding and tendering, which directly impacts project timelines and costs. Enhanced functionality in this segment allows users to streamline workflows, improve collaboration among stakeholders, and enable better decision-making. Current trends highlight a growing emphasis on automation and digital tools, which enhance the accuracy and speed of bid submissions.
Valued at USD 0 million in 2033, the Bid and Tender Management segment is projected to grow at a CAGR of 7.9% during the forecast period. Adoption of cloud-based solutions enhances accessibility and flexibility, allowing teams to manage bids from various locations while ensuring real-time updates. This shift toward digital platforms aligns with the broader trend of technological maturation within the market, driving innovation and supporting the evolution of product offerings.
Increased regulatory compliance requirements further drive demand for sophisticated Bid and Tender Management tools. Organizations actively seek software solutions that facilitate adherence to these standards while maintaining competitive advantages in the bidding process. The ongoing evolution in this segment presents strategic opportunity windows for suppliers, allowing them to capture a larger share of the growing market.
In the context of the Retail Construction Management Software market, the Contractor and Vendor Management application segment plays a critical role in enhancing project efficiency and collaboration among various stakeholders. This segment experiences increasing demand driven by the necessity for streamlined communication and effective management of subcontractors and suppliers.
Technological advancements significantly influence the evolution of Contractor and Vendor Management tools, incorporating features including automated workflows, real-time tracking, and analytics. These innovations facilitate improved decision-making processes and strengthen relationships between contractors, vendors, and project owners.
Adoption of these tools has accelerated, particularly among retail chains and franchise operators, who prioritize project timelines and budget adherence. This trend reflects a broader market movement toward digital transformation, where organizations implement integrated solutions to optimize their construction processes.
Regulatory compliance continues to shape the functionality of Contractor and Vendor Management applications. Increasing standards and certifications in the construction sector demand robust monitoring and reporting capabilities, compelling firms to invest in sophisticated software that ensures adherence to legal requirements.
Cost structures within this segment reflect investments in technology and training necessary for maximizing the benefits of Contractor and Vendor Management solutions. Organizations navigate pricing volatility while managing ongoing developments in software capabilities and market competition.
Strategic opportunity windows emerge from the growing emphasis on supply chain resilience and the need for effective vendor management due to market fluctuations. Firms that capitalize on these opportunities position themselves favorably within the competitive landscape of the Retail Construction Management Software market.
Strong emphasis on field reporting and site coordination enhances project management efficiency within the Retail Construction Management Software market. Accurate and timely reporting improves decision-making for contractors and project managers, addressing challenges related to communication and data capture on construction sites. Integration of mobile technologies enables real-time updates, improving site coordination and enhancing collaboration across teams.
Technological maturation contributes to the advancement of field reporting tools, introducing features including automated reporting, drone imaging, and IoT integration. These innovations support effective data collection and analysis, allowing stakeholders to monitor project progress and resolve issues swiftly. Adoption of cloud-based platforms ensures that data is accessible from any location, further enhancing the operational effectiveness of teams engaged in construction projects.
Increased focus on regulatory compliance and safety standards drives the integration of robust reporting mechanisms within construction management software. Compliance with safety regulations necessitates thorough documentation and reporting, reinforcing the importance of effective field reporting solutions. Enhanced reporting capabilities lead to improved accountability and transparency, essential for maintaining trust among stakeholders in the market.
The market benefits from strategic investments in upgrading field reporting and site coordination tools, driven by companies striving to improve their project delivery capabilities. Continuous development of user-friendly interfaces and advanced analytics features plays a critical role in capturing user interest and enhancing adoption rates. Consequently, effective field reporting and site coordination emerge because key components in driving overall success in the Retail Construction Management Software market.
Demand for applications classified under the Others category within the Retail Construction Management Software market stems from a variety of specialized functions tailored to meet unique business requirements. These applications enhance operational efficiency by addressing specific workflows, often filling gaps not covered by mainstream solutions. Companies in the retail sector increasingly seek customized tools to streamline processes including contractor and vendor management, field reporting, and site coordination, generating interest in this segment.
Adoption of innovative technologies drives development of next-generation applications that integrate advanced features, facilitating real-time data access and improved project visibility. Such enhancements support the shift towards more agile construction management practices, where flexibility and responsiveness are critical. While organizations prioritize digital transformation, demand for these tailored applications strengthens, further propelling market growth.
End-user dynamics significantly influence the market, with retail chains and franchise operators driving demand for customized solutions. These entities navigate unique project demands, requiring tools that address specific operational challenges. Consequently, the development of specialized applications creates a strategic opportunity window, allowing suppliers to capture market share within niche areas while responding to evolving customer needs.
Regulatory compliance standards and certifications shape the competitive environment, ensuring that solutions meet industry benchmarks. Companies focusing on these applications adapt to evolving regulations, supporting ongoing product evolution. This adaptability enhances the market's resilience against technological obsolescence, strengthening the growth potential of the Others sub-segment.
Retail Chains and Franchise Operators represent a key segment within the Retail Construction Management Software market, valued at USD 303.1 million in 2026 and projected to reach USD 563.7 million by 2033, at a CAGR of 9.3% during the forecast period. Demand for advanced construction management solutions among retail operators hinges on the necessity for efficient project execution, budget adherence, and timely completion of renovations across multiple locations.
Investment in technology that facilitates project planning and scheduling, along with budgeting and cost management, remains crucial for retail chains aiming to streamline operations. Current trends indicate a shift towards cloud-based deployment, providing operators with scalable solutions compatible with their dynamic requirements. Enhanced collaboration and visibility across projects support the strategic objectives of these end users, enabling adaptation to changing market conditions.
Regulatory compliance standards related to safety and environmental impact drive the adoption of sophisticated construction management software. Retail chains recognize the significance of leveraging technology to ensure compliance while maintaining operational efficiency. The retail construction landscape evolves, with firms focusing on long-term sustainability and adaptability to achieve competitive advantages in the market.
Valued at USD 303.1 million in 2026, the General Contractors segment is estimated to reach USD 219.6 million by 2033, at a CAGR of 8% during the forecast period. Demand for Retail Construction Management Software among general contractors stems from the increasing complexity of construction projects and the need for enhanced collaboration and communication among stakeholders. Robust software solutions facilitate project tracking, resource management, and cost control, ensuring adherence to timelines and budgets.
Technological advancements drive adoption within this segment, driven by general contractors prioritizing cloud-based solutions that offer scalability and remote accessibility. The trend toward digital transformation in construction enhances operational efficiency and supports real-time decision-making. This shift aligns with broader industry efforts to embrace automation and data analytics, enabling contractors to optimize processes and reduce waste.
End-use dynamics reflect a heightened focus on compliance with safety and quality standards, compelling general contractors to invest in software that includes features for regulatory adherence and reporting. Integration of these compliance functionalities into Retail Construction Management Software becomes a crucial factor for contractors looking to mitigate risks and avoid penalties.
Cost structures present a noteworthy challenge, particularly with fluctuating material prices and labor costs. General contractors increasingly seek software solutions that provide accurate budgeting and forecasting tools, helping them navigate pricing volatility effectively. This focus on financial management drives demand for specific applications within the software that cater to contractor requirements.
While the market evolves, strategic opportunity windows emerge, particularly for software providers incorporating advanced technologies including artificial intelligence and machine learning. These innovations promise to enhance project outcomes and reduce operational inefficiencies, positioning general contractors to capitalize on emerging trends within the Retail Construction Management Software market.
Investment in advanced digital solutions particularly influences the growth of Construction Project Management Firms within the Retail Construction Management Software market. These firms increasingly adopt software that enhances project tracking, scheduling, and resource allocation, driving efficiencies across varied project types. The integration of cloud-based solutions allows for real-time collaboration, significantly improving project outcomes. Demand for effective deployment in this sector aligns with a broader trend toward digital transformation in construction management.
By 2033, the Construction Project Management Firms segment is expected to reach USD 242 million. This growth stems from a heightened focus on budget management and cost control among these firms, driven by the optimize operational workflows and reduce project overruns. Given the competitive landscape, firms increasingly prioritize technology investments that align with strategic objectives, creating a culture of continuous improvement and innovation.
Regulatory compliance requirements further contribute to software adoption in this segment. Firms face increasing pressures to adhere to safety and quality standards, prompting investments in solutions that streamline compliance tracking and reporting. The successful navigation of these regulatory landscapes enhances operational resilience and positions firms favorably within the market.
Continuous advancements in technology drive product evolution, compelling firms to upgrade existing systems and implement next-generation solutions. The need for integration with other business processes highlights a strategic opportunity window for software providers. While firms strive to remain competitive in a changing market, the emphasis on adopting innovative tools and methodologies ensures a sustained growth trajectory within the Construction Project Management Firms segment.
Investment in technology solutions enhances operational efficiency for Real Estate Developers, driving demand for Retail Construction Management Software. This segment is projected to grow at a CAGR of 9.4% during the forecast period, reflecting a continuous shift towards sophisticated project management tools that improve construction processes.
The growing complexity of real estate projects compels developers to adopt advanced software that integrates various functions, including budgeting, scheduling, and documentation. Enhanced regulatory compliance standards further influence adoption, prompting developers to seek solutions that ensure adherence to local regulations while minimizing risks associated with non-compliance.
Technological maturation shapes the product landscape, with developers gravitating towards cloud-based platforms that facilitate collaboration and real-time data access. The shift to digital solutions addresses the demand for enhanced project visibility, allowing developers to make informed decisions throughout the construction lifecycle.
Investment in next-generation upgrades ensures that developers remain competitive in a market that evolves quickly. While stakeholders seek to enhance their technological capabilities, solutions that offer integration with existing systems emerge because critical differentiators. The Retail Construction Management Software market sees notable growth in demand from developers focused on maximizing their operational efficiencies and minimizing project delays.
While the real estate sector recovers from economic fluctuations, increased capital investments in construction projects contribute to the expansion of this segment. Real Estate Developers prioritize tools that optimize resource allocation and improve project outcomes, reinforcing the importance of effective project management software in achieving strategic objectives.
Investment in innovative digital solutions significantly influences the demand dynamics within the Others sub-segment of the Retail Construction Management Software market. Organizations increasingly recognize the importance of maximizing efficiency and control over various operational processes. This recognition drives the adoption of software solutions that enhance performance through improved project management capabilities and integrated functionalities.
Technological advancements play a crucial role in enhancing the capabilities of the software, enabling users to better manage complexities associated with diverse construction projects. The shift towards technology-driven processes encourages end users beyond traditional sectors, allowing for greater customization and adaptability in addressing unique challenges encountered in construction management.
The demand for compliance with regulatory standards contributes to the growth of solutions within this sub-segment. Organizations increasingly emphasize adherence to industry regulations and certifications, necessitating sophisticated tools that ensure operational integrity and accountability. This trend generates continuous investment opportunities, driving market evolution and expansion.
Engagement with emerging trends, including sustainability practices and resource optimization, further shapes consumption patterns in the market. Companies seek to align their operations with sustainable practices, promoting a shift towards software solutions that facilitate environmental and resource efficiency. This alignment supports corporate responsibility and enhances competitive positioning within the broader construction landscape.
The Others sub-segment reflects a dynamic combination of demand drivers, technological maturation, and regulatory compliance needs, leading to robust evolution within the Retail Construction Management Software market.
Based on geography, the Global Retail Construction Management Software market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
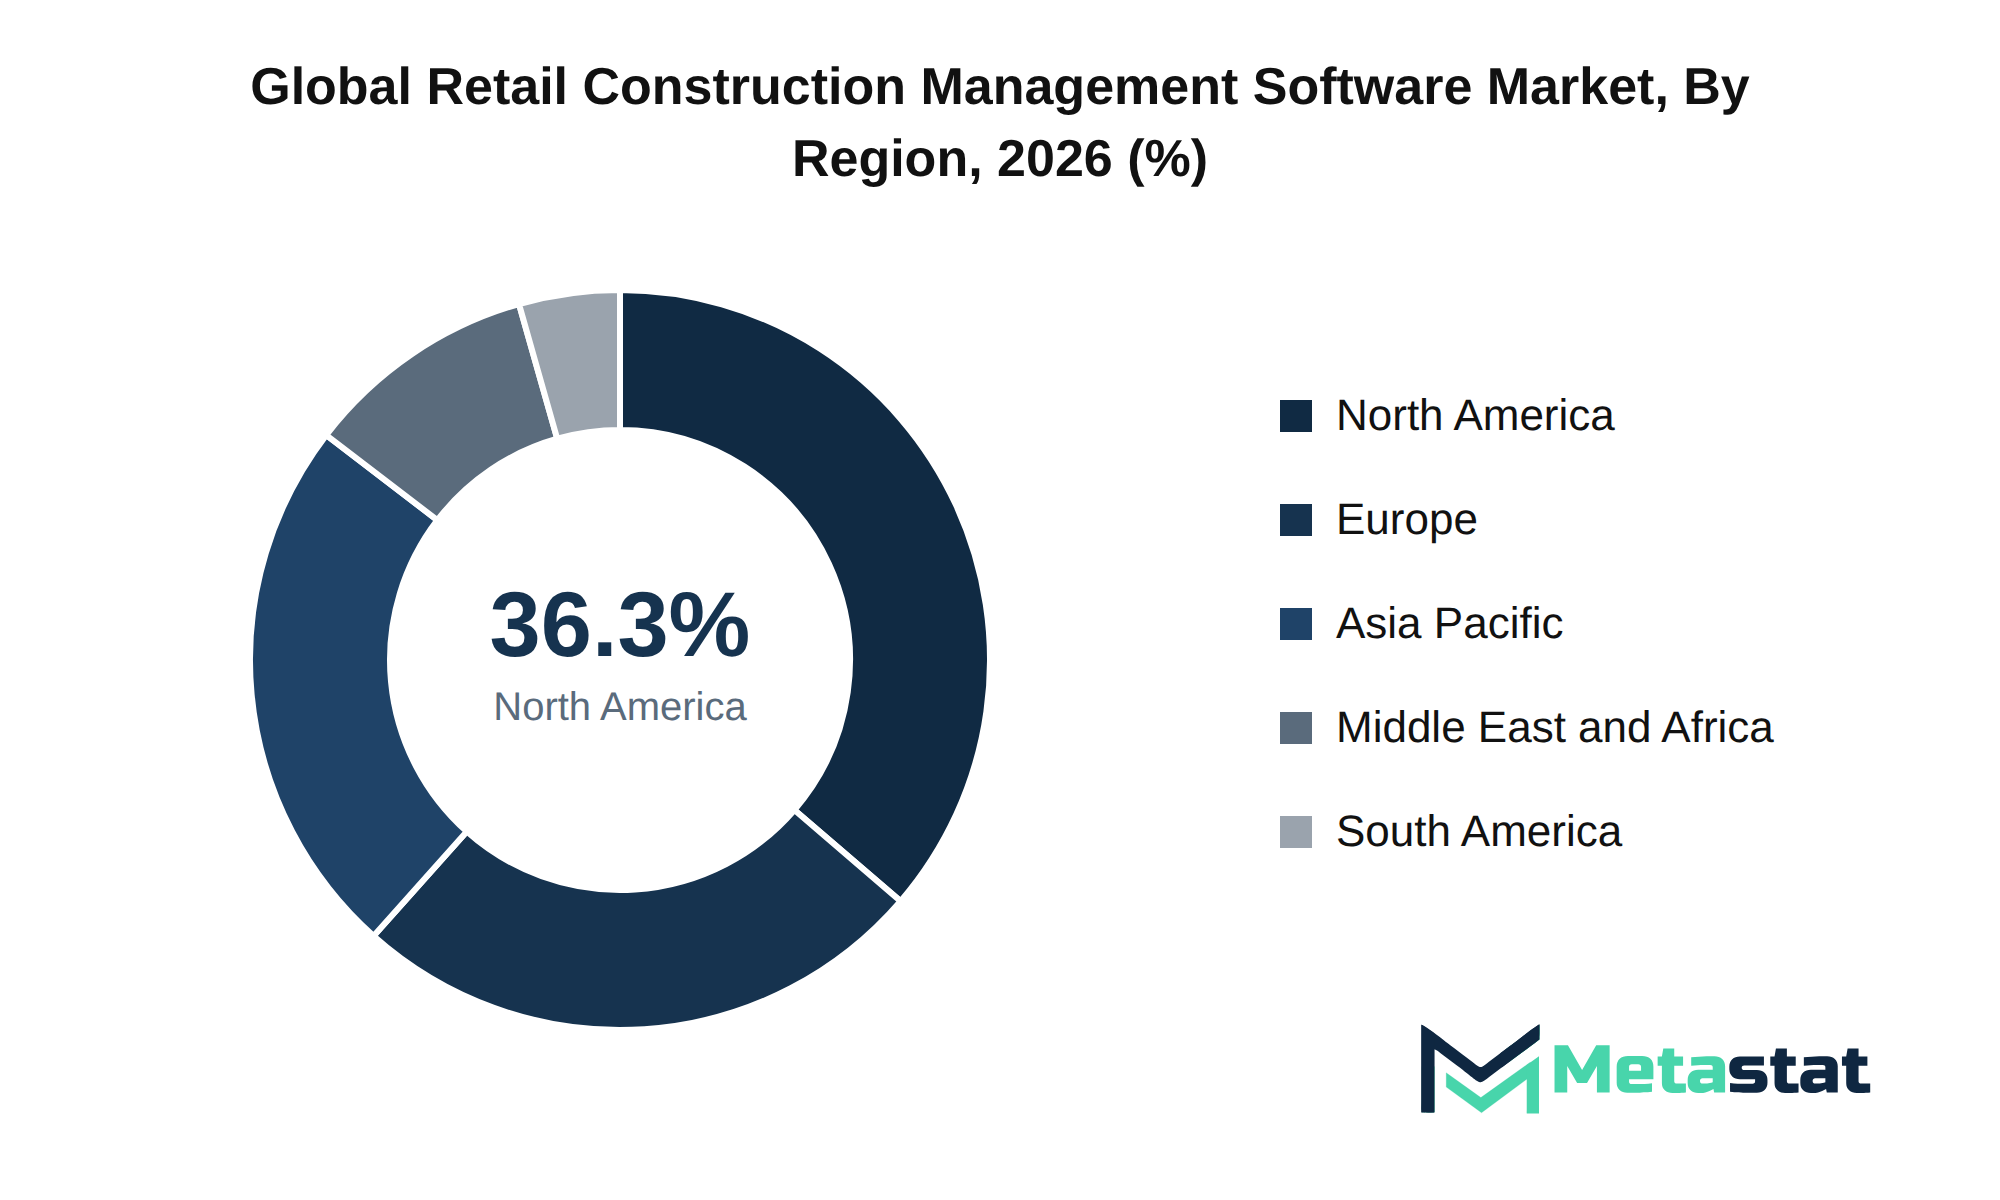
North America represents a significant portion of the Retail Construction Management Software market, accounting for 36.3% of the global market in 2025. The market is set to expand at a CAGR of 9.8% within the forecast period, reaching a market size (TAM) of USD 429.3 million by the end of 2033. Factors contributing to this growth include increasing investment in cloud-based solutions and a rising need among retail chains and franchise operators for enhanced project management tools.
Infrastructure modernization within the region drives adoption rates. Local compliance mandates and regulatory frameworks facilitate the implementation of advanced software solutions, ensuring that companies meet necessary requirements. Localized procurement dynamics influence purchasing decisions, leading to a preference for software that addresses specific regional challenges.
Emerging market front-runners, particularly in the United States, highlight the potential for significant growth in the Retail Construction Management Software market. Companies actively engage in nearshoring initiatives, aiming to optimize supply chains and reduce operational risks. This shift towards localized manufacturing densities not only enhances regional competitiveness but stimulates demand for effective construction management solutions.
Investment in technology solutions, including budgeting and cost management applications, supports incremental growth vectors within the market. The presence of domestic market leaders creates a competitive landscape that drives innovation and attracts new entrants. Strategic entry barriers within North America further define the market, shaping the dynamics of vendor consolidation trends because companies seek to leverage existing resources and capabilities.
With a projected share of 25.3% in 2025, Europe represents a significant portion of the Retail Construction Management Software market. The region benefits from robust demand driven by increased investments in infrastructure modernization and digital transformation. Countries including Germany, France, and the UK lead in adoption rates, focusing on integrating advanced solutions to enhance project efficiency and ensure compliance with local regulations.
Regional competitive landscapes feature a mix of established players and emerging vendors. This dynamic encourages innovation and collaboration, addressing unique regional requirements. Factors including localized procurement dynamics and cultural nuances shape B2B buying behaviors, ensuring solutions align with market expectations.
Infrastructure readiness in Europe supports market growth, particularly in urban areas experiencing significant development. Investments in energy grid resiliency and strategic entry barriers create an environment conducive to expansion. While companies increasingly prioritize operational efficiency, demand for Retail Construction Management Software is expected to strengthen, driven by the optimization of resource utilization and enhanced project delivery timelines.
Asia-Pacific represents a significant market for Retail Construction Management Software. This region demonstrates strong growth potential driven by rapid urbanization and infrastructure development across key countries including China, India, and Japan. Large-scale construction projects and ongoing renovations in urban areas enhance the demand for advanced management software solutions, resulting in increased operational efficiency and cost control.
The adoption of cloud-based deployment models significantly improves access to innovative tools for project management. Countries including South Korea and Australia leverage these technologies to enhance efficiency and collaboration among project stakeholders. Enhanced project planning and scheduling capabilities support the needs of various end users, including retail chains and franchise operators, who seek streamlined operational processes, thereby reinforcing their competitive position in the market.
Challenges related to local compliance and regulatory frameworks further shape the market dynamics in Asia-Pacific. Geopolitical considerations influence cross-border trade and supply chain strategies, affecting software procurement and implementation decisions. Domestic players continually adapt to meet the specific demands of regional clients, creating a competitive landscape characterized by ongoing vendor consolidation and partnerships that enhance market reach.
Infrastructure modernization initiatives across the region drive incremental growth vectors within the market. Emerging markets in Southeast Asia demonstrate underpenetrated territories where construction management software solutions present opportunities for expansion. By focusing on localized procurement dynamics and cultural nuances, suppliers effectively address the unique requirements of this diverse market, supporting long-term growth and adoption.
The Retail Construction Management Software market in South America presents a unique landscape characterized by growing investment in infrastructure modernization and digital transformation. Countries including Brazil and Argentina lead in adopting innovative software solutions to enhance project efficiency and streamline operations. The market benefits from a significant push towards localized procurement dynamics, with businesses increasingly seeking tailored solutions that address specific regional challenges.
In Brazil, a strong emphasis on sustainable construction practices and compliance with local regulations supports market growth. Argentina experiences similar trends, focusing on improving project management capabilities amid economic fluctuations. The Rest of South America is gradually adopting retail construction management solutions, highlighting an opportunity for increased market penetration.
Investment in cloud-based deployments significantly influences the competitive landscape, allowing organizations to leverage scalable solutions that accommodate varying project needs. Anticipated market growth aligns with ongoing efforts towards supply chain regionalization and foreign direct investment flows, creating an environment conducive to technological advancement.
The Middle East and Africa region accounts for several market participants in the global Retail Construction Management Software market in 2025. Rapid urbanization and infrastructural development drive demand for retail construction management solutions across countries including Saudi Arabia, UAE, and South Africa. A strong focus on enhancing operational efficiency and project management capabilities contributes to the adoption of cloud-based solutions, which are projected to experience significant growth. The regional market presents untapped potential, particularly in underpenetrated territories, creating opportunities for software providers to expand their presence.
Emerging market front-runners, including Saudi Arabia and the UAE, prioritize investments in innovative technologies, supporting the transition towards smart and sustainable building practices. Local compliance mandates and regulatory frameworks shape the competitive landscape, compelling vendors to ensure alignment with regional standards. The dynamic nature of consumer behavior within retail segments further influences procurement decisions, reflecting businesses seeking solutions that enhance productivity and streamline construction processes. While infrastructure modernization initiatives gain momentum, the Retail Construction Management Software market attracts increased attention from domestic and international players.
The competitive landscape in the Retail Construction Management Software market features a dynamic array of players employing diverse strategies to strengthen their positions. Companies including Procore Technologies, Inc., Autodesk, Inc., and Accruent focus on product differentiation by offering tailored solutions that address specific client needs in project management and cost control. This strategic approach enhances brand equity and customer retention, facilitating long-term client relationships.
Several players engage in strategic alliances and partnerships to expand their market reach and enhance technological capabilities. Collaborations between Kahua, Inc. and other software providers aim to integrate advanced functionalities into existing frameworks. This trend reflects a broader market strategy focused on value chain integration, where firms leverage partnerships to improve procurement efficiency and supply chain dominance.
The threat of new entrants remains a constant consideration for established players. Barriers to entry include significant capital requirements and the necessity of developing proprietary technology moats. Companies like Oracle Corporation and STACK Construction Technologies emphasize the importance of robust intellectual property portfolios to maintain competitive advantages and fend off disruptions from startups.
The Retail Construction Management Software market anticipates growth driven by emerging technologies and evolving customer expectations. Firms invest in research and development pipelines to innovate and stay ahead of market trends. Consequently, the competitive outlook illustrates a landscape ripe for strategic growth vectors, facilitating enhancements in service offerings and operational efficiencies.
Market size is forecast to rise from USD 662.6 million in 2025 to over USD 1,390.7 million by 2033. The base case outlines a growth trajectory characterized by a 9.8% CAGR over this period.
Economic conditions will significantly impact the Retail Construction Management Software market. Robust infrastructure commitments and capital expenditures, alongside evolving regulatory frameworks, will influence demand dynamics. Strategic capital allocation directives will direct investments toward next-generation technologies, enhancing operational efficiencies and driving growth.
Increasing adoption of cloud-based solutions will lead to a shift toward innovative deployment models. The integration of advanced technologies, including artificial intelligence and machine learning, will support enhanced project planning and scheduling capabilities, enabling broader market penetration.
Geopolitical realignments and evolving trade corridors will reshape supply chain dynamics, affecting the availability and pricing of essential materials. Firms operating in the Retail Construction Management Software market will face challenges and opportunities stemming from these shifts, necessitating agile business strategies to maintain competitive advantage.
The maturation of core industries will require companies to adapt to structural consumption shifts. Emerging white-space opportunities present avenues for growth, particularly in addressing unmet enterprise needs. Focusing on high-growth pockets within the market will enable suppliers to capitalize on evolving consumer demands and secure market share.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Retail Construction Management Software market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 9.8% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Project Type, Deployment, Application, End User, and Region |
By Region | North America (By Project Type, Deployment, Application, End User, and Country)
|
Europe (By Project Type, Deployment, Application, End User, and Country)
| |
Asia Pacific (By Project Type, Deployment, Application, End User, and Country)
| |
South America (By Project Type, Deployment, Application, End User, and Country)
| |
Middle East and Africa (By Project Type, Deployment, Application, End User, and Country)
|
Find answers to common questions about this report
The Retail Construction Management Software market size was valued at USD 662.6 million in 2025, according to the Metastat Insights study.
The Retail Construction Management Software market is projected to grow at a CAGR of 9.8% during the forecast period from 2026 to 2033.
The North America Retail Construction Management Software market size is estimated to reach USD 429.3 million by 2033.
The segment leading the Retail Construction Management Software market is New Construction Projects, with a projected value of USD 589.3 million by 2033. This segment demonstrates a compound annual growth rate (CAGR) of 7.8% during the forecast period.
Increased investment in infrastructure and economic growth drive the Retail Construction Management Software market. Demand for efficient project management solutions rises because businesses seek to optimize operations and reduce costs while embracing digital transformation initiatives. Enhanced efficiency and a focus on sustainability further increase software adoption across various sectors.
North America holds the dominant share of the Retail Construction Management Software market, with a projected value of USD 429.3 million in 2033, representing 36.3 percent of the total market.
The Retail Construction Management Software market faces significant restraints from regulatory compliance challenges and high capital investment requirements. Varying regulatory environments complicate software deployment, incurring additional costs and delaying project timelines. High initial costs deter smaller firms from entering the market, leading to reduced competition and stifled innovation.
Increased investment in infrastructure and economic growth significantly influences product adoption in the Retail Construction Management Software market. The push for digital transformation, automation of processes, and compliance with sustainability mandates drives organizations to seek advanced software solutions that enhance operational efficiency and project management capabilities.
The Retail Construction Management Software market is estimated to reach a valuation of USD 1,390.7 million by 2033.
Key players in the Retail Construction Management Software market include Accruent, Procore Technologies, Inc., Autodesk, Inc., Oracle Corporation, and STACK Construction Technologies.
Choose Your License
Global Retail Construction Management Software Market
The analysts below cover Professional Services research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.
PRINCIPAL CONSULTANT - QUALITY SYSTEMS & COMPLIANCE
Electronics and Semiconductor · Machinery & Equipment · Professional Services
Omkar Phadtare is an Industry Consultant at MetaStat Insight, specializing in quality systems, regulatory compliance, and standards benchmarking to drive data-driven market intelligence and strategic industry research.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Tracking capacity expansion in single-use bioprocessing requires dependable data on raw material availability and cleanroom-grade polymer supply chains. The competitive landscape chapter gave a grounded evaluation of secondary component suppliers across North America and Asia-Pacific rather than simply reprinting press releases. Having that level of supplier benchmarking helped clarify dual-sourcing considerations for our clinical pipeline planning.
When evaluating distributed energy resource management systems, standard research summaries tend to gloss over the operational differences between front-of-the-meter utility deployments and behind-the-meter industrial sites. The MetaStat Insight report addressed those distinctions directly, especially regarding software interoperability standards and grid interconnection backlogs. The five-year market sizing across regional transmission organizations provided actionable context for our grid modernization strategy.
Most industry reports on warehouse automation bundle autonomous mobile robots and fixed conveyor installations into the same top-level numbers, which complicates advisory work. This study split the market cleanly by payload tiers, navigation technology, and fleet management software layers. The regional forecast for Western Europe gave our team defensible adoption benchmarks when evaluating capital allocation for logistics clients, saving us days of secondary data scrubbing.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950