
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Shadow Banking Market Size, Share, By Financial Intermediary Type (Finance Companies, Investment Funds, Money Market Funds, Broker-Dealers and Securities Firms, Mortgage REITs, Securitization Vehicles, Trust Companies, Credit Insurance and Guarantee Companies), By Credit Type (Consumer Credit, Corporate Credit, SME Credit, Residential Mortgage Credit, Commercial Real Estate Credit, Infrastructure and Project Finance, Trade and Receivables Finance, Equipment and Vehicle Finance, Financial Institution Credit), By End User (Individuals, Small and Medium Enterprises, Large Enterprises, Financial Institutions, Real Estate Companies, Government and Public Sector Entities), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5339
September 22, 2026
301 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $85,576.4 Million in 2025, projected to reach $139,559.1 Million by 2033 at a 6.3% CAGR.
Dominant Segment: The Finance Companies segment leads the market, driven by the increasing need for alternative financing solutions among consumers and businesses. This segment is projected to grow from USD 19,889.8 million in 2026 to USD 28,484 million by 2033.
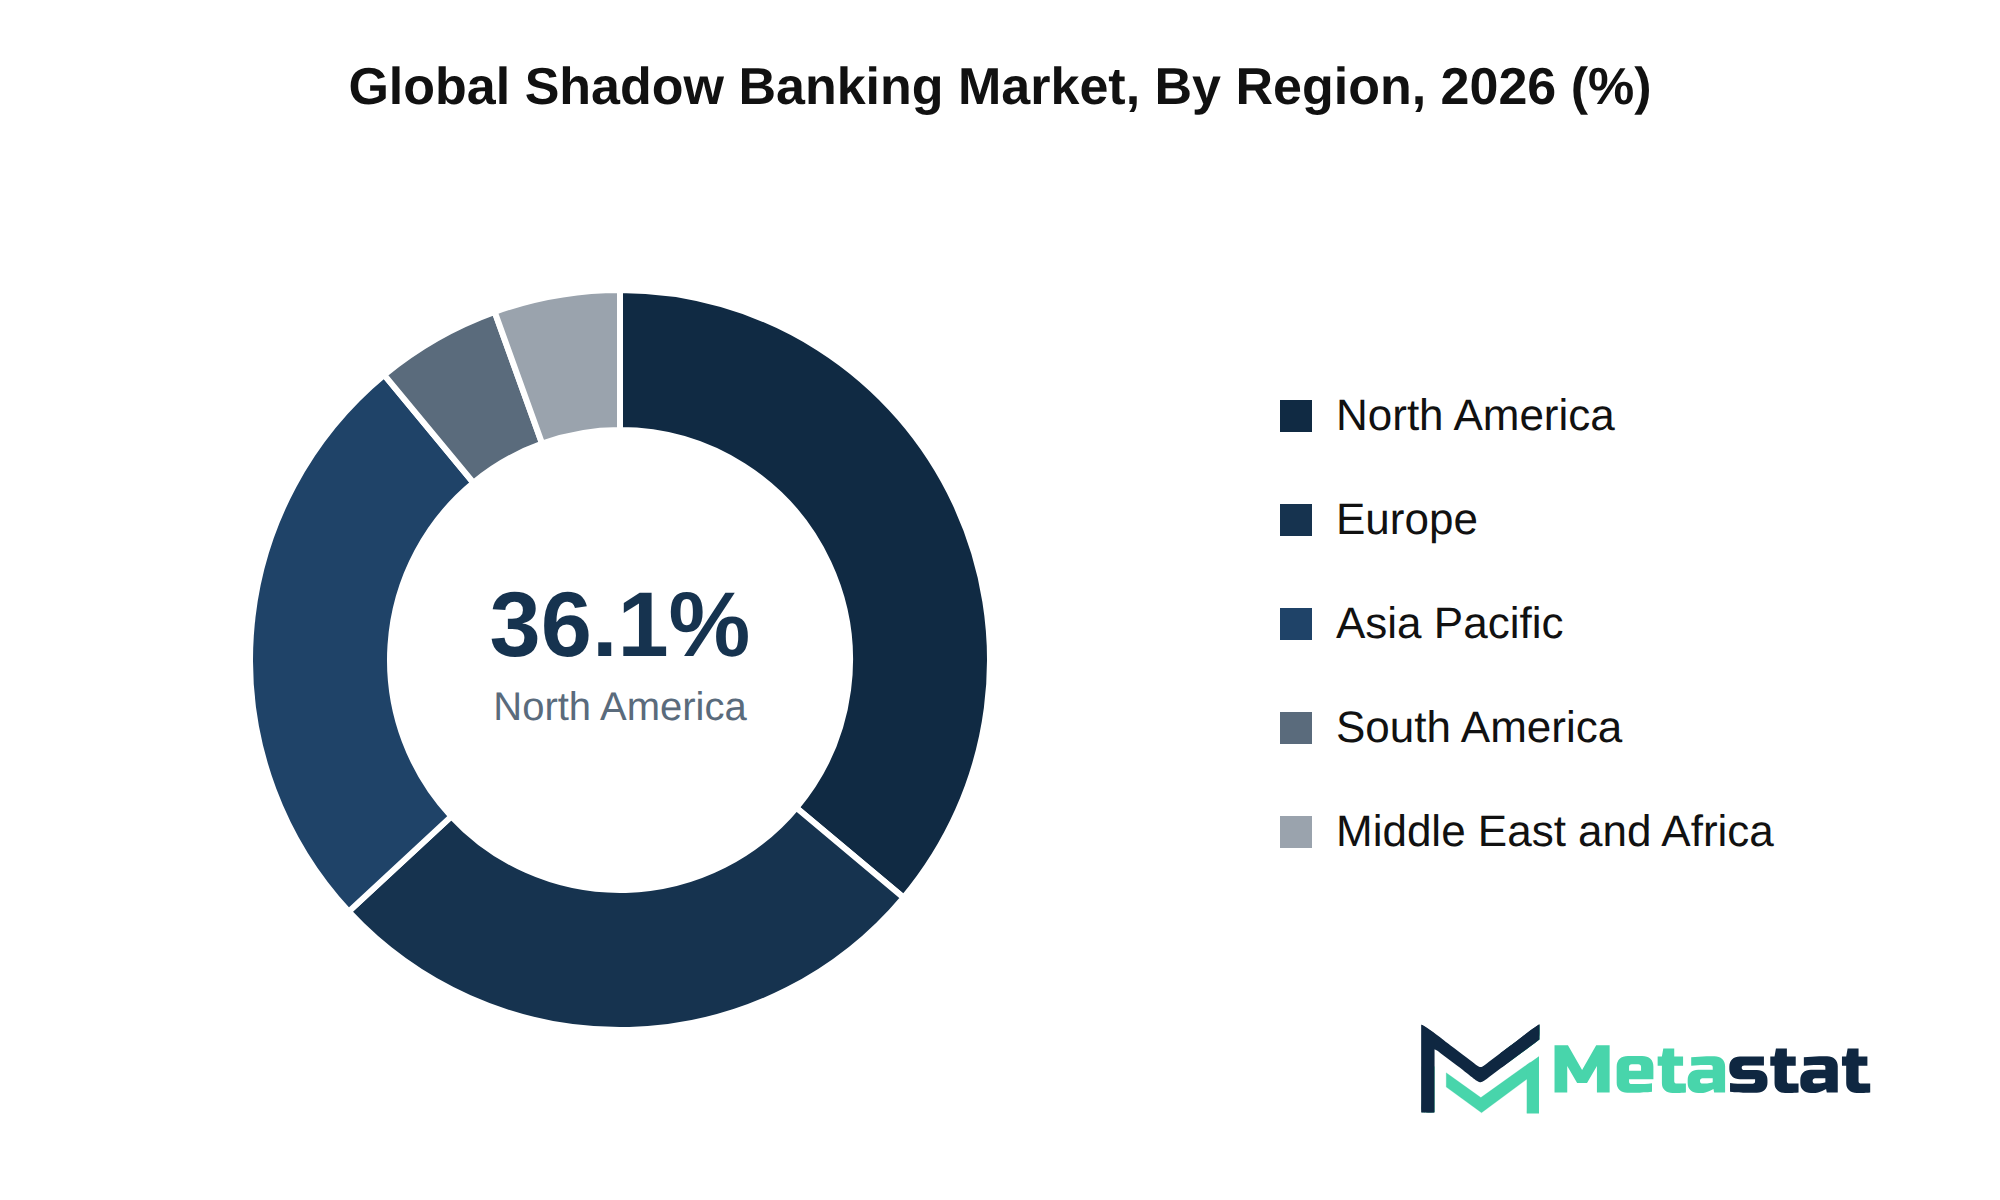
Geographic Lead: North America is expected to be the leading region in the Shadow Banking market, supported by rising financing requirements and advancements in financial technology. This region is well-positioned to leverage non-bank financial services for economic growth.
What's Inside: The report provides a comprehensive analysis of market dynamics, competitive landscape, and growth trends across various financial intermediary types. It includes detailed forecasts from 2026 to 2033, with insights into segment performance and regional developments.
Emerging Regional Demands: The market is witnessing significant opportunities from emerging regional demands, particularly in North America, Europe, and Asia Pacific. These regions are experiencing increased financing requirements, enhancing the attractiveness of non-bank financial services.
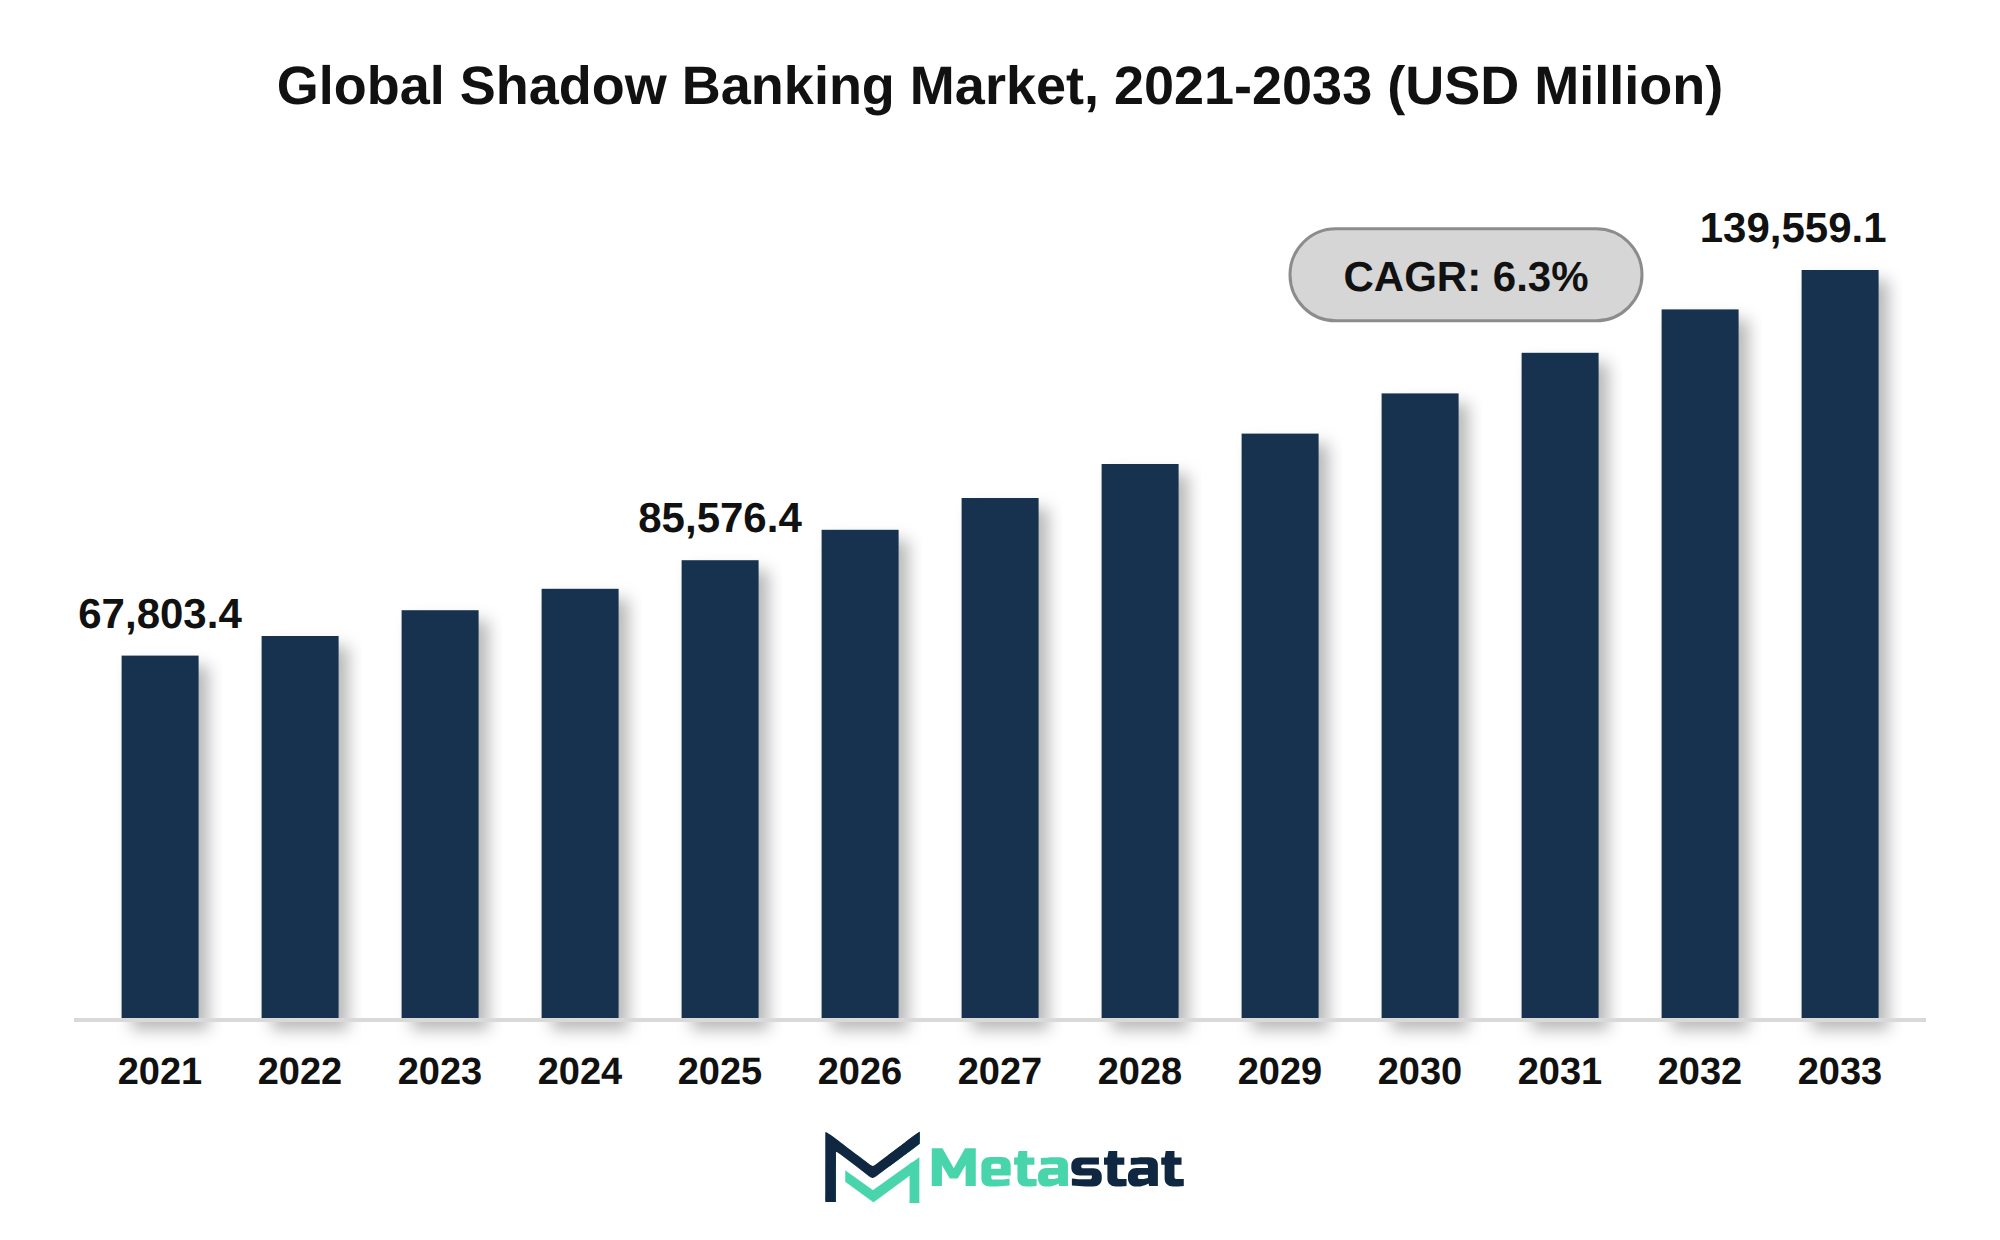
The global Shadow Banking market was valued at USD 85,576.4 million in 2025 and is projected to reach USD 139,559.1 million by 2033, growing at a CAGR of 6.3% over the forecast period.
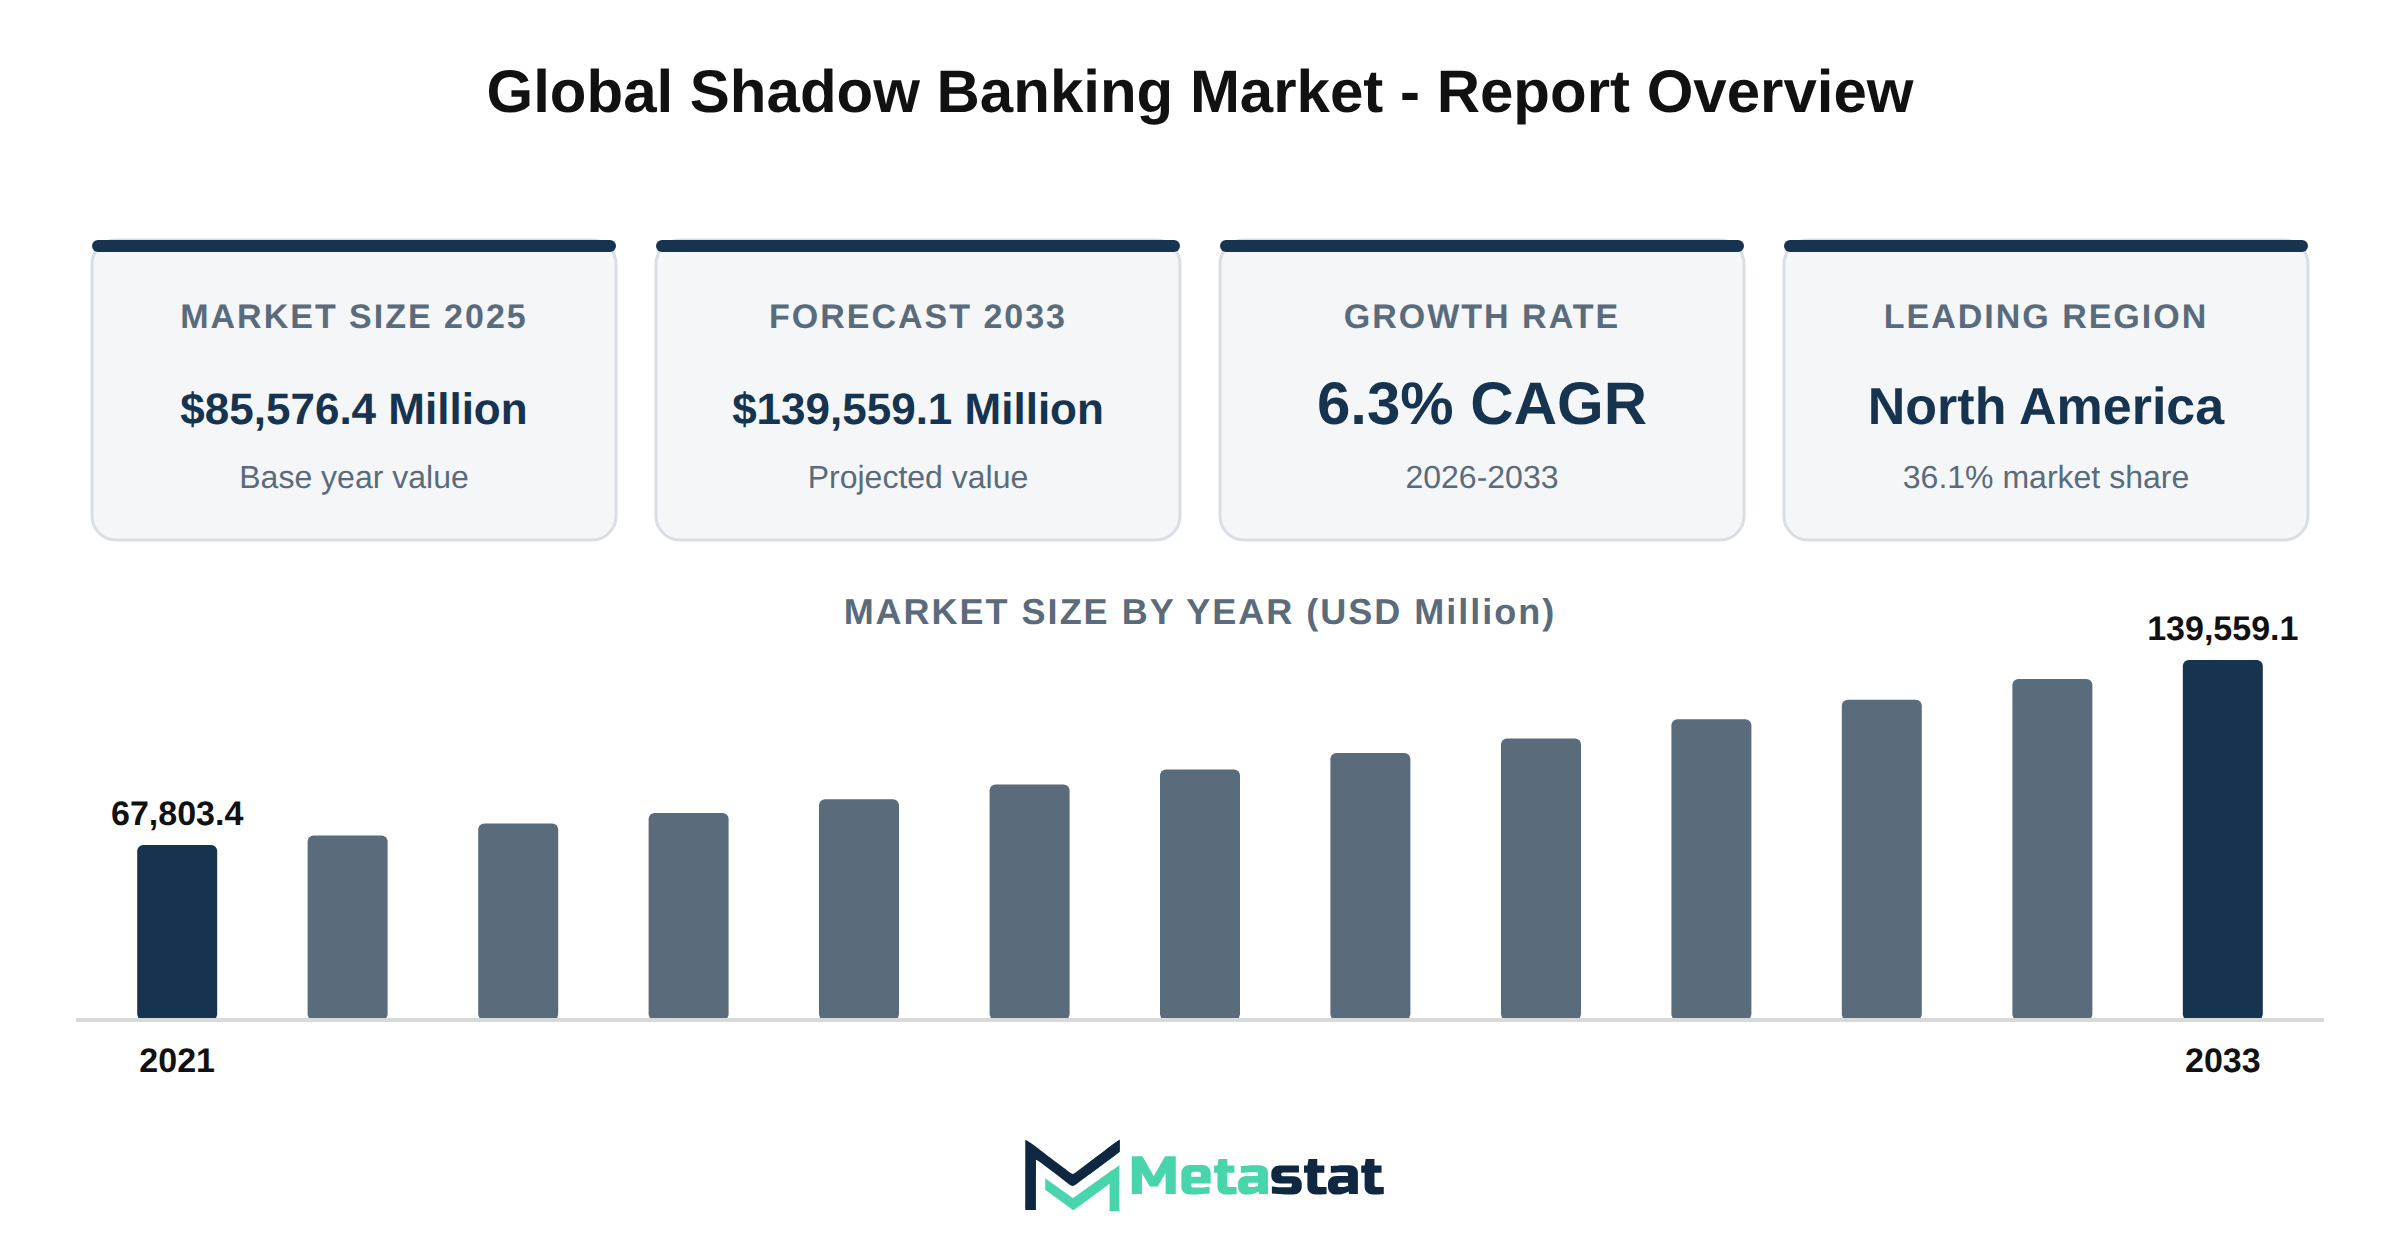
The Shadow Banking market reached a value of USD 85,576.4 million in 2025, reflecting a significant growth trajectory since USD 67,803.4 million in 2021. The market is projected to expand to USD 139,559.1 million by 2033, representing a compound annual growth rate (CAGR) of 6.3% from 2026 to 2033. This growth is primarily driven by the increasing demand for alternative financial services and credit options.
The expansion of private credit significantly reshapes the market. Institutional investors are increasingly allocating capital to private debt, seeking higher yields compared to traditional fixed income. This shift leads to greater competition among lenders and a more dynamic lending environment.
Investment funds and money market funds play a crucial role in driving the growth of non-bank financial institutions (NBFIs). These entities provide essential liquidity and investment opportunities, attracting both retail and institutional investors. The evolving landscape of investment strategies and fund management continues to enhance the prominence of these financial intermediaries.
Finance companies are expanding alternative credit access, targeting underserved segments including small and medium-sized enterprises (SMEs). This expansion enables these businesses to secure necessary funding for growth, thereby stimulating economic activity and job creation.
The evolution of securitization vehicles and structured credit markets encourages innovation in financing options. Financial institutions are increasingly employing these vehicles to manage risk and improve capital efficiency, contributing to a more resilient financial ecosystem.
Institutional demand for private debt and non-bank lending continues to grow, reflecting a shift in investor preferences toward less liquid assets offering attractive returns. This trend influences the overall dynamics of the market, reflecting institutional investors' pursuit of diversified portfolios that include alternative credit sources.
SME and corporate borrowing is shifting toward shadow banking alternatives, driven by the need for flexible financing solutions. Businesses are increasingly turning to non-bank lenders to meet their financing needs, enhancing the role of shadow banking in the broader credit landscape.
Consumer credit growth through non-bank financial intermediaries highlights the expansion of credit access for individuals. The availability of diverse financial products and services enables consumers to meet their personal financing requirements more effectively, contributing to overall economic growth.
Opportunities in real estate and mortgage credit within the shadow banking sector are expanding. Non-bank lenders are increasingly participating in residential and commercial mortgage markets, providing essential capital to borrowers and enhancing liquidity in these sectors.
Infrastructure and project finance growth through alternative lenders signifies a shift in financing mechanisms for large-scale projects. Non-bank entities provide essential funding for infrastructure development, supporting economic growth and sustainability initiatives.
The Shadow Banking market experiences significant growth driven by the expansion of non-bank credit. This sector has gained traction owing to the increasing demand for alternative financing sources among businesses and individuals. The trend reflects a shift in borrowing behavior, with non-bank financial institutions (NBFIs) offering competitive terms and flexible options compared to traditional banks. This dynamic creates a more diverse lending landscape, attracting a wider range of borrowers seeking immediate financial solutions.
Private credit growth significantly reshapes the market. Institutional investors are increasingly allocating capital to private debt, enticed by the potential for higher returns compared to public market investments. This trend facilitates the development of a robust private credit ecosystem, where borrowers find tailored financing solutions that align with their specific needs, further expanding the shadow banking landscape.
Investment funds and money market funds significantly drive NBFI growth, because these entities provide a range of investment opportunities for clients seeking liquidity and yield. The preference for these funds reflects a broader trend toward alternative investment strategies, positioning them because key players in the shadow banking market. Their ability to respond rapidly to market changes enhances their appeal among investors and borrowers alike.
Finance companies are expanding alternative credit access, providing a vital source of funding for consumers and businesses. These firms often cater to sectors underserved by traditional banks, including small and medium enterprises (SMEs) and individuals with limited credit histories. This expansion enhances financial inclusion and supports economic growth by enabling a wider array of borrowers to secure necessary financing.
Securitization vehicles and structured credit markets evolve concurrently with the shadow banking sector. These instruments facilitate the pooling of various financial assets, which improves capital flow and risk dispersion. The growth of such vehicles contributes to the stability and efficiency of the overall financial system while offering investors diversified opportunities.
Institutional demand for private debt and non-bank lending continues to rise. This demand stems from the search for yield in a low-interest-rate environment, positioning shadow banking because a viable alternative for institutional investors. Consequently, this trend supports the market's growth trajectory and enhances its overall attractiveness.
SME and corporate borrowing increasingly shift toward shadow banking, reflecting a changing landscape where businesses seek flexible financing solutions. This shift allows SMEs to access capital more efficiently, promoting growth and innovation within the sector. The market adapts to these trends by offering tailored products that meet the specific needs of various borrower segments.
Consumer credit growth through non-bank financial intermediaries highlights a broader shift in borrowing patterns. These intermediaries provide accessible financing options that cater to consumers' immediate financial needs, enhancing overall market participation. This trend contributes to the sustained growth of the shadow banking market.
Opportunities in real estate and mortgage credit flourish within the shadow banking sector. Alternative lenders increasingly provide financing for real estate projects, supporting the housing market and related industries. This trend highlights the significance of shadow banking in addressing gaps in traditional mortgage lending.
Infrastructure and project finance growth through alternative lenders reflects a commitment to funding essential projects that drive economic development. The involvement of non-bank entities in financing infrastructure projects supports the overall health of the economy by ensuring that crucial developments receive necessary capital.
Asset managers and alternative lenders intensify competition within the market. Increased participation from these players encourages innovation and improves service offerings, benefiting borrowers seeking competitive financing options. This competitive environment promotes efficiency and responsiveness in the shadow banking sector.
Bank and shadow banking interconnectedness reshapes financial risk dynamics. The integration of traditional and non-bank financing sources highlights the importance of monitoring systemic risks and ensuring stability in the financial system. This interconnectedness necessitates ongoing scrutiny to mitigate potential risks associated with shadow banking activities.
Liquidity transformation risks in investment and money market funds present challenges for participants in the shadow banking market. These risks highlight the importance of effective liquidity management and regulatory oversight to ensure the sustainability of these financial vehicles.
Leverage and short-term funding risks across non-bank intermediaries require careful consideration. Market participants navigate these risks to maintain stability and promote growth within the sector. Ongoing assessment of these factors will contribute to the long-term health of the shadow banking market.
Shadow banking regulation and global NBFI policy reforms continue to evolve in response to changing market dynamics. These regulatory adjustments aim to enhance transparency and mitigate risks associated with non-bank financial activities, ultimately promoting a safer financial ecosystem.
Private credit transparency and valuation challenges persist, reflecting critical issues within the shadow banking sector. Stakeholders address these challenges to improve market confidence and facilitate investment growth. Enhanced transparency will support informed decision-making among investors and borrowers alike.
Digital lending and fintech expansion in shadow banking represent significant trends reshaping the market landscape. The integration of technology enhances access to financing and streamlines the borrowing process, positioning shadow banking because an increasingly attractive option for consumers and businesses.
Cross-border non-bank credit and capital flow trends illustrate the global nature of the shadow banking market. Increased international collaboration among financial institutions promotes the flow of capital across borders, enhancing the overall market's liquidity and depth.
Asia Pacific shadow banking growth and regional opportunities highlight the potential for expansion in emerging markets. This region presents unique opportunities for non-bank credit providers seeking to capitalize on increasing demand for alternative financing solutions.
North America private credit and NBFI market expansion illustrate the region's commitment to fostering a diverse financial ecosystem. This growth positions North America because a key player in the global shadow banking market, attracting investment and innovation.
Europe shadow banking regulation and alternative finance growth reflect the ongoing evolution of the market. Regulatory developments in this region aim to create a balanced approach that supports innovation while maintaining market integrity.
Emerging market opportunities for non-bank credit providers signify the expanding role of shadow banking in global finance. These opportunities present avenues for growth and development, enhancing the overall market landscape.
Shadow banking investment and funding activity continue to evolve, driven by changing market dynamics. This ongoing activity highlights the importance of the sector in meeting diverse financing needs and promoting economic growth.
The shadow banking market outlook remains positive, with growth opportunities expected through 2033. Continued innovation and adaptation to changing market conditions will drive the sector's evolution, positioning it for sustained success in the future.
The Shadow Banking market benefits from favorable macro-economic factors, particularly rising GDP growth and favorable capital investment environments. These elements create a conducive landscape for investment and financial activities. Increased consumer confidence and disposable income contribute to the demand for various financial services provided by the market.
Interest rates play a crucial role in shaping the dynamics of the market. Lower interest rates generally encourage borrowing and lending activities, enhancing liquidity in the financial system. Increased access to capital positions businesses and individuals to engage more actively in financial transactions, thus propelling the growth of the Shadow Banking market.
The digital transformation of financial services further supports market development. Advancements in technology enable the integration of innovative solutions that streamline operations and improve customer experiences. Automation and the adoption of artificial intelligence enhance efficiency in service delivery, allowing the market to meet the evolving needs of consumers and businesses.
Shifting demographic patterns, including urbanization and changes in consumer behaviors, influence demand within the market. Urbanization increases the demand for diversified financial products. Individuals and businesses seek tailored financial solutions, creating opportunities for growth in various segments of the Shadow Banking market.
Overall, these macro-economic factors, along with technological advancements and demographic shifts, are projected to drive significant growth in the Shadow Banking market in the coming years.
The Shadow Banking market experiences substantial growth fueled by advancements in digital transformation. Financial institutions increasingly adopt automation, artificial intelligence, and software solutions to streamline legacy processes. This shift allows organizations to enhance operational productivity, improve accuracy, and reduce timeframes associated with financial transactions. The push towards digital transformation aligns with market demands for faster, more efficient services in an evolving economic landscape.
Investment in technological integration significantly shapes the market. Enhanced digital capabilities lead to improved customer experiences, attracting a broader range of clients, including individuals and small to medium enterprises. This trend expands revenue streams and creates competitive advantages among key players. While the sector embraces innovation, the Shadow Banking market positions itself for sustained growth, reflecting an increasing reliance on digital solutions across the financial industry.
Regulatory tightening presents significant challenges for the Shadow Banking market, owing to compliance hurdles that increase operational complexity for financial intermediaries. The implementation of stringent regulations impacts finance companies, investment funds, and other entities within the market, leading to higher costs and reduced operational efficiencies.
Macroeconomic headwinds, including inflationary pressures, create obstacles that affect capital stagnation and investment decisions. These factors restrict the availability of funds for expansion and innovation, resulting in diminished growth potential for the market.
Geopolitical instability introduces uncertainties that complicate investment climates, impacting investor confidence. This instability leads to supply chain disruptions, making it difficult for firms to maintain consistent operations and affecting overall market performance.
The high capital investment requirements associated with technological advancements pose additional barriers. Many firms in the Shadow Banking market face challenges in securing the necessary funds for infrastructure upgrades, limiting their ability to adopt innovative solutions and remain competitive.
Data security vulnerabilities and privacy concerns contribute to market restraints, because firms grapple with protecting sensitive information from potential breaches. Increased scrutiny over data management practices leads to additional compliance costs, further constraining market growth.
Market fragmentation complicates the competitive landscape, because diverse regional regulations create inconsistencies that hinder collaboration among stakeholders. This fragmentation results in inefficiencies and slower adoption of new financial products and services, ultimately affecting the overall growth trajectory of the Shadow Banking market.
Geopolitical fragmentation generates considerable uncertainty within the Shadow Banking market, complicating cross-border investments and financial transactions. Heightened tensions among nations trigger increased tariffs and trade deficits, which subsequently create an unpredictable operating environment for financial intermediaries. This volatility affects investment strategies and discourages potential investors, leading to reduced market participation and lower overall growth.
Technological disruptions further complicate these challenges by necessitating complex research and development integrations. Financial institutions face mounting pressure to innovate while managing the intricacies of interoperability among various systems. The resulting technological debt hinders efficient operations and increases compliance overhead, driven by firms striving to meet tightening global regulatory standards.
Pricing compression and margin pressures emerge from the operational complexities introduced by geopolitical tensions. Financial institutions operating in diverse regions confront escalating input cost structures, which threaten profitability. This situation necessitates strategic adjustments that divert resources from growth initiatives within the market.
Workforce skill gaps exacerbate these issues, resulting from firms struggling to retain talent adept at navigating these shifting dynamics. Automation displacements create additional workforce challenges, complicating efforts to maintain operational continuity amid evolving market demands. Consequently, the pressure to adapt to these environmental factors influences strategic priorities and investment decisions within the Shadow Banking market.
The Shadow Banking market exhibits significant opportunities driven by emerging regional demands across North America, Europe, and Asia Pacific. Increased financing requirements in these regions fuel growth in sectors including consumer credit and investment funds, positioning the market for expansion. The rise of financial technology enhances access to non-bank financial services, enabling a broader range of consumers and enterprises to seek alternative funding solutions.
Infrastructure modernization facilitates this growth. Upgraded financial systems and technological advancements streamline operations, leading to improved efficiency in service delivery. This modernization enhances the market's attractiveness, particularly for small and medium enterprises, which increasingly rely on these services for their financing needs. The integration of advanced technologies supports the development of tailored financial products, driving greater market penetration.
Geographical expansion presents further opportunities in the Shadow Banking market. Regions with underdeveloped financial services stand poised for growth owing to local investors seeking alternatives to traditional banking. The introduction of innovative financial products tailored to the needs of these regions satisfies unfilled demand, promoting overall market development. Strategic consolidation and cross-industry mergers enable companies to enhance their portfolios and expand their reach, strengthening competitive positioning.
Shifts in consumer behaviors significantly influence the market landscape. Evolving buying patterns reflect a growing preference for digital procurement solutions, compelling financial intermediaries to adapt their offerings. This adaptation includes the development of niche applications that cater to specific customer segments, further diversifying the market's product range. Such diversification enhances customer engagement and loyalty, contributing to sustained revenue growth.
The Shadow Banking market is well-positioned to leverage these opportunities, driven by technological disruptions and a focus on sustainability. The increasing emphasis on eco-friendly investments and ESG-driven alignments creates avenues for innovative financial products that align with market demands. By capitalizing on these trends, the market achieves significant growth in the upcoming years while addressing the evolving needs of diverse consumer bases.
The Global Shadow Banking market is segmented based on Financial Intermediary Type, Credit Type, and End User.
Growth in the Finance Companies segment of the Shadow Banking market is significant, with a valuation of USD 19,889.8 million projected for 2026 and an anticipated increase to USD 28,484 million by 2033. This growth reflects a compound annual growth rate (CAGR) of 5.3% during the forecast period. Primary demand drivers for finance companies include the increasing need for alternative financing solutions among consumers and businesses, driven by traditional banking channels that often impose stringent requirements. Investments in technology and the digitalization of services enhance operational efficiency, allowing finance companies to offer competitive products tailored to the evolving preferences of borrowers.
Expansion catalysts include a favorable regulatory environment that encourages the growth of these entities while ensuring consumer protection. The adoption of next-generation technologies, including artificial intelligence and data analytics, enables finance companies to improve risk assessment and customer service. The rising trend of financial inclusion boosts demand for finance companies, particularly in underserved markets where access to traditional banking remains limited. Evolving consumer behavior, characterized by a shift towards online and mobile platforms, necessitates finance companies to innovate continuously to remain relevant in the market.
With these dynamics in play, the Finance Companies segment is positioned to capture significant market share within the broader Shadow Banking market, contributing to its overall expansion and resilience. Increased capital investments into technology and marketing strategies are likely to further enhance their competitive stance, allowing them to meet the diverse financial needs of individuals and businesses alike.
Investment Funds segment is estimated to reach USD 43,989 million by 2033, at a CAGR of 6.9% during the forecast period. This growth stems from increasing demand for diversified investment options among institutional and individual investors. Rising awareness regarding the benefits of alternative investments drives growth, with many participants seeking to enhance portfolios by including non-traditional assets. Investment funds serve various sectors, including private equity, hedge funds, and real estate, contributing to a more dynamic investment landscape.
The expansion of this segment reflects technological advancements that streamline fund management processes, improve transparency, and enhance investor access. Digital platforms facilitate quicker onboarding and more efficient communication between fund managers and investors. Regulatory compliance standards around disclosures and risk management practices support investor confidence, fueling further interest in investment funds. These factors collectively create a favorable environment for growth in the Shadow Banking market.
Changing consumption patterns, particularly among younger investors, emphasize the shift toward sustainable and impact investing. This trend encourages fund managers to align their offerings with social and environmental goals, appealing to a broader base of investors. Consequently, investment funds benefit from this strategic opportunity window, allowing for innovative product development. This evolution is likely to lead to enhanced revenue streams and stronger market positioning for firms operating within the investment funds segment.
Growth in the Money Market Funds segment reflects increased demand for stable, liquid investments. Investors seek these funds for capital preservation during economic uncertainty and volatility, driving substantial adoption across various sectors. Financial institutions, corporate treasurers, and individual investors manage cash efficiently with Money Market Funds for short-term financing.
Technological maturation contributes significantly to the evolution of Money Market Funds, enabling improved transaction processing and enhanced reporting capabilities. Next-gen upgrades, including the integration of artificial intelligence and machine learning, enhance risk assessment and portfolio management, attracting a broader range of investors. Regulatory compliance standards shape operational frameworks, ensuring transparency and security, which cultivates trust among users.
Cost structures influence profitability in this segment; competition among providers continues to pressure fees and expenses. Pricing volatility in underlying assets affects the returns generated by these funds, compelling managers to adapt strategies. Despite these challenges, the Money Market Funds segment is projected to reach USD 19,370.8 million by 2033, highlighting its critical role in the overall Shadow Banking market.
Strategic opportunity windows emerge due to market participants innovating product offerings, targeting underrepresented consumer segments. Increased capital investment in technology and infrastructure further supports the segment's growth, ensuring resilience and competitiveness. Overall, the Money Market Funds segment demonstrates strong potential within the Shadow Banking market, driven by evolving investor preferences and advancements in financial technology.
Growth in the Broker-Dealers and Securities Firms segment significantly reflects the increasing demand for capital markets services and investment opportunities. The segment is projected to grow at a CAGR of 5.4% during the forecast period. This growth results from evolving market dynamics, including heightened investor interest in alternative investment strategies and the ongoing shift toward digital trading platforms. Broker-dealers play a critical role in facilitating transactions and providing access to various financial products, which aligns with the growing sophistication of investors. The segment benefits from strong regulatory compliance standards, ensuring reliability and trust in financial transactions.
Investment in technology represents a crucial driver for the segment, with firms adopting advanced trading systems and analytical tools to enhance their services. This technological maturation enables brokers to offer tailored solutions to clients, adjusting to the rising demand for personalized investment strategies. The segment experiences increased competition, pushing firms to innovate and expand their service offerings. The market's resilience is evident, driven by firms navigating the challenges posed by pricing volatility and margin pressures, adapting their strategies to maintain profitability.
The growing focus on transparency and accountability within the market shapes the operational landscape for broker-dealers and securities firms. Firms that prioritize regulatory compliance and ethical practices position themselves favorably with rising scrutiny from regulators and investors alike. Overall, the Broker-Dealers and Securities Firms segment stands to benefit from favorable market conditions and evolving investor preferences, reinforcing its role within the broader Shadow Banking market.
Mortgage REITs play a crucial role in the Shadow Banking market by providing capital to real estate owners and investors through financing options that traditional banks often do not offer. Primary demand drivers include the ongoing need for liquidity in the real estate sector and increasing property values, which prompt investors to seek alternative funding sources. The segment's expansion is driven by a growing number of investors looking for income-producing real estate assets and a rise in the demand for residential and commercial properties.
Technological maturation facilitates advancements in Mortgage REITs, enhancing operational efficiency and enabling better risk management strategies. Next-gen upgrades in financial technology and data analytics allow these firms to assess credit risk and property valuations more accurately. Product evolution within this segment leads to innovative financing solutions tailored to changing real estate market dynamics.
Downstream applications of Mortgage REITs significantly influence end-use dynamics, particularly in residential and commercial sectors. Consumption shifts towards rental properties and multifamily housing increase reliance on Mortgage REITs for financing solutions. Regulatory compliance standards, including those imposed on lending practices and risk management, shape the operational landscape for these firms while ensuring systemic stability within the market.
Cost structures and pricing volatility remain critical factors affecting profitability in this segment. Margin pressures arise from competition and fluctuating interest rates, impacting the cost of capital for Mortgage REITs. Strategic opportunity windows exist for firms that adapt quickly to market trends and incorporate regulatory changes into their business models. Overall, these dynamics highlight the resilience and strategic importance of Mortgage REITs within the broader Shadow Banking market.
Investment in securitization vehicles demonstrates robust interest from financial institutions seeking to enhance liquidity and diversify funding sources. This interest stems from the need for efficient capital allocation and risk management. Securitization provides opportunities to convert illiquid assets into marketable securities, attracting various investors. The demand for these vehicles often aligns with the performance of underlying assets, influencing investment strategies across sectors.
Technological maturation supports segment development by enabling sophisticated analytics and risk assessment models. Advanced technologies facilitate more accurate pricing and risk evaluation, attracting institutional investors. The evolution of product offerings, including collateralized loan obligations and asset-backed securities, enhances the appeal of securitization vehicles in the Shadow Banking market.
Regulatory compliance presents both challenges and catalysts for growth. Stricter capital requirements prompt financial institutions to explore alternative funding avenues, pushing securitization into the spotlight. The ongoing adaptation to evolving regulatory frameworks ensures that the segment remains aligned with industry standards, building trust among investors.
The strategic opportunity windows created by market dynamics allow for increased innovation within the sub-segment. Financial institutions continuously evaluate risk-adjusted returns, leading to the adoption of securitization because a tool for managing exposure and enhancing portfolio performance. Investment in this segment aligns with the broader trends in the Shadow Banking market, reflecting changing consumer preferences and economic conditions.
Trust companies play a vital role in managing financial transactions and assets for individuals and businesses within the Shadow Banking market. These entities cater to a diverse clientele, including high-net-worth individuals, corporations, and institutional investors. Trust companies provide services including estate planning, trust administration, and investment management, highlighting their significance in maintaining financial stability for their clients.
Adoption of trust company services is driven by increasing demand for personalized financial solutions and asset protection strategies. Clients seek these services to navigate complex regulatory environments and ensure compliance with evolving standards. The segment experiences expansion due to heightened awareness of the benefits of trust arrangements, particularly in wealth preservation and intergenerational asset transfer.
Technological advancements have significantly shaped the market for trust companies. The integration of digital platforms enhances client engagement and streamlines administrative processes, allowing for efficient management of assets. Next-gen upgrades including blockchain technology are anticipated to improve transparency and security in transactions, building greater trust and confidence among clients.
Downstream applications of trust company services extend to various sectors, including real estate, investments, and charitable giving. These entities enable clients to optimize their financial portfolios while addressing the unique needs of each sector. This customization enhances client satisfaction and strengthens relationships, promoting sustained growth in the market.
Regulatory compliance remains a critical factor influencing the operations of trust companies. Staying abreast of regulatory changes requires significant investment in compliance infrastructure and training. Firms that successfully navigate these challenges position themselves favorably within the competitive environment, enhancing their market share in the Shadow Banking market.
Strategic opportunities within the trust company segment arise from increasing demand for wealth management and estate planning services. Companies that effectively identify and capitalize on these windows gain a competitive edge, driving revenue growth. The focus on innovative service offerings and enhanced client experiences positions trust companies for long-term success in the evolving market.
In the Shadow Banking market, Credit Insurance and Guarantee Companies support the financial sector by providing essential risk mitigation solutions. Demand for these services arises from increasing complexity in financial transactions and a heightened focus on risk management among lenders and investors. The segment benefits from growing awareness of the importance of credit insurance among small and medium enterprises, which often seek alternatives to traditional financing methods. Expansion of this segment aligns with broader trends in financial technology that enhance service delivery and customer experience.
Technological maturation within the market encourages innovation in product offerings. Companies invest in advanced analytics and data-driven solutions, improving risk assessment capabilities and enabling tailored coverage options. Downstream applications of credit insurance and guarantees extend across various industries, including real estate, healthcare, and manufacturing, reflecting a diverse pool of end-users. Regulatory compliance standards shape operational frameworks, prompting companies to align with evolving legislation and customer expectations.
Increasing competition and pricing volatility exert pressure on margins, compelling firms to enhance operational efficiency and diversify their service portfolios. Firms assess supply chain resilience and raw material sourcing to mitigate potential disruptions. Strategies focusing on disruptive alternatives and technological obsolescence help firms maintain relevance. Strategic opportunity windows emerge through partnerships and collaborations that expand market reach and customer engagement. Continuous investment in the sector signals a robust outlook, supporting growth within the Shadow Banking market.
Valued at USD 16,693 million in 2026, the Consumer Credit segment is projected to reach USD 24,506.6 million by 2033, reflecting a CAGR of 5.6% during the forecast period. This consistent growth correlates with increasing consumer spending, driven by rising disposable incomes and favorable credit conditions. A growing preference for flexible financing options influences adoption among individuals, particularly those seeking personal loans and credit lines.
Segment expansion is supported by technological advancements in lending platforms, enhancing customer experience and simplifying the application process. Digitalization facilitates access to credit for underserved populations, driving demand across various demographics. Regulatory frameworks that promote consumer protection establish trust among borrowers, further encouraging market growth.
End-user dynamics indicate a shift towards more personalized lending solutions, with borrowers seeking tailored credit products that address specific financial needs. Financial institutions increasingly prioritize data analytics to assess creditworthiness, leading to more informed lending decisions. This trend enhances risk management while expanding the customer base for credit products.
Cost structures within the segment face pressures from fluctuating interest rates and operational expenses, necessitating strategic pricing adjustments by lenders. The competitive landscape consists of both traditional financial institutions and new fintech entrants, intensifying competition. Such dynamics within the Consumer Credit segment of the shadow banking market position it for sustained growth, driven by evolving consumer preferences and innovative financial solutions.
Corporate credit within the Shadow Banking market experiences significant growth driven by rising demand from businesses requiring liquidity and financing solutions. Economic expansion across various sectors contributes to an increase in corporate borrowing, enabling companies to finance investments and manage cash flow effectively. The segment is estimated to reach USD 30,717 million by 2033, at a CAGR of 5.9% during the forecast period.
Investment in technology and innovative financing solutions supports growth in this segment. Financial institutions increasingly adopt advanced credit assessment tools and data analytics to improve risk management and enhance underwriting processes. This technological maturation results in more efficient and tailored credit offerings, appealing to a broader range of corporate clients.
Changes in regulatory frameworks influence corporate credit dynamics. An evolving regulatory landscape encourages financial institutions to explore alternative lending mechanisms, which ultimately drives demand for shadow banking services. The flexibility offered by these structures allows companies to secure funding quickly, which aligns with the changing economic environment.
Increased competition among financial intermediaries creates a diverse range of credit products, catering to varying borrower needs. Corporations access customized financing solutions that facilitate growth and operational efficiency, reinforcing the appeal of corporate credit within the market.
Continued investment in corporate credit solutions leads to an enhancement of the overall financial ecosystem, improving access to capital for businesses. This trend positions the Shadow Banking market because a critical component in meeting the financing needs of corporations, driving sustained demand in the coming years.
Strong growth in the SME Credit segment reflects increasing demand from small and medium enterprises seeking flexible financing options. By 2033, this segment is projected to reach USD 19,998.8 million, primarily driven by a rise in entrepreneurial activities and innovation within the sector. The demand for SME Credit aligns with the broader trends in the Shadow Banking market, where alternative financing solutions gain traction among businesses facing traditional banking hurdles.
Technological advancements contribute significantly to the segment's expansion, with FinTech solutions enhancing accessibility and efficiency in credit delivery processes. These advancements enable quicker loan approvals and a more streamlined application process, allowing SMEs to respond agilely to market opportunities. The adoption of digital platforms and tools enables lenders to analyze creditworthiness with greater accuracy, further supporting the growth trajectory.
End-user dynamics indicate a growing preference for tailored financing solutions among small and medium enterprises. These businesses increasingly value personalized services that align with their unique operational needs. This shift in preference drives competition among financial intermediaries in the market, compelling them to innovate their offerings to capture and retain clientele. Consequently, SMEs experience improved access to credit, directly impacting their growth and sustainability.
The regulatory environment surrounding SME Credit continues to evolve, with favorable policies encouraging lending to smaller businesses. Governments often implement initiatives aimed at boosting entrepreneurship, which in turn supports demand for credit solutions tailored for SMEs. Compliance with emerging regulations becomes crucial for financial institutions, owing to adherence building trust and expanding their market presence.
Robust competition within the market leads to pricing pressures, prompting lenders to optimize their cost structures. Effective management of these costs ensures competitive interest rates, making credit more attractive for SMEs. These dynamics present strategic opportunity windows for new entrants, who leverage innovative delivery models to challenge established lenders and capture market share.
Residential Mortgage Credit segment is projected to grow at a CAGR of 5.5% during the forecast period. The increasing demand for housing and favorable interest rates contribute to sustained growth in this segment. Individuals seeking home ownership drive significant demand, supported by government policies promoting affordable housing solutions. In response to this upward trend, financial institutions adapt their offerings, enhancing accessibility to mortgage products. The Shadow Banking market benefits from innovations that streamline mortgage approval processes, making it easier for consumers to secure financing.
Investment in technology improves the efficiency of mortgage lending. Next-gen upgrades in data analytics enable lenders to better assess borrower risk, while advanced digital platforms facilitate quicker loan processing. These enhancements create a competitive edge for players within the market. Evolving consumer preferences reflect a shift toward more flexible and personalized mortgage solutions, prompting firms to tailor their offerings accordingly.
Regulatory compliance standards influence operational approaches among lenders. Financial institutions face pressures to align with changing regulations, impacting their cost structures and pricing strategies. Maintaining profitability while adhering to compliance measures presents challenges, yet it opens avenues for strategic innovation. While the segment expands, players that effectively navigate regulatory environments position themselves favorably within the Shadow Banking market.
In the commercial real estate credit sector, increasing demand for property financing drives growth. A recovering economy, rising consumer confidence, and the ongoing need for residential and commercial properties contribute to this demand. Financial institutions and private lenders actively seek opportunities to provide loans, creating a competitive environment that benefits borrowers.
Regulatory compliance standards play a significant role in shaping this segment. Adherence to guidelines ensures stability and transparency within the market. Institutions that navigate these regulations successfully establish trust with clients, enhancing their market position and attracting further investment.
Technological maturation influences the commercial real estate credit segment, with advancements in fintech facilitating quicker loan approvals and more efficient risk assessments. Innovations in data analytics allow lenders to make informed decisions, reducing default risk and enhancing profitability. These advancements promote increased lending activity and market expansion.
Cost structures and pricing volatility present challenges within the segment. Fluctuating interest rates affect borrowing costs, while margin pressures impact profitability for lenders. Effective management of these variables is crucial for sustainable growth in the commercial real estate credit segment.
Strategic opportunity windows arise through evolving consumer preferences and emerging trends in real estate investment. The demand for sustainable and energy-efficient properties influences financing decisions, encouraging lending institutions to adapt their offerings. Capital investment outlook in this sector remains optimistic. Stakeholders recognize the potential for long-term returns within the shadow banking market.
Interest in infrastructure and project finance remains high within the Shadow Banking market, driven by the increasing demand for developing sustainable, large-scale projects. Governments and private investors seek alternative funding sources to complement traditional financing methods, creating a robust environment for this sub-segment.
Adoption of innovative financing solutions supports segment expansion, facilitating access to capital for infrastructure projects. Enhanced collaboration among financial institutions, private equity firms, and project developers enables efficient resource allocation, which drives the growth of this financial avenue.
Technological advancements streamline the infrastructure and project finance domain, allowing for more efficient project evaluation and risk assessment. Financial entities increasingly leverage data analytics and digital platforms to enhance decision-making processes, thereby improving overall performance within the market.
The ongoing shift towards sustainable and green projects further influences end-use dynamics, creating opportunities for infrastructure and project finance. Stakeholders increasingly prioritize environmental, social, and governance factors in project selection, which aligns with global trends towards sustainability.
Regulatory compliance standards remain critical, because entities involved in infrastructure and project finance navigate a complex landscape of guidelines and requirements. Adherence to these regulations builds trust and credibility among investors, ultimately promoting greater investment in this area.
Strategic opportunity windows continue to evolve, driven by the need for resilient infrastructure in response to changing environmental and economic conditions. Financial institutions actively scout the market for innovative projects that align with shifting consumer preferences and regulatory demands.
The outlook for infrastructure and project finance indicates significant potential for growth, supported by increased capital investment and a strong focus on sustainable development. This segment's evolution shapes the future of the Shadow Banking market, reflecting broader trends in global finance and investment strategies.
Demand for Trade and Receivables Finance stems from businesses seeking efficient cash flow management solutions. Companies increasingly prefer these financing options to bridge gaps between accounts receivable and payable, ensuring liquidity during operational fluctuations. The growing emphasis on prompt payment systems enhances adoption, driven by organizations aiming to minimize the risks associated with delayed cash inflows.
Segment expansion is fueled by technological advancements that improve invoicing and payment processing. Integration of digital platforms offers businesses an efficient experience, facilitating quicker transactions and reducing administrative burdens. While organizations prioritize efficiency, the shadow banking market experiences heightened interest in innovative financing solutions.
The evolving regulatory landscape impacts trade and receivables finance, necessitating compliance with standards that ensure transparency and risk mitigation. Financial institutions actively adapt their offerings to meet these regulatory demands, enhancing market stability. Companies specializing in this segment benefit from adherence to evolving compliance frameworks, positioning themselves because reliable partners for businesses navigating financial complexities.
Pricing volatility in the trade and receivables finance sector influences profitability for financial intermediaries. Competitive pressure drives organizations to optimize pricing strategies while maintaining lucrative margins. Participants in this market continuously evaluate their cost structures to ensure sustainable profitability during fluctuating economic conditions.
Investment in next-generation technologies creates strategic opportunity windows within trade and receivables finance. Companies leveraging advanced analytics and automation enhance their service offerings, catering to an expanding client base. By embracing these innovations, the market strengthens its position, providing businesses with tailored solutions that address their unique financial needs.
Downstream applications of trade and receivables finance extend across various sectors, including manufacturing and distribution. The demand for efficient cash flow solutions in these industries reinforces the importance of this segment within the broader shadow banking market. Companies that effectively utilize trade and receivables finance position themselves for growth, aligning with the evolving financial landscape.
Investment in Equipment and Vehicle Finance reflects a significant trend within the Shadow Banking market, driven by rising consumer demand for mobility solutions and the increasing cost of traditional financing methods. Financial institutions focus on this segment to capitalize on growth opportunities associated with the expanding automotive and equipment sectors.
Technological advancements in financing solutions enhance adoption rates, with digital platforms streamlining the application process for consumers and businesses alike. This technological maturation creates competitive pricing, attracting a broader customer base seeking flexible financing options tailored to their specific needs.
Downstream applications highlight a shift towards electric and autonomous vehicles, which promise to reshape the financing landscape because these technologies gain traction. End-user dynamics indicate a growing preference for leasing rather than purchasing, allowing businesses to better manage cash flow while accessing the latest equipment and vehicles.
Regulatory compliance standards play a critical role in shaping the operational framework of Equipment and Vehicle Finance. Financial institutions navigate evolving regulations to minimize risks and ensure sustainable growth within the segment. This focus on compliance influences cost structures, pricing strategies, and overall market dynamics.
Strategic opportunities arise from shifts in consumer behavior and the introduction of disruptive alternatives in financing, including peer-to-peer lending platforms. This competitive landscape prompts traditional institutions to innovate and adapt, ensuring relevance in a quickly changing environment.
In the Shadow Banking market, Financial Institution Credit represents a significant component driven by the increasing demand for flexible financing solutions among various financial entities. The expansion of this segment is propelled by heightened lending activities from financial institutions that seek to diversify their portfolios and enhance liquidity. Financial institutions are increasingly focused on meeting the evolving financing needs of their clients, which contributes to a growth trajectory.
Technological advancements play a vital role in shaping the dynamics of Financial Institution Credit. Financial institutions are adopting next-generation technologies to streamline operations and improve credit assessment processes. Enhanced data analytics and artificial intelligence contribute to more informed lending decisions, ultimately building confidence among borrowers and increasing the overall market size. Regulatory compliance standards influence this segment, with institutions adapting to new policies aimed at ensuring transparency and risk management.
Consumption shifts towards innovative financial products have further stimulated demand within this segment. Financial institutions are adapting their offerings to include customized credit solutions tailored to individual and business needs, thereby attracting a broader customer base. Strategic opportunity windows arise from institutions seeking to capitalize on emerging market trends while navigating the complexities of regulatory landscapes. The connection between technological maturation and evolving consumer preferences positions this segment for sustained growth in the coming years.
Growth in the Individuals segment reflects a significant shift in consumer borrowing patterns. Increasing financial inclusion and the rising adoption of digital financial services drive demand for alternative credit sources. The segment is valued at USD 25,620.3 million in 2026 and is projected to reach USD 37,555.3 million by 2033, at a CAGR of 5.6% during the forecast period. Enhanced accessibility to credit options allows individuals to meet personal financing needs without relying solely on traditional banking institutions, which impose stringent lending criteria.
Technological advancements in mobile banking and fintech solutions contribute to the segment's expansion. Innovations in data analytics enable more accurate credit assessments, allowing financial intermediaries to expand their customer base and tailor products to meet individual needs. The growing preference among consumers for personalized financial services influences the dynamics of the Shadow Banking market, encouraging providers to develop innovative solutions that address specific consumer requirements.
Regulatory compliance standards significantly impact the Individuals segment, shaping how financial services are delivered. Adapting to evolving regulations ensures that service providers maintain trust and transparency with their clientele. The emphasis on responsible lending practices creates a more sustainable growth environment, enhancing the market's overall dynamics and facilitating the entry of new participants.
Economic factors, including fluctuating interest rates and changing employment landscapes, influence consumer credit demand. Individuals increasingly seek flexible financing solutions that accommodate their financial situations. This trend highlights opportunities within the market for providers to offer competitive products and build long-term relationships with borrowers by prioritizing consumer education and financial literacy initiatives.
Growing recognition of the contribution of Small and Medium Enterprises (SMEs) to the economy drives demand for shadow banking services tailored to this segment. SMEs often face challenges accessing traditional financing, creating a need for alternative funding sources. Financial intermediaries play a crucial role in providing innovative credit solutions designed specifically for these enterprises, enhancing their growth and operational stability.
The Small and Medium Enterprises segment is estimated to reach USD 28,553.8 million by 2033, at a CAGR of 7.4% during the forecast period. This growth reflects increasing investment in technology-driven financial services that enhance access to capital for SMEs. A shift toward digital platforms enables faster loan processing and more efficient service delivery, aligning with the evolving needs of these enterprises.
Regulatory compliance standards impact SMEs significantly, driven by financial institutions adapting to new requirements that ensure greater transparency and consumer protection. This compliance landscape necessitates that SMEs engage with shadow banking entities that provide a mix of competitive rates and flexible terms, encouraging sustained engagement with the market.
Investments in next-generation upgrades, including automated credit assessment tools, enhance the efficiency of shadow banking services available to SMEs. The ability to analyze creditworthiness quickly allows financial institutions to extend credit more confidently, increasing acceptance rates for loans among SMEs. These technological advancements improve service delivery and help financial institutions reduce risk exposure.
The shadow banking market continues to evolve with the introduction of disruptive alternatives that challenge traditional lending models. SMEs benefit from these developments, which provide them with a broader array of financing options that suit their unique requirements. Ongoing capital investment in this market signals a commitment to meeting the needs of SMEs, creating an environment conducive to growth and innovation.
Large Enterprises within the Shadow Banking market exhibit a significant growth trajectory, projected to reach USD 30,535.5 million by 2033. This growth results from the increasing need for alternative financing solutions that cater to the unique operational requirements of large businesses. The demand for tailored financial products drives the expansion of this segment, allowing large enterprises to leverage the flexibility and efficiency offered by shadow banking entities.
Technological advancements play a crucial role in enhancing the operational capabilities of large enterprises, enabling them to access innovative financial solutions. The adoption of digital platforms facilitates streamlined interactions between enterprises and shadow banking providers, promoting a more efficient financing process. This evolution in technology builds confidence among large enterprises, leading to increased investment in shadow banking services.
Regulatory compliance standards impact large enterprises, necessitating adherence to evolving financial regulations. This compliance creates challenges and opportunities for financial service providers within the market. Large enterprises seek shadow banking solutions that align with regulatory requirements while offering favorable terms compared to traditional banking options.
The market for large enterprises benefits from strategic opportunity windows presented by evolving economic conditions. Financial institutions recognize the value of catering to this segment, resulting in enhanced product offerings tailored to meet specific needs. Consequently, large enterprises experience improved access to capital, driving growth within the shadow banking market.
Financial Institutions within the Shadow Banking market represent a critical segment poised for growth. This segment is projected to grow at a CAGR of 5.2% during the forecast period. Demand for financial services among institutions stems from a need for diversified funding sources and risk management solutions. Increasing regulatory requirements and compliance standards drive financial institutions to seek innovative financing options that shadow banking provides.
Technological advancements facilitate transaction efficiency and enhance service delivery, promoting growth within the segment. Investment in next-generation technologies including blockchain and artificial intelligence contributes to improved operational capabilities, which supports financial institutions in managing risk and optimizing capital allocation. The evolution of products offered by shadow banking entities aligns with the specific needs of financial institutions, ensuring tailored solutions for their diverse requirements.
While competition intensifies, financial institutions increasingly rely on the shadow banking market to secure funding that traditional banks do not provide. This reliance creates strategic opportunity windows for alternative finance providers. The projected market size for financial institutions highlights the growing recognition of shadow banking because a vital component within the broader financial landscape.
Investments from Real Estate Companies significantly influence the dynamics of the Shadow Banking market. Demand for financing solutions remains strong, driven by ongoing projects in both residential and commercial sectors. Increased property values and the need for liquidity highlight the importance of alternative financing options available through shadow banking. Regulatory compliance standards impact how these companies approach funding, often steering them toward non-traditional lending sources.
Technological maturation across the financial services industry enables Real Estate Companies to access innovative financial products tailored to their needs. Adoption of digital platforms facilitates more efficient transactions and enhances the overall experience for borrowers. This shift in consumption patterns emphasizes the importance of integrating technology within traditional financing methods, allowing real estate firms to streamline operations and reduce delays.
Investment in property development and management continues to expand, offering strategic opportunity windows for shadow banking participants. Companies focusing on real estate appreciate the flexibility provided by shadow banking options, particularly during economic fluctuations. This adaptability enhances the resilience of supply chains while allowing firms to navigate changing market conditions.
The evolving landscape of the Shadow Banking market presents numerous prospects for Real Estate Companies to leverage alternative financing methods. By capitalizing on these developments, companies improve their financial positions and respond effectively to shifting market demands.
Increasing demand for financial solutions among Government and Public Sector Entities drives growth within the Shadow Banking market. These entities seek alternative funding options to support various projects, including infrastructure development and public services. The need for efficient capital allocation and liquidity management expands their reliance on shadow banking mechanisms.
Adoption of innovative financial instruments within the public sector accelerates segment expansion. Government entities increasingly access investment funds and finance companies to address budget constraints and improve service delivery. This trend highlights a shift towards embracing non-traditional financing sources, which enhances operational flexibility and financial resilience.
Technological advancements in financial services contribute to the maturation of this segment. The integration of digital platforms simplifies access to funding and streamlines transaction processes, benefitting public sector entities. These developments enable more efficient project financing and improve transparency in governmental financial activities.
Regulatory compliance remains a crucial factor affecting the operations of Government and Public Sector Entities within the market. Adhering to stringent regulations influences funding strategies and financial product choices. This regulatory environment shapes the competitive landscape and encourages entities to seek compliant shadow banking solutions that align with governmental policies.
The balance between cost structures and pricing volatility poses challenges for public sector stakeholders. Fluctuations in interest rates and financial product pricing impact budget allocations for various projects. Consequently, entities focus on strategic financial planning to mitigate risks associated with pricing uncertainties, which ultimately influences investment decisions.
Strategic opportunity windows arise owing to governments increasingly recognizing the need for alternative financing solutions. The pursuit of sustainable development goals further motivates public sector entities to explore shadow banking options for funding initiatives. This strategic shift enhances the capabilities of government agencies and supports broader economic growth within the sector.
Based on geography, the Global Shadow Banking market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America holds a significant position in the Shadow Banking market, with a projected market size of USD 48,720.1 million by the end of 2033. The region experiences a CAGR of 6.3% during the forecast period, driven by strong financial institutions and a growing focus on alternative financial services. The United States, Canada, and Mexico form the core of this market, exhibiting robust demand for various financial products.
Investment Funds and Finance Companies represent prominent segments within North America, addressing the diverse needs of consumers and enterprises. The increasing reliance on non-bank financial intermediaries fuels growth, supported by their provision of tailored financial solutions that align with market demands. The expanding role of technology in enhancing service delivery continues to play a critical function in shaping market dynamics.
Market participants leverage strategic entry barriers and localized procurement dynamics to strengthen their market position. The presence of established domestic players contributes to competitive landscapes, promoting innovation and responsive service offerings. The focus on compliance with geographic regulatory frameworks encourages businesses to adapt, ensuring alignment with local mandates and enhancing operational efficiency.
Investment in infrastructure modernization and localized manufacturing densities supports growth, providing avenues for firms to capitalize on emerging opportunities. The North American market for shadow banking stands poised for further development, driven by incremental growth vectors and the evolving financial landscape.
Europe's share of the global Shadow Banking market stands at 27.00% in 2025, highlighting the region's significance within the financial landscape. Key countries including Germany, France, and the UK lead the way in market activity, driven by established financial institutions and a robust regulatory environment. Italy and Spain provide additional momentum, fueled by increasing integration of shadow banking practices into mainstream finance.
The emergence of innovative financial solutions tailored to consumer and corporate credit requirements drives adoption across diverse sectors. The presence of sophisticated investment funds and finance companies indicates a competitive landscape, with domestic players including BlackRock, Inc. and Apollo Global Management, Inc. actively participating. This competitive environment creates conditions conducive to growth and expansion within the market.
Localized procurement dynamics and cultural nuances influence B2B buying behaviors across Europe. Countries including Germany and France exhibit distinct preferences for financial products, creating opportunities for tailored offerings. The ongoing interest in modernizing financial infrastructures and enhancing compliance mandates strengthens the market outlook. Regional players adapt to evolving regulations.
Geopolitical factors and cross-border trade corridors significantly impact the market. The ongoing stability within Europe enhances investor confidence, encouraging foreign direct investment flows aimed at capturing emerging opportunities. While the landscape evolves, aligning local compliance mandates with international standards remains crucial for maintaining relevance and competitiveness in the Shadow Banking market.
Asia-Pacific represents a growing segment of the global Shadow Banking market. The region's robust economic growth, driven by increasing urbanization and rising disposable incomes, fuels demand for diverse financial products. Countries including China, Japan, and India lead in shadow banking activities, supported by their vast populations and expanding middle class.
Investment Funds are particularly influential in the region, with a notable CAGR of 6.9% projected through 2033. This segment's strength derives from a growing appetite for alternative investment opportunities and the search for better yields during fluctuating market conditions. Finance Companies and Consumer Credit experience growth, appealing to both individuals and small and medium enterprises seeking flexible financing solutions.
In South Korea and Australia, strong regulatory frameworks and advanced financial systems enable smoother adoption of shadow banking practices. Emerging markets within Southeast Asia exhibit untapped potential, with increasing financial literacy and digital adoption leading to innovative financial products. Financial Institutions across the region adapt to changing market dynamics, focusing on enhancing their service offerings and operational efficiencies to meet evolving customer needs.
The local competitive landscape features key players like BlackRock, Inc., and Apollo Global Management, Inc., contributing to the market's expansion. Their strategic initiatives emphasize localized procurement dynamics and cultural nuances, ensuring alignment with regional B2B buying behaviors. This localized approach strengthens client relationships and improves service delivery across diverse markets.
Ultimately, the Shadow Banking market within Asia-Pacific is poised for incremental growth, driven by regulatory support, changing consumer preferences, and increasing investments in financial technology. The region's diverse economic landscape presents both challenges and opportunities, with ongoing infrastructure modernization and foreign direct investment shaping the future of shadow banking activities.
South America accounts for 5.5% of the global Shadow Banking market in 2025. The regional landscape is characterized by varying demand dynamics, with Brazil and Argentina emerging because notable players. Brazil stands out due to its robust financial services sector, while Argentina faces challenges related to economic fluctuations and regulatory changes.
Efforts to improve financial inclusion drive growth in consumer credit across the region. Individuals increasingly seek alternative financing options, supporting the expansion of non-traditional financial institutions. In addition, small and medium enterprises (SMEs) contribute significantly to the demand for credit, emphasizing the need for accessible financing solutions tailored to their needs.
Investment funds play an important role in the market, with increased interest from both domestic and international investors. This trend creates a competitive environment, leading to consolidation among local players and the establishment of partnerships to enhance service offerings. The regulatory framework evolves to accommodate these developments, promoting a more structured approach to shadow banking activities.
The market continues to experience incremental growth vectors driven by infrastructure modernization and localized procurement dynamics. Emerging technologies facilitate access to financial services, enabling market participants to capitalize on untapped opportunities. Despite challenges, South America presents a promising outlook for the Shadow Banking market, with potential for increased penetration and growth in the coming years.
The Shadow Banking market in the Middle East and Africa represents a developing segment. Countries including Saudi Arabia, UAE, and South Africa show potential for growth driven by increasing demand for alternative financial solutions and investment opportunities. Corporate borrowers in these regions seek flexible financing options beyond traditional bank loans, particularly for short-term liquidity needs and specialized funding requirements.
Emerging market front-runners in this region benefit from strategic entry barriers and foreign direct investment flows, providing a foundation for expansion. Local compliance mandates and geographic regulatory frameworks shape industry dynamics, influencing how financial intermediaries operate in these markets. Regulatory variations create distinct operational challenges, necessitating tailored strategies for market participants.
Investment funds and finance companies play significant roles in the market, focusing on consumer and corporate credit. Growth vectors driven by localized procurement dynamics and regional B2B buying behaviors enhance market opportunities. The integration of technology within financial services further supports the expansion of shadow banking activities in the region.
Energy grid resiliency and local infrastructure readiness contribute to a favorable environment for the development of the market. Domestic market participants, including established financial institutions, contribute to competitive landscapes, promoting vendor consolidation trends and enhancing service offerings. This competitive environment fosters innovation and adaptability among financial intermediaries, positioning them to better meet evolving customer needs.
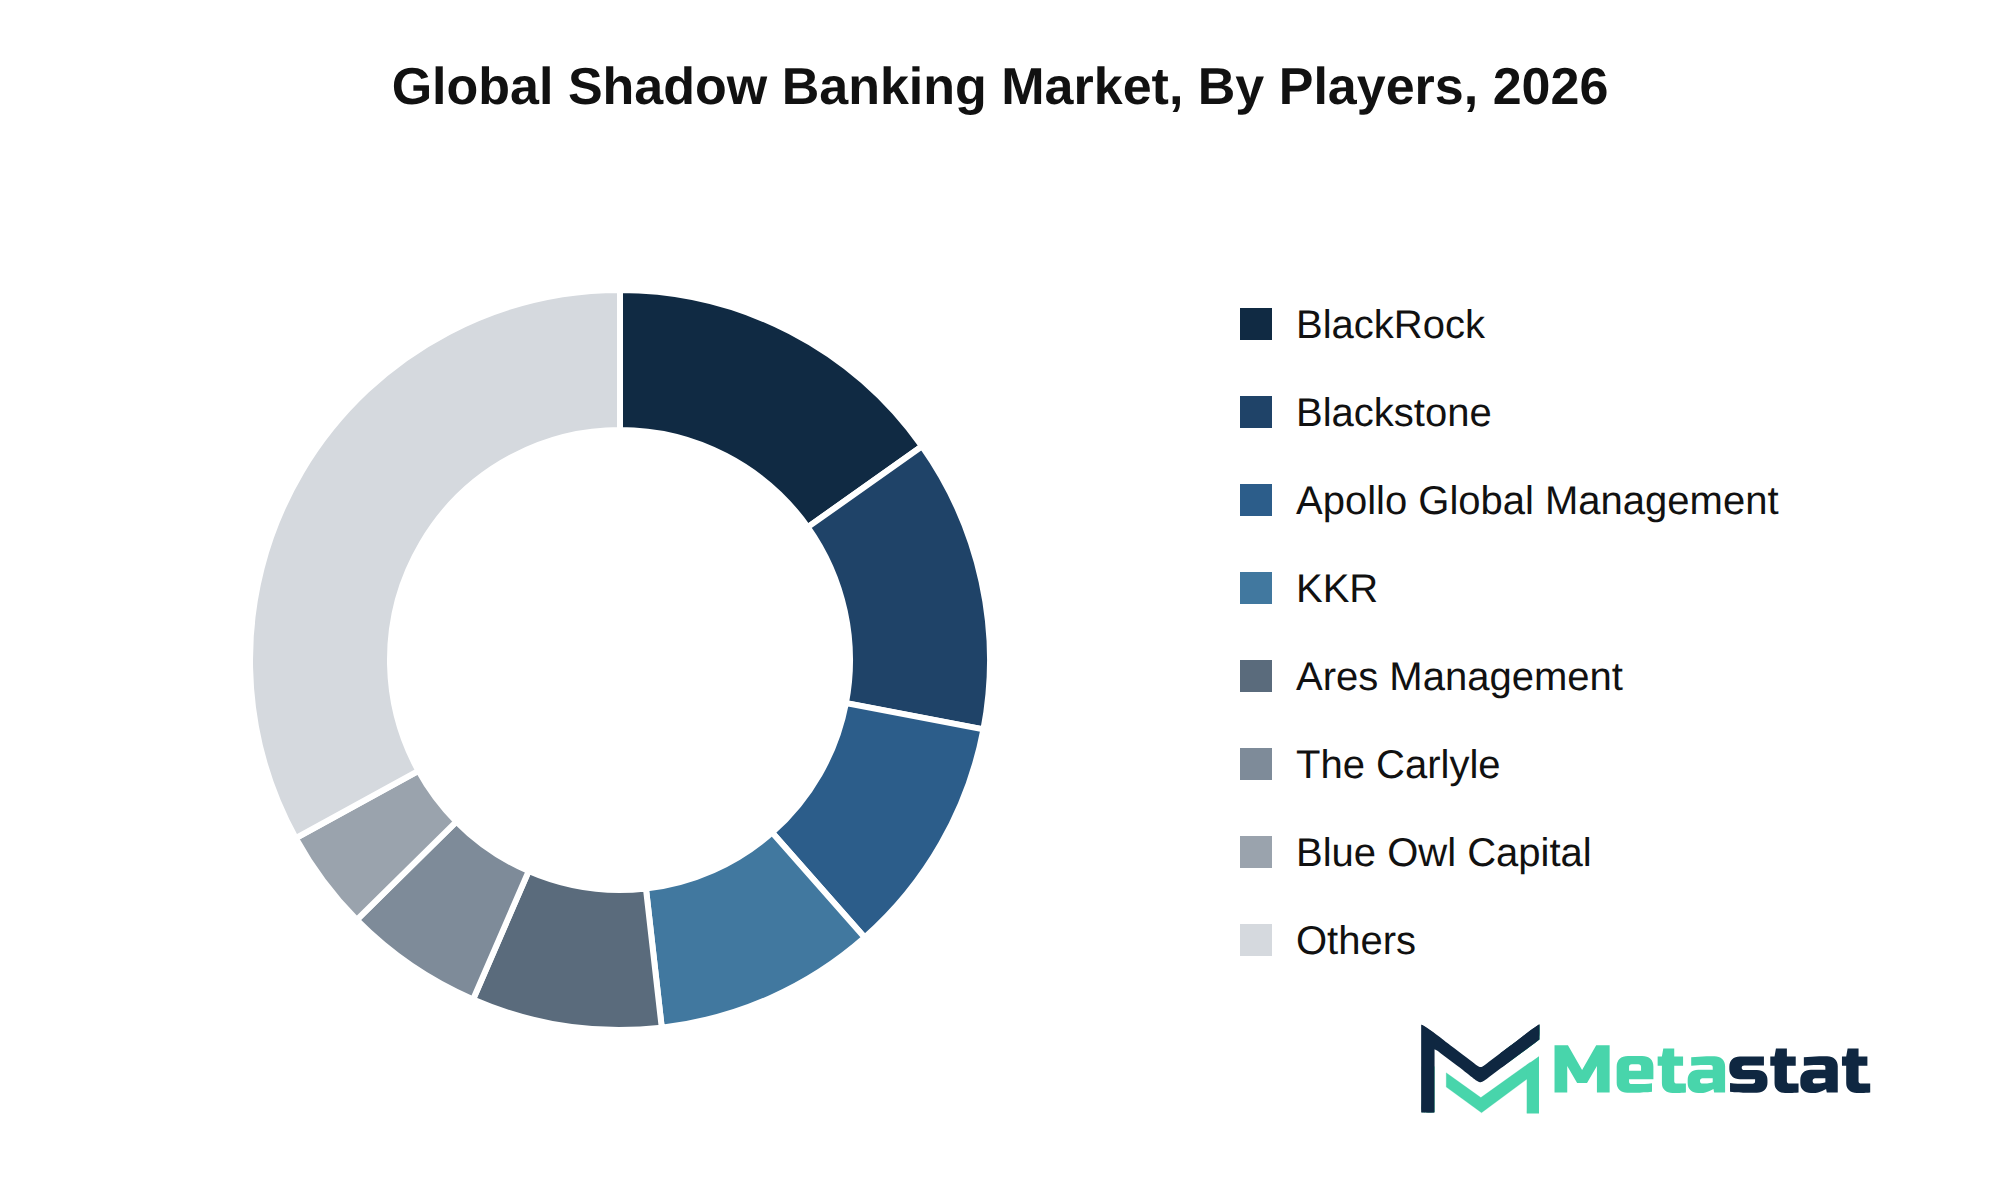
The Shadow Banking market features a diverse array of players engaging in various strategic behaviors to enhance their competitive positioning. Leading firms including BlackRock, Inc., Apollo Global Management, Inc., and Blackstone Inc. leverage mergers and acquisitions to consolidate market presence and expand service offerings.
Investment funds and finance companies have established partnerships and joint ventures to create cross-industry ecosystems, enhancing customer access and diversifying risk. Companies like PIMCO and KKR & Co. Inc. focus on product differentiation through innovative financial solutions and proprietary technologies, which strengthen their market standing.
The competitive dynamics of the market will evolve significantly owing to increased barriers to entry resulting from heightened regulatory scrutiny and complex financial environments. Established entities including The Carlyle Group Inc. and Oaktree Capital Management, L.P. benefit from strong brand equity and customer retention strategies, which contribute to their sustained growth and market influence.
Anticipated shifts in consumer preferences towards alternative financing options favor agile firms that adapt quickly. The emphasis on strategic growth vectors will guide companies in navigating this competitive landscape effectively.
Market size is forecast to rise from USD 85,576.4 million in 2025 to over USD 139,559.1 million by 2033. The base case indicates a growth trajectory at a CAGR of 6.3%. Various factors contribute to this outlook, including macroeconomic trends and shifts in downstream demand. The maturation of core industries necessitates adaptation to changing consumer preferences, creating opportunities for growth in the Shadow Banking market.
Economic cycles influence capital allocation strategies, with fluctuations in demand prompting adjustments in investment approaches. Regulatory evolution shapes the landscape, with imminent compliance milestones driving operational changes within the market. Geopolitical realignments and global supply chain shifts impact both supply dynamics and market stability, prompting firms to reassess their strategic imperatives.
Next-generation technology integration enhances operational efficiency and creates new growth pockets within the market. R&D commercialization timelines dictate the introduction of innovative products, positioning players to meet evolving enterprise needs. Strategic capital allocation directives, including infrastructure commitments and CapEx investments, reflect a commitment to long-term growth and competitiveness.
Emerging white-space opportunities present avenues for market players to capture unmet needs, stimulating further investment and innovation. Executive-level strategic imperatives focus on defensibility roadmaps that ensure sustainable growth. With these insights, stakeholders navigate the complexities of the Shadow Banking market, aligning their strategies with anticipated trends and demands.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Shadow Banking market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 6.3% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Financial Intermediary Type, Credit Type, End User, and Region |
By Region | North America (By Financial Intermediary Type, Credit Type, End User, and Country)
|
Europe (By Financial Intermediary Type, Credit Type, End User, and Country)
| |
Asia Pacific (By Financial Intermediary Type, Credit Type, End User, and Country)
| |
South America (By Financial Intermediary Type, Credit Type, End User, and Country)
| |
Middle East and Africa (By Financial Intermediary Type, Credit Type, End User, and Country)
|
Find answers to common questions about this report
The Shadow Banking market size was valued at USD 85,576.4 million in 2025, according to the Metastat Insights study.
The Shadow Banking market is projected to grow at a CAGR of 6.3% during the forecast period from 2026 to 2033.
The North America Shadow Banking market size is estimated to reach USD 48,720.1 million by 2033.
The Investment Funds segment leads the Shadow Banking market with a projected value of USD 43,989 million by 2033, based on its growth rate compared to other segments.
Key drivers for the Shadow Banking market include favorable macro-economic factors including rising GDP growth and increased consumer confidence, which enhance demand for financial services. advancements in digital transformation, including automation and artificial intelligence, improve operational efficiency and customer experience, further propelling market growth.
North America holds the dominant share of the Shadow Banking market, with a value of USD 48,720.1 million projected for 2033, representing 36.1 percent of the total market.
Favorable macro-economic factors, including rising GDP growth and increased consumer confidence, support product adoption in the Shadow Banking market. advancements in digital transformation, including automation and artificial intelligence, enhance operational efficiency and customer experiences, driving demand for diversified financial products.
The Shadow Banking market is estimated to reach a valuation of USD 139,559.1 million by 2033.
Key players operating in the Shadow Banking market include BlackRock, Inc., Apollo Global Management, Inc., Ares Management Corporation, Blackstone Inc., KKR & Co. Inc., The Carlyle Group Inc., and The Vanguard Group, Inc.
Regulatory tightening presents significant challenges for the Shadow Banking market, increasing compliance hurdles and operational complexity. Macroeconomic headwinds, including inflationary pressures and geopolitical instability, further complicate investment climates and affect overall market performance.
Choose Your License
Global Shadow Banking Market
The analysts below cover Banking & Finance research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.
Replacing petrochemical surfactants with bio-based alternatives requires realistic timelines on industrial precision fermentation scaling. The market research broke down commercialization timelines, feedstock sugar price sensitivities, and regional cosmetic ingredient regulatory approvals in Europe and East Asia. That supplier readiness mapping gave our formulations team reliable context when comparing renewable chemical sourcing roadmaps.
Tracking ceramic matrix composite adoption in high-bypass aero engines requires strict attention to material qualification cycles and FAA airworthiness testing milestones. The MetaStat Insight team provided a detailed timeline of silicon carbide fiber manufacturing capacity and commercial foundry lead times. Having clear visibility into upstream thermal barrier coating supply helped us stress-test our long-term component procurement strategy.
Transitioning ultra-class mining haul trucks to alternative power requires concrete data on remote hydrogen refueling infrastructure economics. The report evaluated megawatt-scale electrolyzer installation expenses, onsite storage safety mandates, and heavy-duty fuel cell stack degradation under continuous duty cycles. That technical rigor helped our engineers benchmark realistic total operating cost horizons for off-highway fleet decarbonization.
Explore related market intelligence reports worth reading alongside this one.