
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Norway Data Center Market Size, Share, By Data Center Type (Hyperscale Data Centers, Colocation Data Centers, Edge Data Centers and Others), By Tier Level (Tier 1 and Tier 2, Tier 3 and Tier 4), By Data Center Capacity (Below 5 MW, 5-20 MW, 20-50 MW, 50-100 MW and Above 100 MW), By End-Use Industry (Cloud Service Providers and Internet Platforms, Telecommunications, BFSI, Government and Public Sector, Energy and Utilities, Manufacturing and Industrial, Retail and E-commerce, Healthcare and Others), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5302
September 18, 2026
261 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $1,081.7 Million in 2025, projected to reach $2,017.6 Million by 2033 at a 8.1% CAGR.
Dominant Segment: Colocation data centers lead the Norway Data Center market, capturing 45.1% of the market share. This growth is driven by increasing demand from enterprises for flexible and scalable infrastructure solutions.
Geographic Lead: Norway is positioned as an attractive location for data center investments, primarily due to its abundant renewable energy resources and commitment to sustainability, which significantly reduce operational costs.
What's Inside: The report provides a comprehensive analysis of the Norway Data Center market, covering competitive dynamics, market segmentation by type, tier level, capacity, and end-use industry, along with detailed forecasts through 2033.
Emerging Demands: The rising demand for cloud services is a key growth driver, with revenues in this segment projected to increase significantly, reflecting the broader trend of digital transformation across various industries.
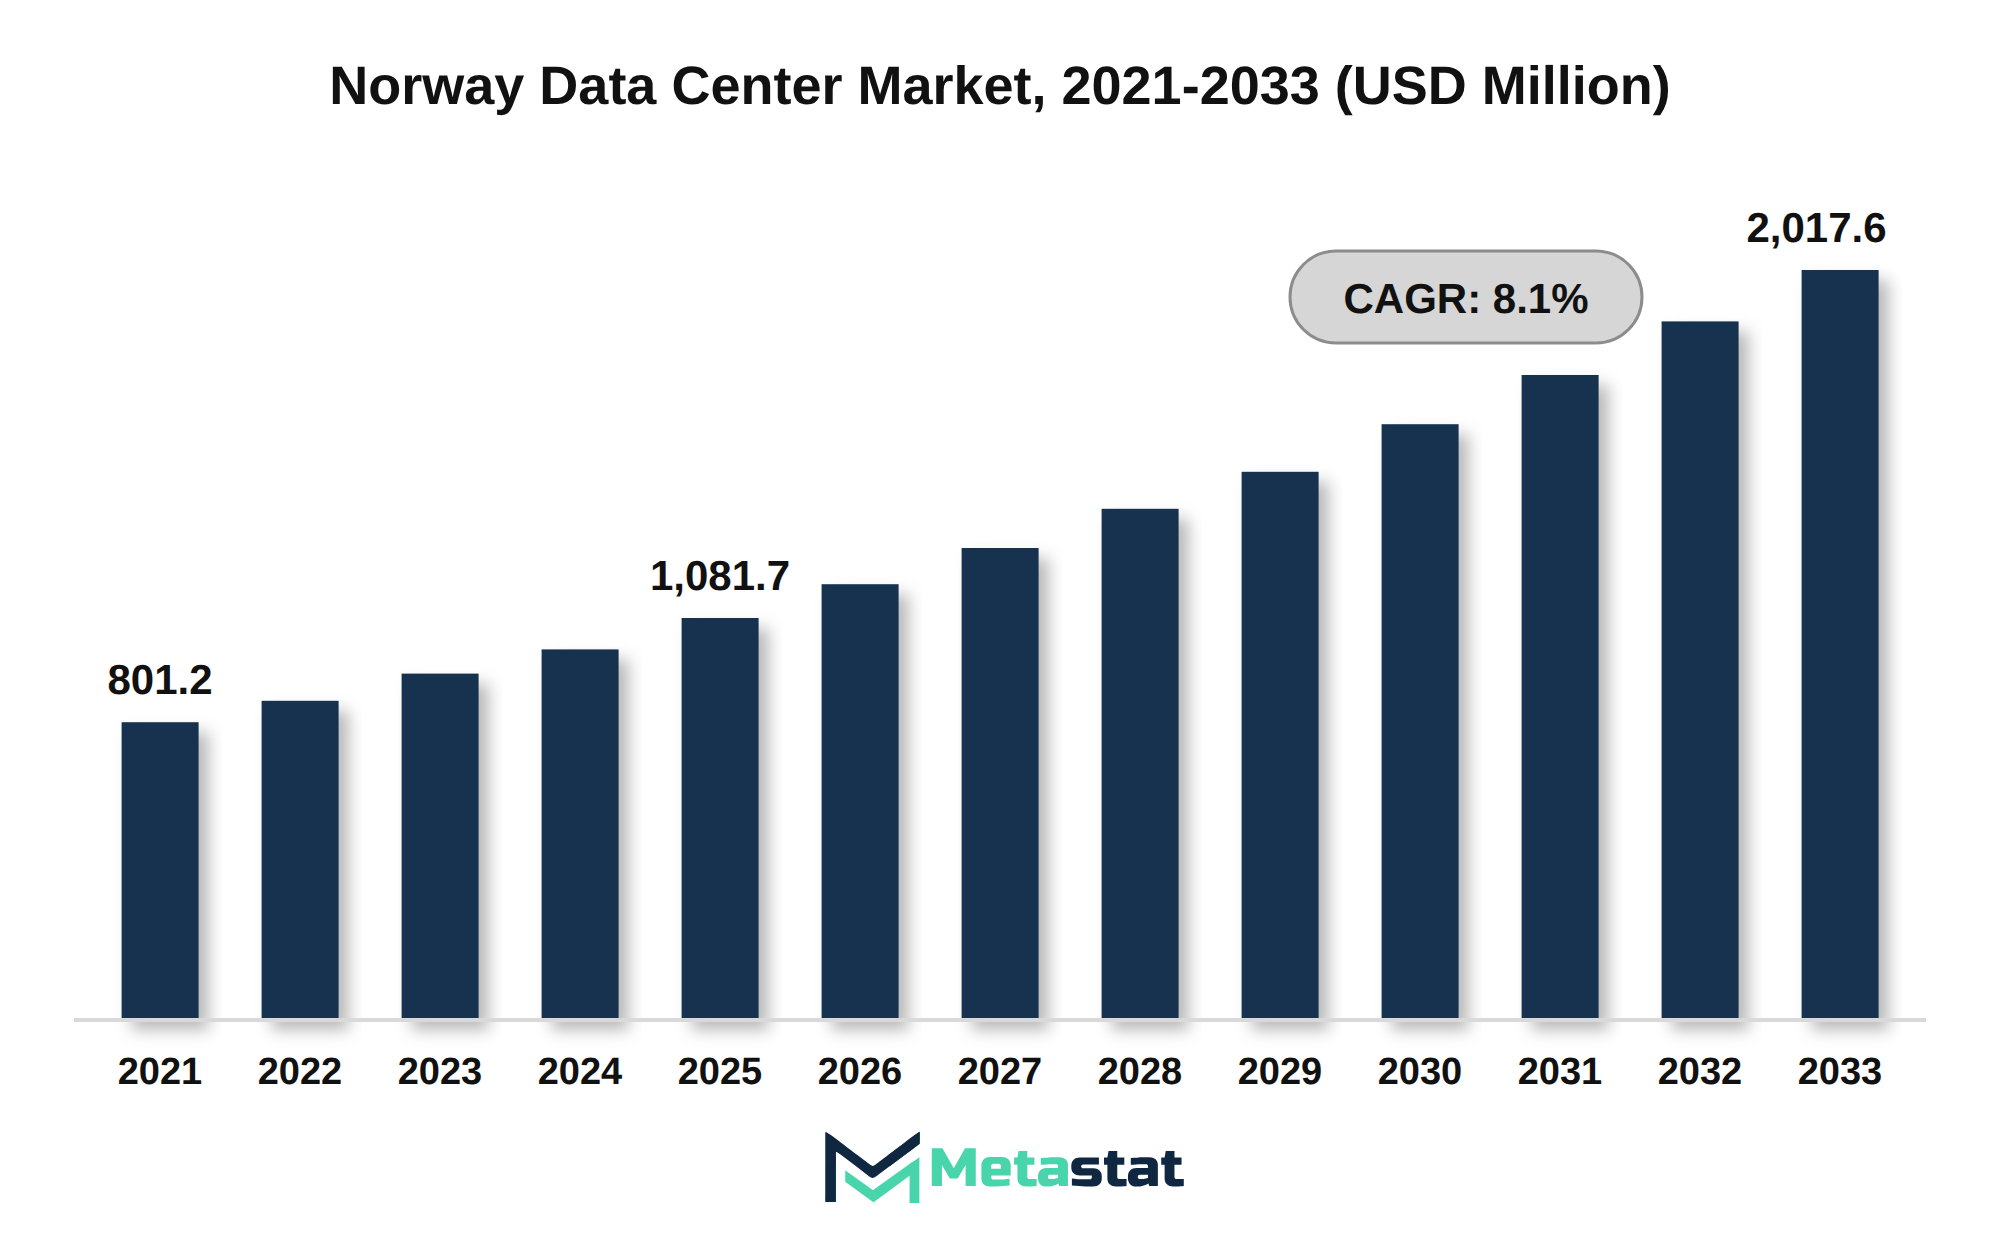
The Norway Data Center market was valued at USD 1,081.7 million in 2025 and is projected to reach USD 2,017.6 million by 2033, growing at a CAGR of 8.1% over the forecast period.
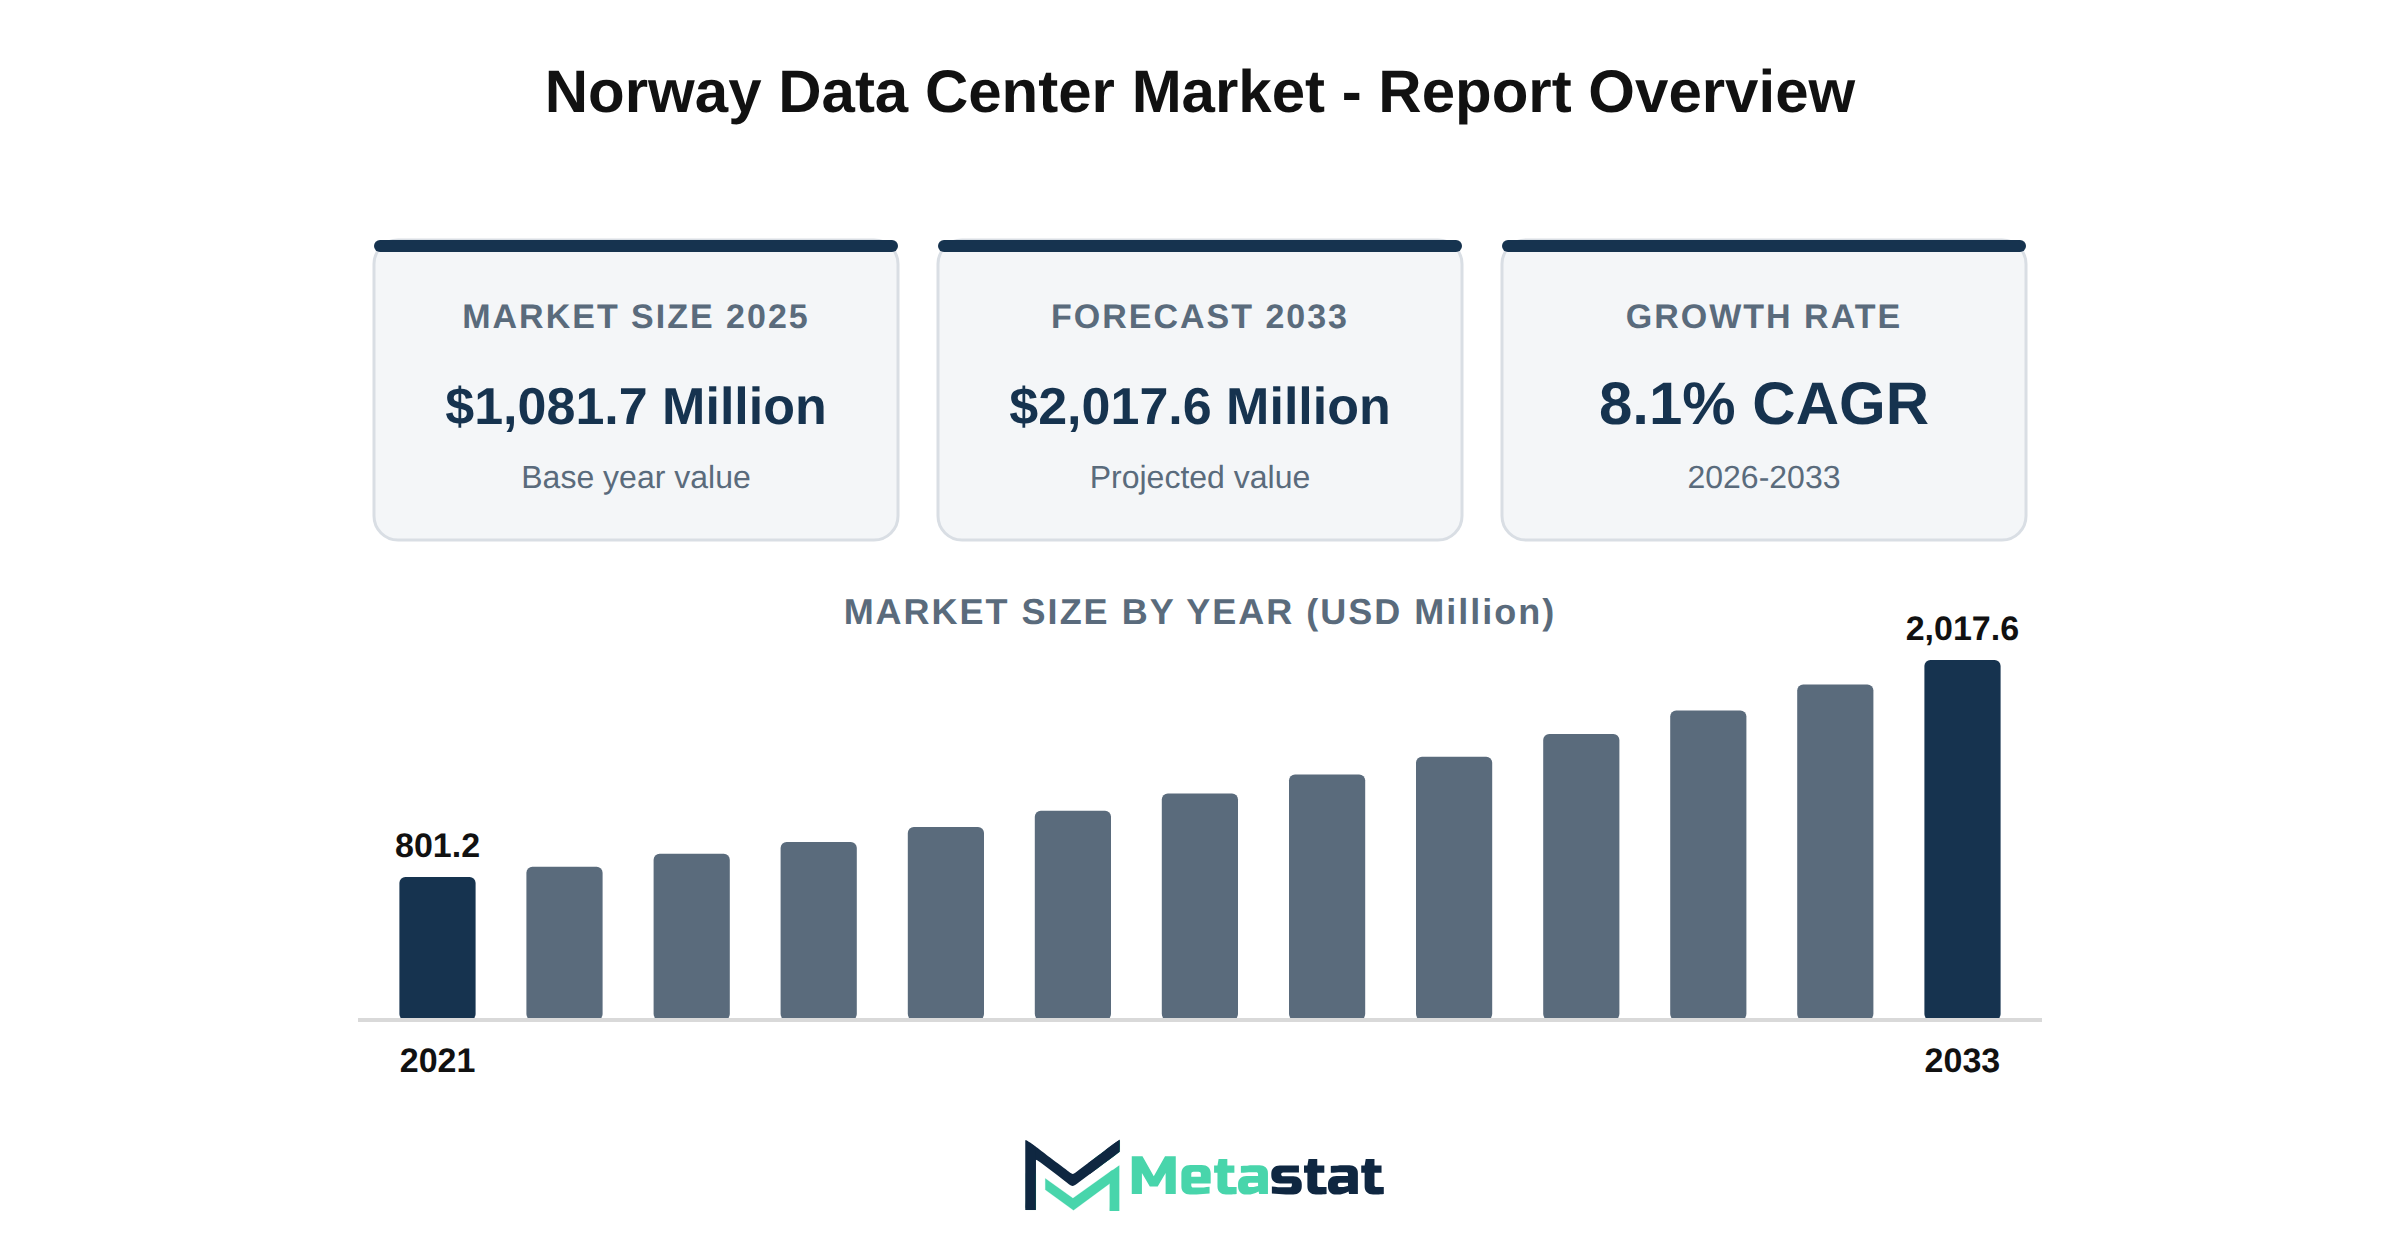
The Norway Data Center market is positioned for significant growth, evidenced by a compound annual growth rate (CAGR) of 8.1% from the base value of USD 1,081.7 million in 2025 to an estimated USD 2,017.6 million by 2033. The increasing demand for data processing capacity aligns with trends in various sectors, including cloud services, telecommunications, and government initiatives.
Hyperscale data centers, representing 32.4% of the market share, play a crucial role in this expansion. These facilities are projected to grow from USD 390.5 million in 2026 to USD 763.1 million by 2033. This growth is driven by the rise in cloud service providers and high-performance computing applications, which leverage the scalability and efficiency offered by hyperscale facilities.
Colocation data centers constitute the largest segment, capturing 45.1% of the market. This segment is expected to reach USD 880.5 million by 2033, indicating strong demand from enterprises seeking flexible and scalable infrastructure solutions. The increasing reliance on third-party data center services reflects the shift in operational strategies across various industries.
Grid connection capacity and constraints significantly impact the development trajectory of the market. Investment in grid infrastructure is essential to support the growing demand for power, particularly owing to the requirement for reliable and high-capacity electrical supply. The integration of renewable energy sources into the grid enhances sustainability efforts while addressing concerns related to energy costs.
Norway's abundant renewable power availability presents a competitive advantage for data center operators. The country's commitment to sustainability, coupled with the lower costs of renewable energy, positions it because an attractive location for data center investments. This factor influences operational costs and aligns with global sustainability goals.
The demand for artificial intelligence (AI) and high-performance computing (HPC) continues to shape the requirements of the Norway Data Center market. Businesses increasingly rely on advanced computing capabilities, driving the need for robust data center infrastructure that supports intensive workloads and rapid data processing.
Regulatory frameworks and permitting processes in Norway reflect the increasing focus on data sovereignty and compliance. Operators navigate a landscape that emphasizes security and environmental standards, ensuring that facilities meet national and international regulations. This regulatory environment influences the speed and efficiency of data center deployment.
Investment and development pipelines in Norway's data center sector reflect a strong outlook for growth. Stakeholders, including cloud service providers and telecommunications companies, actively pursue opportunities to enhance their infrastructure capabilities. The expanding footprint of data centers aligns with the increasing digitalization across various sectors.
The development pipeline for hyperscale data centers in Norway indicates strong growth, driven by increasing demand for data processing and storage. Key players are investing significantly in expanding their facilities to accommodate the needs of cloud service providers and high-performance computing applications.
Colocation utilization trends reflect a competitive pricing landscape, influenced by growing demand from various sectors. Providers are adjusting their pricing strategies to attract more clients, enhancing market penetration and increasing overall revenue potential.
Grid connection capacity presents both opportunities and constraints for new data center projects. Existing infrastructure supports moderate expansion of operations, while ongoing upgrades are essential to meet the rising energy demands of new developments.
Renewable power availability in Norway offers a strategic advantage for data center operators. The country's commitment to sustainability and its abundant renewable resources contribute to lower energy costs, enhancing operational efficiency and environmental compliance.
Demand for AI and high-performance computing continues to influence investments in the market. Organizations are increasingly seeking data center capacity that supports advanced computing capabilities, driving innovation and technological advancements.
Regulatory frameworks and permitting processes for data centers in Norway evolve to accommodate market growth. Streamlined procedures and supportive policies facilitate the establishment of new facilities, ensuring compliance with environmental standards while promoting development.
Growth drivers in the Norway Data Center market include increased cloud adoption, rising data consumption, and the push for digital transformation across industries. These factors create a favorable environment for investment and expansion opportunities.
Hyperscale data center expansion in Norway is expected to accelerate due to the increasing presence of global technology firms. This trend highlights the country's attractiveness for large-scale operations, resulting in heightened competition among providers.
Colocation demand and capacity growth are prevalent across Norway, driven by the influx of businesses seeking scalable solutions. Facilities are adapting to accommodate varying client needs, ensuring flexibility and responsiveness in service delivery.
The surge in AI and high-performance computing demand prompts data centers to enhance their service offerings. This trend positions facilities to capture a larger share of the market, catering to organizations focused on data-intensive applications.
Norway's renewable power advantage enhances its appeal within the data center industry. Facilities leveraging green energy sources benefit from lower operational costs, aligning with the global emphasis on sustainability.
Grid capacity and power availability for new projects remain critical considerations for development. Enhanced infrastructure investment supports the energy requirements of expanding data center operations, ensuring reliable service delivery.
The investment and development pipeline for data centers in Norway reflects ongoing confidence in the market. Strategic partnerships and collaborations further support growth, facilitating the entry of innovative technologies and solutions.
Cloud service provider demand for Norwegian data center capacity is expected to persist, driven by increasing reliance on cloud-based services. This trend highlights the importance of infrastructure investments to support future growth.
Deployment trends for edge data centers in Norway indicate a shift toward localized solutions. These facilities address latency concerns and improve service delivery for end-users, enhancing overall market dynamics.
Construction and site selection trends illustrate a focus on strategic locations that optimize operational efficiency. Proximity to renewable energy sources and strong connectivity options are key factors influencing site decisions.
Cooling technologies in Norwegian data centers prioritize energy efficiency and sustainability. Innovations in cooling solutions contribute to reduced energy consumption, aligning with the market's environmental objectives.
Data center sustainability initiatives and heat reuse opportunities highlight the industry's commitment to minimizing environmental impact. Efforts to repurpose waste heat further enhance operational efficiency, positioning the market favorably for future growth.
Regulatory compliance and permitting trends for data centers in Norway evolve in response to market needs. Continued collaboration between industry stakeholders and regulatory bodies ensures a conducive environment for development.
Demand for secure hosting and data sovereignty in Norway drives interest in local data center solutions. Organizations prioritize compliance with data protection regulations, strengthening the market's appeal to businesses seeking reliable hosting options.
The competitive landscape among Norway's data center operators reflects a dynamic environment. Providers are diversifying their service offerings and enhancing operational capabilities to maintain a competitive edge.
Pricing dynamics within the hyperscale and colocation segments in Norway highlight the importance of adaptability. Operators are responding to market fluctuations by adjusting pricing strategies to remain competitive in a changing environment.
Fiber connectivity and digital infrastructure play a crucial role in supporting data center growth. Enhanced connectivity options facilitate efficient data transfer, positioning the market favorably for future expansion.
Enterprise and public sector demand for data center services in Norway continues to rise. This trend reinforces the need for reliable infrastructure that addresses the diverse needs of various sectors.
Opportunities for regional data center development extend beyond Oslo, with several areas showing potential for growth. The increasing demand for data services prompts exploration of new locations, diversifying the market landscape.
Investment in digital transformation significantly influences the Norway Data Center market. Increasing demand for enhanced data processing capabilities, coupled with the transition of businesses toward cloud-based solutions, drives the requirement for advanced data center infrastructure. Companies seek to enhance operational efficiency and improve service delivery, necessitating substantial capital investments in upgraded facilities and technology.
Growing reliance on automation, artificial intelligence, and software integration pushes enterprises to modernize existing data center capacities. This trend attracts substantial venture funding and public-private partnerships, creating a robust capital investment environment. Enhancing technological integration optimizes operational productivity and supports cost-efficiency initiatives.
Cloud service providers and telecommunications industries benefit from this shift, leading to increased competition among data center operators. Consequently, the market expands rapidly, with projections indicating significant revenue growth through the forecast period. The focus on innovation and sustainability strengthens the competitive landscape, ensuring the Norway Data Center market remains a key contributor to the region's digital economy.
The Norway Data Center market experiences significant growth driven by technological integration, particularly in automation and artificial intelligence. This investment allows operators to digitize legacy processes while enhancing operational efficiency. Advanced software solutions streamline data management, increase processing speeds, and reduce operational costs.
Cloud service providers and internet platforms heavily influence this trend, requiring advanced data center capabilities to support expanding digital offerings. The shift towards automation enables these service providers to manage vast amounts of data more effectively, leading to improved service delivery and customer satisfaction.
This growth aligns with the ongoing digital transformation across various sectors, where organizations increasingly rely on data-driven insights. Enhanced data center capabilities position providers to attract a larger share of the growing demand, contributing to increased revenue streams and market penetration.
Regulatory compliance hurdles present challenges within the Norway Data Center market, affecting operational efficiency and cost structures. Stringent regulations and legal mandates create complexities for data center operators, leading to increased expenditure on compliance measures. The necessity to align with evolving regulatory requirements strains financial resources, particularly for smaller players in the market, impacting their competitiveness and ability to scale operations.
Macroeconomic headwinds contribute to a more challenging environment for the market. Inflationary pressures increase operational costs, while capital stagnation hampers investment in infrastructure development. These economic factors impede expansion efforts, particularly in segments requiring substantial upfront capital investment, including hyperscale and colocation data centers. Operators face increasing pressure to maintain profitability while navigating these economic challenges.
Infrastructure gaps and connectivity deficits further restrain growth potential. Regions with outdated infrastructure experience difficulty in meeting the rising demand for data services, limiting service reliability and overall market expansion. Deployment bottlenecks arise from inadequate telecommunications and power infrastructure, particularly in rural areas, affecting service delivery timelines and operational efficiency. These elements collectively inhibit the market's ability to cater to the growing needs of end-user industries.
Workforce overhead contributes to rising operational costs. The shortage of skilled labor in the data center sector exacerbates hiring challenges, forcing operators to offer competitive salaries to attract qualified professionals. This dynamic leads to increased overhead, impacting profit margins and hindering the ability to invest in innovative technologies and operational improvements. Consequently, these labor challenges limit the overall growth potential of the Norway Data Center market.
Data security vulnerabilities and privacy concerns remain key issues for stakeholders. The increasing volume of sensitive data stored within data centers raises the risks associated with data breaches and IP theft. Heightened awareness surrounding cybersecurity threats pressures operators to invest in advanced security measures, driving up costs and potentially diverting funds from expansion initiatives. Such factors contribute to a cautious approach towards growth within the market.
The Norway Data Center market faces challenges stemming from geopolitical fragmentation, impacting supply chain stability and operational efficiency. Variability in international relations often leads to trade deficits and tariff friction, complicating the procurement of essential components. This situation affects suppliers who rely on global networks for feedstock and technology, resulting in heightened costs and delays.
Technological disruptions further exacerbate market challenges by introducing complexities in research and development integrations. Companies encounter interoperability friction that hinders operations within their data center ecosystems. Such barriers increase compliance overhead and increase operational risks, straining resources in an already competitive landscape.
Pricing compression and margin pressures arise from evolving legal liabilities and the demand for sustainable practices. The push for decarbonization mandates adds another layer of complexity, driven by firms striving to meet environmental expectations while managing rising input costs. The workforce skill gap presents an additional hurdle; the demand for specialized talent remains high while retention pressures mount, impacting overall productivity.
These factors collectively create a challenging environment for the Norway Data Center market, influencing growth prospects and strategic investments. Companies navigate these turbulent dynamics to maintain competitiveness and meet the evolving demands of the industry.
Increasing demand for cloud services significantly influences the Norway Data Center market. Cloud service providers and internet platforms represent a growing segment, with revenues projected to rise from USD 359.3 million in 2026 to USD 699.7 million by 2033, reflecting a compound annual growth rate of 10 percent. This shift aligns with the global trend toward digital transformation, where businesses transition to cloud-based solutions for enhanced operational efficiency and scalability.
The market benefits from infrastructure modernization initiatives that support the expansion of data center capabilities. Investments in next-generation innovations drive improvements in energy efficiency and operational performance, appealing to sustainability-conscious businesses. These developments promote the adoption of environmentally friendly practices, aligning with broader environmental, social, and governance (ESG) objectives.
Geographical expansion further drives opportunities within the market. Businesses increasingly seek to establish data center operations in Norway due to its favorable regulatory environment and access to renewable energy sources. This strategic positioning attracts both local and international players, enhancing competition and stimulating investment in advanced data center technologies.
Evolving buying behaviors and digital procurement shifts reshape the market landscape. Organizations prioritize vendors that demonstrate a commitment to sustainability and offer integrated solutions tailored to specific industry needs. This focus on niche application growth encourages providers to diversify their service offerings, ultimately enhancing market resilience and driving innovation throughout the sector.
Overall, these factors collectively position the Norway Data Center market for sustained growth through 2033, driven by emerging demands, strategic investments, and evolving consumer expectations.
The Norway Data Center market is segmented based on Data Center Type, Tier Level, Data Center Capacity, and End-Use Industry.
Valued at USD 390.5 million in 2026, the hyperscale data centers segment is projected to reach USD 763.1 million by 2033, reflecting a CAGR of 10% during the forecast period. This growth aligns with rising demand from cloud service providers and internet platforms, which increasingly rely on robust data processing capabilities. The transition towards advanced cloud solutions contributes to heightened investment in hyperscale facilities across the Norway Data Center market.
Technological maturation plays a crucial role in driving segment expansion. Enhanced efficiency and scalability of hyperscale data centers support the growing need for data storage and processing. Consequently, operators prioritize next-gen upgrades to their infrastructure, focusing on energy efficiency and sustainability. Increased focus on sustainability leads to innovations in cooling technologies and power management systems, which further strengthens the segment.
The end-use dynamics indicate a notable shift towards cloud-based applications, with hyperscale data centers serving because a backbone for digital transformations across various industries. This trend drives consumption patterns toward greater reliance on cloud infrastructures for IT operations, data analytics, and service delivery. Regulatory compliance standards compel organizations to adopt more secure and efficient data management practices, reinforcing the value of hyperscale facilities within the market.
Cost structures and pricing volatility present challenges while driving operators to optimize their investment strategies. High capital expenditure associated with building and maintaining hyperscale data centers requires careful financial planning. However, the long-term operational efficiencies achieved through scale economies often mitigate these pressures, leading to improved margins over time.
Strategic opportunity windows arise from the evolving technological landscape, offering avenues for innovative solutions in hyperscale data center operations. Continuous advancements in artificial intelligence and machine learning enhance data management capabilities, ensuring that operators stay ahead of demand fluctuations. The Norway Data Center market benefits from these developments, positioning hyperscale facilities because vital components in the digital ecosystem.
Strong growth in the Colocation Data Centers segment reflects increasing demand from various industries. This segment is estimated to reach USD 880.5 million by 2033, at a CAGR of 7.6% during the forecast period. Factors including the rise of digital transformation initiatives and the growing reliance on cloud services drive significant market expansion. The need for scalable and flexible infrastructure pushes businesses to adopt colocation services, enabling them to reduce operational costs while enhancing efficiency.
Adoption rates among cloud service providers, telecommunications, and other sectors accelerate owing to their pursuit of reliable and secure data management solutions. Companies benefit from reduced capital expenditures and the ability to focus on core competencies while relying on third-party providers for data center operations. The market's evolution is influenced by the ongoing technological maturation and demand for next-generation upgrades, which improve performance and energy efficiency.
With a growing emphasis on regulatory compliance and data security, colocation data centers offer robust solutions that meet the requirements of diverse end-use industries. Cost structures around energy and real estate play a critical role in pricing volatility and margin pressures, compelling operators to adopt innovative strategies. The Norway Data Center market presents a strategic opportunity window, driving investment in enhanced infrastructure and service offerings.
Investment in Edge Data Centers aligns with the increasing need for low-latency applications and real-time data processing, particularly in urban environments. This demand arises from the expansion of Internet of Things (IoT) devices and the growing reliance on applications that require rapid data transmission, including autonomous vehicles and smart cities. Companies seeking to enhance their operational efficiency and improve user experiences drive this trend, making Edge Data Centers a critical component of the overall data center infrastructure.
Technological maturation in networking and computing capabilities supports the proliferation of Edge Data Centers. Advances in virtualization and server technology enable the deployment of smaller, more efficient data centers closer to end-users, reducing latency and enhancing speed. The market's evolution reflects the shift towards distributed computing architectures, where processing occurs at or near the data source rather than centralized locations.
Edge Data Centers segment is expected to reach USD 227.4 million by 2033. This growth forecast highlights the important role of edge computing in the Norway Data Center market, where businesses increasingly prioritize infrastructure that supports local data processing and storage. The strategic significance of Edge Data Centers is further emphasized by the rising demand for services that ensure compliance with stringent data privacy regulations.
Investment in Edge Data Centers presents a strategic opportunity window for companies looking to capitalize on the evolving landscape of digital services. The drive towards enhanced customer experience and the need for agility in service delivery highlight the importance of edge computing solutions. While organizations expand their digital footprints, the focus on integrating edge solutions into broader IT strategies becomes essential, positioning these facilities because vital assets in the competitive data center market.
The Others (Managed, Modular) segment is projected to grow at a CAGR of 0.6% during the forecast period. This segment, while smaller in scale compared to others, plays a crucial role in accommodating specific client requirements for flexibility and customized solutions within the Norway Data Center market. Managed and modular data centers attract companies seeking cost-effective solutions that do not compromise on performance and reliability. Increased awareness of sustainable practices influences adoption, driving demand for energy-efficient designs and renewable energy sources in data center operations.
Strategic partnerships with technology providers enhance the capabilities of managed data centers, enabling effective integration of advanced technologies. The ability to scale solutions rapidly aligns with the evolving needs of various end-use industries, including telecommunications and BFSI, creating a favorable environment for growth. While organizations continue to seek efficient and adaptable infrastructure, the segment's contribution to the overall market reinforces its significance.
Valued at USD 203.6 million in 2026, the Tier 1 and Tier 2 segment is projected to reach USD 267.1 million by 2033, achieving a CAGR of 4% during the forecast period. This segment's growth reflects the increasing importance of reliable, scalable infrastructure to meet the demands of various industries, particularly in light of rising data consumption and the shift towards cloud-based solutions.
Key demand drivers for this segment include the expansion of digital services and the need for enhanced operational efficiency. The growing reliance on data-driven decision making across industries emphasizes the necessity for robust data center solutions. Businesses focusing on maintaining competitive advantages invest in Tier 1 and Tier 2 facilities, providing the necessary foundation for supporting complex data operations.
Technological maturation contributes to this segment. Advancements in data center design and management allow for more efficient energy use and improved performance. This evolution attracts enterprises aiming to optimize their IT infrastructure, contributing to the segment's expansion within the Norway Data Center market.
End-use dynamics influence the growth of the Tier 1 and Tier 2 segment. Industries including telecommunications, BFSI, and government sectors exhibit increasing demand for secure and reliable data processing capabilities. These sectors require stringent compliance with regulatory standards, further driving the demand for certified data center solutions.
Cost structures and pricing volatility remain critical factors impacting investments in this segment. While initial capital expenditures for Tier 1 and Tier 2 facilities are substantial, long-term operational savings and enhanced performance justify these investments. Competition intensifies in the market, prompting suppliers to focus on providing cost-effective solutions without compromising quality.
Overall, the growth trajectory of the Tier 1 and Tier 2 segment within the Norway Data Center market highlights the increasing demand for resilient and scalable infrastructure capable of supporting diverse applications and industries. With ongoing technological evolution and market dynamics, this segment is well-positioned to capture further growth opportunities.
Increasing investment in data center infrastructure in Norway supports the growth of the Tier 3 segment. This segment is anticipated to reach USD 1,153.7 million by 2033, at a CAGR of 7.8% during the forecast period. The demand for high-availability and scalable solutions drives organizations to adopt Tier 3 data centers, particularly among cloud service providers and enterprises requiring robust data management capabilities. Technological maturation, especially in virtualization and automation, enhances the efficiency of Tier 3 facilities, allowing operators to optimize resource utilization and reduce operational costs.
Adoption of cloud services and digital platforms continues to increase demand for Tier 3 data centers, aligning with shifts in end-use dynamics across industries. Enterprises increasingly rely on these solutions to support their IT infrastructures, ensuring uptime and performance. Regulatory compliance standards in Norway influence investments in these data centers, driven by operators seeking certifications that affirm their commitment to security and reliability.
Pricing volatility, stemming from supply chain challenges and raw material costs, affects cost structures and margins within the segment. Strategic opportunity windows arise from innovations that enhance operational efficiency and sustainability in Tier 3 facilities. This segment’s growth reflects a broader trend in the Norway Data Center market, emphasizing the importance of adaptable and reliable data infrastructure in meeting evolving business needs.
Investment in Tier 4 data centers shows a clear upward trajectory within the Norway Data Center market, driven by a combination of rising enterprise demand for high-availability infrastructure and the growing importance of regulatory compliance. Increasing reliance on digital services across industries necessitates robust, reliable systems, resulting in heightened focus on data center capabilities that meet stringent uptime requirements.
The projected market value of USD 596.8 million by 2033 reflects a response to evolving technological demands and the push for next-generation upgrades. Firms investing in Tier 4 facilities prioritize resilience and efficiency, often integrating advanced cooling solutions and power management technologies to enhance operational performance and reduce environmental impact.
While organizations across various sectors, including telecommunications and BFSI, adopt more complex IT architectures, the need for higher-tier data centers becomes evident. Consumption patterns are shifting towards facilities that offer enhanced security and redundancy features. Consequently, the demand for Tier 4 data centers in the market is expected to accelerate, reinforcing their significance in supporting critical business operations.
The upward trajectory of the Tier 4 segment highlights the strategic opportunity for growth within the Norway Data Center market. Investment in top-tier infrastructure aligns with the increasing necessity for reliability and compliance, creating opportunities for sustained expansion through 2033.
Valued at USD 155.7 million in 2026, the Below 5 MW segment is projected to reach USD 191.3 million by 2033, at a CAGR of 3% during the forecast period. This segment serves an essential role in the Norway Data Center market, catering primarily to small and medium-sized enterprises that require efficient yet scalable data solutions. Rising demand for data processing and storage drives growth in this segment.
Adoption of cloud services and virtualization technologies significantly contributes to the growth of the Below 5 MW segment. Businesses increasingly require flexible and cost-effective data management solutions, creating upward pressure on capacity in this segment. Regulatory compliance standards, alongside the rising necessity for data security, influence client decisions, leading to greater investment in smaller, focused data center solutions.
Technological maturation in cooling and energy efficiency boosts the attractiveness of the Below 5 MW segment, enabling providers to offer competitive pricing without compromising performance. This trend enhances market viability, attracting a diverse range of end-use industries, including telecommunications, healthcare, and retail. Companies recognize the advantages of smaller data centers in improving operational efficiency and reducing capital expenditures, creating strategic opportunity windows.
Investment in infrastructure resilience and supply chain stability remains critical for the segment, especially given the increasing complexity of data management needs. The Norway Data Center market anticipates further evolution driven by technological advancements and shifting consumer preferences, ensuring growth trajectories for the Below 5 MW segment in the coming years.
Significant growth in the 5-20 MW capacity segment reflects increasing demand for reliable data center solutions within various industries. Adoption stems from expanding digital infrastructure requirements, particularly among cloud service providers and telecommunications companies. Consumer reliance on data-driven applications drives demand for this segment, positioning it for continuous expansion.
Valued at USD 478.6 million by 2033, this segment is projected to grow at a CAGR of 5.3% during the forecast period. Technological maturation and next-generation upgrades facilitate the development of data centers in this capacity range, enhancing operational efficiency and service delivery.
Downstream applications span various sectors, including BFSI and government, which require robust data solutions. Regulatory compliance standards and certifications contribute to the evolving landscape, further motivating investments and operational strategies aimed at achieving competitive advantage within the Norway Data Center market.
Investment in the 20-50 MW capacity segment reflects a growing demand for larger data center solutions within the Norway Data Center market. This segment is anticipated to reach USD 531.4 million by 2033, driven by the increasing requirements of cloud service providers and other enterprises seeking robust infrastructure. The need for higher data processing capabilities and storage has prompted the adoption of larger data centers, particularly among technology and telecommunications sectors.
Technological advancements and the maturation of data center infrastructure result in enhanced efficiency and reduced operational costs. These factors encourage investment in larger facilities, allowing companies to meet rising consumer expectations for speed and reliability. Strategic opportunities arise from the evolving landscape of data usage, where larger capacities support emerging technologies including artificial intelligence and big data analytics.
While businesses continue to transition to digital platforms, the demand for 20-50 MW data centers is expected to grow, positioning this segment because a key component of the market's expansion. The ongoing shift towards cloud computing and the increasing emphasis on data security drive investments into this segment, creating a favorable environment for growth. Overall, the Norway Data Center market demonstrates a robust trajectory, driven by evolving client needs and advancements in technology.
Factors driving growth in the 50-100 MW capacity segment stem from rising demand for efficient and scalable data center solutions. Enterprises increasingly seek robust infrastructure to support digital transformation initiatives, leading to heightened investment in this capacity range. Demand from cloud service providers and large enterprises seeking high-performance computing capabilities fuels the expansion of this segment, contributing to projected growth at a CAGR of 10.4% during the forecast period.
The evolution of technology significantly influences the expansion of the Norway Data Center market. Advances in cooling technologies and energy-efficient designs enhance operational efficiency, driving investments in data centers with higher capacities. Enterprises recognize the necessity for energy-efficient solutions, prompting the adoption of 50-100 MW facilities to achieve sustainability targets while maintaining performance. This trend aligns with broader market developments that prioritize environmentally friendly practices.
Increased focus on regulatory compliance and industry certifications further influences the 50-100 MW capacity segment. Organizations face pressure to adhere to stringent data protection regulations, necessitating investment in upgraded facilities that meet compliance standards. Demonstrating compliance enhances competitive positioning for data center operators, attracting clients seeking reliable services.
The impact of economic factors on pricing structures presents challenges within the market. Fluctuations in energy prices and operational costs influence the overall margins for service providers operating in the 50-100 MW segment. Efficient cost management becomes essential for sustaining profitability while maintaining competitive pricing. Strategic partnerships and innovations in technology assist operators in mitigating these pressures, allowing for continued growth in this capacity range.
Capital investment outlook for the 50-100 MW segment indicates strong potential for growth. Investors recognize the increasing demand for enhanced data center capabilities, resulting in significant funding directed toward new facility construction and existing infrastructure upgrades. This influx of capital supports the development of next-generation data centers, positioning the Norway Data Center market for sustained expansion in the coming years.
Demand for data center capacity above 100 MW in the Norway Data Center market arises from the increasing requirements of large-scale enterprises and hyperscale cloud service providers. These organizations seek efficient, high-capacity facilities to support vast data processing and storage needs, driving investments into this sub-segment. The expansion of cloud computing and digital services enhances the necessity for substantial data handling capabilities, contributing to market growth.
Technological maturation plays a critical role in the adoption of larger data center capacities. Innovations in energy efficiency, cooling technologies, and modular designs facilitate the establishment of facilities that handle high power loads. These advancements attract investment from firms focusing on sustainability and operational efficiency, aligning with the evolving demands of end-use industries.
The evolving dynamics of the Norway Data Center market reflect shifts in consumption patterns, with major content providers and social media platforms pushing for increased server capacity. This trend creates a strategic opportunity window for developers looking to establish or upgrade facilities capable of supporting extensive workloads. Increased collaboration between public and private sectors around infrastructure development further enhances prospects for capacity beyond 100 MW.
Investments in the above 100 MW capacity segment align with market trends toward energy-efficient solutions and renewable energy sources, responding to customer expectations for sustainable operations. Firms prioritizing these aspects within their offerings position themselves favorably in a competitive environment. Market growth hinges on continuous improvements in technology and infrastructure, which support enhanced capabilities to meet the increasing demands of various sectors.
Cloud Service Providers & Internet Platforms segment is valued at USD 359.3 million in 2026 and is projected to reach USD 699.7 million by 2033, at a CAGR of 10% during the forecast period. The rapid expansion of digital services fuels demand for robust data infrastructure, pushing providers to enhance capacity and performance. Increasing reliance on cloud computing and digital platforms drives adoption across various industries, including finance, healthcare, and retail. This trend creates a strategic opportunity window for data center operators to upgrade facilities and pivot toward next-generation technologies.
Technological maturation in data center services enables operators to deliver enhanced performance and efficiency, thus attracting more clients. Investment in advanced cooling systems and energy-efficient designs aligns with sustainability goals, further supporting the growth of the segment. Adoption of innovative data management solutions enhances operational efficiency, ensuring competitiveness within the Norway Data Center market.
Regulatory compliance standards concerning data protection and privacy significantly influence service offerings. Providers invest in certifications to assure clients of their commitment to security and compliance, which, in turn, enhances market credibility. Cost structures are impacted by the need for compliance, where investments in security infrastructure lead to increased operational expenses.
Pricing volatility remains a consideration, driven by surging demand for services that support data-heavy applications. Market players respond by diversifying service portfolios and adjusting pricing strategies to maintain margins amid fluctuating demand. The overall landscape indicates a promising future for Cloud Service Providers & Internet Platforms within the Norway Data Center market, supported by continuous technological advancements and evolving consumer needs.
Valued at USD 261.1 million by 2033, the telecommunications segment exhibits a compound annual growth rate (CAGR) of 6.9% during the forecast period. Key demand drivers include the increasing reliance on mobile data, the growth of cloud-based services, and the expansion of 5G networks, which directly impacts the requirements for data processing and storage. Rising mobile data consumption necessitates robust data center infrastructure, driving investments in equipment and services tailored for the telecommunications sector.
Technological maturation and continuous upgrades within the telecommunications sector contribute significantly to market dynamics. Service providers consistently seek next-generation solutions that enhance network efficiency and reliability. Investments in data centers that support enhanced connectivity and provide low-latency services are essential for addressing the increasing demand for high-speed internet and data transmission. The ongoing shift towards cloud computing and edge computing further drives the telecommunications segment, increasing the need for flexible and scalable data center solutions.
Regulatory compliance standards and certification requirements play critical roles in shaping the telecommunications market. Adherence to data privacy regulations and security certifications influences the operational frameworks of telecommunications companies, impacting their choice of data center solutions. Cost structures and pricing volatility associated with energy consumption and infrastructure development create pressures that affect profitability. Service providers continually evaluate their strategies to mitigate these challenges while maintaining competitive margins.
Strategic opportunity windows arise from the growing demand for telecommunications infrastructure, particularly in urban and underserved areas. Investments in the Norway Data Center market align with the increasing need for capacity and efficiency in data handling. While telecommunications companies expand their services, collaboration with data center operators becomes vital for ensuring a resilient supply chain that meets evolving consumer expectations.
Growth in the BFSI segment stems from increasing digitalization in financial services, driving demand for efficient data management and storage solutions. Financial institutions prioritize secure and scalable data center services, accommodating heightened regulatory scrutiny and consumer expectations for data privacy. Enhanced technological capabilities facilitate quick data processing and storage, aligning with the growing trend toward cloud-based solutions.
The BFSI segment is projected to reach USD 207 million by 2033. This expansion relies on the adoption of innovative technologies including artificial intelligence and machine learning, which enhance data analytics capabilities. Financial institutions increasingly integrate these technologies into their operations to improve decision-making processes and customer service.
Investment in next-generation upgrades plays a critical role in the segment's development. Financial companies prioritize modernizing their IT infrastructure to remain competitive, ensuring they meet evolving customer demands and regulatory requirements. The shift toward digital banking and online transactions continues to push firms to enhance their data center capabilities, ultimately driving growth in the Norway Data Center market.
Investment in the Government & Public Sector segment reflects a commitment to modernizing infrastructure and enhancing service delivery through digitalization. Increased demand for reliable and secure data storage solutions significantly influences this trend, driven by government initiatives aimed at improving efficiency and public access to services. Adoption of advanced technologies, including cloud computing and big data analytics, supports the need for robust data center capabilities. The segment is projected to grow at a CAGR of 7.2% during the forecast period. Regulatory compliance standards and policy headwinds contribute to the acceleration of investments in data centers, ensuring adherence to data protection and privacy regulations.
Strategic opportunities arise from the increasing focus on sustainability within government operations. Public sector entities seek energy-efficient data center solutions to reduce environmental impact while maximizing operational efficiency. This shift aligns with broader goals of reducing carbon footprints and promoting green technology initiatives. In the Norway Data Center market, the focus on enhancing data center capabilities positions government entities to better serve the public and adapt to changing technological landscapes.
Investment in the Energy & Utilities segment within the Norway Data Center market arises from increasing demand for reliable and efficient power sources. The push towards renewable energy generation and management requires advanced infrastructure, driving the need for data centers that support these activities. Utilities are integrating more sophisticated data analytics and machine learning applications to optimize operations and improve energy efficiency.
Technological maturation drives segment expansion. Innovations in energy management systems, smart grid technology, and data processing capabilities enable energy providers to better manage resources. This trend aligns with regulatory compliance standards focusing on sustainability and energy efficiency, influencing operators to adopt modern data center solutions.
The growing emphasis on environmental concerns leads to shifts in consumption patterns among energy and utility companies. The transition towards cleaner energy sources and increased digitization in utility services creates opportunities for data centers optimized for high-performance computing. This evolution enhances operational capabilities. However, it introduces cost structures that operators manage carefully, particularly in a fluctuating market.
Strategic opportunity windows emerge due to energy providers seeking to leverage data centers for enhanced performance and reliability. Investment in next-gen upgrades ensures that facilities meet the evolving demands of the market while addressing pressure from margin dynamics. Overall, the Energy & Utilities segment remains integral to the future of the Norway Data Center market.
Demand for data centers within the manufacturing and industrial sector arises primarily from increased automation and digital transformation efforts. Manufacturers increasingly rely on data centers to support advanced analytics, supply chain management, and real-time processing. Adoption of Internet of Things (IoT) technologies within manufacturing environments drives the need for robust data center infrastructure, enabling companies to collect and analyze data generated by connected devices efficiently.
Investment in innovative technologies enhances operational efficiency and reduces downtime, underpinning the segment's growth within the Norway Data Center market. Companies face significant pressure to comply with regulatory standards and certifications, influencing their choice of data center solutions. This compliance ensures adherence to environmental and safety regulations while building trust among consumers and partners.
Cost structures within the manufacturing and industrial segment reflect the demand for scalable and efficient data center solutions. Pricing volatility remains a concern. Strategic investments in next-generation technologies, including artificial intelligence and machine learning, provide opportunities for operational cost reductions. Organizations increasingly seek partnerships with data center providers that offer tailored solutions to address unique operational challenges.
Next-gen upgrades facilitate enhanced performance and energy efficiency, essential for maintaining competitiveness. This focus on technological maturation aligns with industry trends toward sustainable practices, allowing companies to leverage data centers for improved resource management. Investment in resilient supply chains and raw material sourcing has become critical, ensuring continuity in manufacturing processes.
Disruptive alternatives, including edge computing, influence the landscape by providing localized processing capabilities. This shift allows companies to reduce latency and improve response times, particularly in time-sensitive manufacturing applications. The strategic opportunity window for players in the Norway Data Center market remains robust, driven by the ongoing need for modernization and digitalization across manufacturing and industrial sectors.
Retail and e-commerce sectors demonstrate increasing reliance on data center capabilities to support online transactions and enhance customer experiences. Growth in this segment stems from the ongoing shift towards digital commerce and the necessity for robust infrastructure to handle rising data volumes. The expansion of online retail platforms requires scalable solutions that ensure quick data processing and storage, influencing data center operators to enhance their offerings. Enhanced internet connectivity and advancements in technology facilitate online transactions, further driving demand for data centers within the market.
Customer expectations regarding speed and reliability of service create a competitive environment among retailers, propelling investment in advanced data center technologies. Efficient data management systems play a critical role in enabling retailers to analyze consumer behavior, optimize inventory, and personalize marketing efforts. This focus on data-driven strategies strengthens the position of retail and e-commerce within the Norway Data Center market, highlighting the importance of technological maturation in achieving operational excellence.
Robust infrastructure ensures compliance with regulatory standards and certifications, particularly regarding data security and privacy, which remain essential for retailers handling sensitive customer information. The market reflects a commitment to maintaining high levels of security, with investments directed towards improving resilience in data management and storage solutions. Retailers increasingly view data centers not only because facilities for storage but because integral components in their overall business strategy, reinforcing the segment's growth trajectory within the Norway Data Center market.
Healthcare providers increasingly rely on data centers to manage vast amounts of patient data, ensure compliance with regulatory standards, and improve operational efficiency. The ongoing digital transformation within the healthcare sector drives adoption of advanced technologies, including electronic health records and telemedicine, necessitating robust data solutions.
Investment in security measures remains critical. Healthcare organizations face stringent regulations regarding data privacy and security, influencing the demand for highly secure data center facilities. Compliance with these regulations promotes partnerships between healthcare providers and data center operators, ensuring adequate infrastructure for safeguarding sensitive information.
Technological maturation of cloud-based solutions enhances data storage and processing capabilities, enabling healthcare organizations to leverage big data analytics for improved patient outcomes. Adoption of innovative technologies contributes to streamlined operations and cost reductions throughout the sector.
Downstream applications in the healthcare market increasingly focus on telehealth and remote patient monitoring, which require reliable data center services to function effectively. This shift towards digital healthcare highlights the importance of data centers in supporting the evolving needs of healthcare delivery systems.
Investment in the Norway Data Center market reflects strategic opportunities for addressing healthcare data management challenges. While healthcare organizations prioritize efficiency and data security, demand for advanced data center solutions is expected to grow.
Investment in data centers serving the Others (Research & Education, Transport & Logistics) segment reflects a shift toward digital transformation across various sectors. Increasing reliance on data analytics and online resources drives demand for robust data infrastructure, enabling organizations to optimize operations and enhance service delivery. Educational institutions leverage data centers to manage vast amounts of information and support online learning platforms, while logistics companies adopt advanced technologies for inventory management and supply chain optimization.
Technological advancements in the Norway Data Center market facilitate the development of tailored solutions for these end-users. Enhanced energy efficiency and scalability of data center facilities cater to the unique needs of research and logistics operations, allowing for smooth integration of emerging technologies. Organizations increasingly prioritize compliance with regulatory standards, ensuring that data management practices align with industry requirements and maintain data security.
Market participants recognize opportunities to enhance service offerings, integrating cloud services and edge computing solutions to address the diverse requirements of research and logistics entities. These developments contribute to the overall growth trajectory of the market, reinforcing the positioning of data centers because critical components in the digital ecosystem. The strategic focus on innovative solutions positions the Others (Research & Education, Transport & Logistics) segment favorably within the broader context of the Norway Data Center market.
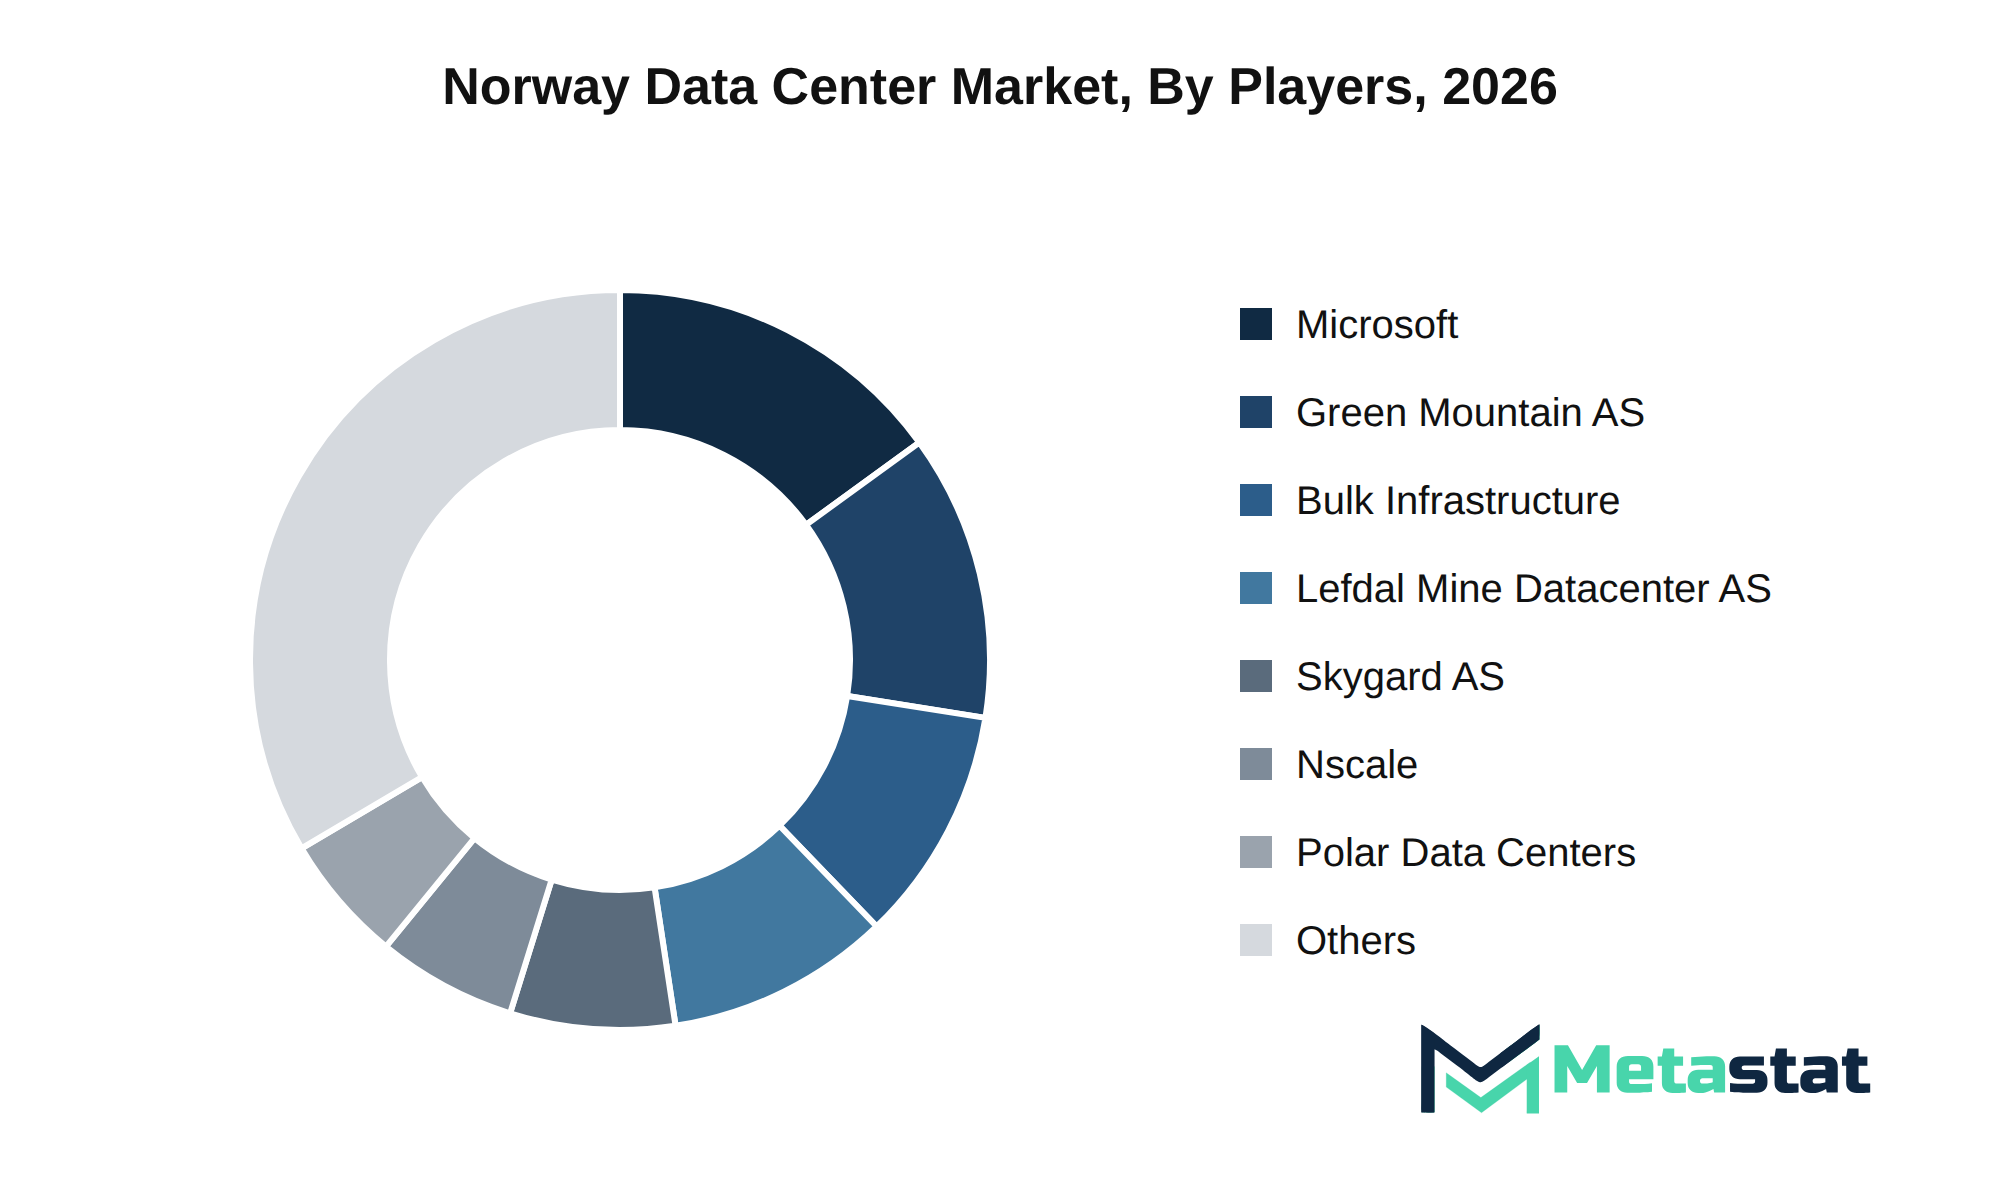
The Norway Data Center market features a diverse range of players offering various services and solutions. Key participants including Green Mountain AS, Bulk Infrastructure, and Microsoft Corporation focus on expanding their presence through strategic alliances and technological advancements. Mergers and acquisitions in the region contribute to market consolidation, enabling firms to combine resources and enhance operational efficiencies, which strengthens their competitive position.
Companies like Amazon.com, Inc. and Google LLC leverage extensive resources to establish competitive advantages in areas including pricing and service offerings. Differentiation through proprietary technology and customer-centric approaches supports retention strategies and enhances brand equity. The overall landscape reflects ongoing competition among established firms and emerging startups, emphasizing the importance of innovation and adaptability in the Norway Data Center market to meet evolving customer demands.
Market size is forecast to rise from USD 1,081.7 million in 2025 to over USD 2,017.6 million by 2033. The outlook for the Norway Data Center market reflects robust expansion influenced by several macroeconomic factors, including increasing digital transformation and cloud adoption across industries. This transformation drives demand for enhanced data center capabilities, with particular emphasis on hyperscale and colocation data centers.
In a bull case scenario, accelerated adoption of next-generation technologies and increased capital investments in infrastructure are likely to drive the market beyond expectations. Strong demand from cloud service providers and internet platforms indicates a sustained growth trajectory. Conversely, in a bear case scenario, economic downturns and geopolitical tensions could hinder expansion, leading to potential delays in investment and project timelines.
The overall market experiences maturation in core industries, stimulating shifts towards more efficient, scalable data center solutions. This evolution aligns with strategic capital allocation directives focused on sustainability and compliance with emerging regulatory frameworks. While organizations prioritize operational efficiency, opportunities arise to address unmet needs within the market, encouraging innovation and enhancing competitive positioning.
Future growth recommendations emphasize the importance of aligning product life cycles with technological advancements and evolving customer demands. By proactively addressing high-growth pockets and emerging white-space opportunities, industry players position themselves for long-term success within the Norway Data Center market.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Data Center market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 8.1% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Data Center Type, Tier Level, Data Center Capacity, End-Use Industry, and Region |
Find answers to common questions about this report
The Norway Data Center market size was valued at USD 1,081.7 million in 2025.
The Norway Data Center market is projected to grow at a CAGR of 8.1% during the forecast period from 2026 to 2033.
Colocation Data Centers lead the Norway Data Center market, with a projected value of USD 880.5 million by 2033, representing the largest share compared to other segments.
Investment in digital transformation and the transition to cloud-based solutions drive the Norway Data Center market. Companies prioritize enhanced data processing capabilities, operational efficiency, and improved service delivery, leading to increased demand for advanced data center infrastructure. This trend creates a competitive environment among data center operators and supports substantial revenue growth.
Regulatory compliance hurdles, macroeconomic headwinds, and infrastructure gaps significantly restrain the Norway Data Center market growth. Stringent regulations increase operational costs, while inflation and inadequate infrastructure limit service reliability and expansion efforts. a shortage of skilled labor raises overhead, impacting profit margins and hindering investment in innovative technologies.
Investment in digital transformation, driven by the demand for enhanced data processing capabilities and the shift toward cloud-based solutions, supports product adoption in the Norway Data Center market. Companies seek advanced infrastructure to improve operational efficiency and service delivery, attracting substantial capital investments and increasing competition among data center operators.
The Data Center market is estimated to reach a valuation of USD 2,017.6 million by 2033.
Key players in the Norway Data Center market include Green Mountain AS, Bulk Infrastructure, Lefdal Mine Datacenter AS, STACK Infrastructure, Microsoft Corporation, GlobalConnect AS, and Amazon.com, Inc.
Oslo serves because a key destination for data center development due to its strong connectivity and established digital infrastructure. Other emerging locations include Stavanger, Trondheim, and Telemark, driven by rising demand for digital services.
Automation enhances operational efficiency within the Norway Data Center market. This trend enables operators to manage large volumes of data more effectively, leading to improved service delivery and customer satisfaction.
Choose Your License
Norway Data Center Market
The analysts below cover Information & Technology research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Floating offshore wind feasibility relies heavily on specialized installation vessel availability and port crane limits, which most broad renewable energy forecasts ignore. The report delivered a thorough analysis of dry dock capacity, mooring chain supply constraints, and raw material pricing trends for deepwater anchor installations. It served as a solid independent sanity check for our offshore project capital expenditure assumptions.
Assessing commercial microgrid software adoption requires looking past top-level installation numbers and examining utility interconnection queues. The research provided verifiable data on average permitting timelines, tariff structures, and battery storage integration costs across regional utility territories. That grounded perspective was valuable for our team when building five-year demand projections for industrial microgrid controllers.
Ambulatory surgical centers have very different purchasing cycles for robotic-assisted surgery platforms than major hospital networks. The MetaStat Insight study focused squarely on capital expenditure depreciation, procedural reimbursement pathways, and surgeon training overhead. That operational clarity made it much simpler to validate multi-year procedure growth forecasts against actual ambulatory center adoption patterns.
Explore related market intelligence reports worth reading alongside this one.