
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Caster Wheels Market Size, Share, By Product Type (Swivel Casters, Rigid Casters, Twin-Wheel Casters, Locking Casters, Leveling Casters, Shock-Absorbing Casters, Motorized/Drive Casters, Ball Casters, Specialty Casters), By Load Capacity (Light Duty Caster Wheels, Medium Duty Caster Wheels, Heavy Duty Caster Wheels, Extra Heavy Duty Caster Wheels), By Wheel Material (Polyurethane, Rubber, Nylon/Polyamide, Polypropylene/Polyolefin, Thermoplastic Rubber, Cast Iron, Steel, Phenolic Resin, Aluminum), By Application (Furniture and Office Equipment, Medical and Healthcare Equipment, Material Handling and Logistics Equipment, Industrial Machinery and Equipment, Carts, Trolleys and Platform Trucks, Automotive and Aerospace Ground Equipment, Retail and Shopping Equipment, Scaffolding and Construction Equipment, Waste and Recycling Equipment), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-5226
Published
October, 2026
Pages
253 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
Market Valuation: Valued at $7,077.3 Million in 2025, projected to reach $10,464.8 Million by 2033 at a 5.1% CAGR.
Dominant Segment: Swivel casters lead the market, driven by their adaptability and enhanced maneuverability in various applications, including healthcare and material handling.
Geographic Lead: North America is the leading region, holding 28.6% of the market in 2025, with the US projected to maintain this position through 2026 due to high demand for efficient mobility solutions.
What's Inside: The report provides a comprehensive analysis of the global caster wheels market, covering product types, load capacities, wheel materials, and applications, along with competitive insights and growth forecasts through 2033.
Growing Demand for Medical Applications: The medical and healthcare equipment segment is projected to grow significantly, reflecting a compound annual growth rate of 6.1% through 2033, driven by the need for specialized mobility solutions in healthcare settings.
Increased Durability of Caster Wheels: Advancements in materials, particularly polyurethane, enhance the durability of caster wheels, attracting investment from industries that require reliable performance and lower maintenance costs.
Choose Your License
Global Caster Wheels Market
The global Caster Wheels market was valued at USD 7,077.3 million in 2025 and is projected to reach USD 10,464.8 million by 2033, growing at a CAGR of 5.1% over the forecast period.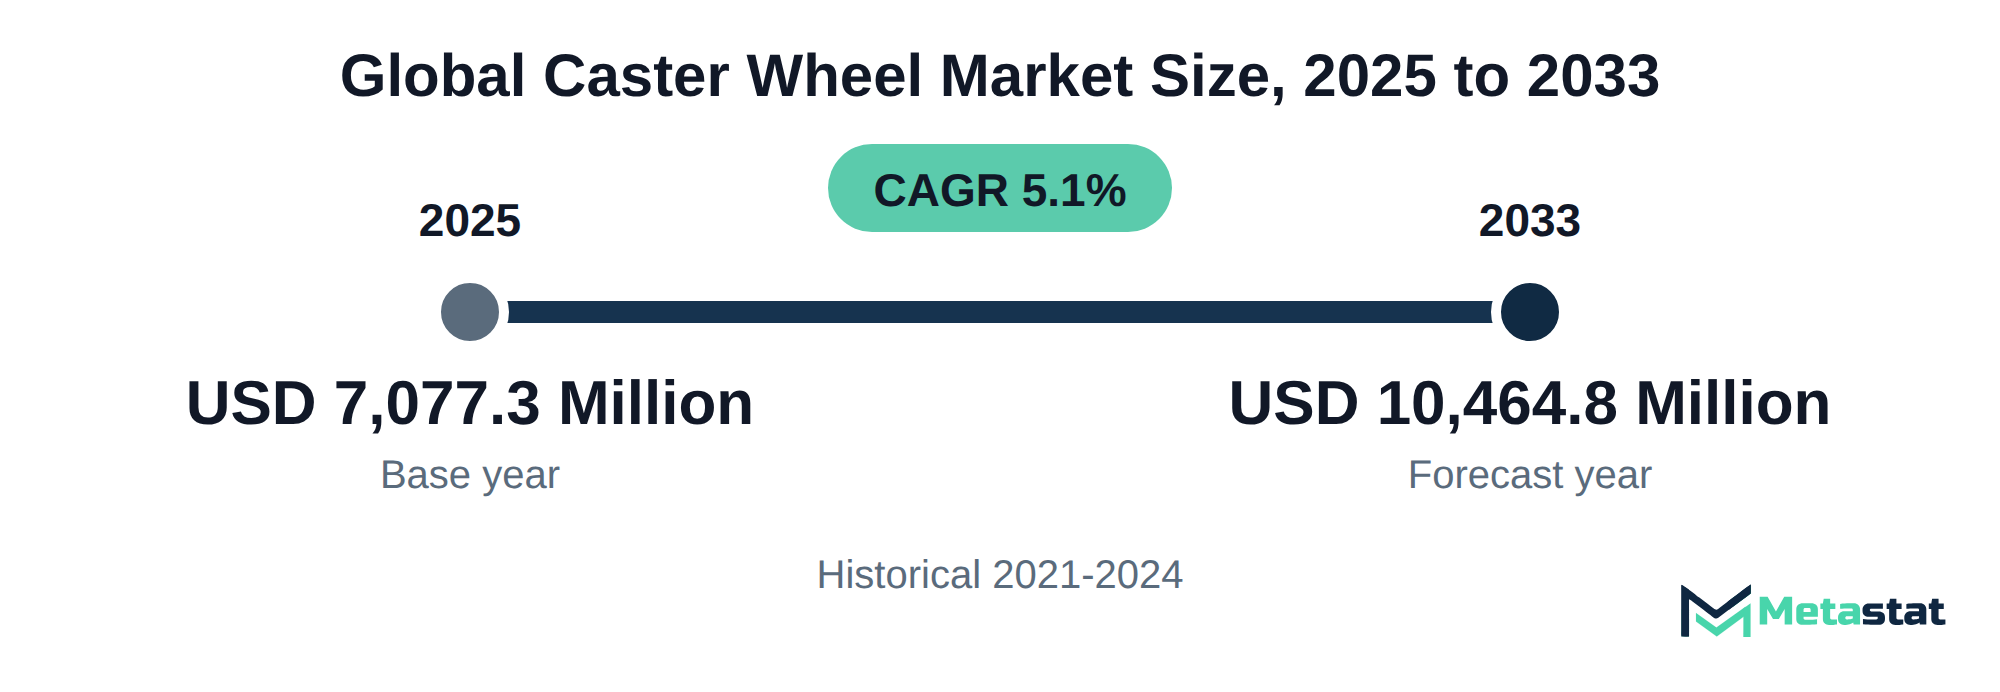
The Caster Wheels market covers products designed to move equipment across multiple applications. Buyers invest in caster wheels to enhance mobility, improve operational efficiency, and ensure safety in environments including warehouses, hospitals, and manufacturing facilities. The versatility of caster wheels, along with innovations in design and materials, supports increased spending among key buyer groups, including manufacturers and healthcare providers.
Growth in the market is driven by several factors, including rising demand for efficient material handling solutions across industries. Among the various segments, swivel casters represent the largest value, attributed to their adaptability in diverse settings. North America holds 28.6% of the market in 2025, with the US leading in 2026. The ability of swivel casters to provide enhanced maneuverability and ease of use positions them as a preferred choice in many applications.
Technological advancements in materials and designs drive demand for caster wheels, particularly in sectors that require specialized solutions. The increasing focus on ergonomics and safety further influences purchasing decisions, compelling buyers to invest in high-quality caster wheels that meet specific operational needs. These trends highlight the importance of innovation and adaptability in driving market dynamics.
Investment in caster wheels stems from their essential role in enhancing mobility and efficiency across various sectors. Buyers prioritize these products to improve operational workflows, reduce manual handling, and ensure safety in equipment movement. This market caters to diverse applications, including healthcare, industrial machinery, and furniture, reflecting the broad applicability of caster wheels in both commercial and residential settings.
Growth drivers in the market include increasing demand for ergonomic solutions and automation in material handling. The segment of swivel casters holds the largest share, attributed to their versatility and effectiveness in navigating tight spaces. Asia Pacific presents significant potential for expansion, driven by rapid industrialization and urbanization, which fuels the need for efficient mobility solutions.
Technological advancements in wheel materials and designs contribute to improved performance and durability, further stimulating market growth. Innovations including noise-reducing and shock-absorbing features enhance the user experience and attract more buyers. The ongoing trend toward sustainability encourages the development of eco-friendly caster wheel options, aligning with global environmental initiatives and increasing market appeal.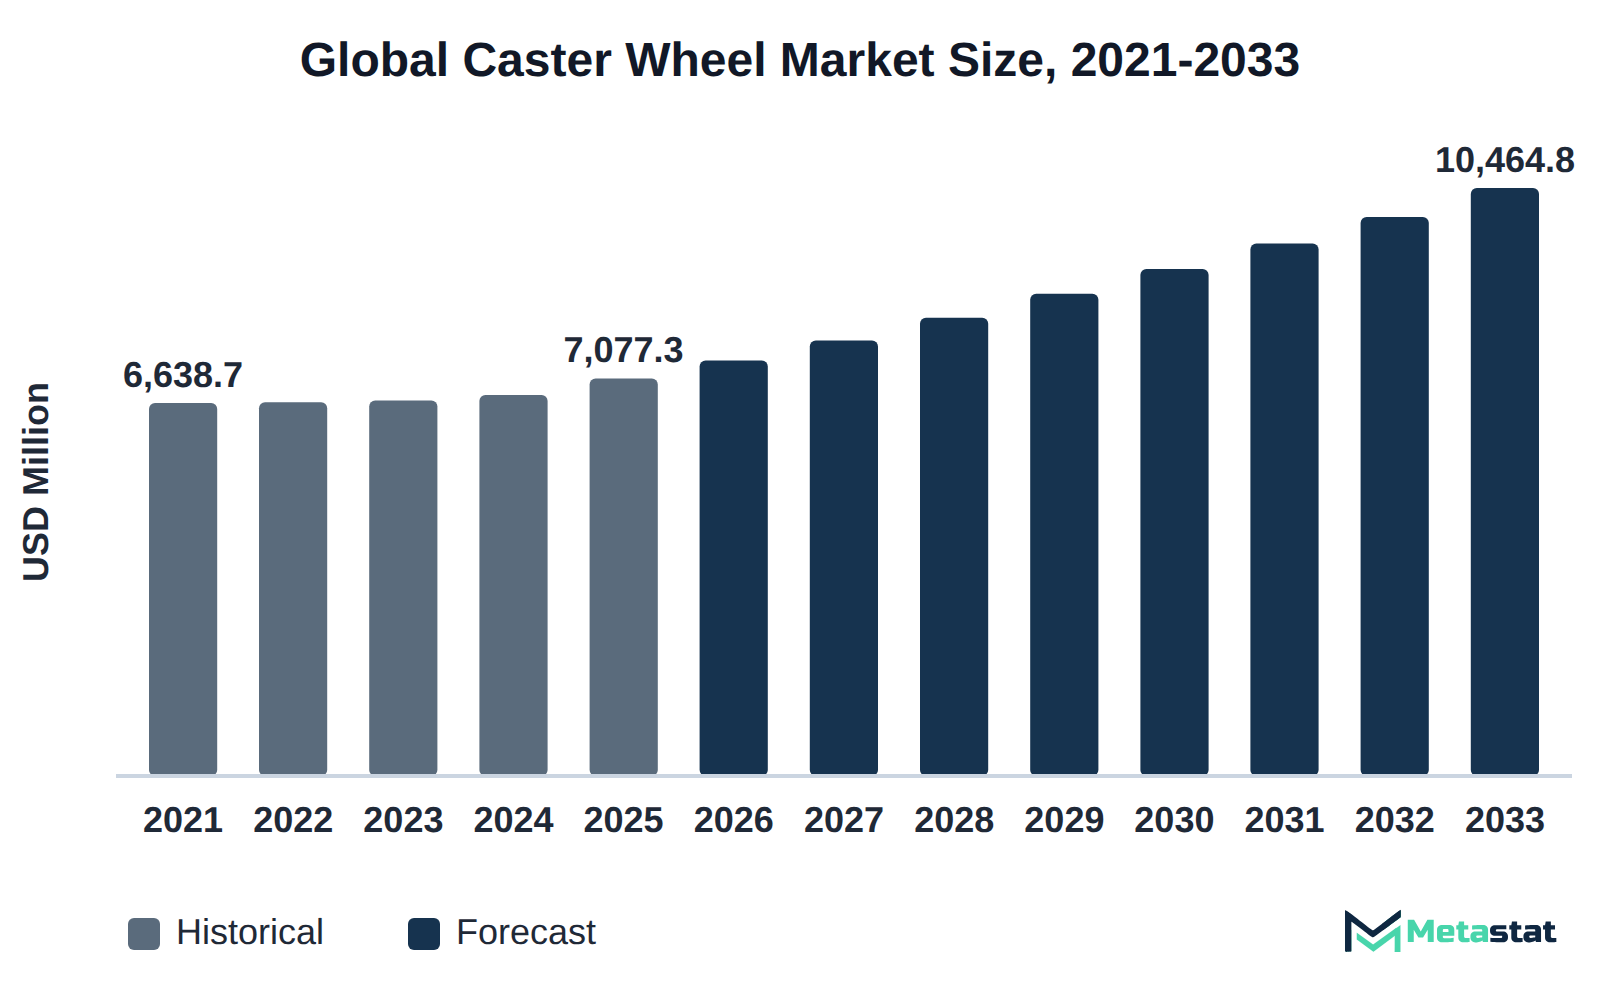
Designing caster wheels for Automated Guided Vehicles (AGVs) and automated material handling systems demands specific considerations to enhance efficiency and reliability. These wheels support smooth movement and maneuverability to navigate complex environments, including warehouses and manufacturing floors. The demand for effective load management in such applications drives innovation in wheel materials and designs. AGVs form part of the wider mobile robotics industry.
In the Caster Wheels market, the segment of Polyurethane wheels is projected to grow from USD 2,185.8 million in 2026 to USD 3,343.4 million by 2033, reflecting a compound annual growth rate of 6.3%. This growth highlights the increasing preference for lightweight, durable materials that provide superior performance under various loads. Polyurethane wheels exhibit excellent wear resistance, making them suitable for high-frequency operations typical of AGVs, which require minimal maintenance.
Advancements in caster wheel technology, particularly with materials like Polyurethane, position manufacturers to meet the rigorous demands of automated systems. Meeting these design requirements improves operational efficiency and strengthens the competitive position of suppliers.
Choosing between polyurethane and rubber treads for caster wheels significantly impacts floor protection and lifetime operating costs. Polyurethane treads typically offer superior floor protection due to their ability to distribute weight more evenly, reducing the risk of floor damage. This material delivers a longer lifespan compared to rubber, which is beneficial for high-traffic areas. Polyurethane treads see strong adoption among buyers seeking durable and cost-effective solutions.
In contrast, rubber treads provide adequate floor protection but tend to wear down more quickly in demanding applications, leading to higher replacement frequency and associated costs over time. Buyers focused on minimizing long-term expenses increasingly favor polyurethane solutions, given their durability and lower maintenance requirements. The choice between these materials directly affects operating costs. Investment in polyurethane reduces how often wheels need replacement and maintenance, which improves the operational efficiency of equipment.
Medical caster wheels provide essential mobility for medical equipment while ensuring quiet operation and ease of cleaning. The segment for medical and healthcare equipment in the caster wheels market is projected to reach USD 1,736.4 million by 2033, highlighting significant investment in this area. Such features are critical for maintaining sterile environments and minimizing disturbances in hospitals and clinics.
Distinct requirements from healthcare professionals drive demand for medical caster wheels. These wheels facilitate the smooth transport of sensitive equipment, including hospital beds and diagnostic machines, while offering reliable braking systems to ensure safety. The emphasis on cleanability enhances their importance, with healthcare facilities prioritizing hygiene to prevent infections.
The growth of the healthcare sector, paired with the increasing complexity of medical equipment, positions medical caster wheels as a vital component in the caster wheels market. Suppliers focused on innovation in this space benefit from heightened demand, resulting in increased market share and revenue opportunities.
Dynamic load ratings guide heavy-duty caster wheel selection by defining capacity and performance under operational stress. Heavy-duty caster wheels are designed to support substantial weights and loads, ensuring safe and efficient movement in various applications. Heavy-duty caster wheels are projected to reach a value of USD 2,470.1 million by 2033. This growth highlights the importance of selecting the right caster based on load specifications to prevent equipment failure and maintain operational integrity.
When selecting heavy-duty casters, understanding the dynamic load rating involves recognizing the impact of varying conditions, including speed and surface type. This rating is often distinct from static load ratings, which focus solely on stationary conditions. Buyers prioritize casters with dynamic load ratings that exceed the expected loads during operation to ensure safe transportation of goods. Incorrect wheel selection leads to premature failures and replacement needs, resulting in increased operational costs.
In the Caster Wheels market, dynamic load ratings serve as a key metric for ensuring that selected wheels align with operational demands. Through careful evaluation of these ratings, buyers optimize their equipment, enhance productivity, and minimize maintenance costs. Purchasing decisions based on dynamic load ratings ensure that heavy-duty caster wheels meet the demands of applications across various industries.
The research projects the global caster wheels market to grow through 2033 from a narrow set of demand pools rather than evenly across products and end uses. Material handling and logistics equipment, together with medical and healthcare equipment, account for 45.2% of the market's incremental revenue between 2025 and 2033, from 33.8% of 2025 revenue. What links the two is specification. Warehouses, fulfilment centres and hospitals buy castors against requirements for load rating, braking, noise and floor protection, and those requirements raise the value of each castor bought.
Growing demand for lightweight materials drives increased expenditure on caster wheels. Industries including furniture manufacturing, healthcare, and logistics prioritize mobility solutions that enhance operational efficiency. The shift toward lightweight materials aligns with efforts to improve product design and facilitate easier movement of equipment. For instance, the adoption of lightweight materials in furniture and office equipment led to a notable increase in the usage of caster wheels, which enhance mobility without compromising stability. This trend promotes higher demand in sectors focusing on efficiency, ultimately boosting sales in the caster wheels market.
Advancements in materials and manufacturing processes contribute to enhanced durability in caster wheels, attracting various industries to invest in these products. Innovations in wheel materials, particularly in polyurethane and thermoplastic rubber, provide increased resistance to wear and tear, extending product lifespan. This focus on durability appeals to sectors including healthcare and industrial machinery, where reliable performance is critical. Enhanced durability correlates with reduced maintenance and replacement costs, making caster wheels more appealing for long-term investment. The Caster Wheels market benefits from this trend, with buyers prioritizing products that offer longevity and reliability in demanding environments. Consequently, businesses experience improved operational efficiency and lower overall expenditure on equipment mobility solutions. This emphasis on durability drives the market toward further innovation and competitive advantages among suppliers, who strive to meet the evolving demands of diverse applications.
Price fluctuations in raw materials restrict budget allocations for buyer groups, particularly in sectors reliant on cost-effective solutions. The furniture and office equipment segment experiences slower uptake due to rising manufacturing expenses, impacting the overall demand for caster wheels. Buyers in this category often face challenges in balancing quality and price, leading to smaller orders and delayed replacements. Higher costs compel businesses to postpone investments in new caster wheel technologies, hindering opportunities for innovation and efficiency improvements. The market's growth trajectory suffers from these pressures, with many buyers prioritizing short-term savings over long-term benefits associated with advanced caster technologies. This constraint poses a significant challenge for manufacturers seeking to expand their market presence, as economic pressures directly affect buyer confidence and willingness to invest in caster wheels.
Suppliers in the Caster Wheels market face significant input cost pressures, stemming from rising prices of raw materials and components necessary for manufacturing. Increased costs of materials including polyurethane, steel, and rubber contribute to tighter profit margins for manufacturers. To mitigate these challenges, suppliers implement various strategies, including optimizing supply chains and negotiating long-term contracts with raw material providers to stabilize prices. Investing in innovative manufacturing techniques enhances efficiency and reduces waste, further alleviating financial strain. Suppliers focus on diversifying material sources to minimize reliance on any single supplier, thereby securing more competitive pricing options. These proactive measures support manufacturers' ability to maintain profitability while addressing the growing demand in various industries reliant on caster wheels for mobility solutions.
Investment in medical and healthcare equipment represents a significant growth opportunity within the Caster Wheels market. The segment is projected to achieve a compound annual growth rate of 6.1% through 2033, indicating strong demand for specialized mobility solutions in healthcare environments. Increasing focus on hygiene, safety, and efficient equipment movement drives this demand, with hospitals and medical facilities requiring reliable and cleanable caster wheels. The growing need for advanced medical devices creates further demand for caster wheels that support mobility while adhering to strict regulatory standards. This growth aligns with innovations in caster wheel design and materials that enhance user experience and operational efficiency. Addressing this specific pocket of growth enables suppliers to capture a share of the expanding healthcare market, reinforcing their competitive position and driving long-term demand. The market potential in this area reflects a broader trend toward investing in efficient and adaptable medical equipment solutions.
The Global Caster Wheels market is segmented based on Product Type, Load Capacity, Wheel Material, and Application.
The Swivel Casters segment is valued at USD 2,483.4 million in 2026 and is projected to reach USD 3,337.9 million by 2033, at a CAGR of 4.3% during the forecast period. These casters offer maneuverability and flexibility, making them ideal for furniture, medical equipment, and material handling applications. The demand for swivel casters is driven by the increasing need for efficient movement in workspaces and healthcare settings. Unlike rigid casters, which provide stability with limited mobility, swivel casters cater to environments requiring both mobility and adaptability. This segment's growth rate surpasses that of rigid casters, which see a CAGR of 4%. Swivel casters allow users to navigate tight spaces, enhancing operational efficiency, particularly in dynamic industries. Their unique design facilitates sharp turns and directional changes, making them essential for various applications in the market.
Rigid Casters segment is estimated to reach USD 1,526.6 million by 2033, at a CAGR of 4% during the forecast period. Typically employed in applications requiring stability and direct movement, rigid casters function effectively in settings including warehouses, manufacturing facilities, and retail environments. Demand for this segment experiences growth driven by an increase in automated material handling systems, where efficient mobility is essential. Compared to swivel casters, rigid casters offer a simpler design and lower cost, appealing to price-sensitive buyers. This segment's growth rate is slower than that of locking casters, which benefit from a higher CAGR of 5.6%. The market shows strong potential due to ongoing investments in industrial automation and material handling solutions, enhancing the relevance of rigid casters in various industries.
Twin-Wheel Casters segment is expected to reach USD 905.3 million by 2033. This segment serves various applications, including furniture and medical equipment, where stability and maneuverability play crucial roles. Users value the balance between load capacity and ease of movement. The growth of this segment reflects increasing demand for versatile wheels that enhance operational efficiency in both industrial and commercial settings. Driving forces include the rising adoption of lightweight materials, which support easier mobility, and advancements in manufacturing technology that enhance product performance. Compared to other caster types, Twin-Wheel Casters exhibit a unique combination of agility and stability, positioning them well in the competitive environment. This segment's growth rate aligns closely with overall market trends, highlighting its relevance in emerging sectors.
Locking Casters segment is projected to grow at a CAGR of 5.6% during the forecast period. These casters play a significant role in ensuring stability for equipment across various applications, particularly in environments requiring secure and controlled movement, including medical facilities and warehouses. The growth of this segment is driven by an increasing focus on safety and operational efficiency among end-users. Manufacturers looking to enhance product functionality are exploring innovations in locking mechanisms, making these casters more appealing to sectors focused on reliable performance. With a projected value of USD 1,526.6 million by 2033, this segment stands out due to its higher growth rate compared to other product types, reflecting the specific needs of buyers prioritizing stability and safety in their equipment choices. The market is adapting to the requirements of industries that rely on efficient mobility solutions.
Leveling casters provide stability and adjustability across various applications. These components are often used in environments including industrial machinery, office furniture, and medical equipment, where precise height adjustments are necessary. Demand for leveling casters stems from the increasing focus on ergonomic designs and operational efficiency, prompting investments in adjustable solutions. In comparison to other caster types, including swivel and rigid casters, leveling casters do not experience the same rate of growth due to their niche application focus. However, the growing emphasis on workplace safety and comfort drives interest in these products. The market exhibits strong competition, with manufacturers emphasizing innovative designs that enhance functionality while ensuring cost-effectiveness.
Shock-absorbing casters feature advanced designs that minimize vibrations and shocks, enhancing the stability of transported items. These casters find applications in various sectors, particularly in medical and industrial environments, where sensitive equipment requires gentle handling. A significant growth driver for this segment is the rising demand for safety and comfort in transportation systems. Buyers in healthcare and logistics prioritize these casters for their ability to provide smooth mobility and protect delicate items during transit. This segment distinguishes itself from rigid and swivel casters due to its unique functionality, focusing on shock absorption rather than maneuverability alone. The market's emphasis on safety and equipment protection continues to shape the development of shock-absorbing casters, reflecting evolving user requirements within the Caster Wheels market.
Our analysis identifies motorized and drive castors as the fastest-growing product type, at 13.1% a year, driven by autonomous mobile robot fleets and powered hospital beds. Their small base limits the absolute gain: standard swivel castors add twice as much revenue over the forecast period (USD 934.6 million against USD 461.0 million). Locking castors deliver the second-largest gain because they grow on top of large installed equipment bases, including hospital beds, roll containers, food-service carts and mobile scaffold towers, where braking is a safety or standards requirement rather than an option. For suppliers, the larger prize is upgrading high-volume platforms with braked, quieter and better-engineered castors. Motorized castors remain an engineering-intensive niche whose revenue follows the deployment schedules of robot and bed manufacturers.
This segment's growth trajectory is likely influenced by ongoing advancements in automation and robotics, enabling more efficient loading and transport solutions across industries. Such innovations attract a different buyer demographic focused on operational efficiency and productivity, differentiating motorized casters from other product types in the market.
Ball casters provide a unique mobility solution characterized by their spherical design, enabling smooth movement in multiple directions. These casters find application in diverse environments, including furniture, medical equipment, and industrial machinery. The demand for ball casters is primarily driven by their ability to enhance maneuverability, especially in tight spaces. Buyers, including manufacturers and distributors, appreciate their versatility and ease of use. Compared to other caster types, ball casters face slower growth due to their niche application and specific use cases, which cater to distinct customer needs. Their pricing fluctuates based on materials and design complexity, influencing procurement strategies among buyers. Ball casters serve a specialized segment of the Caster Wheels market.
Specialty casters serve specific operational needs across various industries, providing tailored solutions for unique applications. These casters are employed in niche markets including robotics, automotive assembly, and custom equipment manufacturing. Demand for specialty casters is driven by the increasing need for custom solutions that enhance operational efficiency and productivity. This segment differentiates itself from others through its focus on specialized applications, often commanding higher prices due to the customization and advanced materials involved. Unlike standard caster segments, specialty casters typically appeal to manufacturers seeking unique design elements or performance characteristics, resulting in strong growth in sectors prioritizing innovation. The Caster Wheels market benefits from this trend towards specialization, with industries increasingly seeking innovative products that enhance their operational capabilities.
Light Duty Caster Wheels segment is valued at USD 2,326.3 million in 2026 and is projected to reach USD 3,121.1 million by 2033, at a CAGR of 4.3% during the forecast period. These casters primarily serve the furniture and office equipment sectors, where lightweight mobility solutions are essential. Demand from industries prioritizing ease of movement and flexibility drives growth in this segment. The lower load capacity of Light Duty Caster Wheels distinguishes them from Medium and Heavy Duty variants, which cater to heavier applications and exhibit higher price points. The growth rate of 4.3% aligns closely with overall market trends, reflecting specific user requirements and operational needs, while lighter applications do not necessitate the same robustness as heavier duty options.
Medium Duty Caster Wheels segment is estimated to reach USD 4,069.9 million by 2033, at a CAGR of 5.2% during the forecast period. This segment primarily serves industries including manufacturing, logistics, and healthcare, where moderate load capacities are essential for efficient operations. Demand is driven by the increasing need for material handling solutions that efficiently manage weight distributions. Compared to other load capacity segments, Medium Duty Caster Wheels differentiate themselves through their balance of performance and affordability, appealing to cost-conscious buyers seeking reliable options without compromising quality. The growth trajectory reflects broader industrial trends, focusing on enhanced operational efficiency and durability. This segment’s steady growth supports significant investment in equipment upgrades across various sectors, contributing positively to the overall dynamics of the Caster Wheels market.
Heavy Duty Caster Wheels segment is expected to reach USD 2,470.1 million by 2033. This segment is essential in supporting heavy equipment and machinery across sectors including manufacturing, construction, and transportation. Demand for heavy-duty solutions rises due to increasing industrial activity and the need for equipment that withstands higher loads. This segment features a higher price point compared to light and medium duty segments, incorporating robust materials and engineering to ensure durability and performance. The growth rate for heavy-duty options differs from other segments, with a CAGR of 5.5% forecasted for the coming years. This segment's focus on high-capacity applications distinguishes it from lighter alternatives, appealing to buyers seeking strength and reliability in demanding environments. Ongoing advancements in material technology enhance the appeal of heavy duty casters, contributing to growth in the market.
Extra Heavy Duty Caster Wheels segment is projected to grow at a CAGR of 5.5% during the forecast period. These casters are critical for transporting heavy loads in various industrial settings, including manufacturing and construction. Key factors driving demand include the increasing need for reliable material handling solutions and the expansion of industries requiring robust mobility solutions. This segment stands out for its capacity to support significantly heavier weights compared to lighter duty options, making it essential for sectors that rely on heavy machinery and equipment. The market shows strong growth potential, driven primarily by ongoing industrialization and infrastructure development initiatives in several regions. Increased investments in heavy equipment and machinery further enhance the demand for Extra Heavy Duty Caster Wheels, differentiating this segment through specialized applications in demanding environments.
In our forecast, polyurethane captures 37.7% of incremental revenue, more than any other wheel material, while rubber, polypropylene and cast iron lose share. The shift follows the growing applications. Polyurethane treads combine load capacity with low rolling resistance, quiet running and floor protection, which count in automated warehouses and hospital corridors far more than in furniture or retail. The upgrade has the most room to run in China, where plastic and rubber wheels still account for most industrial castor value. Our analysis indicates that part of the market's value growth comes from this shift toward higher-value treads, not only from additional units. Capacity in polyurethane casting and tread bonding therefore becomes a gating capability for suppliers that want to follow demand upmarket.
The rubber segment is estimated to reach USD 1,522.5 million by 2033, at a CAGR of 3.6% during the forecast period. Demand is driven by the segment's ability to provide a balance of durability and flexibility, suitable for diverse operational requirements. Compared to other wheel materials, rubber offers quieter operation and enhanced grip, appealing to buyers in sectors where noise reduction and surface protection are crucial. While the growth rate is lower than polyurethane, projected at a CAGR of 6.3%, rubber remains a popular choice for applications prioritizing comfort and ease of use. The Caster Wheels market reflects steady demand for rubber wheels, particularly in industrial machinery where reliability and performance are significant.
The Nylon/Polyamide segment is expected to reach USD 1,527 million by 2033. This type of wheel material is used in various applications, particularly in industrial machinery and healthcare equipment, driven by its durability and resistance to wear. Growth in the segment is primarily supported by increasing demand from the medical and healthcare sector, which requires reliable and robust materials for mobility solutions. Compared to other materials, including rubber, which is projected to grow at a CAGR of 3.6%, the Nylon/Polyamide segment exhibits relatively stable performance. Its strong and lightweight properties contribute to its adoption across diverse industries, where reliability and performance are critical. Buyers prefer this material for its ability to handle varying loads without compromising functionality. Overall, the Nylon/Polyamide segment signifies a vital part of the Caster Wheels market, aligning with broader trends of material innovation and application expansion.
Polypropylene/Polyolefin segment is projected to grow at a CAGR of 3.9% during the forecast period. This segment finds widespread usage in applications requiring lightweight and cost-effective wheel solutions, including furniture and office equipment. Buyers including manufacturers of medical equipment and logistics companies benefit from its properties, which ensure durability and ease of movement. Demand is driven by an increased focus on productivity and efficiency in operations, leading to a preference for materials that balance performance with cost. Compared to other segments, Polypropylene/Polyolefin offers a lower price point, making it attractive for budget-conscious buyers while delivering satisfactory performance. This positioning results in steady growth, although it trails behind segments like Polyurethane, which enjoys a higher CAGR of 6.3%. The Caster Wheels market reflects a variety of material preferences that cater to specific application needs.
Thermoplastic Rubber consists of a versatile material widely used for various applications in caster wheels. Its unique properties, including excellent resilience and durability, make it a preferred choice for many industries, including healthcare and furniture manufacturing. Growing demand for durable caster wheels in medical and healthcare equipment drives this segment, with these applications requiring reliable mobility solutions that withstand frequent use. This segment distinguishes itself from others, including rubber, which has a lower growth rate, indicating a shift in preference toward more advanced materials. The increasing focus on enhancing user experience and performance leads manufacturers to invest in thermoplastic rubber for improved product offerings. This evolution reflects changing consumer expectations and technological advancements in the caster wheels market.
Cast iron is a material option for caster wheels that offers durability and strength in various applications. Industries including manufacturing and heavy equipment frequently use this material due to its ability to withstand heavy loads and harsh conditions. Demand for cast iron wheels is driven by the need for reliability and performance in challenging environments. Compared to other materials, including polyurethane, cast iron tends to exhibit lower growth rates, influenced by the rising preference for lighter and more versatile materials. Buyers in sectors requiring heavy-duty solutions often choose cast iron for its superior load-bearing capabilities, enhancing operational efficiency and safety. The Caster Wheels market reflects these trends while ensuring functionality and performance.
Steel casters offer durability and strength, making them a preferred choice for applications requiring heavy loads and high resistance to wear and tear. Industries including manufacturing, logistics, and warehousing select steel casters due to their ability to withstand significant stress and impact. The rising demand for robust caster solutions supports this segment, driven by increasing automation and material handling processes across various sectors. Compared to other materials, steel casters tend to have a longer lifespan, reducing replacement frequency and overall costs for users. However, their price point is typically higher than alternatives like rubber or polyurethane, which limits adoption in budget-sensitive applications. The advancement of coating technologies is expected to enhance the performance of steel casters, making them more appealing for diverse industrial applications. Participants in the steel caster market focus on improving load capacity and resistance to environmental factors, further driving growth in the market.
Phenolic resin is a wheel material used mainly in applications that require high strength and resistance to wear. Industries including manufacturing and healthcare use this material for items that need durability and reliability, particularly in environments where chemicals and heavy loads are present. The growth of this segment is influenced by increasing demand for caster wheels that perform well under challenging conditions. In comparison to other wheel materials, phenolic resin offers unique performance characteristics but experiences slower growth due to higher production costs. The emphasis on quality over cost in specific market segments drives buyers towards phenolic resin, differentiating it from more price-sensitive alternatives.
Aluminum is a lightweight and durable material choice for caster wheels, offering significant advantages in numerous applications. Industries including automotive, aerospace, and healthcare adopt aluminum wheels due to their high strength-to-weight ratio and resistance to corrosion. Demand for aluminum in the caster wheels market is influenced by the growing preference for lightweight materials that enhance maneuverability and energy efficiency. Compared to other materials like steel and rubber, aluminum offers distinct advantages, including lower weight and increased resistance to environmental factors. The segment's growth trajectory aligns with a shift towards sustainable practices, where manufacturers and end-users prioritize materials that contribute to overall operational efficiency and reduce energy costs.
Composite, Neoprene, and Pneumatic materials offer distinct advantages in specific applications, targeting industries including healthcare and furniture manufacturing. These materials provide enhanced flexibility and resilience, enabling smooth movement and reducing noise during operation. Demand for this sub-segment is driven by the increasing focus on ergonomic solutions and the growing need for quieter operational environments. The segment differs from others primarily in its application scope, appealing to buyers seeking specialized features rather than bulk purchasing, which characterizes segments like Polyurethane or Rubber. While segments like Polyurethane experience faster growth rates, the unique characteristics of Composite, Neoprene, and Pneumatic materials ensure their sustained relevance in the Caster Wheels market.
The Furniture and Office Equipment segment is valued at USD 1,284.9 million in 2026 and is projected to reach USD 1,659.4 million by 2033, at a CAGR of 3.7% during the forecast period. This segment primarily serves businesses and organizations that require mobility solutions for furniture, office equipment, and related items. Demand for these caster wheels is driven by growth in office spaces and the increasing need for adaptable furniture solutions, reflecting changes in work environments. Compared to other segments, this segment experiences slower growth, with a CAGR of 3.7%, differentiating it from segments including Medical and Healthcare Equipment, which has a higher growth rate of 6.1%. The nature of buyers in this segment typically includes furniture manufacturers, office supply companies, and institutions seeking to enhance operational efficiency through versatile furniture arrangements. The increasing trend toward remote work and flexible office designs further supports this segment's growth within the Caster Wheels market.
Medical and Healthcare Equipment segment is estimated to reach USD 1,736.4 million by 2033, at a CAGR of 6.1% during the forecast period. This segment includes caster wheels used in medical devices, hospital beds, and other healthcare equipment, essential for facilitating movement and accessibility in medical settings. The growing demand for advanced healthcare solutions drives the adoption of these caster wheels, driven by the increased focus on patient mobility and safety. Compared to other segments, this segment shows a faster growth rate, reflecting a specific need for durable and reliable mobility solutions in healthcare environments. Factors including stringent regulations and the necessity for high-quality materials influence the design and production of these wheels, ensuring compliance with rigorous safety standards. The Caster Wheels market continues to evolve with innovations that enhance functionality and performance in medical applications.
The Material Handling and Logistics Equipment segment is expected to reach USD 2,183.2 million by 2033. This segment serves various industries, including warehousing, manufacturing, and retail, focusing on transporting goods efficiently. Increasing warehouse automation drives demand for caster wheels designed for material handling applications. This area exhibits a higher growth rate due to the rising need for efficient logistics solutions. The CAGR for this segment remains at 6.1%, reflecting robust demand. Buyers in this segment seek durability and adaptability in caster wheels, influencing manufacturers to innovate and improve design features. Competition in this segment intensifies as suppliers strive to offer enhanced performance products, differentiating themselves from alternatives in furniture or medical applications. The emphasis on cost-effective and high-performance solutions further enhances the segment's attractiveness, contributing to overall growth in the market.
Industrial Machinery and Equipment segment is projected to grow at a CAGR of 4.5% during the forecast period. This segment serves various industries, including manufacturing and assembly, where caster wheels facilitate the movement of equipment and machinery. Increasing automation in industrial processes drives demand for high-performance caster wheels capable of handling heavy loads and providing stability. Compared to other applications, this segment experiences moderate growth, influenced by technological advancements and rising labor costs that push companies to invest in automation solutions. In contrast, segments like Medical and Healthcare Equipment, which grow at a CAGR of 6.1%, exhibit faster expansion due to heightened demand for innovative medical solutions. The focus on efficiency and mobility in industrial settings remains a primary factor influencing demand for caster wheels in this application.
Carts, trolleys, and platform trucks serve crucial functions in transporting goods and materials across various industries. Commonly used in retail, warehouses, and healthcare settings, these applications demand efficient movement solutions. This segment experiences growth driven by increasing e-commerce activities and the need for efficient logistics management. Factors including product innovation and advancements in caster technology enhance the reliability and performance of these solutions. Compared to other segments, the adoption of caster wheels for carts and trolleys reflects a unique market dynamic, focusing on lightweight and maneuverable designs that accommodate diverse environments. The ongoing trend toward automation and mechanization within logistics further influences the demand for these specialized caster wheels, positioning this sub-segment favorably within the broader caster wheels market.
Automotive and Aerospace Ground Equipment is essential in the transportation and logistics sectors, specifically focusing on vehicles and equipment used in ground operations. This segment finds use in various applications including aircraft tugs, baggage carts, and maintenance platforms, serving industries that demand reliability and efficiency, including airport services. The increasing emphasis on safety and efficiency drives demand for innovative caster solutions in this area. Compared to other application segments, this one often experiences higher pricing due to stringent safety and performance standards required in the automotive and aerospace industries. Ongoing advancements in technology push manufacturers to develop more specialized products, enhancing the segment’s potential. While sectors like Medical and Healthcare Equipment show rapid growth, the Automotive and Aerospace Ground Equipment segment significantly contributes to the overall performance of the market.
Retail and Shopping Equipment includes caster wheels designed specifically for applications involving carts, trolleys, and other shopping-related equipment. This segment primarily serves retailers, supermarkets, and logistics companies seeking effective mobility solutions for their products. Significant market influences include increasing consumer demand for efficient shopping experiences and innovations in wheel design aimed at enhancing maneuverability and load capacities. Unlike segments focused on medical or industrial applications, this segment experiences growth driven by changing consumer behaviors and technological advancements. Retailers invest in high-quality caster wheels to improve the functionality of their equipment, leading to a competitive edge in customer satisfaction and operational efficiency. The Caster Wheels market faces ongoing trends toward automation and smart technology, further impacting the design and performance requirements of wheels used in retail environments. These trends sit within the wider smart retail industry.
Scaffolding and Construction Equipment serves a critical role in various construction and renovation projects, providing mobility and support for heavy loads. Users include construction companies and contractors who rely on efficient movement of equipment and materials on site. Mobile construction scaffolding is one example of equipment that relies on caster wheels for movement. This segment experiences growth driven by increasing construction activities and urban development projects worldwide. The demand for durable and high-capacity caster wheels specifically tailored for heavy equipment differentiates this segment from others, resulting in enhanced resilience against wear and tear compared to lighter-duty applications. In the Caster Wheels market, growth in this segment reflects broader trends in infrastructure development, emphasizing the need for reliable and robust solutions in construction environments.
Waste and Recycling Equipment encompasses various applications requiring efficient mobility solutions for waste management and recycling operations. This segment targets municipal services, recycling facilities, and commercial establishments needing reliable and sturdy caster wheels for the transportation of waste bins, recycling containers, and related equipment. Demand in this segment relies heavily on increasing environmental regulations mandating recycling practices, driving higher adoption rates. The growing focus on sustainability within industries enhances the need for effective waste handling equipment. Compared to other sub-segments, Waste and Recycling Equipment experiences unique challenges related to cost and durability requirements, with buyers prioritizing robust solutions that withstand harsh environments. The segment's growth trajectory aligns with broader trends in the caster wheels market, particularly reflecting shifts toward eco-friendly practices and technological advancements that improve operational efficiencies.
The Others segment covers applications in Food-Service, Laboratory, Cleanroom, and Specialized Equipment. These casters serve essential roles in various environments requiring cleanliness and precision, including hospitals and laboratories. This segment attracts demand from healthcare providers, food service industries, and research facilities focused on maintaining sanitation and operational efficiency. Key factors driving this segment include advancements in healthcare technology and increased regulatory requirements for sanitary equipment. Unlike other segments, which experience higher growth rates, this segment typically faces slower expansion, reflecting a more specialized and regulated market. The emphasis on maintaining high standards of cleanliness distinguishes it from broader applications in furniture or industrial machinery.
Asia Pacific contributes 47.4% of the global increment, the largest of any region. Its demand base leans toward furniture and office-chair castors, reflecting chair and furniture manufacturing in China and Southeast Asia. Yet furniture loses share within the region through 2033, while logistics and healthcare gain. The region's new revenue therefore comes mainly from express-parcel and e-commerce handling and from hospital build-out, applications with stricter performance requirements than its furniture base.
The Middle East and Africa grows at nearly the same rate but adds less than a tenth of Asia Pacific's increment, and its demand is different in kind. It is driven by hospital, logistics-zone and airport projects in the Gulf and is supplied mainly through imports, so tender specifications and project timing matter more there than local production scale.
The headline growth rate blends two markets. Specification-led pools (logistics, healthcare, polyurethane treads, braked and powered castors) grow faster than the market. Commodity pools (furniture, retail, rubber and polypropylene wheels) grow more slowly but keep a large base of established OEM and replacement purchasing. Through 2033, suppliers should put capacity and engineering into the first group and defend the second on cost. Buyers are likely to weigh total cost of ownership, including floor damage, noise and replacement intervals, more heavily than unit price. The development to watch is warehouse automation investment in China and North America. Logistics is the largest application source of new revenue, so a slowdown in automated fulfilment spending would weaken the outlook more than any change in furniture demand.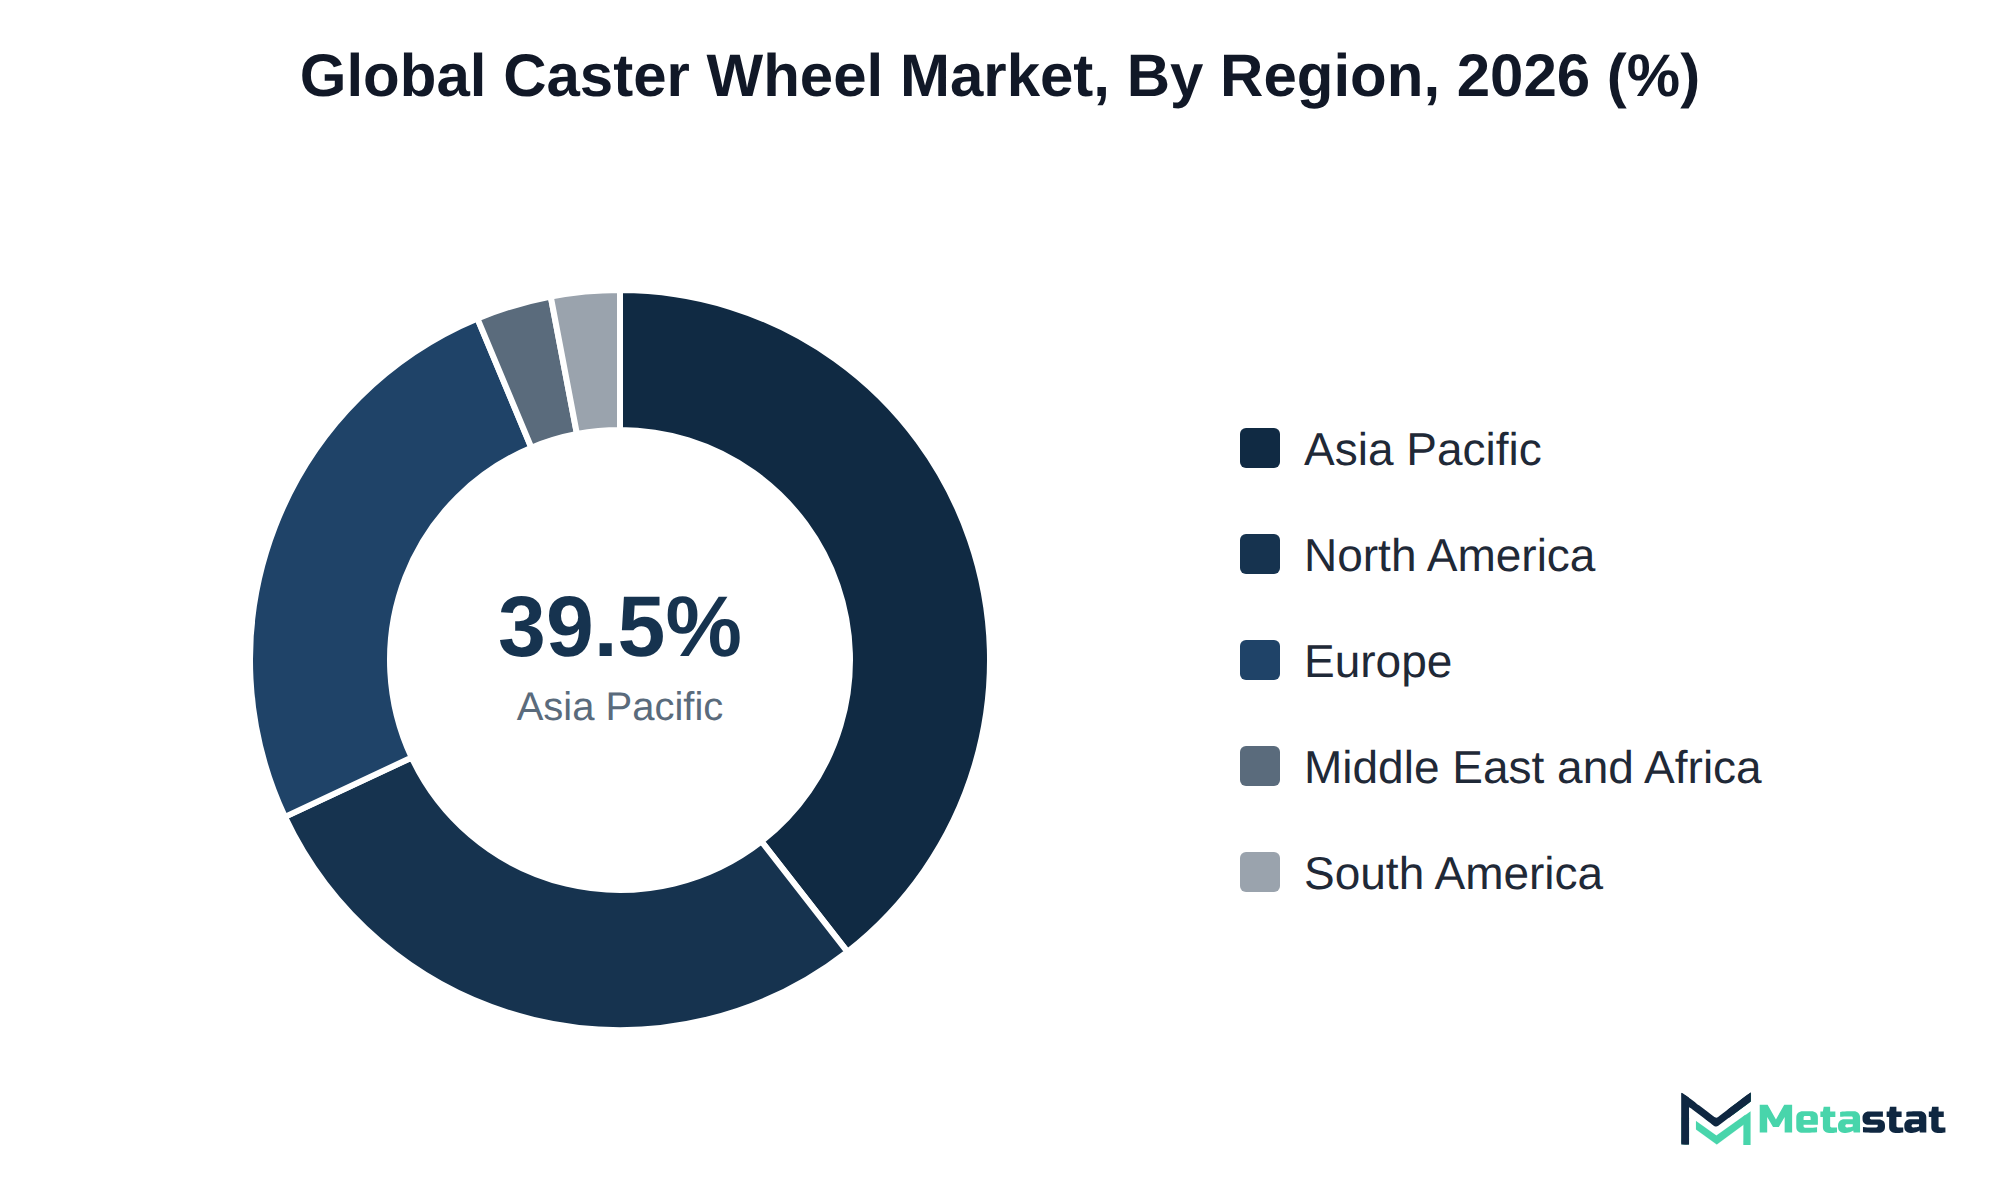
A few specialist manufacturers from North America and Germany lead the global caster wheels market, but none comes close to controlling it. Our bottom-up model sizes the market at USD 7,076.2 million in 2025, rising to USD 10,425.8 million by 2033 at a 4.96% CAGR. The basis is manufacturer revenue from castors and caster wheels, excluding forklift wheels and distributor margins. On that basis Colson Group leads with a 5.1% share in 2025, a figure triangulated from its workforce, stated unit output and plant footprint. TENTE and Blickle follow closely, and the 47 suppliers profiled in our analysis together hold 21.1% of the market. Scale matters less to competitive success than three things: being designed into OEM platforms, meeting each application's standards for braking, load and floor protection, and delivering locally at prices that hold up against Chinese supply.
Colson Group is the largest. It does not publish revenue, so its share is derived by cross-checking headcount, daily unit output and site count rather than from reported financials. Its position rests on breadth. A multi-brand portfolio (Colson, Albion, Shepherd, Faultless, Bassick and Revvo) runs from light furniture castors to extra-heavy industrial units, and the group combines a large US manufacturing base with distribution. That breadth suits buyers who want one supplier across many cart, bed and equipment platforms. The lead over TENTE and Blickle is narrow, however, and concentrated in North America. Colson's acquisitions of Manner Castors in Finland and ARBCO in 2023, Esco Plastics in 2025 and Custom Engineered Wheels in 2026 widen its reach, but they have not yet shown up as share gains. Third-party figures that give the leader a far larger share fail a cross-check against its workforce of 1,600.
TENTE shows a different route to scale. Its focus on castors for hospital beds and stretchers (group revenue of EUR 263.5 million in 2025) ties it to medical-equipment OEMs. Once a castor is validated on a bed platform, it typically remains for the life of that platform. Our forecast shows locking castors and medical equipment both gaining share through 2033, which makes a position built on specification structurally more defensible than one built on breadth alone. Blickle reaches a similar outcome through engineering depth. It makes more than 30,000 wheel and castor types, rated from 20 kg to 100 tonnes, at a single site in Rosenfeld, Germany, and it also builds ErgoMove powered drive systems.
Motorized and drive castors are the fastest-growing product type in our model, but that growth does not automatically reach caster makers. Builders of autonomous mobile robots can integrate drive units themselves, and where the caster's value cannot be separated from the drive module, it falls outside this market. Suppliers that co-engineer drive castors with robot and powered-bed OEMs are better placed than those that simply add a motorized line to their catalogue. Size in wheels is also a weak guide to standing in castors. Wicke's largest market is forklift wheels, and Räder-Vogel's range extends into rollers and wheel linings, so both carry less weight in the caster market than their size suggests.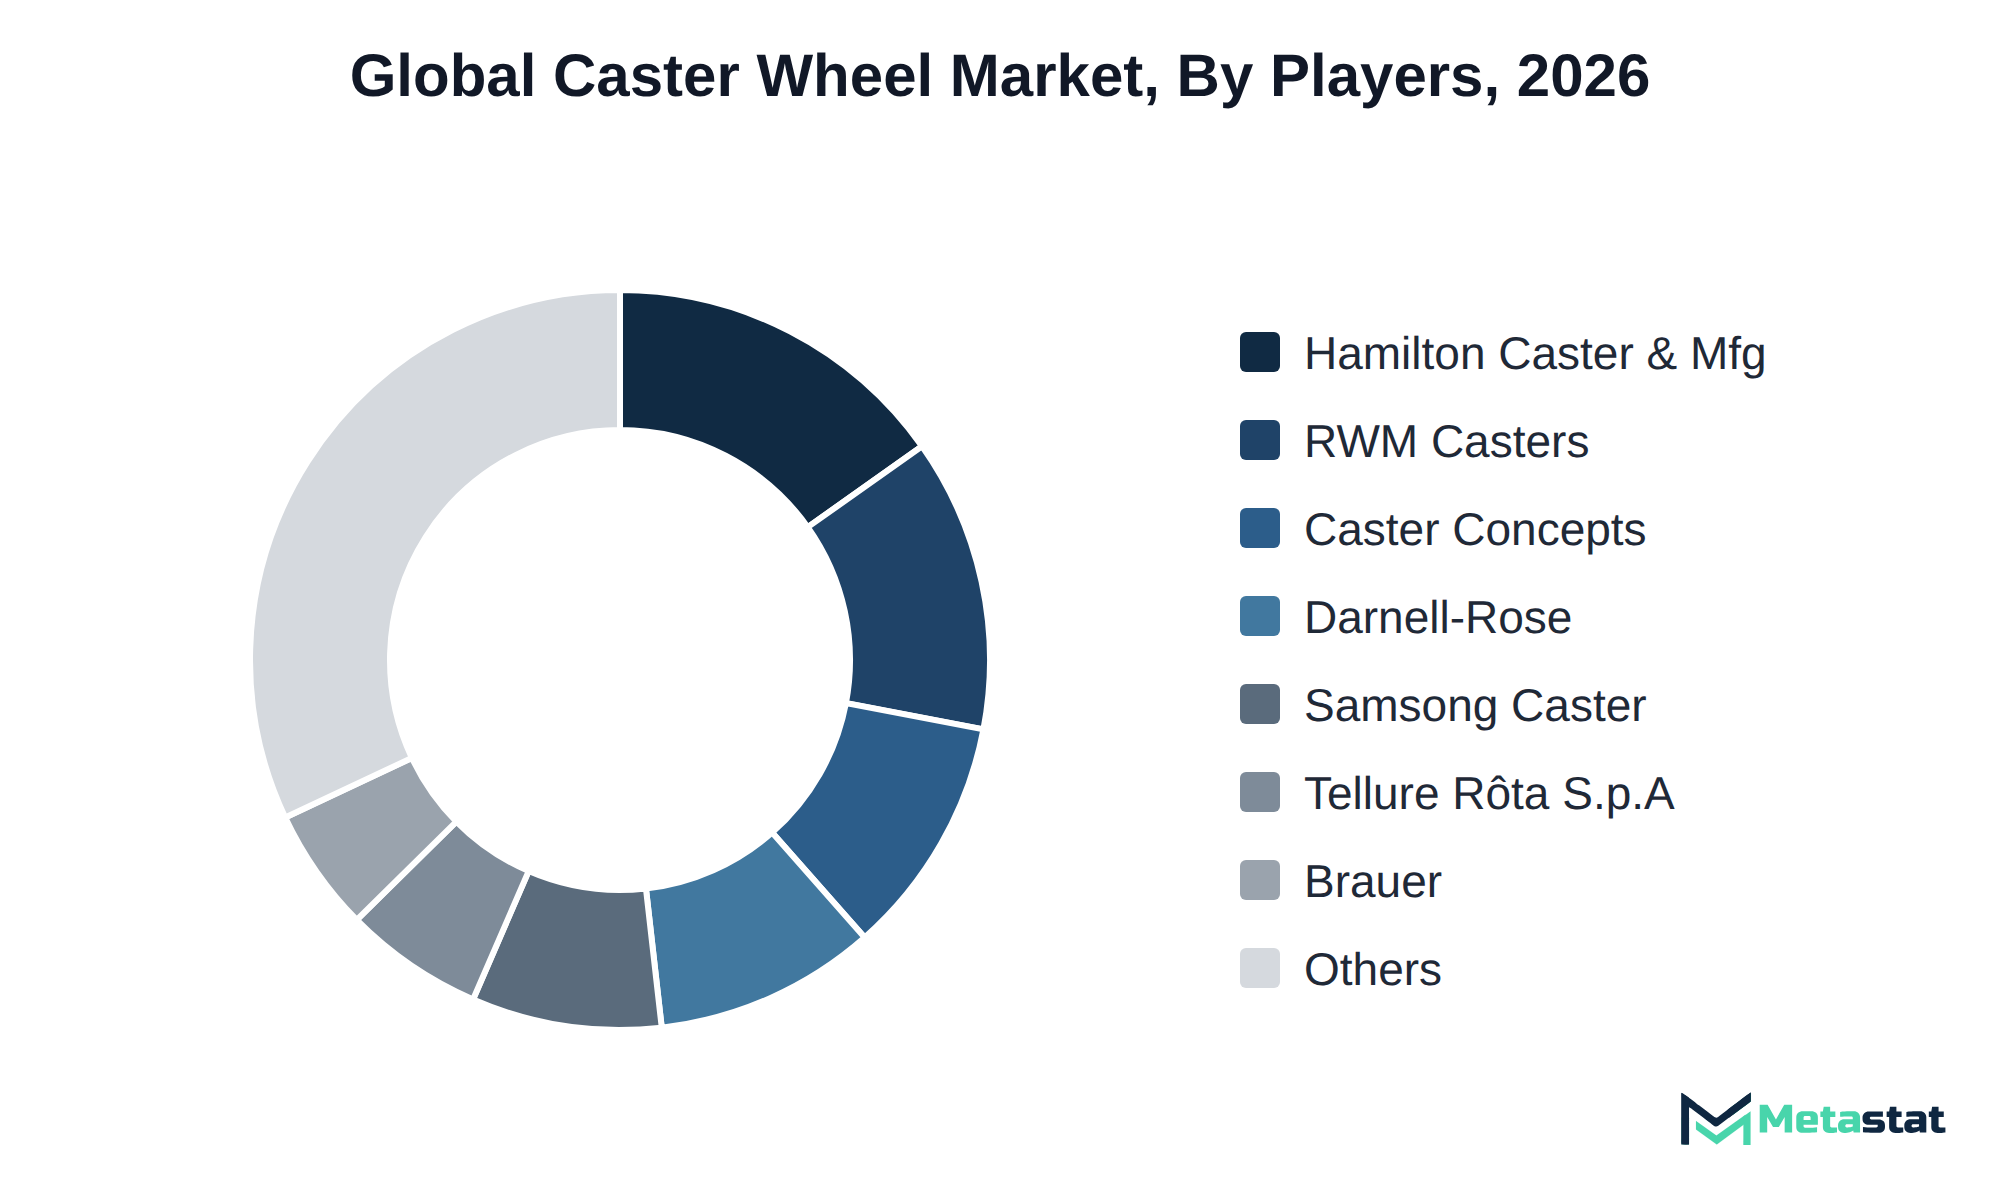
Our company model places 43.0% of the profiled suppliers' caster revenue in Europe, a region that accounts for 25.7% of global demand. Asia Pacific accounts for 39.5% of demand but only 17.7% of their sales. China alone exported USD 630.8 million of castors with metal mountings (HS 830220) in 2023, which is 52.5% of the combined exports of the 29 largest exporting countries. Chinese industrial castor output remains dominated by plastic and rubber wheels, and our model projects polyurethane gaining share faster in Asia Pacific than any other wheel material as producers move up-range. Global leadership in this market is therefore largely Western regional leadership. For growth in Asia, local plants such as TENTE's in Suzhou and Wicke's Chinese operation matter more than export catalogues.
US tariffs introduced in 2025 have the opposite effect in North America. They raise the landed cost of imported castors, which gives domestic producers such as Colson, Hamilton, RWM and Caster Concepts room to raise prices; in our model this supported 4.5% North American growth in 2025. Price-led revenue growth is not the same as share gain, however. Buyers facing higher costs can redesign equipment or source from Mexico, which is the fastest-growing North American country in our forecast.
Three questions will decide how competition reorders over the 2026–2033 forecast period. Will caster specialists or robot OEMs capture the value of drive castors? How long will US tariff protection last? Will Chinese producers win medical and heavy-duty specifications that currently favour European and US brands? Consolidation is the development to watch. Elesa completed its acquisition of Tellure Rôta in June 2026, putting an Italian castor maker inside a machine-components distribution network that reaches more than 60 countries, and Colson keeps buying smaller makers. With the leader holding 5.1% of revenue, such deals concentrate the market only if the acquirers turn the added breadth into OEM design-ins rather than overlapping catalogues.
Growth in the Caster Wheels market depends on several developments across different segments. Increased demand for swivel casters, projected to experience a CAGR of 4.3%, will drive substantial revenue growth, particularly in North America. The segment of medium duty caster wheels, anticipated to reach USD 4,069.9 million by 2033 at a CAGR of 5.2%, reflects a broader trend in industries requiring heavier load-bearing solutions, including industrial machinery. Adoption of polyurethane wheels, with an impressive CAGR of 6.3%, will enhance performance across various applications, including medical and healthcare equipment, which is expected to reach USD 1,736.4 million by 2033.
The primary risk to this forecast stems from fluctuations in raw material prices, which could constrain production capabilities and raise costs across the market. Such price volatility impacts manufacturers' margins, potentially leading to higher consumer prices and reduced demand. Balancing these factors will be essential for the caster wheels market to achieve its forecasted growth trajectory.
By Product Type: Swivel Casters, Rigid Casters, Twin-Wheel Casters, Locking Casters, Leveling Casters, Shock-Absorbing Casters, Motorized/Drive Casters, Ball Casters, Specialty Casters
By Wheel Material: Polyurethane, Rubber, Nylon/Polyamide, Polypropylene/Polyolefin, Thermoplastic Rubber, Cast Iron, Steel, Phenolic Resin, Aluminum, Others (Composite, Neoprene and Pneumatic)
By Application: Furniture and Office Equipment, Medical and Healthcare Equipment, Material Handling and Logistics Equipment, Industrial Machinery and Equipment, Carts, Trolleys and Platform Trucks, Automotive and Aerospace Ground Equipment, Retail and Shopping Equipment, Scaffolding and Construction Equipment, Waste and Recycling Equipment, Others (Food-Service, Laboratory, Cleanroom and Specialized Equipment)
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Caster Wheels market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 5.1% from 2026 to 2033 |
|
Revenue Unit |
USD million |
|
Segmentation |
By Product Type, Load Capacity, Wheel Material, Application, and Region |
|
By Region |
North America (By Product Type, Load Capacity, Wheel Material, Application, and Country)
|
|
Europe (By Product Type, Load Capacity, Wheel Material, Application, and Country)
|
|
|
Asia Pacific (By Product Type, Load Capacity, Wheel Material, Application, and Country)
|
|
|
South America (By Product Type, Load Capacity, Wheel Material, Application, and Country)
|
|
|
Middle East and Africa (By Product Type, Load Capacity, Wheel Material, Application, and Country)
|
Find answers to common questions about this report
The Caster Wheels market size was valued at USD 7,077.3 million in 2025.
The market is projected to grow at a CAGR of 5.1% during the forecast period from 2026 to 2033.
The North America Caster Wheels market size is estimated to reach USD 2,936.4 million by 2033.
Swivel Casters lead the Caster Wheels market with a projected value of USD 3,337.9 million by 2033, based on the highest growth rate among product types.
Growing demand for lightweight materials drives increased expenditure on caster wheels, particularly in industries prioritizing mobility solutions. Investment in medical and healthcare equipment represents a significant growth opportunity within the market, fueled by the need for specialized mobility solutions that adhere to strict regulatory standards.
Price fluctuations in raw materials restrict budget allocations for buyer groups, particularly in sectors reliant on cost-effective solutions. Higher costs compel businesses to postpone investments in new caster wheel technologies, hindering opportunities for innovation and efficiency improvements.
Factors favoring adoption in the caster wheels industry include the increasing focus on hygiene and safety in healthcare environments, driving demand for specialized mobility solutions. The segment for medical and healthcare equipment is projected to achieve a compound annual growth rate of 6.1 percent through 2033, indicating strong growth potential.
The Caster Wheels market is estimated to reach a valuation of USD 10,464.8 million by 2033.
Key players operating in the Caster Wheels market include Hamilton Caster & Mfg. Co., RWM Casters, Caster Concepts, Inc., Darnell-Rose, Samsong Caster Co., Ltd., and Sigerist GmbH.
The Light Duty Caster Wheels segment is projected to reach USD 3,121.1 million by 2033, reflecting a compound annual growth rate of 4.3 percent.
The analysts below cover Machinery & Equipment research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
INDUSTRY CONSULTANT - CHEMICALS & ADVANCED MATERIALS
Chemicals and Materials · Machinery & Equipment · Packaging
Amit Gadhekar Consultant for Chemicals and Materials at MetaStat Insight, directing sector-specific intelligence, research, and strategic consulting across global chemical and processing markets.
PRINCIPAL CONSULTANT - QUALITY SYSTEMS & COMPLIANCE
Electronics and Semiconductor · Machinery & Equipment · Professional Services
Omkar Phadtare is an Industry Consultant at MetaStat Insight, specializing in quality systems, regulatory compliance, and standards benchmarking to drive data-driven market intelligence and strategic industry research.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Most industry reports on warehouse automation bundle autonomous mobile robots and fixed conveyor installations into the same top-level numbers, which complicates advisory work. This study split the market cleanly by payload tiers, navigation technology, and fleet management software layers. The regional forecast for Western Europe gave our team defensible adoption benchmarks when evaluating capital allocation for logistics clients, saving us days of secondary data scrubbing.
Standard industry briefs frequently blur the operational distinctions between isobaric pressure exchangers and centrifugal turbines. In this study, MetaStat Insight categorized mega-scale desalination tenders across the GCC and Mediterranean basins by membrane replacement frequencies and salinity tolerances. Their primary research helped us evaluate local content requirements in Saudi Arabia and the UAE without relying on marketing literature. We found the segment-level equipment replacement estimates grounded and well-reasoned throughout.
The technical breakdown of ISO 20022 migration readiness across correspondent banking corridors was remarkably thorough. Rather than treating cross-border corporate payments as a single block, the report drew a useful distinction between multilateral netting platforms and domestic instant payment rails across ASEAN economies. MetaStat Insight highlighted regulatory constraints on foreign exchange liquidity management that many publications gloss over. The research material offered practical clarity for our platform development roadmap.
Explore related market intelligence reports worth reading alongside this one.