
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Europe Fund Administration Services Market Size, Share, By Service Type (Fund Accounting & NAV Calculation, Transfer Agency & Investor Services, Regulatory & Compliance Reporting, Corporate Secretarial & Fund Entity Administration, Tax Compliance & Reporting, Middle Office, Data & Treasury Services and Fund Depositary Oversight), By Fund Type (Mutual Funds & ETFs, Private Equity Funds, Venture Capital Funds, Hedge Funds, Private Debt Funds, Real Estate Funds, Infrastructure Funds and Others (Securitisation, Digital Asset Funds)), By Provider Type (Independent Fund Administrators and Bank-Owned Fund Administrators), By Region (Germany, France, UK, Italy, Spain, Russia and Rest of the Europe), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-5569
Published
October, 2026
Pages
288 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
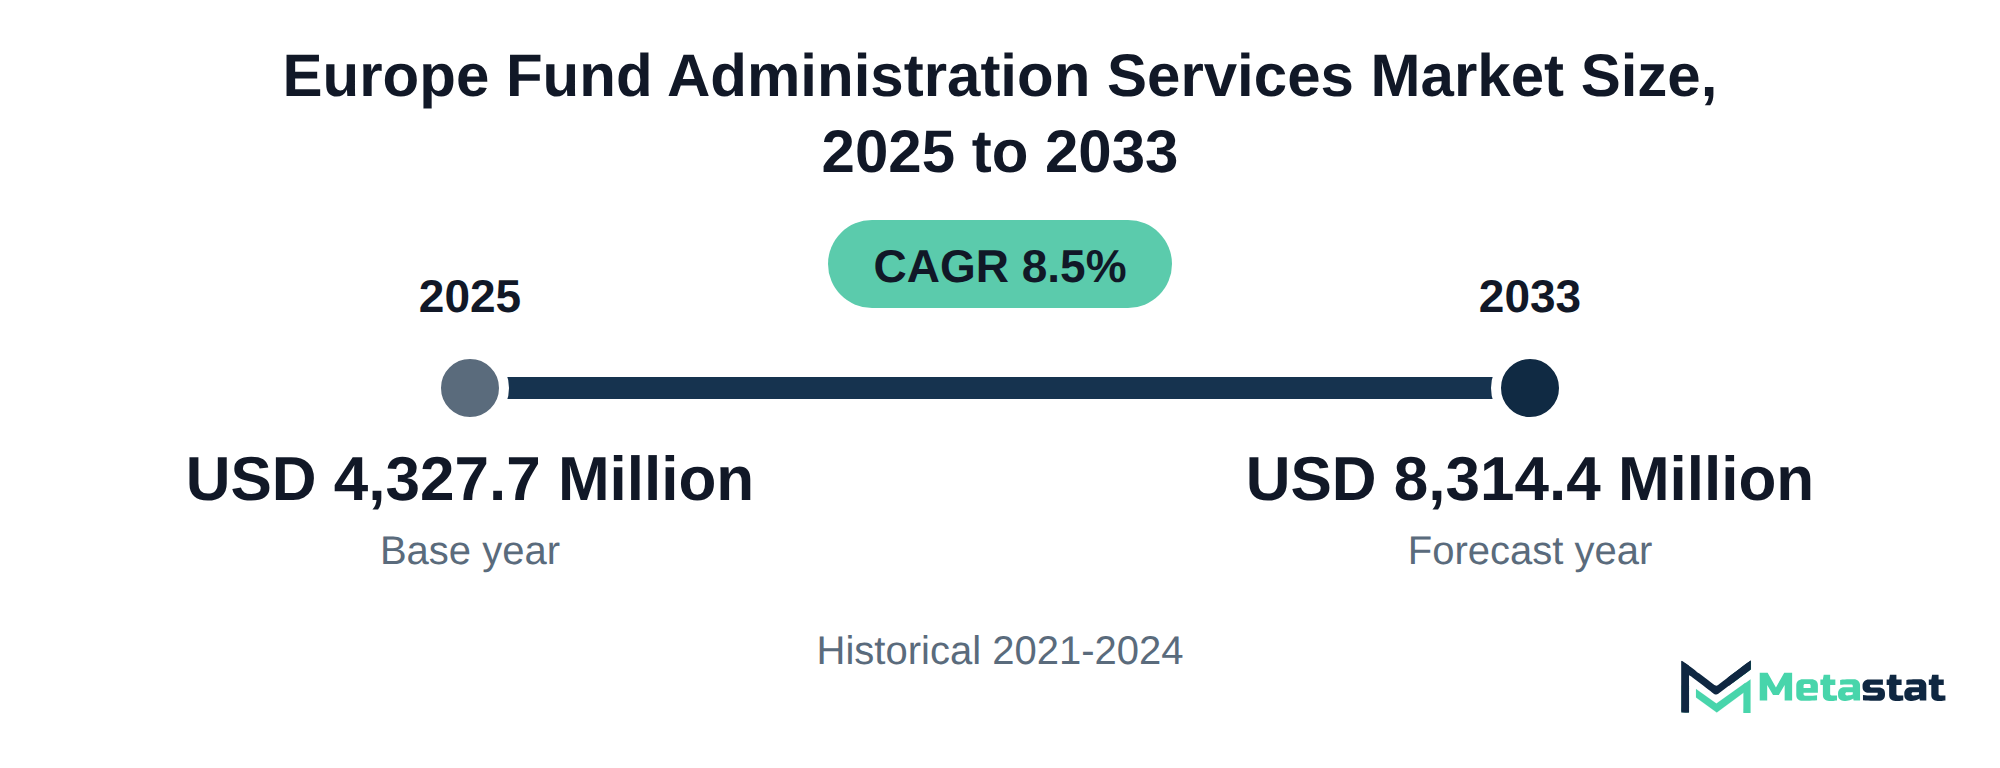
Market Valuation: Valued at $4,327.7 Million in 2025, projected to reach $8,314.4 Million by 2033 at a 8.5% CAGR.
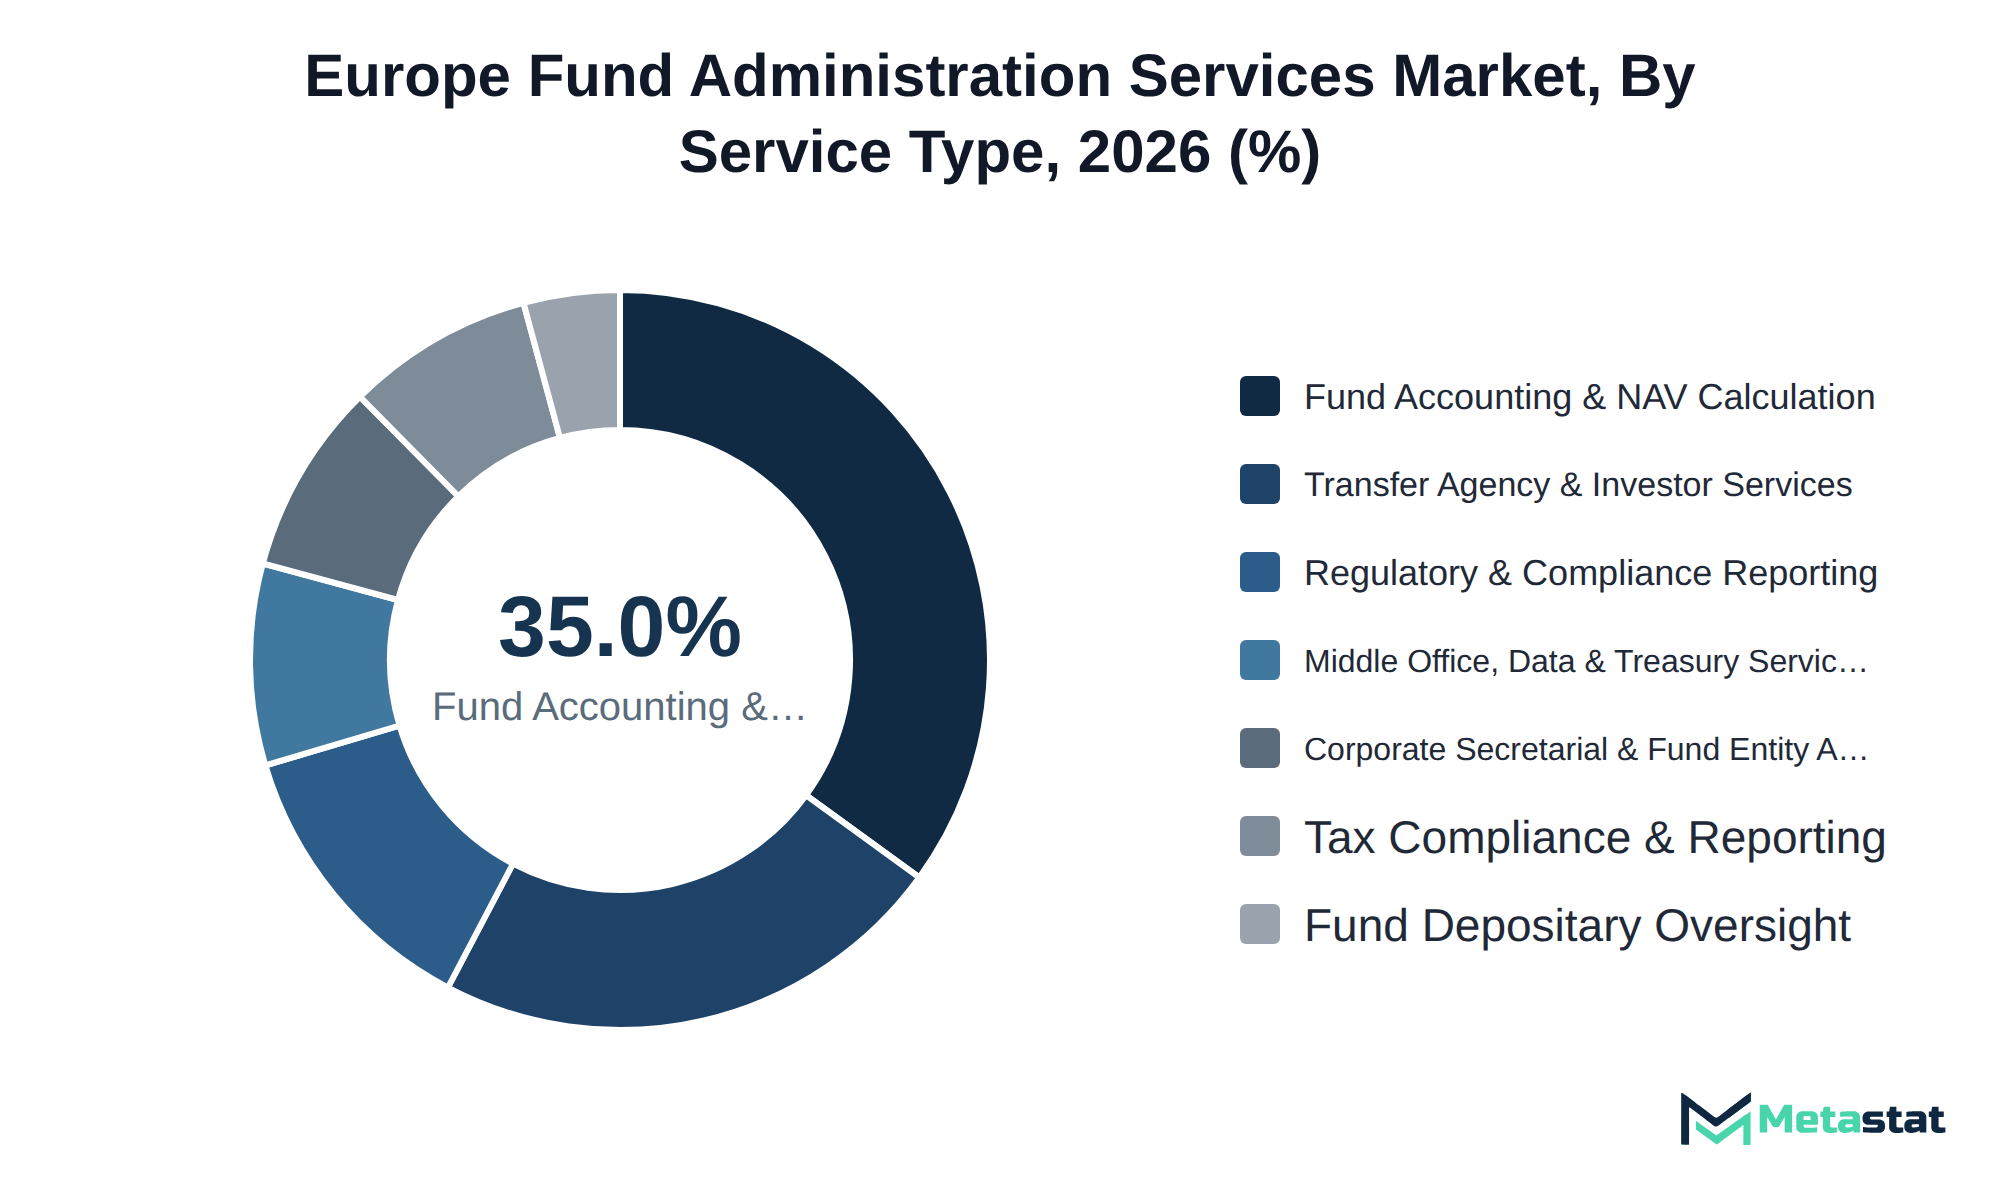
Dominant Segment: Fund Accounting & NAV Calculation leads the Europe Fund Administration Services market, driven by the critical need for accurate fund valuation and reporting.
Geographic Lead: Germany holds the largest market share, supported by its robust financial sector and significant investments in fund administration capabilities.
What's Inside: The report provides a comprehensive analysis of service types, fund types, and provider types, along with competitive coverage and market dynamics from 2026 to 2033.
Emerging Trends: The rise of private credit and evergreen funds is reshaping administration workloads, increasing the complexity of fund administration services.
Regulatory Impact: AIFMD II and DORA are driving demand for enhanced compliance and operational efficiency, compelling fund administrators to adopt sophisticated systems.
Choose Your License
Europe Fund Administration Services Market
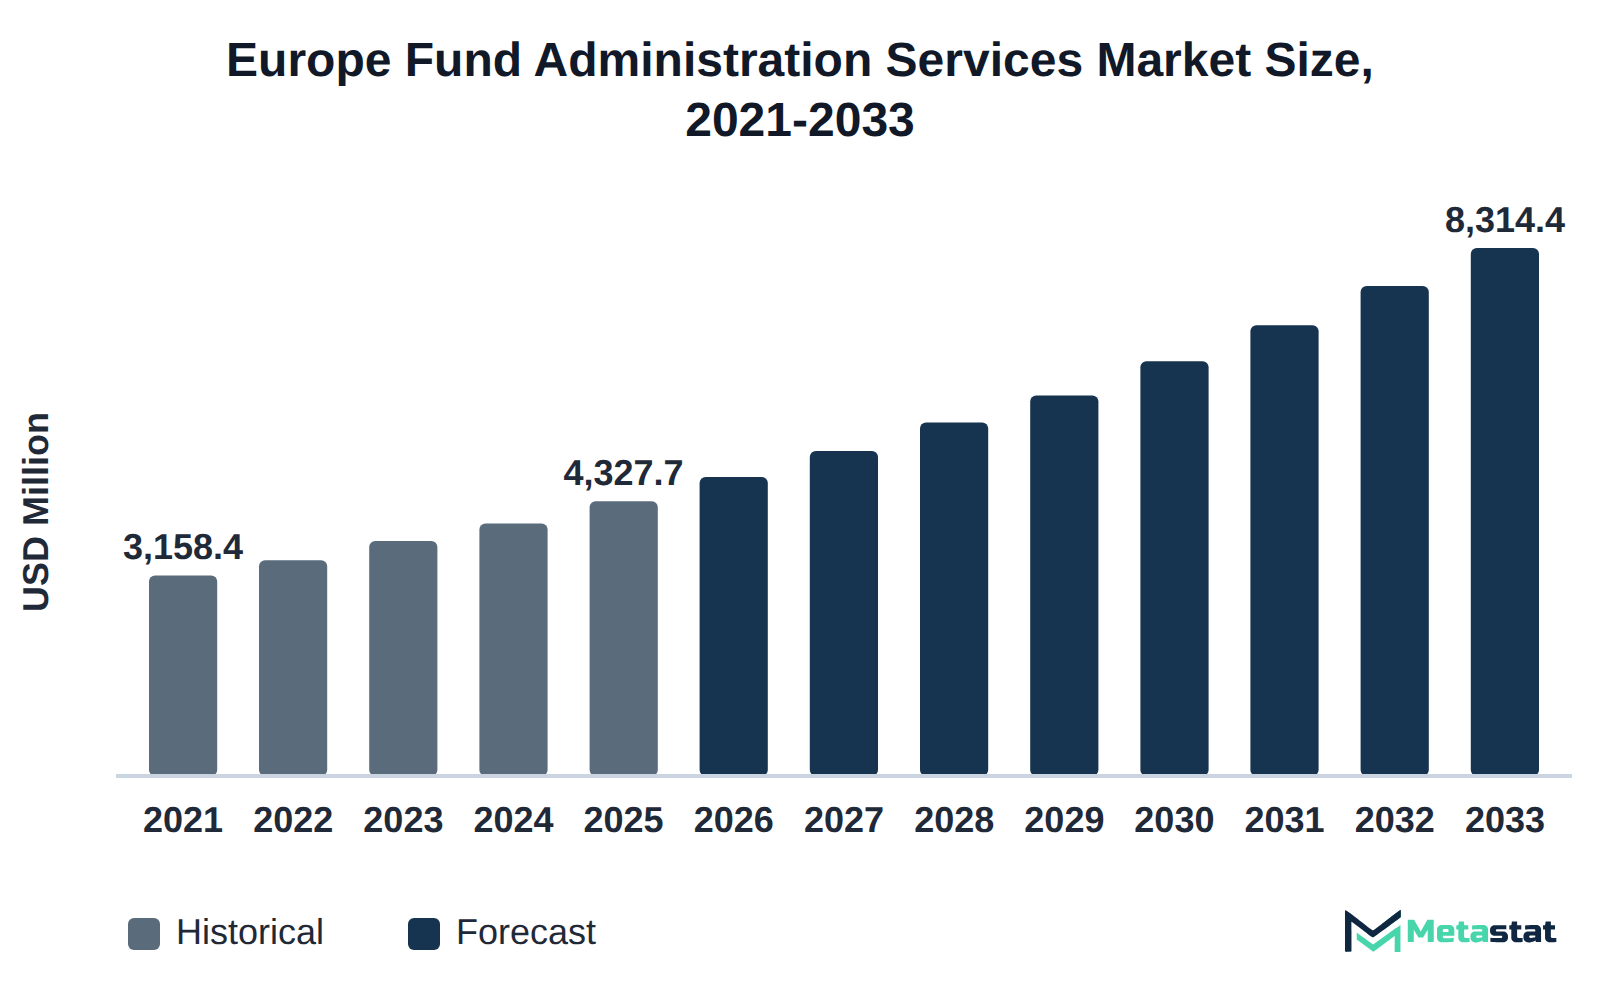
The Europe Fund Administration Services market was valued at USD 4,327.7 million in 2025 and is projected to reach USD 8,314.4 million by 2033, growing at a CAGR of 8.5% over the forecast period.
The Europe Fund Administration Services market covers support services for managing investment funds, including fund accounting, regulatory compliance, and investor services. Buyers invest in these services to ensure adherence to complex regulations, streamline operations, and enhance transparency within their fund structures. The growing complexity of financial markets drives increased expenditure on these services, with firms seeking to maintain competitive advantages while minimizing operational risks.
Growth in the market is primarily fueled by rising demand for effective fund management solutions across various investment vehicles. Among the segments, Fund Accounting & NAV Calculation holds the largest share, reflecting the critical nature of accurate fund valuation and reporting. Regionally, Germany holds the largest share of the market, driven by its strong financial sector and significant investments in fund administration capabilities.
One main growth driver stems from increasing regulatory scrutiny on fund operations, compelling firms to enhance their compliance frameworks. This trend fuels demand for services that ensure adherence to evolving regulations, allowing firms to focus on their core investment strategies while effectively managing compliance obligations. Regulatory adherence shapes market dynamics and sustains demand for fund administration services.
The services within the Europe Fund Administration Services market focus on enhancing operational efficiency and ensuring compliance for investment funds. Buyers, including asset managers and institutional investors, allocate resources to these services to streamline fund operations, mitigate risks, and meet regulatory requirements. This investment enables firms to focus on core investment strategies while outsourcing complex administrative tasks.
Growth in the market is driven by increasing demand for regulatory compliance and transparency in fund operations. The segment of Fund Accounting and NAV Calculation represents the largest value, reflecting the essential nature of accurate financial reporting in maintaining investor confidence. Germany holds the largest share in the region, highlighting the country’s robust financial services sector and strong regulatory framework that supports market expansion.
One primary driver of growth stems from the rising complexity of investment products and the regulatory landscape. Funds diversify and expand into new asset classes, increasing the demand for specialized administration services. This trend drives competition among service providers, leading to innovations and enhancements in service offerings within the market.
The emergence of private credit and evergreen funds is reshaping administration workloads within the Europe Fund Administration Services market. These fund types present unique operational demands, contributing to an increase in the complexity of fund administration. For instance, private equity funds are projected to reach a value of USD 1,817.5 million by 2033, reflecting a significant growth trajectory driven by increasing appetite for alternative investments.
Administration services for private credit and evergreen funds require advanced technological solutions to handle bespoke investment structures and dynamic reporting requirements. The complexity arises from the need to provide tailored services that accommodate the long-term nature of evergreen funds and the diverse strategies employed in private credit. This demand pushes fund administrators to enhance their service offerings, using technology to streamline operations and improve compliance.
The shift towards these fund types requires administrators to invest in advanced data management systems and analytics capabilities, ensuring they meet the rigorous reporting standards expected by investors. Firms specializing in the Europe Fund Administration Services market are expected to strengthen their technological infrastructure, resulting in improved operational efficiency and client satisfaction.
Automated NAV (Net Asset Value) processes and improved investor onboarding significantly impact payment structures within the Europe Fund Administration Services market. Efficient automation reduces operational bottlenecks, allowing service providers to streamline funding and processing for their clients. In 2026, the market value is expected to reach USD 4,708.3 million, indicating strong growth driven by technological advancements.
Contract models in the market have evolved to accommodate various client needs, with many providers implementing usage-based pricing strategies. By adopting these flexible pricing structures, fund administrators align costs with actual service utilization, allowing for improved cash flow management and budgeting accuracy. Independent Fund Administrators are projected to grow from USD 2,473.8 million in 2026 to USD 4,691 million by 2033, reflecting a compound annual growth rate (CAGR) of 9.6%. This growth highlights the increasing importance of automation in enhancing service delivery and client satisfaction.
The integration of intelligent automation in onboarding processes accelerates client acquisition and enhances compliance and due diligence. Competitive pressures intensify, prompting buyers to seek fund administration services that offer transparent pricing and efficient onboarding practices. This trend drives innovation and investment in technology-driven solutions.
Investment managers increasingly prefer Luxembourg and Ireland for cross-border fund servicing due to robust regulatory frameworks and operational efficiencies. These countries serve as primary hubs for fund administration, attracting numerous international asset managers seeking to establish a European presence. In 2026, independent fund administrators in the Europe Fund Administration Services market will generate USD 2,473.8 million, highlighting significant demand for services tailored to funds operated in these jurisdictions.
The distinct needs of investment managers in Luxembourg and Ireland center around regulatory compliance and tax efficiency. These regions provide specialized services, including fund accounting and NAV calculation, which cater to the requirements of various fund types, including mutual funds and private equity funds. With a projected compound annual growth rate of 9.6% for independent fund administrators through 2033, the market recognizes the importance of these jurisdictions in addressing complexities faced by global investors.
Consequently, Luxembourg and Ireland's prominence in the Europe Fund Administration Services market enhances their attractiveness for investment managers. Growing cross-border fund servicing in these regions gives asset managers easier access to European investors.
The implementation of AIFMD II and DORA significantly influences the Europe Fund Administration Services market, creating a need for enhanced compliance and operational efficiency. AIFMD II introduces stricter requirements for alternative investment funds, particularly concerning risk management and reporting obligations. These changes compel fund administrators to adopt more sophisticated systems to manage and report data accurately. In 2025, the market is valued at USD 4,327.7 million, reflecting the growing demand for such services as firms adapt to regulatory pressures.
DORA emphasizes the importance of digital operational resilience within financial institutions, further driving demand for robust fund administration services. The regulation aims to ensure that financial services firms withstand severe operational disruptions, thereby increasing reliance on fund administrators to facilitate compliance. For instance, the segment of Transfer Agency & Investor Services is projected to reach USD 1,946.4 million by 2033, indicating the urgency of enhancing service offerings to meet new compliance standards. This rising demand presents a significant opportunity for growth within the market, pushing administrators to innovate and strengthen their service capabilities.
Shifts in investor demographics significantly influence spending patterns within the Europe Fund Administration Services market. An aging population and the growing wealth among millennials contribute to heightened investment in mutual funds and private equity. While more individuals seek long-term financial security, institutions that provide fund administration services experience an increase in demand. In 2026, the market value stands at USD 4,708.3 million, reflecting the growing appetite for diverse investment vehicles.
This trend indicates a strong growth trajectory, with many financial institutions focusing on catering to these evolving client needs. The shift in investor behavior drives demand for tailored solutions, enhancing overall service volumes and price stability in the market.
Changes in regulatory frameworks significantly impact the operational capabilities of service providers within the Europe Fund Administration Services market. These modifications require investment managers to adopt advanced solutions for compliance and reporting, influencing market dynamics. Emphasis on enhanced transparency and accountability leads to increased demand for fund administration services that facilitate these requirements. Service providers streamline their offerings to ensure compliance with evolving regulations, attracting a wider range of clients.
Investment firms face pressure to enhance their operational efficiency while adhering to stricter compliance protocols. Increased demand for specialized services, including regulatory reporting and compliance tracking, drives providers to innovate their service models. The focus shifts toward RegTech solutions that simplify complex compliance processes, ensuring regulatory obligations are met without compromising operational effectiveness. This transformation supports growth within the Europe Fund Administration Services market, reflecting a proactive approach to managing regulatory challenges.
Increasing costs present a significant challenge for buyers in the Europe Fund Administration Services market. This limitation primarily affects smaller investment firms and new market entrants, leading to slower uptake of essential fund administration services. Rising service costs prompt many firms to delay necessary investments in technology and compliance, hindering their operational capabilities. Budget constraints often result in smaller orders, which restrict access to the full service portfolio. Heightened costs suppress demand for advanced solutions, affecting firms' ability to remain competitive in an evolving market. Consequently, the operational efficiency of these firms faces potential setbacks, resulting in a slower growth trajectory for the market overall. Price sensitivity among buyers highlights the need for scalable solutions that accommodate various budget levels without compromising service quality.
Suppliers in the Europe Fund Administration Services market face significant margin pressure, impacting their ability to deliver services profitably. Rising operational costs, particularly related to talent acquisition and retention, significantly diminish profit margins. The demand for skilled professionals in fund administration has escalated, driven by complex regulatory requirements and client expectations for enhanced service delivery. Organizations respond by investing in training programs to upskill existing staff and enhance productivity. This strategy aims to mitigate rising labor costs while maintaining service quality.
Several suppliers explore technological solutions to streamline processes and reduce dependency on manual labor, thus improving operational efficiency. By automating routine tasks, firms focus their resources on higher-value services, which enhance client satisfaction and retention. These strategies aim to maintain competitiveness in a market where service differentiation is increasingly crucial.
Independent Fund Administrators exhibit growth potential within the Europe Fund Administration Services market, driven by private equity funds. This segment is projected to reach USD 1,817.5 million by 2033, reflecting a compound annual growth rate (CAGR) of 9.2%. The increasing demand for specialized services tailored to private equity structures necessitates a focus on operational efficiency and regulatory compliance. Investment firms gravitate towards Independent Fund Administrators for their expertise in managing complex fund structures and ensuring adherence to evolving regulatory requirements. This dynamic highlights a significant opportunity for service providers to enhance their offerings, catering to the unique needs of private equity investors. Growth in this segment adds to overall market expansion and strengthens the position of providers seeking a foothold in private equity.
The Europe Fund Administration Services market is segmented based on Service Type, Fund Type, Provider Type, and Region.
Fund Accounting & NAV Calculation segment is valued at USD 1,637.1 million in 2026 and is projected to reach USD 2,729.6 million by 2033, at a CAGR of 7.6% during the forecast period. This segment provides essential services for calculating net asset values and maintaining accurate fund accounting records for investment funds. Asset managers and institutional investors engage these services to ensure transparency and compliance with regulatory standards. Growth in this segment is driven by increasing demand for detailed reporting and compliance amid evolving market regulations. Transfer Agency & Investor Services exhibits a higher growth rate of 8.9%. Fund Accounting & NAV Calculation offers steadier growth, appealing to clients prioritizing reliability in their accounting practices. The focus on automation and technological advancements further enhances operational efficiencies, providing competitive advantages to service providers in the market.
Transfer Agency & Investor Services segment is estimated to reach USD 1,946.4 million by 2033, at a CAGR of 8.9% during the forecast period. This segment provides essential services for managing investor relationships, processing transactions, and ensuring regulatory compliance, including mutual fund transfer agency functions. Investment funds, including mutual funds and private equity, heavily rely on these services to maintain accurate records and provide timely information to investors. The growing complexity of regulatory requirements drives demand for enhanced compliance capabilities, influencing service providers to improve their offerings. Compared to Fund Accounting & NAV Calculation, which has a CAGR of 7.6%, the Transfer Agency & Investor Services segment experiences faster growth, reflecting increasing investment activity and a rising number of investors seeking reliable services. This accelerated growth positions the segment as a critical element in the broader Europe Fund Administration Services market, catering to the evolving needs of fund managers and investors.
Regulatory & Compliance Reporting segment is expected to reach USD 1,190.6 million by 2033. This segment involves the preparation and submission of necessary documentation to ensure adherence to legal and regulatory requirements, a task closely tied to investment management regulatory reporting. Investment managers, fund administrators, and financial institutions access these services to mitigate risks associated with regulatory non-compliance. The increasing complexity of regulations drives demand for these services, particularly among private equity funds, which typically require stringent compliance measures. Growth in this segment stands at a CAGR of 8.9%, surpassing the overall market growth rate and reflecting a heightened emphasis on regulation across the financial landscape. Unlike other segments, Regulatory & Compliance Reporting has a specialized focus on legal adherence rather than operational efficiency, which distinguishes it from broader service offerings within the market.
Corporate Secretarial & Fund Entity Administration segment is projected to grow at a CAGR of 7.8% during the forecast period. This segment provides essential services for maintaining compliance and governance for investment funds, primarily serving private equity firms and real estate funds. Increasing regulatory scrutiny has heightened the importance of these services, driving demand for reliable administration solutions. Unlike the Transfer Agency & Investor Services segment, which exhibits a higher CAGR of 8.9%, Corporate Secretarial & Fund Entity Administration faces a more stable growth trajectory. The evolving corporate governance environment emphasizes the need for strong oversight, influencing buyers to prioritize transparency. This proactive approach to compliance aids in mitigating risks associated with regulatory breaches, enhancing the operational efficiency of service providers in the market.
Tax Compliance & Reporting addresses the obligations and requirements that investment funds face regarding taxation. This segment serves clients including mutual funds, private equity funds, and hedge funds, ensuring compliance with evolving tax regulations across multiple jurisdictions. Demand for these services is driven by increasing regulatory scrutiny and the complexity of tax laws, compelling funds to seek specialized tax management expertise. Unlike other segments, Tax Compliance & Reporting experiences steady growth due to the persistent need for accurate tax reporting and compliance solutions. This segment does not exhibit the same rapid growth as Transfer Agency & Investor Services, which benefits from higher transaction volumes and ongoing investor engagement. Strong performance in tax compliance services positions it as a critical element of the Europe Fund Administration Services market.
Middle Office, Data & Treasury Services refers to the support provided to investment managers, focusing on data management, treasury operations, and middle office functions. This segment serves investment funds, hedge funds, and private equity firms, facilitating data integrity and enhancing operational efficiency. Demand for these services is driven by increasing complexity in financial transactions and regulatory compliance requirements. Clients seek to streamline processes, reduce risks, and improve decision-making, which places emphasis on data accuracy and real-time reporting capabilities. Compared to other segments in the market, this segment experiences a moderate growth rate, influenced by regulatory pressures and the evolving technological landscape. Increased reliance on digital solutions and automation highlights the importance of data management and treasury services in achieving a competitive advantage.
Fund Depositary Oversight involves the oversight and management of fund depositary functions, ensuring compliance with regulations and safeguarding investors' assets. Investment firms, including mutual funds and private equity funds, engage this service to meet regulatory requirements and enhance investor trust. Growth in this segment primarily stems from increasing regulatory scrutiny and the demand for enhanced investor protection measures. This segment differentiates itself from others in the service type category through its specific focus on compliance and risk management, which influences the pricing structure and attracts clients seeking robust regulatory assurance. Unlike segments including Transfer Agency & Investor Services that experience significant growth rates, Fund Depositary Oversight exhibits a more stable growth trajectory driven by the ongoing evolution of regulatory frameworks in the Europe Fund Administration Services market.
Valued at USD 1,771 million in 2026, this segment is projected to reach USD 2,846 million by 2033, at a CAGR of 7% during the forecast period. Investment managers apply mutual funds and ETFs for diversified portfolios, attracting both retail and institutional investors seeking liquidity and lower costs. Growth in this segment is propelled by an increasing preference for passive investment strategies, particularly among younger investors. Comparatively, mutual funds and ETFs experience slower growth than private equity funds, which show a CAGR of 9.2%. The shift towards digital platforms for trading and investment management enhances accessibility, driving adoption among a broader range of investors. Regulatory requirements, particularly those surrounding transparency and reporting, shape the operational landscape and influence how services are delivered. The Europe Fund Administration Services market continues to adapt to these evolving demands, positioning mutual funds and ETFs as key components of investment strategies.
This segment serves institutional investors and high-net-worth individuals by offering investment opportunities in private companies, aiming to generate substantial returns over time. The demand for Private Equity Funds is driven by a growing appetite for alternative investments, perceived to offer higher returns compared to traditional equity markets. Compared to other fund types, this segment exhibits faster growth, with a CAGR of 9.2%, outpacing Mutual Funds and ETFs, which have a CAGR of 7%. Increased capital inflows into private equity highlight the segment's attractiveness, influencing both investors and fund administrators to enhance their service offerings in the Europe Fund Administration Services market.
Venture Capital Funds segment is expected to reach USD 429.9 million by 2033. This segment primarily serves investors seeking to finance startup companies and small businesses, aiming for high growth potential. The increasing number of technology startups and innovative business models significantly drives this segment's growth, reflecting a shift in investor focus toward emerging markets. The projected CAGR of 9.2% during the forecast period positions Venture Capital Funds among the fastest-growing segments within the market, outperforming other fund types. Distinctively, this segment attracts a different buyer profile, including institutional investors and high-net-worth individuals, who exhibit a higher risk tolerance compared to traditional fund investors. This appetite for risk aligns with the expectation of substantial returns, differentiating Venture Capital Funds from more conservative fund types in the Europe Fund Administration Services market.
The Hedge Funds segment is projected to grow at a CAGR of 7.5% during the forecast period. Hedge funds are used by institutional investors and high-net-worth individuals seeking diverse investment strategies and potential high returns. The demand for hedge fund administration services is driven by increasing investment activities and the need for sophisticated risk management and compliance solutions. This segment differs from others in the Fund Type category, including Mutual Funds and ETFs, which experience a lower growth rate of 7% during the same period. The complexity of hedge fund structures often requires specialized services, leading to higher price points compared to more traditional fund types. Investors in volatile markets value tailored administrative support, which continues to enhance the relevance of the Hedge Funds segment within the Europe Fund Administration Services market.
Private Debt Funds focus on providing financing to companies that are not publicly traded. This segment attracts investment from institutional investors seeking higher returns than traditional asset classes offer. Demand for private debt funds increases due to a shift in borrowing patterns, with companies seeking alternative lending options instead of bank financing, especially during periods of economic uncertainty. Regulatory changes have encouraged this trend, making private debt an appealing option for both borrowers and lenders. Compared to other fund types, private debt funds often charge higher fees, reflecting their bespoke nature and specialized management. While mutual funds and ETFs grow steadily, private debt funds capture niche opportunities, appealing to investors seeking tailored financing solutions. This segment features unique characteristics that differentiate it from others, particularly regarding its appeal to institutional investors and the specific risks involved in lending to non-public entities.
Real Estate Funds encompass investment vehicles that pool capital for the purpose of buying, managing, and selling real estate assets, which places them within real estate investment management. Institutional investors, high-net-worth individuals, and investment firms use these funds to diversify portfolios and gain exposure to real estate markets without directly owning properties. The growth of this segment is driven by increasing interest in alternative investments and the demand for stable income sources. Compared to other fund types, Real Estate Funds experience different competitive dynamics, often attracting investors seeking lower volatility and long-term capital appreciation. Regulatory considerations and changes in tax treatment for real estate investments play a significant role in shaping the operating environment. While segments including Private Equity Funds show faster expansion, Real Estate Funds present stable growth opportunities that appeal to risk-averse investors within the Europe Fund Administration Services market.
Infrastructure Funds focus on financing essential physical assets that support economic development, including transportation, energy, and utilities. These funds attract institutional investors and private equity firms seeking stable long-term returns. The growth of this segment reflects the increasing global need for infrastructure development and modernization, driven by urbanization and population growth. This sector typically experiences higher capital requirements and longer investment horizons compared to other fund types, leading to a more cautious approach from investors. Infrastructure Funds differ from segments including Private Equity Funds, which pursue more aggressive growth strategies. The stable cash flows and essential nature of infrastructure investments position this segment uniquely to withstand economic fluctuations and provide consistent returns, appealing to risk-averse investors in the Europe Fund Administration Services market.
This segment encompasses Securitisation and Digital Asset Funds, which represent innovative financial structures and investment vehicles. These funds attract institutional investors and asset managers, often focusing on enhancing liquidity and offering exposure to emerging digital assets. The growth of this segment is significantly influenced by advancements in blockchain technology and regulatory developments. Increasing interest in digital asset investment management drives demand, attracting both retail and institutional investors looking for diversification. Compared to traditional funds, this segment operates with different risk profiles and regulatory requirements, impacting pricing and operational structures. Identifying the appropriate regulatory framework remains a critical factor for stakeholders aiming to capitalize on the opportunities presented by digital assets. The Europe Fund Administration Services market reflects a dynamic relationship between traditional finance and innovative asset management strategies.
This segment primarily caters to asset managers and institutional investors, providing essential services including fund accounting, investor reporting, and compliance management. Growth in this segment is driven by increasing regulatory requirements and a rising number of investment funds seeking specialized administration services. Compared to Bank-Owned Fund Administrators, which have a projected CAGR of 7.1%, Independent Fund Administrators demonstrate a stronger growth trajectory, reflecting a shift towards outsourcing administrative functions to enhance operational efficiency and cost-effectiveness. The market for Independent Fund Administrators expands, supported by ongoing demand for tailored fund management solutions.
Bank-Owned Fund Administrators segment is estimated to reach USD 3,623.4 million by 2033, at a CAGR of 7.1% during the forecast period. This segment provides fund administration services specifically through financial institutions that own and operate their own fund administration divisions. These services cater to a range of investment vehicles, including mutual funds, hedge funds, and private equity funds, primarily targeting institutional investors and asset managers. Factors driving growth in this segment include increasing demand for regulatory compliance and reporting, alongside a rising emphasis on risk management. Compared to Independent Fund Administrators, which exhibit a higher growth rate at a CAGR of 9.6%, Bank-Owned Fund Administrators experience more moderate expansion yet offer integrated services that leverage the banks' existing financial infrastructure. This integration often leads to competitive pricing, providing a distinct advantage in the Europe Fund Administration Services market.
Germany segment is valued at USD 580.4 million in 2026 and is projected to reach USD 981.9 million by 2033, at a CAGR of 7.8% during the forecast period. This segment serves investment funds and financial institutions by providing essential fund administration services, which include fund accounting, compliance reporting, and investor services. Strong growth is driven by increasing regulatory requirements and demand for transparency in fund operations. Compared to other regions, Germany stands out due to its robust financial sector, which attracts a diverse range of fund types seeking reliable administrative support. The growth rate of Germany's segment is slower than that of the Private Equity Funds segment, which has a CAGR of 9.2%, indicating a varying pace of market development within the Europe Fund Administration Services market. The market's overall expansion reflects the ongoing evolution and sophistication of financial services in this region.
France segment is estimated to reach USD 841.4 million by 2033, at a CAGR of 7.6% during the forecast period. This segment serves investment funds and financial institutions, focusing on the administration and management of various funds. Growth in this segment is driven by regulatory compliance and increasing investments in the financial sector. France experiences steady demand, influenced by its robust financial infrastructure and a diverse range of investment products compared to other regional segments. Investor confidence, supported by favorable regulations, contributes to its growth trajectory and distinguishes it from markets facing more stringent compliance challenges. The market is anticipated to expand consistently, aligning with broader trends in the Europe Fund Administration Services market.
UK segment is expected to reach USD 1,327 million by 2033. This segment serves investment managers and institutional clients through efficient fund administration services, including fund accounting, compliance reporting, and investor services. A significant driver of growth stems from increasing regulatory requirements, which compel firms to adopt robust compliance frameworks to meet standards. This segment outpaces others in the region, reflecting higher growth prospects compared to more traditional fund types like Mutual Funds and ETFs, which have a CAGR of 7%. The market's evolution reflects the demand for tailored services, enabling firms to manage complexities arising from regulatory changes and investor expectations. By 2033, UK fund administration services position themselves as essential support for capital markets, contributing significantly to the overall growth of the Europe Fund Administration Services market.
Valued at USD 1,004.1 million in 2026, the Italy segment is projected to grow at a CAGR of 9% during the forecast period. This segment primarily serves fund managers and institutional investors who require reliable fund administration services to ensure compliance and transparency. Demand is driven by the increasing need for efficient fund accounting and regulatory reporting solutions, particularly in a complex regulatory environment. Compared to other regions, Italy's growth trajectory is notable, with a faster CAGR than many neighboring countries. Investors seek robust administrative support to navigate evolving compliance requirements, enhancing the segment's appeal. The Italy segment differentiates itself with a competitive landscape characterized by local and international administrators providing tailored services to meet specific investor needs.
Spain is a notable segment within the Europe Fund Administration Services market. This segment provides fund administration services to various financial institutions and investment firms. Demand for these services is driven primarily by the growing complexity of regulatory requirements and the increasing need for compliance among fund managers. Spain differs from other regions, particularly in terms of its regulatory environment, which influences operational costs and service pricing. The competitive landscape in Spain includes a mix of independent fund administrators and bank-owned entities, reflecting a diverse service provision tailored to local investor needs. The emphasis on regulatory compliance presents both a challenge and an opportunity for growth, encouraging service providers to enhance their offerings and capabilities.
Russia's involvement in fund administration services entails a unique set of needs, particularly among local investors and asset managers seeking efficient solutions. These services support the management and oversight of various investment funds, ensuring compliance with regional regulations. Demand within this segment is influenced by increasing foreign investment interest in Russian markets, driving the need for transparent and reliable fund administration services. Compared to other regions, the growth trajectory is affected by heightened regulatory scrutiny and geopolitical challenges, which impact investor confidence. Unlike the independent fund administrators found in more stable markets, local providers navigate a complex environment of regulations, influencing their pricing strategies and service offerings. The Europe Fund Administration Services market reflects significant variations in regional dynamics, highlighting the importance of localized expertise and responsiveness to market conditions.
Rest of the Europe segment includes various countries that contribute to the overall landscape of fund administration services. This segment serves institutional investors, private equity firms, and mutual fund entities seeking to ensure compliance and streamline operations. Increasing regulatory requirements drive demand for robust compliance and reporting services. The diversity of market participants in this region influences the adoption of innovative fund administration solutions, which differ from those offered in more prominent markets like Germany or France. While specific growth metrics for this segment remain unavailable, its dynamic nature highlights a significant opportunity for providers to cater to unique regional needs and preferences. The Europe Fund Administration Services market is expected to evolve, driven by shifts in investment strategies and regulatory frameworks across diverse European nations.
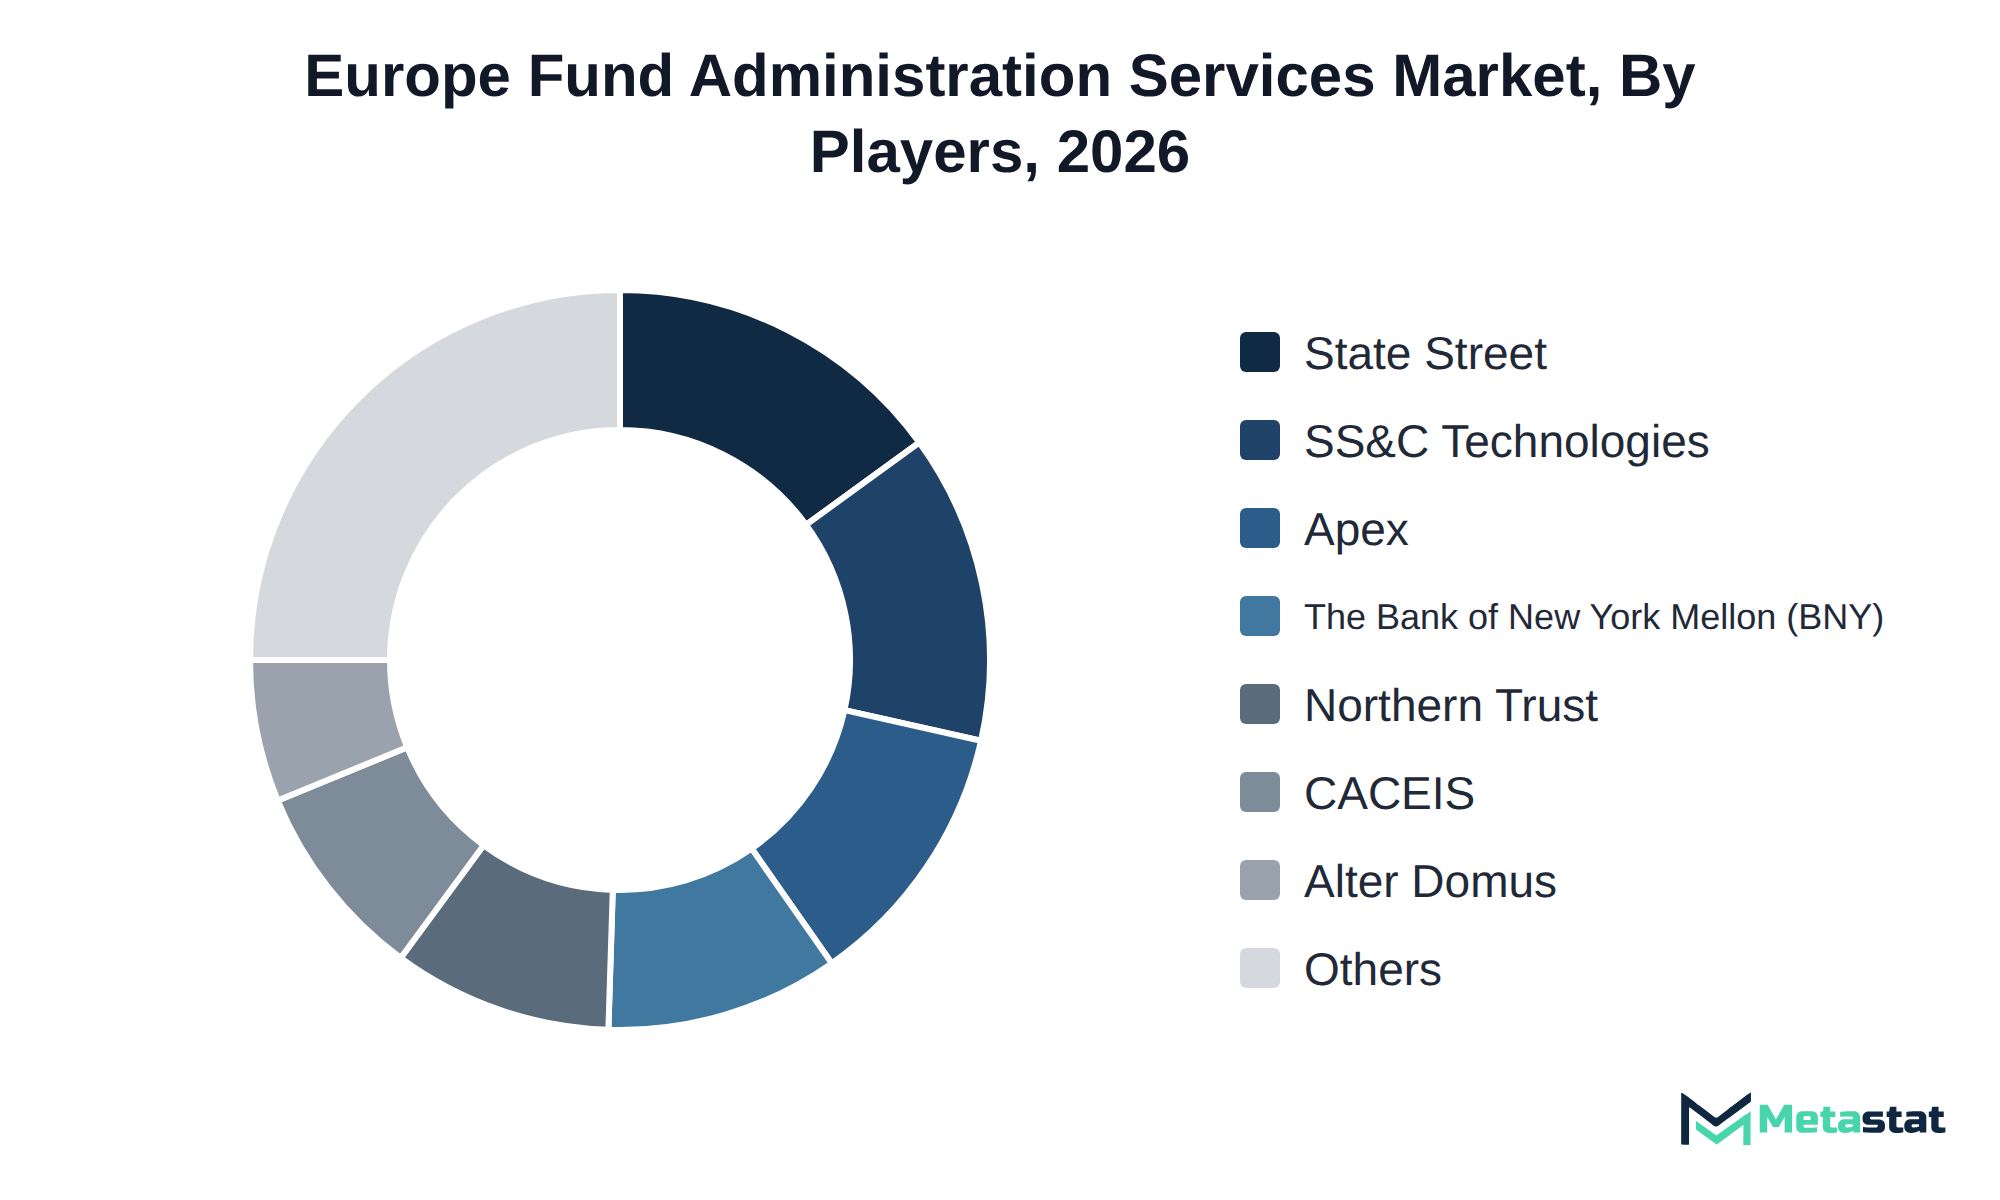
Competition within the Europe Fund Administration Services market occurs across various service types, with distinct strategies adopted by different providers. Independent fund administrators, exemplified by Apex Group, SS&C Technologies Holdings, Inc., and State Street Corporation, emphasize a broad range of customized services to cater to diverse client needs. In contrast, bank-owned fund administrators, including The Bank of New York Mellon Corporation (BNY) and HSBC Holdings plc, leverage extensive banking networks and regulatory expertise, providing clients with integrated financial solutions.
Buyers prioritize several factors when selecting fund administration services, including price, certification, and service quality. For instance, Transfer Agency & Investor Services offered by Northern Trust Corporation aligns with clients seeking robust support and compliance. In the area of Regulatory & Compliance Reporting, firms like Citigroup Inc. focus on ensuring accurate and timely reporting to satisfy regulatory demands, enhancing their appeal in the market. This competitive landscape drives innovation and enhances service delivery to meet evolving client expectations.
Growth in the Europe Fund Administration Services market relies on several factors. These include increasing demand for Transfer Agency and Investor Services, projected to reach USD 1,946.4 million by 2033, driven by heightened investor engagement and regulatory compliance requirements. The segment of Independent Fund Administrators is expected to expand significantly, growing from USD 2,473.8 million in 2026 to USD 4,691 million by 2033, reflecting a shift towards outsourcing and the need for specialized services. The potential for growth in the Private Equity Funds segment, anticipated to reach USD 1,817.5 million by 2033, will further support market expansion while investors seek tailored fund solutions.
Several risks could inhibit this anticipated growth. Economic downturns or regulatory changes in key regions, including Germany and France, could slow adoption rates and dampen investment flows. The market's capacity to reach USD 8,314.4 million hinges on favorable economic conditions and continued demand for innovative fund administration solutions.
By Service Type: Fund Accounting & NAV Calculation, Transfer Agency & Investor Services, Regulatory & Compliance Reporting, Corporate Secretarial & Fund Entity Administration, Tax Compliance & Reporting, Middle Office, Data & Treasury Services, Fund Depositary Oversight
By Fund Type: Mutual Funds & ETFs, Private Equity Funds, Venture Capital Funds, Hedge Funds, Private Debt Funds, Real Estate Funds, Infrastructure Funds, Others (Securitisation, Digital Asset Funds)
By Provider Type: Independent Fund Administrators, Bank-Owned Fund Administrators
By Region: Germany, France, UK, Italy, Spain, Russia, Rest of the Europe
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Fund Administration Services market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 8.5% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Service Type, Fund Type, Provider Type, Region, and Region |
Find answers to common questions about this report
The Fund Administration Services market size was valued at USD 4,327.7 million in 2025.
The market is projected to grow at a CAGR of 8.5% during the forecast period from 2026 to 2033.
The leading segment in the Fund Administration Services market is Transfer Agency & Investor Services, with a projected value of USD 1,946.4 million by 2033. This segment surpasses others in terms of growth potential and revenue generation.
Shifts in investor demographics, particularly an aging population and growing wealth among millennials, drive increased investment in mutual funds and private equity. Changes in regulatory frameworks necessitate advanced solutions for compliance and reporting, influencing market dynamics and enhancing demand for fund administration services.
Increasing costs present a significant challenge for buyers, particularly affecting smaller investment firms and new market entrants. This limitation leads to slower uptake of essential services, hindering operational capabilities and overall market growth.
Several factors favor adoption in the Europe Fund Administration Services market. The increasing demand for specialized services, particularly in private equity, drives investment firms to seek Independent Fund Administrators for their expertise. evolving regulatory requirements necessitate enhanced compliance solutions, further supporting the growth of fund administration services.
The Fund Administration Services market is estimated to reach a valuation of USD 8,314.4 million by 2033.
Key players operating in the Fund Administration Services market include Apex Group, SS&C Technologies Holdings, Inc., State Street Corporation, The Bank of New York Mellon Corporation (BNY), BNP Paribas S.A. (Securities Services), CACEIS, and The Citco Group Limited.
Independent Fund Administrators are projected to reach USD 4,691 million by 2033, reflecting a compound annual growth rate (CAGR) of 9.6%.
Private Equity Funds exhibit the highest growth potential, projected to reach USD 1,817.5 million by 2033, with a CAGR of 9.2%.
The analysts below cover Banking & Finance research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.
Enterprise zero-trust network rollouts are often slowed down by multi-cloud transit latency and proprietary hardware retirement schedules. This study provided realistic total cost of ownership models comparing cloud-delivered security edge solutions against traditional hardware refreshes. The analysis of contract renewal lengths and software maintenance fees gave us clear visibility into enterprise replacement cycles over the next three to five years.
Scaling antibody-drug conjugate manufacturing hinges on contract manufacturing availability for high-potency active ingredients. The MetaStat Insight analysis looked closely at global cleanroom slot constraints, bioconjugation batch failure rates, and supply chain redundancies between the US, Europe, and India. The supplier capability matrix proved genuinely useful for our team when mapping secondary source options across our clinical pipeline.
Floating offshore wind feasibility relies heavily on specialized installation vessel availability and port crane limits, which most broad renewable energy forecasts ignore. The report delivered a thorough analysis of dry dock capacity, mooring chain supply constraints, and raw material pricing trends for deepwater anchor installations. It served as a solid independent sanity check for our offshore project capital expenditure assumptions.
Explore related market intelligence reports worth reading alongside this one.