
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Europe Terminal Block Market Size, Share, By Connection Technology (Screw Clamp, Push-in Spring Clamp, Spring Clamp with Actuator, Bolt and Stud, Others), By Mounting Method (DIN-Rail Mounted, PCB-Mounted, Panel and Chassis Mounted), By End-Use Industry (Industrial Manufacturing and Process Industries, Power and Energy, Building and Construction, Transportation, Telecommunications and Data Infrastructure), By Region (Germany, France, UK, Italy, Spain, Russia, Rest of Europe), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-2590
Published
October, 2026
Pages
250 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
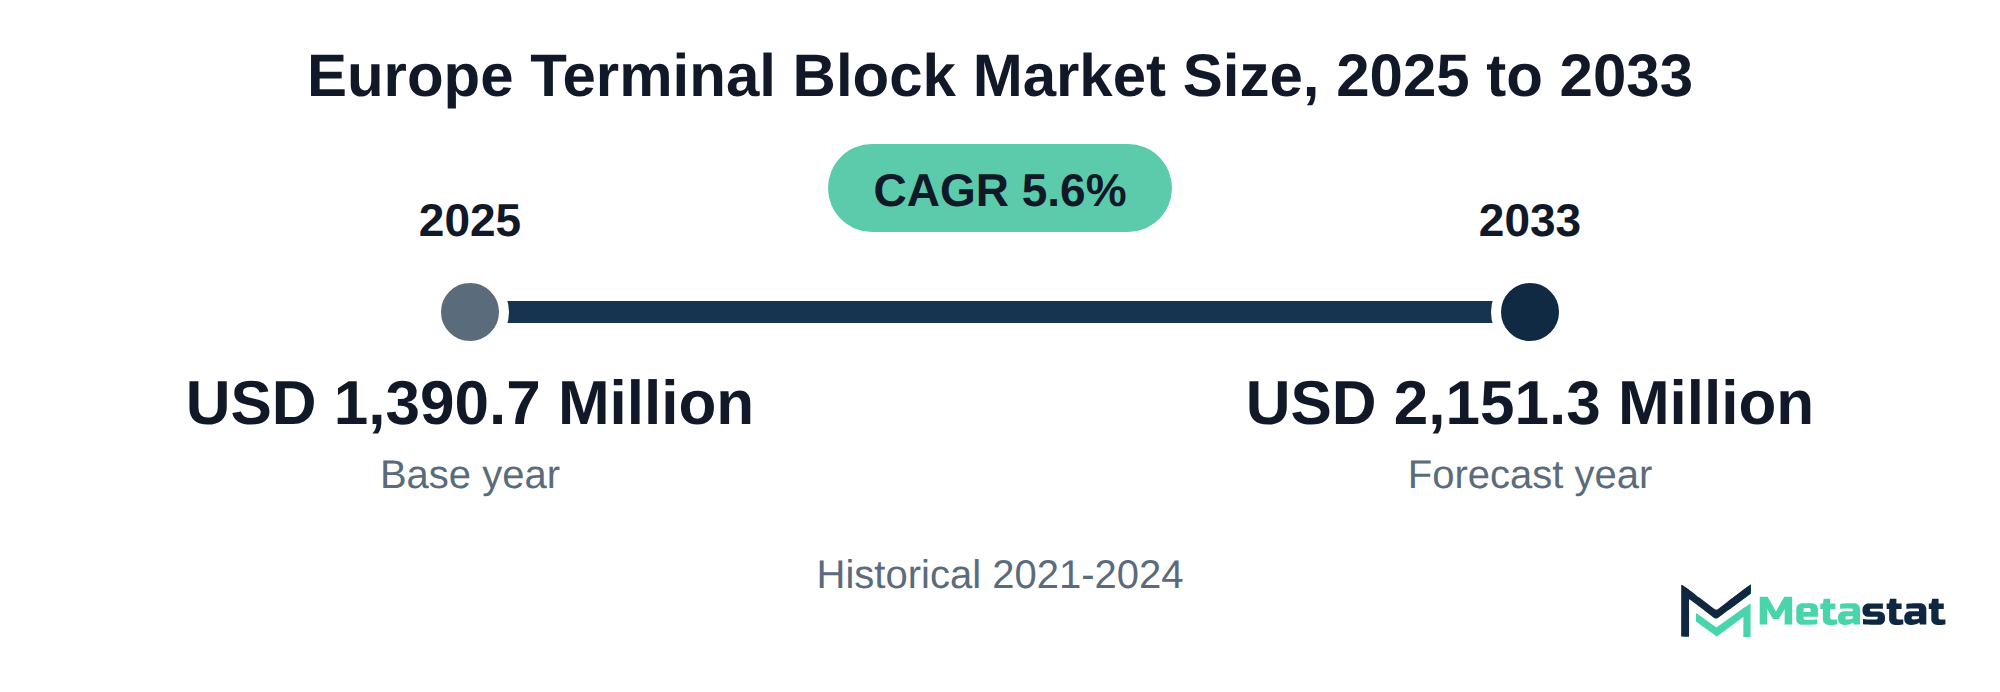
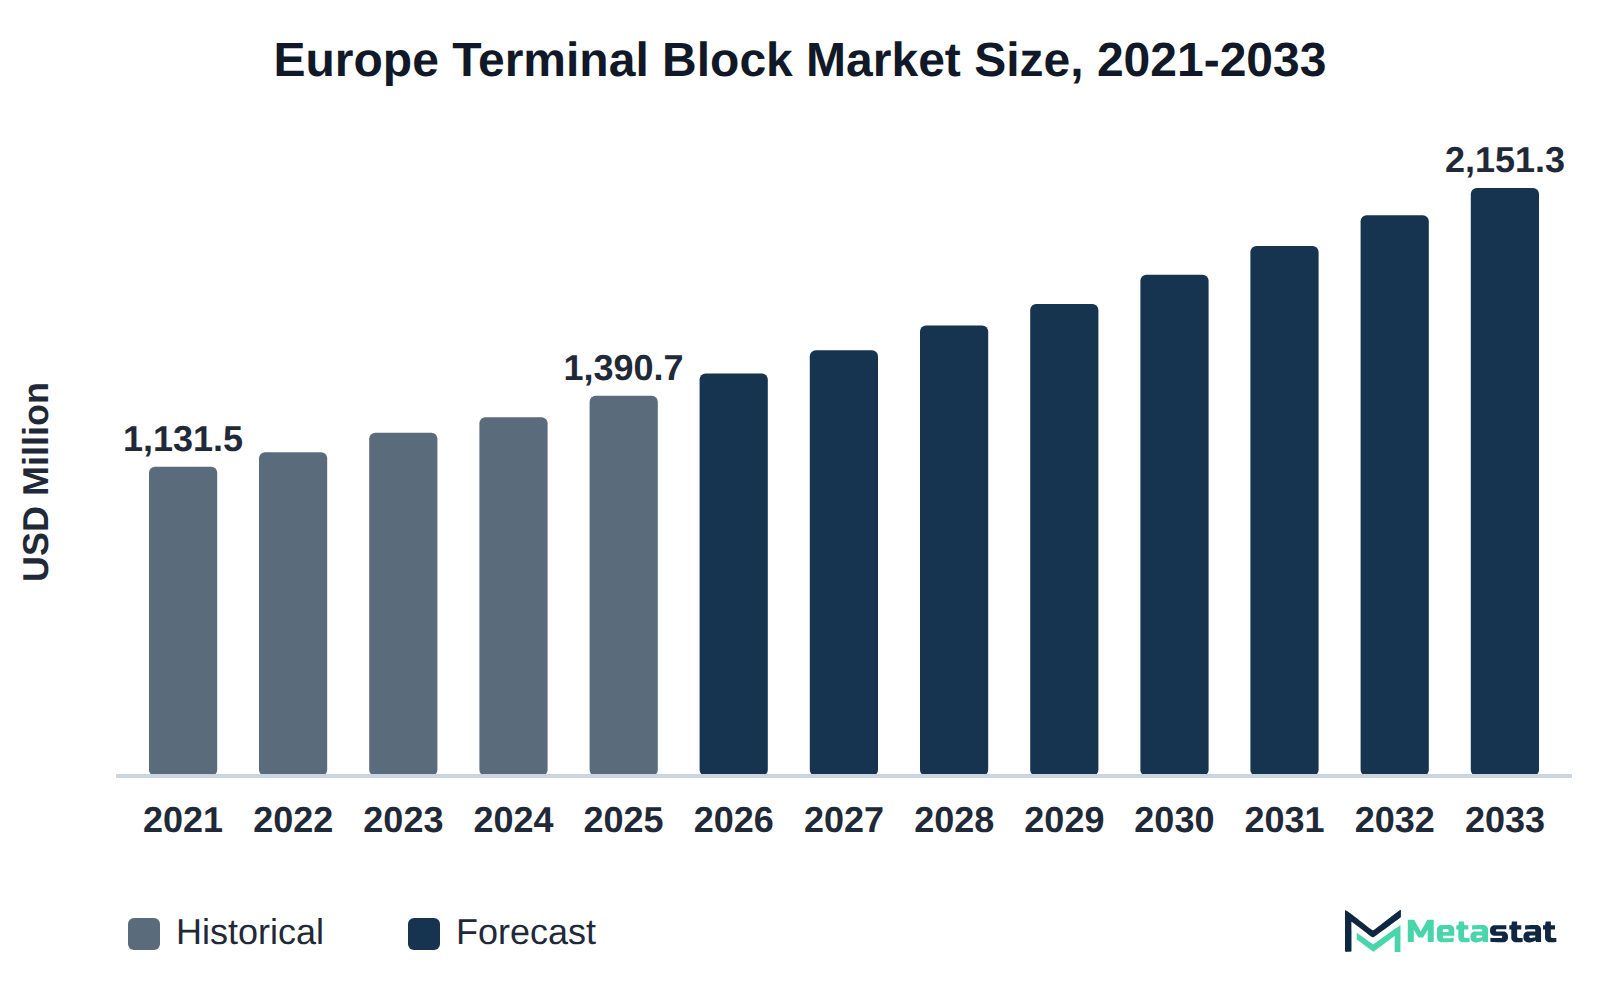
Market Valuation: Valued at $1,390.7 Million in 2025, projected to reach $2,151.3 Million by 2033 at a 5.6% CAGR.
Dominant Segment: The Push-in Spring Clamp segment leads the Europe Terminal Block market, driven by its efficiency and ease of installation, with projected revenues reaching USD 921.4 million by 2033.
Geographic Lead: Germany holds the largest market share, benefiting from a strong industrial base and significant investments in advanced electrical connectivity solutions.
What's Inside: The report provides comprehensive competitive coverage, detailed analyses of market dynamics, and forecasts extending to 2033, focusing on various connection technologies and end-use industries.
Growth Areas: Key growth areas include the Power and Energy segment, projected to grow at a CAGR of 6.6%, fueled by increasing investments in renewable energy infrastructure.
Market Dynamics: The report highlights challenges such as price sensitivity among buyers and rising input costs for suppliers, impacting adoption rates and market strategies.
Choose Your License
Europe Terminal Block Market
The Europe Terminal Block market was valued at USD 1,390.7 million in 2025 and is projected to reach USD 2,151.3 million by 2033, growing at a CAGR of 5.6% over the forecast period.
The Europe Terminal Block market encompasses various products designed for the secure connection of electrical circuits. Terminal blocks belong to the wider category of cables and connectors used to join electrical systems. Buyers invest in terminal blocks because they deliver reliable and efficient electrical connections across multiple applications. Industries including industrial manufacturing, power and energy, and building and construction drive demand significantly, using these components to improve operational efficiency and safety in their electrical systems.
Growth in the market is propelled by the increasing adoption of automation technologies and the expansion of renewable energy projects. Among the connection technology segments, the Push-in Spring Clamp segment stands out with the highest anticipated value. The German market leads in regional share, reflecting a robust industrial base and strong demand for advanced electrical connectivity solutions.
Investments in infrastructure and advancements in electrical standards further contribute to market expansion. The focus on energy efficiency and sustainability encourages buyers to seek innovative solutions, driving competition among suppliers. This competitive environment supports the development of new technologies and enhances product offerings, positioning the market for sustained growth.
Investment in the Europe Terminal Block market reflects the need for reliable connections in electrical systems across various industries. Buyers prioritize these products for their ability to enhance safety and efficiency in applications ranging from industrial manufacturing to energy management. Multiple connection technologies and mounting methods allow tailored solutions that meet specific operational requirements.
Growth in the market is driven primarily by increasing demand for automation and advanced technologies in industrial sectors. Among the various segments, the Push-in Spring Clamp technology stands out for its significant value, addressing the industry's need for quick and secure connections. Germany represents the largest share of the market, benefiting from a robust manufacturing base and an emphasis on innovation in electrical components.
Technological advancements continue to shape the Europe Terminal Block market. The expansion of smart infrastructure, coupled with a growing focus on energy efficiency, increases demand for advanced terminal block solutions. This trend creates opportunities for manufacturers to develop innovative products that cater to the evolving needs of various end-use industries.
Push-in terminal blocks represent a significant advancement in wiring technology, particularly for automated control cabinet wiring within the Europe Terminal Block market. This technology facilitates faster and more reliable connections, reducing the need for tools during installation. By 2033, revenue for push-in spring clamp terminal blocks is projected to reach USD 921.4 million, reflecting a strong compound annual growth rate of 8.9%. This growth reflects increasing demand for efficient, user-friendly solutions in electrical installations.
The simplicity of push-in terminal blocks, which employ spring mechanisms for wire retention, enhances overall operational efficiency, appealing to manufacturers focused on automation and streamlined processes. This technology aligns with the ongoing trend toward compact designs in control cabinets, enabling more flexible layouts and reducing the overall footprint of electrical systems. Cabinet layout planning also involves wire and cable management systems, which organize the conductors that connect to terminal blocks.
The expansion of push-in terminal blocks within the Europe Terminal Block market drives competitive advantages for manufacturers who adopt these solutions. Improved speed and reduced labor costs during installation translate into higher profitability and market share for companies embracing this innovation.
Pricing models in the Europe Terminal Block market are evolving to accommodate the increasing demand for high-current connections, driven by the renewable energy sector. A significant portion of these connections is used in solar power installations and energy storage systems, where reliability is critical. The market's projected value of USD 2,151.3 million by 2033 reflects this growing trend, with specific segments including Power and Energy set to achieve a compound annual growth rate of 6.6%.
Contract models for high-current connections often include long-term agreements, allowing buyers to secure stable pricing over extended periods. These contracts frequently incorporate performance guarantees, ensuring that suppliers meet specified electrical standards and safety regulations. Such arrangements help buyers manage procurement costs effectively, leading to improved project budgeting in the expanding renewable energy sector.
The strategic focus on high-current connections enhances operational efficiency and positions buyers favorably in a competitive landscape. Suppliers who align with the emerging needs of the renewable energy sector gain a significant advantage, building stronger partnerships and driving market growth. Continued investment in high-current connections is expected to serve as a critical factor in the overall expansion of the Europe Terminal Block market.
Compact PCB terminal blocks fulfill specific requirements for industrial device design, particularly in applications demanding space efficiency and reliability. These components enable manufacturers to optimize layout and reduce overall device dimensions while maintaining reliable electrical performance. The growing trend toward miniaturization in devices within the Europe Terminal Block market drives the need for these compact solutions, enhancing interconnectivity without compromising quality.
The forecast for PCB-mounted terminal blocks indicates a target value of USD 599.3 million by 2033, reflecting a compound annual growth rate of 6.5%. This growth arises from increasing demand in various sectors, including telecommunications and industrial manufacturing, where space constraints in equipment design necessitate high-density interconnect solutions. Buyers prioritize compactness and performance in terminal blocks, ensuring their devices meet industry standards while accommodating smaller form factors.
The emphasis on efficient and reliable PCB terminal blocks aligns with broader trends in automation and digitalization. Manufacturers focusing on compact designs find opportunities to enhance product appeal and performance, positioning themselves favorably within a competitive market. The demand for innovative solutions within the Europe Terminal Block market continues to rise, driven by the complexities of modern industrial design.
Panel builders in the Europe Terminal Block market increasingly favor push-in spring connections over traditional screw connections due to enhanced efficiency and ease of installation. This growth indicates a substantial shift in preference among builders, driven by the need for faster assembly times and reduced labor costs.
While screw clamp connections remain popular, their market value is expected to rise to USD 670.8 million during the same forecast period, representing a more conservative growth rate of 2.9%. Builders evaluating the choice between these two connection types weigh installation speed and reliability as critical factors. Push-in spring connections allow for quicker connections and disconnections, minimizing downtime during assembly.
The transition towards push-in spring clamps aligns with industry trends emphasizing productivity and efficiency. By adopting this technology, panel builders enhance operational efficiency, allowing them to respond more effectively to market demands. This shift signifies a strategic move towards innovation in the Europe Terminal Block market, impacting competitive positioning and overall growth within the sector.
Increased adoption of push-in spring clamps drives growth within the market. Buyers in sectors including industrial manufacturing and process industries favor this technology due to its efficiency and ease of use. The shift toward automation and the need for faster, more reliable connections contribute to increased volumes and a higher demand for these products. With a compound annual growth rate of 8.9% projected through 2033, push-in spring clamps significantly influence the overall growth of the Europe Terminal Block market. Enhanced installation speed and reduced labor costs attract customers to this connection technology.
The transition from traditional screw clamps to push-in spring clamps reflects broader trends in the industry, focusing on streamlined assembly processes. This transition generates opportunities for suppliers to expand their offerings and capture a larger share of the growing market. Buyers seek improved performance and reduced installation times, leading to the continued rise in acceptance of push-in spring clamps across various applications.
Innovations in push-in spring clamp technology significantly enhance connectivity solutions within the Europe Terminal Block market. These advancements improve the speed and efficiency of electrical connections, catering to the growing demand for streamlined assembly processes in various applications. The increasing complexity of electrical systems in industries including industrial manufacturing and power generation drives the need for reliable and quick installation methods, thereby boosting adoption rates among manufacturers.
Users across diverse sectors benefit from reduced labor costs and higher operational efficiency through the use of push-in spring clamps. This technology eliminates the need for tools during installation, allowing for quicker assembly times. Enhanced safety features, including better vibration resistance and secure connections, further contribute to the appeal of these products. With a projected compound annual growth rate of 8.9% for push-in spring clamp technology through 2033, the market is expected to expand strongly, reflecting a major shift in how electrical connections are approached.
Price sensitivity among buyers in the Europe Terminal Block market significantly limits adoption rates, particularly in the Industrial Manufacturing and Process Industries segment. High costs associated with terminal block products deter several firms from making larger purchases or transitioning to advanced technologies. This reluctance results in slower uptake of new solutions and delayed replacement cycles for existing systems. The challenge manifests particularly for manufacturers aiming to integrate newer technologies into their operations, driven by budget constraints that restrict their ability to invest in higher-quality components. Consequently, the competitive landscape becomes constrained, leading to missed opportunities for both suppliers and customers. Suppliers face pressure to offer competitive pricing structures, while customers struggle to balance cost and performance in their purchasing decisions.
Increased material costs present a significant challenge for suppliers in the Europe Terminal Block market. Suppliers face escalating prices for essential components, driven by fluctuations in raw material availability and geopolitical factors impacting production. These pressures affect profit margins and force suppliers to develop strategies to mitigate impacts on their operations. Many suppliers explore alternative sourcing options and negotiate long-term contracts to stabilize input costs. This dynamic influences pricing strategies, compelling suppliers to balance competitive pricing with maintaining profitability. Consequently, suppliers invest in technologies that enhance production efficiency, enabling them to withstand volatility in input costs while meeting the demands of diverse applications. The need for innovation in manufacturing processes remains a priority to sustain growth in the market.
The push-in spring clamp segment within the Europe Terminal Block market demonstrates significant growth potential, driven by rising demand for efficient and reliable electrical connections. This segment is projected to achieve a compound annual growth rate of 8.9% through 2033, reflecting growing interest in streamlined installation processes and reduced operational time. Several industries, particularly industrial manufacturing and process industries, favor push-in spring clamps due to their ease of use and enhanced mechanical stability.
Automated systems gain traction across various sectors, resulting in robust demand for push-in spring clamps. Manufacturers focusing on improving designs and functionalities of these components address the evolving needs of end-users, resulting in increased market penetration. The push-in spring clamp segment stands out due to its ability to reduce assembly time and enhance connection reliability, which translates directly into operational efficiency for manufacturers.
The Europe Terminal Block market is segmented based on Connection Technology, Mounting Method, End-Use Industry, and Region.
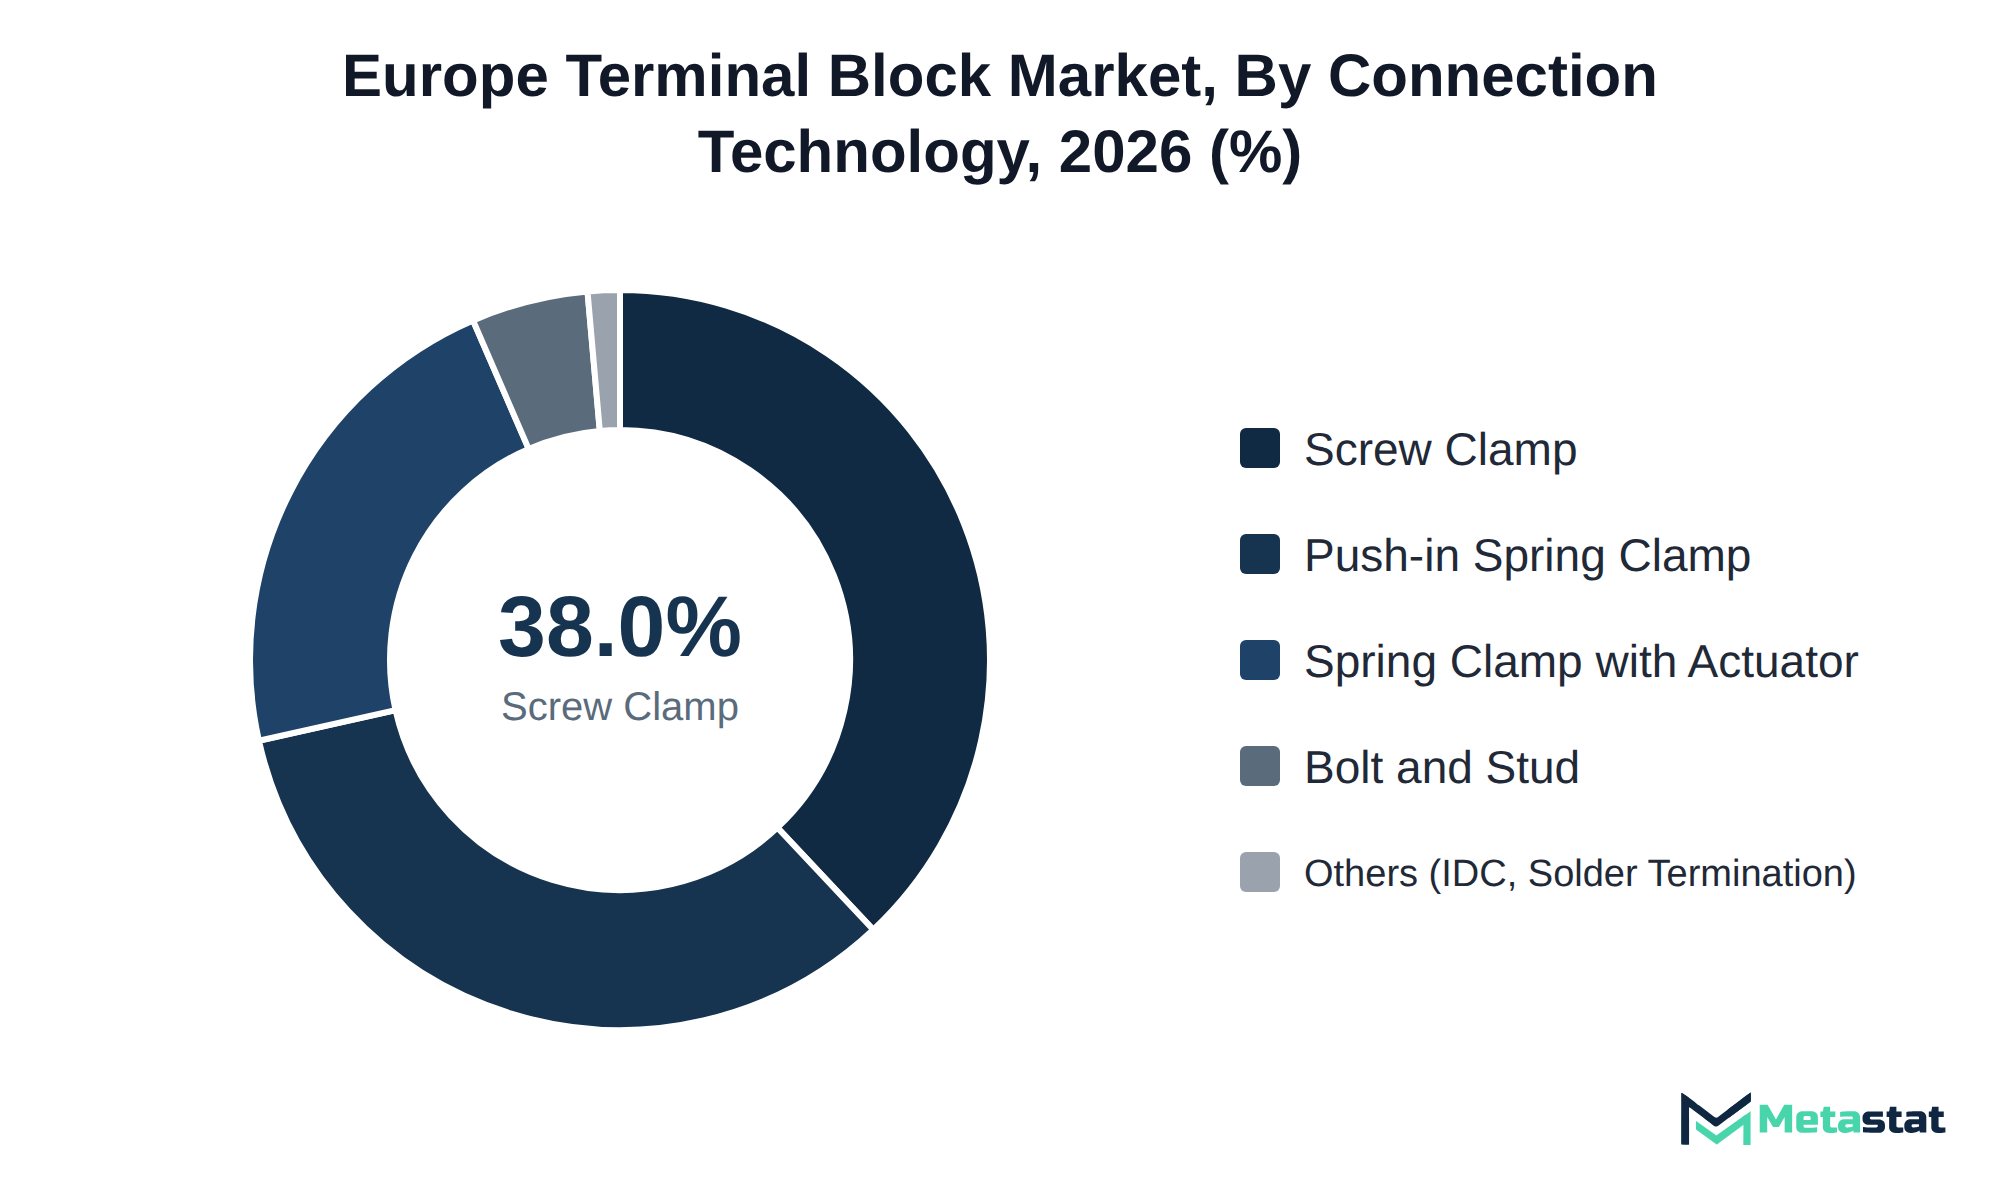
Screw Clamp segment is valued at USD 548.5 million in 2026 and is projected to reach USD 670.8 million by 2033, at a CAGR of 2.9% during the forecast period. These terminal blocks primarily serve industries requiring secure and reliable electrical connections, applied in various applications from industrial machinery to residential wiring. The growth of this segment is influenced by increasing demand for robust connection methods that ensure stability in electrical systems. Compared to other connection technologies, including Push-in Spring Clamp, which exhibits a higher growth rate due to its efficiency, the Screw Clamp segment experiences steadier growth. This reflects a preference among traditional sectors for proven technology, ensuring reliable performance while addressing specific connectivity needs. The focus on durability and ease of installation continues to drive interest in screw clamp solutions, keeping them relevant in the Europe Terminal Block market.
Push-in spring clamps excel in providing reliable electrical connections, particularly in applications requiring quick and efficient assembly. These components find extensive use in industries like industrial manufacturing and process industries, where efficiency and ease of installation are essential. Increased demand for automation and streamlined processes drives this segment, distinguishing it from others, including the Screw Clamp segment, which has a slower growth rate at a CAGR of 2.9%. The focus on minimizing assembly time and enhancing safety features in electrical systems supports the upward trajectory of push-in spring clamps, making them a preferred choice for manufacturers aiming to optimize production processes. The growing emphasis on cost-effective solutions in the Europe Terminal Block market contributes to the expansion of this segment.
Spring Clamp with Actuator segment is expected to reach USD 418.9 million by 2033. This technology finds extensive use in industrial applications where secure and efficient connections are critical. Industries including manufacturing and automation use this segment for its reliability and ease of installation. Growth in this segment is primarily driven by increasing demand for high-efficiency connections that reduce assembly time and overall operational costs, addressing the preferences of manufacturers focused on enhancing productivity. Compared to other connection technologies, Spring Clamp with Actuator features a higher growth rate, expected at a CAGR of 8.9%, making it a more attractive option for buyers seeking advanced connectivity solutions. This positioning within the Europe Terminal Block market reflects a trend toward automation and optimized wiring systems.
Bolt and Stud segment is projected to grow at a CAGR of 5.3% during the forecast period. This segment serves primarily in heavy-duty applications where reliable connections are essential, including industrial machinery, automotive, and construction equipment. Demand stems from the ongoing need for robust and durable connections in environments exposed to vibrations and mechanical stress. Compared to other connection technologies, this segment faces specific challenges related to installation complexity and cost. While the market experiences growth, factors including pricing pressures and technological advancements in alternative connection methods influence its trajectory. The overall performance of the Bolt and Stud segment highlights its significance within the Europe Terminal Block market, driven by industrial demand and the pursuit of reliable electrical connections.
Others (IDC, Solder Termination) involves alternative connection methods that cater to specific needs in electrical applications. These methods facilitate simplified wiring processes, appealing to manufacturers in sectors including telecommunications and data infrastructure. Growth in this sub-segment occurs due to advancements in technology that enhance the reliability and efficiency of connections. While other connection types focus on traditional methods, this sub-segment provides unique solutions that meet the demands of modern electronic designs. Demand for cost-effective and space-efficient connection options drives interest in these alternatives, differentiating it from connection technologies including screw or push-in spring clamps, which target broader applications. The Europe Terminal Block market continues to evolve, with these innovative approaches gaining traction among specialized buyers seeking tailored solutions.
DIN-Rail Mounted segment is valued at USD 920.3 million in 2026 and is projected to reach USD 1,320.2 million by 2033, at a CAGR of 5.3% during the forecast period. This segment finds extensive application in various industrial settings, particularly for housing terminal blocks in control cabinets and equipment. Manufacturers of industrial machinery and automation systems primarily adopt DIN-Rail Mounted terminal blocks for their ease of installation and space-saving design. Growing automation in several sectors influences the demand for this segment, while the ongoing transition toward more compact and efficient designs poses challenges for adaptation. Compared to other mounting methods, including PCB-Mounted, this segment experiences steady growth, fueled by its robust performance in high-volume applications. The market's evolution indicates a strong inclination toward enhanced functionality and flexibility, significant factors driving the value of DIN-Rail Mounted solutions.
This segment finds extensive application in electronic devices and systems, primarily used by manufacturers in telecommunications, consumer electronics, and industrial automation. Growth in this segment derives from advancements in technology that enhance connection reliability and reduce assembly time. Compared to other mounting methods, PCB-Mounted terminals offer a compact design, making them ideal for space-constrained applications. This segment exhibits a faster growth rate than several traditional methods, reflecting a shifting preference among buyers toward efficient, modern solutions. Increased demand for innovative electrical equipment drives manufacturers to adopt PCB-Mounted terminals, ensuring they remain competitive in the evolving landscape of the Europe Terminal Block market.
Panel and Chassis Mounted segment is expected to reach USD 196.2 million by 2033. This segment finds application in various equipment and devices requiring secure and robust mounting solutions, particularly in the building and construction sectors. Demand is driven by the increasing focus on compact and efficient designs, along with the growing trend toward modular systems in new constructions. Compared to other mounting methods, this segment demonstrates a slower growth rate, influenced by the broader adoption of DIN-Rail Mounted solutions, which show a higher projected value at USD 1,320.2 million by 2033. The technical requirements for panel and chassis mounted solutions present unique challenges, often involving higher installation complexity and costs relative to alternatives. This segment's specific applications cater to buyers focused on reliability and durability, positioning it distinctly within the Europe Terminal Block market.
Others (Free-Hanging, Busbar-Mounted) segment is projected to grow at a CAGR of 4.9% during the forecast period. This segment finds applications in various industrial settings, particularly for connecting busbars and free-hanging wires in electrical distribution systems. Demand from power generation and transmission companies drives growth, with the need for reliable and efficient connections in these sectors remaining critical. Compared to other mounting methods, this segment presents unique challenges due to installation requirements and space constraints, affecting its pricing dynamics. While segments like DIN-Rail Mounted offer more streamlined installation processes, Others (Free-Hanging, Busbar-Mounted) remains essential for applications requiring flexibility and adaptability in mounting solutions. Competition among suppliers focusing on customization and design innovation influences the segment's performance within the Europe Terminal Block market.
Industrial Manufacturing and Process Industries segment is valued at USD 577.8 million in 2026 and is projected to reach USD 800.5 million by 2033, at a CAGR of 4.8% during the forecast period. This segment encompasses the production and processing of goods, involving various applications in sectors including automotive, aerospace, and machinery manufacturing. Demand stems from the push for automation and efficiency improvements across these industries, with manufacturers seeking reliable connectivity solutions to enhance operational performance. This area experiences a stable growth trajectory due to consistent investment in industrial technology and infrastructure, reflected in its projected CAGR of 4.8%. Innovations in automation technologies continue to unfold, leading manufacturers to increasingly rely on advanced terminal blocks to streamline operations. The ongoing need for robust electrical connectivity solutions supports the segment’s expansion, distinguishing it from others in the market.
Power and Energy segment is estimated to reach USD 594.4 million by 2033, at a CAGR of 6.6% during the forecast period. This segment serves critical applications in electrical infrastructure and energy management, catering primarily to utility companies and industrial plants. Power cable terminations and joints are a related category of electrical connection hardware used in these networks. Rapidly growing demand for renewable energy sources supports this segment, with increasing investments in solar and wind energy infrastructure. The segment differs from others due to its higher growth potential, reflecting the ongoing transition towards sustainable energy solutions. In comparison, Industrial Manufacturing and Process Industries exhibit a lower CAGR of 4.8%, highlighting the faster pace of adoption in the Power and Energy sector. Technological advancements in energy efficiency and regulatory support for greener practices further enhance market opportunities, positioning the Power and Energy segment as a key driver of the overall market expansion.
The Building and Construction segment is expected to reach USD 368.7 million by 2033. This segment serves essential roles in various construction projects, including residential, commercial, and industrial buildings. Demand for terminal blocks arises from contractors and electrical engineers who require reliable connectivity solutions. Growth in construction activities across Europe increases demand within this segment. The segment benefits from increasing investments in infrastructure and urban development projects, which support its expansion. Comparatively, the Building and Construction segment experiences a lower growth rate than the Power and Energy segment, projected to grow at a CAGR of 6.6%. This distinction highlights varying dynamics in buyer needs and project timelines, directly impacting demand patterns in the market.
Transportation segment is projected to grow at a CAGR of 7.2% during the forecast period. This segment provides electrical connectivity for vehicles, public transport systems, and logistics operations. Key players in this segment include automotive manufacturers and transportation infrastructure providers, which require reliable and efficient solutions for electrical systems. Increasing investments in electric vehicles and advancements in transportation technology drive demand for more sophisticated terminal block solutions. Electric vehicle high voltage wire harness systems are one example of the electrical connectivity these vehicles require. Compared to other segments, the transportation segment shows faster growth due to rising environmental regulations and the shift toward sustainable transportation solutions. The market faces unique challenges, including compliance with stringent industry standards, influencing product development and pricing strategies.
Telecommunications and Data Infrastructure involves the systems and networks that facilitate communication and data transfer across various platforms. This segment targets industries including telecommunications providers, data centers, and IT infrastructure, where reliable and efficient connections are essential. The growth of the digital economy acts as a significant driver, with increasing demand for robust connectivity solutions. This segment experiences faster growth than others in the market, fueled by the expansion of mobile networks and cloud computing services. The ongoing digital transformation across sectors further increases the necessity for advanced connectivity solutions, differentiating it from more traditional end-use industries. Evolving technology and regulatory requirements shape this segment's trajectory, setting it apart from segments with slower growth patterns.
Medical equipment and laboratory equipment rely on specialized terminal blocks for various applications, including circuit connections and signal transmission. This segment caters to healthcare facilities, research laboratories, and medical device manufacturers, ensuring reliable and safe connections in critical environments. Demand for advanced technology in medical devices drives growth, alongside regulatory requirements for safety and reliability. Differentiating this segment from others, it encounters unique challenges related to stringent regulations and the need for high-quality materials, influencing pricing and product specifications. While other segments experience rapid growth, this segment's trajectory reflects stable demand, closely tied to advancements in healthcare technology, shaping its development within the Europe Terminal Block market.
Germany segment is valued at USD 399.5 million in 2026 and is projected to reach USD 563.2 million by 2033, at a CAGR of 5% during the forecast period. This segment primarily serves the industrial manufacturing and process industries, where reliable electrical connections are essential for operational efficiency. Increasing automation and the emphasis on energy-efficient systems drive demand in this region. Compared to other segments, Germany's growth aligns with a solid industrial base and a focus on technological advancements. The segment's growth rate remains moderate relative to the more rapidly growing Push-in Spring Clamp segment, which is projected to achieve a CAGR of 8.9%. Factors influencing demand include a strong manufacturing sector and ongoing investments in infrastructure that prioritize safety and reliability in electrical connectivity. Growth in the German segment reflects the rising complexity and requirements of modern electrical systems.
France segment is estimated to reach USD 288.7 million by 2033, at a CAGR of 5.3% during the forecast period. This segment serves various applications in industrial settings, offering reliability and efficiency in electrical connections. Demand is driven by the growth of sectors including industrial manufacturing and energy, which require robust connection solutions. Compared to other segments, the France segment experiences moderate growth, influenced by local market dynamics and industry standards. The steady expansion of the manufacturing sector in France, alongside rising energy demands, creates a favorable environment for terminal blocks. Investment in infrastructure and energy efficiency initiatives further supports development, enhancing the attractiveness of the market.
UK segment is expected to reach USD 264 million by 2033. This segment serves various industries, including industrial manufacturing and construction, which rely on terminal blocks for efficient electrical connections. Demand for terminal blocks is driven by ongoing advancements in automation and increasing safety standards in electrical installations. The UK segment exhibits a moderate growth trajectory compared to others, maintaining a stable market position supported by robust manufacturing activities. Higher investments in infrastructure projects and energy sectors contribute to this growth. In contrast to faster-growing segments like Push-in Spring Clamp, the UK segment's growth rate reflects established demand patterns rather than rapid technological shifts, positioning it as a stable yet essential component of the Europe Terminal Block market.
Italy is projected to grow at a CAGR of 5.3% during the forecast period. This segment serves various industries, including industrial manufacturing and process industries, which rely on terminal blocks for reliable electrical connections in their operations. Demand is driven by the increasing need for automation and efficiency within these sectors, resulting in heightened investment in electrical infrastructure. Italian electrical distribution is a closely related area, since terminal blocks are used within distribution equipment. With a growing focus on sustainable manufacturing practices, the transition to more efficient technologies further boosts this segment. Compared to other regions, Italy's specific regulatory environment and industrial focus differentiate its growth trajectory, presenting unique challenges and opportunities for companies operating in the market.
Spain's segment focuses on terminal blocks used in various electrical and electronic applications, catering to the needs of multiple industries including manufacturing, energy, and construction. This region sees demand driven by increasing investment in infrastructure and industrial projects, thereby enhancing the overall functionality and reliability of electrical connections. The distinct growth trajectory of this segment stems from specific adoption in sectors that prioritize energy efficiency and safety standards. Compared to other regions, Spain's market experiences moderate growth, reflecting regional economic conditions and competitive pricing strategies. Enhanced regulatory measures aimed at safety and efficiency further support the segment's development, positioning Spain as a notable player in the Europe Terminal Block market.
Russia's terminal block segment is significant in various industrial applications, particularly in manufacturing and energy sectors. The region's adoption of terminal blocks is primarily driven by increasing investments in infrastructure and industrialization projects. Industries including power generation and manufacturing heavily rely on reliable electrical connections for operational efficiency and safety. The segments in Russia experience slower growth compared to other regions due to economic fluctuations and regulatory challenges. However, the shift towards modernization and automation in manufacturing processes could provide growth opportunities. Unlike the faster-growing segments, the dynamics in Russia reflect unique local demands and regulatory frameworks that influence purchasing decisions and product preferences. The Europe Terminal Block market benefits from these regional nuances, shaping the strategies of suppliers and stakeholders involved.
This segment includes various countries across Europe that do not fall under the specific classifications of Germany, France, the UK, and Italy. Terminal blocks in this region find usage in diverse applications, supporting industries including manufacturing, energy, and building construction. The push for modernization in electrical infrastructure drives investment in terminal blocks, with increased adoption among manufacturers seeking reliable and efficient connection solutions. Compared to established countries, this segment experiences slower growth due to differing regulatory frameworks and market maturity. Demand remains consistent, driven by ongoing infrastructure projects and the introduction of advanced technologies. The market benefits from the increasing need for safety and efficiency in electrical systems, aligning with broader trends in energy management and automation.
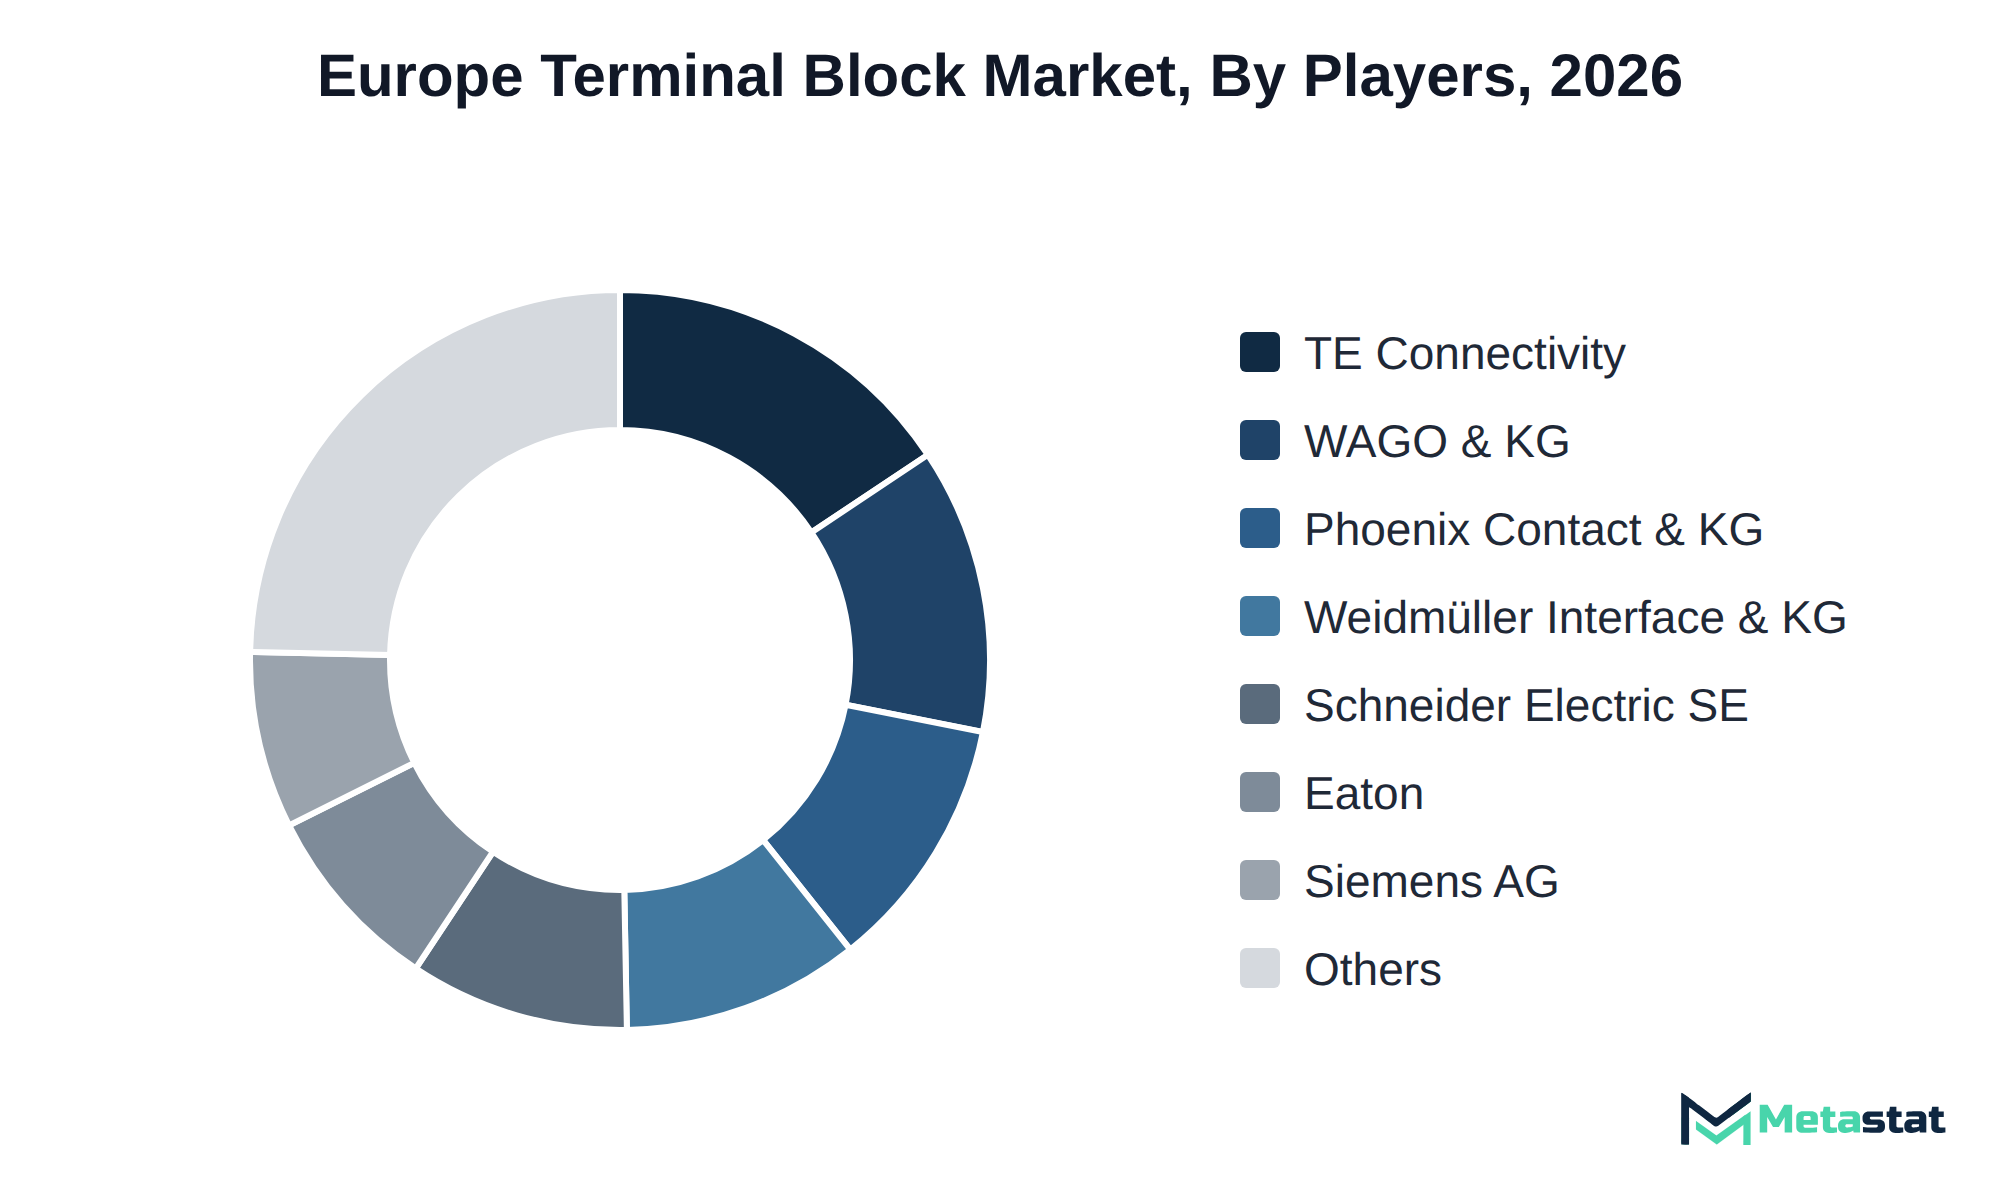
In the Europe Terminal Block market, companies compete based on various factors including pricing, product certification, customization options, and service quality. Pricing strategies significantly influence buyer decisions, with several customers seeking cost-effective solutions that do not compromise on quality or regulatory compliance. The emphasis on certification ensures that products meet specific industry standards, which is crucial for industries like power and energy.
Several companies emphasize innovative connection technologies. For instance, Phoenix Contact GmbH & Co. KG is recognized for its advanced push-in spring clamp technology, which enhances efficiency in terminal block applications. TE Connectivity plc focuses on a broad range of connectivity solutions, catering to diverse industrial needs. WAGO GmbH & Co. KG is known for its DIN-rail mounted terminal blocks, which offer reliable performance in industrial automation.
Growth in the Europe Terminal Block market hinges on several developments. First, robust demand for Push-in Spring Clamp technology is anticipated, driven by increasing adoption in industrial applications. This segment is projected to experience significant growth, contributing to overall revenue expansion. Second, the mounting method of DIN-Rail Mounted terminal blocks is expected to see heightened utilization in various sectors, particularly in industrial manufacturing and process industries, which highlights the need for reliable and efficient connections. Potential risks exist that hinder market progress. Economic fluctuations or regulatory changes in key regions, including Germany and France, could restrict investment in infrastructure upgrades or automation, negatively impacting demand across the board. Maintaining focus on technological advancements and adhering to industry standards will be essential to the market's ability to meet its projected growth. Together, these factors will determine whether the market reaches its forecast.
By Connection Technology: Screw Clamp, Push-in Spring Clamp, Spring Clamp with Actuator, Bolt and Stud, Others (IDC, Solder Termination)
By Mounting Method: DIN-Rail Mounted, PCB-Mounted, Panel and Chassis Mounted, Others (Free-Hanging, Busbar-Mounted)
By End-Use Industry: Industrial Manufacturing and Process Industries, Power and Energy, Building and Construction, Transportation, Telecommunications and Data Infrastructure, Others (Medical Equipment, Laboratory Equipment)
By Region: Germany, France, UK, Italy, Spain, Russia, Rest of the Europe
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Terminal Block market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 5.6% from 2026 to 2033 |
|
Revenue Unit |
USD million |
|
Segmentation |
By Connection Technology, Mounting Method, End-Use Industry, Region, and Region |
Find answers to common questions about this report
The Terminal Block market size was valued at USD 1,390.7 million in 2025.
The market is projected to grow at a CAGR of 5.6% during the forecast period from 2026 to 2033.
The Push-in Spring Clamp segment leads the Terminal Block market with a projected value of USD 921.4 million by 2033. This segment demonstrates the highest growth potential compared to others in the Connection Technology category.
Key drivers for the Europe Terminal Block market include increased adoption of push-in spring clamps, which support efficient and reliable electrical connections. The demand for streamlined installation processes and reduced operational time in sectors including industrial manufacturing and process industries significantly influences market growth.
Price sensitivity among buyers limits adoption rates in the Terminal Block market, particularly within the Industrial Manufacturing and Process Industries segment. Increased material costs challenge suppliers, affecting profit margins and compelling them to develop strategies to manage operational impacts.
The transition from traditional screw clamps to push-in spring clamps reflects a trend toward streamlined assembly processes, generating opportunities for suppliers to expand their offerings. Enhanced installation speed and reduced labor costs further attract customers, driving increased adoption across various applications.
The Terminal Block market is estimated to reach a valuation of USD 2,151.3 million by 2033.
Key players operating in the Terminal Block market include Phoenix Contact GmbH & Co. KG, WAGO GmbH & Co. KG, Weidmüller Interface GmbH & Co. KG, TE Connectivity plc, Schneider Electric SE, Siemens AG, Eaton Corporation plc, and Rockwell Automation, Inc.
The DIN-Rail Mounted segment is expected to grow from USD 920.3 million in 2026 to USD 1,320.2 million by 2033, reflecting a compound annual growth rate of 5.3%.
The Push-in Spring Clamp segment is projected to reach USD 921.4 million by 2033, with a compound annual growth rate of 8.9%, driven by increasing demand for efficient electrical connections.
The analysts below cover Electronics and Semiconductor research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.
PRINCIPAL CONSULTANT - QUALITY SYSTEMS & COMPLIANCE
Electronics and Semiconductor · Machinery & Equipment · Professional Services
Omkar Phadtare is an Industry Consultant at MetaStat Insight, specializing in quality systems, regulatory compliance, and standards benchmarking to drive data-driven market intelligence and strategic industry research.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Analyzing the transition from natural gas to green hydrogen in iron ore reduction requires realistic infrastructure timelines. Meta stat insight supplied a detailed regional assessment of DRI plant conversion costs and scrap metal availability in North America and Western Europe. Their report carefully examined pellet quality specs and electrical grid access constraints without making oversimplified market assumptions. The research material served as a practical reference during internal technology roadmap discussions.
Integrating zero-trust access controls across legacy electronic health record systems involves complex compliance overhead. Team produced an analysis that clearly separated identity governance and administration tools from privileged access management platforms. Their evaluation of HIPAA and GDPR compliance features across cloud native solutions gave our architecture group clear baseline criteria. The custom data request regarding biometric authentication adoption in hospital networks was returned promptly with clear documentation.
Evaluating calorific value requirements and air permit compliance across municipal waste facilities requires localized data. Metastat Insight structured their analysis around operational throughput capacity and feedstock composition variations in Latin America and Eastern Europe. Their competitive mapping of sorting equipment vendors helped clarify technology differences between optical separators and heavy media systems. The study provided an objective baseline during our capital expenditure reviews.
Explore related market intelligence reports worth reading alongside this one.