
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Telecom MLCC Market Size, Share, By Dielectric Type (Class 1 Ceramic (C0G / NP0) and Class 2 Ceramic (X5R / X7R)), By Rated Voltage (Low Voltage (≤100 V), Mid Voltage (>100-500 V), and High Voltage (>500 V)), By Case Size (1005, 201, 402, 603, 805, 1206, 1210, 1808 and 1812, 2220/2225 and Above), By Telecom Equipment Application (Radio Access Network Equipment, Core Network Servers and Gateways, Routers and Ethernet Switches, Optical Transport and Access Systems, Microwave and Millimeter-Wave Backhaul Equipment, Broadband CPE and Fixed Wireless Access Equipment, Satellite Communication Ground Equipment, and Telecom Power and Rectifier Systems), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
MSI-5354
September, 2026
310 Pages
Historical
Base year
Forecast
Forecast period
Report Details
Comprehensive Market Analysis And Insights
Market Valuation: Valued at $1,579.2 Million in 2025, projected to reach $4,634.3 Million by 2033 at a 14.4% CAGR.
Dominant Segment: The Class 2 Ceramic (X5R / X7R) segment leads the market, driven by the increasing demand for high-capacitance components in advanced telecom applications.
Geographic Lead: The Asia-Pacific region is expected to experience the fastest growth, fueled by significant investments in 5G infrastructure and telecommunications modernization.
What's Inside: This report provides a comprehensive analysis of market dynamics, competitive landscape, and detailed forecasts through 2033, covering various segments and applications.
Emerging Technologies: Technological advancements in 5G, IoT, and smart devices are key growth drivers, enhancing the demand for high-performance MLCCs across multiple sectors.
The global Telecom MLCC market was valued at USD 1,579.2 million in 2025 and is projected to reach USD 4,634.3 million by 2033, growing at a CAGR of 14.4% over the forecast period.
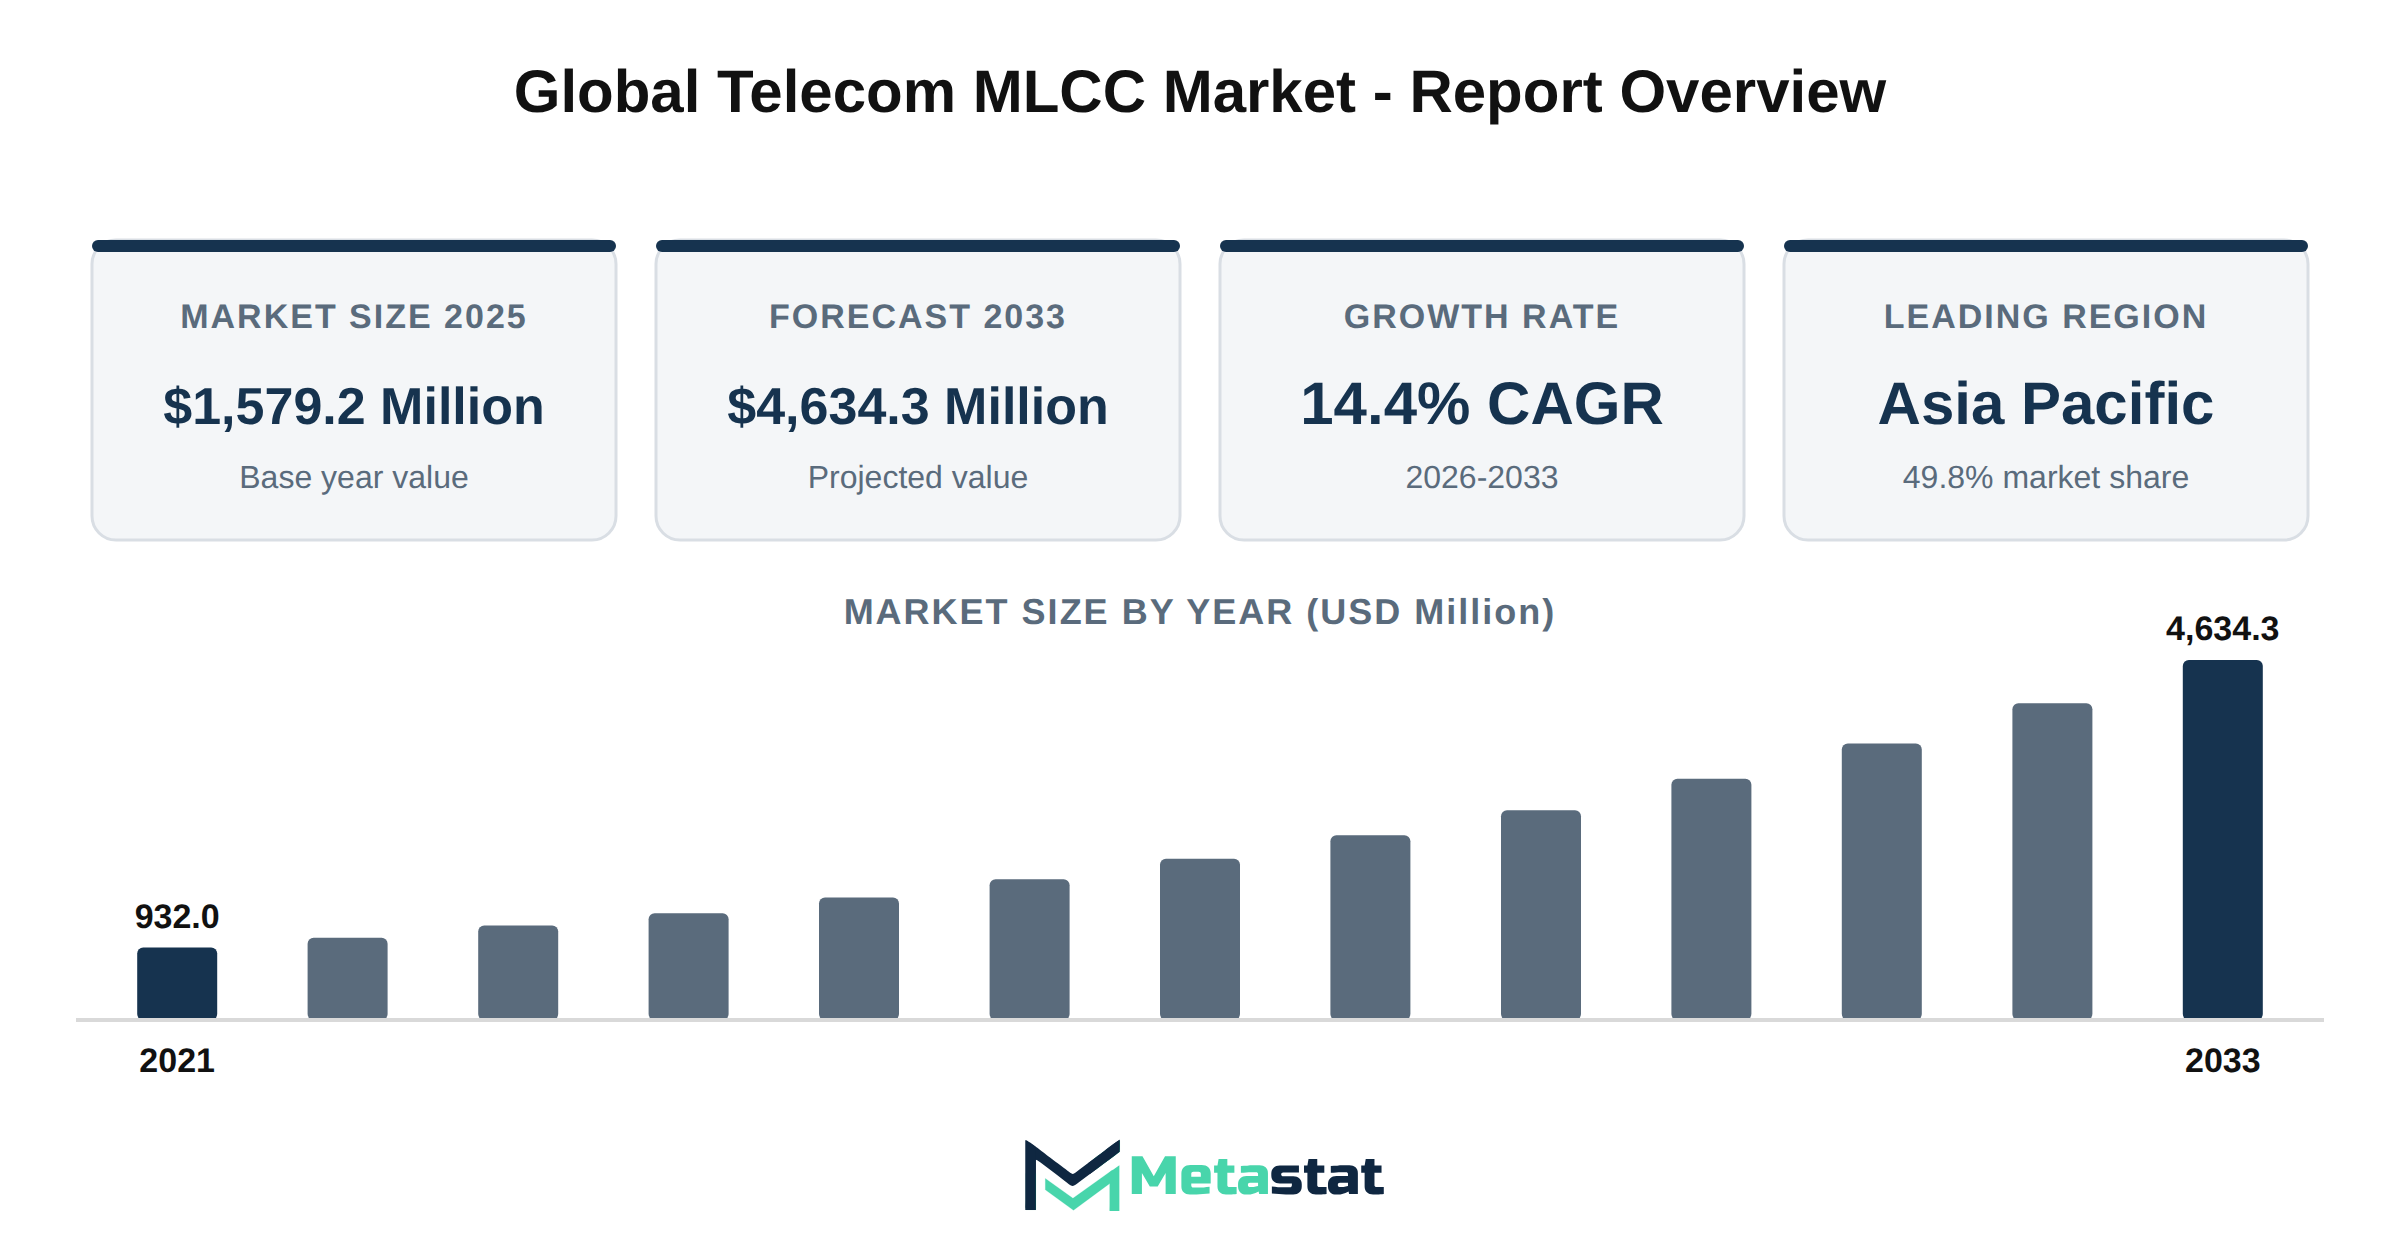
The global Telecom MLCC market is projected to grow from USD 1,579.2 million in 2025 to USD 4,634.3 million by 2033, representing a compound annual growth rate (CAGR) of 14.4%. This growth is driven by various factors, including the expansion of 5G networks, which increases the demand for multilayer ceramic capacitors (MLCCs) in telecommunications infrastructure. The shift towards high-capacitance MLCCs supports the requirements of advanced telecom systems, enhancing overall performance and reliability.
Miniaturization trends in telecom-grade MLCCs influence product design, allowing for more compact and efficient devices. High-frequency MLCC demand from RF and microwave systems continues to rise, with increased usage in applications including satellite communication and optical transport networks. The expansion of these networks necessitates a higher consumption of MLCCs, contributing to overall market growth.
Telecom MLCC demand is strong in radio access network equipment, with projected values reaching USD 1,289.3 million by 2033. Routers and Ethernet switches represent a significant segment, with ongoing advancements in technology driving the need for more efficient passive components. Fixed wireless access technology further supports growth, enhancing connectivity and network reliability.
The growth of millimeter-wave backhaul systems creates opportunities for high-quality MLCCs, which are essential for maintaining signal integrity at higher frequencies. The expansion of satellite communication infrastructure increases the range of applications for MLCCs, further diversifying market demand. High-voltage MLCCs find crucial applications in telecom power systems, ensuring efficient operation and stability across networks.
In terms of dielectric types, C0G and NP0 MLCC adoption is prevalent in RF signal circuits, while X5R and X7R MLCCs cater to the growing demands of telecom electronics. Smaller case sizes reshape telecom MLCC design, allowing manufacturers to meet the evolving requirements of compact electronic devices. The electrification of telecom equipment increases the density of passive components, necessitating innovative approaches to MLCC design and manufacturing.
AI-driven data traffic growth supports the demand for robust network hardware, creating a significant market opportunity for Telecom MLCCs. The deployment of Open RAN technology influences component requirements, driven by operators seeking flexible and efficient solutions. Edge computing infrastructure adds further demand for specialized MLCCs, reflecting the shift towards localized processing and connectivity.
5G network expansion drives significant demand in the Telecom MLCC market. Increased deployment of 5G infrastructure necessitates high-performance components, with telecom operators seeking reliable and efficient passive devices to support advanced capabilities. This trend supports a robust market environment, driven by surging demand for multilayer ceramic capacitors across various applications.
High-capacitance MLCCs gain traction within telecom infrastructure, enabling enhanced performance in devices including base stations and signal processing units. These components contribute to improved power management and signal integrity, essential for meeting the evolving requirements of modern telecommunications.
Miniaturization trends in telecom-grade MLCCs reflect the industry's focus on compact and efficient designs. Smaller components facilitate the development of space-constrained devices while maintaining performance levels, driving adoption across multiple sectors within the market.
The demand for high-frequency MLCCs in RF and microwave systems intensifies, fueled by advancements in communication technologies. These components play a critical role in ensuring stable signal transmission and reception, essential for the effective functioning of modern communication systems.
MLCC requirements in radio access network equipment reflect the growing complexity and performance expectations of telecom networks. Enhanced functionalities in these systems necessitate high-quality capacitors capable of supporting demanding operational conditions.
Telecom MLCC demand from routers and Ethernet switches continues to rise, driven by the increasing need for robust data handling capabilities. The integration of advanced features in networking equipment creates opportunities for manufacturers to supply high-performance capacitors tailored to specific applications.
Optical transport networks see increased MLCC consumption driven by the need for high-speed data transmission. The critical role of reliable capacitors in these systems supports the overall efficiency and performance of optical networks, contributing to the market's growth.
Fixed wireless access technologies support telecom MLCC growth by enabling high-speed internet access in underserved areas. This expansion promotes the adoption of advanced telecom equipment requiring robust passive components, further stimulating market demand.
Millimeter-wave backhaul creates high-Q MLCC opportunities because the demand for high-frequency transmission solutions escalates. These components are essential for ensuring effective signal integrity and performance in next-generation wireless communication systems.
Satellite communication infrastructure expands MLCC applications through the deployment of advanced technologies requiring reliable and efficient components. The rising need for satellite-based services drives demand for specialized capacitors designed to meet stringent performance standards.
High-voltage MLCC demand in telecom power systems reflects the industry's focus on enhancing energy efficiency and reliability. Capacitors designed for high-voltage applications support the stability and performance of essential telecom infrastructure.
C0G and NP0 MLCC adoption in RF signal circuits enhances signal stability and precision, aligning with the increasing requirements for high-performance communication systems. These dielectric types offer unique characteristics that contribute to optimal circuit performance.
X5R and X7R MLCC demand in telecom electronics supports the production of compact and efficient devices. These capacitors provide the necessary capacitance and voltage ratings while maintaining performance across various temperature ranges.
Smaller case sizes reshape telecom MLCC design, allowing manufacturers to create more compact and efficient components. This trend aligns with the industry's emphasis on miniaturization, driving innovation in capacitor design and manufacturing processes.
Telecom equipment electrification increases passive component density, placing greater emphasis on the performance and reliability of MLCCs. This shift supports the market's growth because manufacturers seek to optimize their product offerings to meet evolving technological demands.
AI data traffic growth supports network hardware MLCC demand, driven by increased data processing requirements that necessitate high-performance components. The expansion of AI-driven applications propels the need for advanced telecom infrastructure, creating market opportunities.
Open RAN deployment influences telecom component requirements by promoting interoperability and flexibility in network architectures. This trend encourages the adoption of advanced passive components, including specialized MLCCs designed for diverse applications.
Edge computing infrastructure creates new MLCC demand because the industry shifts towards decentralized data processing. This transformation drives the need for reliable and high-performance components capable of supporting innovative technology solutions.
The telecom MLCC supply chain experiences shifts in ceramic material availability, impacting production capabilities and pricing dynamics. Manufacturers navigate these changes to ensure a steady supply of high-quality components to meet market demands.
MLCC capacity expansion among Asian manufacturers supports growing demand in the telecom sector. Increased production capabilities enable suppliers to address the rising need for high-performance components across various applications.
Pricing dynamics for telecom-grade multilayer ceramic capacitors reflect market trends and competition among suppliers. Manufacturers balance cost considerations with the goal to provide high-quality products that meet stringent performance criteria.
Reliability requirements for telecom infrastructure MLCCs are critical, because components withstand demanding operational conditions. This focus on reliability influences product design and manufacturing processes, ensuring components meet industry standards.
Competitive innovation in high-Q and low-ESR MLCCs shapes the market, because manufacturers strive to develop advanced solutions catering to the evolving needs of telecom applications. This innovation drives growth and enhances market competitiveness.
Asia Pacific telecom infrastructure drives MLCC consumption, reflecting the region's significant investments in network expansion and modernization. This trend positions Asia Pacific because a critical market for passive components, fostering continued growth opportunities.
North American 5G and broadband investment supports MLCC demand, because telecom operators seek reliable components to enhance service delivery. This investment enhances the overall market environment and encourages innovation among suppliers.
European fiber and mobile network upgrades expand MLCC opportunities, because enhanced communication capabilities require high-performance components. This focus on network modernization positions the market for sustained growth in the coming years.
Emerging markets accelerate telecom infrastructure MLCC adoption, because increased connectivity drives demand for advanced communication technologies. This trend creates growth opportunities for manufacturers targeting these developing regions.
Future growth opportunities in 6G-ready telecom MLCCs reflect the industry's forward-looking approach to technology advancement. Manufacturers remain agile in adapting to emerging trends and requirements, positioning themselves for success in the evolving market.
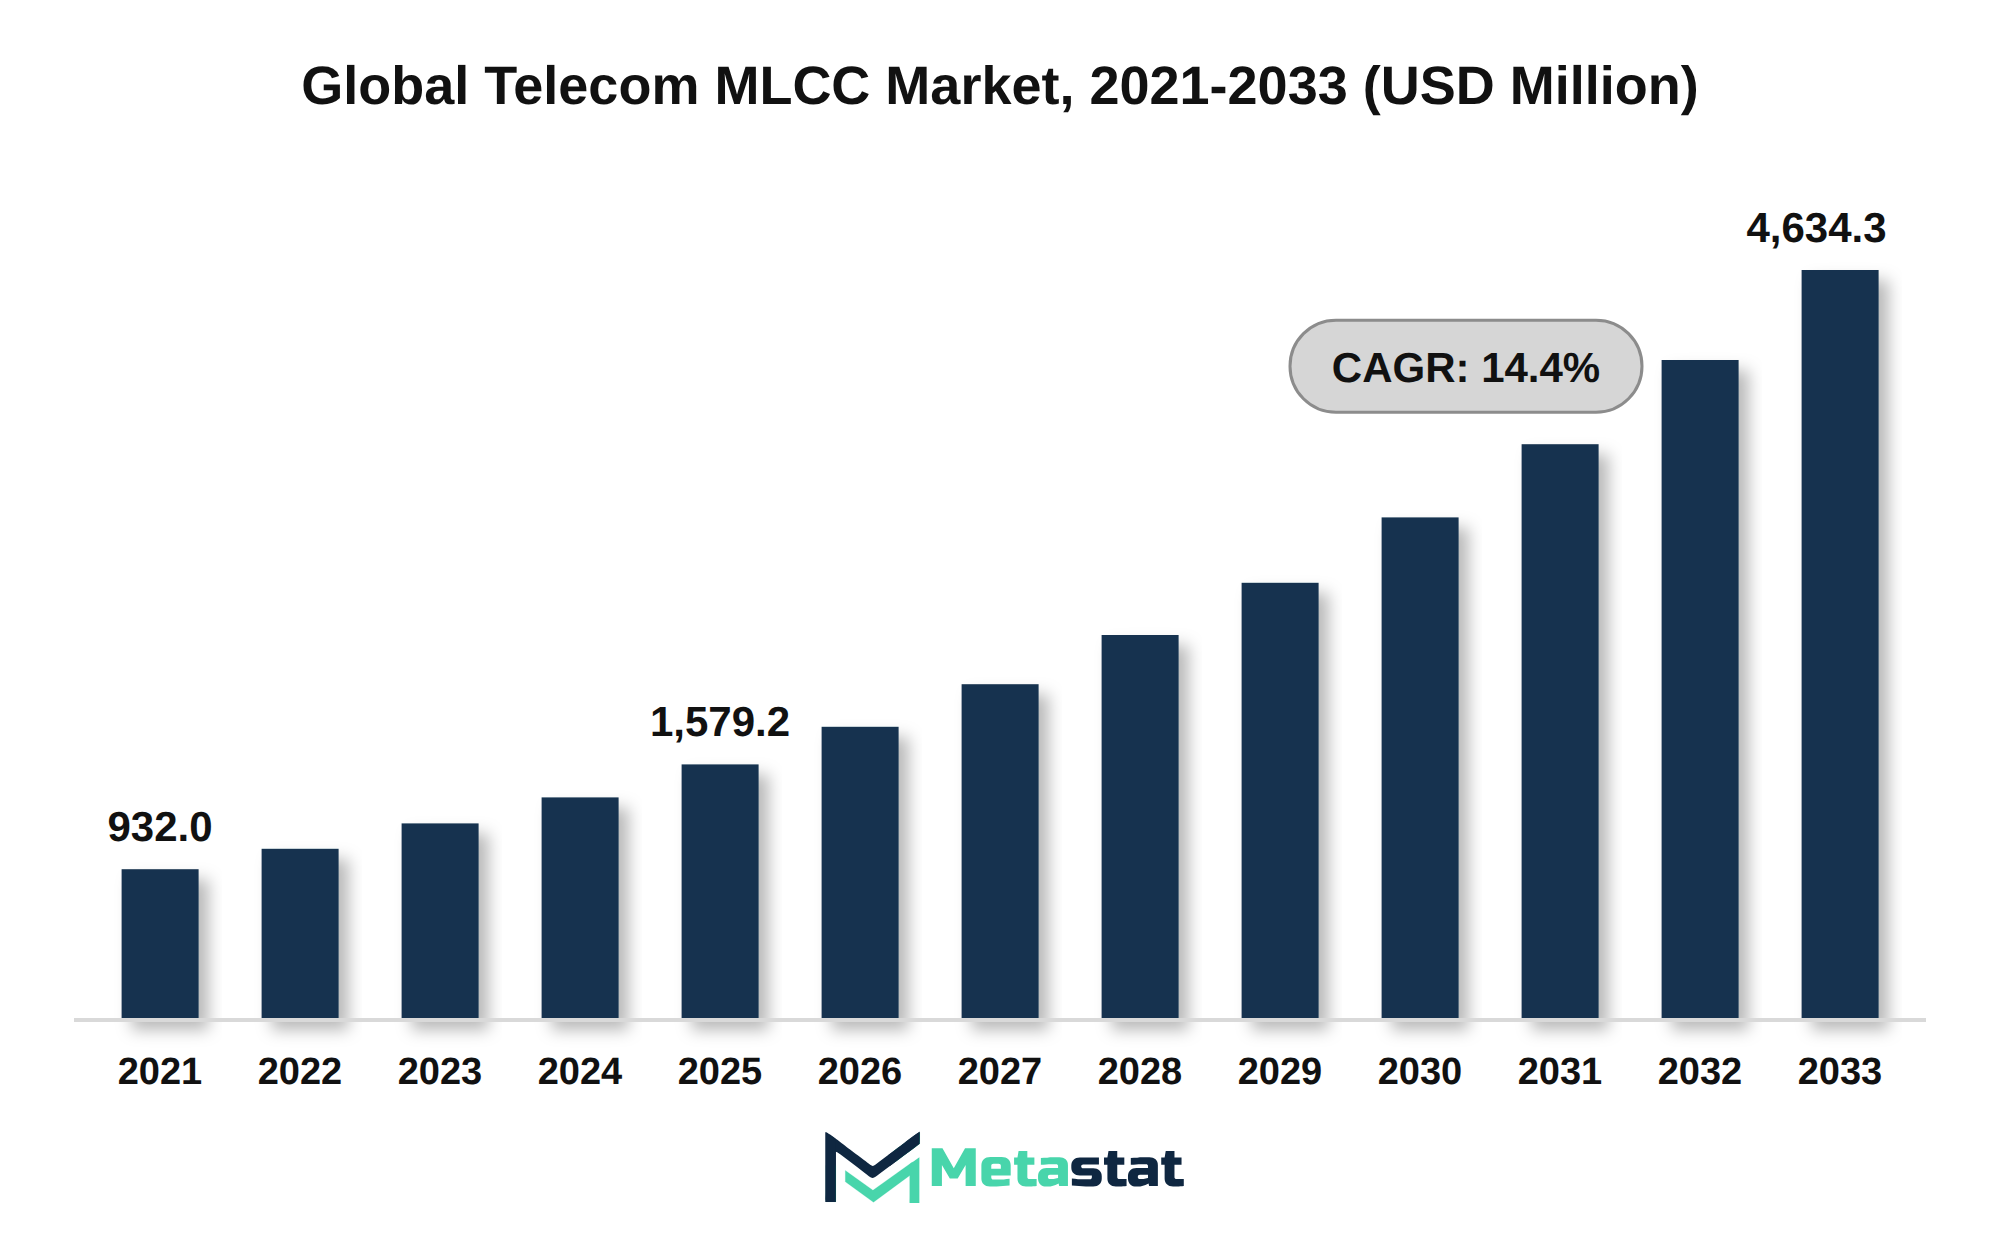
The ongoing digital transformation significantly influences the Telecom MLCC market, driven by the increasing demand for enhanced connectivity and advanced network capabilities. Companies invest heavily in automation and artificial intelligence, enabling streamlined processes and improved efficiency. This wave of technological integration increases the need for robust telecommunications infrastructure, directly impacting the consumption of multi-layer ceramic capacitors.
Investment in digital solutions enhances operational productivity across various sectors, including telecommunications, where the integration of modern technologies requires reliable components like MLCCs. While businesses upgrade their systems, the demand for high-performance capacitors surges, ensuring effective communication and data transmission in an increasingly interconnected world. This evolution drives the market's growth trajectory, contributing to the projected compound annual growth rate of 14.4 percent from 2026 to 2033.
The shift toward digital services influences consumer behaviors, with heightened expectations for reliable connectivity and rapid data access. This change compels telecommunication companies to enhance their service offerings, thereby driving demand for advanced components in their equipment. The Telecom MLCC market stands to benefit significantly from these trends, resulting in a robust market expansion driven by stakeholders prioritizing technological advancement.
Infrastructure development plays a critical role in the growth of the Telecom MLCC market. Significant investments in upgrading both physical and digital capacities enhance network capabilities, leading to increased demand for telecommunications equipment. Emerging technologies, including 5G, drive the need for more advanced components, including multi-layer ceramic capacitors (MLCCs) due to their reliability and performance. Governments and private entities commit substantial resources to expand telecommunications infrastructure, promoting connectivity in urban and rural areas. This commitment results in higher demand for telecom equipment, stimulating the market for Telecom MLCCs.
Investment in network modernization enables operators to improve service quality and meet consumer expectations for faster and more reliable telecommunications. The emphasis on expanding digital infrastructure aligns with global trends toward urbanization and evolving consumer behaviors, which necessitate robust telecommunications solutions. The shift toward smart city initiatives and IoT applications accelerates the necessity for high-performance components, including Telecom MLCCs. The growth trajectory of the market reflects these infrastructural advancements, with a projected CAGR of 14.4% from 2025 to 2033, indicating substantial opportunities for manufacturers and suppliers.
High capital investment requirements present a significant restraint within the Telecom MLCC market. The need for advanced manufacturing technologies and equipment increases the initial financial outlay for companies entering or expanding in this sector. This situation burdens smaller players, limiting their ability to compete effectively against larger, established manufacturers with greater financial resources.
Escalating operating costs associated with raw materials, labor, and compliance with industry standards compound the financial challenges faced by suppliers. These factors create a barrier to entry, particularly in regions where access to funding is restricted. Slower adoption rates and reduced innovation impact overall growth potential.
Technological obsolescence and the rapid pace of development in telecommunications equipment create pressure on companies to continually invest in upgrading their production capabilities. Firms unable to keep pace with technological advancements risk losing market share to competitors that effectively leverage new technologies. This dynamic contributes further to capital stagnation within the market.
Consequently, the combination of high capital investment requirements, operating costs, and technological demands significantly affects the overall landscape of the Telecom MLCC market, creating headwinds that impede growth and expansion.
Geopolitical fragmentation significantly impacts the Telecom MLCC market, complicating international trade and resulting in increased tariffs on components. These tariffs inflate production costs, affecting price competitiveness and profit margins for manufacturers. Trade deficits create additional challenges, with countries prioritizing domestic sourcing, which limits access to essential materials and technologies needed for telecom MLCC production.
Technological disruptions introduce complexities in research and development (R&D) integrations, making innovation more challenging for companies. Striking a balance between advancing technologies and existing production capabilities requires significant investment and resources, straining smaller players in the market. Interoperability friction arises from varying standards across regions, complicating the integration of products and technologies, leading to delays in product launches.
Supply chain instability poses ongoing challenges, driven by logistical disruptions and component volatility that create uncertainties in availability and pricing. This instability hinders manufacturers' ability to meet growing demand, especially in emerging applications including 5G infrastructure. Rising input costs further pressure profit margins, forcing companies to reassess pricing strategies and operational efficiencies.
The Telecom MLCC market faces pressures from tightening global regulatory standards, which heighten compliance overhead and potential liabilities. Companies navigate evolving legal landscapes, leading to increased operational complexities and costs. These factors contribute to an environment where maintaining competitiveness and profitability becomes increasingly difficult.
Environmental sustainability demands exert additional pressure on manufacturers to reduce their ecological footprints. Implementing decarbonization mandates entails significant investments in new technologies and processes, hindering short-term profitability. The combination of these challenges creates a scenario in which the Telecom MLCC market adapts continually to remain viable amid external pressures.
Technological disruptions significantly shape the Telecom MLCC market, driven by advancements in telecommunications and electronics. Innovations in 5G technology, IoT applications, and smart devices create increasing demand for high-performance capacitors. These shifts enable companies to enhance network efficiency and reliability, driving adoption across various sectors.
Infrastructure modernization further supports this growth, with investments in next-generation telecom networks. Companies actively upgrade existing systems and integrate new technologies to meet rising consumer expectations for connectivity and speed. This trend presents opportunities for suppliers to develop advanced materials and integrate them into diverse applications, improving operational performance.
Geographical expansion remains an important opportunity, particularly in emerging markets across Asia Pacific and South America. These regions exhibit rising demand for telecommunications solutions, driven by increased urbanization and mobile penetration. Suppliers that establish a presence in these markets capture significant market share, contributing to overall growth in the Telecom MLCC sector.
Consumer preferences shift towards sustainable and green technologies, prompting suppliers to align their offerings with environmental standards. The demand for eco-friendly solutions presents an opportunity for innovation in product development. Companies focusing on sustainability differentiate themselves in the market, appealing to environmentally conscious customers and organizations.
Strategic consolidation and cross-industry mergers further shape the competitive environment within the Telecom MLCC market. Companies pursue partnerships and acquisitions to enhance their technological capabilities and expand product portfolios. This trend allows firms to respond more effectively to evolving customer needs and leverage synergies across various sectors.
The Global Telecom MLCC market is segmented based on Dielectric Type, Rated Voltage, Case Size, and Telecom Equipment Application.
Valued at USD 437.3 million in 2026, the Class 1 Ceramic (C0G / NP0) segment is projected to reach USD 1,038.6 million by 2033, at a CAGR of 13.2% during the forecast period. The demand in this segment primarily arises from the growing need for reliable and high-performance capacitors within various telecom equipment applications. Increased deployment of advanced telecommunications infrastructure, particularly 5G technology, drives the adoption of Class 1 Ceramic capacitors due to their stable electrical properties and low temperature coefficients.
Technological maturation in the electronics industry supports the transition towards smaller and more efficient devices. This shift enhances the relevance of Class 1 Ceramic capacitors, because their compact size and reliability align with the requirements of next-generation telecom equipment. Downstream applications, including Radio Access Network Equipment and Core Network Servers & Gateways, significantly influence demand dynamics, enhancing the segment's growth prospects.
Regulatory compliance standards and certifications related to electronic components further facilitate market expansion by ensuring product quality and reliability. Pricing volatility and margin pressures in raw material sourcing impact the overall cost structures within the segment, necessitating strategic sourcing approaches to maintain competitiveness. While the Telecom MLCC market evolves, opportunities for investment and innovation within the Class 1 Ceramic segment will continue to emerge, driving sustained growth and adoption across the telecommunications landscape.
Demand for Class 2 Ceramic (X5R / X7R) capacitors experiences significant growth, driven by the increasing requirements of advanced telecom applications. The ongoing shift towards higher data rates and bandwidth in communication networks results in heightened demand for effective energy storage solutions. These capacitors excel in applications that require high capacitance and stability over a wide temperature range, aligning with the evolving needs of telecom equipment manufacturers.
Class 2 Ceramic (X5R / X7R) segment is estimated to reach USD 3,595.8 million by 2033, at a CAGR of 14.7% during the forecast period. This growth reflects the increasing reliance on compact, high-capacitance components, driven by the evolution of telecom infrastructure. Rising investments in 5G and next-generation technologies further stimulate this segment, encouraging manufacturers to innovate and enhance the performance characteristics of their products.
Regulatory compliance standards play a crucial role in shaping the market dynamics. Manufacturers actively seek certifications to ensure their products meet safety and reliability benchmarks, building confidence among telecom operators. The segment's evolution continues to adapt to these requirements, reinforcing its position within the broader Telecom MLCC market.
Technological maturation enhances the capabilities of Class 2 Ceramic capacitors, enabling them to meet the stringent demands of modern telecom applications. Ongoing advancements in materials science and manufacturing processes lead to improved performance, driving further adoption in various downstream applications, including routers, gateways, and optical transport systems.
Valued at USD 1,300.7 million in 2026, the Low Voltage (≤100 V) segment is projected to reach USD 3,215.3 million by 2033, with a compound annual growth rate (CAGR) of 13.8% during the forecast period. This growth results from the increasing adoption of advanced telecommunications infrastructure, which requires reliable and efficient components. The surge in demand for communication devices, powered by a growing reliance on data transmission and connectivity, drives the expansion of this segment.
Technological maturation within the sector facilitates the development of next-generation components that meet evolving specifications. Innovations in materials science lead to enhanced performance characteristics of low voltage multipurpose ceramic capacitors, appealing to diverse end-use applications. Industries including consumer electronics and automotive benefit significantly from these advancements, promoting increased adoption across various specifications and device categories.
Regulatory compliance standards and certifications ensure that products within this segment adhere to safety and performance benchmarks, further driving market confidence. Competition among key players remains intense, with firms focusing on pricing strategies to maintain market share during fluctuating raw material costs. Supply chain resilience supports sustaining production capabilities, driven by manufacturers optimizing sourcing strategies to mitigate vulnerabilities in logistics.
Investment in research and development remains a strategic priority for industry participants, allowing for continuous product evolution and adaptation to consumer preferences. The Telecom MLCC market experiences dynamic shifts in consumption patterns, driven by businesses seeking components that deliver greater efficiency and reliability. While the demand for low voltage solutions continues to rise, opportunities for growth and expansion within this segment become increasingly evident.
Increasing demand for advanced telecommunications infrastructure significantly drives growth in the Mid Voltage (>100-500 V) segment of the Telecom MLCC market. This segment is estimated to reach USD 1,041.3 million by 2033, at a CAGR of 15.3% during the forecast period. The expansion of telecommunication networks, particularly to support high-capacity data transmission, drives the requirement for reliable and efficient components. Regulatory compliance standards emphasizing enhanced performance and safety in electrical systems strengthen the need for high-quality capacitors in this segment.
Technological maturation in the telecom sector leads to the integration of next-generation upgrades, particularly with the rollout of 5G networks. These upgrades necessitate components that handle higher voltages and improved efficiency. Consequently, end-use dynamics reflect a growing demand for Mid Voltage capacitors, particularly in applications including core network servers and routers, which require robust performance under varying load conditions. Pricing volatility observed in raw materials influences cost structures, prompting manufacturers to optimize their sourcing strategies.
Market participants navigate substitution risks posed by alternative technologies, which could disrupt the demand for traditional components. Investment in research and development persists, targeting innovations that enhance product performance and longevity. This strategic opportunity window enables players to strengthen their market position while addressing evolving consumer preferences and regulatory challenges. Overall, the Mid Voltage segment remains poised for substantial growth driven by technological advancements and increasing consumption shifts within the Telecom MLCC market.
In the Telecom MLCC market, demand for high voltage capacitors, specifically those rated above 500 V, is driven by the increasing need for high-performance electronic devices and infrastructure. This segment is projected to reach USD 377.7 million by 2033. Growth stems from the expanding adoption of renewable energy systems and electric vehicles, where high-voltage applications are critical. Industries focusing on enhancing energy efficiency and reliability find the adoption of high voltage capacitors essential.
Technological maturation in capacitor design contributes to improved performance characteristics and reduced size, enabling integration into compact electronic systems. Next-gen upgrades in telecommunications equipment further increase the need for reliable high voltage components. Regulatory compliance standards promote the use of efficient and robust components, enhancing market demand. Cost structures reflect ongoing investments in research and development aimed at innovating within the high voltage segment, ensuring competitive pricing and maintaining profit margins.
The high voltage segment reflects a strategic opportunity window, particularly for manufacturers focusing on advanced materials and technologies to meet evolving market demands. Capital investment in production capabilities strengthens supply chain resilience, while raw material sourcing strategies mitigate risks associated with supply chain disruptions. While the market evolves, emphasis on product evolution and adaptation to end-use dynamics will shape the future trajectory of the high voltage segment.
Valued at USD 105.3 million in 2026, the 1005 segment is projected to reach USD 330.4 million by 2033, at a CAGR of 17.7% during the forecast period. This growth reflects increasing adoption of high-demand applications in the Telecom MLCC market, where the need for compact and efficient components drives significant product evolution. Compact case sizes, including 1005, align with the trend towards smaller, more efficient devices, emphasizing the importance of size in technological advancements.
Technological maturation across telecommunication infrastructures drives further expansion of the 1005 segment. Innovations in network equipment, including Radio Access Networks and Optical Transport Systems, generate increased demand for components that require high-performance capacitors. Downstream applications in broadband connectivity, alongside the expansion of 5G networks, ensure strong growth and require substantial investment in capacity and capability enhancements.
Pricing volatility represents a notable factor influencing margins within the Telecom MLCC market. Fluctuations in raw material sourcing, particularly for dielectric materials, impact overall production costs. Strategic opportunity windows arise for manufacturers adept at navigating these challenges, allowing them to enhance supply chain resilience and mitigate potential disruptions.
Adoption dynamics indicate a shift towards more sophisticated designs and applications. The continuous demand for advanced telecommunications solutions necessitates ongoing upgrades and enhancements in component specifications. Regulatory compliance and certification standards dictate quality and reliability, further propelling the growth of this segment, driven by players striving to meet stringent market requirements.
Growing adoption of advanced communication technologies supports the expansion of the 201 segment within the Telecom MLCC market. This segment is estimated to reach USD 751.7 million by 2033, at a CAGR of 16.7% during the forecast period. Demand for smaller case sizes drives manufacturers to optimize designs, aligning with the trend toward miniaturization in electronic devices. Increased functionality in mobile devices, coupled with the rise of IoT applications, necessitates efficient energy storage solutions, propelling segment growth. Enhanced performance requirements for telecommunications equipment further stimulate investments in the 201 segment, enabling manufacturers to meet evolving consumer expectations.
Valued at USD 1,163.7 million by 2033, the 402 segment reflects a growing trend driven by the increasing demand for compact, efficient components in telecommunications. This segment benefits from the rising importance of miniaturization in electronic devices, allowing manufacturers to produce smaller and more powerful telecom equipment. The shift toward higher integration in telecommunications applications further supports growth in this segment, because devices require greater density of components, including capacitors.
Adoption of advanced technologies, including 5G and IoT, significantly influences the 402 segment's expansion. The demand for these technologies necessitates components that handle higher frequencies and power levels, driving innovation and evolution within the market. The trend toward next-generation upgrades increases the need for capacitors that meet the stringent performance requirements of modern telecom applications.
Cost structures continue to impact the 402 segment, with raw material pricing volatility affecting overall production costs. Manufacturers focus on optimizing sourcing strategies and production efficiencies to maintain competitive pricing while ensuring quality. This focus on cost management and margin pressures influences the overall dynamics within the telecom MLCC market, emphasizing the need for strategic planning and investment in R&D to mitigate risks associated with material sourcing.
Overall, the 402 segment demonstrates significant growth potential, driven by evolving industry standards, technological maturation, and increasing adoption across various telecommunications applications. The segment's projected growth aligns with broader trends within the telecom MLCC market, reflecting the ongoing transformation of the telecommunications landscape.
Projected growth in the 603 segment aligns with the increasing complexity of telecommunications systems, which require higher efficiency and performance from components. This segment is expected to grow at a CAGR of 13.7% during the forecast period. The rise in demand for advanced telecom infrastructure directly influences the need for capacitors that meet stringent operational requirements.
Product evolution in the market emphasizes miniaturization without compromising performance. Capacitors in the 603 segment are increasingly applied in a variety of applications, including routers and Ethernet switches. These applications demand high reliability and performance, pushing manufacturers to innovate constantly.
Regulatory compliance and certification requirements will further drive market dynamics, because manufacturers work to ensure their products meet international standards. Compliance with these standards not only enhances product credibility but expands market opportunities globally.
Cost structures in the market face challenges from raw material sourcing and pricing volatility. Manufacturers navigate these complexities by optimizing supply chain resilience and exploring alternative materials. Consequently, strategic investment in technology and production capabilities will remain crucial for maintaining competitive advantage.
The Telecom MLCC market anticipates a shift toward greater adoption of advanced materials and technologies, directly benefiting segments like 603. This shift will facilitate improved performance characteristics in telecommunications applications, enabling firms to capture emerging opportunities and respond to evolving consumer demands.
Growing interest in the 805 case size reflects the ongoing evolution of telecommunications technology. The shift toward more compact and efficient designs in equipment drives demand for capacitors that meet stringent performance requirements. Manufacturers investing in advanced materials and design techniques enhance their offerings, positioning themselves to capture a larger share of the Telecom MLCC market.
Downstream applications across various sectors, including mobile and broadband communications, fuel the adoption of this specific capacitor size. With the increasing focus on miniaturization and energy efficiency, the need for high-performance capacitors becomes critical. Regulatory compliance and certification standards further drive the segment's growth, ensuring that products meet the necessary quality and safety benchmarks.
The market for the 805 case size will evolve with advancements in raw material sourcing and supply chain resilience. Companies focusing on sustainability and efficient sourcing strategies gain a competitive advantage. Technological obsolescence poses a challenge, arising from newer alternatives that emerge, emphasizing the need for continual innovation.
Strategic opportunity windows exist for manufacturers that align their product development with emerging trends in telecommunications. Capital investments aimed at enhancing production capabilities will play a role in meeting the rising demand. While the market progresses, the 805 segment remains an integral part of the overall growth trajectory within the Telecom MLCC market.
Consumer electronics and telecommunications equipment drive demand for the 1206 case size in the Telecom MLCC market. The segment benefits from growing trends in miniaturization and enhanced performance requirements. Device manufacturers increasingly prioritize compact and efficient electronic components, leading to a greater need for 1206 capacitors. Technological maturation within the telecom sector accelerates the adoption of these components, driven by providers upgrading infrastructure for next-generation communication networks.
The demand for 1206 capacitors aligns with evolving end-use dynamics, particularly in mobile devices and networking equipment. Their application in Radio Access Network Equipment and Optical Transport Systems supports significant growth in this segment. Cost structures and pricing volatility exert pressure on margins, necessitating strategic maneuvering by suppliers to maintain competitiveness in the market. Supply chain resilience remains vital, owing to raw material sourcing and logistics vulnerabilities that could impact production capabilities.
Regulatory compliance and certification requirements play a significant role in shaping the operational landscape for 1206 capacitors. Manufacturers that adhere to these standards position themselves favorably in the market, enhancing their appeal to major telecommunications players. Strategic opportunity windows arise, resulting from technological obsolescence prompting manufacturers to innovate and evolve product offerings, ensuring alignment with market demands. The market’s trajectory hinges on the balance of these factors, emphasizing the importance of adaptability within the Telecom MLCC segment.
Significant demand for the 1210 case size arises from the growing need for compact and high-performance components in the Telecom MLCC market. Adoption of next-generation communication technologies drives the necessity for smaller, more efficient capacitors that fit increasingly dense circuit designs. The evolution of mobile networks, particularly with the rollout of 5G technology, intensifies the focus on smaller case sizes, including 1210, to accommodate the higher frequency and performance requirements of advanced telecommunications systems.
Expansion catalysts for this segment revolve around technological maturation and product evolution. Manufacturers innovate to enhance performance characteristics while optimizing the size of components, leading to heightened competition among suppliers. Downstream applications requiring high reliability and miniaturization further support the growing demand for the 1210 case size. These dynamics reflect broader trends in the market, where the focus shifts toward meeting stringent performance standards while managing cost structures effectively.
Regulatory compliance standards influence product development in the Telecom MLCC market, ensuring that components meet industry specifications for safety and performance. Increased scrutiny on environmental impacts prompts manufacturers to pursue sustainable sourcing of raw materials, affecting procurement strategies and supply chain resilience. Strategic opportunity windows emerge due to companies seeking to align their offerings with evolving requirements, balancing innovation with cost considerations to maintain competitive advantage.
Overall, consumption shifts toward compact solutions with high performance continue to characterize the market. The 1210 case size positions itself because a vital segment in addressing these trends, offering manufacturers and end-users alike a reliable component suited for modern telecommunications applications.
Strong demand for advanced telecommunications infrastructure significantly influences the 1808 & 1812 sub-segment within the Telecom MLCC market. This segment aligns with the increasing adoption of high-performance components in communication devices, emphasizing the need for reliable and efficient energy storage solutions. Rapid technological advancements drive the evolution of product specifications, enabling manufacturers to enhance performance characteristics. The growing emphasis on miniaturization in electronic devices intensifies competition among suppliers, encouraging innovation and differentiation in product offerings.
Industry trends highlight a shift towards higher capacitance and lower profile designs, pushing manufacturers to focus on optimizing production processes and material selection. The regulatory landscape impacts the segment, with compliance to safety and environmental standards shaping product development strategies. Suppliers face challenges related to pricing volatility, driven by fluctuations in raw material costs that influence profit margins. Strategic investment in research and development enhances competitive positioning, allowing players in the market to capitalize on emerging opportunities and address rising consumer expectations.
Downstream applications, particularly in mobile communications and networking equipment, create substantial opportunities for growth. The increasing complexity of telecom systems necessitates higher-performance capacitors, further cementing the relevance of the 1808 & 1812 sizes. While companies navigate supply chain vulnerabilities and substitution risks, focusing on establishing resilient sourcing strategies remains essential. The outlook for this segment continues to strengthen, driven by the demand for robust performance in an evolving technological landscape within the Telecom MLCC market.
Increasing integration of advanced telecommunications systems contributes to the development of the 2220/2225 and Above segment within the Telecom MLCC market. This segment aligns with the growing need for compact and efficient components that support high-performance applications. The rise in demand for next-generation communication infrastructures drives manufacturers to innovate in design and capacity, addressing evolving technology requirements.
Technological maturation in the electronics industry drives a shift towards higher-performance capacitors, enhancing the utility of the 2220/2225 and Above segment. Manufacturers focus on product evolution to meet rigorous performance standards while maintaining compliance with regulatory requirements. These factors create an environment conducive to growth and investment within the market.
Demand patterns reflect a transition towards high-capacity applications, particularly in telecommunications and data transmission sectors. End-use dynamics highlight the preference for larger case sizes, which offer improved functionality for complex systems. While the market progresses, increased capital investment is expected to focus on enhancing product offerings and expanding manufacturing capabilities.
Supply chain resilience influences the landscape for the 2220/2225 and Above segment. Raw material sourcing strategies evolve to mitigate risks associated with supply disruptions, while companies explore sustainable options to ensure long-term viability. This proactive approach strengthens operational frameworks, enabling manufacturers to adapt to fluctuations in demand and maintain competitive pricing.
Growing interest in the Others (0204, 0306, 0508, 0612) sub-segment is evident within the Telecom MLCC market. This sub-segment caters to niche applications, particularly in compact electronic devices that require specialized sizing. The ongoing evolution in consumer electronics and telecommunications drives demand for these smaller capacitors, highlighting the need for tailored solutions to meet unique device specifications. With increasing emphasis on miniaturization, manufacturers prioritize product evolution, ensuring that these capacitors align with technological advancements and market expectations.
Regulatory compliance standards play a crucial role in shaping the development of the Others sub-segment. Adherence to industry certifications enhances consumer confidence and market acceptance while influencing product design and manufacturing practices. Consequently, companies focus on maintaining robust supply chain resilience, optimizing raw material sourcing, and addressing logistics vulnerabilities. Strategic opportunity windows arise because manufacturers seek to enhance their offerings in this competitive landscape, aligning with the broader trends observed within the Telecom MLCC market.
Growing investments in telecommunications infrastructure drive demand for Radio Access Network Equipment, which is valued at USD 514.5 million in 2026 and is projected to reach USD 1,289.3 million by 2033, at a CAGR of 14% during the forecast period. Increased adoption of 5G technology contributes significantly to this growth, driven by network operators enhancing their capabilities to support higher data rates and improved connectivity. The transition to next-generation networks necessitates the deployment of advanced radio access solutions, thereby creating opportunities for market players.
Technological maturation in wireless communication systems results in the evolution of Radio Access Network Equipment, with innovative designs and enhanced functionalities meeting the demands of modern applications. This segment experiences substantial interest from telecom operators and equipment manufacturers focused on optimizing network performance and ensuring high-quality user experiences. Regulatory compliance standards in various regions further influence the development of advanced equipment, emphasizing quality and performance metrics that align with industry expectations.
Cost structures play a critical role in shaping the market. Rising prices for raw materials used in manufacturing and fluctuations in component availability exert pressure on profit margins for suppliers. Manufacturers are responding by optimizing production processes and exploring alternative sourcing strategies to mitigate these challenges. Market participants actively seek strategic opportunities to enhance supply chain resilience, ensuring a steady flow of essential materials and components.
While the Telecom MLCC market continues to expand, competition intensifies among suppliers. Key players invest in research and development to create innovative solutions that address the evolving needs of telecommunications infrastructure. This environment encourages innovation, prompting firms to enhance their product offerings and strengthen their market positions. The strategic focus on next-gen upgrades and product evolution aligns with the broader trends in the telecommunications sector, positioning players for sustained growth and profitability.
Growth in the Core Network Servers & Gateways segment aligns with rising investments in network infrastructure and the shift towards next-generation communication technologies. Increasing demand for reliable and efficient data transmission drives operators to upgrade their core network capabilities, enhancing the performance of telecommunications services. This segment is estimated to reach USD 461.6 million by 2033, at a CAGR of 13.3% during the forecast period.
The ongoing evolution of telecommunications, including the deployment of 5G networks, significantly influences demand within the market. Operators prioritize advanced network solutions that facilitate high data throughput and low latency, positioning Core Network Servers & Gateways because critical components. Enhanced capabilities in network management and security further contribute to market expansion, attracting investments in infrastructure development.
Adoption of cloud-based solutions and virtualization within the telecommunications sector supports growth in this segment. Companies increasingly leverage these technologies to optimize resource management and reduce operational costs while enhancing service delivery. Such trends highlight the strategic importance of Core Network Servers & Gateways in enabling efficient network operations.
Regulatory compliance standards and certifications around network security and performance play a vital role in shaping the market landscape. Telecommunications providers face pressure to meet these standards, prompting investments in advanced core network solutions. This dynamic creates a competitive atmosphere, encouraging innovation among industry players to develop compliant products that meet evolving regulatory requirements.
The Core Network Servers & Gateways segment reflects a critical facet of the Telecom MLCC market, driven by technological advancements and the continuous demand for enhanced communication capabilities. Continued investment in this area signals a commitment to addressing the needs of modern telecommunications infrastructure, positioning the segment for sustained growth in the coming years.
Growth in the Routers & Ethernet Switches sub-segment of the Telecom MLCC market stems from increasing demand for reliable connectivity and higher data transfer rates. Advances in cloud computing, Internet of Things (IoT), and 5G technologies drive significant investments in networking infrastructure, necessitating more efficient and reliable components. This demand results in the requirement for higher-capacity capacitors, contributing to the segment's expansion.
Valued at USD 514.5 million in 2026, this sub-segment is expected to reach USD 685 million by 2033. The anticipated growth reflects the ongoing evolution of telecommunications infrastructure, necessitating next-generation upgrades and enhanced capabilities in networking equipment. With a compound annual growth rate (CAGR) of 14% for the segment, manufacturers increasingly focus on developing advanced capacitors tailored for Routers & Ethernet Switches.
Technological maturation and product evolution play critical roles in the segment. The integration of artificial intelligence and machine learning into network management systems demands higher performance and reliability from components. This trend encourages manufacturers to innovate and enhance the functional properties of capacitors, ensuring compliance with evolving industry standards and certifications.
Investment in downstream applications, including core network servers and gateways, directly influences demand dynamics. Growing requirements for data storage and processing power compel operators to upgrade their infrastructure, increasing consumption of Telecom MLCC products. The transition to more complex and feature-rich networking solutions generates higher demand for efficient capacitors, making Routers & Ethernet Switches a key focus area in the market.
Strategic opportunities arise from ongoing digital transformation across various industries, leading to an upsurge in data traffic. While businesses and consumers demand faster and more reliable internet connections, investment in Routers & Ethernet Switches is expected to increase, presenting a lucrative market for suppliers and manufacturers. Enhanced capital investment outlooks further support the segment's growth prospects, contributing to the overall expansion of the Telecom MLCC market.
Continued advancements in technology drive the demand for Optical Transport & Access Systems within the Telecom MLCC market. This segment serves critical roles in data transmission and network reliability, contributing to the increasing need for high-capacity optical connections in telecommunications. Expected growth at a CAGR of 15.7% during the forecast period reflects strong market dynamics influenced by rising bandwidth requirements and the expansion of fiber-optic networks.
Ongoing investments in next-generation network infrastructure, including 5G deployment, further enhance market expansion. Enhanced capabilities of Optical Transport & Access Systems align with the rising demand for faster data transfer rates and greater network efficiency. Telecom providers prioritize upgrading existing systems, focusing on solutions that support higher data throughput and lower latency.
Regulatory frameworks promoting the adoption of broadband connectivity enhance the growth trajectory of this segment. Government initiatives aimed at improving digital infrastructure facilitate investment in Optical Transport & Access Systems, creating strategic opportunities for revenue generation within the market. The market environment reflects a strong outlook driven by the convergence of technological evolution and regulatory support, indicating a robust future for Optical Transport & Access Systems.
Investment in advanced telecommunications infrastructure stimulates interest in Microwave & Millimeter-Wave Backhaul Equipment within the Telecom MLCC market. Increasing demand for high-speed data transmission fuels the need for efficient backhaul solutions in various applications, including mobile networks and enterprise connectivity. This segment benefits from the broader shift towards next-generation connectivity solutions, particularly the transition to 5G networks, which require robust backhaul systems capable of handling increased data loads.
Technological advancements in microwave and millimeter-wave technologies enhance product performance and reliability, allowing for higher capacity and improved efficiency. These upgrades create strategic opportunities for manufacturers to innovate and differentiate their offerings, contributing to a competitive advantage in the market. Regulatory compliance standards push for enhanced performance metrics, encouraging manufacturers to invest in R&D for more efficient and compliant products.
Cost structures in this segment reflect the shifting dynamics of raw material sourcing and supply chain resilience. Fluctuations in pricing and margin pressures challenge profitability, prompting manufacturers to optimize production processes and explore cost-effective alternatives. Strategic partnerships within the supply chain help mitigate these challenges, ensuring a stable flow of materials and resources essential for production continuity.
Demand for high-capacity networks continues to rise. Microwave & Millimeter-Wave Backhaul Equipment positions itself because a critical component within the Telecom MLCC market. The need for advanced solutions to support increasing data traffic creates favorable conditions for growth, making this segment a focal point for both investment and innovation in the telecommunications landscape.
Increasing demand for high-speed internet and improved connectivity drives growth in the Broadband CPE & Fixed Wireless Access Equipment segment. The push for enhanced broadband services drives telecommunications providers to invest in next-generation technologies, resulting in increased adoption of fixed wireless access solutions. Developments in remote work, online education, and digital entertainment further fuel consumption shifts toward reliable broadband options, creating urgency for advanced equipment in this sector.
Technological maturation of wireless communication standards, including 5G, leads to significant upgrades in existing infrastructures. Market participants invest heavily in product evolution to meet the standards and expectations of modern consumers. These advancements involve integrating more sophisticated components, including multi-layer ceramic capacitors (MLCCs), to improve performance and efficiency, ultimately enhancing the user experience.
The evolving landscape of regulatory compliance standards impacts the segment. Ensuring adherence to these regulations maintains consumer trust and establishes a competitive edge in the Telecom MLCC market. Firms that invest in meeting stringent standards benefit from enhanced market positioning and greater customer loyalty.
Pricing volatility in raw materials influences cost structures across the segment. Manufacturers face challenges in sourcing materials due to market fluctuations and supply chain vulnerabilities. Strategic opportunity windows arise from companies looking to secure long-term contracts and diversify their supplier base, mitigating risks associated with pricing and availability.
Overall, strong demand dynamics, driven by technological advancements and evolving consumer expectations, position the Broadband CPE & Fixed Wireless Access Equipment segment for substantial growth within the broader Telecom MLCC market. Companies focusing on innovation and adaptability within their product offerings will capitalize on emerging opportunities and enhance their market presence.
Investment in satellite communication infrastructure drives demand for the Telecom MLCC market. The ongoing evolution of satellite technology increases the need for efficient and reliable components. This dynamic influences advancements in satellite communication ground equipment, enhancing connectivity and operational capabilities.
Technological maturation influences the expansion of this segment. Innovations in satellite communication, particularly in reducing latency and improving bandwidth, generate opportunities for advanced components. This trend aligns with the broader goals of providing high-quality communication services, impacting both commercial and governmental applications.
Regulatory compliance standards and certifications for satellite communication systems further shape the market dynamics. Compliance with international standards necessitates the use of high-performance components, driving investments in robust Telecom MLCC products. Suppliers focusing on meeting these standards position themselves favorably within the market.
Strategic opportunity windows arise from the increasing demand for satellite communication solutions in remote and underserved regions. While global connectivity initiatives progress, investment in ground equipment becomes critical. This shift attracts capital investment, enhancing competition and promoting innovation in the Telecom MLCC market.
Supply chain resilience remains vital in addressing raw material sourcing challenges and logistics vulnerabilities specific to the satellite communication ground equipment segment. Manufacturers that streamline their supply chains while ensuring quality control navigate potential disruptions effectively. This focus contributes to improved cost structures and pricing stability, further enhancing competitive positions.
Overall, the ongoing evolution of satellite communication technology, coupled with regulatory frameworks and investment trends, positions the Telecom MLCC market for substantial growth. Key players who adapt to these changes benefit from increased demand and opportunities within this segment.
Investment in reliable power supply systems for telecommunications drives demand for Telecom Power & Rectifier Systems. This segment benefits from the ongoing transition to more efficient and sustainable energy solutions in telecommunication infrastructure. Growing requirements for energy efficiency and regulatory compliance encourage manufacturers to innovate and enhance product offerings, ensuring resilience against fluctuations in energy costs.
Technological maturation in power supply systems creates opportunities for next-generation upgrades. Integration of smart technologies enhances performance and reliability, making these systems vital for modern telecommunications applications. The Telecom MLCC market experiences shifts in consumption patterns driven by end-users prioritizing advanced systems that provide higher efficiency and longer operational lifespans.
Raw material sourcing and supply chain resilience play crucial roles in this segment. Manufacturers face challenges related to raw material availability and pricing volatility, which directly affect production costs and margins. Strategic partnerships and local sourcing initiatives strengthen supply chains, reducing risks associated with global disruptions.
Regulatory compliance standards significantly influence product development. Adherence to evolving regulations ensures market participants remain competitive while meeting consumer expectations for quality and sustainability. Continuous evaluation of policy headwinds allows manufacturers to adapt and align their offerings with market demands, positioning them favorably within the Telecom MLCC market.
Growing investments in Network Test Equipment and Legacy Wireline Equipment reflect the ongoing evolution of telecommunications infrastructure. Demand for high-performance equipment arises from the necessity for accurate testing and validation of network functionality. The increasing complexity of networks drives the need for advanced testing solutions that ensure reliability and performance optimization. Integration of next-gen technologies compels equipment upgrades, promoting the continuous evolution of offerings in this sub-segment.
Shifts in consumption patterns fuel ongoing interest in more sophisticated testing methodologies. Regulatory compliance and standards for network performance necessitate advanced equipment to meet stringent requirements, influencing purchasing decisions among stakeholders. Suppliers focus on delivering innovative solutions that cater to these regulatory demands, further propelling the segment's growth within the broader Telecom MLCC market.
Technological obsolescence disrupts the Telecom MLCC market, leading firms to adopt newer equipment to maintain competitive advantages. Strategic opportunities arise from the ongoing digital transformation within telecommunications, positioning companies to capitalize on emerging trends in connectivity. Capital investments directed toward developing robust testing solutions enhance supplier resilience and expand market presence in response to evolving industry challenges.
Based on geography, the Global Telecom MLCC market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
North America Telecom MLCC market experiences steady expansion, driven by demand from the United States, Canada, and Mexico. The ongoing modernization of telecommunications infrastructure significantly contributes to this growth, focusing on enhancing connectivity and network reliability. Investment in advanced technologies, including Radio Access Network Equipment, stimulates demand across these countries.
By 2026, the market is projected to reach USD 1,811.3 million, reflecting a strong trajectory toward the anticipated market size of USD 920.4 million by 2033, growing at a CAGR of 14.4%. This expansion is fueled by the increasing adoption of low voltage telecom components, which are essential for efficient network operations. The prevalence of localized manufacturing and supply chain regionalization enhances the ability to meet market demands promptly.
The competitive landscape features several domestic players, positioning themselves prominently within the market. Regional participants, including Murata Manufacturing Co., Ltd. and TDK Corporation, play important roles in driving innovation and ensuring the availability of high-quality materials. These companies actively contribute to the development of telecom solutions tailored to the unique needs of North American consumers.
Infrastructure readiness and resource availability further enable market growth. The emphasis on energy grid resiliency ensures that telecom systems operate smoothly, even during peak demand periods. The North America Telecom MLCC market stands poised for sustained growth, benefiting from strategic investments and local compliance mandates that support the development of advanced telecommunications networks.
The Telecom MLCC market in Europe exhibits strong growth potential, driven by increasing investments in telecommunications infrastructure. Countries including Germany, France, the UK, Italy, and Spain are key contributors, with Russia representing an important segment of the market. The share of the global market in 2025 is projected at 17.7%, reflecting the region's significant role in the telecommunications landscape.
High demand for advanced communication technologies and the ongoing modernization of infrastructure serve because primary catalysts for market expansion. Local compliance mandates and the regulatory frameworks in European nations create a structured environment conducive to investment. These factors collectively enhance the competitive landscape, encouraging domestic market leaders to pursue innovative solutions to meet the evolving demands of telecommunications.
Localized procurement dynamics influence B2B buying behaviors, ensuring that suppliers align their offerings with regional preferences. This strategic focus creates partnerships and strengthens supply chain networks, enhancing the market's resilience and adaptability. The presence of established manufacturers supports incremental growth vectors and encourages new entrants to capitalize on emerging opportunities within the Telecom MLCC market.
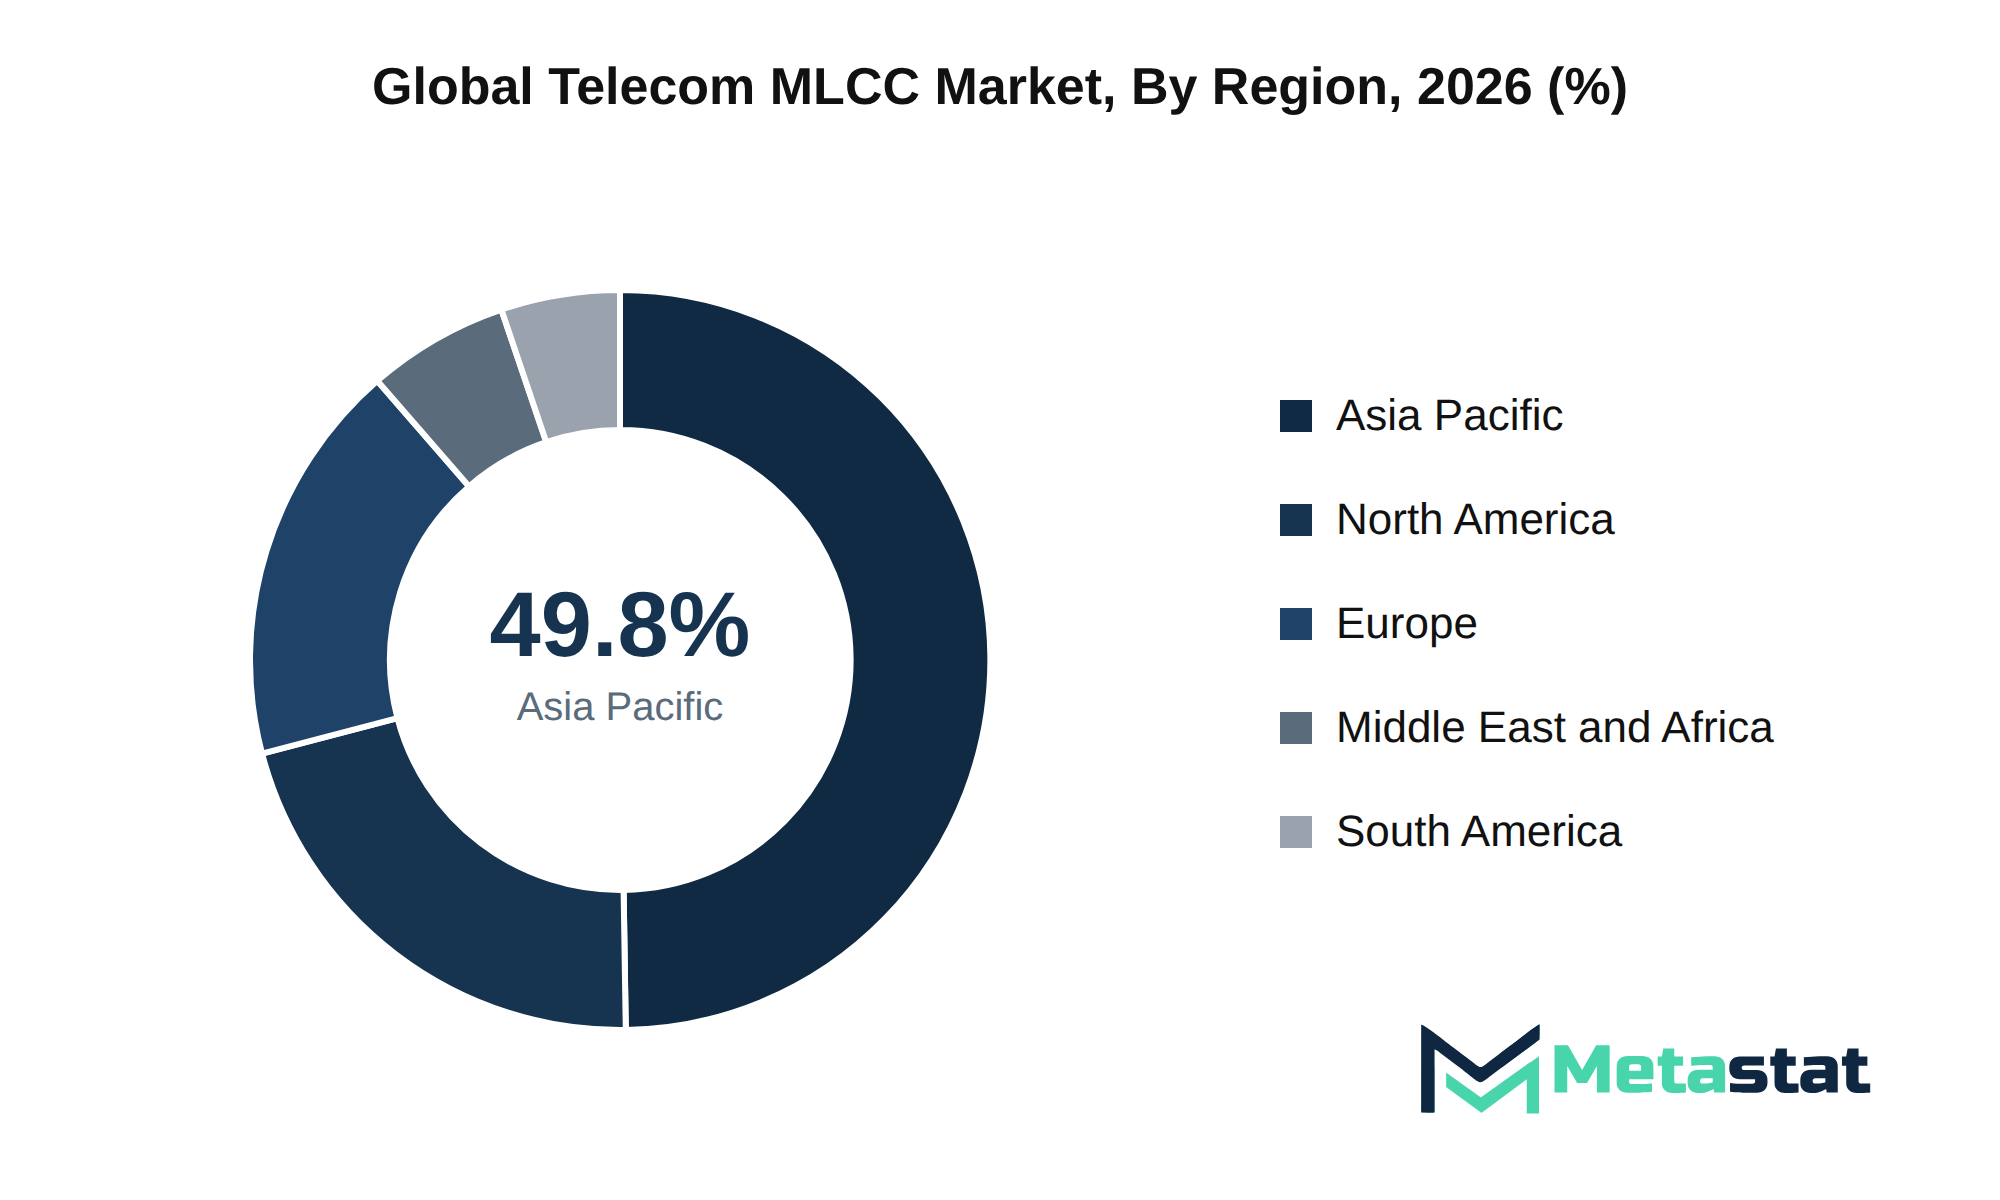
Asia-Pacific represents a substantial share of the global Telecom MLCC market, accounting for 49.8% in 2025. This region benefits from rapid advancements in telecommunications technology, creating an environment conducive to increased demand. China, Japan, and India serve because primary drivers of market growth, supported by a surge in digital transformation initiatives and infrastructure modernization efforts.
Investment in telecom infrastructure, particularly in developing economies like India and Southeast Asia, enhances market penetration and supports the adoption of advanced technologies. The region experiences a high-value replacement cycle, where aging equipment necessitates upgrades to maintain competitive advantage. This trend creates significant opportunities for suppliers catering to the evolving needs of telecom operators.
Localized manufacturing densities in countries including China and South Korea streamline supply chains, reduce lead times, and enhance responsiveness to market demands. Geopolitical factors lead to increased regionalization of supply chains, encouraging businesses to establish operations closer to their target markets. This shift optimizes costs and improves compliance with regional regulatory frameworks.
Strategic entry barriers, including domestic market leaders and vendor consolidation trends, shape the competitive landscape. Prominent players operating in the region include Murata Manufacturing Co., Ltd., Samsung Electro-Mechanics Co., Ltd., and TDK Corporation, which leverage their strengths to capture a larger market share. Cultural nuances and regional B2B buying behaviors influence procurement decisions, emphasizing the importance of tailored marketing strategies.
Energy grid resiliency and local infrastructure readiness in Asia-Pacific countries provide a solid foundation for the growth of the Telecom MLCC market. The increasing demand for high-speed internet and connectivity further supports investment in advanced telecommunications systems, indicating a positive outlook for the industry in this region.
South America accounts for USD 1,004.1 million of the global Telecom MLCC market in 2025, with growth driven by increasing demand for telecommunications infrastructure in Brazil and Argentina. Investment in network expansion and modernization enhances the operational capabilities of local telecom providers, contributing to the market's development.
The demand for Telecom MLCC is influenced by evolving consumer preferences for high-speed internet and enhanced connectivity solutions. Telecommunications operators in South America prioritize upgrades in their infrastructure to meet these expectations, creating a conducive environment for growth in the market.
Localized manufacturing initiatives in Brazil and Argentina strengthen supply chain dynamics and promote regional production capacities. This shift supports the market's expansion by reducing dependency on imports and encouraging domestic innovation within the Telecom MLCC segment.
Strategic collaboration among domestic players and international vendors encourages competitive advantages, enhancing market positioning. The presence of leading manufacturers in South America, coupled with the region's growing adoption of advanced technology, positions the market for sustained growth and expansion in the coming years.
The Telecom MLCC market in the Middle East and Africa faces unique dynamics characterized by varying demand drivers across the region. Countries including Saudi Arabia and the UAE invest significantly in telecommunications infrastructure modernization, driven by government initiatives aimed at enhancing digital connectivity. South Africa's growing urbanization and focus on improving mobile network reliability contribute to market expansion.
Localized manufacturing densities and regional resource availability influence the competitive landscape in the market. Emerging players seek to capitalize on underpenetrated territories, increasing competition and driving innovation. The region's supply chain regionalization and nearshoring initiatives support the development of local manufacturing capabilities, enhancing responsiveness to market demands.
Cross-border trade corridors and geopolitical factors shape the operational landscape. Countries in the Middle East and Africa adapt to local compliance mandates and regulatory frameworks, which affect the procurement strategies of businesses in the market. Demand for efficient local solutions increases, while domestic market participants pursue strategic entry barriers to enhance their competitive advantage.
The Telecom MLCC market evolves, with energy grid resiliency and local infrastructure readiness playing critical roles in supporting growth. A CAGR of 14.4% through 2033 presents significant opportunities for investment and development, particularly in high-value replacement cycles and incremental growth vectors.
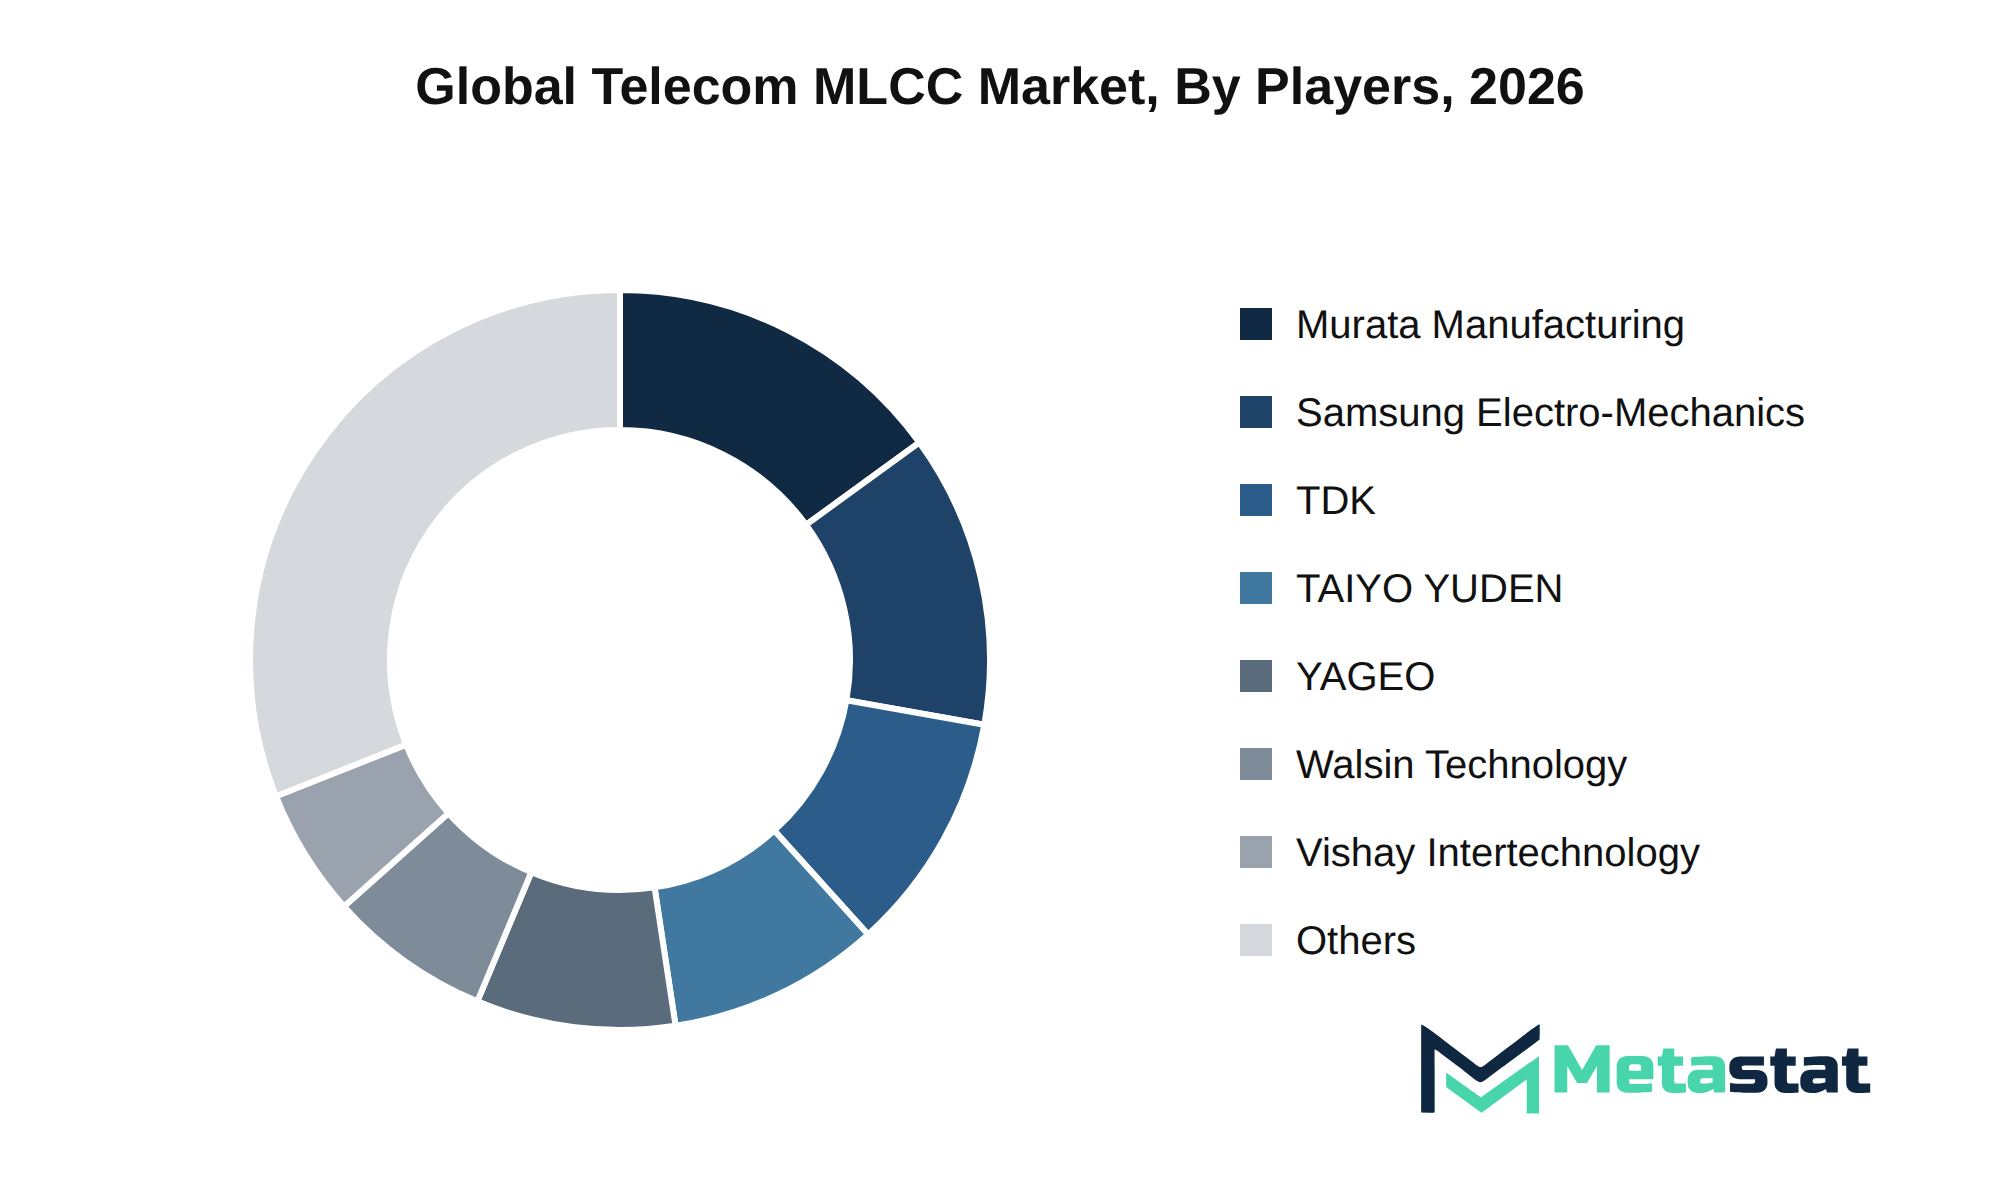
The Telecom MLCC market features significant competition among various players, emphasizing strategic consolidation, product differentiation, and value chain integration. Companies including Murata Manufacturing Co., Ltd., Samsung Electro-Mechanics Co., Ltd., and TDK Corporation actively leverage proprietary technologies to create competitive advantages and enhance market positions.
Strategic alliances, joint ventures, and partnerships are common tactics employed by firms like TAIYO YUDEN CO., LTD. and YAGEO Corporation to expand reach and capabilities. These collaborations enable players to combine resources and expertise, driving innovation in product development and enhancing overall service delivery.
Brand equity dynamics and customer retention strategies remain vital for success in the market. Firms including Walsin Technology Corporation and Vishay Intertechnology, Inc. invest in improving customer relationships and maintaining high switching costs, contributing to long-term profitability and market stability.
The competitive environment is further defined by the threat of new entrants and startup disruption dynamics. A strong focus on research and development by established players helps maintain technological defensibility against potential disruptors. This approach ensures robust future competitive outlooks, with companies like KYOCERA Corporation and Shenzhen Eyang Technology Development Co., Ltd. continually evolving R&D pipelines to address market demands efficiently.
Market size is forecast to rise from USD 1,579.2 million in 2025 to over USD 4,634.3 million by 2033. The base case presents a growth trajectory at a 14.4% CAGR. Economic cycles significantly influence demand within the Telecom MLCC market. Downstream demand fluctuations arise from technological advancements and evolving consumer preferences, compelling manufacturers to adapt their offerings accordingly.
Next-generation technology integration plays a critical role in shaping the market landscape. R&D commercialization timelines determine how swiftly innovations transition from concept to market-ready products. Regulatory evolution and compliance milestones require strategic alignment from industry players, influencing investment decisions and operational priorities.
Geopolitical realignments and changing trade corridors impact global supply chains, affecting sourcing strategies and production capabilities. Strategic capital allocation directives emphasize infrastructure commitments while prioritizing CapEx investment vectors in high-growth regions. Emerging white-space opportunities arise from unmet enterprise needs, indicating areas ripe for development within the market.
Defensibility roadmaps and future growth recommendations guide executive-level strategic imperatives. Focusing on sustainability and efficiency in production processes will enhance competitive positioning. The Telecom MLCC market is set for transformation driven by companies navigating these multifaceted challenges and opportunities.
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Telecom MLCC market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 14.4% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Dielectric Type, Rated Voltage, Case Size, Telecom Equipment Application, and Region |
By Region | North America (By Dielectric Type, Rated Voltage, Case Size, Telecom Equipment Application, and Country)
|
Europe (By Dielectric Type, Rated Voltage, Case Size, Telecom Equipment Application, and Country)
| |
Asia Pacific (By Dielectric Type, Rated Voltage, Case Size, Telecom Equipment Application, and Country)
| |
South America (By Dielectric Type, Rated Voltage, Case Size, Telecom Equipment Application, and Country)
| |
Middle East and Africa (By Dielectric Type, Rated Voltage, Case Size, Telecom Equipment Application, and Country)
|
Find answers to common questions about this report
The Telecom MLCC market size was valued at USD 1,579.2 million in 2025.
The Telecom MLCC market is projected to grow at a CAGR of 14.4% during the forecast period from 2026 to 2033.
The North America Telecom MLCC market size is estimated to reach USD 920.4 million by 2033.
Class 2 Ceramic (X5R / X7R) leads the Telecom MLCC market with a projected value of USD 3,595.8 million by 2033, based on its higher growth rate compared to Class 1 Ceramic (C0G / NP0).
The key drivers for the Telecom MLCC market include the ongoing digital transformation, which increases demand for enhanced connectivity, and significant investments in telecommunications infrastructure, particularly for emerging technologies like 5G. These trends lead to a projected compound annual growth rate of 14.4 percent from 2026 to 2033 because companies seek reliable components for improved service quality.
High capital investment requirements and escalating operating costs present significant restraints within the Telecom MLCC market. Smaller players face challenges competing against larger manufacturers due to these financial burdens, which limit innovation and slow adoption rates, ultimately impacting overall market growth. Geopolitical fragmentation and tightening regulatory standards further complicate operational dynamics and increase compliance costs.
The ongoing digital transformation and significant investments in telecommunications infrastructure favor product adoption in the Telecom MLCC market. The demand for enhanced connectivity and advanced network capabilities, particularly driven by emerging technologies like 5G, creates a strong need for reliable components including multi-layer ceramic capacitors.
The Telecom MLCC market is estimated to reach a valuation of USD 4,634.3 million by 2033.
Key players in the Telecom MLCC market include Murata Manufacturing Co., Ltd., Samsung Electro-Mechanics Co., Ltd., TDK Corporation, TAIYO YUDEN CO., LTD., YAGEO Corporation, Walsin Technology Corporation, and Vishay Intertechnology, Inc.
Asia Pacific leads the Telecom MLCC market, accounting for 49.8 percent of the regional share.
Choose Your License
Global Telecom MLCC Market
The analysts below cover Electronics and Semiconductor research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.
PRINCIPAL CONSULTANT - QUALITY SYSTEMS & COMPLIANCE
Electronics and Semiconductor · Machinery & Equipment · Professional Services
Omkar Phadtare is an Industry Consultant at MetaStat Insight, specializing in quality systems, regulatory compliance, and standards benchmarking to drive data-driven market intelligence and strategic industry research.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Integrating zero-trust access controls across legacy electronic health record systems involves complex compliance overhead. Team produced an analysis that clearly separated identity governance and administration tools from privileged access management platforms. Their evaluation of HIPAA and GDPR compliance features across cloud native solutions gave our architecture group clear baseline criteria. The custom data request regarding biometric authentication adoption in hospital networks was returned promptly with clear documentation.
Evaluating calorific value requirements and air permit compliance across municipal waste facilities requires localized data. Metastat Insight structured their analysis around operational throughput capacity and feedstock composition variations in Latin America and Eastern Europe. Their competitive mapping of sorting equipment vendors helped clarify technology differences between optical separators and heavy media systems. The study provided an objective baseline during our capital expenditure reviews.
Decarbonizing industrial thermal processes hinges on refrigerant regulations and compressor efficiency limits. Metastat Insights delivered a thorough market analysis that evaluated natural refrigerants like CO2 and hydrocarbons against synthetic low-GWP alternatives. The breakdown of utility incentives and grid capacity constraints across key European manufacturing hubs offered valuable perspective. The follow-up conversation with their sector analysts addressed our specific questions on mechanical vapor recompression systems efficiently.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950