
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Switzerland Cloud Gaming Market Size, Share, By Service Type (Game Streaming Services and Cloud Gaming PC Services), By Device Type (Desktops and Laptops, Smartphones, Smart TVs and TV Streaming Devices, Home Gaming Consoles, Tablets, and Handheld Gaming Devices), By Revenue Source (Subscription Fees, Usage-Based Fees, and Advertising Revenue), By Access Network (Fixed Broadband and Mobile Broadband), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-5517
Published
October, 2026
Pages
258 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
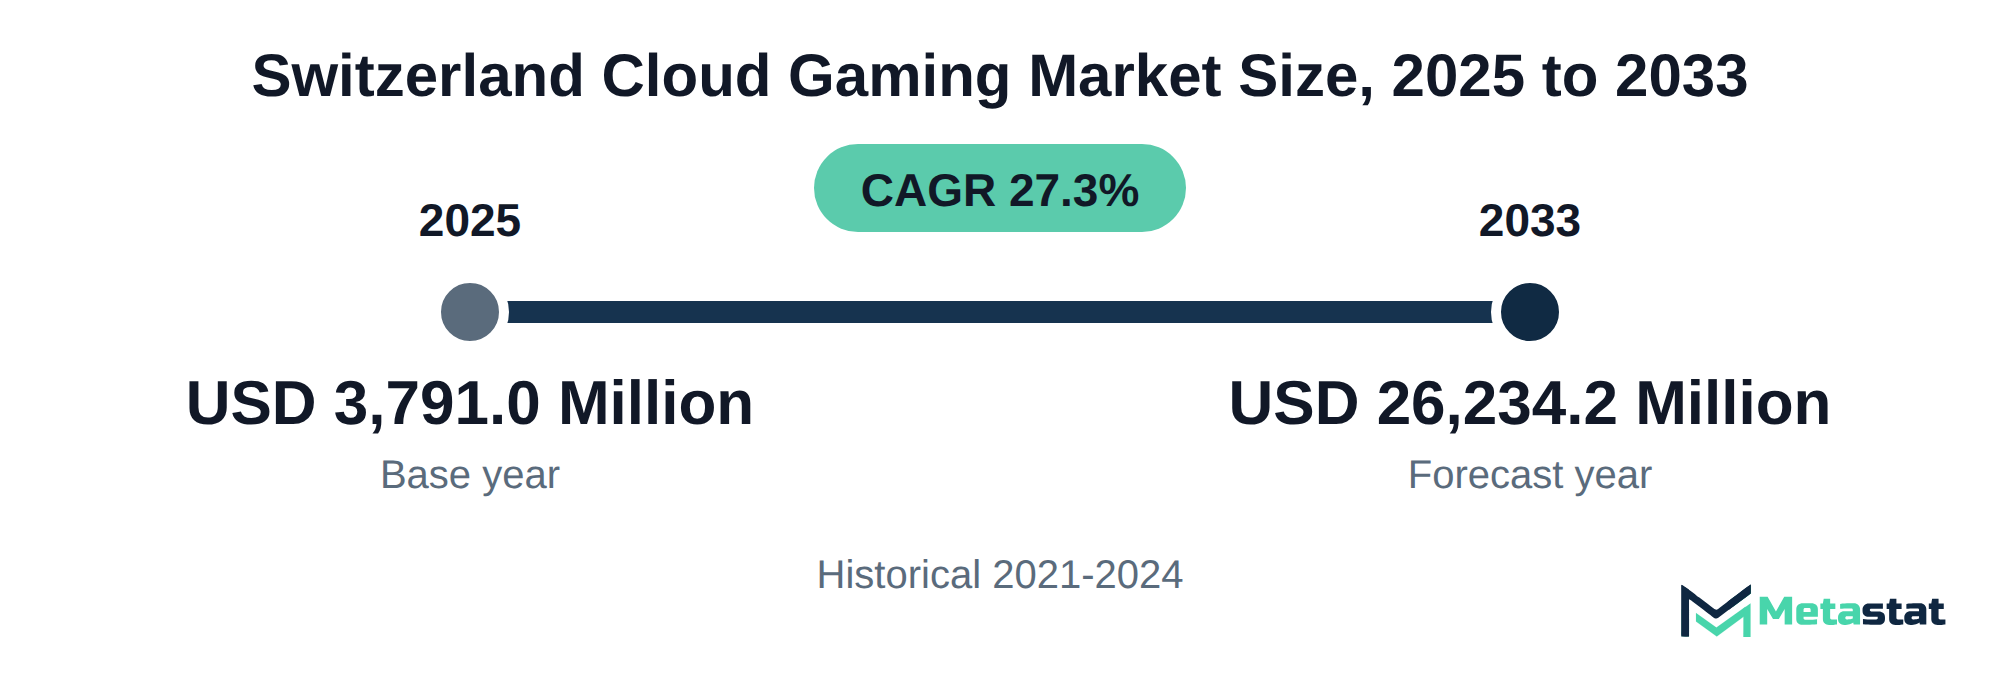
Market Valuation: Valued at $3,791 Million in 2025, projected to reach $26,234.2 Million by 2033 at a 27.3% CAGR.
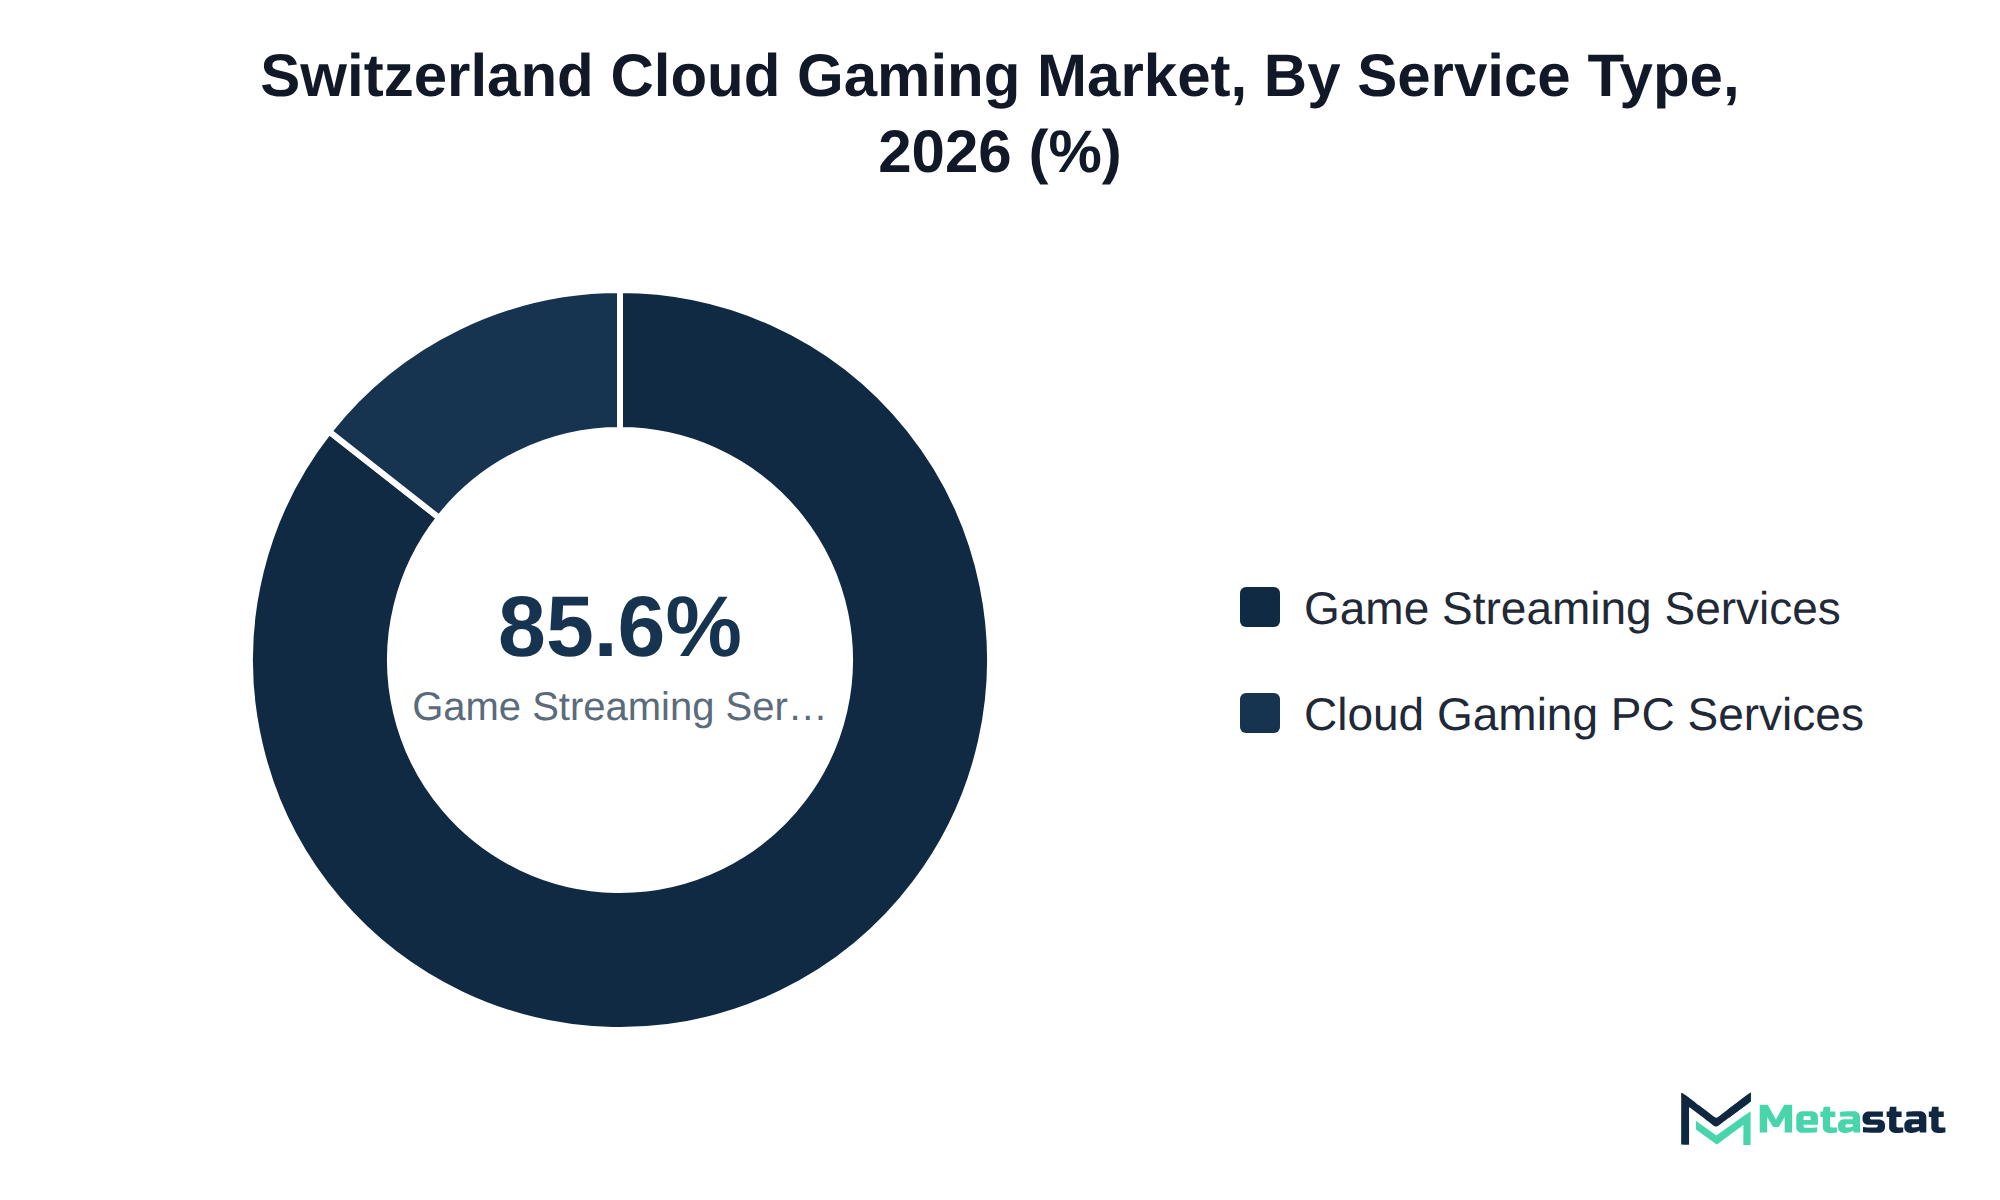
Dominant Segment: Game Streaming Services lead the Switzerland Cloud Gaming market, driven by increasing demand for subscription-based models that provide extensive game libraries and easy access.
Geographic Lead: Switzerland is the leading region in cloud gaming adoption, thanks to high broadband penetration rates and a tech-savvy population, fostering robust demand for cloud gaming solutions.
What's Inside: This report provides a comprehensive analysis of the Switzerland Cloud Gaming market, including competitive coverage, segment breakdowns, and a forecast window from 2026 to 2033.
Revenue Source Trends: Subscription Fees are a primary revenue source, but Usage-Based Fees are projected to grow faster, appealing to budget-conscious gamers seeking flexibility.
Device Growth: The smartphone segment is expected to experience the highest growth rate, reflecting the increasing popularity of mobile gaming among diverse demographics.
Choose Your License
Switzerland Cloud Gaming Market
The Switzerland Cloud Gaming market was valued at USD 3,791 million in 2025 and is projected to reach USD 26,234.2 million by 2033, growing at a CAGR of 27.3% over the forecast period.
The Switzerland Cloud Gaming market encompasses various services that enable users to stream video games over the internet, significantly reducing the need for high-end hardware at home. Buyers invest in this market primarily due to the convenience and flexibility it offers, allowing access to a vast library of games without significant upfront costs. This model appeals to gamers who prioritize diverse gaming experiences and the ability to play on multiple devices.
Growth in the market is driven by increasing consumer preference for digital gaming experiences over traditional console or PC gaming. Among the segments, Game Streaming Services represent the largest share, reflecting strong demand for subscription-based models that provide extensive game libraries and easy access. The market is expanding rapidly, with the smartphone segment expected to experience the highest growth rate, attracting a broad audience of mobile gamers.
Factors including the rise in mobile broadband usage contribute significantly to market expansion. Enhanced internet connectivity allows consumers to enjoy high-quality gaming experiences without the need for physical gaming consoles or PCs. This shift towards mobile and cloud-based solutions positions the Switzerland Cloud Gaming market for substantial growth in the coming years.
Investment in the Switzerland Cloud Gaming market primarily originates from consumers seeking enhanced gaming experiences through cloud-based services. The market provides access to a diverse range of games without the requirement for expensive hardware, appealing to various demographics, including casual gamers and enthusiasts. The convenience of gaming on multiple devices, including smartphones, desktops, and smart TVs, drives significant spending among users.
Growth in the market is propelled by increasing internet speeds and improved streaming technologies, enabling smooth gameplay experiences. Game streaming services represent the segment with the highest value, projected to expand significantly through 2033. Switzerland leads in adoption due to high broadband penetration rates and a tech-savvy population, which creates strong demand for cloud gaming solutions.
The market thrives on the rising trend of subscription-based models, which provide users with flexible access to numerous games. This model allows consumers to enjoy a variety of titles without the upfront costs associated with traditional gaming. The focus on subscription fees as a primary revenue source reflects the shift in consumer preferences and supports sustained market growth.
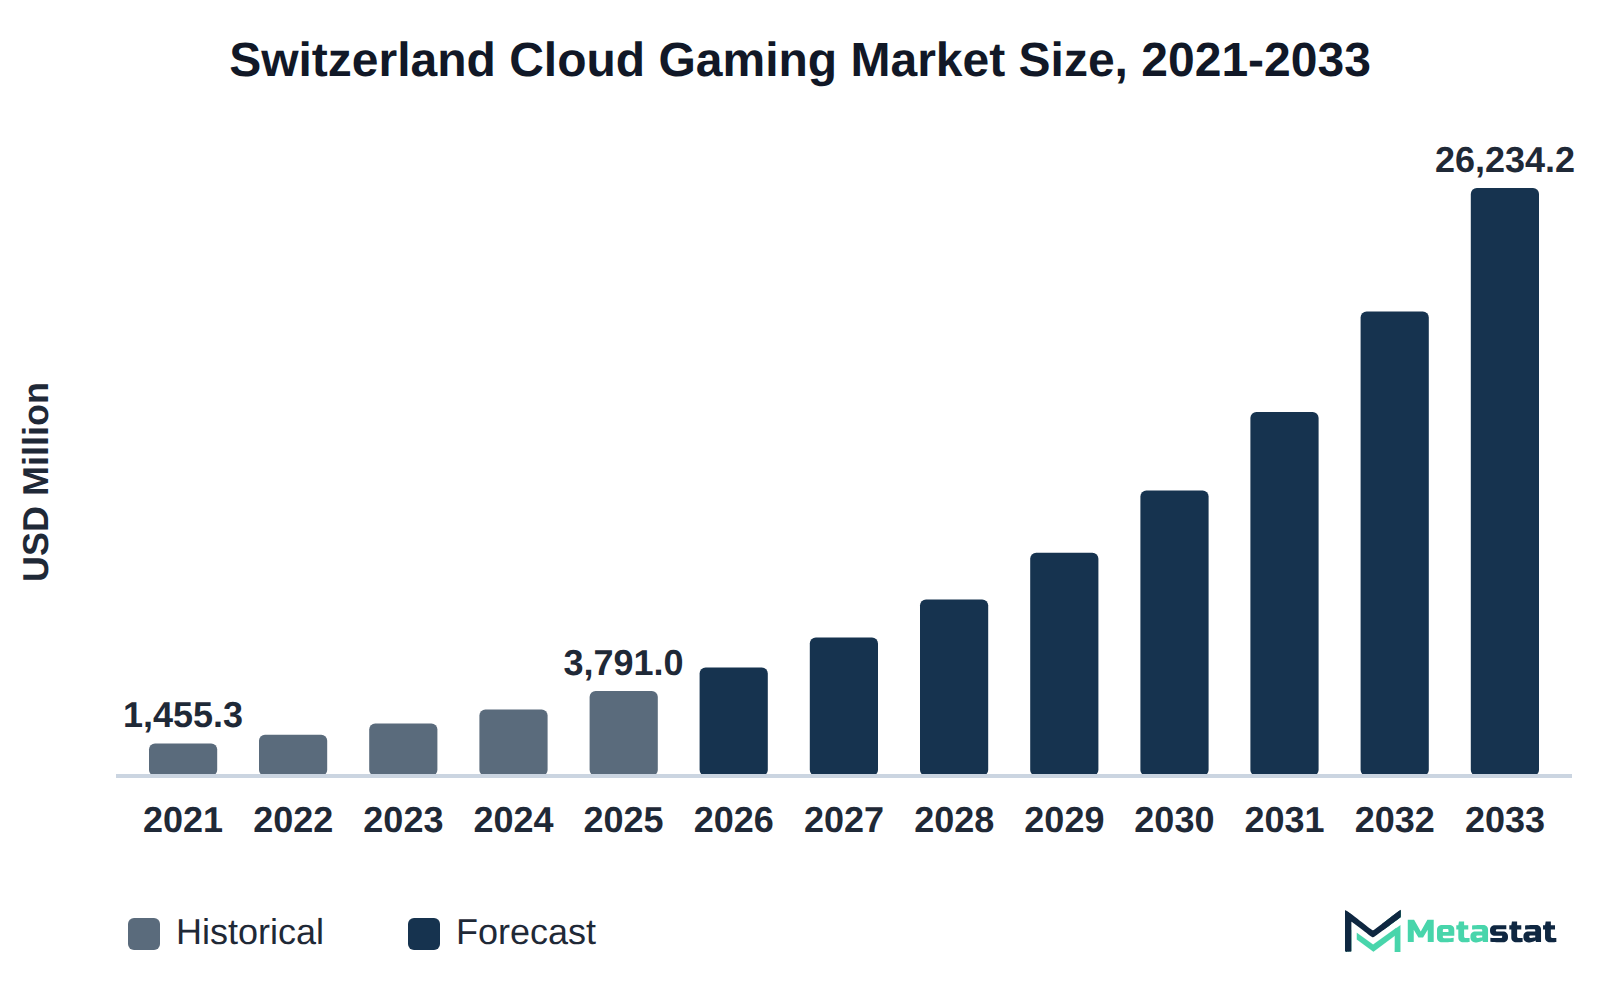
Cloud gaming subscription pricing influences user adoption and revenue generation within the Switzerland Cloud Gaming market. With the growing demand for smooth gaming experiences, service providers focus on competitive pricing strategies. Subscription fees for cloud gaming services are projected to grow from USD 3,748.6 million in 2026 to USD 19,313.6 million by 2033, reflecting a CAGR of 26.4%. This significant increase demonstrates the market's emphasis on delivering value through attractive pricing models.
Telecom bundles represent a vital approach to enhancing the attractiveness of cloud gaming subscriptions. By integrating cloud gaming services into mobile and fixed broadband plans, providers offer compelling packages that appeal to consumers. This strategy aligns with the projected growth of mobile broadband revenue, which is expected to reach USD 6,920.6 million by 2033, supported by a CAGR of 30.2%. Telecom bundles enable service providers to penetrate different consumer segments, driving user acquisition and retention.
The convergence of cloud gaming subscription pricing and telecom bundles results in enhanced value propositions for consumers, making gaming more accessible. This approach leads to increased investment in cloud gaming infrastructure and technology, thereby accelerating market growth. Optimizing pricing strategies and using telecom partnerships helps stakeholders succeed in the Switzerland Cloud Gaming market.
Cloud gaming on Smart TVs and handheld devices involves diverse pricing and contract models that influence buyer behavior in the Switzerland Cloud Gaming market. This model offers users an accessible entry point, enabling them to experience a range of games without the need for high upfront hardware investments.
Usage-based fees provide another purchasing option, allowing users to pay according to the actual time spent gaming. This model caters to casual gamers who prefer flexibility over commitment. Such pricing structures encourage broader adoption across various demographics, including younger audiences who embrace mobile gaming and smart TV gaming. The anticipated growth in usage-based fees, projected to reach USD 4,415.2 million by 2033, illustrates the rising trend of pay-per-play models within the market.
The commercial implications of these pricing strategies extend beyond immediate sales. They increase engagement and retention, driving revenue growth and expanding the overall user base. These developments position the Switzerland Cloud Gaming market for expansion, with competitive pricing and flexible contracts appealing to a broader spectrum of consumers.
In the Switzerland Cloud Gaming market, expanding game licensing rights significantly influences the breadth of available content for consumers. Growth in the game streaming services segment, projected to reach USD 22,986.4 million by 2033, highlights the importance of diverse titles for attracting and retaining subscribers. Game developers across the broader gaming industry increasingly recognize the value of licensing agreements to enhance their visibility and revenue potential, aligning with the growing demand for an extensive library of games.
Platforms compete for user engagement. Securing exclusive titles becomes a key strategy. Established players including NVIDIA Corporation and Microsoft Corporation actively pursue partnerships with game publishers, enabling access to popular franchises and new releases. This strategy diversifies the gaming library and raises the platform’s status, making it more appealing to potential users.
This trend reflects the commercial advantage of offering a rich selection of games to meet the preferences of various demographics. A well-rounded game library enhances user satisfaction, driving higher retention rates and stimulating market growth.
High-speed internet is essential for optimal cloud gaming experiences. Typically, a minimum download speed of 15 Mbps is recommended for basic cloud gaming. However, for an uninterrupted experience with high-definition graphics, speeds of 25 Mbps or higher prove beneficial. In the Switzerland Cloud Gaming market, demand for game streaming services is increasing and is expected to grow from USD 4,156.9 million in 2026 to USD 22,986.4 million by 2033. This growth highlights the need for reliable internet connections.
The correlation between internet speed and user satisfaction becomes more pronounced with higher speeds. For instance, latency becomes a significant factor impacting gameplay, particularly in competitive titles. Gaming and network optimization solutions address this latency concern by improving network performance for players. A stable internet connection minimizes lag and enhances overall performance, which influences customer retention in the market. Consequently, investing in superior internet infrastructure supports both service providers and consumers as cloud gaming grows, enabling immersive gaming experiences.
Consumer preferences have shifted towards cloud gaming services, significantly increasing spending. Gamers increasingly seek convenient and accessible gaming experiences that do not require expensive hardware investments. This trend leads to heightened demand for game streaming services, which cater directly to this demographic. The market anticipates a substantial expansion, with revenue from game streaming services projected to reach USD 22,986.4 million by 2033, reflecting a compound annual growth rate of 27.7%. The surge in consumer interest raises both subscription volume and overall market value, illustrating a transformation in gaming consumption patterns. This shift indicates a clear opportunity for service providers to enhance their offerings and capture a growing audience prioritizing flexibility and affordability.
The expansion of cloud gaming service offerings significantly influences the Switzerland Cloud Gaming market. Diverse services, including game streaming and cloud gaming PC options, cater to various user preferences and skill levels. This variety captures a wider audience and enhances user retention, with gamers exploring different titles and experiences without the financial burden of high-end hardware. Competitive pricing strategies among service providers play a vital role in attracting users. By offering flexible subscription models and promotional discounts, companies entice several consumers who have previously hesitated to switch from traditional gaming methods. This collective approach to service diversification and strategic pricing boosts overall market growth, enabling increased revenue generation. As the market continues to evolve, maintaining a broad service portfolio becomes essential for providers aiming to sustain their competitive advantage and drive long-term adoption.
High subscription costs present a significant barrier for potential buyers in the Switzerland Cloud Gaming market, particularly among budget-conscious consumers. These elevated fees lead to slower market uptake and reduced engagement from users, especially those unfamiliar with cloud gaming services. Affordability influences purchasing decisions, particularly for casual gamers who prefer lower-cost entertainment options. In addition, the availability of free-to-play alternatives further complicates the decision-making process, with consumers weighing the value of subscription-based services against no-cost gaming options. The impact of these pricing challenges manifests in smaller orders and a reluctance to commit to long-term gaming subscriptions. Potential buyers delay entry into the market until pricing structures become more competitive or favorable. This dynamic ultimately restricts overall growth potential within the market and highlights the importance of addressing these pricing concerns to stimulate broader adoption.
Talent costs pose a significant challenge within the Switzerland Cloud Gaming market, impacting the ability of suppliers to deliver services efficiently and profitably. The growing complexity of cloud gaming technology and the demand for skilled professionals in game development and streaming infrastructure raise operational costs. Suppliers face pressure to attract and retain talent in a competitive job market, where expertise in cloud computing, game design, and user experience has become essential. This situation often leads to increased billing rates and a need for efficient resource allocation.
In response, suppliers implement strategies aimed at optimizing workforce efficiency and enhancing employee training programs. Many firms invest in automated systems and cloud services to streamline operations, reducing reliance on highly skilled personnel for routine tasks. This approach reduces operational costs while maintaining service quality. The shift towards developing in-house talent and remote work opportunities supports the competitive positioning of suppliers within the market and addresses the talent cost challenge effectively.
Game streaming services represent a significant growth opportunity within the market, particularly with a compound annual growth rate (CAGR) of 27.7% projected from 2026 to 2033. This segment addresses the increasing demand for accessible gaming experiences without the necessity for high-performance hardware. Factors including the rise of mobile gaming and the popularity of subscription-based models contribute to its expansion. The projected revenue for game streaming services is expected to reach USD 22,986.4 million by 2033, illustrating the lucrative potential for providers operating in the Switzerland Cloud Gaming market. The consumer base increasingly favors flexible, on-demand gaming options that cater to diverse preferences, highlighting the importance of innovation in service delivery. The adaptability of these services in supporting various devices enhances their appeal, reinforcing their position as a key driver of market dynamics.
The Switzerland Cloud Gaming market is segmented based on Service Type, Device Type, Revenue Source, and Access Network.
This segment enables gamers to access and play video games via streaming, eliminating the need for high-performance hardware. It primarily attracts consumers seeking flexibility and convenience in gaming. The rising demand for accessible gaming experiences fuels this segment's growth, positioning it as a leading choice among various service types. Growth in this area outpaces the Cloud Gaming PC Services segment, which shows a CAGR of 25%. Increasing smartphone penetration and enhanced internet connectivity further support the expansion of game streaming services, driving revenue through a subscription-based model. The growing number of titles available for streaming enhances the appeal, establishing a strong market presence that distinguishes it from the other segments in this group.
Cloud Gaming PC Services segment is estimated to reach USD 3,247.8 million by 2033, at a CAGR of 25% during the forecast period. This segment primarily enables users to access and play video games on remote servers, alleviating the necessity for high-end local hardware. Gamers, particularly those seeking flexibility and convenience, access these services for high-quality gameplay without the associated costs of owning powerful PCs. Demand increases due to the growing preference for subscription-based models and the rising availability of diverse gaming options, attracting a wider audience. Compared to other segments, including Game Streaming Services, the growth rate in Cloud Gaming PC Services remains slightly lower. However, it maintains substantial revenue potential, anticipating a shift in consumer spending dynamics within the Switzerland Cloud Gaming market.
Desktops and Laptops segment is valued at USD 1,610.4 million in 2026 and is projected to reach USD 7,592.2 million by 2033, at a CAGR of 24.8% during the forecast period. This segment primarily serves gamers seeking a versatile platform for accessing cloud gaming services, enabling high-quality gameplay without investing in expensive hardware. The increasing availability of high-speed internet and growing consumer preferences for digital gaming experiences drive demand in this segment. Compared to other device segments, including Smartphones, which exhibit a CAGR of 27.9%, Desktops and Laptops experience moderate growth but offer a robust user experience for more demanding gaming applications. The segment's unique positioning appeals to dedicated gamers who prioritize performance and graphics, distinguishing it from mobile-centric gaming solutions.
The smartphones segment is estimated to reach USD 7820.4 million by 2033, at a CAGR of 27.9% during the forecast period. This segment appeals to mobile gamers who prefer gaming experiences on handheld devices, facilitating gaming on the go. The surge in smartphone ownership and advancements in mobile network infrastructure drive demand, allowing consumers to engage with high-quality gaming content without the need for dedicated gaming hardware. This segment differs from others in the Device Type group, exhibiting faster growth due to its accessibility and convenience. In contrast, the desktops and laptops segment, while substantial, experiences a lower CAGR of 24.8% during the same forecast period. The smartphones segment caters to a wider audience, comprising casual gamers and younger demographics who prioritize mobility and ease of access when choosing gaming platforms. The dynamic nature of mobile gaming reshapes consumer preferences, positioning this segment as a key player in the Switzerland Cloud Gaming market.
The Smart TVs and TV Streaming Devices segment is expected to reach USD 4,622.5 million by 2033. This segment serves users seeking convenient and high-quality gaming experiences directly on their television without the need for additional hardware. The primary demand driver stems from the increasing popularity of streaming services and the integration of cloud gaming capabilities in smart TVs. Compared to other device types, the growth rate for this segment stands out with a compound annual growth rate (CAGR) of 27.9%, reflecting a faster adoption trajectory than desktops and laptops, which achieve a CAGR of 24.8%. The accessibility of these devices allows a broad range of consumers to engage with cloud gaming, differentiating it from other segments that rely on more specific hardware requirements. In the market, this segment attracts users interested in flexible entertainment options, blending gaming with traditional media consumption.
Home Gaming Consoles segment is projected to grow at a CAGR of 25.1% during the forecast period. This segment appeals to gamers who prefer dedicated hardware for immersive gaming experiences. Frequent upgrades in console technology support this demand, enabling access to advanced gaming titles with enhanced graphics and performance. Unlike other device types, Home Gaming Consoles attract buyers seeking high-quality gaming experiences without the need for additional purchases like high-performance PCs. The ability to play exclusive titles often drives consumer interest. Compared to the Smartphones segment, which is expected to grow at a CAGR of 27.9%, Home Gaming Consoles experience slower growth. However, dedicated gaming consoles maintain a loyal user base that values the unique gaming experience offered, distinguishing this segment within the broader context of the Switzerland Cloud Gaming market.
Tablets are versatile devices that enhance the cloud gaming experience for players seeking portability and convenience. Gamers frequently use tablets for mobile gameplay, allowing them to engage with gaming content anywhere with an internet connection. The segment faces unique dynamics, driven by increasing demand for mobile gaming solutions and the necessity for high-quality streaming services. Compared to other device types, the segment stands out due to its adaptability and accessibility. This distinguishes it from platforms like desktops and laptops, which cater to more traditional gaming experiences. Price sensitivity remains a critical aspect, influencing consumer choices and adoption rates. Tablets typically offer a balance between performance and affordability, attracting a diverse user base that includes casual gamers and dedicated enthusiasts. Factors including improvements in wireless technology and enhanced user interfaces further support the segment's development in the Switzerland Cloud Gaming market.
Handheld gaming devices serve a vital role in the gaming ecosystem, appealing to users who value portability and convenience. These devices attract consumers who prefer gaming on-the-go, allowing access to a variety of games without the constraints of traditional gaming setups. Demand for handheld gaming devices is driven by trends in mobile gaming and the increasing availability of cloud gaming services. These devices differ from other segments, including desktops and laptops, where users typically seek more robust performance and larger screens. The focus on immersive gaming experiences on handheld devices results in slower growth compared to other segments. However, innovations in technology, including improved battery life and enhanced user interfaces, support sustained interest among consumers in the Switzerland Cloud Gaming market.
Virtual reality (VR) headsets enable immersive gaming experiences, appealing to a distinct group of consumers seeking high engagement levels. Players who desire realistic interactions and environments engage with these devices, enhancing their gaming experience. The growing popularity of VR technology drives demand in this segment, with innovations in hardware and software continuously attracting interest. Compared to other device types, VR headsets typically require higher investments, which narrows their audience base. However, strong growth potential exists in this sub-segment due to increasing interest from developers creating exclusive VR content. Within the market, demand for VR gaming experiences contrasts with the broader appeal of more accessible devices including smartphones and desktops, defining its unique position.
This segment caters primarily to gamers who prefer predictable pricing structures for their cloud gaming experiences. The rise in demand for subscription-based models stems from users seeking affordable access to a wide variety of games without the burden of significant upfront costs. Unlike advertising revenue, which relies heavily on user engagement and content promotion, subscription fees provide a more stable revenue stream for service providers. This segment stands out with its significant growth potential compared to Usage-Based Fees, which experiences a CAGR of 29.1%. The increasing willingness to pay for uninterrupted gaming experiences drives growth in the market.
Usage-Based Fees segment is estimated to reach USD 4,415.2 million by 2033, at a CAGR of 29.1% during the forecast period. This segment appeals to consumers favoring flexible payment options tied to their actual usage of gaming services. Such a model attracts budget-conscious gamers who hesitate to commit to fixed subscription fees. Strong growth in this segment is driven by increased demand for accessible gaming experiences, particularly among younger demographics valuing cost-effective solutions. Compared to Subscription Fees, which are projected to grow at a CAGR of 26.4%, Usage-Based Fees exhibit faster growth, reflecting a shift towards more adaptable payment structures. The flexibility inherent in this approach enhances its appeal, increasing engagement levels among consumers while contributing positively to overall market momentum.
Advertising Revenue segment is expected to reach USD 2,505.4 million by 2033. This revenue source comprises income generated from digital advertising placed within cloud gaming platforms. Game developers and service providers leverage this segment to monetize their offerings, appealing primarily to advertisers targeting gaming audiences. The segment's growth is driven by increasing interest from brands seeking to engage younger demographics, who frequently use these platforms. Compared to other revenue sources including subscription fees, advertising revenue exhibits slower growth, reflecting a compound annual growth rate (CAGR) of 29.1%. In contrast, subscription fees are projected to grow at a CAGR of 26.4%. This dynamic creates a competitive environment where innovative advertising strategies enhance user engagement, providing an opportunity for advertisers to reach a captive audience effectively.
This segment primarily supports gamers who require stable and high-speed internet connections for optimal gaming experiences. Increased demand for high-quality gaming content drives growth in this segment, with players seeking faster download speeds and lower latency. Compared to other access networks, Fixed Broadband experiences significant growth due to its capability to deliver consistent performance, while Mobile Broadband follows with higher flexibility but lower speed. The need for immersive and responsive gaming experiences makes Fixed Broadband a core component of the Switzerland Cloud Gaming market. It drives significant investment and development in the infrastructure necessary for advanced cloud gaming services.
This segment serves users looking for high-speed internet access for gaming on the go. With the increasing prevalence of mobile devices and the demand for flexible gaming experiences, mobile broadband enables users to play games seamlessly anywhere. The rapid expansion of mobile networks enhances user engagement, significantly impacting adoption rates. Compared to Fixed Broadband, this segment experiences faster growth, driven by a CAGR of 30.2% against Fixed Broadband's 26.4%. Competition among service providers fuels investments in infrastructure improvements, resulting in enhanced service quality and broader market reach. This trend highlights the growing importance of mobile access in the Switzerland Cloud Gaming market.
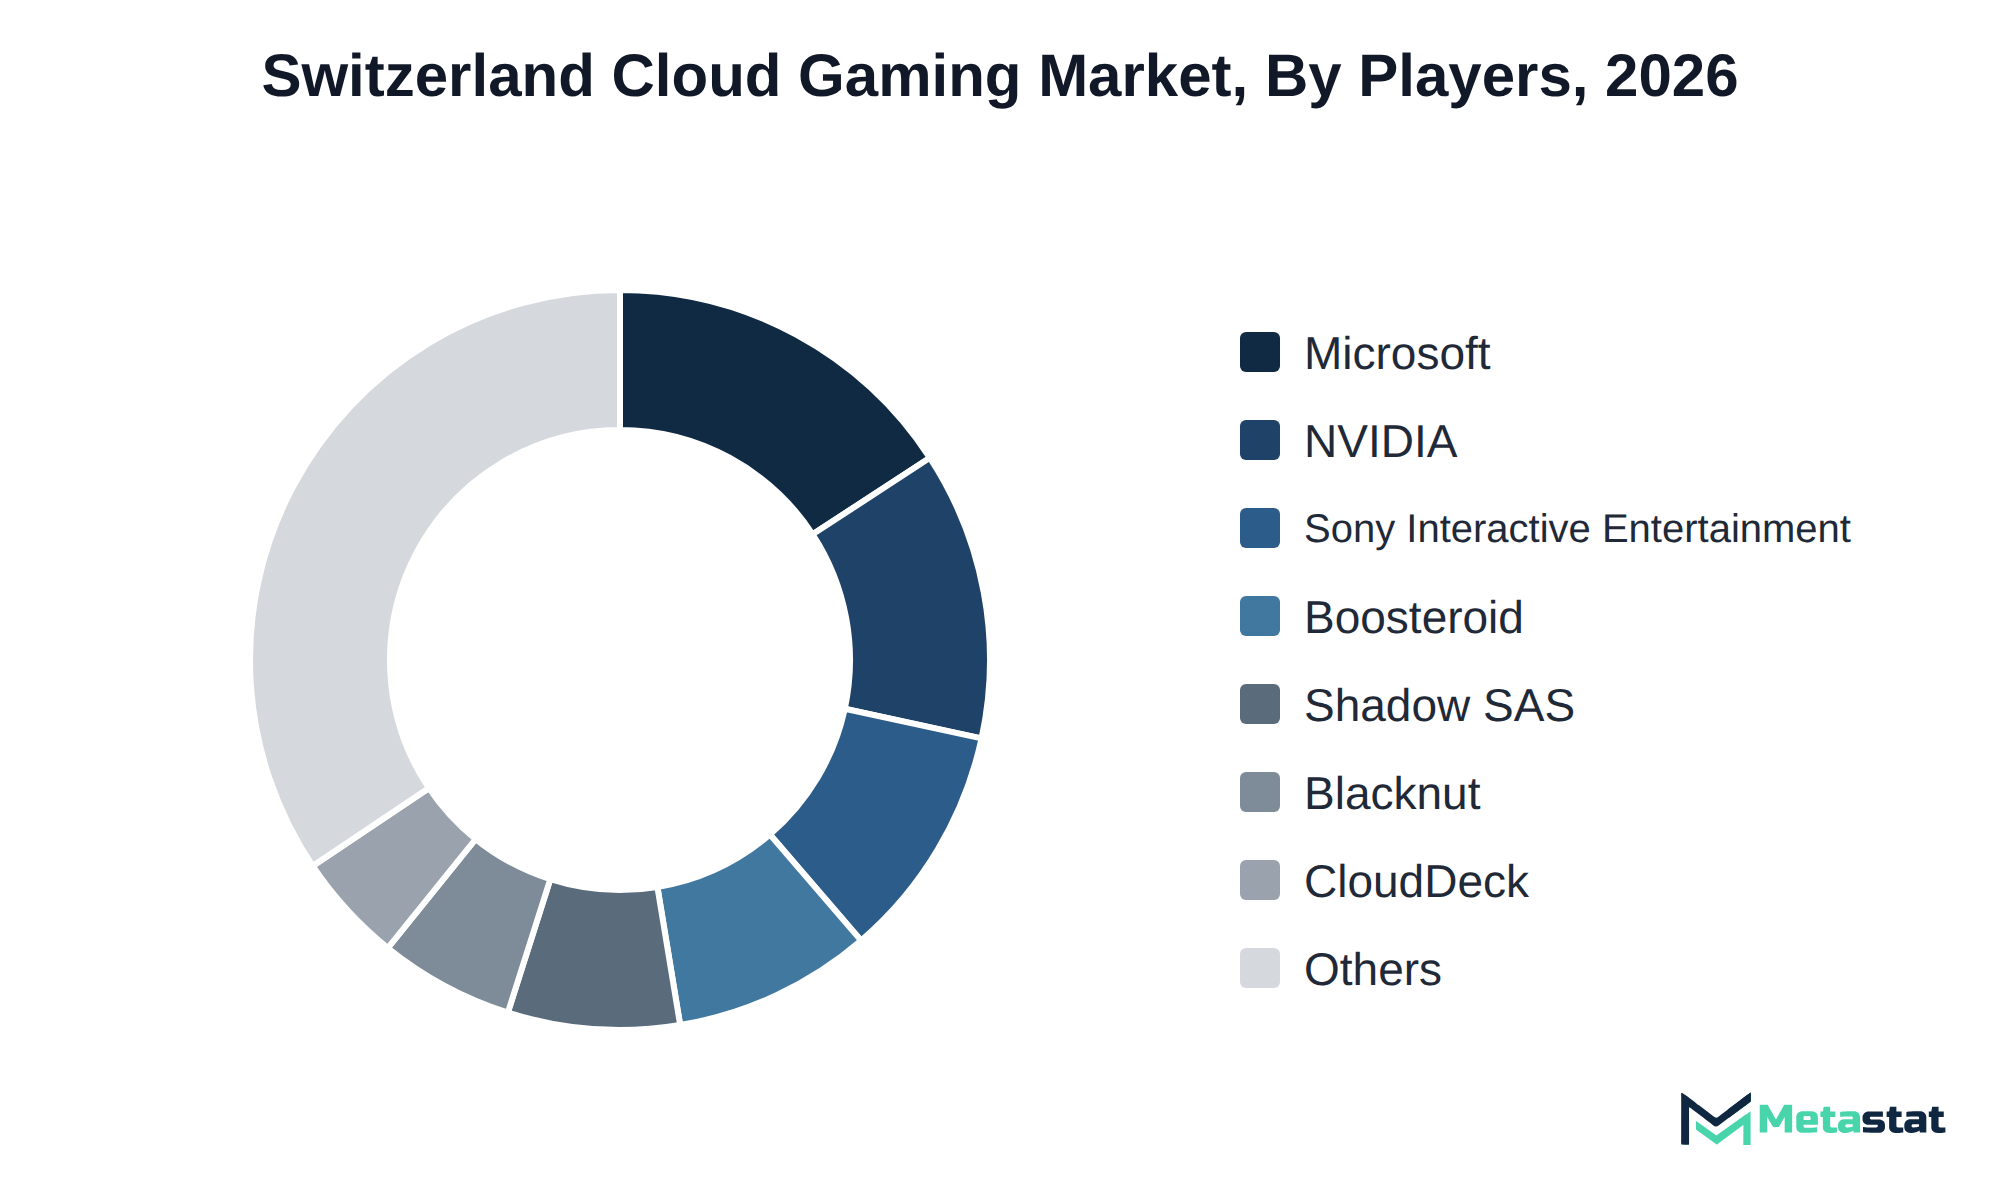
The Switzerland Cloud Gaming market features a diverse set of companies competing across various service types and device categories. Companies differentiate themselves by focusing on distinct offerings, including game streaming services and cloud gaming PC services. Pricing strategies, user experience, and ecosystem integration influence buyer decisions.
NVIDIA Corporation and Microsoft Corporation emphasize strong gaming ecosystems, giving consumers broad access to gaming titles through subscription models. Sony Interactive Entertainment LLC focuses on integrating its gaming consoles with cloud services, enhancing user engagement through exclusive content. Boosteroid and Blacknut cater to niche segments by offering innovative subscription-based models, while Shadow SAS targets users seeking high-performance cloud gaming experiences.
Companies leverage various device types to capture market segments, including desktops, laptops, and smartphones. For instance, Netflix, Inc. extends its service to mobile devices, tapping into the growing demand for on-the-go gaming experiences. Antstream Ltd concentrates on retro game streaming, attracting a dedicated user base interested in classic titles. CloudDeck positions itself to serve emerging markets by emphasizing affordability and accessibility across a range of devices.
The projected growth relies on several key developments in the Switzerland Cloud Gaming market. A significant increase in mobile broadband access will drive user engagement, with revenue anticipated to reach USD 6,920.6 million by 2033. However, risks exist that could impede progress. Significant infrastructure limitations restrict market penetration, particularly in regions with underdeveloped broadband access. These factors hinder the overall growth trajectory, impacting the market's ability to achieve the forecasted USD 26,234.2 million by 2033.
By Service Type: Game Streaming Services, Cloud Gaming PC Services
By Device Type: Desktops and Laptops, Smartphones, Smart TVs and TV Streaming Devices, Home Gaming Consoles, Tablets, Handheld Gaming Devices, Others (VR Headsets)
By Revenue Source: Subscription Fees, Usage-Based Fees, Advertising Revenue
By Access Network: Fixed Broadband, Mobile Broadband
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Cloud Gaming market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 27.3% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Service Type, Device Type, Revenue Source, Access Network, and Region |
Find answers to common questions about this report
The Cloud Gaming market size was valued at USD 3,791 million in 2025.
The market is projected to grow at a CAGR of 27.3% during the forecast period from 2026 to 2033.
Game Streaming Services leads the Cloud Gaming market with a projected value of USD 22,986.4 million by 2033, significantly surpassing other segments. This segment demonstrates a compound annual growth rate of 27.7 percent during the forecast period.
Consumer preferences have shifted towards cloud gaming services, driving increased demand for game streaming options that offer convenience and accessibility without expensive hardware investments. Competitive pricing strategies among service providers attract users, enhancing market growth and encouraging wider adoption.
High subscription costs present a significant barrier for potential buyers, particularly among budget-conscious consumers. Talent costs challenge suppliers' ability to deliver services efficiently, impacting operational costs and service quality. These factors restrict overall growth within the Switzerland Cloud Gaming market.
Consumer preferences for flexible and affordable gaming experiences drive adoption in the Switzerland Cloud Gaming market. The increasing popularity of game streaming services, alongside competitive pricing strategies, enhances user engagement and attracts a broader audience seeking accessible gaming options.
The Cloud Gaming market is estimated to reach a valuation of USD 26,234.2 million by 2033.
Key players operating in the Cloud Gaming market include NVIDIA Corporation, Microsoft Corporation, Sony Interactive Entertainment LLC, Boosteroid, Blacknut, Shadow SAS, Netflix, Inc., and Antstream Ltd.
The Cloud Gaming market includes game streaming services and cloud gaming PC services, catering to diverse user preferences and skill levels.
Revenue from cloud gaming PC services is expected to reach USD 3,247.8 million by 2033, reflecting significant growth potential.
The analysts below cover Information & Technology research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Scaling antibody-drug conjugate manufacturing hinges on contract manufacturing availability for high-potency active ingredients. The MetaStat Insight analysis looked closely at global cleanroom slot constraints, bioconjugation batch failure rates, and supply chain redundancies between the US, Europe, and India. The supplier capability matrix proved genuinely useful for our team when mapping secondary source options across our clinical pipeline.
Floating offshore wind feasibility relies heavily on specialized installation vessel availability and port crane limits, which most broad renewable energy forecasts ignore. The report delivered a thorough analysis of dry dock capacity, mooring chain supply constraints, and raw material pricing trends for deepwater anchor installations. It served as a solid independent sanity check for our offshore project capital expenditure assumptions.
Assessing commercial microgrid software adoption requires looking past top-level installation numbers and examining utility interconnection queues. The research provided verifiable data on average permitting timelines, tariff structures, and battery storage integration costs across regional utility territories. That grounded perspective was valuable for our team when building five-year demand projections for industrial microgrid controllers.
Explore related market intelligence reports worth reading alongside this one.