
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global DWDM Optical Transport Equipment Market Size, Share, By Equipment Type (Integrated DWDM Transport Systems, Optical Transponders, Optical Muxponders, DWDM Multiplexers and Demultiplexers, Reconfigurable Optical Add-Drop Multiplexers (ROADMs), Optical Amplifiers), By Network Topology (Point-to-Point Networks, Linear Add-Drop Networks, Ring Networks and Mesh Networks), By Application (Data Center Interconnect (DCI), Metro and Regional Optical Transport, Long-Haul and Ultra-Long-Haul Transport, Submarine Optical Transport, Mobile Fronthaul and Backhaul, Enterprise and Campus Network Interconnection), By End User (Telecommunications Operators and Internet Service Providers, Cloud and Colocation Data Center Operators, Enterprise Network Operators, Government and Defense Organizations, Power and Utility Companies, Railway and Transportation Operators, Cable Television and Broadcasting Operators), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-5477
Published
October, 2026
Pages
269 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
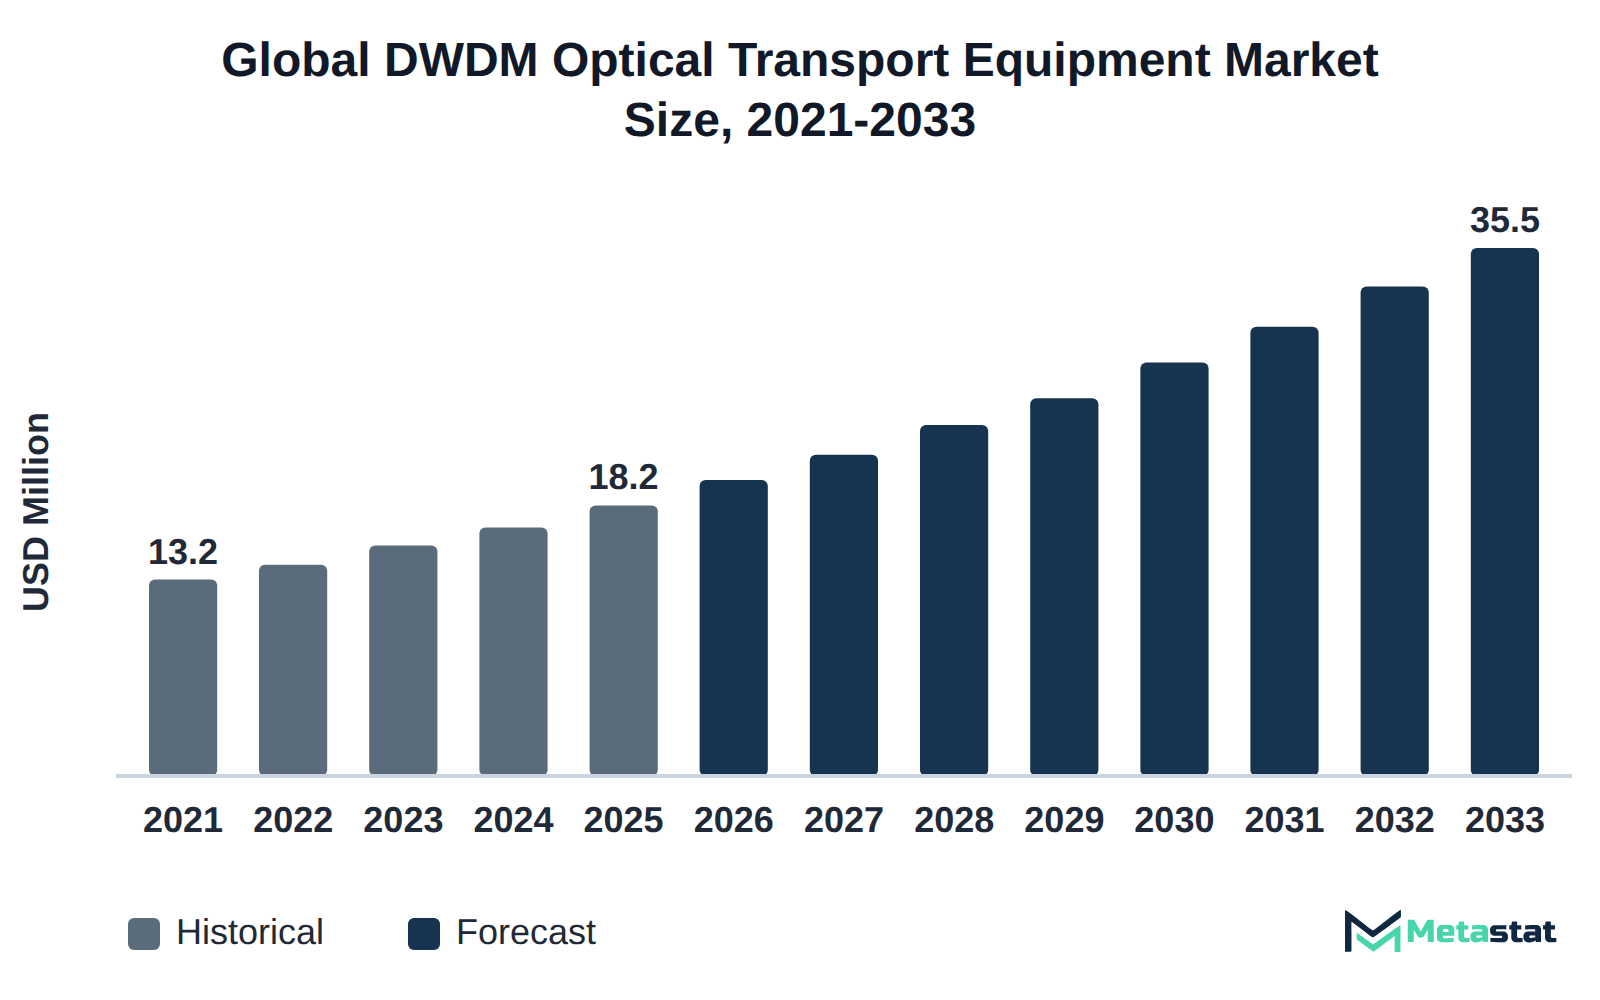
Market Valuation: Valued at $18.2 Million in 2025, projected to reach $35.5 Million by 2033 at a 8.7% CAGR.
Dominant Segment: Integrated DWDM Transport Systems lead the market, driven by the increasing need for higher bandwidth and efficient data transmission among telecommunications operators and Internet service providers.
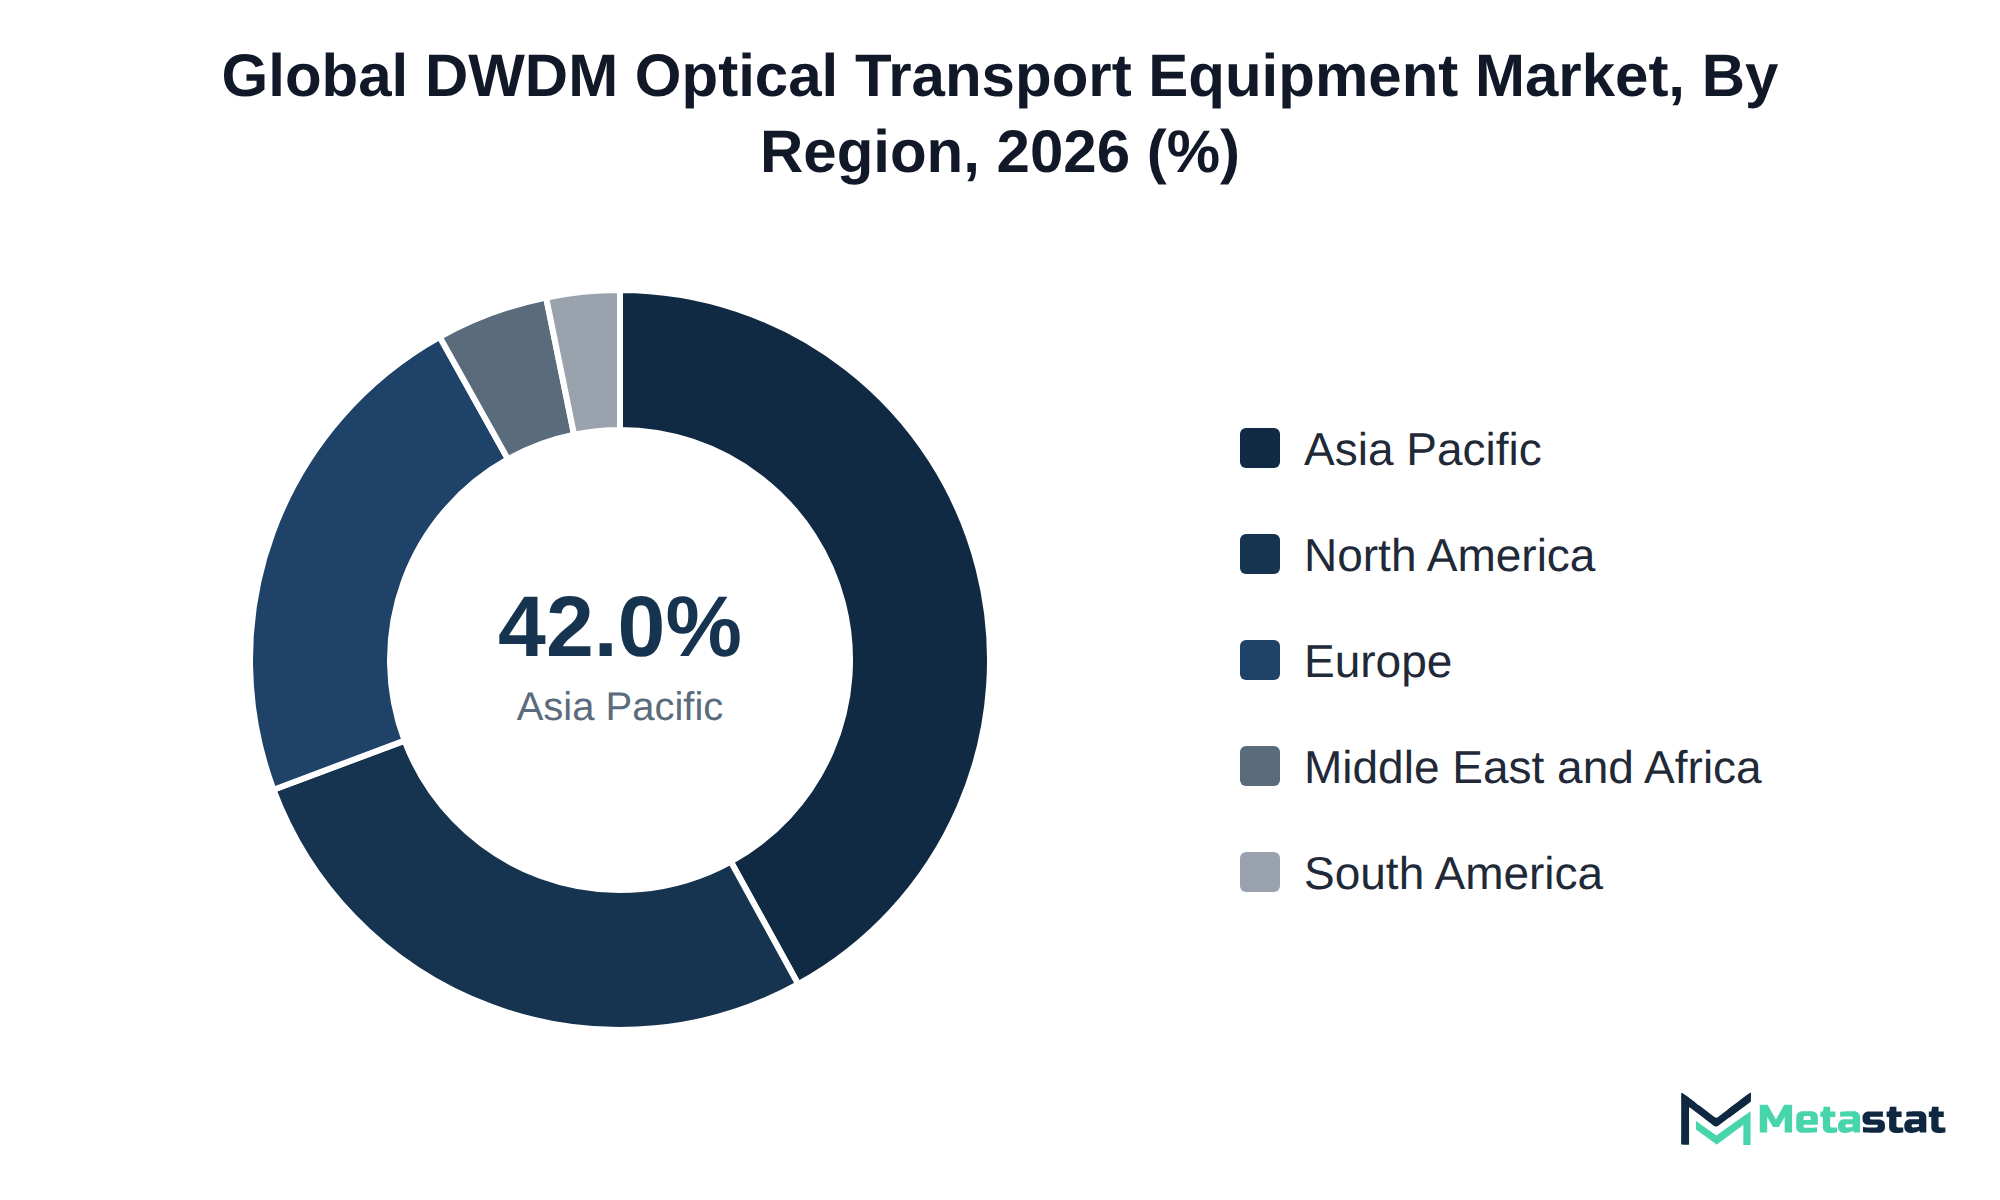
Geographic Lead: The Asia Pacific region commands the largest market share at 42%, fueled by rapid infrastructure development and rising data traffic in emerging markets.
What's Inside: The report provides a comprehensive analysis of market dynamics, competitive landscape, and detailed forecasts from 2026 to 2033, covering various equipment types and applications.
Data Center Interconnect Growth Potentia: The Data Center Interconnect (DCI) segment exhibits the highest growth potential, projected to grow at a CAGR of 11.6% by 2033, driven by the increasing demand for efficient connectivity between data centers.
Cost-effective Optical Components Drive: Advancements in cost-effective optical components are enhancing affordability and accessibility, supporting growth in the DWDM Optical Transport Equipment market.
Choose Your License
Global DWDM Optical Transport Equipment Market
The global DWDM Optical Transport Equipment market was valued at USD 18.2 million in 2025 and is projected to reach USD 35.5 million by 2033, growing at a CAGR of 8.7% over the forecast period.
The DWDM Optical Transport Equipment market encompasses various products and technologies designed to enhance data transmission over optical fibers. Buyers invest in these solutions to address the increasing demand for high-capacity bandwidth and reliable connectivity. Telecommunications operators, Internet service providers, and data center operators are the primary purchasers, driven by the need for efficient data handling and strong network performance.
Growth in the market stems from several factors, particularly the rising demand for data center interconnect (DCI) solutions. This segment is projected to capture significant value, reflecting the industry's shift toward more robust networking capabilities. North America holds 27.3% of the market in 2025, with the US leading in 2026. The Asia Pacific region, however, commands the largest share at 42%, reflecting a strong focus on infrastructure development and expanding telecommunications networks in emerging markets.
The increasing reliance on cloud services and digital transformations across industries further fuels market demand. Enhanced connectivity solutions support businesses in optimizing operations and improving service delivery. Organizations seek to adapt to the evolving technological landscape, and investments in DWDM optical transport equipment will play a critical role in achieving operational excellence.
The DWDM Optical Transport Equipment market includes advanced systems and components that facilitate high-capacity data transmission. Buyers invest in these technologies to enhance network efficiency, support growing data demands, and maintain competitive advantages in the telecommunications and data center sectors. The increasing reliance on cloud computing and the proliferation of high-bandwidth applications drive significant expenditure in this market.
Growth in the market is propelled by the increasing demand for integrated solutions that support higher data rates and improved network performance. Integrated DWDM Transport Systems represent the largest segment by value, reflecting a strong preference among operators for streamlined, high-capacity systems. North America holds 27.3% of the market in 2025, with the US leading in 2026, indicating a robust investment environment in this region.
Investment in related infrastructure and advancements in optical technologies further support growth. The Asia Pacific region, accounting for 42% of the market, exhibits rapid expansion fueled by increasing internet penetration and rising data traffic. The need for efficient data management solutions drives operators to adopt DWDM systems, facilitating enhanced connectivity and performance across diverse applications.
Coherent 800G transmission technology and pluggable optics are transforming the DWDM Optical Transport Equipment market by enhancing bandwidth efficiency and network flexibility. The increasing demand for data capacity among telecommunications operators and internet service providers drives this technological shift. With a CAGR of 7.6% projected for the telecommunications sector from 2026 to 2033, the impact of these advancements is expected to be significant.
This technology enables higher data rates over existing fiber infrastructure, allowing for a more cost-effective upgrade path compared to deploying new fiber. Coherent 800G solutions deliver robust performance while simplifying network design, which appeals to service providers striving for operational efficiency. The integration of pluggable optics further complements this shift by providing flexibility in network configurations and reducing time to deployment.
The adoption of coherent 800G transmission and pluggable optics strengthens competitive positions for companies within the DWDM Optical Transport Equipment market, positioning them to meet the growing demands of high-capacity networks. This evolution enhances overall network performance and supports increased investment in future-proofed optical systems.
The growing demand for Data Center Interconnect (DCI) solutions significantly influences pricing strategies in the DWDM Optical Transport Equipment market. DCI applications, projected to increase from USD 4.8 million in 2026 to USD 10.4 million by 2033, highlight the need for flexible and scalable pricing structures. This rising demand encourages suppliers to adopt value-based pricing models, allowing them to align costs with performance outcomes rather than purely on equipment specifications.
Flexible contract models have emerged in response to diverse customer needs, particularly among telecommunications operators and internet service providers, who represent a substantial buyer group in this market. The trend toward subscription-based or usage-based pricing allows customers to manage costs more effectively while accommodating fluctuating bandwidth requirements. This model reduces upfront capital expenditure and provides a means for clients to scale services in line with growing operational demands.
Such approaches facilitate better cash flow management for buyers, as investments in DWDM Optical Transport Equipment become more predictable and manageable. With anticipated growth driven by advancements in optical transport technologies, these pricing strategies enhance market competitiveness and stimulate further investments in network infrastructure.
Open line systems and reconfigurable optical add-drop multiplexers (ROADMs) significantly influence procurement strategies within the DWDM Optical Transport Equipment market. These technologies provide flexibility and scalability for network operators, enabling efficient management of data traffic and operational costs. The emergence of reconfigurable ROADMs aligns with the growing demand for adaptable network infrastructures, catering especially to telecommunications operators and Internet service providers.
For instance, the segment of integrated DWDM transport systems is expected to grow from USD 6.7 million in 2026 to USD 11.3 million by 2033, reflecting a compound annual growth rate of 7.7%. This growth indicates a shift toward more dynamic network solutions that facilitate rapid deployment and configuration of optical networks. Buyers within this segment, particularly those in high-demand environments, prioritize systems that enhance bandwidth and streamline network provisioning.
Incorporating open line systems and reconfigurable ROADMs addresses the pressing needs of network operators and supports overall market expansion. While these technologies gain traction, procurement strategies increasingly favor equipment that offers operational agility and cost efficiency, positioning buyers to leverage advancements in the DWDM Optical Transport Equipment market.
Telecom operators are implementing advanced technologies to reduce costs in the DWDM Optical Transport Equipment market while simultaneously expanding network capacity. These systems consolidate multiple functions into a single platform, streamlining operations and minimizing the need for additional hardware investments.
The trend towards point-to-point networks supports this cost reduction strategy, with anticipated growth from USD 8.1 million in 2026 to USD 13.6 million in 2033, demonstrating a CAGR of 7.7%. This topology improves efficiency and enhances data transmission by creating direct paths between nodes, reducing latency and operational complexity. By leveraging these integrated solutions and efficient network topologies, telecom operators achieve significant operational savings while expanding capacity to meet increasing demand for high-speed data.
Telecommunications operators and Internet service providers are increasing investments in high-capacity optical transport solutions to support the growing need for data center interconnect (DCI). This shift stems from a substantial rise in data traffic driven by cloud computing, remote work, and the proliferation of Internet of Things (IoT) devices. The DCI segment is projected to achieve a compound annual growth rate of 11.6% by 2033, reaching USD 10.4 million. Such growth reflects a fundamental change in how operators approach network infrastructure, emphasizing the necessity for fast, reliable connections between data centers. The DWDM Optical Transport Equipment market benefits from this heightened demand, leading to increased volume and potentially higher prices for advanced transport solutions. Competition among suppliers accelerates innovation, further enriching the product offerings available in the market.
Advancements in cost-effective optical components drive growth in the DWDM Optical Transport Equipment market. Suppliers optimize their product offerings through innovation and competitive pricing, enhancing affordability and accessibility for telecommunications operators and Internet service providers. The integration of high-performance optical transponders and multiplexers allows for greater flexibility in network design, resulting in improved efficiency and reduced operational costs for end users.
Market participants prioritize the development of scalable technologies that provide enhanced functionality while minimizing expenses. Demand for high-capacity networks accelerates manufacturers' efforts to produce adaptive solutions that meet evolving customer requirements. Continuous improvements in manufacturing processes contribute to lower production costs, facilitating the introduction of advanced optical transport solutions at competitive price points.
The overall impact of these cost-effective optical components leads to expanded market reach and heightened adoption among various end users. Enhanced performance at reduced prices results in increased investment from telecommunications operators and Internet service providers, driving a competitive edge within the market. This trend positions the industry for sustained growth through 2033.
High prices for advanced optical transport equipment present a notable constraint for telecommunications operators and Internet service providers, who typically invest significant capital in network infrastructure. The high costs associated with DWDM Optical Transport Equipment hinder timely upgrades, resulting in slower adoption of newer technologies. This financial barrier leads to smaller orders and delayed equipment replacement cycles, ultimately constraining the overall growth of the market. Operators prioritize cost-effective alternatives or defer investments until budgets allow, impacting network performance and competitiveness. Given the increasing demand for high-capacity data solutions, addressing pricing challenges becomes essential for enabling broader adoption within the telecommunications sector. Without strategies to mitigate the financial impact, the momentum toward advanced optical transport solutions risks stagnation, limiting the potential for innovation and growth within the market.
Data Center Interconnect (DCI) solutions exhibit the highest growth potential within the DWDM Optical Transport Equipment market, driven by increasing data traffic and the growing need for efficient connectivity between data centers. Organizations expand their digital infrastructure, intensifying the demand for robust and scalable optical transport solutions. This growth presents significant opportunities for suppliers focusing on innovative optical transport technologies that enhance bandwidth and reduce latency in data transmission.
The rise of cloud computing and the proliferation of Internet of Things (IoT) applications further support this trend, necessitating advanced networking capabilities to handle large data volumes. Telecommunications operators and cloud service providers prioritize DCI to ensure efficient connectivity and scalability, emphasizing the potential for investment in next-generation optical transport solutions. Expanding this segment within the market is expected to contribute to overall revenue growth while addressing the evolving needs of data-driven businesses.
The Global DWDM Optical Transport Equipment market is segmented based on Equipment Type, Network Topology, Application, and End User.
This segment provides comprehensive solutions for optical transport, primarily used by telecommunications operators and Internet service providers for enhancing network capacity. Demand for these systems rises due to the increasing need for higher bandwidth and efficient data transmission. The growth of cloud services and data centers further fuels this demand, aligning with the segment's focus on high-capacity infrastructure. Compared to other segments, including Optical Transponders, which exhibit a higher CAGR of 9.1%, Integrated DWDM Transport Systems show steady growth driven by established demand patterns and the ongoing need for infrastructure upgrades in telecommunications networks. The unique combination of performance and reliability differentiates this segment from others in the market.
Optical Transponders segment is estimated to reach USD 6.2 million by 2033, at a CAGR of 9.1% during the forecast period. These devices convert optical signals to electrical signals and vice versa, primarily used by telecommunications operators and Internet service providers. The segment experiences robust demand due to increasing needs for higher bandwidth and improved network efficiency. Growth in cloud computing and the adoption of data-intensive applications further increase this demand. In comparison to other segments, Optical Transponders display faster growth driven by technological advancements that allow for higher data rates and better performance. This segment's pricing structure remains competitive, making it attractive for buyers focused on optimizing network infrastructure.
Optical Muxponders segment is expected to reach USD 3.6 million by 2033. This segment enhances data transmission efficiency by enabling multiple signals to be transmitted over a single optical fiber. Telecommunications operators and Internet service providers use optical muxponders to optimize bandwidth usage and reduce costs associated with infrastructure. The growing demand for efficient data handling in various applications drives this segment. Optical Muxponders exhibit a higher expected growth rate compared to other equipment types, supported by a projected CAGR of 9.1%. This growth is propelled by the increasing need for bandwidth in applications including data center interconnect and long-haul transport. Competitive pricing and technological advancements in optical muxponders further differentiate this segment from others, ensuring its relevance in the evolving market of the DWDM Optical Transport Equipment.
DWDM Multiplexers and Demultiplexers segment is projected to grow at a CAGR of 7.4% during the forecast period. This segment facilitates the efficient routing of optical signals within telecommunications networks, primarily used by telecommunications operators and Internet service providers to enhance data transmission capacity. The increasing need for high-speed data services drives demand for these solutions, reflecting a shift toward more complex network architectures. Unlike other equipment types, including Optical Transponders which show a higher growth rate at 9.1%, DWDM Multiplexers and Demultiplexers focus on expanding existing infrastructure rather than introducing entirely new capabilities. This segment's growth reflects the ongoing trend of integrating advanced multiplexing technologies into legacy systems to improve performance while managing costs effectively. The market's evolution indicates a strategic emphasis on optimizing current network resources rather than solely investing in new systems.
Reconfigurable Optical Add-Drop Multiplexers (ROADMs) serve to manage and optimize optical signals in telecom networks. These devices allow operators to add or drop specific wavelengths without disrupting the entire network, providing flexibility and efficiency in data transmission. Telecommunications operators and Internet service providers widely apply ROADMs to enhance network capacity, support diverse applications, and respond to fluctuating bandwidth demands. The demand for ROADMs is driven by the increasing complexity of network architectures and the need for scalable solutions that accommodate growth in data traffic. Compared to other segments, ROADMs demonstrate a significant growth trajectory due to their ability to simplify network management and reduce operational costs. This sub-segment stands out due to technological advancements that enable faster wavelength provisioning and improved service delivery, distinguishing it from traditional multiplexing solutions.
Optical Amplifiers enhance signal strength within fiber optic networks. These devices are essential for telecommunications operators and Internet service providers, facilitating long-distance data transmission without significant loss of quality. Demand for Optical Amplifiers is driven by the increasing need for higher bandwidth and improved data rates in various applications, including data centers and metropolitan networks. The differentiation from other equipment types stems from their specific role in boosting signals rather than multiplexing data or performing routing functions. While Integrated DWDM Transport Systems and Optical Transponders exhibit strong growth, the adoption of Optical Amplifiers occurs at a steadier pace, reflecting their critical yet niche function in the optical transport ecosystem. This steady demand supports growth in the DWDM Optical Transport Equipment market, with operators investing in technologies that enhance overall network performance.
Optical Protection and Monitoring Equipment safeguards the integrity and performance of optical networks. This equipment is used predominantly by telecommunications operators and Internet service providers to monitor signal quality, detect faults, and ensure optimal performance across their networks. The increasing complexity of optical networks drives demand for advanced monitoring solutions that enhance reliability and reduce downtime. Several factors influence this segment, including the rapid expansion of data traffic and the ongoing need for enhanced network resilience. Compared to other segments, Optical Protection and Monitoring Equipment typically faces lower growth rates, driven by its reliance on the broader market's development and the existing infrastructure's adaptation. Investment in this segment focuses on integrating new technologies to improve monitoring capabilities, positioning it uniquely among the different equipment types within the market.
This segment establishes direct connections between two network nodes, primarily serving telecommunications operators and internet service providers that require reliable, high-capacity links for data transmission. Growth in this segment is driven by increasing demand for efficient bandwidth allocation and the expansion of digital services. Compared to other network topologies, Point-to-Point Networks has a more straightforward deployment process, which contributes to its stable growth trajectory. The anticipated growth rate of 7.7% is lower than the 11.6% growth seen in Data Center Interconnect (DCI), highlighting distinct market positioning and differing buyer requirements, focusing primarily on direct connectivity rather than complex interconnections.
Linear Add-Drop Networks segment is estimated to reach USD 4.1 million by 2033, at a CAGR of 7.8% during the forecast period. This topology enables selective addition or removal of specific wavelengths in optical networks, making it particularly useful for telecommunications operators. Increasing demand for flexible and scalable optical transport solutions drives growth in this segment, emphasizing the need for efficient wavelength management. Unlike Point-to-Point Networks, which exhibit a CAGR of 7.7%, Linear Add-Drop Networks provide a more adaptable approach to network architecture. This adaptability attracts operators seeking to optimize bandwidth usage without significant capital expenditure, thereby differentiating it within the DWDM Optical Transport Equipment market. The segment's growth reflects the broader trend of evolving network requirements, aligning with advancements in optical technology and increasing data traffic across various sectors. This adaptability positions Linear Add-Drop Networks as a significant solution in the evolving environment of optical transport.
Ring Networks segment is expected to reach USD 8.7 million by 2033. This topology is employed to create resilient and efficient communication networks, often used by telecommunications operators and Internet service providers. The segment experiences demand driven by the increasing need for reliable and high-speed data transmission. Factors including expanding data traffic from cloud services and the growth of Internet of Things (IoT) applications fuel this trend. Compared to Point-to-Point Networks and Linear Add-Drop Networks, the Ring Networks segment exhibits a lower growth rate. While Point-to-Point Networks experience a CAGR of 7.7%, Ring Networks face competitive dynamics that influence their adoption trajectory. The market reflects ongoing technological advancements and cost optimization strategies that enhance the appeal of Ring Networks in meeting evolving communication needs.
Mesh Networks segment is projected to grow at a CAGR of 11.4% during the forecast period. This topology provides a highly resilient network structure, ideal for dynamic environments that require robust data transmission. Organizations implementing Mesh Networks include telecommunications operators and large enterprises seeking to optimize their connectivity. Increased demand for higher bandwidth and redundancy drives growth in this segment. This structure differs from other network topologies, including Point-to-Point Networks, which exhibit slower growth at a CAGR of 7.7%. The distinct advantages offered by Mesh Networks in terms of reliability and flexibility appeal to buyers prioritizing resilience in their infrastructure.
Data Center Interconnect (DCI) segment is valued at USD 4.8 million in 2026 and is projected to reach USD 10.4 million by 2033, at a CAGR of 11.6% during the forecast period. This segment serves critical functions by facilitating high-speed connectivity between data centers, enabling efficient data transfer and management. Key buyers include telecommunications operators and cloud service providers, who prioritize robust and scalable connections to meet growing data traffic demands. The increasing reliance on cloud services and hybrid IT environments drives significant demand for DCI solutions. This segment differs from others due to its higher growth rate, reflecting the urgent need for enhanced data center connectivity compared to slower-growing segments including Long-Haul and Ultra-Long-Haul Transport. The DCI segment's projected growth highlights its importance in the evolving landscape of the DWDM Optical Transport Equipment market.
Metro and Regional Optical Transport segment is estimated to reach USD 8.5 million by 2033, at a CAGR of 8% during the forecast period. This segment operates to facilitate connectivity within metropolitan areas and regional networks, primarily serving telecommunications operators and internet service providers. Stringent demand for high-capacity data transmission fuels growth in this segment, driven by increasing consumer demand for bandwidth and enhanced internet services. Compared to other applications, Metro and Regional Optical Transport exhibits a moderate growth trajectory, reflecting a stable market position. In contrast to Data Center Interconnect (DCI), which is projected to achieve a higher CAGR of 11.6%, the Metro and Regional Optical Transport segment maintains a competitive advantage through cost-effectiveness in regional deployments. The market continues to evolve to meet the growing needs for efficient and reliable optical transport solutions.
Long-Haul and Ultra-Long-Haul Transport segment is expected to reach USD 7.4 million by 2033. This segment is critical for transmitting data over vast distances, primarily serving telecommunications operators and internet service providers. The increasing demand for high-bandwidth applications, including video streaming and cloud computing, drives growth in this segment. Operators expand their networks to support these applications, increasing the requirement for efficient long-haul transport solutions. The segment exhibits a higher growth rate compared to traditional metro transport systems, benefiting from advancements in optical technologies that enhance capacity and reduce costs. The Long-Haul and Ultra-Long-Haul Transport segment significantly shapes the DWDM Optical Transport Equipment market, addressing the needs of businesses seeking reliable and efficient connectivity across regions.
Submarine Optical Transport segment is projected to grow at a CAGR of 9.2% during the forecast period. This segment facilitates long-distance data transmission under oceans and large bodies of water, primarily serving telecommunications operators and internet service providers. Increasing global internet usage and rising demand for high-bandwidth applications drive investments in submarine optical transport systems. Compared to other application segments, this area exhibits faster growth, fueled by the need for enhanced connectivity across continents. The high costs associated with deployment and maintenance pose challenges; however, advancements in technology continue to improve efficiency and reduce operational barriers. Ultimately, the growth of the Submarine Optical Transport segment reflects broader trends in the DWDM Optical Transport Equipment market, focusing on meeting escalating data traffic requirements.
Mobile Fronthaul and Backhaul focuses on facilitating connectivity between mobile base stations and the core network, serving telecommunications operators and internet service providers. This segment enables high-speed data transmission essential for modern mobile communication standards. A significant driver for this segment is the increasing demand for mobile bandwidth, driven by the proliferation of smartphones and data-intensive applications. Compared to other segments, Mobile Fronthaul and Backhaul experiences faster growth due to rising consumer expectations for mobile data speeds and network reliability. This segment typically demands more advanced technology, resulting in higher price points than traditional optical transport solutions. Competition within the market encourages continuous innovation, pushing providers to enhance their offerings further.
Enterprise and Campus Network Interconnection facilitates connectivity between various networks, including data centers and local area networks. This segment is essential for telecommunications operators, cloud service providers, and enterprise network operators, who rely on robust interconnectivity solutions to enhance communication and data transfer efficiency. Increasing demand for cloud services significantly drives expansion in this area, prompting service providers to upgrade their infrastructure. In contrast to the Data Center Interconnect segment, which focuses on large-scale, high-capacity connections, Enterprise and Campus Network Interconnection emphasizes flexibility and cost-effectiveness. The market exhibits different growth dynamics, appealing to enterprises seeking to optimize their network capabilities while avoiding substantial costs. Increased adoption of remote work solutions and digital transformation strategies further enhances the need for reliable interconnection options. The market experiences opportunities for innovation in technologies designed to meet specific interconnection requirements, ensuring efficient data flow and improved network performance.
Access Network Aggregation facilitates the consolidation of various network services into a unified infrastructure, optimizing resource allocation and performance. This application primarily serves telecommunications operators and internet service providers, enabling efficient connectivity for end-users. The rising demand for high-speed internet and increasing mobile data consumption drive growth in this segment. Compared to other applications, Access Network Aggregation experiences slower growth due to challenges associated with existing infrastructure upgrades and integration complexities. However, the segment's focus on cost reduction and performance enhancement differentiates it from applications including Data Center Interconnect, which has a higher growth rate. Overall, advancements in technology and increasing urbanization create significant opportunities for enhancing access network aggregation capabilities, contributing to the overall growth of the DWDM Optical Transport Equipment market.
Valued at USD 9.5 million in 2026, this segment is projected to reach USD 15.9 million by 2033, at a CAGR of 7.6% during the forecast period. Telecommunications operators and internet service providers employ DWDM optical transport equipment to enhance data transmission and network reliability across vast distances. The segment experiences robust demand driven by the increasing need for high-speed internet and the proliferation of data traffic generated by cloud services and multimedia applications. This segment exhibits slower growth compared to others, including Data Center Interconnect (DCI), which is expected to grow at a CAGR of 11.6%. The market dynamics reflect a growing emphasis on improving network capabilities, prompting investments in advanced optical technologies to meet evolving user expectations.
Cloud and Colocation Data Center Operators segment is estimated to reach USD 10.5 million by 2033, at a CAGR of 11.5% during the forecast period. This segment primarily serves telecommunications operators and internet service providers who require efficient and scalable interconnectivity solutions. Growth in this segment is driven by increasing demand for data storage and processing capabilities, stemming from rising adoption of cloud services and digital transformation across industries. Compared to other segments in the end-user category, Cloud and Colocation Data Center Operators segment exhibits a faster growth trajectory, reflecting significant investment in infrastructure to support growing data requirements. This segment differs from traditional telecommunications operators, which generally experience slower growth rates and different pricing structures. Unique needs of cloud service providers drive innovation and investment, influencing the overall direction of the market.
Enterprise Network Operators segment is expected to reach USD 3.4 million by 2033. This segment supports organizations that require robust optical transport solutions to manage data traffic efficiently within their networks. Demand for scalable and high-capacity bandwidth drives growth, primarily fueled by the increasing need for data transmission and communication services across various sectors. This segment experiences a slower growth rate, reflecting a compound annual growth rate (CAGR) of 8.2%. Telecommunications operators and service providers represent key users of these systems, focusing on enhancing their network capabilities. Investment in advanced technologies within this segment influences adoption rates, leading to marked improvements in operational efficiency for end users. The market is characterized by ongoing technological advancements, which continue to improve the performance and reliability of optical transport systems.
Government and Defense Organizations segment is projected to grow at a CAGR of 8.2% during the forecast period. This segment serves various national and local agencies, focusing on critical infrastructure and security communications. Increased investments in defense capabilities and the need for secure communication systems drive demand in this sector. Unlike other segments, including Telecommunications Operators and Internet Service Providers, which show a CAGR of 7.6%, this segment highlights a distinct priority for secure and reliable communication. The focus on advanced technologies and regulatory compliance further differentiates this segment, compelling organizations to adopt sophisticated solutions that ensure data integrity and security.
Power and Utility Companies represent a critical segment within the broader framework of the market, focusing on delivering reliable energy and utility services. This segment employs DWDM optical transport solutions to enhance communication networks, ensuring efficient data transmission and interoperability among various systems. The increasing demand for reliable grid management and smart grid technology drives growth in this area, leading to a greater need for advanced communication infrastructure. The growth rate of this segment aligns closely with technology advancements in energy efficiency and regulatory requirements for smart grid implementations. Distinct from segments including Telecommunications Operators and Internet Service Providers, Power and Utility Companies prioritize reliability and resilience in their infrastructure, reflecting their operational needs and strategic objectives.
Railway and Transportation Operators employ advanced optical transport solutions to enhance communication and data transmission across networks. This sector serves primarily government and private entities involved in public transport and logistics. Significant factors influencing this segment include the ongoing modernization of transportation infrastructure and the increasing demand for reliable data services for operational management and passenger information systems. Compared to other segments like Telecommunications Operators and Internet Service Providers, this sub-segment exhibits slower growth due to higher regulatory hurdles and capital investment requirements. However, the push for smart transportation solutions is expected to drive investments in optical transport solutions. Overall, the market focuses on improving connectivity within railway and transportation networks, contributing to the overall growth of the DWDM Optical Transport Equipment market.
Cable Television and Broadcasting Operators employ optical transport equipment to ensure efficient transmission of video and audio signals to consumers. This segment serves telecommunications operators and internet service providers, providing essential infrastructure for high-quality broadcasting services. The increasing demand for high-definition and on-demand content drives the need for advanced optical transport solutions. Consumer preferences shift toward streaming services, prompting operators to invest in enhanced network capabilities to deliver effective experiences. This segment differs from others in the end-user category, exhibiting unique growth dynamics and pricing structures. The focus on maintaining high-quality service while accommodating diverse content delivery methods influences operational strategies, impacting the overall market. The DWDM Optical Transport Equipment market is expected to evolve, driven by these trends and the ongoing need for reliable broadcasting services.
Research and Educational Institutions employ DWDM Optical Transport Equipment to enhance data transmission and communication capabilities. This segment primarily serves universities, research centers, and educational organizations that require reliable and high-capacity data links for collaborative projects, distance learning, and research activities. The growing demand for advanced research capabilities drives investments in optical transport solutions, facilitating data-intensive applications including real-time data analysis and high-performance computing. Unlike other segments, this category emphasizes specialized applications, often involving complex networking requirements and unique user needs. Investment in this sector reflects an increasing focus on technology-driven educational initiatives and research collaborations, positioning it differently compared to broader segments focused on traditional telecommunications operators and service providers. The market is expected to grow steadily, driven by advancements in optical technologies and the necessity for efficient data handling in the educational landscape.
Based on geography, the Global DWDM Optical Transport Equipment market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Strong growth in the DWDM Optical Transport Equipment market is anticipated in North America, driven by increasing demand from telecommunications operators and internet service providers. Investments in infrastructure modernization and the rollout of next-generation networks contribute to this demand. The region's focus on enhancing connectivity and data transmission capabilities aligns with the rapid expansion of data center interconnect solutions. North America holds a 27.3% share of the global market in 2025 and is projected to reach USD 9.3 million by the end of 2033. This growth reflects ongoing technological advancements and competitive pressures among service providers striving to improve offerings.
The European market demonstrates a significant demand for DWDM Optical Transport Equipment, driven primarily by telecommunications operators and internet service providers. Countries like Germany, France, and the UK stand out due to their advanced infrastructure and high demand for data transmission solutions. The emphasis on enhancing network capacity and reliability fuels investments in optical transport technologies. The growing number of cloud and colocation data center operators in the region contributes to robust market expansion. The market share in Europe is projected at 22.6% in 2025, reflecting strong growth potential. Innovative applications in metro and regional optical transport alongside long-haul services highlight the market's dynamic nature, appealing to various end users across the continent.
Rapid technological advancements in Asia-Pacific drive significant growth in the DWDM Optical Transport Equipment market. Countries including China, Japan, and India represent substantial demand sources, particularly through investments in telecommunications infrastructure and data centers. Enhanced connectivity requirements from enterprises and the rise of cloud services contribute to the increasing adoption of optical transport solutions. Network expansions and advanced digital transformation initiatives across the region further stimulate market growth. By 2025, Asia-Pacific is projected to capture 42.0% of the global market share. This market dynamic results in an anticipated increase in capacity and performance of DWDM systems, supporting various applications in data center interconnect and telecommunications sectors.
In South America, the DWDM Optical Transport Equipment market faces unique dynamics driven by growing telecommunications infrastructure in Brazil and Argentina. The expansion of data centers and increased demand for high-speed connectivity are key factors influencing market growth. The region's share of the global market stands at 3.2% in 2025. Investment in advanced optical transport solutions supports the development of reliable network services in urban and rural areas. Challenges related to funding and investment in infrastructure persist, impacting the pace of adoption. The market is expected to capture attention from regional telecommunications operators and internet service providers seeking to enhance their service offerings and accommodate rising data consumption demands.
In the Middle East and Africa, the market reflects a growing interest from telecommunications operators, internet service providers, and data center operators seeking efficient optical transport solutions. Countries including Saudi Arabia and the UAE represent significant demand, driven by ongoing investments in digital infrastructure and smart city initiatives. The region's developing telecommunications environment, particularly in South Africa, supports the adoption of advanced technologies essential for enhancing connectivity and data transmission. The DWDM Optical Transport Equipment market is projected to experience steady growth, propelled by increasing bandwidth requirements and the expansion of fiber optic networks.
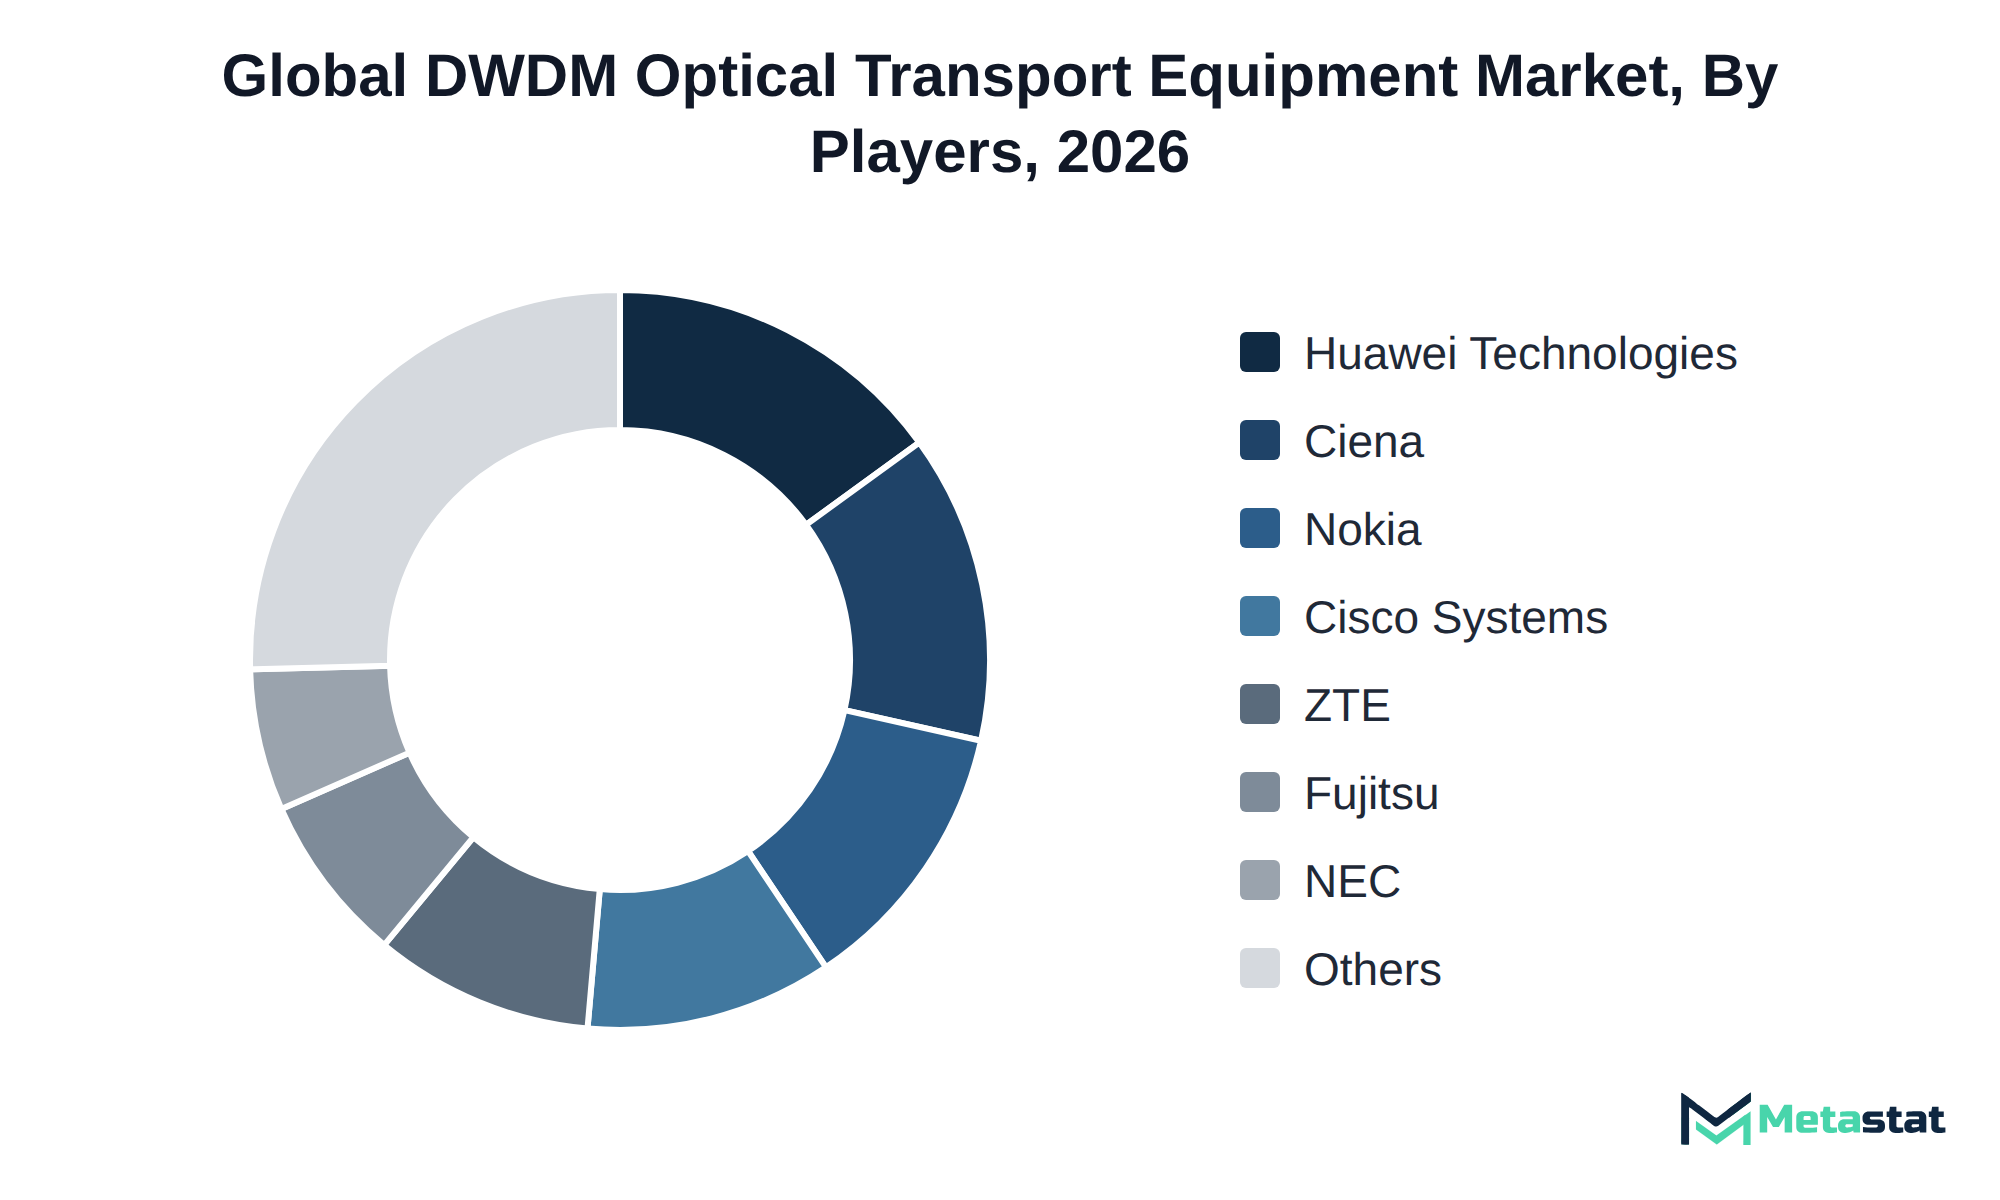
Companies in the DWDM Optical Transport Equipment market compete primarily through product innovation, pricing strategies, and service quality. Buyers evaluate options based on factors including cost efficiency, customization capabilities, and ecosystem compatibility. This focus on buyer-centric strategies enables companies to differentiate their offerings within a competitive landscape.
Nokia Corporation emphasizes integrated solutions that cater to diverse operational environments, enhancing its appeal to telecommunications operators and data center operators. Ciena Corporation focuses on advanced optical networking technologies, positioning itself as a provider of high-capacity interconnect solutions. Huawei Technologies Co., Ltd. leverages a broad portfolio, addressing varying needs across applications and end users while maintaining competitive pricing strategies.
This growth relies on several key developments within the market. First, significant advancements in Data Center Interconnect (DCI) technology, projected to grow from USD 4.8 million in 2026 to USD 10.4 million by 2033, will drive demand among cloud and colocation data center operators. Second, the expansion of Point-to-Point Networks, expected to increase from USD 8.1 million in 2026 to USD 13.6 million by 2033, supports telecommunications operators and internet service providers in enhancing network performance. A major risk that could impede growth includes supply chain disruptions affecting key components, which could delay the deployment of DWDM Optical Transport Equipment across regions. In North America, the anticipated market value of USD 9.3 million by 2033 highlights the importance of regional investments in infrastructure to support this growth trajectory. Overall, the market's success hinges on technological advancements and the ability to mitigate supply chain challenges.
By Equipment Type: Integrated DWDM Transport Systems, Optical Transponders, Optical Muxponders, DWDM Multiplexers and Demultiplexers, Reconfigurable Optical Add-Drop Multiplexers (ROADMs), Optical Amplifiers, Optical Protection and Monitoring Equipment
By Network Topology: Point-to-Point Networks, Linear Add-Drop Networks, Ring Networks, Mesh Networks
By Application: Data Center Interconnect (DCI), Metro and Regional Optical Transport, Long-Haul and Ultra-Long-Haul Transport, Submarine Optical Transport, Mobile Fronthaul and Backhaul, Enterprise and Campus Network Interconnection, Access Network Aggregation
By End User: Telecommunications Operators and Internet Service Providers, Cloud and Colocation Data Center Operators, Enterprise Network Operators, Government and Defense Organizations, Power and Utility Companies, Railway and Transportation Operators, Cable Television and Broadcasting Operators, Research and Educational Institutions
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the DWDM Optical Transport Equipment market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 8.7% from 2026 to 2033 |
Revenue Unit | USD million |
Segmentation | By Equipment Type, Network Topology, Application, End User, and Region |
By Region | North America (By Equipment Type, Network Topology, Application, End User, and Country)
|
Europe (By Equipment Type, Network Topology, Application, End User, and Country)
| |
Asia Pacific (By Equipment Type, Network Topology, Application, End User, and Country)
| |
South America (By Equipment Type, Network Topology, Application, End User, and Country)
| |
Middle East and Africa (By Equipment Type, Network Topology, Application, End User, and Country)
|
Find answers to common questions about this report
The DWDM Optical Transport Equipment market size was valued at USD 18.2 million in 2025.
The market is projected to grow at a CAGR of 8.7% during the forecast period from 2026 to 2033.
The North America DWDM Optical Transport Equipment market size is estimated to reach USD 9.3 million by 2033.
Integrated DWDM Transport Systems leads the market with a projected value of USD 11.3 million by 2033, based on its growth trajectory compared to other segments.
Increasing investments in high-capacity optical transport solutions support the growing need for data center interconnect, driven by rising data traffic from cloud computing and IoT devices. Advancements in cost-effective optical components enhance affordability and accessibility for telecommunications operators and Internet service providers, facilitating broader adoption.
High prices for advanced optical transport equipment hinder timely upgrades for telecommunications operators and Internet service providers. This financial barrier leads to smaller orders and delayed equipment replacement cycles, ultimately constraining overall market growth.
The increasing demand for high-capacity data solutions and the growth of Data Center Interconnect (DCI) solutions drive adoption within the DWDM Optical Transport Equipment market. Telecommunications operators and cloud service providers prioritize efficient connectivity, resulting in significant opportunities for suppliers focusing on innovative optical transport technologies.
The DWDM Optical Transport Equipment market is estimated to reach a valuation of USD 35.5 million by 2033.
Key players operating in the DWDM Optical Transport Equipment market include Nokia Corporation, Ciena Corporation, Huawei Technologies Co., Ltd., ZTE Corporation, Cisco Systems, Inc., and Fujitsu Limited.
The Data Center Interconnect segment is projected to achieve a compound annual growth rate of 11.6 percent, reaching USD 10.4 million by 2033.
The analysts below cover Information & Technology research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.

LEAD CONSULTANT - COMMUNICATION, TELECOM, AND IT
Electronics and Semiconductor · Information & Technology · Machinery & Equipment · Professional Services
Ravindra Sathe Consultants for Communication, Telecom, and IT at MetaStat Insight. He leads the firm's industry research initiatives across telecommunications infrastructure, digital connectivity, enterprise networking, and emerging information technology domains.
Tracking ceramic matrix composite adoption in high-bypass aero engines requires strict attention to material qualification cycles and FAA airworthiness testing milestones. The MetaStat Insight team provided a detailed timeline of silicon carbide fiber manufacturing capacity and commercial foundry lead times. Having clear visibility into upstream thermal barrier coating supply helped us stress-test our long-term component procurement strategy.
Transitioning ultra-class mining haul trucks to alternative power requires concrete data on remote hydrogen refueling infrastructure economics. The report evaluated megawatt-scale electrolyzer installation expenses, onsite storage safety mandates, and heavy-duty fuel cell stack degradation under continuous duty cycles. That technical rigor helped our engineers benchmark realistic total operating cost horizons for off-highway fleet decarbonization.
Enterprise zero-trust network rollouts are often slowed down by multi-cloud transit latency and proprietary hardware retirement schedules. This study provided realistic total cost of ownership models comparing cloud-delivered security edge solutions against traditional hardware refreshes. The analysis of contract renewal lengths and software maintenance fees gave us clear visibility into enterprise replacement cycles over the next three to five years.
Explore related market intelligence reports worth reading alongside this one.
Starting from
$2950
Starting from
$2950