
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Mergers and Acquisitions Advisory Market Size, Share, By Advisory Mandate (Sell-Side Advisory, Buy-Side Advisory, Merger Advisory, Standalone Fairness Opinions and Transaction Valuation), By Client Type (Corporations, Private Equity Firms and Other Financial Sponsors, Government and State-Owned Enterprises), By Target Industry (Technology, Media and Telecommunications, Industrials and Transportation, Energy and Utilities, Healthcare and Life Sciences, Financial Services, Consumer and Retail, Business Services, Real Estate), By Transaction Geography (Domestic Transactions and Cross-Border Transactions), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-5790
Published
November, 2026
Pages
265 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
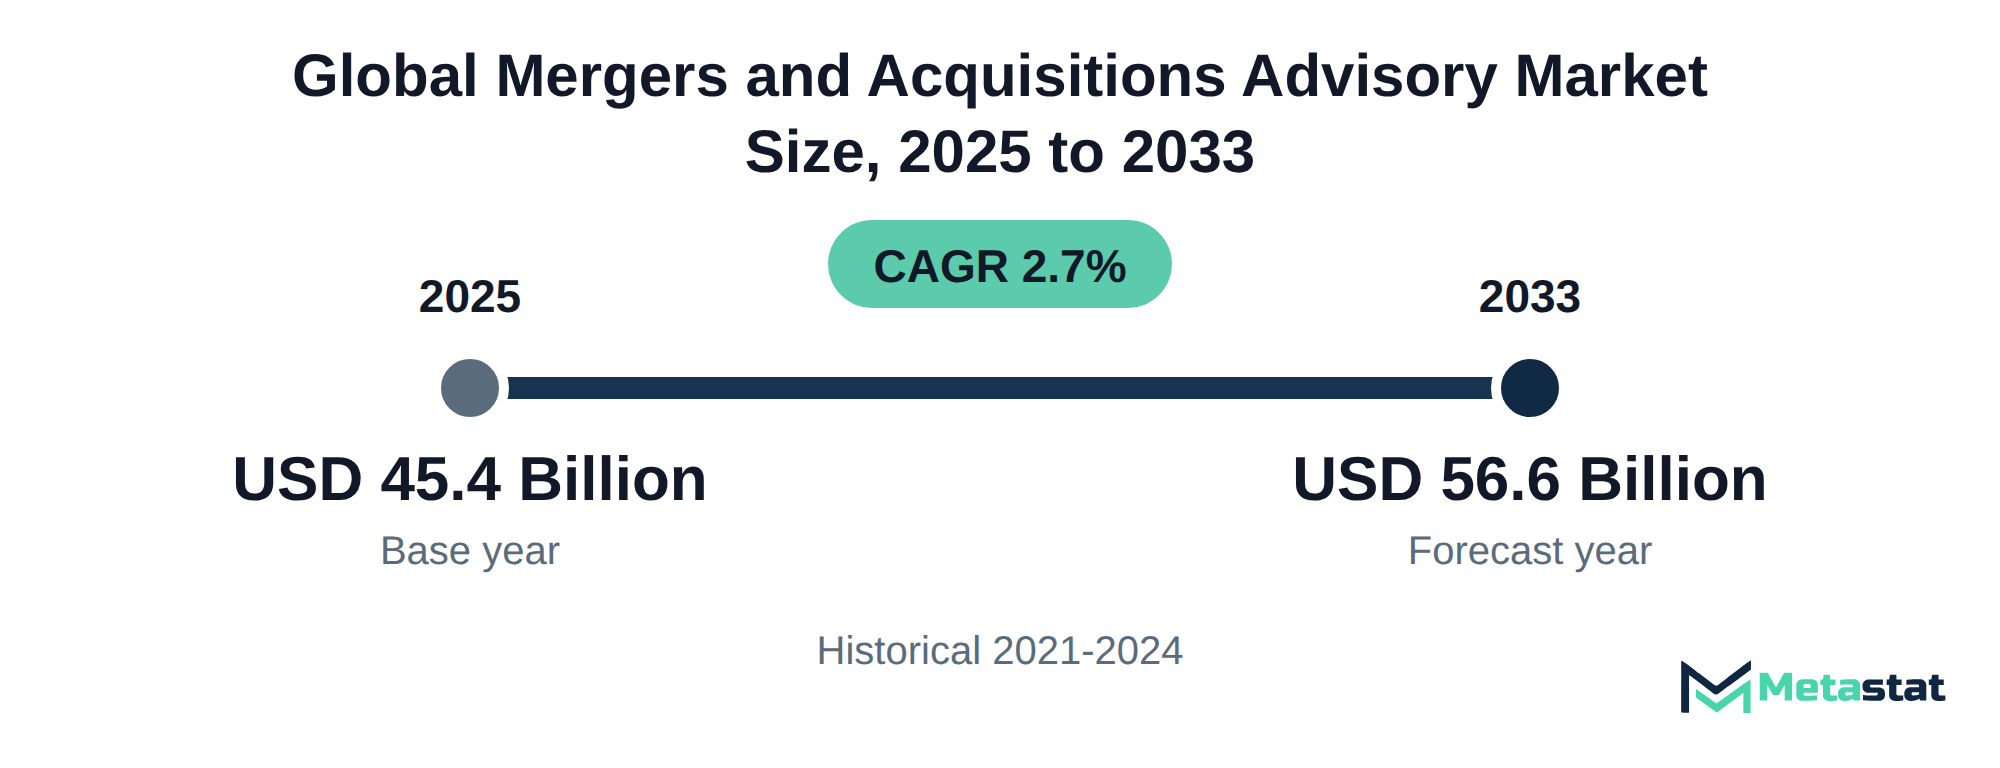
Market Valuation: Valued at $45.4 Billion in 2025, projected to reach $56.6 Billion by 2033 at a 2.7% CAGR.
Dominant Segment: The Sell-Side Advisory segment leads the market, driven by heightened demand among sellers seeking optimal deal structures and valuations.
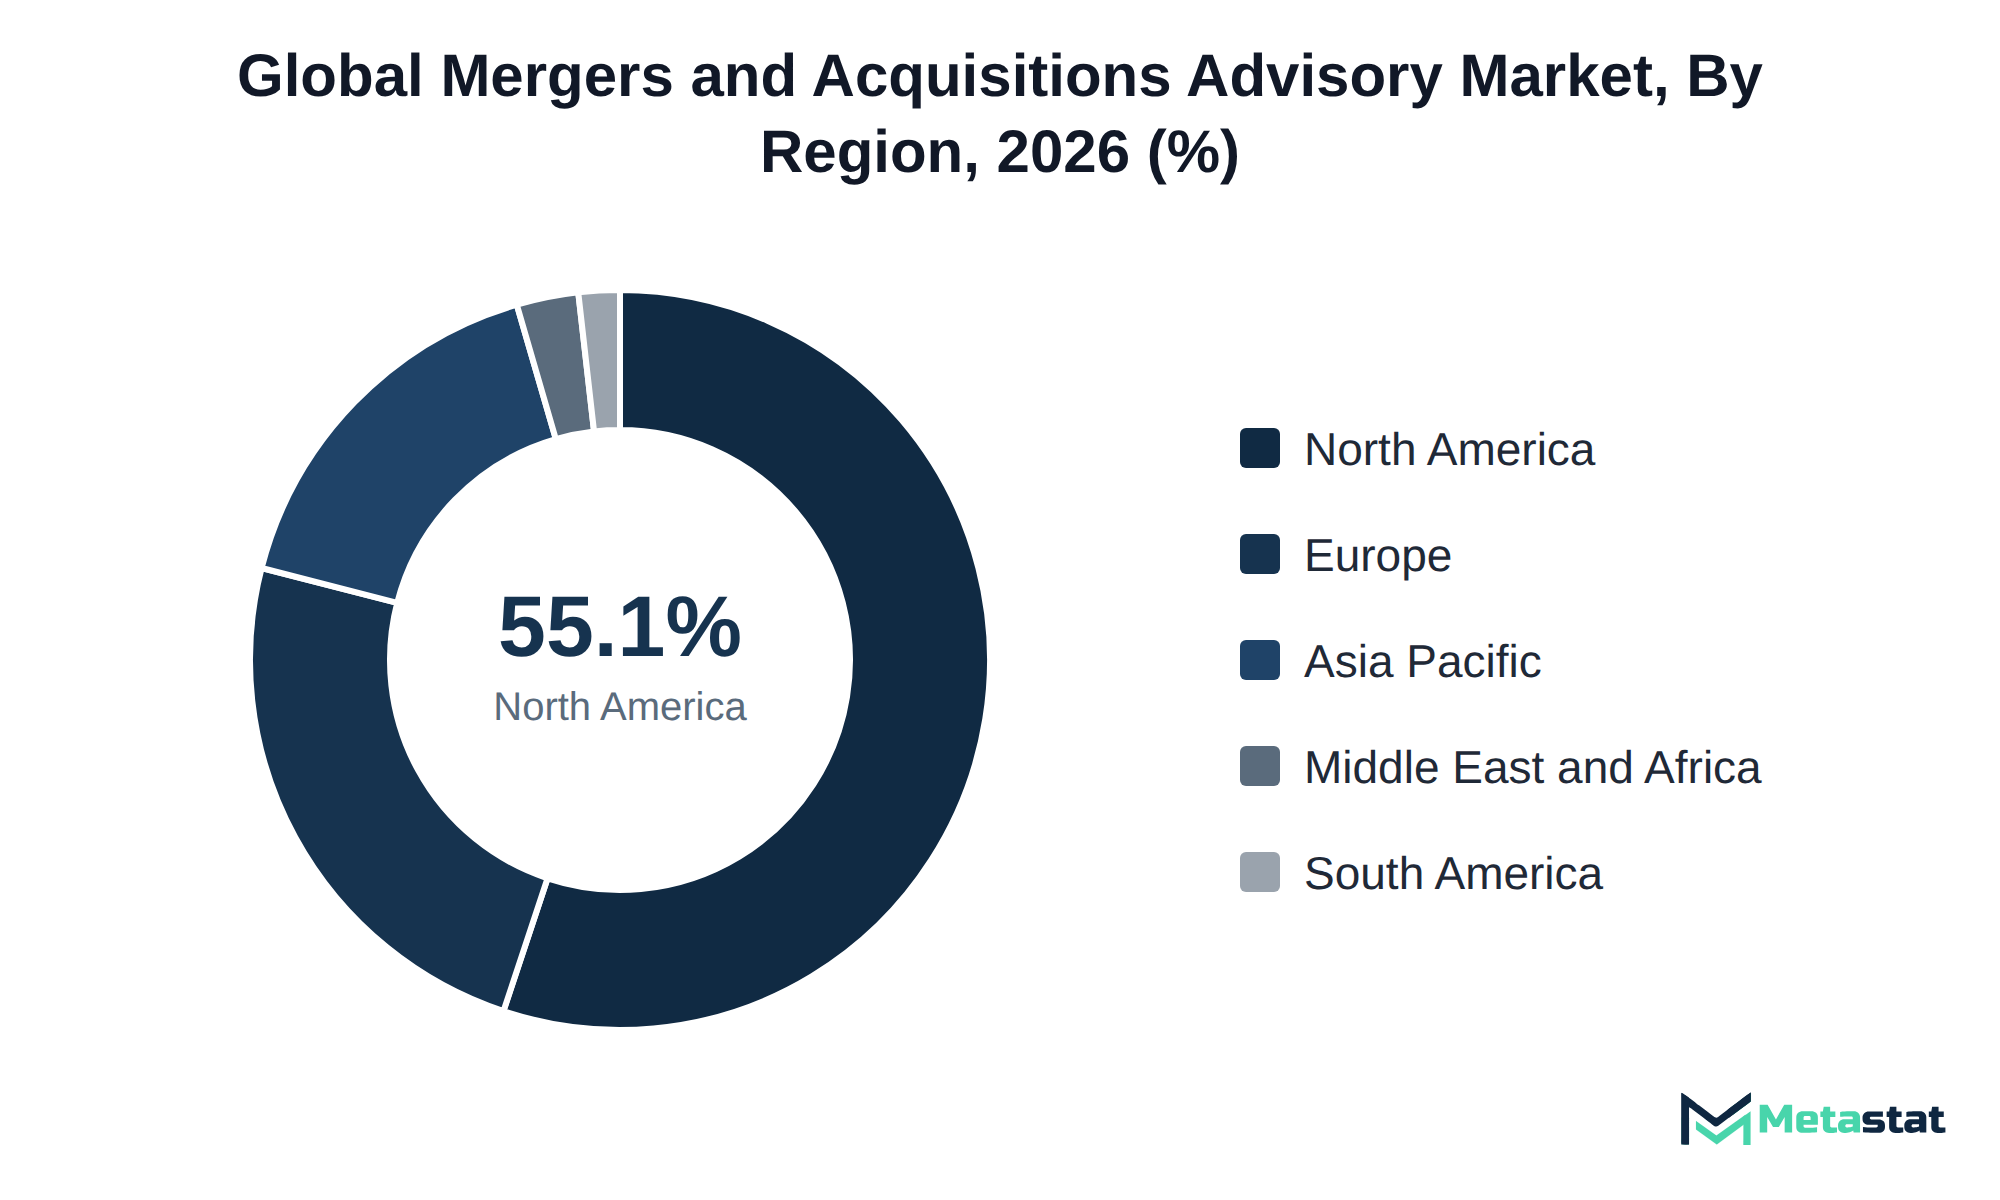
Geographic Lead: North America is the leading region, accounting for 55.1% of the market in 2025, with the US expected to maintain its dominance through 2026.
What's Inside: The report provides comprehensive coverage of the competitive landscape, detailed analyses of market dynamics, and forecasts extending to 2033.
Increased Demand for Buy-Side Advisory: The Buy-Side Advisory segment is projected to reach USD 22.1 billion by 2033, reflecting a growing appetite for acquisitions among private equity firms and corporations.
Growth in Technology Sector: The Technology, Media and Telecommunications segment is expected to grow significantly, from USD 11.7 billion in 2026 to USD 14.8 billion by 2033, driven by ongoing consolidation trends.
Choose Your License
Global Mergers and Acquisitions Advisory Market
The global Mergers and Acquisitions Advisory market was valued at USD 45.4 billion in 2025 and is projected to reach USD 56.6 billion by 2033, growing at a CAGR of 2.7% over the forecast period.
The Mergers and Acquisitions Advisory market covers services that help organizations execute complex transactions, including mergers, acquisitions, and divestitures. Buyers invest in these services for expert guidance that raises transaction value and reduces risk. The need for strategic advisory support becomes critical, ensuring alignment with organizational goals and market conditions during the transaction process.
Increasing corporate activity and a rising trend of cross-border transactions drive growth in the market. The segment of Sell-Side Advisory commands the most significant value within the market, reflecting heightened demand among sellers seeking optimal deal structures and valuations. North America holds 55.1% of the market in 2025, with the US leading in 2026.
While companies pursue expansion opportunities, the role of advisory services becomes increasingly vital. The expectation of sustained economic recovery and favorable market conditions fuels investment in advisory support, ensuring organizations remain competitive. Demand for advisory services continues to evolve alongside the economic environment, adding to the importance of the Mergers and Acquisitions Advisory market.
The Mergers and Acquisitions Advisory market includes various services that assist organizations in executing complex financial transactions. Buyers invest in these services primarily to leverage expert guidance, enhance negotiation outcomes, and facilitate the assessment of market conditions. This strategic support is critical for companies seeking to optimize their financial performance while navigating the intricacies of mergers and acquisitions.
Rising demand for specialized advisory services, particularly in the technology sector, drives market expansion. The Buy-Side Advisory segment represents the most substantial value, reflecting the heightened activity among investors looking for acquisitions that align with their strategic goals. This regional dominance highlights the strong investment landscape and the concentration of corporate activity in this area.
While companies continue to explore opportunities for expansion and consolidation, the emphasis on cross-border transactions is expected to rise. The ongoing globalization of markets encourages firms to seek advisory support that accommodates complex regulatory environments and cultural considerations. This trend emphasizes the market's role in facilitating successful transactions across diverse jurisdictions.
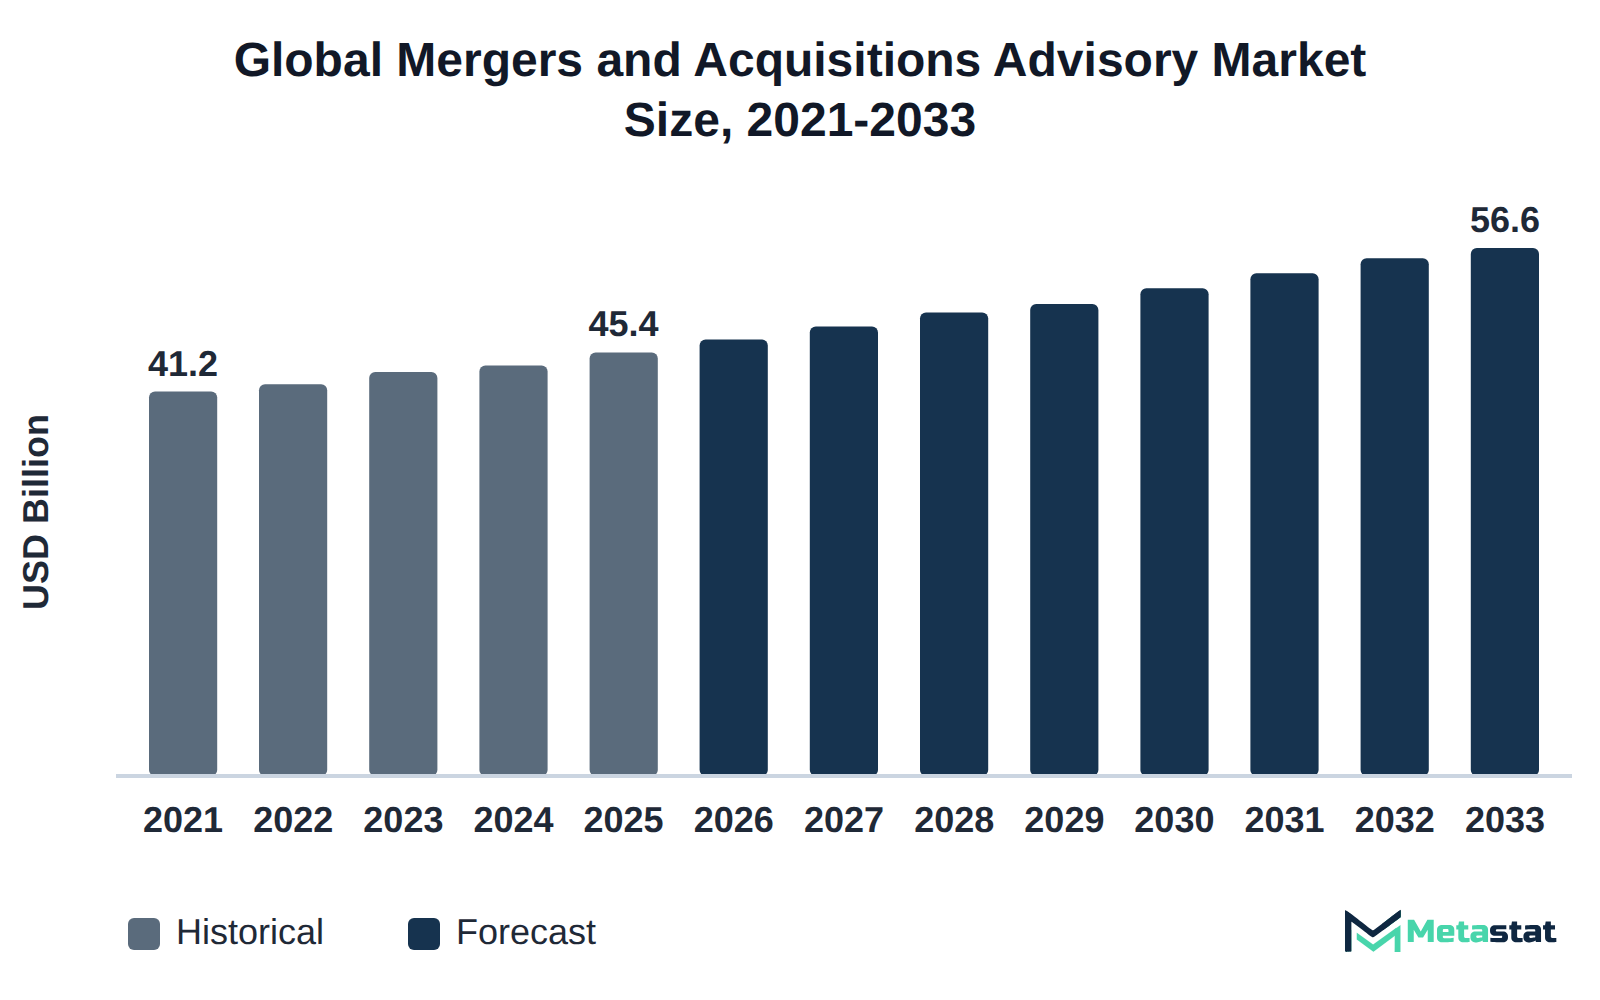
The increasing activity of private equity exits drives the demand for sell-side M&A advisory services. In 2026, the sell-side advisory segment is projected to reach USD 20.8 billion, growing to USD 24.6 billion by 2033, reflecting a compound annual growth rate (CAGR) of 2.4%. This growth points to a healthy market for advisory services tailored to private equity firms seeking to maximize returns on their investments through strategic divestitures.
Demand for sell-side advisory stems from the need for private equity firms to carry out exit strategies efficiently in a competitive landscape. Factors influencing these exits include favorable market conditions and the pursuit of optimal valuation metrics. Enhanced advisory services provide private equity firms with the expertise required to streamline the selling process, ensuring that stakeholders achieve maximum value from their assets.
This shift towards increased reliance on sell-side M&A advisory services enhances competitiveness within the Mergers and Acquisitions Advisory market. Advisors equipped with industry-specific knowledge better cater to private equity clients, contributing to an uptick in transaction volumes. The ongoing evolution within the advisory services landscape remains essential for private equity firms to capitalize on emerging opportunities in a complex market environment.
Pricing models in the Mergers and Acquisitions Advisory market vary significantly, influenced by transaction complexity and client expectations. Cross-border transactions often involve more intricate pricing structures due to regulatory considerations and the necessity for compliance in multiple jurisdictions. Advisory firms typically employ a tiered pricing model, where fees scale based on the transaction value and additional services required. For example, in 2033, the market is projected to see cross-border transactions reaching a value of USD 19.3 billion, reflecting the growing importance of international deals.
Payment structures often comprise retainer fees, success fees, and hourly rates. Retainer fees, paid upfront, secure the advisory firm's commitment throughout the transaction process. Success fees, contingent upon successful deal closure, align the advisors' interests with those of the client, encouraging optimal outcomes. Hourly rates apply for specific consultancy services required during the advisory process, providing flexibility for clients encountering varying levels of complexity.
The diverse pricing strategies result in competitive differentiation among advisory firms. Clients increasingly prefer firms that offer transparent fee structures while demonstrating a strong understanding of the complexities involved in cross-border mergers. This focus on clear communication and value-oriented pricing supports the overall growth of the market, enhancing client trust and promoting longer-term relationships between advisory firms and their clients.
The Technology, Media and Telecommunications sector demonstrates significant growth in the Mergers and Acquisitions Advisory market, driven by ongoing consolidation trends. The segment is expected to increase from USD 11.7 billion in 2026 to USD 14.8 billion by 2033, reflecting a compound annual growth rate of 3.4%. This growth indicates rising interest among corporations and private equity firms in acquiring innovative technology businesses to enhance their portfolios and competitive positioning.
Corporations prioritize M&A advisory services to manage complex transactions and integrate new technologies effectively. The need for specialized advisory services arises from the unique challenges in merging tech-focused enterprises, including aligning organizational cultures, managing intellectual property, and ensuring compliance with evolving regulations. Advisory firms that specialize in technology transactions provide essential insights and strategies, helping clients achieve successful mergers and acquisitions.
While the demand for technology-driven solutions escalates, investment in M&A advisory services within this sector is anticipated to rise. The strategic acquisition of technology firms enables companies to remain competitive and responsive to market shifts, driving overall growth in the Mergers and Acquisitions Advisory market.
Mergers and Acquisitions Advisory fees for mid-market deals typically follow a tiered structure based on the transaction value. This structure aligns incentives between advisors and clients, ensuring that advisory services remain competitive while reflecting the complexity of the deal. For mid-market transactions, advisory fees generally range from 1% to 3% of the total deal value, with fees decreasing as transaction sizes increase. For instance, a mid-market transaction valued at USD 50 million has an advisory fee of USD 1 million, representing 3% of the deal value.
In the context of the Mergers and Acquisitions Advisory market, the segment focusing on private equity firms and other financial sponsors is projected to reach USD 21.4 billion by 2033, reflecting a growing appetite for advisory services in this sector. This growth emphasizes the importance of transparent fee structures, as clients seek value for their investment in advisory services.
Understanding the fee structure is crucial for mid-market buyers, influencing their decision-making process and overall transaction costs. A well-structured fee arrangement enhances client trust and supports the feasibility of successful negotiations in complex deal environments.
Private equity firms increasingly pursue buy-side advisory services due to a surge in acquisition opportunities across various sectors. This trend arises from efforts to enhance portfolio value and capitalize on favorable market conditions. The influx of funds into these firms, coupled with strategic shifts towards growth through acquisitions, significantly increases demand for tailored advisory services. The market shows a notable increase in buy-side advisory transactions, reflecting a projected growth rate of 3.2% for this segment through 2033. This heightened interest in acquisitions leads to greater competition among firms, ultimately driving up advisory fees and further stimulating market expansion.
In addition to private equity, corporations actively seek advisory services to navigate complex transactions effectively, pushing the Mergers and Acquisitions Advisory market towards its forecasted growth trajectory.
Growing complexity in financial transactions raises the demand for standalone fairness opinions and transaction valuation services. Factors including fluctuating market conditions, regulatory scrutiny, and the need for accurate assessments drive clients to seek expert advisory. Corporations and private equity firms increasingly focus on ensuring transactions align with fair market value, particularly in high-stakes deals. This trend is evident across various industries where accurate valuations are essential for maintaining investor confidence and regulatory compliance.
Clients recognize the importance of thorough and independent evaluations to support their decision-making processes. The need for these services becomes more pronounced in sectors like technology and healthcare, where valuations vary significantly due to rapid innovation or regulatory changes. The Mergers and Acquisitions Advisory market is expected to continue benefiting from this trend, reflecting the growing importance of transparency and accountability in financial dealings.
High transaction costs present a significant restraint in the Mergers and Acquisitions Advisory market, particularly affecting corporations and private equity firms. These costs encompass various fees related to advisory services, legal expenses, and regulatory compliance, leading to slower decision-making processes and potentially smaller transaction volumes. Companies delay or reconsider engagement in M&A activities due to the financial burden associated with these processes, thereby limiting market growth. The increased complexity of deals often contributes to higher advisory fees, which deter several firms from pursuing strategic acquisitions or divestitures. This situation results in a cautious approach among buyers, further inhibiting the frequency and scale of transactions.
The pressure of high transaction costs particularly impacts private equity firms, which require a more favorable cost-to-benefit ratio to justify their investments. The combination of high costs and market uncertainty leads to reduced appetite for mergers and acquisitions, ultimately affecting the overall health of the market.
The Mergers and Acquisitions Advisory market faces significant challenges in talent acquisition, primarily driven by increased competition for skilled professionals. High demand for expertise in complex transactions requires firms to invest substantially in attracting and retaining top talent. Compensation pressures arise as firms compete with each other and other industries for the same pool of qualified candidates. This situation leads to increased operational costs and reduced profit margins for advisory firms.
In response to these challenges, many firms enhance their training programs and expand recruitment and staffing efforts to include a wider talent pool. An increasing emphasis on professional development and providing competitive benefits packages improves employee retention rates. Firms explore technology solutions to streamline operations and optimize workforce efficiency, aiming to maintain service quality despite rising talent costs. The outcome of these strategies will significantly influence the long-term viability of firms operating within the market.
The buy-side advisory segment in the Mergers and Acquisitions Advisory market exhibits a strong growth trajectory, driven primarily by increasing acquisition opportunities across multiple sectors. This segment is projected to reach USD 22.1 billion by 2033, reflecting a compound annual growth rate of 3.2%. The rise in private equity investments and corporate mergers fuels this demand, with organizations seeking expert guidance to navigate complex transactions effectively. Financial sponsors and corporations increasingly rely on specialized advisory services to optimize their acquisition strategies. The performance of this segment reflects broader trends in investment activity, highlighting the market's responsiveness to evolving financial landscapes. Strategic partnerships and enhanced advisory capabilities are expected to further support growth in buy-side advisory services, positioning firms to capitalize on emerging opportunities.
The Global Mergers and Acquisitions Advisory market is segmented based on Advisory Mandate, Client Type, Target Industry, and Transaction Geography.
This segment focuses on assisting sellers in maximizing value during the sale of their assets or companies, targeting corporations and private equity firms looking to divest. The increasing focus on strategic exits drives demand. This service offering is tailored for sellers, and its growth rate is comparatively lower than that of the Buy-Side Advisory segment, which has a CAGR of 3.2%. The Sell-Side Advisory requires expertise in valuation and negotiation, reflecting a strong need for quality advisory services to navigate complex transactions effectively. The segment's growth is supported by heightened competition and the ongoing need for optimal asset valuation.
Buy-Side Advisory segment is estimated to reach USD 22.1 billion by 2033, at a CAGR of 3.2% during the forecast period. This segment primarily serves private equity firms and corporations seeking to acquire assets or companies that align with their strategic goals. The increasing volume of acquisition opportunities across various sectors contributes significantly to the growth of this segment. Compared to other advisory mandates, Buy-Side Advisory exhibits faster growth, driven by a robust appetite for expansion among financial sponsors. Growing competition in the investment landscape fuels demand for tailored advisory services, enabling clients to navigate complex transactions effectively. The market's focus on providing in-depth analysis and valuation insights differentiates Buy-Side Advisory from other segments, enhancing its appeal to discerning buyers.
Merger Advisory segment is expected to reach USD 7.4 billion by 2033. This segment primarily focuses on facilitating mergers between corporations, allowing them to achieve strategic growth, enhance market position, and realize synergies. Corporations and financial sponsors frequently seek merger advisory services to navigate the complexities involved in these transactions. A notable factor influencing this segment includes an increase in domestic transactions, projected to grow at a CAGR of 2.3% through 2033, reflecting the overall expansion in merger activity. Compared to other advisory segments, Merger Advisory exhibits a slower growth rate, indicated by its lower CAGR of 2.4% relative to Buy-Side Advisory’s 3.2%. The distinct nature of this segment emphasizes the importance of tailored advice and negotiation skills to align interested parties and achieve favorable outcomes.
Standalone Fairness Opinions and Transaction Valuation segment is projected to grow at a CAGR of 3.2% during the forecast period. This segment provides essential valuation services, allowing clients to assess the fairness of transaction terms and ensuring compliance with regulatory requirements. Corporations and private equity firms primarily engage these services to validate acquisition prices and defend against potential shareholder litigation. Demand for these services is driven by increasing scrutiny from regulatory bodies and the complexities of modern financial transactions. This segment differentiates itself from others within the advisory mandate, exhibiting a higher growth rate compared to Merger Advisory, while maintaining competitive pricing structures. With a projected value reaching USD 7.4 billion by 2033, the market reflects a growing recognition of the importance of thorough valuation processes in the broader Mergers and Acquisitions Advisory market.
The Corporations segment is valued at USD 27.1 billion in 2026 and is projected to reach USD 31.5 billion by 2033, at a CAGR of 2.2% during the forecast period. This segment serves large and medium enterprises seeking professional advisory services for mergers, acquisitions, and divestitures. Demand is driven by the growing need for strategic growth and diversification, with corporations recognizing the potential for value enhancement through M&A activities. Compared to other segments, the Corporations segment experiences slower growth than the Buy-Side Advisory segment, which anticipates a CAGR of 3.2%. Increasing complexities in regulatory compliance and market dynamics impact corporate transactions, requiring advisory services to navigate these challenges effectively. The market adapts to evolving corporate strategies, emphasizing advisory engagements tailored specifically to the needs of corporations.
Private Equity Firms and Other Financial Sponsors segment is estimated to reach USD 21.4 billion by 2033, at a CAGR of 3.4% during the forecast period. This segment serves private equity firms and financial sponsors in executing key investment strategies, including acquisition and divestiture transactions. The demand for advisory services in this segment stems from increased competition for high-value assets, driving firms to seek expert guidance on strategic deals. A notable difference from other client types lies in the segment's faster growth rate compared to Corporations, which is projected to reach USD 31.5 billion at a CAGR of 2.2%. The focus on specialized financial expertise allows for tailored solutions that address complex financial structures, ensuring successful execution of transactions. The presence of a competitive investment landscape heightens the need for sophisticated advisory services, positioning this segment for sustained growth in the evolving market environment.
The Government and State-Owned Enterprises segment is expected to reach USD 1.4 billion by 2033. This segment primarily involves public sector consulting and advisory services provided to government entities and state-owned companies seeking to engage in mergers and acquisitions. These entities pursue M&A activities to enhance operational efficiencies, expand market reach, or restructure for better service delivery. The segment's growth is influenced by increasing governmental focus on privatization and public-private partnerships, driving demand for advisory services. Compared to other client types, this segment typically experiences slower growth, reflecting the cautious approach these entities take toward acquisitions. The sector is characterized by a distinct regulatory environment, presenting unique challenges in accessing capital and navigating compliance issues. The Mergers and Acquisitions Advisory market continues to adapt to these dynamics, ensuring tailored support for government and state-owned enterprises.
Segment Others (Founders and Family Offices) is projected to grow at a CAGR of 3.8% during the forecast period. This segment caters to individual founders and family office entities seeking strategic advisory services for mergers and acquisitions. These clients pursue tailored solutions that align with their unique investment goals and risk profiles. Demand arises from increasing interest in diversifying portfolios and seeking lucrative investment opportunities. Compared to Corporations and Private Equity Firms, which necessitate larger transactions and more complex advisory structures, this segment emphasizes personalized service and strategic insight, resulting in relatively lower transaction volumes. The market continues to evolve, reflecting expanding interest in bespoke advisory services that meet the needs of specific clientele.
Technology, Media and Telecommunications segment is valued at USD 11.7 billion in 2026 and is projected to reach USD 14.8 billion by 2033, at a CAGR of 3.4% during the forecast period. This segment serves various clients, including corporations seeking strategic acquisitions to enhance their technological capabilities and media companies pursuing mergers to consolidate market positions. Increasing investment in digital transformation drives demand, particularly from private equity firms keen on acquiring innovative technology assets. Compared to other segments, this sub-segment exhibits a stronger growth trajectory, reflecting the rapid evolution of technology and media. In contrast, segments like Industrials and Transportation experience slower growth, with a CAGR of 2.5%. The focus on innovation and the need for digital adaptation influence the dynamics of the Technology, Media and Telecommunications segment, positioning it as a significant area within the Mergers and Acquisitions Advisory market.
Industrials and Transportation segment is estimated to reach USD 8.9 billion by 2033, at a CAGR of 2.5% during the forecast period. This segment serves corporations engaged in manufacturing, logistics, and transportation services, facilitating their strategic planning and operational efficiency through advisory services. Demand for these services is driven by ongoing consolidation trends within the sector and the necessity for operational improvements. Unlike other segments, the Industrials and Transportation segment exhibits relatively slower growth compared to Technology, Media and Telecommunications, which is projected at a CAGR of 3.4%. The focus on reducing operational costs while enhancing efficiency positions this segment differently, highlighting its importance to corporate strategies within the Mergers and Acquisitions Advisory market.
The Energy and Utilities segment is expected to reach USD 7.3 billion by 2033. This segment serves various stakeholders, including energy companies and utility providers, by facilitating strategic transactions, ensuring effective valuations, and providing advisory services. Demand in this segment is driven by the need for sustainable energy solutions and regulatory changes promoting energy transition investment in renewable resources. Compared to other segments, the Energy and Utilities segment experiences a moderate growth rate, reflecting a CAGR of 3.3%, positioning it slightly behind the Technology, Media and Telecommunications segment. The evolving technology landscape and increasing focus on sustainability present both opportunities and challenges, influencing overall market dynamics.
The Healthcare and Life Sciences segment is projected to grow at a CAGR of 3.3% during the forecast period. This segment serves various stakeholders, including healthcare corporations, pharmaceutical companies, and biotechnology firms, necessitating specialized advisory services for transactions and valuations. The increasing demand for innovative healthcare solutions drives acquisition activity, enhancing the segment's appeal. Regulatory changes and the evolving landscape of healthcare markets further influence this segment, compelling firms to adapt their strategies. Compared to other segments, including Industrials and Transportation, which is projected to grow at a CAGR of 2.5%, the Healthcare and Life Sciences segment demonstrates stronger growth potential, reflecting a higher urgency in adapting to market dynamics. The Mergers and Acquisitions Advisory market benefits from this heightened activity, providing firms with opportunities to capitalize on strategic acquisitions and consolidations.
Financial Services encompasses a broad array of activities critical to the functioning of the economy. This segment is used by banks, investment firms, and insurance companies, focusing on transactions and advisory services. In this context, financial institutions increasingly seek advisory services to navigate complex market conditions, regulatory changes, and evolving consumer demands. The push for digital transformation and the integration of financial technologies significantly influence this segment, driving demand for data analytics and improved customer experiences. Compared to other segments, this area experiences slower growth due to stringent regulatory requirements and the inherent risks associated with financial transactions. These factors necessitate a careful approach to advisory services, distinguishing it from the more rapidly expanding technology-related advisory segments. Firms in the Financial Services sector look to advisors to mitigate risks and enhance operational efficiency.
Consumer and Retail encompasses a diverse range of businesses focused on selling goods and services directly to consumers. Corporations operating in this segment engage Mergers and Acquisitions Advisory services to optimize their market positions, enhance operational efficiencies, and drive growth opportunities. The segment experiences upward pressure from changing consumer preferences, with increasing demand for innovative products and services driving acquisition activity. The potential for digital transformation within retail, including smart retail technology, drives interest in technology-related partnerships and acquisitions. Compared to other segments, including Technology, Media and Telecommunications, this segment encounters a slower growth trajectory, reflecting the industry's maturation and heightened competition among major players. The market prioritizes strategic adaptability to maintain relevance and ensure sustainable growth owing to evolving consumer behavior.
Business Services encompasses a diverse range of professional and administrative services, such as management consulting services, that facilitate the operations of various organizations. This segment primarily serves corporations seeking advisory services for mergers and acquisitions, enabling them to navigate complex transactions and make informed decisions. Demand for Business Services is propelled by the increasing need for operational efficiency and strategic alignment during mergers and acquisitions. This segment distinguishes itself from others in the advisory landscape through its focus on specialized knowledge and expertise, often resulting in higher service fees. Compared to segments including Technology, Media and Telecommunications, which anticipates a CAGR of 3.4%, Business Services demonstrates a unique growth trajectory driven by specific client needs and industry dynamics. The evolving landscape of business transactions emphasizes the essential role of advisory services in ensuring successful outcomes, further enhancing its importance in the Mergers and Acquisitions Advisory market.
Real estate encompasses a vital aspect of the economy, facilitating transactions involving residential, commercial, and industrial properties. Investors, corporations, and financial institutions engage advisory services in this segment to optimize their portfolios and navigate market complexities in real estate investment management. Demand for real estate advisory services experiences an upward trajectory driven by increasing transaction volumes and rising property prices. Regulatory changes and economic conditions significantly influence market dynamics, affecting investment strategies. This segment differs from others in its group through its unique buyer base, which includes a diverse range of stakeholders from individual investors to large corporate entities. Compared to segments including Technology, Media and Telecommunications, growth in real estate advisory services often aligns with regional market fluctuations and infrastructure developments. The Mergers and Acquisitions Advisory market highlights the importance of real estate in shaping investment decisions and impacting broader economic trends.
This sub-segment encompasses activities related to the agriculture and materials sector, focusing on transactions that facilitate mergers and acquisitions among businesses in these industries. Clients in this segment typically include companies engaged in agribusiness, forestry, mining, and materials production, seeking expert guidance to navigate complex transactions. Demand for advisory services in this area is driven by the need for consolidation within industries facing fluctuating commodity prices and evolving regulatory environments. The market for these services often experiences slower growth compared to segments like Technology, Media, and Telecommunications, which benefit from rapid innovation and technological advancements. Agricultural and materials firms prioritize transaction efficiency and regulatory compliance, distinguishing this sub-segment's dynamics from those of others focused on high-growth sectors, where investment and mergers occur at a much faster pace. The Mergers and Acquisitions Advisory market reflects these trends, with each segment adapting to its specific challenges and opportunities.
Domestic Transactions segment is valued at USD 31.8 billion in 2026 and is projected to reach USD 37.3 billion by 2033, at a CAGR of 2.3% during the forecast period. This segment involves transactions that occur within a single country, primarily by corporations and private equity firms seeking to strengthen their market positions through acquisitions or mergers. Demand in this segment is driven by a robust domestic economic environment and favorable regulatory conditions that support business consolidation. Compared to Cross-Border Transactions, which exhibit a higher growth rate of 3.7%, Domestic Transactions experience steadier growth, reflecting the preference of buyers for familiar markets and regulatory landscapes. The market's focus on domestic integration often results in lower transaction costs, enhancing the appeal for companies looking to optimize their operations without venturing into more complex international dealings.
Cross-Border Transactions segment is estimated to reach USD 19.3 billion by 2033, at a CAGR of 3.7% during the forecast period. This segment involves transactions between companies located in different countries, facilitating international mergers and acquisitions. Typically, corporations and private equity firms engage in cross-border transactions to expand their market presence and diversify their portfolios. Factors driving this segment include increasing globalization and the pursuit of strategic synergies across borders. Compared to other segments, including Domestic Transactions, which is valued at USD 31.8 billion in 2026, Cross-Border Transactions exhibits a higher growth rate, reflecting evolving market dynamics and the increasing inclination of firms to explore international opportunities. This trend highlights the growing role of the Mergers and Acquisitions Advisory market in supporting businesses working through complex cross-border landscapes.
Based on geography, the Global Mergers and Acquisitions Advisory market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
The North American market exhibits strong dynamics, driven predominantly by the United States, Canada, and Mexico. Corporations in these countries increasingly seek advisory services for mergers and acquisitions due to heightened competition and the pursuit of strategic growth opportunities. Regulatory frameworks in North America encourage consolidation, particularly in industries including technology and healthcare, where the demand for advisory services continues to rise. North America holds a 55.1% share of the global market, projected at USD 1,004.1 million in 2025. The market is projected to reach USD 30.3 billion by the end of 2033, reflecting a steady growth trajectory. Factors including a robust financial sector and a highly developed infrastructure contribute to the region's demand for Mergers and Acquisitions Advisory services.
The Mergers and Acquisitions Advisory market in Europe experiences dynamic demand driven by various industries, including Technology, Media and Telecommunications, which is expected to grow significantly through 2033. Key countries including Germany, France, the UK, Italy, Spain, and Russia contribute to this trend, with robust corporate activity and an expanding private equity landscape highlighting the regional market's potential. Regulatory factors, including financial compliance and transparency measures, shape the advisory services landscape, encouraging firms to seek expert guidance. With a market share of 23.9% in 2025, Europe remains an important player in global M&A activities, reflecting increased investment and transaction activity across diverse sectors. This environment supports sustained growth for the market, driven by strategic mergers and acquisitions tailored to local needs and conditions.
The Asia-Pacific region shows significant engagement in the Mergers and Acquisitions Advisory market, driven by strong economic growth in countries including China and India. The increasing number of domestic companies seeking strategic expansion and foreign investment opportunities drives demand within the market. The technology sector, particularly in China and Japan, experiences heightened activity, reflecting ongoing digital transformation and innovation trends. In addition, the rising number of mergers and acquisitions in Southeast Asia highlights evolving investor interest in emerging markets. The market share of the Asia-Pacific region stands at 16.5% in 2025, underlining its role in the global advisory landscape. Regulations supporting foreign investment further enhance market dynamics, creating a favorable environment for advisory services. Overall, these factors contribute to growing demand for advisory services within the region.
The Mergers and Acquisitions Advisory market in South America presents unique characteristics driven by specific economic conditions. Brazil stands out as a primary player within the region, with significant activity in various industries fueling demand for advisory services. The presence of private equity firms and other financial sponsors in Brazil and Argentina enhances engagement in mergers and acquisitions. The market share in South America reflects the evolving dynamics of local investment strategies. Infrastructure development and regulatory factors influence the market, shaping acquisition activities and driving the growth of advisory services. Various sectors, including technology and energy, contribute to the overall expansion of the market within the region.
The Mergers and Acquisitions Advisory market in the Middle East and Africa reflects a growing interest from major economies including Saudi Arabia, UAE, and South Africa. Demand arises primarily from the expanding technology and energy sectors, driven by regional investments and initiatives aimed at diversification. The market benefits from a favorable regulatory environment that encourages foreign investment and facilitates transactions. Infrastructure improvements, particularly in financial services, enhance transaction efficiency and attractiveness. The region's share of the global market stands at 2.7% in 2025, with expectations for gradual growth through 2033. This growth trajectory presents opportunities for advisory firms to expand their presence and service offerings in the market, particularly in cross-border transactions.
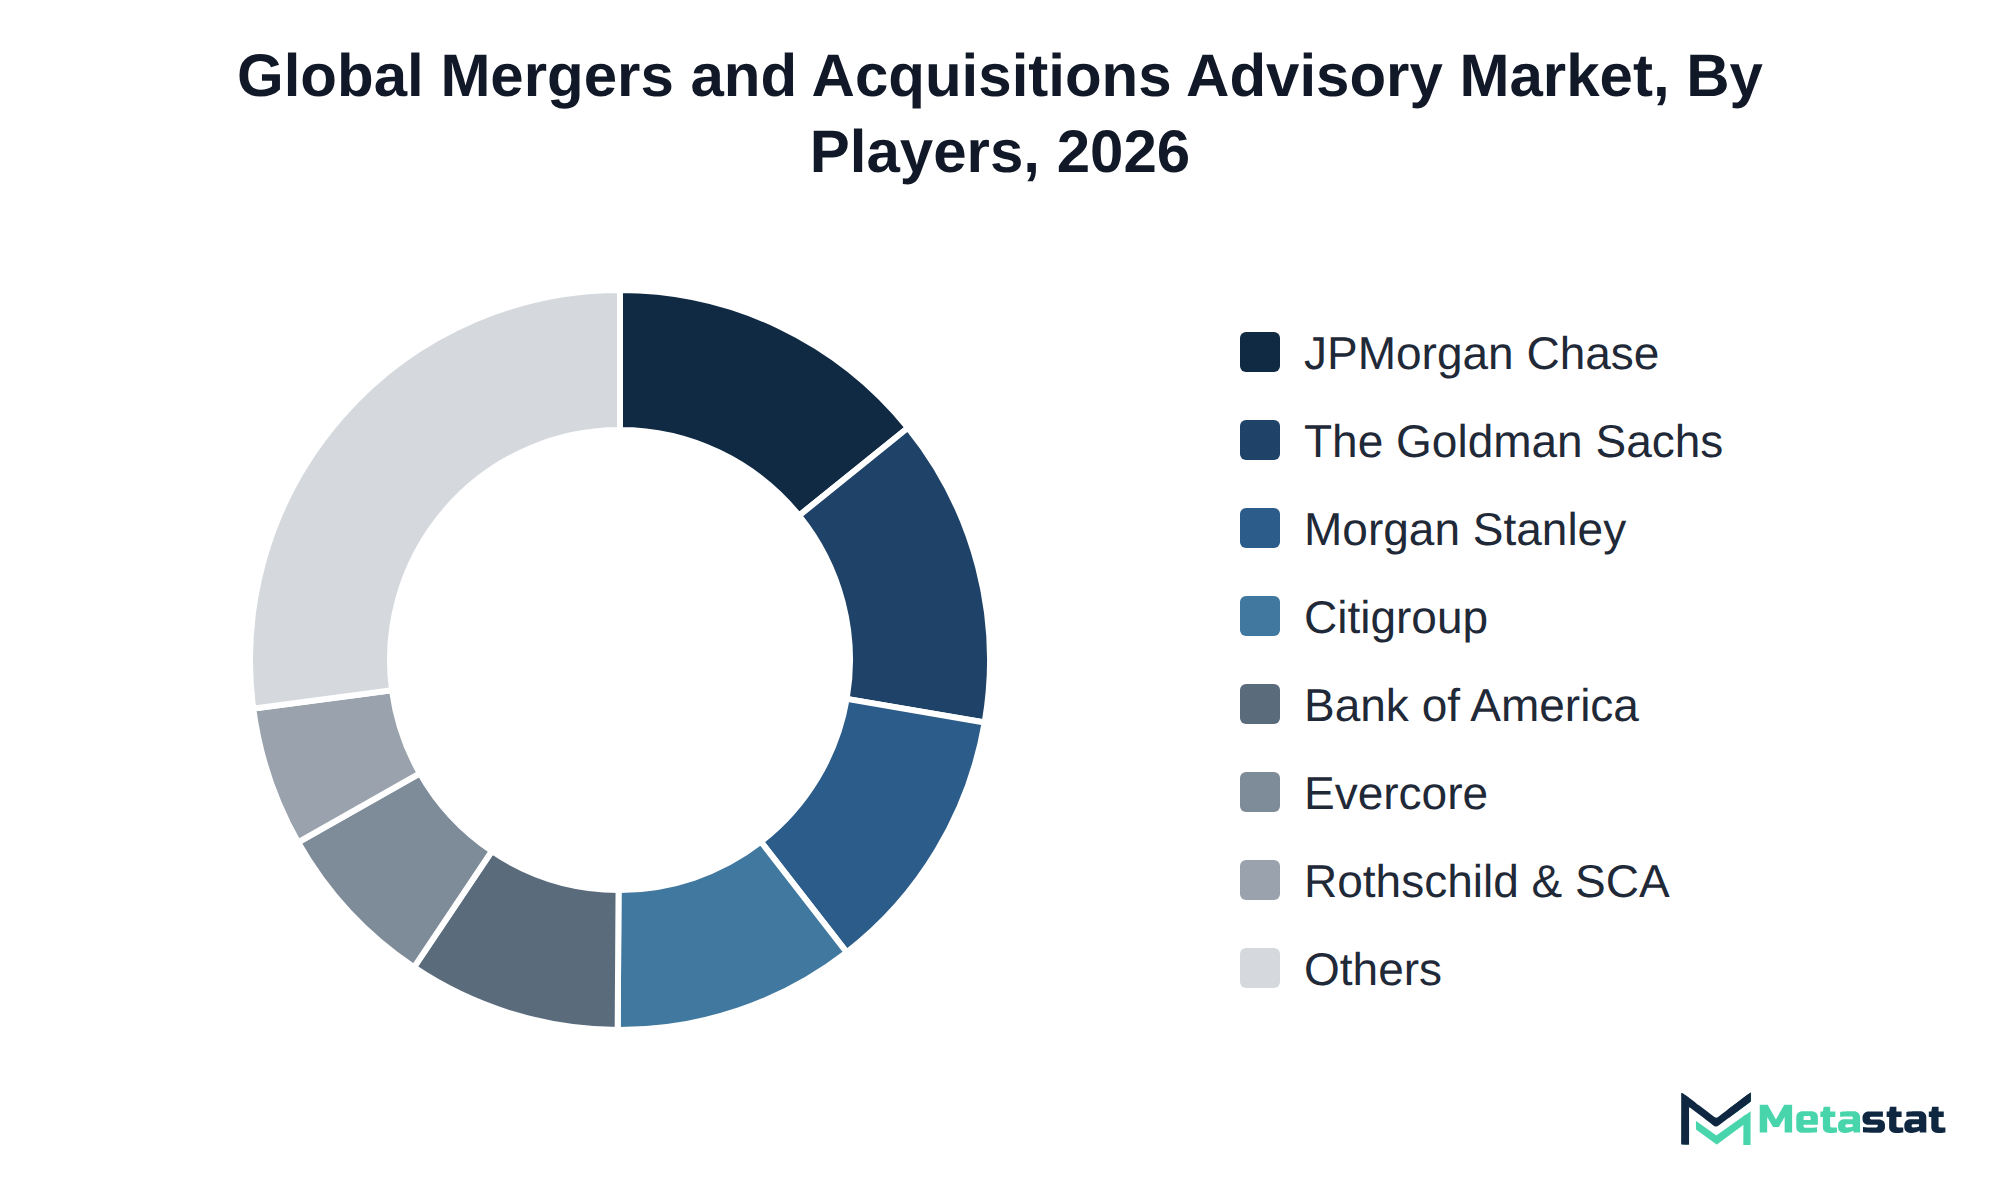
Companies in the Mergers and Acquisitions Advisory market adopt various strategies to differentiate their offerings. Many firms focus on specific advisory mandates, including sell-side or buy-side advisory, to cater to distinct client needs. For example, The Goldman Sachs Group, Inc. emphasizes sell-side advisory, targeting corporations seeking to optimize asset sales.
In contrast, JPMorgan Chase & Co. and Morgan Stanley prioritize buy-side advisory services, supporting private equity firms and financial sponsors in identifying strategic acquisitions. Advisory work of this kind sits within the wider investment banking and trading services industry. The choice of service often hinges on factors including expertise in a particular industry, pricing structures, and the ability to customize solutions for clients.
Buyers in the market select advisory firms based on the quality of service, reputation, and capabilities in handling complex transactions. Citigroup Inc. and Bank of America Corporation excel in providing tailored solutions for large corporations, demonstrating their extensive industry knowledge. In the area of fairness opinions and transaction valuation, firms like Lazard, Inc. and Evercore Inc. draw on their analytical strengths to deliver high-quality assessments that guide client decisions.
Firms seek to enhance their positioning, with a focus on technology, media, and telecommunications becoming increasingly prominent. Companies including UBS Group AG and Houlihan Lokey, Inc. are well-versed in navigating these dynamic sectors, ensuring they remain competitive in the Mergers and Acquisitions Advisory market.
Reaching USD 56.6 billion in M&A advisory by 2033 depends on several key developments. First, the increase in demand from private equity firms and other financial sponsors, projected to reach USD 21.4 billion by 2033, will strengthen the market. This segment's growth reflects rising investment activities and acquisitions in various industries. Second, the expansion of buy-side advisory, expected to achieve USD 22.1 billion during the same period, is crucial. The demand for advisory services in mergers and acquisitions boosts operational efficiencies and strategic growth for corporations. Third, continued activity in domestic transactions, anticipated to grow from USD 31.8 billion in 2026 to USD 37.3 billion by 2033, supports overall market growth by prioritizing local partnerships and investments.
However, economic uncertainties and potential regulatory changes pose risks to this outlook. A slowdown in cross-border transactions, which are projected to reach USD 19.3 billion by 2033, could hinder the market's ability to reach the forecasted value. The Mergers and Acquisitions Advisory market navigates these challenges to achieve its growth potential.
By Advisory Mandate: Sell-Side Advisory, Buy-Side Advisory, Merger Advisory, Standalone Fairness Opinions and Transaction Valuation
By Client Type: Corporations, Private Equity Firms and Other Financial Sponsors, Government and State-Owned Enterprises, Others (Founders and Family Offices)
By Target Industry: Technology, Media and Telecommunications, Industrials and Transportation, Energy and Utilities, Healthcare and Life Sciences, Financial Services, Consumer and Retail, Business Services, Real Estate, Others (Agriculture and Materials)
By Transaction Geography: Domestic Transactions, Cross-Border Transactions
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Mergers and Acquisitions Advisory market.
Report Attributes | Details |
Study Period | 2021-2033 |
Base Year | 2025 |
Estimated Year | 2026 |
Forecast Period | 2026-2033 |
Historical Period | 2021-2025 |
Growth Rate | CAGR 2.7% from 2026 to 2033 |
Revenue Unit | USD billion |
Segmentation | By Advisory Mandate, Client Type, Target Industry, Transaction Geography, and Region |
By Region | North America (By Advisory Mandate, Client Type, Target Industry, Transaction Geography, and Country)
|
Europe (By Advisory Mandate, Client Type, Target Industry, Transaction Geography, and Country)
| |
Asia Pacific (By Advisory Mandate, Client Type, Target Industry, Transaction Geography, and Country)
| |
South America (By Advisory Mandate, Client Type, Target Industry, Transaction Geography, and Country)
| |
Middle East and Africa (By Advisory Mandate, Client Type, Target Industry, Transaction Geography, and Country)
|
Find answers to common questions about this report
The Mergers and Acquisitions Advisory market size was valued at USD 45.4 billion in 2025.
The market is projected to grow at a CAGR of 2.7% during the forecast period from 2026 to 2033.
The North America Mergers and Acquisitions Advisory market size is estimated to reach USD 30.3 billion by 2033.
Sell-Side Advisory leads the Mergers and Acquisitions Advisory market with a value of USD 20.8 billion in 2026. This segment surpasses others in terms of initial market size.
Increasing acquisition opportunities across multiple sectors drive demand for advisory services. The rise in private equity investments and corporate mergers fuels the need for expert guidance to navigate complex transactions effectively.
North America holds the dominant share of the Mergers and Acquisitions Advisory market, with a value of USD 30.3 billion projected for 2033, representing 55.1 percent of the total market.
High transaction costs present a significant restraint, affecting corporations and private equity firms by leading to slower decision-making processes and potentially smaller transaction volumes. The challenge in talent acquisition arises from increased competition for skilled professionals, resulting in higher operational costs and reduced profit margins for advisory firms.
Increasing acquisition opportunities across various sectors and the rising focus on ensuring transactions align with fair market value significantly favor adoption in the Mergers and Acquisitions Advisory industry. Corporations and private equity firms actively seek expert guidance to navigate complex transactions, enhancing demand for tailored advisory services.
The Mergers and Acquisitions Advisory market is estimated to reach a valuation of USD 56.6 billion by 2033.
Key players operating in the Mergers and Acquisitions Advisory market include The Goldman Sachs Group, Inc., JPMorgan Chase & Co., Morgan Stanley, Citigroup Inc., Bank of America Corporation, Evercore Inc., and Raymond James Financial, Inc.
The analysts below cover Banking & Finance research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.
Floating offshore wind feasibility relies heavily on specialized installation vessel availability and port crane limits, which most broad renewable energy forecasts ignore. The report delivered a thorough analysis of dry dock capacity, mooring chain supply constraints, and raw material pricing trends for deepwater anchor installations. It served as a solid independent sanity check for our offshore project capital expenditure assumptions.
Assessing commercial microgrid software adoption requires looking past top-level installation numbers and examining utility interconnection queues. The research provided verifiable data on average permitting timelines, tariff structures, and battery storage integration costs across regional utility territories. That grounded perspective was valuable for our team when building five-year demand projections for industrial microgrid controllers.
Ambulatory surgical centers have very different purchasing cycles for robotic-assisted surgery platforms than major hospital networks. The MetaStat Insight study focused squarely on capital expenditure depreciation, procedural reimbursement pathways, and surgeon training overhead. That operational clarity made it much simpler to validate multi-year procedure growth forecasts against actual ambulatory center adoption patterns.
Explore related market intelligence reports worth reading alongside this one.