
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Cookware Market Size, Share, By Product Type (Pots, Pans, Woks, Pressure Cookers, Bakeware, Kitchen Tools and Accessories), By Material (Stainless Steel, Aluminum, Cast Iron, Carbon Steel, Copper, Ceramic and Stoneware), By Coating Type (Standard / Non-Coated and Non-Stick / Coated), By Distribution Channel (Offline and Online), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-3279
Published
October, 2026
Pages
293 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
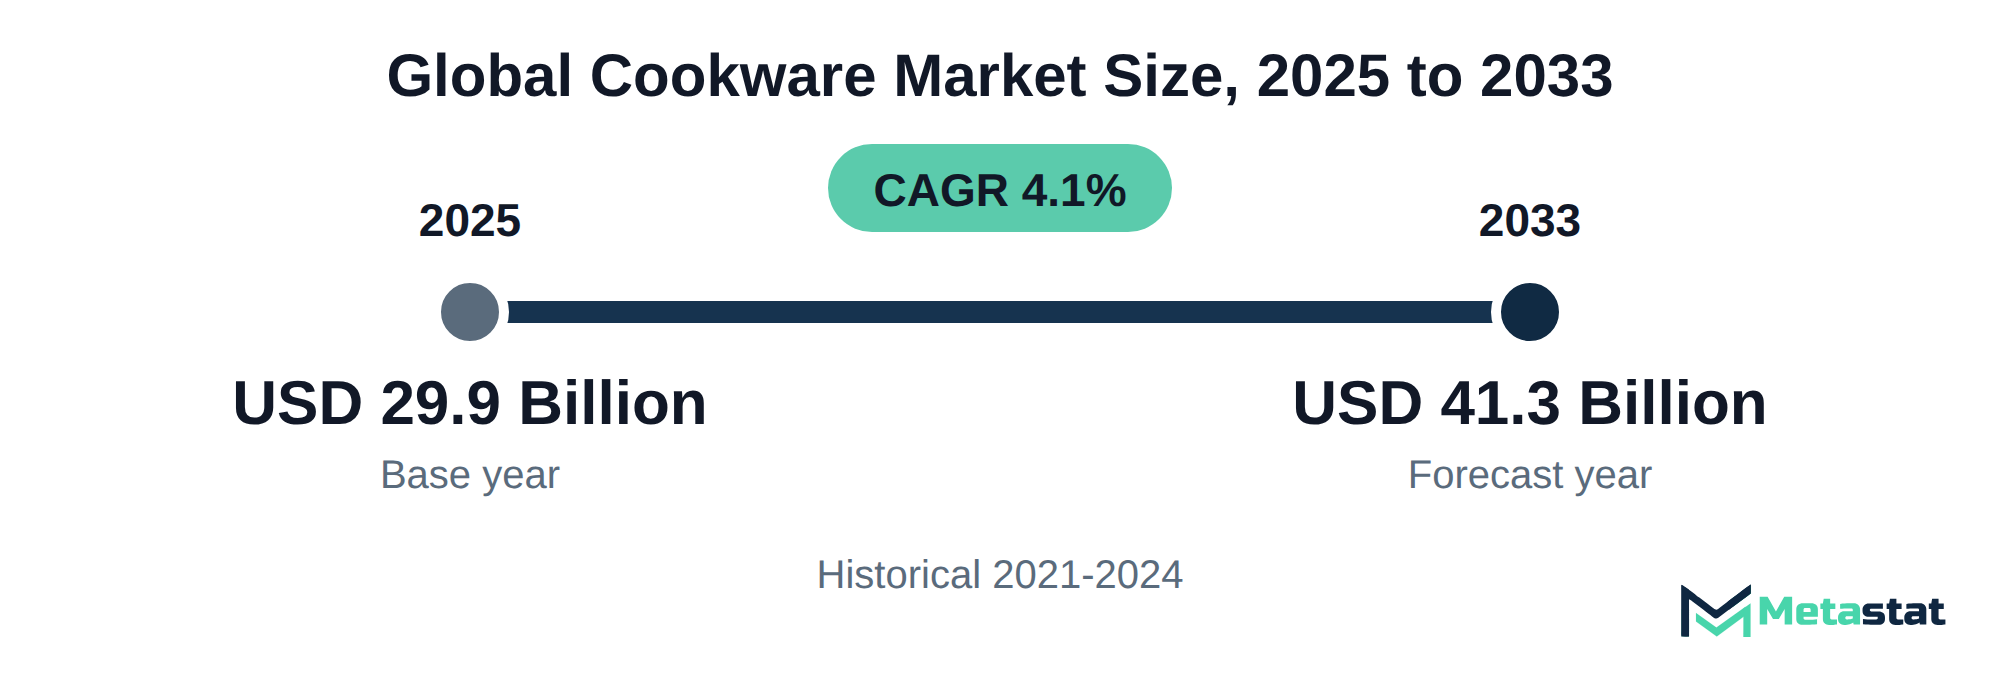
Market Valuation: Valued at $29.9 Billion in 2025, projected to reach $41.3 Billion by 2033 at a 4.1% CAGR.
Dominant Segment: The pans segment leads the cookware market, driven by consumer preference for versatile cooking options suitable for various methods such as frying and sautéing. This category is projected to reach USD 11.4 billion by 2033, reflecting a CAGR of 4.3%.
Geographic Lead: North America holds a significant market share of 31.2% in 2025, with the US projected to lead in 2026. The region's strong growth is attributed to high consumer purchasing power and demand for premium cookware.
What's Inside: The report provides comprehensive coverage of the global cookware market, including detailed analyses of product types, materials, and distribution channels, along with forecasts extending to 2033.
Rising Demand for Eco-Friendly Materials: There is a notable shift towards eco-friendly cookware materials, driven by consumer awareness of sustainability. Buyers increasingly seek products made from recycled aluminum and sustainable wood.
Increased Consumer Interest in Home Cook: Demographic shifts, particularly among millennials and Gen Z, are fueling a rise in home cooking, leading to increased demand for high-quality cookware that enhances cooking experiences.
Choose Your License
Global Cookware Market
The global Cookware market was valued at USD 29.9 billion in 2025 and is projected to reach USD 41.3 billion by 2033, growing at a CAGR of 4.1% over the forecast period.
The cookware market encompasses cooking vessels such as pots, pans, woks, and pressure cookers, serving both professional chefs and home cooks. Buyers invest in this market due to the increasing focus on healthy cooking, convenience, and the desire for durable, high-quality products. Growing culinary interest and the rise of home cooking trends drive demand across various consumer segments.
Growth in the cookware market is propelled by rising consumer awareness regarding healthy cooking practices and the demand for versatile kitchen tools. The segment of pans holds the most value within the overall market, reflecting a significant portion of consumer spending. North America holds 31.2% of the market in 2025, with the US leading in 2026.
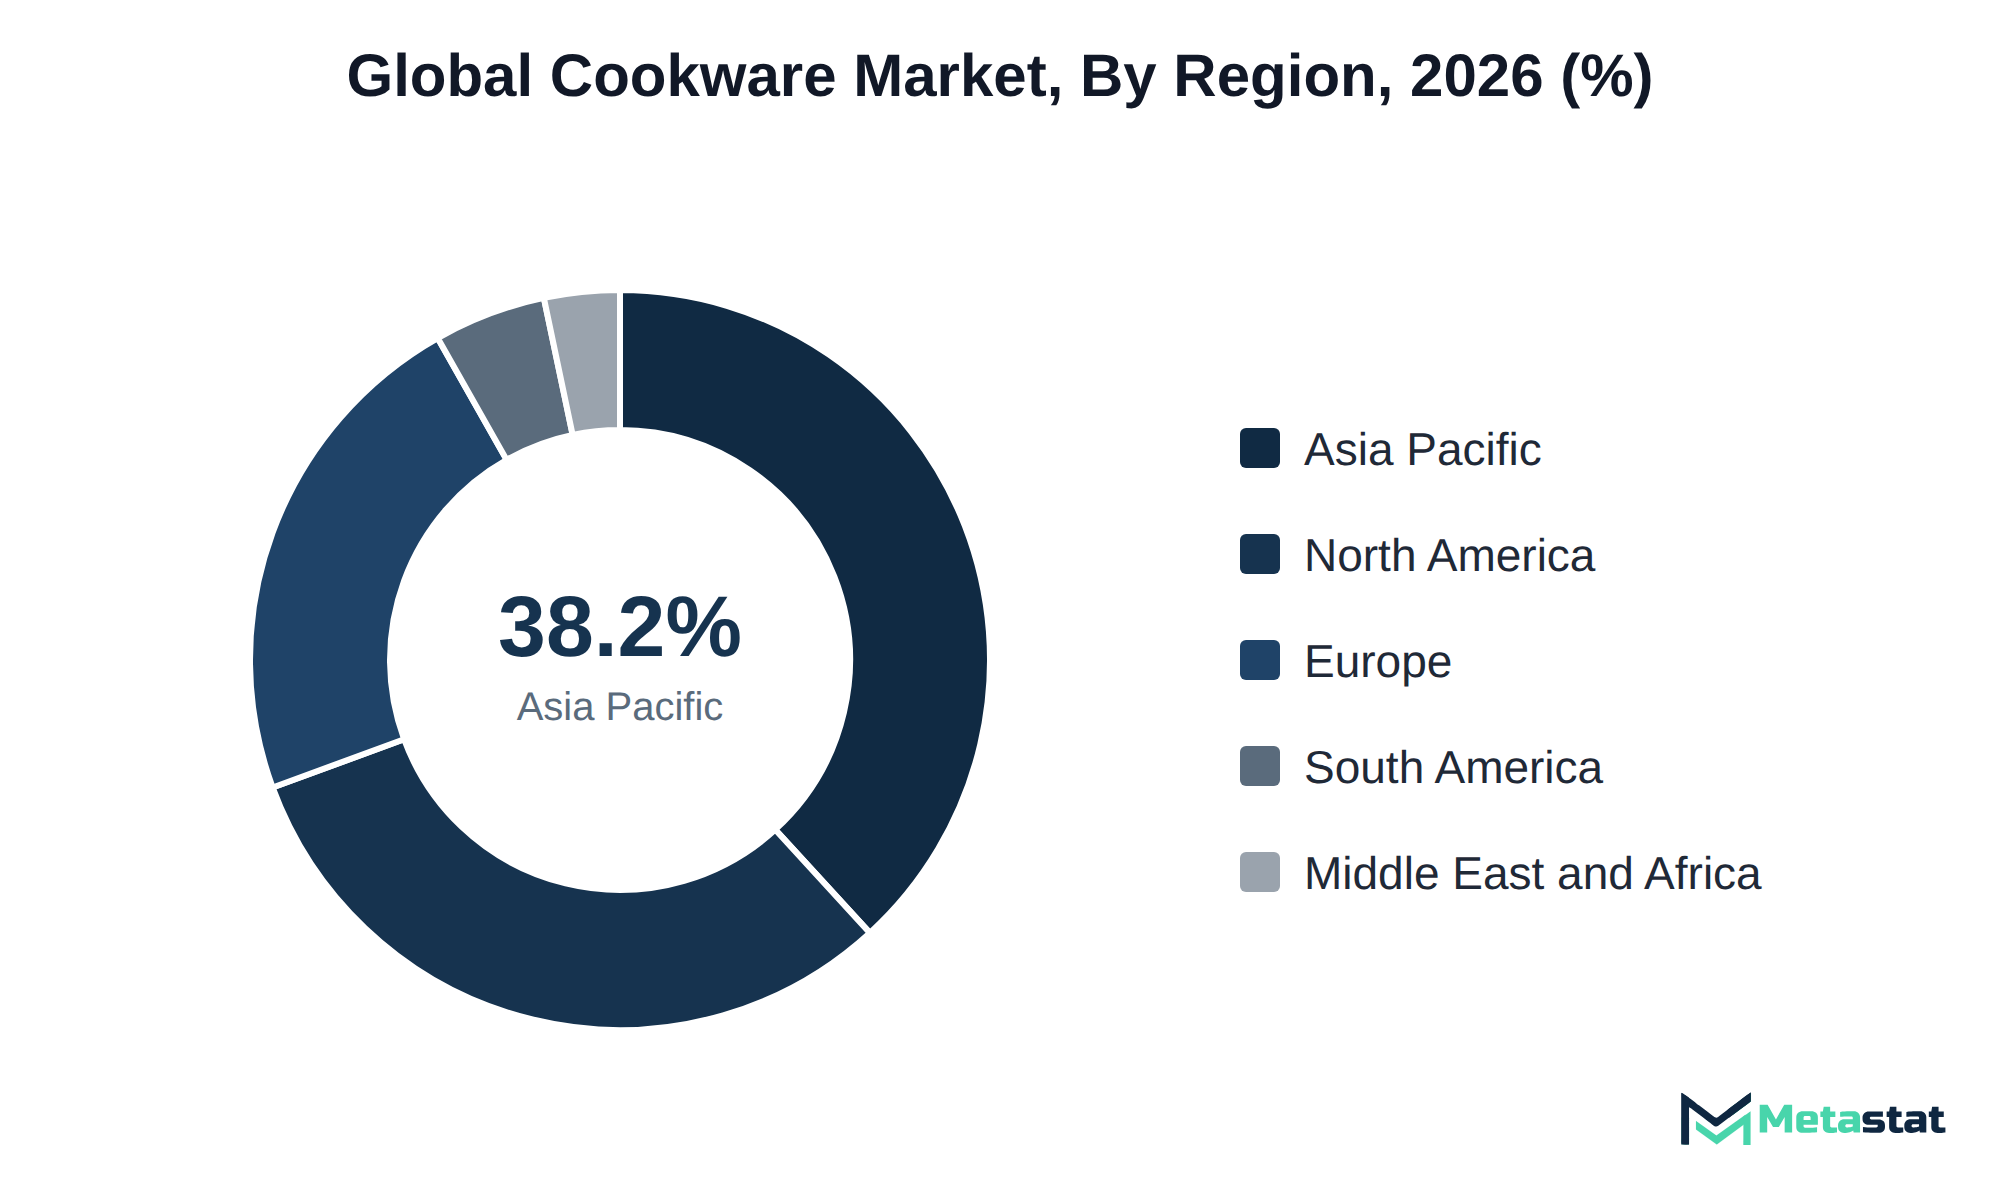
Regional dynamics illustrate varied consumer preferences, with Asia Pacific claiming 38.2% of the market share, following North America. This region's strong growth results from an expanding middle class and increasing urbanization. The ongoing trend toward premium cookware attracts attention, driving further investment in innovative designs and materials.
The cookware market includes various categories of cooking vessels, with buyers investing in these products for their durability, versatility, and efficiency in meal preparation. Different user groups, including professional chefs and home cooks, prioritize quality and functionality, leading to increased expenditures. The market offers a variety of options, ranging from traditional pots and pans to specialized tools, catering to diverse culinary needs and preferences. Cookware also sits within the wider homeware category.
Growth in the market is driven by rising consumer interest in home cooking and culinary experiences. Among the product segments, pans represent the highest value, contributing significantly to overall market revenue. This region's strong purchasing power and demand for high-quality cookware support continued expansion.
Technological advancements in cookware materials and design enhance performance and attract buyers. Non-stick and coated options, along with stainless steel and aluminum materials, enjoy strong popularity. These innovations improve cooking experiences and align with evolving consumer preferences for healthier cooking solutions. The combination of increased consumer interest and product innovation positions the market for sustained growth.
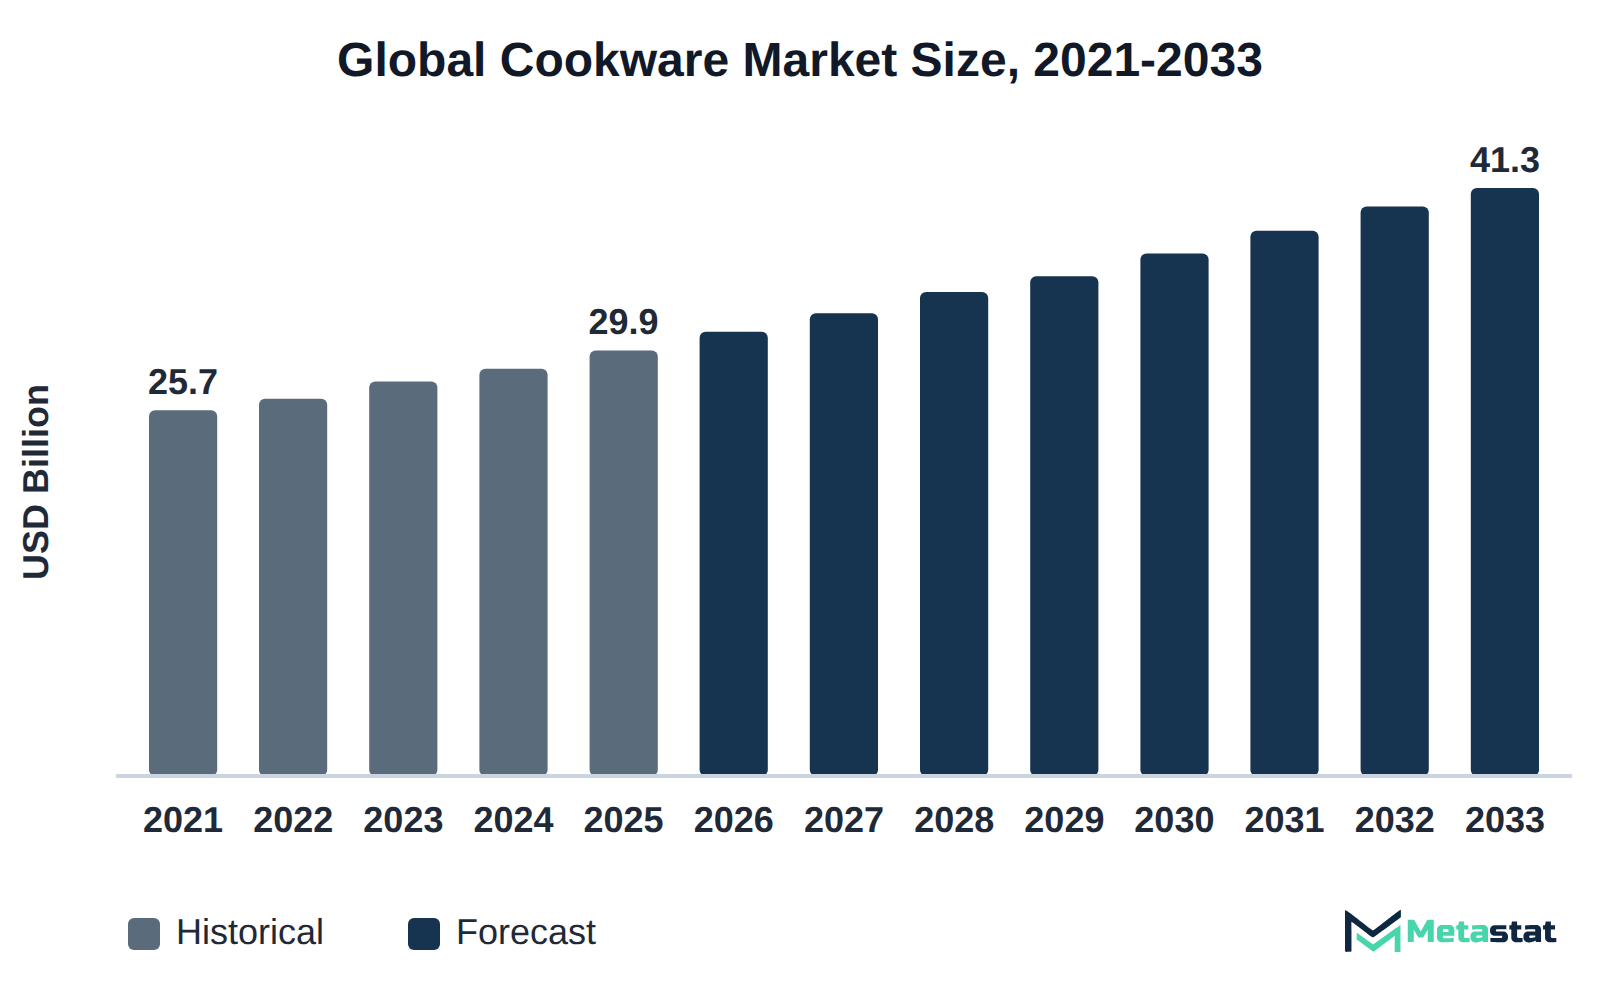
The cookware market experiences a significant shift towards stainless steel and ceramic materials. Stainless steel cookware enjoys a projected growth rate of 4.4% from 2026 to 2033, with values expected to rise from USD 10.7 billion to USD 14.4 billion. This trend reflects consumer preferences for durability, ease of maintenance, and resistance to corrosion.
In parallel, ceramic cookware attracts attention for its non-reactive properties and aesthetic appeal, which align with health-conscious consumer trends. This material provides an alternative to traditional non-stick surfaces, appealing to buyers seeking safer cooking options. The market for non-stick/coated cookware is anticipated to reach USD 23 billion by 2033, driven by demand for healthier cooking solutions.
The increasing adoption of stainless steel and ceramic cookware supports market expansion, responding to evolving consumer preferences. Innovation in cookware materials is central to competitive positioning in the market. Suppliers focusing on these materials enhance their appeal among health-conscious consumers and capitalize on changing perceptions regarding cookware safety and performance.
The cookware market is experiencing a significant shift toward nonstick coatings, reflecting evolving consumer preferences for convenience and ease of use. Nonstick cookware appeals to a diverse range of buyers, from home cooks to professional chefs, due to its ability to reduce the need for added fats while facilitating effortless food release and cleanup. The segment for non-stick or coated cookware is projected to reach USD 23 billion by 2033, driven by increasing adoption across various cooking styles.
Safety regulations on nonstick coatings strongly shape buyer decisions. These regulations ensure that coatings meet specific safety standards, addressing concerns regarding harmful substances. Compliance with safety rules influences pricing and purchasing processes, as manufacturers invest in safer materials and technologies to meet regulatory requirements. Buyers often seek products certified to comply with safety standards, ensuring that their selections do not expose their families to potential health risks. The increased focus on safety drives demand and shapes pricing strategies, further enhancing the competitive landscape of the market.
While manufacturers focus on redesigning products, they integrate innovative materials and technologies that align with consumer expectations for safety and performance. This evolution within the market encourages greater investment in research and development, enabling firms to differentiate themselves by offering superior nonstick solutions. Ongoing advancements in nonstick cookware enhance consumer satisfaction and contribute to long-term growth within the industry.
Online cookware retail continues to expand rapidly, driven by increasing demand from younger consumers who prioritize convenience and accessibility. This demographic often seeks innovative and aesthetically pleasing options, which online platforms present effectively. The market reflects this trend, with online distribution channels projected to reach USD 9.6 billion by 2033, demonstrating a compound annual growth rate of 5.1% during the forecast period.
While consumers become more comfortable with digital shopping, they turn to online platforms for a diverse range of cookware products, including specialty items that traditional retail locations do not stock. Retailers therefore need e-commerce strategies that improve user experience and keep product offerings aligned with the preferences of their target audience.
The growing online segment offers significant commercial opportunities for cookware manufacturers and retailers. Engaging with consumers through digital marketing and social media directly influences purchasing decisions, driving sales growth in the market. Retailers that use these digital channels well are likely to capture a larger share of the increasing demand for cookware among tech-savvy consumers.
Growth in specific cookware categories and materials significantly influences the overall Cookware market. The demand for pans is projected to reach USD 11.4 billion by 2033, reflecting a compound annual growth rate (CAGR) of 4.3%. This increase is driven by consumer preference for versatile cooking options, with pans suitable for various cooking methods, including frying, sautéing, and baking. The versatility of pans, along with ongoing innovations in design and material, supports their rising popularity among home cooks and professional chefs.
In terms of materials, stainless steel cookware is anticipated to gain substantial traction. This growth results from the material's durability, resistance to rust, and ease of maintenance. Stainless steel cookware attracts health-conscious consumers due to its non-reactive properties and ability to withstand high temperatures without compromising food quality. The increasing consumer focus on quality and the trend toward premium cookware contribute to the expanding market share of stainless steel products.
Demographic shifts significantly influence purchasing behavior in the cookware market. Increased numbers of millennials and Gen Z consumers are adopting home cooking habits, driven by lifestyle changes and a growing emphasis on health and sustainability. This demographic prioritizes high-quality cookware that enhances cooking experiences and promotes healthier meal preparation. The rise in home cooking has driven demand for various cookware types, including pots and pans, with these consumers seeking reliable tools for their culinary activities. While more individuals embrace cooking at home, the volume of cookware sales is expected to rise, further contributing to market growth. Higher spending on cookware reflects evolving consumer preferences and the importance of quality and functionality in culinary tools.
A significant pivot towards eco-friendly materials influences the cookware market, driven by increasing consumer awareness regarding sustainability. Buyers increasingly seek products made from environmentally friendly materials, including recycled aluminum and sustainable wood, reflecting a broader trend of responsible consumption. This shift aligns with the growing desire to minimize environmental impact while maintaining functionality and aesthetic appeal in cookware products.
Manufacturers adapt to these changing preferences by investing in renewable production processes and sourcing sustainable materials. This commitment to sustainability meets consumer demand while enhancing brand reputation and loyalty among environmentally conscious buyers. Producers that embrace eco-friendly practices gain competitive advantages, allowing them to capture a larger market share. Continued innovation in eco-friendly cookware is expected to support long-term growth, with the market projected to expand steadily through 2033.
Increasing raw material costs significantly affect consumer purchasing behavior in the cookware market. Buyers, particularly in the residential segment, experience slower uptake due to rising prices for essential materials including stainless steel and aluminum. This situation leads to smaller orders and delayed replacement cycles for existing cookware. Consumers prioritize value, and heightened prices push them toward cheaper alternatives or second-hand options, impacting overall sales growth. The pressure on pricing results in an environment where manufacturers face challenges in maintaining profit margins while trying to offer competitive pricing. Consequently, the market's expansion encounters obstacles, restricting broader adoption across various consumer demographics. The persistent rise in raw material costs necessitates strategic adjustments from manufacturers to address consumer concerns regarding affordability and accessibility.
Rising costs of raw materials present a significant challenge for suppliers in the cookware market. Increased prices for essential materials like stainless steel and aluminum impact production expenses, squeezing margins. Suppliers respond by exploring alternative materials and enhancing operational efficiency. Innovations in manufacturing processes and supply chain management help mitigate cost increases while maintaining product quality. Several suppliers focus on premium product offerings, allowing for higher pricing strategies that offset input costs. Ongoing pressure on profitability influences investment decisions and market dynamics, driving suppliers to adapt their strategies to maintain competitiveness. Regular review of sourcing and production practices remains important for sustaining growth and profitability.
Increasing online sales of cookware reflect a significant growth opportunity within the market, driven by a shift in consumer purchasing habits. Younger consumers increasingly prefer the convenience and accessibility of online shopping, leading to higher engagement with e-commerce platforms. This trend creates a favorable environment for brands to enhance their online presence and capitalize on digital marketing strategies.
Online sales allow for wider product offerings and the ability to present unique features, which appeal to consumers seeking specific cookware types and materials. Brands that invest in user-friendly websites and targeted online promotions are likely to see increased sales and brand loyalty. The rise in online cookware sales supports revenue growth and expands market reach, enabling suppliers to connect with a broader customer base seeking diverse cookware solutions.
The Global Cookware market is segmented based on Product Type, Material, Coating Type, and Distribution Channel.
Pots segment is valued at USD 7.3 billion in 2026 and is projected to reach USD 9.5 billion by 2033, at a CAGR of 3.8% during the forecast period. These cooking vessels serve various culinary purposes, appealing to both home cooks and professional chefs. Rising interest in home cooking drives demand for pots, particularly among consumers seeking convenience and versatility in meal preparation. Compared to other segments, including pans, which are expected to grow at a higher CAGR of 4.3%, pots show moderate growth. The enduring popularity of pots stems from their essential role in cooking, facilitating the preparation of a variety of dishes. Innovations in materials and designs enhance their appeal, attracting consumers focused on durability and functionality. The market increasingly caters to a diverse range of culinary preferences, reinforcing pots' position in the cookware market.
These versatile cooking vessels serve a broad audience, from home cooks to culinary professionals, facilitating various cooking techniques including frying, sautéing, and searing. The rising trend toward health-conscious cooking fuels demand, with consumers increasingly preferring non-stick options that require less oil. This segment distinguishes itself from other cookware types due to its faster growth rate and broader consumer appeal. While stainless steel and cast iron serve specific niches, pans attract a wider demographic, reflecting a shift in consumer preferences toward convenience and ease of use. The market experiences strong competition, leading to innovation in materials and technologies to enhance performance, ultimately supporting sustained growth throughout the forecast period.
The woks segment is expected to reach USD 3.5 billion by 2033. Woks are versatile cooking vessels, popular among both professional chefs and home cooks for their ability to stir-fry, steam, and sauté. Growing interest in Asian cuisine drives demand for this segment, influencing buyers from various culinary backgrounds. The segment's growth rate, while steady, lags behind pans with a CAGR of 4.3%. Woks generally appeal to consumers seeking authentic cooking experiences, differentiating them from other cookware types that prioritize different cooking styles. In terms of pricing, woks typically offer a range of options, with high-quality models commanding premium prices due to their craftsmanship and materials. The market for woks reflects the increasing popularity of diverse cooking methods, positioning itself favorably in the broader cookware market.
Pressure cookers segment is projected to grow at a CAGR of 3.6% during the forecast period. These cooking vessels are popular among home cooks and professional chefs for their ability to prepare meals quickly while retaining flavor and nutrients. The demand for pressure cookers is influenced by the increasing preference for time-efficient cooking solutions and the rising interest in home cooking due to lifestyle changes. Compared to other categories, including pans and pots, pressure cookers offer unique advantages in meal preparation speed, contributing to their growth. The segment faces competition from alternative cooking methods and small kitchen appliances, yet remains distinct due to its specific functionality and appeal to health-conscious consumers. This market reflects broader trends in consumer preferences, focusing on convenience and efficiency in culinary practices.
Bakeware includes various products designed for preparing and baking a wide range of dishes, primarily in ovens. Consumers, including both home cooks and professional bakers, apply bakeware for its versatility in cooking different types of baked goods, including bread, pastries, and casseroles. Demand for innovative designs and materials that enhance cooking performance drives interest in this segment. The increasing focus on health-conscious cooking influences the adoption of materials that promote healthier baking options. Compared to other segments, bakeware commands a higher price point due to specialized functions and materials; its growth trajectory aligns with broader trends in the market. Buyers prioritize durability and ease of use when selecting these products, which sets bakeware apart from traditional cookware categories.
Kitchen tools and accessories serve essential purposes in meal preparation and cooking, enhancing efficiency and convenience for both professional chefs and home cooks. This segment includes various items including spatulas, measuring cups, and cutting boards, which support diverse culinary tasks. Increasing consumer interest in multifunctional kitchen tools significantly drives demand, reflecting a trend toward versatile cooking solutions. Unlike other product types in the market, kitchen tools and accessories often feature lower prices, attracting budget-conscious consumers. The rising popularity of online shopping has facilitated greater access to these products, allowing buyers to explore a broader range of options. The unique attributes of this segment position it favorably within the overall dynamics of the cookware market.
Specialty cooking vessels encompass a diverse range of products designed for niche culinary applications, appealing to both home cooks and professional chefs. These vessels are essential for specific cooking techniques or regional cuisines, facilitating unique culinary experiences. Demand for specialty cooking vessels increases due to rising interest in gourmet cooking and culinary exploration, attracting consumers seeking distinctive cooking tools. Unlike mainstream cookware categories, these products typically command higher prices due to their specialized design and functionality. The market for cookware reflects a growing appreciation for culinary diversity, encouraging producers to innovate and expand their offerings. Specialty cooking vessels differentiate themselves by targeting enthusiasts who prioritize quality and unique cooking methods, positioning this segment distinctly within the broader cookware market.
This material is favored for its durability and resistance to corrosion, making it suitable for various cookware applications. Professional chefs and home cooks widely use stainless steel cookware, providing excellent heat conductivity and versatility for different cooking methods. Increased consumer preference for high-quality and long-lasting products drives demand for this segment. Compared to aluminum and cast iron, stainless steel experiences a moderate growth rate, reflecting a steady shift towards premium cookware options. The material's superior performance in terms of safety and longevity further differentiates it from others in the market, providing a compelling choice for discerning buyers.
Aluminum segment is estimated to reach USD 13 billion by 2033, at a CAGR of 3.9% during the forecast period. This material is commonly used for a variety of cookware items, including pots and pans, appealing to both home cooks and professional chefs. Growing consumer preference for lightweight and durable cookware drives demand, particularly among younger demographics who prioritize ease of use and maintenance. Competitive pricing of aluminum cookware attracts a broader consumer base, positioned lower than premium materials like stainless steel. While the aluminum segment experiences steady growth, it faces competition from alternative materials including stainless steel and cast iron, which consumers perceive as more durable or traditional. The market adapts to consumer preferences, ensuring aluminum cookware remains a staple in kitchens worldwide.
Cast Iron segment is expected to reach USD 5.3 billion by 2033. Cast iron cookware is renowned for its durability and heat retention, making it ideal for a variety of cooking methods including frying, baking, and sautéing. Home cooks and professional chefs prefer these products for their ability to develop a natural non-stick surface over time, enhancing cooking performance. Demand for cast iron cookware is influenced by the growing trend of traditional cooking techniques and the preference for long-lasting materials. Compared to other materials like stainless steel and aluminum, cast iron typically enjoys a slower growth rate due to its higher price point and weight, but it appeals to a niche market that values craftsmanship and culinary heritage. The market experiences steady interest driven by the resurgence of home cooking and appreciation for high-quality kitchenware.
Carbon Steel segment is projected to grow at a CAGR of 4.7% during the forecast period. This material is valued for its durability and ability to withstand high temperatures, making it a popular choice among professional chefs and home cooks seeking reliable cookware. The increasing focus on traditional cooking methods drives demand for carbon steel cookware, which delivers excellent heat retention and even cooking results. Unlike aluminum or stainless steel, carbon steel requires proper seasoning to enhance its non-stick properties, which poses a challenge for several users. However, its growing recognition in culinary circles for creating superior searing and browning results supports its expansion, especially among enthusiasts and professionals dedicated to high-quality cooking performance. In comparison, other materials like aluminum exhibit competing growth rates, but carbon steel’s niche positioning offers a unique appeal that differentiates it within the market.
Copper is a high-performance material in cookware, known for its excellent thermal conductivity and aesthetic appeal. Professional chefs and culinary enthusiasts frequently choose copper cookware for its ability to provide precise temperature control, enhancing cooking techniques. Demand for copper cookware is driven by increasing consumer interest in high-quality cooking tools that offer superior performance. This sub-segment differs from others, including stainless steel or aluminum, often commanding higher prices due to the material's premium nature and the craftsmanship involved in its production. The market remains influenced by trends emphasizing artisanal cooking and gourmet experiences, which strengthen copper's position as a sought-after choice among discerning buyers.
Ceramic and stoneware cookware includes a variety of items valued for their aesthetic appeal and effective heat retention. This segment finds use among home cooks and professional chefs alike, serving purposes from slow cooking to baking. The popularity of ceramic coatings aligns with consumer preferences for non-toxic cooking surfaces, presenting advantages over traditional materials. A trend toward healthier cooking options enhances demand for this segment, particularly among health-conscious consumers. While ceramic and stoneware cookware does not exhibit the rapid growth rates of non-stick alternatives, it stands out due to its durability and visual appeal. This segment appeals to a niche market prioritizing style and function, differentiating itself from conventional materials through unique design elements and cooking benefits. The cookware market benefits from evolving consumer tastes, creating an environment conducive to sustained interest and growth.
This sub-segment includes materials like glass, enamelled steel, and composites, which appeal to consumers seeking unique aesthetic options and specific cooking benefits in their cookware. Glass cookware offers non-reactive properties, making it suitable for various cooking techniques, while enamelled steel cookware provides durability and easy maintenance, often preferred by home cooks and professional chefs. The rising demand for eco-friendly and non-toxic cooking options drives interest in these specialized materials. Unlike traditional materials including stainless steel and aluminum, which are widely used, glass and enamelled steel often command higher prices due to their unique properties. This pricing structure leads to a more niche market, attracting consumers willing to invest in specialized cookware that enhances culinary experiences and aligns with preferences for healthier cooking methods. The cookware market evolves, reflecting changes in consumer tastes and trends.
Standard / Non-Coated segment is valued at USD 14.2 billion in 2026 and is projected to reach USD 18.3 billion by 2033, at a CAGR of 3.7% during the forecast period. This segment serves basic cooking applications, appealing to both home cooks and professional chefs seeking reliable cookware. Growth in this segment is driven by the increasing preference for traditional cooking methods and rising awareness of health concerns related to non-stick coatings. Compared to the Non-Stick / Coated segment, which is projected to reach USD 23 billion by 2033 at a CAGR of 4.4%, the Standard / Non-Coated segment exhibits a slower growth trajectory. Its appeal lies in affordability and simplicity, attracting budget-conscious consumers while maintaining steady demand in the cookware market.
This segment serves a wide audience, including casual cooks and professional chefs, offering convenience and ease of cooking with reduced food sticking. Rising demand for healthier cooking options drives this segment, with consumers seeking alternatives that require less oil and fat. The appeal of non-stick cookware lies in its simplicity of use and cleaning. Compared to the Standard / Non-Coated segment, which has a CAGR of 3.7%, the Non-Stick / Coated segment experiences faster growth due to these consumer preferences. The market’s expansion is further supported by advancements in coating technologies that enhance durability and performance, positioning this segment as a significant player in the cookware market.
Offline segment is valued at USD 24.4 billion in 2026 and is projected to reach USD 31.7 billion by 2033, at a CAGR of 3.8% during the forecast period. This segment serves consumers looking to purchase cookware through traditional retail methods, including department stores, specialty shops, and supermarkets. The preference for an in-person shopping experience drives this segment, with many buyers valuing the ability to physically inspect products before making a purchase. Compared to online channels, which are projected to grow at a CAGR of 5.1%, the offline segment shows slower growth. The tactile experience offered in offline retail attracts buyers seeking immediate fulfillment, contrasting the convenience and broader selection typically found in online platforms. The ongoing popularity of physical retail locations reinforces the segment's importance in the overall cookware market.
This segment facilitates the purchase of cookware through digital platforms, appealing primarily to tech-savvy consumers and younger generations who prefer the convenience of online shopping. Increased internet penetration and a shift toward e-commerce significantly drive growth. In addition, promotional activities and targeted marketing by retailers enhance visibility and access to a broader audience. Compared to offline channels, the online distribution channel exhibits faster growth, reflecting changing consumer preferences toward digital purchasing. The market benefits from the flexibility and variety that online platforms provide, allowing buyers to explore diverse product options and price ranges with ease.
Based on geography, the Global Cookware market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Demand for cookware in North America derives significantly from the cooking habits of consumers in the United States, Canada, and Mexico. Growth in the culinary sector, driven by increased interest in home cooking and gourmet food preparation, supports market expansion. The region's share of the global cookware market stands at 31.2% in 2025, reflecting its strong consumer base and purchasing power. North America is projected to reach USD 12.5 billion by the end of 2033. The online distribution channel is gaining traction, driven by the convenience of e-commerce platforms, appealing to tech-savvy consumers seeking a diverse range of cookware options. This trend enhances the competitive landscape within the market, promoting innovation and variety among suppliers.
Germany, France, the UK, Italy, and Spain drive significant demand in the cookware market due to strong culinary traditions and high consumer spending on kitchenware. The region benefits from a well-developed retail infrastructure, enhancing accessibility for consumers seeking quality cookware. Innovation in design and functionality stands out, appealing to both home cooks and professional chefs. Increasing awareness of health-conscious cooking supports growth in non-stick and coated cookware segments. Sustainability trends influence purchasing decisions, with consumers favoring eco-friendly materials and manufacturing processes. This shift impacts manufacturers, pushing them to adapt to consumer preferences while maintaining competitive pricing. By 2025, Europe holds a market share of 22.4%, reflecting its established position within the global cookware market.
The Asia Pacific region stands out for its significant contribution to the cookware market, holding a 38.2% share of the global market in 2025. Countries including China, Japan, and India drive demand through a rising middle class and increasing disposable incomes, fueling the need for modern cookware solutions. Urbanization trends lead to high demand for innovative cookware that aligns with contemporary lifestyles. Infrastructure improvements, particularly in e-commerce, enable consumers to access a diverse range of products. The online distribution channel experiences strong growth, supporting a dynamic shift in purchasing behavior. Australia and Southeast Asia reflect emerging markets with unique culinary preferences, further enhancing the overall dynamics of the cookware market.
In South America, the cookware market generates demand primarily from households focusing on improving culinary experiences. Brazil and Argentina lead in consumer interest driven by a growing trend toward home cooking and meal preparation. A range of factors influences this shift, including urbanization and increased disposable income among middle-class families. Local manufacturers and international brands compete to satisfy the evolving tastes of consumers. This competitive environment encourages innovation in product offerings, particularly in non-stick and specialty cookware. The region's share of the global cookware market is projected to hold 4.9% in 2025, indicating its emerging potential.
The cookware market in the Middle East and Africa is driven by growing culinary trends and the rising number of households investing in kitchen essentials. Key markets include Saudi Arabia, the UAE, and South Africa, where consumers increasingly seek high-quality cooking tools. Local manufacturers face challenges related to infrastructure and supply chain efficiencies, impacting product availability and pricing. The region's share of the global market in 2025 stands at 3.3%, indicating a modest yet stable demand landscape. The market experiences interest in both traditional and modern cookware, with specific awareness of materials that enhance cooking performance and sustainability. This dynamic environment encourages manufacturers to adapt their offerings, targeting diverse consumer preferences and culinary practices.
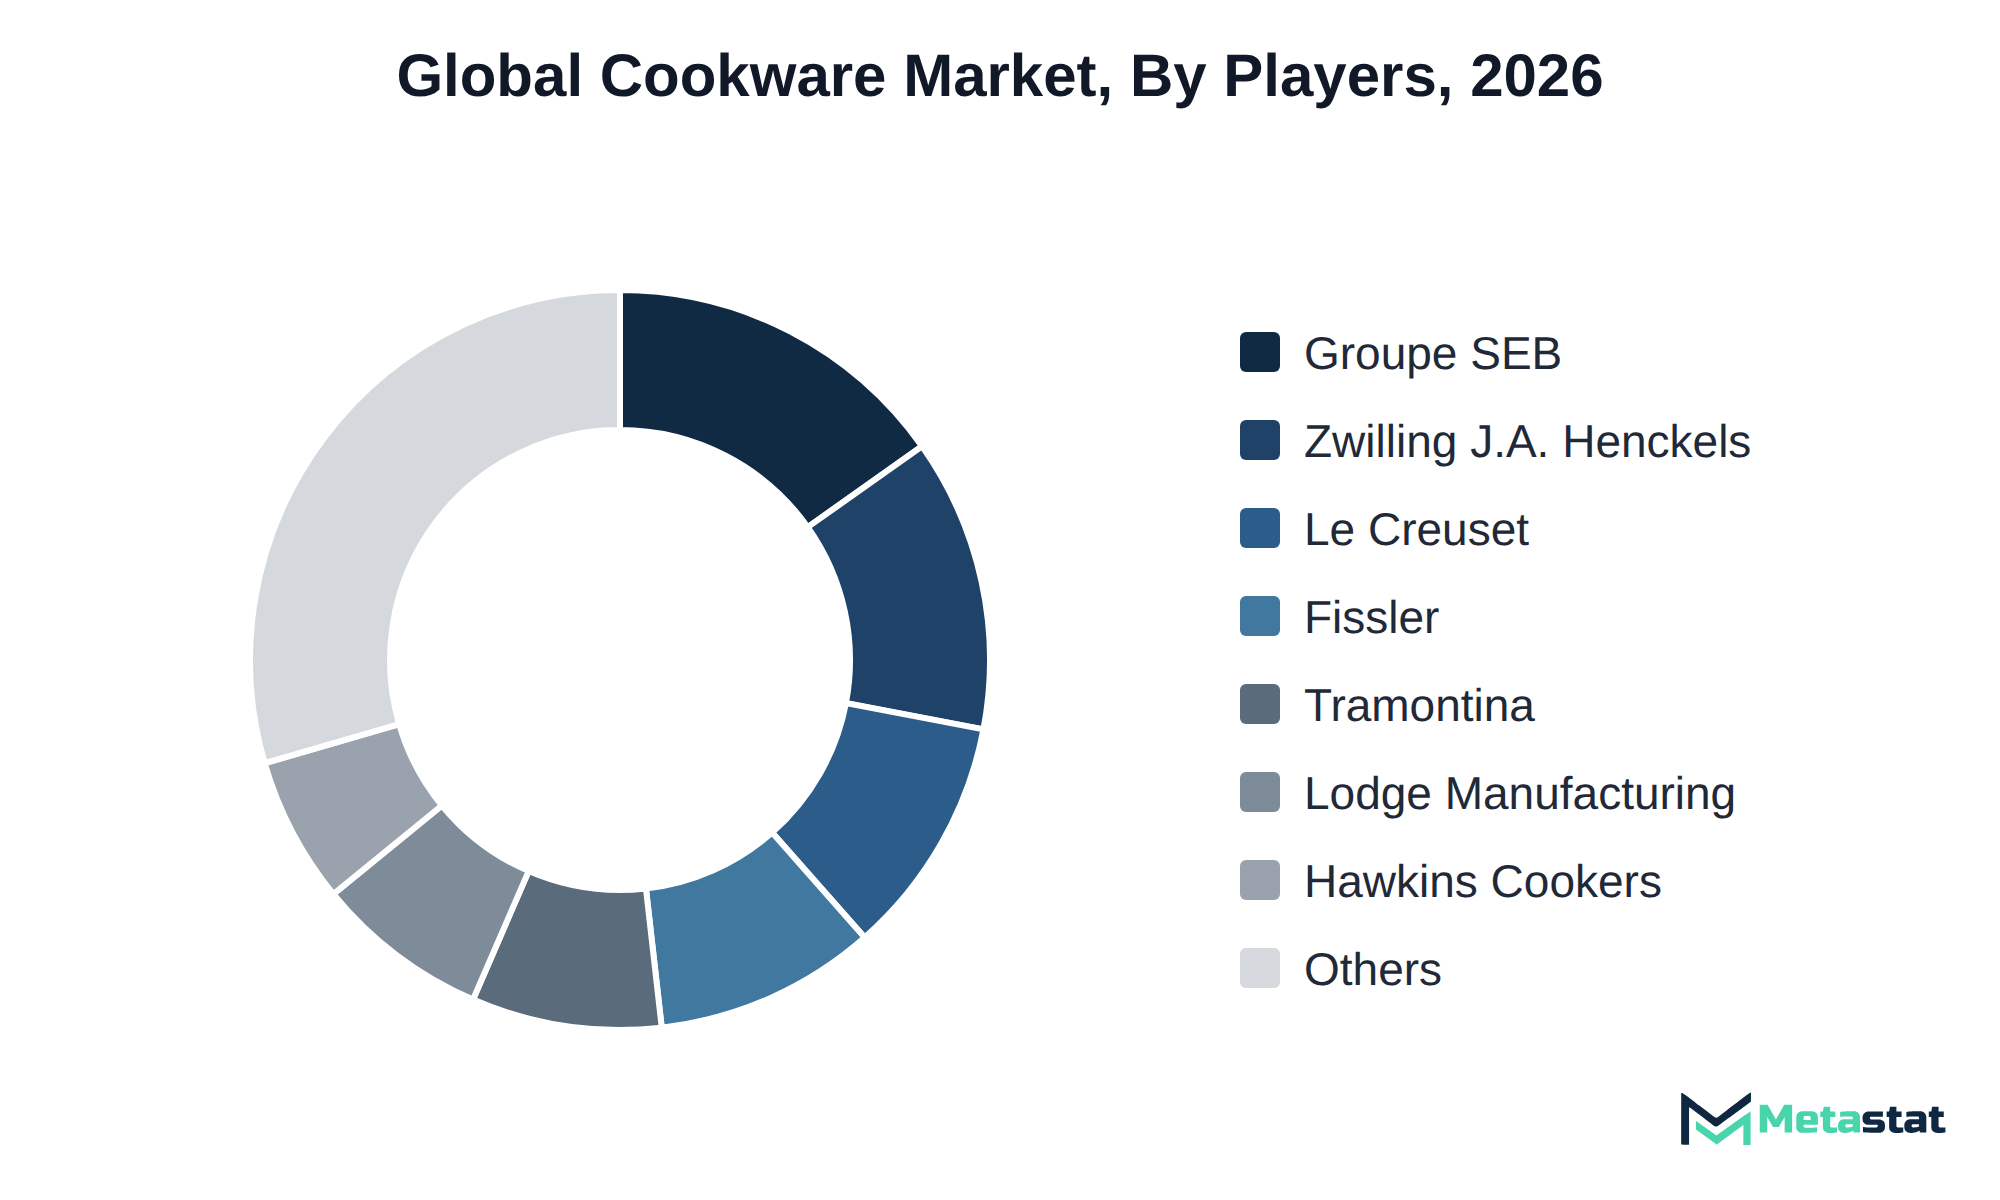
The Cookware market features varied strategies among key players. Companies focus on different segments, including material types and product offerings, targeting specific buyer needs. For instance, Groupe SEB emphasizes innovation in cookware technology and a broad product range, appealing to consumers seeking high-quality kitchen tools. In contrast, Tramontina prioritizes affordability and accessibility, addressing price-sensitive buyers with a selection of functional cookware.
Product differentiation remains crucial in the market. Le Creuset, known for its premium cast iron cookware, targets consumers desiring high-end products that offer aesthetic appeal alongside superior performance. On the other hand, HexClad leverages a unique hybrid technology, attracting buyers interested in non-stick performance combined with durability. The competitive landscape reflects these varied approaches, catering to distinct buyer preferences while driving overall growth.
The market expansion relies on several key developments. First, increasing consumer preference for premium cookware drives demand, particularly for stainless steel and non-stick cookware, which are projected to experience significant growth rates. Second, the ongoing shift towards e-commerce platforms enhances accessibility, with online sales anticipated to reach USD 9.6 billion by 2033, reflecting a CAGR of 5.1%. Third, the rising interest in eco-friendly materials, including aluminum and cast iron, presents opportunities for innovation and market penetration. However, economic fluctuations challenge growth, particularly in North America, where pricing pressures impact consumer spending. The combination of these factors significantly influences the trajectory of the cookware market, ultimately determining whether the market achieves its projected value by 2033.
By Product Type: Pots, Pans, Woks, Pressure Cookers, Bakeware, Kitchen Tools and Accessories, Others (specialty cooking vessels)
By Material: Stainless Steel, Aluminum, Cast Iron, Carbon Steel, Copper, Ceramic and Stoneware, Others (glass, enamelled steel, composites)
By Coating Type: Standard / Non-Coated, Non-Stick / Coated
By Distribution Channel: Offline, Online
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Cookware market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 4.1% from 2026 to 2033 |
|
Revenue Unit |
USD billion |
|
Segmentation |
By Product Type, Material, Coating Type, Distribution Channel, and Region |
|
By Region |
North America (By Product Type, Material, Coating Type, Distribution Channel, and Country)
|
|
Europe (By Product Type, Material, Coating Type, Distribution Channel, and Country)
|
|
|
Asia Pacific (By Product Type, Material, Coating Type, Distribution Channel, and Country)
|
|
|
South America (By Product Type, Material, Coating Type, Distribution Channel, and Country)
|
|
|
Middle East and Africa (By Product Type, Material, Coating Type, Distribution Channel, and Country)
|
Find answers to common questions about this report
The Cookware market size was valued at USD 29.9 billion in 2025.
The market is projected to grow at a CAGR of 4.1% during the forecast period from 2026 to 2033.
The North America Cookware market size is estimated to reach USD 12.5 billion by 2033.
The leading segment in the Cookware market is Pans, with a projected value of USD 11.4 billion by 2033. This segment surpasses others in terms of revenue generation.
Demographic shifts, particularly the adoption of home cooking by millennials and Gen Z, drive demand for high-quality cookware. the rise in online sales reflects changing consumer purchasing habits, presenting significant growth opportunities in the market.
Increasing raw material costs restrain cookware market growth by affecting consumer purchasing behavior. Higher prices for essential materials like stainless steel and aluminum lead to smaller orders and delayed replacement cycles, impacting overall sales growth. This pressure on pricing restricts broader adoption across various consumer demographics.
Several factors favor adoption in the cookware industry. Increasing consumer interest in home cooking drives demand for high-quality cookware, while a significant shift toward eco-friendly materials reflects growing sustainability awareness. the rise in online sales presents opportunities for brands to connect with a broader customer base, enhancing market reach.
The Cookware market is estimated to reach a valuation of USD 41.3 billion by 2033.
Key players operating in the Cookware market include Groupe SEB, Tramontina, Zwilling J.A. Henckels, Hawkins Cookers Limited, TTK Prestige Limited, and Le Creuset.
The cookware market is projected to expand at a compound annual growth rate of 4.1% from USD 29.9 billion in 2025 to USD 41.3 billion by 2033.
The analysts below cover Consumer Goods research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.
Tracking capacity expansion in single-use bioprocessing requires dependable data on raw material availability and cleanroom-grade polymer supply chains. The competitive landscape chapter gave a grounded evaluation of secondary component suppliers across North America and Asia-Pacific rather than simply reprinting press releases. Having that level of supplier benchmarking helped clarify dual-sourcing considerations for our clinical pipeline planning.
When evaluating distributed energy resource management systems, standard research summaries tend to gloss over the operational differences between front-of-the-meter utility deployments and behind-the-meter industrial sites. The MetaStat Insight report addressed those distinctions directly, especially regarding software interoperability standards and grid interconnection backlogs. The five-year market sizing across regional transmission organizations provided actionable context for our grid modernization strategy.
Most industry reports on warehouse automation bundle autonomous mobile robots and fixed conveyor installations into the same top-level numbers, which complicates advisory work. This study split the market cleanly by payload tiers, navigation technology, and fleet management software layers. The regional forecast for Western Europe gave our team defensible adoption benchmarks when evaluating capital allocation for logistics clients, saving us days of secondary data scrubbing.
Explore related market intelligence reports worth reading alongside this one.