
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

Global Utility Poles Market Size, Share, By Material (Wood, Concrete, Steel, Fiber-Reinforced Polymer, Aluminum, Hybrid Materials), By Application (Electricity Distribution, Electricity Transmission, Telecommunications, Street and Area Lighting, Railway Electrification, Traffic Signals), By Pole Size (Below 40 ft, 40-70 ft, Above 70 ft), By Installation Type (Replacement and Upgrade and New Network Installation), Industry Analysis, Growth, Trends, and Forecast, 2026-2033
Report ID
MSI-3281
Published
October, 2026
Pages
305 Pages
Format
Historical
Base year
Forecast
Forecast period
Report Details
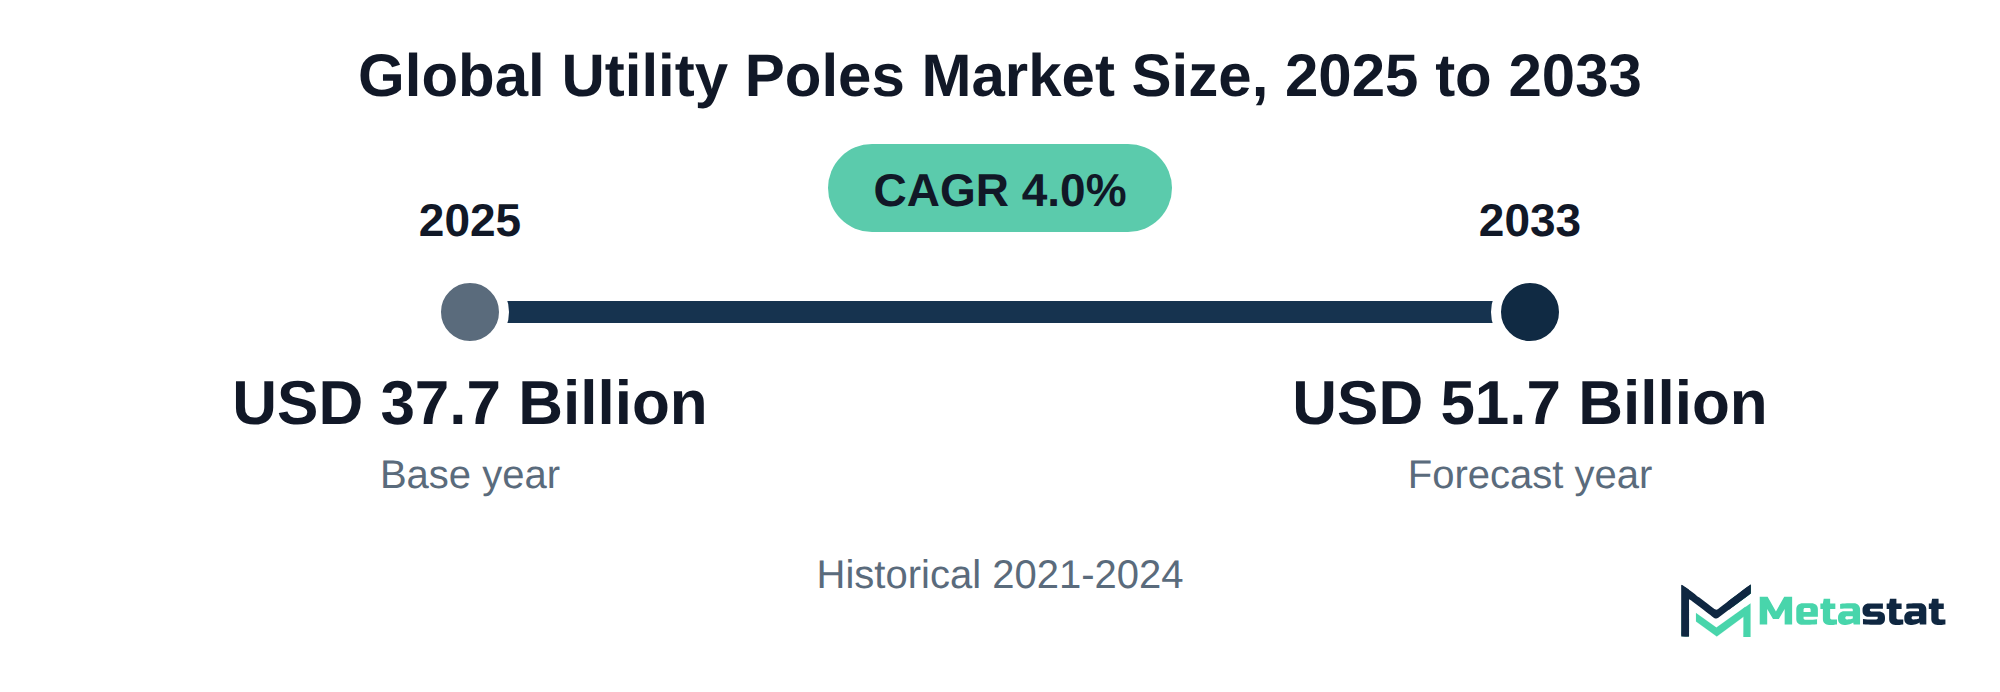
Market Valuation: Valued at $37.7 Billion in 2025, projected to reach $51.7 Billion by 2033 at a 4.0% CAGR.
Dominant Segment: Electricity distribution leads the Utility Poles market, driven by the essential need for reliable power delivery to consumers. This segment reflects significant investments from utility companies aiming to modernize aging infrastructure.
Geographic Lead: North America is projected to hold a substantial market share, with the US leading in 2026. This growth is attributed to increased infrastructure investment and a focus on enhancing energy delivery systems.
What's Inside: The report provides a comprehensive analysis of market dynamics, competitive landscape, and detailed segmentation by material, application, pole size, and installation type, covering the forecast period from 2026 to 2033.
Emerging Material Trends: The fiber-reinforced polymer (FRP) segment shows significant growth potential, with a CAGR of 8.6%, as utility companies seek advanced materials that offer durability and reduced maintenance costs.
Market Restraints: High material costs pose challenges for utility companies, affecting procurement budgets and potentially delaying infrastructure upgrades, particularly for smaller municipalities.
Choose Your License
Global Utility Poles Market
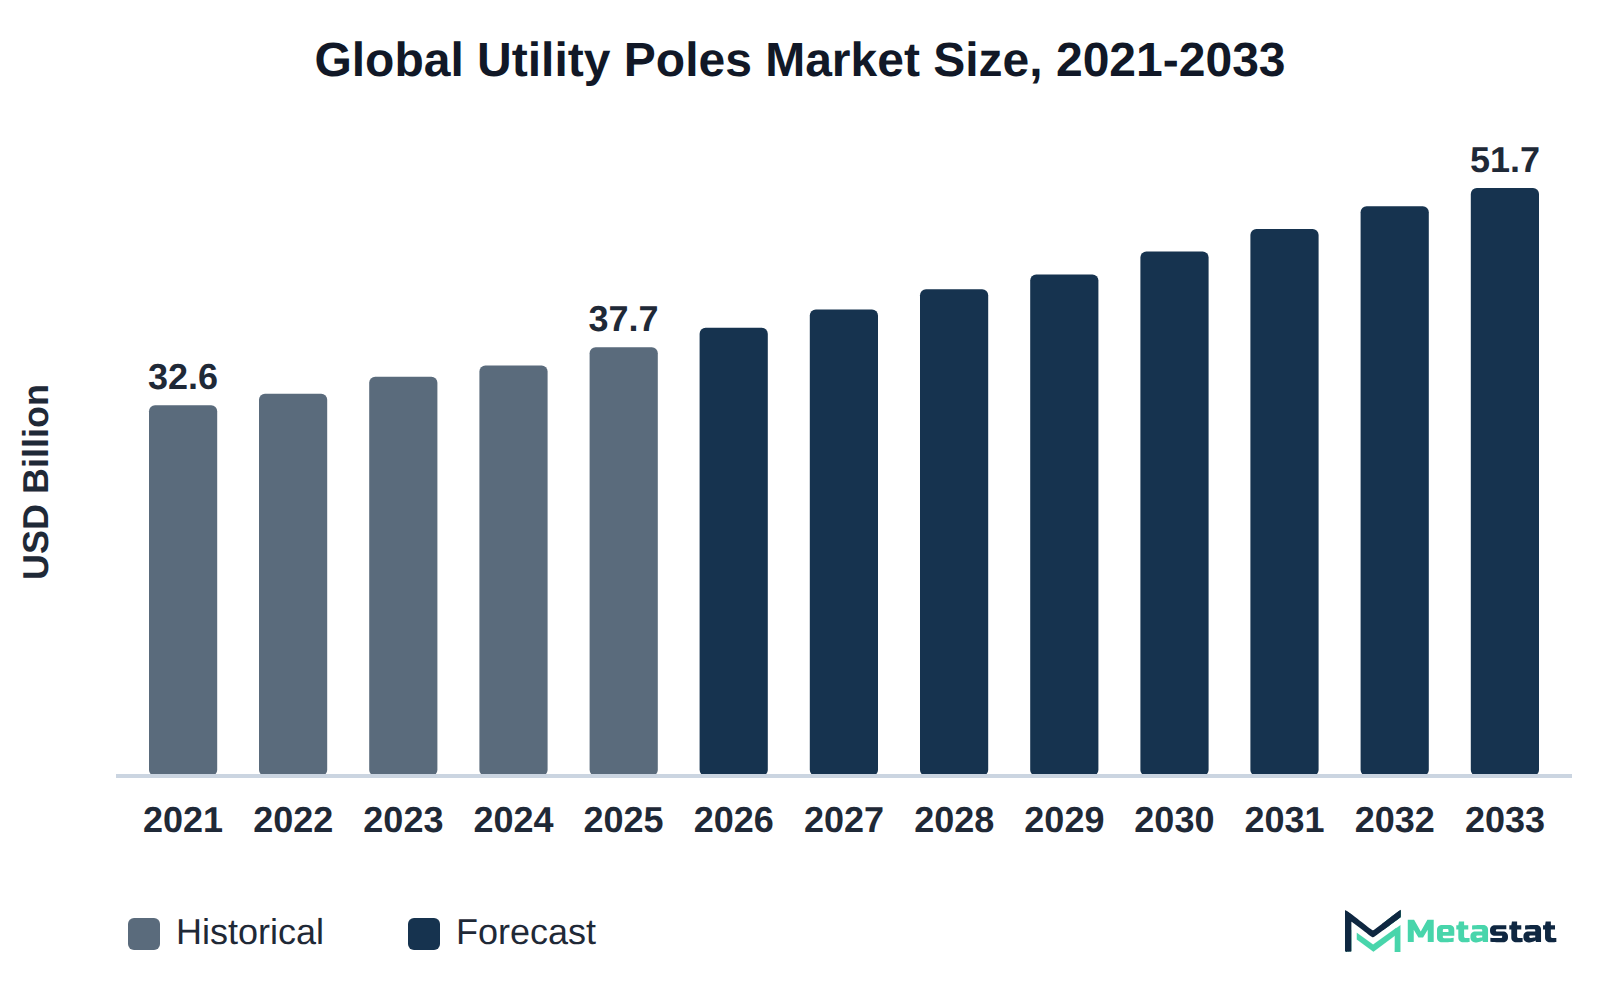
The global Utility Poles market was valued at USD 37.7 billion in 2025 and is projected to reach USD 51.7 billion by 2033, growing at a CAGR of 4.0% over the forecast period.
The Utility Poles market encompasses a variety of products for electricity distribution, transmission, telecommunications, and street lighting, driving significant investment from utility companies, municipalities, and construction firms. The demand arises from the need for reliable infrastructure to support growing urbanization and energy requirements. Buyers invest in utility poles to ensure consistent service delivery, comply with regulatory standards, and enhance safety in public spaces.
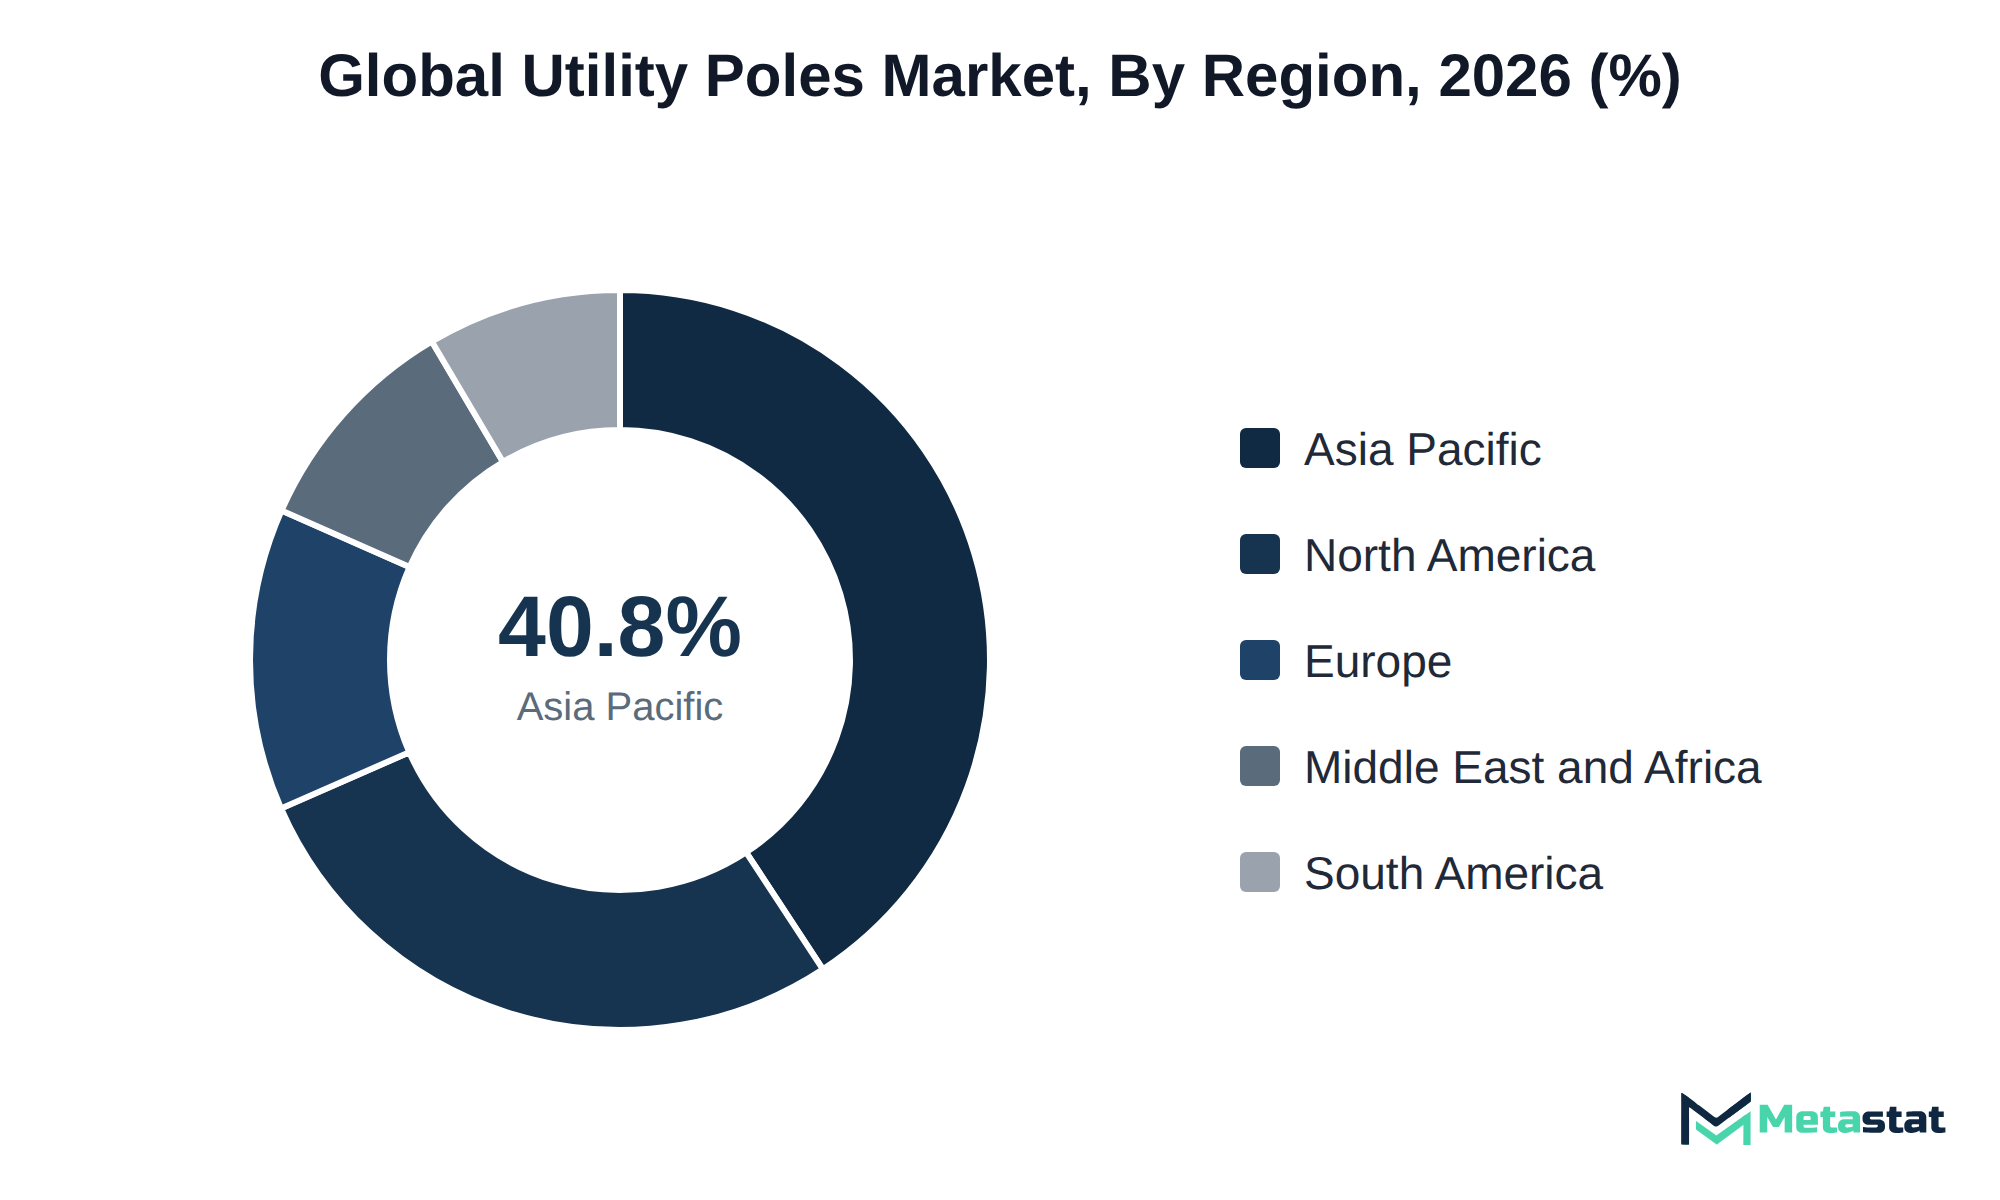
Growth in the market is propelled by increasing energy consumption and the expansion of renewable energy projects. Among the segments, electricity distribution holds the highest value, reflecting its essential role in delivering power to consumers. North America holds 27.7% of the market in 2025, with the US leading in 2026. The Asia Pacific region follows closely, capturing 40.8% of the market share. Demand for utility infrastructure varies across these regional markets.
Investment in utility poles is further supported by the transition towards smart grids and modernized energy systems. The increasing focus on sustainability drives demand for materials including fiber-reinforced polymer. The market is shifting toward more efficient and adaptable energy solutions, which supports continued growth in the coming years.
The Utility Poles market serves various sectors, including electricity distribution, transmission, telecommunications, and street lighting, reflecting the increasing demand for reliable infrastructure. Investment from utility companies and government agencies drives this spending, highlighting the critical nature of utility poles in maintaining and enhancing energy networks. The emphasis on sustainable and durable materials influences purchasing decisions, with stakeholders seeking long-lasting solutions for their infrastructure needs.
Growth in the market is primarily fueled by increasing urbanization and the need for improved energy distribution networks. Electricity distribution is the highest-value segment, with strong demand stemming from the need for reliable power supply in urban areas. This region's focus on upgrading aging infrastructure contributes to its substantial market share.
Investment in renewable energy sources and smart grid technologies further accelerates market expansion. The growing emphasis on environmental sustainability and energy efficiency influences the adoption of advanced materials, including fiber-reinforced polymer (FRP), which offers significant advantages over traditional materials. The Utility Poles market is expected to enhance its role in the global energy landscape.
Groundline decay presents a significant challenge for the utility poles market, particularly concerning wood poles. This issue arises from the deterioration of the pole's lower section, where it meets the ground, often leading to structural weaknesses. In the market, wood poles represent a significant share, with a forecasted value increasing from USD 21.8 billion in 2026 to USD 26.8 billion by 2033, reflecting a compound annual growth rate of 3.0%. Such figures highlight the necessity for effective preservative treatments to extend the lifespan of wood poles and mitigate replacement costs.
Preservative treatments enhance the resistance of wood poles to groundline decay, promoting longevity and reliability. Micronized copper azole is one example of a wood preservative used to protect timber from decay. Utility companies increasingly invest in advanced treatments, ensuring poles withstand environmental factors that contribute to decay. Growing demand for treated wood poles influences purchasing decisions among utility companies aiming to optimize their infrastructure investments. Consequently, preventive measures against groundline decay are expected to affect operating costs and performance standards in the utility poles market.
The shift towards storm hardening has driven procurement strategies in the Utility Poles market, increasing interest in steel and fiber-reinforced polymer (FRP) structures. Buyers prioritize durable materials that withstand extreme weather conditions, resulting in a notable increase in the use of steel poles, projected to reach USD 8.6 billion by 2033. This growth reflects a larger trend among utility companies to reduce service interruptions and maintenance costs associated with storm damage.
Pricing models in the market often depend on the materials selected, with steel and FRP poles generally commanding higher upfront costs compared to traditional wood. Long-term savings in maintenance and replacement offset these initial expenditures, making steel and FRP attractive options for utilities. The long lifespan and resilience of these materials lead to a more favorable total cost of ownership, prompting more buyers to invest in them.
Contracts in this sector tend to favor long-term agreements, allowing utility companies to secure favorable pricing and ensure stable supply levels. Such arrangements support budgeting and facilitate better inventory management for buyers. Enhanced reliability in supply is critical given the increasing frequency and severity of storms, influencing procurement strategies across the market.
Accurate pole inventories hold significant value for utility companies, particularly when integrating joint-use attachments. These attachments facilitate shared infrastructure, allowing multiple utilities to share a single pole, which enhances operational efficiency. The revenue generated from joint-use agreements contributes substantially to the overall profitability of utility operations. For instance, the Electricity Distribution application segment is projected to grow from USD 21.7 billion in 2026 to USD 27.8 billion by 2033, reflecting a compound annual growth rate (CAGR) of 3.6%. This growth reflects increasing demand for shared infrastructure.
Utility companies that invest in complete pole inventories optimize their assets while meeting diverse regulatory and customer needs. With the expected rise in demand for joint-use attachments, companies that maintain accurate inventory data identify opportunities for expanding service offerings and enhancing customer satisfaction. Accurate inventories streamline maintenance practices and provide insights for future investments, which is critical for competitive positioning within the Utility Poles market. Pole inventory data also supports asset performance management, which tracks the condition and maintenance needs of equipment. Efficient pole inventory management supports profitability and positions companies for future growth.
Utilities face critical decisions regarding the maintenance and replacement of aging poles. Reinforcing an aging pole is a viable option when the structural integrity remains intact and the pole still meets operational demands. The reinforcement process often involves adding support structures or materials to enhance strength and durability, which extends the lifespan of the pole at a lower cost compared to full replacement.
Investment in reinforcement saves utilities significant amounts, particularly when considering the cost of new materials and installation. The Replacement and Upgrade segment of the Utility Poles market is expected to grow from USD 24.5 billion in 2026 to USD 33.2 billion by 2033, reflecting a compound annual growth rate (CAGR) of 4.4%. This growth indicates a strong focus on maintaining existing infrastructure, where reinforcement plays a role in optimizing expenditures while addressing safety and reliability concerns.
Ultimately, the decision to reinforce rather than replace hinges on individual pole assessments and the financial implications involved. By choosing reinforcement in suitable scenarios, utilities better allocate resources and enhance service continuity without incurring the full costs associated with new installations.
Utility companies are increasingly investing in infrastructure improvements, driven by the need for reliable and resilient power delivery systems. The focus on modernizing electricity transmission and distribution systems and expanding telecommunication networks generates substantial demand for utility poles. This investment shift reflects a growing awareness of the importance of infrastructure integrity, particularly in regions prone to severe weather events. The Electricity Distribution application segment is expected to grow from USD 21.7 billion in 2026 to USD 27.8 billion by 2033, demonstrating significant spending by utility companies on new installations and upgrades. Stronger infrastructure commitments raise demand for suppliers in the Utility Poles market and influence pricing and volume dynamics across pole material segments.
Advancements in pole materials drive growth in the Utility Poles market by enhancing durability and performance. Innovations including fiber-reinforced polymer (FRP) offer superior resistance to environmental factors compared to traditional wood and concrete options. These developments attract utility companies seeking efficient solutions to prolong asset life and reduce maintenance costs. Increased awareness of the long-term benefits of using advanced materials influences purchasing decisions, particularly in regions prone to extreme weather conditions. Utility companies prioritizing reliability in their infrastructure increasingly adopt these innovative materials. The market's growth reflects the ongoing transition toward more resilient utility pole options, aligning with broader sustainability goals among industry stakeholders.
High material costs represent a significant constraint for buyers in the Utility Poles market. The increasing prices of wood, concrete, and steel directly impact procurement budgets for utility companies. For utility providers, rising costs lead to delayed replacement schedules and reduced orders for new installations. This situation particularly affects smaller municipalities and rural utilities, which operate under tighter financial constraints. Suppliers experience slower sales growth as a result, affecting their production and investment strategies. Raw material costs create challenges for market participants and could stall broader infrastructure development initiatives.
Rising input costs present a considerable challenge for suppliers in the utility poles market, particularly impacting the manufacturing of wooden and concrete poles. Increased prices for raw materials, including timber and cement, significantly squeeze profit margins, affecting overall competitiveness in the market. Suppliers are responding by seeking alternative materials, including fiber-reinforced polymer (FRP), which offer cost-competitive advantages and reduce reliance on traditional inputs. Companies optimize production processes to enhance efficiency while minimizing waste, thus addressing rising costs. Investment in research and development facilitates the exploration of innovative manufacturing techniques, enabling suppliers to maintain profitability in the face of escalating costs. Material innovation and process improvement help suppliers adapt to market pressures while maintaining product availability and quality.
The fiber-reinforced polymer (FRP) segment presents significant growth potential within the Utility Poles market. With a compound annual growth rate (CAGR) of 8.6%, FRP poles are gaining traction due to their advanced durability and lightweight characteristics. This segment appeals to utility companies seeking materials that enhance structural resilience while reducing overall weight for easier installation. Increasing demand for utilities to adopt advanced materials drives procurement towards FRP options, particularly in regions facing severe weather conditions. Traditional materials face limitations, and FRP poles emerge as a viable alternative, addressing the need for improved performance in challenging environments. This shift reflects broader trends in the market where innovation in materials supports growth and adoption across multiple applications.
The Global Utility Poles market is segmented based on Material, Application, Pole Size, and Installation Type.
The wood segment is valued at USD 21.8 billion in 2026 and is projected to reach USD 26.8 billion by 2033, at a CAGR of 3% during the forecast period. Utility companies use wood poles primarily for electricity distribution and street lighting applications, favoring their cost-effectiveness and availability. The demand for wood poles is driven by the need for affordable infrastructure solutions, particularly in regions with existing wood pole networks. In comparison to other materials, wood poles offer a lower initial cost but exhibit slower growth relative to concrete and fiber-reinforced polymer segments, which experience CAGRs of 4.3% and 8.6% respectively. Environmental considerations, including sustainable sourcing and treatment processes, shape the procurement of wood poles, ensuring compliance with regulatory standards while meeting demand in the market.
Concrete poles are projected to reach USD 12 billion by 2033, at a CAGR of 4.3% during the forecast period. These poles serve critical functions in electricity distribution and transmission, widely used by utility companies aiming to enhance their infrastructure's resilience. The increasing focus on durability and longevity drives demand for concrete poles, particularly in regions prone to extreme weather conditions. This segment demonstrates stronger growth compared to wood poles, which face challenges including groundline decay. While both materials compete in the market, concrete poles typically command higher prices due to their extended lifespan and lower maintenance requirements. Factors including stringent regulations regarding safety and environmental impact further influence the adoption of concrete poles, reinforcing their position in the market.
Steel segments are expected to reach USD 8.6 billion by 2033. This material is widely employed in utility poles for applications in electricity distribution, transmission, and telecommunications, serving utility companies seeking durable structures. The growth of the steel segment is driven by increasing investments in infrastructure and a growing emphasis on storm-resistant solutions. With a compound annual growth rate (CAGR) of 4.1%, this segment experiences a faster growth trajectory compared to concrete, which has a CAGR of 4.3%. The unique properties of steel, including its strength and longevity, offer advantages that differentiate it from wood and fiber-reinforced polymer (FRP) poles, appealing to utilities focused on sustainability and resilience. Competitive pricing for steel enhances accessibility, positioning this segment favorably in the market.
Fiber-Reinforced Polymer (FRP) segment is projected to grow at a CAGR of 8.6% during the forecast period. This segment finds application in various utility sectors, particularly in the construction of poles for electricity distribution and telecommunications. The growth of this segment is primarily driven by the increasing demand for lightweight yet durable materials that enhance resilience against environmental factors. Utility companies recognize FRP's advantages, which include lower maintenance costs and greater longevity compared to traditional materials. Compared to the other segments under material, including wood and concrete, which are predicted to grow at CAGRs of 3% and 4.3% respectively, FRP exhibits a higher growth rate, suggesting a shift in preference toward advanced materials in the market due to their superior properties and cost-effectiveness over time.
Utility poles made from aluminum and hybrid materials incorporate innovative designs and compositions. These alternatives cater to industries focusing on lightweight and corrosion-resistant solutions, particularly in telecommunications and renewable energy sectors. The demand for these materials is driven by the increasing emphasis on sustainable infrastructure and reduced maintenance costs. Unlike traditional materials including wood and concrete, which face challenges related to decay and heavy weight, aluminum and hybrid options provide enhanced durability and longevity. This segment attracts utility companies and telecommunications providers seeking efficiency and long-term cost savings. The market is expected to experience steady growth in this area, supported by technological advancements that improve material properties and performance.
Utility providers employ this segment for the delivery of electric power to residential, commercial, and industrial customers, reflecting the essential infrastructure needed for reliable energy access. Growth in this segment stems from increased investments in grid modernization and the expansion of renewable energy sources, which require robust distribution networks. In comparison to other applications, Electricity Distribution demonstrates a slower growth rate than Electricity Transmission, which is projected to reach USD 11.8 billion in the same timeframe. The market faces challenges related to aging infrastructure and the urgency for upgrades, prompting utility companies to prioritize spending in this area.
Electricity Transmission segment is estimated to reach USD 11.8 billion by 2033, at a CAGR of 4.7% during the forecast period. This segment facilitates the movement of electricity over long distances, serving utility companies and energy providers that require reliable infrastructure for power delivery. Growing investments in grid modernization and the need for efficient energy distribution drive demand for this segment. Compared to the Electricity Distribution segment, which expands at a CAGR of 3.6%, this segment experiences a faster growth rate, highlighting its importance in supporting energy infrastructure upgrades. Continuous advancements in technologies, including smart grid systems and enhanced pole materials, significantly contribute to the segment's expansion. Overall, the Electricity Transmission segment holds significant value in the Utility Poles market, reflecting the evolving needs of the energy sector.
Telecommunications segment is expected to reach USD 6.2 billion by 2033. This segment serves the needs of telecommunications companies by providing infrastructure for communication networks, including fiber optics and wireless towers. Growth in this area is primarily driven by increased demand for high-speed internet, including fixed broadband, and mobile connectivity, resulting in ongoing investments in telecommunications infrastructure. Compared to other applications, the telecommunications segment experiences faster growth, reflected in its CAGR of 4.7%. The segment's expansion is influenced by technological advancements that enhance the efficiency and performance of communication networks, positioning it as a critical component of modern infrastructure. Investments in smart city initiatives and IoT connectivity further increase demand for utility poles tailored to telecommunications, distinguishing this segment's growth trajectory from that of electricity distribution and transmission.
Street and Area Lighting segment is projected to grow at a CAGR of 3.6% during the forecast period. This segment serves essential functions in urban planning and public safety by providing light for streets, pathways, and public spaces. Municipalities and urban developers primarily use these poles to enhance visibility and safety for pedestrians and vehicles. Increasing emphasis on smart city initiatives drives demand for advanced lighting solutions, including lighting control systems, contributing to market expansion. This segment differs from others, including Electricity Distribution, where higher growth rates occur, reflecting differing buyer priorities. While Street and Area Lighting focuses on municipal requirements and aesthetics, Electricity Distribution emphasizes reliability in power supply. The segment's growth trajectory is expected to remain steady, driven by infrastructure investments aimed at improving urban environments.
Utility poles for railway electrification and traffic signals support the infrastructure for rail transportation and road traffic systems. Utilities and transportation agencies employ these poles to facilitate safe and efficient operation of railway lines and manage traffic effectively. Growth in urbanization and increased demand for public transport solutions drive the need for enhanced electrification and integrated traffic management systems. This segment experiences unique dynamics compared to other applications, with investment heavily relying on government funding and regulatory initiatives for transportation improvements. These factors contribute to a relatively slower growth rate compared to segments like electricity distribution, which benefits from ongoing modernization efforts. The demand for reliable signaling and electrification solutions continues to emphasize the importance of this segment within the Utility Poles market.
Below 40 ft segment is valued at USD 15 billion in 2026 and is projected to reach USD 18.8 billion by 2033, at a CAGR of 3.3% during the forecast period. This segment finds applications in urban areas where utility companies focus on electricity distribution and street lighting. Demand for these poles primarily comes from municipalities and utility providers aiming to improve infrastructure efficiency and reliability. Competition within this segment remains robust, with customers seeking cost-effective solutions. This sub-segment exhibits slower growth compared to larger pole sizes, including the 40-70 ft segment, which has a CAGR of 4.1%. The relatively lower pricing of below 40 ft poles, coupled with demand for flexible installation options in dense urban settings, drives adoption among several buyers.
The 40-70 ft segment is estimated to reach USD 24 billion by 2033, at a CAGR of 4.1% during the forecast period. This size category primarily serves utility companies for both electricity distribution and transmission applications, where pole height is critical for effective service delivery. Demand in this segment strengthens due to ongoing infrastructure upgrades and urbanization, increasing the necessity for reliable electricity and communication networks. Compared to other pole sizes, the 40-70 ft segment experiences moderate growth, influenced by the expanding requirements of urban and suburban developments. In contrast, the below 40 ft segment shows a slower growth rate of 3.3%, highlighting a distinct market dynamic. This segment's growth reflects a shift in buyer preferences toward taller poles that improve service coverage and reliability, shaping the competitive landscape of the Utility Poles market.
The Above 70 ft segment is expected to reach USD 8.9 billion by 2033. These utility poles serve significant functions in high-voltage electricity distribution and telecommunications, particularly in areas requiring robust infrastructure. The demand for larger poles is driven by the increasing need for more resilient structures that handle heavy loads and adverse weather conditions. This segment experiences higher growth potential compared to smaller pole categories, primarily due to rising investments in infrastructure projects globally. The CAGR for this segment is not explicitly stated; however, its importance is evident in applications including electricity transmission. The cost of producing larger poles often exceeds that of smaller alternatives, influencing purchasing decisions predominantly among utility companies and infrastructure developers focused on long-term investments. Growth in this segment contributes positively to the overall projections for the market.
This segment focuses on the enhancement and modernization of existing utility pole networks, primarily serving electricity distribution and telecommunications providers. Factors influencing growth include aging infrastructure in many regions, necessitating upgrades to ensure reliability and efficiency. Compared to other segments, Replacement and Upgrade exhibits robust demand driven by utility companies addressing safety and regulatory compliance issues. The segment is expected to grow at a faster rate than new network installations, which project a CAGR of 3.2%. The ongoing emphasis on replacing outdated poles with more durable and resilient options aligns with broader trends in infrastructure investment, enhancing the value proposition of this segment in the Utility Poles market.
New Network Installation segment is estimated to reach USD 18.5 billion by 2033, at a CAGR of 3.2% during the forecast period. This segment involves the deployment of utility poles for newly established electrical and telecommunications networks, used by utility companies and telecommunications providers to expand infrastructure. The driving force behind this segment includes the increasing demand for reliable connectivity and electricity distribution in urban and rural areas. Compared to other installation types, this segment experiences slower growth due to the higher costs associated with new installations, contrasting with replacement and upgrades that often utilize existing infrastructure. The market reflects continued investment in developing energy-efficient systems and smart grid technologies, which influences the strategies employed by suppliers in this segment.
Based on geography, the Global Utility Poles market is divided into North America, Europe, Asia-Pacific, South America, Middle East, and Africa.
Demand for utility poles in North America is driven by significant investments in infrastructure modernization and renewable energy projects. The United States, Canada, and Mexico prioritize upgrading their electricity distribution networks, enhancing reliability and efficiency. This region's focus on aligning with environmental standards supports market growth, reflecting the commitment to sustainable energy. North America is projected to reach USD 13.8 billion by the end of 2033. The market benefits from a strong supply chain, with established manufacturers capable of meeting increasing demand across segments, including wood and concrete utility poles. Investment in smart grid technologies further strengthens the market, creating opportunities for advanced utility poles that support evolving electrical needs.
Demand within the Utility Poles market in Europe benefits from investments in renewable energy and infrastructure modernization. Key countries including Germany, France, and the UK emphasize sustainable energy initiatives, driving the need for enhanced electricity distribution networks. Government policies aimed at upgrading aging power infrastructure create significant opportunities for utility pole manufacturers. The region's share of the global market stands at 13.2% in 2025, indicating substantial activity within the sector. Cost considerations, including rising material prices, challenge several buyers. However, the transition toward more durable and sustainable materials is expected to influence purchasing decisions positively. France and Germany lead in adopting advanced technologies for utility poles, enhancing operational efficiency and safety standards across various applications.
Asia-Pacific holds a 40.8% share in the global Utility Poles market for 2025. Rapid urbanization and industrial growth drive demand in this region, particularly in countries like China, India, and Japan. Investments in renewable energy and electricity infrastructure, backed by government initiatives, support the electricity distribution and transmission sectors. The increasing focus on smart city projects enhances the need for telecommunications infrastructure, which directly impacts the demand for utility poles. Local manufacturers seek to innovate and improve production capabilities to meet this growing demand. Competitive pricing remains a critical factor, influencing procurement decisions among utility companies and contractors in the region. Investment in the Utility Poles market is expected to continue its upward trajectory, reflecting the expanding infrastructure requirements across the region.
In South America, the Utility Poles market is shaped by significant activities in the electricity distribution and telecommunications sectors. Brazil and Argentina represent key drivers of demand due to ongoing infrastructure investments aimed at enhancing electricity accessibility and improving telecommunications networks. Governments in these countries actively promote initiatives to modernize aging infrastructure, positively impacting the market. The region, holding an 8.5% share of the global market in 2025, reflects growth opportunities influenced by rising urbanization and population expansion. Challenges persist, including cost constraints linked to material sourcing and logistics, yet the market shows potential for expansion driven by increased electrification efforts and new project developments.
Investment in energy infrastructure plays a significant role in the demand for utility poles within the Middle East and Africa. The region's rapid urbanization, particularly in Saudi Arabia and the UAE, drives significant requirements for electricity distribution and telecommunications. Government initiatives focusing on energy efficiency and renewable energy adoption support this growth, creating opportunities for market expansion. South Africa's aging utility infrastructure necessitates replacement and upgrades, further enhancing market prospects. The region's share of the global market stands at 9.9% in 2025, with growth expected to continue through 2033. Development in telecommunications infrastructure complements electricity distribution efforts, targeting improved connectivity across urban and rural areas. Together, these factors support participants in the utility poles market and point to a strong outlook for the coming years.
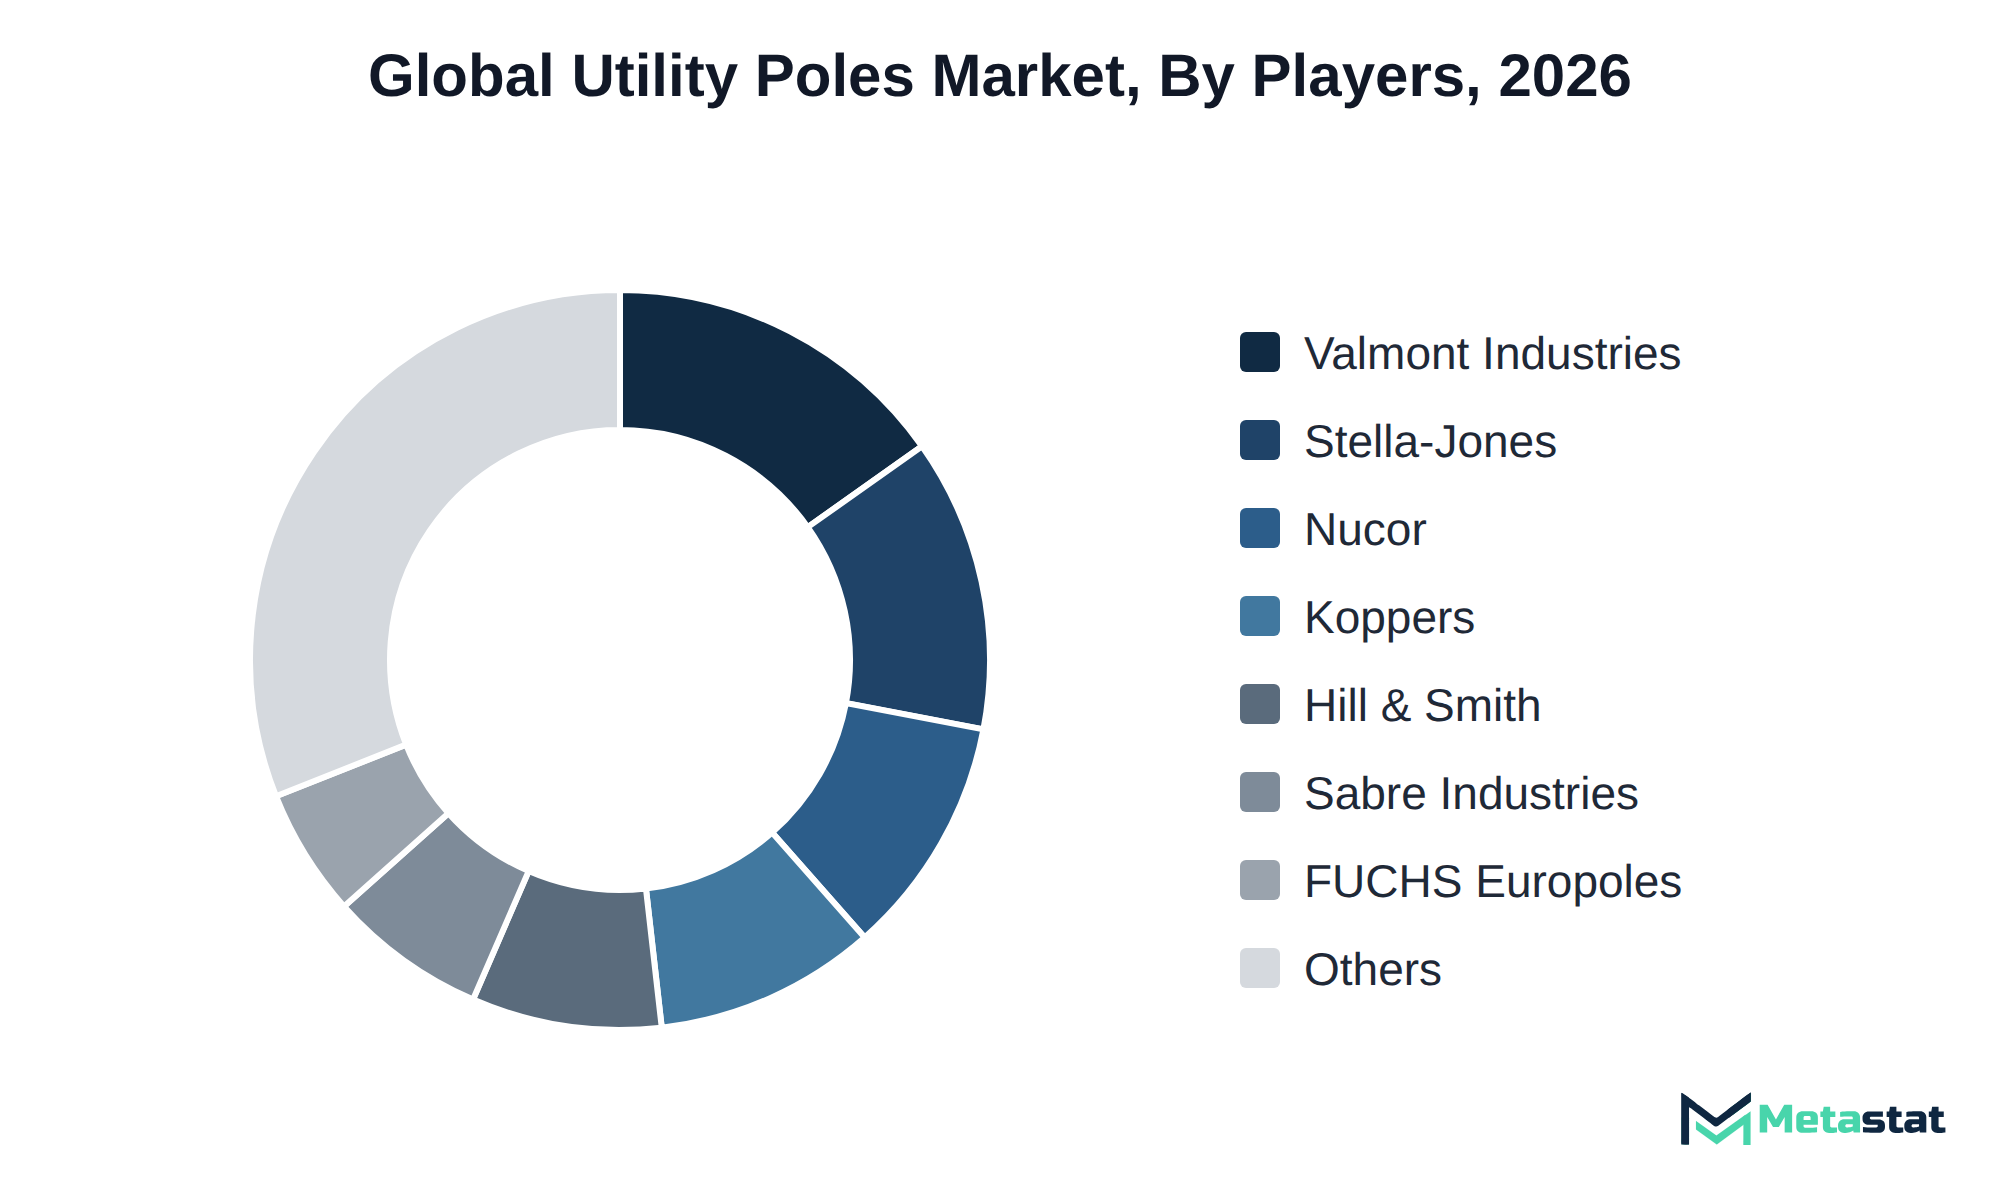
Competition in the Utility Poles market reflects a diverse range of strategies and specializations among key players. Companies differentiate themselves based on material offerings, service quality, and customization capabilities. For instance, Valmont Industries, Inc. focuses on a variety of materials, including wood and concrete, to address varying customer needs, while Stella-Jones Inc. emphasizes its extensive distribution network to enhance service delivery across multiple regions.
Buyers evaluate options based on factors including pricing, certification standards, and the ability to provide tailored solutions. Koppers Holdings Inc. highlights its commitment to high-quality standards and certifications, appealing to buyers prioritizing compliance and reliability. In contrast, Sabre Industries, Inc. emphasizes innovation in product design, catering to clients seeking advanced features in utility poles. This competitive landscape encourages an environment where companies continually enhance their offerings to meet evolving customer demands.
Achieving this target requires significant developments across various segments of the Utility Poles market. One key factor involves the increased adoption of wood poles, anticipated to grow from USD 21.8 billion in 2026 to USD 26.8 billion by 2033, driven by rising demand for sustainable and cost-effective materials. This growth reflects ongoing investments in power infrastructure across several regions, particularly in North America and Asia Pacific. A major risk to this forecast involves potential supply chain disruptions and rising material costs, particularly affecting concrete and steel poles, which could hinder growth in the market. Addressing these challenges is essential to maintaining the projected trajectory towards USD 51.7 billion.
By Material: Wood, Concrete, Steel, Fiber-Reinforced Polymer (FRP), Others (Aluminum, Hybrid Materials)
By Application: Electricity Distribution, Electricity Transmission, Telecommunications, Street and Area Lighting, Others (Railway Electrification, Traffic Signals)
By Installation Type: Replacement and Upgrade, New Network Installation
The report strategically identifies and profiles the key market players and analyses their core competencies in each sub-segment of the Utility Poles market.
|
Report Attributes |
Details |
|
Study Period |
2021-2033 |
|
Base Year |
2025 |
|
Estimated Year |
2026 |
|
Forecast Period |
2026-2033 |
|
Historical Period |
2021-2025 |
|
Growth Rate |
CAGR 4.0% from 2026 to 2033 |
|
Revenue Unit |
USD billion |
|
Segmentation |
By Material, Application, Pole Size, Installation Type, and Region |
|
By Region |
North America (By Material, Application, Pole Size, Installation Type, and Country)
|
|
Europe (By Material, Application, Pole Size, Installation Type, and Country)
|
|
|
Asia Pacific (By Material, Application, Pole Size, Installation Type, and Country)
|
|
|
South America (By Material, Application, Pole Size, Installation Type, and Country)
|
|
|
Middle East and Africa (By Material, Application, Pole Size, Installation Type, and Country)
|
Find answers to common questions about this report
The Utility Poles market size was valued at USD 37.7 billion in 2025.
The market is projected to grow at a CAGR of 4.0% during the forecast period from 2026 to 2033.
The North America Utility Poles market size is estimated to reach USD 13.8 billion by 2033.
The leading segment in the Utility Poles market is Electricity Distribution, with a projected value of USD 27.8 billion by 2033. This segment surpasses others in terms of revenue generation within the market.
Investment in infrastructure improvements is driven by the need for reliable and resilient power delivery systems. Advancements in pole materials enhance durability and performance, attracting utility companies seeking efficient solutions to prolong asset life and reduce maintenance costs.
High material costs significantly restrain market growth, impacting procurement budgets for utility companies and leading to delayed replacement schedules. Rising input costs, particularly for wooden and concrete poles, squeeze profit margins and affect overall competitiveness in the market.
The shift towards advanced materials, particularly fiber-reinforced polymer (FRP), supports adoption due to their enhanced durability and lightweight characteristics. This trend aligns with utility companies' need for resilient infrastructure solutions, especially in regions prone to severe weather conditions.
The Utility Poles market is estimated to reach a valuation of USD 51.7 billion by 2033.
Key players operating in the Utility Poles market include Valmont Industries, Inc., Stella-Jones Inc., Koppers Holdings Inc., Bell Lumber & Pole Company, Sabre Industries, Inc., Hill & Smith PLC, and Tata Steel Limited.
The Electricity Distribution application segment is expected to grow from USD 21.7 billion in 2026 to USD 27.8 billion by 2033, reflecting significant investment by utility companies.
The analysts below cover Energy and Power research at Metastat Insights.
LEAD ANALYST
Utkarsh Khirodkar is a Lead Market Research Analyst at MetaStat Insight, specializing in market intelligence, technology sector assessments, and competitive strategy.

PRINCIPAL CONSULTANT - ENTERPRISE AI & EMERGING TECHNOLOGIES
Banking & Finance · Electronics and Semiconductor · Energy and Power · Healthcare IT · Information & Technology · Professional Services
Vijay Gunti is a Principal Consultant at MetaStat Insight, bringing over two decades of experience across enterprise digital transformation, technology strategy, and intelligent systems.
ENERGY & INFRASTRUCTURE INDUSTRY CONSULTANT
Automotive and Transportation · Electronics and Semiconductor · Energy and Power · Machinery & Equipment
Saurabh Vasant Ganvir consults for Energy & Infrastructure Industry at MetaStat Insight, specializing in renewable energy, solar EPC, and electric vehicle (EV) infrastructure markets.
Integrating zero-trust access controls across legacy electronic health record systems involves complex compliance overhead. Team produced an analysis that clearly separated identity governance and administration tools from privileged access management platforms. Their evaluation of HIPAA and GDPR compliance features across cloud native solutions gave our architecture group clear baseline criteria. The custom data request regarding biometric authentication adoption in hospital networks was returned promptly with clear documentation.
Evaluating calorific value requirements and air permit compliance across municipal waste facilities requires localized data. Metastat Insight structured their analysis around operational throughput capacity and feedstock composition variations in Latin America and Eastern Europe. Their competitive mapping of sorting equipment vendors helped clarify technology differences between optical separators and heavy media systems. The study provided an objective baseline during our capital expenditure reviews.
Decarbonizing industrial thermal processes hinges on refrigerant regulations and compressor efficiency limits. Metastat Insights delivered a thorough market analysis that evaluated natural refrigerants like CO2 and hydrocarbons against synthetic low-GWP alternatives. The breakdown of utility incentives and grid capacity constraints across key European manufacturing hubs offered valuable perspective. The follow-up conversation with their sector analysts addressed our specific questions on mechanical vapor recompression systems efficiently.
Explore related market intelligence reports worth reading alongside this one.